
Global Memory Deep Dive: 2Q26 Earnings Divergence; Can Better 3Q Pricing Restart the Memory Stock Re-Rating?
目录
Too Long; Didn’t Read
1. This Update Is Really About 3Q Slope, Not 2Q
2. Why 2Q Diverged: Pricing Is Not Rising Uniformly; It Is Re-Segmenting
3. The Key in 3Q Is Mainstream DRAM: Beyond HBM, Commodity Memory Is Starting to Catch Up
4. HBM’s New Question: Not Whether It Is Scarce, but Whether Margins Can Catch Up
5. The Value of LTAs: Whether Peak-Cycle Profits Can Be Capitalized Depends on Contracts
6. Samsung and SK Hynix: One Is Buying Asymmetry, the Other Execution
7. Data-Center Ledger: Memory Has Moved from Supporting Cost to Hard Constraint on Compute Budgets
8. Supply Is Expanding, but Far Less Evenly
9. NAND’s Second Curve: After Rubin, Flash Re-enters the AI Architecture Budget
10. How to Read Valuation: Not Who Is Cheapest, but Whose Peak Profit Can Persist
11. From Korea to Global Assets: What This Report Really Affects Is the Entire Memory Chain
12. Three Worldviews: Asset Revaluation, Strong Cyclical Rebound, and Demand Mismatch
13. Profit Bridge: Why 2027 Matters More Than 2026
14. How to Rank Them: Buy Cash-Flow Certainty First, Then NAND Second-Order Leverage
15. The Real Reflexivity in This Cycle: High Profits Themselves Change Supply and Demand
16. How to Validate the Next Four Quarters: Do Not Watch Only Spot Prices; Watch Contracts and Capacity
17. Risks and Falsification: What This Cycle Fears Most Is Not Volatility, but Profits Being Re-Cyclicalized
18. Conclusion: This Is Not an Ordinary Price-Hike Report, but a Stress Test of Memory Stocks’ Transition from Cyclical Products to Cash-Flow Assets
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The real incremental takeaway from Nomura’s global memory update is not who earned slightly more in 2Q, but that it reconnects 3Q pricing slope, HBM margin catch-up, long-term agreements, and valuation multiples into one line: memory stocks are moving from cyclical rebound into cash-flow asset re-rating. But the verification points are also tougher. Over the next four quarters, contract prices, LTA terms, and supply discipline will need to be tested repeatedly.
Too Long; Didn’t Read
3Q pricing is the main battlefield. Nomura raised its 3Q26 commodity DRAM q/q assumption from +5% to +24%, with NAND at +25%. Price increases are spreading from HBM and servers into broader products.
2Q divergence cannot be judged only by OP. Samsung OP was revised up to KRW 76tn; SK hynix OP is below the prior estimate, but Kioxia gains lift net profit.
HBM still has a margin gap. Nomura believes its margin remains below standard DRAM, and 2027 price increases may be stronger, depending on HBM4 pricing, share, and LTAs.
NAND is not ordinary restocking. Rubin is starting to include flash in its budget, while enterprise SSDs and the AI inference data layer extend the shortage cycle. SanDisk and Kioxia still have upside elasticity.
Samsung is a valuation-odds trade; SK hynix is an execution trade. Samsung depends on valuation, HBM4, and dividends; SK hynix depends on HBM leadership, M15X ramp, and LTA cash flow.
The risk is profit re-cyclicality. Data-center delays, customer bargaining power, Chinese supplier expansion, and HBM supply release could push high profits back to peak-cycle discounts.
Watch five indicators from here: 3Q contract prices, LTA terms, HBM4 yield, capacity ramp, and cloud capex. They determine whether asset re-rating can continue and will affect subsequent positioning.
1. This Update Is Really About 3Q Slope, Not 2Q
Nomura’s global memory report appears to update 2Q26 earnings, but the real investment implication lies in its 3Q26 pricing assumptions. 2Q did show divergence: Samsung Electronics’ operating profit forecast was revised up because of memory pricing, bonus provisions, and FX assumptions; SK hynix operating profit may be below Nomura’s prior expectation, but Kioxia stake disposal and valuation gains push net profit far above consensus. If one only looks at “who beat and who missed,” the report is easy to misread too narrowly.
The more important point is that the price curve has been redrawn. Nomura raised its 3Q26 commodity DRAM price increase assumption from roughly +5% q/q to +24%, while maintaining NAND at +25%. This is not a mild revision. It changes the narrative from “memory price hikes are still being realized in a few categories” to “price increases are spreading from HBM and high-end server memory into broader commodity DRAM and NAND.”
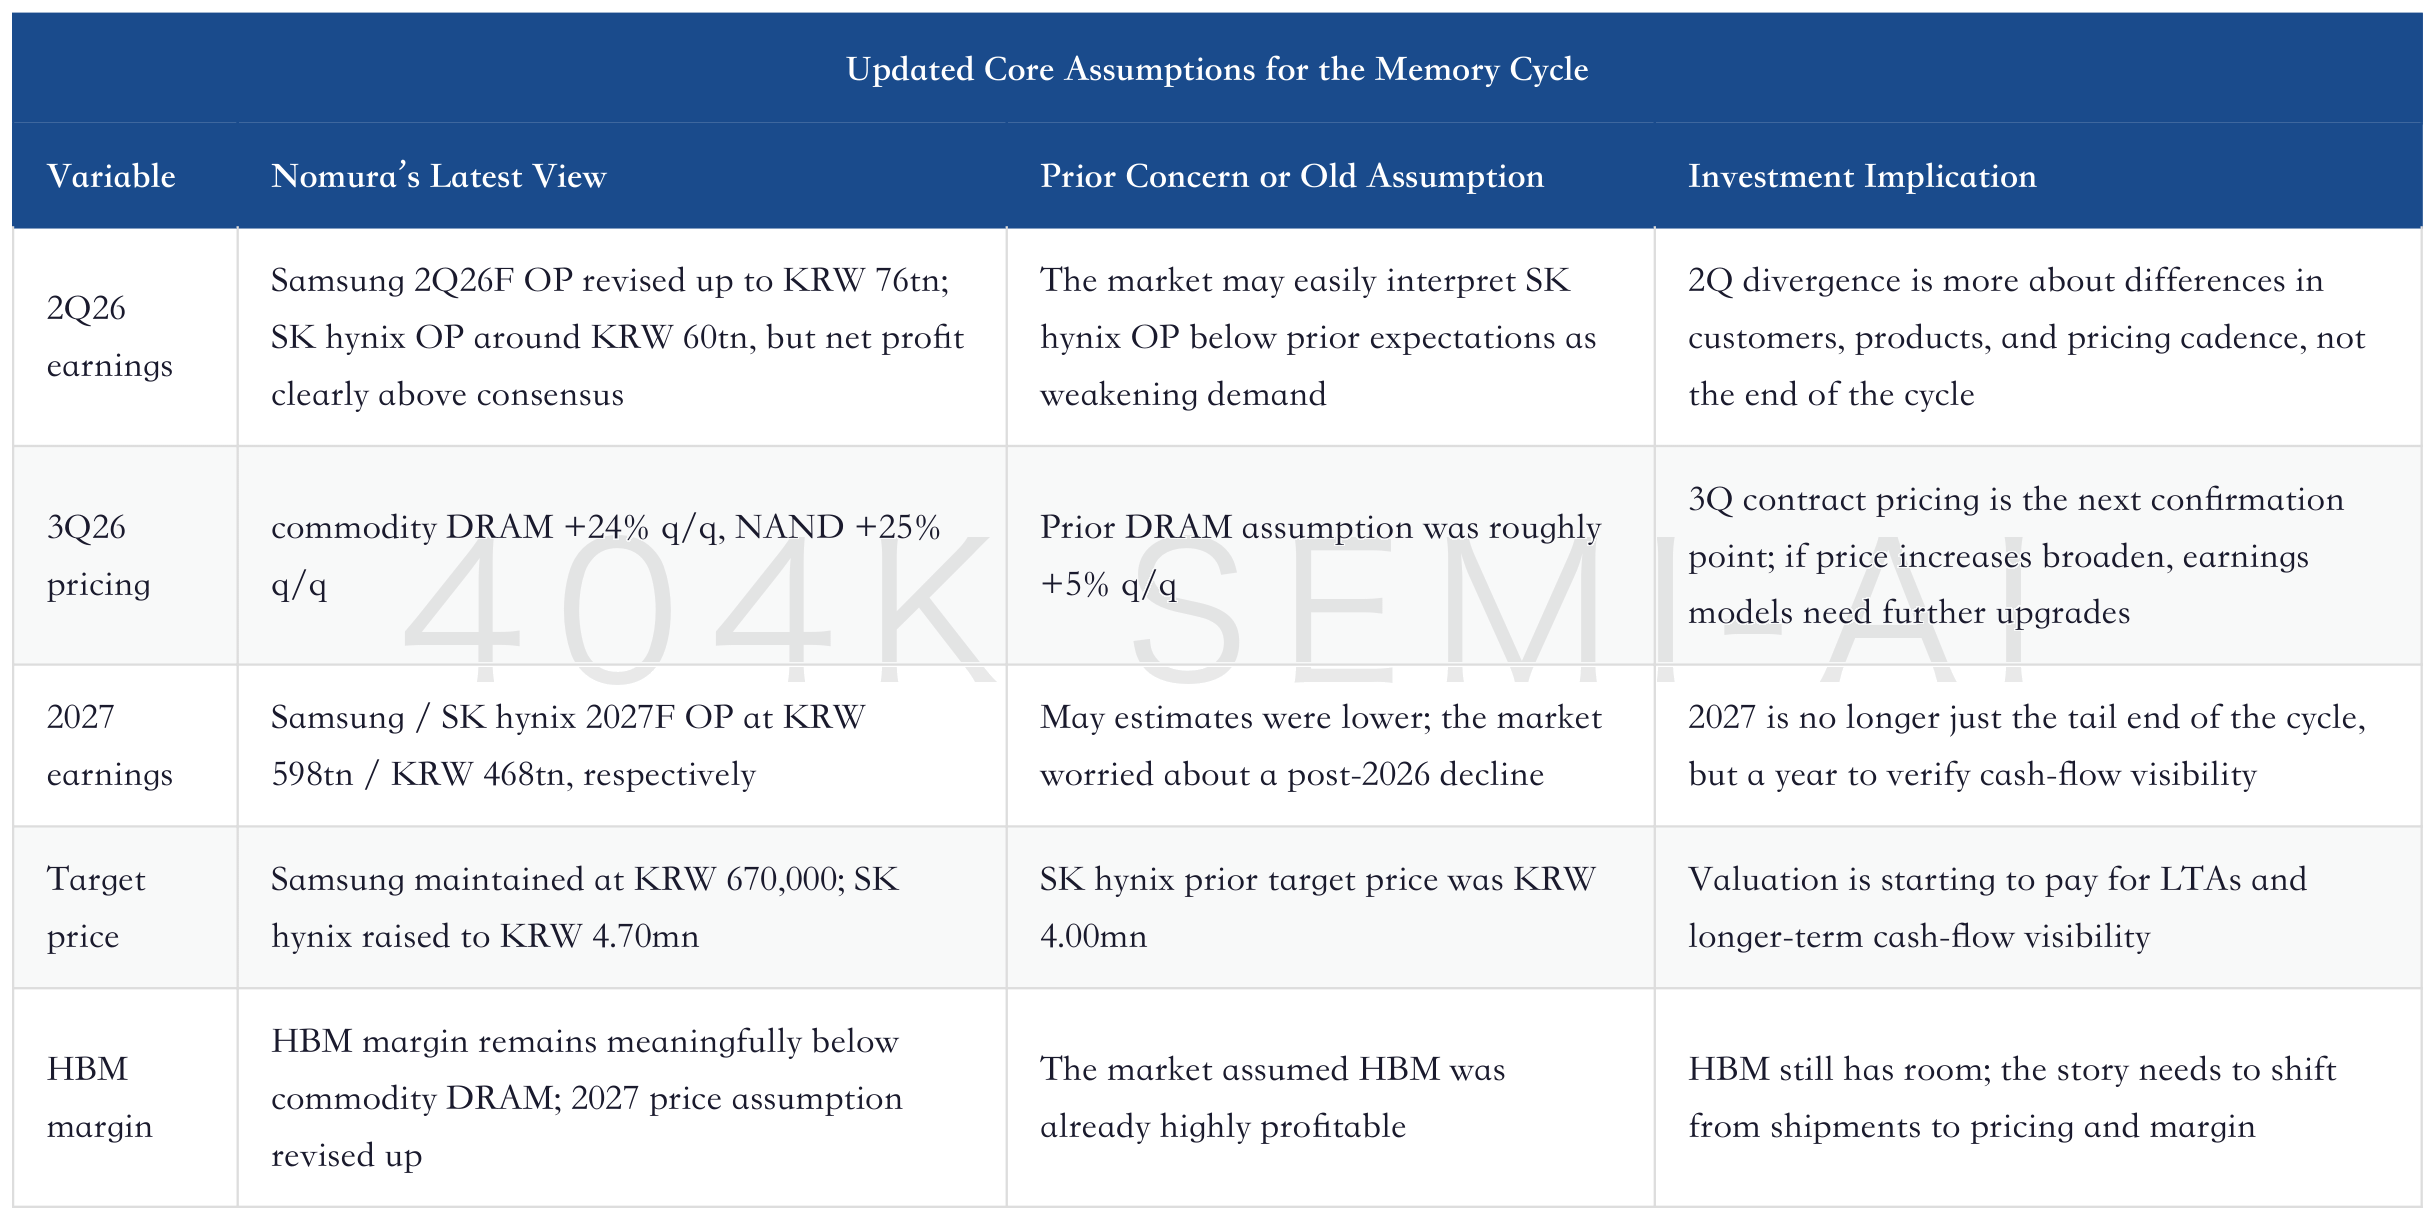
This table brings out the report’s real tension. Memory stocks have risen quickly over the past few months. The market’s question is no longer “is the industry recovering?” but “does this profit cycle deserve to be capitalized?” If 3Q contract prices are only a short-term catch-up, valuations still need to be discounted as cycle peaks. If LTAs, customer prepayments, and price bands make 2027 earnings more visible, the valuation anchors for Samsung, SK hynix, Micron, Kioxia, and SanDisk-type assets will all be lifted again.
2. Why 2Q Diverged: Pricing Is Not Rising Uniformly; It Is Re-Segmenting
2Q divergence was not caused by a sudden weakening in demand. Rather, customers, products, and contract timing have started to split memory companies’ income statements apart. In the past, DRAM and NAND cycles were often summarized with one industry ASP or spot price. That approach is increasingly crude. Cloud providers, GPU platforms, smartphone customers, PC customers, and enterprise SSD customers do not have the same price elasticity or supply priority. HBM, commodity DRAM, server DRAM, LPDDR, NAND, and eSSD are no longer moving in sync.
Samsung’s 2Q looks smoother. Nomura raised Samsung’s 2Q26F operating profit from KRW 67tn to KRW 76tn, partly from pricing and partly from bonus-related provisions being lower than previously assumed. More importantly, Samsung’s investment label is slowly shifting from “lagging HBM execution” to “a low-valuation odds asset in a major memory cycle.” If HBM4 catch-up, commodity DRAM and NAND price increases, and dividend capacity are all realized, Samsung is not merely a catch-up stock; it could recover from its valuation discount.
SK hynix’s 2Q is easier to misread. Nomura believes SK hynix’s 2Q26F operating profit may be roughly 10% below its prior estimate, due to price increases for some customers and products coming in below expectations. But Kioxia stake disposal and valuation gains could contribute around KRW 60tn in the quarter, making net profit significantly higher than consensus. What really matters for SK hynix is what happens after 3Q: M15X commodity DRAM capacity ramp, 3Q price revisions, higher HBM price assumptions, and progress in LTA negotiations all matter more than a single-quarter operating-profit miss.
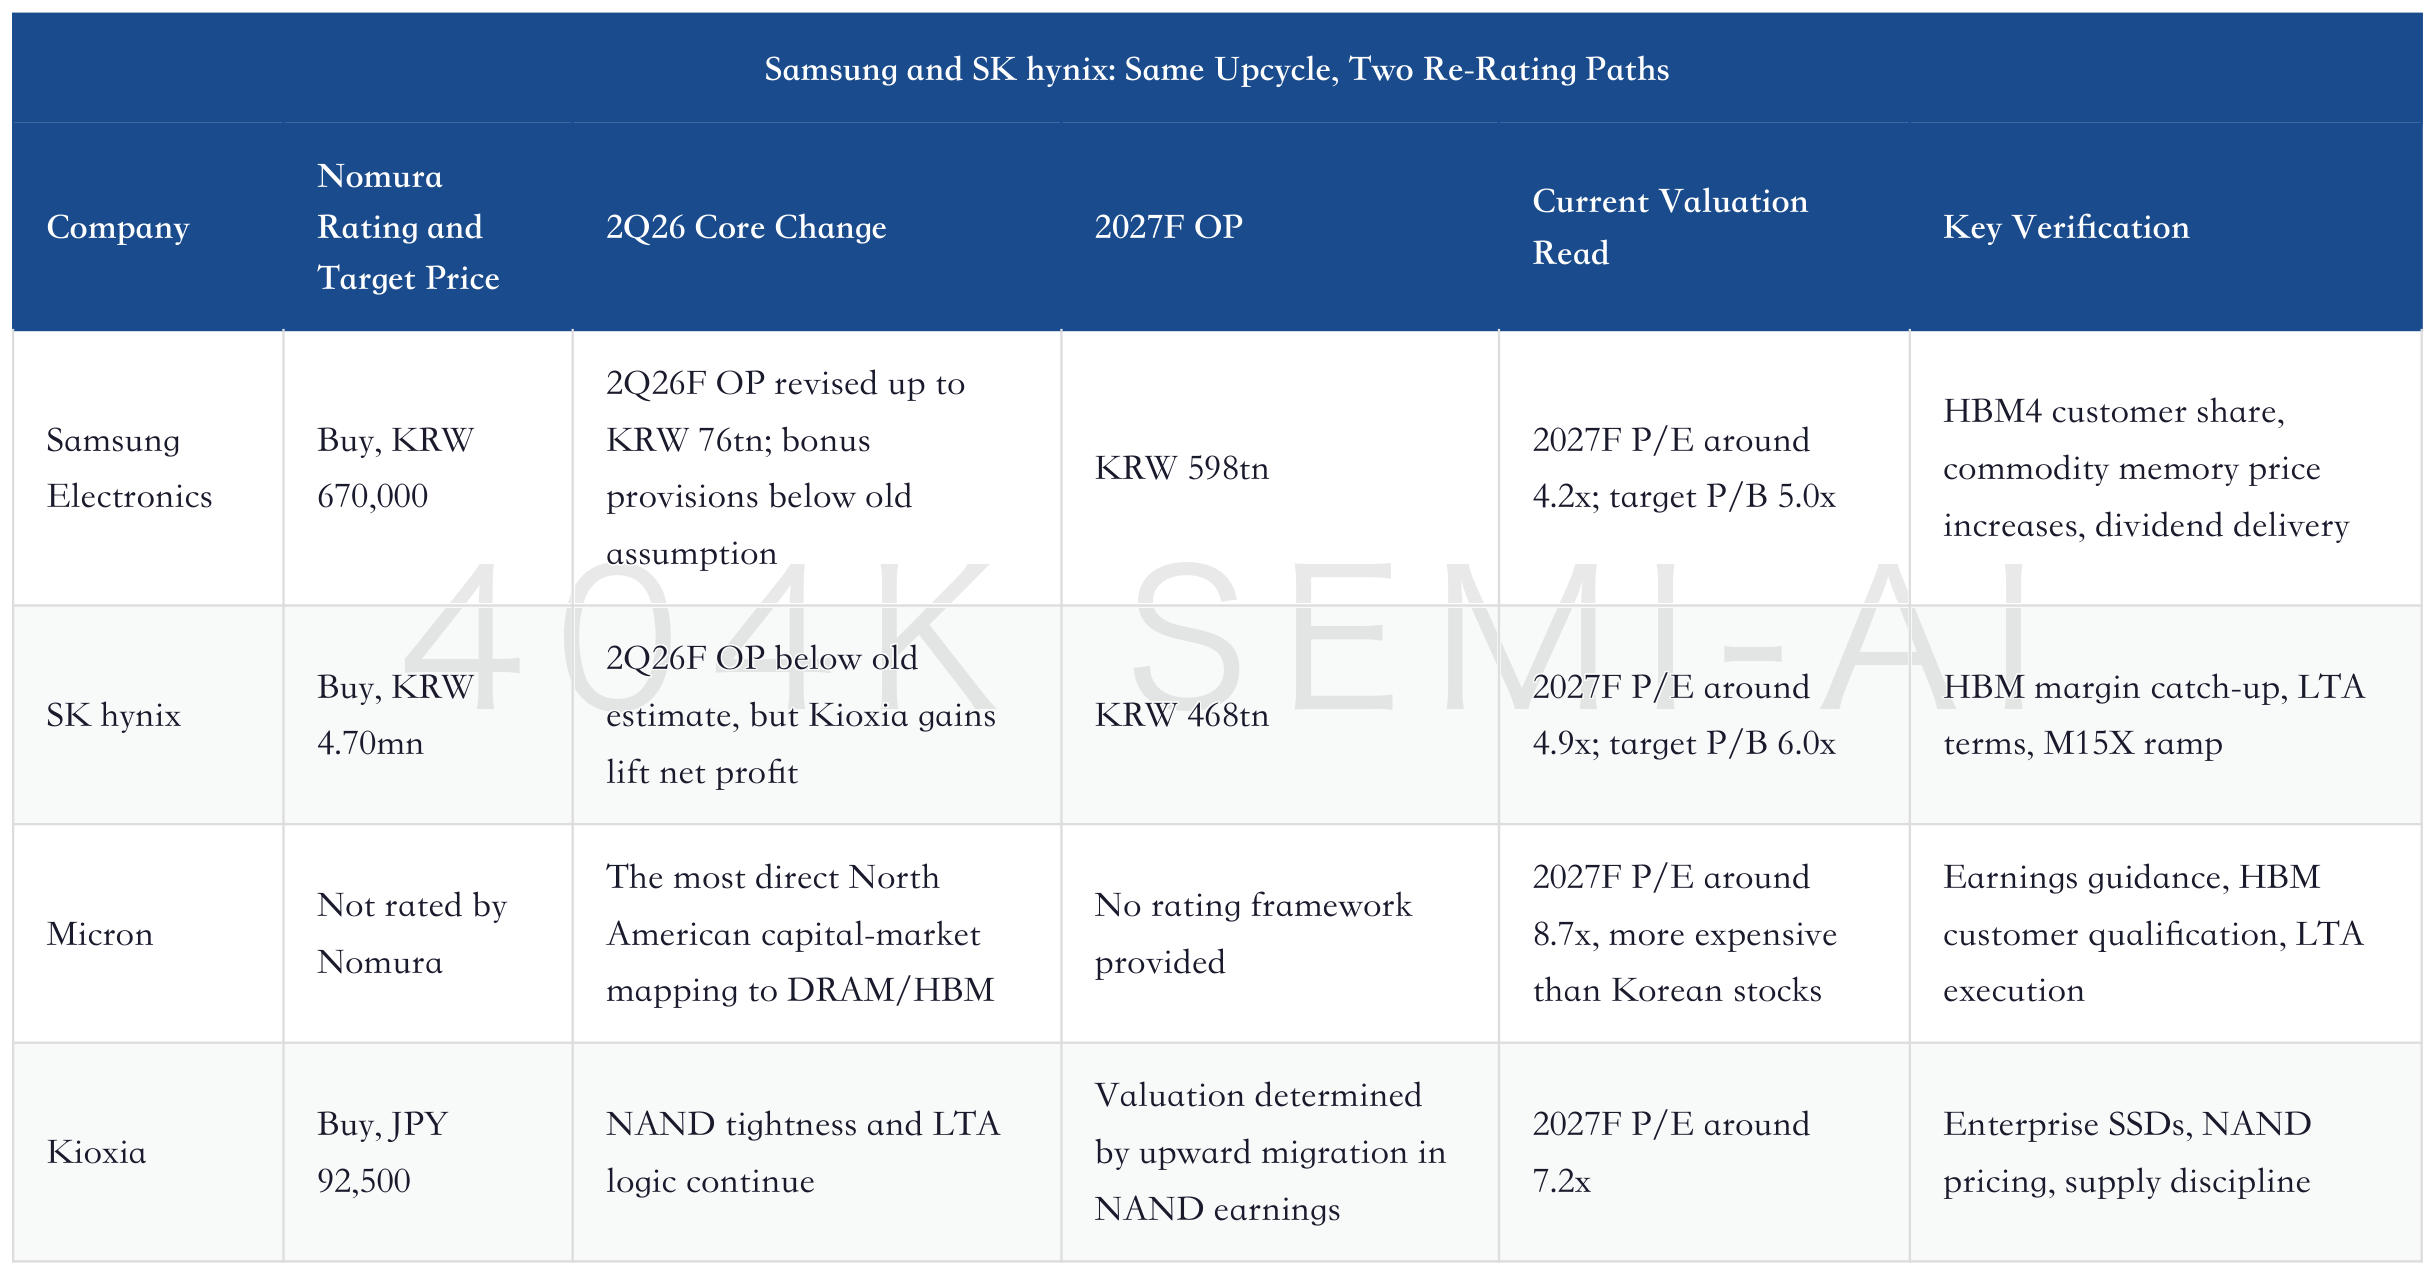
This table shows that memory assets are not the same beta. Samsung is more like an odds-repair trade: it has many legacy issues, low valuation, and a more complex business mix, but once memory upside and dividends are confirmed, the elasticity is significant. SK hynix is more like an execution asset: it leads in HBM and has purer cash flow, but the market has already assigned it a higher quality premium, so it must prove profits are not just peak-cycle earnings. Micron is the U.S. market proxy, and its earnings and guidance will amplify global investor sentiment. Kioxia, SanDisk, and WDC are more direct beneficiaries of NAND and enterprise storage pricing.
3. The Key in 3Q Is Mainstream DRAM: Beyond HBM, Commodity Memory Is Starting to Catch Up
The most easily underestimated part of this memory cycle is that HBM is so prominent it obscures the earnings elasticity in mainstream DRAM. HBM is the valuation story; mainstream DRAM is the income-statement engine. HBM shortages absorb advanced DRAM wafers, tightening commodity DRAM supply; demand from AI servers and CPUs also increases consumption of DDR5, LPDDR, and system memory. As a result, mainstream DRAM beyond HBM is no longer just a traditional PC/smartphone cyclical product, but is being repriced by the increasing memory intensity of AI systems.
Nomura’s move to raise its 3Q commodity DRAM QoQ price-increase assumption to +24% matters for this reason. It effectively acknowledges that mainstream DRAM price elasticity was underestimated in 2Q. As long as customers continue locking in supply for AI servers, cloud expansion, CPU-side memory, and inventory security, mainstream DRAM price increases may last longer than the market expects.
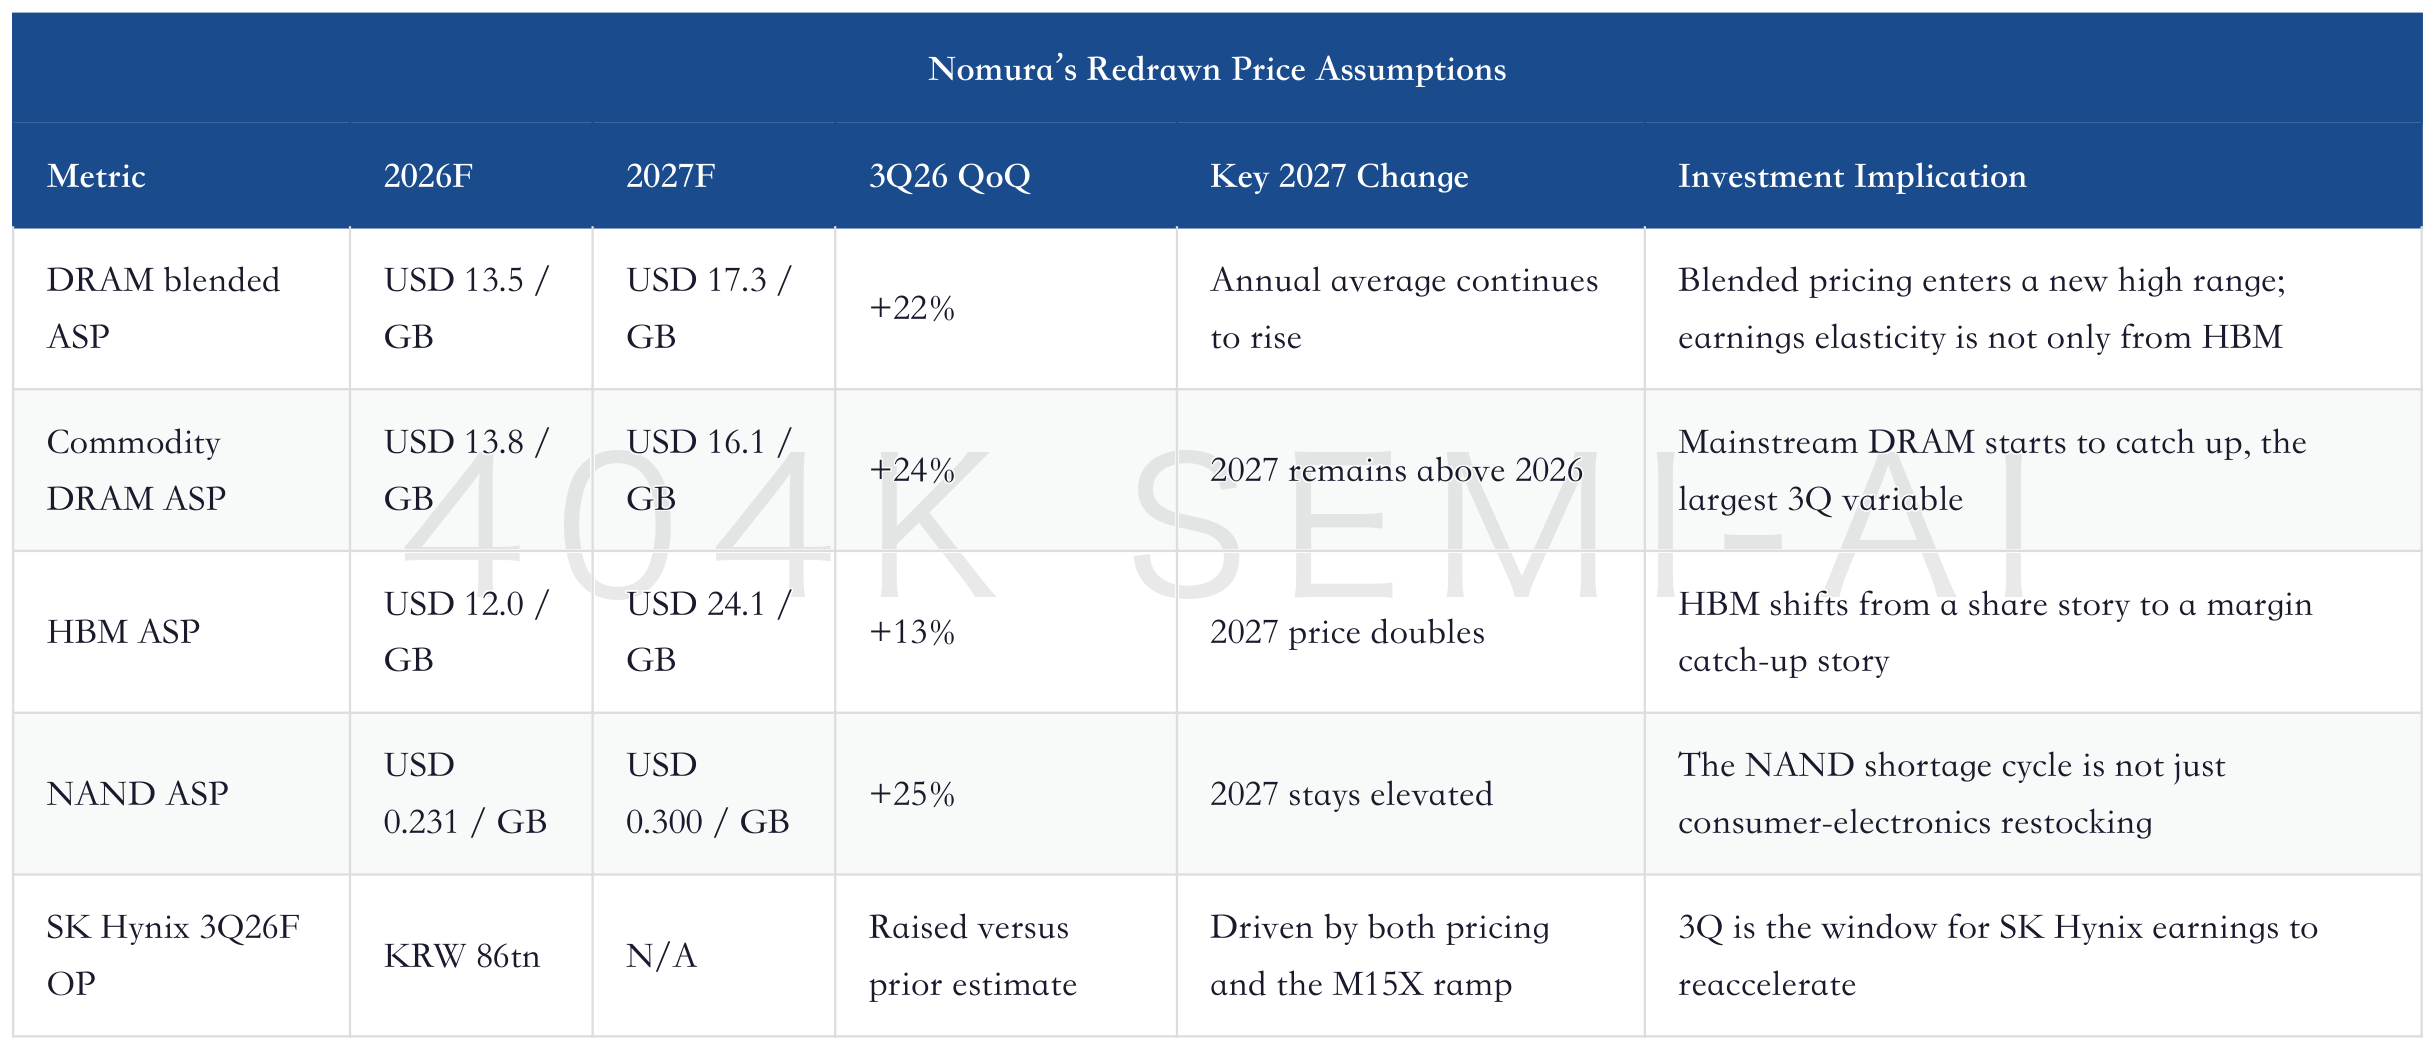
The catch-up in mainstream DRAM will change how investors understand earnings in 2H26. In the past, the market was willing to assign HBM a high valuation, but often treated mainstream DRAM as cyclical profit and was reluctant to assign it a multiple. The question now becomes: if mainstream DRAM price increases are driven by HBM capacity absorption, rising AI-server memory intensity, and long-term agreements rather than a simple inventory cycle, should this portion of profit still be fully discounted as peak earnings?
The Second Engine of the Memory Supercycle: CPU Comeback, HBM Spillover, and a USD 1.7tn TAM Re-Rating
4. HBM’s New Question: Not Whether It Is Scarce, but Whether Margins Can Catch Up
Consensus on HBM is already strong. The new debate is more nuanced: HBM is of course still the highest-value category in the AI memory chain, but its profitability is not as perfect as the market imagines. Nomura explicitly states this time that HBM profitability remains significantly below commodity DRAM. In other words, HBM is the tightest, most strategic, and most sought-after product by customers, yet it may not have achieved margins that match its scarcity.
This point is important. The market previously treated HBM as a product whose price was “already very high,” worrying that what follows would only be share competition and supply release. But if HBM’s current operating margin remains below mainstream DRAM, then the core issue for 2027 is not whether HBM shipments can grow, but whether HBM ASP and margins can catch up with mainstream DRAM. Nomura has therefore raised its HBM price assumptions, with particular emphasis on price improvement in 2H26 and 2027.
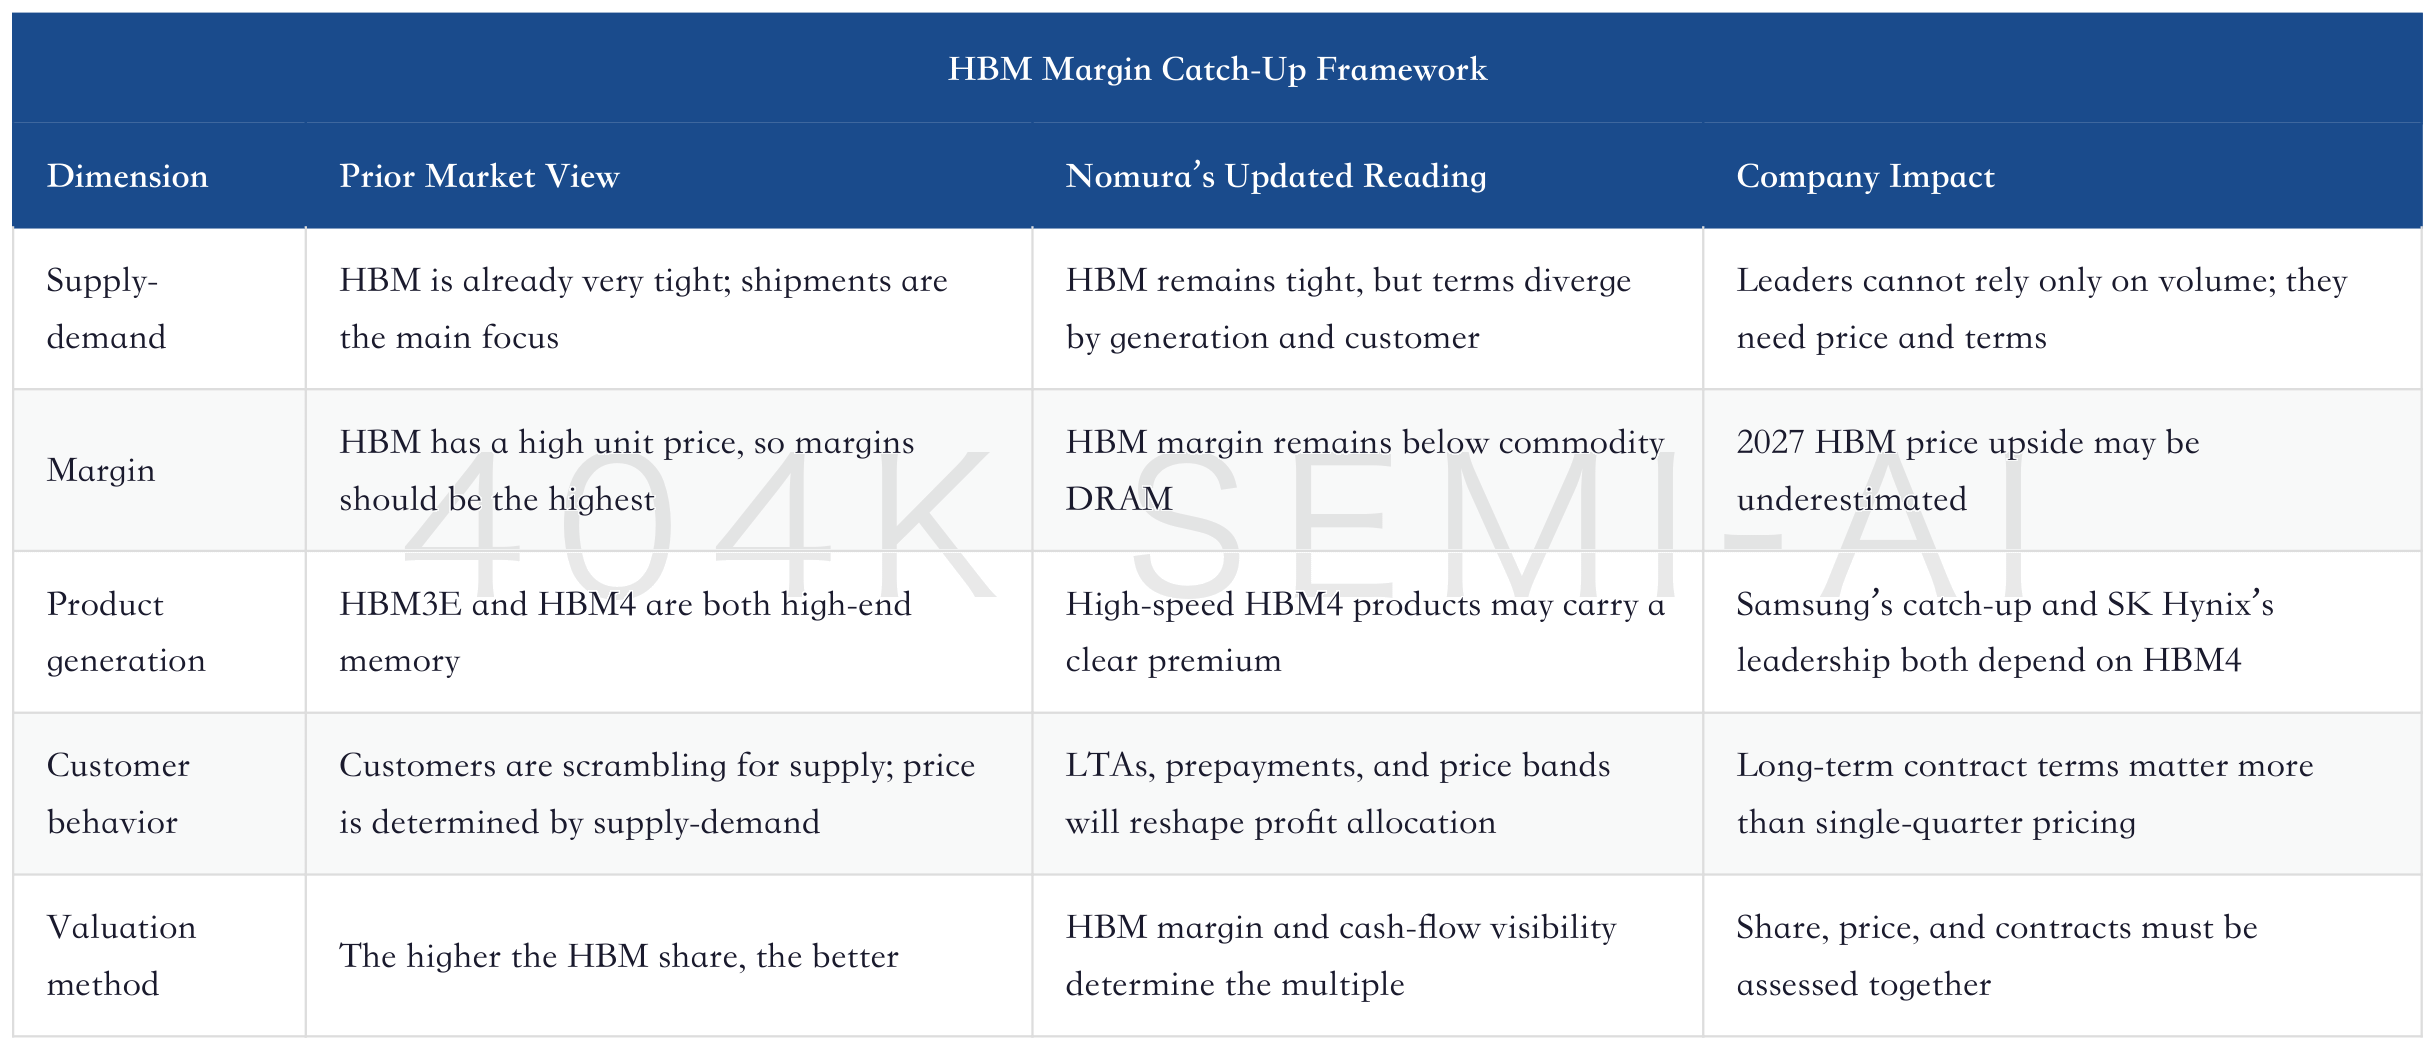
This is also the essence of the divergence between SK Hynix and Samsung. SK Hynix has already proven itself as the HBM leader; the question is whether its lead can be further entrenched through HBM4, pricing terms, and customer supply locks. Samsung’s issue is the opposite: it does not lack resources or capacity, but it must prove that HBM4 catch-up can translate into real share and margins. The market assigns Samsung a lower multiple because it is penalizing past execution uncertainty; once HBM4 progress exceeds expectations, the low multiple becomes a source of elasticity.
Another impact of HBM is that it squeezes mainstream DRAM supply. As more advanced DRAM wafers are allocated to HBM, incremental commodity DRAM supply is less abundant than headline capacity suggests. This mechanism means HBM and mainstream DRAM are no longer two isolated markets: the stronger HBM becomes, the tighter mainstream DRAM supply gets; rising mainstream DRAM prices then lift memory companies’ overall margins in turn. The resilience of the memory supercycle comes precisely from the mutual squeeze between these two markets.
The Memory Tax Has Arrived: How AI Is Turning HBM, DRAM, and NAND into a Global Macro Bottleneck
5. The Value of LTAs: Whether Peak-Cycle Profits Can Be Capitalized Depends on Contracts
Long-term agreements are the dividing line between this memory rally as a “cyclical rebound” and as an “asset re-rating.” Customers’ willingness to sign LTAs shows they no longer care only about next month’s price, but are worried about failing to secure supply over the next two to three years. Suppliers are willing to sign LTAs not simply to sell more volume, but to use price bands, prepayments, capacity priority, and customer roadmap binding to turn part of high profit into visible cash flow.
Nomura’s framing is clear: LTAs are expected to be signed mainly with CSPs and customers such as Nvidia, with each memory supplier negotiating with around two to four customers, and terms varying by supplier and customer. The key point is not that “there are long-term agreements,” but that “long-term agreement terms will diverge.” Both may be called LTAs, but if they only lock volume without locking price, their valuation benefit is limited; if they include prepayments, minimum prices, price-adjustment mechanisms, and capacity priority, they can reduce the cyclical discount.
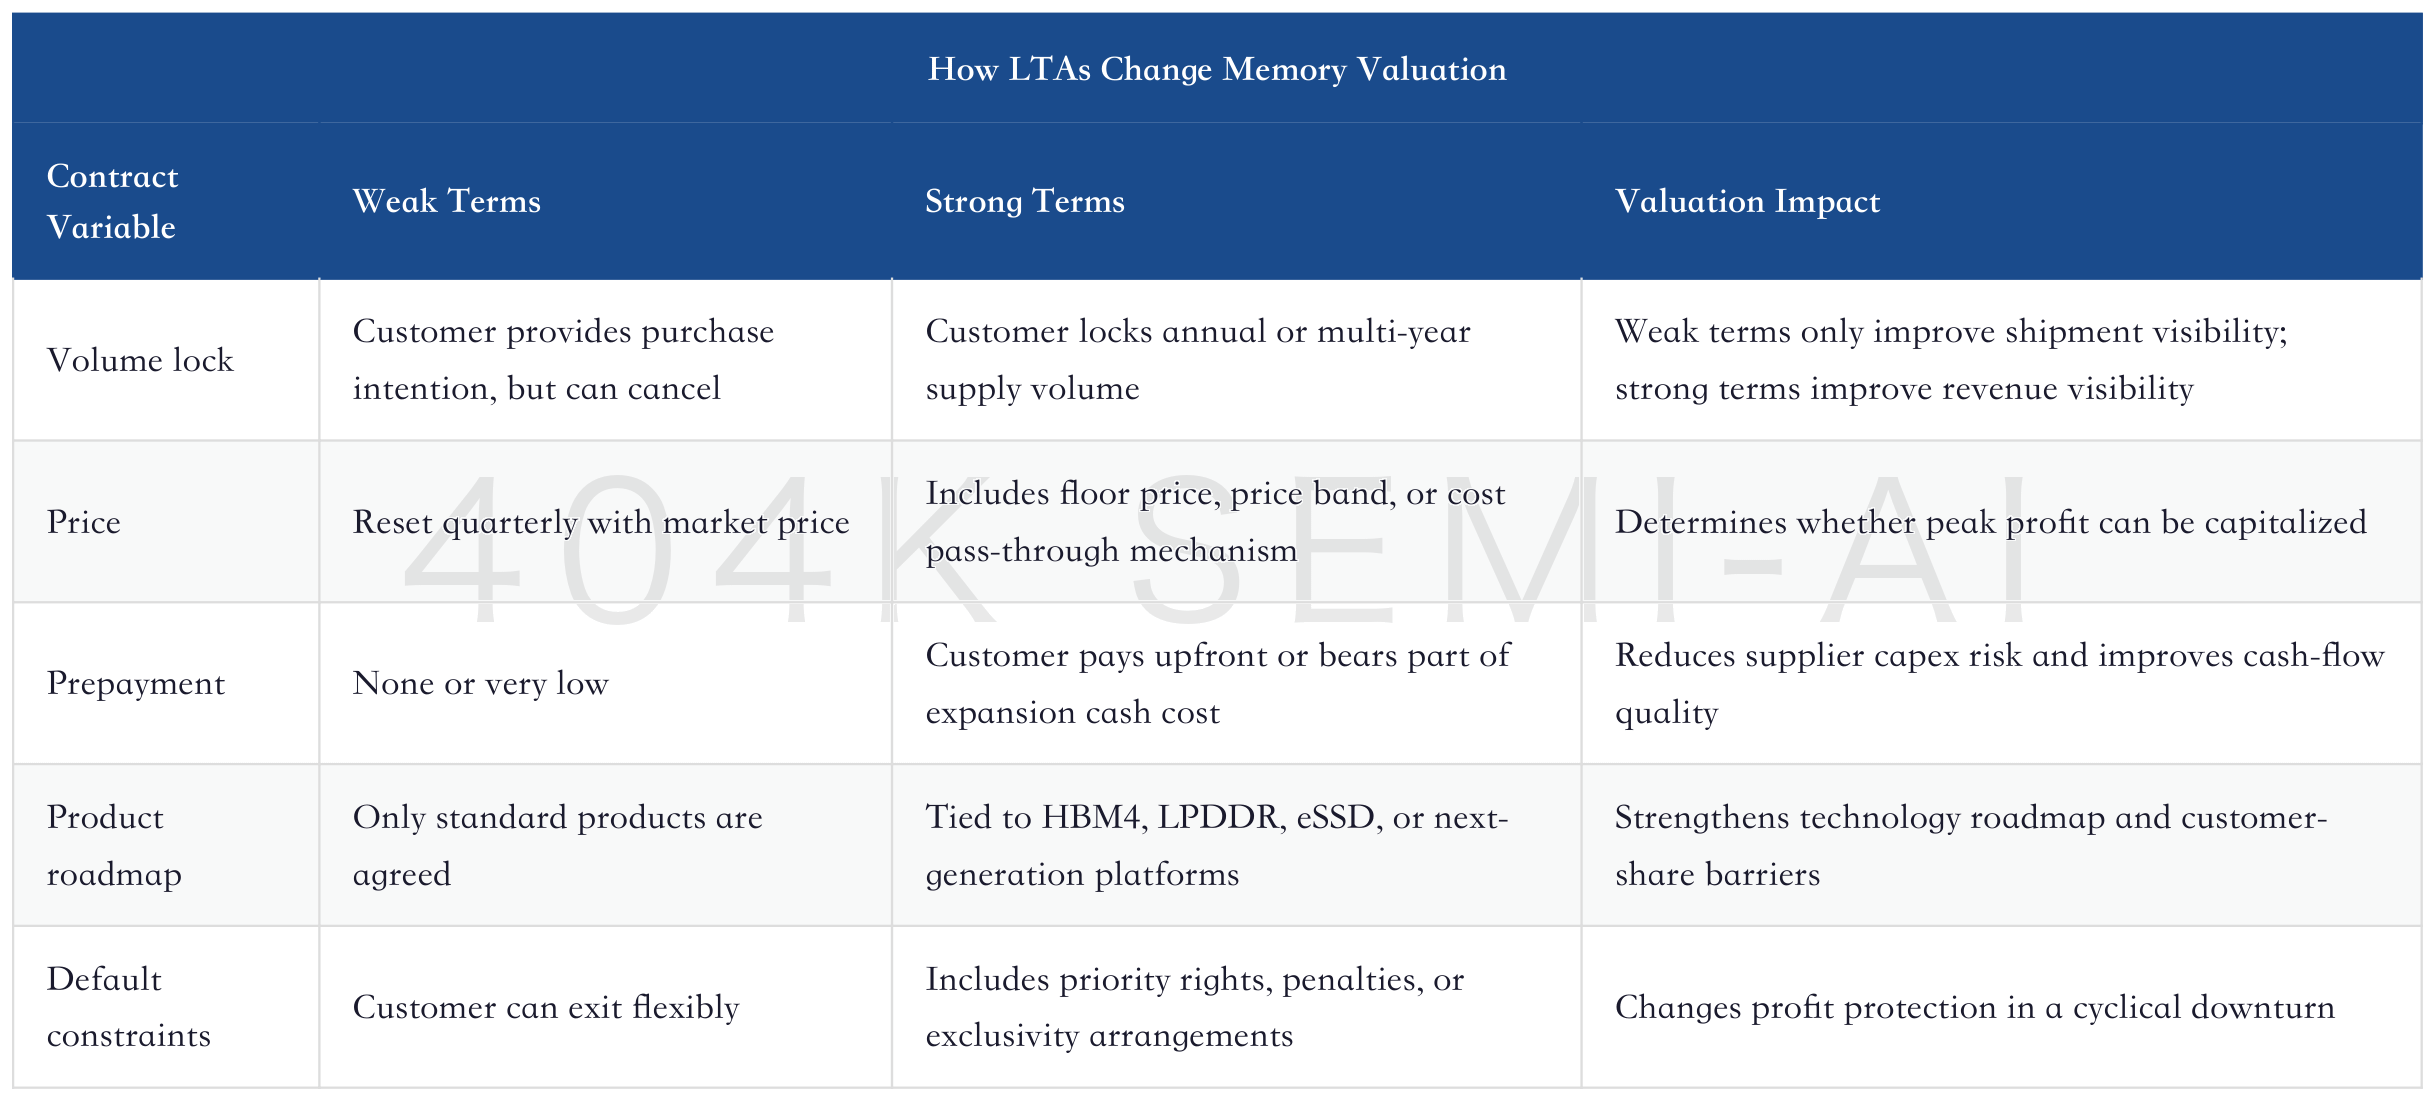
This is why research frameworks for Micron, SK Hynix, Samsung, Kioxia, and SanDisk are starting to look increasingly like “contract asset” analysis. In the past, memory companies struggled to receive high multiples because pricing and inventories were too volatile. Now, if customers lock supply long term for AI infrastructure, memory companies have an opportunity to migrate part of their profit from “pricing cycle” to “contract profit.” The market is not buying the idea that memory has no cycle; it is buying the idea that contractual arrangements weaken cyclical volatility.
To judge whether an LTA truly has value, one cannot just look at headlines. The five details that really matter are: who the customer is, how much volume is locked, how price is determined, whether there is prepayment, and whether next-generation products are tied in. If the customer is merely signing a flexible procurement framework to prevent shortages, valuation should not be too high; if the customer exchanges real cash and multi-year pricing mechanisms for future supply, then the memory company is no longer just a cyclical stock.
6. Samsung and SK Hynix: One Is Buying Asymmetry, the Other Execution
Both Samsung and SK Hynix benefit from the major memory upcycle, but the entry points are entirely different. Samsung is an odds-repair trade; SK Hynix is an execution-delivery trade. Lumping the two companies together misses the point of this report.
Samsung’s core strengths are scale, product breadth, balance sheet, and low valuation. Nomura maintains its KRW 670,000 target price for Samsung Electronics, corresponding to a target P/B of 5.0x, and expects ROE to approach 60% in 2026-2027. If that ROE materializes, Samsung’s 2027F P/E of around 4.2x is not expensive. The issue is that Samsung’s non-memory businesses will drag on the income statement: smartphones and logic are instead under pressure in a high-memory-cost environment; HBM execution still needs to be proven.
Another implicit thread for Samsung is shareholder returns. Nomura assumes total dividends in 2027 could approach KRW 97tn, roughly 9x the 2025 level. For a company long treated as a low-return Korean large cap, this change would affect the investor base willing to own the stock. If memory profits, dividends, and HBM catch-up all materialize at the same time, Samsung’s upside would come not only from EPS, but also from the market’s willingness to assign a higher discount rate to capital returns.
SK Hynix’s logic is cleaner. Nomura raises its target price for SK Hynix from KRW 4.0mn to KRW 4.7mn, corresponding to a target P/B of 6.0x, citing increased confidence in the long-term cash-flow mechanism. SK Hynix’s 2026F/2027F operating profit is KRW 288tn / 468tn, respectively, while 2027F ROE remains as high as 74%. That margin profile looks like a cycle peak, but if HBM, commodity DRAM, NAND, and LTAs all support it at the same time, it is not simply peak earnings.
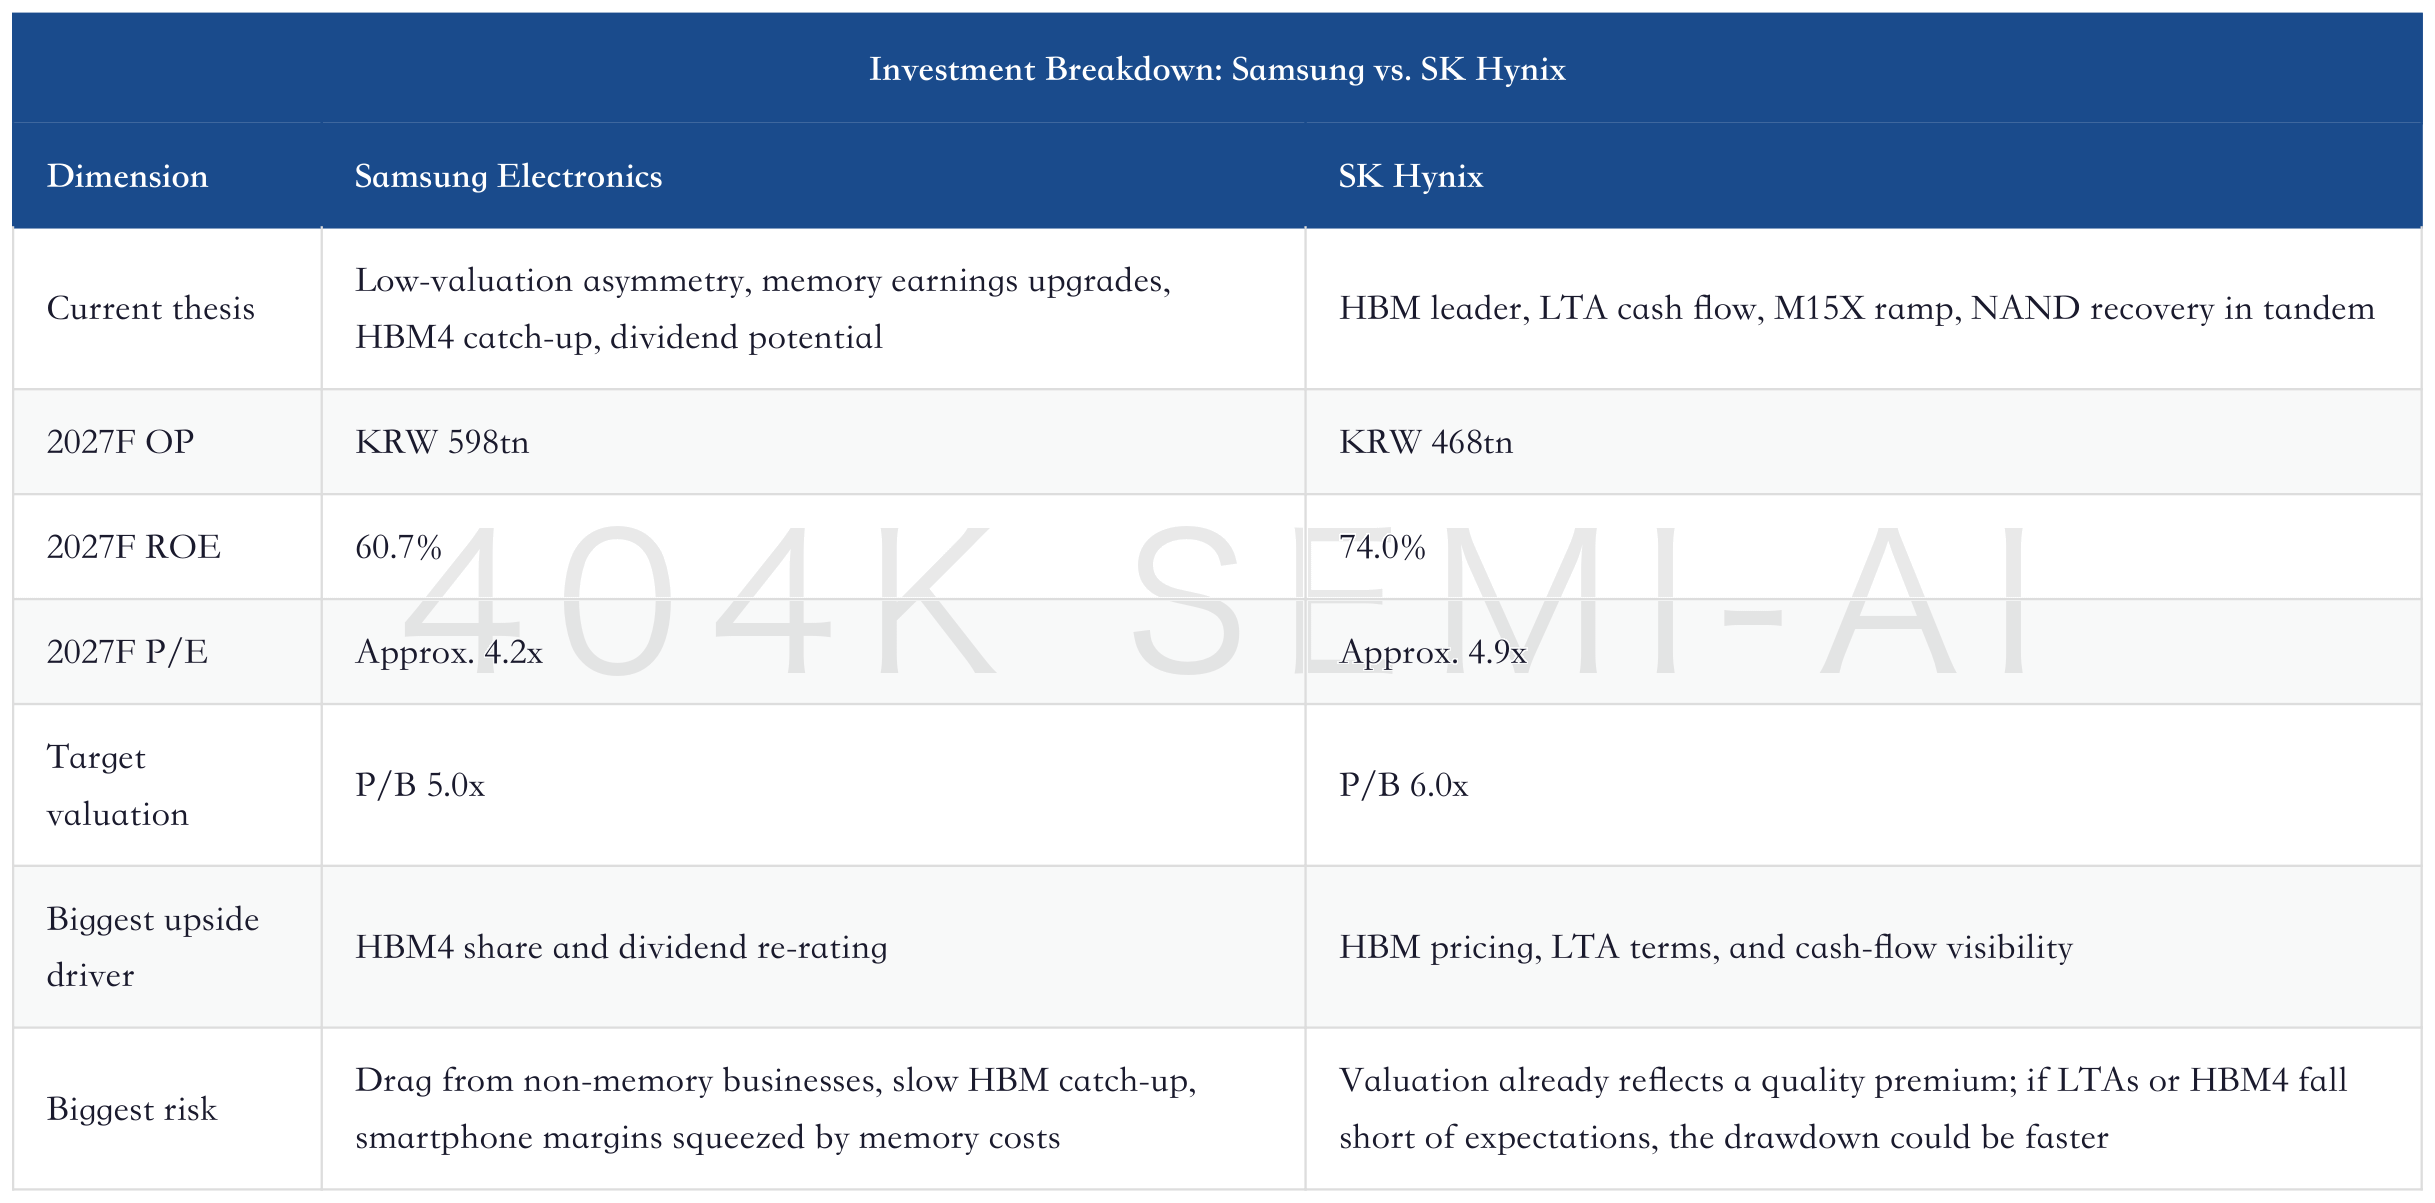
The portfolio implication from this table is straightforward. For investors who want to buy “the memory cycle continues but valuation has not fully reflected it,” Samsung offers better asymmetry. For investors who want to buy “the strongest company in the AI memory chain continues locking profits into contracts,” SK Hynix is cleaner. Neither is without risk: Samsung has to prove that catch-up is not just a slogan, and SK Hynix has to prove that leadership is not merely a cycle peak.
7. Data-Center Ledger: Memory Has Moved from Supporting Cost to Hard Constraint on Compute Budgets
Whether this memory re-rating can continue ultimately comes back to data-center capex. Nomura’s data-center ledger is aggressive, but it explains why the market is willing to accept a step-up in memory companies’ earnings models: global data-center capex rises from USD 668bn in 2024 to USD 2.295tn in 2026F and USD 6.127tn in 2030F; data-center memory demand rises from USD 60bn in 2024 to USD 454bn in 2026F and USD 1.398tn in 2030F.
The more important point is mix. Memory demand as a share of global data-center capex rises from 9% in 2024-2025 to 20% in 2026F, and stays broadly at 22%-23% in 2027F-2030F. This means memory is no longer an ordinary supporting cost in the server BOM, but an increasingly hard constraint within AI infrastructure budgets.
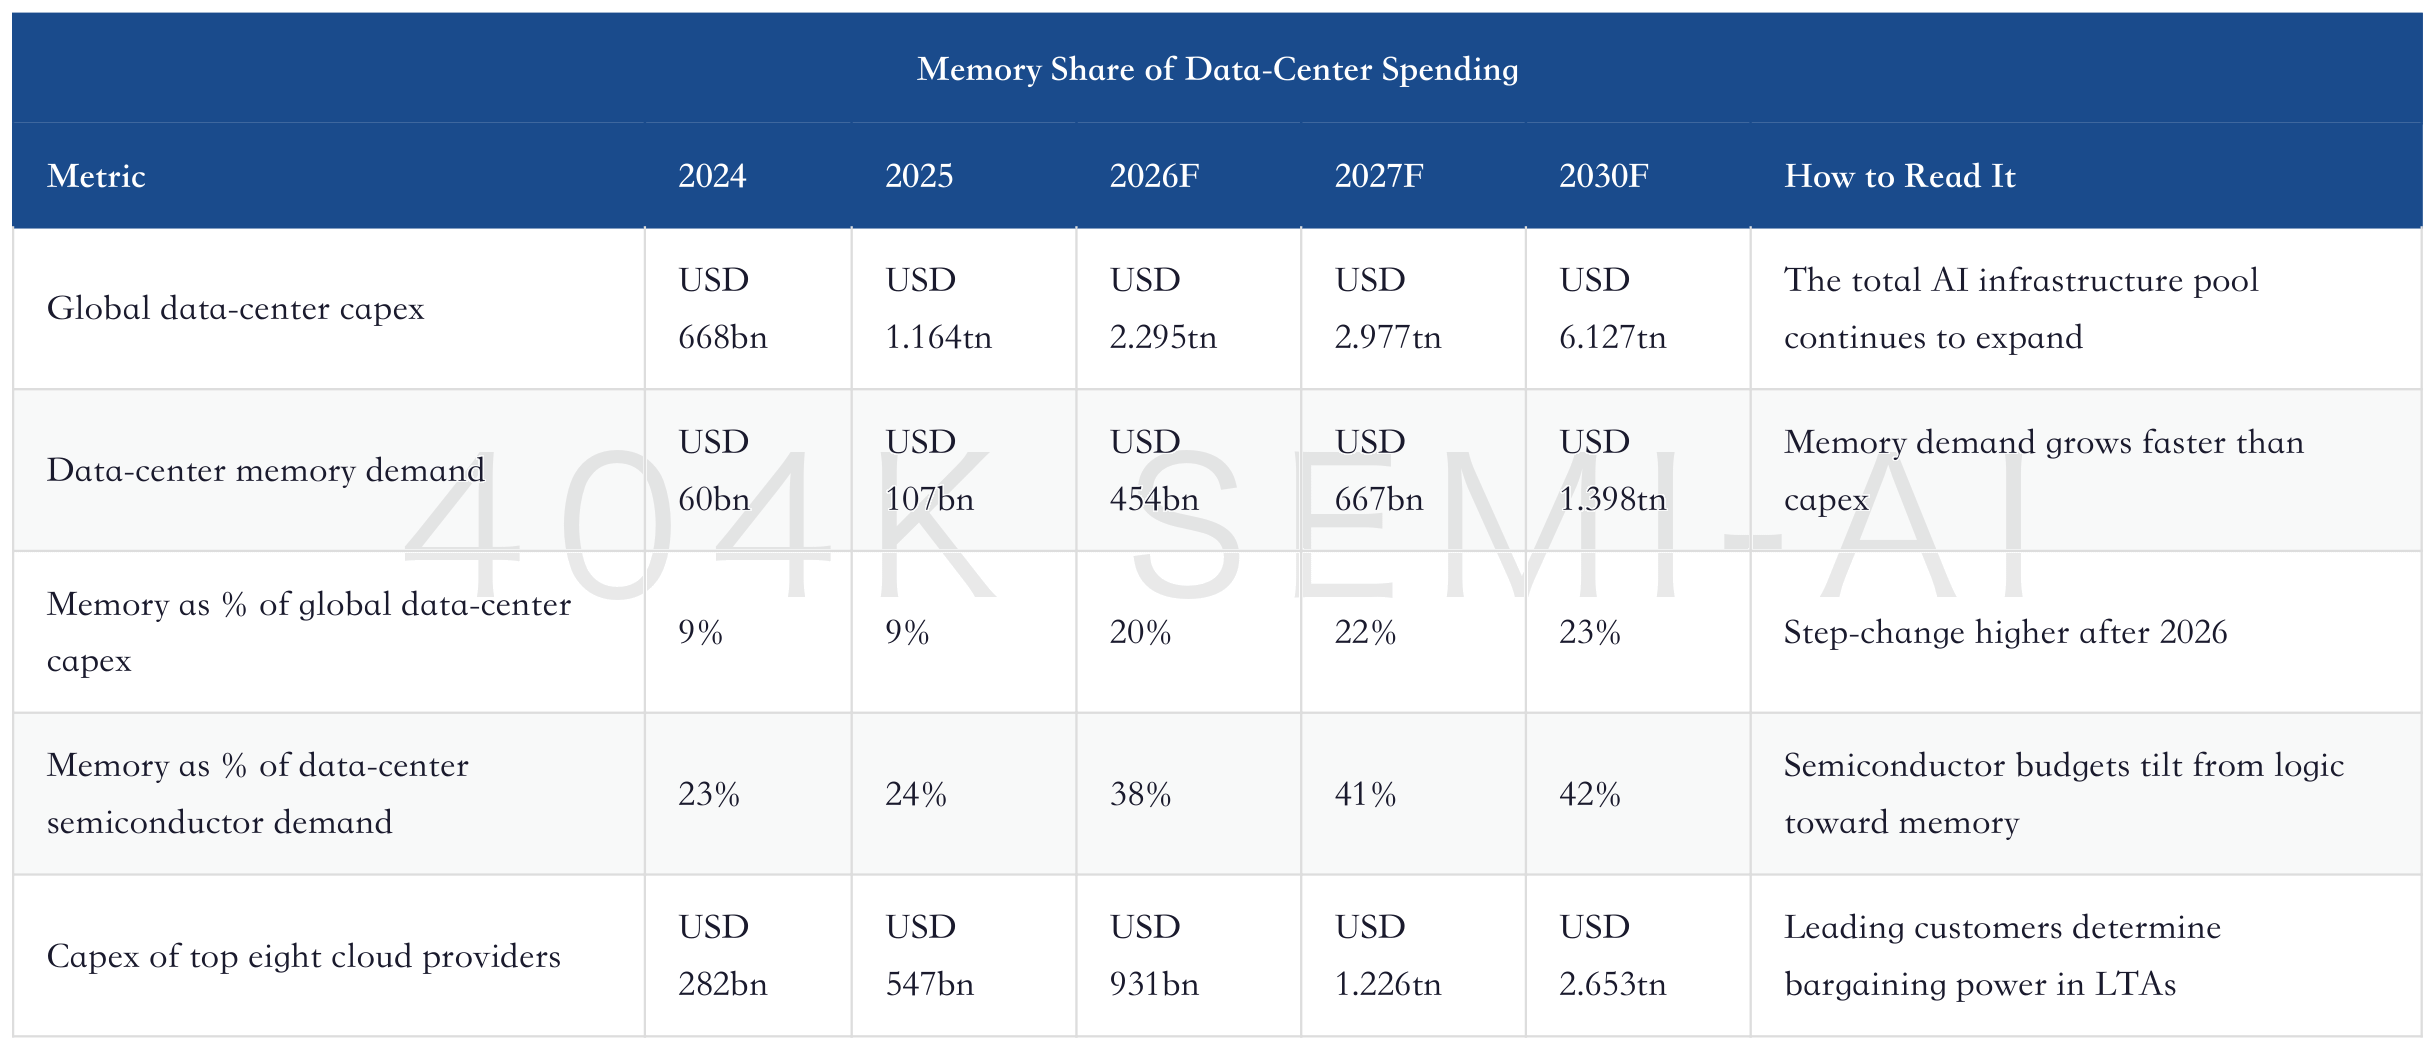
This table is the underlying evidence for the valuation uplift in memory stocks. As long as AI infrastructure continues expanding, customers are not “replenishing inventory while prices are rising”; they are buying insurance for future training, inference, caching, enterprise data, and multimodal applications. Memory companies’ pricing power comes from customers’ fear of supply disruption, not from suppliers unilaterally wanting to raise prices.
But the data-center ledger also highlights risk. The larger the global capex assumption, the greater the dependence on power, construction, equipment delivery, financing, and customer cash flow. If U.S. data centers are delayed by power access, labor, community approvals, or grid-connection delays, memory demand will also shift later. Investors cannot look only at the upward demand curve; they also need to watch project execution speed.
8. Supply Is Expanding, but Far Less Evenly
What the memory industry fears most is not demand revisions, but a breakdown in supply discipline. In every major DRAM/NAND cycle, the old question eventually has to be answered: will high profits trigger excessive capacity expansion and push prices back down?
Nomura’s supply table shows that the industry is indeed expanding capacity, but very unevenly. Total average annual DRAM wafer capacity rises from 1.878mn wafers/month in 2025 to 2.720mn wafers/month in 2028F; HBM average annual capacity rises from 318,000 wafers to 785,000 wafers; commodity DRAM average annual capacity rises from 1.561mn wafers to 1.935mn wafers. On the surface, capacity expansion is meaningful, but HBM is consuming advanced capacity faster, while the incremental addition to commodity DRAM before 2027 is not excessive.
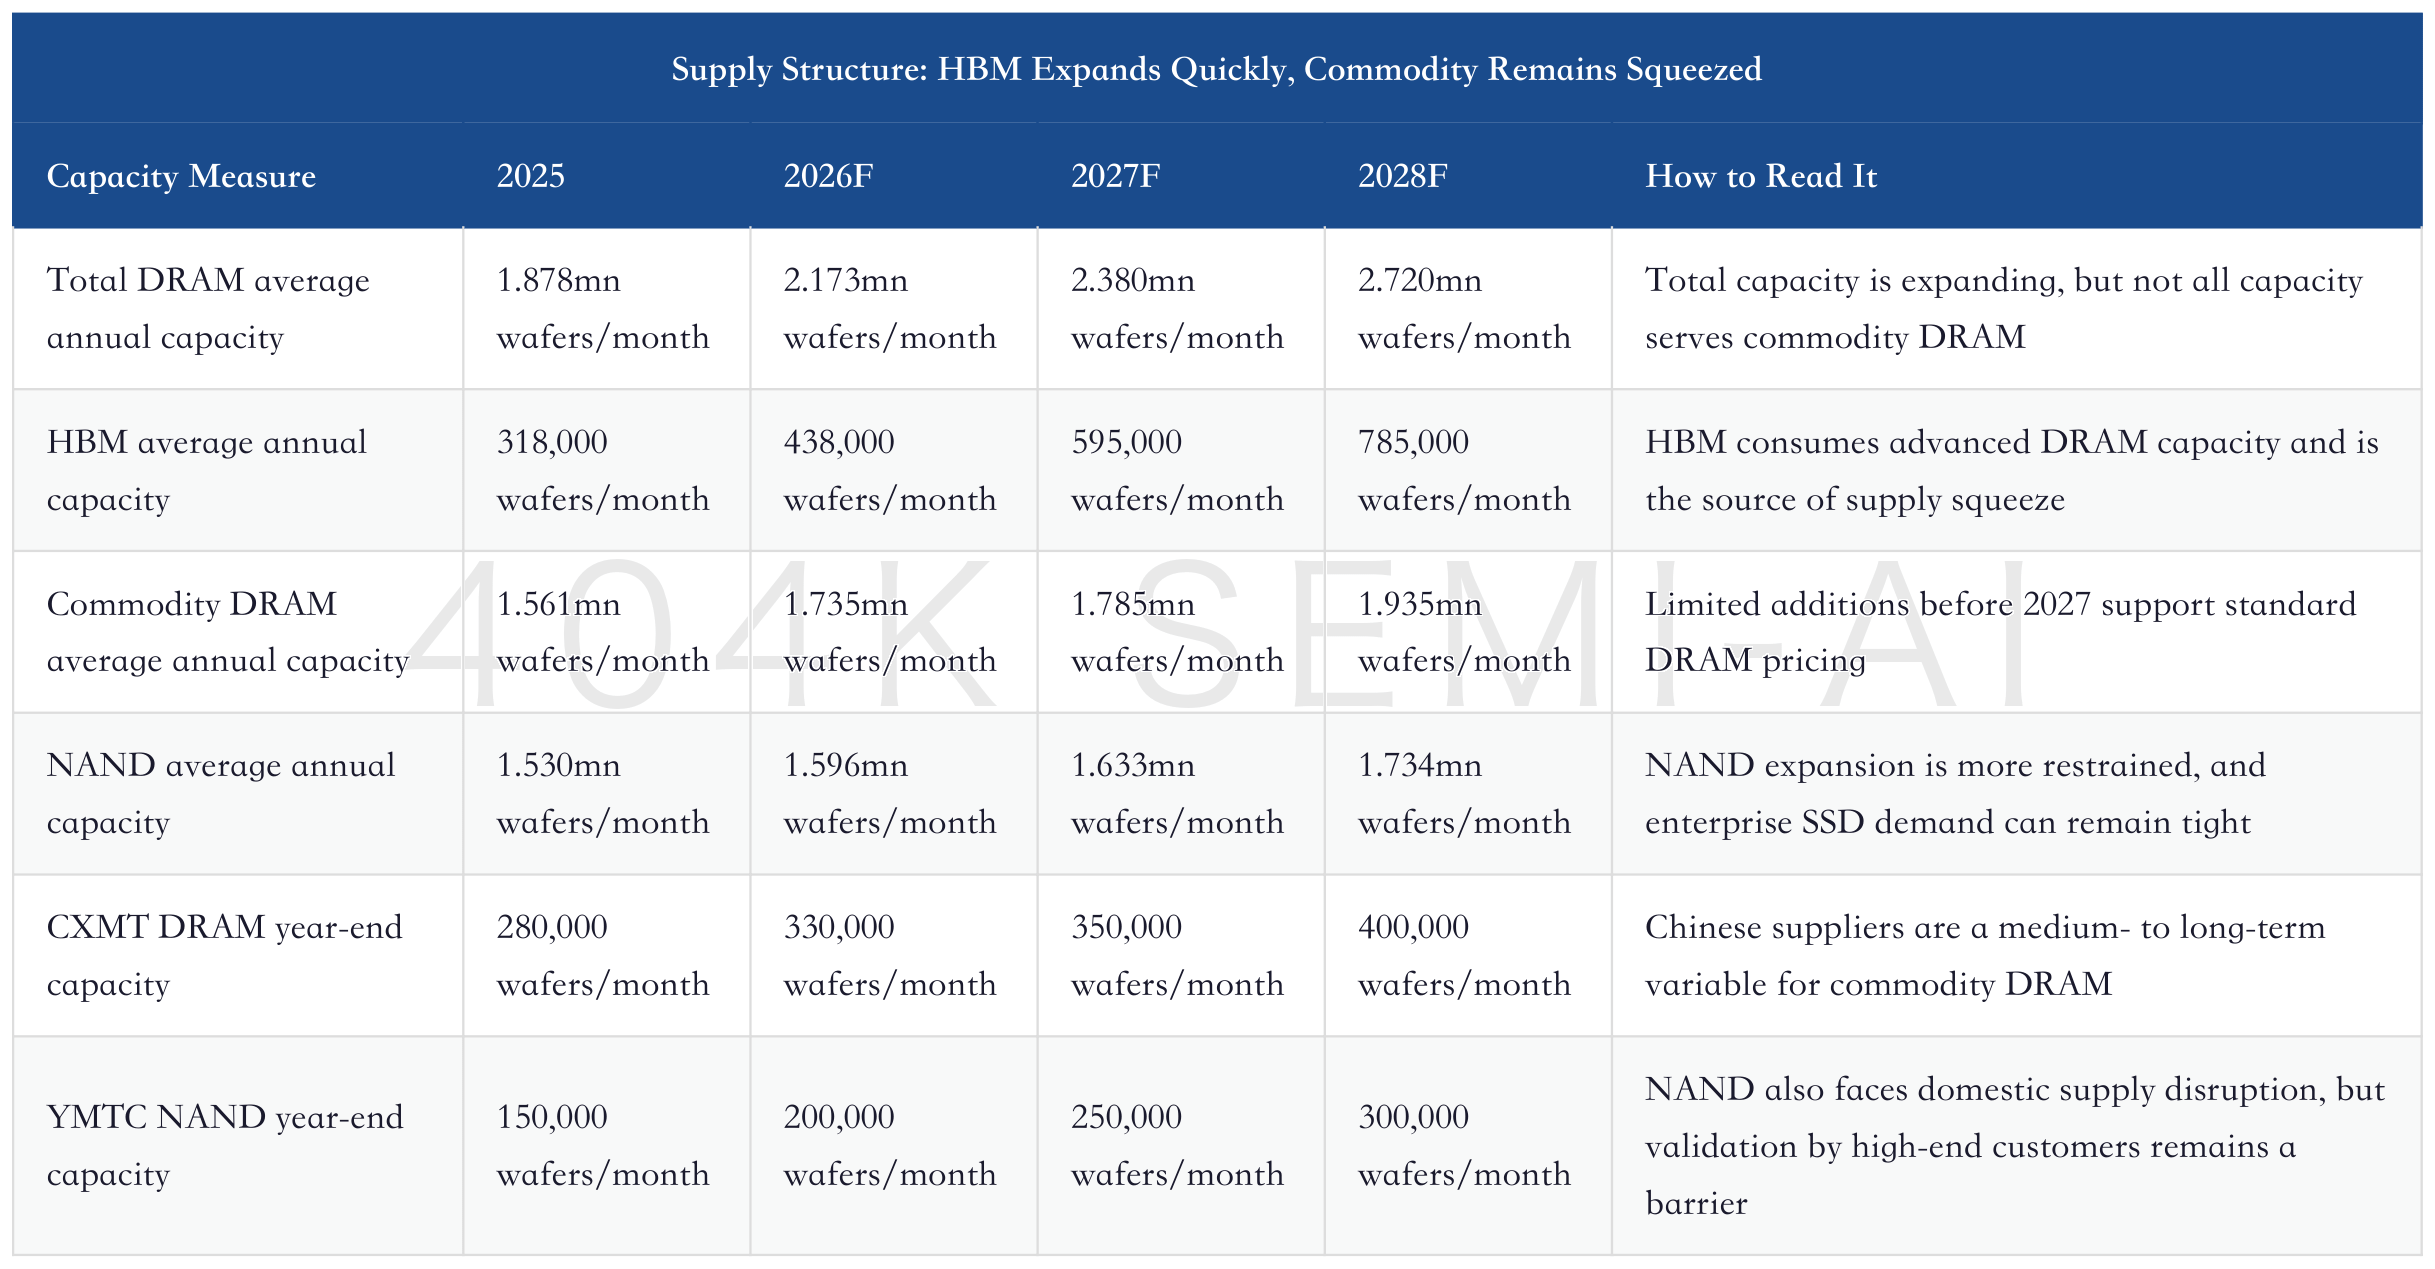
The conclusion from this dataset is not that “there is no supply risk,” but that “supply risk has layers.” HBM capacity is expanding the fastest, but it also consumes advanced DRAM resources; commodity DRAM may remain tight before 2027; NAND supply expansion is slower than demand recovery, leaving profit room for enterprise SSDs and high-end NAND. Capacity expansion by Chinese suppliers will affect commodity markets, especially the China market and price-sensitive products, but entering leading global cloud providers and high-end AI server configurations still requires product quality, reliability, validation, and supply-chain trust.
This supply framework also explains why 2027 is the real test. The 2026 shortage is easier for the market to believe; in 2027, the question is whether new capacity, HBM4 migration, LTA supply locks, and cloud demand can continue to match. If supply discipline holds, memory profits can remain high; if suppliers concentrate capacity expansion because of high profits, the cycle discount will quickly return.
9. NAND’s Second Curve: After Rubin, Flash Re-enters the AI Architecture Budget
NAND is not a supporting character in this report. Nomura breaks down the OpenAI architecture-related memory TAM across Blackwell, Blackwell Ultra, Rubin, and Rubin Ultra. The most interesting change is that NAND had almost no budget in the Blackwell era, but begins to enter large-scale memory demand with Rubin and Rubin Ultra. Under the report’s methodology, Rubin corresponds to a NAND TAM of USD 49.371 billion, and Rubin Ultra to USD 65.829 billion; the Memory / Logic ratio rises from 200% for Blackwell to 677% for Rubin and 1190% for Rubin Ultra.
The direction of these numbers matters more than the absolute values. The further AI architecture evolves, the higher the budget weight of memory and storage relative to logic chips. In the training phase, the market tends to focus only on HBM; after inference, caching, retrieval, enterprise data, and multimodal applications proliferate, NAND, eSSD, high-performance SSD, HDD, and system storage will all be pulled into the compute budget. The investment logic for NAND therefore upgrades from “consumer electronics restocking” to “AI data-layer expansion.”
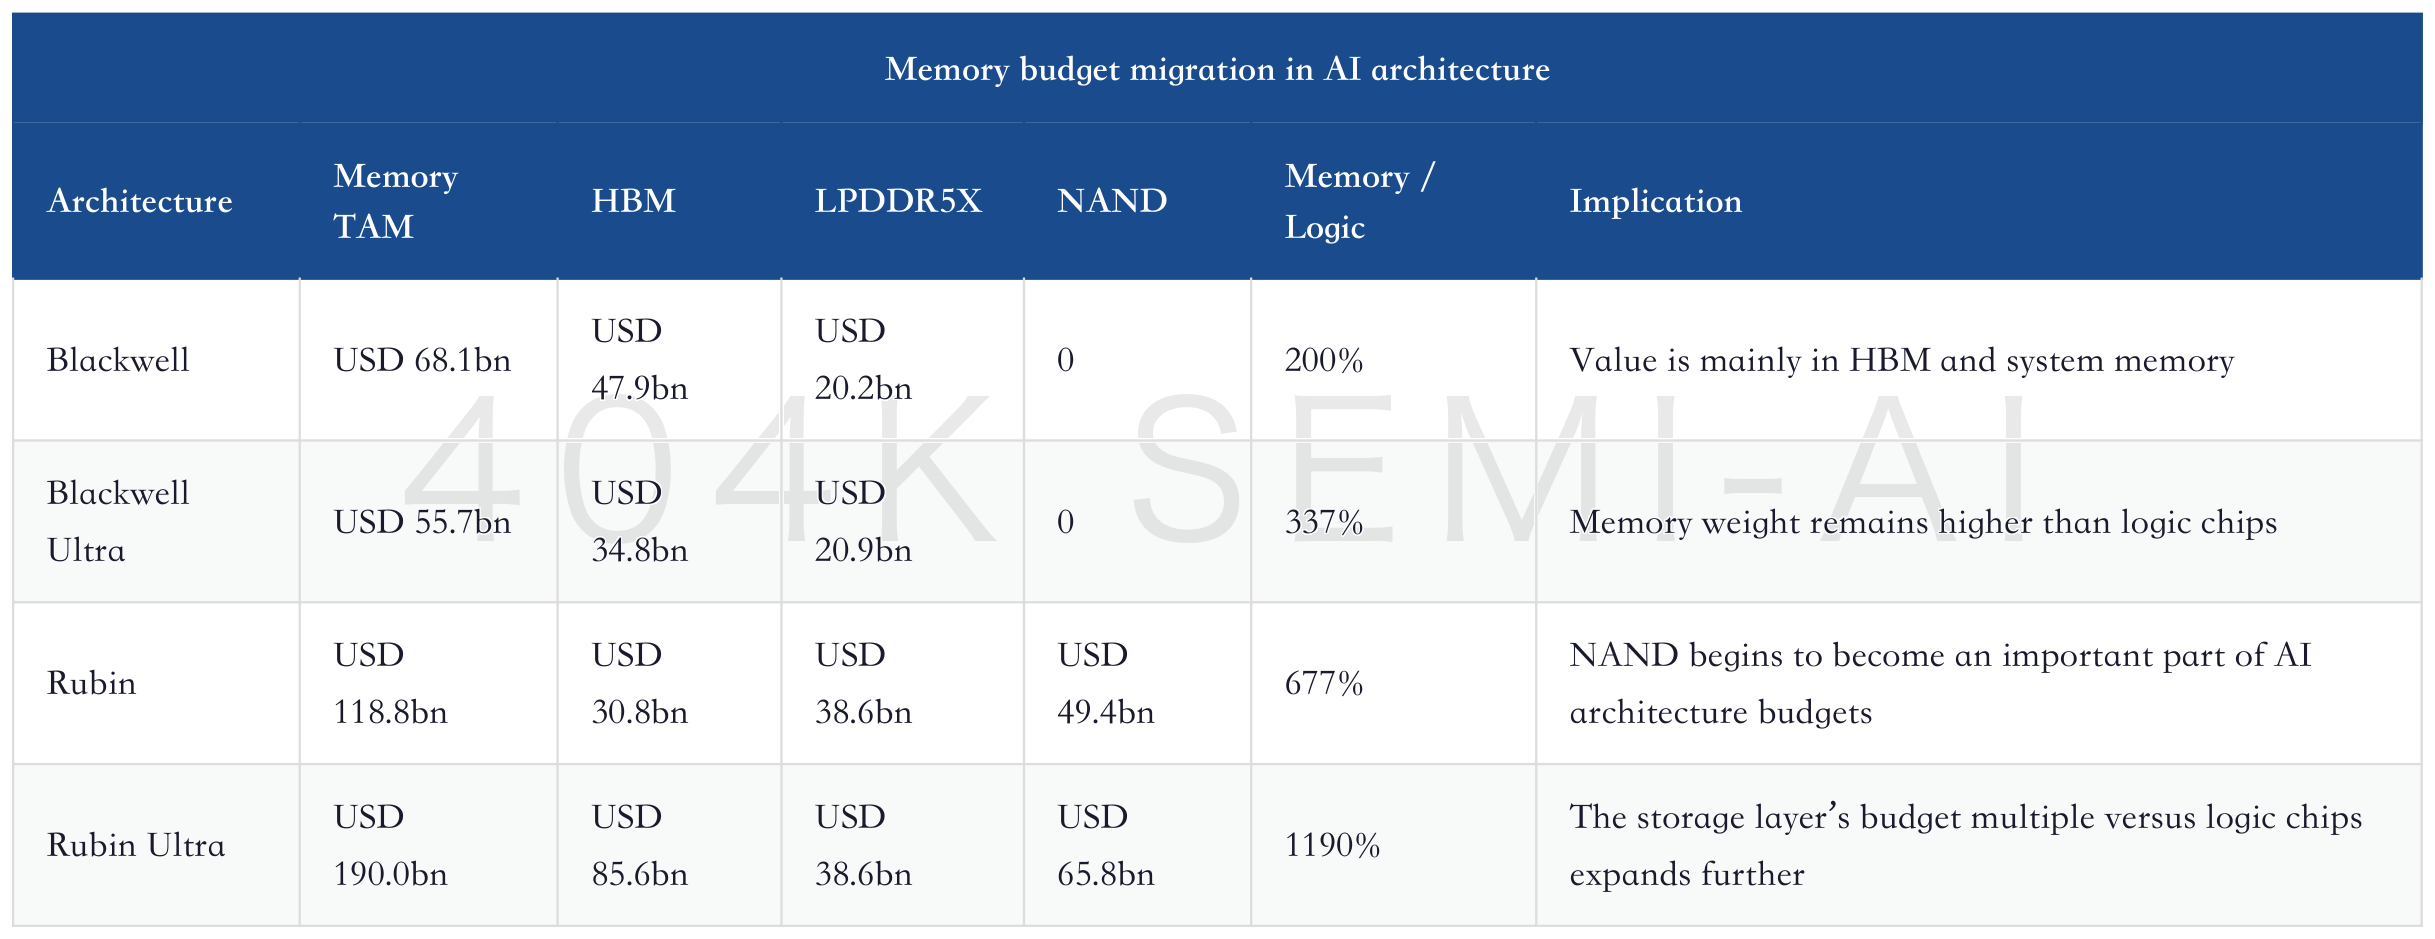
This is why assets such as Kioxia, SanDisk, WDC, and Seagate cannot be viewed only through traditional NAND or HDD cycles. NAND supply-demand is already benefiting from consumer electronics restocking and enterprise SSD tightness, but the longer-term variable is the AI inference data layer. Longer model context windows, KV cache spillover, growth in enterprise knowledge bases, and broader adoption of vector databases and retrieval-augmented generation will all increase the strategic importance of high-performance storage.
SanDisk Deep-Dive Update: Citi Raises Target Price to USD 2,500; NAND Shortage Cycle Extended Beyond CY27
Kioxia Holdings: Call Confirms Tight Supply-Demand and Profit Priority; NAND Profit Center Continues to Move Higher
The risks for NAND are also clearer. First, NAND is more easily affected by supply discipline than DRAM, and the industry has historically seen more intense price wars. Second, if enterprise SSD demand cannot transition from training to inference and enterprise deployment, the high-end shift in NAND will be slower than expected. Third, if Chinese NAND suppliers catch up faster in performance and reliability, commodity NAND prices will come under pressure first. Fourth, the paths among HDD, SSD, HBF, XL-Flash, and other technologies have not been fully settled, so investors should not overcommit in advance to a single technology route.
10. How to Read Valuation: Not Who Is Cheapest, but Whose Peak Profit Can Persist
Nomura’s global peer valuation table is highly instructive. On a 2027F basis, Samsung trades at about 4.2x P/E, SK hynix at about 4.9x, Micron at about 8.7x, Kioxia at about 7.2x, while WDC and Seagate remain at more than 20x. On the surface, the two Korean leaders look cheap, while U.S. and Japanese storage assets look more expensive; but this is not a simple exercise in ranking low P/E stocks.
The real valuation question is the nature of earnings. Samsung is cheap because the market worries about non-memory drag, HBM execution, and the Korea market discount; SK hynix is not expensive because earnings are too high and the market worries about the peak; Micron is more expensive because U.S. capital markets are willing to assign a higher narrative multiple to AI storage; Kioxia sits in the middle because NAND’s earnings center has been re-rated but still carries cyclical shadows; WDC and Seagate trade at high valuations, reflecting enterprise storage, HDD tightness, and capital structure variables.
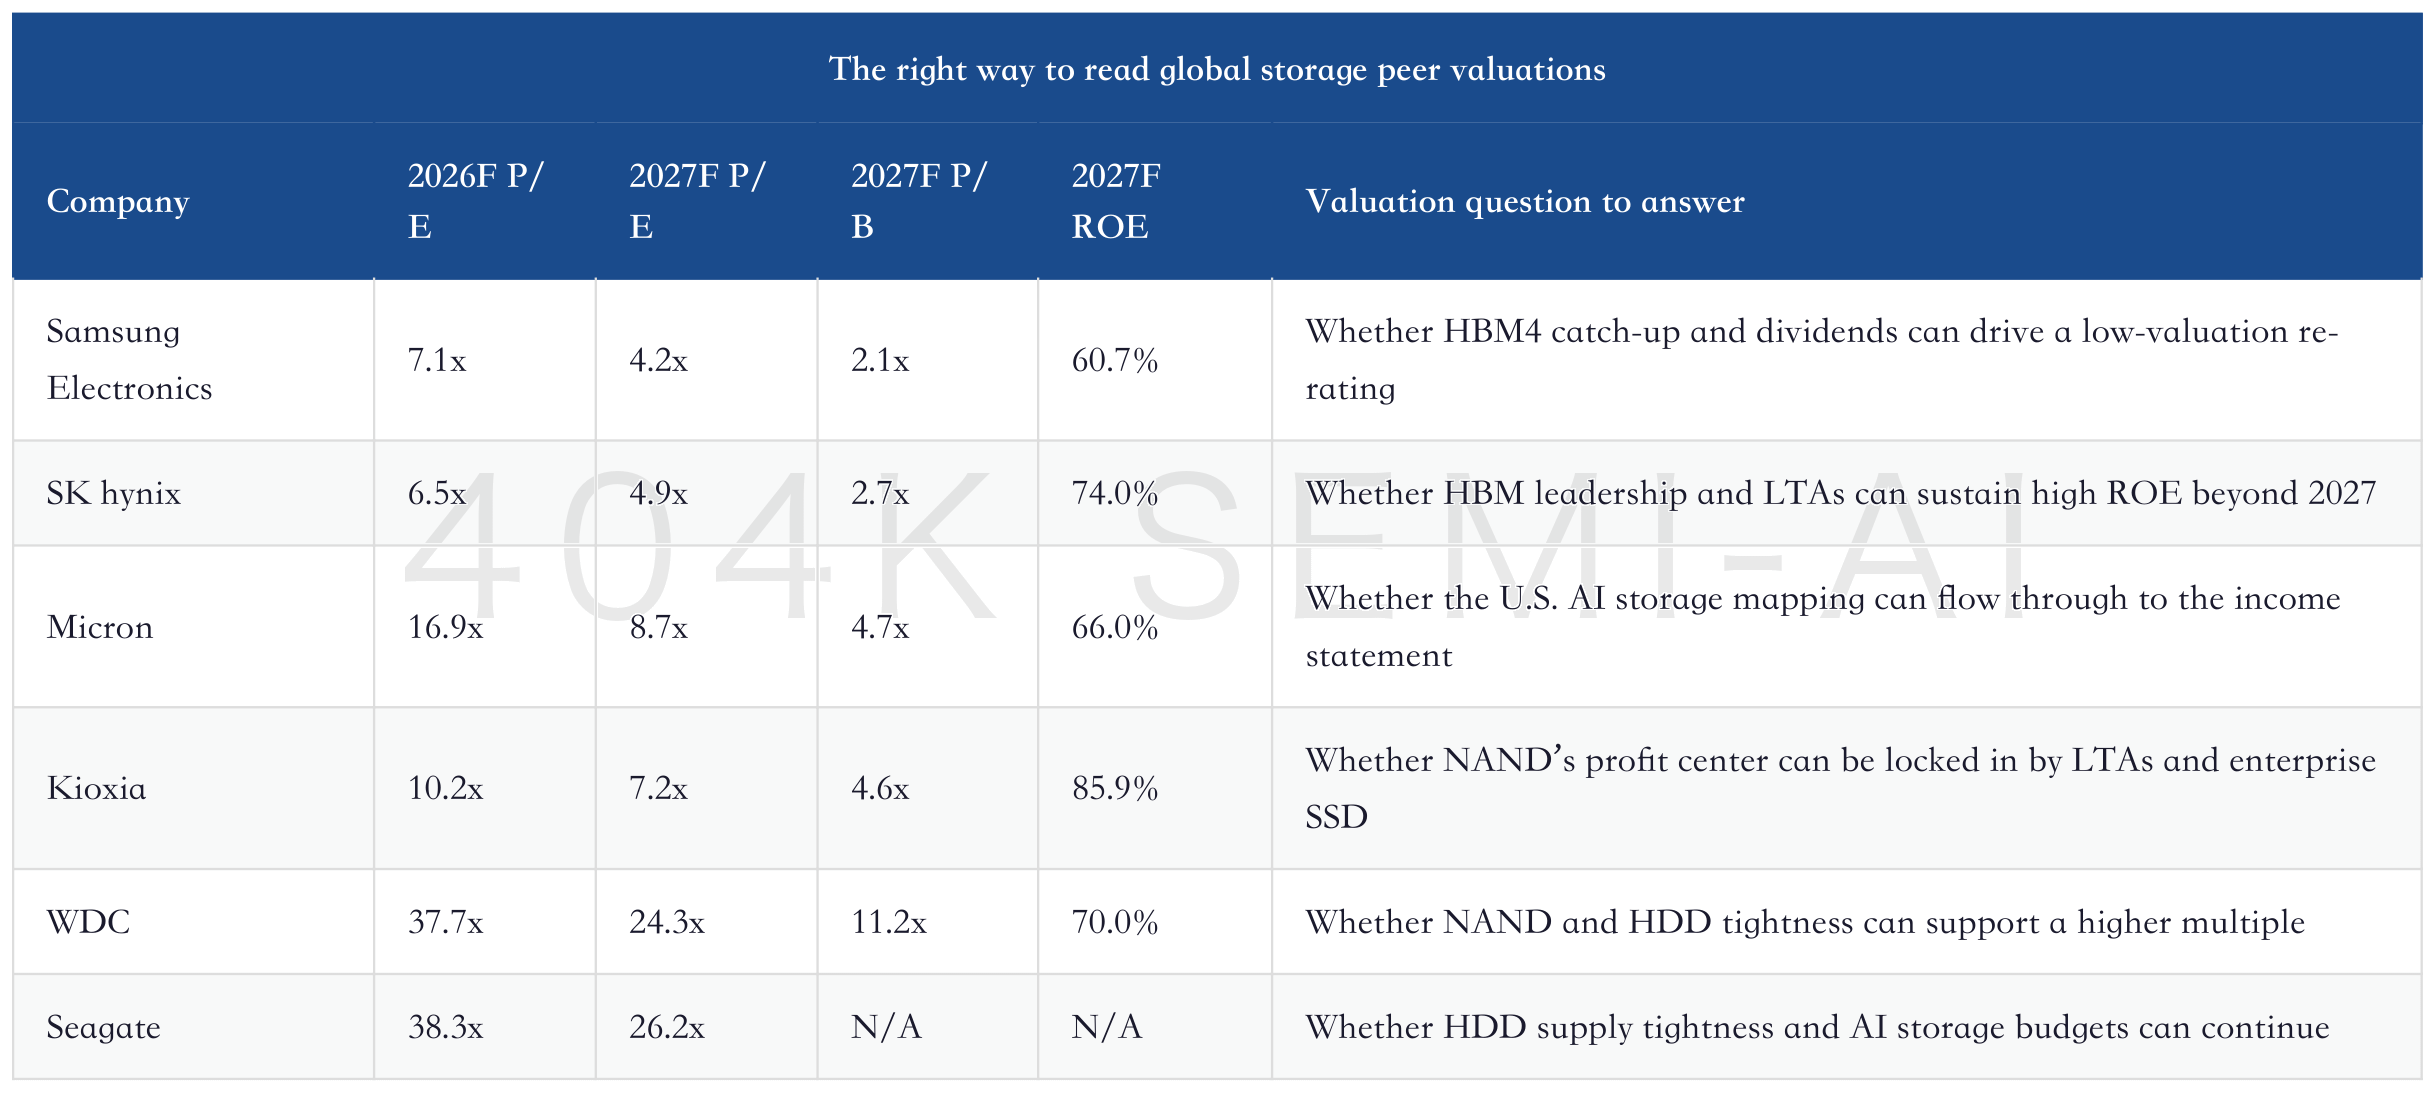
This table should not be read as “buy the lowest P/E.” If 2027 is a super-peak, even 4-5x P/E may not be cheap; if LTAs, HBM4, NAND/eSSD, and data center capex continue to provide support after 2027, then 4-8x P/E may instead underestimate cash-flow durability. The valuation anchor for memory stocks has shifted from “how much prices rise next quarter” to “how much peak profit can be retained into the next cycle.”
A more practical framework is to divide storage assets into three categories. The first is cash-flow-locked assets, represented by SK hynix, Samsung, and Micron, where the core variables are LTAs, HBM, commodity DRAM prices, and shareholder returns. The second is NAND profit-center re-rating assets, represented by Kioxia, SanDisk, and WDC, where the core variables are enterprise SSD, NAND contract prices, and supply discipline. The third is AI storage spillover assets, represented by HDD, controllers, storage systems, and parts of the equipment chain, where the core variables are order conversion and whether valuation has over-discounted the opportunity.
11. From Korea to Global Assets: What This Report Really Affects Is the Entire Memory Chain
Although this report focuses on updates to Samsung and SK Hynix, its implications extend well beyond Korea. Nomura’s higher 3Q commodity DRAM assumptions, continued expectation of sharp NAND price increases, emphasis on HBM margin catch-up, and LTA visibility are, in effect, re-ranking global memory assets. The two Korean leaders are the cleanest income-statement examples; Micron is the most direct DRAM/HBM proxy in the U.S. capital market; Kioxia and SanDisk reflect a reassessment of the NAND earnings center; WDC and Seagate put the AI data layer, HDD shortages, and enterprise storage budgets into the same trading framework.
The global memory chain is no longer a linear market where “prices rise, so everything rises together.” DRAM leaders benefit from HBM capacity diversion, catch-up pricing in conventional DRAM, and LTA visibility. NAND companies benefit from enterprise SSDs, the AI inference data layer, and supply discipline. HDD companies benefit from tight nearline storage supply and data-center storage-capacity budgets. Equipment and materials companies benefit from capacity expansion, advanced packaging, and yield ramp-up, but they are also more prone to valuation pull-forward.
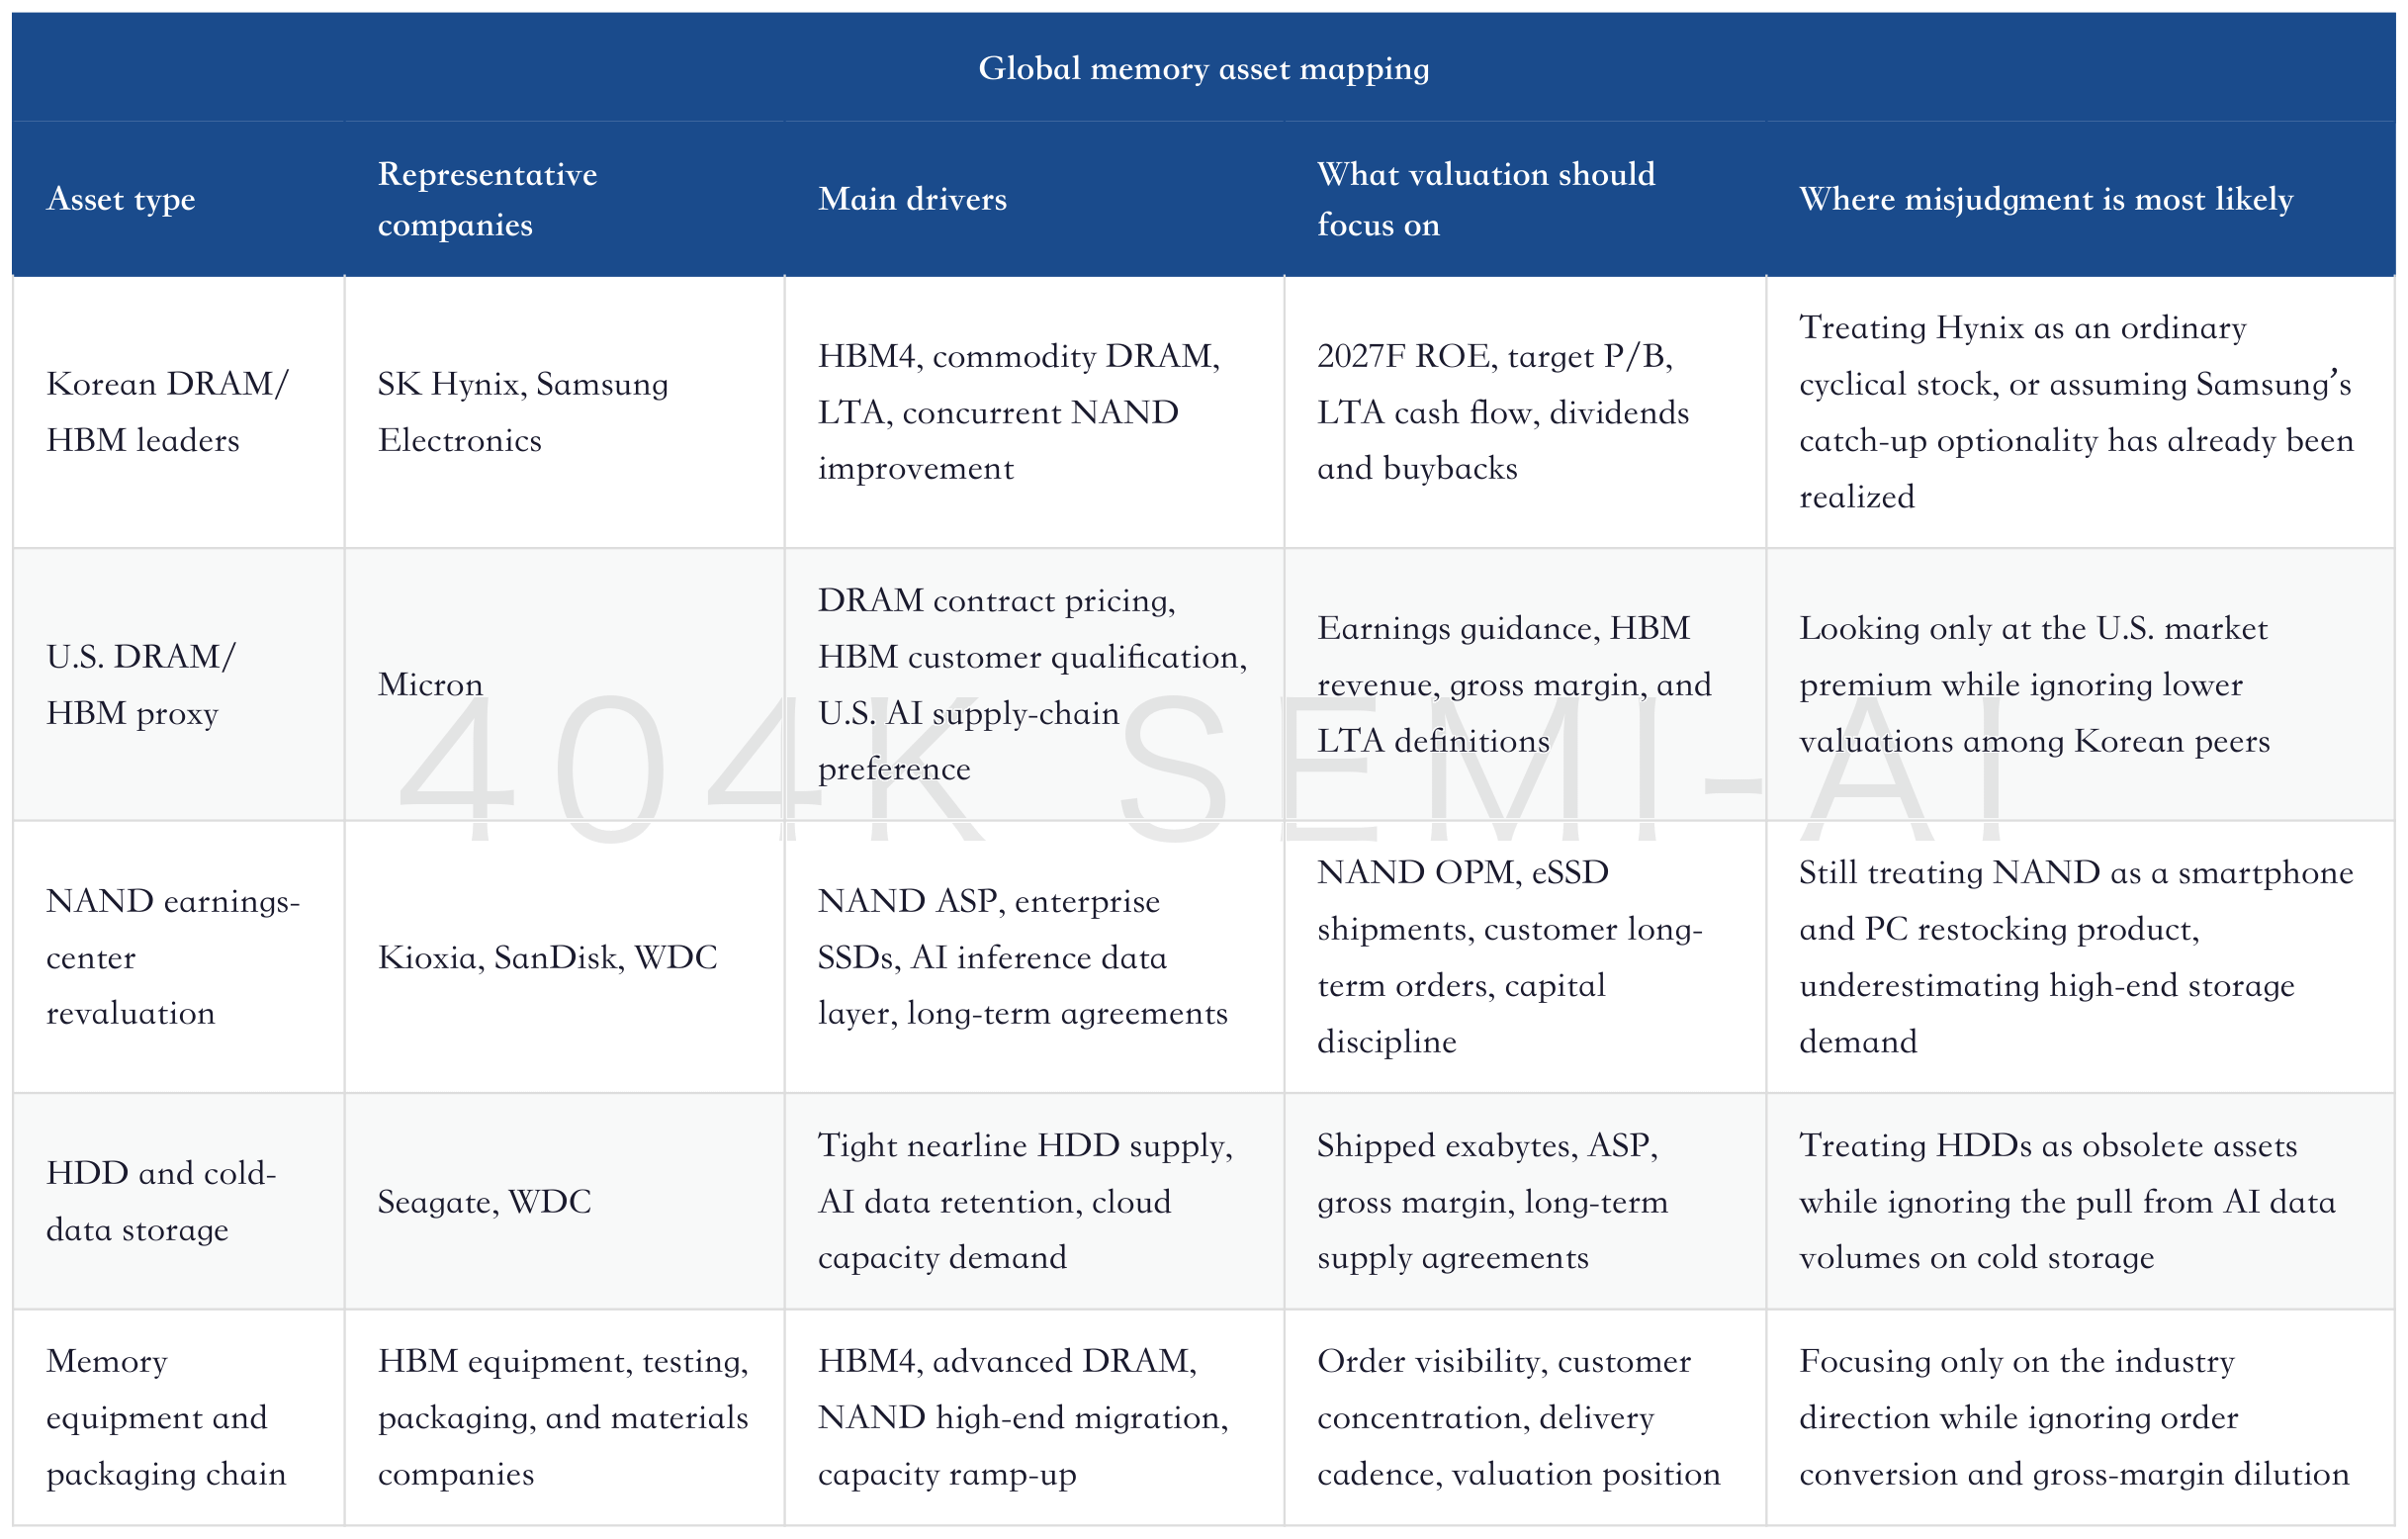
The investment implication of this mapping is that the global memory trade should not be compressed into “buy HBM leaders.” HBM is the strongest main line, but conventional DRAM, NAND, eSSD, HDD, advanced packaging, and memory equipment all sit on the same capex chain. The real question is what each layer earns, how it is validated, and how long profits can be retained.
Micron is a useful reference point. Micron’s earnings have already shown that AI memory demand can quickly flow through revenue, gross margin, and guidance. But U.S. equity valuations usually price future expectations more quickly, while Korean and Japanese assets may offer cheaper cash flow during the earnings-delivery phase. For global investors, Hynix and Samsung are not simple substitutes for Micron. They are different risks in the same AI memory cycle bought at lower multiples: Hynix offers leadership, Samsung offers repair, and Micron offers capital-market liquidity and U.S. supply-chain exposure.
The mapping of NAND assets is more interesting. SanDisk, Kioxia, and WDC do not directly replicate the logic of DRAM leaders. They need to prove whether the NAND earnings center can move from a strong cyclical rebound to a structural uplift. Enterprise SSDs, post-Rubin flash budgets, the AI inference data layer, and HDD shortages provide NAND with a second demand curve. But NAND has historically had weaker supply discipline, while customer qualification and product mix are also more complex. Therefore, NAND assets should not be evaluated only by spot prices; high-end products, long-term contract pricing, customer structure, and capex matter more.
12. Three Worldviews: Asset Revaluation, Strong Cyclical Rebound, and Demand Mismatch
Whether memory stocks can keep rising does not depend on the simple statement that “prices are still rising.” It depends on which worldview the market ultimately adopts. The first is asset revaluation: AI infrastructure turns memory and storage into long-term bottlenecks, customers use LTAs to lock in supply, and peak profits are partly capitalized. The second is a strong cyclical rebound: prices rise sharply, but after 2027 supply is released, demand slows, and profits still need to be discounted as cyclical peak earnings. The third is demand mismatch: long-term AI demand remains, but power, construction, customer budgets, and product-introduction schedules push orders out, sending stock prices into a volatile consolidation phase.
The distinction among these three worldviews is not as simple as bullish versus bearish. Asset revaluation does not mean there will be no drawdowns. A strong cyclical rebound does not mean there will be no profits. Demand mismatch certainly does not mean demand has disappeared. The real difference lies in valuation multiples: asset revaluation brings higher P/B and a smaller cyclical discount; a strong cyclical rebound brings low P/E and quick in-and-out peak earnings; demand mismatch brings still-strong fundamentals but repeated valuation volatility.
