
GE Vernova Q2 Results Deep Dive: $24.2 Billion in Orders, 116 GW of Gas Turbine Commitments, and $12 Billion Free Cash Flow Guidance
目录
TL;DR
1. The Real Change This Quarter Was the Credibility of Growth, Not Just Larger Numbers
2. The Value of the $176.3 Billion Backlog Lies in Its Conversion Timeline, Not Its Absolute Size
3. Power: One Quarter of Gas Turbine Contracts Equal to a Full Year of Capacity
4. Electrification: M&A Expands Scale, While Organic Margins Show the Core Business Is Also Strengthening
5. Wind: Breaking Even in the Third Quarter Is Only the First Step; Full-Year Guidance Requires a Clearly Profitable Fourth Quarter
6. Cash Flow: The $5.1 Billion Is Real, but Not Replicable Every Quarter
7. Guidance Raised: Earnings Must Accelerate in the Second Half, While Cash Flow Can Slow
8. Prolec GE and Capital Allocation: Ample Net Cash, but Both M&A and Buybacks Raise Execution Requirements
9. What Has Changed Since Q1—and What Has Not
10. Six Numbers to Watch
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Orders, margins, and cash flow all moved higher. The key questions are how much cash came from customer advances, when Wind will genuinely break even, and whether the backlog can be delivered at high margins in the second half.
TL;DR
GE Vernova (NYSE: GEV) converted “strong demand” into verifiable orders and earnings in the second quarter. Orders reached $24.216 billion, up 88% organically; revenue was $11.104 billion, up 12% organically; and adjusted EBITDA was $1.25 billion, with an 11.3% margin, up 280 basis points year over year. Remaining performance obligations rose to $176.284 billion, an increase of $13.008 billion sequentially. Power and Electrification both expanded orders, revenue, and margins, making growth less dependent on a single business.
The midpoint of 2026 free cash flow guidance increased from $7 billion to $12 billion, far exceeding the roughly 2.2% increase in the revenue midpoint, indicating that the revision was driven primarily by cash timing rather than a sudden change in margin assumptions. First-half free cash flow already reached $9.897 billion, equivalent to 82.5% of the new guidance midpoint; contract liabilities and current deferred revenue generated $13.695 billion of working-capital inflows. Customer advances are real cash and improve project certainty, but future equipment production and delivery will consume cash through inventory, labor, and the supply chain. The second quarter’s $5.107 billion of free cash flow therefore should not be annualized directly.
Power was the strongest order engine this quarter. Orders reached $16.729 billion, up 134% organically, with a quarterly book-to-bill ratio of approximately 3.1x. Gas turbine backlog stood at 53 GW, with another 63 GW in slot reservations, for a combined 116 GW. The company signed 20 GW of new gas turbine contracts during the quarter, equivalent to its current annual production capacity of 20 GW. Demand is no longer the issue. The next test is whether the company can deliver on its capacity roadmap of 24 GW by 2028 and 30 GW by 2030 while maintaining margins of approximately 18%.
Electrification’s growth was not driven solely by the consolidation of Prolec GE. Quarterly orders were $6.347 billion, up 66% organically; revenue was $3.637 billion, up 29% organically; and segment EBITDA margin reached 18.4%, with organic margin expanding 700 basis points year over year. Year-to-date data center-related orders exceeded $5 billion, more than twice the total for full-year 2025. The acquisition expanded transformer capacity and revenue, but the combined improvement in pricing, volume, and productivity is the primary evidence behind the margin expansion.
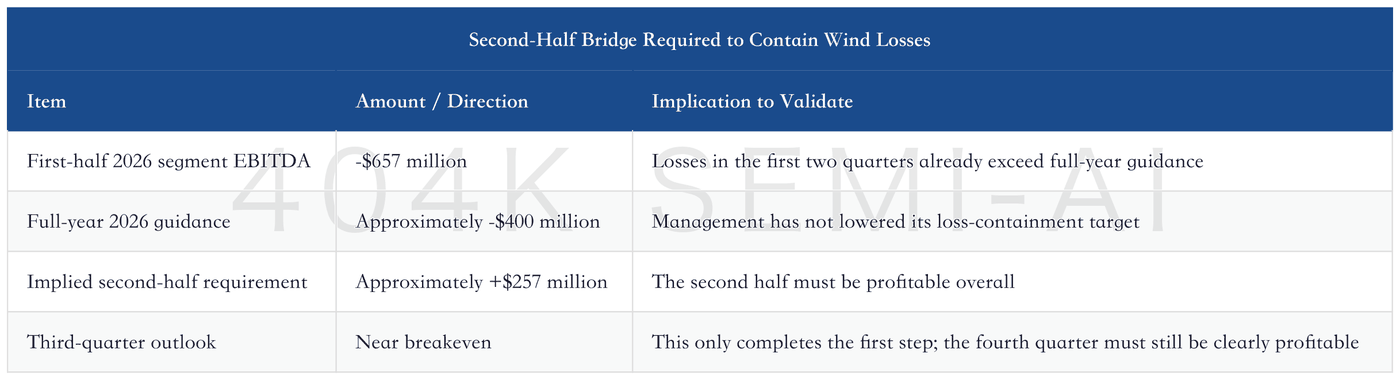
Wind remains the clearest counterpoint in the entire set of results. Orders declined 40% organically, revenue fell 11% organically, and segment EBITDA recorded a $275 million loss. The cumulative first-half loss was $657 million. Yet the company maintained its full-year loss guidance of approximately $400 million, implying that Wind must generate approximately $257 million of positive EBITDA in the second half. Being “near breakeven” in the third quarter is only the first hurdle; the segment must then deliver a meaningful profit in the fourth quarter to meet the full-year outlook.
The $12 billion free cash flow guidance should not be treated as a permanent annual run rate for valuation purposes. A more appropriate framework is to assess operating earnings through adjusted EBITDA, revenue through the conversion rate of remaining performance obligations, cash quality through changes in contract liabilities and inventory, and the earnings ceiling through Wind’s ability to move from losses to profitability. If equipment deliveries accelerate in the second half, margins hold, and contract-liability growth moderates, lower cash flow would not necessarily indicate weaker operations. If inventory continues to rise rapidly, deliveries slow, and Wind remains loss-making, today’s high order levels will become an execution burden.
1. The Real Change This Quarter Was the Credibility of Growth, Not Just Larger Numbers
The most important change in the second quarter was that orders, revenue, margins, and cash flow all moved strongly in the same direction for the first time. Orders reached $24.216 billion, up 88% organically year over year, with equipment orders up 130% and services orders up 15%. Revenue was $11.104 billion, up approximately 22% under U.S. GAAP and 12% organically. Adjusted EBITDA increased 62%, from $770 million to $1.25 billion, while margin rose from 8.5% to 11.3%.
Equipment orders grew far faster than services orders, implying that the revenue mix will shift toward equipment over the next several years. Equipment typically carries lower gross margins than mature services, so a higher equipment mix can weigh on consolidated margins. Nevertheless, the adjusted organic EBITDA margin expanded by 340 basis points this quarter, indicating that pricing, productivity, and higher volumes more than offset the adverse equipment mix for now. This is more meaningful than revenue growth alone because it addresses whether capacity expansion is generating only low-margin revenue.
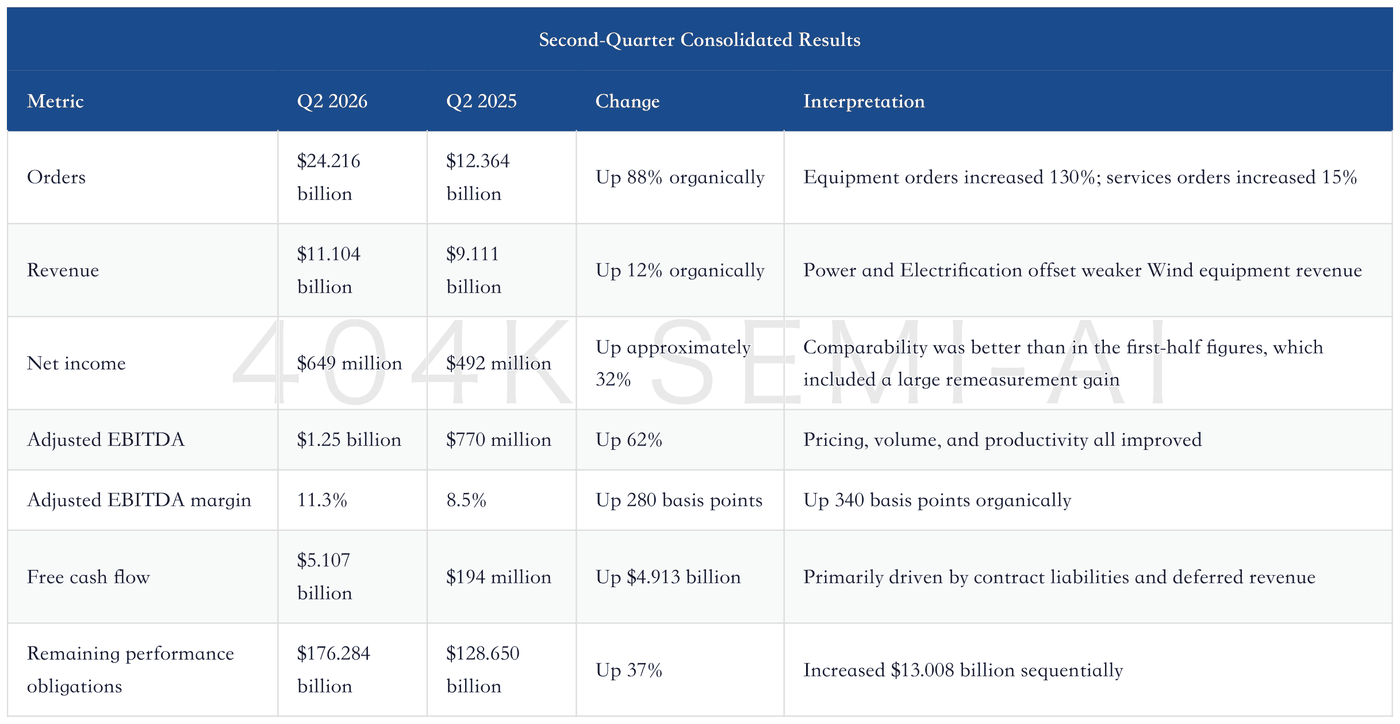
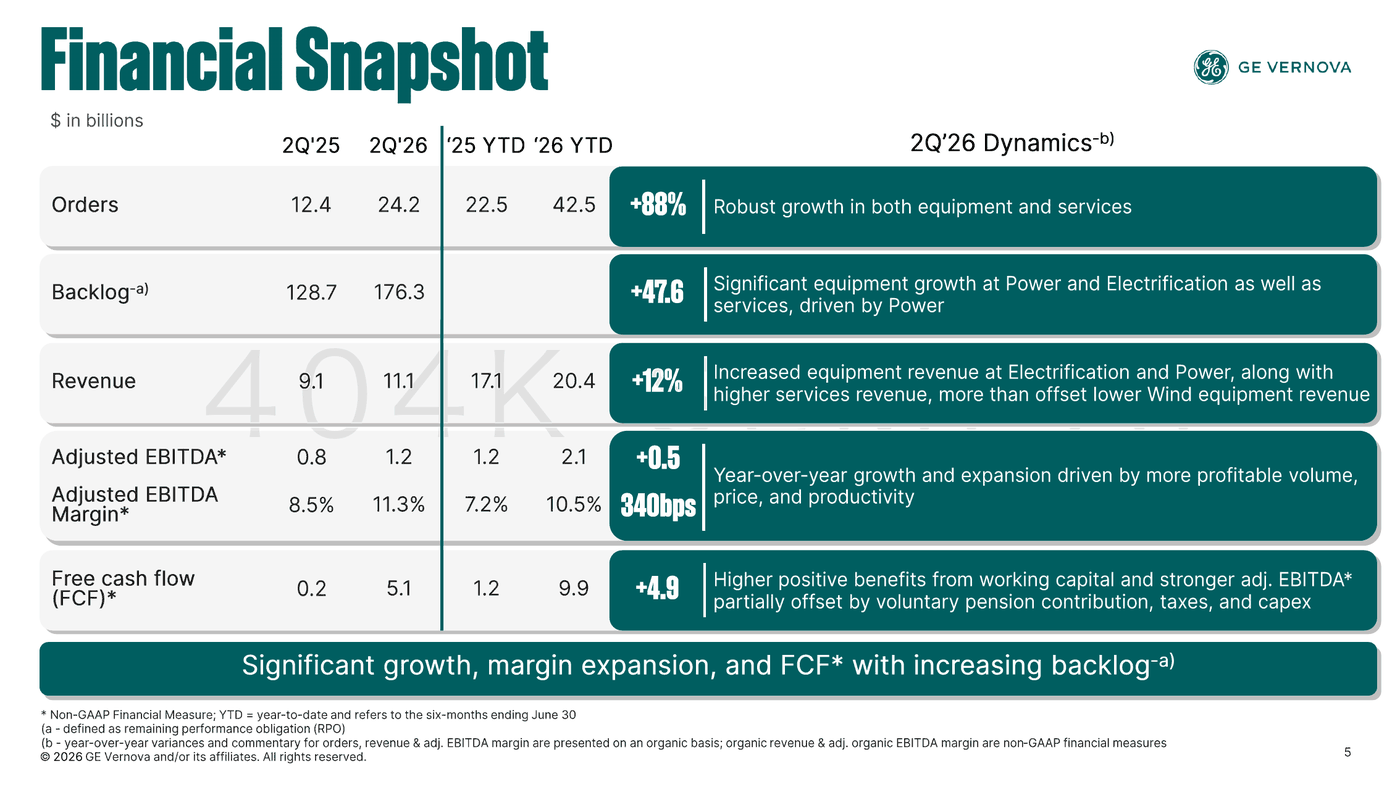
Orders, revenue, adjusted EBITDA margin, and free cash flow improved simultaneously. Source: GE Vernova, Q2 2026 Earnings Presentation, p. 5; amounts in billions of U.S. dollars.
U.S. GAAP net income of $649 million and a net margin of 5.8%, only 0.4 percentage points higher year over year, are not inconsistent with the strong improvement in adjusted EBITDA. Depreciation and amortization totaled $418 million this quarter, compared with $202 million a year earlier. Within that figure, intangible asset amortization increased from $60 million to $236 million, mainly reflecting intangible assets recognized in the Prolec GE acquisition. Operating earnings improved, but purchase-accounting amortization weighed on the bottom line.
First-half net income of $5.398 billion should not be used as the starting point for annualizing operating earnings. It included a $3.992 billion pre-tax gain from remeasuring the company’s existing stake when it acquired the remaining 50% of Prolec GE, as well as a $330 million pre-tax gain from business disposals. Adjusted EBITDA, segment EBITDA, and free cash flow are more appropriate measures of ongoing operations, while the timing effect of customer advances within free cash flow should be analyzed separately.
2. The Value of the $176.3 Billion Backlog Lies in Its Conversion Timeline, Not Its Absolute Size
Remaining performance obligations (RPO) increased from $128.650 billion a year ago to $176.284 billion, including a further sequential increase of $13.008 billion. This represents approximately 3.8x the midpoint of the company’s updated 2026 revenue guidance and provides multiyear revenue visibility. However, the simple view that “a larger backlog is always better” remains inadequate because equipment and services convert on entirely different timelines.
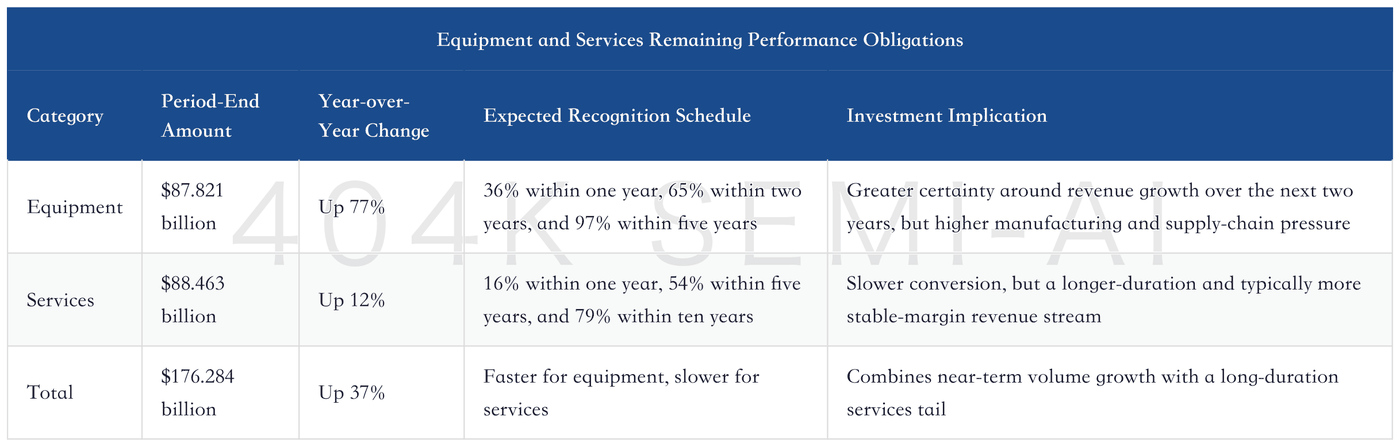
Based on the company’s disclosed percentages, approximately $31.6 billion of equipment RPO and $14.2 billion of services RPO could be recognized over the next year, for a combined total of approximately $45.8 billion. This is close to the scale of the company’s full-year 2026 revenue guidance, but it should not be treated directly as a forecast for the next year because revenue recognition will depend on project progress, customer site conditions, contract modifications, and service milestones. It is better viewed as evidence of the revenue base than as a precise quarterly forecast.
Equipment RPO increased 77% year over year, versus only 12% for services, creating the first pressure test for future margins. If equipment deliveries increase while the services mix declines, the company must continue relying on pricing, productivity, and design standardization to protect margins. This quarter’s organic margin expansion indicates that the company has managed this successfully so far. However, as capacity increases from 20 GW to 24 GW and ultimately 30 GW, costs related to additional shifts, supplier expansion, quality control, and R&D; could precede the associated revenue.
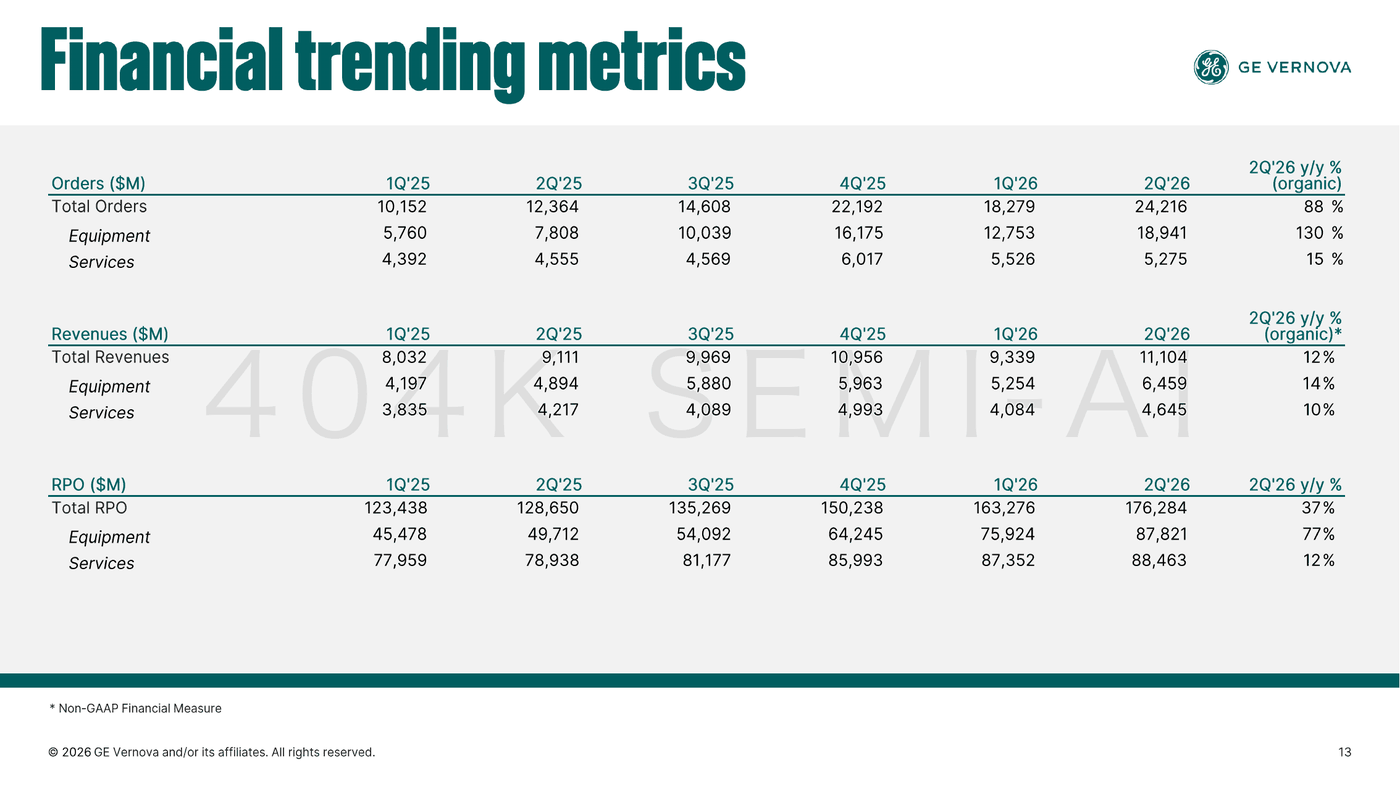
Equipment RPO grew significantly faster than services RPO, bringing the second-quarter total to $176.284 billion. Source: GE Vernova, Q2 2026 Earnings Presentation, p. 13.
Large customer advances improve order quality while also bringing GE Vernova’s execution obligations forward. Contract liabilities mean that customers have already paid even though the company has not yet recognized the corresponding revenue. They are not interest-bearing debt in the traditional sense, but they represent future delivery obligations. Stronger orders and larger advances improve current cash generation; once projects enter production and installation, however, the company must use that cash to purchase materials, expand capacity, and fulfill its contracts. Assessing backlog quality therefore requires evaluating orders, contract liabilities, inventory, deliveries, and gross profit together.
3. Power: One Quarter of Gas Turbine Contracts Equal to a Full Year of Capacity
Power orders were $16.729 billion in the second quarter, up 134% organically, making the segment the primary driver of incremental orders this quarter. Equipment orders were $12.650 billion, up 259% organically; services orders were $4.078 billion, up 12%. Revenue was $5.477 billion, up 14% organically; segment EBITDA was $1.031 billion, with an 18.8% margin, up 240 basis points year over year and 320 basis points organically.
The book-to-bill ratio of approximately 3.1x shows that customers are securing gas turbines and related equipment far faster than the company can deliver them. New gas equipment contracts totaled 20 GW during the quarter, including 18 GW of slot reservations and 2 GW of firm orders. Over the same period, 10 GW of reservations were converted into firm orders and 3 GW was delivered. Firm backlog rose from 44 GW to 53 GW, while slot reservations increased from 56 GW to 63 GW, taking the combined total from 100 GW to 116 GW.
The 20 GW of new contracts signed is exactly equivalent to the annualized production capacity the company currently plans to reach in the third quarter of 2026. This indicates that demand already far exceeds current supply. The revenue trajectory is no longer determined by customer availability, but by whether castings, blades, control systems, testing, installation, and on-site grid connection can ramp in sync. The company plans to reach 24 GW in 2028 and prepare for 30 GW by 2030 through lean improvements and incremental equipment at existing facilities.
Moving from 116 GW to at least 125 GW by year-end appears to require only another 9 GW, but this cannot be assessed through simple net arithmetic. The company is signing new contracts while simultaneously converting reservations into firm orders and delivering equipment. If deliveries accelerate in the second half, new contracts must also offset the reduction from delivered units for the combined backlog and reservation total to continue rising. The 125 GW year-end target is therefore both a demand indicator and a combined measure of sales momentum and capacity execution.
The services business extends the value of gas turbine capacity expansion beyond equipment revenue. The company disclosed that 130 HA gas turbines are already in operation and 195 are under contract, with contracted units set to more than double the current HA fleet. New equipment first contributes hardware revenue, then enters a long-term cycle of maintenance, spare parts, and upgrades. Services remaining performance obligations are growing more slowly but are more durable, helping cushion future equipment-cycle volatility.
Power’s 18.8% margin this quarter demonstrates that pricing and productivity are sufficient to cover capacity-expansion investment, but this remains only an interim validation. Management explicitly noted that higher R&D; and capacity spending continued to be offset by better pricing, volume, and productivity. If orders continue to grow rapidly while the margin falls below the 17% lower bound of full-year guidance, investors will need to distinguish among temporary equipment mix, expansion costs, and changes in supply-chain bargaining power.
4. Electrification: M&A; Expands Scale, While Organic Margins Show the Core Business Is Also Strengthening
Electrification orders were $6.347 billion in the second quarter, up 66% organically, with a book-to-bill ratio of approximately 1.7x. Revenue was $3.637 billion, up 68% under US GAAP and 29% organically; segment EBITDA was $671 million, with an 18.4% margin, up 390 basis points year over year and 700 basis points organically. Equipment remaining performance obligations were $40.589 billion, up 69% year over year.
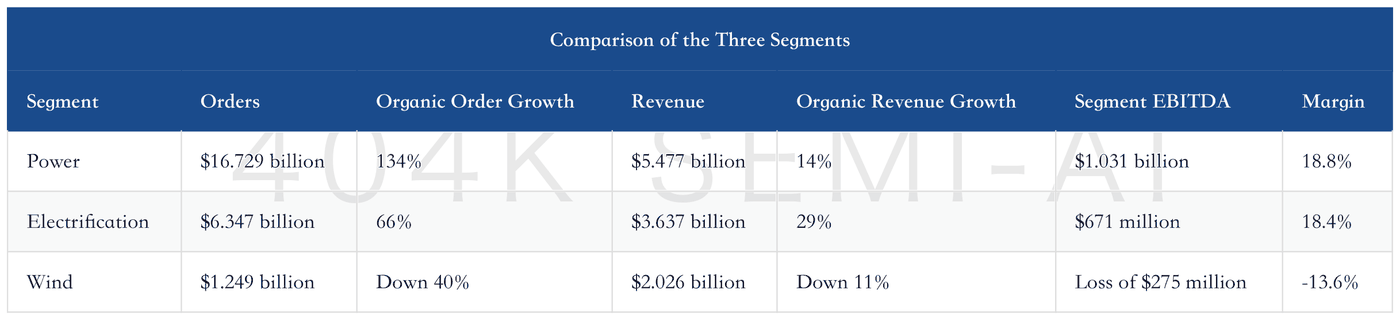
Prolec GE contributed $859 million of second-quarter revenue, approximately 24% of Electrification revenue, but consolidation is not the whole story. Prolec GE recorded a pretax loss of $57 million this quarter, reflecting inventory fair-value step-up amortization, intangible-asset amortization, and integration costs. Meanwhile, Electrification’s organic revenue grew 29% and its organic margin improved by 700 basis points, indicating that the legacy businesses—including power transmission, AC substations, high-voltage direct-current systems, and power conversion—are also scaling and improving efficiency.
Business-unit data show where growth is concentrated. Power Transmission generated $1.877 billion in revenue, making it Electrification’s largest component; Grid Systems Integration contributed $806 million, Power Conversion & Storage $539 million, and Grid Automation & Software $416 million. Transformers, switchgear, and high-voltage systems were the principal growth drivers, while software revenue was relatively stable. In other words, this growth cycle is primarily driven by supply-demand tightness in heavy equipment and engineered systems, rather than a sudden acceleration in asset-light software.
Year-to-date data-center-related orders exceeded $5 billion, already more than double the full-year 2025 level. These orders span power supply, substations, switchgear, and power-quality systems, indicating that power constraints at large-scale computing projects are now flowing into equipment manufacturers’ order books. The company is also working with major cloud customers to develop solid-state transformer prototypes and medium-voltage uninterruptible power supplies to improve data-center efficiency and resilience. These products remain in the development and validation stage; near-term revenue should be assessed primarily through the existing backlog for transformers, switchgear, and systems integration.
Management expects switchgear backlog deliveries to accelerate in 2027, providing a more specific time anchor than simply stating that “long-term demand is strong.” Continued capacity expansion in 2026 followed by higher volume in 2027 means part of this year’s margin improvement reflects pricing and productivity, while the capacity contribution should become more fully visible next year. The risks are equally clear: a slow expansion would delay revenue, while expanding too quickly could create fixed-cost and inventory pressure if order growth decelerates.
5. Wind: Breaking Even in the Third Quarter Is Only the First Step; Full-Year Guidance Requires a Clearly Profitable Fourth Quarter
Wind orders were $1.249 billion, down 40% organically; revenue was $2.026 billion, down 11% organically; segment EBITDA was a loss of $275 million, representing a -13.6% margin. Equipment revenue declined 23%, while services revenue grew 39%. Onshore wind is currently seeing insufficient equipment deliveries following weak orders in the first half of 2025; offshore wind revenue increased, but was burdened by project costs.
Wind generated a cumulative loss of $657 million in the first half, while full-year guidance remains a loss of approximately $400 million. On simple arithmetic, the second half must contribute approximately $257 million of positive EBITDA to reach the full-year loss target of $400 million. The company’s third-quarter outlook is for “near breakeven,” driven primarily by improved services performance and lower offshore project costs. If the third quarter merely breaks even, the fourth quarter must generate approximately $257 million of positive EBITDA—a substantial improvement.
Losses come from three sources: insufficient onshore equipment volume, offshore project costs, and tariffs. The company expects the 2026 tariff impact after mitigation measures to be $100 million to $200 million. Installation at Vineyard Wind is complete, but commissioning, claims, and counterclaims have not yet been fully resolved. Improving services profitability can provide a buffer, but it cannot permanently substitute for a recovery in the equipment business.
Wind’s long-term optionality comes from approximately 10 GW of onshore installed capacity eligible for the new production tax credit, creating retrofit and upgrade opportunities before the end of this decade. However, this opportunity cannot replace near-term loss containment. What is needed now is not more long-dated narratives, but the elimination of losses in the third quarter, a return to profitability in the fourth quarter, no further offshore project cost increases, and a renewed flow of onshore orders into delivery.
Wind goodwill remains approximately $3.236 billion, with no impairment recognized in the financial statements. If orders continue to decline, project costs keep rising, or the recovery in profitability is delayed again, both goodwill and long-term contract estimates will face more stringent testing. Wind’s share of group revenue has declined, but its impact on earnings volatility and management credibility remains substantial.
6. Cash Flow: The $5.1 Billion Is Real, but Not Replicable Every Quarter
Second-quarter operating cash flow was $5.492 billion; after deducting $386 million in capital expenditures, free cash flow was $5.107 billion. First-half operating cash flow was $10.68 billion, and free cash flow was $9.897 billion. The figures are genuine: the cash has entered the balance sheet, with period-end cash, cash equivalents, and restricted cash reaching $13.12 billion.
The surge in cash flow was driven primarily by increases in contract liabilities and current deferred revenue. This item generated an $8.121 billion cash inflow in the second quarter and $13.695 billion in the first half, reflecting customer payments for equipment and projects before revenue recognition. Accounts receivable, inventories, and contract assets consumed cash over the same period, consistent with the company procuring, producing, and funding project progress ahead of future deliveries.
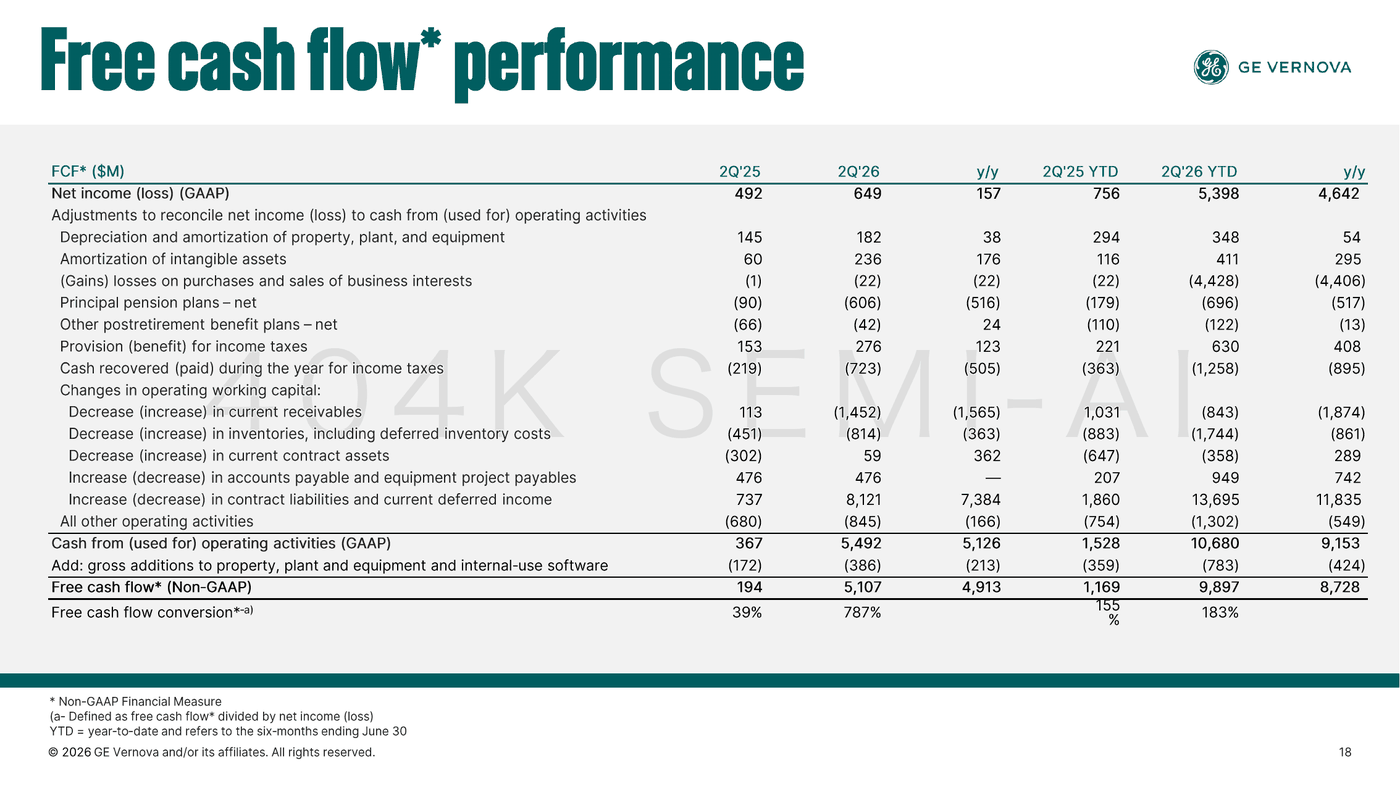
The $8.121 billion increase in contract liabilities and current deferred revenue was the main driver of the second-quarter free cash flow surge. Source: GE Vernova, “Second Quarter 2026 Earnings Presentation,” p. 18; amounts in USD millions.
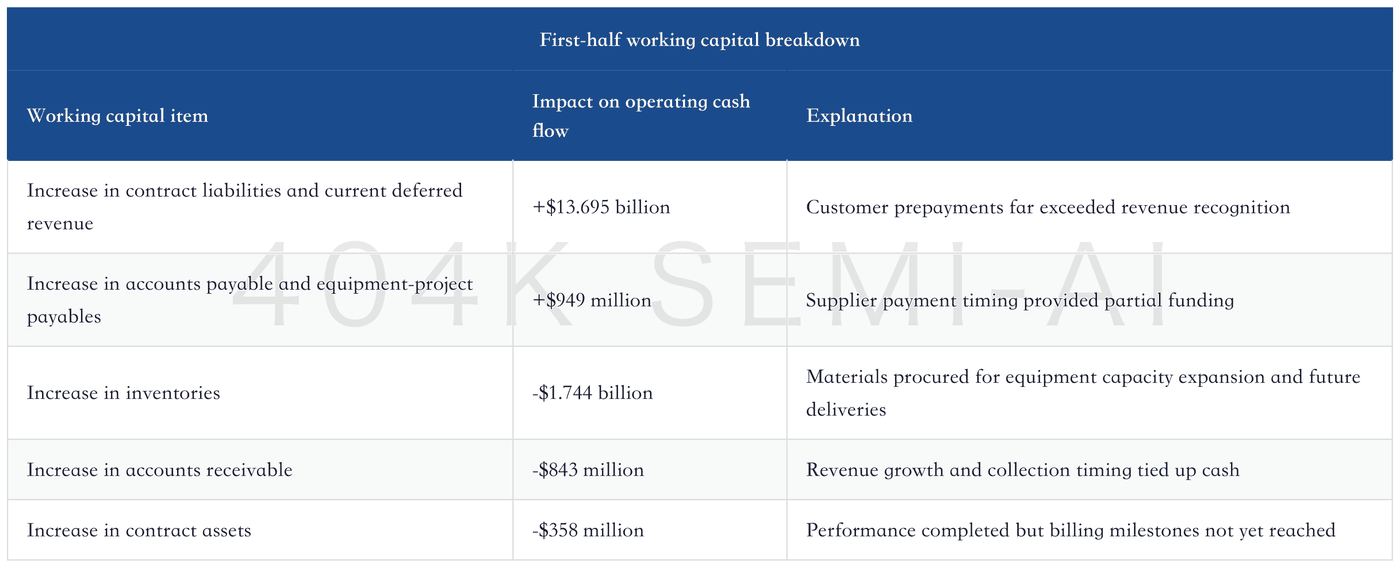
Contract liabilities rose from approximately $25.774 billion at year-end 2025 to $39.944 billion at the end of June 2026, an increase of $14.17 billion. Part of the increase came from the consolidation of Prolec GE, while the remainder primarily reflected new collections exceeding revenue recognition. Power segment contract liabilities rose to $27.679 billion, making it the main source of prepayment growth and corroborating the expansion in gas-turbine slot reservations and equipment orders.
Prepayments are not low-quality cash, but they have a clear interperiod dimension. For long-cycle equipment companies, customer advance payments reduce financing needs and cancellation risk, and can even shift part of the capacity-expansion funding burden to customers. The issue is that when future deliveries occur, revenue and profit will be recognized without an equivalent cash receipt. Inventory consumption, supplier payments, and project execution may then cause free cash flow to fall below earnings.
First-half free cash flow of $9.897 billion has already reached 82.5% of the midpoint of the new $12 billion guidance. The second half therefore needs only approximately $2.103 billion to reach the midpoint, $1.603 billion to reach the $11.5 billion low end, and $2.603 billion to reach the $12.5 billion high end. Management clearly expects second-half cash flow to be significantly lower than in the first half, consistent with front-loaded prepayments, accelerating deliveries, and renewed working-capital absorption.
7. Guidance Raised: Earnings Must Accelerate in the Second Half, While Cash Flow Can Slow
The company raised its 2026 revenue guidance from $44.5–45.5 billion to $45.5–46.5 billion and free cash flow guidance from $6.5–7.5 billion to $11.5–12.5 billion, while maintaining its adjusted EBITDA margin guidance at 12%–14%. The revenue midpoint increased by only $1 billion, or approximately 2.2%, while the free cash flow midpoint rose by $5 billion, or approximately 71.4%. This divergence again indicates that the cash-flow upgrade primarily reflects working capital and collection timing.
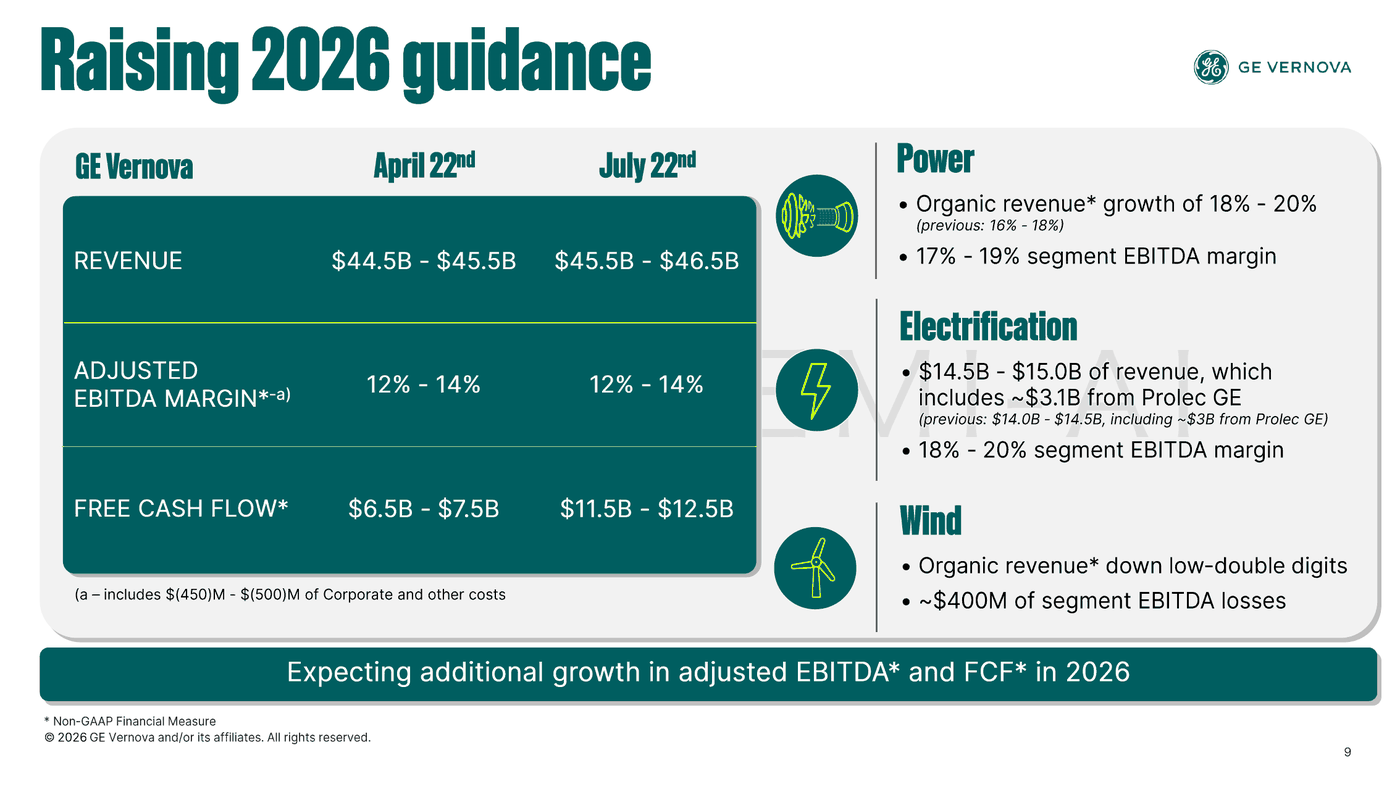
The company raised its revenue and free cash flow guidance while maintaining its adjusted EBITDA margin guidance at 12%–14%. Source: GE Vernova, “Second Quarter 2026 Earnings Presentation,” p. 9.
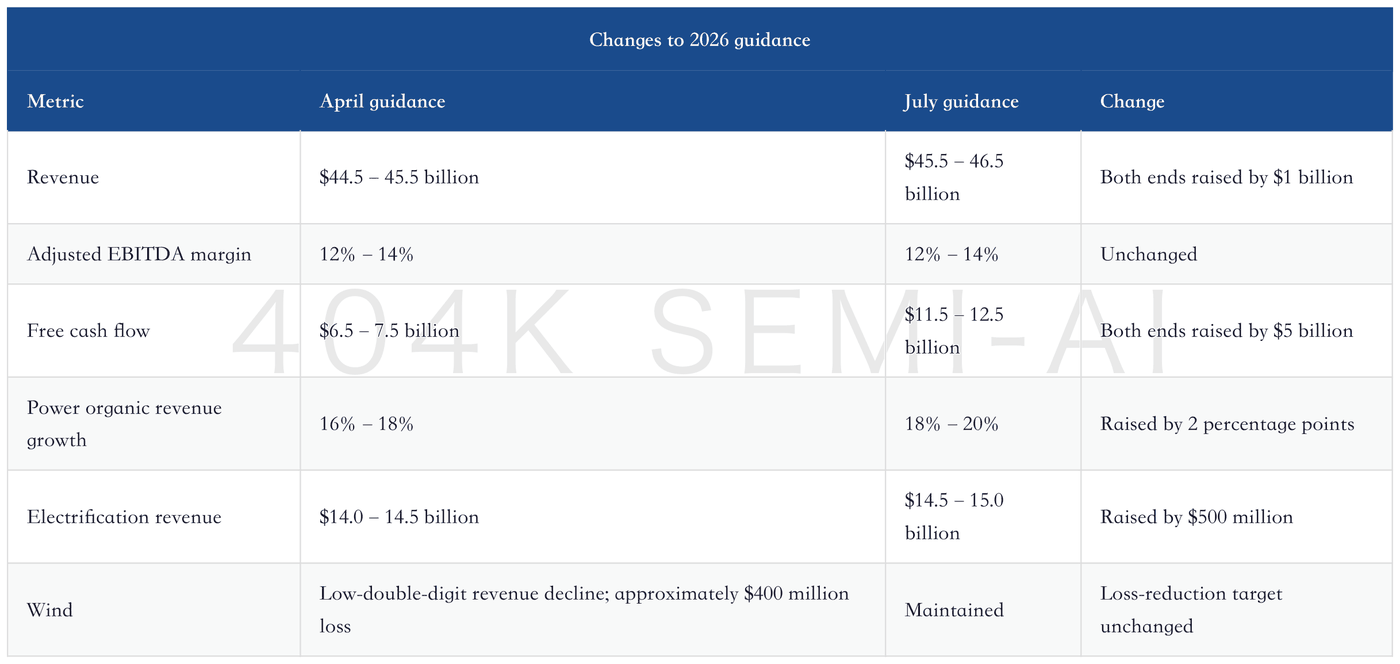
The $46 billion revenue midpoint and 13% margin midpoint imply approximately $5.98 billion in full-year adjusted EBITDA. The company generated $2.146 billion in the first half, leaving approximately $3.834 billion required in the second half, or an average of $1.917 billion per quarter—approximately 53% above the second quarter’s $1.25 billion. This is not formal quarterly guidance, but a simple bridge to test what is required to achieve the full-year target.
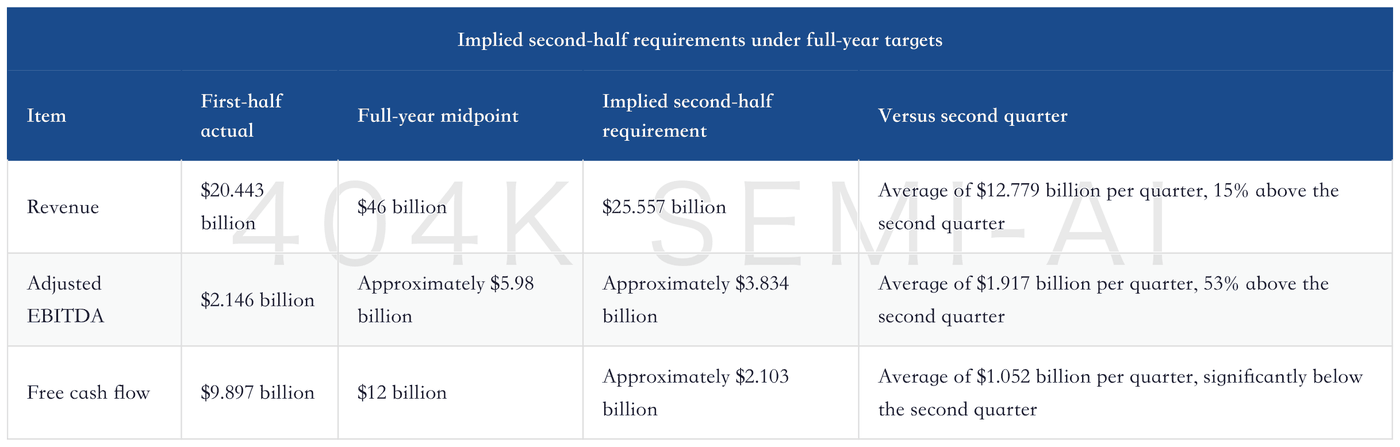
This creates the most important second-half combination: “earnings up, cash down.” Accelerating Power and Electrification equipment deliveries should drive revenue and EBITDA, while Wind needs to turn profitable. Meanwhile, earlier prepayments have already been collected, and production and delivery will consume working capital. Lower second-half free cash flow therefore does not automatically indicate operating deterioration; it may instead signal that backlog is beginning to convert.
The genuinely dangerous combination would be a failure of revenue to accelerate, continued inventory growth, and a marked slowdown in contract-liability growth. That would indicate fewer new prepayments while existing orders are also failing to convert smoothly into revenue. Conversely, if revenue and EBITDA rise as planned and inventories subsequently decline, even a normalization of free cash flow would indicate that cash is transitioning from “customer prepayments” to “project profits.”
8. Prolec GE and Capital Allocation: Ample Net Cash, but Both M&A; and Buybacks Raise Execution Requirements
The Prolec GE acquisition adds transformer capacity to Electrification while creating significant accounting and cash-flow distortions. The company paid approximately $5.254 billion in cash for the remaining 50% stake and preliminarily recognized approximately $5.313 billion of goodwill and $4.172 billion of intangible assets. The remeasurement of the previously held stake generated a $3.992 billion pretax gain, sharply increasing first-half net income without representing cash operating profit.
Prolec GE generated $859 million in second-quarter revenue and a $57 million pretax loss. The loss included the amortization of the inventory fair-value step-up, intangible-asset amortization, and integration costs, and therefore does not directly represent the business’s normalized earnings capacity. However, future amortization, capacity investment, and integration expenses will continue to flow through the financial statements. The acquisition’s success should be assessed through Electrification’s organic margin, delivery lead times, conversion of equipment backlog, and returns on capital—not the remeasurement gain.
Period-end cash stood at $13.12 billion, with total borrowings of approximately $2.794 billion, leaving net cash above $10 billion. The company also had $6 billion of total credit facilities, all undrawn at period-end. S&P; rated the company BBB with a positive outlook, while Fitch rated it BBB+ with a positive outlook. The balance sheet is sufficient to support capacity expansion, R&D;, and acquisition integration.
The company repurchased approximately 4.27 million shares for $3.645 billion in the first half, at an average price of approximately $854; in the second quarter, it repurchased 2.467 million shares for $2.35 billion, at an average price of $952.47. At the end of June, $3.037 billion remained under the $10 billion repurchase authorization. Buybacks reduce the share count and can improve per-share metrics, but they draw from the same pool of cash as capacity expansion, R&D;, and acquisitions.
The capital-allocation debate is not whether the company has sufficient cash, but how that cash should be prioritized. From 2025 through 2028, the company plans to invest a cumulative $6 billion in capital expenditures and $5 billion in R&D;, while gas turbines and Electrification remain capacity-constrained. If substantial buybacks do not impair capacity, quality, or deliveries, reducing the share count can amplify future earnings. If the supply chain and factories require more investment, repurchasing shares at high prices will reduce the company’s flexibility to absorb execution shortfalls.
9. What Has Changed Since Q1—and What Has Not
The biggest change is the cash flow baseline. The company raised its 2026 free cash flow guidance to $6.5 billion–$7.5 billion in Q1, then raised it again to $11.5 billion–$12.5 billion in Q2. Nearly all of the additional $5 billion comes from stronger customer advances and working capital performance, rather than higher margin guidance. Any analysis of GE Vernova must therefore separate operating profit growth from the cash timing benefit of customer financing.
Secured gas turbine demand increased from 100 GW to 116 GW, further improving demand visibility. At the end of Q1, firm backlog stood at 44 GW and reserved slots at 56 GW; these increased to 53 GW and 63 GW, respectively, in Q2. The company also raised its year-end target from at least 110 GW to at least 125 GW. The change is not that the market suddenly embraced another data center narrative, but that customers continue to secure equipment through contracts and payments.
The margin outlook for Electrification has strengthened. With the acquisition only recently completed in Q1, it was difficult to distinguish Prolec GE consolidation effects from improvement in the legacy business. In Q2, organic revenue grew 29% and organic margin expanded by 700 basis points, indicating that the legacy grid equipment business is also benefiting from pricing, volume growth, and efficiency gains. Accelerating switchgear deliveries in 2027 provide a timing anchor for the next phase of revenue growth.
What has not changed is the risk in Wind. The segment lost $382 million in Q1 and another $275 million in Q2. Management did not lower its full-year loss target of approximately $400 million; instead, it concentrated more of the expected improvement in the second half. If Wind cannot progress quarter by quarter from near breakeven to positive earnings, it will be the largest potential shortfall versus the midpoint of full-year adjusted EBITDA guidance.
Execution also remains more important than demand. The current order book is already sufficient to support growth; the real constraints are gas turbine and grid equipment capacity, together with project management capabilities. Continued order growth is clearly positive, but from this point forward the market should place greater weight on on-time delivery, stable quality, margin discipline, and inventory reduction—not simply reward a larger backlog.
10. Six Numbers to Watch
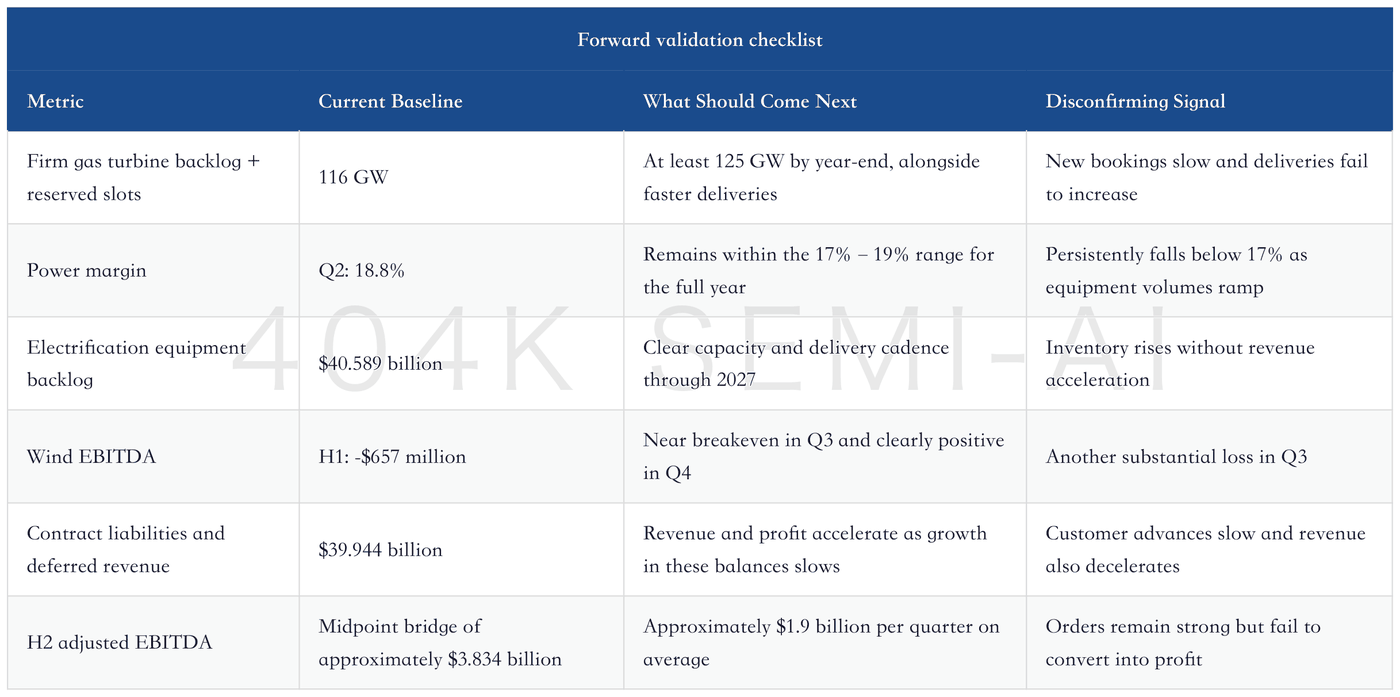
This earnings report supports a clear operating conclusion: GE Vernova is in a multiyear power equipment expansion cycle, with Power and Electrification converting orders into higher revenue and margins. Quarterly orders of $24.2 billion, remaining performance obligations of $176.3 billion, and 116 GW of secured gas turbine demand make future growth more visible than it was a year ago.
However, the $12 billion free cash flow guidance should not be mechanically interpreted as a new permanent level of cash earnings. Nearly $9.9 billion of free cash flow in the first half was driven primarily by customer advances, and cash flow will naturally decline as orders convert into equipment deliveries. The source of long-term value is not the advances themselves, but whether the company can use those funds to expand capacity and convert equipment backlog into high-margin revenue and longer-duration service contracts.
Power and Electrification have provided a positive answer; Wind has not yet done so. If Wind approaches breakeven in Q3, adjusted EBITDA accelerates materially in the second half, and inventory and contract liabilities show a normal delivery pattern, this report could mark the transition from an “order story” to realized earnings. If Wind continues to lose money, deliveries fall short of plan, or margins are pressured by equipment mix and capacity-expansion costs, the large order book will instead amplify execution risk.
The research focus from here should therefore be conversion efficiency, not further speculation about the ceiling for demand. The order book is already large enough. GE Vernova’s ability to manufacture on schedule, deliver at contracted pricing, control project costs, turn Wind profitable, and retain sustainable free cash flow after customer advances normalize will determine how far this growth cycle can ultimately run.