
From GPUs to Fabs: How an $860 Billion Cloud Budget Turns into $237 Billion of WFE
目录
TL;DR
1. After a 13%-15% Pullback, the Market Now Wants Earnings Revisions to Materialize
2. How $860 Billion of Cloud CapEx Turns into $237 Billion of WFE
III. WFE to Grow for Three Consecutive Years, with Incremental Demand from Capacity and Process Intensity
IV. TSMC N2/N3 Leads First, While DRAM Greenfield Fabs Determine the 2027 Slope
V. KLA, Lam Research, Applied Materials, and MKS Instruments Have Different Earnings Levers
VI. Smartphone, PC, and Auto Demand Will Determine Whether WFE Upgrades Can Carry Through the Cycle
VII. 2H26 Pricing Conclusion: Strong Equipment Totals, Returns Concentrated in Process Positioning
VIII. Institutional Differences and Peer Ranking: NAND Timing and Profit Conversion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
JPMorgan anchors its 2H26 semiconductor view in a longer capex chain: data-center budgets at the four largest U.S. cloud providers rising to $860 billion in 2027, and the wafer fab equipment market approaching $237 billion in 2028. The winners among equipment stocks will be determined by order visibility, process intensity, and margin delivery, while end-market weakness in consumer devices provides the counter-evidence.
TL;DR
The equipment cycle has already extended. JPMorgan expects the global wafer fab equipment market to rise from $124 billion in 2025 to $237 billion in 2028, sustaining double-digit growth for three consecutive years. Equipment demand is coming from both new cleanrooms and the higher step count required by GAA, backside power delivery, advanced packaging, and other process changes. The next variables to watch are whether equipment lead times, backlogs, and customer capex can extend in tandem.
Cloud budgets are flowing through to fabs. Data-center capex at the four largest U.S. cloud providers is expected to increase from $575 billion in 2026 to $860 billion in 2027, while AI accelerator shipments rise from 16.3 million units to 23.3 million units over the same period. Compute procurement first tightens advanced nodes, HBM, and packaging, then drives capacity additions at TSMC and memory manufacturers. Whether 2027 cloud budgets continue to be revised upward is the first hurdle for the WFE forecast to be realized.
Memory expansion determines the slope for equipment. JPMorgan estimates aggregate DRAM capex of about $368 billion in 2026-2028, with industry monthly capacity increasing by 829,000 wafers by end-2028. NAND capex over the same period is expected to be about $85 billion, adding 155,000 wafers of monthly capacity. DRAM is prioritizing greenfield fabs, while NAND is prioritizing layer-count migration, which means Lam Research and Applied Materials will not see the same order cadence.
Process intensity matters more than wafer count. GAA transistors, backside power delivery, high-layer-count 3D NAND, and advanced packaging increase etch, deposition, metrology, and inspection steps. The same wafer output requires more equipment time. KLA benefits from higher process-control intensity, Lam Research from etch and deposition, Applied Materials from DRAM and materials engineering, and MKS Instruments feels component inventory build earlier.
A quarterly beat is not the main issue. JPMorgan’s 2Q26 revenue forecasts for Applied Materials, KLA, and Lam Research remain slightly below consensus, while its 3Q view is only beginning to improve. This shows that the current pricing depends on 2027-2028 order visibility. Equipment stocks are already trading at about 30-54x 2026E P/E. If order revisions do not flow into revenue and margins, valuations will come under pressure first.
Consumer demand is the clear counter-evidence. JPMorgan expects 2026 smartphone and PC shipments to fall by about 11% and 9%, respectively, and global light-vehicle production to decline by about 1.8%-2.4%. If memory price increases further pressure end-market shipments, returns on memory capacity expansion and equipment orders may both be reassessed. Investors therefore need to track cloud capex, DRAM prices, equipment lead times, industrial orders, and consumer-electronics shipments at the same time.
1. After a 13%-15% Pullback, the Market Now Wants Earnings Revisions to Materialize
JPMorgan’s 2H26 view rests on continued upward earnings revisions, not a simple rebound in share prices. Over the past two earnings seasons, excluding memory, forward EPS estimates for semiconductor and equipment companies have already been raised by 20%-40%; 95% of covered companies saw positive earnings revisions for 1Q26. The sector’s 13%-15% pullback ahead of earnings did reduce near-term crowding, but whether valuations can hold still depends on the next round of estimate revisions moving higher.
Compared with the industry preview from early July, this report adds a stronger layer of manufacturing-side evidence. The market had already seen DRAM price increases, analog chip price hikes, and long-term WFE revisions. JPMorgan goes further by laying out a coherent path for 2027 cloud capex, accelerator shipments, TSMC capex, and memory monthly capacity. The demand side and manufacturing side are starting to use the same order of magnitude, giving the equipment cycle verifiable intermediate variables.
U.S. Semiconductor 2Q26 Preview: DRAM Price Hikes, Analog Price Hikes, and the $250 Billion WFE Validation Window
JPMorgan’s 2Q forecasts are actually restrained. Revenue and EPS for Applied Materials, KLA, and Lam Research are all close to or slightly below consensus. Divergence only begins to appear in 3Q, with KLA and Lam Research improving while Applied Materials remains close to consensus. Equipment stocks currently look more like a test of forward order validation; a small single-quarter beat is unlikely to support elevated valuations on its own.
U.S. Semiconductor Equipment Companies: 2Q26 and 3Q26 Revenue Estimate Differences
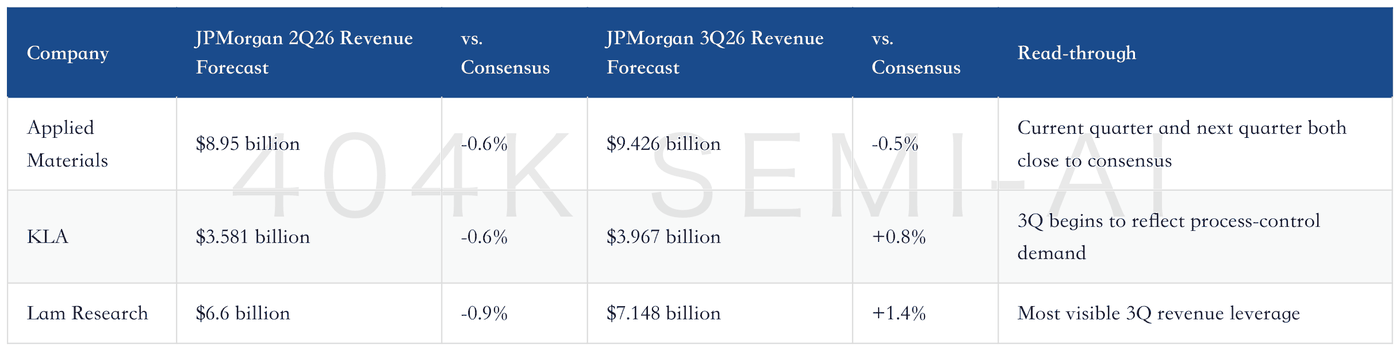
The differences in the table are modest. On the earnings calls, order duration, delivery lead times, and 2027 customer budgets will be more informative than a few tenths of a point of 2Q revenue upside.
2. How $860 Billion of Cloud CapEx Turns into $237 Billion of WFE
Cloud capex does not directly equal equipment revenue. It has to pass through accelerator procurement, wafer manufacturing, memory, networking, and advanced packaging. Capex at the four largest U.S. cloud providers is expected to rise to $860 billion in 2027, while AI accelerators increase to 23.3 million units over the same period. The annual path of budgets and shipments is checked in the table below.
The expansion of custom XPUs will broaden this chain. GPUs are expected to fall from 68% of total accelerator units in 2025 to 58% in 2026 and 47% in 2027, while ASIC/XPU share rises to 42% and 53%. More chip designs, more platforms, and more complex process mixes will simultaneously increase demand for EDA, advanced nodes, packaging, and testing. Equipment companies are facing a rising number of customer projects and technology road maps; volatility in a single accelerator platform no longer explains total WFE demand.
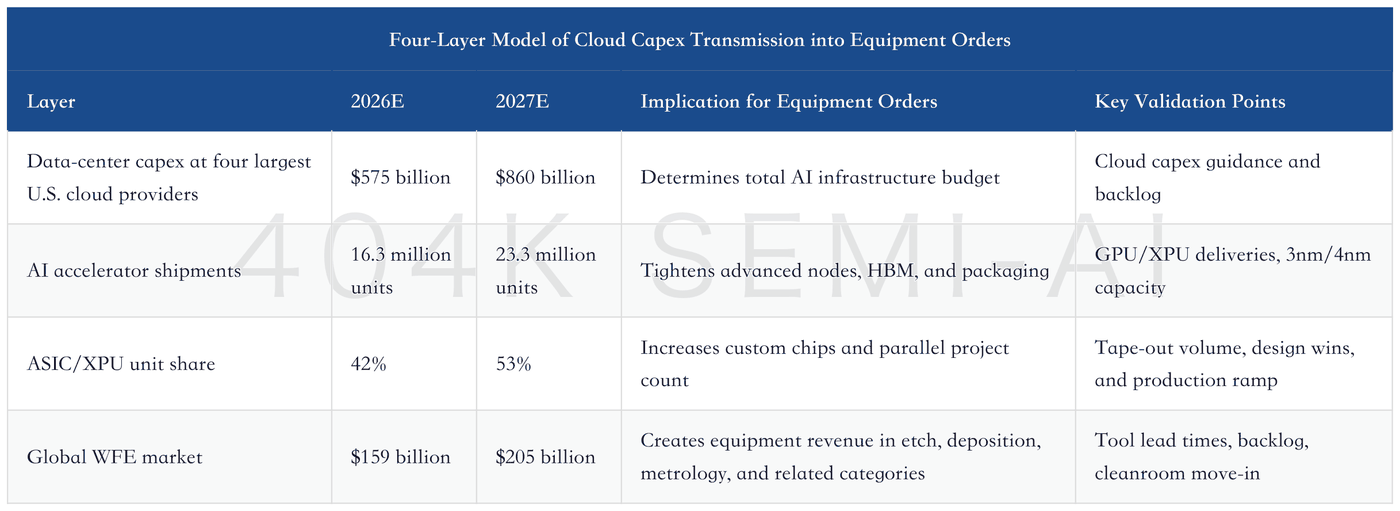
This transmission has a time lag. For the 2027 compute budgets cloud providers are confirming today, fabs need to lock in cleanrooms, critical equipment, and components in advance. JPMorgan’s May discussions with equipment companies showed that the 2H26 WFE environment was meaningfully stronger than 1H26, as customers competed for tool slots for future fabs. Front-loaded orders can allow equipment revenue to arrive before new capacity is fully ramped, but they also amplify volatility if customers delay projects.
The WFE Supercycle Is Just Beginning: How AI Capex Pushes Semiconductor Equipment Toward $250 Billion
III. WFE to Grow for Three Consecutive Years, with Incremental Demand from Capacity and Process Intensity
J.P. Morgan expects WFE to grow for three consecutive years, reaching US$205 billion in 2027 and rising further to US$237 billion in 2028. Citi’s mid-June 2028 scenario of US$250 billion points in the same direction, with the two institutions highly aligned on the length of the cycle.
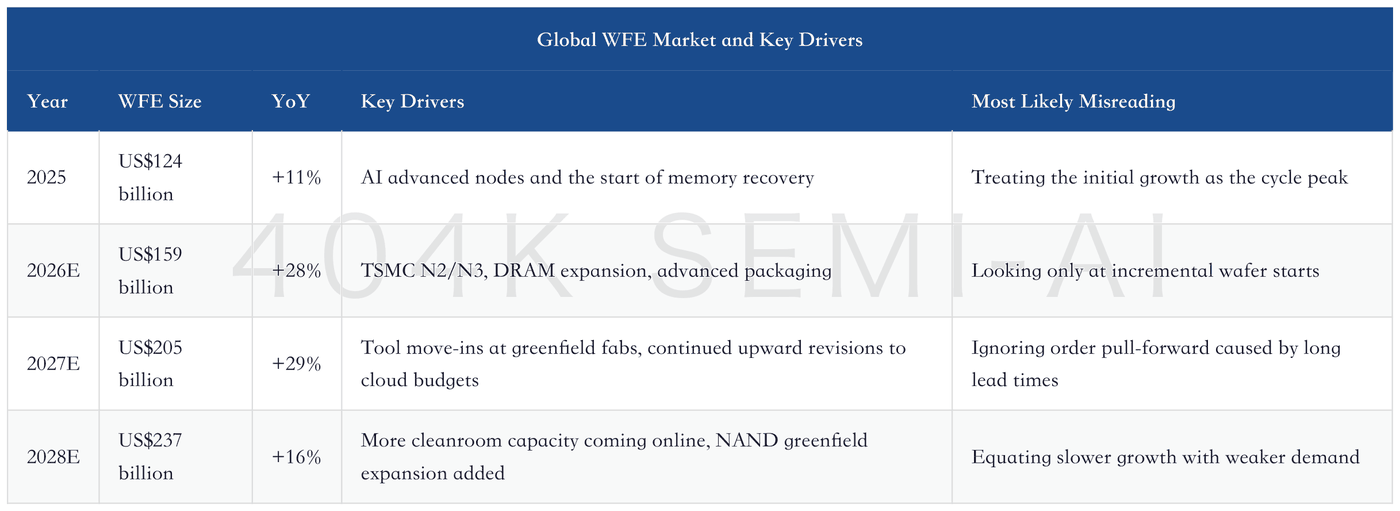
Capacity expansion explains the total size; process intensity explains why equipment revenue can grow faster than wafer volumes. GAA (gate-all-around transistors, used to improve advanced logic performance and energy efficiency; requiring more deposition, etch, and metrology steps), backside power delivery (moving the power delivery network to the wafer backside; adding new process and inspection steps), high-layer-count 3D NAND, and advanced packaging all increase the number of steps each wafer goes through. Even if monthly capacity is unchanged, equipment utilization time and the number of critical tools increase.
This kind of intensity increase changes company rankings. Metrology and inspection depend more on yield and defect control, giving process-control equipment more stable benefits. Etch and deposition are more sensitive to changes in layer count, structure, and materials, giving them higher cyclical elasticity. Component suppliers need to build inventory before main-tool shipments, so revenue recognition comes earlier. Total WFE is the shared backdrop; profit differences come from each company’s position in the process flow.
Equipment Capex Ledger Update: AI Financing, US$250 Billion WFE, and Semiconductor Equipment Repricing
IV. TSMC N2/N3 Leads First, While DRAM Greenfield Fabs Determine the 2027 Slope
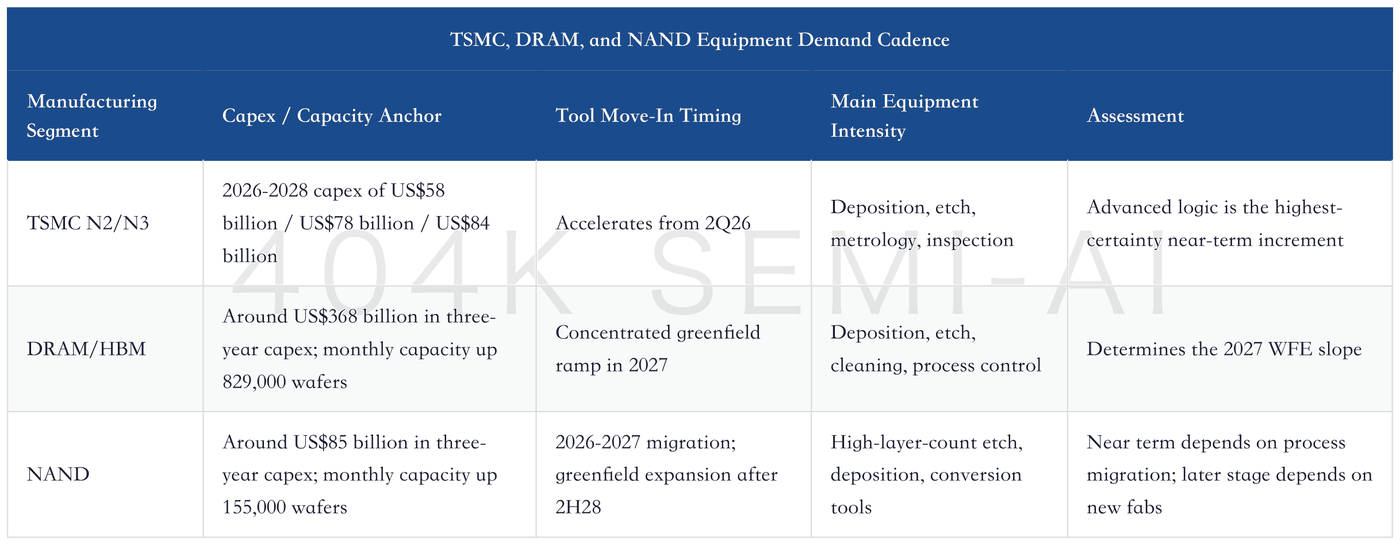
The largest variable on the foundry side is TSMC. J.P. Morgan raised its 2027 capex forecast from US$65 billion to US$78 billion, and its 2028 forecast from US$72 billion to US$84 billion. The increase is concentrated in N2/N3 advanced nodes and more aggressive equipment orders. TSMC will begin building multiple new fab shells in 1H26, with equipment procurement accelerating from 2Q26, directly supporting advanced logic WFE.
The memory-side scale is larger. J.P. Morgan expects the three major DRAM vendors to spend around US$368 billion in aggregate capex over 2026-2028, with DRAM monthly capacity rising to roughly 2.76 million wafers by the end of 2028, up 829,000 wafers from 1Q26. HBM capacity crowds out commodity DRAM wafers, while server CPUs and inference workloads lift commodity memory demand, giving memory makers an incentive to allocate more cleanroom capacity to DRAM first.
NAND follows a different cadence. In 2026-2027, demand is driven mainly by process migration and layer-count transitions, while greenfield expansion becomes visible only after 2H28. J.P. Morgan expects NAND capex of around US$85 billion over 2026-2028, with monthly capacity of roughly 1.44 million wafers by the end of 2028, up 155,000 wafers from 1Q26. Near-term equipment orders skew more toward layer-count upgrades; later on, incremental fab capacity drives total-volume elasticity.
From HBM to WFE: How AI Turns the Memory Cycle into an Equipment Supercycle, and How Much Longer Semiconductor Equipment Can Rise
V. KLA, Lam Research, Applied Materials, and MKS Instruments Have Different Earnings Levers
KLA (KLAC) captures process-control intensity. The more complex advanced logic, HBM, and advanced packaging become, the higher the cost of defects, and the more willing fabs are to add metrology and inspection. J.P. Morgan ranks KLA as its most preferred large-cap name in the equipment segment, but its 2026E P/E is around 53.5x, the highest among the four companies. High quality and high valuation coexist, and further upward revisions to orders and service revenue are needed.
Lam Research is more directly exposed to etch, deposition, and memory process migration. DRAM greenfield expansion, high-layer-count NAND, and GAA structures all increase etch and deposition steps. J.P. Morgan’s 3Q26 revenue forecast for Lam Research is 1.4% above consensus, the strongest among the three large U.S. equipment companies. Its 2026E P/E is around 50.5x, leaving both elasticity and valuation pressure elevated.
Applied Materials has the broadest coverage, with revenue contributions from DRAM expansion, materials engineering, advanced logic, and advanced packaging. Its 2Q and 3Q forecasts are still slightly below consensus, suggesting no clear near-term upside in the model. Its 2026E P/E is around 44.4x, below KLA and Lam Research. If the 2027 DRAM equipment mix and service revenue recognition accelerate, earnings revisions will matter more than single-quarter orders.
MKS Instruments (MKSI) sits upstream of main equipment. RF power, vacuum, and critical subsystems usually need to be stocked before full-tool delivery. J.P. Morgan believes it will benefit earlier from new fab construction. Its 2026E P/E is around 30.2x, well below the three large equipment vendors, but smaller scale, customer concentration, and the component cycle bring higher volatility.
