
目录
TL;DR
I. An Overseas X Sentiment Report: Where Is the Market Weakening?
II. July 10–16: Overseas X Was Almost Unanimously Bullish
III. July 17–23: The Market Weakened First as Sentiment Shifted from Chasing Gains to Rotation
IV. July 24–30: Positive News Stopped Working as Memory and Semiconductor Stocks Reached Their Weakest Point
V. July 31–August 6: The Rebound Did Not Restore Broad-Based Bullishness
VI. August 7–9: International X’s Verdict on the Current Market
VII. Why Continued Strength in HBM and DRAM Does Not Mean the Market Is Healthy
VIII. What Would Escalate a Weak Market into an Industry Bear Case?
IX. Six Developments to Watch Over the Next 1 Month
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Over the past month, overseas sentiment on X toward memory and semiconductors has cooled markedly. As the market weakened and positive news stopped lifting stocks, the debate shifted from broad-based bullishness to scrutiny of valuations, earnings momentum, and incremental supply.
TL;DR
The broader memory and semiconductor rally has weakened, and overseas X sentiment has shifted from broadly bullish to cautious and slightly bearish. In mid-July, the dominant narrative was that AI demand, rising memory prices, foundry activity, and equipment orders were all improving. By early August, even strong results or raised guidance did not necessarily lift share prices, and the debate had shifted to whether valuations already discounted too much.
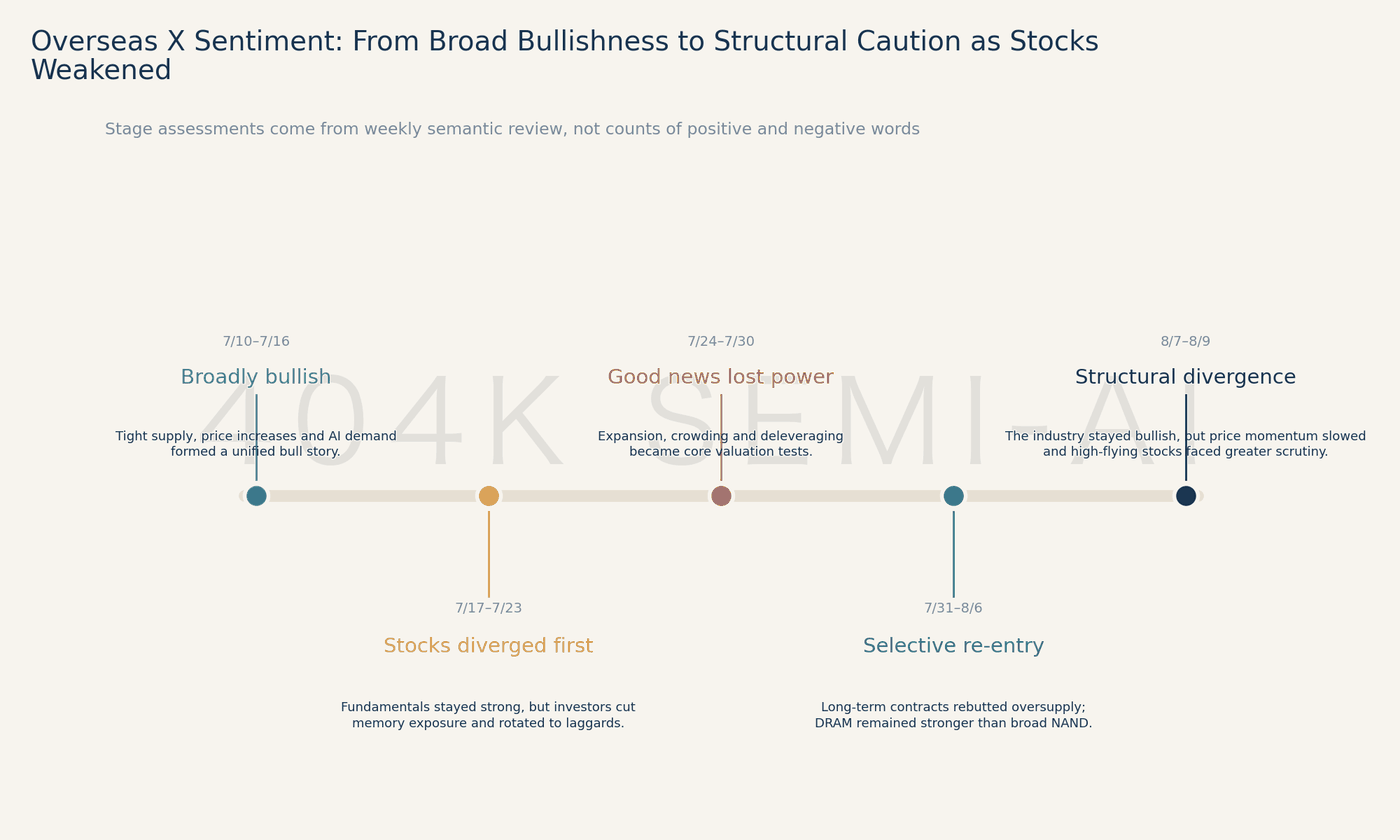
The sentiment shift unfolded in five stages: broad-based bullishness, rotation away from crowded winners, positive-news fatigue, selective re-entry, and valuation skepticism. The transition took nearly one month. Investors first reduced exposure to high-flying stocks, then reassessed earnings momentum, supply responses, and returns on capital expenditure.
Weak equity performance must now be distinguished from pockets of continued industry strength. Overseas X is cautious on memory and semiconductor stocks broadly, while selective bullish consensus remains around demand and long-term contracts for HBM, commodity DRAM, and enterprise SSDs.
The weaker market is evident in four ways. Strong results no longer drive share-price gains; price targets for high-flying memory leaders have been cut and positions reduced; momentum and leveraged trades are unwinding; and capital is shifting from broad semiconductor beta toward a small group of companies with long-term contracts and cash flow.
Performance dispersion is widening across NAND and the semiconductor value chain. Enterprise SSDs are stronger than consumer storage, while advanced packaging and some critical equipment segments are outperforming generic capacity-expansion themes. Analog, power, and mature-node markets still await a recovery in end demand.
The evidence has not yet justified upgrading a “weak market” call to a bearish industry-cycle view. A full industry-cycle reversal would require spot and contract prices to decline together, long-term contracts to loosen, customer returns on capital expenditure to deteriorate, effective supply to grow faster than demand, and both inventories and free cash flow to worsen.
I. An Overseas X Sentiment Report: Where Is the Market Weakening?
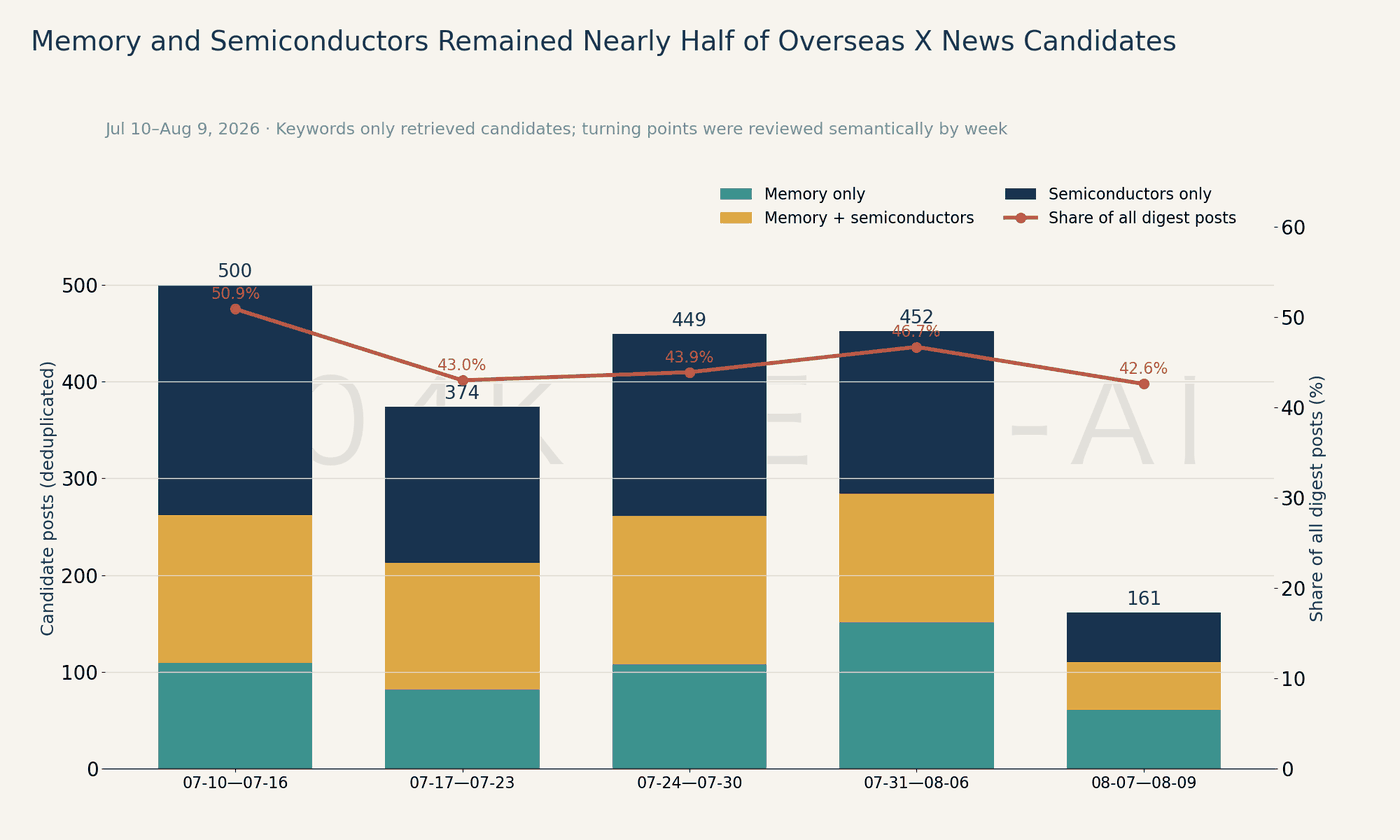
This analysis covers July 10 to August 9, 2026, Beijing time. The formal X news digests contained 4,589 records, or 4,222 after deduplication by post ID. Chinese- and English-language keyword searches covering memory, HBM, DRAM, NAND, SSDs, foundries, semiconductor equipment, and advanced packaging retrieved 1,936 candidates, which were then reviewed semantically by week. These candidates represented 42.6%—50.9% of all weekly digest posts, indicating that memory and semiconductors remained central themes in overseas social-media discussions throughout the period.
This report tracks changes in market attitudes on overseas X over time. Keywords were used only to retrieve material; sentiment was assessed from the full semantic context. For example, “the market is concerned about oversupply, but long-term contracts have already rebutted the risk of a near-term supply shock” contains both negative language and a positive conclusion, which a mechanical regex approach would misclassify. Each week’s views were therefore separated into four layers—industry fundamentals, earnings momentum, equity valuations, and positioning—to determine which had weakened.
Overseas X provides clear behavioral evidence of the market’s deterioration. First, some companies’ strong results and raised guidance failed to lift their shares. Second, high-flying memory leaders and semiconductor momentum names saw positions cut. Third, deleveraging and the unwinding of crowded trades became important explanations for market declines. Fourth, investors no longer accepted that every company in the AI value chain should rally; they demanded concrete delivery on long-term contracts, market share, margins, and free cash flow. Together, these changes indicate that the broader equity market had weakened and, at least temporarily, lost the upside momentum previously driven by narrative and valuation expansion.
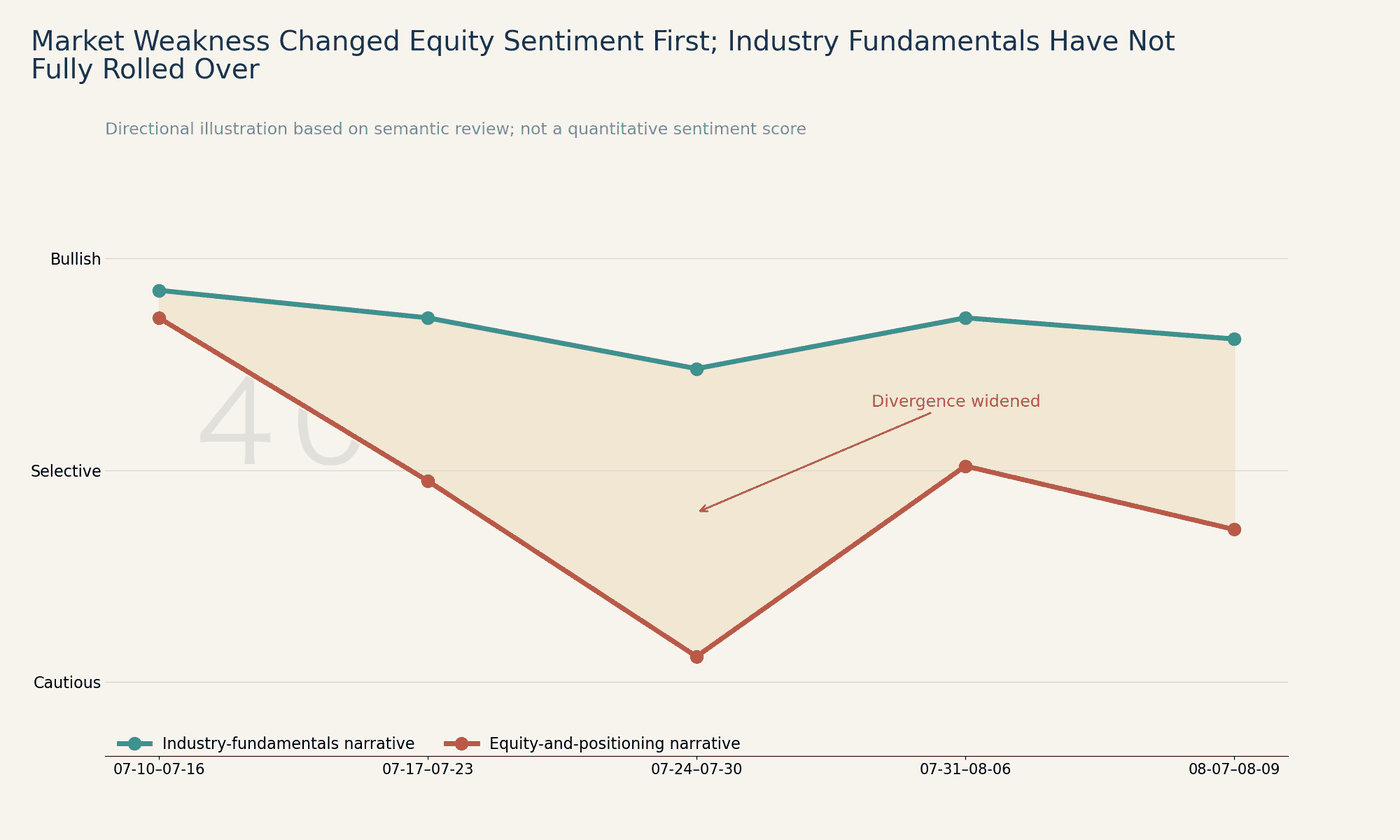
Weak equity performance, however, does not mean that all industry data have simultaneously turned bearish. HBM and high-end DRAM remain constrained by capacity, yields, advanced packaging, and customer qualification, while enterprise SSDs continue to benefit from the data-throughput requirements of AI clusters. What has truly changed on overseas X is confidence in share-price upside: the market still believes pockets of demand remain, but increasingly doubts whether higher expectations can continue to support elevated valuations.
II. July 10–16: Overseas X Was Almost Unanimously Bullish
The first week of the sample period came closest to broad-based bullishness. Overseas X repeatedly argued that memory shortages would persist, HBM capacity had already been locked in by customers, cloud capital expenditure would continue to rise, foundry utilization was improving, and equipment and advanced packaging would benefit. Demand, supply, pricing, profits, and equity valuations were treated as a single upward chain: expanding AI clusters increased per-system HBM and system-memory content; advanced nodes and HBM consumed more wafer and packaging capacity; supply could not respond quickly; and long-term contracts and prepayments improved order visibility.
The market’s implicit judgment was straightforward: the shortage was credible, earnings would rise, and share prices should follow. Bullishness was not limited to HBM. Commodity DRAM, NAND, foundries, equipment, and advanced packaging were also included in the broader semiconductor beta trade. As long as AI capital-expenditure forecasts kept rising, investors tended to extrapolate the benefits across the entire value chain.
Cracks had already emerged, but they did not yet dominate the market. A small number of posts warned that HBM product mix, the pace of price increases, and next-generation product ramps might slow subsequent profit improvement. Others discussed the pressure of rising memory prices on margins and shipment volumes for end products such as smartphones and PCs. These views were generally accompanied by statements that the long-term thesis remained intact or by unchanged positive ratings, suggesting that the risks were still treated as earnings details rather than core constraints on equity positioning.
III. July 17–23: The Market Weakened First as Sentiment Shifted from Chasing Gains to Rotation
The second week produced the first clear divergence. Overseas X still endorsed the outlook for AI capital expenditure and memory supply-demand conditions, but began recommending reduced exposure to memory leaders that had already risen sharply and rotation into assembly and testing, substrates, testing equipment, and other segments that had yet to be fully priced in. Sentiment did not immediately turn bearish, but the trading approach had already shifted from chasing gains to avoiding expensive winners and rotating elsewhere.
DRAM export unit prices, bottlenecks in HBM and commodity DRAM, foundry orders, and the equipment market had not suddenly deteriorated. Yet pullbacks in semiconductor indices and high-beta stocks were increasingly attributed to crowded positioning and deleveraging. Earlier tracking of crowded semiconductor positioning had already indicated that extreme positioning reduces the marginal impact of positive news. Fundamental investors saw tight supply and demand, while traders saw that “everyone already knows.” When incremental buying is insufficient, even a correct industry thesis may not generate short-term equity returns.
Analog, power, industrial, and automotive chips had also not joined the AI upcycle, and related companies were still awaiting inventory normalization and a recovery in end demand. This further weakened the case for buying the entire semiconductor sector. By the end of the second week, the overseas X view had become more conditional: remain bullish on the industry direction, but assess crowding before buying the stocks; capital expenditure may keep growing, but companies must prove that orders can translate into profits.
IV. July 24–30: Positive News Stopped Working as Memory and Semiconductor Stocks Reached Their Weakest Point
The third week marked the low point for equity sentiment during the sample period. Overseas X still featured extensive commentary that “memory is expensive and scarce,” “DRAM and enterprise SSD prices continue to rise,” and “long-term contracts improve visibility.” Yet the equity market was no longer willing to pay broadly higher prices for such news. Equipment companies could report strong results or raise their outlooks and still see their shares fall if margins were no longer expanding. Chip companies could beat revenue expectations and still be sold off because capital expenditure was rising and free cash flow was under pressure.
“Positive news stopped working” captured the shift in sentiment better than an ordinary correction. The standard had changed from whether a company was growing to whether growth could justify its valuation and investment intensity. Orders, price increases, and capital-expenditure announcements that had previously supported share-price gains could now only prevent rapid earnings downgrades; they were no longer sufficient to drive further valuation expansion. Overseas X therefore shifted from debating market direction to examining how much future profit was already priced into each company.
Supply responses also re-entered valuation models. Reports that Samsung Electronics was increasing DRAM output, new-fab construction was advancing, and potential new entrants might intensify competition prompted investors to ask when incremental capacity would become effective supply. Capacity-expansion announcements do not immediately translate into marketable bits, but they can still reduce the premium investors are willing to pay for future scarcity.
Sharp declines among leading Asian memory and semiconductor stocks were also widely attributed to the unwinding of leverage and momentum trades. Earlier analysis of deleveraging in the South Korean equity market showed that leveraged products and crowded positioning can amplify selling pressure. That pressure does not prove that end-customer orders have disappeared, but it leaves high-flying stocks with no margin for error: earnings must repeatedly exceed already elevated expectations if existing valuations are to hold.
The conclusion for this week was clear: the broader memory and semiconductor market had indeed weakened. What was being compressed was the broad-based rally thesis, positioning, and valuation premiums; industry demand had not yet collapsed in parallel. Precisely because fundamentals did not immediately turn bearish, the overseas X debate shifted from “does AI demand exist?” to “what valuation is that demand worth?”
V. July 31–August 6: The Rebound Did Not Restore Broad-Based Bullishness
The fourth week brought a recovery, with accelerating cloud growth, upward revisions to capital expenditure, and reports that major suppliers’ capacity had been locked in reviving bullish confidence. Long-term agreements, customer bookings, and sold-out capacity were cited to challenge the view that oversupply in 2027 is inevitable. International commentary on X again acknowledged that effective advanced-memory supply depends on equipment availability, yields, packaging, and customer qualification—not merely announced fab capacity.
The rebound, however, was clearly selective. Investors focused more on shipment value, product mix, and pricing than on bit growth alone. Enterprise SSDs were viewed as a relative bright spot within NAND, while signals from consumer products and raw NAND wafer prices were more mixed. Our previous tracking of the divergence between NAND and SSDs also showed that enterprise SSD strength cannot automatically be extrapolated to all NAND products.
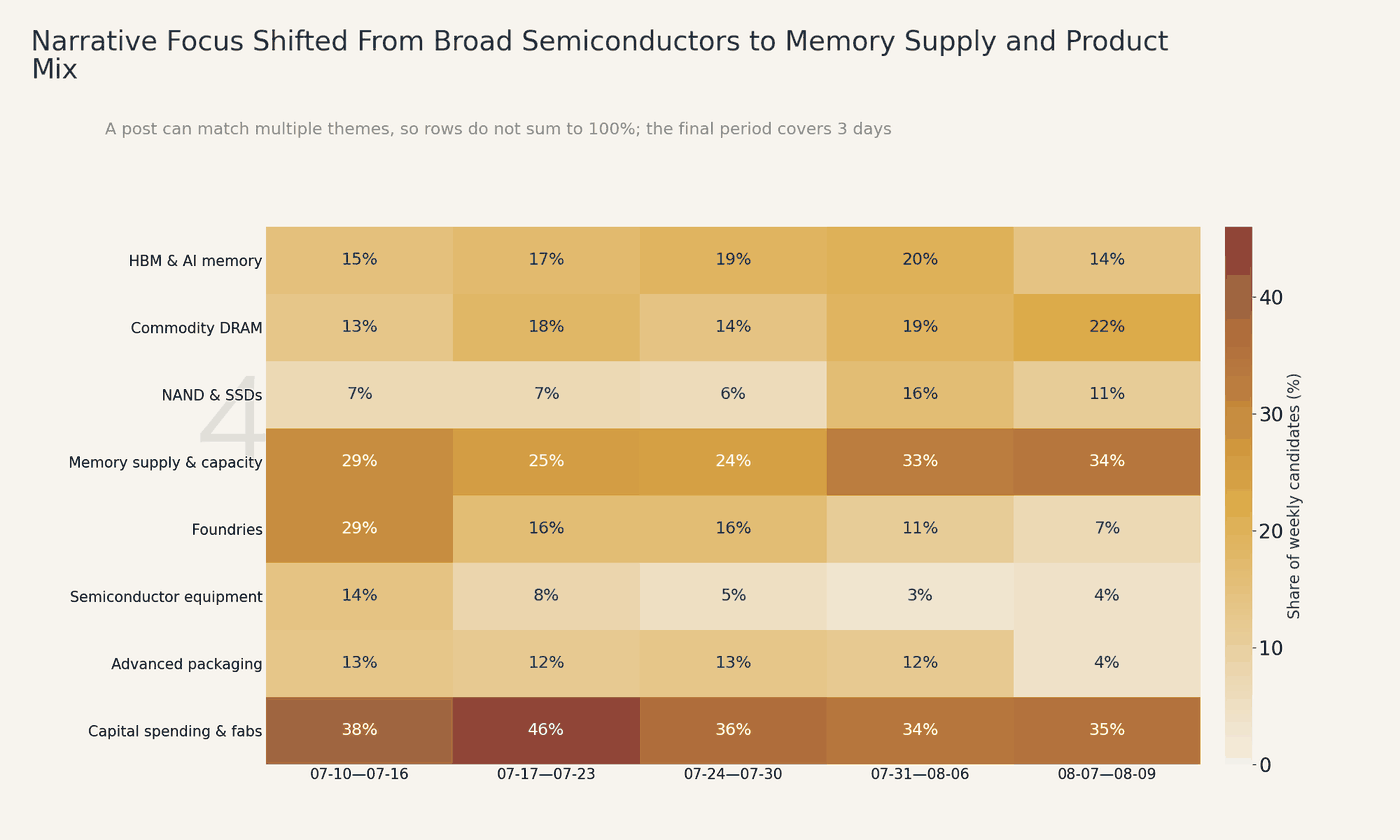
The heat map shows that from July 31 to August 6, memory supply and capacity accounted for 33% of candidate discussions, HBM and AI memory for 20%, commodity DRAM for 19%, and NAND and SSDs for 16%. The debate is shifting from “semiconductors benefit broadly” to “which products, supplied by whom, and monetized at what margin.” The rebound demonstrated that the industry bull case retains support, but it did not restore broadly bullish equity sentiment.
VI. August 7–9: International X’s Verdict on the Current Market
Although the final 3 days did not constitute a full week, they clearly captured the prevailing view. One side continued to emphasize AI-server memory demand, locked-in capacity for HBM and high-end DRAM, and memory’s rising share of system value. The other focused increasingly on slowing DRAM and NAND price increases, an approaching earnings peak, price-target cuts, and the need to incorporate future supply additions into long-term valuations.
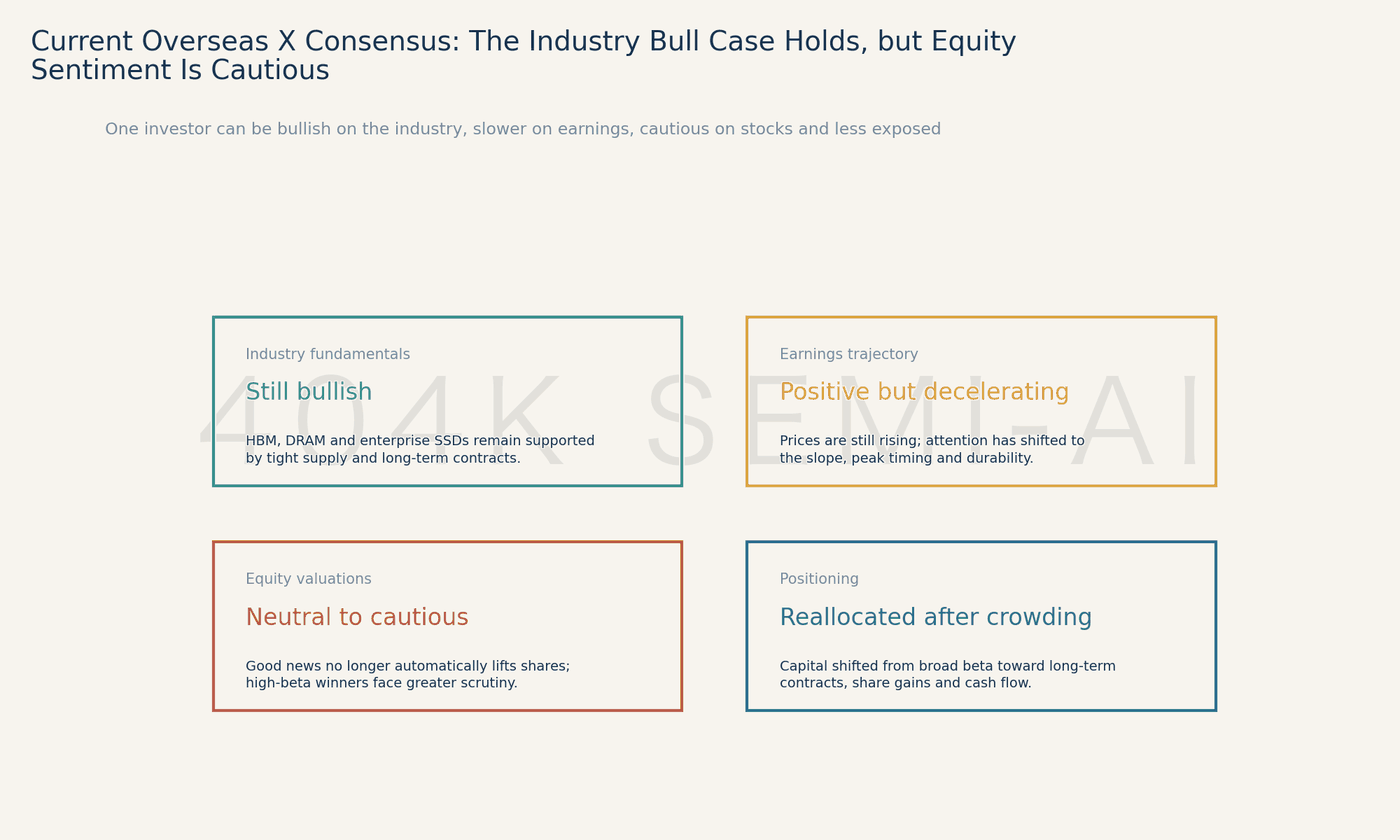
The view on the broader equity market is cautious and somewhat bearish. Good news no longer automatically drives share prices higher. Companies with the greatest operating leverage, strongest prior gains, and fullest expectations are being scrutinized first. The market is unwilling to continue paying a uniform premium for the entire memory and semiconductor sector.
The view on industry fundamentals remains selectively bullish. Bottlenecks in HBM, commodity DRAM, and enterprise SSDs continue to be supported by long-term agreements, customer qualification, and cloud capital expenditure. That support, however, cannot be extrapolated to all NAND products, every equipment company, or all mature-node capacity.
The earnings trajectory remains positive but is decelerating. Prices can continue rising even as the pace of increase slows. International X is beginning to ask when earnings will peak, how product mix will evolve, and how long high margins can persist—not merely whether earnings will grow next quarter.
Positioning is being reallocated after crowded trades unwind. Capital is rotating away from broad beta toward companies with greater long-term contract coverage, rising market share, clear customer qualification, disciplined capital expenditure, and improving free cash flow. The consensus is clear: this is no longer a market in which everything rises, but a comprehensive industry bear case has not yet formed.
VII. Why Continued Strength in HBM and DRAM Does Not Mean the Market Is Healthy
HBM and high-end DRAM remain the areas of strongest industry consensus. AI servers increase memory content per system, while advanced processes, yields, advanced packaging, and customer qualification create multiple constraints. Signed long-term agreements also make part of suppliers’ revenue more visible than in a traditional spot-driven cycle. These factors are sufficient to support orders and earnings for leading suppliers, but not necessarily further share-price appreciation, as valuations may already reflect the next 2 years of tight supply and market-share gains.
Enterprise SSDs form the second tier. Data throughput and storage requirements from AI training and inference provide a source of growth distinct from consumer electronics. However, enterprise SSD strength does not represent all NAND categories. Broad NAND and consumer storage still face uncertainty over end-market affordability, wafer pricing, and incremental supply. Excessively rapid price increases may even squeeze component budgets for smartphones and personal computers.
Foundries, semiconductor equipment, and advanced packaging are also no longer ranked uniformly. AI bottlenecks continue to support advanced nodes, advanced packaging, and certain critical equipment categories, but the equipment-order peak, returns on customer capital expenditure, and headroom for margin expansion will directly affect valuations. Mature nodes, analog semiconductors, and power semiconductors depend more heavily on a genuine recovery in industrial, automotive, and consumer demand.
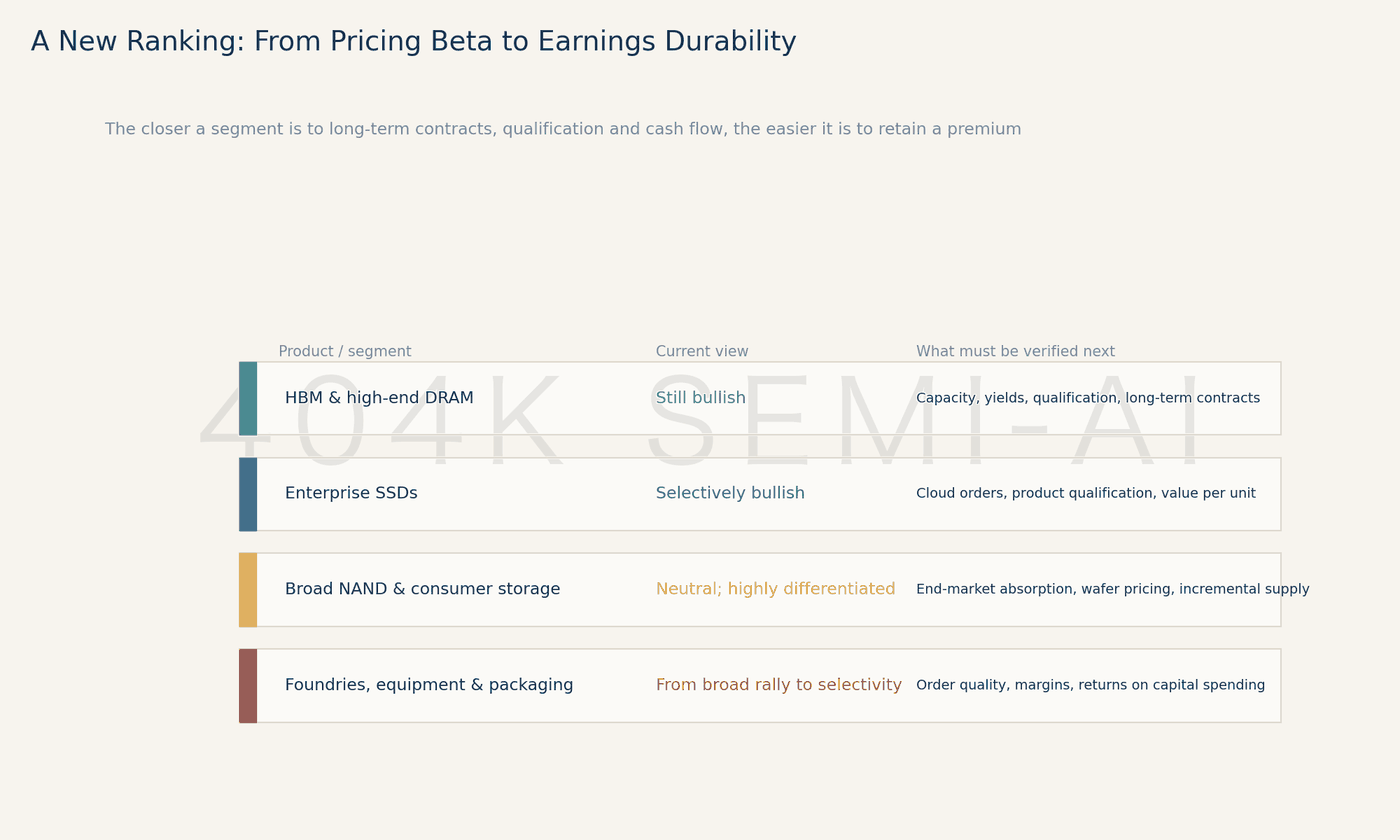
International X is now comparing the durability of earnings rather than their current absolute level. Micron is more akin to a high-beta cyclical and pricing vehicle, leaving it exposed to both the slope of price increases and valuation multiples. SK hynix commands a higher-quality premium through its HBM share, customer relationships, and long-term agreements, although elevated expectations also magnify execution shortfalls. Samsung Electronics combines scale advantages in DRAM and NAND with the complexity of broad end-market exposure, capital expenditure, and product mix. Even if industry data are favorable for all 3 companies, their shares may perform very differently.
VIII. What Would Escalate a Weak Market into an Industry Bear Case?
First, spot and contract prices would need to decline outright at the same time. A slowdown in quarterly price increases from elevated levels indicates only slower earnings growth. Only a sustained deterioration in actual transaction prices would signal a material shift in supply and demand.
Second, long-term agreements and customer commitments would need to weaken. Cancellations, volume reductions, delays, renegotiations, or lower prepayments provide stronger evidence of softening demand than ordinary forecasts. If major capacity remains contractually covered, incremental supply will have limited near-term pricing impact.
Third, customer capital expenditure would fail to translate into supplier revenue and cash flow. Rising investment by cloud providers does not guarantee that every supplier will benefit. Cluster utilization, customer revenue, order quality, and cash collection must also be assessed.
Fourth, effective supply would expand faster than demand. Announced fab construction alone is insufficient evidence for a bear case. Supply truly exceeds demand only if equipment installation, yield ramp-up, packaging capacity, customer qualification, and saleable bit output all increase—and ultimately shorten lead times and create pricing pressure.
Fifth, inventories, receivables, and free cash flow would deteriorate together. If revenue continues growing while inventories accumulate, receivable periods lengthen, capital expenditure rises, and free cash flow declines, earnings quality would genuinely worsen.
The clearest negative evidence currently consists of weaker share-price performance, a possible slowdown in price increases, and the need to reprice future supply into valuations. Long-term agreements, AI demand, and tight high-end product supply remain countervailing evidence. Equity sentiment has therefore turned cautious, but a comprehensive industry bear case has not yet formed.
IX. Six Developments to Watch Over the Next 1 Month
First, monitor whether customer agreements for HBM and commodity DRAM continue to lengthen, particularly regarding 2027 capacity coverage and prepayment arrangements. Second, distinguish enterprise SSD pricing from raw NAND wafer pricing to avoid allowing a single average price to obscure product mix. Third, assess whether capacity-expansion announcements actually progress to equipment move-in, yield ramp-up, and customer qualification. Fourth, after cloud providers raise capital-expenditure plans, verify whether supplier orders, revenue, and cash flow materialize in parallel. Fifth, track semiconductor share-price reactions to good news; if earnings beats still trigger broad declines, the unwinding of crowded positioning and valuation excess has not yet ended. Sixth, compare leading companies’ free cash flow, buybacks, and capital-expenditure discipline to determine whether earnings represent a cyclical peak or have gained durability through longer contract terms.
The conclusion is that sentiment on international X has shifted from broad-based bullishness to valuation skepticism. The market is now better characterized as “selectively bullish industry fundamentals, a weak overall market, and equities that must continue validating expectations through earnings.” This is no longer a phase in which buying the entire memory and semiconductor sector reliably generates returns.
HBM, commodity DRAM, and enterprise SSDs remain the core industry bull themes; NAND must be assessed by product category. Semiconductor stocks at elevated valuations need earnings upgrades to absorb those valuations, while broad semiconductor beta must again demonstrate customer returns and free-cash-flow delivery. The most important question ahead is whether strong fundamentals can restore positive share-price reactions. The mere volume of bullish language on social media has no analytical value.