
目录
Executive Summary
I. After the Record High, the Question Is No Longer Whether Earnings Exist, but Whether They Can Carry Through to 2027
II. Earnings Are Real, but 2 Large Valuation Gains Must First Be Removed from the 47.4% Headline
III. Market Breadth Is Improving, but SPY’s Performance Is Still Determined by a Handful of Mega-Caps
IV. Current Prices Are Not Merely Discounting 2026—they Have Already Begun Discounting 2027
V. Why AI Capex Can Lift Index Earnings Before the Return Cycle Is Complete
VI. Three Paths Will Determine Whether the New High Marks the Start of an Earnings Cycle, a Valuation Plateau, or Overextended Expectations
VII. The 6 “Delivery Rate” Indicators Most Worth Tracking After the New High
1. Adjusted Earnings Delivery Rate
2. Revenue-to-Cash-Flow Conversion Rate
3. 2027 Earnings Revision Rate
4. Alignment Between Price Breadth and Earnings Breadth
5. AI Capital-Expenditure Coverage Rate
6. Discount-Rate Stability
VIII. Conclusion: This New High Has an Earnings Foundation, but the Market Has Already Priced In Part of the 2027 Outcome
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The S&P; 500 Index, tracked by SPY, closed at a record 7,736.52 on August 4. The earnings acceleration is real, but one-off valuation gains, index concentration, and the delayed depreciation impact of capital spending mean the new high cannot yet be equated with realized AI returns.
Executive Summary
This rally has genuine earnings support. As of July 31, blended Q2 earnings for the S&P; 500 were up 47.4% year over year; excluding Google’s and Amazon’s substantial investment valuation gains, growth was still 28.8%. Revenue rose 14.1%, with all 11 sectors posting growth, providing a broader earnings foundation than a rally driven solely by a handful of AI stocks.
But the headline 47.4% growth rate cannot be extrapolated. Investment valuation gains of approximately $98 billion at Google and $53.4 billion at Amazon materially boosted index earnings and margins. These gains increase current-period net income but do not prove that enterprise customers are generating sustainable cash returns from AI applications.
Improving breadth and rising index concentration can coexist. The equal-weight index and Russell 2000 have outperformed at times, indicating broader capital rotation; however, SPY’s top 10 securities still account for 38.01%, while information technology represents 36.65%. Broader participation does not eliminate the decisive influence of a few mega-cap companies on index earnings and valuation.
At 7,736.52, the market is already pricing in 2027 earnings. Based on Goldman Sachs’ and JPMorgan’s publicly disclosed forecast of $385 in S&P; 500 EPS for 2027, the index trades at approximately 20.1x. On 2026 estimates of $330–340, the multiple is 22.8–23.4x. Further gains depend on continued upward revisions to 2027 earnings—not merely one quarter of Q2 outperformance.
Realized earnings provide the floor; 2027 expectations define the ceiling. Current evidence is insufficient either to confirm a systemic market top or to declare that the AI investment-return cycle has closed. The real dividing lines are whether adjusted earnings can hold up, AI revenue and free cash flow can catch up with capital expenditure, market breadth can persist, and the 10-year Treasury yield and credit spreads remain stable.
I. After the Record High, the Question Is No Longer Whether Earnings Exist, but Whether They Can Carry Through to 2027
On August 4, the S&P; 500 rose 1.8% to 7,736.52; the Nasdaq Composite gained 2.6%, the Dow Jones Industrial Average 1.7%, and the Russell 2000 1.8%. As of that date, the S&P; 500, Nasdaq Composite, and Russell 2000 were up approximately 13%, 14.4%, and 22.4%, respectively, year to date. Lower oil prices, a decline in the 10-year Treasury yield from 4.70% to 4.62%, and strong earnings jointly lifted risk assets.
This performance matters because it changes the starting point of the debate. From 2025 into early 2026, investors focused primarily on whether AI capital spending was excessive and whether macro interest rates would compress valuations. The latest record high provides a provisional answer: corporate earnings have not only withstood elevated rates but accelerated. Yet prices lead financial statements. The index is no longer trading on what occurred in Q2, but on whether the current earnings trajectory can extend through 2027.
Assessing whether the record high is healthy requires reconciling at least 3 sets of accounts.
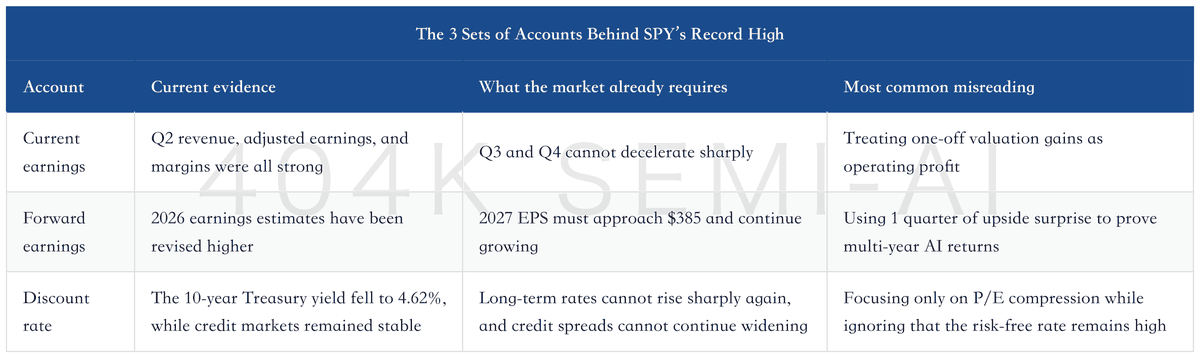
The record high is therefore neither evidence of a bubble in itself nor proof that returns have been realized. It simply shows that the market is willing to capitalize higher future earnings into today’s prices. The next question is whether those future earnings will come from recurring operating revenue—or from one-off accounting gains, front-loaded capital expenditure, and sustained valuation multiples.
II. Earnings Are Real, but 2 Large Valuation Gains Must First Be Removed from the 47.4% Headline
FactSet data as of July 31 showed that 61% of S&P; 500 constituents had reported Q2 results. Of those, 86% beat earnings expectations, above the 5-year average of 78% and the 10-year average of 76%; 77% exceeded revenue expectations, with aggregate revenue beating estimates by 2.9%. Blended Q2 revenue grew 14.1% year over year, with all 11 sectors expanding. Earnings rose in 10 of the 11 sectors, including double-digit growth in 8.
The strength is therefore multidimensional: a high share of companies beat expectations, revenue growth was broad, and sector participation was extensive. Even apart from AI, consumer, financial, industrial, and international businesses all contributed incremental growth. FactSet’s revenue-source analysis found that companies deriving more than 50% of revenue overseas delivered Q2 earnings growth of 74.7% and revenue growth of 20.5%. Excluding Google, Exxon Mobil, and Chevron, earnings and revenue still rose 27.5% and 16.0%, respectively. Outliers exist, but so does genuine growth beyond them.
The issue is that the headline 47.4% earnings growth rate includes 2 gains that cannot be annualized as normal operating profit: Google recognized approximately $98 billion in investment valuation gains, while Amazon recorded approximately $53.4 billion in pretax other income, primarily from the revaluation of its Anthropic investment. Amazon alone accounted for 76% of the net increase in aggregate S&P; 500 earnings over the preceding week. These gains are genuine accounting profits, but they are not cloud-service revenue, advertising revenue, or cash revenue from AI applications.
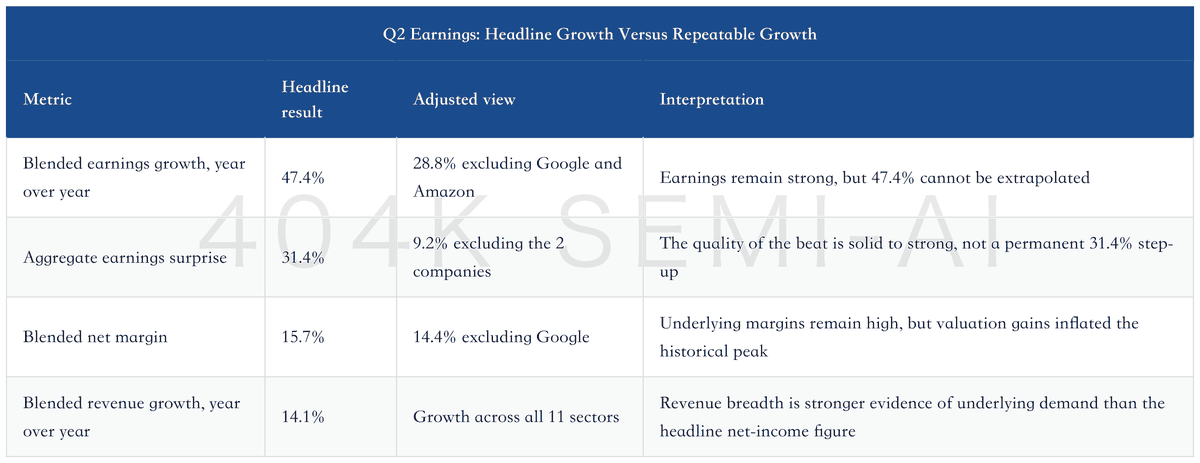
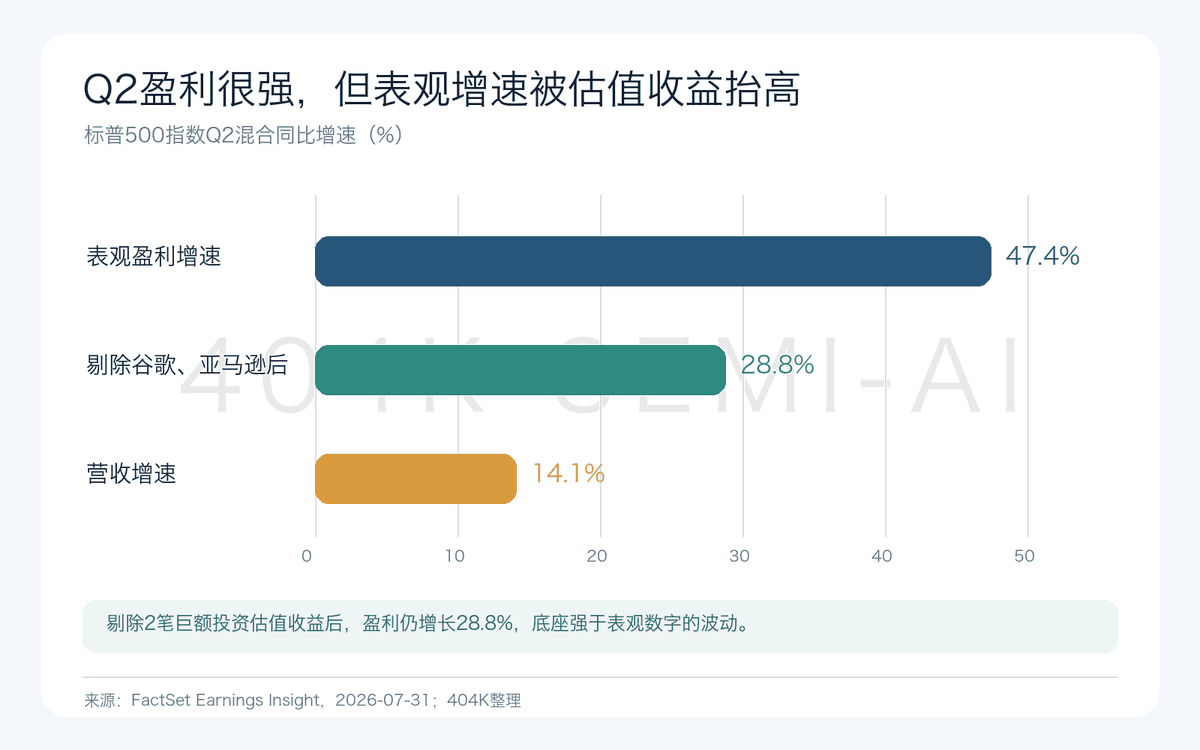
Earnings strength must be separated into layers. Layer 1 is revenue and operating profit, which can support sustained valuations. Layer 2 is appreciation in investment holdings, which can strengthen the balance sheet but may reverse as market prices fluctuate. Layer 3 is potential revenue from future AI projects, much of which has yet to enter the income statement. Conflating these 3 layers would simultaneously overstate current AI returns and understate underlying operating growth.
In other words, Q2 is sufficient to refute the claim that US equities have no earnings support, but not enough to prove that AI capital spending has already generated cash returns of comparable scale at the end-customer level. What the market needs over the next several quarters is for adjusted earnings to sustain near-double-digit or even above-20% growth without substantial investment valuation gains—and for that growth to be supported by both revenue and cash flow.
III. Market Breadth Is Improving, but SPY’s Performance Is Still Determined by a Handful of Mega-Caps
There are 2 competing narratives around the latest highs. One argues that the rally remains driven by a few technology giants and is therefore highly fragile; the other contends that outperformance by the equal-weight index and small caps shows that concentration is no longer a concern. Both capture part of the picture.
State Street’s SPY holdings as of August 3 show that the top 10 securities account for 38.01% of the fund. The 8 securities representing 7 companies—Nvidia, Apple, Microsoft, Amazon, Alphabet’s 2 share classes, Broadcom, and Meta—together account for 35.12%. Information technology carries a 36.65% weight, while communication services and consumer discretionary represent another 10.18% and 9.51%, respectively. Changes in the earnings, capital spending, and valuations of a few mega-cap technology companies therefore continue to have a direct, weight-driven impact on SPY’s direction.
Market breadth has nevertheless improved. The S&P; 500 Equal Weight Index assigns each company a weight of approximately 0.2% at quarterly rebalancing and was up 11.44% year to date as of July 24. CME’s Q2 review showed periods when the equal-weight index outperformed its market-cap-weighted counterpart, while the Russell 2000 also strengthened. By August 4, the Russell 2000 was up approximately 22.4% year to date, substantially outperforming the S&P; 500.
These 2 sets of data are not contradictory. Breadth measures how many stocks participate in a rally; concentration measures which stocks determine the index outcome. Gains across more sectors and small caps reduce the risk that earnings growth is confined to a few companies, but they do not change the mathematical reality that mega-cap technology stocks contribute more whenever SPY rises or falls by 1 percentage point.
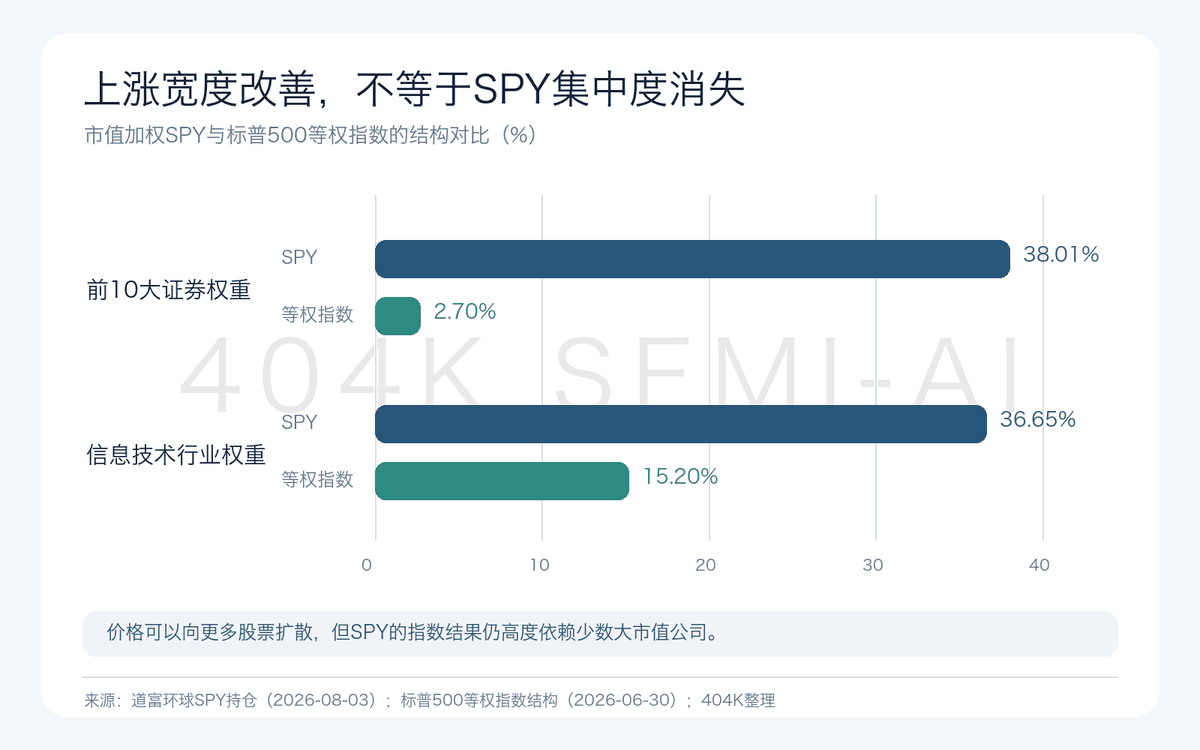
This explains why the current rally is healthier than a pure “Magnificent Seven” trade, even though valuation tolerance has not improved proportionately:
If the equal-weight index continues to outperform and earnings growth broadens, the market could remain elevated even through rotation within technology;
If technology giants meet earnings expectations while small- and mid-caps continue to recover, market returns will shift from a concentrated rally toward broader internal participation;
If mega-cap technology earnings are revised down simultaneously and the strength in equal-weight and small-cap indices proves to be only a short-term liquidity effect, SPY will still face significant pressure because of its weighting structure.
SPY’s new highs therefore cannot be assessed solely by counting advancing stocks or by examining the top 10 weights. The most useful signals are the relative performance of the equal-weight index versus SPY, the Russell 2000 versus the S&P; 500, and whether earnings expectations outside mega-cap technology are also being revised upward. Unless both “price breadth” and “earnings breadth” improve, broadening may amount to little more than valuation rotation.
IV. Current Prices Are Not Merely Discounting 2026—they Have Already Begun Discounting 2027
FactSet reported an S&P; 500 forward 12-month P/E of 19.6x on July 31, below 20.4x on June 30 and the 5-year average of 19.9x, but still above the 10-year average of 19.0x. The decline in the P/E does not mean the index became cheaper, because it occurred while earnings estimates were being revised sharply higher; the index then rose another 1.8% on August 4, pushing the price component forward again.
Interest rates matter even more. A 19.6x P/E implies a simple earnings yield of approximately 5.10%. Compared on a rough, static basis with the 4.62% yield on the 10-year U.S. Treasury on August 4, the spread is only approximately 0.48 percentage points. This is not a formal equity risk premium calculation, and the dates of the 2 data points do not align perfectly, but the comparison is sufficient to establish one point: with the risk-free rate still near 4.6%, equity valuations depend on earnings growth, rather than on low rates mechanically lifting multiples.
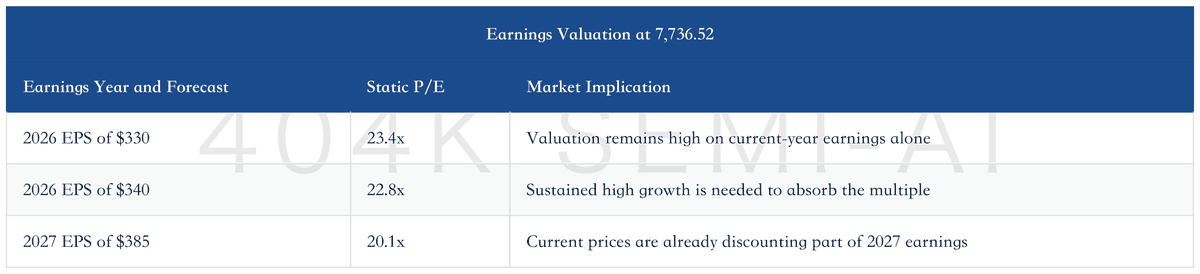
Goldman Sachs publicly forecasts S&P; 500 EPS of $340 and $385 for 2026 and 2027, respectively; JPMorgan forecasts $330 and $385. At a static index level of 7,736.52, current valuations already exhibit a clear cross-year profile.
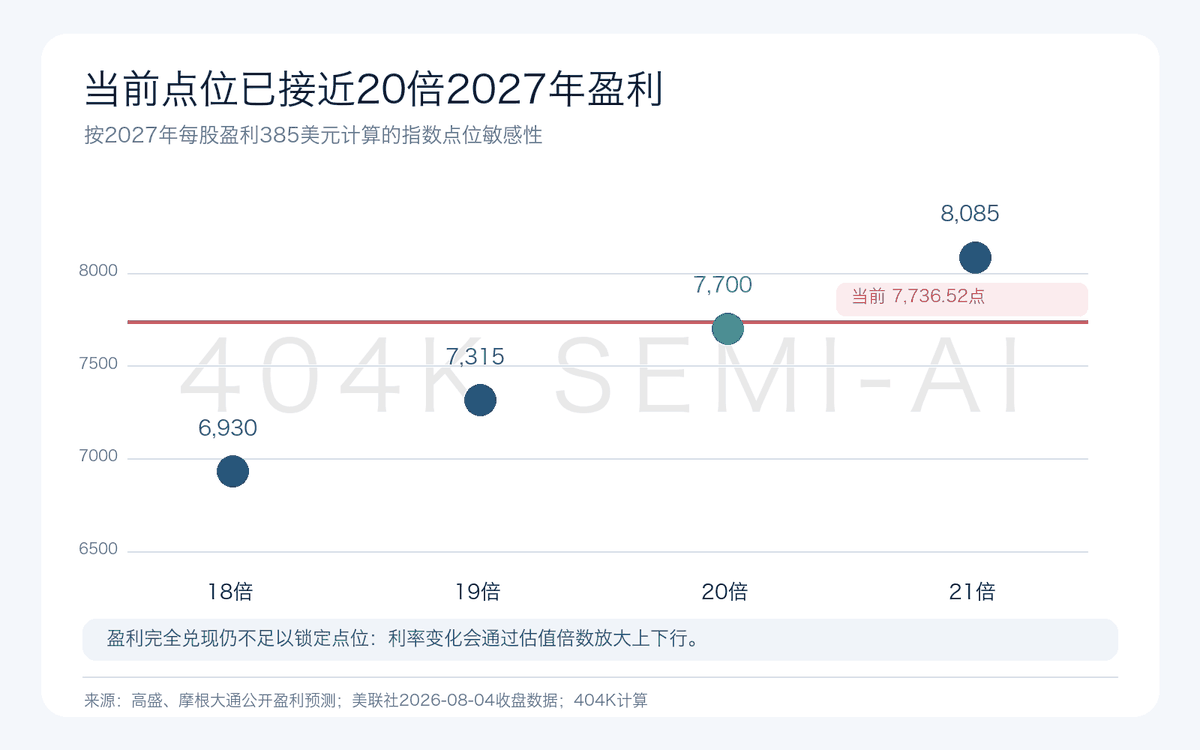
If 2027 EPS does reach $385, further index gains will depend on the P/E multiple investors are then willing to pay. An 18x multiple implies approximately 6,930, 19x implies approximately 7,315, 20x implies approximately 7,700, and 21x implies approximately 8,085. This is a mathematical sensitivity analysis, not an index forecast, but it reveals the binding constraint in current pricing: even if earnings forecasts are fully realized, the index could still fall below its current level if long-term rates rise or risk appetite weakens and the multiple contracts from 20x to 18-19x.
Conversely, if 2027 earnings estimates continue to rise, the 10-year Treasury yield declines, and credit spreads remain stable, current valuations need not mark the top. CME’s comparisons across historical cycles indicate that declining corporate profits, sustained widening in high-yield credit spreads, and rising volatility have typically been more reliable top signals than high valuation alone. Profits are still growing and credit spreads have not shown the sustained deterioration typical of a market peak, so “expensive” should not be treated as synonymous with “an imminent top.”
V. Why AI Capex Can Lift Index Earnings Before the Return Cycle Is Complete
Understanding the relationship between SPY’s new highs and returns on AI investment requires distinguishing the timing of revenue recognition across different parts of the value chain.
Suppliers of GPUs, networking equipment, power equipment, and data-center construction can recognize revenue relatively early after delivering products or services. Cloud providers and large platforms, by contrast, capitalize servers, data centers, and related infrastructure: cash is spent upfront, while depreciation enters expenses gradually over future years. Enterprise customers need even longer to move from model deployment to monetizable products, labor-cost savings, or higher sales conversion. Consequently, AI supply-chain revenue may enter index earnings first, while cash returns for AI buyers may not emerge until several quarters or even years later.
The previous report, Why Is the Return on AI Investment Still Contested When 2026 Capex at 9 Major Cloud Providers Is Expected to Grow by Approximately 90%?, examined this timing gap: 2026 capital expenditure at 9 major cloud providers is expected to exceed $886.7 billion, up approximately 90% year over year. Another sample of hyperscale cloud providers indicates that capital expenditure may grow by approximately 85% in 2026 and 45% in 2027, with capex reaching 107% and 113% of operating cash flow, respectively.
Capital expenditure exceeding operating cash flow does not automatically mean that the investment has failed. If contracted backlog, cloud-service demand, revenue per unit of compute, and customer renewal rates all rise in tandem, upfront spending can create long-lived assets and future cash flows. The issue is that when spending growth remains above operating-cash-flow growth for an extended period, companies must supplement funding with balance-sheet cash, debt, leases, or other financing arrangements, and the market will demand increasingly rapid evidence of returns.
This earnings season, investment valuation gains at Alphabet and Amazon added another layer of mismatch. These gains reflect appreciation in AI ecosystem assets, but they do not mean enterprise customers have already paid an equivalent amount of recurring revenue for AI services. Combining such gains with GPU sales, cloud-service revenue, improved advertising efficiency, and end-application subscription revenue makes “AI returns” appear to be progressing faster than the underlying cash flows.
For returns on AI investment to complete the cycle at the index level, at least 4 conversions must occur:
Infrastructure investment must become usable compute capacity, rather than remaining tied up in prolonged construction or underutilized assets;
Usable compute must translate into cloud-service, model-inference, and enterprise-software revenue, with price declines not outpacing usage growth;
Revenue must convert into operating profit and operating cash flow, without relying indefinitely on capitalized expenditure to obscure cash consumption;
Operating cash flow must cover incremental capital expenditure, interest, and shareholder returns, creating sustainable free cash flow.
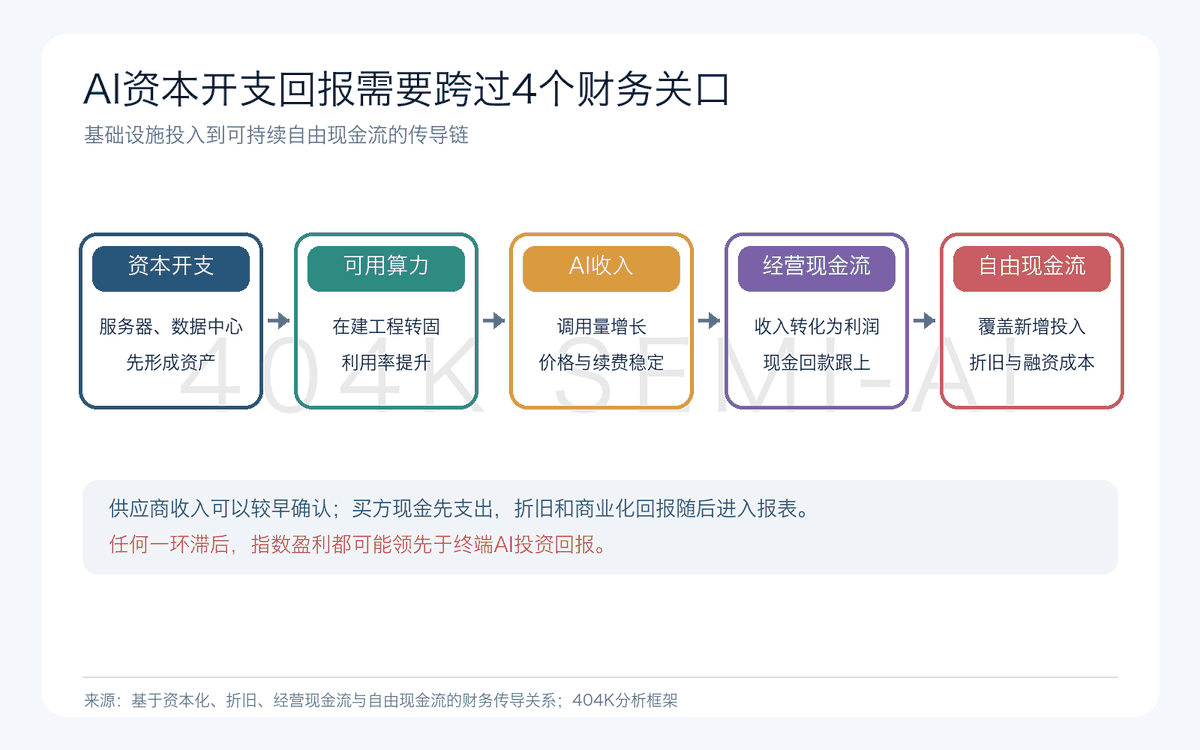
Only after all 4 steps have been completed can the market be said to be “realizing AI returns.” If the process reaches only steps 1 and 2, the index is closer to pricing future revenue in advance. The earlier report, The AI Trade Has Moved Ahead of the Macro Cycle: Recalibrating Compute Capex, Earnings Expectations, and Market Pricing, examined the disconnect between macro conditions and valuations. The implication after the latest highs is that the burden of proof has shifted from demonstrating that demand exists to demonstrating that cash returns are sufficient to cover the cost of capital.
VI. Three Paths Will Determine Whether the New High Marks the Start of an Earnings Cycle, a Valuation Plateau, or Overextended Expectations
Over the next 6-12 months, the market is more likely to rotate among 3 paths than settle into either of 2 simple outcomes: “keep rising” or “fall immediately.”
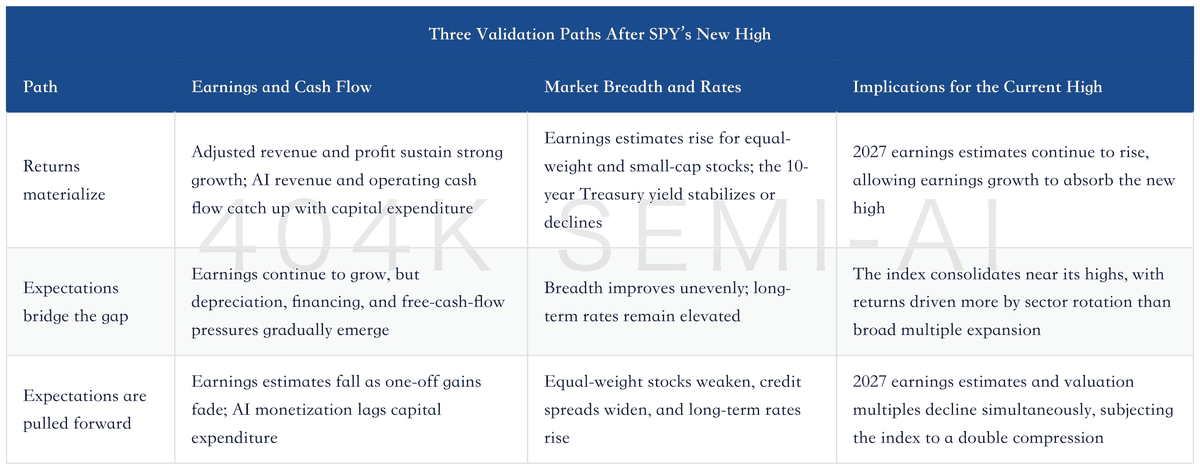
The first path depends on whether the marginal productivity of capital expenditure improves. If every additional $1 invested generates more cloud-service revenue, software-subscription revenue, or cost savings, the market will accept higher spending. If investment rises while unit compute pricing, utilization, and free cash flow continue to decline, revenue growth alone will struggle to prevent a valuation reset.
The second path may be the easiest to overlook. Earnings can continue to grow and the index need not fall sharply, but high interest rates and rising depreciation will limit multiple expansion. SPY could then trade around elevated levels for an extended period, with equal-weight, industrial, financial, or small-cap stocks taking turns leading. Within large-cap technology, performance would diverge with cash-flow quality. The AI thesis need not break; prices may simply be waiting for financial results to catch up.
The third path requires several pieces of evidence to emerge simultaneously. A single company missing expectations, 1 month of rising rates, or 1 index correction would not be enough. More telling signals would be sustained cuts to adjusted earnings estimates, persistently wider credit spreads, a reversal in market breadth, and capital expenditure remaining elevated without improvement in AI revenue or free cash flow. Only when earnings and multiples are cut together would concentrated index weights shift from upside amplifiers to downside transmission channels.
VII. The 6 “Delivery Rate” Indicators Most Worth Tracking After the New High
Daily index highs and pullbacks generate considerable noise. What truly distinguishes earnings delivery from overextended expectations is whether the following 6 groups of indicators move in the same direction.
1. Adjusted Earnings Delivery Rate
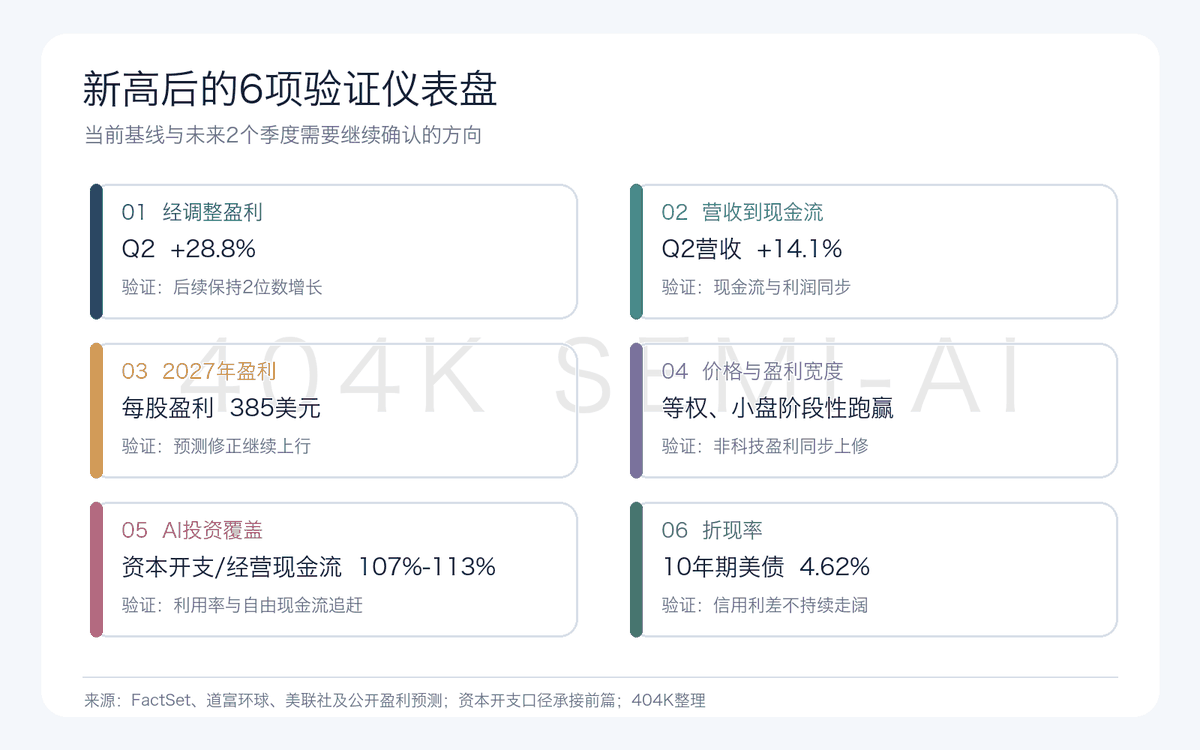
Continue tracking earnings growth and surprise margins after excluding gains from exceptionally large investment revaluations. Q2’s 28.8% adjusted growth and 9.2% adjusted upside surprise provide a more credible baseline. If Q3 and Q4 still deliver double-digit growth, the earnings foundation remains stable. If headline growth stays high while adjusted growth falls rapidly, the market may be overestimating its durability.
2. Revenue-to-Cash-Flow Conversion Rate
Revenue growth of 14.1% provides a better demand baseline than net-income growth of 47.4%. The next test is whether operating cash flow keeps pace with revenue and whether capital expenditure continues to squeeze free cash flow. If margin expansion reflects genuine operating leverage, cash flow should follow. If it comes primarily from valuation gains or capitalization treatments, the gap between cash flow and net income will widen.
3. 2027 Earnings Revision Rate
At the current level, the index trades at approximately 20.1x 2027 EPS of $385. The 2027 forecast is therefore a more important anchor than quarterly earnings in 2026. Key indicators include the number of analyst upgrades versus downgrades, whether sector contributions are broadening, and whether earnings growth remains excessively dependent on a handful of technology companies. Merely maintaining the $385 forecast is no longer sufficient to drive upside; further upgrades may be needed to offset high valuations and elevated interest rates.
4. Alignment Between Price Breadth and Earnings Breadth
Outperformance by the equal-weight index and the Russell 2000 versus SPY signals broader price participation. Genuine fundamental broadening requires earnings estimates for non-technology sectors to rise as well. If price breadth improves without earnings breadth, rotation may primarily reflect valuation recovery. Only if both improve together will the index’s dependence on a few technology giants materially decline.
5. AI Capital-Expenditure Coverage Rate
Track capital expenditure/operating cash flow, construction in progress, depreciation growth, cloud-service revenue, AI-related contracts, and free cash flow. Capital expenditure/operating cash flow remaining above 100% for an extended period is not immediately dangerous, but it requires faster future growth in revenue and cash flow. If construction in progress converts into productive assets while utilization and revenue rise in tandem, the front-loaded investment is justified. If depreciation rises without better utilization or unit revenue, return pressure will flow through the income statement.
6. Discount-Rate Stability
The 10-year Treasury yield, credit spreads, and volatility should be assessed together. If long-term rates are high but stable, earnings growth can still absorb elevated valuations. If rates rise while credit spreads widen, both the risk-free discount rate and risk premium increase, directly compressing multiples for long-duration technology stocks. A decline in the index is more consistent with ordinary valuation volatility only when earnings and credit conditions remain stable.
VIII. Conclusion: This New High Has an Earnings Foundation, but the Market Has Already Priced In Part of the 2027 Outcome
Taken together, earnings, breadth, index concentration, and valuation suggest that the market is best characterized as having “high valuations supported by genuine earnings, with future returns still awaiting validation.” Q2 operating results demonstrated that large US companies retain strong revenue- and profit-generating capacity: after excluding 2 exceptionally large valuation gains, S&P; 500 earnings still grew 28.8%; revenue growth spanned all 11 sectors; and the performance of equal-weight and small-cap stocks showed that participation was broadening.
However, prices are not paying only for earnings already realized. At 7,736.52, the index trades at approximately 22.8-23.4x 2026 earnings, or approximately 20.1x 2027 earnings. With the 10-year Treasury yield still at 4.62%, valuations lack a natural cushion for substantial expansion. Meanwhile, SPY’s top 10 securities account for 38.01%, AI capital expenditure is growing far faster than operating cash flow, and depreciation and financing pressures have not yet been fully reflected in future income statements.
The most accurate characterization of this new high is therefore: upward revisions to genuine earnings provide the foundation, while the market has also pulled forward part of the expected 2027 AI returns into current prices. Realized earnings are supported by financial-report evidence; the portion priced in ahead of delivery still requires proof from future cash flows.
If adjusted earnings continue to grow at a double-digit rate, 2027 EPS estimates keep rising, earnings broaden across equal-weight and small-cap stocks, AI revenue and free cash flow catch up with capital expenditure, and both long-term rates and credit spreads remain stable, future earnings will gradually absorb today’s new high. Conversely, if earnings revisions turn negative as one-off gains fade, capital expenditure/operating cash flow remains above 100% for an extended period, depreciation rises while monetization revenue lags, and credit spreads also widen, the market will cut both earnings estimates and valuation multiples.
Index levels reveal the price of the answer; financial statements determine its quality. After the new high, each round of earnings upgrades should be separated into 2 components: recurring revenue and cash flow, and 2027 expectations pulled forward into today’s price. The changing balance between them matters more than whether SPY immediately sets another record high.
Related Reading
Amazon Q2 2026 Deep Dive: AWS Growth Accelerates to 37%, AI Capex Pushes Free Cash Flow Negative