
Four Clocks in AI Hardware: Memory Peaks Without Collapsing in 4Q26, ABF Shortage in 2027, and the VR200 Capacitor Step-Up
目录
TL;DR
Four Clocks Are Closer to Reality Than a Broad-Based AI Hardware Rally
Cloud Capex Remains Strong, but Spending Must Ultimately Become Revenue
The Real Debate in Memory: Prices May Peak, but Can Earnings Stay Elevated for Two More Years?
Whether Long-Term Agreements Have Teeth Will Determine If Memory Can Be Valued Differently
HBM Remains Tight, but Demand Has Broadened from NVIDIA to Cloud ASICs
NAND’s New Demand Is More Tangible, but Its Supply Risk Is Also More Direct
Agentic AI Turns the CPU from a Supporting Player into a Traffic Controller
ABF’s 2027 Shortfall Will First Be Constrained by Materials and Effective Capacity
MLCC’s 180% Increment Comes from Power-Delivery Complexity, Not Simple Unit Growth
Companies and Segments Should Be Ranked by Their Earnings-Realization Clocks, Not Thematic Purity
Eight Numbers to Watch Over the Next 12 Months
Conclusion: AI Has Not Eliminated the Cycle—It Has Merely Made It More Granular
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This AI hardware cycle is not moving in lockstep: cloud spending remains strong, memory price growth is peaking first, ABF substrates move into shortage from 2027, and MLCCs are only beginning a specification-upgrade cycle.
TL;DR
AI hardware is running on four different clocks. Cloud service provider capex remains in a strong expansion phase; memory pricing and inventories are already approaching a cyclical inflection point; ABF substrates are in mid-cycle; and multilayer ceramic capacitors remain early-cycle. Investors’ biggest mistake is using “strong AI demand” to explain every company while ignoring that each segment converts demand into earnings on a different timeline.
Memory looks more like a peak than a collapse. Morgan Stanley expects DRAM contract prices to peak around 4Q26, while inventories are also recovering from low levels. However, 2027 high-bandwidth memory demand could still exceed output, with the combined supply-demand deficit reaching approximately 15% after including conventional DRAM. Slowing price gains and tight absolute supply-demand conditions can coexist.
Long-term agreements do not automatically trigger a valuation rerating. New-style agreements typically cover three to five years and include volume commitments, price floors, prepayments, or financial guarantees. Samsung Electronics and SK Hynix can justify a lower traditional cyclical discount only if contracts remain enforceable during price downturns and free cash flow translates into buybacks and dividends.
Agentic AI extends the bottleneck from GPUs to CPUs and memory. Complex tasks require planning, tool use, code execution, web access, and multi-agent coordination, materially increasing the orchestration workload handled by CPUs. Morgan Stanley’s bull case implies a CPU opportunity of up to $238 billion and incremental DRAM demand of 221EB by 2030, but this is only a stress test and must be validated against actual deployments and server configurations.
ABF substrates move into shortage from 2027, and the key issue is not nominal capacity expansion. The report expects the Ajinomoto Build-up Film substrate market to grow from $7.048 billion in 2025 to $19.181 billion in 2030, with a subsequent CAGR of approximately 22.2%. AI-related applications will account for more than 75%, while T-glass fiberglass shortages could persist through 2028. Materials, yields, customer qualifications, and effective capacity will determine who captures the profits.
VR200 turns multilayer ceramic capacitors from small components into direct beneficiaries of power-delivery specification upgrades. Content per rack rises from $1,530 for GB300 to $4,320, an increase of more than 180%, while the share of high-capacitance products rises from 18% to 31%. AI-server-related demand is expected to approach $893 million in 2027, with the five largest global vendors accounting for approximately 87%. The incremental value is more likely to accrue to leaders with advanced manufacturing processes and customer qualifications.
Four Clocks Are Closer to Reality Than a Broad-Based AI Hardware Rally
Morgan Stanley divides the same supply chain into different stages. This is more valuable than simply adding another set of bullish forecasts for AI hardware. Cloud capex is still rising, the year-on-year rate of change in memory prices has already begun to decline, ABF substrates will not move into a clearer shortage until 2027, and MLCC sales and earnings forecasts are only now showing an early inflection point. All benefit from AI, but they are not the same trade.
This is consistent with the previously established “system-density pricing” framework. In the prior phase, the market expanded its focus from GPUs alone to HBM, CPU-side memory, enterprise SSDs, PCBs, substrates, and passive components. The question has now moved one step further: which segments are already converting demand into earnings, which are still waiting for orders, and which valuations have already priced in 2027 ahead of time?
AI Hardware Cycle Upgraded Again: Asian Tech Rerating Across Memory, HBM, PCBs, and MLCCs
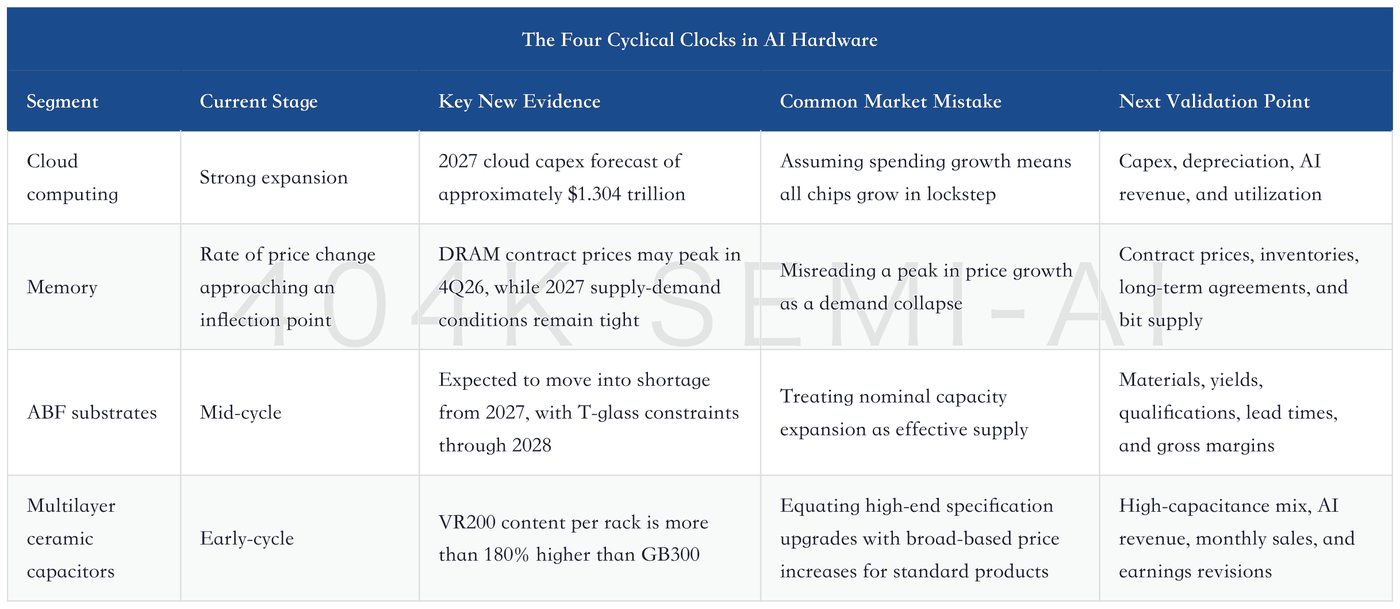
This sequencing also shows that excess returns across the AI supply chain will not be distributed evenly. The closer a segment is to the core chain where demand has already converted into earnings, the higher the earnings visibility—but also the greater the crowding. Segments only beginning to benefit from demand diffusion offer more upside sensitivity but rely on more model assumptions. Each clock requires different falsification criteria; a grand narrative cannot replace segment-by-segment validation.
Cloud Capex Remains Strong, but Spending Must Ultimately Become Revenue
The underlying demand remains solid. Morgan Stanley estimates that capex among the 14 largest listed cloud service providers increased from approximately $293 billion in 2024 to approximately $476 billion in 2025 and will rise further to approximately $916 billion in 2026. For 2027, consensus expects approximately $1.048 trillion, while Morgan Stanley forecasts approximately $1.304 trillion—around 24% higher. Combined capex at Amazon, Google, Microsoft, and Meta grew 95% year on year in 1Q26, with little near-term evidence of deliberate braking.
However, spending intensity has reached a level where orders alone are no longer sufficient. Capex as a percentage of EBITDA at leading cloud providers has risen above 70%, while short-lived assets account for approximately 65% in 2026-2027. Faster server and accelerator replacement cycles benefit the supply chain, but they also mean faster depreciation and greater free-cash-flow pressure for cloud providers. The sustainability of AI infrastructure ultimately depends on whether inference revenue, cloud-service revenue, and application monetization can keep pace with depreciation.
The report is therefore right to separate “infrastructure monetization” from “excess compute capacity.” Cloud providers selling more AI services does not mean they have already overbought servers; conversely, continued capex growth does not prove that returns on investment are sound. There are four genuine leading indicators: the annualized run rate of AI revenue, capex relative to operating cash flow, server utilization, and depreciation growth. If revenue growth fails to keep pace with depreciation, supply-chain orders will adjust earlier than the market expects.
Divergence is also emerging within semiconductors. The report expects logic foundry utilization to recover to approximately 80% in the second half of 2026. However, excluding memory and Nvidia AI GPUs, non-AI semiconductor revenue growth could instead slow. In other words, this is not a supercycle for every chip. AI-related advanced logic, memory, packaging, equipment, and high-specification components are capturing most of the incremental growth.
The Real Debate in Memory: Prices May Peak, but Can Earnings Stay Elevated for Two More Years?
Morgan Stanley expects DRAM contract prices to peak around 4Q26. This view is primarily based on three signals: year-on-year contract-price growth is retreating from extreme levels, supply-chain inventories are recovering from their lows, and spot and contract prices are diverging more visibly. The report’s pricing chart around July shows DDR5 16G spot prices at approximately $48.90 versus contract prices of approximately $40.00. Spot prices remaining above contract prices indicate that near-term tightness persists, but also that trading sentiment has moved ahead of long-term procurement pricing.
Inventories have also begun to turn. DRAM supply-chain inventories declined from their 2024 highs through the end of 2025 before rising modestly again in 2Q26; the rebound in NAND inventories has been more pronounced. Rising inventories have two entirely different interpretations. If customers are building stock for confirmed AI orders, the inventory is healthy. If long-term agreements are forcing customers to take deliveries while end demand fails to absorb them, the inventory will become pressure for the next destocking cycle. The market does not yet have sufficient evidence to distinguish fully between the two.
A peak in year-on-year pricing does not mean absolute prices will immediately fall, much less that industry earnings will collapse at once. Morgan Stanley estimates DRAM bit growth of approximately 37% from 2026 to 2028, versus approximately 15% growth in related wafer-fabrication equipment over the same period. Advanced nodes, HBM, yields, and process complexity have altered the relationship between equipment investment and effective bit output. Supply will increase, but the pace of release depends not only on capex but also on yields, product mix, and capacity ramp-up.
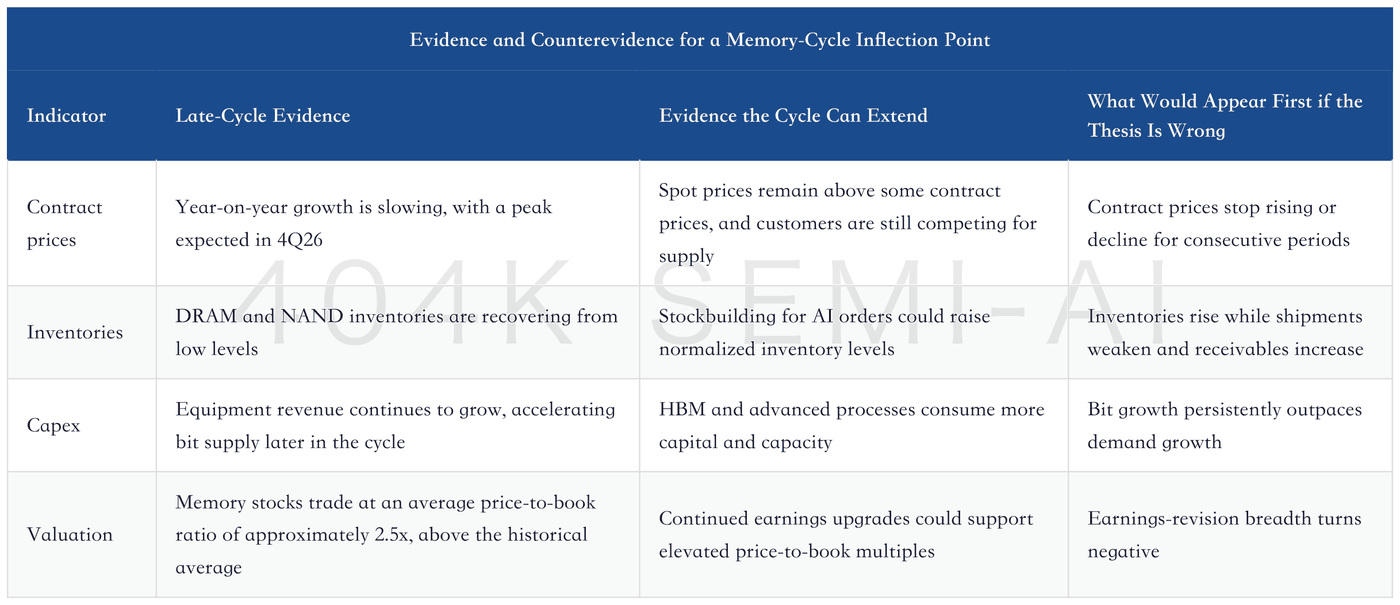
Previous memory research has repeatedly shown that a low static P/E ratio does not protect cyclical stocks. P/E ratios are naturally lowest when earnings are at their peak; once the market begins cutting next year’s earnings estimates, shares can decline while current-period results still look strong. Morgan Stanley therefore places greater emphasis on price-to-book ratios, inventories, and the direction of earnings revisions. Memory stocks are not cheap today, and future returns will depend more on earnings delivery than on straightforward multiple expansion.
AI Drives an Industry-Wide Memory Rerating: Who Has the Greatest Pricing Power Across DRAM, NAND, SSDs, and HDDs—and How Results from Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Corroborate the Thesis
Whether Long-Term Agreements Have Teeth Will Determine If Memory Can Be Valued Differently
Traditional long-term memory agreements are often “long in name, short on commitment”: prices are renegotiated quarterly or annually, purchase volumes are largely indicative, and customer default costs are limited. The new generation of agreements is markedly more binding. Common terms summarized in the report include three- to five-year durations, pre-agreed supply or purchase volumes, pricing formulas or ranges, price floors and caps, as well as prepayments, collateral, or financial guarantees. Customers secure supply, while manufacturers gain revenue and gross-margin visibility.
The logic is straightforward during an upcycle. Customers worried about securing high-bandwidth memory, dynamic random-access memory, and enterprise solid-state drives are willing to make longer-term commitments to lock in supply; manufacturers receiving prepayments or guarantees can plan capacity more prudently. The real test comes only when prices fall: Will customers demand renegotiations? Will price floors remain enforceable? Will uncollected volumes create inventory? Can default guarantees actually be enforced?
Morgan Stanley draws an analogy with Apple’s capital returns from 2013 to 2025: approximately 53% of Apple’s excess compounded return versus the benchmark came from share repurchases and a lower share count, while about 16% came from dividend reinvestment. The point is not that Samsung Electronics and SK hynix have already become Apple, but that rerating requires a complete pathway: contracts improve cash-flow visibility, free cash flow remains after capital expenditure, and that free cash flow is consistently deployed through buybacks and dividends before shareholders truly participate in the cyclical upside.
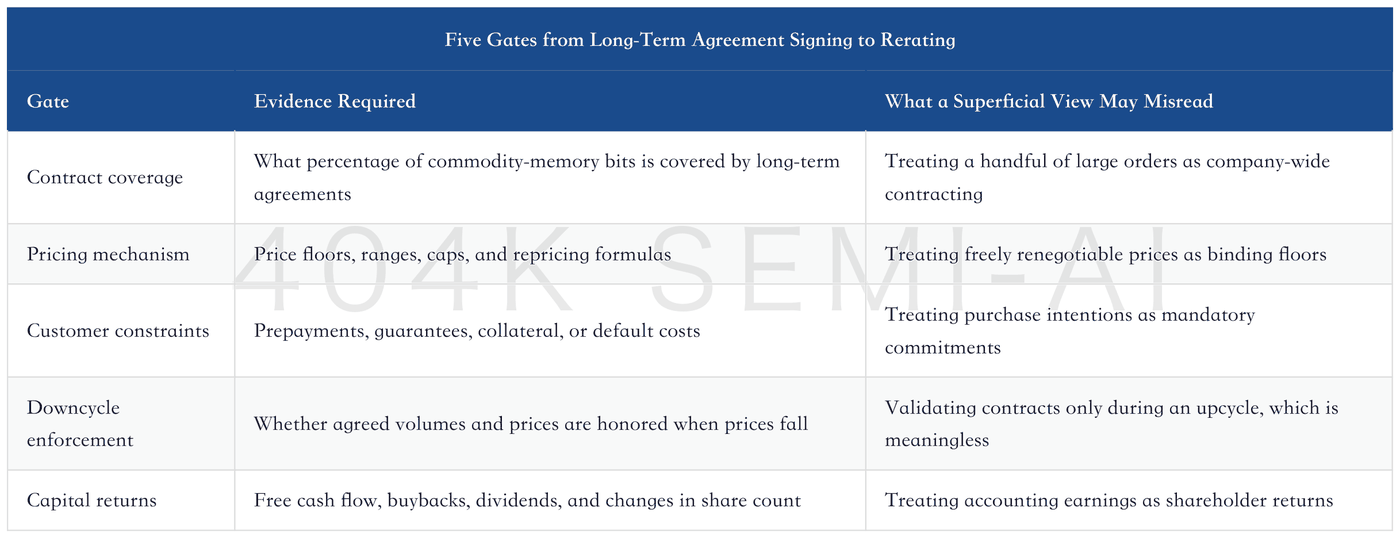
The report’s sensitivity analysis shows that if long-term agreements cover 50%-80% of commodity memory and the market assigns a 6-12x P/E multiple to contracted earnings, the implied group P/E multiples for Samsung Electronics and SK hynix could rise materially above current levels. However, the model is highly sensitive to coverage and enforceability. If contracts soften during a downcycle, the rerating potential will rapidly diminish. This is also why Morgan Stanley is relatively constructive on AI spending but neutral on the rerating potential from long-term agreements.
HBM Remains Tight, but Demand Has Broadened from NVIDIA to Cloud ASICs
The growth of high-bandwidth memory (HBM) is not driven by price increases. In Morgan Stanley’s base case, the average HBM price per GB declines from US$15 in 2023 to US$13 in 2027, while the market expands from US$3 billion to US$94 billion, representing a CAGR of approximately 128% from 2023 to 2027. The real drivers are the rising number of graphics processing units and application-specific integrated circuits, as well as the rapid increase in HBM capacity per chip.
By 2027, general-purpose GPU shipments are expected to reach approximately 12.753 million units, while ASIC shipments reach approximately 9.819 million. HBM capacity per GPU rises from 80GB in 2023 to 317GB, while capacity per ASIC increases from 40GB to 238GB. Product-level and aggregate demand models produce different estimates of approximately 50 billion Gb and 56 billion Gb, respectively. Accordingly, 2027 HBM demand is better understood as a range of 50-56 billion Gb rather than a precise point estimate.
Supply remains tight. Samsung Electronics, SK hynix, and Micron’s combined implied HBM output in 2027 is approximately 53.837 billion Gb, below aggregate-model demand of roughly 56.085 billion Gb. Combining HBM and commodity DRAM, total demand in 2027 is approximately 676.055 billion Gb versus total supply of around 573.503 billion Gb, implying a deficit of roughly 15%. HBM receives priority access to advanced DRAM capacity, crowding out conventional DRAM as well. This is the key channel through which the “HBM boom” spreads across the broader memory industry.
The customer mix is also changing. NVIDIA may still account for approximately 36% of HBM demand in 2027, but Google could represent around 33% through TPUs, AMD about 16%, and the remainder could come from AWS, Microsoft, Meta, and other custom-chip customers. NVIDIA remains the largest single customer but can no longer explain all demand. Whether cloud providers’ internally designed ASICs ramp as planned will become the second major axis of HBM demand, while also increasing customer, product, and qualification complexity.
There are three main risks. First, the model is extremely sensitive to yields and utilization; if Samsung Electronics improves HBM yields more quickly, the supply-demand deficit will narrow. Second, NVIDIA and Google together account for nearly 70% of demand, so any platform delay would amplify volatility. Third, the model assumes 65% year-on-year growth in ASIC shipments in 2027; if cloud providers’ custom-chip deployment proceeds more slowly than expected, total HBM demand will be revised downward.
NAND’s New Demand Is More Tangible, but Its Supply Risk Is Also More Direct
The structural incremental demand for NAND flash comes from enterprise solid-state drives, context storage, and the AI inference data layer. Morgan Stanley estimates that AI-related NAND demand will rise from 205EB in 2025 to 400EB in 2026 and 609EB in 2027, increasing from 18% of total demand to 32% and 41%, respectively. Over the same period, total demand rises from 1,111EB to 1,484EB, while total supply reaches approximately 1,347EB in 2027, implying a deficit of around 9%.
These figures show that NAND is no longer driven solely by smartphone and PC restocking. Google TPUs, AWS Trainium, Meta’s internally designed chips, GPU trays, CPU racks, context storage, and Chinese cloud service providers are all increasing demand for enterprise solid-state drives. Agents need to preserve longer contexts, access enterprise knowledge bases, record intermediate states, and retrieve them repeatedly. DRAM provides speed, while enterprise solid-state drives store larger capacities at lower cost.
However, NAND supply discipline is weaker than in HBM. Yangtze Memory Technologies is building Fab 4 and Fab 5, each planned for approximately 100,000 wafers per month. If all five announced fabs are used for NAND, its global market share could rise to roughly 24%. The report’s 2028 scenario analysis shows that with capacity of 310,000 wafers per month and 60% growth in AI SSD demand, the industry could still face a deficit of around 6%. If capacity rises to 470,000 wafers per month while AI SSD demand grows only 30%, the industry could face approximately 9% oversupply. A single supply variable can shift the same industry from shortage to surplus.
NAND research must therefore shift from asking “Will prices continue to rise?” to three questions: When will equipment be installed at the new fabs? How quickly will yields ramp? Can enterprise products secure customer qualification? Strong near-term pricing cannot substitute for this validation. If new capacity grows faster than AI demand, NAND will return to a traditional cycle sooner than DRAM. If expansion is constrained by equipment, yields, and customer discipline, enterprise solid-state drives will prolong the upcycle.
Agentic AI Turns the CPU from a Supporting Player into a Traffic Controller
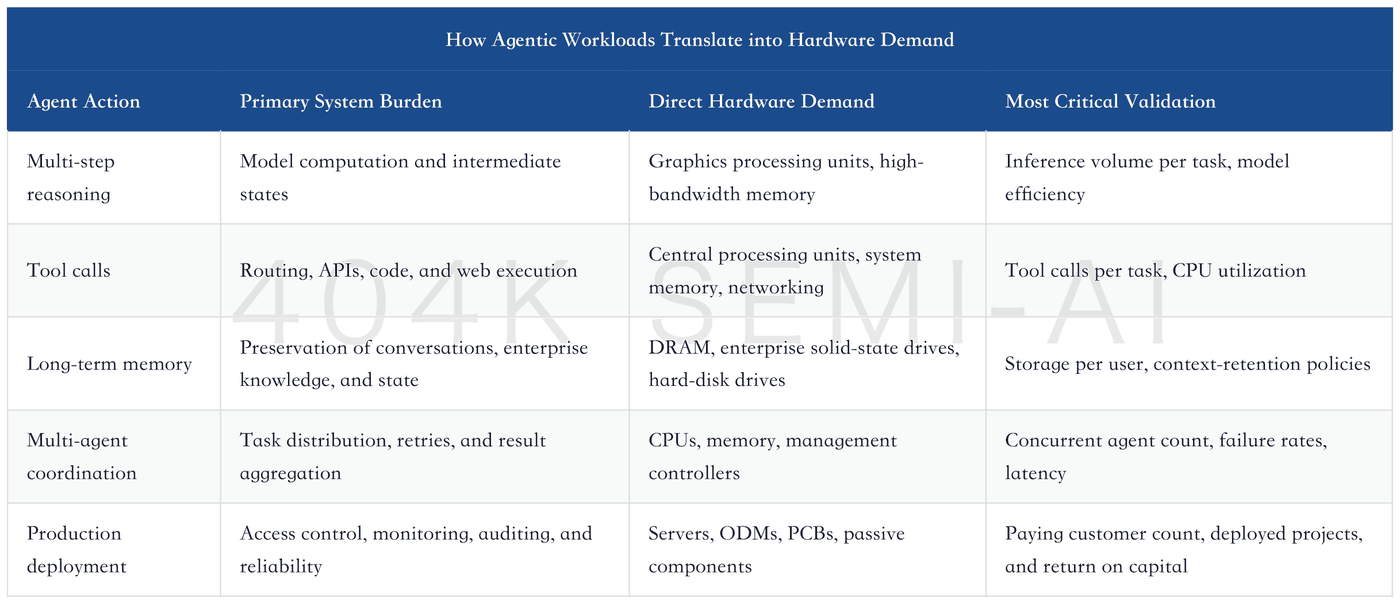
Generative AI primarily solves the problem of “providing an answer”; agentic AI must “get the job done.” A complex task may first read an enterprise database, then call websites and APIs, execute code, check the results, retry after failures, and pass context to the next agent. Graphics processing units handle large-model inference; central processing units (CPUs) handle routing, workflow state, tool calls, and system orchestration; memory and databases preserve short- and long-term memory.
Morgan Stanley uses a directional chart to illustrate the change in workloads: in chatbots, GPUs may account for approximately 85% of total latency; in complex orchestration, the CPU share could rise to around 92%. The CPU-to-GPU ratio can be as low as approximately 1:12 for inference-intensive tasks but may approach 1:1 for tool- and action-intensive tasks. The report explicitly cautions that these ratios are directional estimates, not measured benchmarks, and may vary significantly depending on models, networks, caching, and parallelization architectures.
The bull-case opportunity is substantial. By 2030, agent orchestration could create up to US$238 billion in incremental CPU opportunity, while incremental DRAM demand could reach 221EB—equivalent in the chart to 4.9x 2026 supply. This figure is better treated as a stress test and should not be inserted directly into any company’s revenue forecast. It tells investors that if agents genuinely move from pilots into production, system bottlenecks will spread from accelerators to CPUs, memory, storage, networking, management controllers, and system design.
This is also why the migration of AI value toward applications does not imply that hardware value disappears. The application layer ultimately captures revenue, while infrastructure supports usage. Hardware capital expenditure becomes more sustainable only when applications begin monetizing; applications can scale only when hardware costs decline. The two validate each other rather than operate as a zero-sum trade-off.
ABF’s 2027 Shortfall Will First Be Constrained by Materials and Effective Capacity
Ajinomoto Build-up Film substrates (ABF substrates) have already weathered the decline in PC demand, post-pandemic inventory corrections, and the absorption of new capacity. Morgan Stanley characterizes 2024–2025 as a period of uneven recovery and the post-2026 period as the AI proliferation phase. The market contracted from US$9.023 billion in 2022 to US$7.048 billion in 2025 and is subsequently projected to reach US$19.181 billion by 2030, implying a CAGR of approximately 22.2% in the latter period.
