
目录
Executive Summary
1. The Strongest Part of the Results: Supply Constraints Ease and Revenue Inflects
2. Profit Growth Is Strong, but the Revenue Beat Did Not Fully Flow Through the Income Statement
3. The Real Pressure Point Is the Balance Sheet: Inventory Is Growing Faster Than Profit
4. Goldman Sachs Models a Steep H2 Ramp: Revenue Must Grow Another 60%
5. Why the Earnings Upgrade Added Only RMB6 to the Price Target
6. Six Numbers Will Determine the Thesis Over the Next Two Quarters
Conclusion: Results Have Validated Demand; Cash Flow Will Determine Whether RMB639 Is Justified
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Q2 revenue beat Goldman Sachs’ forecast by 11%, but net profit exceeded it by only 2%. Demand and deliveries have strengthened, but margins, inventory and cash flow will determine whether the RMB639 valuation holds.
Executive Summary
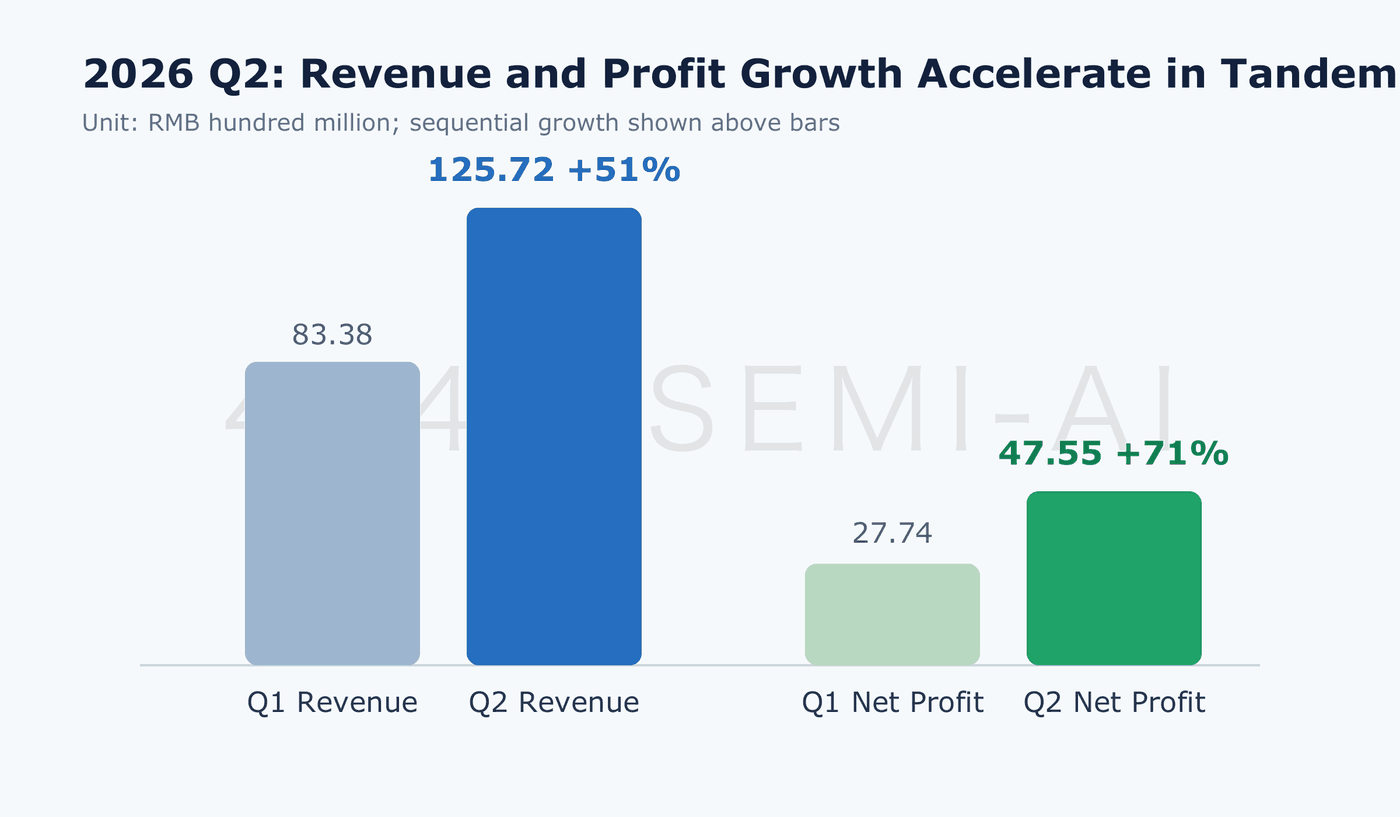
Eoptolink reported 1H26 revenue of RMB20.91 billion, up 100.34% year over year, and attributable net profit of RMB7.529 billion, up 90.98%. Q2 revenue reached RMB12.572 billion, up 51% quarter over quarter, while attributable net profit rose 71% to RMB4.755 billion.
Revenue beat Goldman Sachs’ forecast by 11%, but net profit exceeded it by only 2%. Deliveries benefited from the 800G and 1.6T ramp, improved availability of critical components and capacity expansion, but the incremental revenue has not yet translated fully into additional profit.
Goldman Sachs raised its 2026-2028 earnings forecasts by 4%, 7% and 8%, respectively, while cutting the 2027 earnings multiple from 29.3x to 27.8x. The two effects broadly offset each other, lifting the target price only from RMB633 to RMB639.
At the end of 1H26, inventory stood at RMB11.655 billion, prepayments at RMB870 million and operating cash flow at just RMB1.616 billion, equivalent to 21.5% of net profit. The key question is whether this supply-chain preparation converts into revenue and cash.
Goldman Sachs’ model requires H2 revenue to grow 60.3% over H1 and net profit to rise 84.7%. Q3 revenue, margins, inventory turnover and cash collection will directly test that trajectory.
1. The Strongest Part of the Results: Supply Constraints Ease and Revenue Inflects
Q2 2026 revenue reached RMB12.572 billion, up RMB4.234 billion from RMB8.338 billion in Q1, representing 51% sequential and 97% year-over-year growth. Goldman Sachs had forecast RMB11.283 billion, while consensus was approximately RMB11.826 billion; the actual result beat those estimates by 11% and 6%, respectively. End-demand strength alone is unlikely to explain this performance. A more plausible interpretation is that orders previously constrained by optical chips, digital signal-processing chips, production lines and yields are now converting into recognized revenue more rapidly.
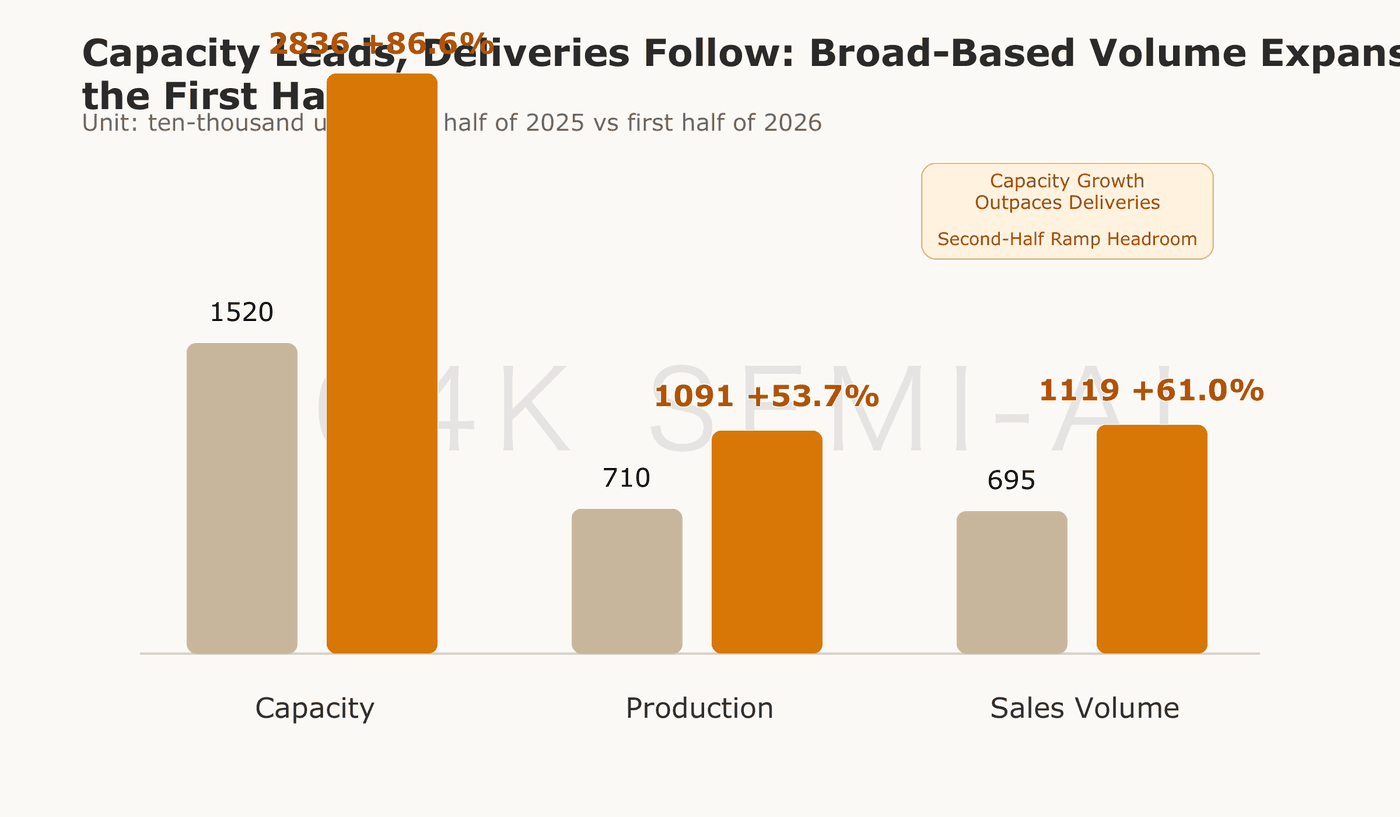
The interim report provides supporting operating evidence. In 1H26, optical-interconnect capacity reached 28.36 million units, up 86.6% year over year; output rose 53.7% to 10.91 million units, while sales increased 61.0% to 11.19 million units. Optical-interconnect revenue grew 100.59% to RMB20.883 billion, with gross margin expanding 0.99 percentage points to 48.46%. Capacity growth materially outpaced production, suggesting Eoptolink is not only fulfilling current orders but also reserving headroom for a steeper shipment ramp in H2.
The product mix will determine whether that capacity represents high-quality supply. Eoptolink identifies 400G, 800G, 1.6T and higher-speed products as its core growth engines and confirms that it is among the first companies globally to mass-produce and deliver 1.6T optical modules. Its technology platform extends beyond electro-absorption modulated lasers (EML) to silicon photonics (SiPh) and thin-film lithium niobate, while product formats span conventional pluggable modules, linear pluggable optics (LPO), near-packaged optics (NPO) and co-packaged optics (CPO). Goldman Sachs highlights that 1.6T is ramping simultaneously across both EML and silicon-photonics architectures, reducing exposure to supply constraints in any single technology path.
It is important, however, to distinguish among three stages: technology launch, volume delivery and financial contribution. Eoptolink has introduced products including 1.6T DR4, 6.4T NPO and 12.8T XPO based on single-lane 400G PAM4, demonstrating that its technology pipeline extends to higher data rates. Yet 2026 earnings will still depend on customer qualification, yields, shipment scale and average selling prices for 800G and 1.6T pluggable products. Longer-term products provide valuation optionality, but they cannot substitute for current-period cash-flow validation.
2. Profit Growth Is Strong, but the Revenue Beat Did Not Fully Flow Through the Income Statement
Q2 gross profit reached RMB6.03 billion, up 47% sequentially, while gross margin declined to 48.0% from 49.2% in Q1. Operating profit rose 45% to RMB5.561 billion, but operating margin fell to 44.2% from 46.0%. Attributable net margin recovered from 33.3% in Q1 to 37.8%, yet remained below Goldman Sachs’ 41.2% forecast and the 40.1% consensus estimate. This explains why revenue beat Goldman Sachs’ forecast by 11%, while attributable net profit exceeded it by only 2%.
In other words, Q2 delivered more convincingly on volume than on unit profitability. A higher mix of high-speed products and stronger capacity utilization drove rapid gross-profit growth, but price reductions, production-ramp costs, raw-material expenses and foreign-exchange volatility prevented all incremental revenue from converting into marginal profit. The interim report shows that finance costs swung from negative RMB208 million a year earlier to positive RMB644 million, primarily because exchange-rate movements generated foreign-exchange losses. This item alone largely explains why net-profit growth slightly lagged revenue growth.
