
Electronic Components Cycle Deep Dive: AI Servers Up 21%, Smartphones Down 11%—Why Orders, Inventories, and High-End Components Continue to Diverge
目录
TL;DR
I. This Is a “Cycle Transmission Map,” Not an Industry Index
II. The 2026 Demand Scissors: Servers Strengthen as All Three Major Traditional End Markets Contract
III. Orders Have Broken Through, but Sales and Inventories Have Yet to Follow Through
IV. Passive Components Are the Relative Bright Spot, but Capacitors Are the Real Growth Engine
V. The MLCC Contradiction: Unit Volumes Have Recovered, but Pricing and Profits May Not Have
VI. A New Answer on Automotive Content: HEVs, PHEVs, and ADAS Matter More Than “BEV Penetration”
VII. Data Center Storage: Focus on Capacity Growth, Not Just Unit Shipments
VIII. AI Compute Is Expanding into Custom Chips, Broadening System-Level Component Value
IX. The Slope of the Semiconductor Equipment Cycle Will Be Driven Primarily by Memory, Especially DRAM
10. Company Mapping: Buy Product Mix and Market Share, Not a Vague “AI Components” Label
11. From Demand to Cash Flow: Five Hurdles Between an Industry Upturn and Corporate Profitability
12. Valuation and Scenarios: Do Not Equate Strong Orders Directly With Strong Cash Flow
XIII. Conclusion: Focus on Just Eight Delivery Metrics Going Forward
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This is not a recovery in which all components rise together: orders have already strengthened, but sales and inventories have yet to fully confirm the upturn. Returns will ultimately be determined by end-market divergence, product mix, and the pace at which valuations are validated.
TL;DR
The electronics components market in 2026 will be driven by divergent end-market demand. Global smartphone, PC, and automobile production is expected to decline by 11.34%, 8.53%, and 2.38%, respectively, while server shipments are projected to grow by 14.57%, including 21.28% growth in AI servers. The segments with real earnings leverage are those capable of converting higher server content per unit and premium specifications into revenue.
Leading indicators are already strong, while coincident indicators are still catching up. Murata, Taiyo Yuden, ROHM, and Hirose all posted book-to-bill ratios above 1 in 1Q26, and factory automation orders are also leading industrial-component sales. Yet industry shipments in US-dollar terms remain near zero growth. Whether orders convert into sales over the next two to three quarters is the most important validation for this trade.
Inventories are no longer deteriorating, but they are not yet clean. Inventory in Japan’s electronic components industry stands at approximately ¥2.7 trillion, with days inventory outstanding still around 80 days. The positive signal is that sales growth of approximately 13%–14% YoY is outpacing inventory growth of roughly 2%–4%. The current environment is better characterized as “destocking nearing completion and restocking beginning” than as a strong cycle supporting broad-based price increases and aggressive capacity expansion.
Multilayer ceramic capacitors are the core passive-components theme, but the market is currently seeing “volume growth and price declines.” Japanese production has recovered to approximately 10%–20% YoY growth, while blended US-dollar ASPs are down nearly 30% YoY. Export ASPs to the US and Europe are approximately 1.7–1.9 times those to Asia, indicating that profitability depends less on unit volume than on high-capacitance, high-reliability part numbers and regional mix.
The automotive multilayer ceramic capacitor thesis is no longer simply “the more EVs, the better.” In 2025, plug-in hybrid vehicles used 8,000–18,000 units per vehicle, slightly above the 7,500–17,500 range for battery-electric/fuel-cell vehicles; advanced driver-assistance systems can independently add another 1,500–5,000 units. Hybrid vehicles, plug-in hybrids, and driver-assistance systems jointly increase content per vehicle, providing a more stable driver than battery-electric vehicle penetration alone.
Data-center storage should be assessed by capacity, not merely drive count. Solid-state drives account for approximately 45% of enterprise/data-center drive units but only around 20% of petabyte capacity, while hard disk drives still provide roughly 80% of capacity. Enterprise SSD capacity is growing approximately 130%–150% YoY, far faster than unit shipments, demonstrating that HDDs and SSDs can grow simultaneously within hot/cold data-tiering architectures.
Incremental AI hardware demand has spread beyond graphics processing units to custom silicon, memory, and equipment. The report forecasts a 52% CAGR for custom silicon from 2025 to 2028, above 20% for high-end graphics processing units; DRAM capital expenditure is projected to rise from approximately US$59.2 billion in 2025 to roughly US$151.6 billion in 2027. These forecasts represent the strongest upside drivers, but also the key risks to monitor after valuations have moved ahead, capital spending has overheated, and raw-material prices have risen.
I. This Is a “Cycle Transmission Map,” Not an Industry Index
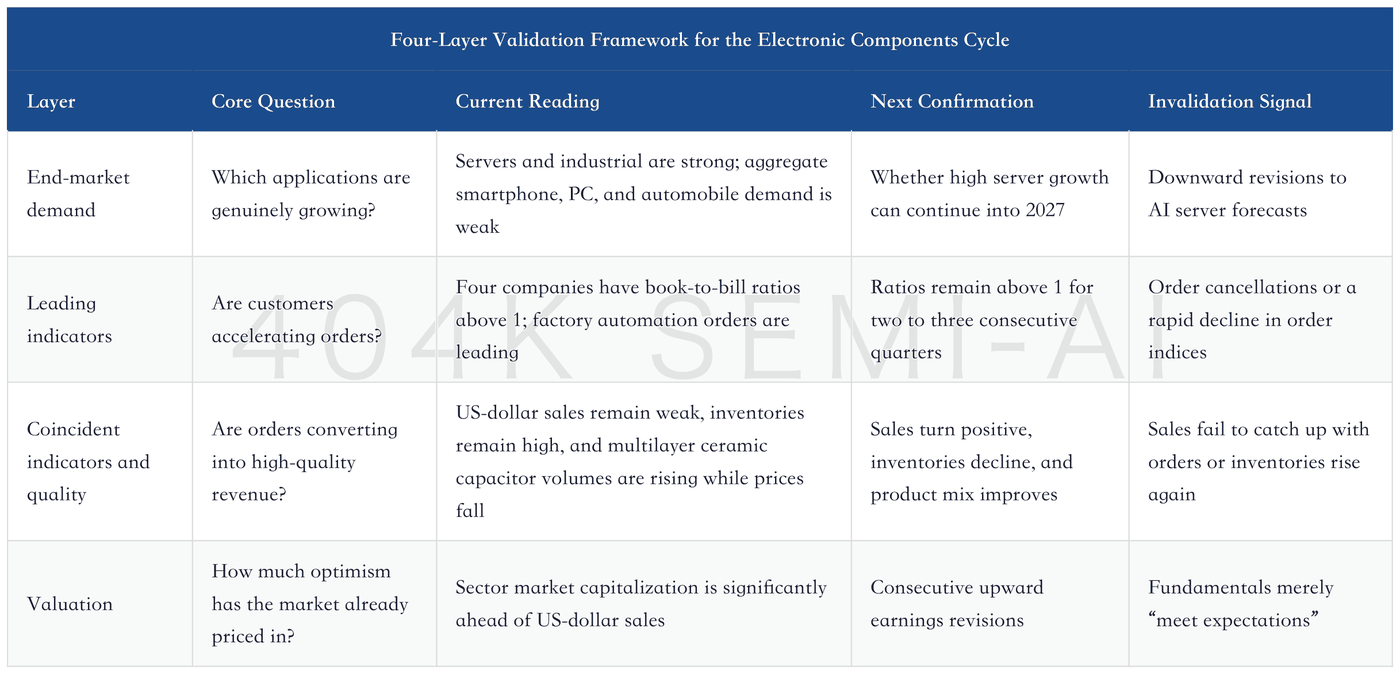
The easiest mistake when reading this type of data handbook is to combine several upward-sloping charts into a single “industry recovery” narrative. Yet the earnings transmission mechanism for electronic components follows a clear sequence: end-market demand changes first, customers place orders, factories schedule production and ship products, inventory turnover improves, and only then do pricing, product mix, and margins respond. Orders and share prices typically lead; revenue and cash flow lag.
The current assessment should therefore be divided into four layers. The first is demand direction: which of servers, smartphones, PCs, automobiles, and industrial equipment are growing. The second is leading indicators: book-to-bill ratios and factory automation orders. The third is coincident and quality indicators: US-dollar sales, inventory turnover, and blended ASPs. The fourth is valuation: how much optimism is already reflected in share prices. As long as the second layer improves without confirmation from the third, investors are still buying expectations rather than an established earnings cycle.
II. The 2026 Demand Scissors: Servers Strengthen as All Three Major Traditional End Markets Contract
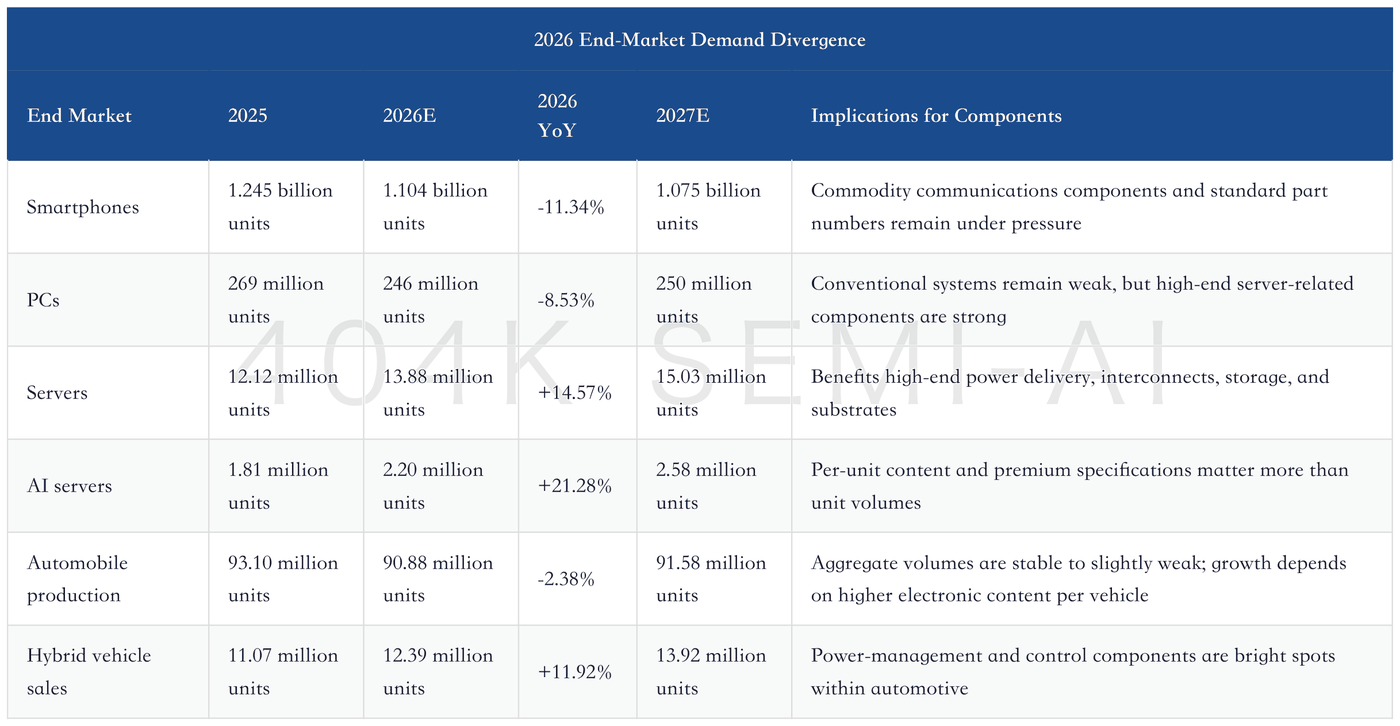
End-market assumptions make clear why investors cannot buy the entire industry indiscriminately. Global smartphone shipments are expected to fall from 1.245 billion units in 2025 to 1.104 billion in 2026, down 11.34% YoY; PC shipments from 269 million to 246 million, down 8.53%; and automobile production from 93.10 million to 90.88 million, down 2.38%. Smartphones, PCs, and automobiles are the largest traditional demand pools for electronic components. Simultaneous contraction across all three means commodity-specification products are unlikely to achieve both volume and price growth through a natural industry recovery alone.
Servers are the clear exception. Global server shipments are projected to increase from 12.12 million units in 2025 to 13.88 million in 2026, up 14.57% YoY. Within that total, AI server shipments are expected to rise from 1.81 million to 2.20 million, up 21.28%, followed by another 17.63% increase to 2.58 million units in 2027. Unit volumes are relatively small, but the per-unit value of power components, multilayer ceramic capacitors, connectors, printed circuit boards, memory and storage, and thermal-management solutions is far higher than in conventional end devices. This explains why the PC/server component sales index can continue reaching new highs even as conventional PC shipments decline: the index also includes packaging substrates and hard-disk-related products, reflecting a higher-value product mix rather than PC shipment volumes.
This divergence will flow directly through to margins. Server components typically have higher specifications and longer qualification cycles, while customers are more sensitive to reliability. An improved product mix can therefore increase both revenue and gross margins. Commodity consumer electronics, by contrast, are more exposed to customer price pressure, underutilized low-end capacity, and inventory write-downs. The earnings implications of 5% revenue growth can be entirely different depending on whether it comes from higher volumes of premium part numbers or low-priced restocking.
III. Orders Have Broken Through, but Sales and Inventories Have Yet to Follow Through
Orders are the most encouraging signal in this dataset. In 1Q26, the book-to-bill ratio for Murata Manufacturing’s multilayer ceramic capacitors was approximately 1.35, versus approximately 1.25 for Taiyo Yuden, 1.35 for Rohm, and 1.15 for Hirose; all four companies were above 1. Their corresponding order indices were approximately 300, 205, 210, and 165. The simultaneous rise in book-to-bill ratios and order indices indicates that new orders have exceeded current-period shipments and backlogs have begun to accumulate.
The industrial chain provides independent confirmation. Factory-automation order indices for FANUC, SMC, and Yaskawa Electric were approximately 145 in 1Q26, versus approximately 123–125 for industrial-component sales indices, leaving orders more than 20 points ahead. Equipment manufacturers’ orders reflect manufacturing capex intentions first, with the impact subsequently flowing through to revenue for motors, connectors, power supplies, and passive components. If the historical lead-lag relationship holds, industrial-component capacity utilization still has room to rise over the next several quarters.
Sales, however, are not as strong as orders. Yen-denominated global shipments of Japanese components are approaching historical highs, but in US dollar terms they have mostly remained at US$2.4–2.9 billion per month, still below the 2021 peak of approximately US$3.5–3.6 billion. The latest YoY growth is fluctuating around zero. This is a reminder that yen depreciation has amplified nominal growth in reported financials, while the recovery in underlying global demand remains more moderate than the order curve suggests.
Inventories are the third constraint. Industry inventories stand at approximately ¥2.7 trillion, while days inventory outstanding remains around 80 days, above the 50–65 days commonly seen in earlier years. The good news is that sales are growing approximately 13%–14% YoY, materially faster than inventory growth of approximately 2%–4%, demonstrating substantive progress in destocking. The bad news is that 80 days is still not an inventory level that supports industry-wide price increases and large-scale capacity expansion.
A confirmed upcycle therefore requires three consecutive conditions: book-to-bill ratios remaining above 1 for two to three quarters; US dollar-denominated shipments turning sustainably positive from around zero; and inventory days continuing to decline from approximately 80 days alongside improving operating cash flow. If sales fail to catch up with orders, the current upturn would look more like channel restocking. If inventories rise again, current order strength may include advance stocking, duplicate ordering, or expectations of price increases.
IV. Passive Components Are the Relative Bright Spot, but Capacitors Are the Real Growth Engine
Passive components are the relative bright spot in the industry, but the strength is uneven. Global monthly industry-association data show passive-component shipments peaking at approximately US$1.6 billion in 2021. Following destocking in 2022–2023, shipments recovered to approximately US$1.3–1.5 billion from 2025 through early 2026. Recent shipments of connecting components were only approximately US$500–600 million, while transducers were around US$400 million. Neither has returned to its previous high, and their latest YoY growth is weaker.
Breaking the data down further, recent monthly capacitor shipments were approximately US$950 million–US$1.05 billion, well above resistors at approximately US$100–120 million, inductors at approximately US$200–240 million, and connectors at approximately US$350–400 million. After recovering in 2024, the latest momentum in resistors and inductors has returned to around zero. Capacitors are the primary contributor to the recovery in passive components. Japanese domestic production data are consistent with this picture: recent monthly multilayer ceramic capacitor output value was approximately US$400–500 million, far above aluminum electrolytic capacitors, resistors, and inductors, making it sufficient to determine the overall direction of Japan’s passive-component industry.
A distinction must be made between “relatively strong” and “broad-based strength.” Industry associations record shipment value, which is affected by exchange rates, product specifications, and regional mix. Japanese domestic output value also does not equal the global sales of Japanese manufacturers, as production is now distributed overseas. These data demonstrate that capacitors are outperforming other categories, but they do not yet prove that all capacitor manufacturers have gained pricing power.
MLCCs: From Passive Components to AI Density Enablers — A Cross-Referenced Deep Dive into Goldman Sachs, JPMorgan, and HSBC Research
V. The MLCC Contradiction: Unit Volumes Have Recovered, but Pricing and Profits May Not Have
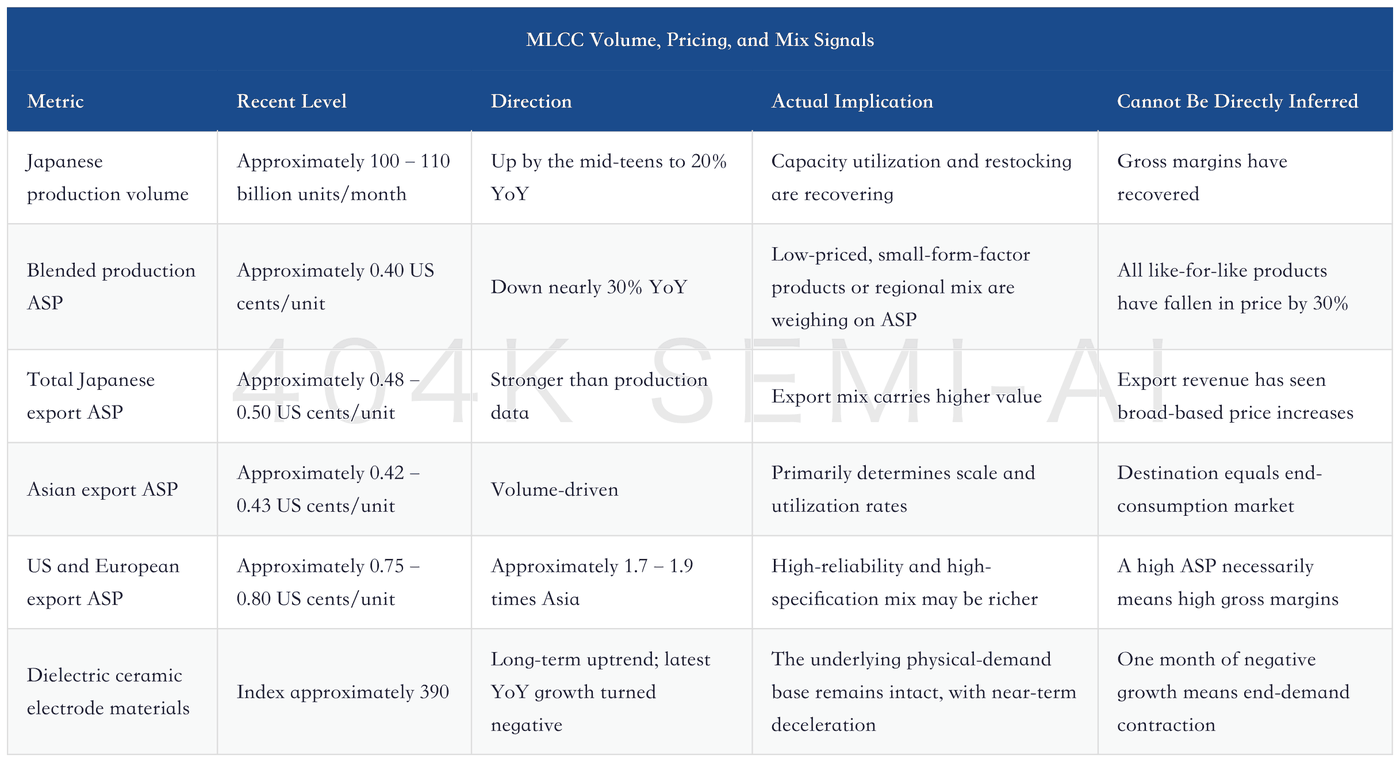
The most important contradiction in multilayer ceramic capacitors today is that volumes, unit value, and regional mix are moving along different trajectories. Recent monthly production in Japan was approximately 100–110 billion units, up roughly in the mid-teens to 20% YoY. US dollar-denominated output value, however, was only approximately US$400–450 million and remained down YoY. The recent blended production ASP was approximately 0.40 US cents per unit, below the 2022 peak of approximately 0.60–0.65 US cents, with the latest YoY decline approaching 30%. This is a classic case of rising volumes and falling prices: it shows only that production lines are busier, not that gross margins are necessarily improving.
However, a decline in the blended ASP does not mean every part number is experiencing price cuts. The blended ASP is calculated by dividing output value by unit volume. A higher share of small-form-factor, low-capacitance products or continued component miniaturization can both drive this figure lower. Assessing profitability requires further analysis of the mix of high-reliability automotive, industrial, and server products, as well as manufacturers’ own capacity-utilization rates.
Export data illustrate these structural differences. Japan’s recent total MLCC exports were approximately 90–100 billion units per month, with US dollar-denominated export value of approximately US$430–460 million and an export ASP of approximately 0.48–0.50 US cents per unit, stronger overall than the total production data. Major Asian markets absorbed approximately 75–80 billion units per month at an ASP of approximately 0.42–0.43 US cents per unit. The US and Europe absorbed only approximately 9–11 billion units per month, but at an ASP of approximately 0.75–0.80 US cents per unit, around 1.7–1.9 times the Asian level. Asia determines capacity utilization, while the US, Europe, and high-end customers are more likely to determine unit value.
Asia is not a single market either. China’s recent monthly MLCC imports were approximately US$550–600 million, making it the largest import center. Taiwan imported approximately US$170–190 million, with faster recent growth, while South Korean exports were approximately US$110–130 million. Thailand and Malaysia are growing rapidly, but their absolute scale remains small, and low bases amplify YoY growth. A more accurate supply-chain picture is that China retains large-scale import and manufacturing demand, South Korea serves as a major exporter, Taiwan supports computing and electronics manufacturing, and Southeast Asia is an incremental node rather than a wholesale replacement for the scale of China, Japan, South Korea, and Taiwan.
VI. A New Answer on Automotive Content: HEVs, PHEVs, and ADAS Matter More Than “BEV Penetration”
Automotive MLCC demand was previously often simplified as “the higher the BEV penetration rate, the greater the content per vehicle.” The 2025 data no longer support this single-variable framework. Total content per internal-combustion-engine vehicle was approximately 4,600–11,500 units, versus approximately 6,500–16,200 for mild hybrids, 6,700–16,600 for full hybrids, 8,000–18,000 for plug-in hybrids, and 7,500–17,500 for battery-electric/fuel-cell vehicles. Plug-in hybrids retain internal-combustion-engine controls while adding electric drive, battery management, charging, and high-voltage components, resulting in greater system complexity than a single-powertrain architecture.
Advanced driver-assistance systems represent a second incremental growth curve independent of powertrain type. In 2025, ADAS content was approximately 1,500–5,000 units per vehicle, including approximately 1,500–3,000 for L2/3 and 3,000–5,000 for L4/5. In addition, safety systems required approximately 300–1,000 units, non-safety electronics approximately 500–2,500, and infotainment approximately 500–2,500. The wide content range within the same powertrain type primarily reflects differences in vehicle segment, ADAS level, and electronic configuration.
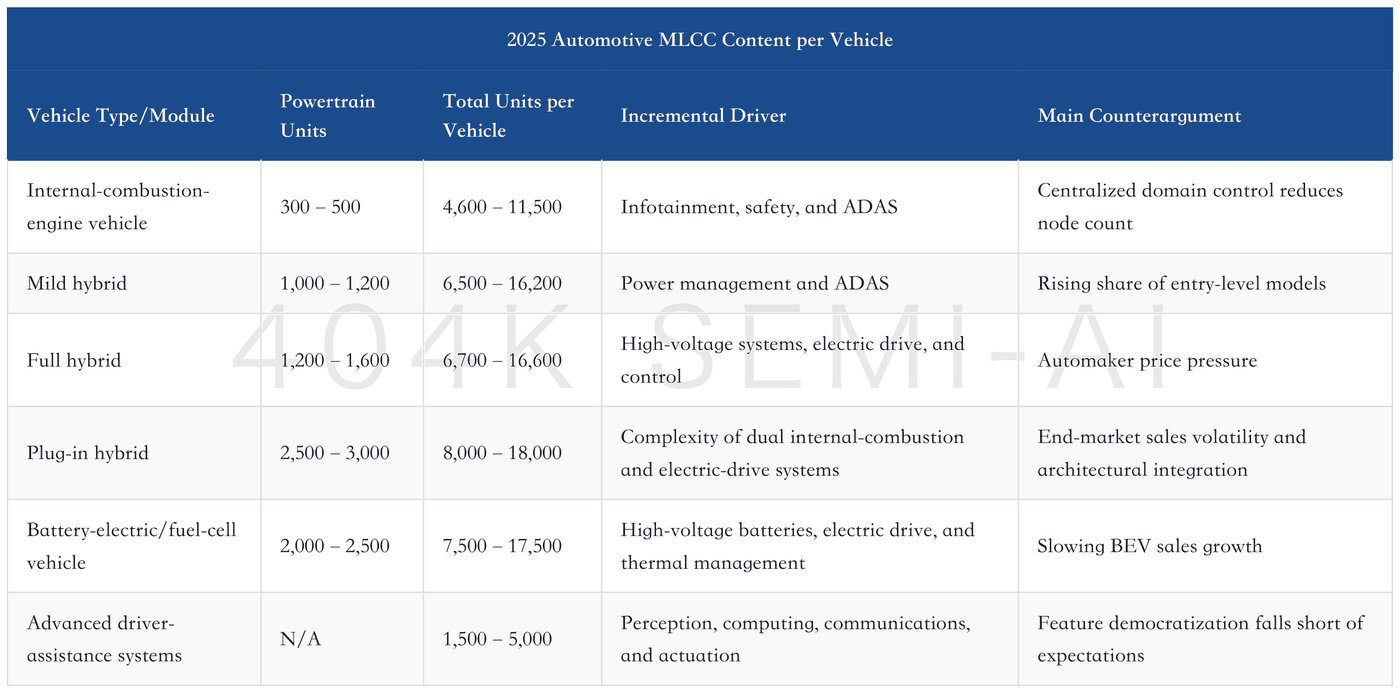
The investment implication is that the market should not be extrapolated using a notional average of “10,000 units per vehicle.” The range is wide and does not represent an industry average weighted by vehicle sales. Higher unit content also does not translate into proportionate revenue growth because prices vary significantly by capacitance, voltage rating, and reliability specifications. The most important metrics to track are the share of revenue from automotive-grade products, platform design wins, the mix of high-voltage/high-capacitance products, and the pace at which ADAS features penetrate mass-market and entry-level vehicles.
VII. Data Center Storage: Focus on Capacity Growth, Not Just Unit Shipments
The storage industry is most often misread when demand is judged by drive shipments. Monthly HDD production has fallen from approximately 35 million units in mid-2017 to approximately 10–11.5 million units in recent years, while total production capacity has risen from approximately 70,000 PB to approximately 170,000 PB over the same period, with nearline HDD capacity approaching 155,000–160,000 PB. Falling unit shipments alongside record-high capacity show that cloud providers are buying data capacity per drive bay, not the number of drive enclosures.
The divergence is even more pronounced for SSDs. Total monthly SSD production peaked at approximately 35 million units in 2021 and has since mostly fluctuated between 25 million and 34 million units, while total capacity increased from approximately 3,000–4,000 PB in 2017 to approximately 55,000 PB by the end of 2025. Monthly enterprise/data center SSD production is approximately 5.8 million units, with capacity already at approximately 41,000 PB. Capacity is growing approximately 130%–150% year over year, far faster than unit growth of approximately 40%–50%. For NAND manufacturers, PB and bit shipments provide a more accurate measure of underlying demand than drive volumes.
HDDs and SSDs therefore do not have a simple substitution relationship. In enterprise/data center storage, SSDs account for approximately 45% of unit shipments but only approximately 20% of capacity, while HDDs still carry approximately 80% of PB. SSDs serve the performance tier, while HDDs retain the low-cost, high-capacity tier. Simultaneous growth in training-data archives, video, logs, backups, and real-time inference will instead sustain the long-term coexistence of both media.
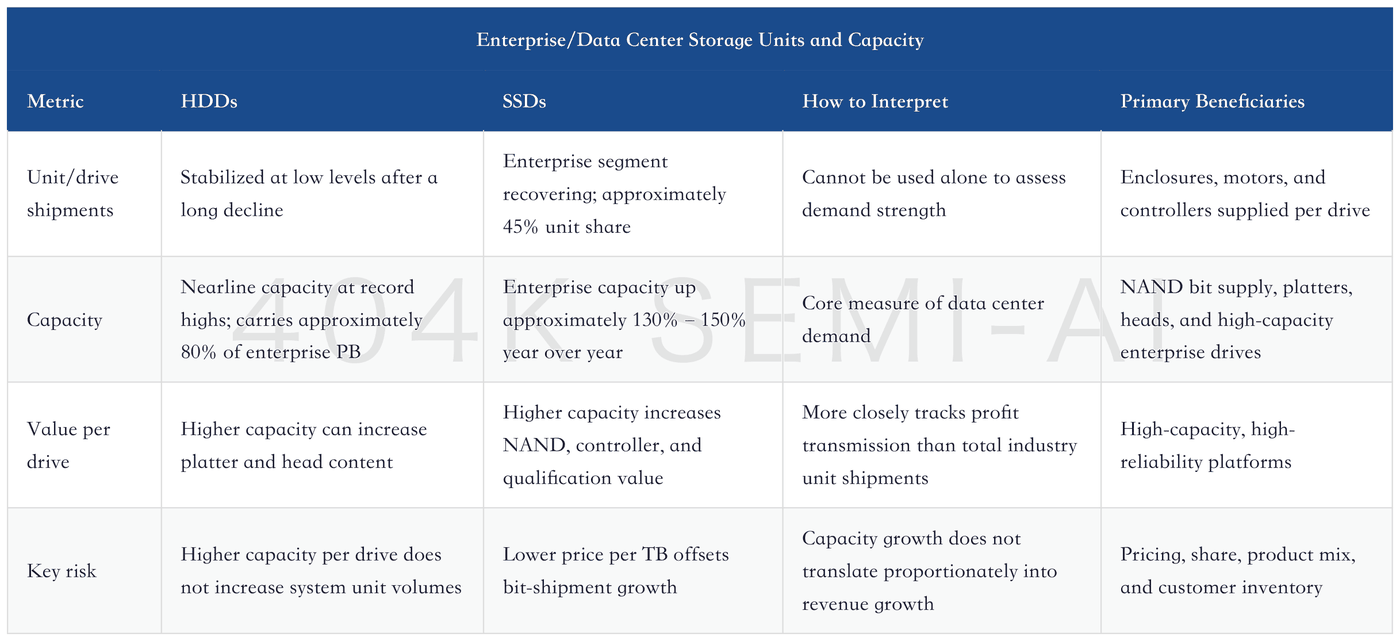
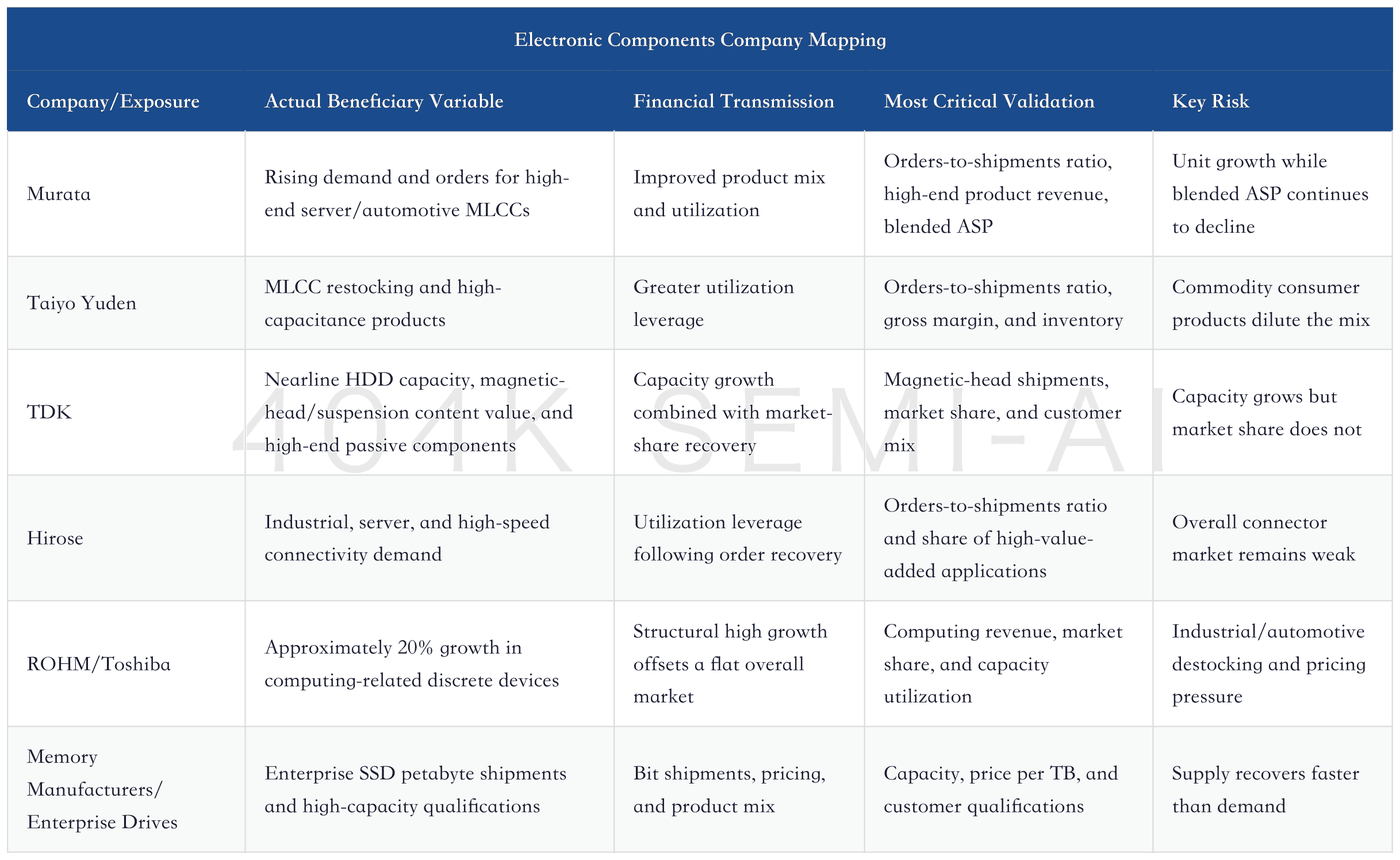
TDK provides a good example of how industry strength does not necessarily translate proportionately into company performance. Shipments of its head suspension assemblies recovered from a 2023 low of approximately 24 million units to approximately 52 million units in the first quarter of 2026, but its market share remains only approximately 13%, below the 2021 peak of approximately 20%, with a more concentrated customer base. Rising nearline capacity can increase head content value, but the ultimate earnings sensitivity will also depend on whether TDK can regain market share.
VIII. AI Compute Is Expanding into Custom Chips, Broadening System-Level Component Value
The next phase of AI hardware growth will not rely solely on rising volumes of high-end GPUs. Total data center AI chip shipments are projected to increase from 10.32 million units in 2025 to 28.23 million in 2028, representing a CAGR of approximately 40%. Within this total, high-end GPU shipments are expected to rise from 6.15 million to 10.70 million, a CAGR of approximately 20%, while custom ASIC shipments are projected to increase from 4.17 million to 14.70 million, a CAGR of approximately 52%. GPUs are still growing, but cloud providers are migrating sufficiently large and stable workloads to internally developed or custom chips to reduce inference costs and dependence on a single platform.
Server volumes and value per system are rising simultaneously. AI server shipments are projected to increase from approximately 1.82 million units in 2025 to approximately 4.24 million in 2028, a CAGR of approximately 32%, while their share of global server shipments rises from 15.0% to 21.3%. Custom-chip server shipments are expected to increase from approximately 610,000 units to 1.84 million, a CAGR of approximately 45%. Chips per server are projected to rise from seven to eight, while some rack architectures use eight or even 16 accelerators. Simultaneous increases in server shipments, penetration, and chips per system naturally broaden demand across motherboards, advanced packaging, high-layer-count PCBs, switching networks, optical interconnects, power supplies, thermal management, connectors, and storage.
Compute-related discrete semiconductors have already provided early validation. The total transistor market grew only approximately 0.9% in 2025, while the data-processing/computing-electronics transistor market grew approximately 19.8%. Infineon still holds approximately 26% of the computing-electronics market, but Asian vendors such as Toshiba and Yangjie Technology are growing faster. Vendors outside the top 10 grew approximately 28% in aggregate, above the top 10’s approximately 17% growth. High-power computing increases demand for switching, protection, rectification, and power-conversion devices, and the incremental value will not flow only to established leaders.
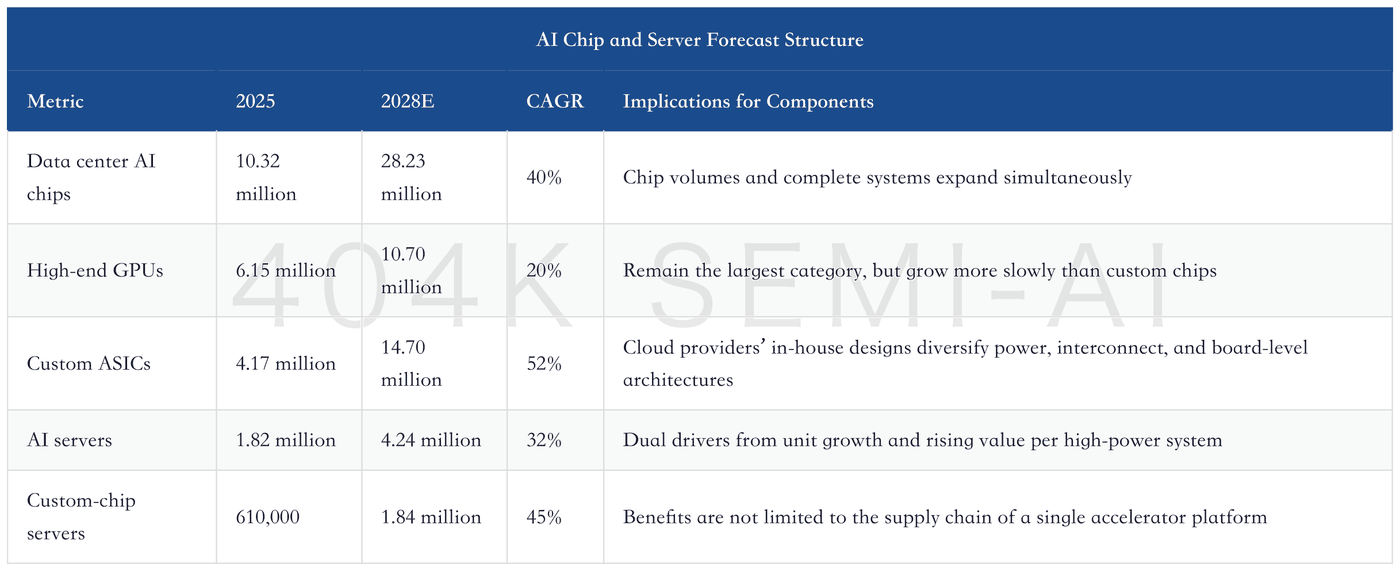
The risks to these forecasts are equally clear. Total AI chip shipments are projected to grow approximately 55% in 2026 and 50% in 2027, while custom-chip shipments are expected to grow approximately 83% and 61%, respectively. These projections are highly sensitive to cloud capital expenditure, data center power availability, advanced-packaging capacity, and optical-network deployment. Faster custom-chip growth does not imply declining GPU shipments; both are growing. The real disconfirming evidence would be stagnating AI-server penetration, delayed customer deployments, or an end to increases in power and chip count per system.
IX. The Slope of the Semiconductor Equipment Cycle Will Be Driven Primarily by Memory, Especially DRAM
The largest variable in the next semiconductor equipment upcycle is not logic, but memory. Total industry capital expenditure is projected to increase from approximately US$166.4 billion in 2025 to approximately US$226.9 billion in 2026 and US$316.4 billion in 2027, representing year-over-year growth of approximately 36% and 39%, respectively. Memory capital expenditure is expected to rise from US$77.3 billion to US$114.9 billion and US$185.8 billion over the same period, accounting for approximately 59% of total industry capital expenditure in 2027.
DRAM has the steepest growth trajectory. DRAM capital expenditure is projected to rise from approximately US$59.2 billion in 2025 to approximately US$91.4 billion in 2026 and US$151.6 billion in 2027, representing year-over-year growth of approximately 54% and 66%, respectively. This spending is not limited to adding conventional memory-wafer capacity. HBM requires more die stacking, tighter yield control, more testing, and advanced packaging, increasing the intensity of etch, deposition, cleaning, inspection, and packaging equipment.
Capital expenditure in other segments is less uniformly strong. NAND capital expenditure is projected to rise from approximately US$18.1 billion in 2025 to approximately US$34.2 billion in 2027, a clear recovery but with lower scale and a shallower trajectory than DRAM. Foundry capital expenditure is expected to increase from US$59.1 billion to US$81.8 billion and US$94.0 billion, with strong growth in 2026 followed by a slowdown in 2027. Logic capital expenditure is approximately US$30.0 billion in 2025, remains broadly flat in 2026, and only recovers to approximately US$36.6 billion in 2027. Equipment companies should not all be treated as the same type of cyclical asset. Companies with greater exposure to DRAM, HBM, and advanced packaging will have steeper order trajectories.
These forecasts also represent the largest medium-term overheating risk. DRAM capital expenditure increases by nearly US$100 billion over two years. If HBM supply improves faster than demand or conventional memory pricing weakens, customers may delay equipment acceptance and cut subsequent orders. The validation sequence should be: first, whether memory capital-expenditure forecasts continue to be revised upward; second, equipment orders, delivery lead times, and customer prepayments; and finally, revenue, gross margin, and cash collections.
10. Company Mapping: Buy Product Mix and Market Share, Not a Vague “AI Components” Label
The same industry data translate very differently into earnings across companies. For Murata Manufacturing and Taiyo Yuden, the key variables are the share of high-end multilayer ceramic capacitor products, utilization rates, and blended ASPs. For Hirose Electric, the question is whether a recovery in connector orders from depressed levels can translate into revenue from high-value-added applications. For ROHM and Toshiba, the issue is whether strong growth in computing-related discrete devices can offset a flat overall market. TDK requires simultaneous monitoring of nearline HDD capacity, its share in magnetic heads and suspension assemblies, and high-end passive components.
The Apple RF front-end table offers another warning: “entering the supply chain” does not mean stable content value per device. Skyworks, Broadcom, and Murata all participate in multiple modules, but module counts, integration approaches, and supply shares vary across models. Murata’s dollar content per device fell from approximately US$3 in the iPhone 15 to approximately US$2.5 in the iPhone 16 series, with some subsequent configurations at approximately US$1.5. Looking only at Apple shipments would overlook the greater impact of integration and market share on component revenue.
In-Depth Update on Japanese Electronic Components: April–June Earnings Preview—How Long Can Strong MLCC and ABF Profits Last?
11. From Demand to Cash Flow: Five Hurdles Between an Industry Upturn and Corporate Profitability
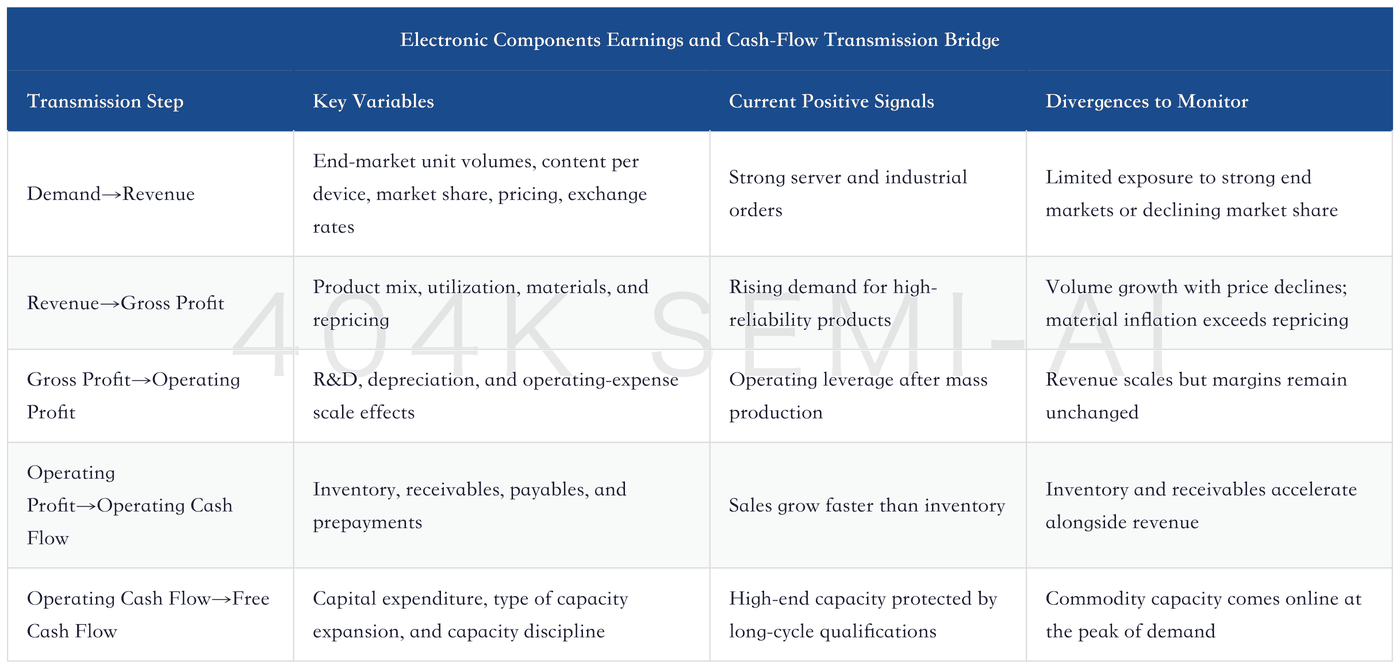
Revenue growth for electronic component companies can be decomposed into five variables: end-market unit volumes, content per device, supply share, blended ASP, and exchange rates. In this data handbook, these five variables frequently offset one another: AI server volumes are growing, but total smartphone and PC volumes are declining; MLCC unit volumes are rising, but blended ASPs are falling; nearline HDD capacity is increasing, but TDK’s market share in magnetic heads and suspension assemblies has yet to recover to its previous peak; yen-denominated revenue is strong, while total shipments in US dollar terms remain near zero growth. Therefore, the first hurdle between an “upward industry curve” and “rising corporate revenue” is identifying which strong variable the company is actually exposed to.
The second hurdle is the transition from revenue to gross profit. Higher capacity utilization can reduce depreciation and fixed costs per unit, but gross margin may still decline if incremental output consists primarily of lower-priced products, or if the costs of copper, gold, silver, aluminum, and electrode materials rise. MLCC volume growth accompanied by price declines is a classic example: busier production lines are not sufficient evidence that the share of high-specification products is increasing. Investors must continue to monitor revenue from high-reliability products, customer qualifications, repricing provisions, and material-cost pass-through cycles.
The third hurdle is the transition from gross profit to operating profit. AI servers, high-bandwidth memory, and high-capacity storage all require R&D;, customer qualification, and investment in new equipment. A company may incur R&D; and depreciation expenses before mass production, with operating leverage emerging only after revenue begins to scale. Consequently, a new business’s failure to immediately lift margins in a given quarter does not necessarily mean the project has failed. However, if operating profit does not improve after revenue has scaled for several consecutive periods, the competitiveness of the product or the efficiency of the capacity should be questioned.
The fourth hurdle is the transition from profit to operating cash flow. During periods of order growth, raw materials, work in progress, and accounts receivable often increase first. The income statement may look strong while cash is absorbed by working capital. With inventory days still at approximately 80, the greatest concern is not quarterly revenue missing expectations by one percentage point, but revenue growth coinciding with simultaneous deterioration in inventory, receivables, and cash flow. This combination often indicates that customer pull-through is weaker than production schedules suggest, or that the company has extended payment terms to maintain utilization.
The fifth hurdle is the transition from cash flow to free cash flow. Equipment and high-end component manufacturers increase capital expenditure during upcycles, but there is a major difference between expanding high-end capacity protected by long-term customer qualifications and expanding commodity capacity that is vulnerable to oversupply. If capacity expansion coincides with the projected 2027 peak in storage capital expenditure and customers subsequently reduce demand, free cash flow will face the dual pressure of declining earnings and lagging capital expenditure.
12. Valuation and Scenarios: Do Not Equate Strong Orders Directly With Strong Cash Flow
Industry market capitalization tends to lead the sales cycle over the long term, but the latest market-cap curve has moved significantly ahead of US dollar-denominated sales. The annotation date in the original chart conflicts with the endpoint of the horizontal axis, so the spike should not be cited as a precise valuation datapoint. The direction, however, is already clear: the market is pricing in AI servers, an industrial recovery, and inventory normalization in advance. At this stage, merely “meeting expectations” does not necessarily generate positive returns; earnings forecasts must be raised repeatedly to absorb the valuation.
Raw materials will further amplify earnings dispersion. Copper, aluminum, cobalt, and precious metals are all significantly above their earlier lows at the endpoint of the charts, while volatility has increased. Connectors, cables, printed circuit boards, motors, power supplies, and electroplating are more sensitive to copper and precious metals. Companies that can reprice monthly or quarterly, have high customer-qualification barriers, and have material costs representing a low share of selling prices are better positioned to defend gross margins. When demand recovers but material prices rise faster, revenue growth may be offset by gross-margin compression.
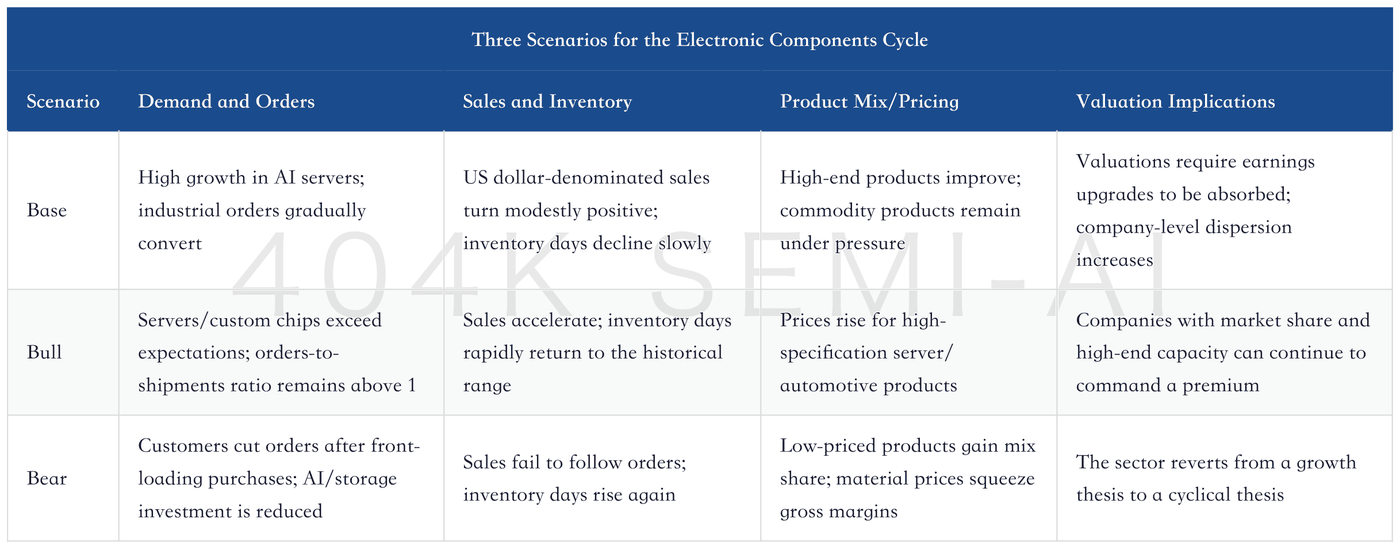
This report does not provide individual-stock target prices, nor is there any need to fabricate precise price targets. It is more useful to tie valuation to verifiable conditions. The base case assumes orders exceed shipments, US dollar-denominated sales gradually turn positive, inventory days decline, and the high-end product mix improves, supporting an earnings recovery without broad-based price increases. The bull case assumes AI servers and custom chips exceed expectations, industrial orders convert into revenue, inventories normalize rapidly, and high-specification components see structural price increases. The bear case assumes the orders-to-shipments ratio declines, sales fail to follow orders, and inventory rises again, alongside reductions in AI infrastructure or storage capital expenditure.
XIII. Conclusion: Focus on Just Eight Delivery Metrics Going Forward
The current electronics-components upcycle is supported by genuine fundamentals, but it is a structural recovery—not a synchronized strong cycle across all end markets, product categories, and companies. Servers, custom chips, enterprise storage capacity, and industrial orders are driving the upside, while weakness in smartphones and mainstream PCs, elevated inventory days, and declining blended MLCC prices preclude a simplistic extrapolation of industry beta.
Going forward, tracking eight metrics monthly and quarterly should suffice: book-to-bill ratios for Murata, Taiyo Yuden, ROHM, and Hirose; year-on-year growth in industry shipments in US dollar terms; inventory days; blended MLCC prices and the share of high-specification products; nearline HDD petabytes and enterprise SSD petabytes; AI server and custom-chip shipments; DRAM capital expenditure and equipment orders; and, finally, each company’s gross margin and operating cash flow. Only if all eight sets of indicators improve simultaneously will the structural recovery develop into an earnings cycle. If orders are strong but sales, inventories, and cash flow fail to follow, current valuations are simply pulling forward future expectations.
The investment approach is therefore clear: first identify products that translate high-power, high-capacity, high-bandwidth, and high-reliability requirements into greater content per system; then identify companies with certification advantages, market share, and capacity discipline; and finally use inventories, pricing, gross margins, and cash flow to validate revenue quality. As long as this sequence is maintained, investors will neither mistake a one-off restocking cycle for secular growth nor overlook companies delivering genuine content upgrades amid subdued aggregate demand.
Related Reading
CCL/PCB Update: High-End Copper-Clad Laminate Shortage Extends to 2027; M9 Materials and HDI Capacity Continue to RepriceElectronic Components Cycle Deep Dive: AI Servers Up 21%, Smartphones Down 11%—Why Orders, Inventories, and High-End Components Continue to Diverge
目录
TL;DR
I. This Is a “Cycle Transmission Map,” Not an Industry Index
II. The 2026 Demand Scissors: Servers Strengthen as All Three Major Traditional End Markets Contract
III. Orders Have Broken Through, but Sales and Inventories Have Yet to Follow Through
IV. Passive Components Are the Relative Bright Spot, but Capacitors Are the Real Growth Engine
V. The MLCC Contradiction: Unit Volumes Have Recovered, but Pricing and Profits May Not Have
VI. A New Answer on Automotive Content: HEVs, PHEVs, and ADAS Matter More Than “BEV Penetration”
VII. Data Center Storage: Focus on Capacity Growth, Not Just Unit Shipments
VIII. AI Compute Is Expanding into Custom Chips, Broadening System-Level Component Value
IX. The Slope of the Semiconductor Equipment Cycle Will Be Driven Primarily by Memory, Especially DRAM
10. Company Mapping: Buy Product Mix and Market Share, Not a Vague “AI Components” Label
11. From Demand to Cash Flow: Five Hurdles Between an Industry Upturn and Corporate Profitability
12. Valuation and Scenarios: Do Not Equate Strong Orders Directly With Strong Cash Flow
XIII. Conclusion: Focus on Just Eight Delivery Metrics Going Forward
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This is not a recovery in which all components rise together: orders have already strengthened, but sales and inventories have yet to fully confirm the upturn. Returns will ultimately be determined by end-market divergence, product mix, and the pace at which valuations are validated.
TL;DR
The electronics components market in 2026 will be driven by divergent end-market demand. Global smartphone, PC, and automobile production is expected to decline by 11.34%, 8.53%, and 2.38%, respectively, while server shipments are projected to grow by 14.57%, including 21.28% growth in AI servers. The segments with real earnings leverage are those capable of converting higher server content per unit and premium specifications into revenue.
Leading indicators are already strong, while coincident indicators are still catching up. Murata, Taiyo Yuden, ROHM, and Hirose all posted book-to-bill ratios above 1 in 1Q26, and factory automation orders are also leading industrial-component sales. Yet industry shipments in US-dollar terms remain near zero growth. Whether orders convert into sales over the next two to three quarters is the most important validation for this trade.
Inventories are no longer deteriorating, but they are not yet clean. Inventory in Japan’s electronic components industry stands at approximately ¥2.7 trillion, with days inventory outstanding still around 80 days. The positive signal is that sales growth of approximately 13%–14% YoY is outpacing inventory growth of roughly 2%–4%. The current environment is better characterized as “destocking nearing completion and restocking beginning” than as a strong cycle supporting broad-based price increases and aggressive capacity expansion.
Multilayer ceramic capacitors are the core passive-components theme, but the market is currently seeing “volume growth and price declines.” Japanese production has recovered to approximately 10%–20% YoY growth, while blended US-dollar ASPs are down nearly 30% YoY. Export ASPs to the US and Europe are approximately 1.7–1.9 times those to Asia, indicating that profitability depends less on unit volume than on high-capacitance, high-reliability part numbers and regional mix.
The automotive multilayer ceramic capacitor thesis is no longer simply “the more EVs, the better.” In 2025, plug-in hybrid vehicles used 8,000–18,000 units per vehicle, slightly above the 7,500–17,500 range for battery-electric/fuel-cell vehicles; advanced driver-assistance systems can independently add another 1,500–5,000 units. Hybrid vehicles, plug-in hybrids, and driver-assistance systems jointly increase content per vehicle, providing a more stable driver than battery-electric vehicle penetration alone.
Data-center storage should be assessed by capacity, not merely drive count. Solid-state drives account for approximately 45% of enterprise/data-center drive units but only around 20% of petabyte capacity, while hard disk drives still provide roughly 80% of capacity. Enterprise SSD capacity is growing approximately 130%–150% YoY, far faster than unit shipments, demonstrating that HDDs and SSDs can grow simultaneously within hot/cold data-tiering architectures.
Incremental AI hardware demand has spread beyond graphics processing units to custom silicon, memory, and equipment. The report forecasts a 52% CAGR for custom silicon from 2025 to 2028, above 20% for high-end graphics processing units; DRAM capital expenditure is projected to rise from approximately US$59.2 billion in 2025 to roughly US$151.6 billion in 2027. These forecasts represent the strongest upside drivers, but also the key risks to monitor after valuations have moved ahead, capital spending has overheated, and raw-material prices have risen.
I. This Is a “Cycle Transmission Map,” Not an Industry Index
The easiest mistake when reading this type of data handbook is to combine several upward-sloping charts into a single “industry recovery” narrative. Yet the earnings transmission mechanism for electronic components follows a clear sequence: end-market demand changes first, customers place orders, factories schedule production and ship products, inventory turnover improves, and only then do pricing, product mix, and margins respond. Orders and share prices typically lead; revenue and cash flow lag.
The current assessment should therefore be divided into four layers. The first is demand direction: which of servers, smartphones, PCs, automobiles, and industrial equipment are growing. The second is leading indicators: book-to-bill ratios and factory automation orders. The third is coincident and quality indicators: US-dollar sales, inventory turnover, and blended ASPs. The fourth is valuation: how much optimism is already reflected in share prices. As long as the second layer improves without confirmation from the third, investors are still buying expectations rather than an established earnings cycle.
II. The 2026 Demand Scissors: Servers Strengthen as All Three Major Traditional End Markets Contract
End-market assumptions make clear why investors cannot buy the entire industry indiscriminately. Global smartphone shipments are expected to fall from 1.245 billion units in 2025 to 1.104 billion in 2026, down 11.34% YoY; PC shipments from 269 million to 246 million, down 8.53%; and automobile production from 93.10 million to 90.88 million, down 2.38%. Smartphones, PCs, and automobiles are the largest traditional demand pools for electronic components. Simultaneous contraction across all three means commodity-specification products are unlikely to achieve both volume and price growth through a natural industry recovery alone.
Servers are the clear exception. Global server shipments are projected to increase from 12.12 million units in 2025 to 13.88 million in 2026, up 14.57% YoY. Within that total, AI server shipments are expected to rise from 1.81 million to 2.20 million, up 21.28%, followed by another 17.63% increase to 2.58 million units in 2027. Unit volumes are relatively small, but the per-unit value of power components, multilayer ceramic capacitors, connectors, printed circuit boards, memory and storage, and thermal-management solutions is far higher than in conventional end devices. This explains why the PC/server component sales index can continue reaching new highs even as conventional PC shipments decline: the index also includes packaging substrates and hard-disk-related products, reflecting a higher-value product mix rather than PC shipment volumes.
This divergence will flow directly through to margins. Server components typically have higher specifications and longer qualification cycles, while customers are more sensitive to reliability. An improved product mix can therefore increase both revenue and gross margins. Commodity consumer electronics, by contrast, are more exposed to customer price pressure, underutilized low-end capacity, and inventory write-downs. The earnings implications of 5% revenue growth can be entirely different depending on whether it comes from higher volumes of premium part numbers or low-priced restocking.
III. Orders Have Broken Through, but Sales and Inventories Have Yet to Follow Through
Orders are the most encouraging signal in this dataset. In 1Q26, the book-to-bill ratio for Murata Manufacturing’s multilayer ceramic capacitors was approximately 1.35, versus approximately 1.25 for Taiyo Yuden, 1.35 for Rohm, and 1.15 for Hirose; all four companies were above 1. Their corresponding order indices were approximately 300, 205, 210, and 165. The simultaneous rise in book-to-bill ratios and order indices indicates that new orders have exceeded current-period shipments and backlogs have begun to accumulate.
The industrial chain provides independent confirmation. Factory-automation order indices for FANUC, SMC, and Yaskawa Electric were approximately 145 in 1Q26, versus approximately 123–125 for industrial-component sales indices, leaving orders more than 20 points ahead. Equipment manufacturers’ orders reflect manufacturing capex intentions first, with the impact subsequently flowing through to revenue for motors, connectors, power supplies, and passive components. If the historical lead-lag relationship holds, industrial-component capacity utilization still has room to rise over the next several quarters.
Sales, however, are not as strong as orders. Yen-denominated global shipments of Japanese components are approaching historical highs, but in US dollar terms they have mostly remained at US$2.4–2.9 billion per month, still below the 2021 peak of approximately US$3.5–3.6 billion. The latest YoY growth is fluctuating around zero. This is a reminder that yen depreciation has amplified nominal growth in reported financials, while the recovery in underlying global demand remains more moderate than the order curve suggests.
Inventories are the third constraint. Industry inventories stand at approximately ¥2.7 trillion, while days inventory outstanding remains around 80 days, above the 50–65 days commonly seen in earlier years. The good news is that sales are growing approximately 13%–14% YoY, materially faster than inventory growth of approximately 2%–4%, demonstrating substantive progress in destocking. The bad news is that 80 days is still not an inventory level that supports industry-wide price increases and large-scale capacity expansion.
A confirmed upcycle therefore requires three consecutive conditions: book-to-bill ratios remaining above 1 for two to three quarters; US dollar-denominated shipments turning sustainably positive from around zero; and inventory days continuing to decline from approximately 80 days alongside improving operating cash flow. If sales fail to catch up with orders, the current upturn would look more like channel restocking. If inventories rise again, current order strength may include advance stocking, duplicate ordering, or expectations of price increases.
IV. Passive Components Are the Relative Bright Spot, but Capacitors Are the Real Growth Engine
Passive components are the relative bright spot in the industry, but the strength is uneven. Global monthly industry-association data show passive-component shipments peaking at approximately US$1.6 billion in 2021. Following destocking in 2022–2023, shipments recovered to approximately US$1.3–1.5 billion from 2025 through early 2026. Recent shipments of connecting components were only approximately US$500–600 million, while transducers were around US$400 million. Neither has returned to its previous high, and their latest YoY growth is weaker.
Breaking the data down further, recent monthly capacitor shipments were approximately US$950 million–US$1.05 billion, well above resistors at approximately US$100–120 million, inductors at approximately US$200–240 million, and connectors at approximately US$350–400 million. After recovering in 2024, the latest momentum in resistors and inductors has returned to around zero. Capacitors are the primary contributor to the recovery in passive components. Japanese domestic production data are consistent with this picture: recent monthly multilayer ceramic capacitor output value was approximately US$400–500 million, far above aluminum electrolytic capacitors, resistors, and inductors, making it sufficient to determine the overall direction of Japan’s passive-component industry.
A distinction must be made between “relatively strong” and “broad-based strength.” Industry associations record shipment value, which is affected by exchange rates, product specifications, and regional mix. Japanese domestic output value also does not equal the global sales of Japanese manufacturers, as production is now distributed overseas. These data demonstrate that capacitors are outperforming other categories, but they do not yet prove that all capacitor manufacturers have gained pricing power.
MLCCs: From Passive Components to AI Density Enablers — A Cross-Referenced Deep Dive into Goldman Sachs, JPMorgan, and HSBC Research
V. The MLCC Contradiction: Unit Volumes Have Recovered, but Pricing and Profits May Not Have
The most important contradiction in multilayer ceramic capacitors today is that volumes, unit value, and regional mix are moving along different trajectories. Recent monthly production in Japan was approximately 100–110 billion units, up roughly in the mid-teens to 20% YoY. US dollar-denominated output value, however, was only approximately US$400–450 million and remained down YoY. The recent blended production ASP was approximately 0.40 US cents per unit, below the 2022 peak of approximately 0.60–0.65 US cents, with the latest YoY decline approaching 30%. This is a classic case of rising volumes and falling prices: it shows only that production lines are busier, not that gross margins are necessarily improving.
However, a decline in the blended ASP does not mean every part number is experiencing price cuts. The blended ASP is calculated by dividing output value by unit volume. A higher share of small-form-factor, low-capacitance products or continued component miniaturization can both drive this figure lower. Assessing profitability requires further analysis of the mix of high-reliability automotive, industrial, and server products, as well as manufacturers’ own capacity-utilization rates.
Export data illustrate these structural differences. Japan’s recent total MLCC exports were approximately 90–100 billion units per month, with US dollar-denominated export value of approximately US$430–460 million and an export ASP of approximately 0.48–0.50 US cents per unit, stronger overall than the total production data. Major Asian markets absorbed approximately 75–80 billion units per month at an ASP of approximately 0.42–0.43 US cents per unit. The US and Europe absorbed only approximately 9–11 billion units per month, but at an ASP of approximately 0.75–0.80 US cents per unit, around 1.7–1.9 times the Asian level. Asia determines capacity utilization, while the US, Europe, and high-end customers are more likely to determine unit value.
Asia is not a single market either. China’s recent monthly MLCC imports were approximately US$550–600 million, making it the largest import center. Taiwan imported approximately US$170–190 million, with faster recent growth, while South Korean exports were approximately US$110–130 million. Thailand and Malaysia are growing rapidly, but their absolute scale remains small, and low bases amplify YoY growth. A more accurate supply-chain picture is that China retains large-scale import and manufacturing demand, South Korea serves as a major exporter, Taiwan supports computing and electronics manufacturing, and Southeast Asia is an incremental node rather than a wholesale replacement for the scale of China, Japan, South Korea, and Taiwan.
VI. A New Answer on Automotive Content: HEVs, PHEVs, and ADAS Matter More Than “BEV Penetration”
Automotive MLCC demand was previously often simplified as “the higher the BEV penetration rate, the greater the content per vehicle.” The 2025 data no longer support this single-variable framework. Total content per internal-combustion-engine vehicle was approximately 4,600–11,500 units, versus approximately 6,500–16,200 for mild hybrids, 6,700–16,600 for full hybrids, 8,000–18,000 for plug-in hybrids, and 7,500–17,500 for battery-electric/fuel-cell vehicles. Plug-in hybrids retain internal-combustion-engine controls while adding electric drive, battery management, charging, and high-voltage components, resulting in greater system complexity than a single-powertrain architecture.
Advanced driver-assistance systems represent a second incremental growth curve independent of powertrain type. In 2025, ADAS content was approximately 1,500–5,000 units per vehicle, including approximately 1,500–3,000 for L2/3 and 3,000–5,000 for L4/5. In addition, safety systems required approximately 300–1,000 units, non-safety electronics approximately 500–2,500, and infotainment approximately 500–2,500. The wide content range within the same powertrain type primarily reflects differences in vehicle segment, ADAS level, and electronic configuration.
The investment implication is that the market should not be extrapolated using a notional average of “10,000 units per vehicle.” The range is wide and does not represent an industry average weighted by vehicle sales. Higher unit content also does not translate into proportionate revenue growth because prices vary significantly by capacitance, voltage rating, and reliability specifications. The most important metrics to track are the share of revenue from automotive-grade products, platform design wins, the mix of high-voltage/high-capacitance products, and the pace at which ADAS features penetrate mass-market and entry-level vehicles.
VII. Data Center Storage: Focus on Capacity Growth, Not Just Unit Shipments
The storage industry is most often misread when demand is judged by drive shipments. Monthly HDD production has fallen from approximately 35 million units in mid-2017 to approximately 10–11.5 million units in recent years, while total production capacity has risen from approximately 70,000 PB to approximately 170,000 PB over the same period, with nearline HDD capacity approaching 155,000–160,000 PB. Falling unit shipments alongside record-high capacity show that cloud providers are buying data capacity per drive bay, not the number of drive enclosures.
The divergence is even more pronounced for SSDs. Total monthly SSD production peaked at approximately 35 million units in 2021 and has since mostly fluctuated between 25 million and 34 million units, while total capacity increased from approximately 3,000–4,000 PB in 2017 to approximately 55,000 PB by the end of 2025. Monthly enterprise/data center SSD production is approximately 5.8 million units, with capacity already at approximately 41,000 PB. Capacity is growing approximately 130%–150% year over year, far faster than unit growth of approximately 40%–50%. For NAND manufacturers, PB and bit shipments provide a more accurate measure of underlying demand than drive volumes.
HDDs and SSDs therefore do not have a simple substitution relationship. In enterprise/data center storage, SSDs account for approximately 45% of unit shipments but only approximately 20% of capacity, while HDDs still carry approximately 80% of PB. SSDs serve the performance tier, while HDDs retain the low-cost, high-capacity tier. Simultaneous growth in training-data archives, video, logs, backups, and real-time inference will instead sustain the long-term coexistence of both media.
TDK provides a good example of how industry strength does not necessarily translate proportionately into company performance. Shipments of its head suspension assemblies recovered from a 2023 low of approximately 24 million units to approximately 52 million units in the first quarter of 2026, but its market share remains only approximately 13%, below the 2021 peak of approximately 20%, with a more concentrated customer base. Rising nearline capacity can increase head content value, but the ultimate earnings sensitivity will also depend on whether TDK can regain market share.
VIII. AI Compute Is Expanding into Custom Chips, Broadening System-Level Component Value
The next phase of AI hardware growth will not rely solely on rising volumes of high-end GPUs. Total data center AI chip shipments are projected to increase from 10.32 million units in 2025 to 28.23 million in 2028, representing a CAGR of approximately 40%. Within this total, high-end GPU shipments are expected to rise from 6.15 million to 10.70 million, a CAGR of approximately 20%, while custom ASIC shipments are projected to increase from 4.17 million to 14.70 million, a CAGR of approximately 52%. GPUs are still growing, but cloud providers are migrating sufficiently large and stable workloads to internally developed or custom chips to reduce inference costs and dependence on a single platform.
Server volumes and value per system are rising simultaneously. AI server shipments are projected to increase from approximately 1.82 million units in 2025 to approximately 4.24 million in 2028, a CAGR of approximately 32%, while their share of global server shipments rises from 15.0% to 21.3%. Custom-chip server shipments are expected to increase from approximately 610,000 units to 1.84 million, a CAGR of approximately 45%. Chips per server are projected to rise from seven to eight, while some rack architectures use eight or even 16 accelerators. Simultaneous increases in server shipments, penetration, and chips per system naturally broaden demand across motherboards, advanced packaging, high-layer-count PCBs, switching networks, optical interconnects, power supplies, thermal management, connectors, and storage.
Compute-related discrete semiconductors have already provided early validation. The total transistor market grew only approximately 0.9% in 2025, while the data-processing/computing-electronics transistor market grew approximately 19.8%. Infineon still holds approximately 26% of the computing-electronics market, but Asian vendors such as Toshiba and Yangjie Technology are growing faster. Vendors outside the top 10 grew approximately 28% in aggregate, above the top 10’s approximately 17% growth. High-power computing increases demand for switching, protection, rectification, and power-conversion devices, and the incremental value will not flow only to established leaders.
The risks to these forecasts are equally clear. Total AI chip shipments are projected to grow approximately 55% in 2026 and 50% in 2027, while custom-chip shipments are expected to grow approximately 83% and 61%, respectively. These projections are highly sensitive to cloud capital expenditure, data center power availability, advanced-packaging capacity, and optical-network deployment. Faster custom-chip growth does not imply declining GPU shipments; both are growing. The real disconfirming evidence would be stagnating AI-server penetration, delayed customer deployments, or an end to increases in power and chip count per system.
IX. The Slope of the Semiconductor Equipment Cycle Will Be Driven Primarily by Memory, Especially DRAM
The largest variable in the next semiconductor equipment upcycle is not logic, but memory. Total industry capital expenditure is projected to increase from approximately US$166.4 billion in 2025 to approximately US$226.9 billion in 2026 and US$316.4 billion in 2027, representing year-over-year growth of approximately 36% and 39%, respectively. Memory capital expenditure is expected to rise from US$77.3 billion to US$114.9 billion and US$185.8 billion over the same period, accounting for approximately 59% of total industry capital expenditure in 2027.
DRAM has the steepest growth trajectory. DRAM capital expenditure is projected to rise from approximately US$59.2 billion in 2025 to approximately US$91.4 billion in 2026 and US$151.6 billion in 2027, representing year-over-year growth of approximately 54% and 66%, respectively. This spending is not limited to adding conventional memory-wafer capacity. HBM requires more die stacking, tighter yield control, more testing, and advanced packaging, increasing the intensity of etch, deposition, cleaning, inspection, and packaging equipment.
Capital expenditure in other segments is less uniformly strong. NAND capital expenditure is projected to rise from approximately US$18.1 billion in 2025 to approximately US$34.2 billion in 2027, a clear recovery but with lower scale and a shallower trajectory than DRAM. Foundry capital expenditure is expected to increase from US$59.1 billion to US$81.8 billion and US$94.0 billion, with strong growth in 2026 followed by a slowdown in 2027. Logic capital expenditure is approximately US$30.0 billion in 2025, remains broadly flat in 2026, and only recovers to approximately US$36.6 billion in 2027. Equipment companies should not all be treated as the same type of cyclical asset. Companies with greater exposure to DRAM, HBM, and advanced packaging will have steeper order trajectories.
These forecasts also represent the largest medium-term overheating risk. DRAM capital expenditure increases by nearly US$100 billion over two years. If HBM supply improves faster than demand or conventional memory pricing weakens, customers may delay equipment acceptance and cut subsequent orders. The validation sequence should be: first, whether memory capital-expenditure forecasts continue to be revised upward; second, equipment orders, delivery lead times, and customer prepayments; and finally, revenue, gross margin, and cash collections.
10. Company Mapping: Buy Product Mix and Market Share, Not a Vague “AI Components” Label
The same industry data translate very differently into earnings across companies. For Murata Manufacturing and Taiyo Yuden, the key variables are the share of high-end multilayer ceramic capacitor products, utilization rates, and blended ASPs. For Hirose Electric, the question is whether a recovery in connector orders from depressed levels can translate into revenue from high-value-added applications. For ROHM and Toshiba, the issue is whether strong growth in computing-related discrete devices can offset a flat overall market. TDK requires simultaneous monitoring of nearline HDD capacity, its share in magnetic heads and suspension assemblies, and high-end passive components.
The Apple RF front-end table offers another warning: “entering the supply chain” does not mean stable content value per device. Skyworks, Broadcom, and Murata all participate in multiple modules, but module counts, integration approaches, and supply shares vary across models. Murata’s dollar content per device fell from approximately US$3 in the iPhone 15 to approximately US$2.5 in the iPhone 16 series, with some subsequent configurations at approximately US$1.5. Looking only at Apple shipments would overlook the greater impact of integration and market share on component revenue.
In-Depth Update on Japanese Electronic Components: April–June Earnings Preview—How Long Can Strong MLCC and ABF Profits Last?
11. From Demand to Cash Flow: Five Hurdles Between an Industry Upturn and Corporate Profitability
Revenue growth for electronic component companies can be decomposed into five variables: end-market unit volumes, content per device, supply share, blended ASP, and exchange rates. In this data handbook, these five variables frequently offset one another: AI server volumes are growing, but total smartphone and PC volumes are declining; MLCC unit volumes are rising, but blended ASPs are falling; nearline HDD capacity is increasing, but TDK’s market share in magnetic heads and suspension assemblies has yet to recover to its previous peak; yen-denominated revenue is strong, while total shipments in US dollar terms remain near zero growth. Therefore, the first hurdle between an “upward industry curve” and “rising corporate revenue” is identifying which strong variable the company is actually exposed to.
The second hurdle is the transition from revenue to gross profit. Higher capacity utilization can reduce depreciation and fixed costs per unit, but gross margin may still decline if incremental output consists primarily of lower-priced products, or if the costs of copper, gold, silver, aluminum, and electrode materials rise. MLCC volume growth accompanied by price declines is a classic example: busier production lines are not sufficient evidence that the share of high-specification products is increasing. Investors must continue to monitor revenue from high-reliability products, customer qualifications, repricing provisions, and material-cost pass-through cycles.
The third hurdle is the transition from gross profit to operating profit. AI servers, high-bandwidth memory, and high-capacity storage all require R&D;, customer qualification, and investment in new equipment. A company may incur R&D; and depreciation expenses before mass production, with operating leverage emerging only after revenue begins to scale. Consequently, a new business’s failure to immediately lift margins in a given quarter does not necessarily mean the project has failed. However, if operating profit does not improve after revenue has scaled for several consecutive periods, the competitiveness of the product or the efficiency of the capacity should be questioned.
The fourth hurdle is the transition from profit to operating cash flow. During periods of order growth, raw materials, work in progress, and accounts receivable often increase first. The income statement may look strong while cash is absorbed by working capital. With inventory days still at approximately 80, the greatest concern is not quarterly revenue missing expectations by one percentage point, but revenue growth coinciding with simultaneous deterioration in inventory, receivables, and cash flow. This combination often indicates that customer pull-through is weaker than production schedules suggest, or that the company has extended payment terms to maintain utilization.
The fifth hurdle is the transition from cash flow to free cash flow. Equipment and high-end component manufacturers increase capital expenditure during upcycles, but there is a major difference between expanding high-end capacity protected by long-term customer qualifications and expanding commodity capacity that is vulnerable to oversupply. If capacity expansion coincides with the projected 2027 peak in storage capital expenditure and customers subsequently reduce demand, free cash flow will face the dual pressure of declining earnings and lagging capital expenditure.
12. Valuation and Scenarios: Do Not Equate Strong Orders Directly With Strong Cash Flow
Industry market capitalization tends to lead the sales cycle over the long term, but the latest market-cap curve has moved significantly ahead of US dollar-denominated sales. The annotation date in the original chart conflicts with the endpoint of the horizontal axis, so the spike should not be cited as a precise valuation datapoint. The direction, however, is already clear: the market is pricing in AI servers, an industrial recovery, and inventory normalization in advance. At this stage, merely “meeting expectations” does not necessarily generate positive returns; earnings forecasts must be raised repeatedly to absorb the valuation.
Raw materials will further amplify earnings dispersion. Copper, aluminum, cobalt, and precious metals are all significantly above their earlier lows at the endpoint of the charts, while volatility has increased. Connectors, cables, printed circuit boards, motors, power supplies, and electroplating are more sensitive to copper and precious metals. Companies that can reprice monthly or quarterly, have high customer-qualification barriers, and have material costs representing a low share of selling prices are better positioned to defend gross margins. When demand recovers but material prices rise faster, revenue growth may be offset by gross-margin compression.
This report does not provide individual-stock target prices, nor is there any need to fabricate precise price targets. It is more useful to tie valuation to verifiable conditions. The base case assumes orders exceed shipments, US dollar-denominated sales gradually turn positive, inventory days decline, and the high-end product mix improves, supporting an earnings recovery without broad-based price increases. The bull case assumes AI servers and custom chips exceed expectations, industrial orders convert into revenue, inventories normalize rapidly, and high-specification components see structural price increases. The bear case assumes the orders-to-shipments ratio declines, sales fail to follow orders, and inventory rises again, alongside reductions in AI infrastructure or storage capital expenditure.
XIII. Conclusion: Focus on Just Eight Delivery Metrics Going Forward
The current electronics-components upcycle is supported by genuine fundamentals, but it is a structural recovery—not a synchronized strong cycle across all end markets, product categories, and companies. Servers, custom chips, enterprise storage capacity, and industrial orders are driving the upside, while weakness in smartphones and mainstream PCs, elevated inventory days, and declining blended MLCC prices preclude a simplistic extrapolation of industry beta.
Going forward, tracking eight metrics monthly and quarterly should suffice: book-to-bill ratios for Murata, Taiyo Yuden, ROHM, and Hirose; year-on-year growth in industry shipments in US dollar terms; inventory days; blended MLCC prices and the share of high-specification products; nearline HDD petabytes and enterprise SSD petabytes; AI server and custom-chip shipments; DRAM capital expenditure and equipment orders; and, finally, each company’s gross margin and operating cash flow. Only if all eight sets of indicators improve simultaneously will the structural recovery develop into an earnings cycle. If orders are strong but sales, inventories, and cash flow fail to follow, current valuations are simply pulling forward future expectations.
The investment approach is therefore clear: first identify products that translate high-power, high-capacity, high-bandwidth, and high-reliability requirements into greater content per system; then identify companies with certification advantages, market share, and capacity discipline; and finally use inventories, pricing, gross margins, and cash flow to validate revenue quality. As long as this sequence is maintained, investors will neither mistake a one-off restocking cycle for secular growth nor overlook companies delivering genuine content upgrades amid subdued aggregate demand.