
目录
TL;DR
I. Behind the Eight Questions: Profit Levels, Duration, and Valuation Transmission
II. HBM Prices Rising Nearly 100%: Fundamentally a Premium and Margin Reset
III. Long-Term Agreements: The Key to Whether the Memory Cycle Can Command a Higher Valuation
IV. Inventory and NAND: Localized Noise Does Not Equate to an Industry-Wide Reversal
V. China’s DRAM Supply: No Near-Term Change to HBM, but a Long-Term Reshaping of Conventional DRAM
VI. Shareholder Returns and ADRs: Can Profits Truly Accrue to Per-Share Value?
VII. Q2 Variance: Demand Remains Intact, but Pricing Timing and Product Mix Fell Short
VIII. Samsung Electronics and SK hynix: Buying the Catch-Up Versus Buying the Leader
9. The Eight Key Validation Points to Monitor Next
Conclusion: The Core of This Re-Rating Is Not That “Memory Is No Longer Cyclical”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Goldman Sachs uses 8 questions to explain the sharp sell-off in memory stocks. The market is reassessing how long high profits can persist, whether they can convert into cash, and what valuation they deserve.
TL;DR
These 8 questions are not 8 isolated positives, but a 3-tier valuation chain: HBM, inventories, NAND, and incremental DRAM supply determine the level of profits; long-term agreements determine their duration; and shareholder returns and ADRs determine whether profits translate into per-share value. SK Hynix’s 2Q variance tests whether the entire forecast is credible.
Goldman Sachs expects the blended HBM ASPs of Samsung Electronics and SK Hynix to rise approximately 87% and 100% YoY, respectively, in 2027, approaching US$2.9/Gb. The more accurate interpretation is not that “the same product suddenly doubles in price,” but that like-for-like prices for core products increase by approximately 60%, with the remainder coming from a higher mix of premium products such as HBM4.
The underlying reason for HBM price increases is that the blended ASP of conventional DRAM briefly exceeded that of HBM in 2026. HBM has higher costs and slower annual price negotiations; if it cannot re-establish a premium in 2027, suppliers will lose the incentive to expand capacity. Next year’s negotiations therefore look more like a “margin reset” than merely a shortage-driven price increase.
Long-term agreements are the most important valuation variable in this report. Contract terms are extending to 5 years, coverage is rising toward 60%—70% of planned capacity, and pricing is shifting from fixed prices to price ranges and floor prices. Combined with deposits, prepayments, and take-or-pay provisions, these changes are turning customers’ shortage concerns into verifiable commitments.
However, long-term agreements are not risk-free annuities. Price caps may limit suppliers’ upside during extreme price increases; deposits ultimately need to be returned and do not equal free cash flow; and terms differ by customer. What investors should actually track is contract coverage, gross margins at floor prices, cancellation costs, and accounting recognition—not merely whether an LTA has been signed.
Inventories and NAND do not yet support a cycle-peak thesis. Goldman Sachs estimates that suppliers hold only 2—4 weeks of DRAM and NAND inventories, below the normal 4—5 weeks and the more than 10 weeks seen before downcycles; enterprise SSD demand is expected to increase from 474EB in 2026 to 755EB in 2028. The pullback in TLC 512Gb spot prices looks more like a product-specific correction after a nearly 600% increase.
Incremental Chinese DRAM supply is more likely to affect domestically produced mature products such as LPDDR4(X) in the near term than to immediately alter the tight global HBM balance. The real medium-term risk is that Chinese suppliers gradually broaden their product-generation and customer coverage, creating regionalized and segmented competition in conventional DRAM; “no impact on HBM for now” must not be misread as “no impact on the industry ever.”
The 2 companies are not the same type of asset. SK Hynix offers exposure to HBM leadership, product-mix recovery, and ADR-driven valuation discovery; its weakness is concentrated expectations, as even modest deviations in market share and ASP can amplify volatility. Samsung Electronics offers exposure to HBM catch-up, a full memory product portfolio, and shareholder-return upside; its weakness is that its business breadth also dilutes memory profits.
I. Behind the Eight Questions: Profit Levels, Duration, and Valuation Transmission
Over the past month, Samsung Electronics and SK Hynix shares have fallen 23% and 35%, respectively. Goldman Sachs attributes the pullback to 6 concerns: weakening memory price expectations, insufficient detail on long-term agreements, rising inventories at module manufacturers, increasing Chinese DRAM supply, the lack of concrete shareholder-return measures, and SK Hynix’s 2Q operating profit falling below market consensus.
On the surface, this is a mixed list spanning pricing, inventories, competition, capital returns, and quarterly results; the more useful framework is to place them within a single valuation chain.
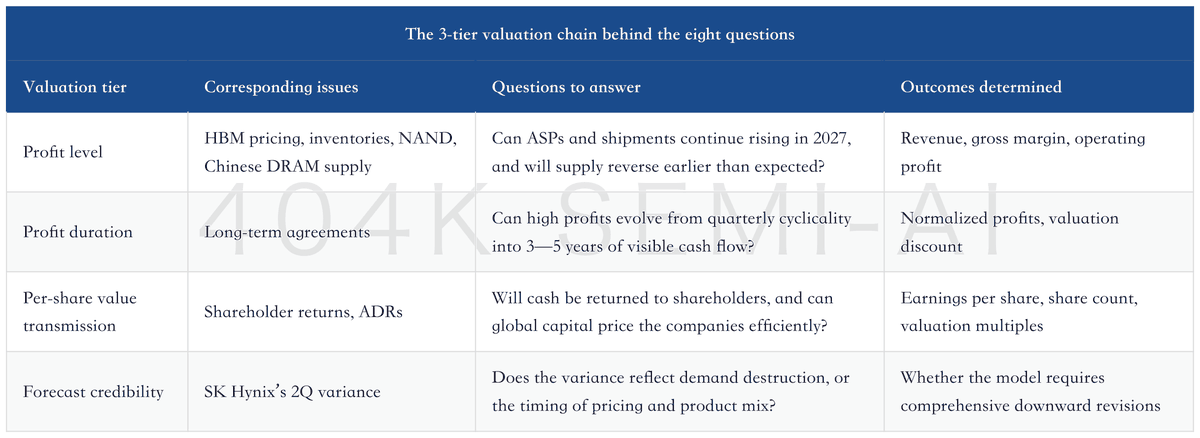
Goldman Sachs notes that, following the pullback, Samsung Electronics trades at approximately 3.6x 2027E P/E and 1.4x P/B, while SK Hynix trades at approximately 3.5x and 1.6x, respectively. Such low P/E multiples do not mean the market has failed to recognize high profits; rather, it treats current profits as an unsustainable peak. The report is therefore not really trying to prove that “the companies can still make money next year,” but to determine how much peak profit can convert into more durable normalized profit.
II. HBM Prices Rising Nearly 100%: Fundamentally a Premium and Margin Reset
Goldman Sachs expects the blended HBM ASPs of Samsung Electronics and SK Hynix to approach US$2.9/Gb in 2027, rising approximately 87% and 100% YoY, respectively. This is an eye-catching figure, but also the one most susceptible to misinterpretation.
First, blended ASP does not represent the quoted price of the same product. Goldman Sachs estimates that like-for-like prices for core products will rise approximately 60%, with the remaining increase coming from HBM4 volume ramp-up, higher stack counts, and a higher-value customer mix. In other words, simultaneous improvements in pricing and product mix produce the near-doubling in blended ASP.
Second, the 2026 base is unusual. HBM pricing is generally negotiated annually, with contracts remaining relatively stable during the year; conventional DRAM prices are updated monthly or quarterly and reflect shortages more quickly. Goldman Sachs estimates that conventional DRAM ASP will rise from approximately US$0.5—0.6/Gb at end-2025 to approximately US$2/Gb at end-2026, causing conventional DRAM to exceed HBM as early as 2Q26. It is difficult to sustain a situation in which higher-cost, technologically more complex HBM carries no premium.
Third, effective supply growth for next-generation HBM is slower than nominal capacity growth. Core dies and base dies use more advanced processes, stack counts are increasing, and yield and packaging complexity are rising; each HBM generation also displaces a growing proportion of conventional DRAM wafers. On this basis, Goldman Sachs expects the HBM supply-demand deficit to widen from -5.4% in 2026 to -6.0% in 2027.
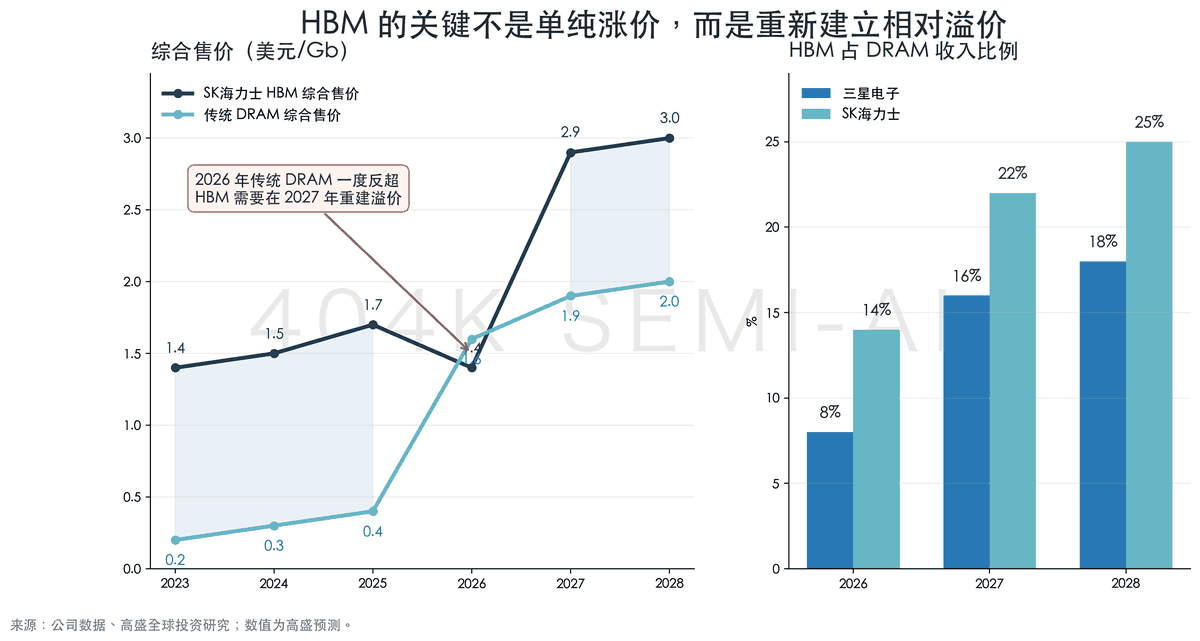
What truly matters is not whether US$2.9/Gb is achieved precisely, but whether HBM can re-establish a per-unit premium over conventional DRAM and generate margins sufficient to cover the additional process, packaging, and yield costs. If like-for-like prices rise close to 60% and the product mix continues to improve, Goldman Sachs’s directional thesis holds; if LTA price caps constrain HBM4 pricing, yields improve faster than expected, or customers adopt multiple suppliers, the nearly 100% increase in blended ASP will be materially reduced.
Samsung Electronics’ official materials have confirmed that HBM4 uses 1c DRAM and a 4nm logic base die, and that mass-production shipments have begun; the company expects 2026 HBM revenue to increase by more than 2x versus 2025. SK Hynix has shipped HBM4 and provided customers with samples of 12-layer HBM4E. Official materials demonstrate that the technology roadmap and product migration are underway, but they do not commit to Goldman Sachs’s projected 2027 pricing; therefore, “mass-production progress” and “ASP realization” must still be verified separately.
III. Long-Term Agreements: The Key to Whether the Memory Cycle Can Command a Higher Valuation
If only one variable were selected as the most important in this report, it would not be HBM price increases, but the enforceability of long-term agreements. Price increases raise profits; binding contracts determine whether those profits can be discounted forward by the capital markets.
Goldman Sachs identifies 4 changes. Contract terms are primarily 5 years, while Samsung Electronics also uses annual rolling extensions; coverage has increased from an initial target of approximately 50% to the 60%—70% of planned capacity cited by Samsung Electronics; pricing is gradually shifting from fixed prices to price ranges or floor prices; and contractual enforceability is being upgraded from ordinary purchase intentions to deposits, prepayments, and take-or-pay provisions.
Micron Technology’s official disclosures provide the clearest industry example: the company has signed 16 strategic customer agreements covering approximately 20% of its DRAM volume and one-third of its NAND volume during the contract periods, with the goal of eventually placing more than half of its revenue under agreements. The remaining contract revenue from 14 agreements, calculated at minimum prices, is approximately US$100 billion; the company expects to receive US$22 billion in cash deposits and related financial commitments, including approximately US$18 billion in cash deposits. Most agreements have fixed prices or minimum and maximum prices and require customers to purchase agreed volumes.
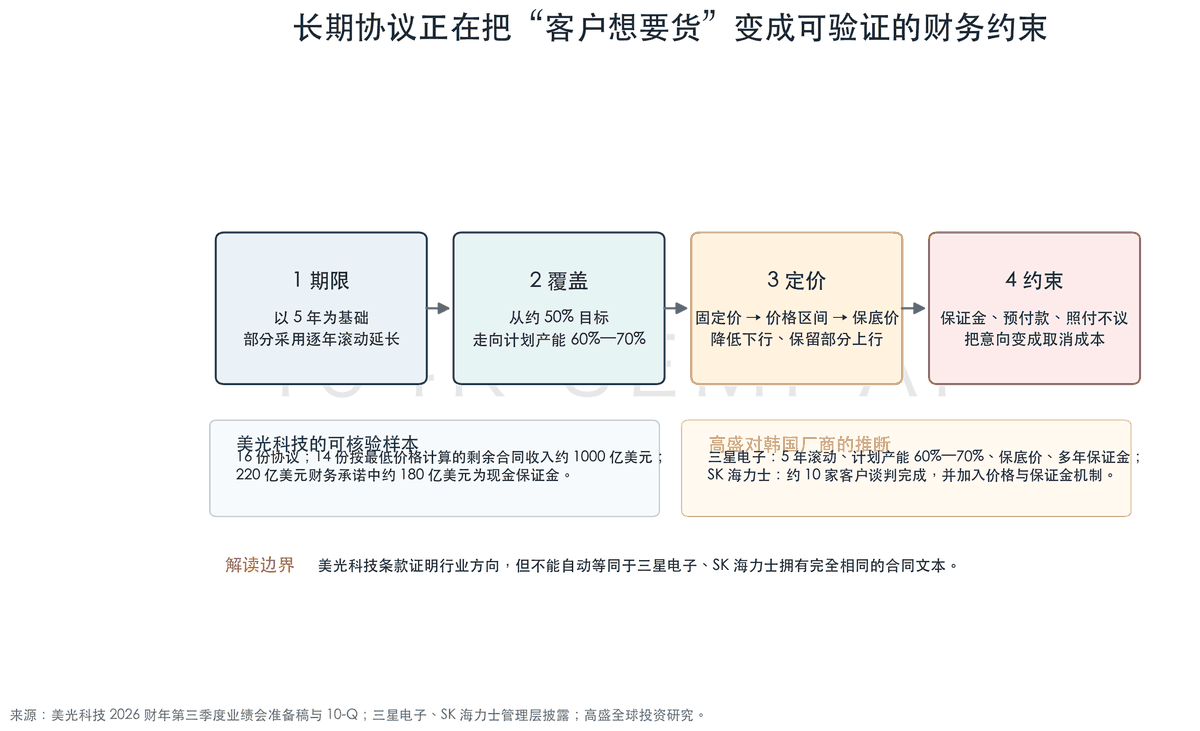
This demonstrates that the memory business model is indeed changing, but Micron Technology’s terms cannot be mechanically applied to Samsung Electronics and SK Hynix. Goldman Sachs’s assessment of Samsung Electronics includes 5-year rolling terms, coverage of 60%—70% of planned capacity, floor prices, and multi-year deposits; SK Hynix management has only explicitly stated that negotiations with approximately 10 customers have been completed, contract terms are typically approximately 5 years, and mechanisms addressing price volatility and ensuring contract performance have been included. Neither company has yet disclosed minimum contracted revenue with the same level of granularity as Micron Technology.
Three accounting and economic boundaries require particular attention. First, price caps can reduce customer risk, but may also limit supplier upside when spot prices surge. Second, deposits strengthen contractual commitments, but Micron Technology has explicitly stated that the associated cash is classified as financing cash flow and will be returned to customers at a later date; it is not free cash flow or profit. Third, the agreements lock in volumes and pricing boundaries, but do not eliminate failed technology transitions, insufficient yields, or customer product delays.
Long-term agreements therefore reduce volatility, not risk itself. Only when coverage, gross margins at floor prices, cancellation costs, receipt of customer deposits, and alignment with capital expenditure are all confirmed will the market have reason to re-rate peak P/E multiples of 3—5x to a more stable normalized valuation.
IV. Inventory and NAND: Localized Noise Does Not Equate to an Industry-Wide Reversal
Rising module-maker inventories are the most visible negative behind this correction. Goldman Sachs does not dispute that smartphone and PC demand is weak or that module makers have increased restocking, but it believes this channel accounts for only a single-digit share of the overall memory market, with a greater impact on sentiment than on industry-wide supply and demand.
Supplier inventories are more important. Goldman Sachs estimates that DRAM and NAND inventories were both at 2—4 weeks at the end of Q2 2026, below the normal 4—5 weeks and far below the more than 10 weeks commonly seen before a downcycle. Much of the memory purchased by server customers is used for just-in-time production, and customer inventories also appear broadly normal. Unless supplier inventories continue rising above 5 weeks, the probability of a sudden price reversal remains low.
Inventory days disclosed by different companies should not be compared directly. Micron Technology reported US$8.6 billion of inventory and 120 inventory days at the end of its fiscal Q3, including work in progress, raw materials, and products with different production cycles; Goldman Sachs’ 2—4 weeks is closer to a specific measure of memory supply. Accounting inventory and weeks of saleable finished goods are not the same metric. The real warning signal would be a simultaneous deterioration in finished-goods inventory, channel inventory, accounts receivable, and pricing.
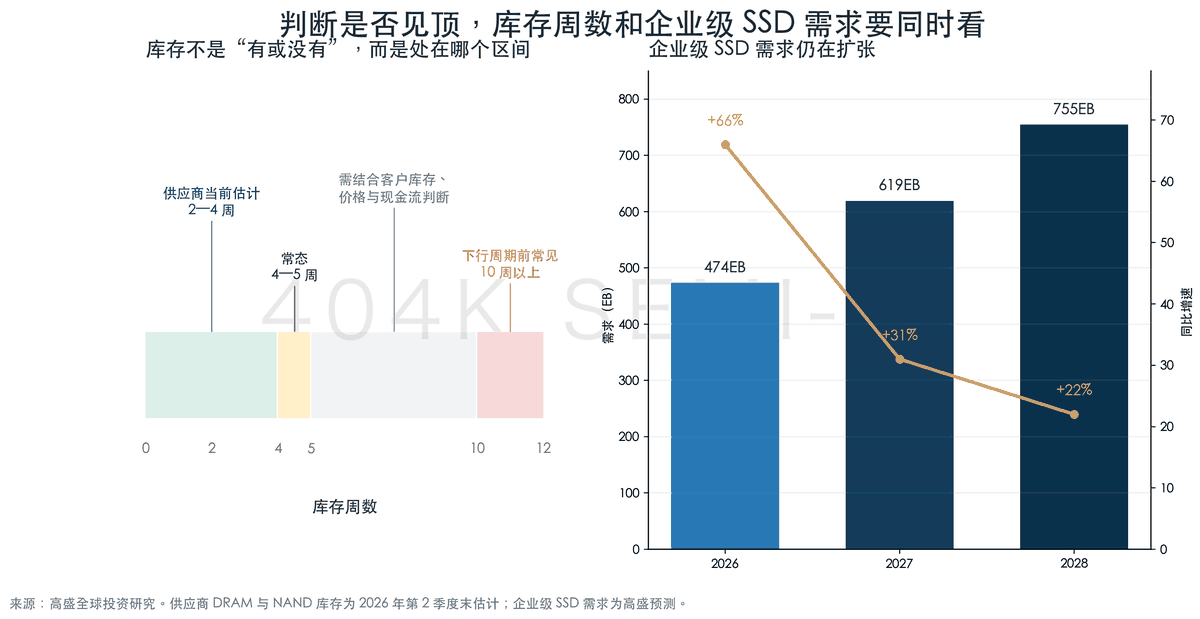
NAND also requires a segmented view. Goldman Sachs expects enterprise SSD demand to reach approximately 474EB, 619EB, and 755EB in 2026—2028, representing year-on-year growth of 66%, 31%, and 22%, respectively. Major suppliers are directing capital expenditure more toward DRAM, while NAND investment is focused on technology migration rather than substantial wafer-capacity additions. Goldman Sachs therefore believes NAND supply and demand will be tighter in 2027 than in 2026, although still not as tight as DRAM and HBM.
The recent correction in TLC 512Gb spot prices is insufficient to prove broad-based oversupply. This category rose nearly 600% over the past 1 year, materially above the more than 400% increase for most products; TLC 1Tb pricing has been more stable. A more reasonable explanation is a correction in a single specification after an outsized rally. Only if enterprise SSD capacity demand is revised down, NAND equipment investment is brought forward, supplier finished-goods inventories rise, and contract prices across multiple specifications begin to decline would there be evidence that a localized correction has escalated into industry-wide oversupply.
V. China’s DRAM Supply: No Near-Term Change to HBM, but a Long-Term Reshaping of Conventional DRAM
Goldman Sachs believes Chinese DRAM manufacturers will first expand in the domestic market, with mobile DRAM still centered on LPDDR4(X); the report estimates that approximately 70% of their mobile DRAM bit shipments in 2026 will come from LPDDR4(X), while approximately 75%—85% of Samsung Electronics’ and SK hynix’s shipments have already shifted to LPDDR5(X). In process technology, Goldman Sachs believes the two sides remain approximately 2—3 generations apart.
For HBM, the barriers extend beyond the DRAM die itself. Transmission speed, power consumption, stacking yield, advanced packaging, base dies, and joint customer validation are all indispensable, while subsequent generations will also require supporting domestic advanced-process capacity. Consequently, incremental supply is less likely to directly alter the tight global HBM balance in the short to medium term.
However, this does not mean the impact can be ignored. Competition will first emerge in LPDDR4(X) and certain conventional DRAM products. A higher procurement share for domestic brands will reduce the incremental growth available to Samsung Electronics and SK hynix in the relevant markets; if product generations, yields, and customer validation subsequently improve, the pressure will spread to LPDDR5(X) and server DRAM. Overall global supply and demand may remain tight, but pricing will begin to diverge across regions, products, and customers.
The investment assessment should therefore avoid two extremes: the technology gap does not mean incremental supply will remain ineffective forever, while increased wafer capacity does not mean HBM will immediately become oversupplied. The first indicators to monitor are LPDDR4(X) pricing and domestic market share, followed by advanced-node shipments and server-customer validation, and only then HBM performance, yields, and major-customer certification.
VI. Shareholder Returns and ADRs: Can Profits Truly Accrue to Per-Share Value?
If high profits are entirely reinvested in capacity expansion, shareholders may not benefit immediately. Both Samsung Electronics and SK hynix are rapidly increasing investment, prompting the market to demand clearer dividend and buyback policies.
Samsung Electronics’ current 3-year shareholder-return policy will expire in 2026 and targets returning 50% of 3-year free cash flow. Goldman Sachs believes the market’s expectation of a KRW 8,638 dividend per share in 2026 is insufficient to fully meet this commitment and has revised its own forecast to KRW 9,500. The real catalyst is not a verbal commitment to “review various options,” but whether the next policy cycle clearly establishes the sequencing among common-share buybacks, share cancellations, special dividends, and future capital expenditure.
SK hynix’s situation is more complex. The company generates substantial cash while also requiring significant capital investment in M15X, advanced packaging, and subsequent capacity. ADR issuance and higher returns on investment assets have added non-operating cash but have also resulted in equity dilution. Buybacks and share cancellations can both return capital to shareholders and partially offset ADR dilution, giving them greater informational value than a one-off special dividend.
ADRs do not automatically eliminate the discount on Korean common shares. Goldman Sachs calculates that since SK hynix’s ADR listing on July 10, the ADRs have traded at an average premium of approximately 26% to the common shares, with the latest premium at approximately 30%. This is because ADR issuance represents only approximately 2.4% of total shares outstanding, while conversion is not fully unrestricted in both directions: ADRs can be converted into common shares, but converting common shares into ADRs is subject to procedural and volume restrictions. Additional ADR issuance is expected to narrow the pricing gap and broaden international institutional coverage, but the premium may persist over the long term unless fungibility becomes complete.
The primary value of ADRs to the common shares is therefore “price discovery,” not risk-free arbitrage. If international investors continue purchasing ADRs at higher multiples and the company expands ADR supply while improving two-way conversion, the common-share discount may gradually narrow; if new issuance merely increases dilution and buybacks fail to keep pace, the common shares may not benefit in tandem.
VII. Q2 Variance: Demand Remains Intact, but Pricing Timing and Product Mix Fell Short
SK hynix reported Q2 2026 revenue of KRW 79.3 trillion, up 51% quarter on quarter and 257% year on year; operating profit was KRW 60.5 trillion, up 61% quarter on quarter and 557% year on year. Operating profit was broadly in line with Goldman Sachs’ forecast but approximately 7% below Bloomberg consensus.
The variance primarily reflected a 29% quarter-on-quarter increase in blended DRAM pricing, below Goldman Sachs’ previous estimate of 39%. Some conventional DRAM orders used prices negotiated in advance, while blended HBM pricing did not fully reflect higher-priced products because the improvement in the HBM4 mix was limited. This gap appears more attributable to revenue-recognition timing and product mix than to a sudden disappearance of customer demand.
Goldman Sachs expects Q3 DRAM bit shipments to increase 10% quarter on quarter and blended pricing to rise 19%, with operating profit reaching approximately KRW 77 trillion as HBM4 and 1c DRAM ramp. This forecast requires two points of validation: first, HBM4 shipments must translate into higher blended pricing; second, the impact of advance pricing agreements for conventional DRAM must not continue to widen. If shipments grow but blended pricing still lags materially, it would indicate that pricing ceilings or product-mix issues are more severe than Goldman Sachs assumes.
There is also an easily overlooked earnings-quality issue in the valuation. SK hynix’s Q2 results included approximately KRW 63 trillion of investment-asset-related gains, prompting Goldman Sachs to raise its 2026 EPS forecast by 20%, but these gains were not memory operating profit. The KRW 3.5 million price target is calculated using average 2026—2027 EPS of KRW 416,265 and a P/E multiple of approximately 9x. When assessing the price target, investors should separate one-off investment gains from DRAM and NAND operating cash flow to avoid using non-recurring earnings to justify a long-term valuation.
VIII. Samsung Electronics and SK hynix: Buying the Catch-Up Versus Buying the Leader
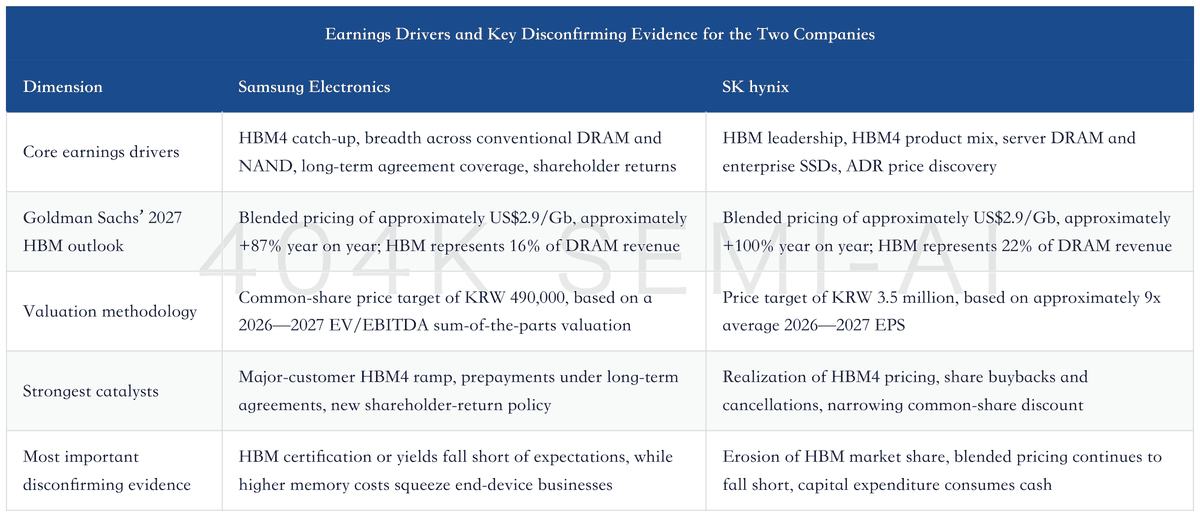
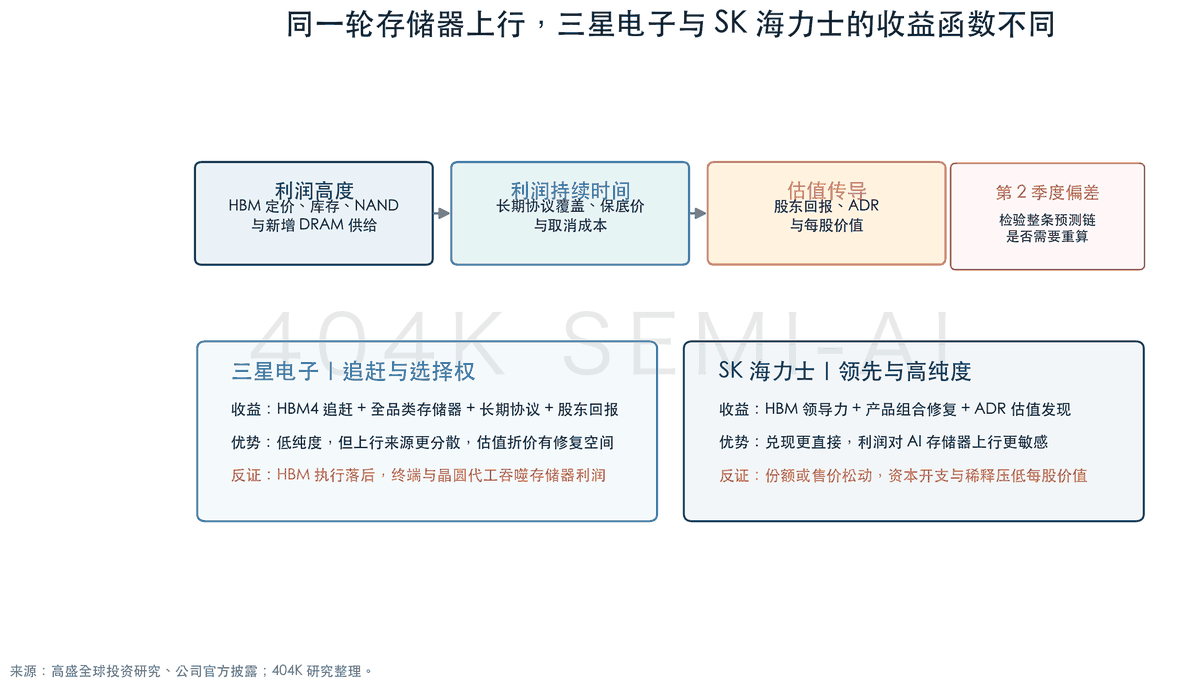
Samsung Electronics’ advantage is optionality. Even if its HBM share trails SK hynix, a successful HBM4 catch-up, sustained high profitability in conventional DRAM and NAND, and stronger shareholder returns would create scope for its valuation discount to narrow. Its weakness also stems from its business breadth: smartphones, displays, and foundry operations may absorb the profits generated by the memory upcycle.
SK hynix’s advantage is execution visibility. Its HBM leadership, advanced packaging, and AI-server products offer more direct exposure, making revenue and profit more sensitive to the memory upcycle. Its weakness is concentrated expectations: once the market begins to question its HBM share, pricing, or yields, its valuation will contract more quickly than that of a diversified company.
Viewed together, Goldman Sachs’ buy thesis is not about “which is cheaper,” but about two different payoff profiles. Samsung Electronics is more akin to a lower-purity catch-up asset with high optionality, while SK hynix is a higher-purity leading asset with greater sensitivity to expectations. Investors should choose based on their assessment of the HBM competitive landscape, long-term agreements, and capital returns, rather than merely comparing static P/E multiples.
9. The Eight Key Validation Points to Monitor Next
Over the next 12 months, the most informative signal will not be daily movements in memory stocks, but whether the following eight pieces of evidence align:
Whether the like-for-like HBM price increase in 2027 approaches 60%, and whether the HBM4 product mix can push the blended selling price toward US$2.9/Gb.
Whether the long-term agreements covering 60%—70% of Samsung Electronics’ planned capacity are ultimately signed, and whether deposits and price floors are formally disclosed.
Whether the coverage, pricing ranges, and deposits under SK hynix’s agreements with approximately 10 customers are quantified further.
Whether suppliers can maintain DRAM and NAND inventories at 2—4 weeks, and whether module inventories spread to server customers and OEMs.
Whether enterprise SSD demand can grow along the 474EB, 619EB, and 755EB trajectory, and whether TLC price adjustments extend to more specifications.
Whether Chinese DRAM manufacturers expand beyond LPDDR4(X) into more advanced products and secure validation from server customers.
Whether Samsung Electronics’ new shareholder-return policy and SK hynix’s share repurchases and cancellations convert high free cash flow into per-share value.
Whether SK hynix’s third-quarter DRAM shipments, blended selling price, and operating profit validate an improved product mix, rather than continuing to fall short of expectations.
If pricing, contracts, inventories, and cash flow all validate simultaneously, the current low P/E multiples are more likely to represent excessive discounting of peak earnings; if long-term agreements specify only volumes without price floors, inventories continue to rise, enterprise SSD demand slows, and capital expenditure expands ahead of schedule, the low P/E multiples may instead be a classic value trap at the top of the cycle.
Conclusion: The Core of This Re-Rating Is Not That “Memory Is No Longer Cyclical”
The most valuable aspect of Goldman Sachs’ report is not its eye-catching forecast that HBM will nearly double by 2027, but how it connects three questions about the memory cycle: how high profits can rise, how long they can be sustained, and whether they can ultimately translate into per-share value.
The restoration of HBM premiums determines the level of profitability; long-term agreements link demand, pricing, and capital expenditure, determining how long profits can be sustained; shareholder returns and improved ADR valuation transmission determine the multiple the market is willing to assign. Inventories, NAND, and incremental DRAM supply are the counter-evidence to this thesis.
Accordingly, the appropriate conclusion is not that memory has escaped the cycle. A more accurate characterization is that this cycle is being extended by firmer contracts, higher technological barriers, and stronger cash flow, but it still must withstand continued scrutiny of price ceilings, supply expansion, customer diversification, and capital expenditure. Whether the low valuations of Samsung Electronics and SK hynix can recover ultimately depends on this evidence, not on a single price target or one share-price rebound.