
Dongshan Precision Deep Dive: From Consumer Electronics Manufacturing to an AI Optical Interconnect Platform, and How Source Photonics, Optical Chips, and AI PCBs Should Be Re-rated
目录
Too Long; Didn’t Read
I. Investment Conclusion: The Market Is Buying an Optical Platform; the Debate Is How Far Valuation Has Already Run
II. From Old Assets to New Assets: Dongshan’s Change Is a Shift in Profit Pools, Not More Themes
III. 2026 Q1 Earnings: This Strong Growth Officially Puts Source Photonics Into the Income Statement
IV. Source Photonics: Dongshan Precision’s Real Value Lies in Optical Chip and Module Integration
V. US$1.2 Billion Expansion: It Raises Order Confidence, but Also Raises ROI Pressure
VI. AI PCB: DSBJ’s Second Growth Leg, Harder to Validate Than Optical Modules
VII. Sell-Side Divergence: Citi Buys Orders, BofA Buys Discipline, HSBC and UBS Record Early-Stage Transformation Noise
VIII. Valuation Framework: DSBJ Is Suited to SOTP, but Every Segment Needs a Discount
9. Three Scenarios: What This Company Fears Most Is Growth Quality Falling Short of Valuation
10. Tracking List for the Next Four Quarters: Use These Numbers to Judge Whether the Re-Rating Continues
11. Falsification Checklist: Order Quality and Cash Collection Determine the Durability of the Re-Rating
12. Conclusion: Dongshan Precision Has Become an AI Optical Platform, but Pricing Must Wait for Profits to Keep Catching Up
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core of Dongshan Precision’s current re-rating is that Source Photonics brings optical modules, optical chips, and AI PCBs into the same delivery system. The US$1.2bn capacity expansion raises long-term order expectations, while also shifting the valuation debate to cash flow, yield, and delivery of effective AI PCB capacity. The key question now is whether earnings can catch up with market-cap expectations.
Too Long; Didn’t Read
Dongshan has entered the validation phase. 2026Q1 revenue was RMB13.138bn and net profit attributable to shareholders was RMB1.110bn. Optical modules have already been consolidated into the income statement; the next focus is whether high-margin businesses can cover M&A; loans, depreciation, and working capital.
Source Photonics determines valuation elasticity. The company has capabilities in 400G, 800G, and 1.6T modules, as well as 100G/200G PAM4 EML and CW lasers. Modules support earnings; optical chips support customer stickiness and valuation multiples.
The US$1.2bn expansion amplifies disagreement. BofA raised its target price to RMB270 but maintained Neutral, while Citi places more weight on order visibility. The debate has shifted to whether the share price has already discounted forward earnings.
AI PCB is the second growth leg. Multek has capabilities in high-layer-count and thick-board HDI. 2026Q1 construction in progress increased 46.96% from the beginning of the year; customer qualification, materials, and yield will determine the pace of monetization.
Legacy businesses provide the cash-flow base. FPC, traditional PCB, precision components, and GMD can stabilize revenue, but the valuation ceiling still depends on the ramp of 800G, 1.6T, EML, and AI PCB.
Track four hard indicators. Over the next four quarters, monitor 800G orders, 1.6T mass production, external laser sales, AI PCB revenue, and free cash flow. If any link slows, the high multiple will contract first.
I. Investment Conclusion: The Market Is Buying an Optical Platform; the Debate Is How Far Valuation Has Already Run
The most important question for Dongshan Precision is straightforward: can it transform from a consumer electronics manufacturer into an AI optical interconnect platform company? The previous 404K SEMI-AI deep-dive report on Dongshan Precision already placed Source Photonics, GMD, and AI PCB into the same asset re-rating framework. The additional materials in June pushed the issue further forward. After the company announced a US$1.2bn investment through Source Photonics to expand optical chip and optical module capacity, the market’s question became: can this capex cycle translate into orders and earnings of sufficiently high quality?
Dongshan Precision Deep Dive: From Consumer Electronics Precision Manufacturing to an AI Optoelectronics Platform — How Source Photonics, GMD, and AI PCB Should Be Re-rated
The core judgment is direct: Dongshan Precision’s asset label has changed, and valuation discipline must change with it. In the past, it was mainly framed as an Apple supply-chain, FPC, traditional PCB, and automotive precision-parts company. Source Photonics now brings it into the framework of AI optical modules, EML optical chips, CW lasers, 1.6T, and CPO/NPO-related light sources, while Multek allows the company to retain an adjacent AI PCB profit pool. This combination makes the company more complex than an ordinary PCB manufacturer, and more asset-heavy than an ordinary optical module vendor.
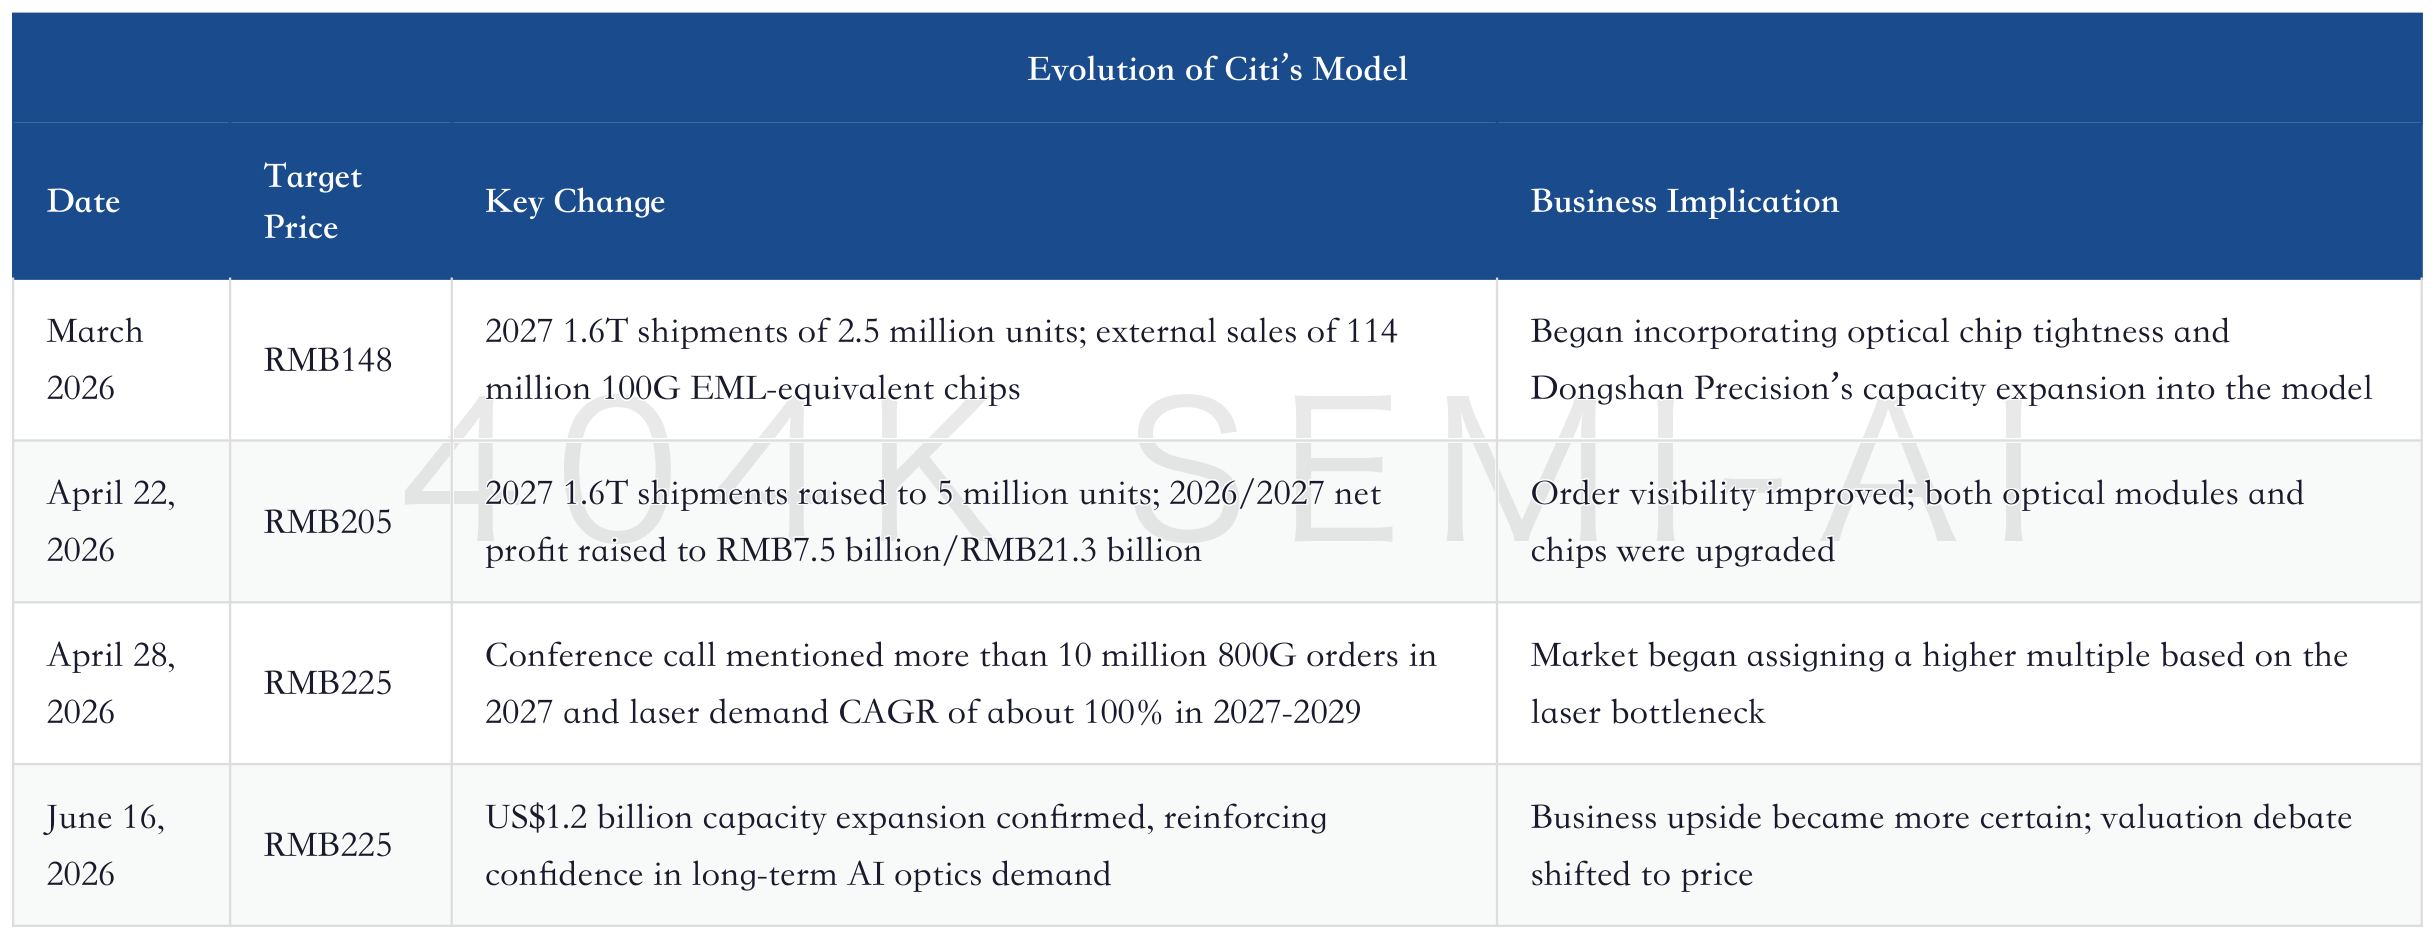
The divergence between BofA and Citi illustrates exactly where the market stands. BofA raised its target price several times in June but maintained Neutral, arguing that the share price already reflects substantial expectations. Citi continued to raise its target price in the spring, placing more emphasis on order visibility and the demand confidence implied by optical capacity expansion. Both sides acknowledge that the business is strengthening. The difference is that Citi is more willing to price in forward orders and the optical chip bottleneck, while BofA is more focused on how much has already been reflected in the share price.
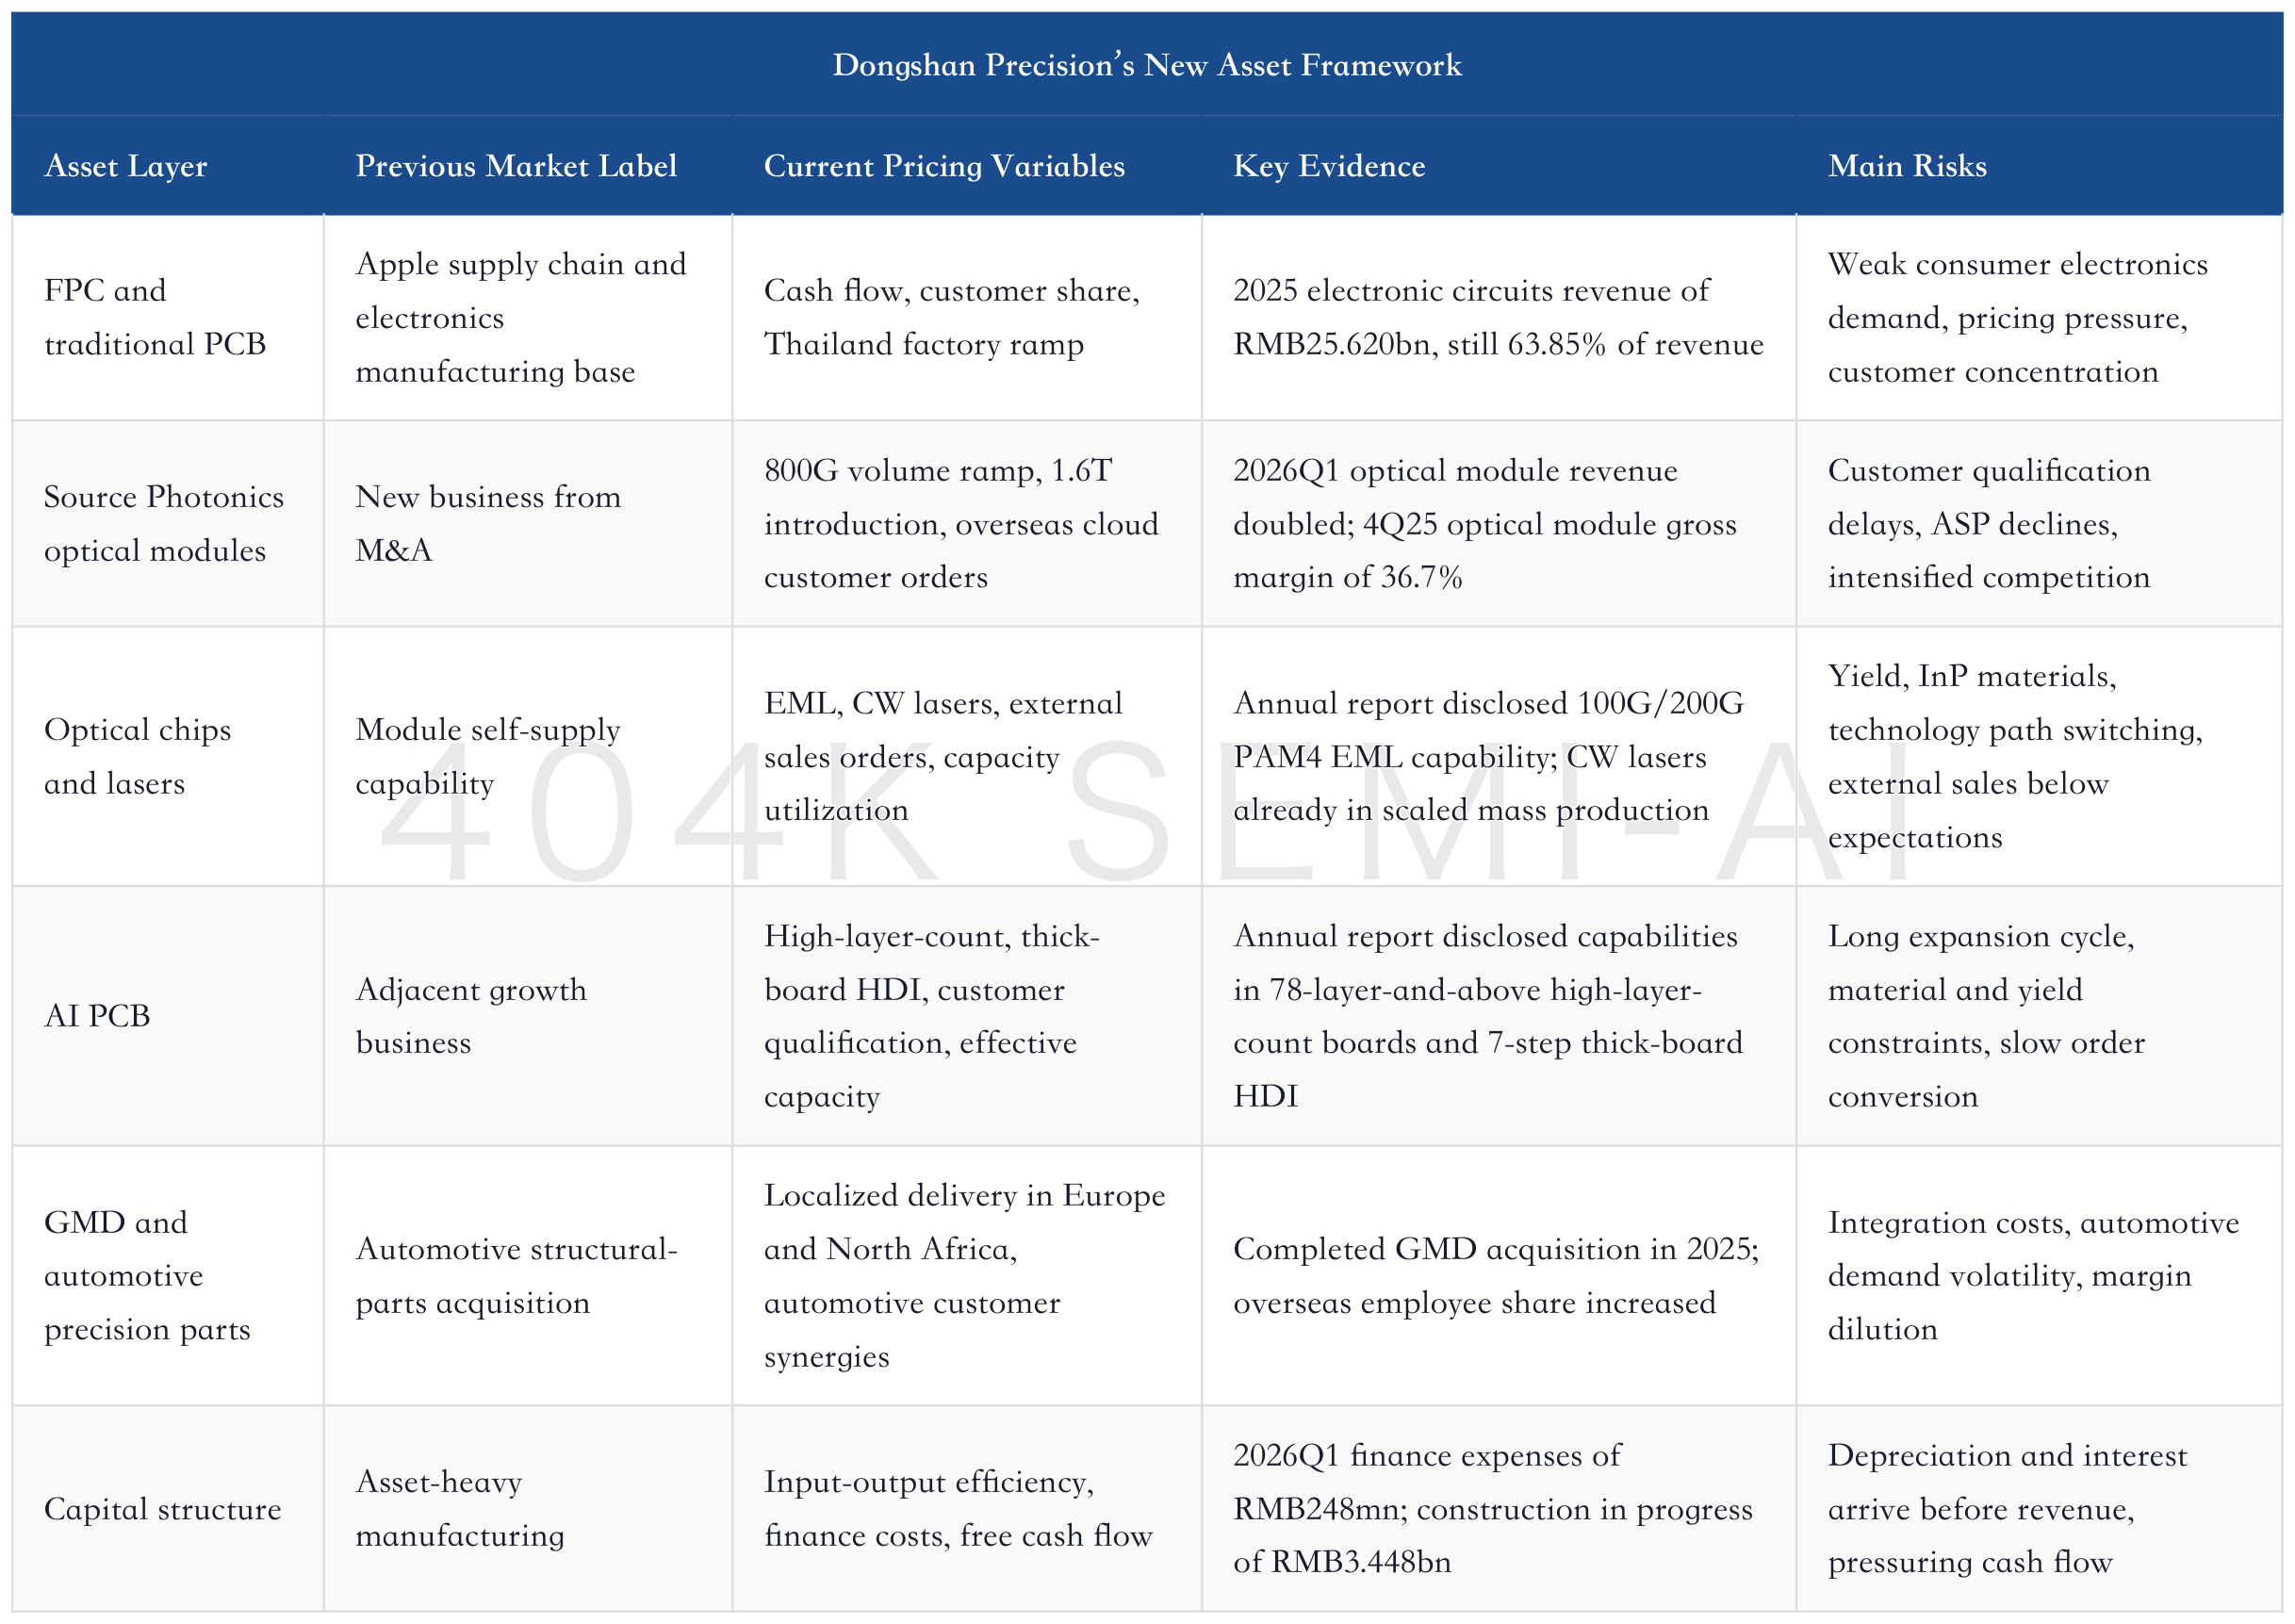
How to read this table matters. Dongshan’s re-rating earnings elasticity is concentrated in Source Photonics and AI PCB, while FPC, consumer electronics PCB, precision components, and GMD mainly determine the base and risk resilience. The real determinants of the market-cap ceiling are whether optical module revenue can sustain high growth, whether optical chips can become a bottleneck asset, and whether AI PCB can move from expansion announcements to high-margin revenue.
For investment purposes, two questions must be separated. At the business level, Dongshan has moved from “having a story” to “having income-statement evidence”; the first-quarter report showed strong growth in revenue, net profit attributable to shareholders, and recurring net profit. At the valuation level, the market has already priced in substantial expectations. The reported price is close to BofA’s target price, and forward multiples are not low. A stronger business does not automatically mean a cheap stock; going forward, earnings must continue to compress valuation.
II. From Old Assets to New Assets: Dongshan’s Change Is a Shift in Profit Pools, Not More Themes
Dongshan Precision’s historical assets are clear. The company started with precision manufacturing, then entered FPC through MFLEX, filled out rigid PCB, rigid-flex boards, and high-end multilayer boards through Multek, entered optical modules and optical chips through Source Photonics, and entered European automotive structural parts through GMD. In the past, these assets looked somewhat scattered. The AI data-center cycle has reconnected them: GPU/ASIC servers require high-speed PCBs, switches require high-layer-count boards and low-loss materials, optical modules require EML and CW lasers, and the automotive and consumer electronics base provides cash flow and global manufacturing management capabilities.
The annual report provides a useful static snapshot. Electronic circuit products remain the main revenue base. Optical module revenue still accounts for a low share, but gross margin is significantly higher, as shown below. This comparison explains why the market is willing to re-rate Dongshan: optical modules are still small in scale in the short term, but have much stronger profitability. After Source Photonics is consolidated for a full year, earnings elasticity will be much greater than its revenue share suggests.
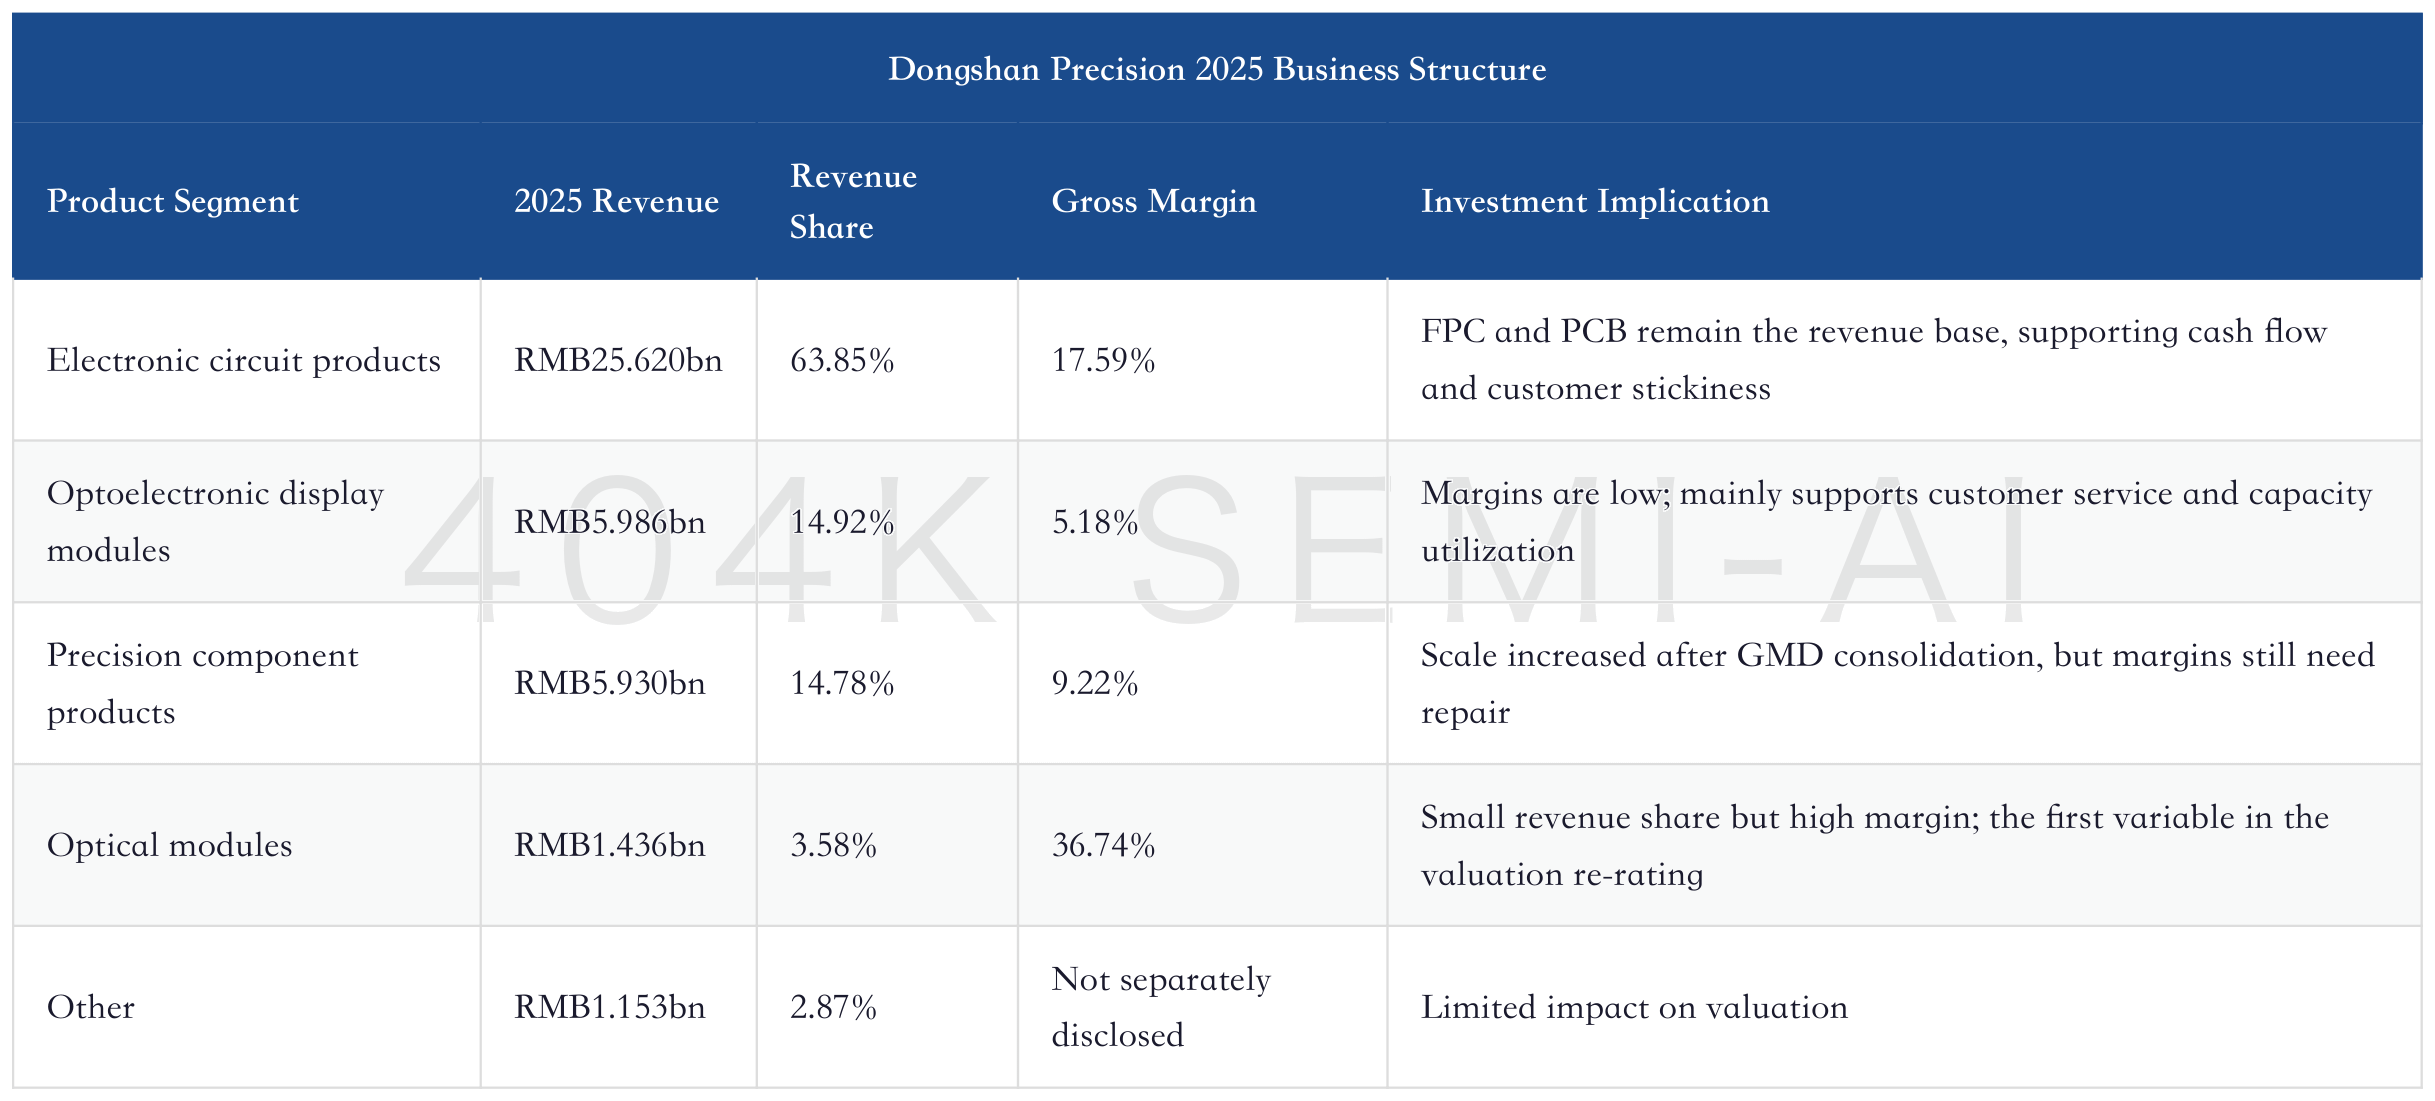
Dongshan’s asset shift can be compressed into one sentence: the revenue base remains traditional electronics manufacturing, while incremental profit is shifting toward AI optics. This judgment is more useful than saying “Dongshan has an AI theme,” because it determines how to track the company. Traditional manufacturing depends on orders and capacity utilization. AI optics requires monitoring customer qualification, product generations, chip self-supply, yield, external sales orders, and gross margin. Investors who value Dongshan only as a traditional PCB company will underestimate Source Photonics’ margin profile; investors who value it only as an optical-module growth stock will overlook capex, finance expenses, and volatility in legacy businesses.
There is another statement in the annual report that is easy to underestimate: the company said Source Photonics has full-process in-house R&D; and mass-production capability as an optical chip IDM, with product rates covering 2.5G to 200G, focusing on high-end 100G/200G PAM4 EML series; optical module products cover 10G to 1.6T, with continued development of 3.2T and above products. The significance is not the product list, but that the company has a vertically integrated path from optical chips to optical modules. After the optical module industry enters 1.6T, the margins of pure assembly will be squeezed by customers and upstream components. Companies that control key light sources will have stronger bargaining power.
AI Optical Module Demand Revised Up Again: How Morgan Stanley’s May Report Pushed 1.6T, InP, and CPO Bottlenecks to 2028
New assets also bring new risks. Dongshan completed two acquisitions in 2025, Source Photonics and GMD. Cash outflow from investing activities increased 85.14% YoY, which the company attributed mainly to the strategic acquisitions of Source Photonics and GMD Group, as well as investments in optical modules including optical chips and AI PCB. In 2026Q1, finance expenses rose sharply YoY, while net cash outflow from investing activities continued to expand. This shows that Dongshan is using heavy capital investment to exchange for new profit pools. As long as optical modules and AI PCB deliver, financial leverage will amplify earnings; if customer orders or yield ramp fall short of expectations, finance expenses and depreciation will pressure valuation first.
III. 2026 Q1 Earnings: This Strong Growth Officially Puts Source Photonics Into the Income Statement
2026 Q1 is the starting point for Dongshan Precision’s current re-rating cycle. Revenue and profit both accelerated across the board in the first quarter, with even stronger elasticity in recurring net profit. The key financial readings are shown below. The company’s explanation was straightforward: Source Photonics and GMD Group were consolidated, the optical module business captured the AI data-center industry boom and customer demand, and the traditional businesses remained stable.
This growth has already gone beyond a simple consolidation explanation. Revenue grew 52.72%, net profit attributable to shareholders rose 143.47%, and profit elasticity was clearly higher than revenue elasticity, indicating an improving business mix. The official first-quarter report disclosed that optical module revenue doubled year on year and became a core contributor to revenue and profit. Citi’s April report listed 4Q25 optical module revenue at RMB1.4 billion, with gross margin of 36.7% and net margin of 21.9%. Taken together, these figures show that Source Photonics has moved from an acquired asset into the income-statement validation stage.
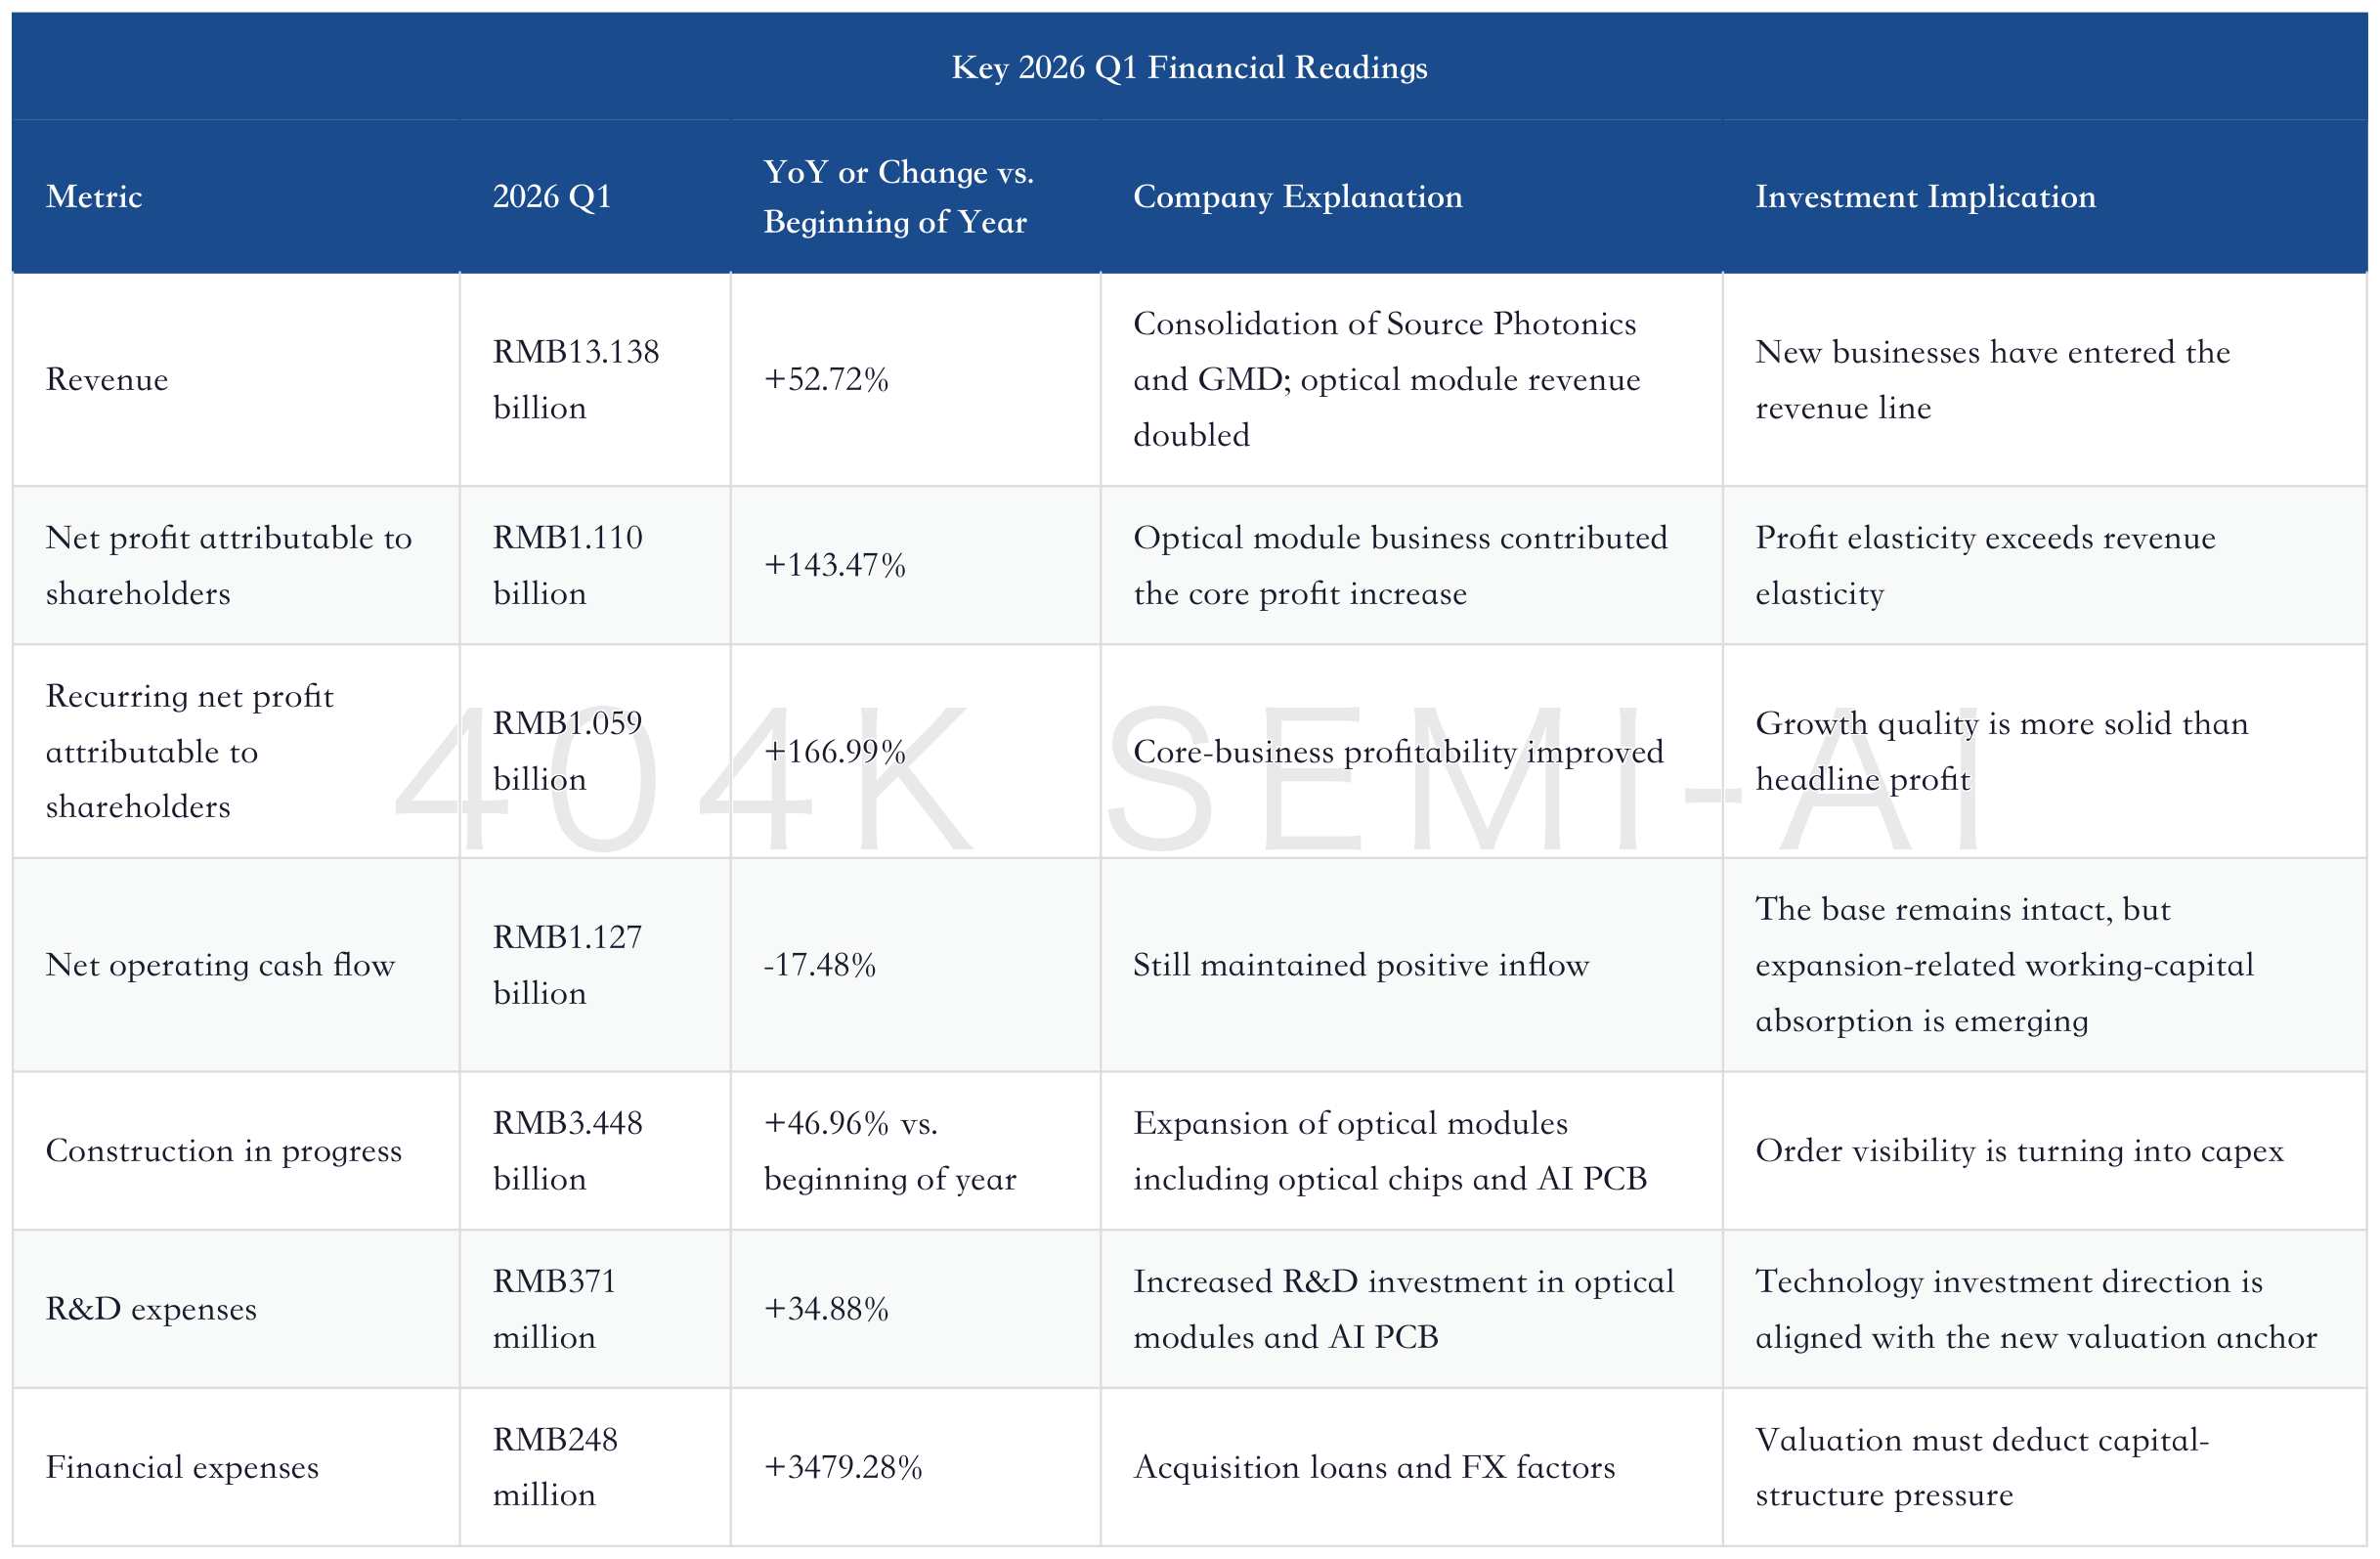
This table puts Dongshan Precision’s opportunity and risk side by side. The opportunity is that the high-margin optical module business has begun to lift net margin. The risk is that to capture this profit curve, the company must keep expanding capacity, financing, investing in R&D;, and integrating assets. After 2026, every quarter Dongshan Precision will need to use its financial statements to answer the same question: can growth in the high-margin new business cover acquisition loans, depreciation from capacity expansion, R&D; investment, and working-capital absorption?
BofA’s model is very suitable as a financial anchor. Its core point is a step-change in net margin as the optical business mix rises; revenue upgrades alone are only the surface. The specific revenue, profit, EPS, and margin assumptions are shown below. The key judgment in this model is that after Source Photonics scales, Dongshan Precision’s margin curve will shift from a traditional manufacturing framework to a high-end optical-module framework.
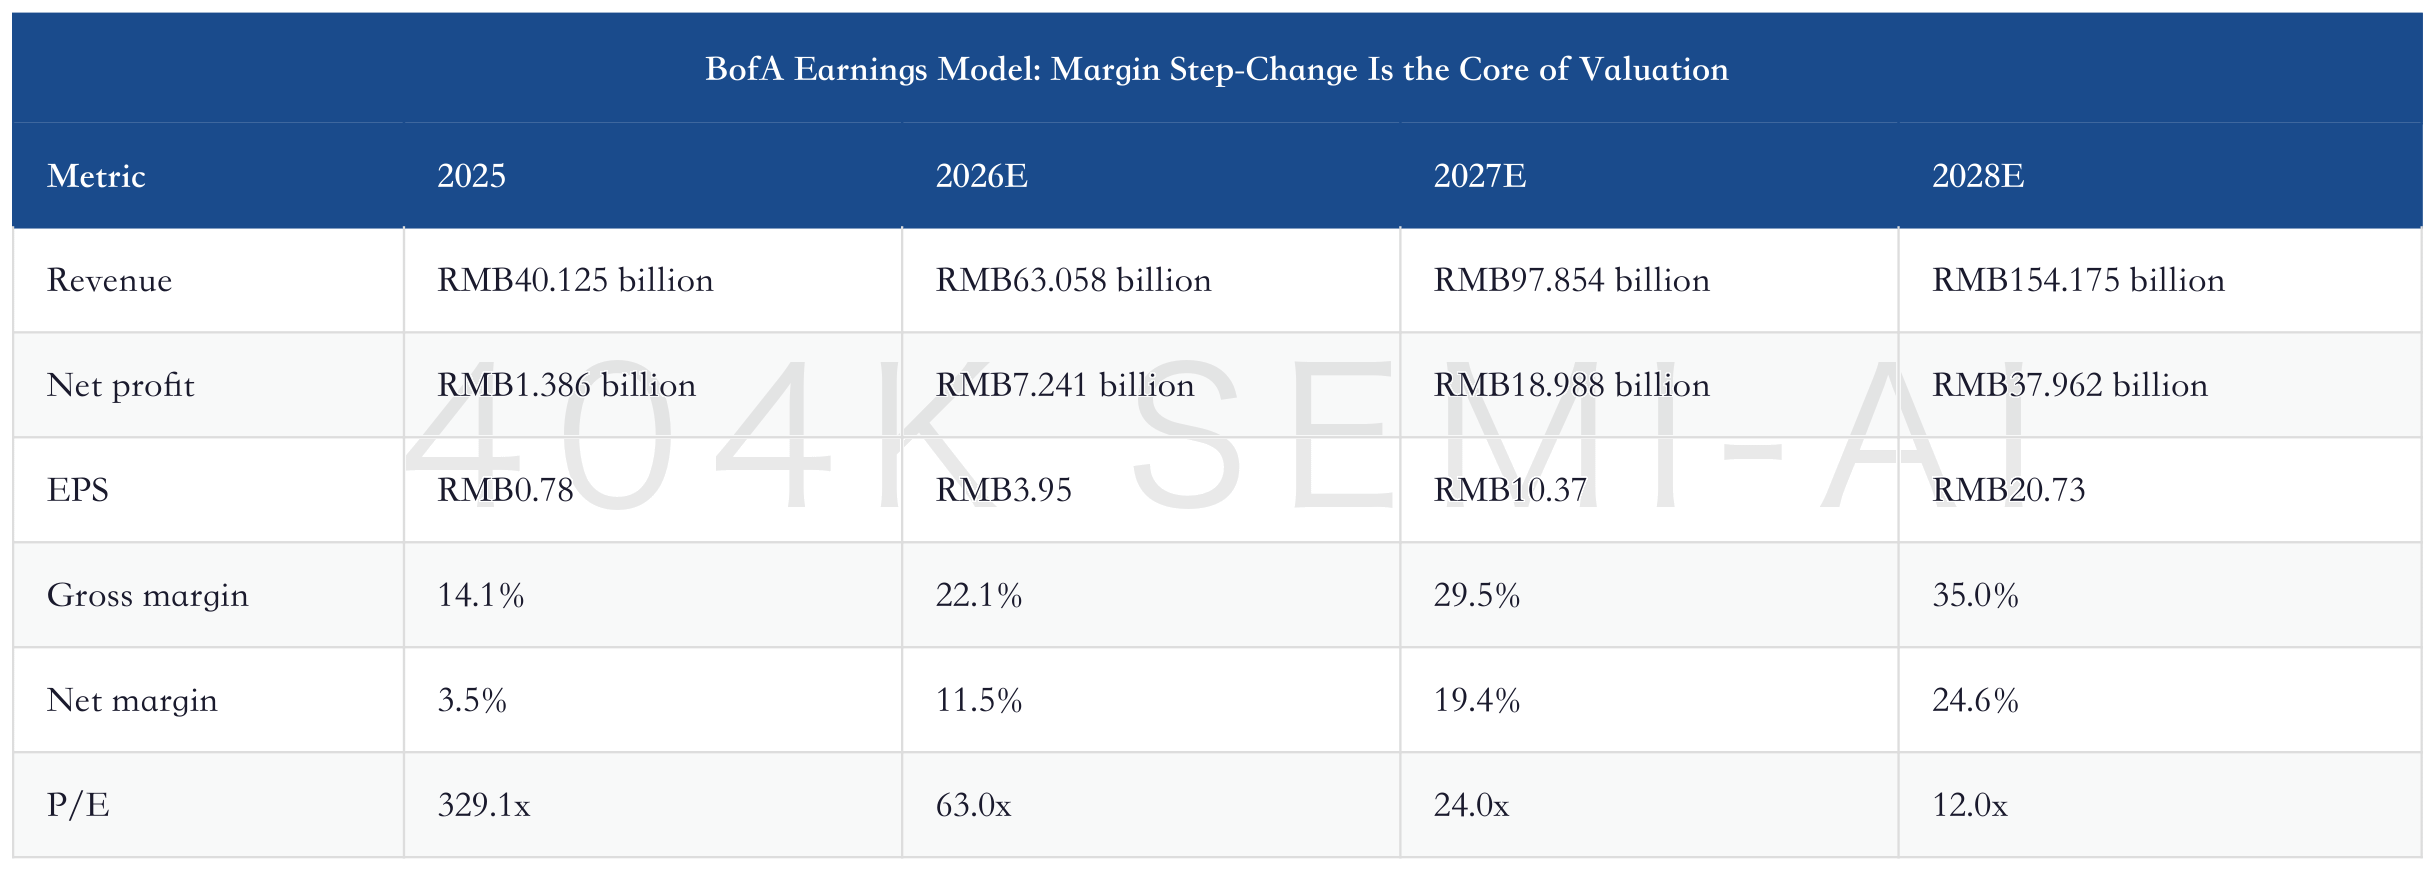
This forecast is aggressive, but also constraining. It requires Dongshan Precision to keep raising revenue scale from 2026 to 2028 while moving gross margin, operating margin, and net margin up step by step. If it achieves this, the stock price does not look unreasonable on 2027 numbers. If it does not, the current valuation will look like it has moved too early. BofA maintains a Neutral rating precisely because it is positive on business growth but believes the share price already partly reflects that growth.
Dongshan Precision’s financial validation points are also more complex than those of pure optical module companies. Companies such as Eoptolink and Zhongji Innolight are mainly assessed on high-end optical module delivery, gross margin, and customer mix. Dongshan Precision also needs to be assessed on whether traditional businesses become a drag, whether GMD creates profit dilution, whether AI PCB requires a longer ramp-up period, and whether financial expenses remain elevated. In other words, Dongshan Precision’s upside elasticity comes from multi-business resonance, while its downside risk also comes from multiple businesses dragging at the same time.
IV. Source Photonics: Dongshan Precision’s Real Value Lies in Optical Chip and Module Integration
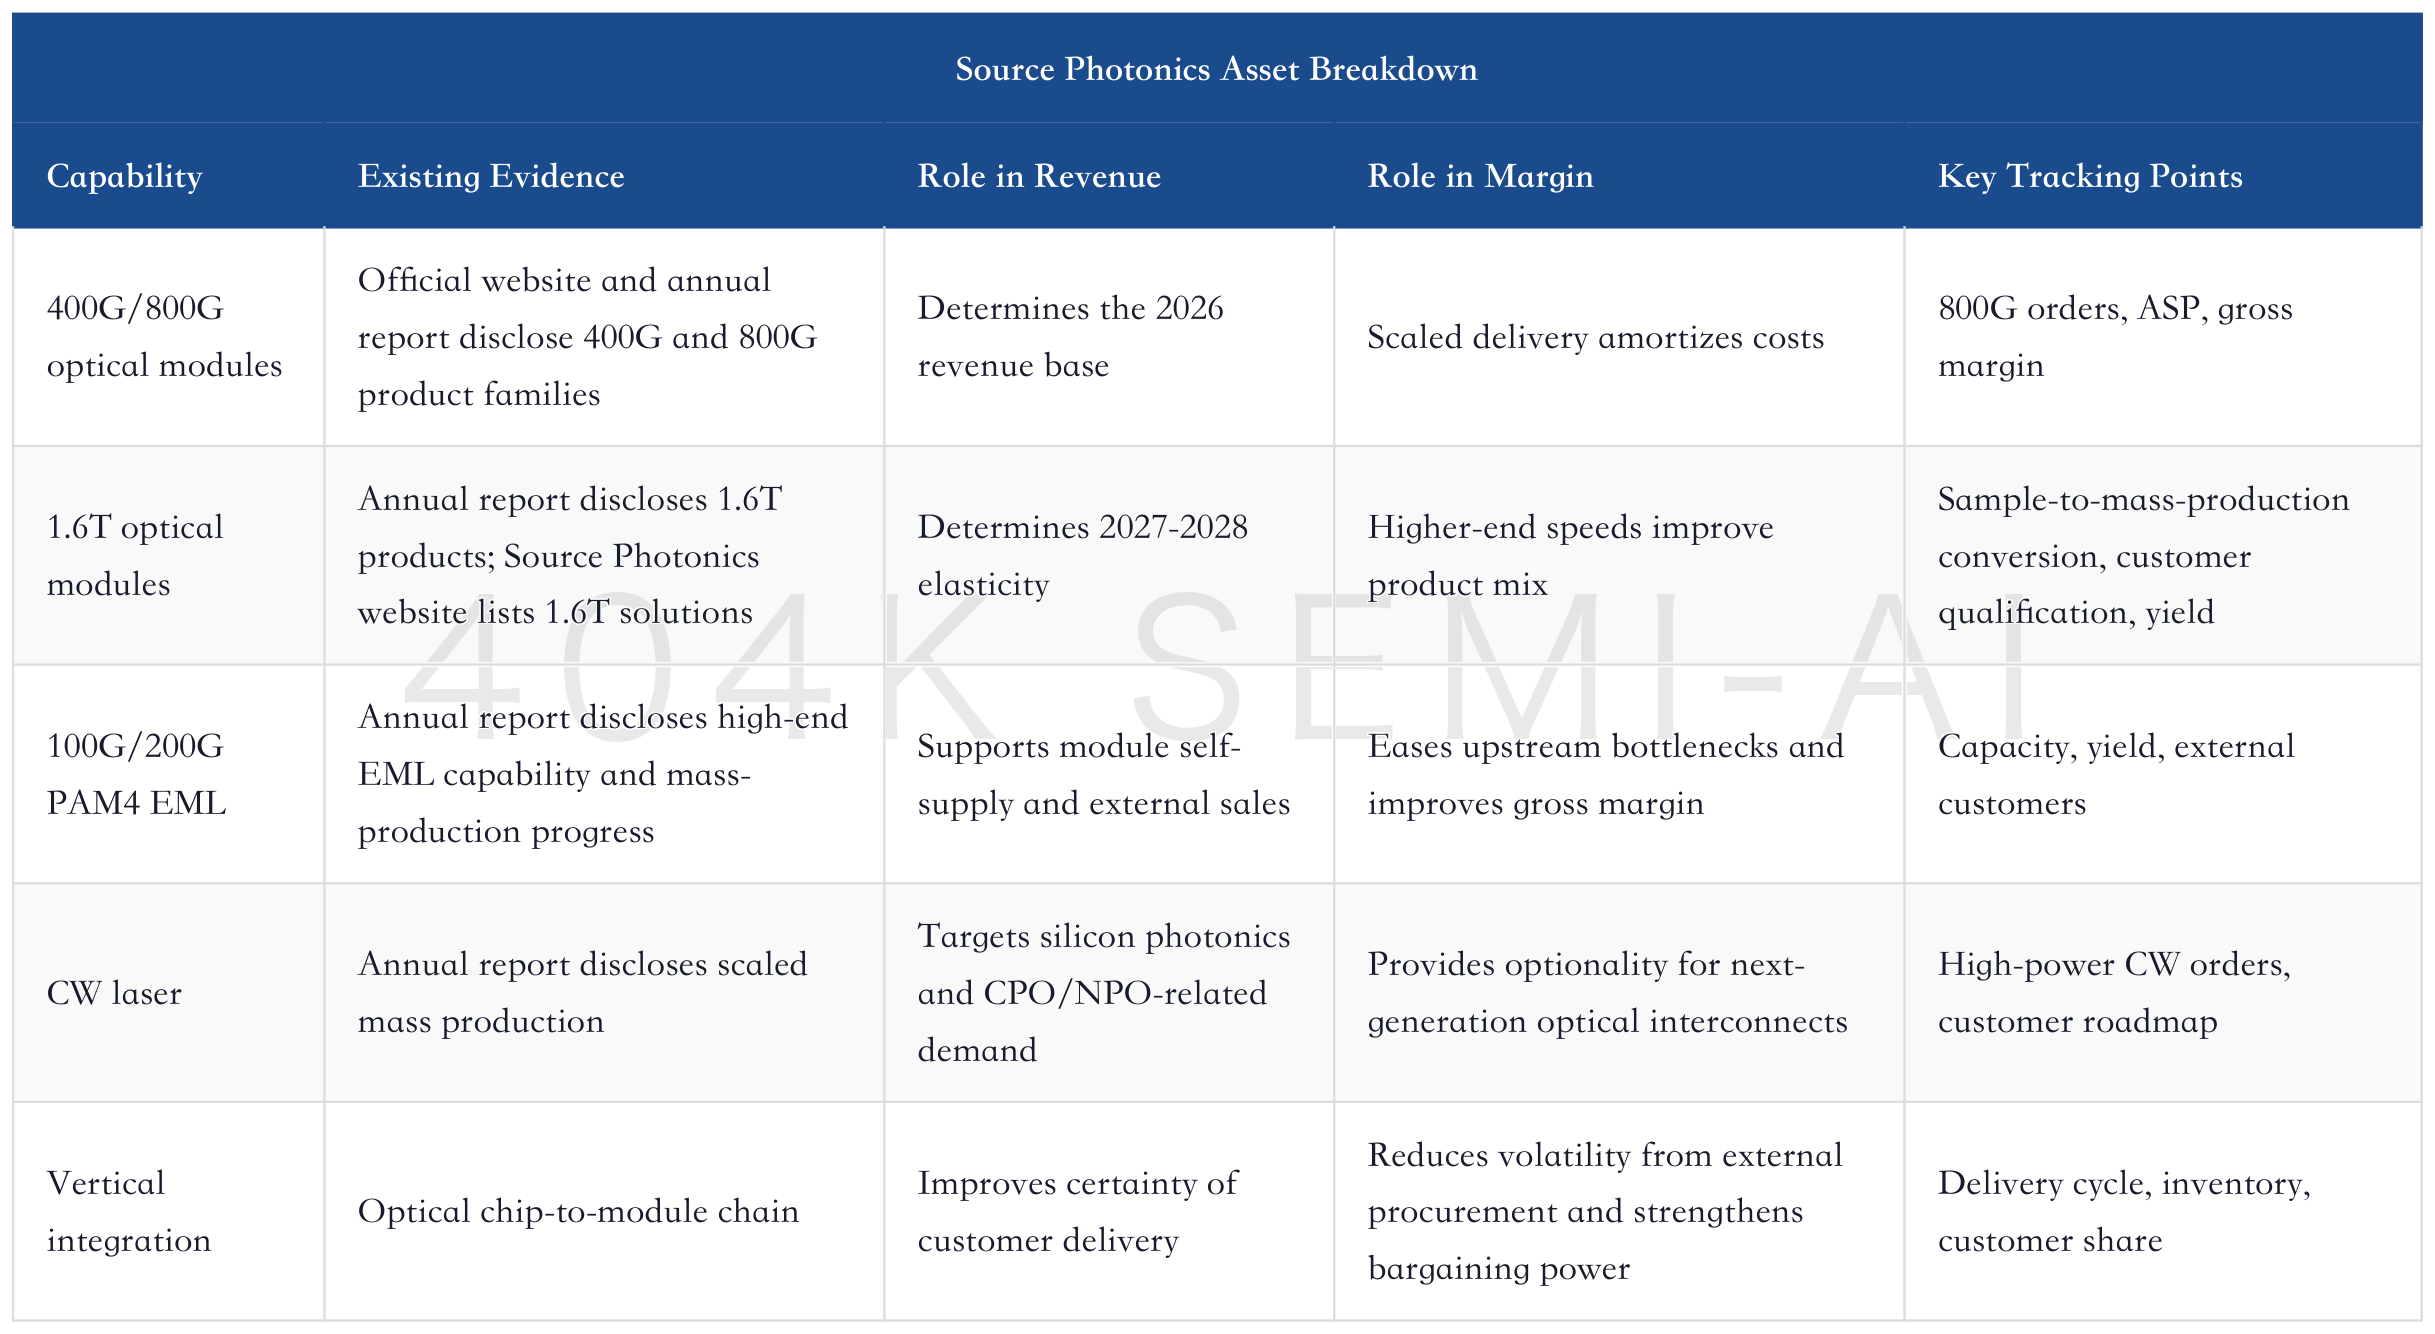
Source Photonics’ strategic value cannot be explained only by “optical module revenue.” In the optical module industry, module assembly revenue is highly elastic, but customers have strong bargaining power, ASPs decline quickly, and there are many competitors. What can truly widen margins is capability in key light sources and chips. The annual report disclosed that Source Photonics has an R&D; and process system spanning indium phosphide substrates, epitaxial materials, and optical chips. 100G/200G PAM4 EML is a core product, CW laser has achieved scaled mass production, and the single-wavelength 400G EML high-speed optical chip R&D; project is progressing as planned.
This means Dongshan Precision has two layers of revenue. The first layer is pluggable optical modules, serving real demand for 400G, 800G, and 1.6T. The second layer is key light sources such as EML and CW laser, which can improve margins and customer stickiness when industry supply is tight. With only the first layer, Dongshan Precision is just a module manufacturer. When both layers are in place, Dongshan Precision has the attributes of an optical platform.
The core change in Citi’s model is that it is gradually writing Dongshan Precision not just as an acquired optical module asset, but as a beneficiary of optical chip shortages. Its spring reports repeatedly upgraded assumptions for 1.6T, 800G, and external EML shipments, indicating that the sell side is chasing order and capacity visibility. The evolution of target prices and business assumptions is shown below.
Citi Sharply Raises AI Optical Module Target Prices: A US$92 Billion Optical Interconnect Market Opens Up; Which of Dongshan Precision, Eoptolink, and TFC Communication Can Deliver the Most?
BofA’s model is more restrained, but it also acknowledges Source Photonics’ growth slope. It significantly raised optical business revenue, profit, and high-speed module shipment assumptions, while noting that laser unit prices are far lower than optical modules, so near-term profit contribution still mainly comes from modules. This reminder is important: laser determines the valuation multiple and strategic customer position, while optical modules determine the absolute profit amount.
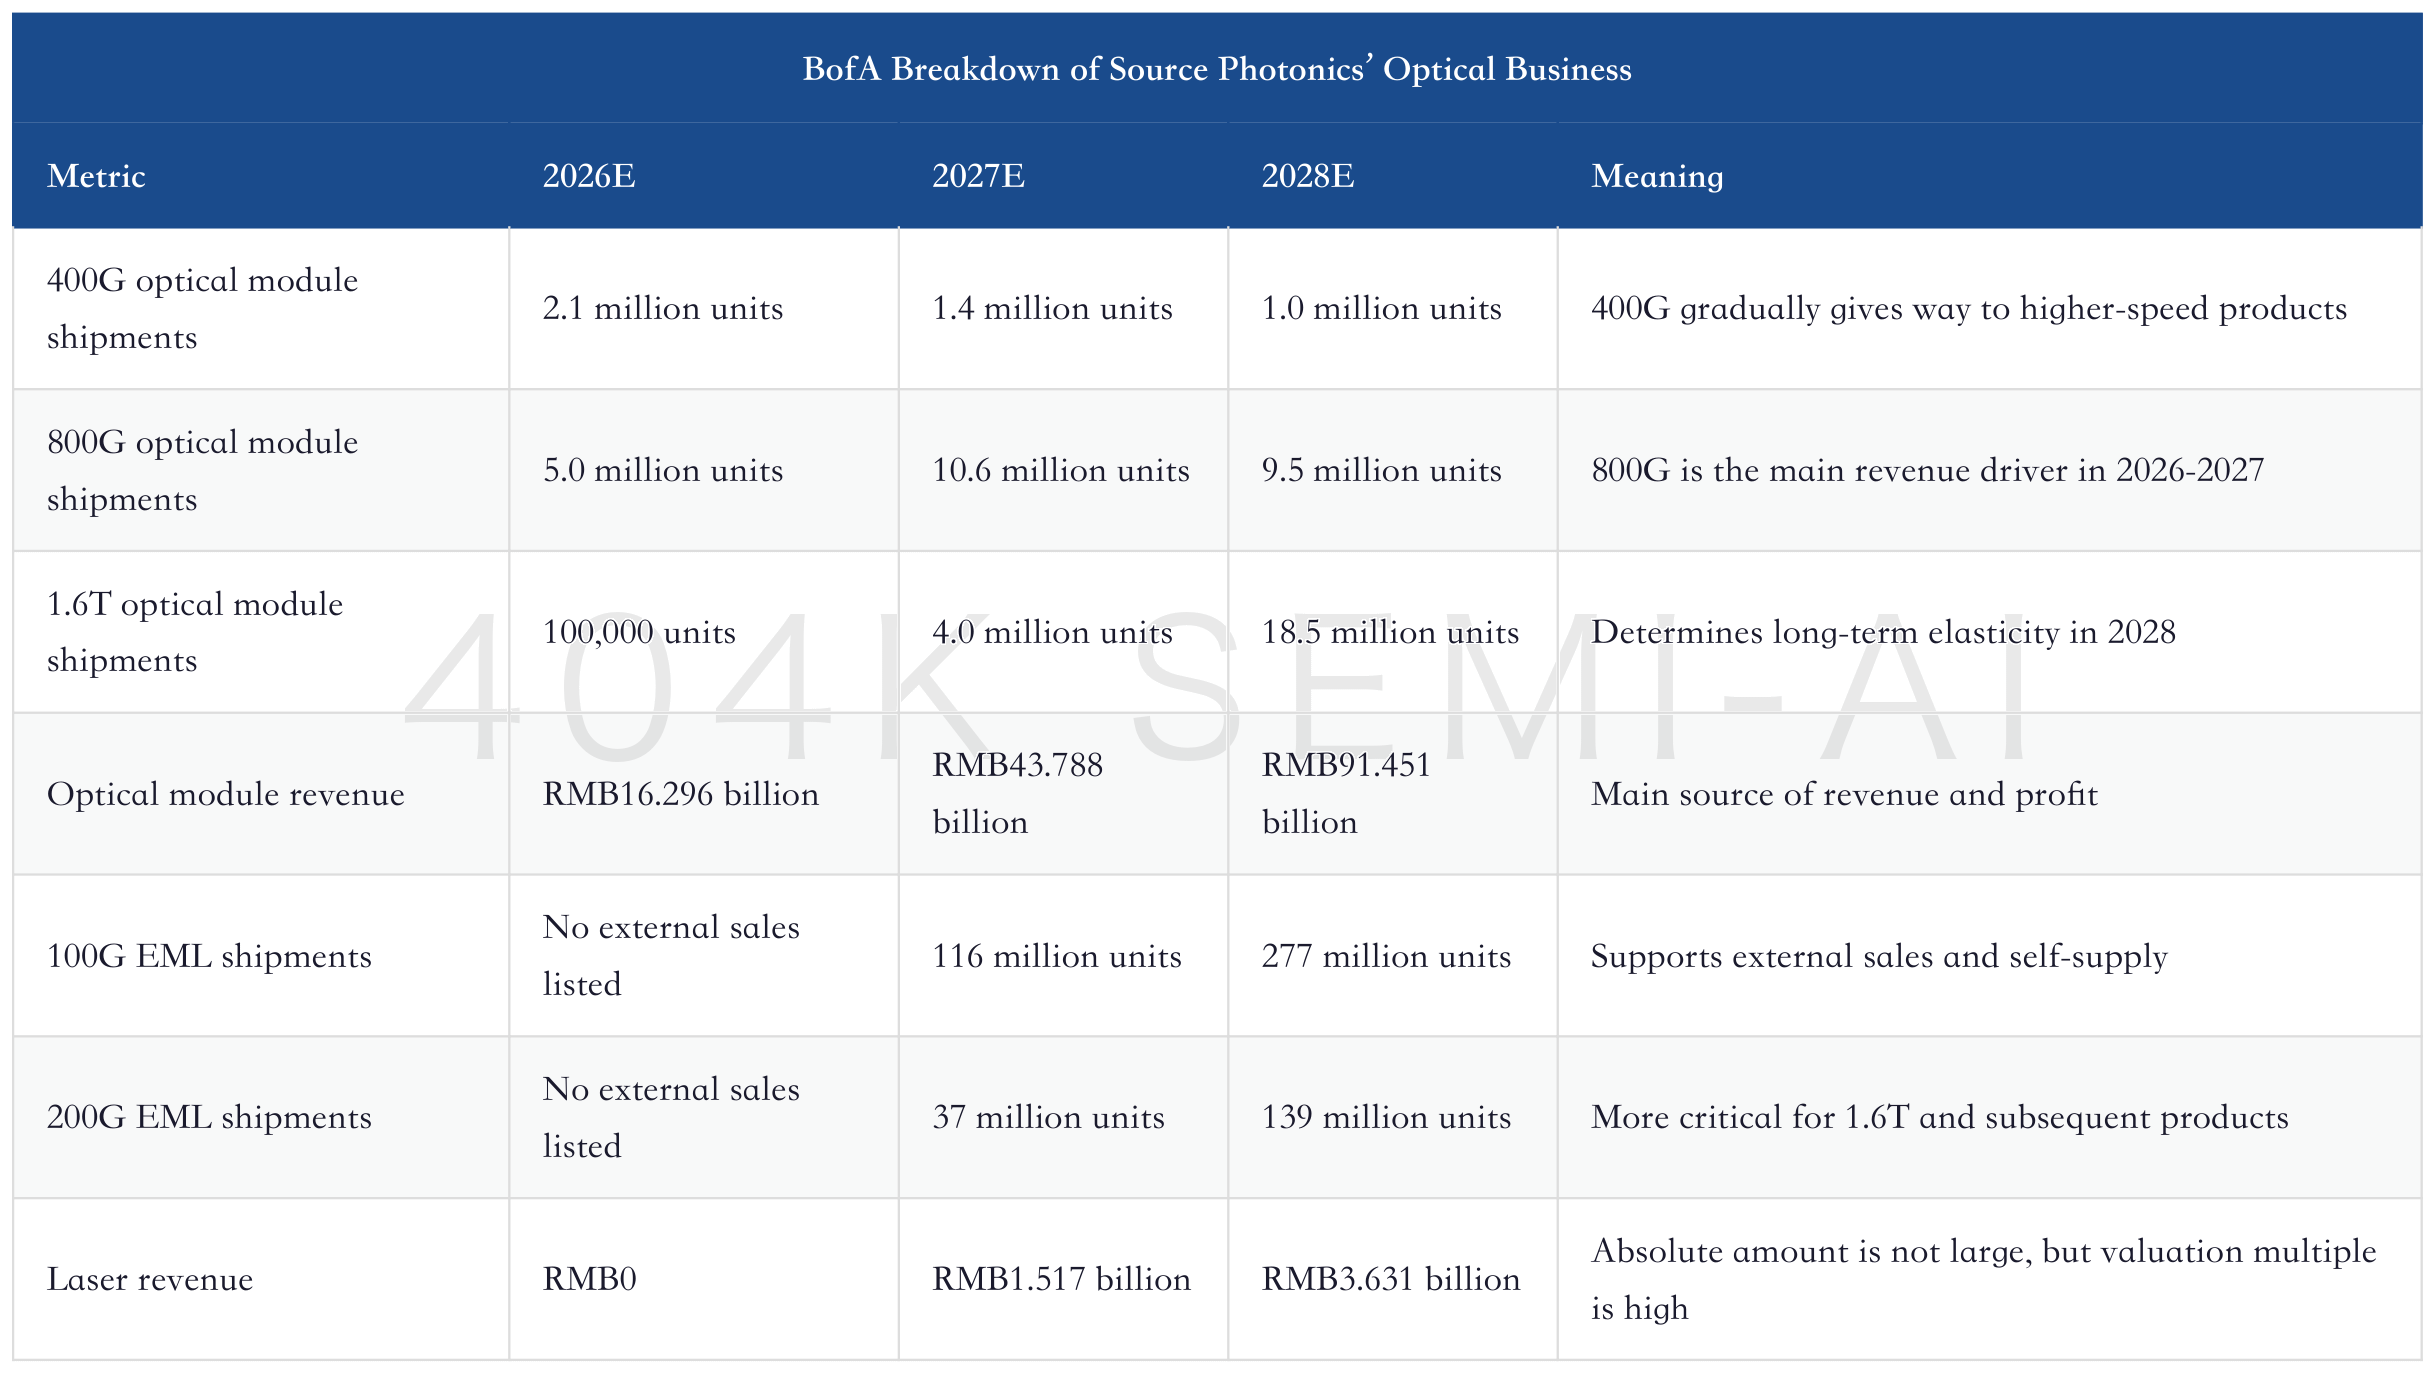
This data set leads to a clear conclusion: in the short term, Source Photonics relies on high-end module scale-up to support profit; the value of laser lies in improving delivery certainty, increasing customer trust, enhancing the SOTP multiple, and preserving the company’s long-term entry ticket into the CPO/NPO and silicon photonics era.
Source Photonics also has three hard risks. First, customer order visibility may be high, but mass-production yield and delivery cadence will still determine profit. Second, 1.6T and subsequent 3.2T products have higher requirements for DSP, EML, silicon photonics, thermal management, and testing; any bottleneck in one link will affect gross margin. Third, overseas customers will introduce multiple suppliers for supply-chain security, so Dongshan Precision needs to defend share through chip self-supply and delivery performance.
V. US$1.2 Billion Expansion: It Raises Order Confidence, but Also Raises ROI Pressure
The US$1.2 billion expansion was the most important incremental data point in the June materials. Citi’s June 16 report showed that DSBJ announced Source Photonics would use self-raised funds to invest US$1.2 billion to expand optical chip and optical module capacity in Changzhou and other regions, addressing capacity shortages and meeting downstream AI compute demand. Citi believes the announcement can reinforce investor confidence in strong AI optical demand. BofA’s June 17 report further explained that management had previously mentioned a potential addition of about 12 million optical modules in 2027 and a doubling of laser capacity to 2 billion units in 2028-2029.
This expansion has two implications. First, it is capacity front-loading after improved customer order visibility. Optical module and optical chip equipment lead times, customer qualification, and yield ramp all take time. If 2027-2028 demand is firm, investment must begin in 2026. Second, it shifts the market from “watch orders” to “watch ROI.” US$1.2 billion is not a small amount. The larger the expansion, the higher the subsequent requirements for cash flow, depreciation, yield, and order conversion.
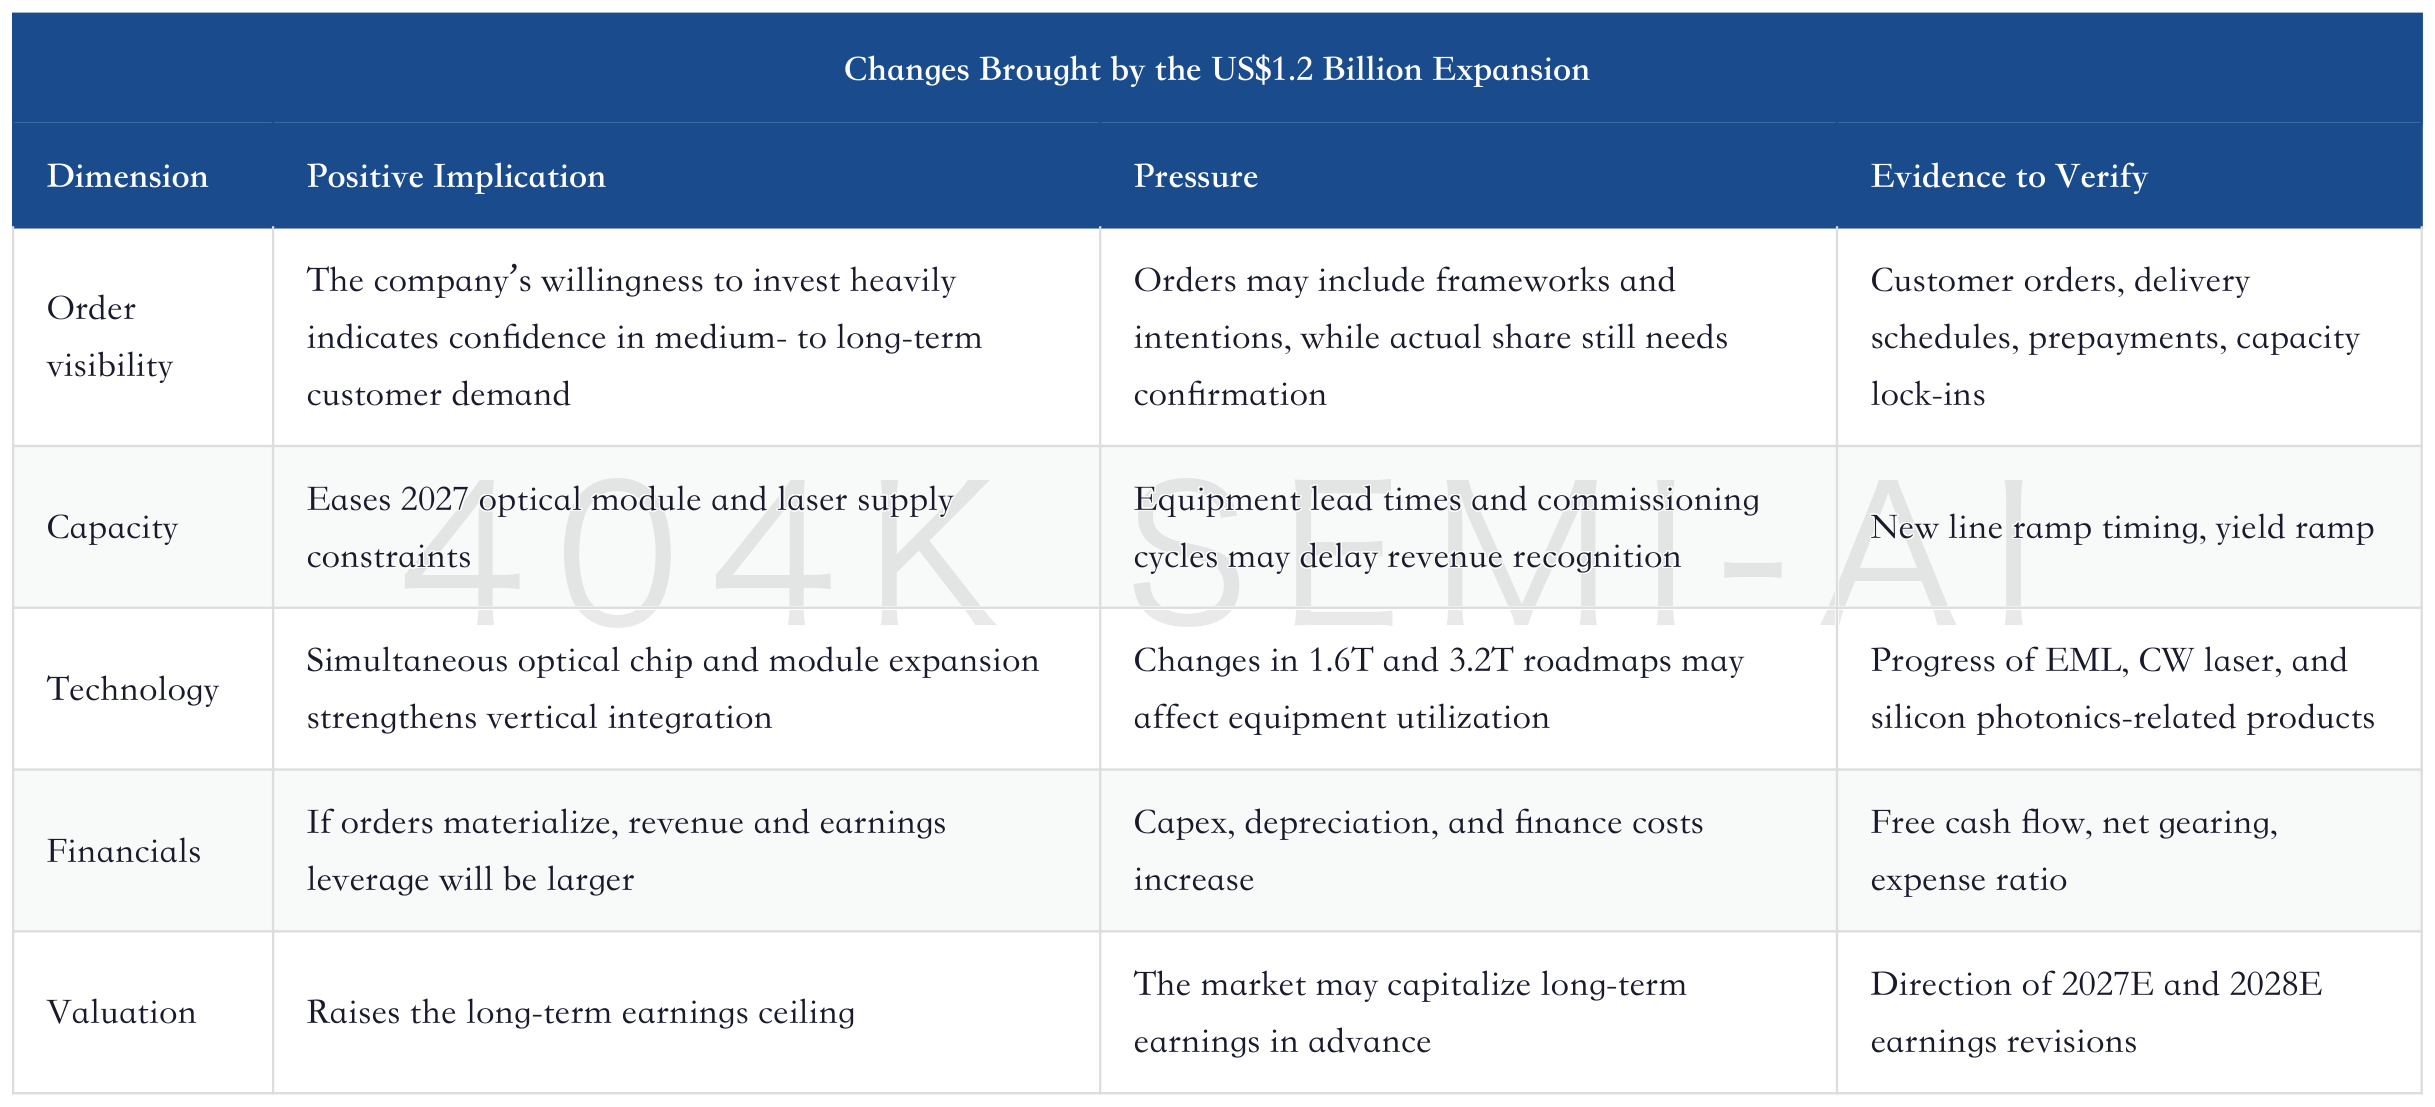
BofA’s reaction to this expansion was highly typical: it raised earnings and its target price, but maintained a Neutral rating. In the SOTP breakdown, the value uplift mainly came from optical modules, while valuations for lasers and legacy businesses changed little. This adjustment shows that BofA is willing to assign a higher multiple to optical modules, but did not upgrade the rating to Buy because it believes the current price is already reasonable.
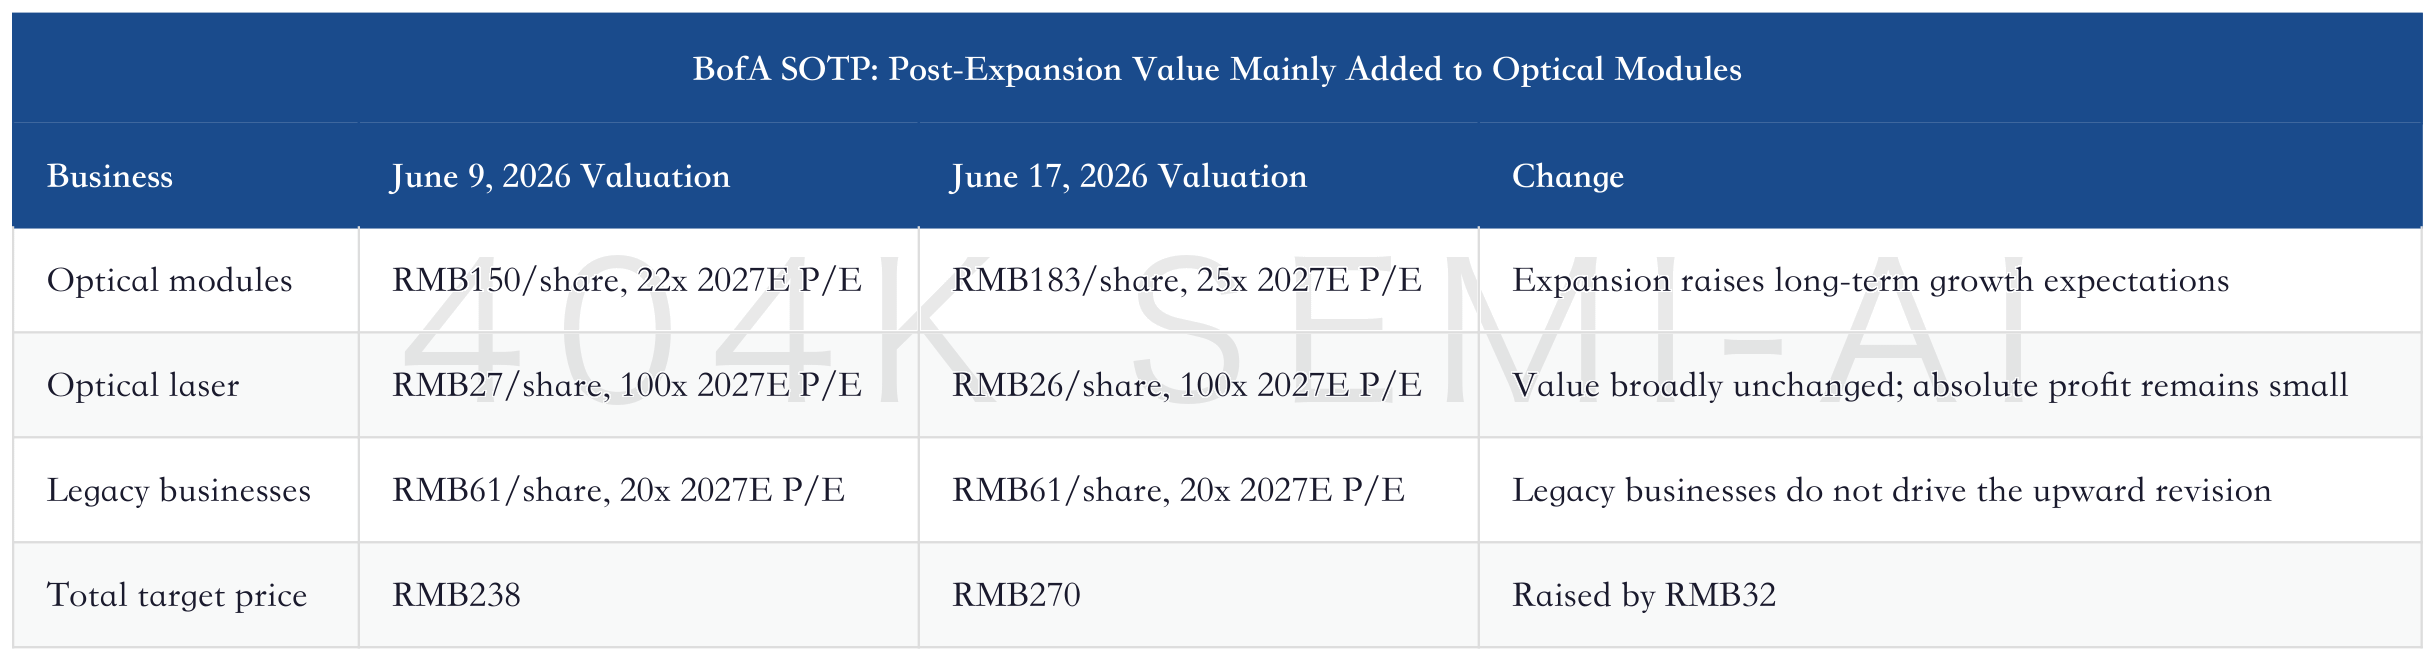
The most useful aspect of the expansion news for investors is that it makes follow-up tracking indicators more concrete. The analysis of DSBJ should not stop at “the company invested US$1.2 billion.” Four questions matter: when will the new capacity reach full production, are customer orders sufficient to fill the capacity, will external optical chip sales truly contribute profit, and will capex crush free cash flow? BofA’s model shows 2026E free cash flow per share at RMB-0.84, recovering to RMB4.31 in 2027E and rising to RMB13.04 in 2028E. If this path materializes, expansion pressure can be absorbed by revenue. If free cash flow does not turn positive in 2027, the market will reassess this expansion.
VI. AI PCB: DSBJ’s Second Growth Leg, Harder to Validate Than Optical Modules
DSBJ’s AI PCB thesis cannot be written simply as “PCB demand is strong.” The real barriers in AI server PCBs are customer qualification, material grade, layer count, HDI process, thermal management, yield, and delivery stability. An expansion announcement itself does not equal effective capacity; this has already been repeatedly validated across the AI PCB series. DSBJ’s advantage is that Multek has a high-end PCB technology foundation and can create customer synergies with Source Photonics’ optical modules. Its weakness is that AI server PCB expansion cycles are long, and competitors are also strong.
AI PCB Phase Six: Expansion Announcements Do Not Equal Effective Capacity — A Full Breakdown of 2026 Equipment Orders at Han’s CNC, Victory Giant Technology, and Shennan Circuits
The annual report disclosed that Multek has manufacturing capabilities for ultra-high-layer-count PCBs of 78 layers and above, as well as 7-stage thick-board HDI PCBs. It focuses on the AI server track and can deliver high-quality PCB products at scale. The company’s high-end PCBs also use M8/9-grade low-loss materials, meeting high-speed transmission requirements for GPUs, AI accelerator cards, AI servers, and data-center switches. Goldman Sachs’ May meeting minutes also noted that management emphasized the company’s end-to-end capabilities in AI PCBs and high-speed optical modules, and that it is expanding PCB product capacity and optimizing its product mix to meet demand from data centers and AI servers.
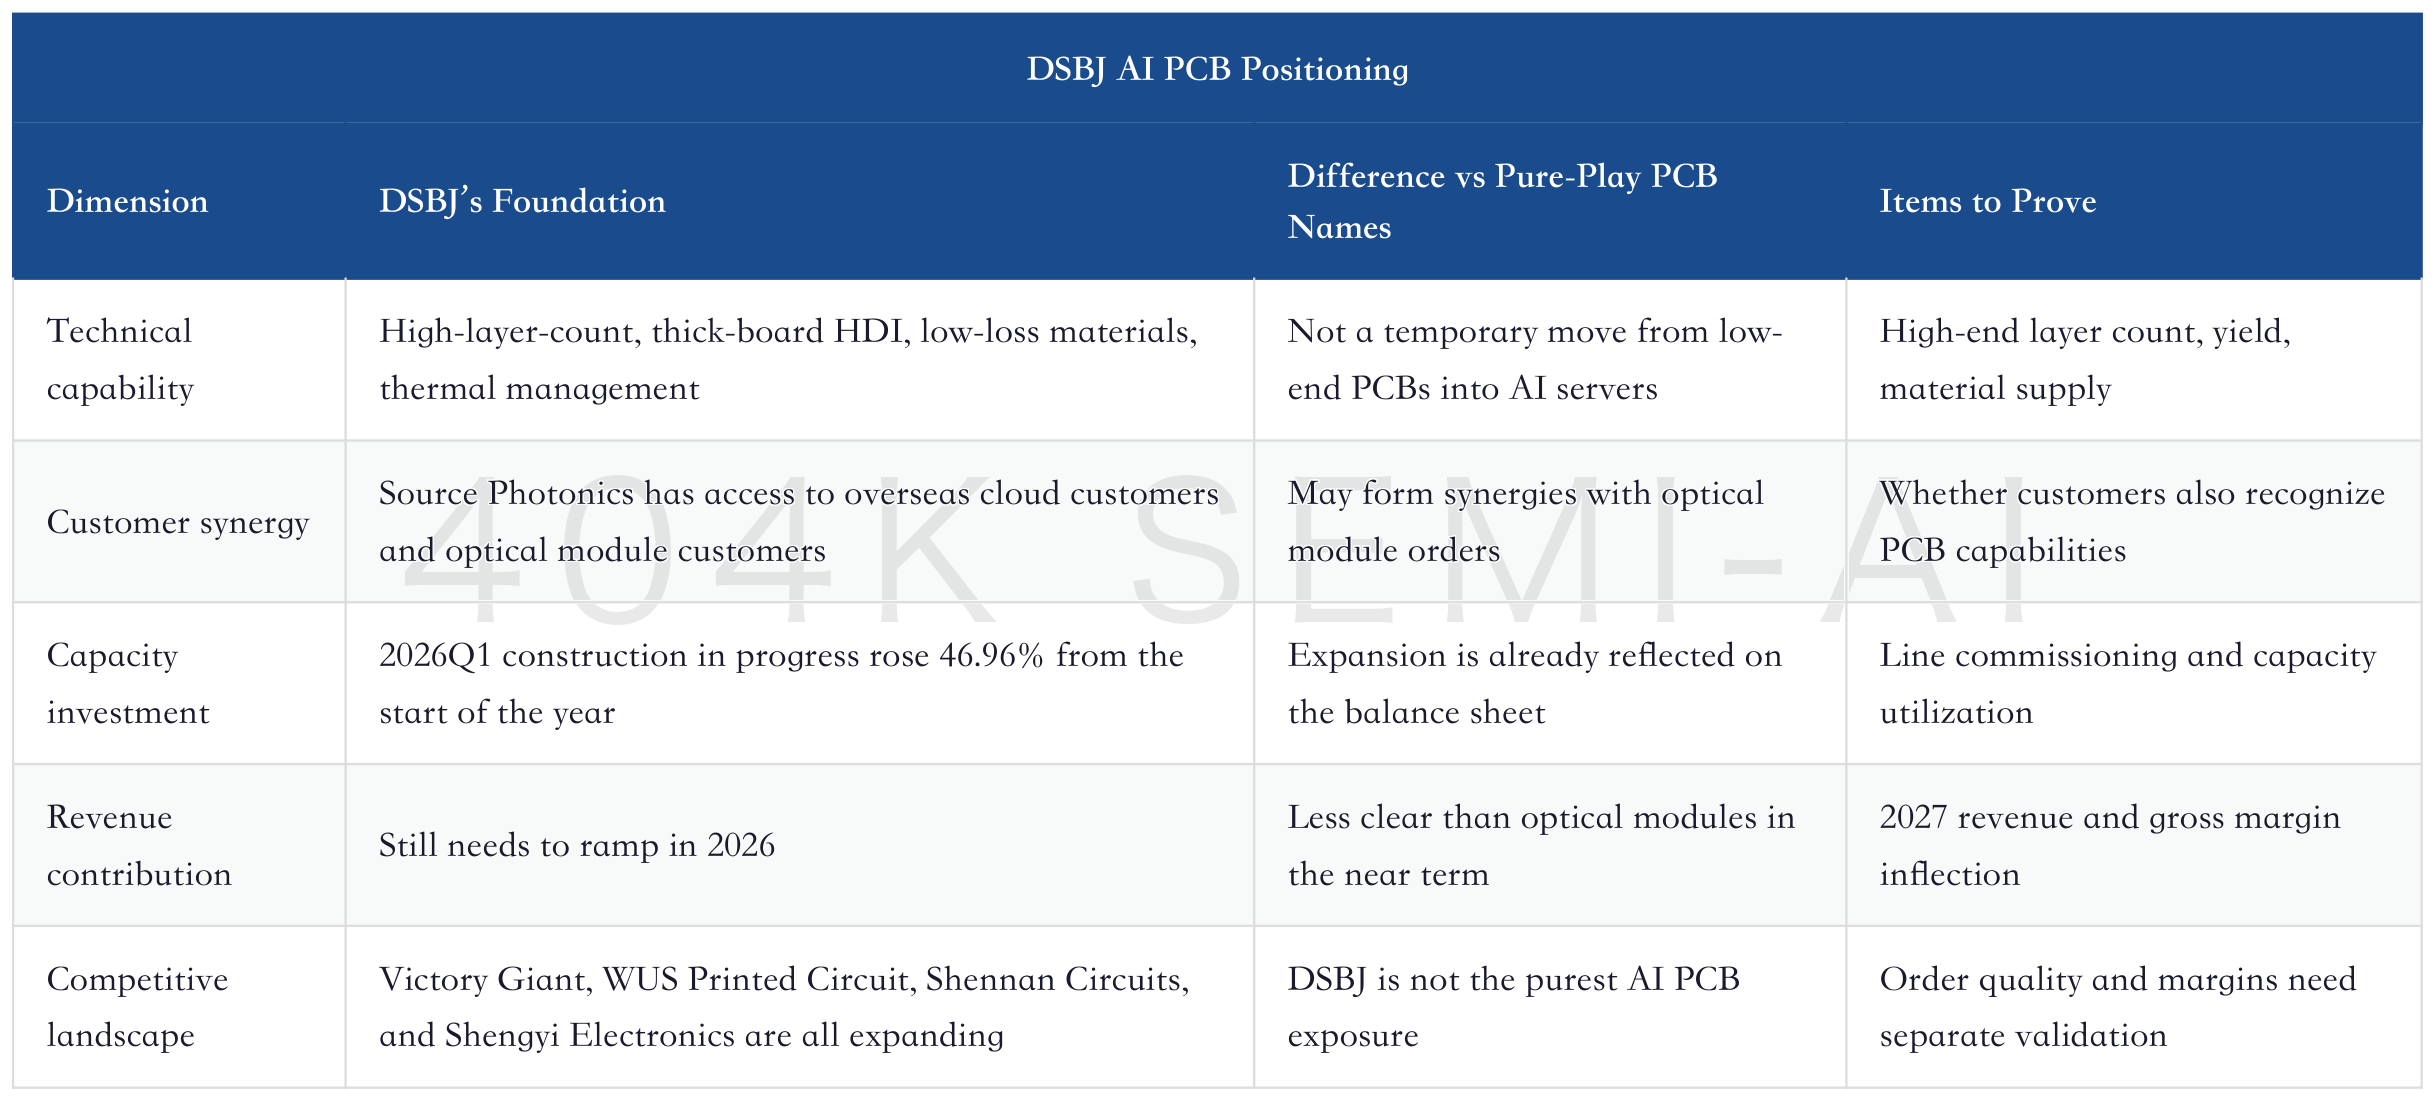
Citi’s April call minutes provided a more positive management message: the company has communicated with almost all AI cloud customers and achieved breakthroughs with most of them; management is confident in its AI PCB capabilities, especially products such as embedded capacitors; AI PCB could double current RPCB revenue and profit over the next 2-3 years. This information is valuable, but it remains a management statement. Actual execution still needs to be assessed through revenue and gross margin.
BofA’s view is clearly more cautious. Its June 9 report noted that future contributions from AI server PCBs will take time because the expansion cycle may be as long as two years, while technical specifications are upgrading rapidly, with high-layer boards evolving from above 20 layers toward 40-100 layers and entry barriers rising. This judgment is important: AI PCB is a long-term option for DSBJ and should not be capitalized immediately in the same way as Source Photonics’ optical modules.
The right way to value DSBJ’s AI PCB business is to treat it as a second growth leg, not the main earnings driver in 2026. The main earnings drivers in 2026 remain optical modules and optical chips. If AI PCB begins contributing high-end revenue in 2027, it will provide thicker valuation support for DSBJ. If progress is slow, it will not fully invalidate the optical thesis, but it will weaken the “optical modules + PCB platform” story.
Victory Giant Technology Deep Dive: AI PCB Enters the Effective Capacity Era; How Victory Giant Is Evolving from a Board Maker into a Server Delivery Asset
The AI PCB line should be tracked through three key numbers. First, the pace at which construction in progress turns into fixed assets and revenue, to determine whether expansion has entered production. Second, whether high-end PCB gross margin improves, to determine whether the company is truly capturing AI server value. Third, customer qualification and order information, especially whether overseas cloud vendors, GPU/ASIC servers, switches, and optical module customers are being introduced together. Until these three numbers are available, AI PCB should remain discounted in the SOTP.
VII. Sell-Side Divergence: Citi Buys Orders, BofA Buys Discipline, HSBC and UBS Record Early-Stage Transformation Noise
The value of this batch of research reports is that they connect DSBJ’s transition from “early-stage legacy-asset transformation” to the “optical-platform realization phase.” HSBC’s July and October 2025 reports focused mainly on AI PCB capacity expansion, the Source Photonics acquisition, and a recovery in growth in 2026. UBS’s August 2025 first take focused more on 2Q25 results missing expectations. In November 2025, BofA raised its target price from RMB28.5 to RMB80 but maintained Neutral, arguing that Source Photonics’ contribution had been fairly well reflected by the market, while the legacy businesses still lacked clearer rerating signals. After March 2026, Citi began putting optical-chip tightness, 800G/1.6T, EML/CW laser, and AI PCB together into its SOTP, and repeatedly raised its target price. By June 2026, BofA also raised earnings and target price sharply, but continued to insist on valuation discipline.
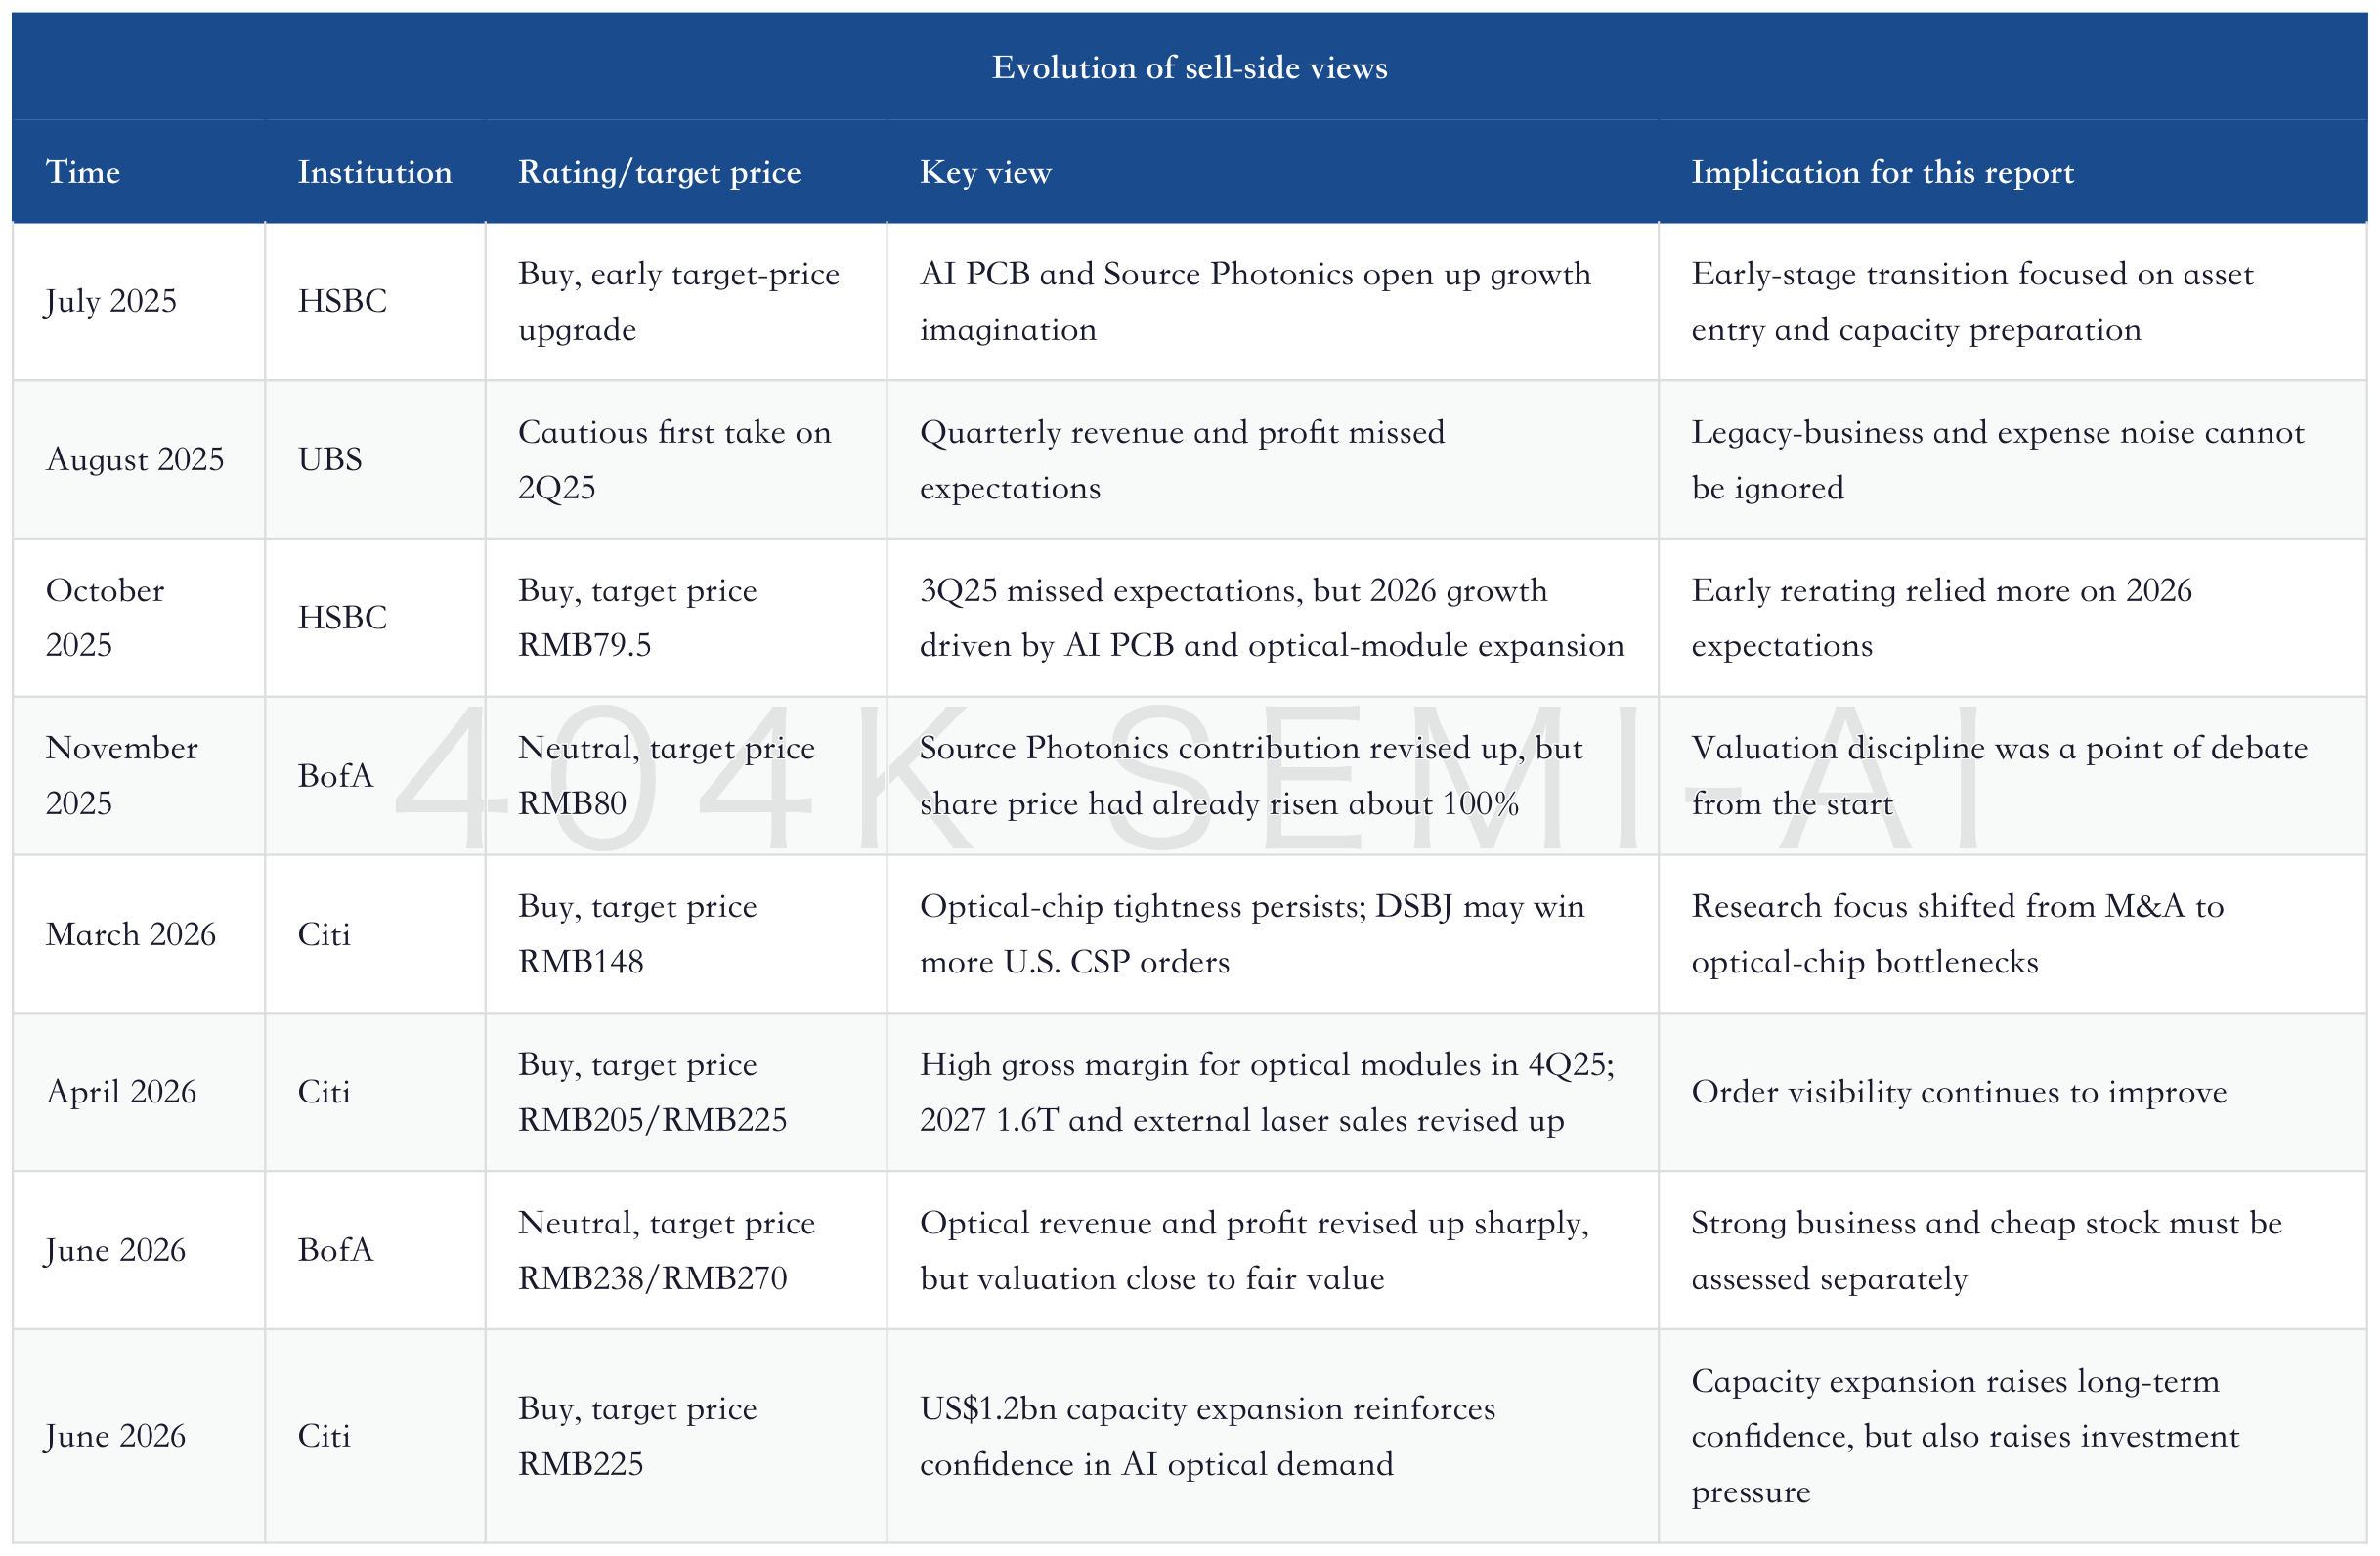
Behind these divergences are two worldviews. Citi’s worldview is that the AI optical supply bottleneck remains tight; demand from 1.6T, EML, CW laser, and CPO/NPO will continue to be revised up; DSBJ has opportunities at both the chip and module ends; therefore it deserves a higher SOTP. BofA’s worldview is that DSBJ has indeed entered a high-growth phase, but the share price already reflects a lot; the company still has 40-50% exposure to consumer electronics and autos; AI PCB contribution will take time; and absolute laser revenue is lower than module revenue, so Neutral is more appropriate at current levels.
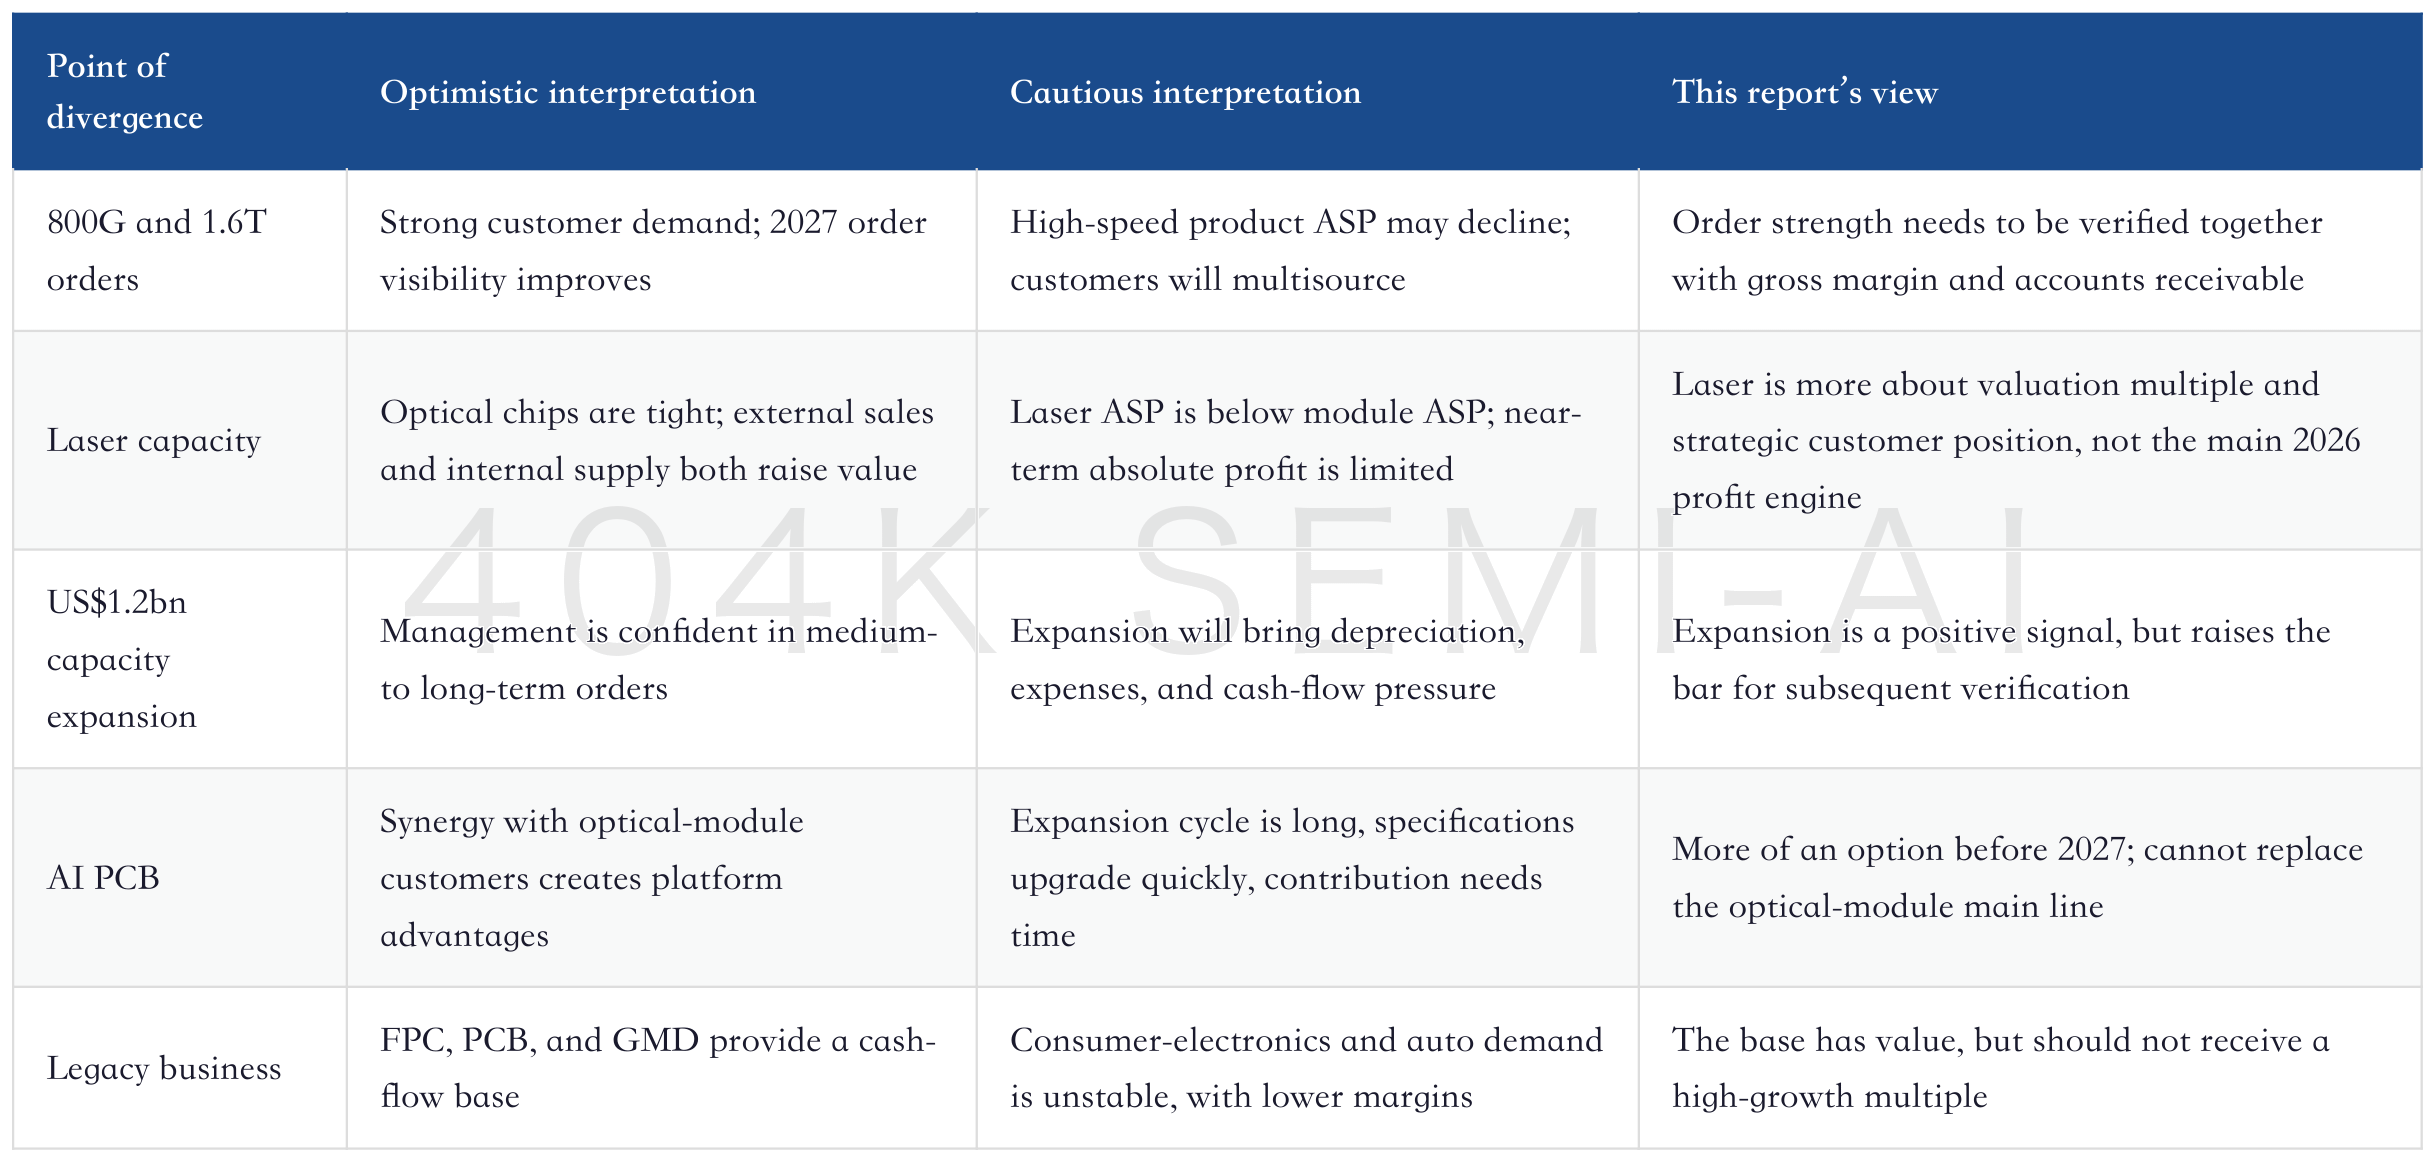
Both worldviews are reasonable. DSBJ is not a company that can only be viewed as a one-way long or one-way short. The bullish core is that Source Photonics’ optical-chip capabilities may turn DSBJ from an ordinary manufacturer into an AI optical bottleneck asset. The cautious core is that the market has already capitalized a large portion of 2027-2028 profit in advance, and even modest business volatility could compress multiples. A real research conclusion should include both points at the same time.
Valuation divergence table: business upgrades and price discipline can both be true
VIII. Valuation Framework: DSBJ Is Suited to SOTP, but Every Segment Needs a Discount
DSBJ can no longer be valued on a single P/E. A single P/E mixes optical modules, optical chips, AI PCB, and legacy businesses together, which either undervalues Source Photonics or overvalues legacy assets. The more reasonable approach is SOTP: legacy businesses receive a multiple based on manufacturing and Apple-chain base value; optical modules receive a multiple based on high-end module profit; optical chips receive a higher multiple as bottleneck assets; AI PCB receives a multiple based on long-term option value and high-end board profit; then discounts are applied for capital structure and execution risk.
Both Citi and BofA use SOTP, but with different segmentation. Citi prices legacy businesses, optical modules, optical chips, and AI PCB separately, while BofA prices optical modules, optical laser, and legacy businesses separately. The difference shows that current valuation is most sensitive to optical-module profit and the optical-chip multiple.
This round of DSBJ target-price upgrades appears on the surface to be brokers raising multiples, but in reality it is a continuous change in the earnings anchor. The earliest increment was Source Photonics consolidation, which in the model looked more like “a traditional manufacturing company plus a high-growth acquired asset.” Citi then shifted the focus to optical-chip shortages, overseas cloud-customer orders, and upward revisions to 800G, 1.6T, and laser demand. By BofA’s June model, the step-change in optical-module revenue and net margin had already been substantially written into long-term assumptions.
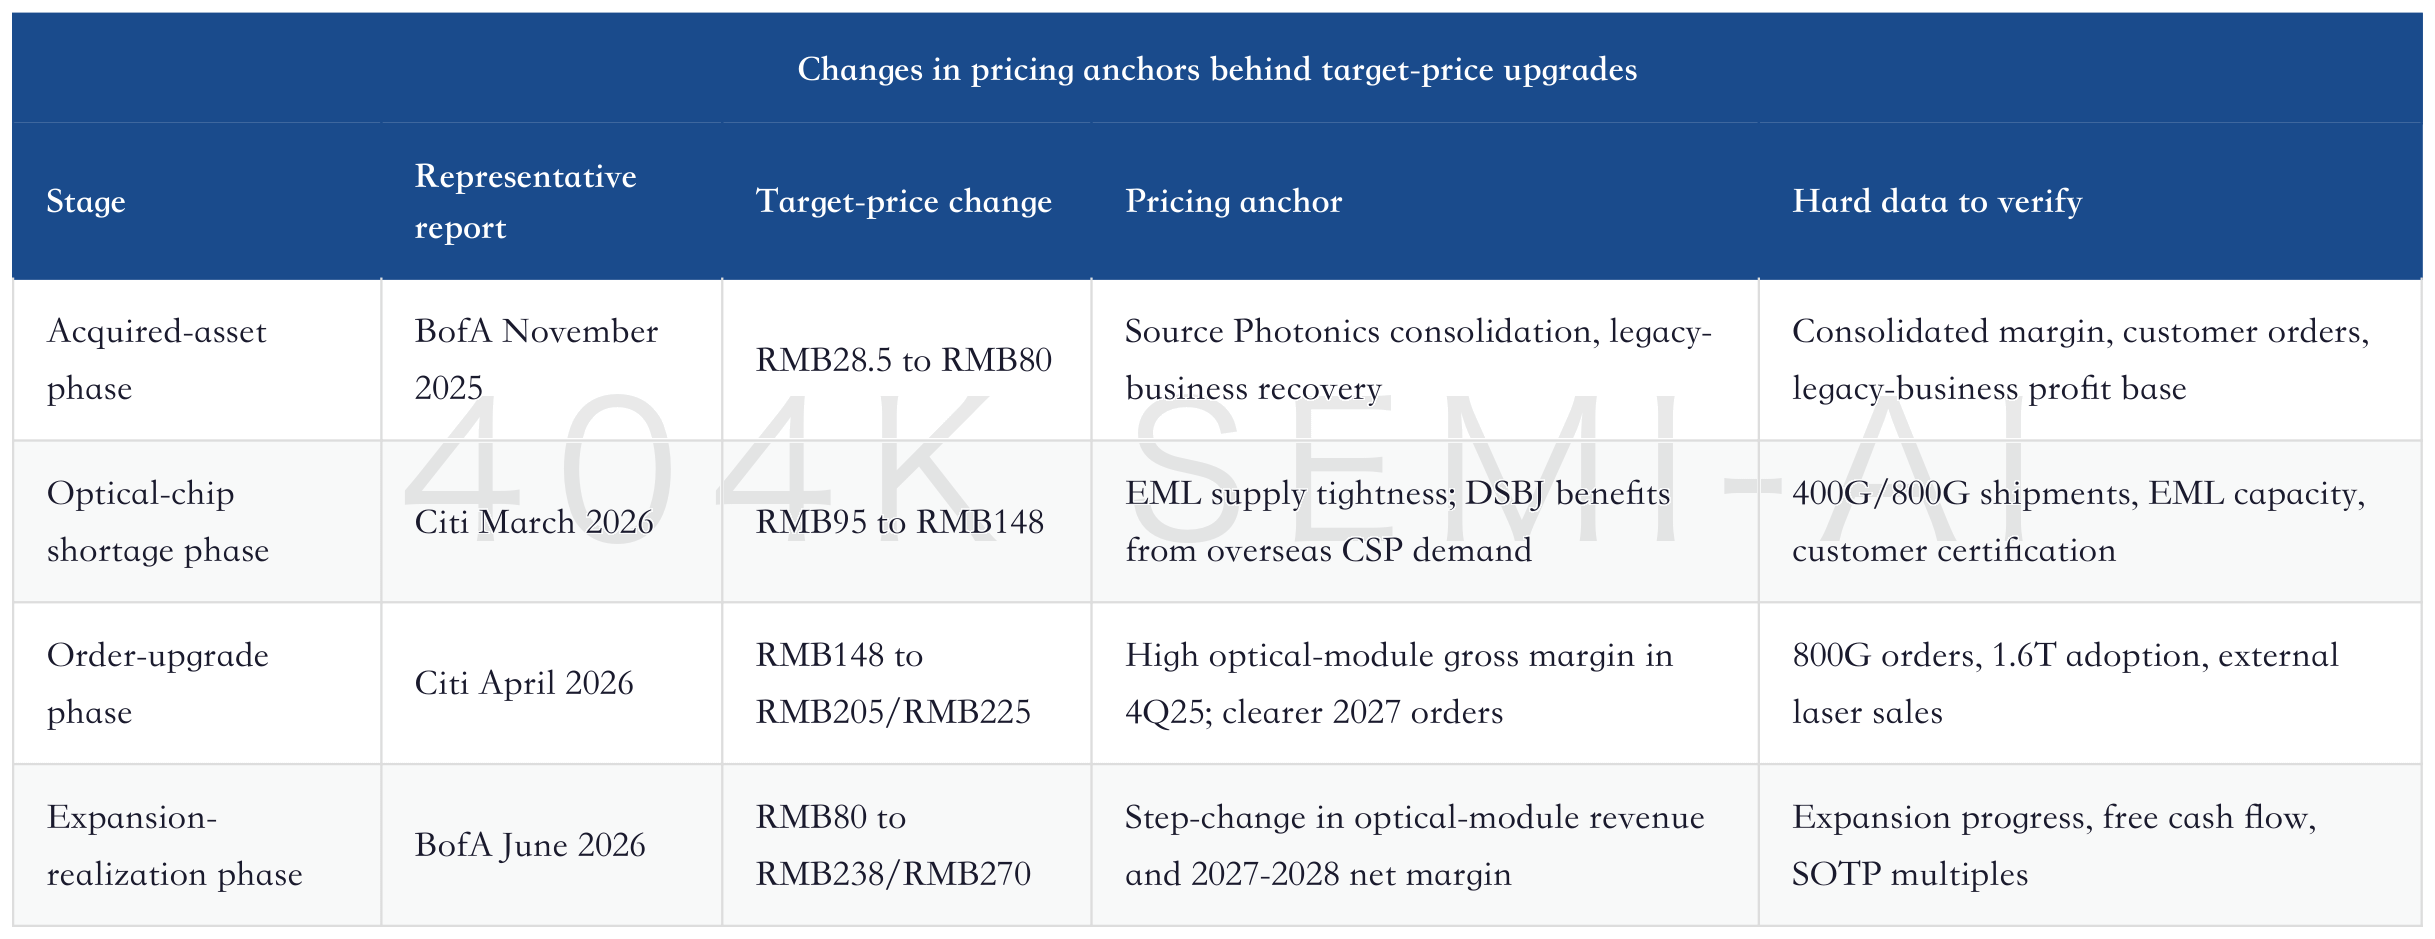
This table shows that DSBJ’s valuation has shifted from “buying an acquired asset” to “buying optical-platform realization.” After the valuation anchor shifts, the share price will require more stringent data. In the acquired-asset phase, as long as Source Photonics could be consolidated and make money, the market was willing to rerate. In the expansion-realization phase, the company must prove simultaneous improvement in order strength, capacity yield, cash collection, and earnings revisions. The biggest risk at this stage is high revenue growth without matching cash flow, because heavy-asset expansion can widen the gap between accounting profit and free cash flow.
The verification method for capex also needs to be specific. The US$1.2bn expansion will first enter construction in progress, prepayments, equipment, R&D;, and labor, then gradually convert into fixed assets, depreciation, and capacity. The earliest signals in financial statements include construction in progress, cash flow, finance costs, and R&D; expenses, while revenue usually appears with a lag. Construction in progress, finance costs, and R&D; expenses already rose together in the first quarter, indicating that expansion is underway. But revenue and gross margin must follow; otherwise, the market will interpret expansion as cost pressure.
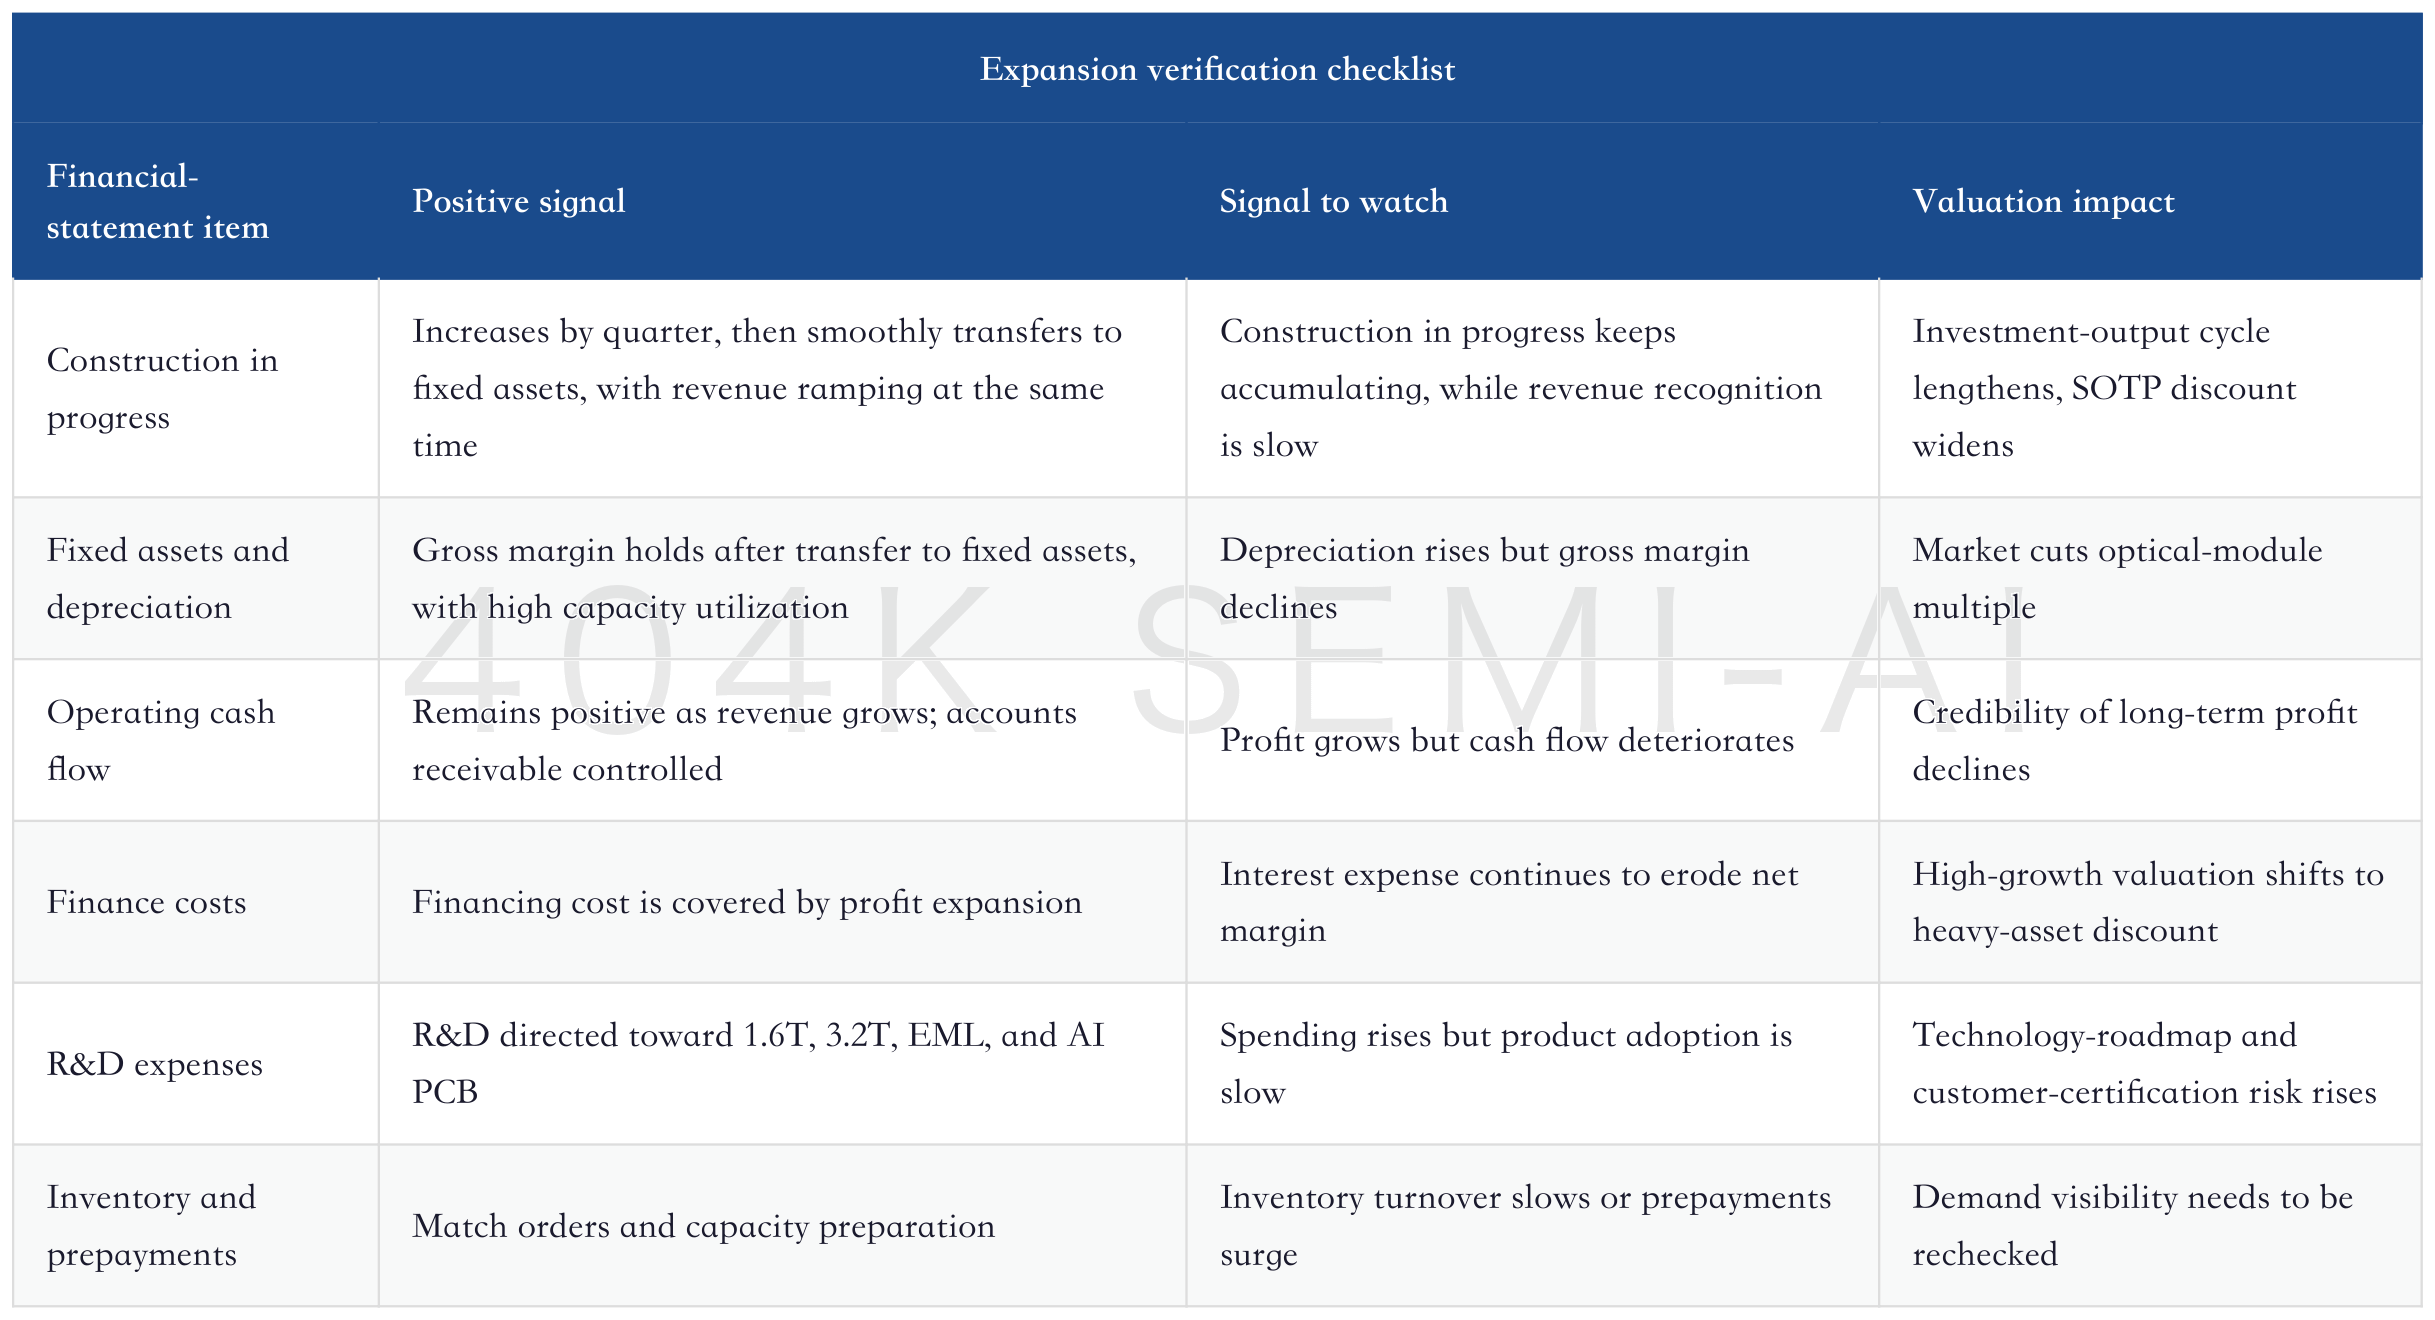
This is also why DSBJ cannot be assessed only by order metrics. In the AI optical-module supply chain, customers give suppliers direction in advance, but final profit comes from mass-production share, pricing, yield, and delivery. If DSBJ wins more 800G and 1.6T orders but needs lower ASP to exchange for share, or if yield ramping causes costs to exceed the model, profit elasticity will be compressed. Conversely, if order volume, gross margin, operating cash flow, and earnings upgrades appear at the same time, the market will continue to treat Source Photonics as a platform asset and raise its value from acquisition contribution to long-term supply-chain position.
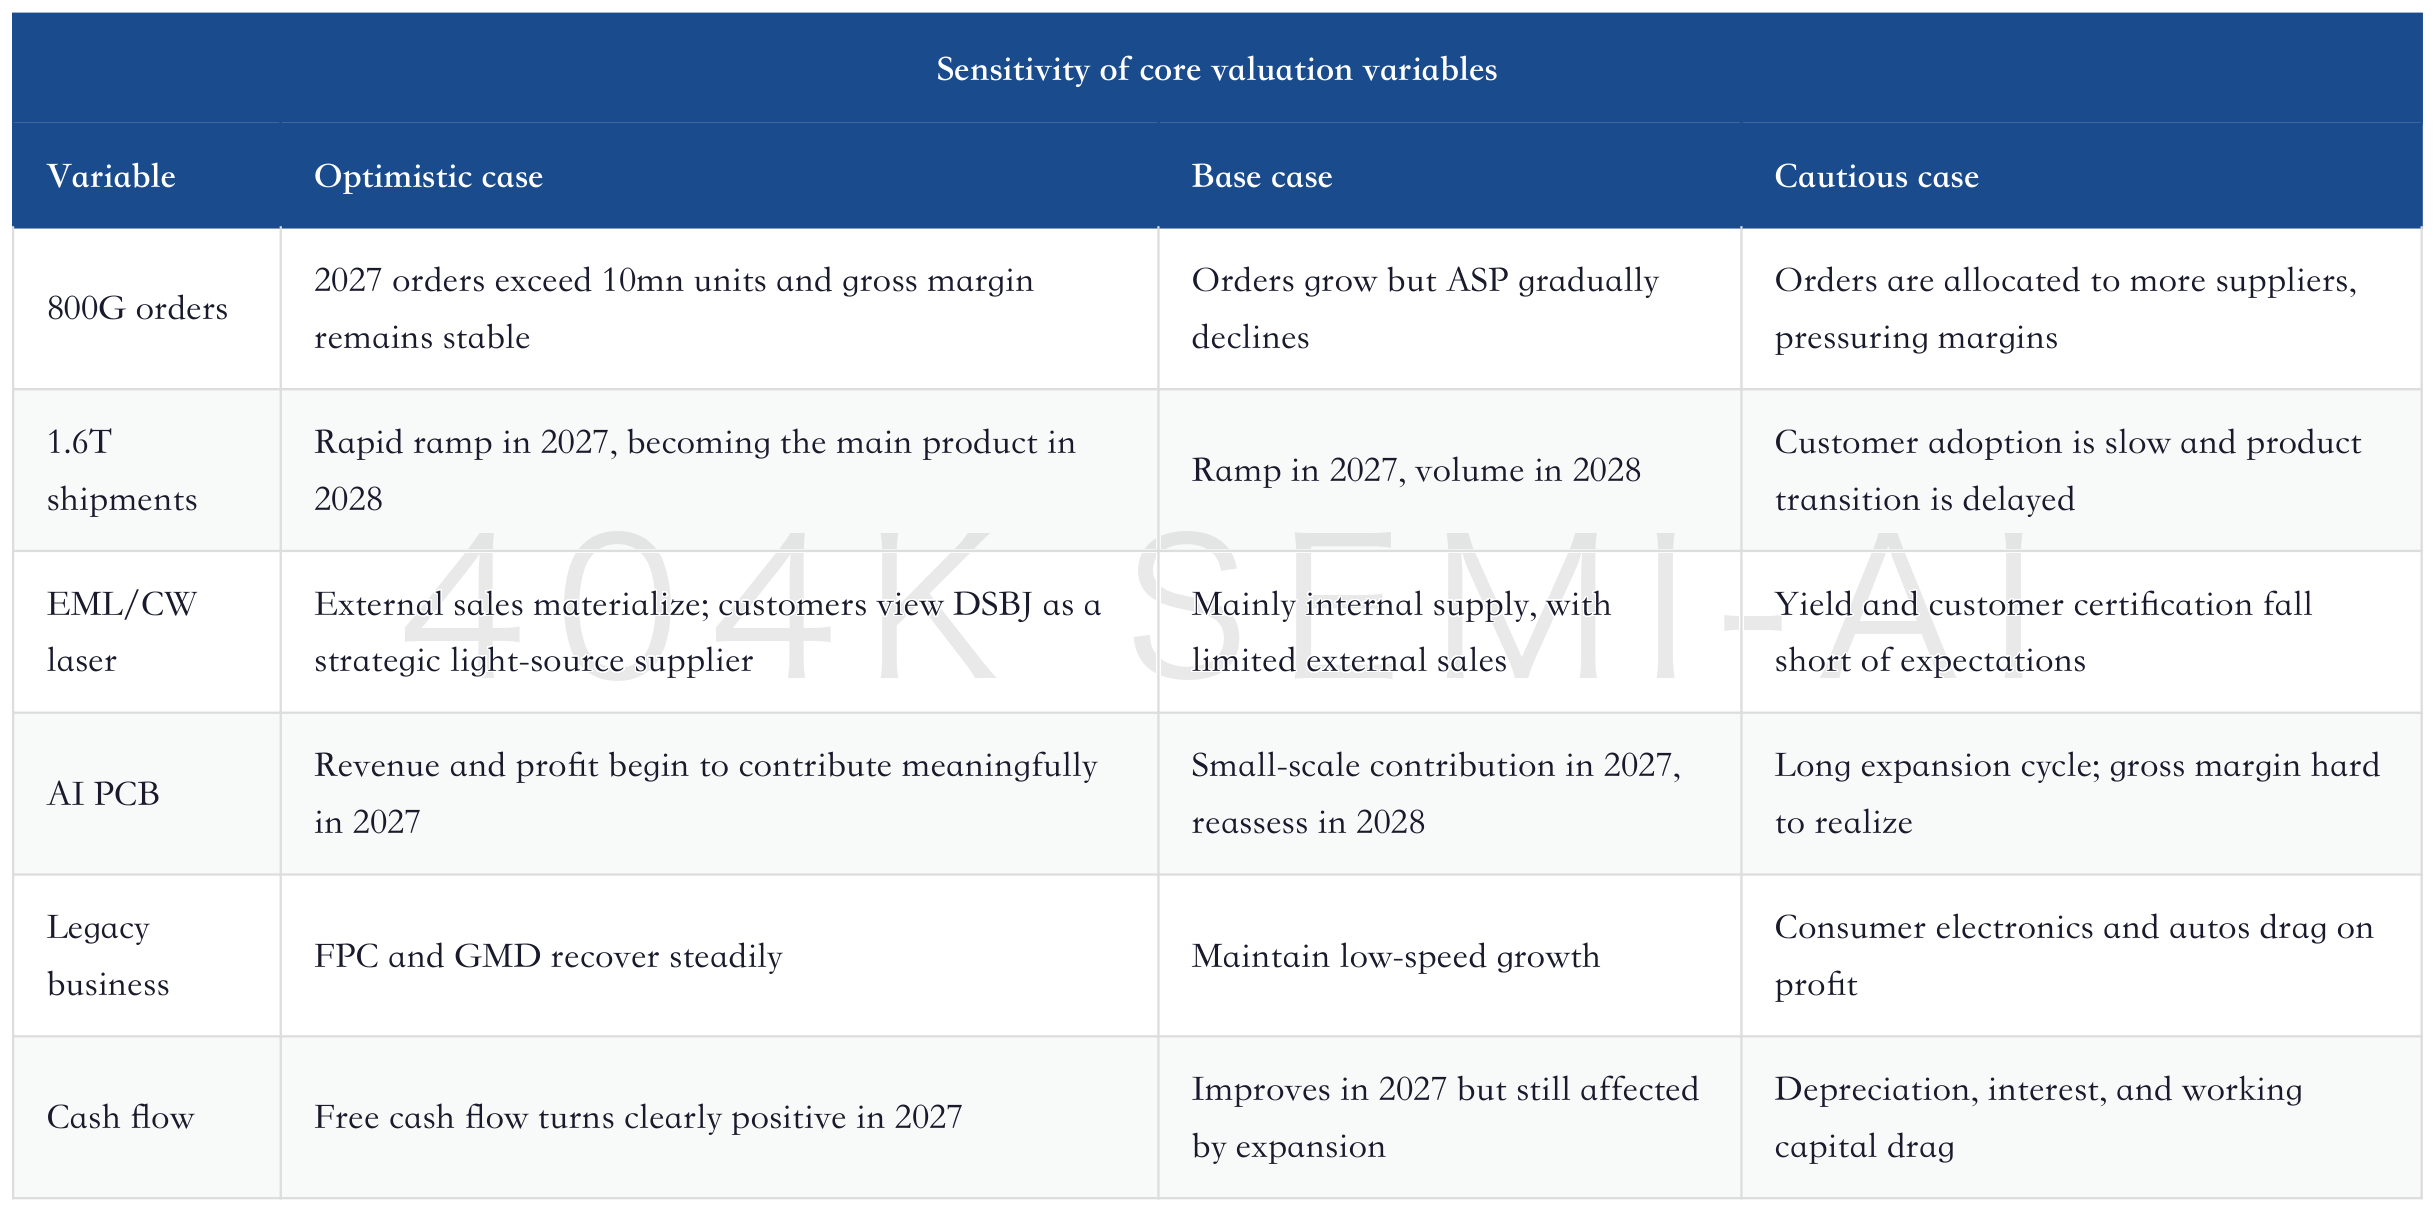
A more realistic valuation cadence is to first watch 2026 profit realization, then look for resonance between 2027 orders and cash flow. In 2026, as long as optical-module revenue and gross margin remain stable, the market will recognize that Source Photonics has completed the first round of validation. In 2027, if 800G orders continue to be revised up, 1.6T enters volume delivery, external laser sales generate real revenue, and free cash flow turns positive, DSBJ’s valuation may have the conditions to continue shifting from “high-growth manufacturer” to “AI interconnect platform.” Conversely, if 2026 profit is strong but cash flow deteriorates, or 2027 orders are strong but gross margin declines, valuation will first pause and wait for data.
The easiest mistake here is to give full valuation to all options. DSBJ does have many good cards, but each card realizes on a different timeline. Optical modules are the fastest, already entering the income statement in 2026. Optical chips come next, with external sales and 200G EML yield in 2027 as the key. AI PCB is slower, with the focus before 2027 mainly on customer certification and capacity. Legacy businesses should only provide a base, and should not enjoy optical-module multiples.
Eoptolink Deep Dive: The Next Stage of AI Optical Modules — 800G, 1.6T, and NPO Rerating
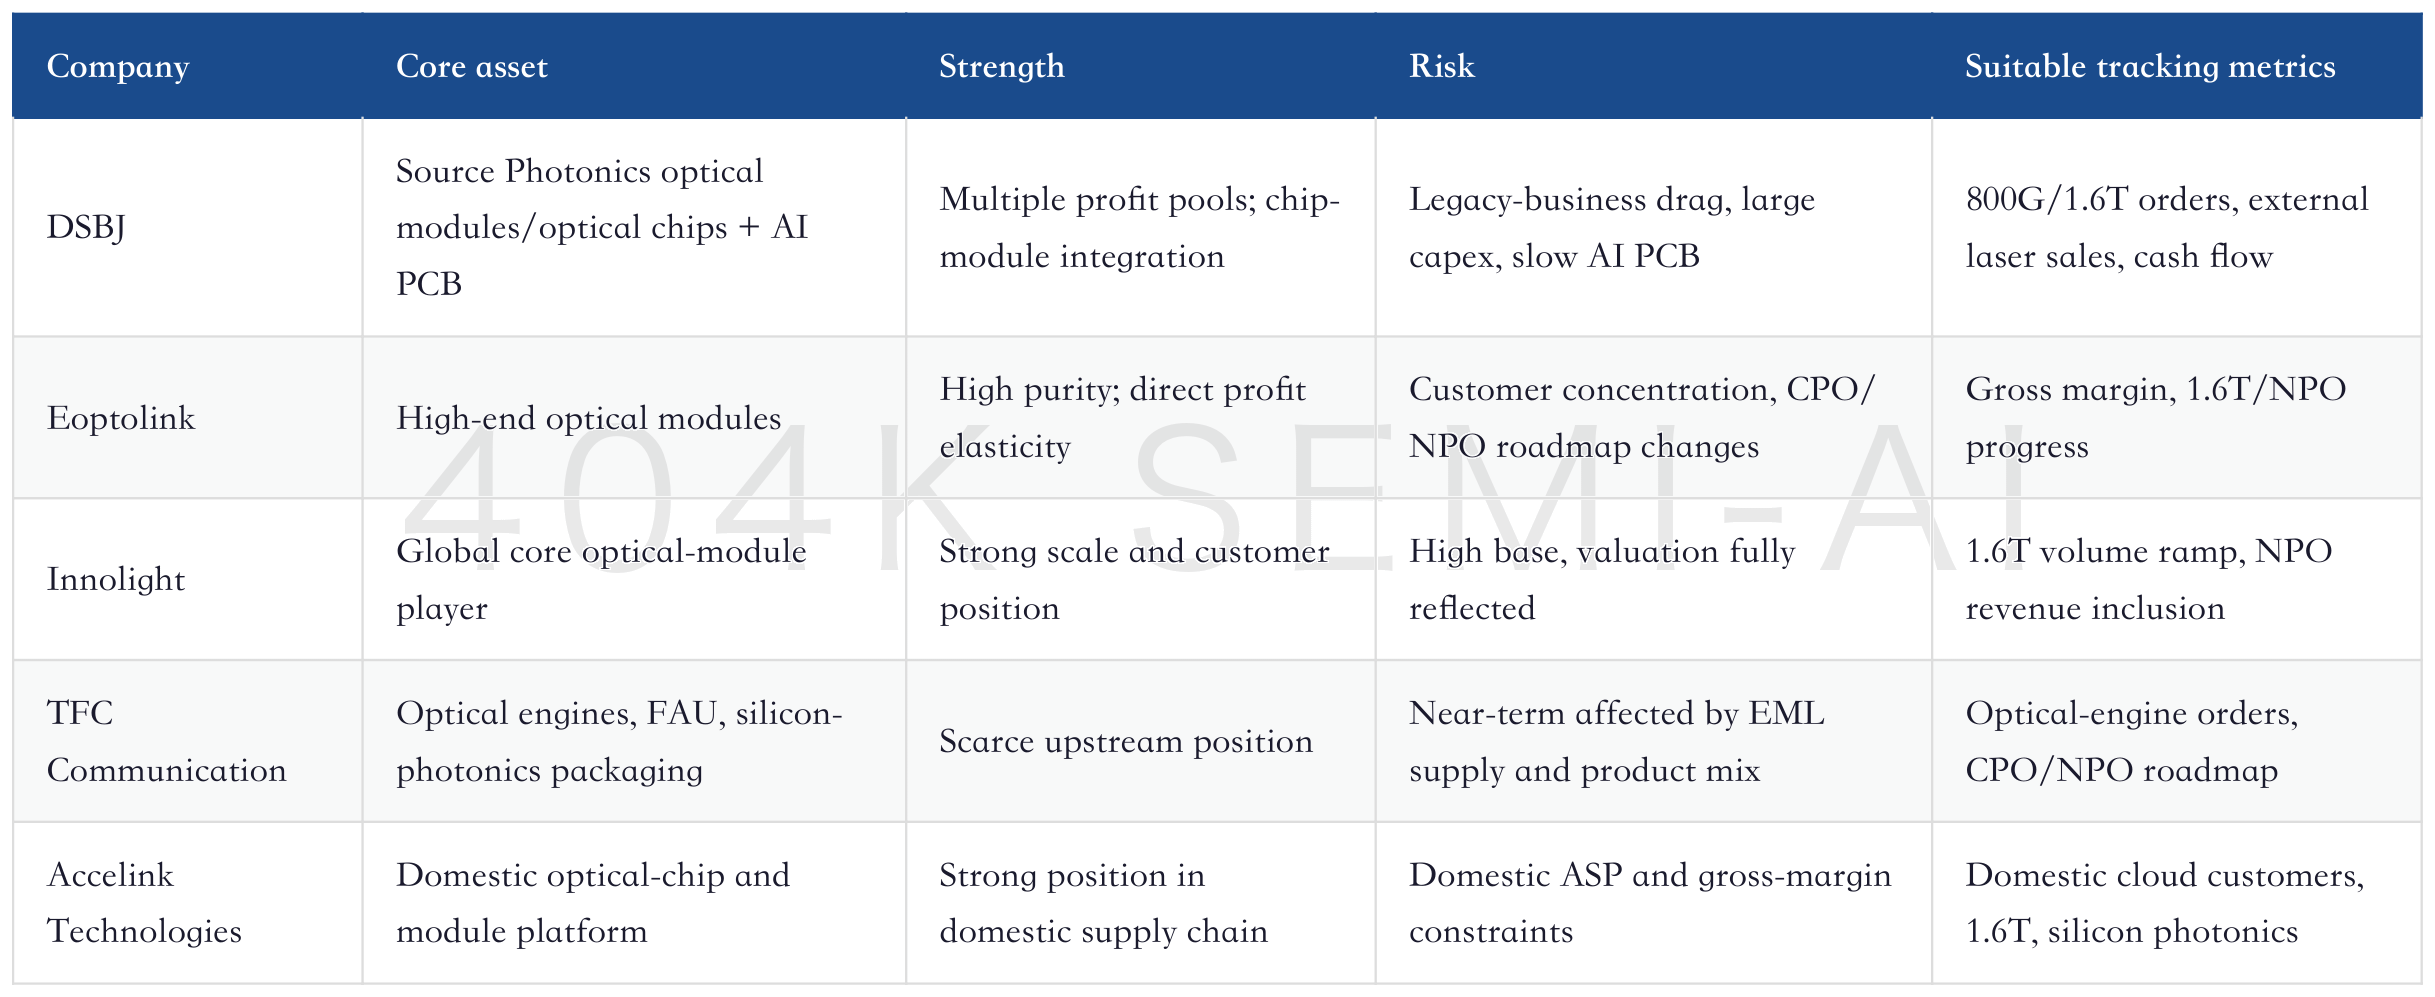
Compared with Eoptolink, DSBJ’s advantage is more options, while its drawback is lower purity. Eoptolink is more like a high-end optical-module profit-realization machine, with more direct gross-margin and customer-structure exposure. DSBJ is more like a composite platform, where optical modules, optical chips, AI PCB, and legacy businesses jointly affect valuation. Compared with TFC Communication, DSBJ has more direct optical-module revenue, while TFC’s optical-engine and CPO/NPO options are purer. Compared with Accelink Technologies, DSBJ has more international overseas customers and Source Photonics assets, while Accelink has stronger domestic optical-chip and central-SOE platform attributes. DSBJ is better placed in the “composite elasticity” bucket, and should not be treated as the purest module stock.
Peer positioning: buy composite elasticity in DSBJ, profit realization in Eoptolink, and optical-engine optionality in TFC Communication
TFC Communication Deep Dive: From Optical-Component Supplier to AI Optical-Engine Platform — 1.6T, NPO, and CPO Rerate Upstream Value
9. Three Scenarios: What This Company Fears Most Is Growth Quality Falling Short of Valuation
DSBJ’s scenario analysis should revolve around growth quality, not just revenue growth. The best-case scenario is strong optical-module orders, rapid 1.6T ramp-up, smooth EML and CW laser capacity expansion, successful AI PCB qualification, stable legacy businesses, and capex quickly converting into profit and cash flow. The neutral scenario is continued optical-module growth but declining ASPs, lasers mainly used for internal supply, slow AI PCB contribution, stable legacy businesses, and valuation being digested by 2027 earnings. The worst-case scenario is that optical-module and optical-chip expansion creates depreciation and finance costs, but customer share, yield, or pricing comes in below expectations, while AI PCB also fails to contribute quickly.
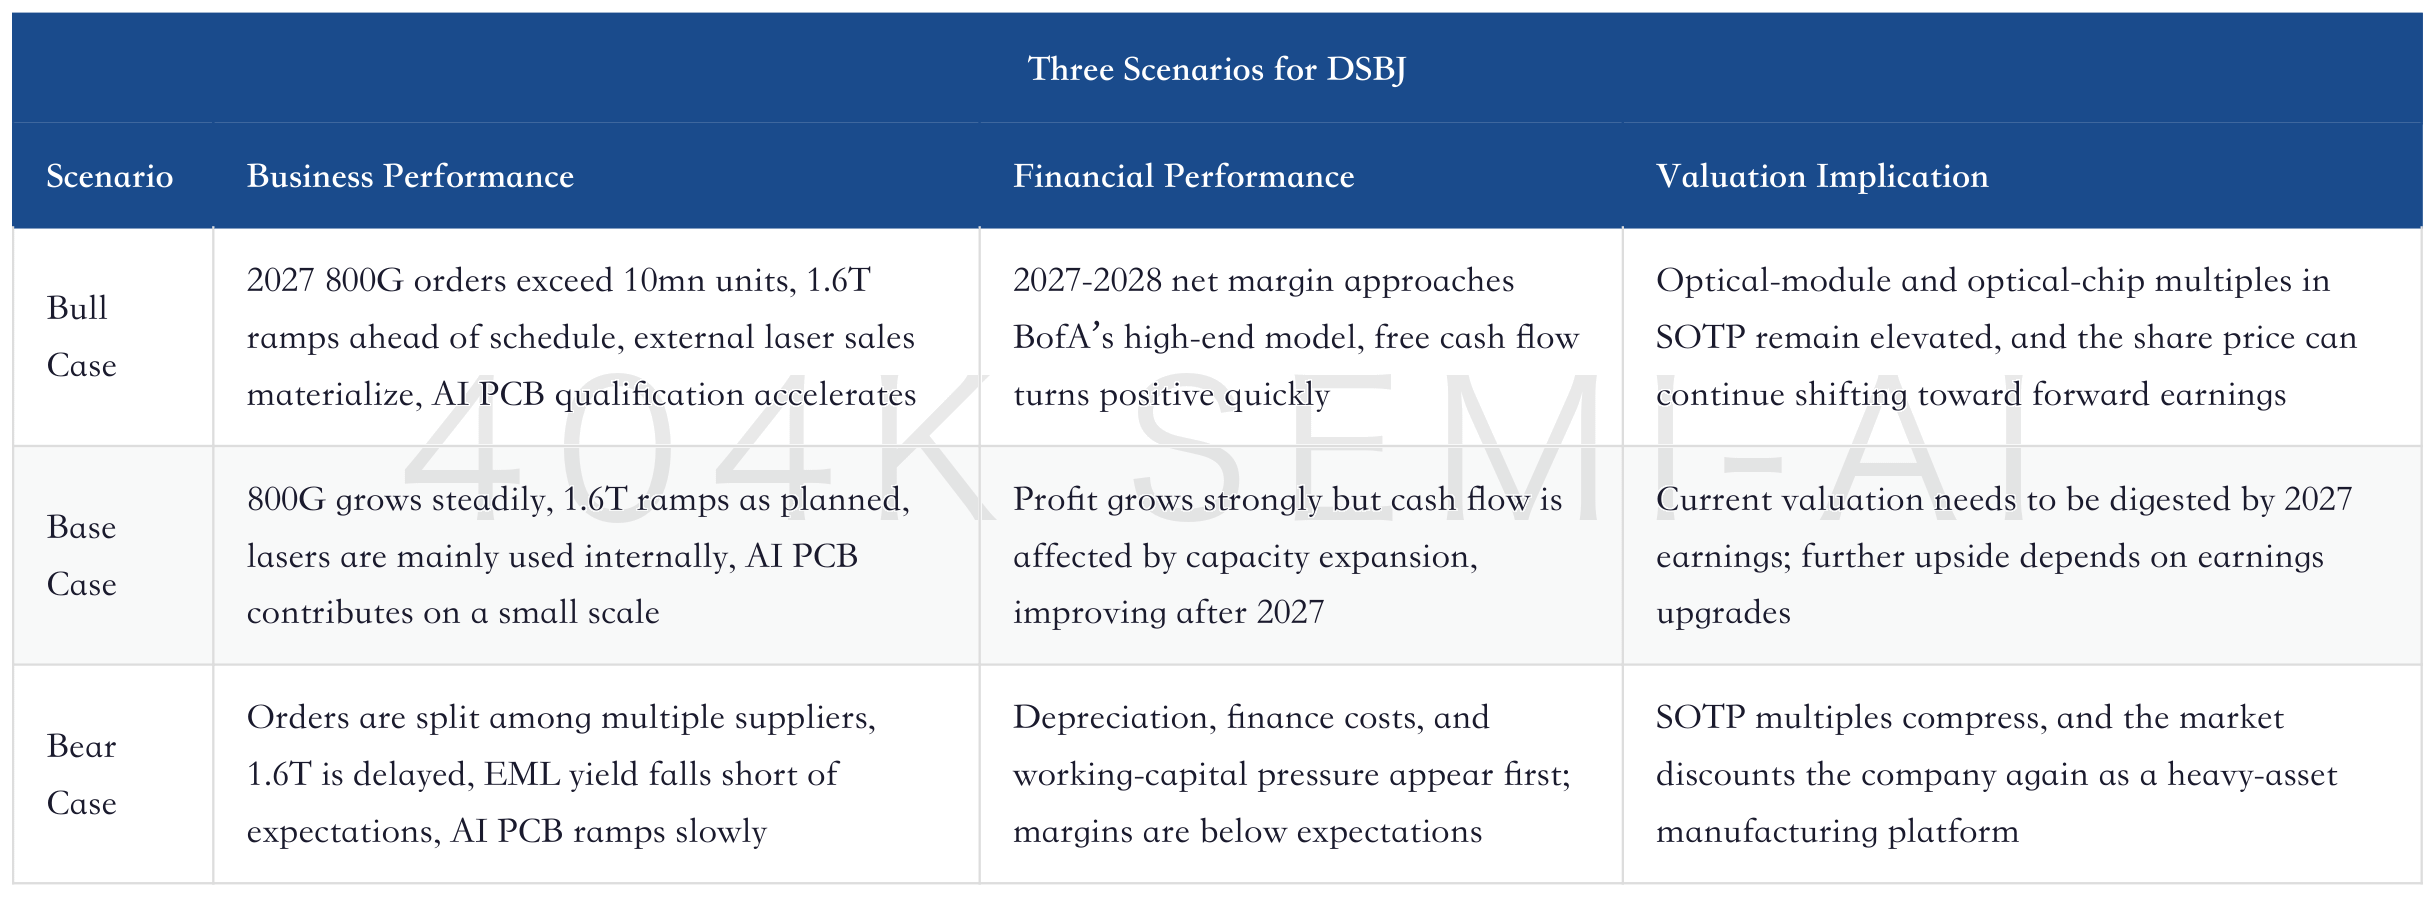
The biggest risk for DSBJ is not a lack of revenue growth. Given that demand for AI optical modules and AI PCB is still likely to grow, it should not be difficult for the company to keep revenue rising. The real risk is that growth quality falls short of valuation. For example, optical-module revenue may grow quickly, but ASP declines, customer bargaining power, externally sourced chip costs, depreciation, and yield losses could compress gross margin. Or optical-chip capacity may be built out, but there may not be enough external customers, leaving more of the capacity as lower-margin internal supply. Or AI PCB investment may be large, but customer qualification may be slow, with depreciation rising before revenue does.
This is also the core reason BofA maintains a Neutral rating. BofA acknowledges DSBJ’s strong growth, while also arguing that the current share price has already capitalized a meaningful portion of that growth. In BofA’s June 17 model, DSBJ’s 2028E EPS reaches RMB20.73. If the market believes this number, the current valuation is not expensive; if 2027-2028 earnings need to be revised down, valuation pressure will increase quickly. For this type of stock, tracking the direction of earnings revisions is more important than watching intraday price action.
10. Tracking List for the Next Four Quarters: Use These Numbers to Judge Whether the Re-Rating Continues
DSBJ’s most important task over the next four quarters is to consistently deliver orders, capacity, gross margin, and cash flow. The tracking list must be as specific as possible; otherwise, investors can easily be led around by each capacity-expansion announcement.
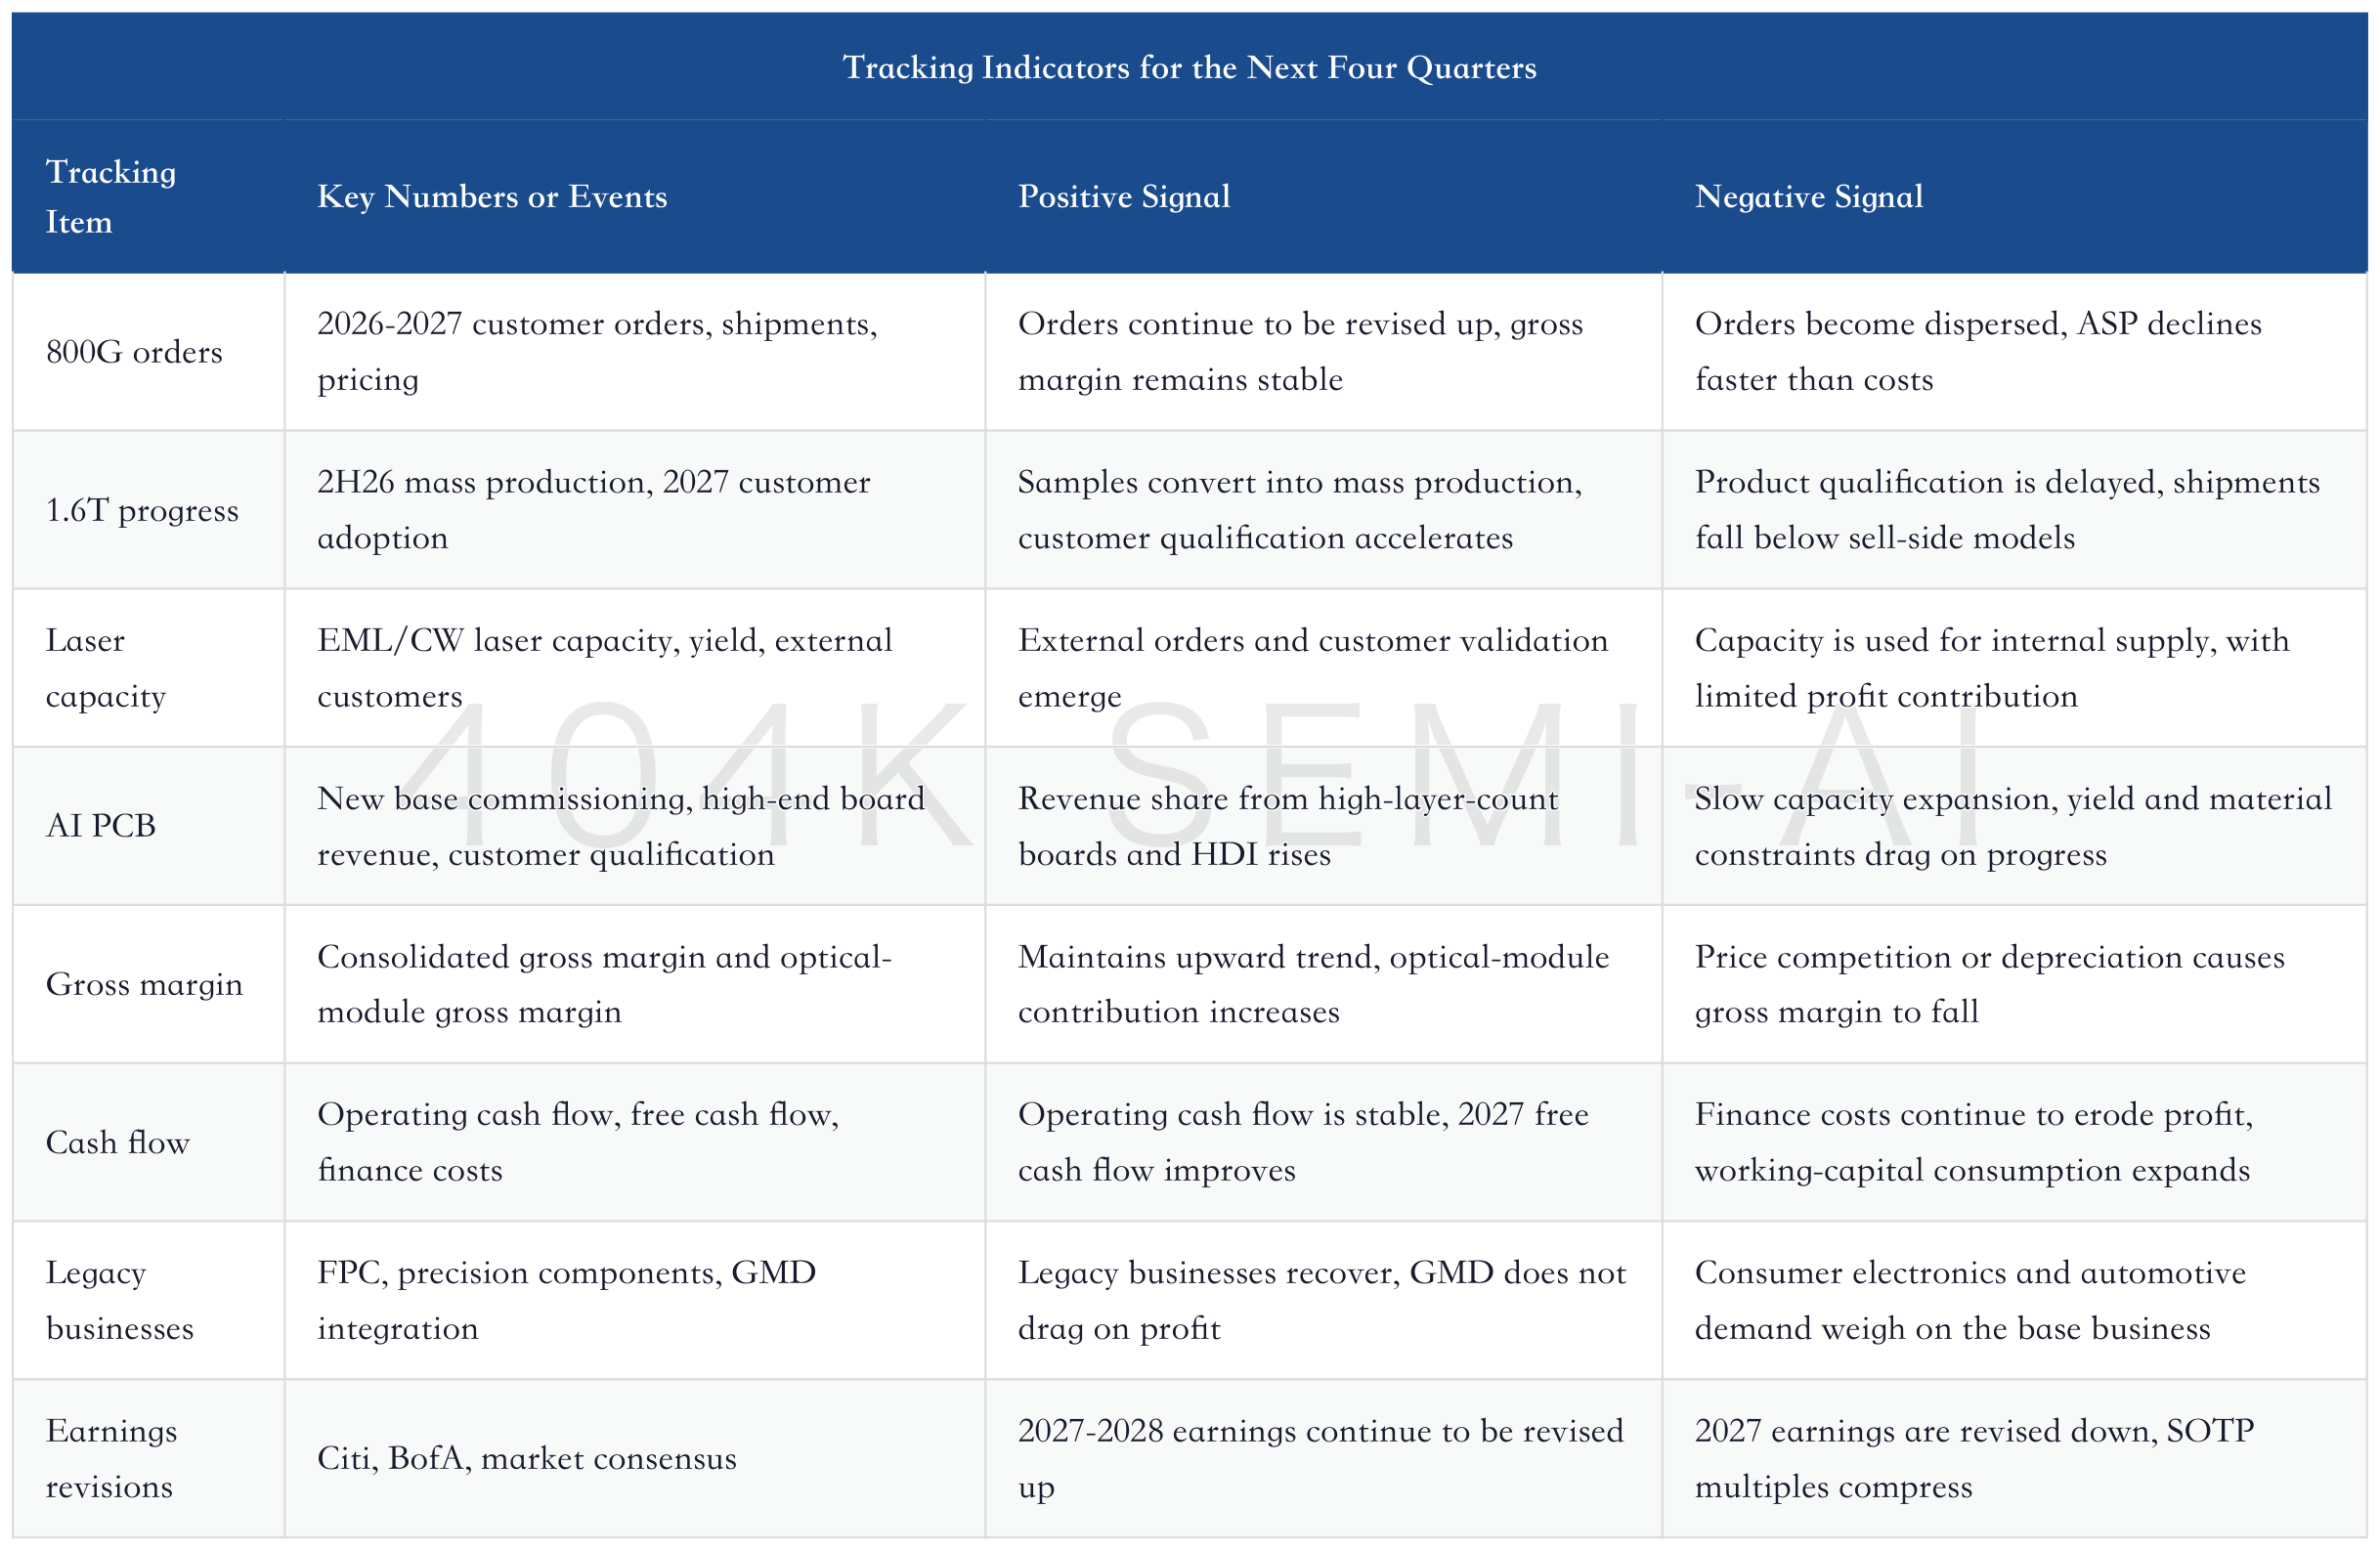
In this list, the most important items are gross margin and free cash flow. Orders can be discussed in advance, capacity can be invested in advance, and target prices can be raised in advance, but gross margin and cash flow are the hardest to mask. If optical modules and optical chips are truly bottleneck assets, gross margin should remain resilient. If capacity expansion can truly bring in high-quality orders, free cash flow should improve meaningfully in 2027. Conversely, if revenue rises but gross margin falls, accounts receivable increases, and free cash flow deteriorates, that would indicate growth quality is below market expectations.
Investors also need to track the combined movement of accounts receivable, inventory, and prepayments. During capacity-expansion periods, high-growth companies usually procure materials in advance, increase equipment prepayments, and may see collection cycles lengthen because of major-customer delivery schedules. A healthy state is one in which revenue, gross margin, operating cash flow, and receivables turnover improve together. A stressed state is one in which the income statement looks strong, but receivables and inventory consumption expand significantly. DSBJ is now in a phase where order upgrades and front-loaded capacity expansion are happening in parallel. These working-capital indicators will reveal growth quality earlier than single-quarter revenue.
11. Falsification Checklist: Order Quality and Cash Collection Determine the Durability of the Re-Rating
The biggest falsification point for DSBJ’s current re-rating is order quality. Demand in the AI optical-module industry is currently very strong, but strong demand will attract more suppliers and encourage cloud vendors to split orders among multiple suppliers. If DSBJ only secures framework demand, without stable share and sustained shipments, the income statement will materialize later than the market expects. Truly high-quality orders need to satisfy several conditions at the same time: customers recognize the product roadmap, delivery cadence is sustainable, pricing is not based on large concessions to gain share, and mass production does not continuously erode gross margin. Each subsequent upward revision to orders by the company or the sell side needs to be verified against gross margin and accounts receivable.
The second falsification point is yield and delivery. As high-speed optical modules move from 800G to 1.6T, requirements for EML, DSP, thermal management, testing, and packaging consistency will all rise. DSBJ has integrated optical-chip and module capabilities. This is an advantage, but it also means yield problems in any link can feed through to delivery and gross margin. The market is currently willing to assign Source Photonics a higher valuation because it is seen as a supply-chain bottleneck asset. Bottleneck assets need to demonstrate stable supply capability. If there are only capacity announcements without stable delivery, valuation multiples will fall.
The third falsification point is external laser sales. Internal optical-chip supply can improve certainty of module delivery, while external sales determine whether the market treats lasers as an independent profit pool. Both BofA and Citi acknowledge the strategic importance of lasers to customers, but the near-term profit driver remains high-end modules. If lasers mainly remain for internal supply, DSBJ can still earn module profits, but the optical-chip high multiple will be discounted. If external customers start to increase, the market will be more willing to view the business within an upstream bottleneck-asset framework. This difference will directly affect the multiple in the SOTP.
The fourth falsification point is AI PCB. Multek’s capabilities in high-layer-count boards, thick-board HDI, and low-loss materials give DSBJ a second growth leg, but the qualification cycle for AI PCB is naturally longer. This business must go through material qualification, process ramp-up, customer audits, yield stabilization, and batch delivery. If any link slows, profit contribution will be pushed out. DSBJ’s advantage is that it may share some customer entry points with Source Photonics. The risk is that pure-play PCB companies are also expanding capacity rapidly, and customers will continue to compare suppliers based on delivery capability and cost. AI PCB should initially be treated as an option in the model, with its weight raised only after revenue and gross-margin inflection points appear.
The fifth falsification point is cash flow. High-growth manufacturing companies are most prone to periods where the income statement looks strong but cash flow cannot keep up, especially when acquisitions, capacity expansion, and customer onboarding occur simultaneously. DSBJ has already entered a period of heavy capital investment. Finance costs, equipment investment, R&D; investment, and working capital will all come before revenue release. As long as operating cash flow is stable, accounts receivable is controllable, and inventory turnover does not deteriorate significantly, the market will accept near-term investment pressure. If profit growth is accompanied by persistent cash-flow deterioration, investors will again view DSBJ as a heavy-asset manufacturing platform rather than an optical platform that can easily enjoy high-growth multiples.
The final falsification point is the base provided by legacy businesses. FPC, traditional PCB, precision components, and GMD do not determine the valuation ceiling, but they do determine whether the company can move smoothly through the capacity-expansion period. If demand from consumer electronics or automotive customers weakens, profit and cash flow from legacy businesses will reduce the company’s ability to absorb expansion pressure. The benefit of a composite platform like DSBJ is multiple profit pools; the drawback is more noise. Investors should not only look at the brightest optical-module business, but also confirm that legacy businesses are not continuously dragging down consolidated margins.
The purpose of this falsification checklist is simple: the market already believes DSBJ has AI assets; the next question is whether those AI assets can become high-quality profit. Orders, yield, external sales, AI PCB, cash flow, and the legacy-business base can each change the direction of earnings revisions. As long as most indicators improve in the same direction, DSBJ’s re-rating can continue. If indicators begin to diverge, the market will first lower the multiple and then wait for the next earnings report for confirmation.
Another easily overlooked falsification point is the granularity of disclosure. DSBJ’s business mix is now much more complex than in the past, and investors need a clearer understanding of the revenue, gross margin, capacity utilization, and order cadence of optical modules, optical chips, AI PCB, and legacy businesses. The clearer the disclosure, the easier it is for the market to break growth into verifiable models. The more general the disclosure, the easier it is for the market to discount all positive news. Source Photonics and Multek in particular are no longer suitable for explanations based only on phrases such as “good growth” and “strong demand.” Going forward, it would be better to provide more specific direction on customers, product generations, capacity, and margins.
Supply-chain position also needs to be verified dynamically. DSBJ’s advantage comes from vertical integration, but vertical integration only amplifies value when key links are in short supply. If future supply improves for EML, CW lasers, DSP, silicon photonics, or other key components, customers may push for lower prices again, and supply-chain profit may flow back from bottleneck links to downstream customers. DSBJ needs to defend its position through continuous iteration and stable delivery, not rely only on the current shortage window. A truly strong platform company can win orders when supply-demand conditions are tight and retain customers through quality, cost, and responsiveness when supply-demand conditions ease.
The competitive landscape also needs to be viewed dynamically. In AI optical modules, Eoptolink, Innolight, Coherent, Lumentum, and others are all competing for high-speed generation opportunities. In AI PCB, Victory Giant Technology, WUS Printed Circuit, Shennan Circuits, Shengyi Electronics, and others are also expanding capacity. In optical devices and optical chips, there are also players with different positioning, such as TFC Communication and Accelink Technologies. DSBJ’s advantage is its combined capability; its disadvantage is that none of its business lines competes in isolation. If the market gives it a platform valuation, it is effectively betting that the company can win multiple local battles at the same time. This is a high bar and must be continuously proven through financial results and orders.
On valuation, investors also need to guard against linear extrapolation. DSBJ’s re-rating this year has mainly come from a shift in asset attributes. Once that asset-attribute shift is complete, the market will move into an earnings-revision trade. Earnings-revision trades are shorter, faster, and more selective: target-price increases can improve sentiment, but the next increase requires new orders, new yield evidence, or new cash-flow improvement. If sell-side models only hold steady rather than move higher, the share price will enter a digestion period. If earnings continue to be revised up, the platform story can continue to expand. For investors, the key is to judge the direction of the next round of earnings revisions; capacity-expansion announcements are only the starting point.
Putting these falsification points together, DSBJ’s best path is clear: Source Photonics continues to deliver high-speed modules, optical-chip capabilities help the company stabilize its customer position, AI PCB begins to contribute higher-quality revenue after customer qualification, legacy businesses maintain cash flow, and capex gradually converts into profit. This path would make the market willing to continue valuing DSBJ within a platform-company framework. The weaker path is also clear: the order narrative looks strong, but gross margin, cash flow, and delivery cadence fail to keep up, leading the market to pull valuation back into a heavy-asset manufacturing framework.
Therefore, every subsequent rise in DSBJ’s share price needs new evidence to take over. As long as the evidence chain remains intact, valuation can shift toward forward earnings. Once the evidence chain breaks, the share price will first wait for financial results to confirm. For this type of stock, investors cannot look only at the strength of the story; they need to look at how quickly the story enters the income statement and cash flow.
Put more simply, DSBJ now needs continuous delivery to digest expectations. As long as orders, gross margin, cash flow, and customer qualification improve in the same direction, the market will continue to give it time. If any one of these items clearly falls behind, investors will reassess the pace of capacity expansion and valuation multiples.
12. Conclusion: Dongshan Precision Has Become an AI Optical Platform, but Pricing Must Wait for Profits to Keep Catching Up
Dongshan Precision’s rerating has already moved past the question of whether it has an AI story. Its 2026 Q1 results showed that Source Photonics can contribute revenue and profit. The US$1.2 billion capacity expansion showed that management has greater confidence in medium- to long-term demand. Citi’s and BofA’s successive upgrades showed that sell-side models have already made optical modules, optical chips, and AI PCBs core inputs. The key question now is whether Dongshan can use 2026-2028 profit and cash flow to substantiate the platform valuation that the market has already assigned.
The most attractive part of the company is that, among A-share names, it is rare in having all three AI interconnect chains: PCB, optical modules, and optical chips. Victory Giant, WUS Printed Circuit, Shennan Circuits, and Shengyi Technology are strongest in PCB/CCL. Eoptolink and Zhongji Innolight are strongest in high-end optical modules. TFC is strongest in optical engines and upstream components. Dongshan’s distinctive feature is its composite profile: it may not be the purest company in every segment, but it has put high-speed optical modules, EML/CW lasers, and AI PCBs inside the same group. If customers recognize this composite capability, it can support a platform valuation.
Composite capability also means a higher validation threshold. Dongshan needs to prove that multiple segments can work together. Source Photonics needs to prove that high-end modules and optical chips can continue to scale. Multek needs to prove that AI PCBs can become effective capacity. GMD and legacy businesses need to prove they will not drag on cash flow. Capex needs to prove that it can convert into orders and profit. As long as this validation keeps progressing, Dongshan remains one of the most worth-tracking assets at the intersection of A-share AI optics and AI PCBs.
When researching Dongshan, the key is to grade management as a “cross-asset integrator.” Source Photonics provides the optical product line, Multek provides high-end board capability, GMD provides European automotive structural-parts assets, and the legacy FPC and precision manufacturing businesses provide the customer, factory, and cash-flow base. Looking at any one business alone, it is hard to explain why the market is willing to assign a higher platform valuation. Only when these businesses are placed inside the same AI interconnect and global delivery system does Dongshan’s asset rerating logic emerge. The issue is also here: composite platform value is high, but management complexity is also high.
What management most needs to prove next is whether asset synergy can lower customer qualification costs, reduce supply-chain risk, and improve delivery certainty. For example, if overseas cloud customers recognize both Source Photonics optical modules and Multek high-end PCBs, Dongshan’s customer relationships will deepen. If optical-chip self-supply can make module delivery more stable, the company’s position in customer supply chains will become more secure. If legacy-business cash flow can support the expansion cycle, capex pressure will not erode valuation too early. Once these synergies materialize, platform value will be more durable than single-point profit.
Investors also need to accept a reality: Dongshan’s execution over the next several quarters is unlikely to be linear. New-line commissioning, customer validation, yield ramp, overseas delivery, and working-capital recovery are unlikely to improve in sync every quarter. What truly matters is direction and quality, especially whether gross margin holds, whether orders move from intention to mass production, and whether cash flow gradually catches up with profit. If these metrics improve consecutively, short-term expense volatility can be understood. If there is only expansion and order rhetoric while profit quality fails to keep up, the market will quickly lose patience with the platform story.
Scoring Dongshan also requires looking at organizational capability. Optical modules, optical chips, PCBs, precision manufacturing, and automotive structural parts differ in process language, customer cadence, and balance-sheet cadence. Source Photonics faces overseas cloud vendors and high-speed optical interconnect upgrades. Multek faces AI server and switch PCB specification upgrades. Traditional businesses face cost management for consumer-electronics and automotive customers. Putting these businesses into the same listed company has the advantage that customer and manufacturing resources can reinforce each other, but the challenge is that management must keep prioritizing across R&D;, capacity expansion, quality, cash flow, and M&A; integration. If the company can continue to show a clear input-output path in quarterly earnings, the market will be more willing to treat Dongshan as a platform company. If disclosure stays only at the level of orders and expansion, investors will demand a higher risk discount.
This also means Dongshan’s trading cadence differs from pure optical-module targets. Pure optical-module names are more directly priced off orders, gross margin, and product-generation changes. Dongshan also requires attention to the legacy-business base, debt cost, construction in progress, M&A; integration, and AI PCB execution. Its upside may be richer, but the validation chain is longer. The right research method for Dongshan is to put optical revenue, optical-chip progress, AI PCB certification, capex, and cash flow into one table every quarter; focus less on single pieces of news and more on whether the data are improving in the same direction.
For this type of company, the most important thing to track is whether a one-quarter surprise can become consecutive earnings revisions. That matters more than reported profit in any single quarter. Dongshan has already secured its ticket for repricing. Next, it must use more stable delivery, clearer customer recognition, and more solid cash collection to convert that ticket into a real platform valuation.
A more direct judgment: Dongshan Precision has entered the high-expectation delivery phase, and the low-base rerating phase is over. Low-base rerating depends on changes in asset labels; high-expectation delivery depends on whether the company can deliver numbers every quarter. The US$1.2 billion expansion raises the long-term revenue ceiling, but it also raises short-term cash-flow and depreciation pressure. As long as 800G orders, 1.6T introduction, external laser sales, and AI PCB certification continue moving upward, valuation can be absorbed by 2027-2028 profit. If any one segment sees a clear delay, the market will first compress the high multiples assigned to optical modules and optical chips in the SOTP.
The conclusion is clear: the business direction has been validated, but the valuation outcome is still in progress. Track four hard numbers: 2027 800G orders, 1.6T shipments, external laser sales, and free cash flow. If Dongshan can deliver them consistently, it will truly transform from a consumer-electronics manufacturing company into an AI optical platform. If it cannot, the US$1.2 billion expansion will shift from an upside option into depreciation and interest pressure.Dongshan Precision Deep Dive: From Consumer Electronics Manufacturing to an AI Optical Interconnect Platform, and How Source Photonics, Optical Chips, and AI PCBs Should Be Re-rated
目录
Too Long; Didn’t Read
I. Investment Conclusion: The Market Is Buying an Optical Platform; the Debate Is How Far Valuation Has Already Run
II. From Old Assets to New Assets: Dongshan’s Change Is a Shift in Profit Pools, Not More Themes
III. 2026 Q1 Earnings: This Strong Growth Officially Puts Source Photonics Into the Income Statement
IV. Source Photonics: Dongshan Precision’s Real Value Lies in Optical Chip and Module Integration
V. US$1.2 Billion Expansion: It Raises Order Confidence, but Also Raises ROI Pressure
VI. AI PCB: DSBJ’s Second Growth Leg, Harder to Validate Than Optical Modules
VII. Sell-Side Divergence: Citi Buys Orders, BofA Buys Discipline, HSBC and UBS Record Early-Stage Transformation Noise
VIII. Valuation Framework: DSBJ Is Suited to SOTP, but Every Segment Needs a Discount
9. Three Scenarios: What This Company Fears Most Is Growth Quality Falling Short of Valuation
10. Tracking List for the Next Four Quarters: Use These Numbers to Judge Whether the Re-Rating Continues
11. Falsification Checklist: Order Quality and Cash Collection Determine the Durability of the Re-Rating
12. Conclusion: Dongshan Precision Has Become an AI Optical Platform, but Pricing Must Wait for Profits to Keep Catching Up
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core of Dongshan Precision’s current re-rating is that Source Photonics brings optical modules, optical chips, and AI PCBs into the same delivery system. The US$1.2bn capacity expansion raises long-term order expectations, while also shifting the valuation debate to cash flow, yield, and delivery of effective AI PCB capacity. The key question now is whether earnings can catch up with market-cap expectations.
Too Long; Didn’t Read
Dongshan has entered the validation phase. 2026Q1 revenue was RMB13.138bn and net profit attributable to shareholders was RMB1.110bn. Optical modules have already been consolidated into the income statement; the next focus is whether high-margin businesses can cover M&A; loans, depreciation, and working capital.
Source Photonics determines valuation elasticity. The company has capabilities in 400G, 800G, and 1.6T modules, as well as 100G/200G PAM4 EML and CW lasers. Modules support earnings; optical chips support customer stickiness and valuation multiples.
The US$1.2bn expansion amplifies disagreement. BofA raised its target price to RMB270 but maintained Neutral, while Citi places more weight on order visibility. The debate has shifted to whether the share price has already discounted forward earnings.
AI PCB is the second growth leg. Multek has capabilities in high-layer-count and thick-board HDI. 2026Q1 construction in progress increased 46.96% from the beginning of the year; customer qualification, materials, and yield will determine the pace of monetization.
Legacy businesses provide the cash-flow base. FPC, traditional PCB, precision components, and GMD can stabilize revenue, but the valuation ceiling still depends on the ramp of 800G, 1.6T, EML, and AI PCB.
Track four hard indicators. Over the next four quarters, monitor 800G orders, 1.6T mass production, external laser sales, AI PCB revenue, and free cash flow. If any link slows, the high multiple will contract first.
I. Investment Conclusion: The Market Is Buying an Optical Platform; the Debate Is How Far Valuation Has Already Run
The most important question for Dongshan Precision is straightforward: can it transform from a consumer electronics manufacturer into an AI optical interconnect platform company? The previous 404K SEMI-AI deep-dive report on Dongshan Precision already placed Source Photonics, GMD, and AI PCB into the same asset re-rating framework. The additional materials in June pushed the issue further forward. After the company announced a US$1.2bn investment through Source Photonics to expand optical chip and optical module capacity, the market’s question became: can this capex cycle translate into orders and earnings of sufficiently high quality?
Dongshan Precision Deep Dive: From Consumer Electronics Precision Manufacturing to an AI Optoelectronics Platform — How Source Photonics, GMD, and AI PCB Should Be Re-rated
The core judgment is direct: Dongshan Precision’s asset label has changed, and valuation discipline must change with it. In the past, it was mainly framed as an Apple supply-chain, FPC, traditional PCB, and automotive precision-parts company. Source Photonics now brings it into the framework of AI optical modules, EML optical chips, CW lasers, 1.6T, and CPO/NPO-related light sources, while Multek allows the company to retain an adjacent AI PCB profit pool. This combination makes the company more complex than an ordinary PCB manufacturer, and more asset-heavy than an ordinary optical module vendor.
The divergence between BofA and Citi illustrates exactly where the market stands. BofA raised its target price several times in June but maintained Neutral, arguing that the share price already reflects substantial expectations. Citi continued to raise its target price in the spring, placing more emphasis on order visibility and the demand confidence implied by optical capacity expansion. Both sides acknowledge that the business is strengthening. The difference is that Citi is more willing to price in forward orders and the optical chip bottleneck, while BofA is more focused on how much has already been reflected in the share price.
How to read this table matters. Dongshan’s re-rating earnings elasticity is concentrated in Source Photonics and AI PCB, while FPC, consumer electronics PCB, precision components, and GMD mainly determine the base and risk resilience. The real determinants of the market-cap ceiling are whether optical module revenue can sustain high growth, whether optical chips can become a bottleneck asset, and whether AI PCB can move from expansion announcements to high-margin revenue.
For investment purposes, two questions must be separated. At the business level, Dongshan has moved from “having a story” to “having income-statement evidence”; the first-quarter report showed strong growth in revenue, net profit attributable to shareholders, and recurring net profit. At the valuation level, the market has already priced in substantial expectations. The reported price is close to BofA’s target price, and forward multiples are not low. A stronger business does not automatically mean a cheap stock; going forward, earnings must continue to compress valuation.
II. From Old Assets to New Assets: Dongshan’s Change Is a Shift in Profit Pools, Not More Themes
Dongshan Precision’s historical assets are clear. The company started with precision manufacturing, then entered FPC through MFLEX, filled out rigid PCB, rigid-flex boards, and high-end multilayer boards through Multek, entered optical modules and optical chips through Source Photonics, and entered European automotive structural parts through GMD. In the past, these assets looked somewhat scattered. The AI data-center cycle has reconnected them: GPU/ASIC servers require high-speed PCBs, switches require high-layer-count boards and low-loss materials, optical modules require EML and CW lasers, and the automotive and consumer electronics base provides cash flow and global manufacturing management capabilities.
The annual report provides a useful static snapshot. Electronic circuit products remain the main revenue base. Optical module revenue still accounts for a low share, but gross margin is significantly higher, as shown below. This comparison explains why the market is willing to re-rate Dongshan: optical modules are still small in scale in the short term, but have much stronger profitability. After Source Photonics is consolidated for a full year, earnings elasticity will be much greater than its revenue share suggests.
Dongshan’s asset shift can be compressed into one sentence: the revenue base remains traditional electronics manufacturing, while incremental profit is shifting toward AI optics. This judgment is more useful than saying “Dongshan has an AI theme,” because it determines how to track the company. Traditional manufacturing depends on orders and capacity utilization. AI optics requires monitoring customer qualification, product generations, chip self-supply, yield, external sales orders, and gross margin. Investors who value Dongshan only as a traditional PCB company will underestimate Source Photonics’ margin profile; investors who value it only as an optical-module growth stock will overlook capex, finance expenses, and volatility in legacy businesses.
There is another statement in the annual report that is easy to underestimate: the company said Source Photonics has full-process in-house R&D; and mass-production capability as an optical chip IDM, with product rates covering 2.5G to 200G, focusing on high-end 100G/200G PAM4 EML series; optical module products cover 10G to 1.6T, with continued development of 3.2T and above products. The significance is not the product list, but that the company has a vertically integrated path from optical chips to optical modules. After the optical module industry enters 1.6T, the margins of pure assembly will be squeezed by customers and upstream components. Companies that control key light sources will have stronger bargaining power.
AI Optical Module Demand Revised Up Again: How Morgan Stanley’s May Report Pushed 1.6T, InP, and CPO Bottlenecks to 2028
New assets also bring new risks. Dongshan completed two acquisitions in 2025, Source Photonics and GMD. Cash outflow from investing activities increased 85.14% YoY, which the company attributed mainly to the strategic acquisitions of Source Photonics and GMD Group, as well as investments in optical modules including optical chips and AI PCB. In 2026Q1, finance expenses rose sharply YoY, while net cash outflow from investing activities continued to expand. This shows that Dongshan is using heavy capital investment to exchange for new profit pools. As long as optical modules and AI PCB deliver, financial leverage will amplify earnings; if customer orders or yield ramp fall short of expectations, finance expenses and depreciation will pressure valuation first.
III. 2026 Q1 Earnings: This Strong Growth Officially Puts Source Photonics Into the Income Statement
2026 Q1 is the starting point for Dongshan Precision’s current re-rating cycle. Revenue and profit both accelerated across the board in the first quarter, with even stronger elasticity in recurring net profit. The key financial readings are shown below. The company’s explanation was straightforward: Source Photonics and GMD Group were consolidated, the optical module business captured the AI data-center industry boom and customer demand, and the traditional businesses remained stable.
This growth has already gone beyond a simple consolidation explanation. Revenue grew 52.72%, net profit attributable to shareholders rose 143.47%, and profit elasticity was clearly higher than revenue elasticity, indicating an improving business mix. The official first-quarter report disclosed that optical module revenue doubled year on year and became a core contributor to revenue and profit. Citi’s April report listed 4Q25 optical module revenue at RMB1.4 billion, with gross margin of 36.7% and net margin of 21.9%. Taken together, these figures show that Source Photonics has moved from an acquired asset into the income-statement validation stage.
This table puts Dongshan Precision’s opportunity and risk side by side. The opportunity is that the high-margin optical module business has begun to lift net margin. The risk is that to capture this profit curve, the company must keep expanding capacity, financing, investing in R&D;, and integrating assets. After 2026, every quarter Dongshan Precision will need to use its financial statements to answer the same question: can growth in the high-margin new business cover acquisition loans, depreciation from capacity expansion, R&D; investment, and working-capital absorption?
BofA’s model is very suitable as a financial anchor. Its core point is a step-change in net margin as the optical business mix rises; revenue upgrades alone are only the surface. The specific revenue, profit, EPS, and margin assumptions are shown below. The key judgment in this model is that after Source Photonics scales, Dongshan Precision’s margin curve will shift from a traditional manufacturing framework to a high-end optical-module framework.
This forecast is aggressive, but also constraining. It requires Dongshan Precision to keep raising revenue scale from 2026 to 2028 while moving gross margin, operating margin, and net margin up step by step. If it achieves this, the stock price does not look unreasonable on 2027 numbers. If it does not, the current valuation will look like it has moved too early. BofA maintains a Neutral rating precisely because it is positive on business growth but believes the share price already partly reflects that growth.
Dongshan Precision’s financial validation points are also more complex than those of pure optical module companies. Companies such as Eoptolink and Zhongji Innolight are mainly assessed on high-end optical module delivery, gross margin, and customer mix. Dongshan Precision also needs to be assessed on whether traditional businesses become a drag, whether GMD creates profit dilution, whether AI PCB requires a longer ramp-up period, and whether financial expenses remain elevated. In other words, Dongshan Precision’s upside elasticity comes from multi-business resonance, while its downside risk also comes from multiple businesses dragging at the same time.
IV. Source Photonics: Dongshan Precision’s Real Value Lies in Optical Chip and Module Integration
Source Photonics’ strategic value cannot be explained only by “optical module revenue.” In the optical module industry, module assembly revenue is highly elastic, but customers have strong bargaining power, ASPs decline quickly, and there are many competitors. What can truly widen margins is capability in key light sources and chips. The annual report disclosed that Source Photonics has an R&D; and process system spanning indium phosphide substrates, epitaxial materials, and optical chips. 100G/200G PAM4 EML is a core product, CW laser has achieved scaled mass production, and the single-wavelength 400G EML high-speed optical chip R&D; project is progressing as planned.
This means Dongshan Precision has two layers of revenue. The first layer is pluggable optical modules, serving real demand for 400G, 800G, and 1.6T. The second layer is key light sources such as EML and CW laser, which can improve margins and customer stickiness when industry supply is tight. With only the first layer, Dongshan Precision is just a module manufacturer. When both layers are in place, Dongshan Precision has the attributes of an optical platform.
The core change in Citi’s model is that it is gradually writing Dongshan Precision not just as an acquired optical module asset, but as a beneficiary of optical chip shortages. Its spring reports repeatedly upgraded assumptions for 1.6T, 800G, and external EML shipments, indicating that the sell side is chasing order and capacity visibility. The evolution of target prices and business assumptions is shown below.
Citi Sharply Raises AI Optical Module Target Prices: A US$92 Billion Optical Interconnect Market Opens Up; Which of Dongshan Precision, Eoptolink, and TFC Communication Can Deliver the Most?
BofA’s model is more restrained, but it also acknowledges Source Photonics’ growth slope. It significantly raised optical business revenue, profit, and high-speed module shipment assumptions, while noting that laser unit prices are far lower than optical modules, so near-term profit contribution still mainly comes from modules. This reminder is important: laser determines the valuation multiple and strategic customer position, while optical modules determine the absolute profit amount.
This data set leads to a clear conclusion: in the short term, Source Photonics relies on high-end module scale-up to support profit; the value of laser lies in improving delivery certainty, increasing customer trust, enhancing the SOTP multiple, and preserving the company’s long-term entry ticket into the CPO/NPO and silicon photonics era.
Source Photonics also has three hard risks. First, customer order visibility may be high, but mass-production yield and delivery cadence will still determine profit. Second, 1.6T and subsequent 3.2T products have higher requirements for DSP, EML, silicon photonics, thermal management, and testing; any bottleneck in one link will affect gross margin. Third, overseas customers will introduce multiple suppliers for supply-chain security, so Dongshan Precision needs to defend share through chip self-supply and delivery performance.
V. US$1.2 Billion Expansion: It Raises Order Confidence, but Also Raises ROI Pressure
The US$1.2 billion expansion was the most important incremental data point in the June materials. Citi’s June 16 report showed that DSBJ announced Source Photonics would use self-raised funds to invest US$1.2 billion to expand optical chip and optical module capacity in Changzhou and other regions, addressing capacity shortages and meeting downstream AI compute demand. Citi believes the announcement can reinforce investor confidence in strong AI optical demand. BofA’s June 17 report further explained that management had previously mentioned a potential addition of about 12 million optical modules in 2027 and a doubling of laser capacity to 2 billion units in 2028-2029.
This expansion has two implications. First, it is capacity front-loading after improved customer order visibility. Optical module and optical chip equipment lead times, customer qualification, and yield ramp all take time. If 2027-2028 demand is firm, investment must begin in 2026. Second, it shifts the market from “watch orders” to “watch ROI.” US$1.2 billion is not a small amount. The larger the expansion, the higher the subsequent requirements for cash flow, depreciation, yield, and order conversion.
BofA’s reaction to this expansion was highly typical: it raised earnings and its target price, but maintained a Neutral rating. In the SOTP breakdown, the value uplift mainly came from optical modules, while valuations for lasers and legacy businesses changed little. This adjustment shows that BofA is willing to assign a higher multiple to optical modules, but did not upgrade the rating to Buy because it believes the current price is already reasonable.
The most useful aspect of the expansion news for investors is that it makes follow-up tracking indicators more concrete. The analysis of DSBJ should not stop at “the company invested US$1.2 billion.” Four questions matter: when will the new capacity reach full production, are customer orders sufficient to fill the capacity, will external optical chip sales truly contribute profit, and will capex crush free cash flow? BofA’s model shows 2026E free cash flow per share at RMB-0.84, recovering to RMB4.31 in 2027E and rising to RMB13.04 in 2028E. If this path materializes, expansion pressure can be absorbed by revenue. If free cash flow does not turn positive in 2027, the market will reassess this expansion.
VI. AI PCB: DSBJ’s Second Growth Leg, Harder to Validate Than Optical Modules
DSBJ’s AI PCB thesis cannot be written simply as “PCB demand is strong.” The real barriers in AI server PCBs are customer qualification, material grade, layer count, HDI process, thermal management, yield, and delivery stability. An expansion announcement itself does not equal effective capacity; this has already been repeatedly validated across the AI PCB series. DSBJ’s advantage is that Multek has a high-end PCB technology foundation and can create customer synergies with Source Photonics’ optical modules. Its weakness is that AI server PCB expansion cycles are long, and competitors are also strong.
AI PCB Phase Six: Expansion Announcements Do Not Equal Effective Capacity — A Full Breakdown of 2026 Equipment Orders at Han’s CNC, Victory Giant Technology, and Shennan Circuits
The annual report disclosed that Multek has manufacturing capabilities for ultra-high-layer-count PCBs of 78 layers and above, as well as 7-stage thick-board HDI PCBs. It focuses on the AI server track and can deliver high-quality PCB products at scale. The company’s high-end PCBs also use M8/9-grade low-loss materials, meeting high-speed transmission requirements for GPUs, AI accelerator cards, AI servers, and data-center switches. Goldman Sachs’ May meeting minutes also noted that management emphasized the company’s end-to-end capabilities in AI PCBs and high-speed optical modules, and that it is expanding PCB product capacity and optimizing its product mix to meet demand from data centers and AI servers.
Citi’s April call minutes provided a more positive management message: the company has communicated with almost all AI cloud customers and achieved breakthroughs with most of them; management is confident in its AI PCB capabilities, especially products such as embedded capacitors; AI PCB could double current RPCB revenue and profit over the next 2-3 years. This information is valuable, but it remains a management statement. Actual execution still needs to be assessed through revenue and gross margin.
BofA’s view is clearly more cautious. Its June 9 report noted that future contributions from AI server PCBs will take time because the expansion cycle may be as long as two years, while technical specifications are upgrading rapidly, with high-layer boards evolving from above 20 layers toward 40-100 layers and entry barriers rising. This judgment is important: AI PCB is a long-term option for DSBJ and should not be capitalized immediately in the same way as Source Photonics’ optical modules.
The right way to value DSBJ’s AI PCB business is to treat it as a second growth leg, not the main earnings driver in 2026. The main earnings drivers in 2026 remain optical modules and optical chips. If AI PCB begins contributing high-end revenue in 2027, it will provide thicker valuation support for DSBJ. If progress is slow, it will not fully invalidate the optical thesis, but it will weaken the “optical modules + PCB platform” story.
Victory Giant Technology Deep Dive: AI PCB Enters the Effective Capacity Era; How Victory Giant Is Evolving from a Board Maker into a Server Delivery Asset
The AI PCB line should be tracked through three key numbers. First, the pace at which construction in progress turns into fixed assets and revenue, to determine whether expansion has entered production. Second, whether high-end PCB gross margin improves, to determine whether the company is truly capturing AI server value. Third, customer qualification and order information, especially whether overseas cloud vendors, GPU/ASIC servers, switches, and optical module customers are being introduced together. Until these three numbers are available, AI PCB should remain discounted in the SOTP.
VII. Sell-Side Divergence: Citi Buys Orders, BofA Buys Discipline, HSBC and UBS Record Early-Stage Transformation Noise
The value of this batch of research reports is that they connect DSBJ’s transition from “early-stage legacy-asset transformation” to the “optical-platform realization phase.” HSBC’s July and October 2025 reports focused mainly on AI PCB capacity expansion, the Source Photonics acquisition, and a recovery in growth in 2026. UBS’s August 2025 first take focused more on 2Q25 results missing expectations. In November 2025, BofA raised its target price from RMB28.5 to RMB80 but maintained Neutral, arguing that Source Photonics’ contribution had been fairly well reflected by the market, while the legacy businesses still lacked clearer rerating signals. After March 2026, Citi began putting optical-chip tightness, 800G/1.6T, EML/CW laser, and AI PCB together into its SOTP, and repeatedly raised its target price. By June 2026, BofA also raised earnings and target price sharply, but continued to insist on valuation discipline.
Behind these divergences are two worldviews. Citi’s worldview is that the AI optical supply bottleneck remains tight; demand from 1.6T, EML, CW laser, and CPO/NPO will continue to be revised up; DSBJ has opportunities at both the chip and module ends; therefore it deserves a higher SOTP. BofA’s worldview is that DSBJ has indeed entered a high-growth phase, but the share price already reflects a lot; the company still has 40-50% exposure to consumer electronics and autos; AI PCB contribution will take time; and absolute laser revenue is lower than module revenue, so Neutral is more appropriate at current levels.
Both worldviews are reasonable. DSBJ is not a company that can only be viewed as a one-way long or one-way short. The bullish core is that Source Photonics’ optical-chip capabilities may turn DSBJ from an ordinary manufacturer into an AI optical bottleneck asset. The cautious core is that the market has already capitalized a large portion of 2027-2028 profit in advance, and even modest business volatility could compress multiples. A real research conclusion should include both points at the same time.
Valuation divergence table: business upgrades and price discipline can both be true
VIII. Valuation Framework: DSBJ Is Suited to SOTP, but Every Segment Needs a Discount
DSBJ can no longer be valued on a single P/E. A single P/E mixes optical modules, optical chips, AI PCB, and legacy businesses together, which either undervalues Source Photonics or overvalues legacy assets. The more reasonable approach is SOTP: legacy businesses receive a multiple based on manufacturing and Apple-chain base value; optical modules receive a multiple based on high-end module profit; optical chips receive a higher multiple as bottleneck assets; AI PCB receives a multiple based on long-term option value and high-end board profit; then discounts are applied for capital structure and execution risk.
Both Citi and BofA use SOTP, but with different segmentation. Citi prices legacy businesses, optical modules, optical chips, and AI PCB separately, while BofA prices optical modules, optical laser, and legacy businesses separately. The difference shows that current valuation is most sensitive to optical-module profit and the optical-chip multiple.
This round of DSBJ target-price upgrades appears on the surface to be brokers raising multiples, but in reality it is a continuous change in the earnings anchor. The earliest increment was Source Photonics consolidation, which in the model looked more like “a traditional manufacturing company plus a high-growth acquired asset.” Citi then shifted the focus to optical-chip shortages, overseas cloud-customer orders, and upward revisions to 800G, 1.6T, and laser demand. By BofA’s June model, the step-change in optical-module revenue and net margin had already been substantially written into long-term assumptions.
This table shows that DSBJ’s valuation has shifted from “buying an acquired asset” to “buying optical-platform realization.” After the valuation anchor shifts, the share price will require more stringent data. In the acquired-asset phase, as long as Source Photonics could be consolidated and make money, the market was willing to rerate. In the expansion-realization phase, the company must prove simultaneous improvement in order strength, capacity yield, cash collection, and earnings revisions. The biggest risk at this stage is high revenue growth without matching cash flow, because heavy-asset expansion can widen the gap between accounting profit and free cash flow.
The verification method for capex also needs to be specific. The US$1.2bn expansion will first enter construction in progress, prepayments, equipment, R&D;, and labor, then gradually convert into fixed assets, depreciation, and capacity. The earliest signals in financial statements include construction in progress, cash flow, finance costs, and R&D; expenses, while revenue usually appears with a lag. Construction in progress, finance costs, and R&D; expenses already rose together in the first quarter, indicating that expansion is underway. But revenue and gross margin must follow; otherwise, the market will interpret expansion as cost pressure.
This is also why DSBJ cannot be assessed only by order metrics. In the AI optical-module supply chain, customers give suppliers direction in advance, but final profit comes from mass-production share, pricing, yield, and delivery. If DSBJ wins more 800G and 1.6T orders but needs lower ASP to exchange for share, or if yield ramping causes costs to exceed the model, profit elasticity will be compressed. Conversely, if order volume, gross margin, operating cash flow, and earnings upgrades appear at the same time, the market will continue to treat Source Photonics as a platform asset and raise its value from acquisition contribution to long-term supply-chain position.
A more realistic valuation cadence is to first watch 2026 profit realization, then look for resonance between 2027 orders and cash flow. In 2026, as long as optical-module revenue and gross margin remain stable, the market will recognize that Source Photonics has completed the first round of validation. In 2027, if 800G orders continue to be revised up, 1.6T enters volume delivery, external laser sales generate real revenue, and free cash flow turns positive, DSBJ’s valuation may have the conditions to continue shifting from “high-growth manufacturer” to “AI interconnect platform.” Conversely, if 2026 profit is strong but cash flow deteriorates, or 2027 orders are strong but gross margin declines, valuation will first pause and wait for data.
The easiest mistake here is to give full valuation to all options. DSBJ does have many good cards, but each card realizes on a different timeline. Optical modules are the fastest, already entering the income statement in 2026. Optical chips come next, with external sales and 200G EML yield in 2027 as the key. AI PCB is slower, with the focus before 2027 mainly on customer certification and capacity. Legacy businesses should only provide a base, and should not enjoy optical-module multiples.
Eoptolink Deep Dive: The Next Stage of AI Optical Modules — 800G, 1.6T, and NPO Rerating
Compared with Eoptolink, DSBJ’s advantage is more options, while its drawback is lower purity. Eoptolink is more like a high-end optical-module profit-realization machine, with more direct gross-margin and customer-structure exposure. DSBJ is more like a composite platform, where optical modules, optical chips, AI PCB, and legacy businesses jointly affect valuation. Compared with TFC Communication, DSBJ has more direct optical-module revenue, while TFC’s optical-engine and CPO/NPO options are purer. Compared with Accelink Technologies, DSBJ has more international overseas customers and Source Photonics assets, while Accelink has stronger domestic optical-chip and central-SOE platform attributes. DSBJ is better placed in the “composite elasticity” bucket, and should not be treated as the purest module stock.
Peer positioning: buy composite elasticity in DSBJ, profit realization in Eoptolink, and optical-engine optionality in TFC Communication
TFC Communication Deep Dive: From Optical-Component Supplier to AI Optical-Engine Platform — 1.6T, NPO, and CPO Rerate Upstream Value
9. Three Scenarios: What This Company Fears Most Is Growth Quality Falling Short of Valuation
DSBJ’s scenario analysis should revolve around growth quality, not just revenue growth. The best-case scenario is strong optical-module orders, rapid 1.6T ramp-up, smooth EML and CW laser capacity expansion, successful AI PCB qualification, stable legacy businesses, and capex quickly converting into profit and cash flow. The neutral scenario is continued optical-module growth but declining ASPs, lasers mainly used for internal supply, slow AI PCB contribution, stable legacy businesses, and valuation being digested by 2027 earnings. The worst-case scenario is that optical-module and optical-chip expansion creates depreciation and finance costs, but customer share, yield, or pricing comes in below expectations, while AI PCB also fails to contribute quickly.
The biggest risk for DSBJ is not a lack of revenue growth. Given that demand for AI optical modules and AI PCB is still likely to grow, it should not be difficult for the company to keep revenue rising. The real risk is that growth quality falls short of valuation. For example, optical-module revenue may grow quickly, but ASP declines, customer bargaining power, externally sourced chip costs, depreciation, and yield losses could compress gross margin. Or optical-chip capacity may be built out, but there may not be enough external customers, leaving more of the capacity as lower-margin internal supply. Or AI PCB investment may be large, but customer qualification may be slow, with depreciation rising before revenue does.
This is also the core reason BofA maintains a Neutral rating. BofA acknowledges DSBJ’s strong growth, while also arguing that the current share price has already capitalized a meaningful portion of that growth. In BofA’s June 17 model, DSBJ’s 2028E EPS reaches RMB20.73. If the market believes this number, the current valuation is not expensive; if 2027-2028 earnings need to be revised down, valuation pressure will increase quickly. For this type of stock, tracking the direction of earnings revisions is more important than watching intraday price action.
10. Tracking List for the Next Four Quarters: Use These Numbers to Judge Whether the Re-Rating Continues
DSBJ’s most important task over the next four quarters is to consistently deliver orders, capacity, gross margin, and cash flow. The tracking list must be as specific as possible; otherwise, investors can easily be led around by each capacity-expansion announcement.
In this list, the most important items are gross margin and free cash flow. Orders can be discussed in advance, capacity can be invested in advance, and target prices can be raised in advance, but gross margin and cash flow are the hardest to mask. If optical modules and optical chips are truly bottleneck assets, gross margin should remain resilient. If capacity expansion can truly bring in high-quality orders, free cash flow should improve meaningfully in 2027. Conversely, if revenue rises but gross margin falls, accounts receivable increases, and free cash flow deteriorates, that would indicate growth quality is below market expectations.
Investors also need to track the combined movement of accounts receivable, inventory, and prepayments. During capacity-expansion periods, high-growth companies usually procure materials in advance, increase equipment prepayments, and may see collection cycles lengthen because of major-customer delivery schedules. A healthy state is one in which revenue, gross margin, operating cash flow, and receivables turnover improve together. A stressed state is one in which the income statement looks strong, but receivables and inventory consumption expand significantly. DSBJ is now in a phase where order upgrades and front-loaded capacity expansion are happening in parallel. These working-capital indicators will reveal growth quality earlier than single-quarter revenue.
11. Falsification Checklist: Order Quality and Cash Collection Determine the Durability of the Re-Rating
The biggest falsification point for DSBJ’s current re-rating is order quality. Demand in the AI optical-module industry is currently very strong, but strong demand will attract more suppliers and encourage cloud vendors to split orders among multiple suppliers. If DSBJ only secures framework demand, without stable share and sustained shipments, the income statement will materialize later than the market expects. Truly high-quality orders need to satisfy several conditions at the same time: customers recognize the product roadmap, delivery cadence is sustainable, pricing is not based on large concessions to gain share, and mass production does not continuously erode gross margin. Each subsequent upward revision to orders by the company or the sell side needs to be verified against gross margin and accounts receivable.
The second falsification point is yield and delivery. As high-speed optical modules move from 800G to 1.6T, requirements for EML, DSP, thermal management, testing, and packaging consistency will all rise. DSBJ has integrated optical-chip and module capabilities. This is an advantage, but it also means yield problems in any link can feed through to delivery and gross margin. The market is currently willing to assign Source Photonics a higher valuation because it is seen as a supply-chain bottleneck asset. Bottleneck assets need to demonstrate stable supply capability. If there are only capacity announcements without stable delivery, valuation multiples will fall.
The third falsification point is external laser sales. Internal optical-chip supply can improve certainty of module delivery, while external sales determine whether the market treats lasers as an independent profit pool. Both BofA and Citi acknowledge the strategic importance of lasers to customers, but the near-term profit driver remains high-end modules. If lasers mainly remain for internal supply, DSBJ can still earn module profits, but the optical-chip high multiple will be discounted. If external customers start to increase, the market will be more willing to view the business within an upstream bottleneck-asset framework. This difference will directly affect the multiple in the SOTP.
The fourth falsification point is AI PCB. Multek’s capabilities in high-layer-count boards, thick-board HDI, and low-loss materials give DSBJ a second growth leg, but the qualification cycle for AI PCB is naturally longer. This business must go through material qualification, process ramp-up, customer audits, yield stabilization, and batch delivery. If any link slows, profit contribution will be pushed out. DSBJ’s advantage is that it may share some customer entry points with Source Photonics. The risk is that pure-play PCB companies are also expanding capacity rapidly, and customers will continue to compare suppliers based on delivery capability and cost. AI PCB should initially be treated as an option in the model, with its weight raised only after revenue and gross-margin inflection points appear.
The fifth falsification point is cash flow. High-growth manufacturing companies are most prone to periods where the income statement looks strong but cash flow cannot keep up, especially when acquisitions, capacity expansion, and customer onboarding occur simultaneously. DSBJ has already entered a period of heavy capital investment. Finance costs, equipment investment, R&D; investment, and working capital will all come before revenue release. As long as operating cash flow is stable, accounts receivable is controllable, and inventory turnover does not deteriorate significantly, the market will accept near-term investment pressure. If profit growth is accompanied by persistent cash-flow deterioration, investors will again view DSBJ as a heavy-asset manufacturing platform rather than an optical platform that can easily enjoy high-growth multiples.
The final falsification point is the base provided by legacy businesses. FPC, traditional PCB, precision components, and GMD do not determine the valuation ceiling, but they do determine whether the company can move smoothly through the capacity-expansion period. If demand from consumer electronics or automotive customers weakens, profit and cash flow from legacy businesses will reduce the company’s ability to absorb expansion pressure. The benefit of a composite platform like DSBJ is multiple profit pools; the drawback is more noise. Investors should not only look at the brightest optical-module business, but also confirm that legacy businesses are not continuously dragging down consolidated margins.
The purpose of this falsification checklist is simple: the market already believes DSBJ has AI assets; the next question is whether those AI assets can become high-quality profit. Orders, yield, external sales, AI PCB, cash flow, and the legacy-business base can each change the direction of earnings revisions. As long as most indicators improve in the same direction, DSBJ’s re-rating can continue. If indicators begin to diverge, the market will first lower the multiple and then wait for the next earnings report for confirmation.
Another easily overlooked falsification point is the granularity of disclosure. DSBJ’s business mix is now much more complex than in the past, and investors need a clearer understanding of the revenue, gross margin, capacity utilization, and order cadence of optical modules, optical chips, AI PCB, and legacy businesses. The clearer the disclosure, the easier it is for the market to break growth into verifiable models. The more general the disclosure, the easier it is for the market to discount all positive news. Source Photonics and Multek in particular are no longer suitable for explanations based only on phrases such as “good growth” and “strong demand.” Going forward, it would be better to provide more specific direction on customers, product generations, capacity, and margins.
Supply-chain position also needs to be verified dynamically. DSBJ’s advantage comes from vertical integration, but vertical integration only amplifies value when key links are in short supply. If future supply improves for EML, CW lasers, DSP, silicon photonics, or other key components, customers may push for lower prices again, and supply-chain profit may flow back from bottleneck links to downstream customers. DSBJ needs to defend its position through continuous iteration and stable delivery, not rely only on the current shortage window. A truly strong platform company can win orders when supply-demand conditions are tight and retain customers through quality, cost, and responsiveness when supply-demand conditions ease.
The competitive landscape also needs to be viewed dynamically. In AI optical modules, Eoptolink, Innolight, Coherent, Lumentum, and others are all competing for high-speed generation opportunities. In AI PCB, Victory Giant Technology, WUS Printed Circuit, Shennan Circuits, Shengyi Electronics, and others are also expanding capacity. In optical devices and optical chips, there are also players with different positioning, such as TFC Communication and Accelink Technologies. DSBJ’s advantage is its combined capability; its disadvantage is that none of its business lines competes in isolation. If the market gives it a platform valuation, it is effectively betting that the company can win multiple local battles at the same time. This is a high bar and must be continuously proven through financial results and orders.
On valuation, investors also need to guard against linear extrapolation. DSBJ’s re-rating this year has mainly come from a shift in asset attributes. Once that asset-attribute shift is complete, the market will move into an earnings-revision trade. Earnings-revision trades are shorter, faster, and more selective: target-price increases can improve sentiment, but the next increase requires new orders, new yield evidence, or new cash-flow improvement. If sell-side models only hold steady rather than move higher, the share price will enter a digestion period. If earnings continue to be revised up, the platform story can continue to expand. For investors, the key is to judge the direction of the next round of earnings revisions; capacity-expansion announcements are only the starting point.
Putting these falsification points together, DSBJ’s best path is clear: Source Photonics continues to deliver high-speed modules, optical-chip capabilities help the company stabilize its customer position, AI PCB begins to contribute higher-quality revenue after customer qualification, legacy businesses maintain cash flow, and capex gradually converts into profit. This path would make the market willing to continue valuing DSBJ within a platform-company framework. The weaker path is also clear: the order narrative looks strong, but gross margin, cash flow, and delivery cadence fail to keep up, leading the market to pull valuation back into a heavy-asset manufacturing framework.
Therefore, every subsequent rise in DSBJ’s share price needs new evidence to take over. As long as the evidence chain remains intact, valuation can shift toward forward earnings. Once the evidence chain breaks, the share price will first wait for financial results to confirm. For this type of stock, investors cannot look only at the strength of the story; they need to look at how quickly the story enters the income statement and cash flow.
Put more simply, DSBJ now needs continuous delivery to digest expectations. As long as orders, gross margin, cash flow, and customer qualification improve in the same direction, the market will continue to give it time. If any one of these items clearly falls behind, investors will reassess the pace of capacity expansion and valuation multiples.
12. Conclusion: Dongshan Precision Has Become an AI Optical Platform, but Pricing Must Wait for Profits to Keep Catching Up
Dongshan Precision’s rerating has already moved past the question of whether it has an AI story. Its 2026 Q1 results showed that Source Photonics can contribute revenue and profit. The US$1.2 billion capacity expansion showed that management has greater confidence in medium- to long-term demand. Citi’s and BofA’s successive upgrades showed that sell-side models have already made optical modules, optical chips, and AI PCBs core inputs. The key question now is whether Dongshan can use 2026-2028 profit and cash flow to substantiate the platform valuation that the market has already assigned.
The most attractive part of the company is that, among A-share names, it is rare in having all three AI interconnect chains: PCB, optical modules, and optical chips. Victory Giant, WUS Printed Circuit, Shennan Circuits, and Shengyi Technology are strongest in PCB/CCL. Eoptolink and Zhongji Innolight are strongest in high-end optical modules. TFC is strongest in optical engines and upstream components. Dongshan’s distinctive feature is its composite profile: it may not be the purest company in every segment, but it has put high-speed optical modules, EML/CW lasers, and AI PCBs inside the same group. If customers recognize this composite capability, it can support a platform valuation.
Composite capability also means a higher validation threshold. Dongshan needs to prove that multiple segments can work together. Source Photonics needs to prove that high-end modules and optical chips can continue to scale. Multek needs to prove that AI PCBs can become effective capacity. GMD and legacy businesses need to prove they will not drag on cash flow. Capex needs to prove that it can convert into orders and profit. As long as this validation keeps progressing, Dongshan remains one of the most worth-tracking assets at the intersection of A-share AI optics and AI PCBs.
When researching Dongshan, the key is to grade management as a “cross-asset integrator.” Source Photonics provides the optical product line, Multek provides high-end board capability, GMD provides European automotive structural-parts assets, and the legacy FPC and precision manufacturing businesses provide the customer, factory, and cash-flow base. Looking at any one business alone, it is hard to explain why the market is willing to assign a higher platform valuation. Only when these businesses are placed inside the same AI interconnect and global delivery system does Dongshan’s asset rerating logic emerge. The issue is also here: composite platform value is high, but management complexity is also high.
What management most needs to prove next is whether asset synergy can lower customer qualification costs, reduce supply-chain risk, and improve delivery certainty. For example, if overseas cloud customers recognize both Source Photonics optical modules and Multek high-end PCBs, Dongshan’s customer relationships will deepen. If optical-chip self-supply can make module delivery more stable, the company’s position in customer supply chains will become more secure. If legacy-business cash flow can support the expansion cycle, capex pressure will not erode valuation too early. Once these synergies materialize, platform value will be more durable than single-point profit.
Investors also need to accept a reality: Dongshan’s execution over the next several quarters is unlikely to be linear. New-line commissioning, customer validation, yield ramp, overseas delivery, and working-capital recovery are unlikely to improve in sync every quarter. What truly matters is direction and quality, especially whether gross margin holds, whether orders move from intention to mass production, and whether cash flow gradually catches up with profit. If these metrics improve consecutively, short-term expense volatility can be understood. If there is only expansion and order rhetoric while profit quality fails to keep up, the market will quickly lose patience with the platform story.
Scoring Dongshan also requires looking at organizational capability. Optical modules, optical chips, PCBs, precision manufacturing, and automotive structural parts differ in process language, customer cadence, and balance-sheet cadence. Source Photonics faces overseas cloud vendors and high-speed optical interconnect upgrades. Multek faces AI server and switch PCB specification upgrades. Traditional businesses face cost management for consumer-electronics and automotive customers. Putting these businesses into the same listed company has the advantage that customer and manufacturing resources can reinforce each other, but the challenge is that management must keep prioritizing across R&D;, capacity expansion, quality, cash flow, and M&A; integration. If the company can continue to show a clear input-output path in quarterly earnings, the market will be more willing to treat Dongshan as a platform company. If disclosure stays only at the level of orders and expansion, investors will demand a higher risk discount.
This also means Dongshan’s trading cadence differs from pure optical-module targets. Pure optical-module names are more directly priced off orders, gross margin, and product-generation changes. Dongshan also requires attention to the legacy-business base, debt cost, construction in progress, M&A; integration, and AI PCB execution. Its upside may be richer, but the validation chain is longer. The right research method for Dongshan is to put optical revenue, optical-chip progress, AI PCB certification, capex, and cash flow into one table every quarter; focus less on single pieces of news and more on whether the data are improving in the same direction.
For this type of company, the most important thing to track is whether a one-quarter surprise can become consecutive earnings revisions. That matters more than reported profit in any single quarter. Dongshan has already secured its ticket for repricing. Next, it must use more stable delivery, clearer customer recognition, and more solid cash collection to convert that ticket into a real platform valuation.
A more direct judgment: Dongshan Precision has entered the high-expectation delivery phase, and the low-base rerating phase is over. Low-base rerating depends on changes in asset labels; high-expectation delivery depends on whether the company can deliver numbers every quarter. The US$1.2 billion expansion raises the long-term revenue ceiling, but it also raises short-term cash-flow and depreciation pressure. As long as 800G orders, 1.6T introduction, external laser sales, and AI PCB certification continue moving upward, valuation can be absorbed by 2027-2028 profit. If any one segment sees a clear delay, the market will first compress the high multiples assigned to optical modules and optical chips in the SOTP.
The conclusion is clear: the business direction has been validated, but the valuation outcome is still in progress. Track four hard numbers: 2027 800G orders, 1.6T shipments, external laser sales, and free cash flow. If Dongshan can deliver them consistently, it will truly transform from a consumer-electronics manufacturing company into an AI optical platform. If it cannot, the US$1.2 billion expansion will shift from an upside option into depreciation and interest pressure.