
Deep Dive on AI’s Employment Shock: Behind the Risk of 15 Million Jobs Being Displaced, Why the Market Is Still Only Buying Compute
目录
TL;DR
I. What This Goldman Report Is Really Asking Is Not “Will AI Cause Layoffs?”
II. Three Worldviews: Substitution, Friction, and Reabsorption
III. Aggregate Data Has Not Broken, but Local Cracks Have Appeared
IV. The Real Unit of Analysis Is Not the “Occupation,” but the “Task”
V. Why New Graduates Feel the Chill First
VI. Companies Have Started Using AI to Redesign Organizations, but the Income Statement Still Has No Unified Answer
VII. The Agent Cost Curve Defines the Boundary of Automation
VIII. Capital Markets Are Temporarily Rewarding Hardware Because Hardware Evidence Is Being Realized First
IX. AI Will Change Labor’s Share and the Distribution of Capital Returns
10. History Creates New Jobs, but History Is Not an Automatic Guarantee
11. Investment Framework: Do Not Just Buy “Labor Savings”; Buy Verifiable Profit Retention
12. The Biggest Misjudgment Risk: Treating “Capability Progress” Directly as “Job Disappearance”
XIII. Indicators to Watch Over the Next Four Quarters
XIV. Three Scenarios: Moderate Reallocation, White-Collar Compression, and Productivity Diffusion
XV. Jobs Will Not Disappear Evenly; They Will Be Repriced
16. Five Gates Before AI Reaches the Corporate Income Statement
17. Second-Order Impact: AI Layoffs Are Not the Endpoint; Demand Reallocation Is
18. How This Affects Consumption, Education, and Urban Structure
XIX. Policy and Corporate Governance Will Become Variables, Not Background Noise
XX. Placing This Report Back Into the Broader AI Trade Framework
XXI. Conclusion: AI Will Not Immediately Destroy All Jobs, but It Will Rewrite the Price List for White-Collar Roles
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The key point in Goldman Sachs’ Top of Mind is not to declare a “job apocalypse,” but to separate AI substitution, task augmentation, corporate earnings, and market pricing. What investors should really watch is not an instant wave of unemployment, but how white-collar jobs, entry-level roles, wage distribution, and profit attribution are reordered over the next decade, and whether the productivity dividend is captured by workers, companies, or platforms.
TL;DR
A job apocalypse is not the base case. None of the three Goldman interviewees supports a near-term mass-unemployment narrative; what is more likely is job substitution, re-employment, and occupational reshuffling over a ten-year horizon.
The shock starts with routine cognitive white-collar work. Customer service, back office, call centers, claims processing, billing, data entry, and some junior coding are most vulnerable to substitution; roles requiring high judgment and collaboration are more likely to be augmented.
Aggregate data has not collapsed. There is still no statistically significant relationship between AI adoption and unemployment or job growth; however, hiring, wages, and entry-level roles in high-substitution-risk industries are already showing pressure.
New graduates are the near-term weak point. The issue is not that degrees are useless, but that many entry-level training tasks are being automated; first jobs, experience accumulation, and starting wages are more vulnerable.
Corporate income statements still lack evidence. Many companies talk about AI efficiency, but few have actually quantified the benefits and linked them to earnings; as a result, the market continues to reward compute, chips, and data centers first.
Agent cost is the next gate. Coding already has a clear cost advantage, while customer service and data entry still depend on reliability, data access, process redesign, and the cost of errors.
The investment conclusion has three tracks. First, watch whether AI enters the income statement; second, whether wage and employment shocks broaden; third, whether retraining and policy can reduce friction. These will determine when the trade broadens from infrastructure to productivity assets. In the absence of evidence, the AI trade remains in the buildout phase; only with sustained evidence improvement does the efficiency-realization phase open.
I. What This Goldman Report Is Really Asking Is Not “Will AI Cause Layoffs?”
Reading this Goldman Sachs Top of Mind issue simply as “Will AI make people unemployed?” narrows the question too much. The more accurate questions are: when does AI move from tool to labor substitute, when does it move from cost item to profit item, and when does it move from a capex story to a whole-market productivity story?
These three questions cannot be reversed. First comes task-level substitution and augmentation, then cost reduction or revenue uplift in corporate income statements, and only then does the capital market shift from “buying compute supply” to “buying productivity beneficiaries.” If investors only look at layoff headlines, they can easily mistake local pressure for aggregate collapse; if they only look at rising mega-cap tech stocks, they may underestimate the structural change already underway in white-collar employment.
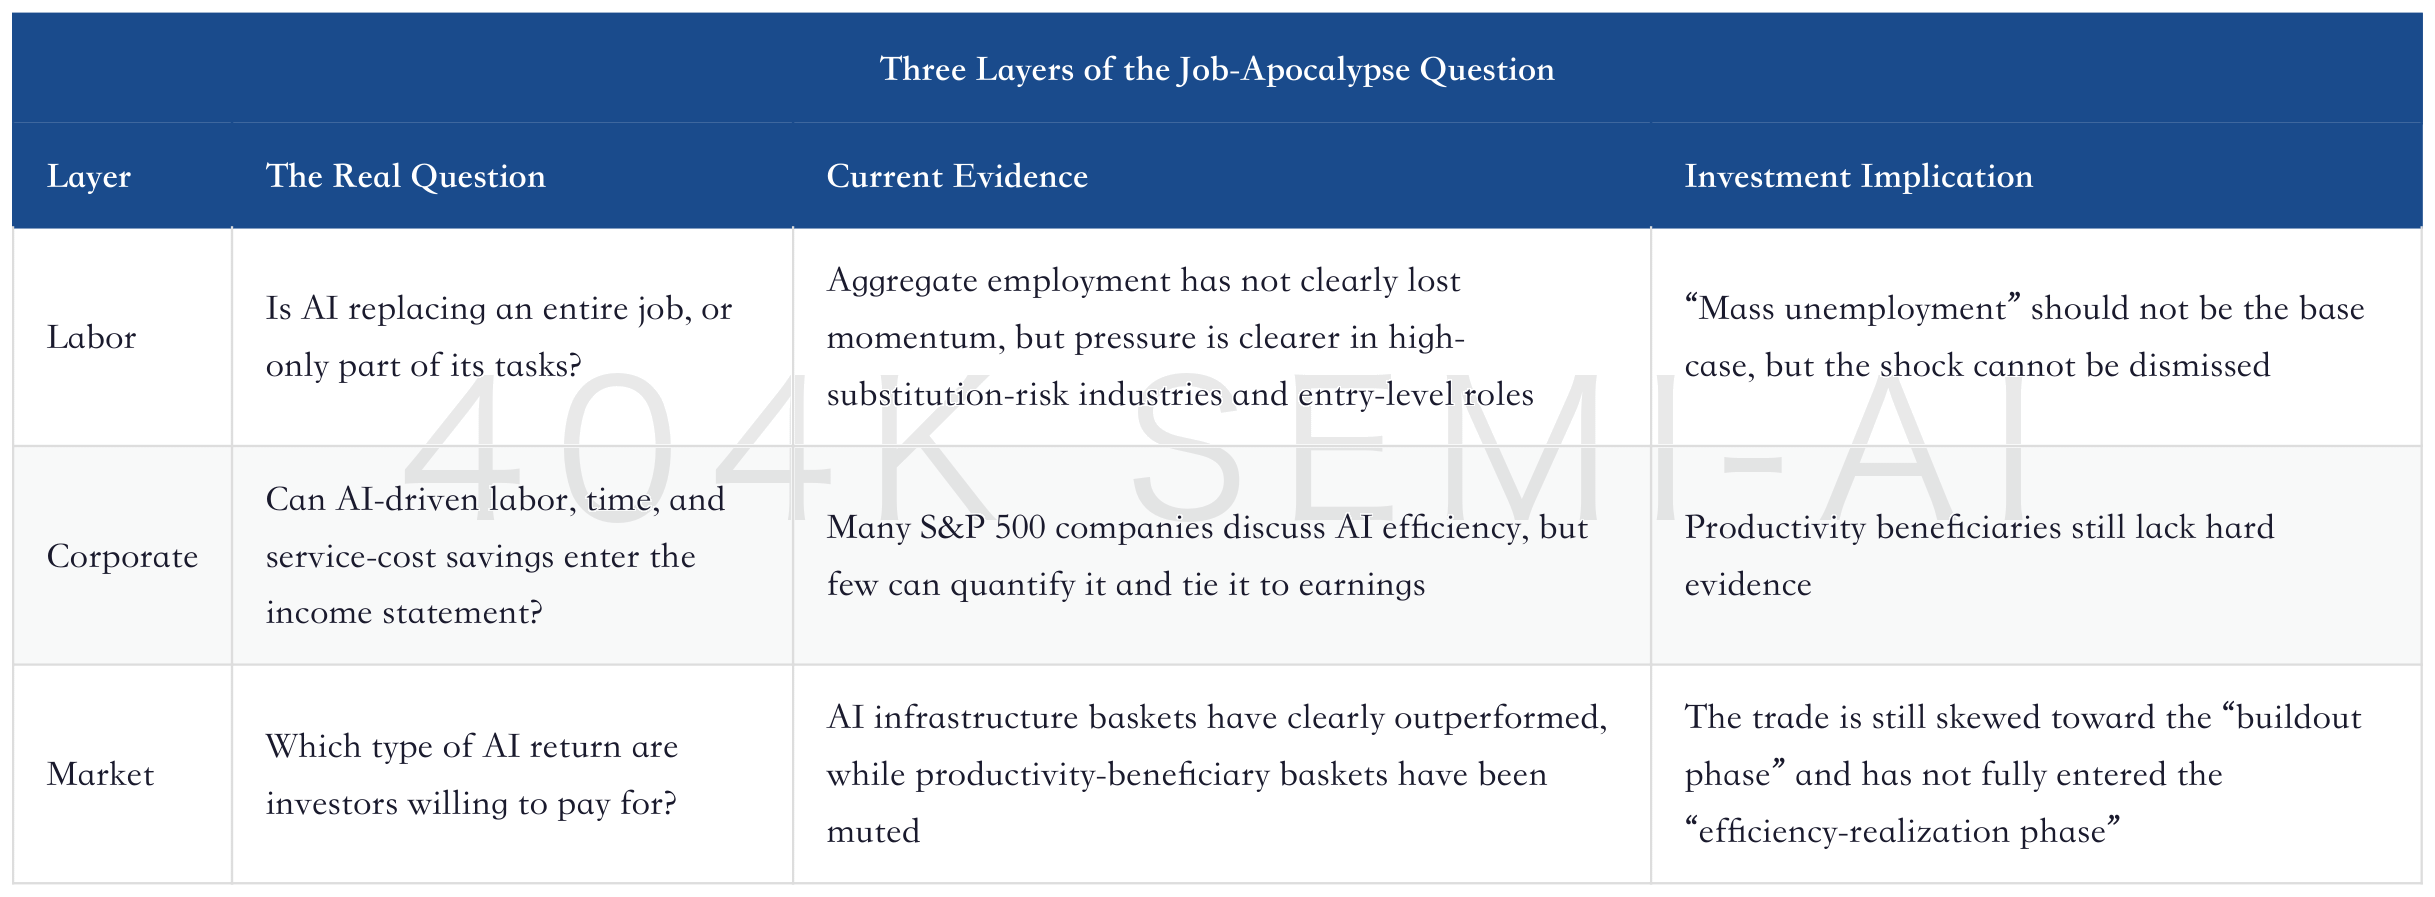
The value of this Goldman issue is that it does not flatten the question into a single conclusion. Acemoglu is more concerned that AI is moving toward substitution rather than complementarity. Thompson emphasizes the long engineering distance between capability and deployment. Briggs offers a clearer quantitative framework: over a ten-year transition period, AI could lead to job displacement for more than 9% of the labor force, or roughly 15 million people, but if new job creation and re-employment keep pace, the peak unemployment-rate impact could be less than 1 percentage point.
This is neither “nothing to worry about” nor “the end.” It is more like a prolonged reshuffling of jobs: job titles may not disappear immediately, but task composition, wage curves, entry-level roles, corporate hierarchy, and profit attribution will change first.
II. Three Worldviews: Substitution, Friction, and Reabsorption
Goldman frames the discussion around three worldviews. All acknowledge that AI will change work, but they differ on speed, scope, and long-term net impact.
Acemoglu focuses on substitution risk. He argues that current models are more likely to replace humans in some cognitive tasks than to systematically enhance human capabilities. In the near term, this creates a modest net drag on employment; over the long term, if capital and R&D; continue to flow toward “using fewer people” rather than “making people more useful,” job losses could be larger. What concerns him most is not technological progress itself, but technological progress being steered toward labor substitution.
Thompson focuses on deployment friction. He does not deny that AI capabilities are improving rapidly, but he notes that there are still several gates between “the model can do it” and “the enterprise can safely automate it”: the model must access the right data, be sufficiently reliable, handle privacy and permissions, operate in workflows where error costs are manageable, and be cheaper than the human alternative. Many jobs are not single tasks but combinations of dozens of tasks. Replacing part of them with AI does not mean the entire job immediately disappears.
Briggs focuses on reabsorption. He acknowledges that AI could cause significant job substitution, even putting the figure above 9% of the labor force, or roughly 15 million people, but still views it as a decade-long transition. The U.S. labor market already creates and destroys 25 million to 35 million jobs a year. If AI also creates new occupations, new divisions of labor, and new demand, the unemployment shock may be temporary.
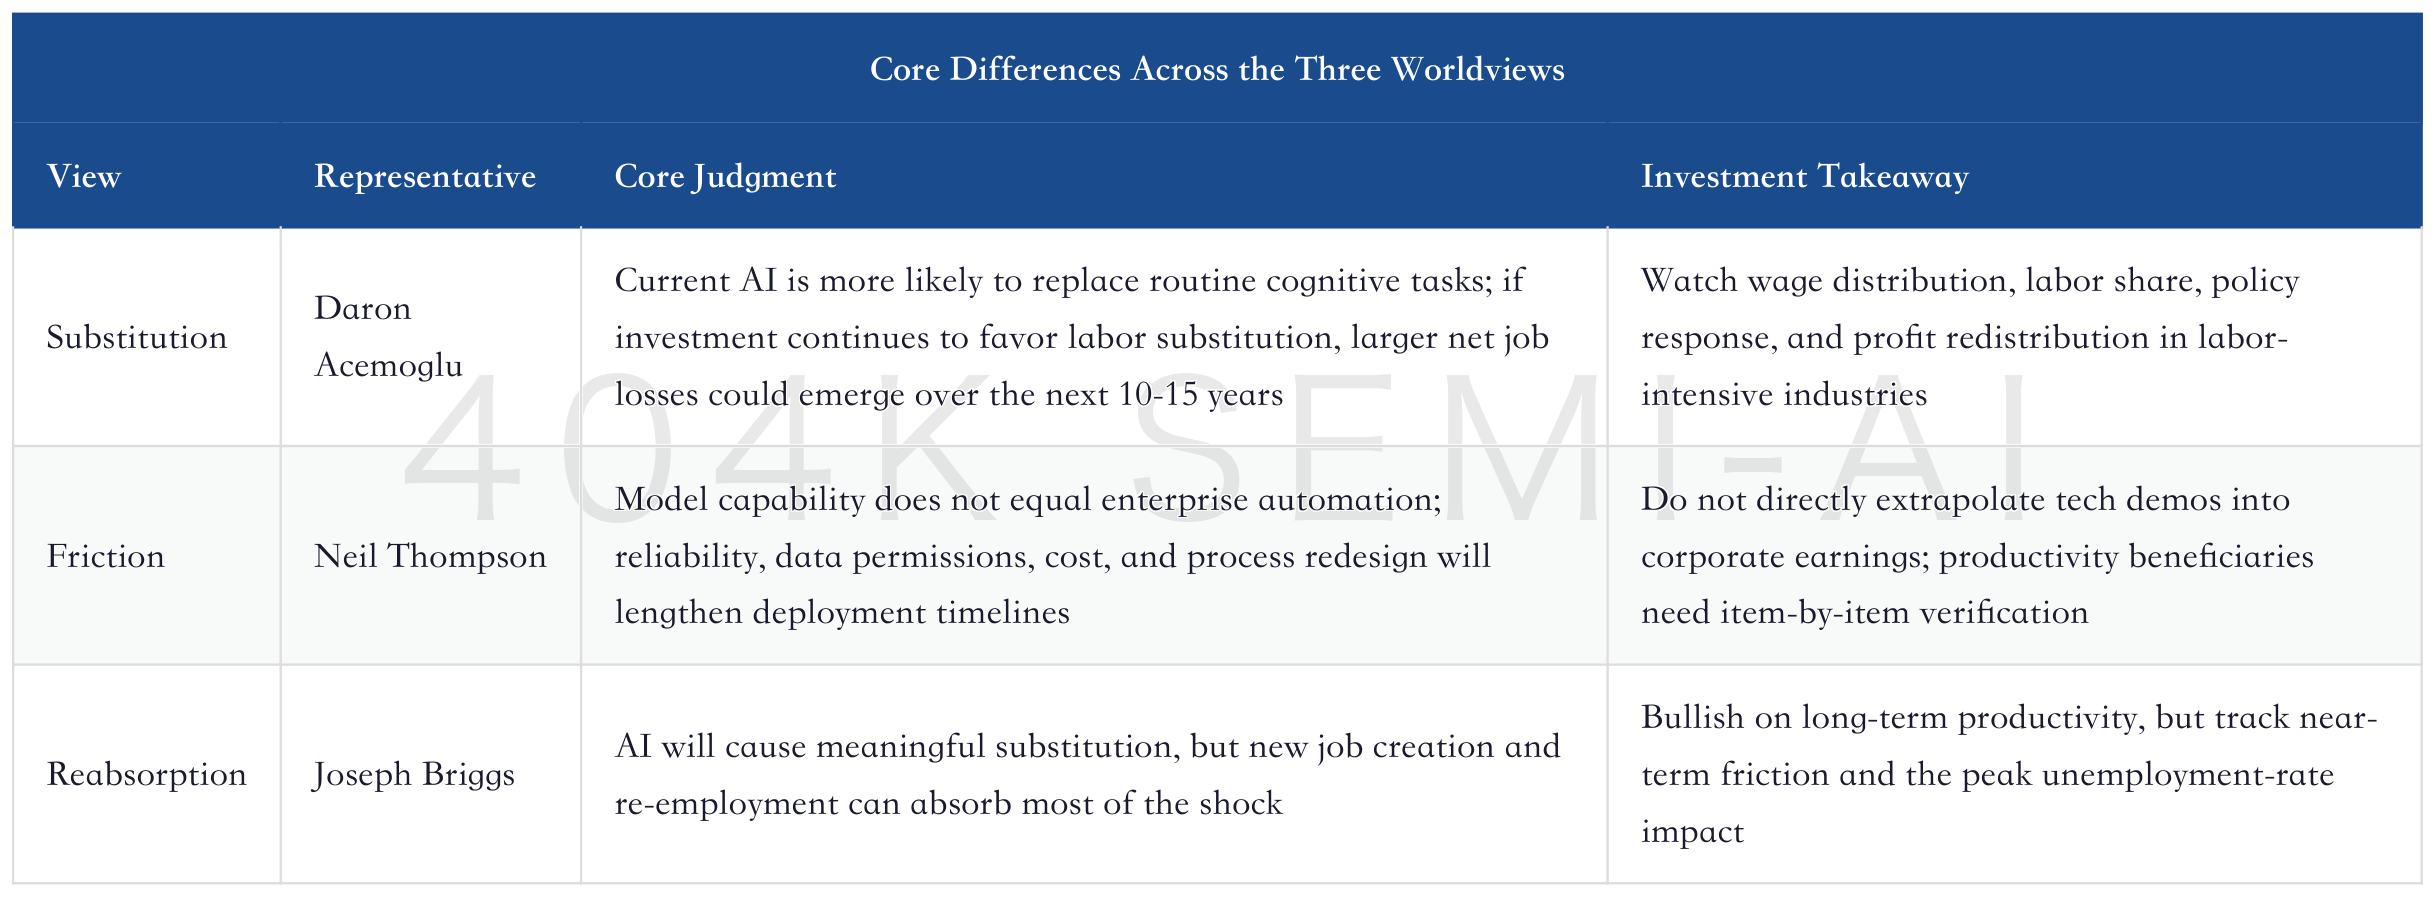
Taken together, these three views provide not a compromise answer, but a tracking framework. If the next two years see only localized substitution in customer service, back office, coding assistance, and marketing workflows, Thompson’s friction view will be closer to reality. If companies broadly convert AI savings into layoffs and hiring freezes, Acemoglu’s risks will be repriced. If AI simultaneously generates a large number of new occupations and new service demand, Briggs’ reabsorption logic will dominate.
III. Aggregate Data Has Not Broken, but Local Cracks Have Appeared
Goldman’s most restrained statement is that, so far, AI has not left a very clear statistical footprint on the aggregate labor market. Looking at AI adoption rates and occupational exposure, there is no significant linear relationship across U.S. occupations in unemployment rates, job growth, or employment changes.
This matters. Over the past year, the market has been easily swayed by two types of headlines: technology companies saying AI has improved efficiency and allowed them to cut some teams, and new graduates finding it harder to get jobs. Both are real signals, but they are not enough to prove that macro employment has entered an AI unemployment cycle. Total U.S. employment, services consumption, corporate hiring, and wage growth are still influenced by multiple factors, including interest rates, immigration, fiscal policy, and industry cycles.
But cracks do exist. Goldman’s AI Adoption Tracker shows that since ChatGPT’s release, employment, unemployment, and job openings in industries and occupations with high AI substitution risk have already underperformed those with high augmentation potential. Elsie Peng’s estimate is more direct: over the past year, AI substitution effects reduced monthly nonfarm payroll growth by about 25,000 jobs and lifted the unemployment rate by 0.16 percentage points; AI augmentation effects partly offset this, adding about 9,000 jobs per month and lowering the unemployment rate by 0.06 percentage points. The net impact is roughly 16,000 fewer nonfarm payroll jobs per month and an unemployment rate about 0.1 percentage points higher.
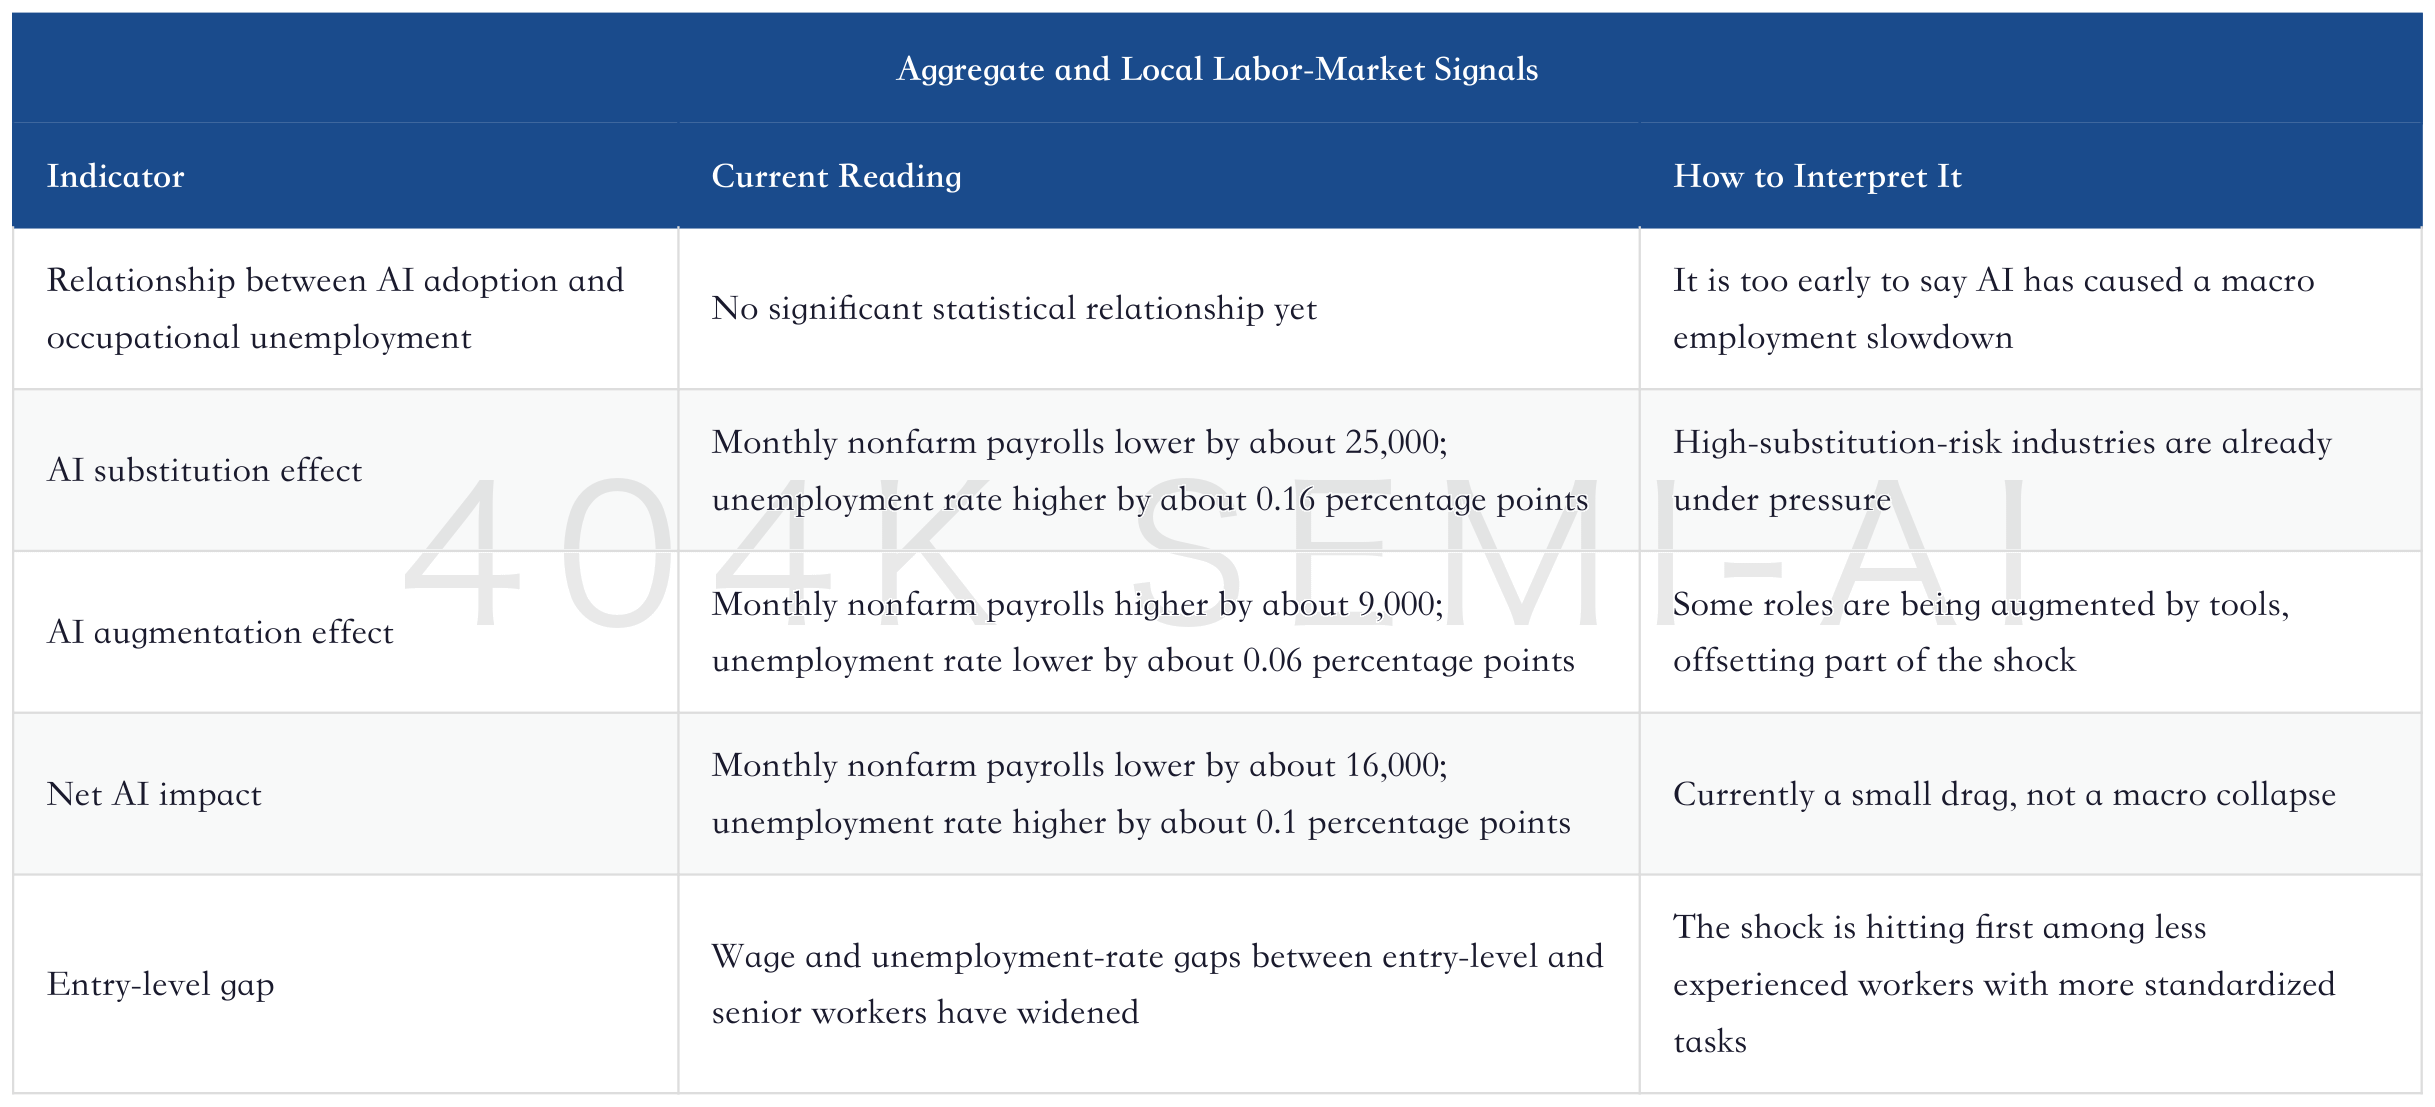
The conclusion from this table is clear: AI’s employment impact currently looks more like “local pressure accumulating” than “aggregate employment suddenly collapsing.” This is also why the equity market has not yet treated AI layoffs as a macro recession trade. The market is more focused on another question: can these local pressures translate into improved corporate earnings?
If AI is only a net drag of 16,000 nonfarm payroll jobs per month, the macro impact remains small for a U.S. economy with more than 150 million employed people. But if it is concentrated in high-paid white-collar roles, new graduates, software development, customer service, and back-office operations, the micro-level experience will be intense. Many households, schools, companies, and cities will not care how smooth the macro statistics look; what they will feel is the disappearance of entry-level roles, higher hiring requirements, and the removal of career ladders.
IV. The Real Unit of Analysis Is Not the “Occupation,” but the “Task”
To assess AI’s labor-market impact, we should not start with job titles, but with task structure. A job is usually not one task, but a bundle of dozens of tasks. If AI replaces 20% of those tasks, employee productivity may rise; if it replaces 60%, companies will recalculate headcount; if it replaces the core expert judgment, wage structures may be reordered; if it replaces the most basic entry-level tasks, career training ladders may become shorter.
Thompson’s framework is useful: if AI automates the least specialized, most repetitive, lowest-value tasks, the remaining workers will spend more time on high-value work, which may result in lower employment but higher wages. If AI automates the most specialized, scarcest, and most output-determining tasks, the remaining workers may be left with low-value execution, in which case employment may not necessarily fall, but wages could come under pressure.
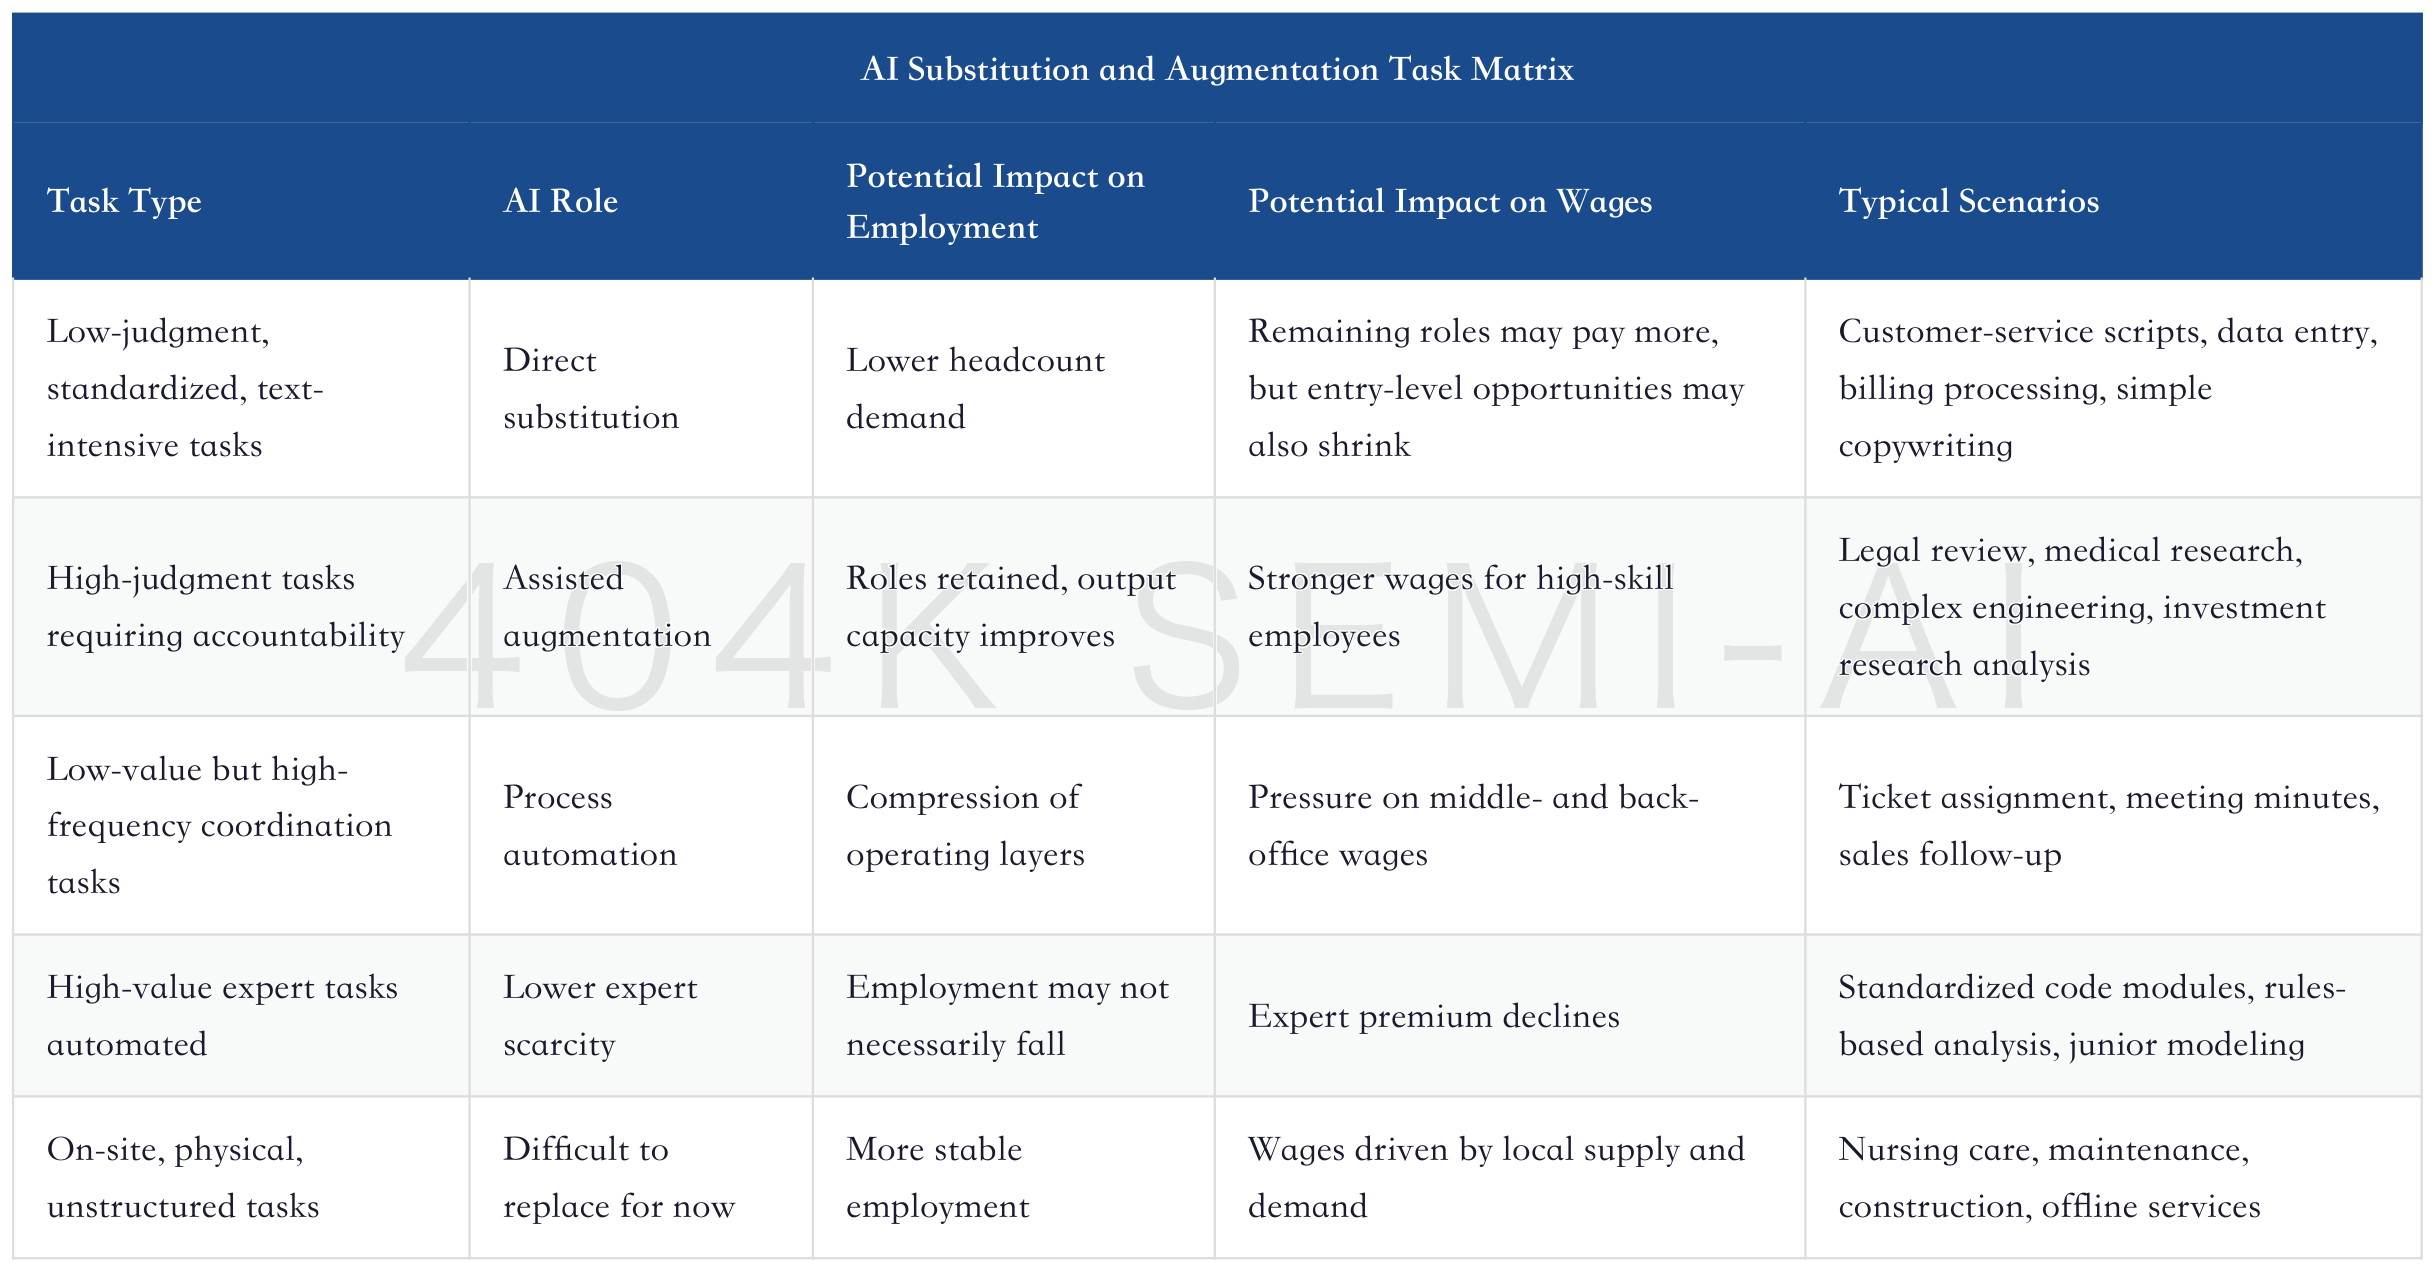
This is also why the statement “white-collar workers are at greater risk than blue-collar workers” is only half right. Among white-collar roles, the most vulnerable are those whose tasks are highly textual, process-driven, verifiable, and require limited accountability. Among blue-collar roles, if robotics matures in combination with AI vision, control, and spatial reasoning, physical tasks will also be repriced. Acemoglu treats the combination of AI and robotics as a long-term variable, because roughly half of U.S. jobs involve physical labor. As long as robotics deployment remains constrained, AI’s direct substitution of labor will not cover all jobs in one step.
The more certain shock today is to routine cognitive white-collar work. Phone customer service, back-office operations, insurance claims, bill collection, standardized data processing, basic analysis, and some junior software development are the first jobs AI can consume. What they have in common is not wage level, but that the tasks can be expressed through text, forms, rules, databases, and API calls.
V. Why New Graduates Feel the Chill First
Goldman Sachs’ discussion of college graduates in this report is important. The U.S. unemployment rate for college graduates reached 2.7% last month, significantly above the 2019 average of 2.1%, and also high relative to groups with other education levels. This is not all caused by AI; tech hiring cycles, the interest-rate environment, corporate cost control, and choice of major all matter. But AI has amplified the vulnerabilities of new graduates.
The reason is straightforward: new graduates are concentrated in industries and occupations where AI adoption is faster and more tasks can be automated. In management, information services, professional services, and finance, the share of college-educated employees is high. In legal, engineering, life sciences, and social-science occupations, the share of college-educated employees is also high, and a substantial portion of the tasks can be automated by AI. By contrast, occupations such as construction, repair, and grounds maintenance have a low share of college-educated workers and low AI exposure.
New graduates are under pressure not because their “degrees are useless,” but because the entry tasks in their career paths are easier for AI to absorb. In the past, junior analysts, junior programmers, junior paralegals, and junior marketing staff were trained through search, organization, first drafts, testing, customer support, spreadsheets, and basic communication. Once AI can automate these tasks, companies will ask: do we still need to hire so many junior roles, or should senior staff complete the work directly with AI?
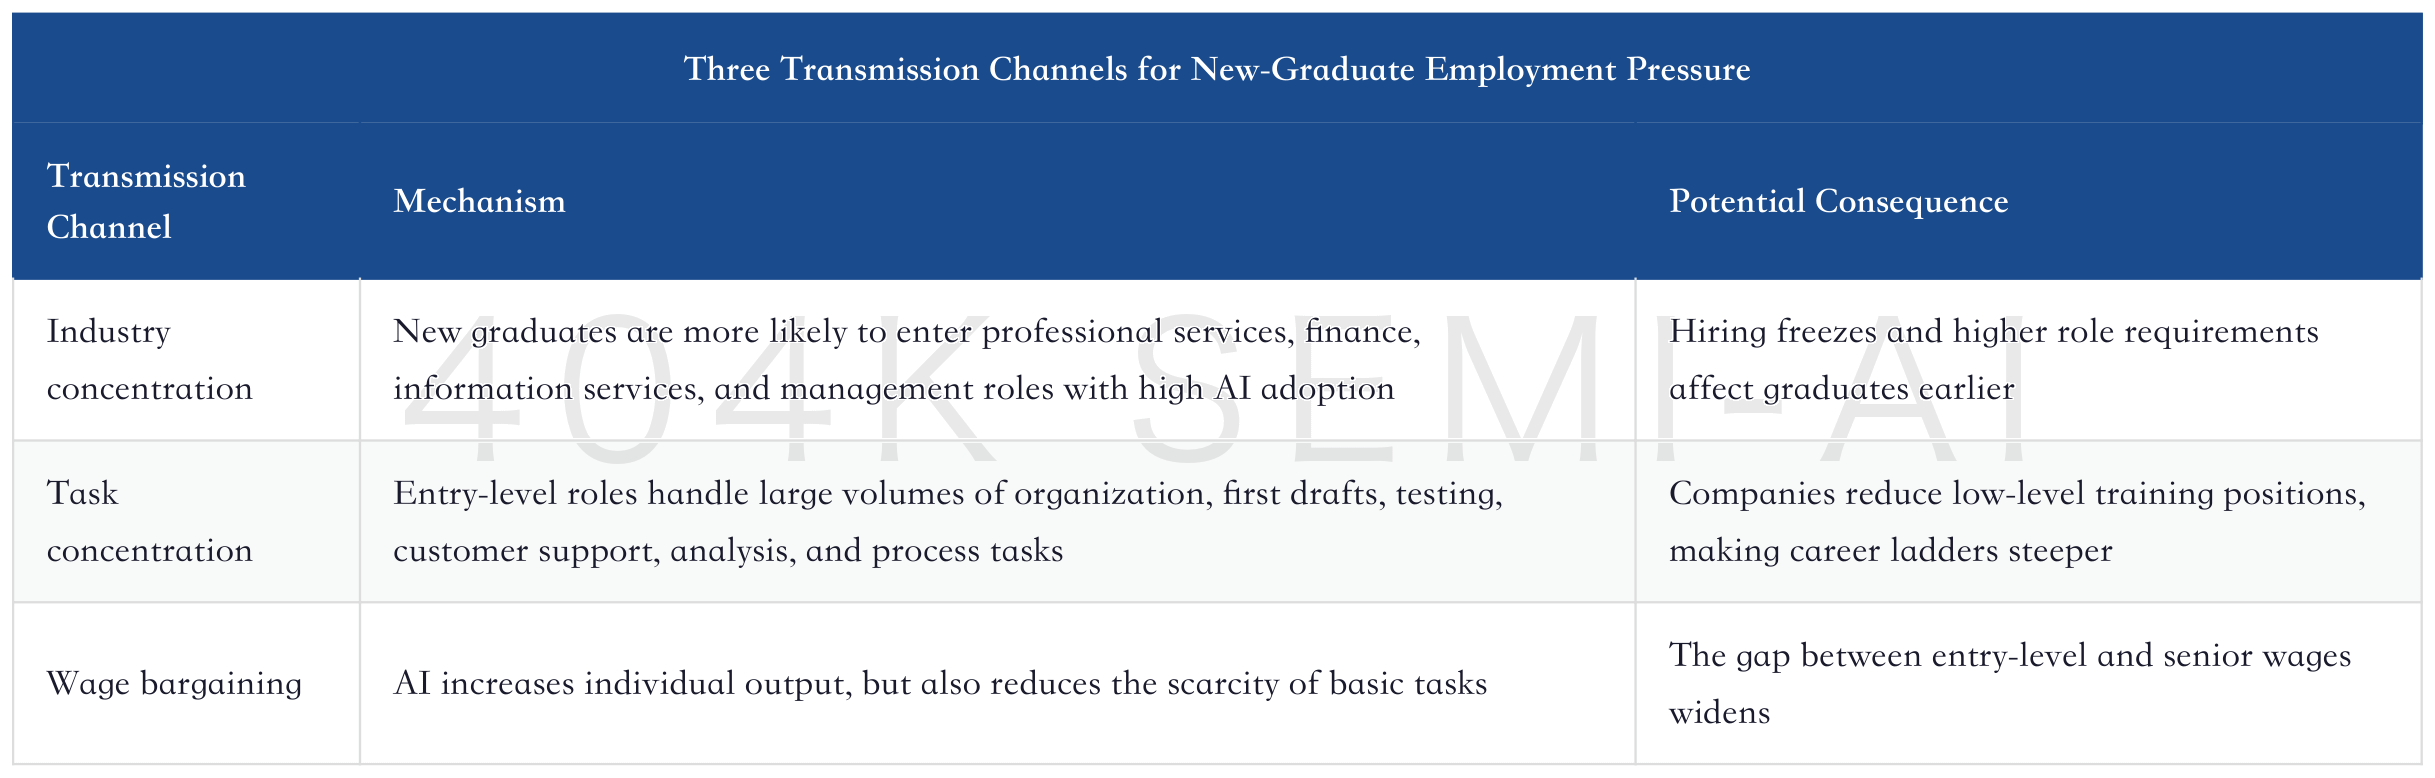
This has long-term implications for both education and companies. If schools still treat “being able to code, write reports, make PPTs, and organize information” as core capabilities, graduates will find it increasingly difficult to differentiate themselves from AI. If companies fully eliminate entry-level roles, they may discover several years later that the supply of mid- and senior-level talent has thinned. AI replacing training tasks is not the same as replacing talent development; but under short-term profit pressure, companies can easily cut the low-level roles that are easiest to quantify first.
Goldman also notes that college graduates have stronger long-term adaptability. Younger, more educated, more urbanized workers are more likely to switch occupations after being displaced, and are more likely to reduce long-term income losses through retraining. The risk is not that they will never find work; it is that the first job becomes harder to obtain, starting wages fall, and the path of experience accumulation is rewritten.
VI. Companies Have Started Using AI to Redesign Organizations, but the Income Statement Still Has No Unified Answer
This report includes a very useful company table: Alphabet says nearly half of its code is generated by AI; Amazon continues to cut white-collar roles as automation advances; Block says code changes per engineer have increased 2.5x, and non-engineers can also contribute significant amounts of code; Cisco, Coinbase, Intuit, Meta, Salesforce, ServiceNow, and Workday have all disclosed AI’s impact on customer service, coding, support, or organizational efficiency. Citi says AI frees up roughly 100,000 developer hours per week, and links its medium-term reduction of 20,000 roles to process optimization.
These cases show that AI has already entered organizational design and is no longer just a trial tool. Companies are starting to use AI in four areas: writing code, handling customer service, compressing back-office functions, and reducing management and support layers. They all point in the same direction: if a process can be standardized, digitized, and verified, AI will first become an employee tool, then become a management tool for calculating headcount.
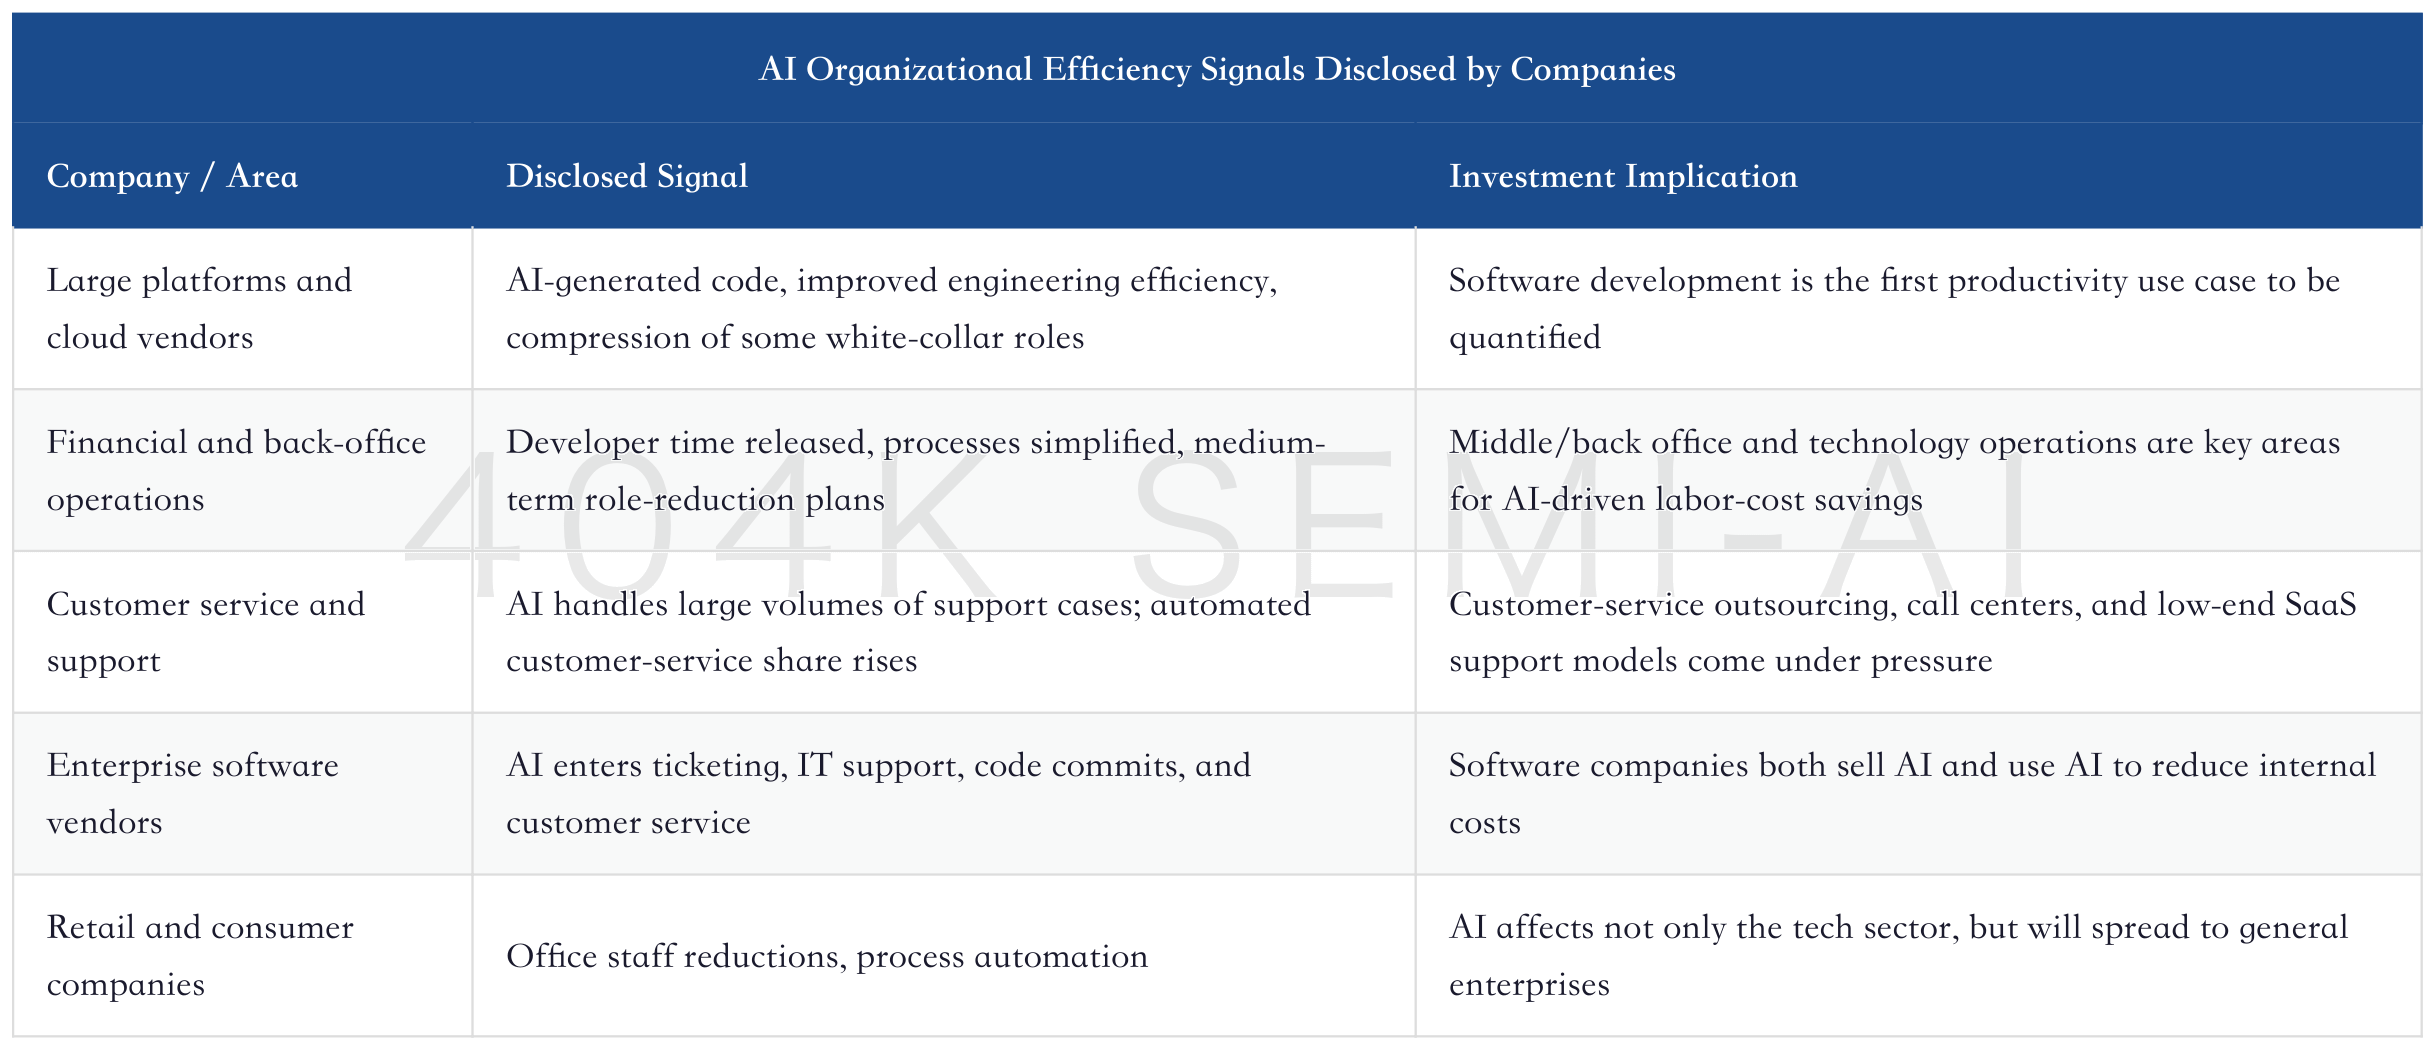
The problem is that disclosure is not the same as the income statement. Hammond’s statistics show that among S&P; 500 companies, 54% mentioned AI productivity or efficiency on first-quarter earnings calls, only 11% quantified productivity gains in specific use cases, and only 2% explicitly linked those gains to profitability. In other words, companies have begun talking about AI-driven labor savings, but the market has not yet seen enough repeatable, predictable, auditable profit contribution.
This explains why the market is still more willing to buy AI infrastructure. Infrastructure orders, capex, supply-chain gaps, and pricing can be verified quarter by quarter. Productivity gains are dispersed across thousands of companies, disclosure standards are inconsistent, and the money saved may be consumed by token costs, data governance, security investment, employee training, and competitive price cuts.
VII. The Agent Cost Curve Defines the Boundary of Automation
AI’s impact on employment ultimately comes down to a very basic calculation: whether automation is cheaper, more reliable, and more controllable than hiring people. Technical capability is only the first step. The cost curve and the cost of errors determine whether companies will replace roles at scale.
Goldman Sachs’ comparison of agent costs is straightforward. A coding agent currently costs about $13.39 per day, versus about $300 per day for comparable human labor. A data-entry agent costs about $59.68 per day, versus about $80 for human labor. A customer-service agent costs about $92.90 per day, versus about $90 for human labor. In other words, coding is already clearly economical, data entry is close to economical, while customer service remains constrained by reliability, real-time voice, complex emotions, and process integration.
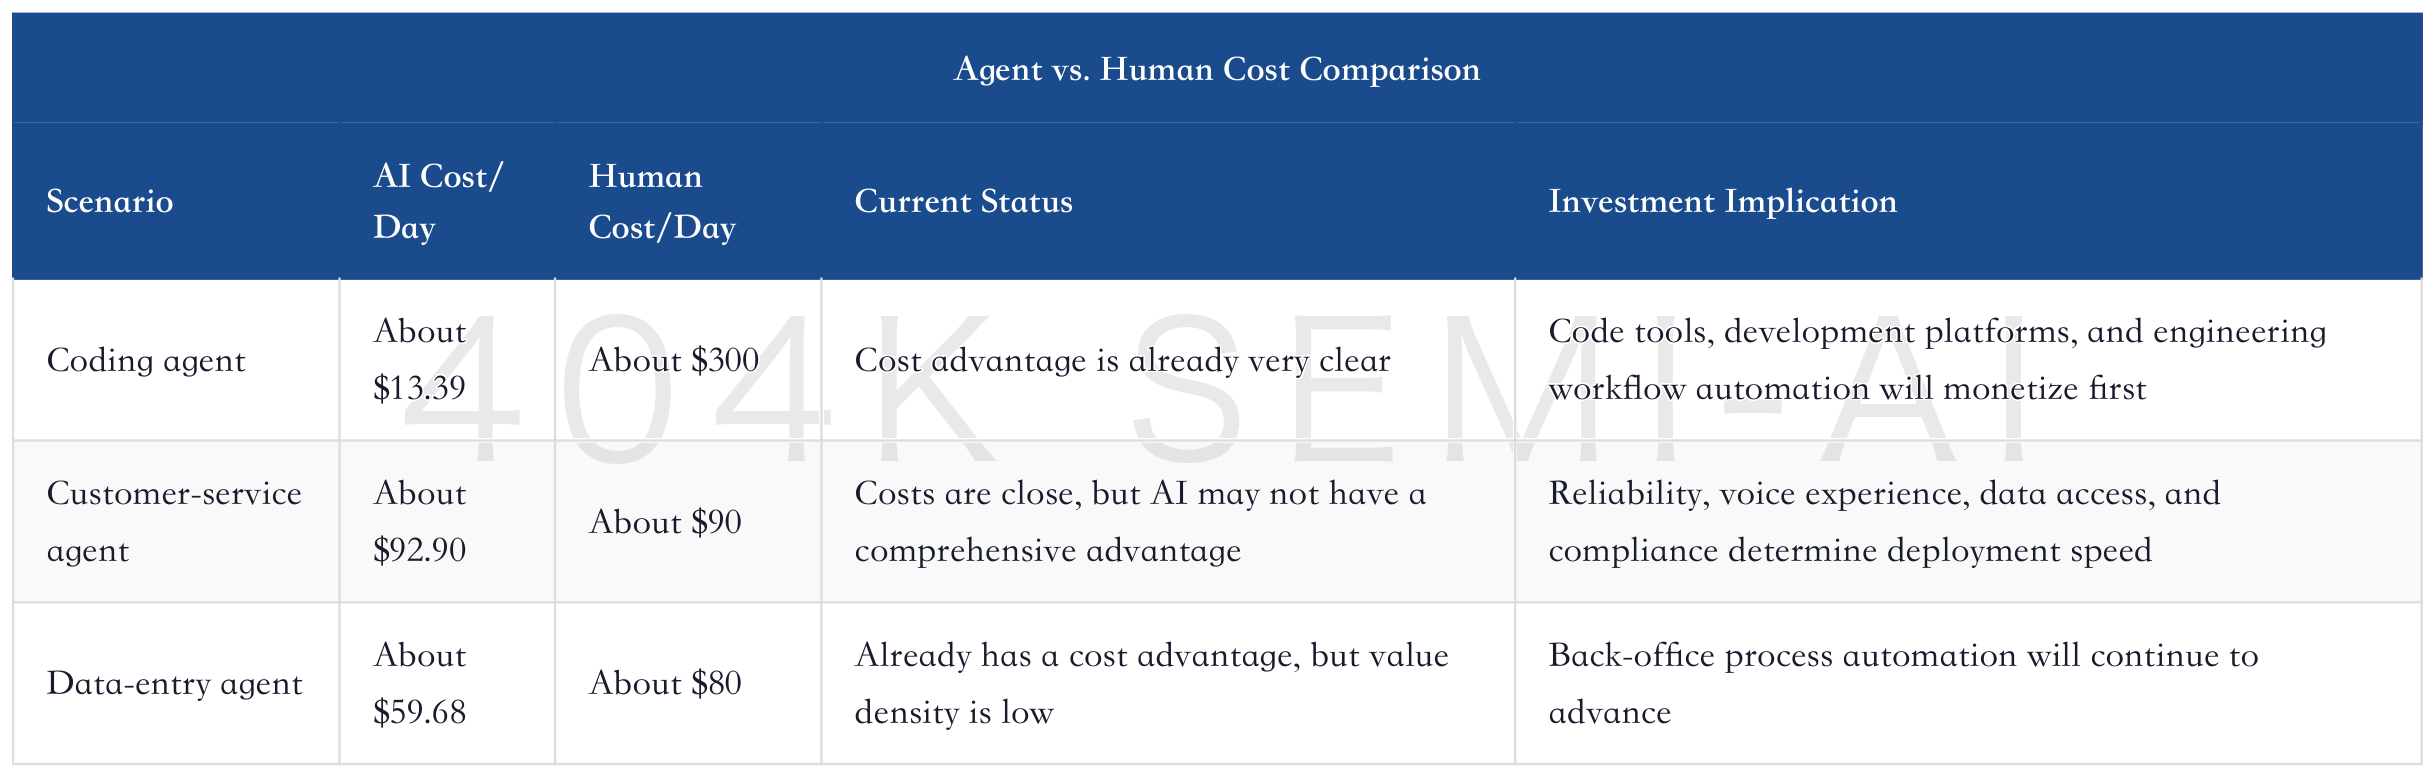
This table is more useful than many grand narratives. AI substitution will not happen evenly. It will start where ROI is clearest. Why is coding moving first? Because it is text-intensive, high-value, verifiable, supported by mature toolchains, and has fast feedback loops. Model-generated code can run tests, be tracked through version control, be reviewed by engineers, and be fixed quickly when errors occur. Why is customer service slower? Because it requires real-time voice, emotion handling, permission management, brand-risk control, and complex exception handling. Why might data entry, although economical, not drive major valuation upside? Because value density is low and customers’ willingness to pay is limited.
The cost curve is still changing. Goldman Sachs expects global token demand by 2030 could be about 24 times higher than in 2026, while token production costs fall, leading model prices stabilize, and the industry may enter a phase in which rising usage can still improve incremental margins. If this judgment proves correct, the boundary of AI substitution will continue to move outward. Processes that were previously uneconomical to automate will gradually become economical as token costs fall and toolchains mature.
But lower costs also have another side: pricing pressure on software and model companies will intensify. Customers will treat falling token costs as a negotiating lever and demand that vendors return efficiency gains. Internally, companies will also shift AI budgets from “experimental budgets” to “production budgets,” strictly comparing the cost, accuracy, risk, and labor-substitution effect of each type of agent.
VIII. Capital Markets Are Temporarily Rewarding Hardware Because Hardware Evidence Is Being Realized First
Goldman Sachs’ market section presents a very clear picture: the AI infrastructure basket is up about 74% year to date, outperforming the equal-weighted S&P; 500 by about 65 percentage points. The productivity-beneficiary basket has also risen over the past few years, but its performance has not been strong since the end of 2023 and has recently moved sideways. The market is not disbelieving that AI will improve efficiency. It simply has not yet seen enough investable, measurable, and sustainable profit evidence.
The AI trade is still in the “buildout phase,” not the “efficiency realization phase.” Winners in the buildout phase are easy to identify: GPUs, ASICs, HBM, advanced packaging, PCBs, servers, networking, optical modules, power, liquid cooling, and data centers. Winners in the efficiency realization phase are harder to identify: which software companies can sell AI functionality as outcomes, which service companies can use AI to improve margins, which enterprises can keep layoff savings for shareholders, and which will simply pass savings on to customers.
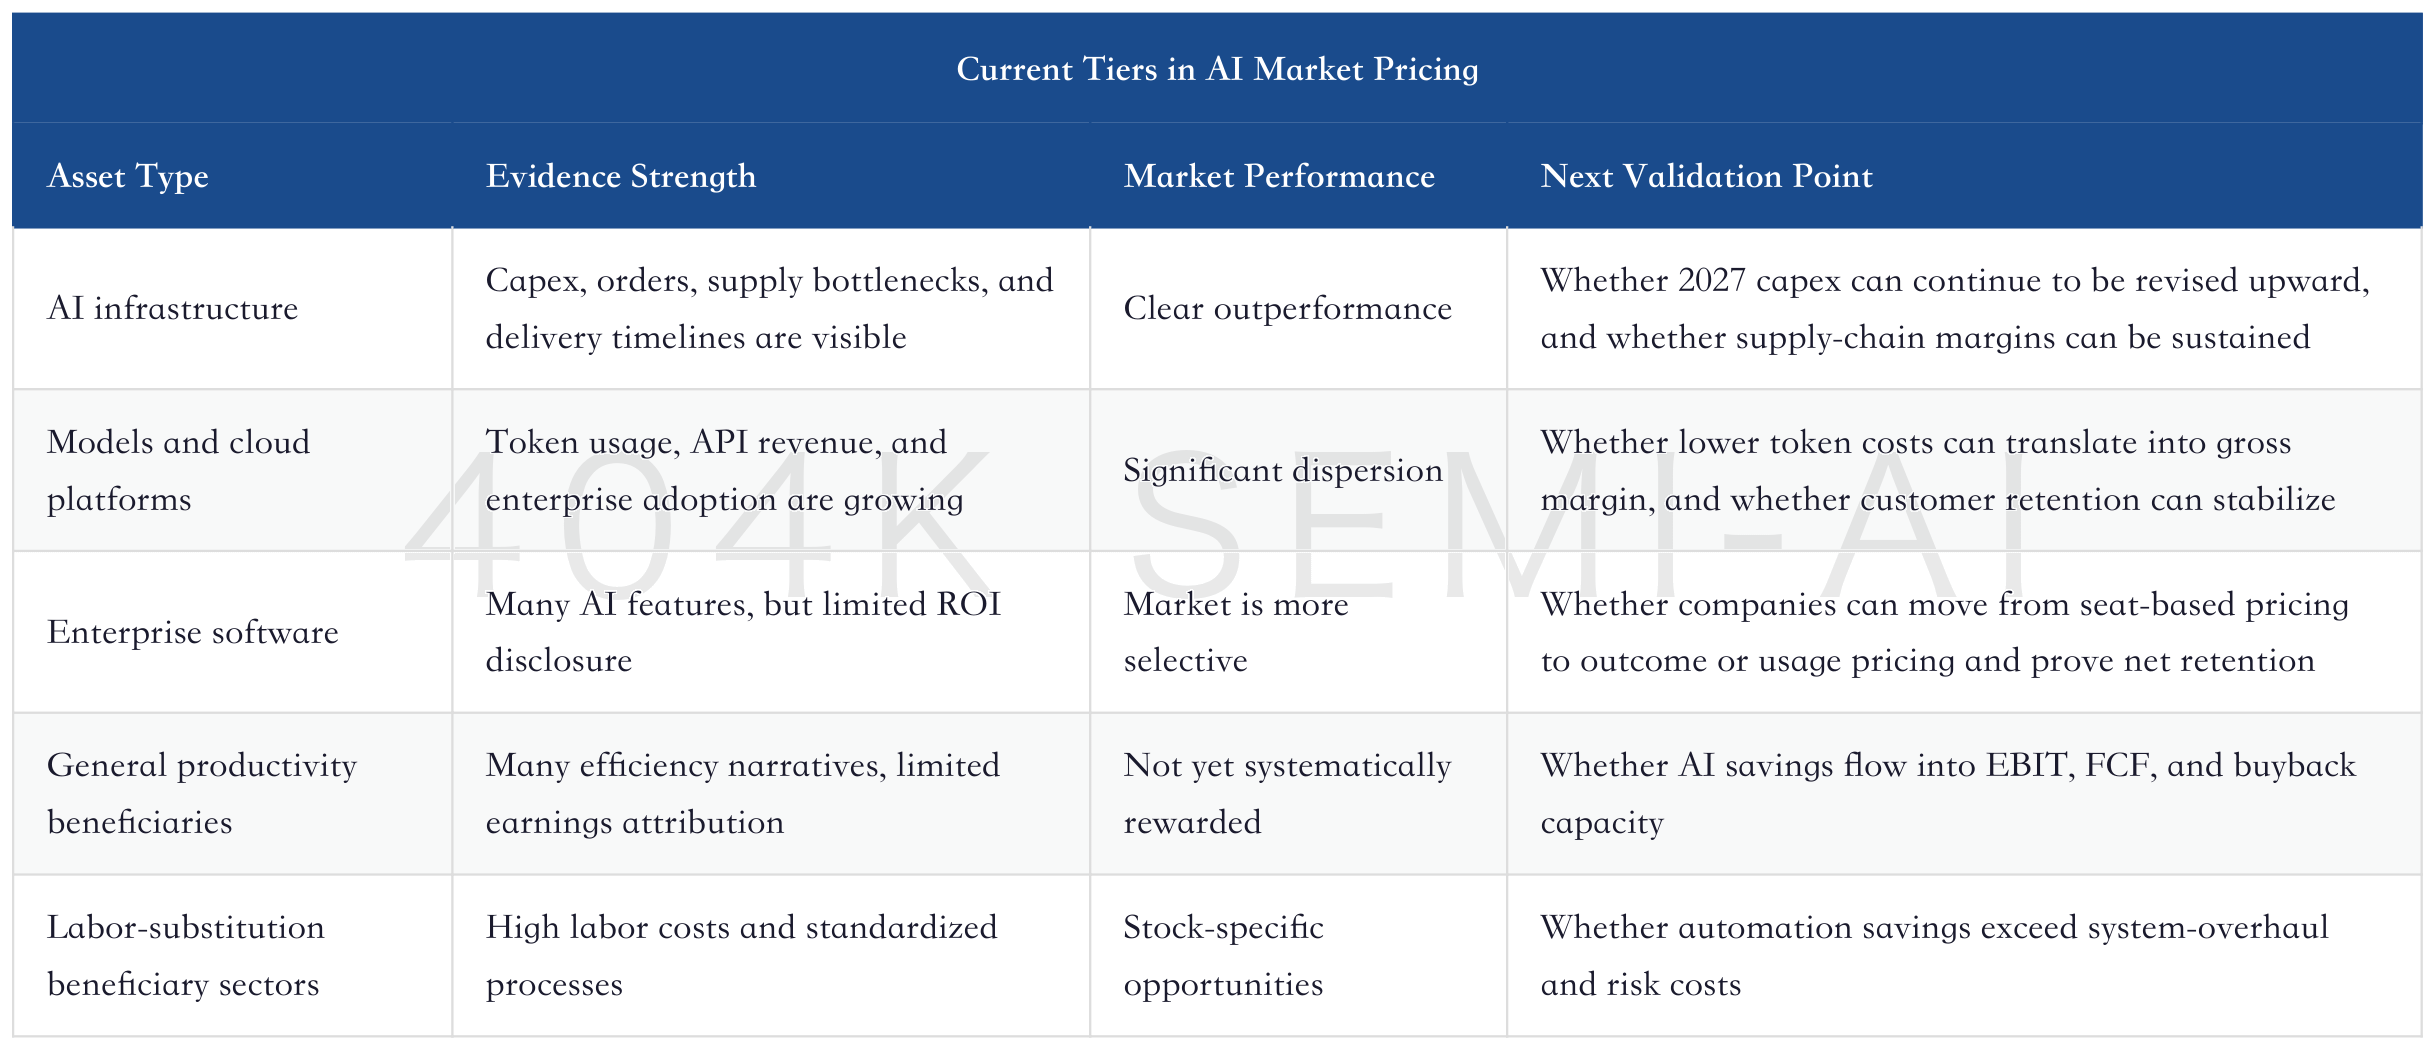
This is also why “AI layoffs” are not necessarily positive. If layoffs are merely the result of slowing demand, organizational bloat, or cyclical downturns, they do not support valuation. Layoffs only become positive for the income statement when they come with lower costs, faster delivery, and higher net retention at the same revenue level. What the market wants is not “fewer people,” but “growth after fewer people.”
IX. AI Will Change Labor’s Share and the Distribution of Capital Returns
Beyond the employment shock, the larger question is who captures productivity gains. If AI is mainly controlled through models, data, compute, and platforms, capital will capture a higher share of the gains. If AI becomes a general-purpose tool like Office, search engines, and cloud software, workers may also share part of the gains. If competition is too intense, the gains may instead be captured by customers.
Acemoglu’s concern is most explanatory here. The key inputs for current AI are compute, data, and models, and ownership is highly concentrated in capital and platforms. If AI mainly replaces white-collar tasks, companies save on wages, model and cloud vendors charge token and platform fees, and residual profits flow into shareholder returns, labor’s share will decline. Income inequality may rise, especially as low-paid white-collar and entry-level roles face greater pressure.
But distribution outcomes do not follow a single path. Thompson’s task framework shows that if AI automates low-value tasks, the remaining employees may become more productive and wages may rise. If AI automates high-value expert tasks, the expert premium may fall and income gaps may narrow. Employment levels, wages, and margins do not have a linear relationship.
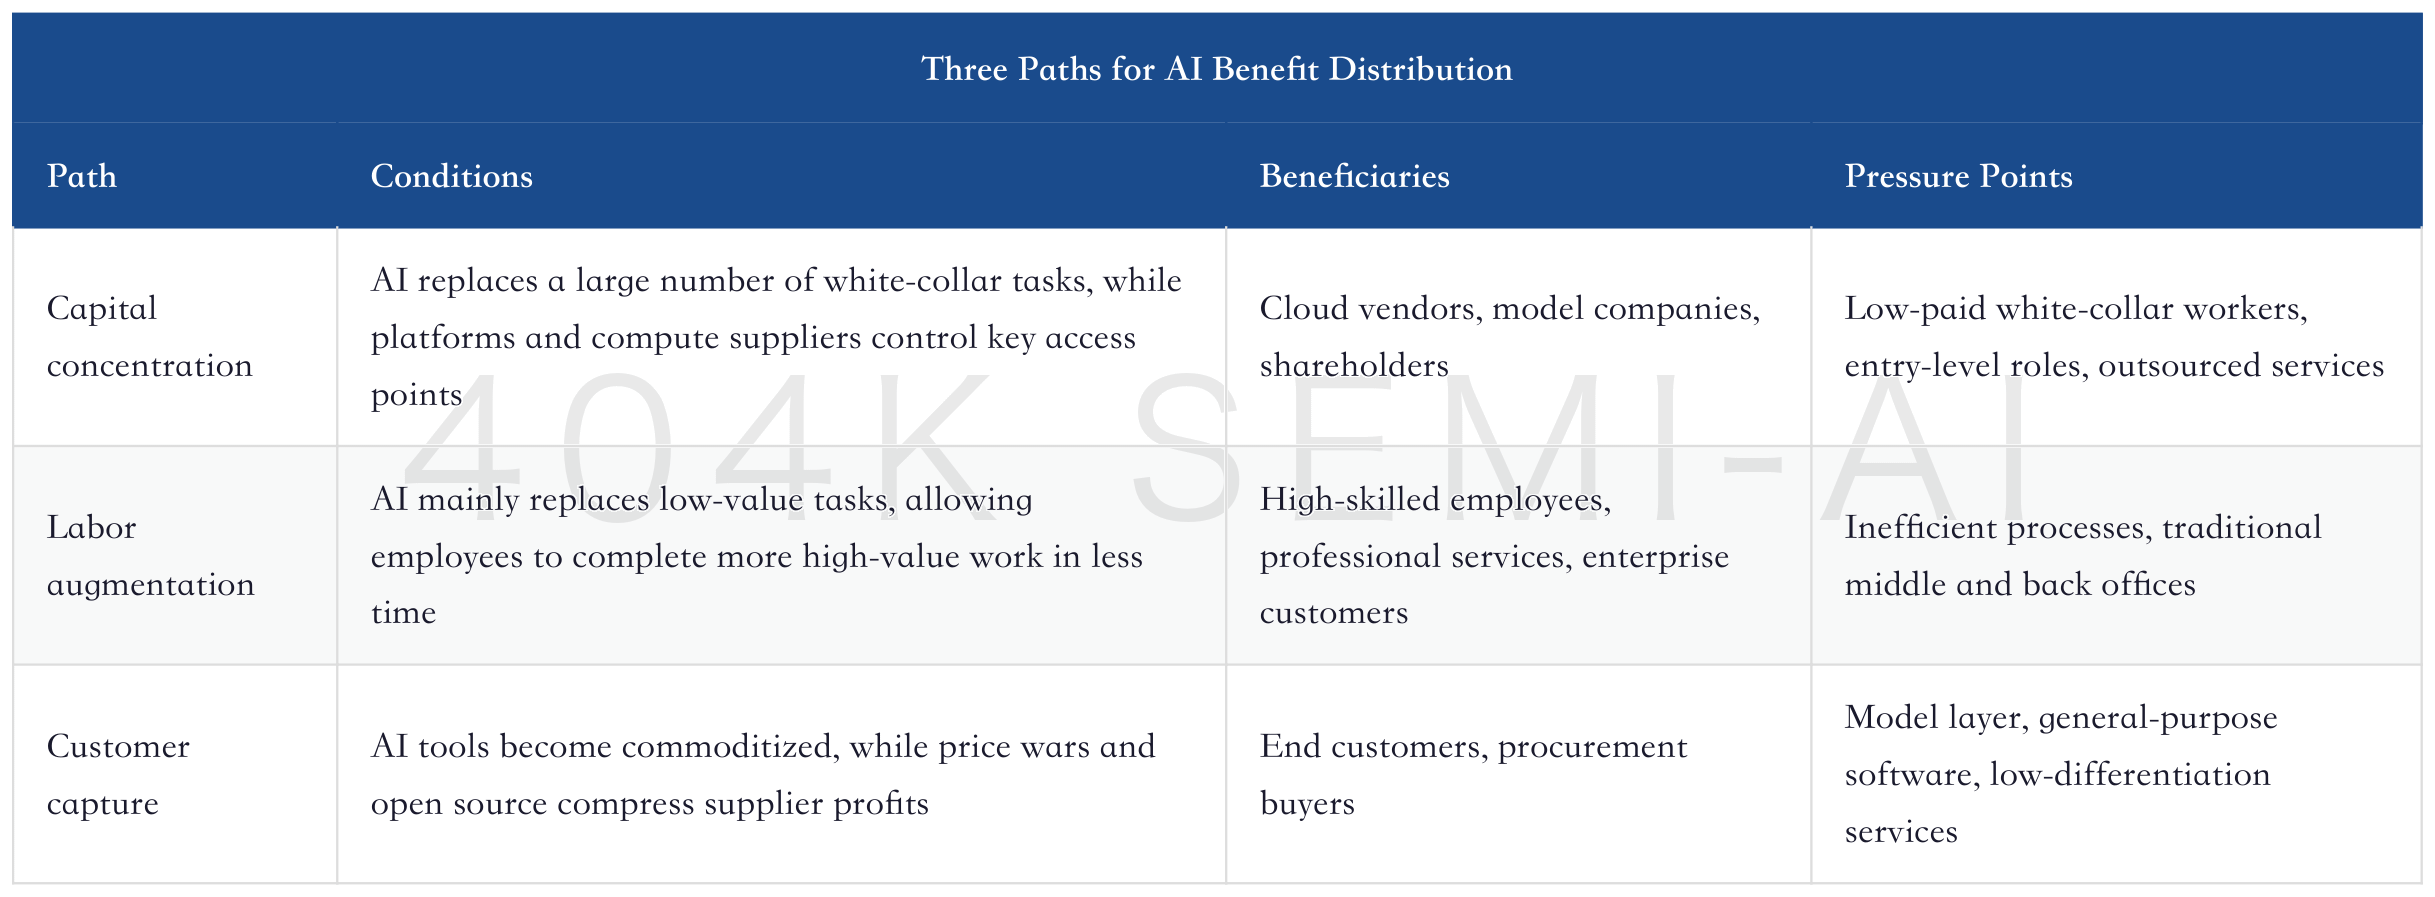
From an investment perspective, it is not enough to judge that “AI improves productivity.” The key is to determine where productivity gains are retained. If they stay in compute and platforms, hardware and cloud continue to lead. If they stay in software workflows, enterprise applications and vertical agents will see valuation upgrades. If customers capture the gains, AI may improve economy-wide efficiency without necessarily creating many investable profit pools.
10. History Creates New Jobs, but History Is Not an Automatic Guarantee
Briggs offers an optimistic but not blind historical perspective: about 60% of U.S. workers today are employed in occupations that did not exist in 1940, and these new occupations have contributed roughly 85% of employment growth since 1940. The U.S. economy creates and destroys 25 million to 35 million jobs each year, and the labor market itself has strong reallocation capacity. The expansion of healthcare employment from roughly 2 million to more than 18 million is also an example of technology, income growth, and professional specialization jointly creating jobs.
This historical evidence is the foundation for the AI optimists. Technology does not only destroy jobs; it also creates new industries, new occupations, and new demand. AI may create new roles in model governance, data operations, agent product management, automation workflow design, AI safety auditing, robotics operations and maintenance, synthetic data, enterprise knowledge engineering, workflow orchestration, and other areas.
But Acemoglu’s warning is equally important: the fact that many jobs have been created historically does not mean every technological revolution will automatically create enough good jobs. Since the late 1970s, hollowing-out caused by technological substitution in manufacturing and some middle-skill jobs has already shown that “creation” and “destruction” are not always symmetrical. New jobs may pay less, be located farther away, require higher skills, or arrive too slowly.
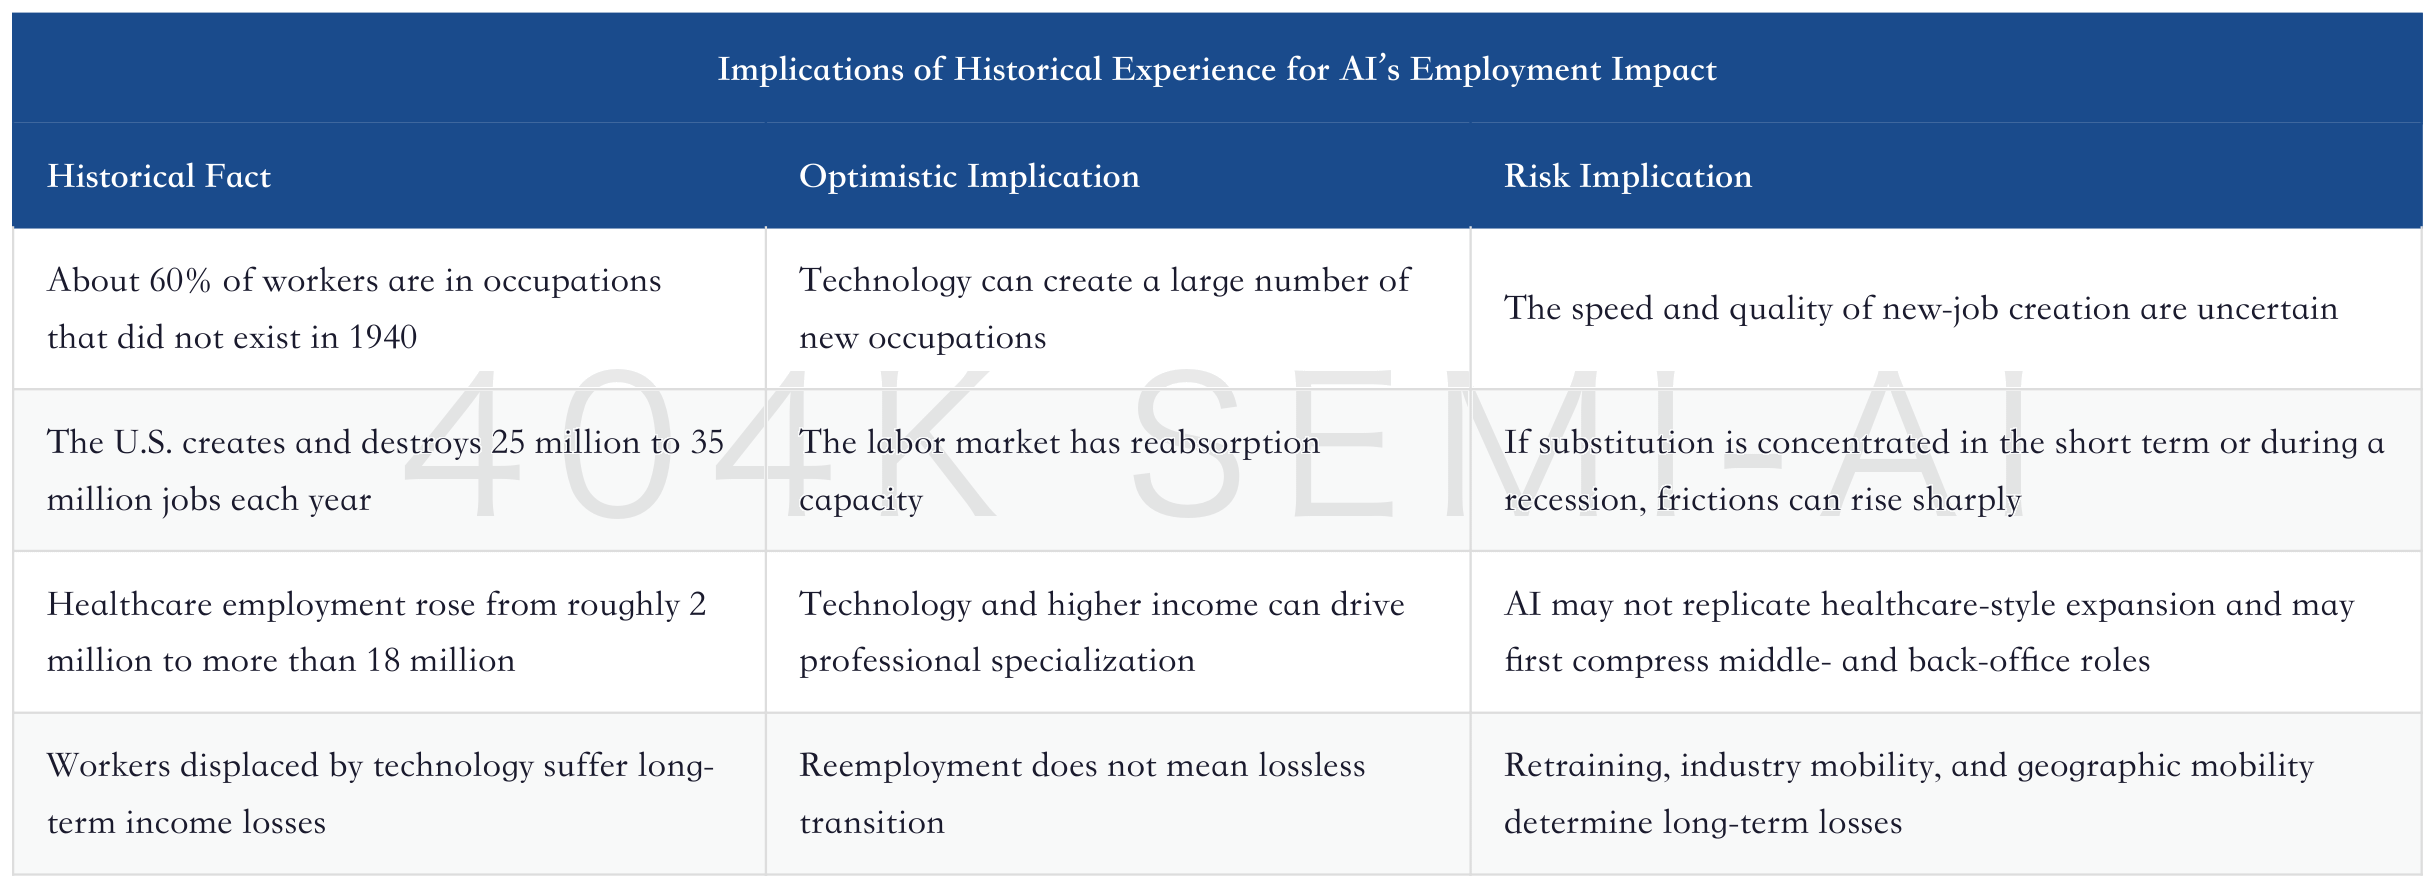
Another Goldman Sachs data point also belongs in the monitoring framework: workers laid off from technology-substituted jobs take longer to find reemployment, suffer larger real income losses after reemployment, and experience materially weaker income growth over the following decade. Retraining can improve outcomes. Laid-off workers who complete retraining within three years see stronger cumulative real wage growth over the following decade and a lower probability of future unemployment. This conclusion is highly practical for both policy and companies: if AI substitution is unavoidable, reducing friction is itself part of realizing productivity gains.
11. Investment Framework: Do Not Just Buy “Labor Savings”; Buy Verifiable Profit Retention
When AI’s employment impact is translated into investing, it does not support a simple conclusion that “labor-intensive industries benefit” or “software services are disadvantaged.” The key lies in four questions: can the industry’s tasks be replaced by AI; can the resulting cost savings flow into the income statement; will the savings be captured by customers or competitors; and will transition frictions consume the gains.
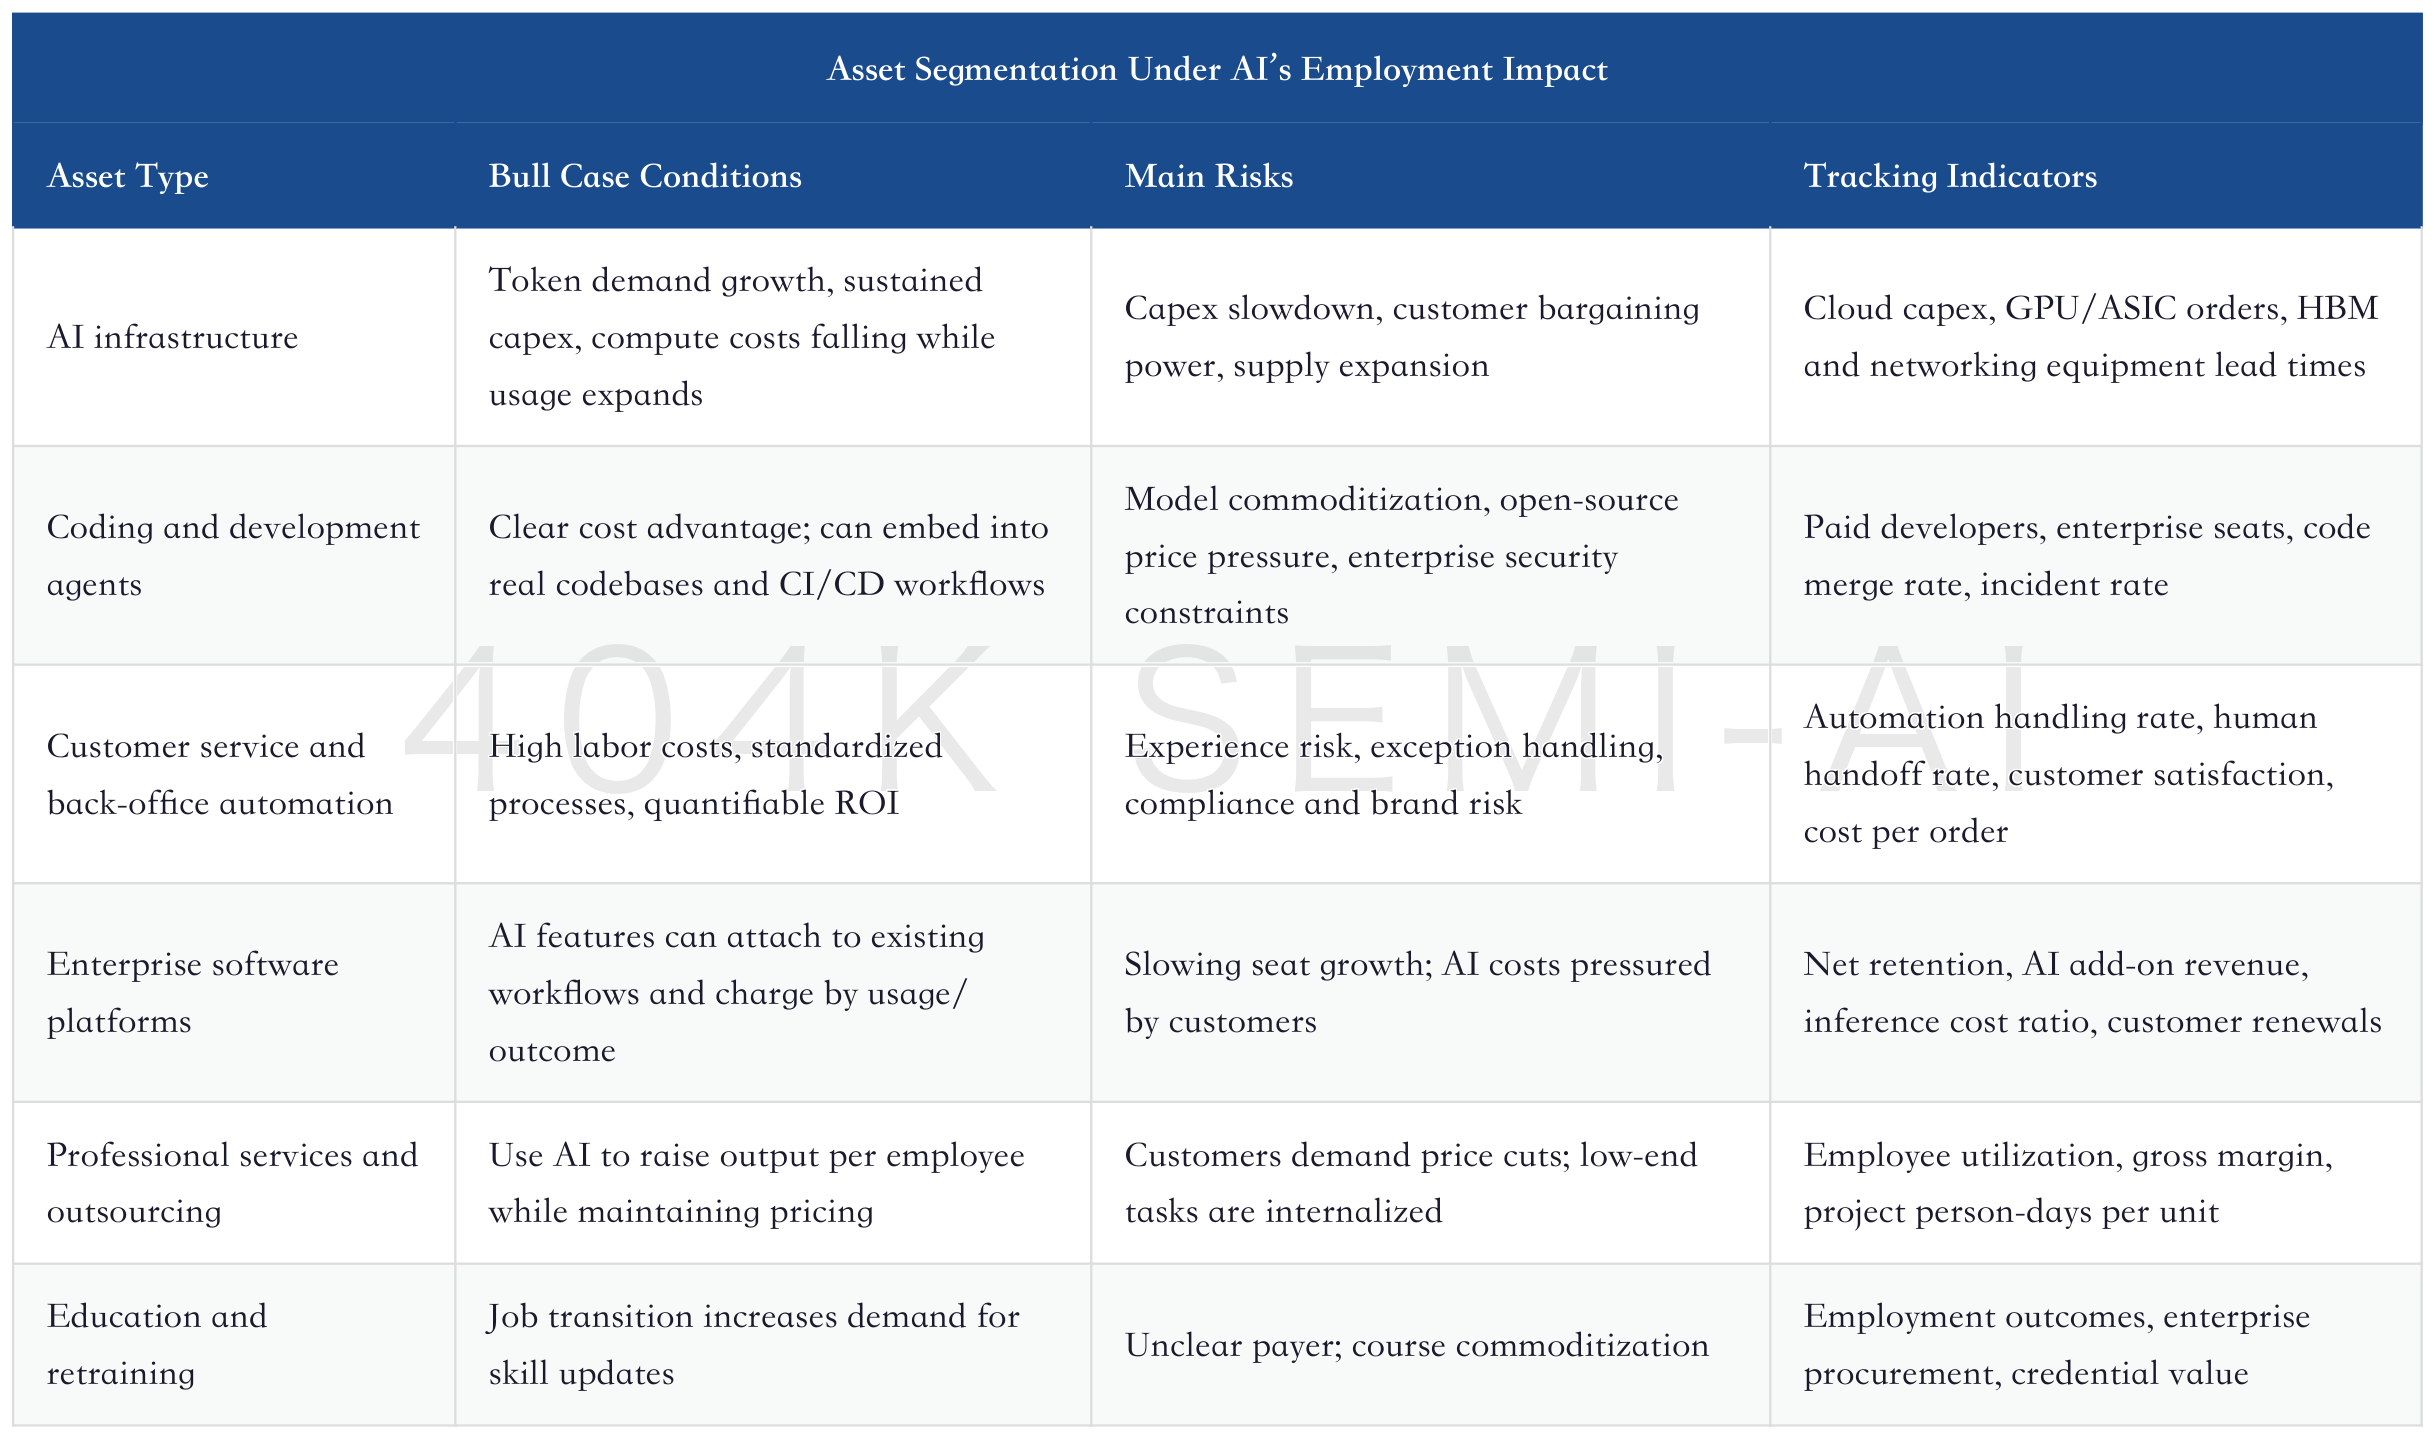
The core behind this table is profit retention. AI’s ability to save labor costs does not necessarily mean share prices rise. If companies pass all cost savings to customers through lower prices, shareholders capture no benefit. If software companies incur higher token costs to provide AI features but cannot raise prices, gross margins will come under pressure. If outsourcing providers use AI to improve efficiency but customers cut pricing based on person-days, profits will also fail to stay with the provider.
Better investment targets should have three characteristics: first, clear automation ROI, with customers willing to pay for outcomes; second, barriers created by data, workflows, channels, or compliance, preventing lower costs from turning entirely into price wars; third, benefits that can show up in financial statements as revenue growth, gross margin improvement, lower expense ratios, or higher free cash flow.
12. The Biggest Misjudgment Risk: Treating “Capability Progress” Directly as “Job Disappearance”
Rapid AI development does not mean jobs will disappear just as rapidly. Enterprise automation must pass through nine gates: capability, reliability, cost, data, permissions, process, regulation, organization, and culture. If any gate blocks adoption, model capability will remain stuck at the demo layer.
Conversely, “aggregate employment still looks fine” cannot be used to dismiss structural change. Many jobs will not show up as “disappearing.” Instead, the impact will appear through reduced hiring, wage pressure, slower promotion, outsourcing price cuts, fewer entry-level roles, and heavier workloads per worker. The macro unemployment rate may look smooth, while the lived experience within specific occupations feels sharp.
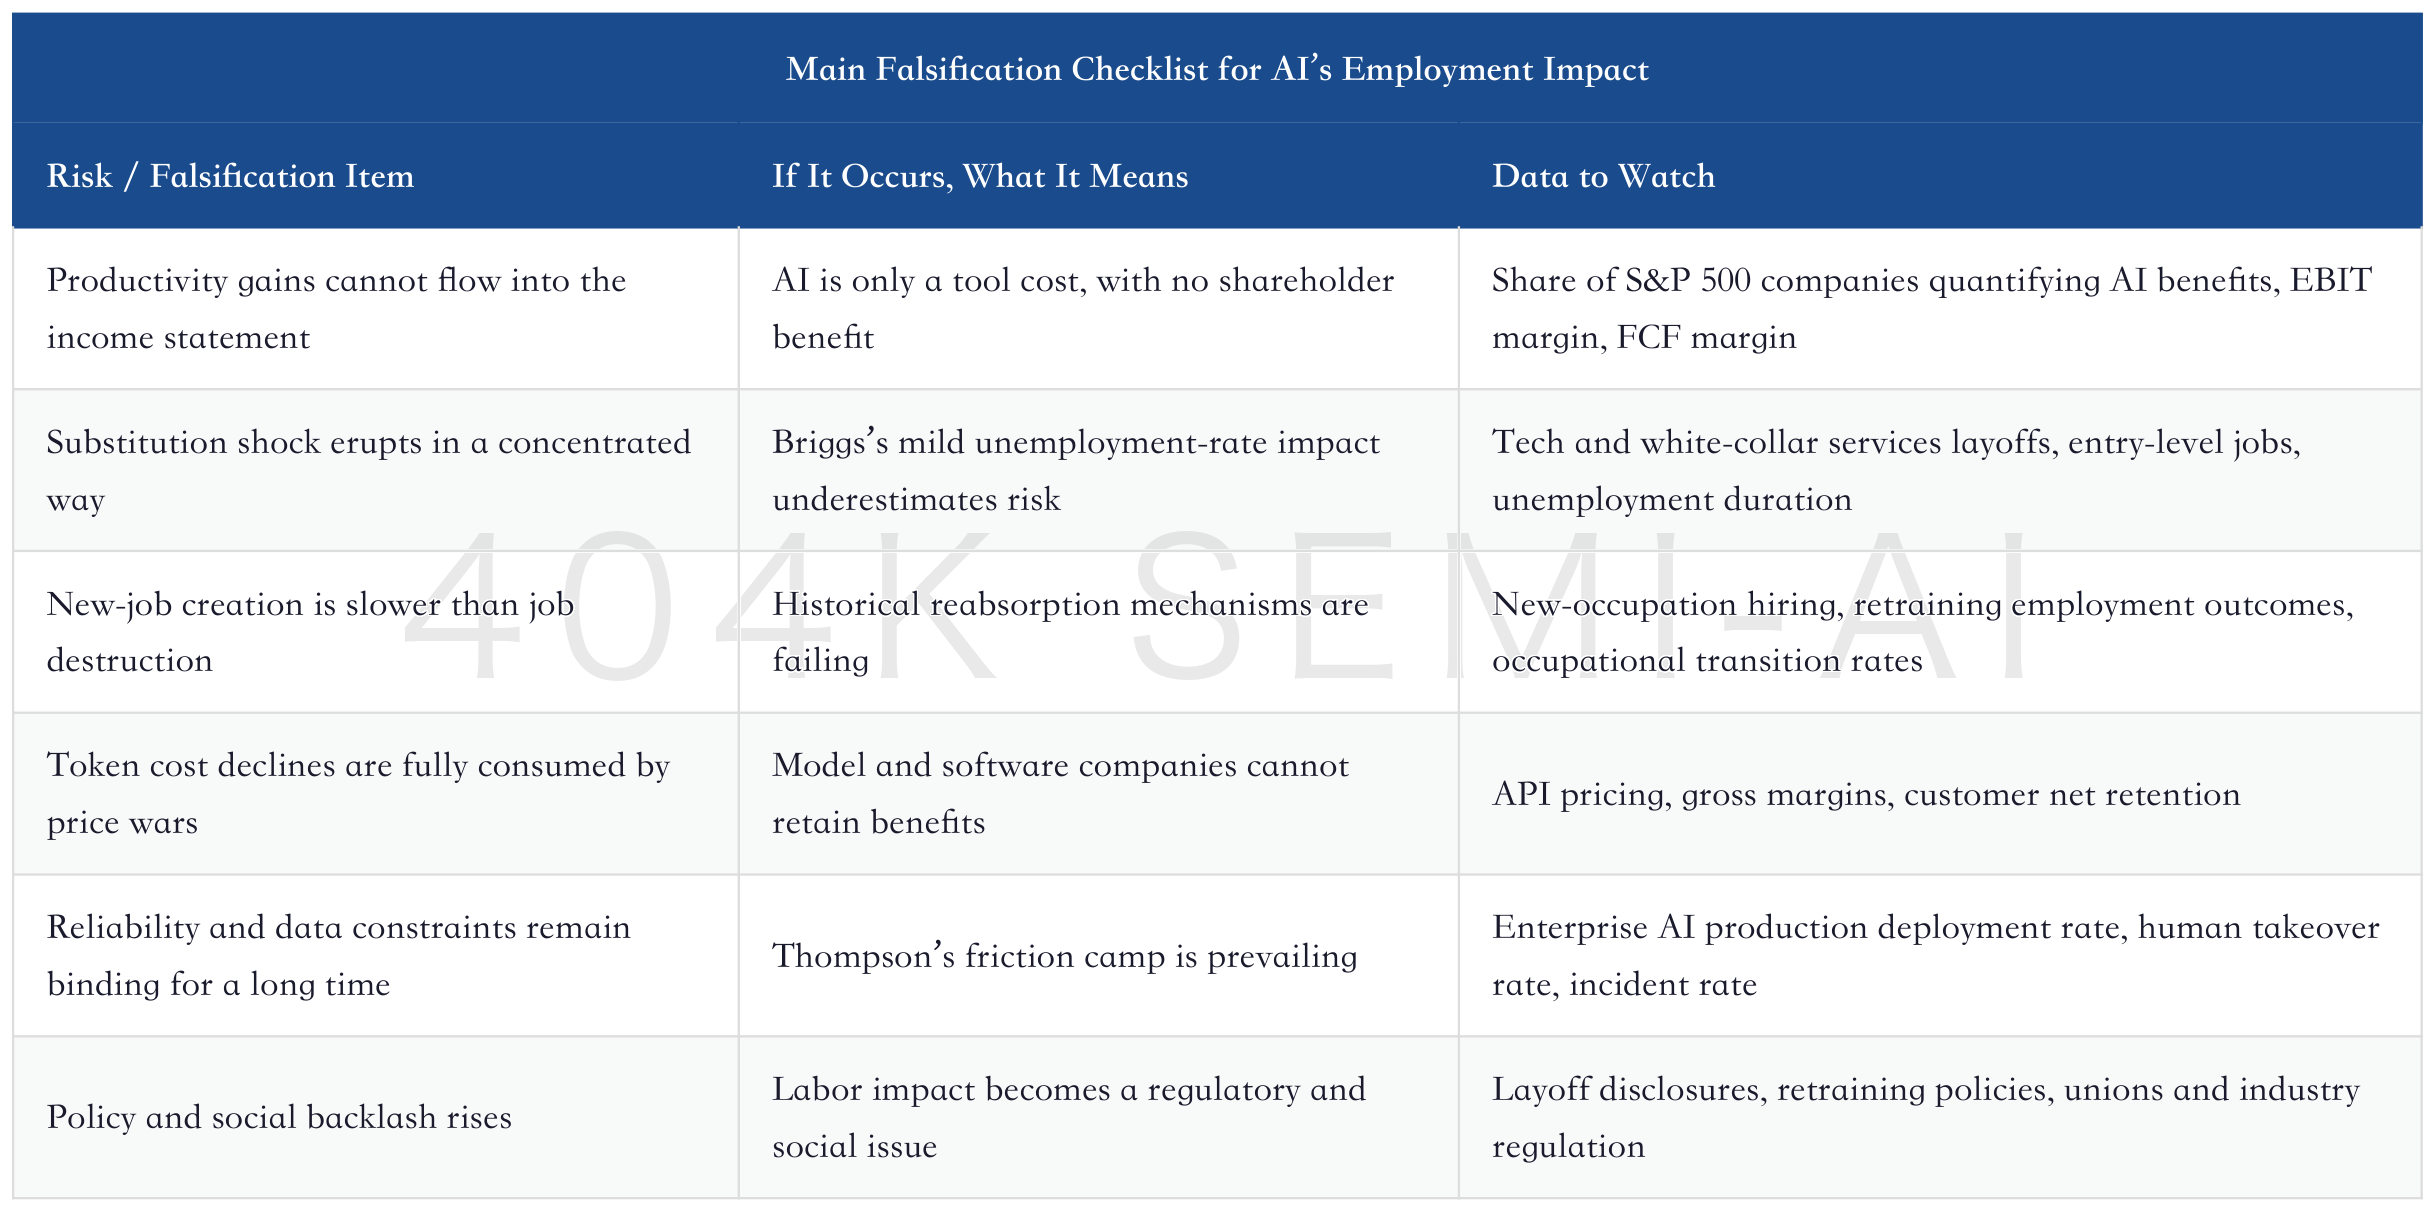
The judgment most worth preserving from this report is that AI’s labor impact is likely not a straight line, but a set of simultaneous divergences. Some jobs will be replaced, some workers will be augmented, some companies will retain profits, some companies will be forced to pass benefits through, some industries will see new demand, and some groups will bear higher transition costs. In investing, trading on a single macro conclusion can easily miss the real dispersion.
XIII. Indicators to Watch Over the Next Four Quarters
To judge whether AI is moving from a “tools boom” into a “jobs and profit reallocation” phase, the best approach is not to track individual layoff headlines, but to monitor a set of indicators that can be updated quarterly.
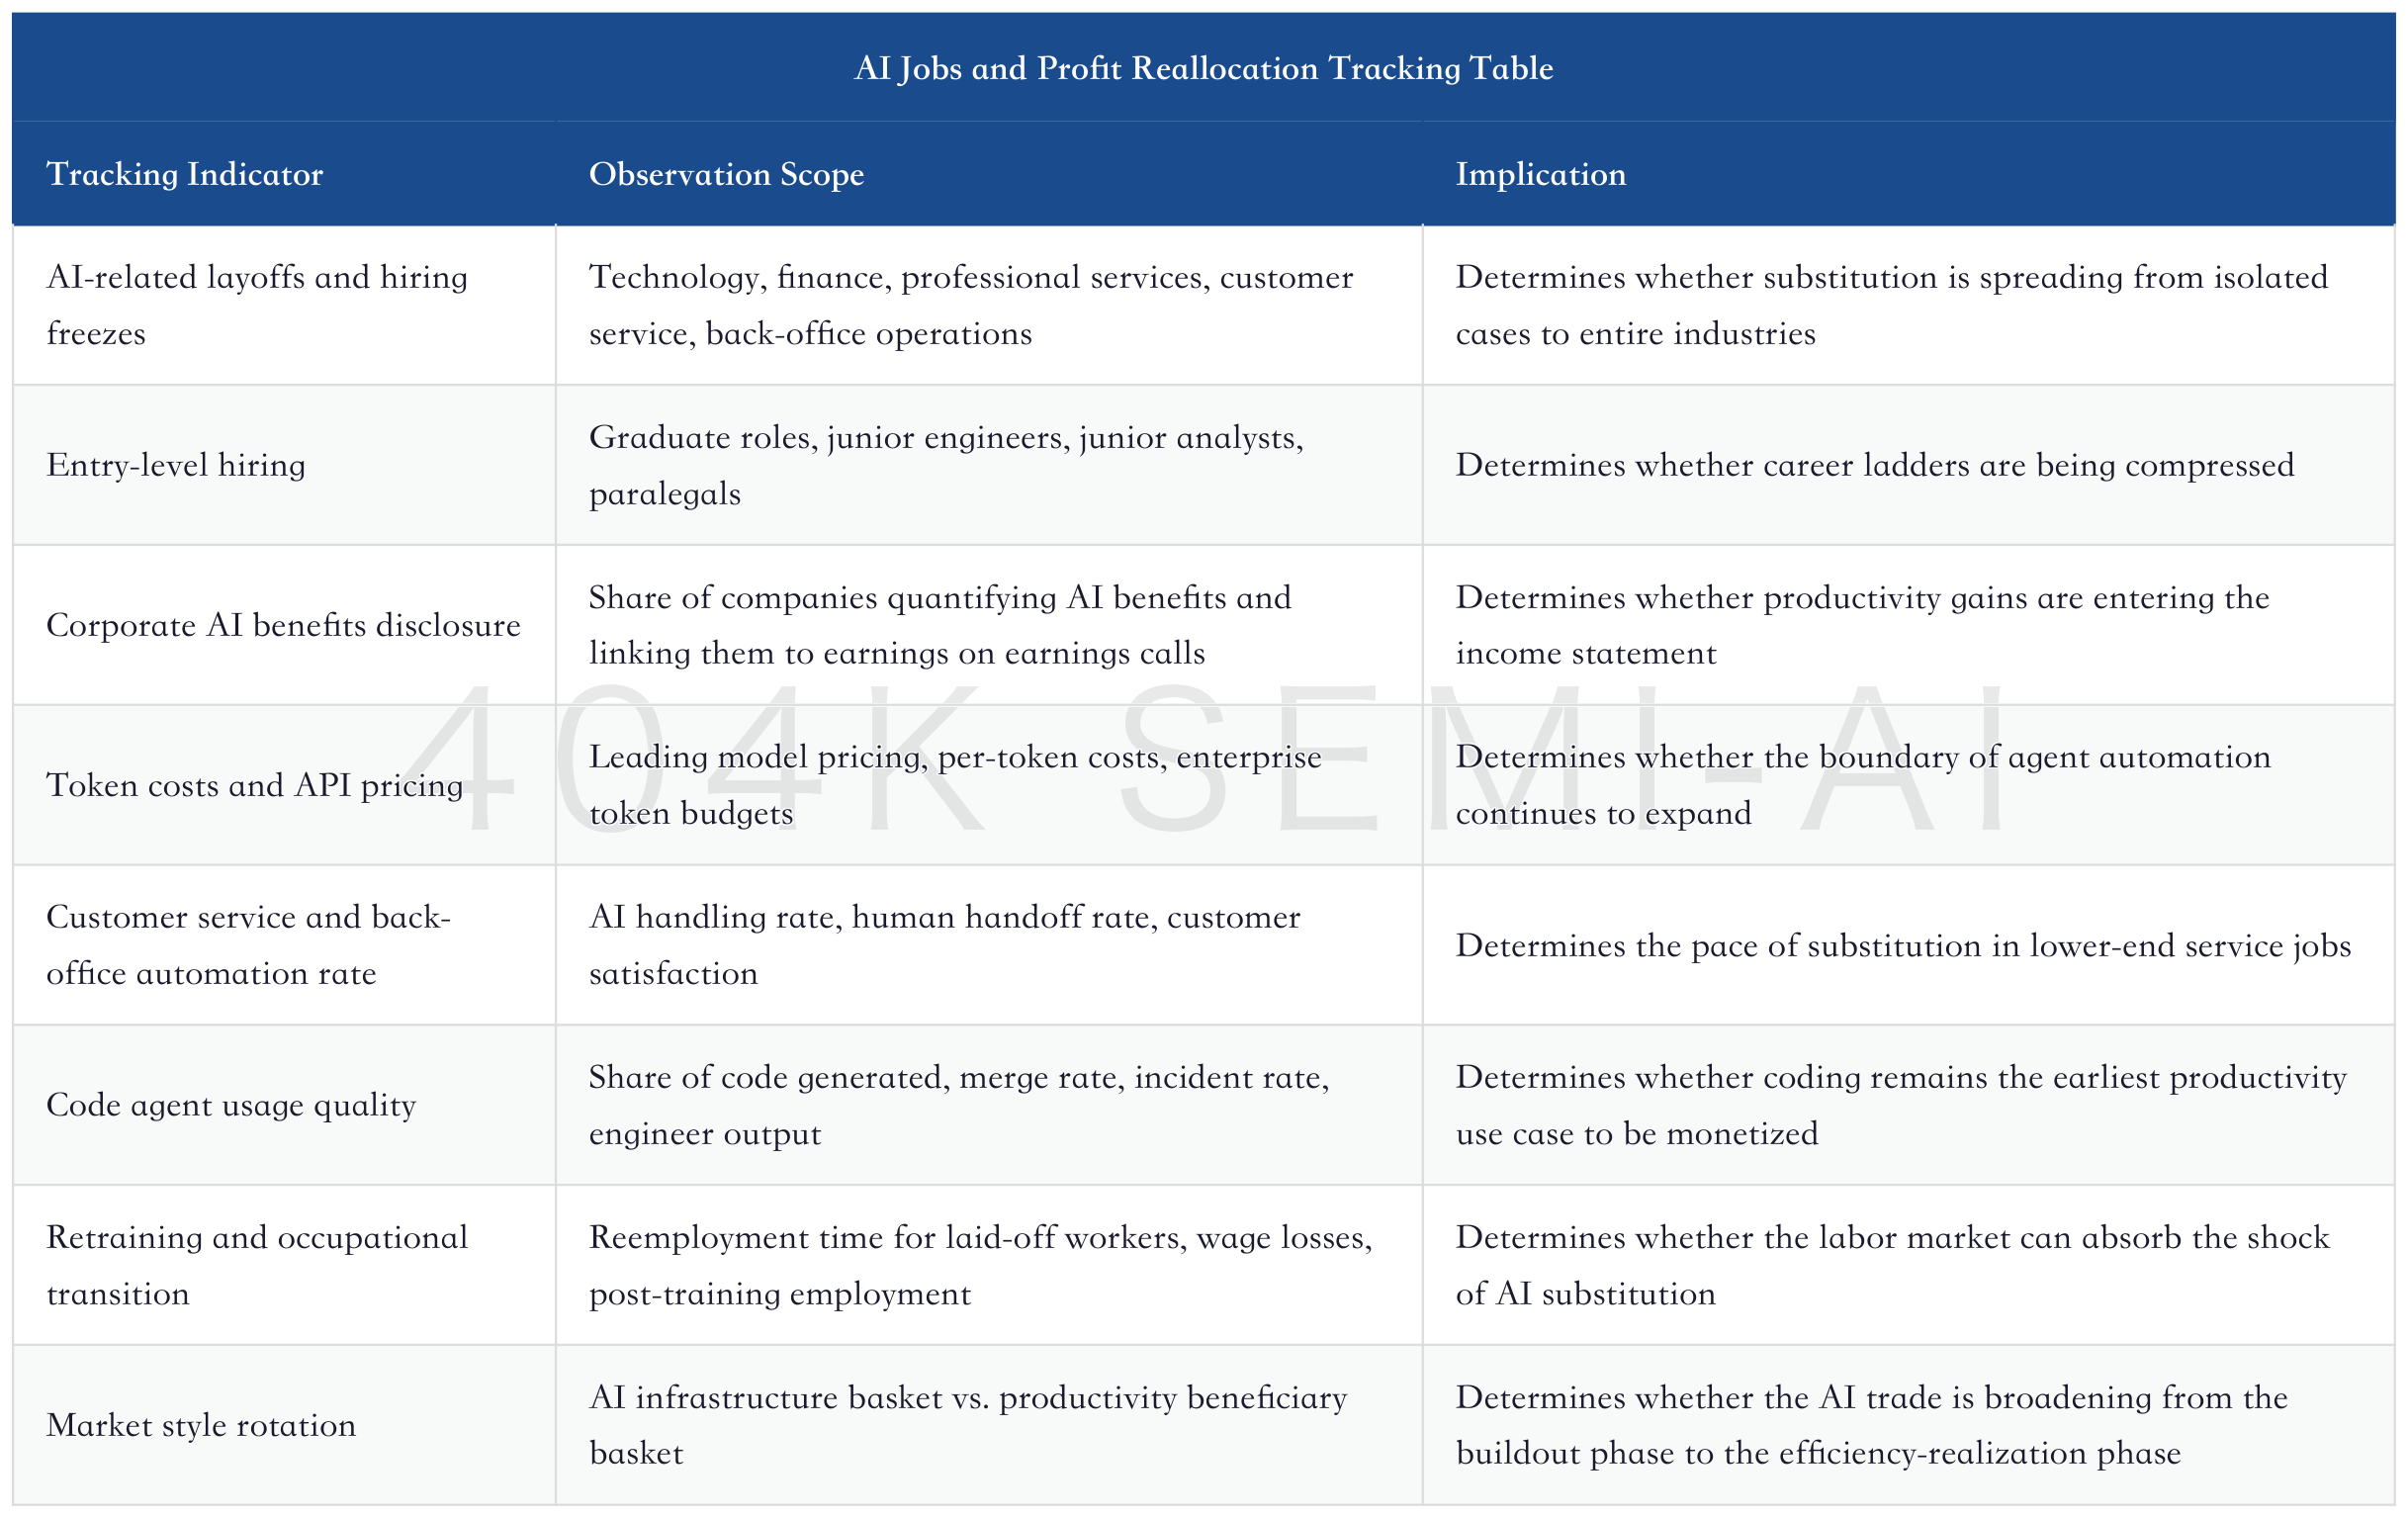
In the near term, the most important indicator is corporate AI benefits disclosure. If 54% of companies discuss AI but only 2% link benefits to earnings, the market will continue to favor infrastructure. If the share of quantified benefits and profit attribution rises meaningfully over the next few quarters, productivity beneficiaries will have a stronger case for systematic re-rating.
The second key indicator is entry-level hiring. What AI most easily changes is the corporate decision that “we no longer need as many people starting from low-level tasks for training.” As long as graduate roles, junior engineers, junior analysts, customer service, and back-office positions continue to shrink, the labor market may accumulate social and political pressure even if aggregate employment remains stable.
The third key indicator is token costs and agent costs. Coding agents are already economical, while customer service and data entry are approaching the threshold. Each step-down in cost expands the automation radius, forcing another recalculation of enterprise organizational design.
XIV. Three Scenarios: Moderate Reallocation, White-Collar Compression, and Productivity Diffusion
The biggest risk in this kind of macro question is a single-path forecast. AI’s impact on employment is not a point estimate, but a probability shift across three scenarios. The base case can be relatively moderate, but markets do not trade the base case itself; they trade whether the base case is being overturned by new evidence.
The first scenario is moderate reallocation. AI substitutes for some tasks, but enterprise adoption is constrained by reliability, data access, process redesign, and organizational resistance. Job reductions unfold over a decade, and the labor market absorbs most of the shock through occupational transitions, new service demand, and new roles. This is closer to Briggs’s world, and it is the scenario equity markets can most easily accept: productivity rises, unemployment is only modestly disrupted, corporate margins improve, and social friction remains manageable.
The second scenario is white-collar compression. AI rapidly matures in coding, customer service, back office, finance, legal, marketing, sales operations, and basic analysis, and companies use hiring freezes and organizational-layer compression instead of traditional layoffs. The headline unemployment rate may not surge immediately, but entry-level roles, low-wage white-collar workers, and outsourced services come under pressure first. The wage curve steepens, and middle management is compressed. This is the direction Acemoglu worries about more, and it is also the scenario in which lived social experience may feel worse than the macro data suggest.
The third scenario is productivity diffusion. AI does not merely substitute for labor; it creates many new jobs, new demands, and new business models. Companies reduce costs while expanding revenue, and workers use AI tools to raise output and share part of the gains. This is the long-term scenario the market most wants to buy, but it requires more evidence: not just model capability, but enterprise process redesign, customer willingness to pay, profit retention, and growth in new roles.
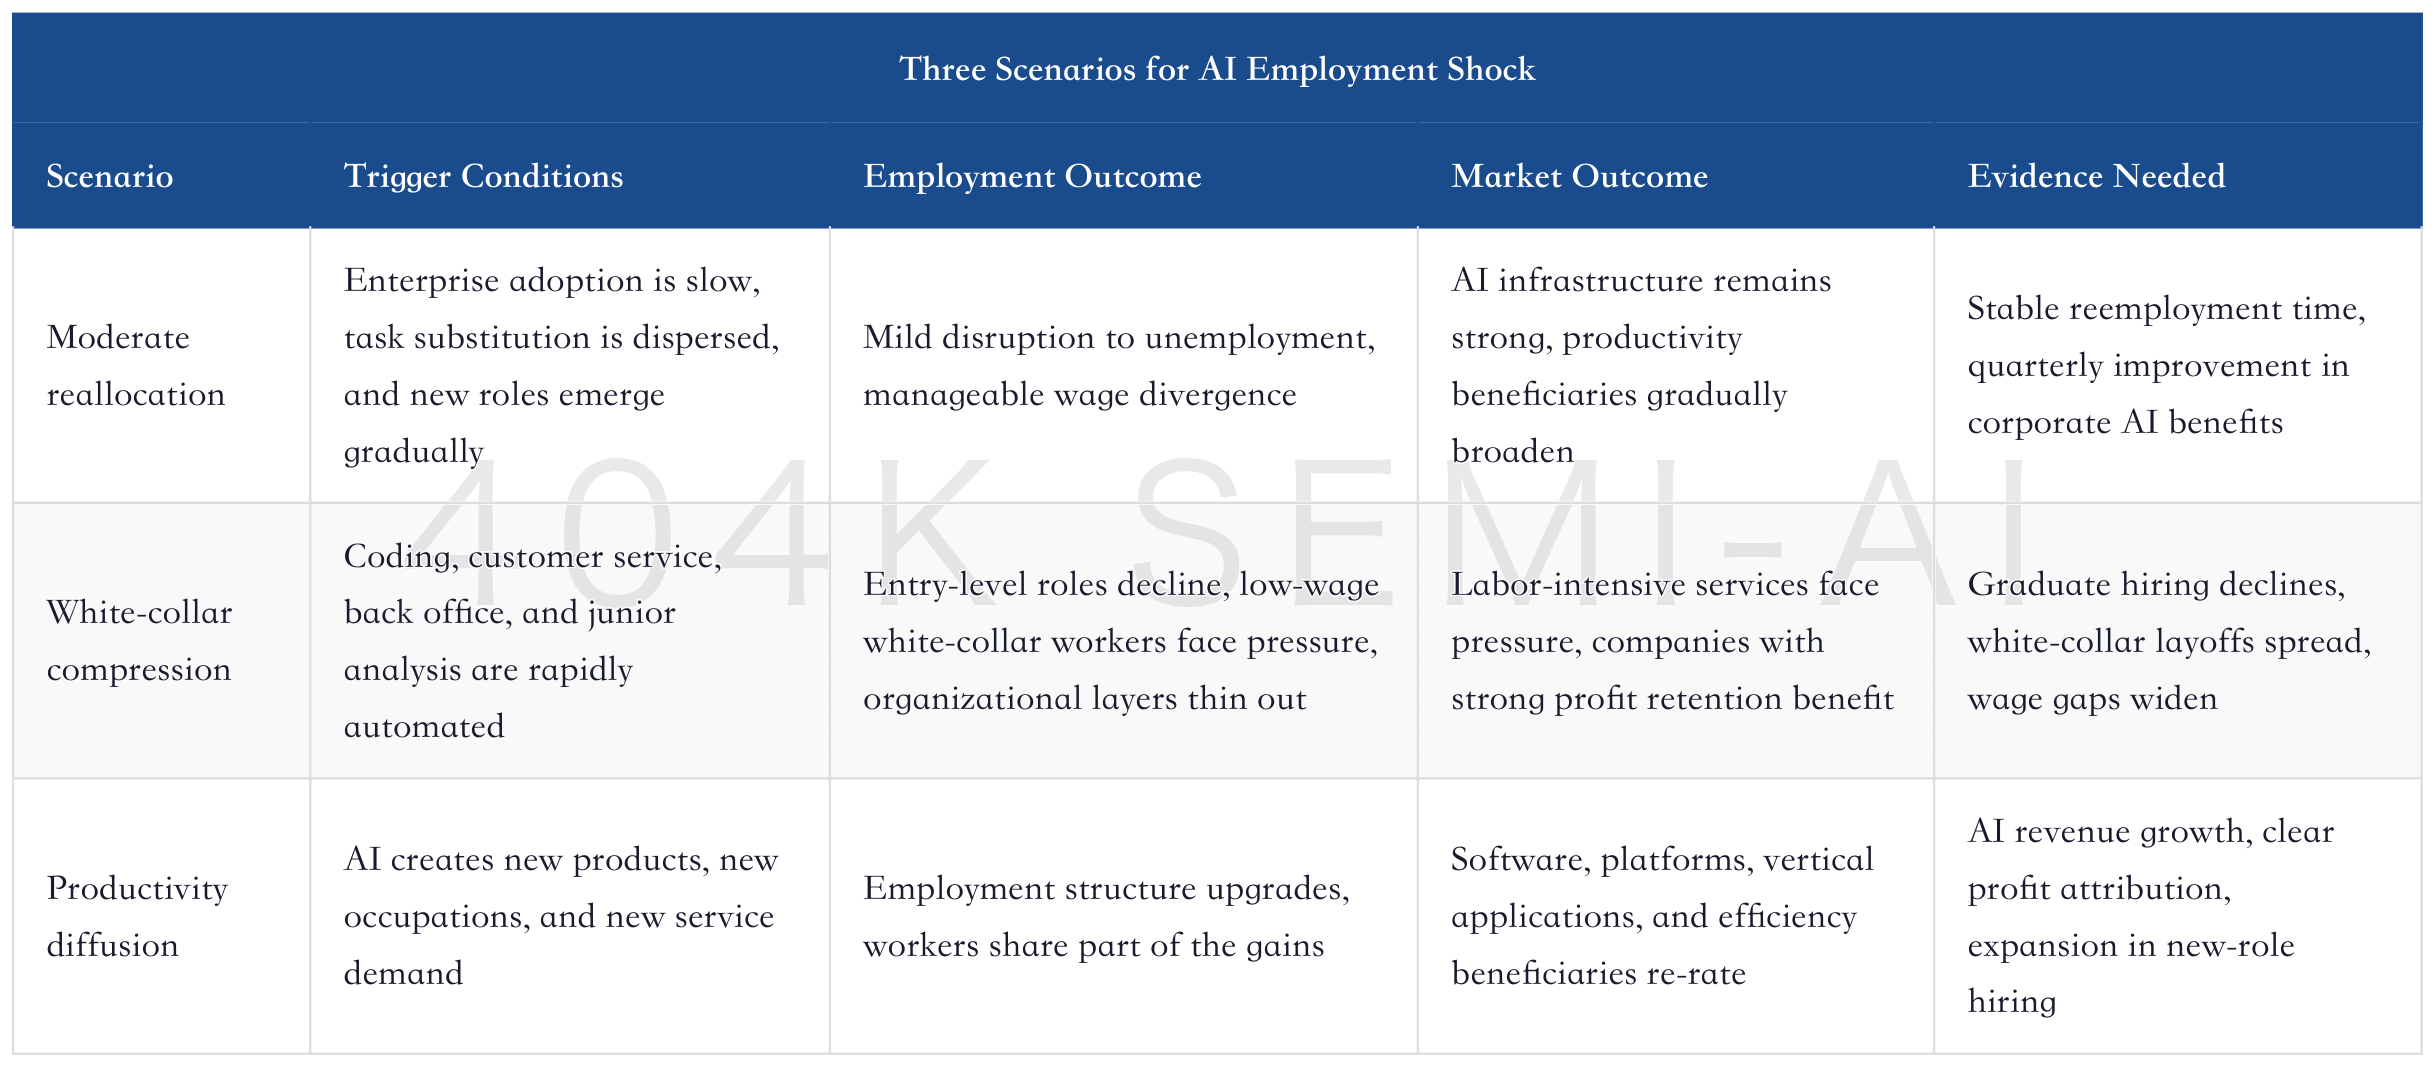
These three scenarios are not mutually exclusive. Over the next few years, all three may occur at the same time: white-collar compression in coding and customer service, productivity diffusion in healthcare, education, and professional services, and moderate reallocation in other industries. The real investment question is which scenario dominates within a given industry, company, or asset class.
For example, software development tools are already closer to a coexistence of white-collar compression and productivity diffusion. AI can materially increase engineer output, and companies may reduce low-level coding roles, but they may also undertake more software projects as development costs fall. Customer service outsourcing leans more toward white-collar compression because the substitution path is clear and incremental demand is limited. Healthcare, research, and complex engineering lean more toward productivity diffusion because AI can help experts expand their capacity, while responsibility, regulation, and on-site execution still require humans.
