
目录
Contents
1. What Going Mainstream Means: The Core Thesis Behind the RMB88 Price Target
2. Where the Business Model’s Upside Comes From: Capacity, Yield, Pricing, and Product Mix
III. How AI Is Reshaping the DRAM Cycle: Servers Take Priority as HBM Absorbs More Wafers
IV. The True State of Technology Catch-Up: GEN4B Is in Production, While GEN5 and HBM Still Require Validation
V. Why the Financial Model Is So Steep: Revenue Surges as the Asset Burden Rises
VI. Can the Valuation Premium Hold? How Much Optimism Is Embedded in RMB 88?
VII. Conclusion and Monitoring Framework: Eight Verifiable Metrics
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
CXMT has joined the ranks of mainstream DRAM suppliers, but the RMB88 price target simultaneously assumes elevated pricing, smooth capacity expansion, and successful technology upgrades. The operating inflection is underway; the valuation still demands more exacting proof.
Contents
[What Going Mainstream Means: The Core Thesis Behind the RMB88 Price Target](#一主流化意味着什么88元目标价背后的核心判断)
[Where the Business Model’s Upside Comes From: Capacity, Yield, Pricing, and Product Mix](#二商业模式的增量来自哪里产能良率价格和产品结构)
[How AI Is Reshaping the DRAM Cycle: Server Prioritization and HBM’s Growing Wafer Demand](#三ai如何改变dram周期服务器优先hbm吃掉更多晶圆)
[The Reality of Technology Catch-Up: GEN4B Is in Production, While GEN5 and HBM Still Need Validation](#四技术追赶的真实位置gen4b已落地gen5与hbm仍待验证)
[Why the Financial Model Is So Steep: Surging Revenue Alongside a Growing Asset Burden](#五财务模型为何如此陡峭收入跃升与资产负担同时发生)
[Can the Valuation Premium Hold? How Much Optimism Is Embedded in RMB88](#六估值溢价能否站住88元包含了多少乐观假设)
[Conclusion and Monitoring Framework: Eight Verifiable Metrics](#七结论与跟踪框架把故事拆成八个可验证数字)
1. What Going Mainstream Means: The Core Thesis Behind the RMB88 Price Target
Morgan Stanley initiated coverage of CXMT with an Overweight rating and an RMB88 price target in a report published on August 26, 2026. The target implied approximately 55.8% upside from the August 25 reference price of RMB56.50. The valuation is striking, but the more important point is the report’s redefinition of the company: CXMT has evolved from a regional import-substitution supplier into the world’s fourth-largest DRAM manufacturer and is expected to gain further share over the next several years through capacity expansion, DDR5 adoption, and AI-driven memory upgrades.
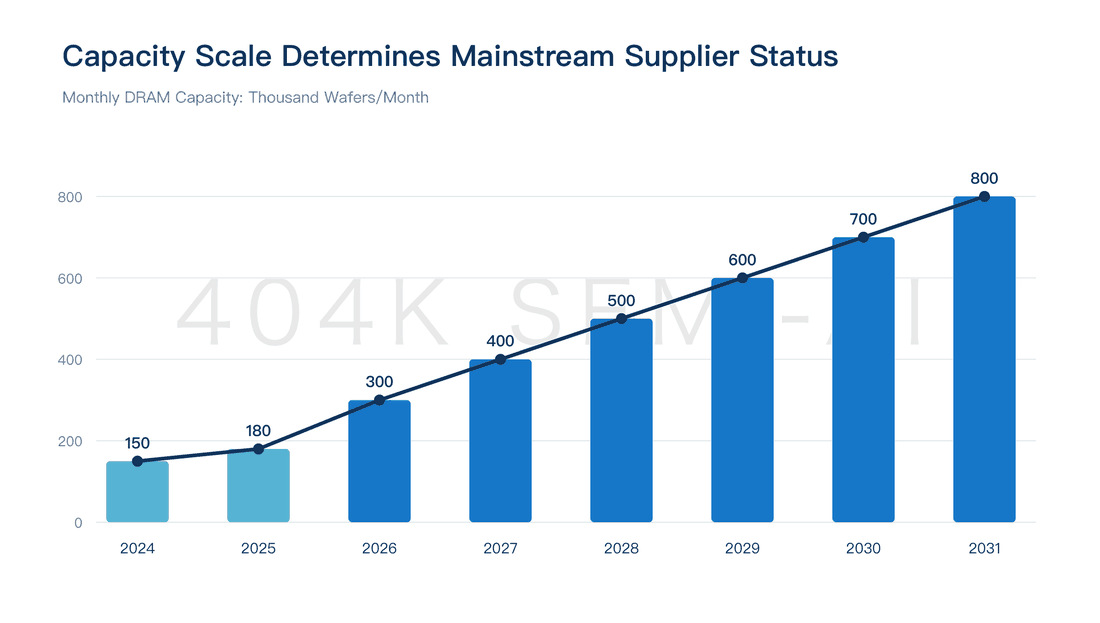
Going mainstream has at least three dimensions. The first is scale. CXMT’s monthly DRAM wafer capacity was approximately 180,000 wafers in 2025; the model forecasts 300,000 in 2026, 500,000 in 2028, and 800,000 in 2031. Once capacity crosses a critical threshold, customer coverage, supply reliability, procurement leverage, and R&D; absorption all improve, enabling the company to serve large customers on a sustained basis.
The second dimension is product capability. Import-substitution credentials in the DDR4 era do not establish competitiveness in advanced products; qualifications and volume production in DDR5, LPDDR5X, server DRAM, and HBM will determine whether CXMT can enter higher-value markets. The report cites maximum speeds of DDR5 8000Mbps and LPDDR5X 10667Mbps, and assumes that CXMT’s HBM portfolio will progress from HBM2E in 2026 to 12-high HBM3E in 2027 and HBM4 in 2028. The roadmap now covers the industry’s mainstream directions, but production yields, supply consistency, and customer adoption remain the key validation points.
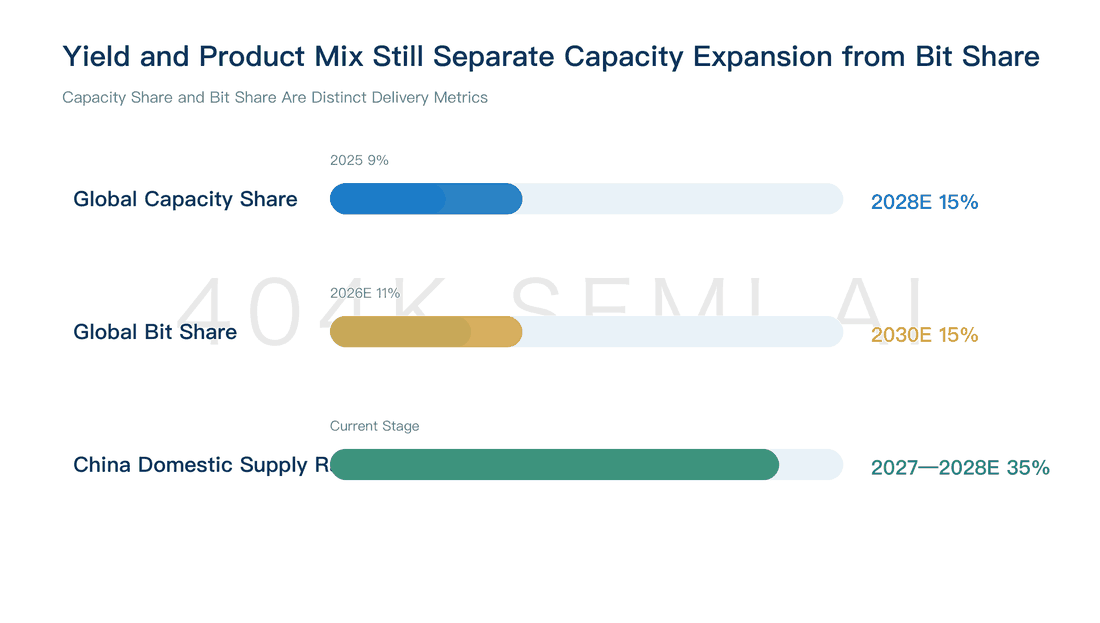
The third dimension is market share. The report estimates that CXMT reached a 7.67% share of global DRAM revenue in the fourth quarter of 2025, while its share of global capacity could increase from 9% in 2025 to 15% in 2028. The company already has visible market influence, but capacity share, bit share, and revenue share are not interchangeable. Process density, yield, product pricing, and the mix of higher-value products all affect the effective bits and revenue generated per wafer.
Industry ranking must also be assessed against the profit pool. Mature products can lift revenue share quickly, but advanced processes, server DRAM, and HBM are more likely to generate high margins. If CXMT expands primarily through mature products, its share gains will still be real, but earnings quality will be lower than under a scenario in which advanced products scale in parallel. Revenue share, bit share, and higher-value product share therefore require separate validation.
Supplier scale also influences customer decisions. Large customers generally require a second source to offer sufficient capacity, a sustained quality record, through-cycle delivery capability, and long-term service resources. CXMT’s capacity expansion can reduce onboarding risk, which in turn helps it secure a larger share of customer procurement. Once established, this positive feedback loop can make market-share gains more durable than equipment additions alone. Conversely, any disruption to quality or delivery could prompt customers to reduce procurement allocations rapidly.
This distinction captures the central tension in the price target. There is substantial evidence that CXMT has become a mainstream supplier, but the earnings quality and technological capabilities of a global leader still require time to prove. The report derives its base-case RMB88 price target from 18.5x forecast 2027 earnings. By comparison, diversified semiconductor manufacturers globally and in Greater China traded at an average valuation of approximately 4.4x, while Greater China DRAM peers averaged approximately 14.8x. The market is already paying a growth premium, making future returns dependent on execution; fourth-largest DRAM producer status alone is unlikely to sustain that premium.
The operating and valuation conclusions should therefore be separated. The operating transformation has already occurred: scale, product breadth, and the customer base have all advanced materially. The valuation remains a forecast: RMB88 requires CXMT to expand capacity smoothly during a strong pricing cycle, increase the contribution from advanced processes and HBM, and sustain margins far above historical levels. The former establishes the research case; the latter defines the validation checklist for the coming quarters.
2. Where the Business Model’s Upside Comes From: Capacity, Yield, Pricing, and Product Mix
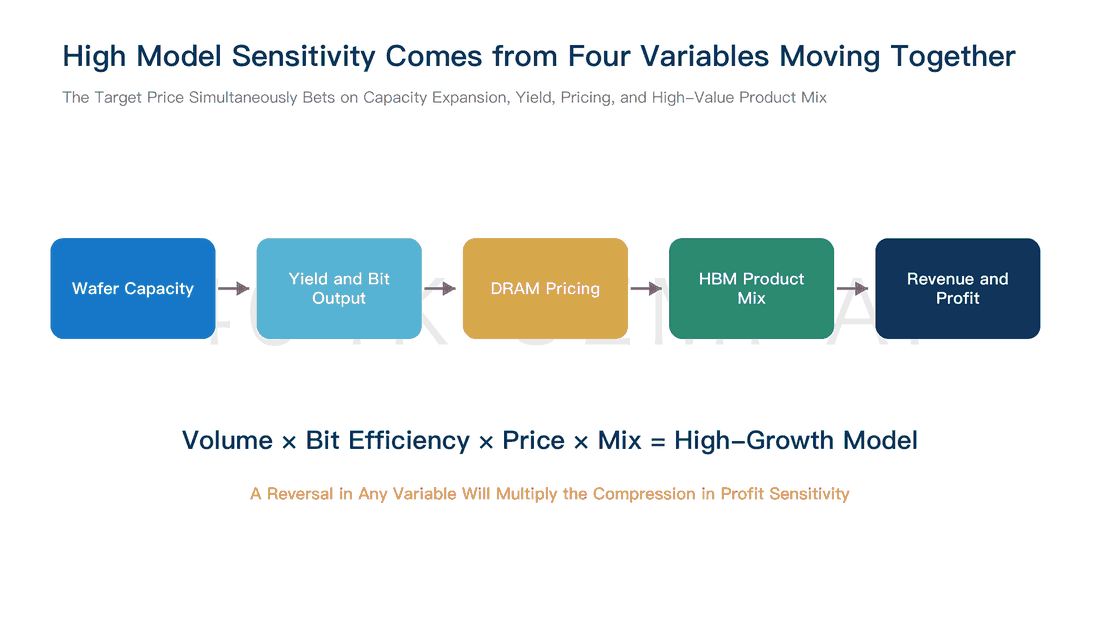
A DRAM manufacturer’s revenue can be decomposed into four variables: usable wafer capacity, effective bits per wafer, selling price per bit, and product mix. CXMT’s growth thesis is compelling because all four could improve simultaneously. That also makes the model highly convex: if any one element falls short, revenue and earnings can diverge rapidly from the base-case forecast.
Capacity is the most visible growth driver. CXMT’s monthly capacity increased from 150,000 wafers in 2024 to 180,000 in 2025 and is forecast to jump to 300,000 in 2026, followed by annual additions of approximately 100,000 wafers until capacity reaches 800,000 in 2031. The 2026 increase is particularly large, requiring fab construction, equipment installation, workforce deployment, process ramp-up, and customer deliveries to proceed concurrently within a compressed timeframe. A “completed” fab proves only that the physical space exists; equipment move-in and production start merely mark the beginning of the ramp. Revenue is generated only when yields stabilize and saleable bits emerge.
Yield and bit density determine effective supply. The report identifies GEN4B, with a line width of approximately 16nm, as the principal near-term process. Channel checks indicate that yields have exceeded 80%, with some evidence pointing to even higher levels. Because these figures are not part of a consistently disclosed company time series, they are best treated as directional evidence. Raising yield from 70% to 85% can materially expand saleable bits without increasing nominal wafer capacity. A stalled yield ramp, by contrast, simultaneously raises unit costs, delays qualification, and consumes additional equipment time.
Pricing amplifies earnings sensitivity. The DRAM cycles reviewed in the report show that revenue has fallen by 34% to 77% during downturns, while average selling prices have declined by 41% to 95%. Memory is standardized and inventory-sensitive, with supply adjustments occurring only after a lag. When prices rise, a large portion of incremental revenue can convert into profit; when prices fall, fixed costs and depreciation cannot decline in tandem, causing earnings to contract faster than revenue. At the report date, the current upcycle had lasted approximately 11 months—still far from any historically supported “safe zone.” Short-term elevated pricing should not be mechanically extrapolated across the full valuation horizon.
Contract structures affect the speed of price transmission. Server customers and customers covered by long-term agreements generally provide more stable procurement plans, but their pricing resets differ from the spot market. Consumer-electronics customers are more cost-sensitive and may offset price increases by delaying purchases or reducing memory content per device. A mix shift toward servers can mitigate short-term volatility, while increasing dependence on a limited number of large customers and annual price negotiations.
Product mix determines whether scale translates into higher value per unit. As DDR5 and LPDDR5X penetrate PCs, servers, and premium smartphones, average selling prices and customer stickiness are generally higher than for mature specifications. Server DRAM and HBM impose additional barriers involving quality, qualification, packaging coordination, and supply reliability. CXMT’s expansion into these markets can improve average selling prices and gross margins, but it also raises the difficulty of R&D;, validation, and yield management. Higher-value products must progress through five stages—technical viability, customer sampling, qualification, volume procurement, and sustained delivery—before their revenue contribution increases. Product-launch announcements are no substitute for actual purchasing.
The customer mix provides demand stability but also creates concentration risk. CXMT’s five largest customers accounted for 74.1%, 67.3%, and 68.1% of revenue in 2023, 2024, and 2025, respectively. Concentration has declined from its earlier peak but remains high. Large customers can help suppliers scale shipments quickly, establish quality-feedback loops, and achieve economies of scale. However, a major customer’s decision to change procurement allocations, delay a product transition, or push down prices could materially affect utilization.
R&D; spending shows that CXMT is investing to close the gap in advanced products. R&D; expenditure was approximately RMB4.7 billion, RMB6.3 billion, and RMB9.6 billion from 2023 through 2025, respectively, totaling approximately RMB20.6 billion over three years—equivalent to 21.7% of cumulative revenue during the period.
In 2025, CXMT employed 6,259 R&D; personnel, representing 32.4% of its workforce, and held 3,929 domestic patents and 3,043 overseas patents. Sustained investment raises the probability of successful catch-up but does not automatically translate into process leadership. Memory competition ultimately turns on cost per bit, yield, reliability, customer qualification, and iteration speed; patent count is only one supporting factor.
