
目录
Executive Summary
The End of the Share-Price Correction Does Not Mean the Industry Crisis Is Over
At a $1.83 Trillion TAM, Pricing Is the First Variable to Deconstruct
Why Configuration Cuts Have Not Ended the Shortage
Why Record Capital Expenditure Still Does Not Deliver Enough Wafers
DRAM, HBM, and NAND: One Crisis, Three Different Curves
LTAs and Shareholder Returns Determine Whether Earnings Can Be Capitalized
The Biggest Ceiling: Memory Is Consuming Customer Budgets
What Makes This Cycle Different: Four Gates Beyond Inventory
Three Worldviews: The Same Data Support Different Valuations
Substantial Valuation Upside, but Not Price Targets
Six Disconfirming Signals to Watch Over the Next Four Quarters
Conclusion: The Real Inflection Point Is When Effective Supply Outgrows Demand, Not When Price Increases Slow
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
J.P. Morgan has raised its 2026–2028 global memory total addressable market (TAM) forecasts by another 4%–8%. Memory stocks have corrected 25%, but wafer capacity, long-term agreements, and AI-server demand indicate that the industry’s supply crisis is far from over.
Executive Summary
Share prices and industry fundamentals are running on two different clocks: Major memory stocks have fallen about 25% quarter-to-date in Q3 2026, yet effective supply of DRAM, high-bandwidth memory (HBM), and NAND remains constrained by wafer capacity, advanced processes, packaging, yields, and qualification.
J.P. Morgan has raised its combined DRAM and NAND revenue forecasts for 2026–2028 to $970.9 billion, $1.4417 trillion, and $1.8262 trillion, respectively—4%, 6%, and 8% above its May model. Per-device memory content has generally been revised down; the upgrades are driven primarily by pricing power, server shipments, and product mix, not uniformly stronger end demand.
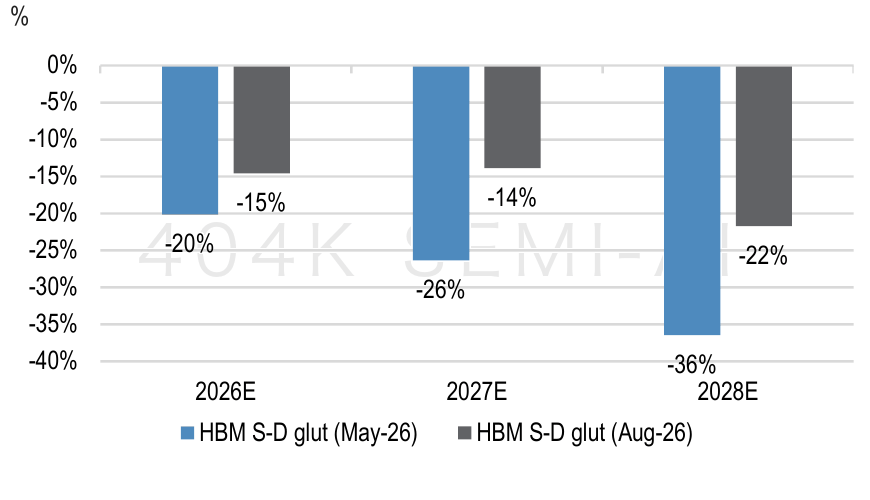
Configuration cuts are a genuine negative. Vera CPU SOCAMM capacity has been reduced from 1.5TB to 768GB, while the Rubin family has also cut HBM stack counts and capacity. Even after lowering 2026–2028 HBM bit-demand estimates by 4%–19%, the new model still projects consecutive shortages of 15%, 14%, and 22%.
Record capital expenditure currently looks more like bottleneck relief than a prelude to oversupply. Closing the modeled gap by 2028 would still require approximately 299,000 additional DRAM wafers per month and 44,000 NAND wafers per month. Producing the same number of HBM bits also consumes approximately 3–4 times as many wafers as conventional DRAM.
DRAM and NAND are at different points in their cycles and should be assessed separately. DRAM’s cumulative shortfall is more likely to persist through 2028, while NAND inventories may begin rebuilding gradually after mid-2027; the model already assumes a 4% year-on-year decline in NAND average selling prices in 2028.
The greatest risk is customers’ ability to pay. Memory’s share of cloud-service-provider hardware capital expenditure is expected to rise from less than 10% before AI to 31% in 2026, 49% in 2027, and 60% in 2028. Unless total capital expenditure is revised upward, further configuration cuts, deployment delays, and migration toward lower-cost media will accelerate.
The End of the Share-Price Correction Does Not Mean the Industry Crisis Is Over
The market previously traded memory on one question: how much further can prices rise? The question has now shifted to how long such elevated pricing and profitability can last. According to J.P. Morgan, memory stocks have fallen about 25% quarter-to-date in Q3 2026 after outperforming the AI value chain for 4 consecutive quarters. Catalysts included near-term earnings disappointments, slower-than-expected AI capital expenditure by cloud-service providers, and deliberate configuration cuts in mainstream products such as SOCAMM and HBM.
The correction reflects a reset from expectations of outsized upgrades every quarter to a market requiring line-by-line validation. It does not, however, establish that supply and demand have reversed. Combined Q2 2026 cloud revenue at AWS, Microsoft Azure, and Google Cloud reached $106.0 billion, up 43% year on year versus 35% in the previous quarter and 23% a year earlier. Consensus 2026 and 2027 capital-expenditure forecasts for those three providers plus Meta have also risen by 6% and 17%, respectively. End-customer cash flow continues to expand, but memory prices are rising faster than customer budgets.
This also refines the assessment following the July roadshow. The central question was previously whether there was evidence that earnings could endure; this report adds wafer-capacity mapping, long-term agreements (LTAs), HBM specifications, and application-level supply-demand models. The five signals to watch after the memory correction can now be distilled into two: whether effective bit supply can grow faster than AI-server demand, and whether cloud-service providers can continue absorbing higher memory prices.
At a $1.83 Trillion TAM, Pricing Is the First Variable to Deconstruct
The global memory market was approximately $214.0 billion in 2025. J.P. Morgan expects it to surge to $970.9 billion in 2026 and then reach $1.4417 trillion in 2027 and $1.8262 trillion in 2028. DRAM is projected to contribute $634.1 billion, $982.9 billion, and $1.3103 trillion, respectively, while NAND contributes $336.8 billion, $458.7 billion, and $515.9 billion. HBM is included within DRAM and must not be added separately.
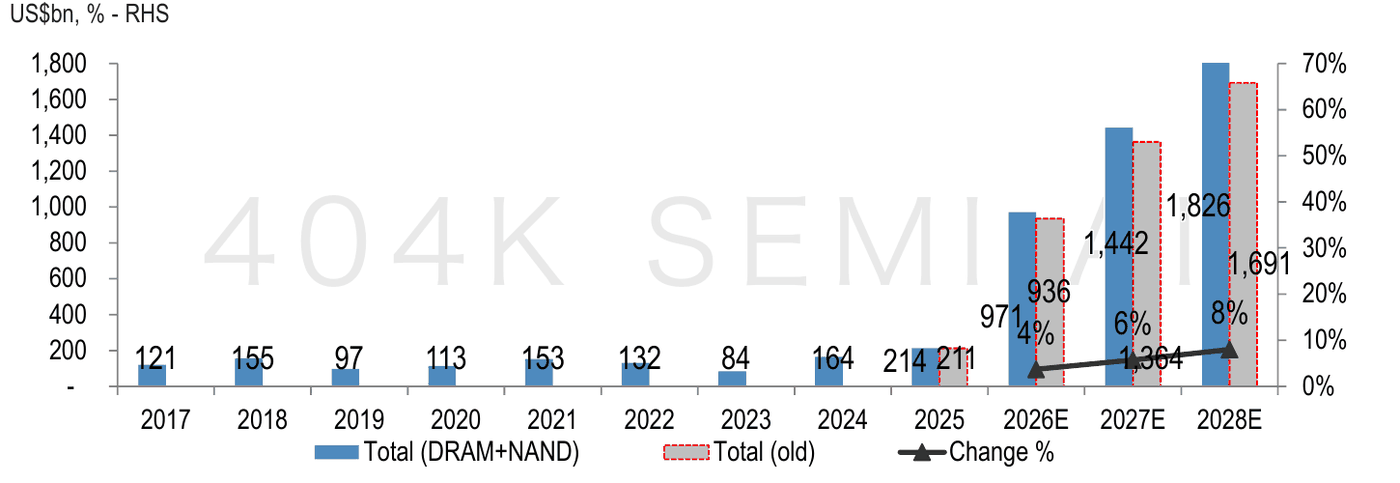
The key concern is that this step-change in market size is driven primarily by pricing rather than bit volumes. DRAM average selling prices are expected to rise 236% in 2026, followed by another 29% in 2027 and 7% in 2028. NAND prices are projected to increase 251% and 23% before declining 4% in 2028. Meanwhile, server DRAM content per system is 3%, 8%, and 8% below the previous model; smartphone DRAM content is 5%, 6%, and 10% lower; and NAND content per SSD is down 2%, 5%, and 8%. In other words, the report acknowledges customer configuration cuts while offsetting lost content through higher shipments and stronger pricing.
The $1.83 trillion estimate is therefore the output of a highly price-sensitive equation, not an end-state that merely awaits realization. If any two of server shipments, content per system, product mix, and average selling prices undershoot assumptions simultaneously, revenue would deviate materially from the model. Investors should look beyond the TAM upgrade and ask whether it reflects greater real bit consumption or simply the repricing of scarce bits at higher levels. The report’s answer clearly leans toward the latter.
Why Configuration Cuts Have Not Ended the Shortage
Vera CPU SOCAMM capacity has been reduced from 1.5TB to 768GB. Rubin Ultra has shifted from a 16-layer HBM4E configuration to 8-layer or 12-layer alternatives, while Rubin also offers lower-capacity 288GB and 192GB configurations. J.P. Morgan has therefore reduced its HBM bit-demand forecasts by 4%, 10%, and 19% for 2026, 2027, and 2028, respectively, assuming that 70% of Rubin and Rubin Ultra SKUs adopt the reduced specifications.
Even so, after adjusting for effective CoWoS supply, HBM shortages remain at 15%, 14%, and 22%. Configuration cuts reflect customers reallocating scarce capacity under supply constraints; they do not mean demand has disappeared. Reducing memory per GPU enables more GPUs, CPUs, or ASICs to be delivered, while inference workloads—including longer contexts, KV Cache, and agentic tasks—spread demand across conventional DRAM, enterprise SSDs (eSSD), high-bandwidth flash (HBF), and Compute Express Link (CXL) memory pools.
This shift from scale-up to scale-out has a clear falsification condition: chip-unit growth must continue to outpace the decline in memory capacity per chip. If power constraints, rack-assembly bottlenecks, or data-center commissioning delays also force downward revisions to GPU and server shipments, configuration cuts would no longer represent rationing; they would become genuine demand contraction. The report does not dismiss this risk, but argues that current cloud revenue, ASIC demand, and AI CPU growth remain sufficient to offset it.
Why Record Capital Expenditure Still Does Not Deliver Enough Wafers
DRAM capital expenditure is projected to rise from $59.2 billion in 2025 to $99.8 billion in 2026, $144.3 billion in 2027, and $154.6 billion in 2028. These are extraordinary absolute figures, yet capital expenditure as a share of DRAM revenue falls from approximately 42% in 2025 to 16%, 15%, and 12%. Manufacturers are not underinvesting; revenue and pricing are simply rising faster, while each $1 of capital expenditure is generating fewer incremental bits.
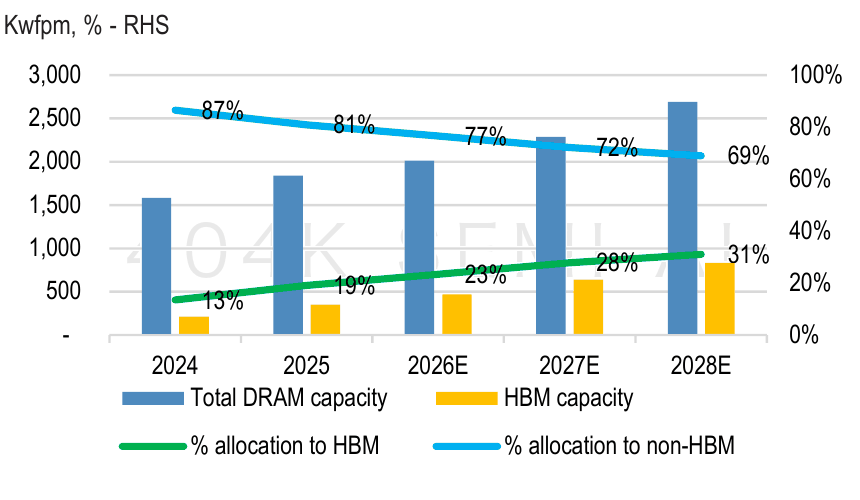
Supply efficiency is deteriorating for three reasons. First, a new wafer fab typically takes 2–2.5 years from groundbreaking to mass production, while capital expenditure reaches bit supply with a 12–18-month lag. Second, advanced processes require more EUV layers and more expensive equipment, while fabs, power availability, and cleanrooms face physical constraints. Third, HBM carries an approximately 3–4 times bit penalty: producing the same number of bits requires approximately 3–4 times as many wafers as conventional DRAM. HBM’s share of DRAM wafer allocation is expected to rise from 19% in 2025 to 31% in 2028, continuously displacing conventional DRAM.
The report estimates that balancing DRAM supply and demand in 2028 would require another 5.5EB of effective supply, equivalent to $58.0 billion of incremental capital expenditure—41% above the current 2027 forecast—and approximately 299,000 additional wafers per month. NAND would require another 76EB of supply, $7.0 billion of capital expenditure, and approximately 44,000 additional wafers per month. Existing monthly DRAM capacity is projected to rise from 1.955 million wafers in Q1 2026 to 2.845 million in Q4 2028, yet still would not organically close the cumulative shortfall.
Whether capacity expansion is bullish or bearish therefore cannot be judged by expenditure alone. As long as incremental effective bit supply remains below demand, expansion is relieving bottlenecks. The same capital expenditure will become a cyclical peak signal only when new fabs ramp, process migrations occur, HBM capacity shifts back to conventional DRAM, and supply growth begins to exceed server demand.
DRAM, HBM, and NAND: One Crisis, Three Different Curves
The core DRAM story is a structural shift in servers. Servers’ share of DRAM bit demand rises from 39% in 2025 to 56% in 2026, 67% in 2027, and 74% in 2028, while the shares of PC and mobile DRAM continue to decline. Server bit demand is expected to grow 83%, 59%, and 39% in 2026-2028, respectively, forcing conventional server memory and HBM to compete for wafers. The report therefore expects DRAM price increases to continue through 2028, though the pace slows from 236% in 2026 to 29% and 7%.
HBM pricing and market share are jointly determined by performance, qualification, and customer mix—not simply the severity of shortages. Blended average selling prices are expected to rise 42% in 2027, including 30%-40% increases for same-generation products and an approximately 20% generational premium for HBM4E over HBM4. Nvidia demand has been revised down, but higher AMD and ASIC demand lifts projected HBM industry revenue for 2027-2028 by 13% and 12% versus the previous model. Samsung Electronics’ HBM sales share is expected to reach 37%-38% in 2027-2028. The report’s near-term preference for Samsung Electronics over SK hynix is effectively a bet on customer qualification and an ASIC share recovery, rather than simply on aggregate HBM volume.
NAND begins normalizing earlier. Enterprise SSD demand is expected to grow 82%, 58%, and 37% in 2026-2028, respectively, while client SSD and smartphone demand remains weak. On a WSTS consumption basis, NAND inventory may decline from 7.2 weeks at end-2025 to 0.3 weeks in 2Q27 before recovering to 2.1 weeks by end-2028; average selling prices also turn negative, falling 4% in 2028. Yangtze Memory Technologies’ bits per wafer are already approaching those of industry leaders, while both its capacity and bit share are expected to reach approximately 16% in 2028, further increasing the risk of a longer-term NAND surplus.
LTAs and Shareholder Returns Determine Whether Earnings Can Be Capitalized
LTAs disclosed in 2Q26 show that prepayments account for approximately 20%-25% of contract value and are expected to cover 50%-70% of sales volume. Server, cloud-service-provider, and AI-related products represent more than 70% of contracted bit demand and more than 85% of revenue, while commanding a 30%-40% price premium over other applications. These terms indicate that during shortages, customers must accept higher prices and make prepayments to secure priority access to capacity.
By locking in volume and cash flow while retaining flexibility to adjust with the market, LTAs can smooth the pricing curve. They may temper the upside slope, but they can also raise the earnings floor during a downturn. The missing pieces are the price-reset ranges, the timing of coverage across customers, and whether customers will continue honoring contracts in a downcycle. If LTAs merely constrain suppliers’ ability to raise prices without minimum-volume, minimum-profit, or take-or-pay protections, the claim of “de-cyclicality” does not hold.
Shareholder returns provide indirect validation. Samsung Electronics and SK hynix currently target returning 50% of cumulative free cash flow, and JPMorgan estimates that the two companies could deliver a combined potential cash yield of 16%-20% over the next two years. Dividends and buybacks are not evidence of supply and demand, but management teams willing to commit substantial capital returns during a period of elevated capex are at least signaling that they do not view free cash flow as a one-quarter peak. Conversely, delayed return programs or payouts materially below the model would reveal management’s true assessment of earnings durability earlier than fluctuations in spot prices.
The Biggest Ceiling: Memory Is Consuming Customer Budgets
Memory’s share of cloud-service-provider hardware capex was only 7%, 4%, 8%, and 8% in 2022-2025, respectively, but jumps to 31% in 2026, reaches 49% in 2027, and rises further to 60% in 2028. JPMorgan itself raises the question in its chart: will investors become uncomfortable once this ratio exceeds 50%?
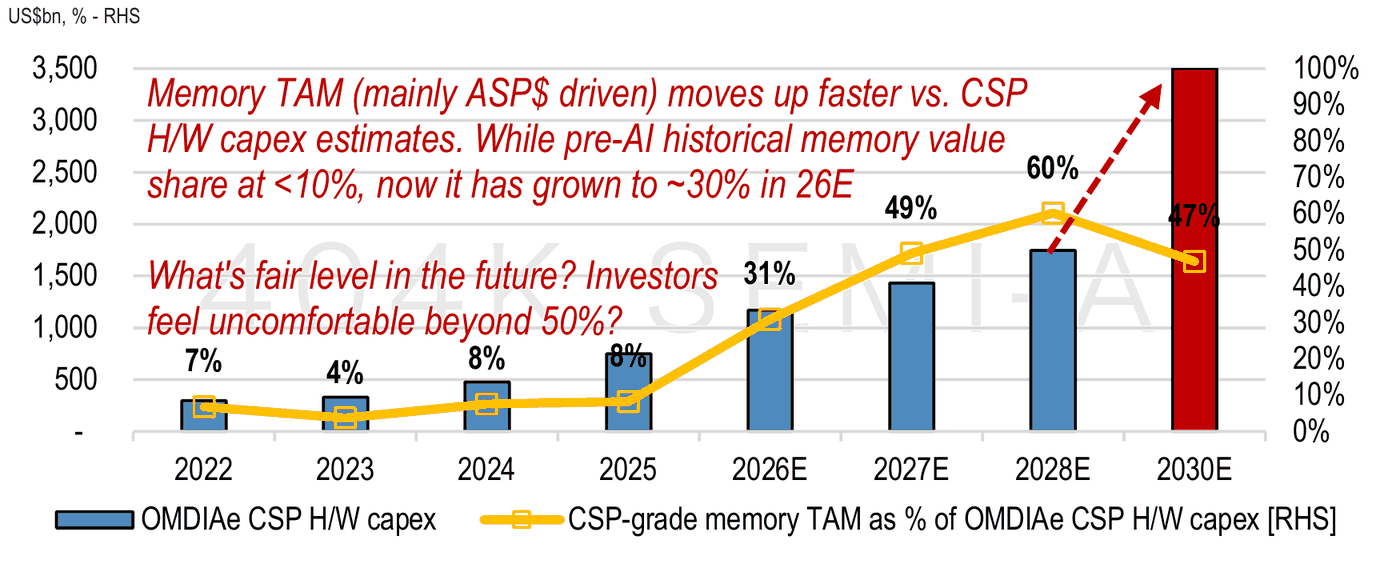
The answer depends on the denominator. If cloud service providers continue raising capex, memory pricing can be sustained within a larger total budget. If the denominator remains unchanged, customers can absorb the “memory tax” only by reducing capacity per system, slowing deployments, substituting NAND or CXL for some DRAM, and extending equipment lifecycles. The report’s projection that the ratio falls back to 47% by 2030 implicitly assumes that at least one of three things occurs: capex catches up, memory-price growth slows, or alternative media gain share.
This is the report’s most important reflexive dynamic: the more successful price increases become, the stronger the incentive for customers to optimize; the higher margins rise, the more they attract capacity expansion and competitors; and the larger the TAM becomes, the more cloud capex is required to demonstrate that it remains affordable. An industry operating margin in the high 70% range can persist for a time, but it cannot be treated as a new normal with no endpoint.
What Makes This Cycle Different: Four Gates Beyond Inventory
Traditional memory cycles often follow a relatively clear sequence: smartphone or PC demand improves, channels restock, spot prices rise, manufacturers increase utilization and capex, and new supply eventually reverses the inventory cycle. Prices, inventories, and wafer utilization are usually sufficient to indicate where the cycle stands. Those dynamics remain intact this time, but four additional gates have become materially more important.
The first is system architecture. HBM does not simply replace conventional DRAM: it consumes more wafers to deliver greater bandwidth, increasing the opportunity cost of conventional DRAM. Inference also tiers data across eSSD, HBF, and CXL memory pools, allowing demand to migrate among media. The second is advanced packaging. Even if HBM dies are available, CoWoS capacity, thermal management, stacking yields, and customer qualification still determine final deliverable volumes. The third is customer deployment. GPU and memory purchases must be supported by power, networking, racks, and operational data centers. When upstream orders are strong but downstream deployment lags, inventories of racks not yet in production may accumulate. The fourth is contract structure. LTAs convert some spot demand into prepayments and multiyear volume commitments, so falling inventories may not immediately trigger order cancellations, while lower prices may not cut through earnings as directly as in prior cycles.
These changes lengthen the causal chain and make the cycle harder to assess. A price peak may merely reflect slower increases; rising capex may only relieve bottlenecks; and lower per-system specifications may be intended to enable more chip deliveries. Complexity, however, does not mean the cycle has disappeared. The ultimate questions remain whether customers can pay, whether equipment can come online, and whether effective bit supply can exceed actual consumption. If all 3 weaken simultaneously, LTAs and a premium product mix can only delay the downturn, not eliminate it permanently.
Three Worldviews: The Same Data Support Different Valuations
The bull case holds that AI is transforming memory from a commodity component into a binding constraint on compute systems. Servers continue to gain share of DRAM demand, HBM crowds conventional DRAM out of wafer capacity, and customers compete for capacity through prepayments. Even if memory per system declines, rising GPU, CPU, and ASIC volumes continue to expand aggregate demand. In this world, the extreme price increases of 2026 translate into elevated earnings in 2027-2028, LTAs raise the earnings floor, and dividends and buybacks capitalize the resulting cash flow. Valuation should gradually shift from “discounted peak earnings” toward “sustainable cash flow plus scarce capacity.”
The neutral case accepts the shortage but does not assume that operating margins in the high 70% range can remain unchanged indefinitely. DRAM still faces a cumulative deficit through 2028, while NAND is the first to replenish inventories after mid-2027. Average selling prices continue to grow, but at a rapidly slowing pace; earnings no longer depend on quarterly upgrades and instead shift toward committed volumes, product mix, and shareholder returns. The sector can still generate gains in this world, but company-level dispersion widens materially: advanced HBM qualification, long-term server contracts, and cash returns become more valuable, while businesses dependent on consumer demand, spot pricing, or a single customer receive lower valuations.
The bear case focuses on the report’s most fragile multiplier. Memory already consumes nearly half of cloud-service-provider hardware budgets, and reductions in memory per system signal customer resistance to pricing. Meanwhile, 2026-2027 capex will translate into supply 12-18 months later, while NAND technology migrations and Chinese manufacturers further increase tail-end bit output. If power and rack constraints slow server deployment, higher chip volumes will not be sufficient to offset lower capacity per system. The TAM would then contract rapidly as ASPs fall below the model, while LTAs may prove to be price ceilings rather than earnings floors.
The evidence currently supports a neutral-to-bullish view. The supply gap remains physically constrained, cloud revenue and capex estimates are still being revised upward, and LTA prepayments demonstrate genuine pricing power. However, NAND price growth turning negative in 2028 and memory’s share of budgets reaching 60% already warn against linearly extrapolating elevated margins. The real choice for investors is not whether to be “bullish or bearish on memory,” but which segment of cash flow, which form of supply constraint, and which customer qualification they are willing to pay for.
Substantial Valuation Upside, but Not Price Targets
The report uses two peak scenarios to illustrate potential upside. If Samsung Electronics, SK hynix, and Micron return to peak price-to-sales multiples of 2.8x, their implied aggregate peak market capitalization would be approximately $3.984 trillion in 2027 and $5.044 trillion in 2028, representing theoretical upside of roughly 50% and 88% from the report date. Valuing the companies at 4x memory operating profit implies theoretical upside of approximately 110%.
These figures should not be treated as price targets. They depend on industry operating margins remaining at 76%, 78%, and 77% in 2026-2028, as well as the realization of extreme pricing assumptions. A more disciplined valuation sequence is to first validate ASPs and effective bit supply, then assess how far LTAs raise the earnings floor, and finally determine whether free cash flow is genuinely converted into dividends and buybacks. Peak earnings for these cyclical stocks may be capitalized only if all three conditions hold.
At the company level, Samsung Electronics offers a combination of market-share recovery and cash returns; SK hynix provides greater HBM exposure but also higher customer concentration; Micron captures the combined tailwinds from US AI memory and conventional DRAM; while Kioxia and other NAND names offer greater pricing sensitivity but face an earlier normalization risk. The report’s continued overweight stance on global memory does not justify applying the same valuation framework to every company.
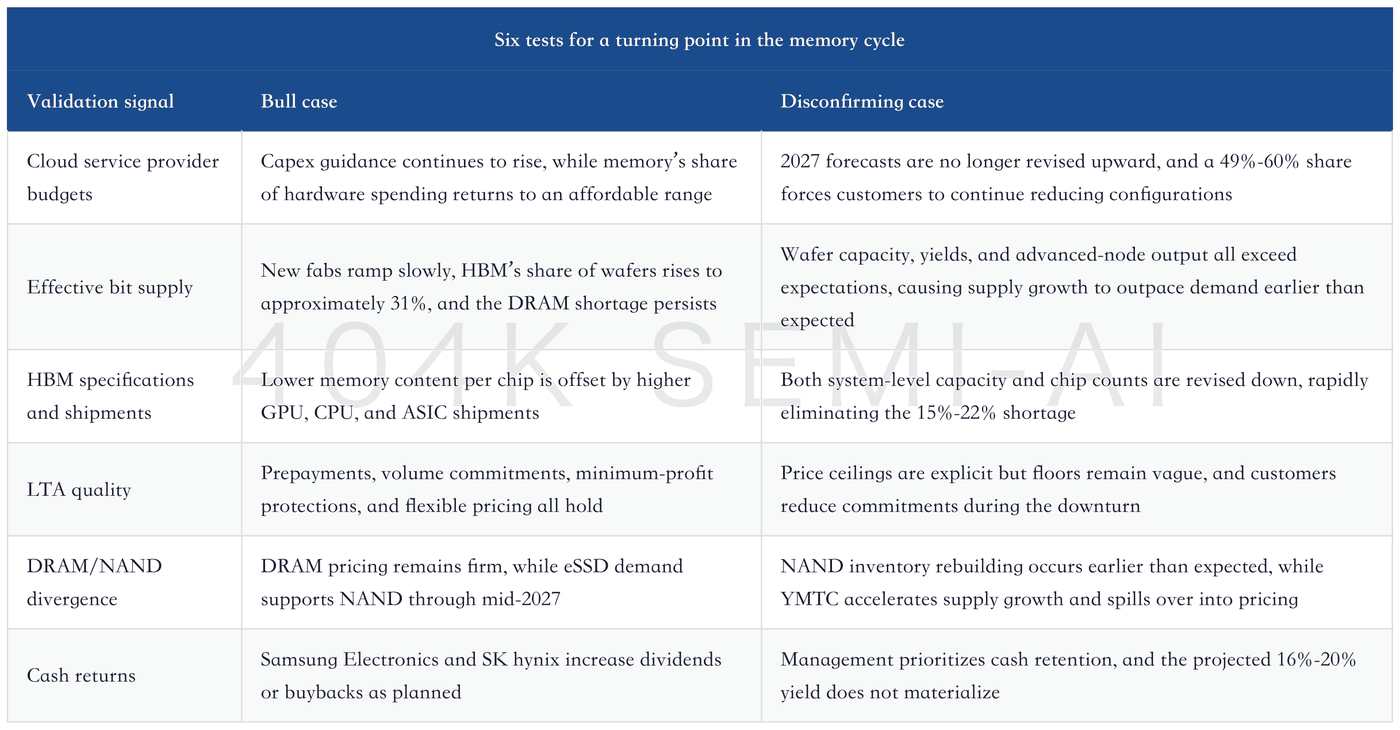
Six Disconfirming Signals to Watch Over the Next Four Quarters
Conclusion: The Real Inflection Point Is When Effective Supply Outgrows Demand, Not When Price Increases Slow
The report advances the “memory crisis” discussion from a matter of sentiment to a quantifiable supply-demand framework. Lower configurations, capacity expansion, and competitive supply have all been incorporated into the model, yet TAM estimates are still being raised. This suggests that the current constraint is not insufficient headline capex, but the combined limits imposed by wafer capacity, advanced processes, HBM’s bit penalty, packaging, and qualification on effective supply. 2027 remains the year in which DRAM and HBM conditions are most likely to deteriorate further, with marginal balance emerging only in 2028. NAND may enter inventory recovery and price normalization earlier.
The report’s most aggressive assumption is equally clear: the 2026 TAM surge is driven primarily by extreme ASPs, and memory cannot indefinitely absorb nearly one-half—or even 60%—of cloud service providers’ hardware budgets. A 25% share-price correction may therefore represent an expectations reset, but it is not an unconditional margin of safety. The next phase should focus not simply on pricing, but on whether customer budgets, effective bit supply, LTA quality, and cash returns are moving in the same direction.
My view is that global memory remains in the latter half of a structural upcycle, rather than at the end of a traditional inventory cycle. DRAM offers greater visibility than NAND, while HBM demand is more certain than its pricing outlook. Suppliers with advanced capacity, customer qualifications, long-term agreements, and explicit shareholder-return policies are preferable to names reliant solely on spot-price increases. The true cyclical inflection point will come only when effective supply growth persistently exceeds demand from servers and AI systems—not merely when capex rises or the pace of price increases slows.