
目录
TL;DR
Where Does the $1.5 Trillion Come From?
Three Similar-Looking Numbers with Entirely Different Economic Meanings
Revenue Growth Provides the First Layer of Validation
The Same Corporate Budget May Be Counted Multiple Times Across the Value Chain
Capital Expenditure Must Clear Five Hurdles to Generate Returns
JPMorgan’s Research Focus Has Shifted from Financing to Final Demand
Who Is Best Positioned to Convert Budgets into High-Quality Revenue?
What Could Invalidate This Bullish Projection?
What to Watch Next in Public Data
JPMorgan extrapolates large enterprises’ AI budgets over the next 12 months to approximately $1.7 trillion. While this strengthens confidence in demand, the investment case must still pass four tests: double counting, depreciation, margins, and cash flow.
TL;DR
The $1.5 trillion in the headline is a survey extrapolation, not the sum of actual spending disclosed by companies. JPMorgan’s survey indicates that large enterprises spent approximately 4.5% of their combined operating expenses and capital expenditure on AI over the past 12 months, with the share expected to rise to 5.8% over the next 12 months. Applied to a total spending base of approximately $30 trillion, these percentages imply about $1.35 trillion and $1.74 trillion, respectively. The headline figure falls roughly between the two.
The $1.7 trillion enterprise budget, $1.6 trillion annualized AI-company revenue run rate, and $7.5 trillion of cumulative five-year capex are three different metrics. They measure end-customer budgets, suppliers’ gross revenue, and multi-year investment, respectively, and cover different time periods. Direct subtraction would overstate demand coverage, while payments within the supply chain can cause multiple companies to recognize the same end-customer spending as revenue.
AI revenue growth has made the capex cycle more viable than it appeared six months ago. JPMorgan estimates that AI cloud providers, model providers, and neoclouds could reach a combined annualized revenue run rate of approximately $1.6 trillion by the end of 2026. With 10%–20% growth, this could rise to $2.5 trillion–$3 trillion by 2030. Revenue provides the first layer of validation, but profitability and cash payback remain unproven.
Future returns depend on whether enterprises can convert experimental budgets into recurring spending. AI budgets must be funded by productivity gains, labor-cost savings, incremental revenue, or the reallocation of traditional IT budgets. Privacy concerns, workforce readiness, and technological maturity will continue to constrain deployment. If budget growth is driven mainly by short-term pilots, compute utilization and pricing will come under pressure.
The market will increasingly distinguish revenue growth from returns on capital. The most important public metrics, in order, are signed enterprise contracts, AI service revenue, facility utilization, gross margin, depreciation as a share of revenue, operating cash flow coverage of capex, and reliance on external financing and equity dilution. Only sustained improvement across these metrics can turn a $1.7 trillion budget into durable returns.
Where Does the $1.5 Trillion Come From?
JPMorgan’s headline extrapolates a budget survey to a global scale. Its survey of AI adoption among large Asia-Pacific enterprises found that respondents spent an average of 4.5% of their combined operating expenses and capital expenditure on AI over the past 12 months. The expected share rises to 5.8% over the next 12 months. The report then applies this percentage to the large enterprises represented by the MSCI Global ex-China Index.
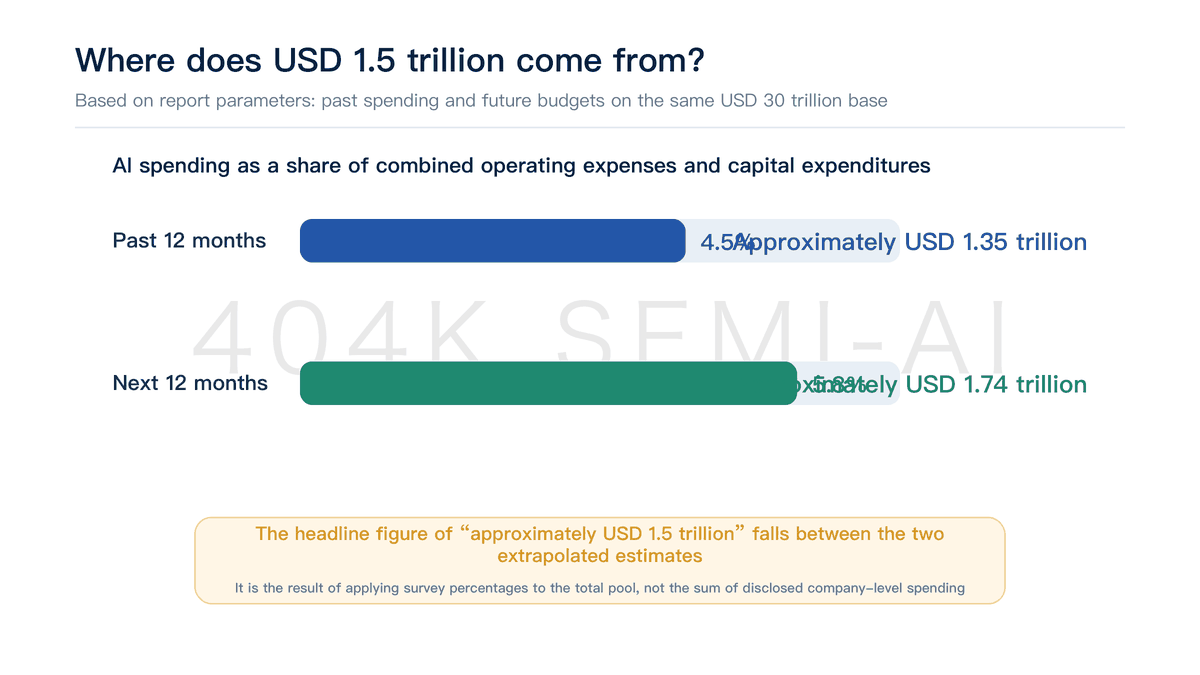
These companies have approximately $30 trillion in combined operating expenses and capital expenditure. Based on the report’s assumptions, 4.5% equates to approximately $1.35 trillion, while 5.8% equates to approximately $1.74 trillion. The headline figure of “$1.5 trillion” falls roughly between the two. The more accurate interpretation is that large-enterprise AI budgets have reached the $1 trillion scale and are still expected to increase over the next 12 months.
This calculation has three limitations. First, the survey covers large Asia-Pacific enterprises, while the extrapolation applies to a broader global corporate universe. Differences in industry mix, compensation levels, cloud adoption, and the proportion of internally built infrastructure can all alter AI’s share of spending. Second, combining operating expenses and capex into a single denominator obscures whether the money is going to GPUs, cloud services, software subscriptions, systems integration, data governance, or internal staff. Third, the projected 5.8% for the next 12 months is a budget expectation; spending may be delayed, revised, or crowded out by other projects.
The $1.7 trillion figure is therefore useful as an indicator of the potential ceiling and direction of demand. It cannot yet be treated as confirmed AI-industry revenue or as evidence that enterprises have already achieved corresponding productivity gains.
Three Similar-Looking Numbers with Entirely Different Economic Meanings
Enterprise budgets, AI-supplier revenue, and data-center capex measure three different things. The report cites approximately $1.7 trillion of enterprise AI budgets, an annualized revenue run rate of approximately $1.6 trillion for AI-related companies, and approximately $5 trillion–$10 trillion of cumulative capex over 2026–2030. JPMorgan uses the midpoint of the latter range, approximately $7.5 trillion.
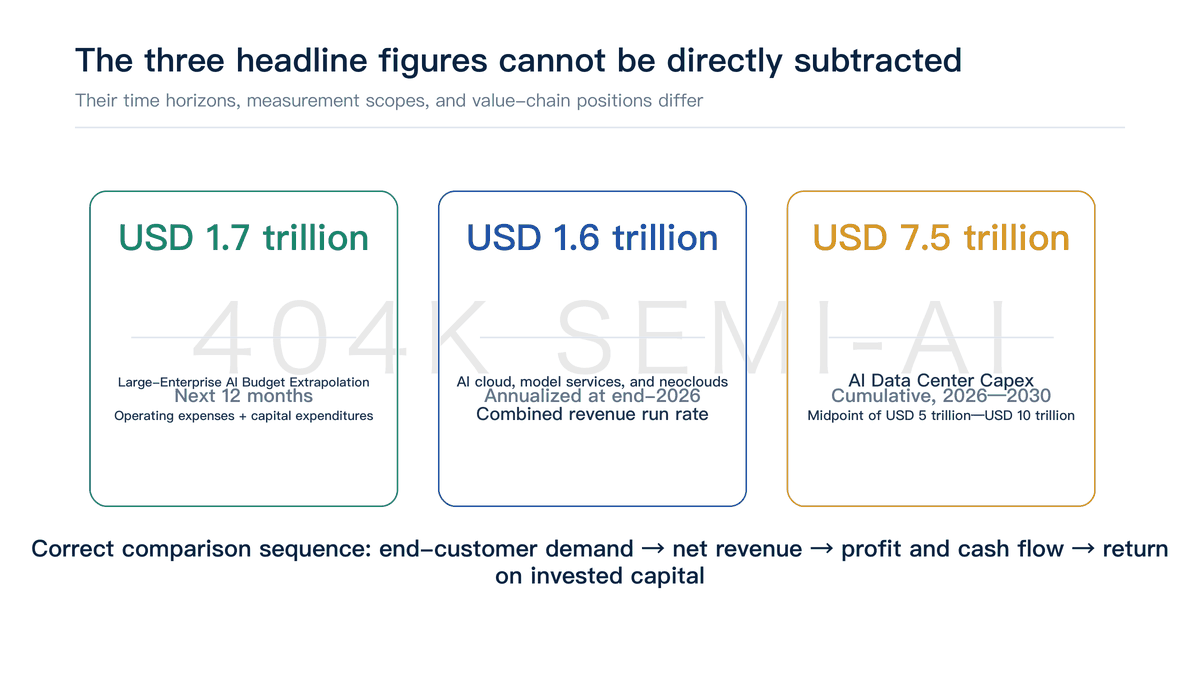
The $1.7 trillion represents enterprises’ spending intentions over the next 12 months. The $1.6 trillion is an annualized revenue run rate at the end of 2026. The $7.5 trillion is cumulative investment over five years. An annualized flow cannot be compared directly with a cumulative total, and enterprise spending and supplier revenue sit at different points in the value chain.
These distinctions determine the correct analytical sequence. Start with how much end customers are ultimately willing to pay, then assess how much of those payments becomes net revenue for AI companies. Next, determine how much operating profit and cash that revenue generates, and finally whether those cash returns can cover invested capital, depreciation, and financing costs.
The report’s budget requirement for 2030 is not extreme, but it requires continued diffusion. If large enterprises’ combined operating expenses and capital expenditure rise with nominal economic growth from approximately $30 trillion to $36 trillion–$38 trillion, $2.5 trillion of AI spending would represent about 6.5%–7.0% of the total. That is above the expected 5.8% for the next 12 months, but the gap remains plausible.
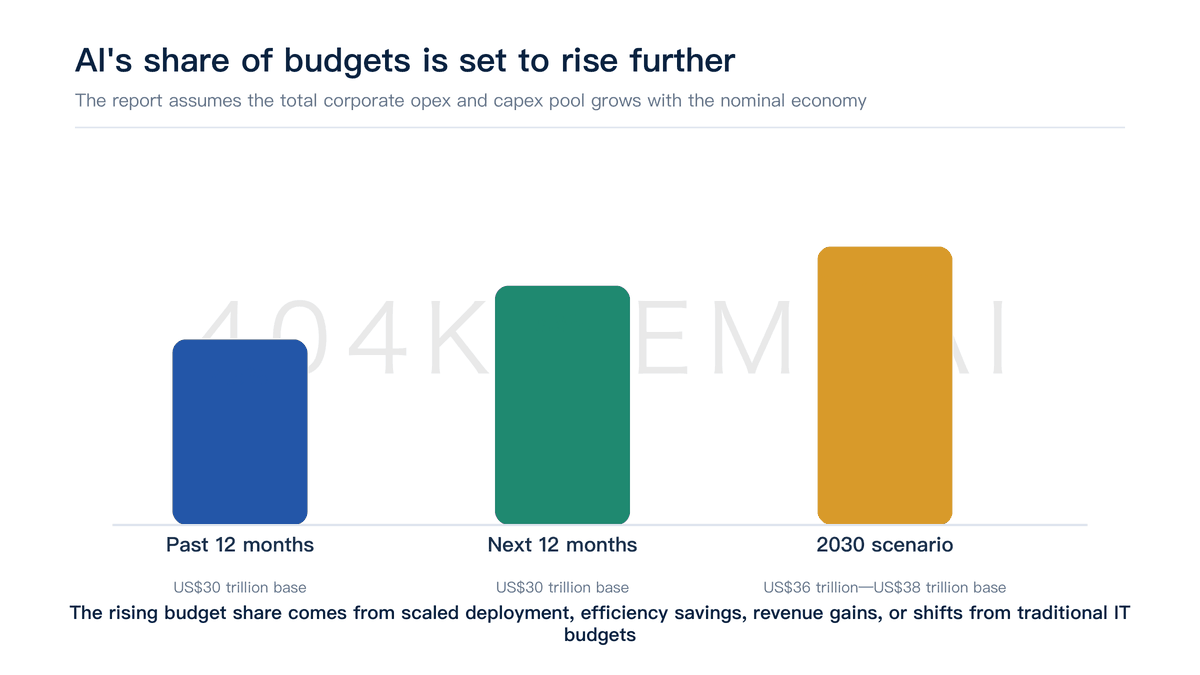
The real challenge is funding. Enterprises can increase AI budgets through productivity gains, labor-cost savings, incremental revenue, or reductions in traditional IT spending. If these benefits fail to materialize, AI will compete for the same cash allocated to wages, marketing, R&D;, conventional cloud migration, and shareholder returns. The higher AI’s budget share rises, the more management teams will need quantifiable returns.
Combining operating expenses and capex in the same denominator also obscures budget quality. Server purchases and data-center construction create assets whose depreciation affects earnings over multiple years. Model subscriptions, cloud usage, consulting, and data services generally flow directly through current-period expenses. Internal staff, process redesign, and data cleansing may also be classified as AI-project spending without fully translating into revenue for external suppliers.
