
Corning Deep Dive: AI Fiber Enters the Capacity-Lock Era, Repricing a Century-Old Materials Platform
目录
TL;DR
I. Core View: AI Puts Corning Back at the Connectivity-Layer Bottleneck
II. Evidence Chain: From 2025 Quarterly Beats to a 2030 Revenue Step-Up
III. The Three Optical Curves: Scale-Out, DCI, and Scale-Up/Photonics
IV. Springboard Is Not a Slogan, but a Financial Repricing Framework
V. Where Sell-Side Models Differ: Not Price Targets, but Three Worldviews
VI. Company Capability: Why Corning, Not an Ordinary Fiber Manufacturer
VII. Peer Positioning: Corning Sits at the "Materials and Connectivity Base" of Optical-Interconnect Value Migration
VIII. Core Model: Revenue Bridge, Profit Bridge, and Three Paths to 2030
IX. Segment Restructuring: Optical Is the Engine, Solar Is the Second Variable, and Traditional Businesses Are the Cash-Flow Base
X. Photonics Is the Largest Option, and the Largest Debate
XI. Falsification Checklist: When Would the Corning Story Deteriorate?
XII. How to Track the Next Four Quarters
XIII. Valuation View: Separate a Good Company from a Good Price
XIV. Conclusion: Corning's Pricing Core Has Moved from "Glass Cycle" to "AI Data Movement"
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Corning's rerating is no longer just a cyclical recovery story in glass, display, and telecom fiber. AI data centers are turning fiber, connectors, and photonic packaging into long-duration capacity-lock assets. Since 2H25, cloud-customer long-term agreements, the NVIDIA partnership, and the 2030 Springboard plan have shifted demand from expectation to capacity commitment.
TL;DR
Corning is moving from a cyclical materials stock to an AI connectivity-layer asset. Historically, the market's valuation anchors for Corning were display glass, traditional telecom fiber cable, automotive glass, and life-sciences consumables, with earnings upside often framed as cyclical recovery. After 2H25, the incremental narrative shifted to locked-in cloud demand for AI data center fiber, connectors, pre-connectorized systems, and future in-rack optical interconnect. What really matters for valuation is not bare-fiber price inflation itself, but whether Corning can convert low-loss fiber, ultra-high-density connectivity, manufacturing yield, and customer-backed capacity expansion into long-term supply rights.
The hardest evidence comes from orders and capacity commitments. In 4Q25, Corning disclosed a multi-year agreement with Meta worth up to US$6bn. In 1Q26, it disclosed that two additional hyperscale customers had signed long-term agreements of similar scale and duration. In May, Corning announced a long-term commercial and technical collaboration with NVIDIA, under which it plans to expand U.S. optical-connectivity capacity by 10x, increase fiber capacity by more than 50%, and build three new advanced manufacturing facilities. Investors therefore need to reclassify Corning from a second-derivative beneficiary of AI capex into a strategic capacity supplier for the physical connectivity layer of the AI factory.
Optical is the earnings engine behind Corning's rerating. In 1Q26, core sales rose 18% YoY to US$4.35bn, while core EPS rose 30% YoY to US$0.70. Optical Communications revenue grew 36% YoY, and segment profit grew even faster. Since 3Q25, multiple sell-side firms have repeatedly raised Enterprise Optical CAGR, DCI opportunity, and 2028-2030 optical revenue assumptions. The core debate has moved from "is there demand?" to "how fast can capacity expand, how long can pricing and product mix hold, and when will Photonics scale?"
2030 Springboard is repricing the company. At the end of 2025, Corning raised its 2028 incremental annualized sales target from US$8bn to US$11bn. After the May 2026 investor day, sell-side models generally centered on a revenue framework of roughly US$30bn in 2028 and roughly US$40bn in 2030, with Optical, Enterprise, Photonics, and Solar as the main incremental drivers. The investment implication is that Corning's earnings leverage comes not only from revenue growth, but also from core operating margin continuing to climb toward the mid-20s after crossing 20%.
Valuation disagreement centers on Photonics and the pace of execution. The more cautious camp believes the share price already discounts a 2030 blue-sky scenario; if scale-up, CPO/NPO, in-rack optical connectivity, or cloud capex move more slowly than expected, multiples will compress first. The more optimistic camp believes optical-connectivity content per GPU, per rack, and per cluster is still rising, and that fiber-density growth will outpace both GPU unit growth and cloud capex growth. Corning cannot be assessed only through next-quarter EPS. The key is whether 2027-2028 incremental capacity is locked by customer long-term agreements.
Four numbers matter when tracking Corning. First, Enterprise Optical and Optical Communications revenue, margin, and order visibility. Second, U.S. optical-connectivity and fiber capacity-expansion milestones, including the three new facilities, yield, and customer prepayment or capex-sharing structures. Third, Photonics MAP samples, design wins, mass-production timing, and content per rack. Fourth, whether Solar can resume its ramp after maintenance downtime and contribute cash rather than consuming the profit upside from Optical.
I. Core View: AI Puts Corning Back at the Connectivity-Layer Bottleneck
The key to Corning's current rerating is not that it has suddenly become an optical-module company, nor is it as simple as short-term price inflation in traditional fiber. The more precise business question is this: as AI clusters move from thousands of GPUs to tens of thousands and then hundreds of thousands of GPUs, and switching, interconnect, power consumption, cooling, and rack density all rise together, who controls the foundational materials and connectivity processes that allow data to move with low loss, high density, and manufacturable scale?
Over the past two decades, the market has viewed Corning as a diversified materials platform. Display glass, fiber and cable, ceramic substrates, automotive glass, pharmaceutical glass, life-sciences consumables, and solar silicon materials together formed the revenue base. The advantage of that mix is resilience against any single cycle. The drawback is that valuation lacks a sharp edge: Display is pulled by the panel cycle, traditional telecom fiber cable is constrained by carrier capex, and automotive and life sciences look more like mid-speed industrial consumer businesses. Investors often treated Corning as a steady manufacturer in the 15-20x earnings range.
AI data centers have changed that valuation framework. The stronger the GPU, the more data must move inside and between clusters. The bottleneck in model training and inference is not only compute silicon, but also networking, switching, cables, connectors, transceivers, low-loss fiber, and optical packaging. Copper interconnect still has a role in short-reach, high-power, and in-rack scenarios, but distance, bandwidth, energy, and density pressures will push more links toward optical connectivity. Corning is not positioned at the most visible optical-module brand layer. It is positioned further down the stack in fiber, connectors, pre-connectorized systems, ultra-high-density cabling, and future Photonics capability.
That is why sell-side coverage of Corning changed noticeably after 2H25. Earlier reports focused on "2Q beat & raise," "Springboard execution," and "strong Enterprise Optical demand." By 2026, the focus had shifted to the US$6bn Meta agreement, long-term agreements with two additional hyperscale customers, the long-term NVIDIA collaboration, a 10x expansion in U.S. optical-connectivity capacity, more than 50% expansion in fiber capacity, and 2030 incremental revenue targets. These are not typical quarterly restocking signals for a cyclical stock. They are advance lock-ins by major customers for physical connectivity supply over the next several years.
AI Network Interconnect Hardware, Part I: Value Migration Behind 1.6T/3.2T, and Who Benefits Most Across Switching, Copper Interconnect, Optical Interconnect, and the Physical Layer
Corning's old asset identity was "materials-science platform plus cyclical recovery plus cash-flow improvement." Its new asset identity is "strategic AI connectivity-layer capacity plus customer-backed expansion plus a visible 2030 revenue step-up." This change has two investment implications.
First, revenue quality has changed. Traditional fiber cable or display glass mostly depends on end demand and industry inventory, and customers find it difficult to make firm commitments for far-future supply. AI data centers are different. Cloud providers and systems vendors need to plan campuses, server rooms, power, GPUs, switches, fiber, and connectivity systems years in advance. If a shortage of critical materials can delay delivery of an entire AI factory, customers become more willing to exchange long-term agreements, joint technical development, and shared capacity expansion for certainty.
Second, the way margins are validated has changed. Corning's historical earnings leverage often came from utilization recovery, cost control, and price repair. In AI Optical, earnings leverage depends more on product mix, pre-connectorized systems, customized connectivity solutions, customer long-term agreements, yield, and scaled manufacturing. Bare fiber itself can rise in price, but the more important value migration is from "per fiber-kilometer" to "optical-connectivity content per GPU, per rack, and per cluster." That raises the engineering content and customer stickiness embedded in each dollar of revenue.
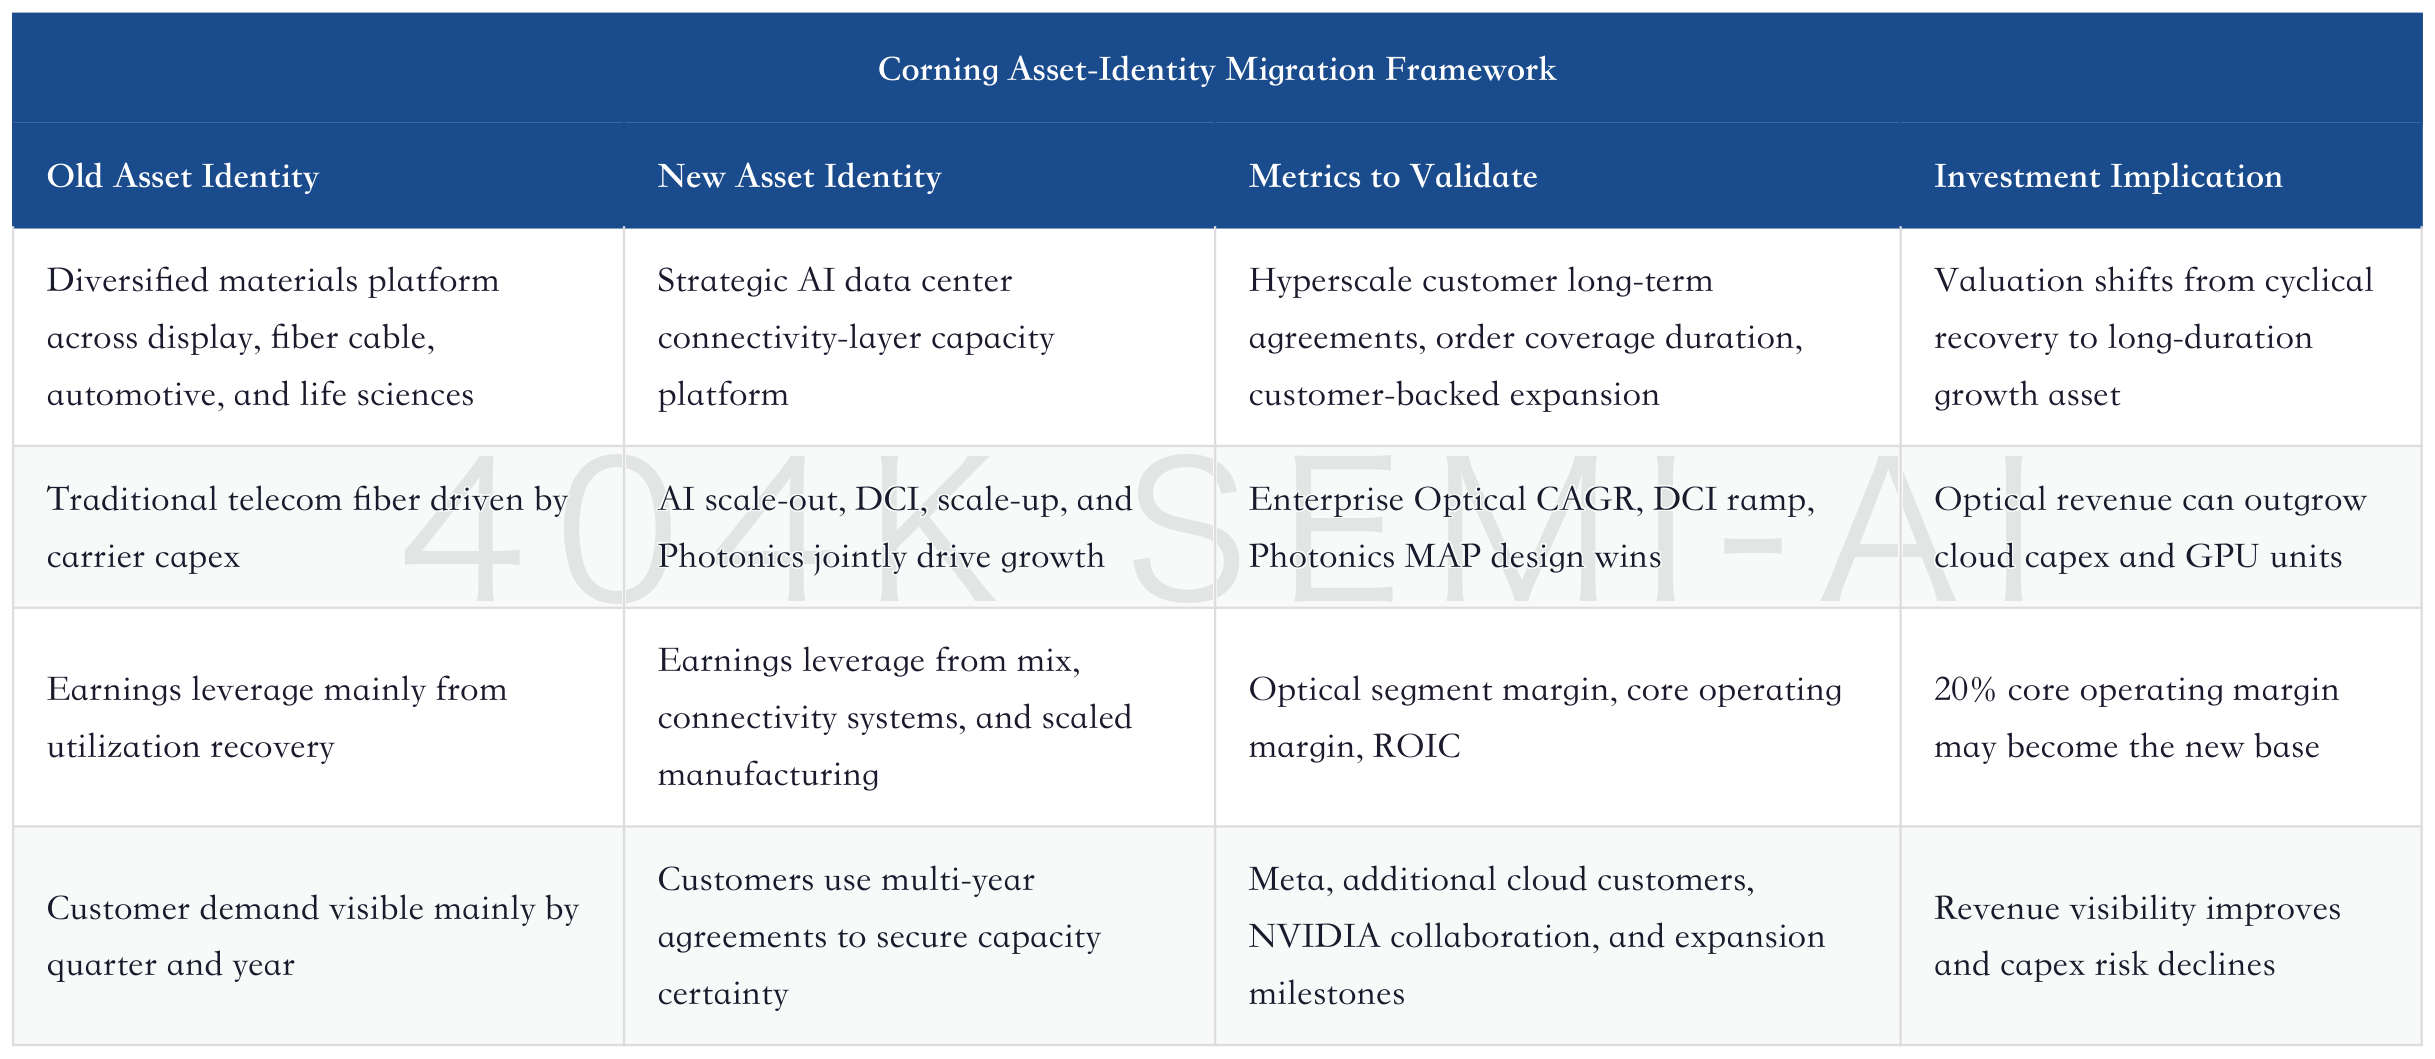
The core view on Corning is straightforward: if Enterprise Optical, DCI, and Photonics progress in 2027-2028 according to the current company and sell-side framework, Corning should no longer be viewed simply as a traditional cyclical materials stock. If Photonics and scale-up move more slowly than expected, Corning remains a high-quality industrial growth company, but its 2030 premium valuation will come under pressure first. In other words, the decisive question is not "will AI investment continue?" It is "how much AI investment can be converted into Corning-deliverable, scalable, profitable optical-connectivity content?"
II. Evidence Chain: From 2025 Quarterly Beats to a 2030 Revenue Step-Up
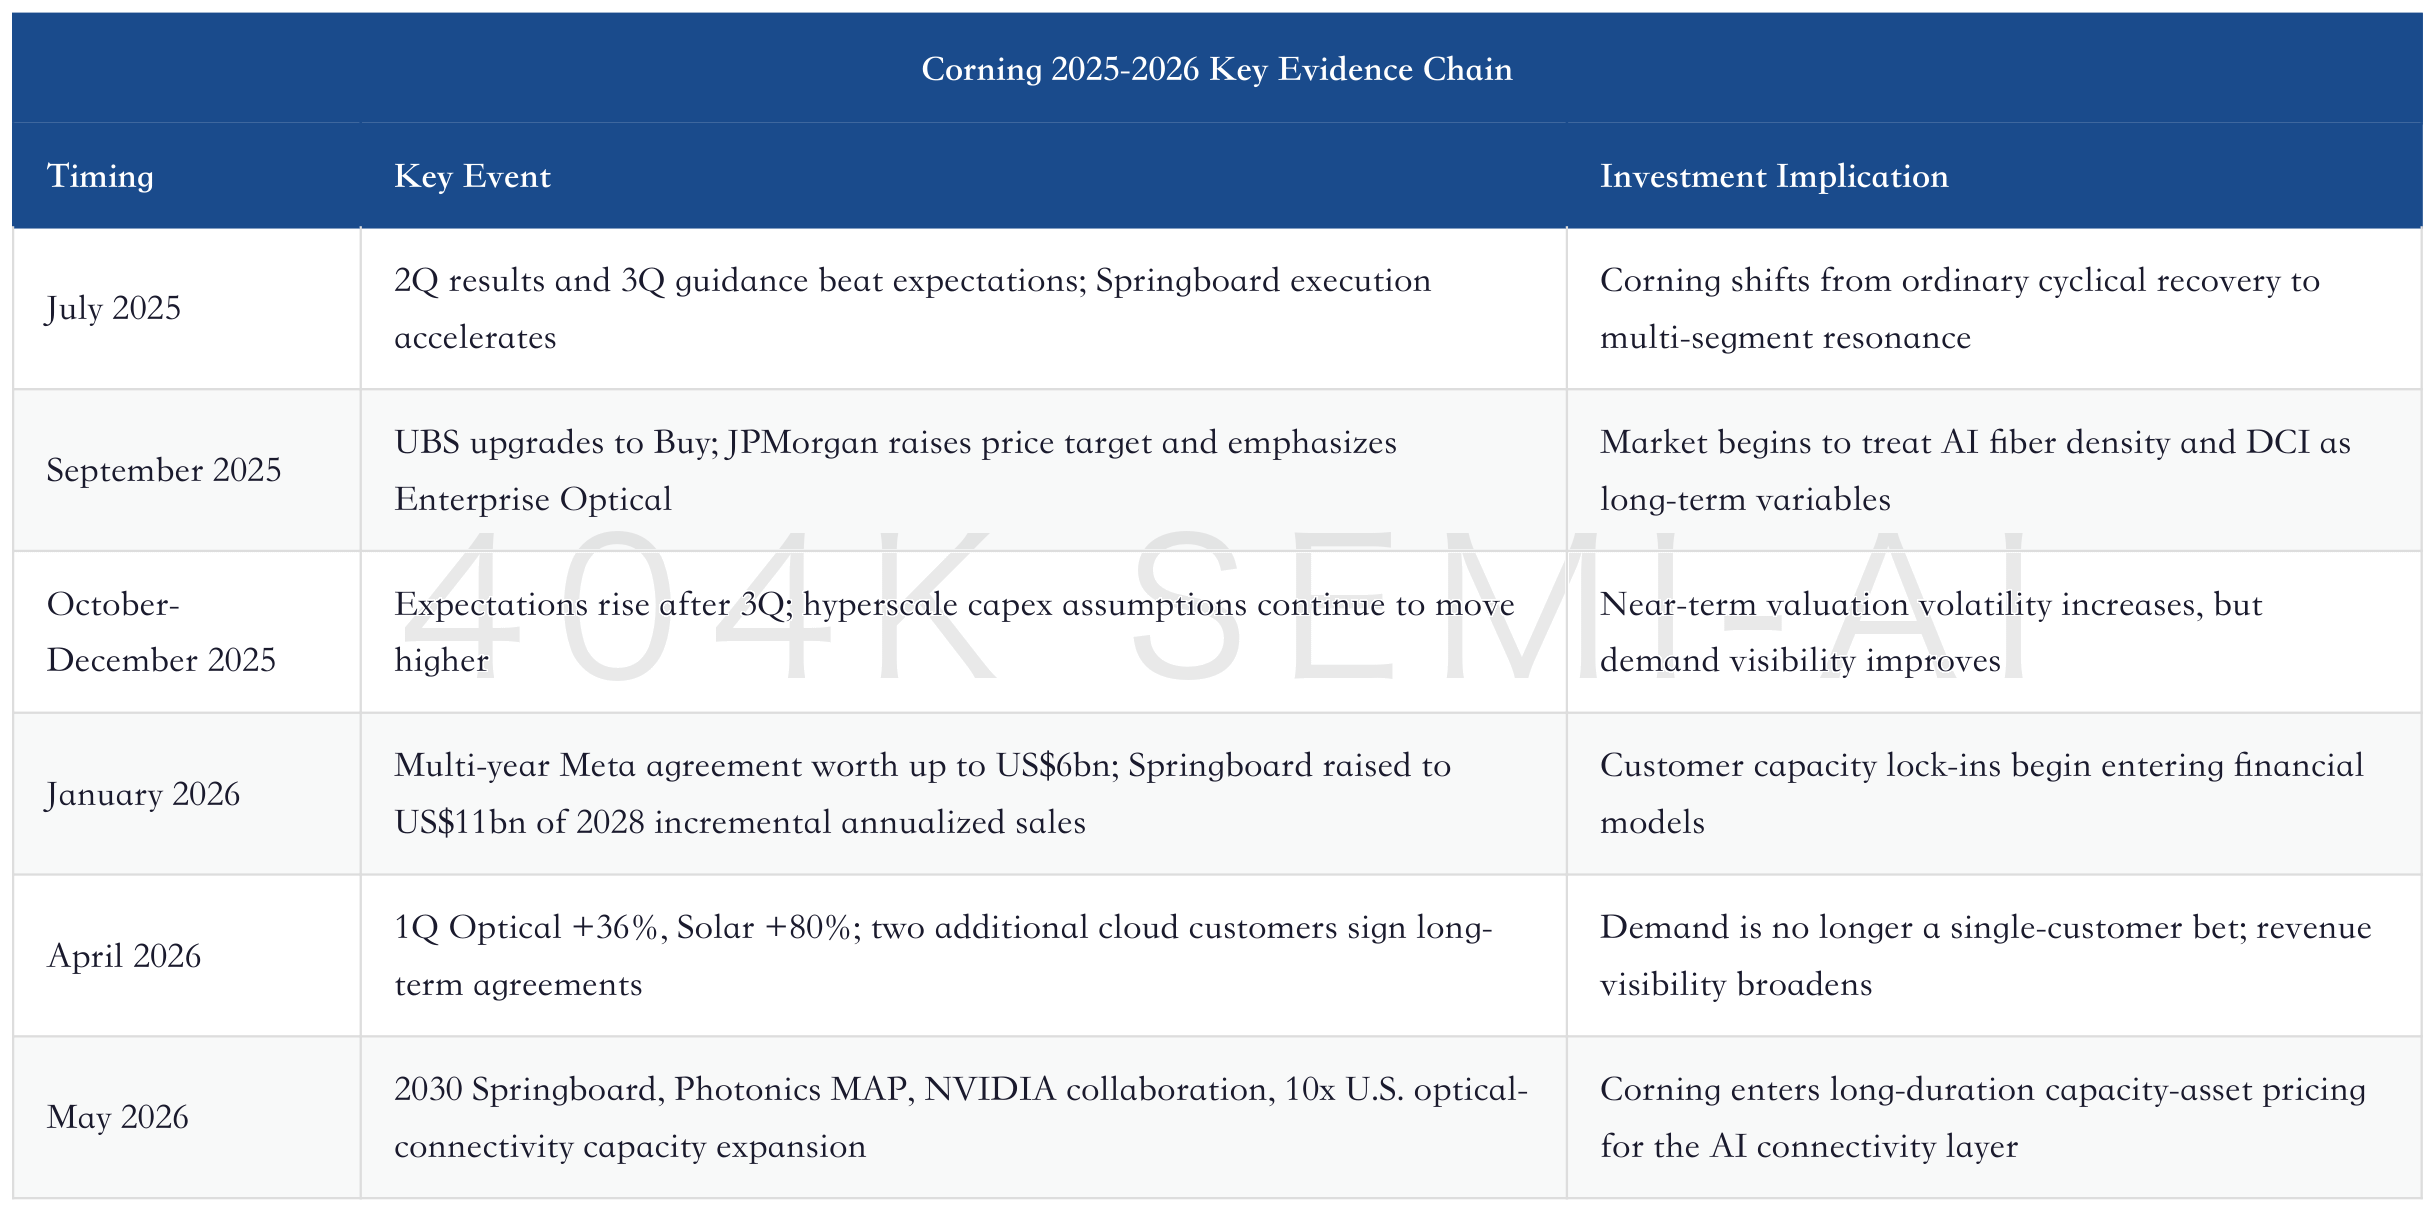
In July 2025, Corning was still in the early stage of accelerated Springboard execution. JPMorgan raised its year-end 2026 price target from US$65 to US$72, citing better-than-expected 2Q results, simultaneous contributions from Optical, Specialty Materials, and Solar, and long-term drivers beginning to outweigh short-term cyclical noise. UBS was still more neutral at that point, but it already acknowledged strong Enterprise Optical and Gen AI data center deployments, with DCI sales ramping independently of traditional telecom projects.
The real inflection came in September 2025. UBS upgraded the rating from Neutral to Buy and raised its 12-month price target to US$84. The core rationale was that hyperscale Optical growth was not a short cycle, and that fiber-density growth would outpace cloud capex growth in 2027-2029. JPMorgan then raised its price target to US$85 after meetings with management, noting that the company was lifting its Enterprise Optical revenue CAGR expectation above 25%, that the DCI opportunity was becoming explicit, and that traditional Carrier also showed signs of recovery.
By 4Q25, the market had begun to realize that Corning was not just an "AI fiber price increase" story. In a November report, UBS lifted its 2026 hyperscale capex growth assumption from roughly 19% to roughly 33%, and argued that Corning's fiber-supply commentary pointed to tight supply that could drive additional upside in volume, price, and mix. After the December technology meeting, UBS maintained its Buy rating and US$109 price target, emphasizing good visibility into fiber demand from the Gen AI build-out.
January 2026 was the second key milestone. Corning announced the multi-year Meta agreement worth up to US$6bn, and in its 4Q25 results the company also raised the Springboard plan: from the 4Q23 starting point through the end of 2028, the internal plan for incremental annualized sales increased from US$8bn to US$11bn; through the end of 2026, the internal plan for incremental annualized sales increased from US$6bn to US$6.5bn, while the high-confidence plan increased from US$4bn to US$5.75bn. Long-term agreements such as Meta's allowed the market, for the first time, to directly connect a single hyperscale customer's demand with Corning's revenue model.
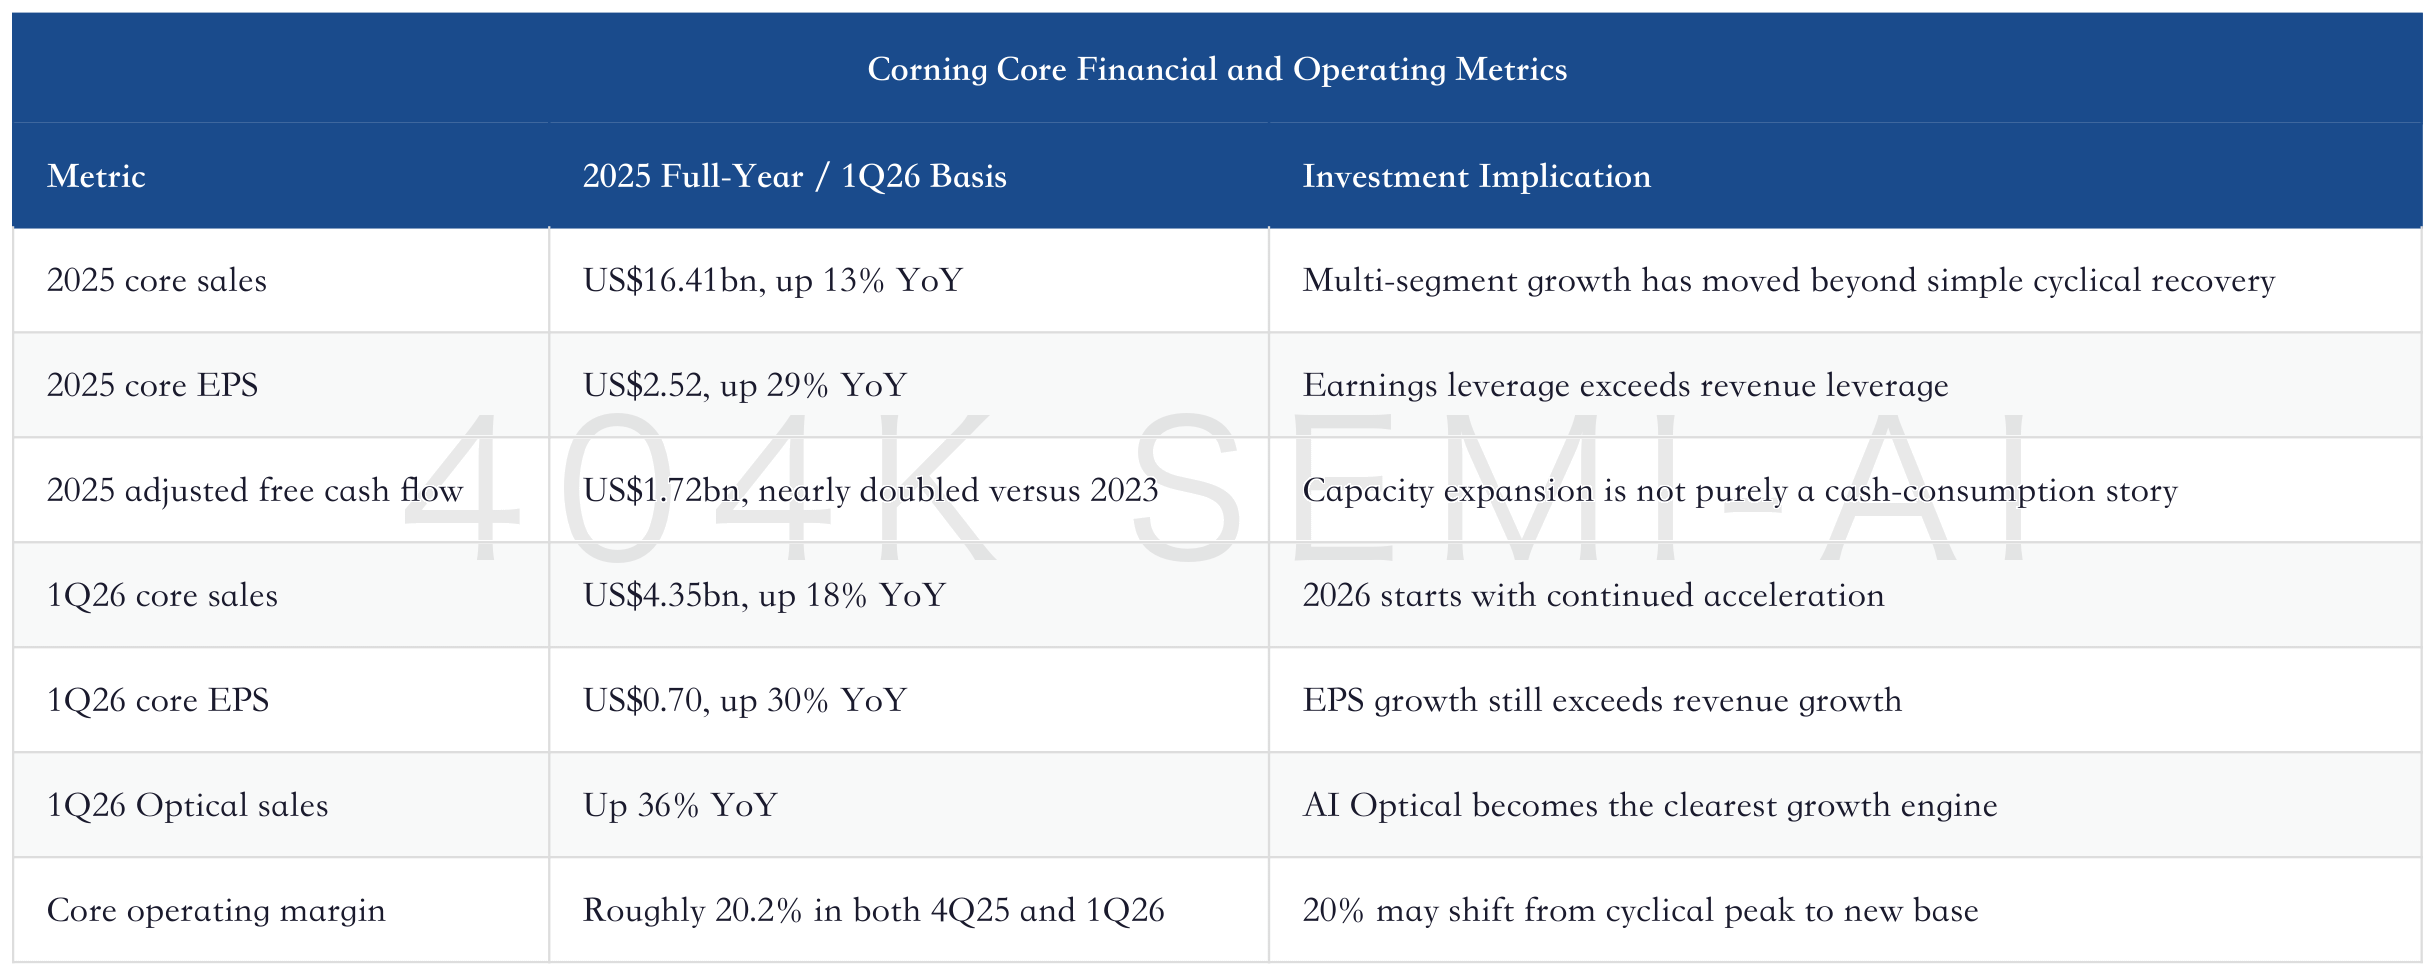
Full-year 2025 results also gave the valuation rerating a more solid base. 2025 core sales were US$16.41bn, up 13% YoY. Core EPS was US$2.52, up 29% YoY. Core operating margin reached 19.3%, and full-year adjusted free cash flow was US$1.72bn. More importantly, from the Springboard starting point in 4Q23 to 4Q25, core operating margin expanded by 390 bps to 20.2%, and core ROIC rose by 540 bps to 14.2%. This shows that growth was not being purchased at the expense of margins.
1Q26 further reinforced the direction. Core sales rose 18% YoY to US$4.35bn, while core EPS rose 30% YoY to US$0.70. Optical Communications sales rose 36% YoY, and Solar sales rose 80% YoY. The company also disclosed that two additional hyperscale customers had signed large-scale long-term agreements of similar scale and duration to the Meta agreement, and said it planned to extend Springboard to 2030 at its May investor day and launch the Photonics Market-Access Platform for Gen AI OEM customers.
Yangtze Optical Fibre and Cable Deep Dive: From Telecom Fiber-Cable Cyclical Stock to AI Data Center Fiber Bottleneck, and How to Validate Earnings Rerating After the Price Surge
One easily overlooked detail in this evidence chain is that in 1Q26, Corning did not merely say demand was strong. It emphasized that the long-term agreements with two additional hyperscale customers were "similar in size and duration" to the Meta agreement. That matters more than an ordinary order. An ordinary order proves current-period demand; a long-term agreement proves that customers are willing to commit for future capacity availability. For a manufacturer that must build capacity ahead of time in fiber, connectors, and pre-connectorized systems, long-term agreements reduce expansion risk, improve expected capital returns, and give the sell side more confidence in putting 2028-2030 revenue into models.
The NVIDIA collaboration pushes the logic one layer further. Meta and other cloud agreements mainly point to connectivity demand outside data centers and between clusters. The NVIDIA collaboration moves Corning into a more central position inside the AI accelerated-computing ecosystem. The official announcement states that Corning will expand U.S. optical-connectivity manufacturing capacity by 10x, increase fiber capacity by more than 50%, build three new advanced manufacturing facilities, and create more than 3,000 jobs. For investors, the key is not the job count. It is that NVIDIA is putting Corning's optical-connectivity capability into the long-term roadmap of AI infrastructure.
This is what makes Corning's story different from a simple price-upcycle. The risk in a price cycle is that prices fall back once supply catches up. The core of a strategic capacity cycle is that customers first lock in suppliers that can deliver, validate, and evolve alongside the roadmap. Corning has accumulated years of capability in low-loss fiber, optical physics, glass and ceramic materials, ultra-high-density connectivity, and scaled manufacturing. Cloud providers and systems vendors are not looking for an easily substitutable commodity. They want an engineering platform that can iterate together with new network architectures.
III. The Three Optical Curves: Scale-Out, DCI, and Scale-Up/Photonics
The easiest mistake in analyzing Corning is to collapse all AI optical demand into one phrase. What truly affects revenue, margin, and valuation multiple is three different curves.
The first curve is scale-out: optical-connectivity demand created by adding more GPUs, switches, and racks inside AI data centers and between clusters. As GPU clusters grow, network layers, switch ports, cable length, and redundancy requirements rise together. Even if performance per GPU increases, model scale, parallel efficiency, and inference traffic continue to push data movement higher. The sell side repeatedly raised Enterprise Optical CAGR in 2H25 because it was effectively acknowledging that fiber-density growth could exceed the headline growth rates of GPU units and cloud capex.
The second curve is DCI, or data center interconnect. Training and inference do not happen only inside a single campus. Interconnection across multiple data centers, disaster recovery, compute scheduling, and data synchronization all generate long-reach or medium-reach fiber demand. After meetings with management in September 2025, JPMorgan emphasized that DCI revenue was ramping and that the non-DCI portion of traditional Carrier also showed signs of recovery. UBS also repeatedly noted that DCI growth was independent of individual long-haul projects, indicating that this curve is not a one-off contribution from one customer or one network project.
The third curve is scale-up and Photonics: shorter-reach but higher-density, higher-bandwidth, lower-power optical-interconnect opportunities inside racks, servers, and accelerator systems. Early on, Corning did not include much scale-up in its Springboard framework because the technology roadmap, the boundary between copper and optical, CPO/NPO adoption, and customer architecture choices were still debated. After May 2026, the company formally launched Photonics MAP, and the sell side began discussing a potential US$10bn revenue opportunity by 2030. The core question here is not how much revenue exists today, but whether Corning can extend the advantages of fiber outside data centers and across campuses into data movement inside racks and systems.
AI Optical-Module Demand Revised Higher Again: How Morgan Stanley's May Report Pushes 1.6T, InP, and CPO Bottlenecks to 2028
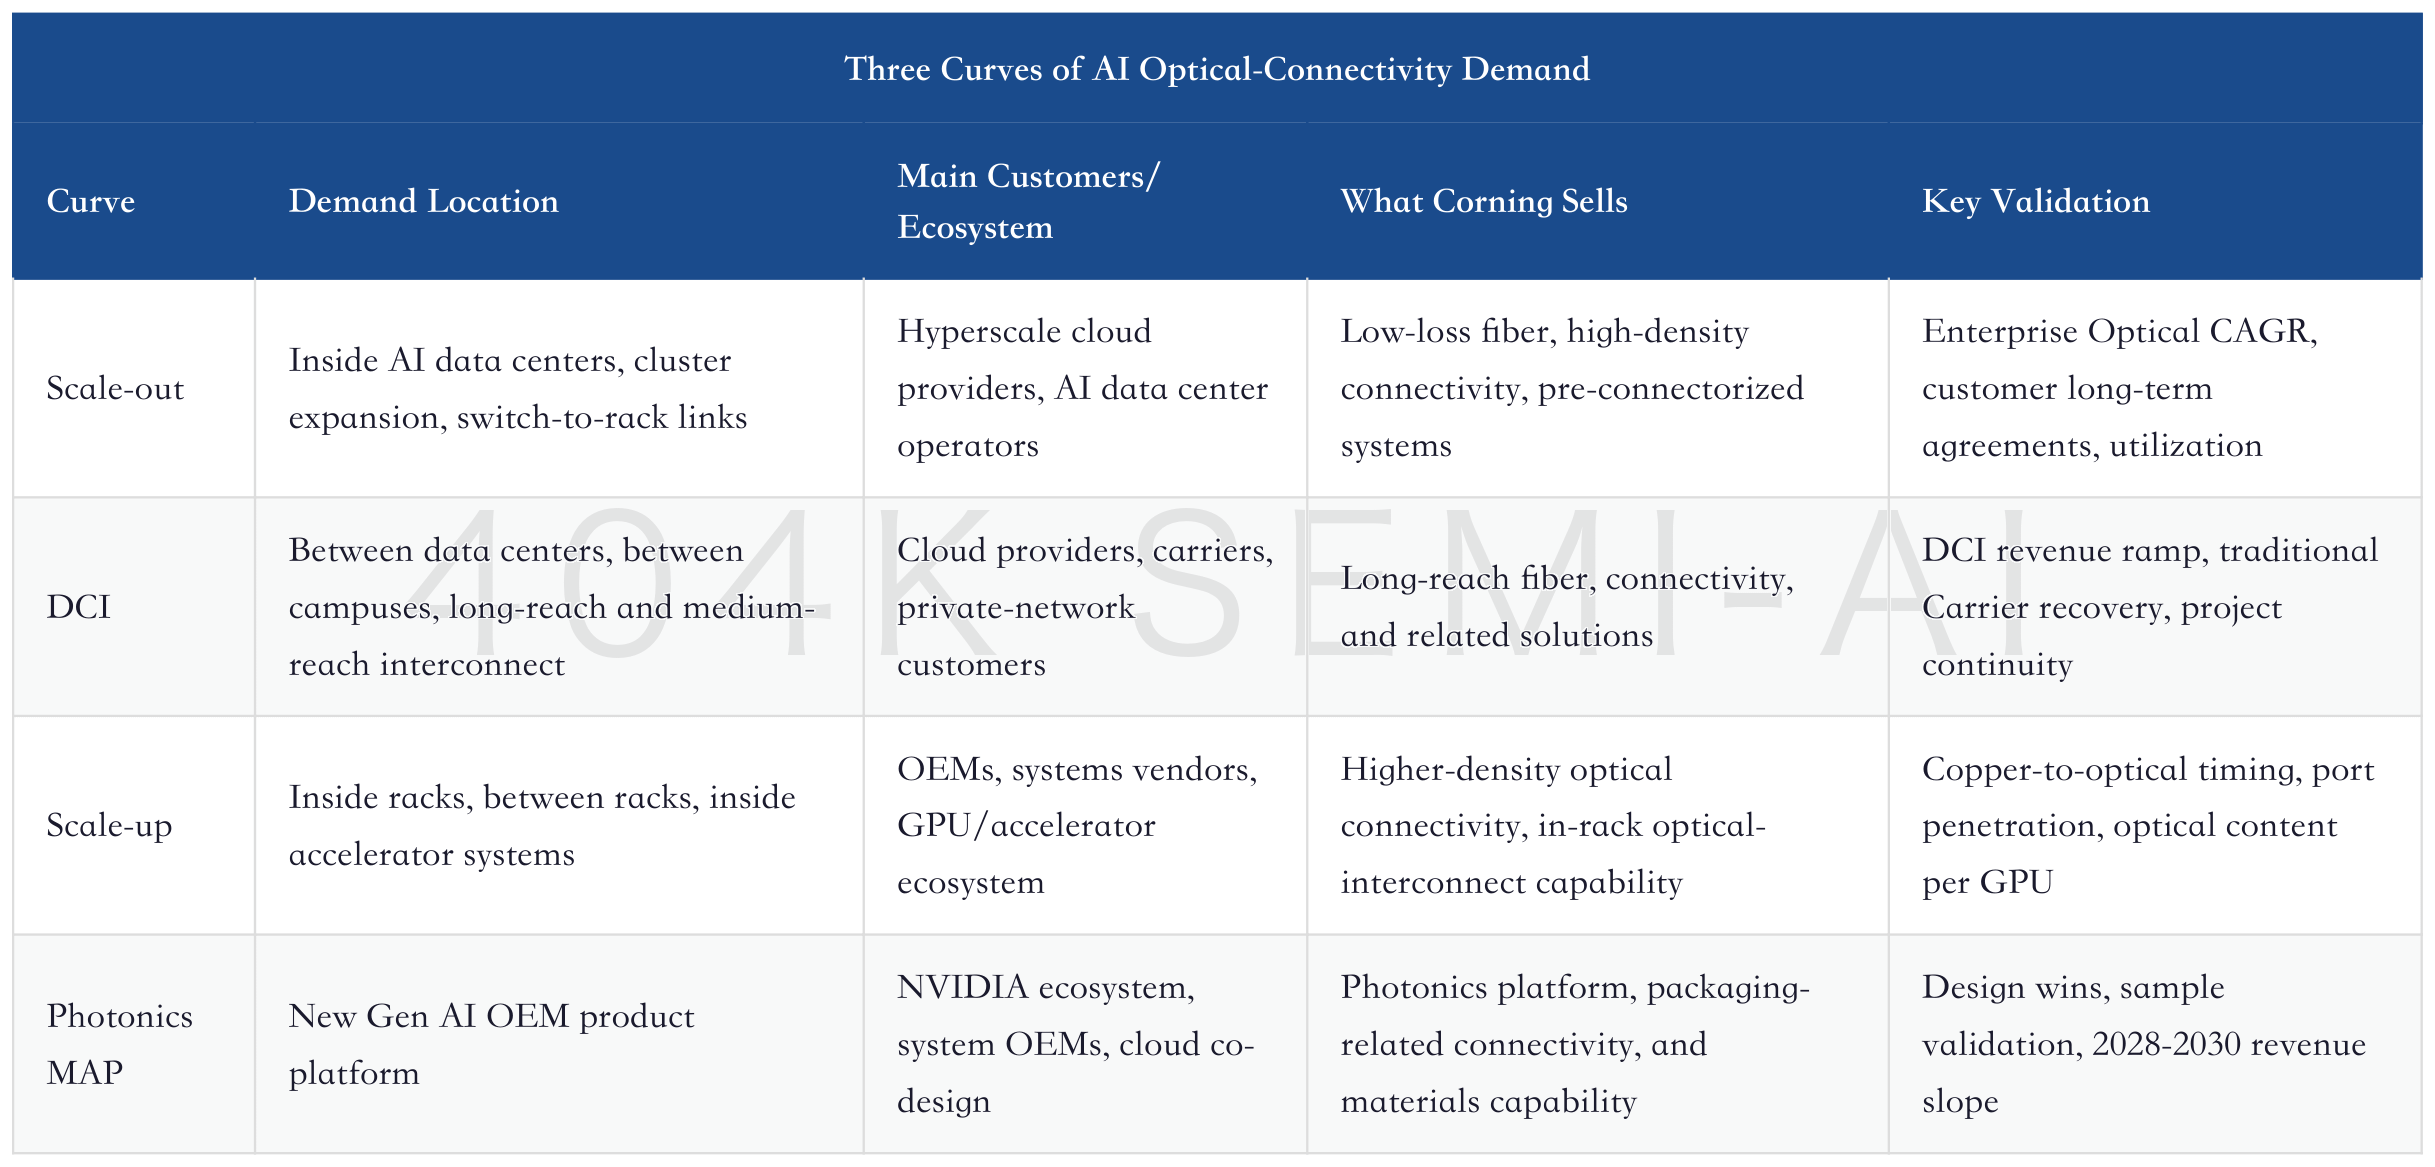
The profit quality of these three curves is not the same. Scale-out has the highest visibility because cloud providers are already building massive clusters, and Meta plus additional customer long-term agreements provide revenue anchors. DCI visibility is next, with demand likely to keep spreading as compute campuses are built in a distributed manner. Scale-up and Photonics have the highest ceiling but also the most debate, because they depend on architecture roadmaps, the pace of optoelectronic integration, systems-vendor design choices, and reliability validation.
Corning's advantage is that it does not sell only a piece of fiber. The company has deep accumulated capability in fiber invention, low-loss glass, connectors, optical physics, and manufacturing processes. In AI data centers, customers want a combined capability from fiber to connectivity and from materials to system-level delivery. Cloud providers will not risk delivery of an entire cluster to save a few cents on bare fiber, and systems vendors will not hand next-generation in-rack optical interconnect to a supplier without scaled manufacturing and a reliability track record.
Corning's constraints are also clear. The first is capacity. Expanding optical-connectivity and fiber capacity takes time, equipment, yield, and customer qualification; capacity is not released immediately once capex is committed. The second is architecture. The boundaries among copper, active copper cables, AEC, optical modules, CPO, NPO, and future Photonics will change with each generation of GPUs, switch chips, and rack designs. The third is competition. Japanese fiber manufacturers, U.S. optical-components companies, and Chinese fiber-cable and connector companies all compete in different parts of the chain. Corning is strong in the materials and connectivity-layer base, but that does not mean every incremental AI optical dollar will flow into its revenue.
Therefore, the best description of Corning is not "a beneficiary of AI fiber price increases," but "a long-duration platform absorbing rising optical-connectivity content in AI factories." The former is easy to treat cyclically. The latter explains why customers are willing to sign multi-year agreements, why NVIDIA is willing to support U.S. optical-connectivity capacity through a long-term collaboration, and why sell-side models extend from traditional Optical to Photonics in 2030.
IV. Springboard Is Not a Slogan, but a Financial Repricing Framework
The Springboard plan was initially easy for the market to treat as a management slogan: add some revenue, improve margins a bit, and lift cash flow. But execution in 2025-2026 shows that it is more like a financial framework for reorganizing a diversified materials platform into high-growth MAPs. Corning no longer tells the story simply by old segments. It manages Optical, Solar, Glass Innovations, Automotive, Life Sciences, and Emerging Growth Businesses across different growth curves.
Full-year 2025 core sales were US$16.41bn, and core EPS was US$2.52. In 1Q26, core sales were US$4.35bn, and core EPS was US$0.70. More importantly, core EPS growth continued to outpace revenue growth, indicating simultaneous improvement in costs, pricing, mix, scale effects, and capital efficiency. By 1Q26, core operating margin was still 20.2%. Since the Springboard starting point, the company's core sales have grown 33%, core EPS has grown 79%, and core operating margin and core ROIC have expanded by 390 bps and 470 bps, respectively.
Springboard's second function is to provide a debatable center for 2028 and 2030 models. At the end of 2025, the company raised its target for incremental annualized sales by the end of 2028 to US$11bn. After the May 2026 investor day, sell-side models moved around higher 2028 and 2030 revenue frameworks, with common discussions centering on roughly US$30bn of revenue in 2028 and roughly a US$40bn run-rate in 2030. Whatever the final number, the market has moved from "can Corning recover to pre-2024 margins?" to "can Corning build a high-margin Optical and Photonics platform much larger than its historical base by 2030?"
There is one important trap: the 2030 framework cannot be linearly extrapolated. The growth path from 2026 to 2030 contains at least four types of revenue with different levels of certainty. The first is the disclosed Meta and additional hyperscale customer long-term agreements, which have relatively high certainty. The second is undisclosed Enterprise Optical customers, DCI, and traditional Carrier recovery, which have medium certainty. The third is new Solar capacity and cost improvement, whose certainty depends on maintenance downtime, yield, and policy environment. The fourth is Photonics/scale-up, which has large opportunity but uncertain technology path and adoption.
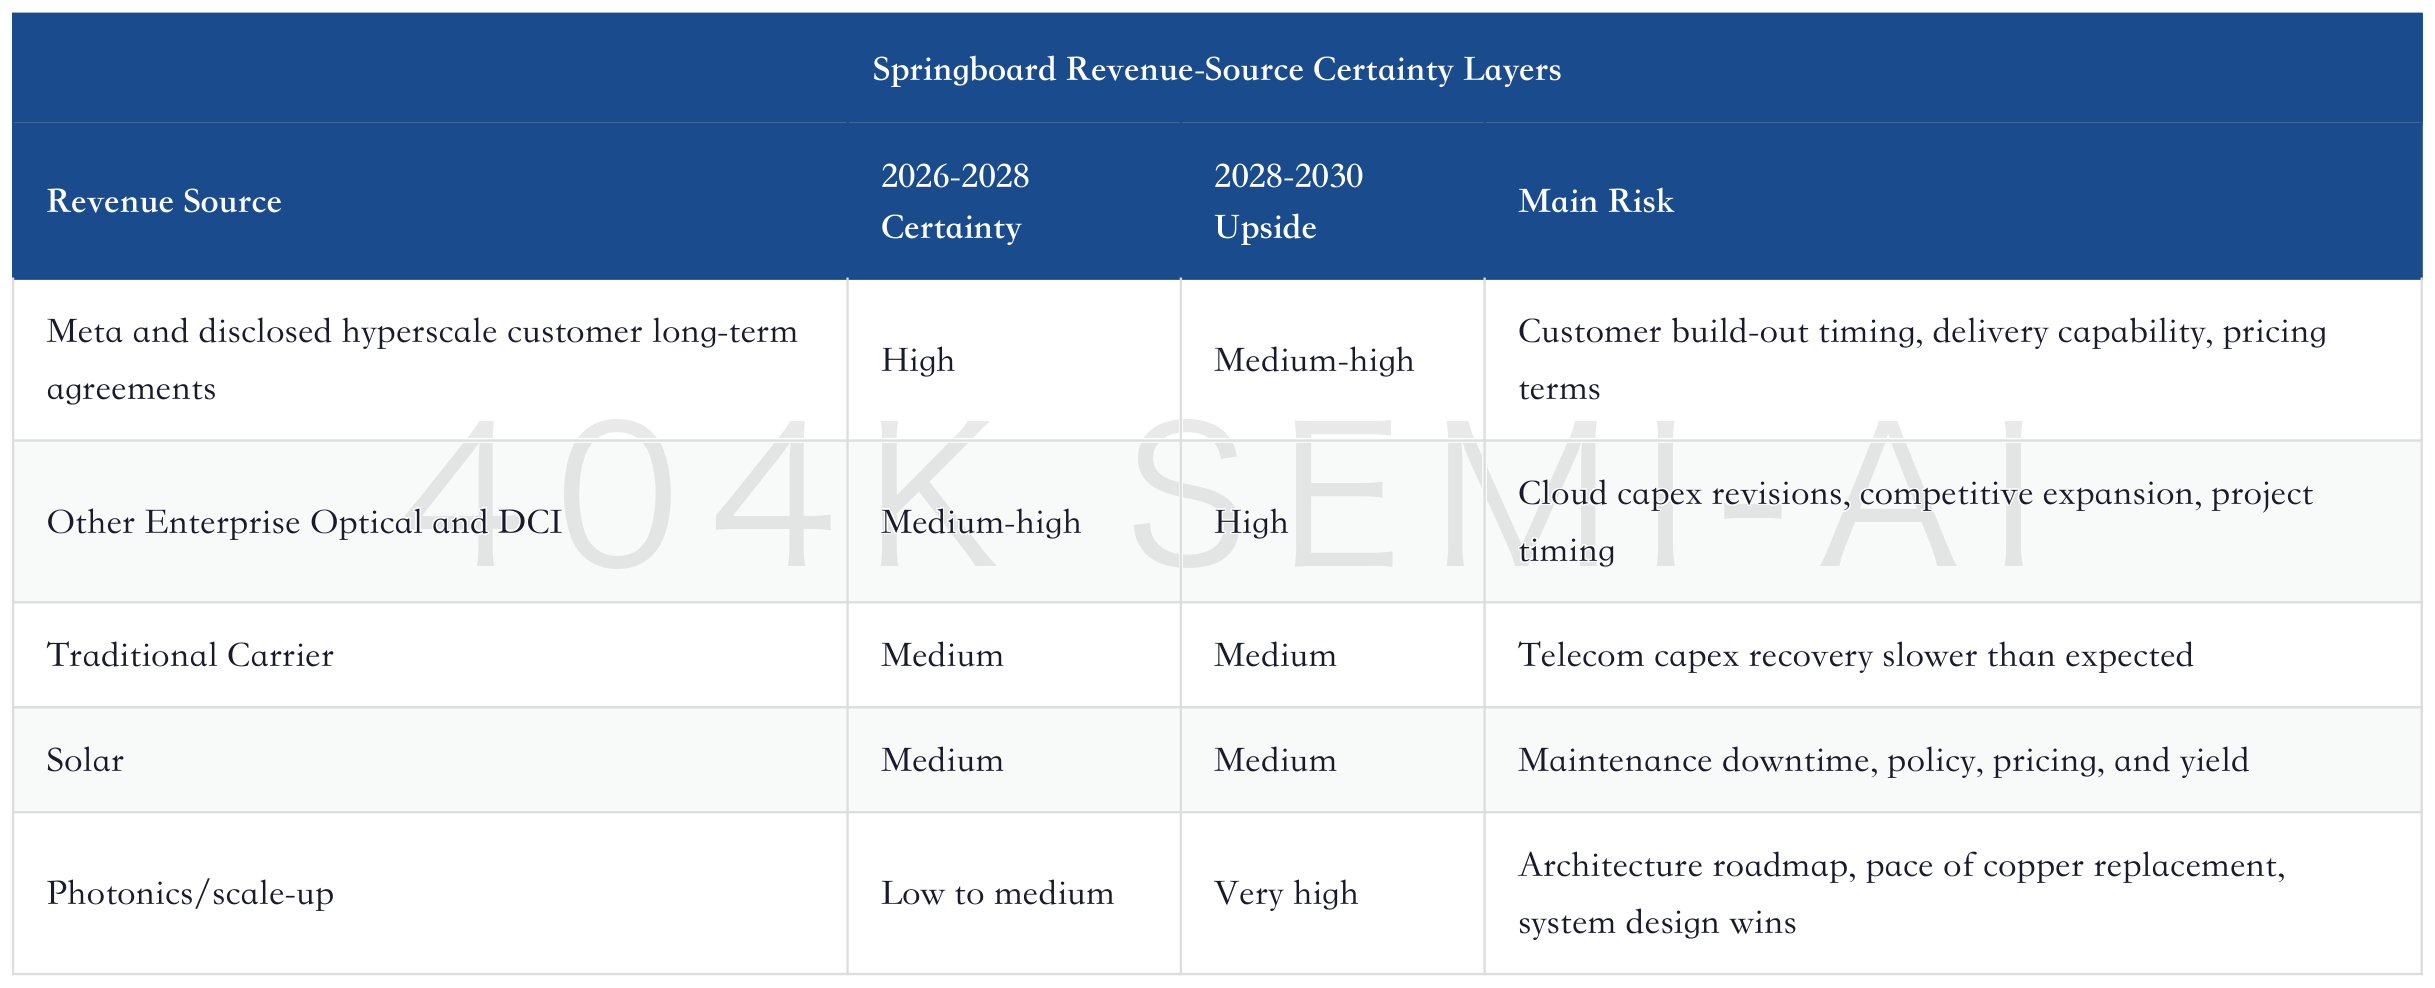
This is why sell-side disagreement has widened. After the May 2026 investor day, JPMorgan still maintained Neutral even though it wrote 2030 earnings power near US$8, because the stock already reflected substantial blue-sky expectations. Morgan Stanley argued that US$10 EPS in 2030 is not unreachable, but that the path depends heavily on Photonics, scale-up, and the growth slope. UBS was more optimistic, raising its price target to the US$223-US$228 area on the view that the market still underestimated the 2027-2030 revenue, margin, and EPS opportunity. The difference in conclusions is not about whether AI will grow. It is about how much Corning can capture, when it can capture it, and at what margin.
V. Where Sell-Side Models Differ: Not Price Targets, but Three Worldviews
From July 2025 to June 2026, sell-side price targets for Corning moved up quickly. JPMorgan moved from US$65, US$72, US$85, US$100, and US$115 to the US$175-US$185 area, but turned Neutral in April-May 2026 because the share price had already substantially reflected the optimistic 2030 scenario. UBS moved from US$65 Neutral to US$84 Buy, and then to US$109, US$125, US$160, US$171, US$179, US$223, and US$228, with the core driver being repeated upward revisions to Enterprise Optical, hyperscale capex, Photonics, and 2030 earnings opportunity. Morgan Stanley emphasized more strongly that expectations had already risen, with targets moving from US$50, US$56, US$75, US$82, and US$140 to US$180, while the rating generally remained Equal-weight.
These price targets should not be mechanically ranked. Report dates, share-price bases, dividends, valuation years, and multiple methodologies all differ. Some targets are based on year-end 2026 EPS, some on 2027 or 2028 NTM EPS, and some have begun to look at 2030 earnings power. A more useful reading is to divide the sell side into three worldviews.
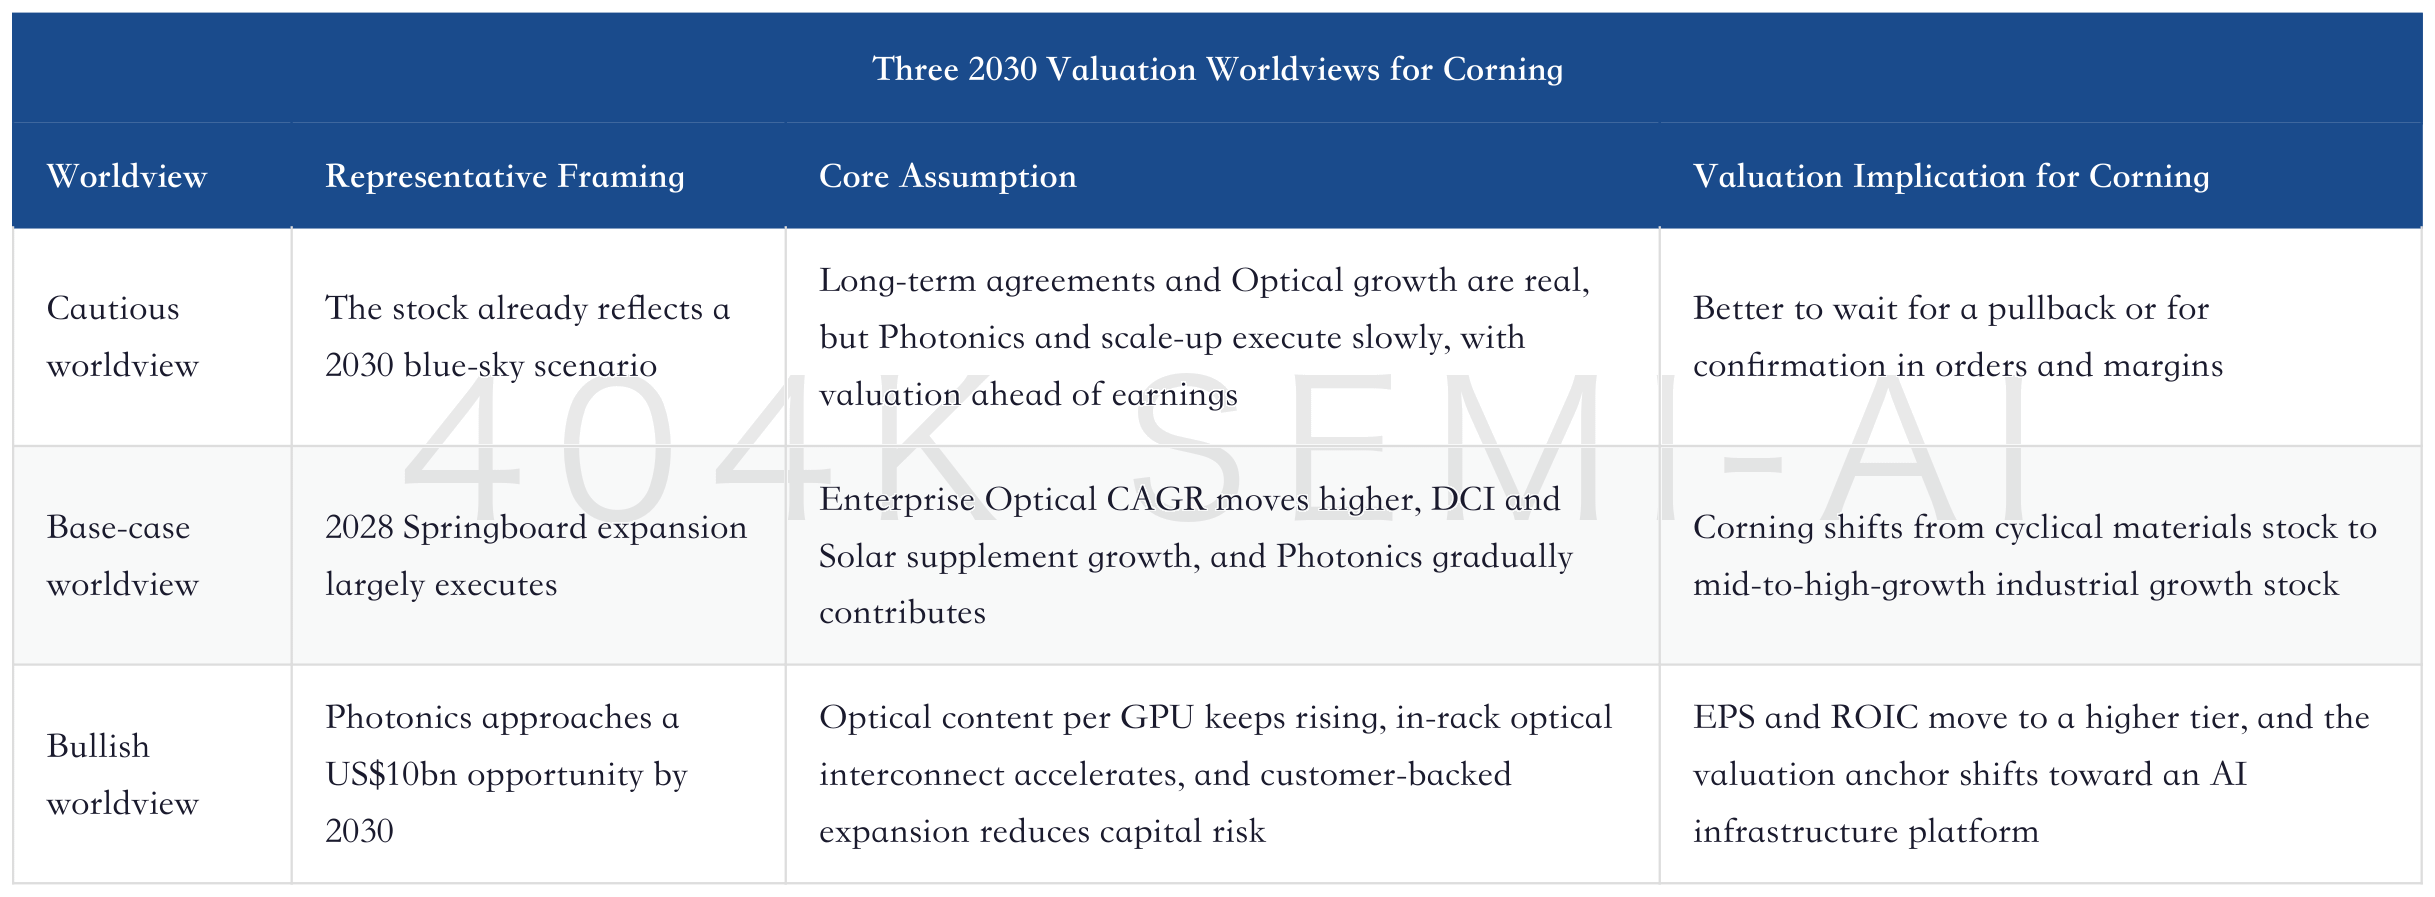
JPMorgan's shift is representative. Earlier, it consistently raised its price target and emphasized Optical, Meta, DCI, Solar, and Springboard. By May 2026, it acknowledged that the company's plan was stronger and that 2030 earnings power was still high, but it moved the rating to Neutral. This was not a bearish view on fundamentals. It was a risk-reward change: when the share price has approached or exceeded many revised-up targets, investors need harder execution evidence for Photonics, scale-up, and the 2030 internal plan.
UBS's logic is closer to "the growth slope is underestimated." Starting in September 2025, it upgraded Corning from Neutral to Buy, arguing that AI-driven fiber growth would exceed market expectations. After Meta in early 2026, UBS continued to raise numbers. After 1Q results in April, it lifted the target to US$179, and after the May investor day raised it further to US$223 and US$228. The core argument was that the 2027-2030 revenue, operating-margin, and EPS opportunity was larger, while PEG remained acceptable.
Morgan Stanley's neutral stance highlights another risk: Corning does not lack a good story; the good story has simply been priced rapidly. After the investor day, the 2030 framework, NVIDIA collaboration, and Photonics MAP were all strong. But if buy-side investors are already trading the stock on US$10 EPS in 2030 or an even higher revenue framework, any later shortfall in capacity, price, customer timing, or technology cadence could compress the multiple.
Bank of America's model best illustrates the blue-sky opportunity. Its March and April 2026 reports separated scale-out, scale-up, DCI, and the Optical TAM, discussing how 2030 revenue and EPS could be far above traditional consensus. In more optimistic scenarios, Optical contributes very substantially to company revenue and EPS, and its 2030 scale could come close to reshaping the whole company. The value of this model is not that it provides a number that must be achieved. It shows investors that if optical content per GPU, AI data center scale, and in-rack optical connectivity all rise together, Corning's revenue ceiling could be much higher than that of a traditional fiber producer.
VI. Company Capability: Why Corning, Not an Ordinary Fiber Manufacturer
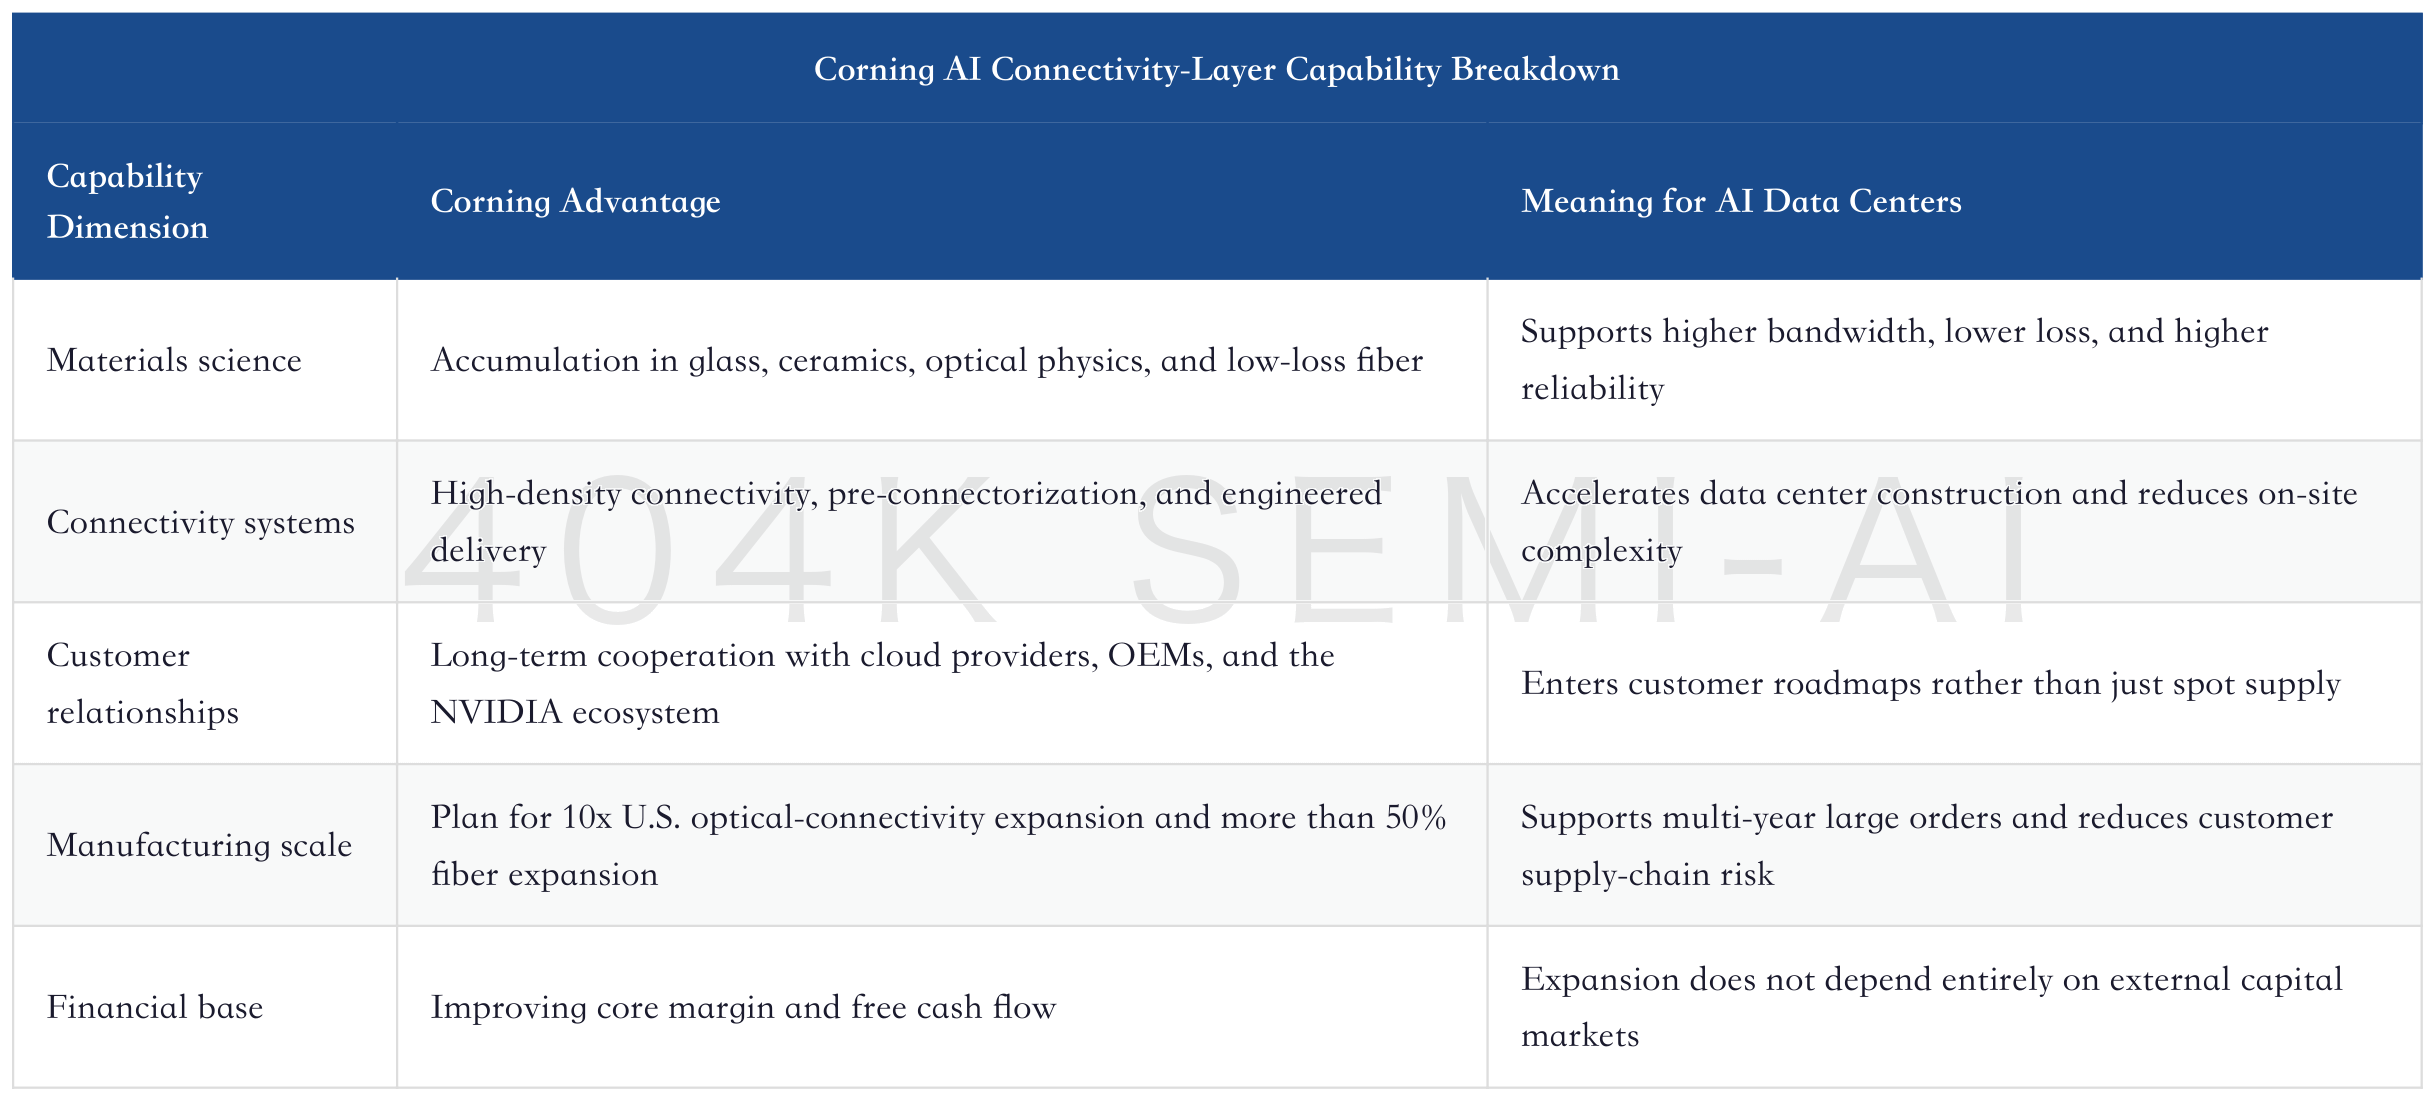
Corning's moat is not just "it can draw fiber." Low-loss fiber is only the entry point. The real barrier is an engineering capability formed by materials science, optical physics, connectivity systems, customer co-design, manufacturing yield, and capex timing.
First, Corning is one of the inventors of low-loss fiber, and its long-term accumulation has become valuable again in the AI era. In telecom fiber, the core issue was transmission cost per unit distance and carrier investment cycles. In AI data centers, the core issues are bandwidth density, power consumption, connectivity reliability, and deployment speed. Low loss, bend performance, high-density connectivity, and pre-terminated solutions directly affect delivery efficiency in hyperscale build-outs.
Second, Corning does not sell materials in isolation. It approaches customers through MAPs. A Market-Access Platform means combining materials, processes, products, and customer scenarios to enter the customer's future roadmap. The Meta multi-year agreement, long-term agreements with two additional hyperscale customers, and NVIDIA collaboration all show that customers are not merely buying standard parts. They are using Corning's manufacturing capability to plan next-generation AI data centers.
Third, scaled manufacturing is the threshold for the AI connectivity layer. Once AI optical-connectivity demand enters large cloud-provider deployments, order scale, quality requirements, and delivery windows become extremely demanding. Smaller suppliers may innovate at a single technical point, but it is difficult for them to support multi-campus, multi-year, cross-product capacity commitments. Corning's plan to expand U.S. optical-connectivity capacity by 10x, increase fiber capacity by more than 50%, and build three new facilities requires customers, equipment, processes, capital, and yield to align.
Fourth, Corning has multi-segment cash flow to support expansion. Adjusted free cash flow was US$1.72bn in 2025, while core operating margin and ROIC both improved materially. This differentiates Corning from many pure-play small-cap optical companies: Corning has a larger asset base and financing capability, allowing it to undertake front-loaded expansion with support from customer long-term agreements rather than relying entirely on external financing or a single product cycle.
TFC Communication Deep Dive: From Optical-Component Supplier to AI Optical-Engine Platform, and the Upstream Rerating from 1.6T, NPO, and CPO
This capability set also defines Corning's position in the AI optical-interconnect value chain. It is not a transceiver brand. It does not compete with NVIDIA GPUs or Broadcom switching ASICs on the "compute narrative." Nor is it simply a small passive-connector supplier. Corning is more like a foundational physical-layer materials and connectivity-systems company: when architecture changes push optical into more distances, higher densities, and higher-reliability scenarios, it can absorb incremental demand through materials and manufacturing capability.
The risk is that foundational companies do not always receive the highest valuation multiple. In the AI value chain, profit allocation among chips, switching ASICs, optical modules, optical components, and connectivity materials is not fixed. Corning needs to prove that it is not merely bearing capex and capacity responsibility, but can retain pricing, mix, and margin advantages in long-term agreements. That is why Optical segment margin, core operating margin, and ROIC matter more than revenue growth alone.
VII. Peer Positioning: Corning Sits at the "Materials and Connectivity Base" of Optical-Interconnect Value Migration
To position Corning inside the AI optical-interconnect chain, the different layers must first be separated. Upstream includes glass preforms, fiber, cable, connectors, ceramics, and optical materials. Midstream includes optical components, lasers, detectors, silicon photonics, thin-film lithium niobate, EML, CW light sources, and optical-module packaging. Downstream includes switches, GPU/accelerator systems, cloud data centers, and carrier networks. Corning's core is not module assembly. It is the upstream base in materials, fiber, connectivity, and future Photonics.
