
目录
TL;DR
1. What the Second Quarter Actually Resolved: “Can CoreWeave Deliver?”
2. The $104.2 Billion Backlog Matters, but It Is Not $104.2 Billion in Cash
3. 1.5GW Is Not the Destination, but a Capital-Conversion Curve
4. A 25% Price Increase Stands Out, but Margin Upside Depends on Contract Deployment
5. Why a 59% Adjusted EBITDA Margin Still Does Not Produce Net Profit
6. Positive Operating Cash Flow Does Not Mean Expansion Is Self-Funded
7. Managed Inference Is the Platform Experiment Most Worth Watching
8. Why Three Banks Arrived at $74–$120 Based on the Same Facts
9. Five Validation Points to Watch Over the Next Two Quarters
Conclusion: A Better Operating Report Card, but Not Yet Proof of Returns on Capital
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
CoreWeave has proven that it can convert power and GPUs into revenue faster, but not yet that this growth will ultimately leave sufficient cash for common shareholders.
TL;DR
Second-quarter revenue reached $2.575 billion, up 112% year over year, while adjusted operating income of $128 million materially exceeded market concerns. The real narrative-changing evidence was the addition of nearly 500MW of active power in a single quarter, bringing the total to 1.5GW. This shows that the company’s large backlog is beginning to move through the physical delivery chain of data-center construction, power supply, GPU delivery, and cluster commissioning.
Demand remains secondary to execution. Backlog stood at $104.2 billion at quarter-end, excluding more than $25 billion of new customer commitments secured early in the third quarter. Contracted power had risen from 3.7GW at quarter-end to approximately 4.2GW by the earnings call. The question has shifted from whether customers exist to when capacity will come online, at what margin, and with how expensive a capital structure.
Evidence of pricing power has strengthened: average prices across SKUs rose approximately 25% in July, typical contribution margins on newly signed contracts were 5—10 percentage points above those on recent additions, and A100 contracts were signed through 2029. However, these developments largely occurred after the second quarter. They cannot directly explain the reported 5% adjusted operating margin, nor should contract contribution margins be equated with company-level net margins.
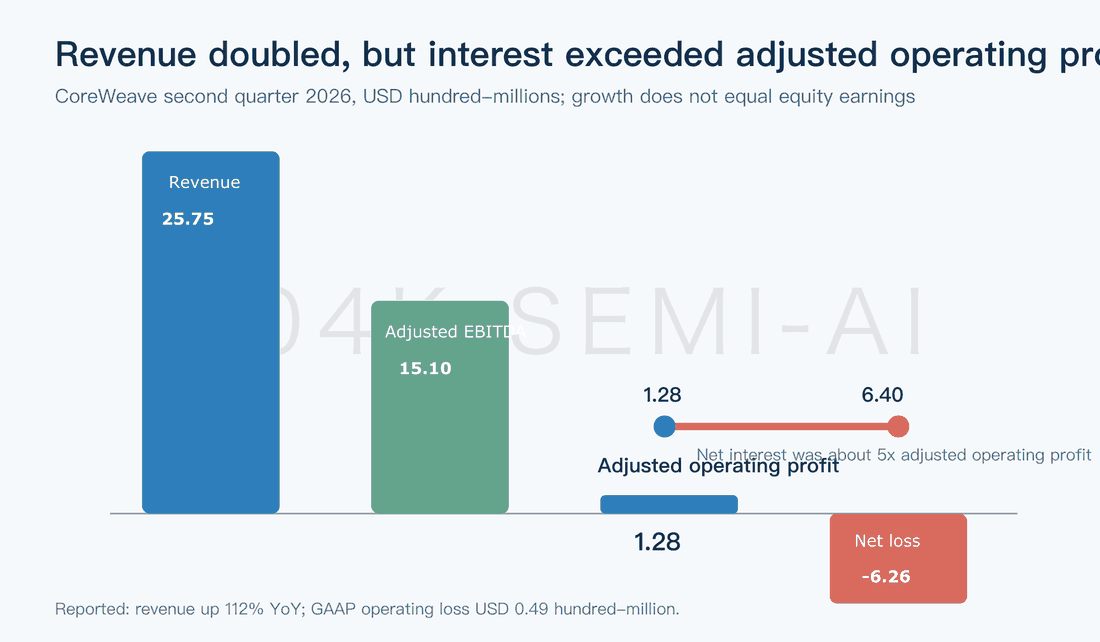
The largest accounting and economic disconnect remains below the operating line. Adjusted EBITDA reached $1.51 billion, representing a 59% margin, yet net interest expense was $640 million—approximately 5 times adjusted operating income. After depreciation, stock-based compensation, interest, and taxes, the company still recorded a net loss of $626 million. High EBITDA proves the assets are operating; it does not mean common shareholders are already earning a return.
Operating cash flow totaled $3.663 billion in the first half, while purchases of property and equipment plus capitalized software spending reached $14.117 billion. Over the same period, net investing cash outflow was $14.874 billion and net financing cash inflow was $13.985 billion. CoreWeave has liquidity, but continued expansion still requires a relay of debt, convertible notes, and equity financing.
All 3 investment banks acknowledge improved near-term execution, yet their price assessments diverge sharply at $74, $99, and $120. The disagreement is not about the second quarter. It is about whether power will remain scarce after 2028, whether GPUs can be re-leased, whether financing costs can continue to decline, and whether managed inference can turn one-off infrastructure demand into recurring platform revenue.
1. What the Second Quarter Actually Resolved: “Can CoreWeave Deliver?”
CoreWeave’s business model is straightforward: secure customer demand and power resources, finance data-center construction and purchases of GPUs and networking equipment, then deliver commissioned clusters to customers and begin billing. The challenge is that contracts, land, power, equipment, construction, networking, and software must all align within the same timeframe. If any link is delayed, construction costs and interest expense accrue before revenue can be recognized.
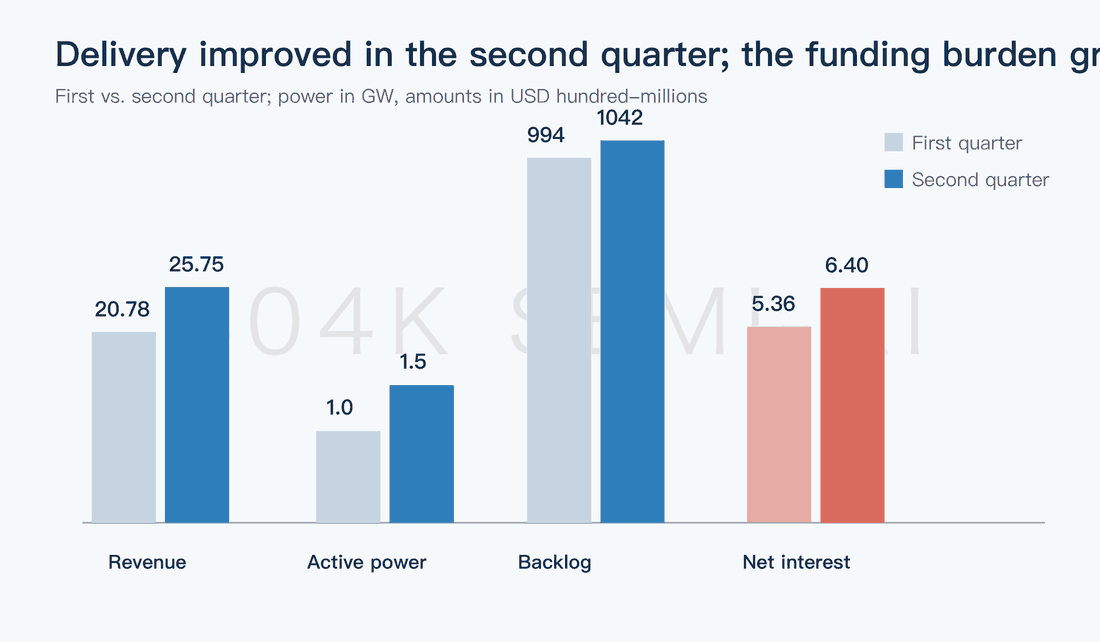
In the first quarter, CoreWeave already had approximately $99.4 billion of backlog and more than 1GW of active power. The market’s primary concern was not demand, but that orders were growing far faster than physical delivery. The company added nearly 500MW in the second quarter alone, lifting total active power to 1.5GW, including more than 300MW added in June. This was the quarter’s most consequential development: it demonstrated that CoreWeave could execute large-scale parallel deployments within a single quarter, while revenue increased from $2.078 billion in the first quarter to $2.575 billion.
Because the new capacity came online late in the quarter, it contributed only a short period of billable revenue in the second quarter. Management expects most of its impact to appear in the third and fourth quarters, supporting third-quarter revenue guidance of $3.45 billion—$3.6 billion. In other words, second-quarter power capacity is a leading indicator of future revenue, not a coincident outcome of this quarter’s revenue. If third-quarter revenue does not rise accordingly, that would point to a new bottleneck in commissioning definitions, utilization, or customer acceptance.
At the same time, improved delivery did not reduce the capital burden. Net interest expense rose from $536 million in the first quarter to $640 million in the second, while quarterly capital expenditure increased from $6.786 billion to $9.352 billion. CoreWeave cleared an important execution hurdle but carried a much larger capital base into the next quarter. The market is no longer asking whether the company can build; it is asking whether, at greater scale, revenue per unit can cover depreciation and financing costs.
2. The $104.2 Billion Backlog Matters, but It Is Not $104.2 Billion in Cash
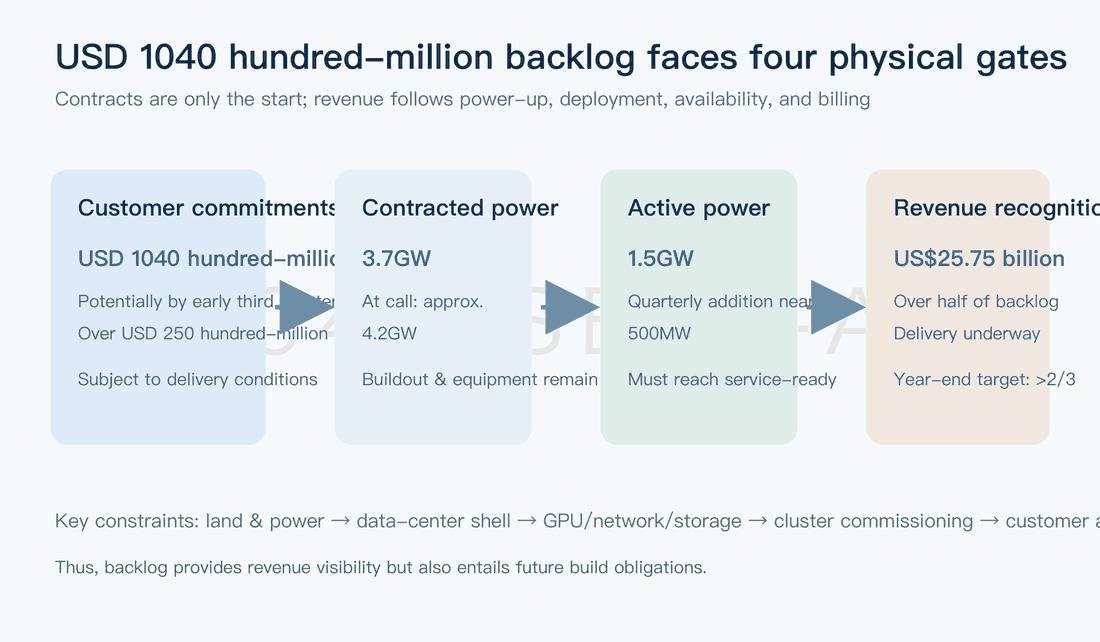
Backlog reached $104.2 billion at the end of the second quarter, up from $99.4 billion in the first quarter, and excluded more than $25 billion of new customer commitments secured early in the third quarter. This figure shows that customers are willing to assume long-term obligations for future compute capacity, giving CoreWeave considerable visibility for financing, procurement, and construction. More than half of the backlog is already being delivered, and management expects that proportion to exceed two-thirds by year-end, indicating that the order book is not merely contractual capacity on paper.
But backlog cannot be treated as revenue at face value, much less as cash. First, contracts typically span multiple years, and revenue recognition depends on when capacity is delivered. Second, contracted power and active power are not interchangeable. Contracted power was 3.7GW at quarter-end and approximately 4.2GW by the earnings call, while active power already online and capable of supporting customer workloads was only 1.5GW. The approximately 2.7GW gap represents future opportunity, but also unfinished capital expenditure, engineering, and financing obligations.
Nor should backlog and the customer commitments secured early in the third quarter simply be added together as though they were reported on the same basis. The former is included in the company’s formally disclosed contractual backlog; the latter consists of incremental commitments received after quarter-end. Together, they confirm strong demand, but the timing of revenue, contract duration, cancellation and delay provisions, and customer concentration will still determine realized value. In particular, when major customers also depend on capital markets to expand AI spending, customer credit, contract-backed financing, and CoreWeave’s own debt capacity may become interconnected.
The correct sequence for analyzing the order book is therefore: determine whether the contract has been signed, whether the associated power has been secured, whether the data center has been completed, whether the GPUs and networking equipment are in place, and finally whether the customer has accepted delivery and billing has begun. Any valuation methodology that jumps directly from $104.2 billion to enterprise value omits the business model’s most expensive and delay-prone stages.
3. 1.5GW Is Not the Destination, but a Capital-Conversion Curve
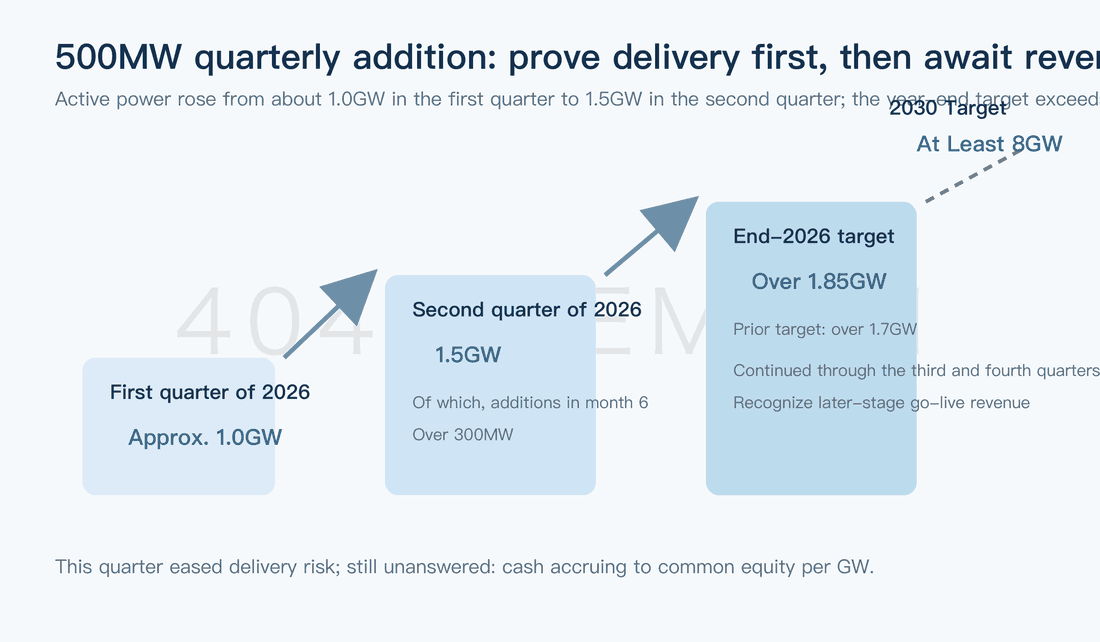
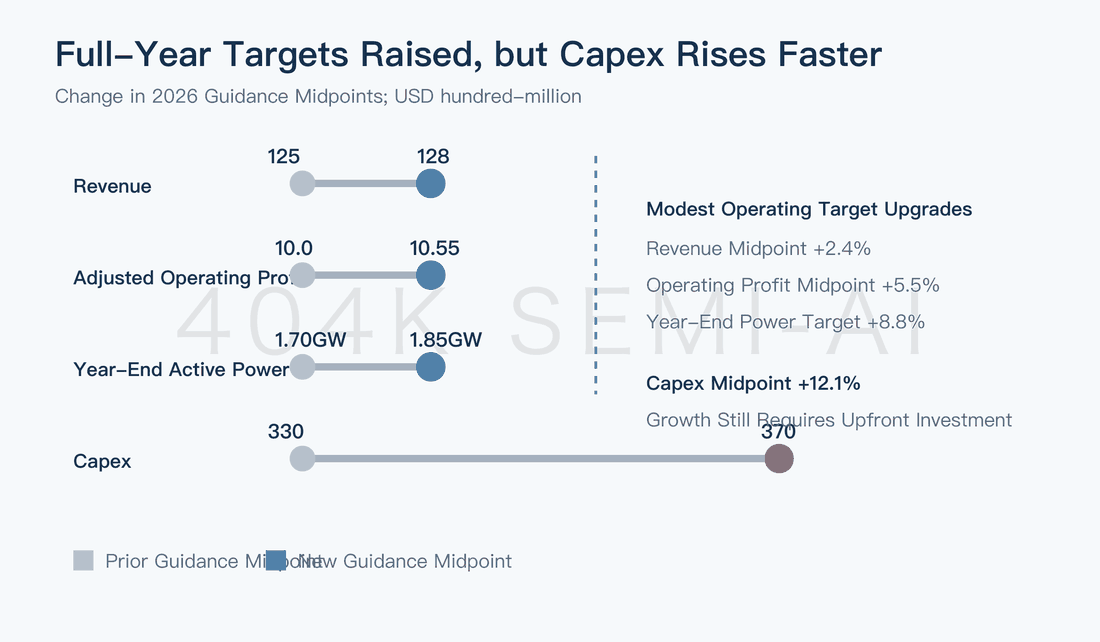
CoreWeave raised its year-end active-power target from more than 1.7GW to more than 1.85GW, while retaining its 2030 target of at least 8GW. Beyond the approximately 4.2GW of contracted power reported at the earnings call, the company disclosed approximately 1.5GW of actionable land and power options, expansion arrangements, and prospective resources. Viewing the 4.2GW of contracted power alongside approximately 1.5GW of potential resources provides substantial visibility into long-term construction, but neither measure can be mechanically added to the 1.5GW of active power.
Active power is capacity already in operation. Contracted power represents resources backed by commercial commitments but still at various stages of construction. Potential resources require further contracting, permitting, interconnection, and development. Their risk and value profiles are entirely different. Rather than combining them into a larger headline figure, investors should track how much contracted power converts into active power each quarter, capital expenditure per MW, and the time required to reach stable utilization after commissioning.
The 500MW added in the second quarter materially increased confidence in delivery, but the year-end target of more than 1.85GW still requires at least approximately 350MW of additional capacity in the second half. That target is not prohibitively aggressive; the real test is whether margins improve alongside deployment. If substantial third-quarter capacity again comes online in the middle or near the end of the quarter, costs will precede revenue recognition once more. Management has therefore guided to a third-quarter adjusted operating margin midpoint of only approximately 6.5%, with low-double-digit margins expected only in the fourth quarter.
Power expansion will also reshape revenue quality. Long-term contracts with major customers support asset-backed financing but increase concentration. Two- to three-year enterprise contracts broaden the addressable market but leave CoreWeave with greater renewal and residual-value risk. The economic life of the assets can exceed the initial contract term only if the same GPUs continue to attract demand after the first contract expires or can be redeployed to new workloads such as managed inference.
4. A 25% Price Increase Stands Out, but Margin Upside Depends on Contract Deployment
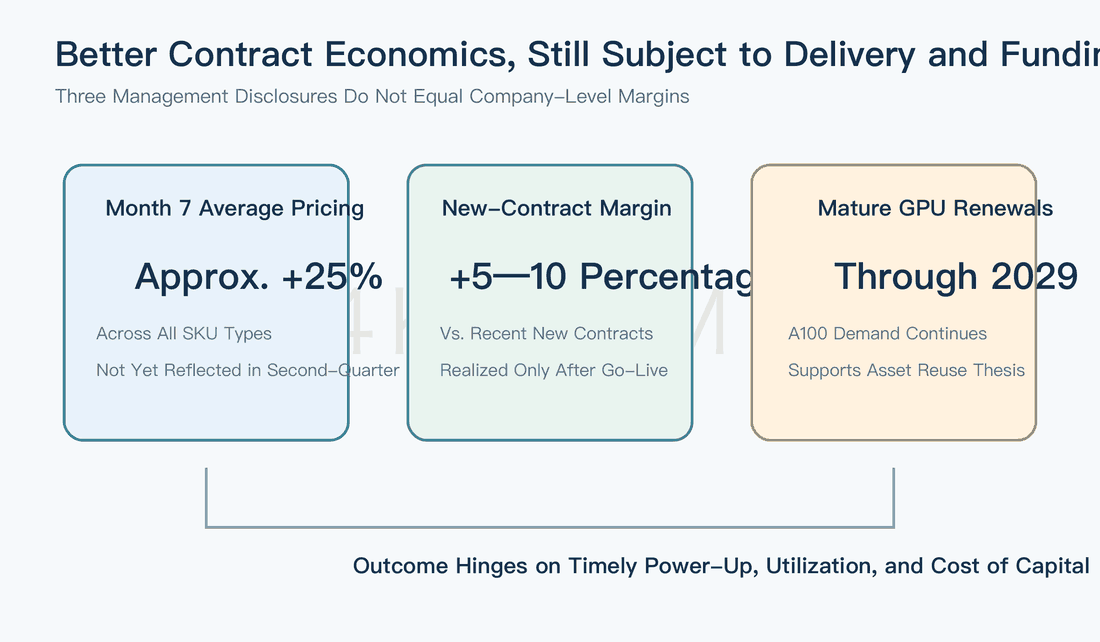
The strongest demand signal from the earnings call was the approximately 25% average price increase across SKUs in July. Management attributed this primarily to tight supply-demand conditions and accelerating customer returns on AI investment, with component-cost pass-through playing only a secondary role. Meanwhile, newly signed contracts carry contribution margins 5—10 percentage points above those added recently, while Vera Rubin delivers better economics starting with the first contracts.
These figures suggest CoreWeave is no longer winning orders simply because it has capacity available; it is beginning to monetize scarce capacity, deployment speed, and platform performance. However, there are at least three limitations. First, the price increase occurred in July and therefore had virtually no impact on second-quarter results. Second, contribution margin generally measures contract-level profit after direct costs and excludes corporate overhead, depreciation, stock-based compensation, interest, and taxes. Third, prices and equipment costs locked in when contracts are signed will translate into earnings only if future deployments remain on schedule.
A100 contracts extending through 2029 help alleviate concerns that older GPUs will rapidly lose value. They show that earlier-generation GPUs do not necessarily become obsolete as soon as new products launch, as customers remain willing to pay for hardware suited to particular training, inference, or enterprise workloads. This lends greater credibility to assumptions about equipment reuse and residual value, but one contract does not prove that every older GPU can be renewed at the same price and utilization rate. The key metrics to track are recontracting rates, contract duration, revenue per unit of power, and the incremental capital expenditure required to redeploy older equipment into managed inference.
The 25% price increase should therefore be viewed as an option on future margin expansion, not profit already realized. If adjusted operating margin reaches the low teens in the fourth quarter without another disproportionate increase in capital expenditure, it would indicate that pricing and deployment are beginning to generate company-wide operating leverage. If revenue surges while operating margin remains in the mid-single digits, construction delays, equipment costs, or platform expenses may still be consuming the contract-level gains.
5. Why a 59% Adjusted EBITDA Margin Still Does Not Produce Net Profit
CoreWeave reported second-quarter adjusted EBITDA of $1.51 billion, representing a margin of approximately 59%; adjusted operating profit was $128 million, with a 5% margin; GAAP operating loss was $49 million; and net loss widened further to $626 million. These figures are not contradictory—they reflect different layers of a capital-intensive business model.
Adjusted EBITDA excludes depreciation, amortization, stock-based compensation, and other items. It is useful for assessing the operating cash earnings generated by deployed assets, but it does not capture the full cost of building those assets. As CoreWeave rapidly expands its GPU fleet, data-center equipment, and capitalized software, depreciation and amortization flow through the income statement. Adding those expenses back makes EBITDA appear high, but does not make the equipment free.
Adjusted operating profit includes depreciation and amortization but still excludes certain noncash or nonrecurring items, which explains the sharp decline from $1.51 billion to $128 million. Further down the income statement, net interest expense of $640 million alone was approximately 5 times adjusted operating profit. Even before considering other items, current operating profit is insufficient to cover financing costs. For common shareholders, this is the quarter’s most important income-statement fact.
The company emphasized that its weighted-average cost of debt has declined by nearly 300 basis points over the past year. Based on quarter-end debt, that equates to approximately $1.1 billion in annual interest savings. This is a genuine improvement, but it has coincided with rising total interest expense: the cost of debt is falling, but principal is expanding faster. Third-quarter net interest expense is guided to $860 million—$940 million, well above the second quarter. Any fourth-quarter margin improvement must therefore first offset a growing financing burden before it can benefit net income.
It is also important to distinguish between “narrowing accounting losses” and “increasing equity value.” If debt-funded equipment is deployed on schedule and can continue generating rental income after the initial contracts expire, upfront interest and depreciation can be spread over a longer asset life. Conversely, if GPU prices decline, customers shorten contract terms, or newer equipment displaces older hardware more quickly, the company may need to keep financing successive hardware refreshes even while maintaining high EBITDA. The real inflection point is not an incidental quarter of positive net income, but the ability to generate distributable cash after operating profit consistently covers net interest, maintenance capital expenditure, and taxes.
6. Positive Operating Cash Flow Does Not Mean Expansion Is Self-Funded
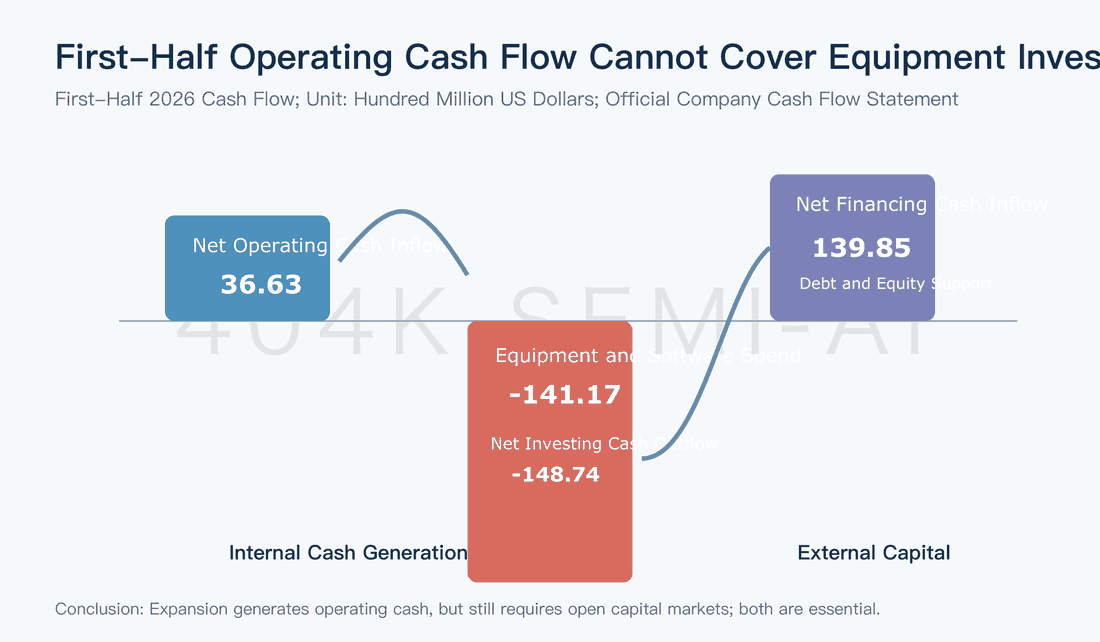
For the six months ended June, CoreWeave generated $3.663 billion of operating cash flow. Purchases of property and equipment and capitalized software totaled $14.117 billion, while net investing cash outflow reached $14.874 billion; net financing cash inflow was $13.985 billion. Put simply, the existing business does generate cash, but nowhere near enough to fund the equipment and infrastructure required by the current pace of expansion.
At the end of June, cash, restricted cash, and marketable securities totaled approximately $6.919 billion; recourse and non-recourse debt totaled approximately $35.068 billion; and operating lease liabilities were approximately $16.319 billion. These figures cannot be netted directly: restricted cash is subject to usage constraints, non-recourse debt has distinct collateral and cash-flow boundaries, and lease liabilities represent long-term data-center usage rights. Together, however, they show that CoreWeave is an infrastructure platform dependent on a complex capital structure—not an asset-light software company.
New financing structures such as DDTL 5.5 allow the company to use shorter-duration customer contracts to support asset-backed financing. This enables CoreWeave to serve more enterprise customers seeking two- to three-year terms rather than relying exclusively on traditional five-year contracts. The structure can expand the addressable market and support higher pricing, but it does not eliminate risk—it reallocates it. As initial contract terms shorten, equipment residual values, renewals, and refinancing become more important. If GPUs cannot be redeployed at reasonable prices after contract expiration, the premium on shorter contracts may not compensate for idle capacity and depreciation.
The capital structure also affects CoreWeave’s growth optionality. When financing markets are open, the company can secure GPUs and power in advance and build capacity ahead of demand, reinforcing its deployment-speed advantage. When credit spreads widen or the share price weakens, the same construction program may require higher interest rates, additional collateral, or greater equity dilution. Customer contracts represent both future revenue and financing collateral, creating a feedback loop between demand and capital availability: expansion accelerates during upcycles, but any disruption to customer credit or financing can simultaneously propagate through contracts, debt, and construction schedules.
Full-year capital-expenditure guidance was raised from $31 billion—$35 billion to $35 billion—$39 billion, increasing the midpoint by $4 billion. Meanwhile, the midpoint of full-year revenue guidance rose only from $12.5 billion to $12.8 billion, while the midpoint of adjusted operating profit guidance increased from $1 billion to $1.055 billion. Capital-expenditure guidance is rising faster than operating targets, indicating that management is pre-funding a larger 2027 revenue base rather than having already achieved a cash-flow inflection point this year.
7. Managed Inference Is the Platform Experiment Most Worth Watching
If CoreWeave can only rent GPUs under long-term contracts, its economics will remain highly dependent on customer concentration, contract duration, and capital markets. The strategic value of managed inference lies in partitioning existing GPU capacity into on-demand services, using software orchestration, model deployment, and inference optimization to improve utilization while serving enterprise customers unwilling to sign long-term take-or-pay contracts. It could both expand the customer base and provide a second use for equipment after its initial contract expires.
Booked annual recurring revenue for managed inference has increased from approximately $1 million at launch to more than $100 million, and the company is targeting at least $250 million by year-end. The annualized revenue run rate from storage, CPUs, networking, and software outside the GPU business has also exceeded $400 million. Relative to quarterly revenue of $2.575 billion, these businesses remain small, but their growth and strategic positioning deserve attention. If they improve customer retention, utilization per GPU, and gross margin, CoreWeave could evolve from a capacity reseller into a platform-services provider.
The trade-off is that managed inference replaces the customer credit risk of long-term contracts with utilization, retention, price competition, and service-quality risks. Usage-based revenue is more flexible but also more volatile; maintaining low latency and peak capacity may require the company to hold idle resources. Hyperscale cloud providers have larger customer funnels, broader software ecosystems, and lower costs of capital. CoreWeave must demonstrate that the performance and deployment speed of its specialized platform are sufficient to offset those disadvantages.
In the near term, the $250 million year-end target can validate demand, but it will not establish profitability. More important indicators include how much existing GPU capacity managed inference consumes, whether it requires incremental capital expenditure, its gross margin and renewal rate, and whether it can absorb equipment rolling off long-term contracts. Only as these data become available can the platform strategy move from narrative to modelable cash flow.
8. Why Three Banks Arrived at $74–$120 Based on the Same Facts
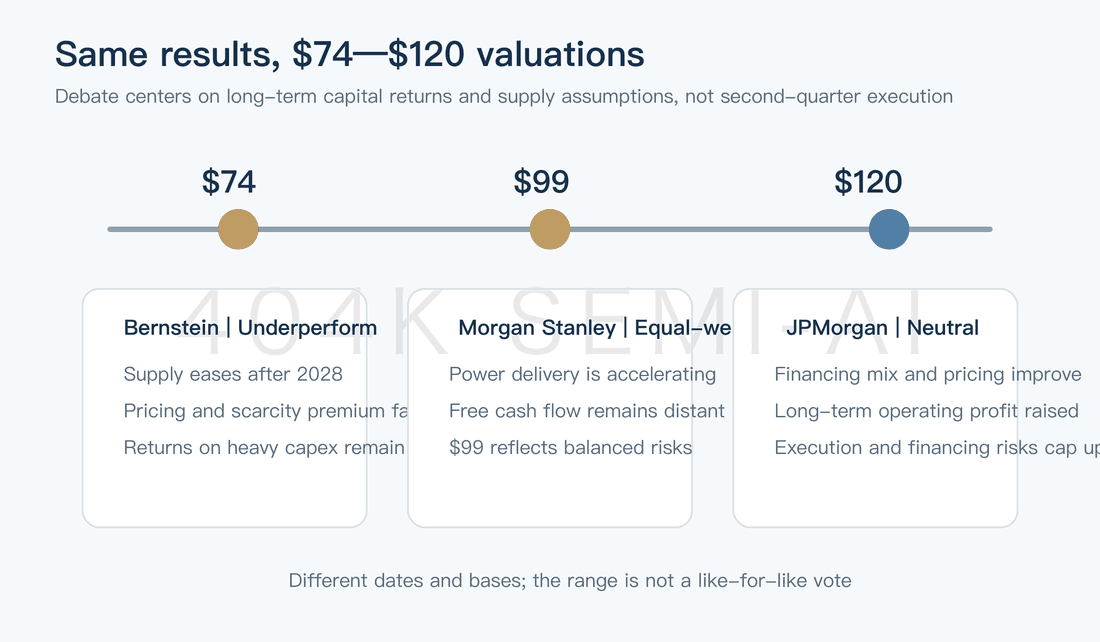
Morgan Stanley, JPMorgan, and Bernstein broadly agree on the quarter’s fundamentals: revenue and adjusted operating profit exceeded expectations; 500MW of incremental active power increased confidence in delivery; and backlog, price increases, and margins on new contracts confirmed that demand remains strong. Their real disagreement is over how long these improvements can last and what multiple should be applied to future earnings.
Morgan Stanley maintained its “Equal-weight” rating and $99 price target. Its framework acknowledges that capacity delivery has reached a new level, but valuation requires projecting free cash flow as far out as 2035 and discounting it back using an enterprise value-to-free-cash-flow multiple. The longer the forecast horizon, the more small changes in GPU useful life, financing costs, competition, and the terminal multiple can amplify the result. The $99 target therefore reflects a broad balance between improved execution and capital risk.
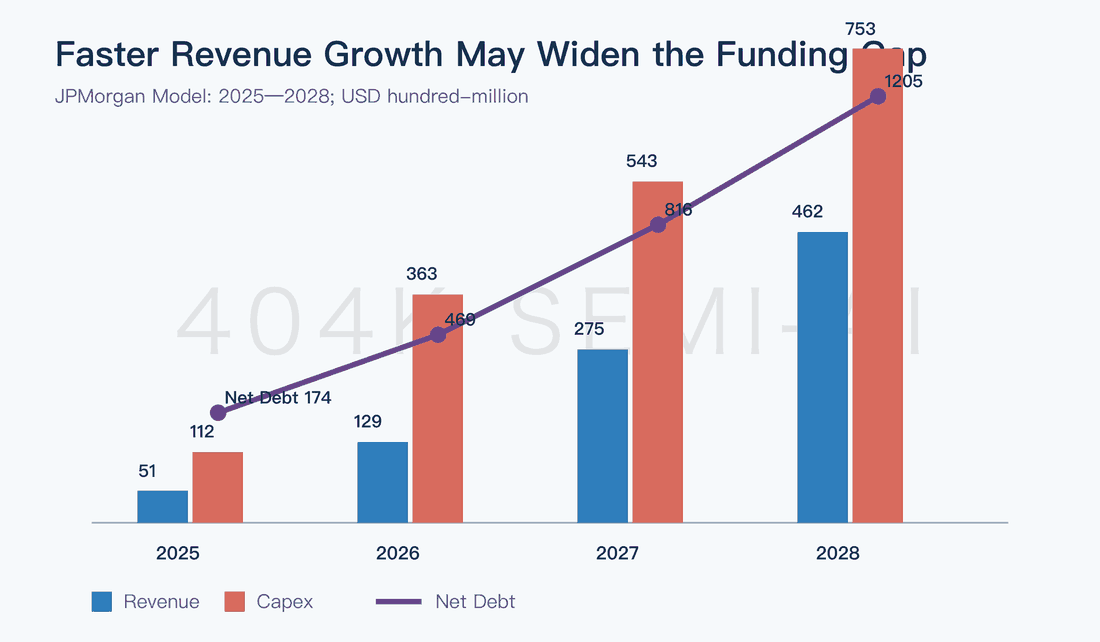
JPMorgan maintained its “Neutral” rating and raised its December 2027 price target from $110 to $120, based on approximately 28x estimated 2028 adjusted operating profit. It places greater weight on DDTL 5.5, short-duration contract financing, the 25% price increase, the 5–10 percentage-point improvement in contract contribution margins, and power visibility through 2030. However, its model also shows capital expenditures remaining above revenue throughout 2025–2028, persistently negative free cash flow, and net debt potentially rising from approximately $17.4 billion to more than $120 billion. A higher price target does not mean the financing problem has disappeared.
Bernstein maintained its “Underperform” rating and raised its price target from $67 to $74. It acknowledged that this was CoreWeave’s strongest quarter of execution, but argued that the improvement primarily increased confidence in 2026 delivery without proving returns on capital beyond 2028. As data-center supply constraints ease and hyperscalers shift from customers to competitors, scarcity premiums, contract pricing, and software differentiation could weaken, while CoreWeave would continue to bear the risks associated with capital expenditures, interest expense, and GPU residual values.
The $74, $99, and $120 targets cannot simply be averaged because the three firms use different profit metrics, forecast years, and valuation multiples. The range conveys a more important message: disagreement over demand and delivery in the next one or two quarters has narrowed, but views on free cash flow beyond 2028 remain widely divergent. For the stock to break out of this range, the company must provide sustained evidence of returns on capital—not merely sign another large contract.
All three frameworks use forward metrics to value current assets, yet those metrics depend heavily on renewals that have not yet occurred. For software companies, uncertainty around forward earnings usually centers on growth and expense ratios. For CoreWeave, investors must also estimate the timing of power activation, equipment prices, depreciation lives, contract duration, residual values, interest rates, and refinancing. The wide divergence in price targets does not reflect calculation errors based on the same financial statements; it reflects the absence of a complete asset cycle for capital-intensive AI infrastructure. The next round of renewals for older GPUs and the first period of large-scale free cash flow will be the real catalysts for narrowing the gap between models.
9. Five Validation Points to Watch Over the Next Two Quarters
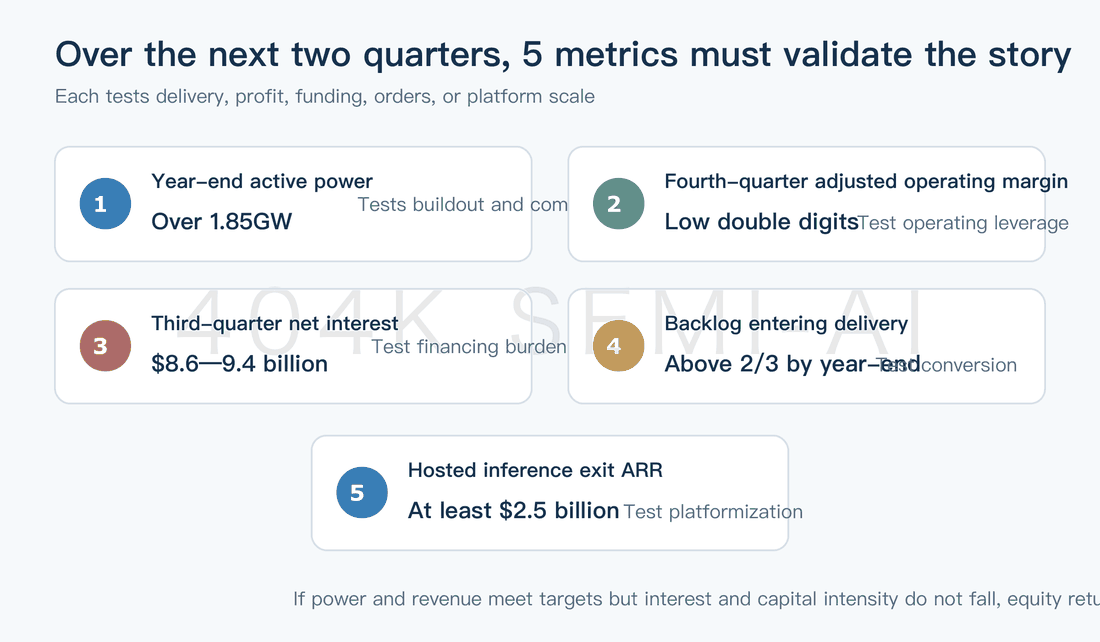
First, can active power exceed 1.85GW by year-end? It had already reached 1.5GW by the end of the second quarter, leaving approximately 350MW, which appears manageable. However, that capacity must come online without compromising delivery quality or capital efficiency per unit. Second, can the adjusted operating margin reach the low teens in the fourth quarter? The midpoint of third-quarter guidance is approximately 6.5%; if the fourth-quarter margin remains in the mid-single digits, price increases and scale will not yet have offset pre-commissioning costs.
Third, after third-quarter net interest expense of $860 million–$940 million, when will interest growth peak? The lower cost of debt deserves recognition, but returns to common shareholders depend on the absolute gap between interest expense and operating profit. Fourth, can the share of backlog that has begun generating revenue rise from more than half to over two-thirds by year-end? This ratio is a better test of conversion than total backlog because it directly connects contracts with revenue.
Fifth, can managed inference exit annualized recurring revenue reach at least $250 million, accompanied by initial disclosures on utilization, margins, or customer retention? If the company merely meets its bookings target but requires substantial incremental GPUs and idle capacity, the platform’s value will be lower than the headline growth rate suggests. If managed inference primarily utilizes existing equipment and generates stable repeat business, it would materially improve assumptions for GPU residual values and customer diversification.
These five metrics must be assessed together. If power and revenue meet targets while capital expenditures and interest continue to grow faster, the company is merely scaling growth. The business model will begin converting scale into equity value only if margins improve, backlog enters service, managed inference absorbs older equipment, and financing needs gradually decline. No single metric is sufficient to prove the case.
Conclusion: A Better Operating Report Card, but Not Yet Proof of Returns on Capital
CoreWeave’s most important second-quarter achievement was increasing active power from approximately 1GW to 1.5GW while delivering 112% year-over-year revenue growth. This directly addressed market concerns about execution. Backlog, new commitments secured early in the third quarter, the July price increase, contribution margins on new contracts, and the A100 renewal collectively show that demand for AI compute remains strong and that the company is beginning to gain pricing power.
Common shareholders, however, face a different set of numbers: $640 million in net interest expense, a net loss with an absolute value of $626 million, $9.352 billion in quarterly capital expenditures, and $13.985 billion in financing cash flow during the first half. CoreWeave is using cheaper capital per unit to support a larger absolute debt burden. That is better than relying on expensive financing, but it does not yet constitute self-funding.
Accordingly, the quarter supports neither the simplistic bear case that demand is merely a bubble and the company cannot deliver, nor the linear bull case that a $104.2 billion backlog will inevitably convert into high profits. The more accurate conclusion is that operating risk has declined, while return-on-capital risk has become the dominant issue. If CoreWeave can simultaneously deliver 1.85GW, a low-teens adjusted operating margin, backlog conversion, and its managed-inference target over the next two quarters—while producing visible inflection points in interest expense and capital intensity—it can begin the transition from an AI infrastructure company skilled at financing expansion into a cloud platform capable of generating sustained cash returns for common shareholders.