
Compute Hardware Deep Dive: VR200 Rack Cost Reaches $7.8 Million, Doubling Server Value While Squeezing Consumer Electronics Margins
目录
Executive Summary
One Cost Cycle Is Pushing Technology Hardware Into Two Different Worlds
Who Actually Captures the $7.8 Million?
Why High-Value Components Can Also Become Delivery Bottlenecks
Assess ODMs by Profit Share, Not Total Rack Value
2026 Is Back-End-Loaded; Profit Visibility Emerges in 2027
Consumer Electronics: Price Increases May Protect Revenue, but Not Necessarily Profit
Regionalization Is Not About Leaving China, but Reallocating Production by Product
How Investments Should Be Prioritized
Only Eight Metrics Need to Be Monitored Going Forward
Conclusion: The Next Round of Excess Returns Will Come From Profit Pools, Not the Bill of Materials
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The same memory price cycle is pushing AI rack costs to $7.8 million while compressing smartphone and PC margins. The real opportunities lie in the reordering of value content, profit contribution, and delivery capabilities.
Executive Summary
Morgan Stanley’s bill-of-materials estimate puts the cost of a single VR200 rack at approximately $7.8 million, up 95% from roughly $3.99 million for the GB300—but this does not mean profits will double across the entire supply chain. Memory accounts for the largest absolute increase at approximately $1.63 million, exceeding the roughly $1.44 million increase in GPUs. PCB, networking chip, and ABF substrate value rises faster, while ODM value added per rack increases by only 38%. Investors must distinguish among total system price, supplier revenue, and supplier profit.
AI hardware is entering a phase in which server volumes rise, value per rack increases, and consumer-device volumes contract simultaneously. The report forecasts server shipments to grow 22% in 2026, while PC and smartphone shipments each decline by approximately 13%. Higher memory prices are expanding the AI rack bill-of-materials pool while undermining demand for low- and mid-range smartphones and PCs. Simply owning the entire electronics sector is no longer sufficient.
The scarcest capacity is high-spec production that can simultaneously meet requirements for high layer counts, low signal loss, high power, and on-time delivery. The VR200 adds a midplane PCB, increasing PCB value per rack by 233%, but this component also delays the production ramp by one to two months. ABF substrates and T-Glass could move into shortage around 2027. Both higher value content and delivery risk stem from the same technical barriers.
The ODM opportunity comes from market share and profit mix—not from multiplying $7.8 million by the number of racks. Wistron, Quanta Computer, Hon Hai Precision, and Wiwynn are all expanding their AI server businesses, but customer allocations are uneven. Liquid cooling, full-rack integration, co-design capabilities, yield, and established delivery records determine who wins orders. A faster increase in AI profit contribution than in AI revenue contribution is a more reliable signal of valuation improvement.
2026 looks more like a year of back-end-loaded realization, while 2027 will be the first full validation year for the supply chain. The VR200 is expected to begin ramping in 4Q26, with midplanes, memory, advanced packaging, and high-end substrates all potential delivery constraints. Current valuations should be tested against both actual 2026 shipments and the realization of supply-demand conditions in 2027. Full-year targets cannot simply be spread evenly across each quarter.
The direction of divergence in consumer electronics is clear: the Apple supply chain is relatively resilient, while the Android supply chain and low-margin system manufacturers are more vulnerable. The modeled memory cost per iPhone rises from approximately $40 to approximately $100, and Apple may still demand price concessions from non-memory suppliers. In PCs, price increases and product upgrades could improve profitability in the first half, while the second half will be the real stress test for demand and gross margins.
One Cost Cycle Is Pushing Technology Hardware Into Two Different Worlds
The most valuable aspect of this report is not that it once again confirms strong AI capital expenditure, but that it places both sides of the same cost shock into a single framework. On the server side, the forecast for 2026 capital-expenditure growth among the 14 largest cloud providers has been raised from 63% to 87%, with total 2026 spending projected at approximately $893 billion. Morgan Stanley estimates 2027 spending at $1.225 trillion, 21% above consensus. Demand is coming not only from Nvidia but also from Google TPUs, Amazon Trainium, AMD racks, and the expansion of general-purpose processing capacity driven by agentic applications.
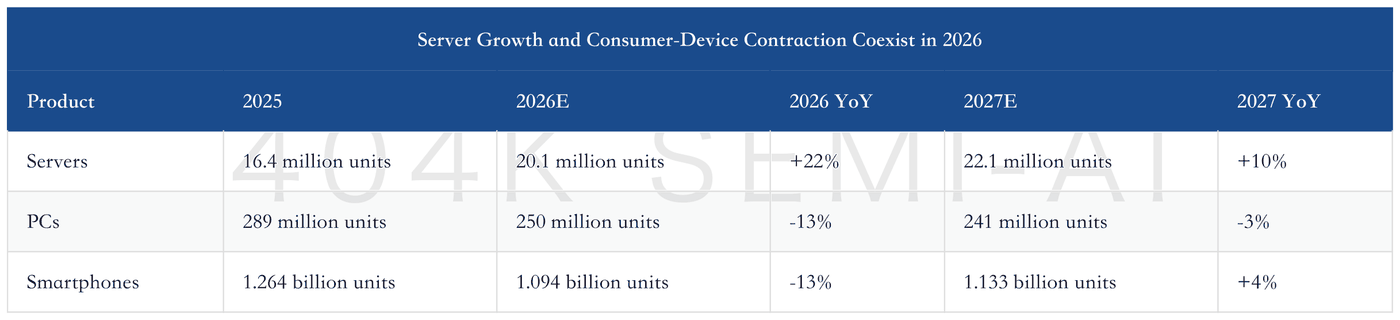
Consumer electronics faces a very different equation. Higher memory prices increase the nominal bill-of-materials value of AI racks, but force smartphone and PC brands to raise prices, reduce specifications, or accept lower margins. The report forecasts server shipments to increase from 16.4 million units in 2025 to 20.1 million in 2026, while PC shipments decline from 289 million to 250 million and smartphone shipments fall from 1.264 billion to 1.094 billion. The hardware industry is moving away from a relatively synchronized demand cycle toward the coexistence of expanding compute infrastructure and contracting consumer-device demand.
AI revenue contribution alone can therefore no longer explain company performance; AI profit contribution is closer to the answer. Even if a company participates in AI servers, profit growth may still lag revenue growth if assembly value added is low, customer concentration is high, and consumer exposure remains substantial. Conversely, a high-spec component with limited revenue scale can generate greater profit leverage if market share is concentrated and yield barriers are high.
Revaluing the Rubin Rack: GPU Share Falls to 51% as AI Hardware Value Shifts Toward Memory, PCBs, Power, and Liquid Cooling—Who Is Capturing the Incremental Value?
Who Actually Captures the $7.8 Million?
The $7.8 million figure is first and foremost Morgan Stanley’s bottom-up estimate based on a specific VR200 rack configuration—not a realized transaction price. Page 12 of the report estimates the bill-of-materials cost of a single GB300 rack at $3.9946 million and the VR200 at $7.8031 million, an increase of 95%. Different pages of the original report label the VR200 configuration as both NVL72 and NVL144. The figure should therefore be understood strictly as the configuration assumption used in the report’s table and should not be combined with a different physical configuration.
Incremental VR200 Value Flows Primarily to Memory, GPUs, Networking, and High-Spec PCBs
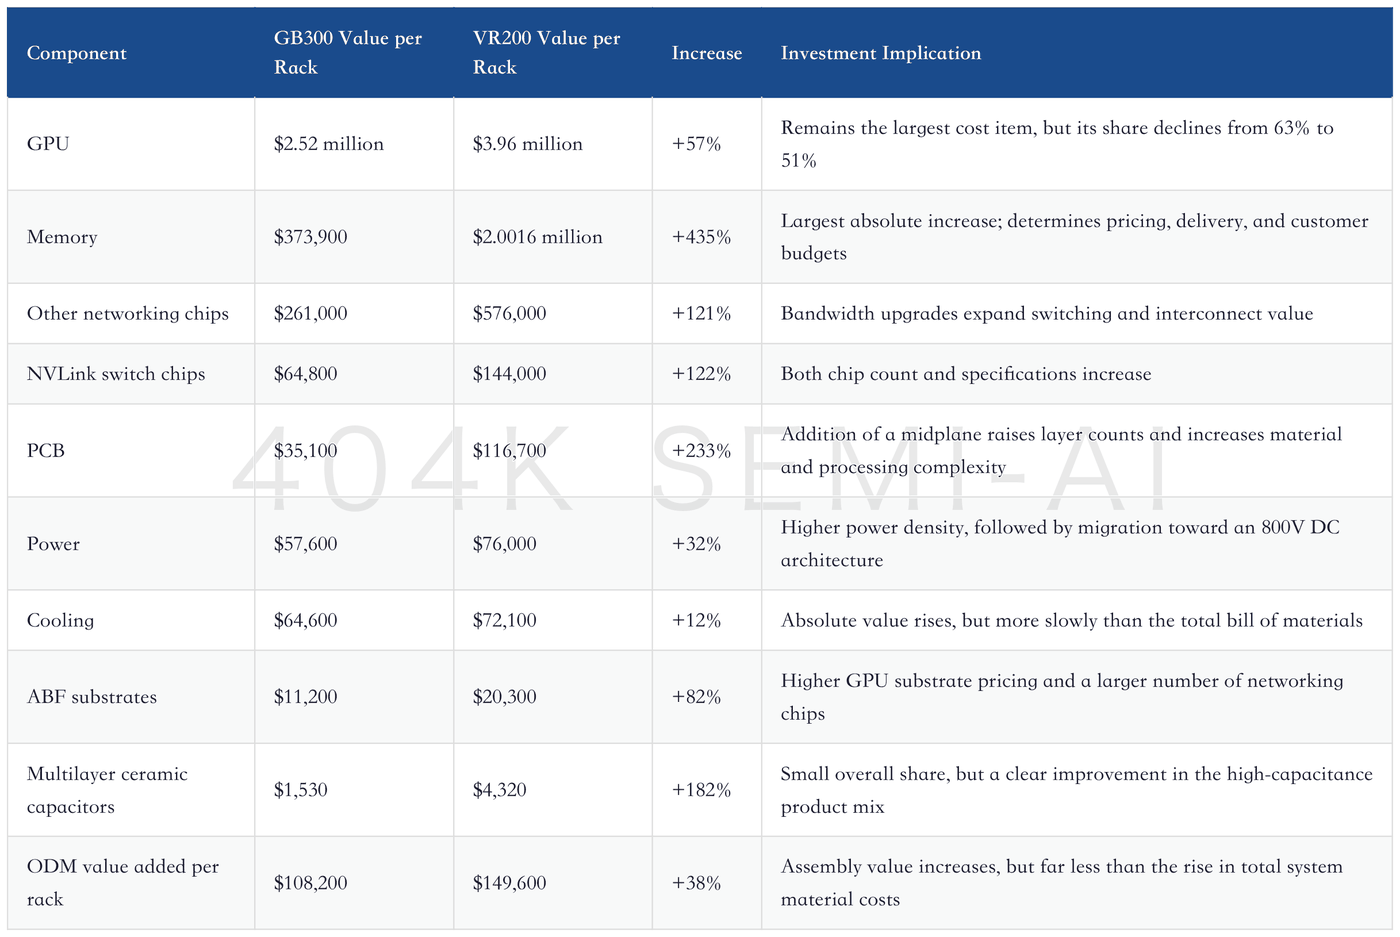
The most important point is not the 435% increase in memory value, but its approximately $1.63 million absolute increase, which already exceeds the roughly $1.44 million increase in GPU value. GPUs remain the system’s core, but incremental budgets are no longer allocated solely around them. Memory supply, pricing, and configuration will directly affect rack pricing and could also constrain cloud customers’ procurement volumes. If memory prices decline, nominal rack bill-of-materials costs will fall, but this would not necessarily indicate a reduction in compute specifications.
The second layer consists of electronic components with high growth rates but low starting bases. PCB value rises from $35,100 to $116,700, an increase of approximately $81,600. The combined increase in networking-chip value exceeds $390,000. ABF substrates and multilayer ceramic capacitors post high percentage gains, but their absolute values remain far below memory. Assessing company-level earnings sensitivity requires adjusting for market share, revenue base, and margins; component value growth cannot be treated directly as company profit growth.
The third layer is ODMs. ODM value added per rack rises from $108,200 to $149,600, an increase of approximately $41,400—only a small fraction of the total increase in system material costs. Most of the $7.8 million flows to chips, memory, networking, and high-spec components rather than assemblers. ODMs still benefit, but their profits are the product of rack volumes, market share, high-value-added modules, yields, and pricing discipline.
Why High-Value Components Can Also Become Delivery Bottlenecks
Midplane PCBs are the clearest example of opportunity and risk sharing the same source in this upgrade cycle. VR200 is estimated to add 18 midplanes priced at approximately US$1,500 each, contributing US$27,000 per rack. Compute board pricing rises from US$650 to US$1,400, while switch board pricing increases from US$800 to US$1,450. Higher layer counts, low-loss materials, and greater processing complexity make PCBs one of the clearest sources of incremental non-chip content value, while also creating a real bottleneck that could delay VR200 by one to two months.
ABF substrates face a threefold upgrade in area, layer count, and supply lead times. Nvidia’s roadmap in the report shows substrate dimensions increasing from 55×55 mm and 12 layers for A100 to 83×97 mm and 18 layers for VR200. The VR200 OAM board increases to 26-layer high-density interconnect, the switch board to 32 layers, and the midplane to 44 layers using M9-grade low-loss materials. The report expects ABF demand to exceed supply from 2027, with the market expanding at a CAGR of approximately 24.4% from 2025 to 2030, while tight T-Glass supply could persist until around 2028.
Technology substitution remains a necessary counterargument. In theory, CoWoP could replace some ABF substrate content with PCBs, improving warpage, interconnect distance, and thermal performance. However, the report considers near-term adoption in Rubin Ultra unlikely because PCB line width and spacing would need to advance below 10/10 microns, versus approximately 40/50 microns for standard high-density interconnect boards and 20/35 microns for substrate-like PCBs. As long as yields and supply-chain restructuring costs remain below the threshold for mass production, ABF retains near-term visibility. Once fine-line capabilities achieve a breakthrough, however, the long-term value chain could be reallocated.
AI Hardware Deep Dive: How PCBs, CPO, and MLCCs Become the Three Physical Bottlenecks for Rubin Racks
Power systems and multilayer ceramic capacitors represent two additional ways to benefit. Rack power rises from approximately 120 kW for GB200 and 140 kW for GB300 to more than 200 kW for Vera Rubin, with subsequent generations potentially adopting standalone 800V DC power cabinets. MLCC content increases from approximately 2,000 units worth US$30 in a general-purpose server to approximately 570,000 units worth US$4,320 in VR200. The former gains absolute content value through architectural change, while the latter benefits from a richer mix of higher-capacitance, higher-specification products. The report’s bar chart supports an AI-server MLCC market approaching US$900 million in 2027, not US$1 billion in 2026.
Assess ODMs by Profit Share, Not Total Rack Value
The ODM sector’s expectation gap depends on whether revenue growth, share-price underperformance, and an improving profit mix can all coexist. The report shows that the ODM basket significantly underperformed the Taiwan Weighted Index at one point during the year, even as related companies continued to grow revenue and valuations remained close to their own historical ranges. This does not automatically mean the sector is cheap, as different charts in the report use inconsistent index dates. A more robust approach is to assess AI profit share alongside forward valuations.
Growth in AI profit share explains ODM valuations better than growth in AI revenue share
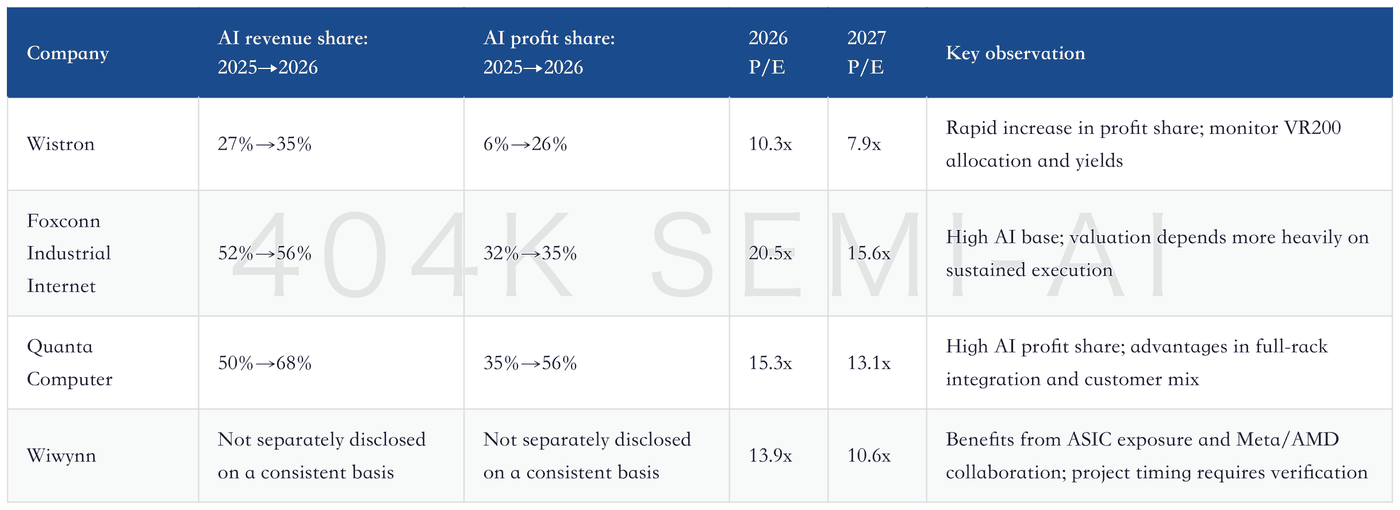
Wistron’s most attractive feature is not the increase in AI revenue share from 27% to 35%, but the rise in AI profit share from 6% to 26%. The report expects its share of GB200/GB300 racks to be approximately 21%, potentially increasing to roughly one-third of VR200 compute trays. This suggests that market-share gains and product-mix improvements could occur simultaneously. However, the sensitivity model also shows that earnings are highly dependent on rack volumes and unit pricing; customer order reallocation or mass-production delays would alter the outcome.
Quanta Computer and Hon Hai Precision Industry benefit from end-to-end integration. GPU server customers typically engage multiple ODMs, while ASIC server orders are also allocated among Wiwynn, Quanta Computer, Hon Hai Precision Industry, Inventec, and overseas suppliers. Liquid cooling, thermal management, full-rack design, and delivery track records are shifting the competitive threshold from contract manufacturing toward systems integration. Entering the supplier list is only the starting point; sustained share and realized gross margins are what ultimately matter.
ASIC and general-purpose processor expansion provide a second growth curve. Google TPU shipment forecasts rise from 1.75 million units in 2025 to 6.65 million in 2027. Meta and AMD have proposed a multiyear, multigeneration deployment framework of up to 6 GW, but this is not a single-year order commitment. If agentic applications increase the total server CPU market by 10 million–15 million units, the report estimates that CPU sockets, ABF substrates, and passive components would also generate incremental revenue. Compute expansion is moving from a single GPU ecosystem toward combined demand from GPUs, ASICs, and CPUs, requiring supply chains to support multiple platforms simultaneously.
2026 Is Back-End-Loaded; Profit Visibility Emerges in 2027
Nvidia’s projected 70,000–80,000 racks in 2026 should not be spread evenly across four quarters. The report estimates approximately 77,400 GB200/GB300-equivalent racks for the full year, yet its fourth-quarter forecast is lower than the first-half run rate. VR200 is also expected to begin ramping only in the fourth quarter due to component issues. Financial performance in 2026 is therefore likely to reflect timing mismatches among legacy-platform shipments, component inventory build, new-platform qualification, and formal revenue recognition.
The key question for 2027 is whether supply can convert demand into revenue. TSMC’s year-end monthly CoWoS capacity is expected to increase from 70,000 wafers in 2025 to 200,000 in 2027, while external packaging houses could expand from 23,000 to 80,000 wafers over the same period. The report estimates that the 2027 revenue markets for AI-chip front-end wafer fabrication and back-end packaging will each approach US$46 billion, with demand shifting from Nvidia dominance toward parallel contributions from Nvidia, AMD, Google, and Amazon. Capacity figures represent nominal capability only; equipment installation, yields, and customer product schedules determine effective output.
