
Citi CIO Survey Takeaways: AI Is Starting to Capture Budget, While Traditional IT Enters Reallocation
目录
Too Long; Didn’t Read
1. CIOs Are Not Pulling Back, but Spending Is Flowing to Narrower Areas
2. AI Budgets Are Entering Phase Two: Incremental Funding Remains, but Substitution Has Started
3. Microsoft Has Secured the First Entry Point, While Cloud Providers Remain in the Main Arena
4. Security Spending Has Not Been Downgraded; AI Has Expanded the Attack Surface
5. Software Divergence Will Become Sharper: Data Platforms Benefit, Seat-Based Software Faces Pressure
6. Hardware Demand Is More Skewed Toward Storage and Networking; PCs Are Not the Main Line
7. IT Services Need to Shift From Labor-Based Projects to AI and Security Delivery
8. Investment Conclusion: The AI Trade Is Starting to Depend on CIO Budget Conversion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Enterprise AI spending is entering the budget-validation phase. Citi’s 2Q26 CIO Survey shows a modest improvement in overall IT budgets. AI still has support from incremental funding, but traditional software, consulting, PCs, and back-office projects are already being crowded out. The next phase of the trade depends on budget conversion, not just theme momentum. Valuation needs to return to the question of who can actually capture real budgets.
Too Long; Didn’t Read
IT budgets are reaccelerating. The 100 IT decision-makers surveyed by Citi expect global IT budgets to grow 3.3% over the next 12 months, up from 2.6% in March and above the seven-year average. Both the U.S. and EMEA were revised higher, suggesting enterprises are still willing to reserve budget for AI, data, security, and cloud despite macro uncertainty.
AI has become the top priority. Data analytics, AI, and data warehousing remain the No. 1 CIO investment priority, followed by cybersecurity at No. 2, digital transformation at No. 3, and customer-facing front-office applications rising to No. 4. Enterprise procurement order has changed. Budgets are first flowing to the data foundation, security control plane, and customer-process automation needed to support AI production deployment.
Incremental funding remains, but crowd-out is intensifying. 69% of respondents said generative AI funding comes from incremental budget, down from 73% in the prior survey. Around 31% is already coming from reallocations of existing budgets. Nearly half of CIOs believe AI spending is negatively affecting traditional IT budgets, with the most pressure on consulting, traditional BI, front-office CRM/marketing/service, back-office HR/ERP, and PCs.
Microsoft is the primary enterprise AI entry point. Among vendors where respondents expect to increase AI spending, Microsoft received 50 nominations, far ahead of Amazon, Google, and AI labs. Enterprises are more willing to buy AI through existing relationships in productivity software, cloud, identity, developer tools, and data platforms than to procure AI as a standalone model.
Cloud benefits, but architectures will be hybrid. 53% of CIOs prefer to run LLM workloads in public cloud, 27% choose hybrid cloud, and 17% choose private cloud. Public cloud remains the largest beneficiary, but cost, latency, compliance, and proprietary model security are leading enterprises to preserve private and dedicated infrastructure options.
Security is becoming the AI foundation. Identity, endpoint, and web security are the current highest-priority security subcategories, driven by new exposure from agents, APIs, non-human identities, bot traffic, and AI-driven attacks. Security budget is not only defensive spending; it also determines whether enterprises can place AI into real business workflows.
Winners depend on budget-capture capability. Cloud platforms, data platforms, AI application platforms, identity security, web security, storage, and network infrastructure are better positioned to receive budget. Traditional outsourcing, low-differentiation collaboration software, HR software, PC refreshes, and seat-based software are more likely to become funding sources for AI budgets. The key metrics to track are AI as a share of IT budget, the share of production use cases, the share of incremental funding, and cloud deployment structure.
1. CIOs Are Not Pulling Back, but Spending Is Flowing to Narrower Areas
This survey first answers a more practical question: do CIOs have budget? The answer is yes, but the budget is becoming more selective.
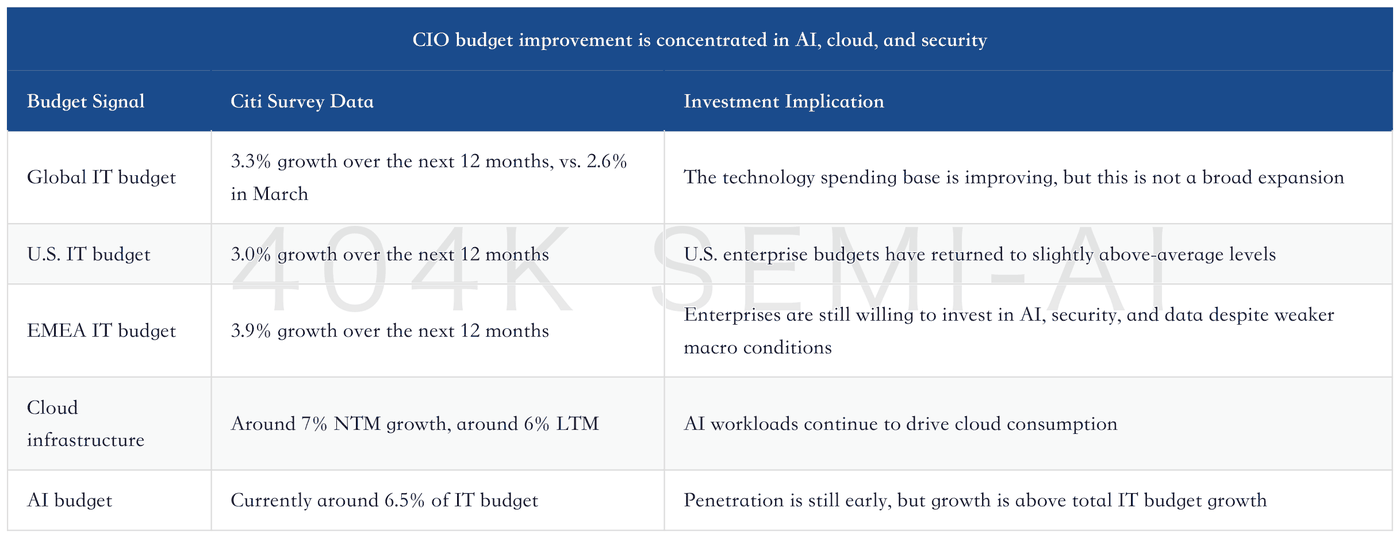
Expected global IT budget growth over the next 12 months rose from 2.6% to 3.3%. The U.S. rose to 3.0%, while EMEA rose to 3.9%. This is not a high number, but it is occurring in a difficult macro environment. In the report, U.S. enterprises’ perception of macro changes over the past three months was broadly neutral, while EMEA was clearly weaker, with around 62% of European respondents saying macro conditions had deteriorated.
CIOs are still raising budgets, which suggests enterprises view part of IT spending as a necessary competitive cost. AI, data architecture, security, and cloud infrastructure no longer look very discretionary. Enterprises can delay HR systems, PC refreshes, or traditional outsourcing contracts, but it is difficult to fully halt data and security investment while competitors are advancing AI.
There is also evidence of budget revisions. Over the past three months, companies with budget changes revised budgets up by an average of around 2.0%, higher than the 0.8% in the March survey. The share of upward revisions rose from 25% to 28%, while downward pressure did not expand. This backdrop is positive for technology spending, but it should not be interpreted as a broad benefit for all software and hardware.
The real change is in ranking. Data analytics, AI, and data warehousing rank first, cybersecurity second, digital transformation third, and customer-facing front-office applications fourth. Lower-ranked items include traditional outsourcing, PC refreshes, HR software, BPO, mobile devices, and some network and storage refreshes. Enterprises are still spending, but they are cutting lower-priority projects and concentrating budget on the areas that support AI deployment.
2. AI Budgets Are Entering Phase Two: Incremental Funding Remains, but Substitution Has Started
AI now accounts for around 6.5% of IT budgets. This share does not look large, but it is critical for investors. A small share means penetration remains low, leaving future growth potential. A high priority ranking means it is already beginning to affect the fate of other budgets.
Citi’s survey shows CIOs expect AI spending to grow around 10% over the next 12 months. This growth rate is higher than overall IT budgets and also higher than public cloud infrastructure growth. Enterprises are still willing to increase AI investment for a direct reason: once AI enters production, it can change customer service, coding, data analytics, marketing, sales support, back-office processes, and security operations.
Funding sources are becoming more sensitive. 69% of CIOs said generative AI funding comes from incremental budgets, which remains high, but this figure fell from 73% in the prior survey. The share coming from reallocations of existing budgets rose to 31%. Nearly half of respondents believe AI spending has already had a negative impact on traditional IT budgets, materially higher than in March and last December.
This is the dividing line for the AI trade. From 2024 to 2025, many enterprises treated AI as an experimental project. Budgets were relatively loose, PoCs were abundant, and vendors could enter the discussion simply by attaching AI features. Entering 2026, CIOs are starting to ask three questions: can this AI project enter production, can it reduce labor or increase revenue, and can it prove it deserves to take budget from elsewhere?
The report’s use-case data also supports this view. The share of AI use cases in production rose from 22% to 24%, while the PoC share rose from 37% to 40%. Production deployment is still early, indicating AI has not fully entered a mature procurement cycle. The continued rise in PoCs shows enterprises are still experimenting. The key metric to watch next is whether the 24% production share can continue to move higher.
Labor impact has already entered the CFO’s field of view. 59% of CIOs believe AI investment and related savings will lead to workforce reductions, with 86% expecting the impact to emerge within the next two years. The largest group expects to see results in six to 12 months. Once AI budgets are tied to labor costs, AI is no longer just technology spending; it becomes a corporate margin-management tool.
3. Microsoft Has Secured the First Entry Point, While Cloud Providers Remain in the Main Arena
The first stop for enterprise AI purchasing is still existing IT vendors.
In the question on vendors most likely to see increased AI spending, Microsoft received nominations from 50 respondents, far above Amazon’s 12, Google’s 10, and AI labs’ 10. Microsoft’s advantage comes from multiple entry points across productivity software, cloud, developer tools, identity, security, and enterprise data. If a CIO wants to put AI into employee workflows, Microsoft is usually the procurement path with the least friction.
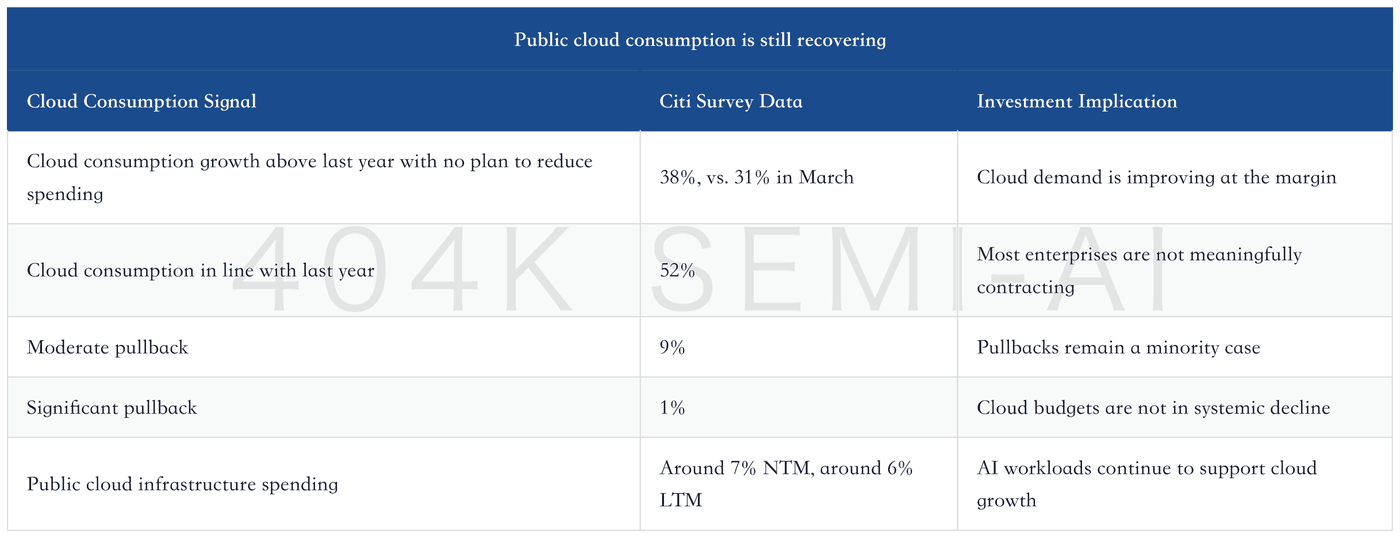
Amazon and Google are more exposed through cloud and model services. Public cloud consumption data remains healthy, with more CIOs seeing consumption growth above last year’s level and very few reporting significant pullbacks. Expected public cloud infrastructure spending over the next 12 months is also higher than in the past 12 months, indicating AI workloads are still driving cloud consumption.
LLM deployment location provides another signal. 53% of CIOs prefer to run LLM workloads in public cloud, 27% choose hybrid cloud, 17% choose private cloud, and 3% choose on-premises deployment. Public cloud remains the largest pool, but enterprises are not assigning all AI workloads to one architecture.
The reason is clear. Training, inference, RAG, private data access, customer-service agents, coding agents, and industry compliance scenarios all have different requirements. Public cloud has scale, elasticity, and model ecosystems. Private and hybrid architectures have advantages in cost, latency, data control, and model security. In the report, the top reason driving enterprises to reduce use of public shared infrastructure is more attractive subscription or usage-based offerings from OEMs, followed by performance and latency, then cost.
The investment implication is direct: hyperscalers remain the largest beneficiaries of enterprise AI adoption, but companies tied to hybrid architectures also have opportunities. Data connectivity, permission governance, model gateways, inference cost optimization, private data retrieval, enterprise vector databases, dedicated servers, and storage networks may all capture budget as AI moves into production.
4. Security Spending Has Not Been Downgraded; AI Has Expanded the Attack Surface
Cybersecurity ranks second among CIO investment priorities. The report notes that security budget growth over the next 12 months has slowed, but security’s position within budgets has not loosened.
Changes by subcategory are more important. The current highest-priority security areas are identity, endpoint, and web security. On a top-three basis, identity, cloud security, and network security remain near the top. This ranking is consistent with the real issues after AI deployment: enterprises are not only worried about employee account theft; they also need to manage agents, APIs, scripts, model calls, and various non-human identities.
Identity security is the gatekeeper for AI workflows. If an agent can read data, call tools, send emails, modify code, and access customer information, it must be authenticated, authorized, audited, and constrained. In the past, identity security solved “who can log in.” Now it also needs to solve “which agent can do what on behalf of whom.” This shifts identity governance from a compliance project to AI infrastructure.
The rise of web security is not accidental either. AI will amplify bot traffic, crawler traffic, API attacks, automated fraud, and DDoS. For media, e-commerce, SaaS, financial, and content platforms, web traffic in the AI era will contain a large volume of invalid or even harmful requests. Enterprises have to pay bandwidth, compute, and security costs for this traffic, even though it may not convert into revenue.
Citi’s interpretation of CDN, WAF, DDoS protection, anti-bot, API security, and security platforms is positive. More specifically, platform security companies, web/API security companies, and vendors that can embed identity and cloud security into AI workflows should find it easier to capture CIO budgets than point-solution tools.
