
China Semiconductor Equipment Deep-Dive Update: CXMT Server DRAM Long-Term Order, Advanced Logic Expansion, and the Shift to 2030E Discounted PE
目录
Too Long; Didn’t Read
1. What Goldman Sachs Really Changed This Time Is the Valuation Clock
2. CXMT’s Server DRAM Long-Term Order Moves Memory Expansion from Rumor to Order Validation
3. Why 2030E Discounted PE Has Become the Dividing Line for This Revaluation
IV. Four-Company Ranking: Platform Equipment, Etch Gatekeeper, Cleaning Category Expansion, High-Margin Materials
V. NAURA: Behind the RMB 1,200 Target Price Is the Revenue Slope of a Platform Equipment Company
VI. AMEC: High-End Etch Is the Clearest, Margin Recovery Is the Most Sensitive
VII. ACM Research: From Cleaning Equipment to PECVD, a Dollar-Listed Name with Both Elasticity and Discount
8. Anji Microelectronics: Advanced Nodes Amplify the High Gross Margins of Materials Companies
9. Scenario Framework: Which Worldview Is the Market Trading?
10. Falsification Checklist: Which Numbers to Watch Over the Next Four Quarters
11. Conclusion: This Cycle Is Not Another Call for Domestic Substitution, but a Test of Whether Advanced Production Lines Can Ramp on Schedule
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The main thread for China semiconductor equipment is shifting from “can domestic substitution happen?” to “can domestic suppliers support advanced memory and advanced logic capacity expansion?” Goldman Sachs has moved Naura Technology, AMEC, ACM Research, and Anji Microelectronics onto a 2030E discounted PE framework, which in essence reprices longer order visibility.
Too Long; Didn’t Read
The valuation clock has been extended. Goldman Sachs is not simply raising earnings forecasts this time; it has shifted the target-price framework for Naura Technology, AMEC, ACM Research, and Anji Microelectronics to 2030E discounted PE. The core signal is that visibility for advanced memory, advanced logic, and domestic materials is no longer only about 2026 orders, but about the capacity expansion slope through 2030.
The CXMT long-term order is the demand anchor. The reported multi-year server DRAM procurement agreement between CXMT and Tencent, worth more than RMB20bn, moves domestic memory expansion from a policy narrative to customer-order validation. The biggest beneficiaries in the equipment chain are not a single tool category, but the broader advanced-process support stack across etch, deposition, furnaces, cleaning, CMP materials, and electroplating chemicals.
Ranking depends on ticket breadth. Naura Technology’s advantage is platform equipment coverage, with exposure across etch, PVD, CVD, furnaces, cleaning, thermal processing, and other steps; AMEC is more like an advanced etch gatekeeper, with the highest sensitivity to revenue elasticity and margin recovery; ACM Research benefits from cleaning category expansion; Anji Microelectronics monetizes advanced-node consumption intensity through high-margin materials.
Target-price differences have logic. Naura Technology and AMEC use 56x 2030E discounted PE, reflecting the scarcity of platform equipment and etch gatekeeper positions; ACM Research uses 40x, reflecting discounts for a USD-listed stock, supply chain, and competition; Anji Microelectronics uses 46x, closer to the valuation center of a high-margin materials company but with higher category concentration. The valuation gap is not about which stock is cheaper, but which type of certainty the market is willing to pay a higher multiple for.
The falsification point is not near-term orders. The real risks are delays in advanced memory expansion, export restrictions expanding to more mature-node or advanced-node equipment, slower domestic fab capex, and gross margins failing to materialize after new product introductions. Over the next four quarters, investors should track equipment deliveries to CXMT and advanced-logic customers, Naura Technology’s expense-ratio inflection, AMEC’s etch order quality, ACM Research’s new-product ramp, and Anji Microelectronics’ materials qualification pace.
This cycle is not a replay of the old narrative. The 2024-2025 equipment rally was more about trading domestic substitution and WFE cycle recovery. For 2026-2030, the key variable becomes whether domestic advanced production lines can keep ramping. If server DRAM, HBM-related support, and advanced logic are delivered simultaneously, China semiconductor equipment will move from “valuation repair” into “revaluation of the revenue curve”; if capacity expansion disappoints, 2030E discounted PE will amplify valuation downside.
1. What Goldman Sachs Really Changed This Time Is the Valuation Clock
The most important change in this Goldman Sachs report is not the target-price increases for several companies, but the shift in valuation perspective from earnings over the next two years to 2030E discounted PE. For semiconductor equipment, this move itself is significant. Equipment companies naturally face time lags between order recognition, revenue recognition, and customer fab ramp-up. If investors only look at 2026E or 2027E profit, the market can easily treat advanced memory expansion as short-cycle orders. Moving to 2030E means the sell side is acknowledging one thing: visibility in this demand cycle may extend beyond a normal equipment cycle.
This is the real meaning of “valuation framework reset” in the report title. Target prices for Naura Technology, AMEC, ACM Research, and Anji Microelectronics have all been raised meaningfully, but the more important point is the change in the valuation model’s time axis: if domestic advanced fabs, category substitution, and margin expansion are still visible in 2030, then 2026 orders should not be priced only on that year’s cycle conditions.
This is consistent with the prior global WFE logic. Equipment-cycle analysis around AI capex has already shown that advanced processes, advanced packaging, and memory are returning to the center of the equipment cycle, and global WFE is no longer merely a function of handset and PC inventory restocking.
The WFE Supercycle Has Just Begun: How AI Capex Is Pushing Semiconductor Equipment Toward US$250bn
What differs for China’s equipment chain is that, beyond the global equipment cycle, it also faces the issue of supply availability for domestic advanced production lines. Overseas equipment leaders are looking at AI capex and advanced customer capex; Chinese equipment companies also need to answer a second question: under restrictions across more process steps, can domestic customers build a sustainable expansion path with domestic equipment and materials? Once this question shifts from “can it be done?” to “can it be delivered at scale?”, valuation moves from a substitution-rate story to a revenue-curve story.
The four companies covered by Goldman Sachs stand in four distinct positions: Naura Technology is a platform front-end equipment supplier; AMEC is an etch and MOCVD gatekeeper; ACM Research is expanding across cleaning, electroplating, and some thin-film categories; Anji Microelectronics supplies CMP slurry, functional wet electronic chemicals, and electroplating additives. Equipment, processes, and materials together form the capability map that advanced memory and advanced logic production lines truly need.
The core conclusion of this deep-dive update is direct: if the CXMT server DRAM long-term order and advanced logic expansion continue to be delivered, China semiconductor equipment will no longer be just a “domestic substitution” story, but will enter a phase of revaluation based on the expansion slope of advanced production lines. If customer expansion pace, introduction yield, or export restrictions move in the opposite direction, 2030E discounted PE will also make valuation volatility more severe.
2. CXMT’s Server DRAM Long-Term Order Moves Memory Expansion from Rumor to Order Validation
What equipment stocks fear most is not the absence of a story, but a story without orders. Over the past two years, China’s equipment chain has had no shortage of narratives: restrictions on advanced processes, accelerated domestic substitution, memory-cycle recovery, and AI servers requiring more DRAM and HBM. But only when downstream customers make longer-term procurement commitments does equipment expansion move from “possible” to “needs to be delivered.”
The core catalyst in Goldman Sachs’ report is the reported multi-year server DRAM procurement agreement between CXMT and Tencent, worth more than RMB20bn. This information by itself does not mean CXMT will immediately increase capex sharply, but it changes the validation sequence for the equipment chain. Previously, the market first looked at equipment tenders and then inferred customer demand. This time, investors first see a major downstream customer willing to lock in domestic server DRAM, and then reassess the necessity of memory-fab expansion.
This matters for equipment companies. Server DRAM is not low-end memory substitution; it requires higher consistency, higher yield, and more stable supply. If customers are willing to sign long-term agreements, memory manufacturers must support them with more certain capacity, process flows, and materials systems. For upstream suppliers, etch, thin-film deposition, furnaces, cleaning, CMP materials, and electroplating chemicals all benefit, but in different sequences: first, whether critical equipment can enter the line; second, whether yield can ramp after introduction; and only then whether materials consumption and maintenance orders can continue to scale.
Based on the earnings forecasts in the report, Goldman Sachs has already embedded this long-term slope into its model. Naura Technology’s 2030E revenue is forecast to reach RMB125.543bn; AMEC’s, RMB47.607bn; ACM Research’s, US$2.790bn; and Anji Microelectronics’, RMB8.503bn. This scale is hard to explain through mature-node stock substitution alone; it implies continued expansion in advanced memory and advanced logic from 2026 to 2030.
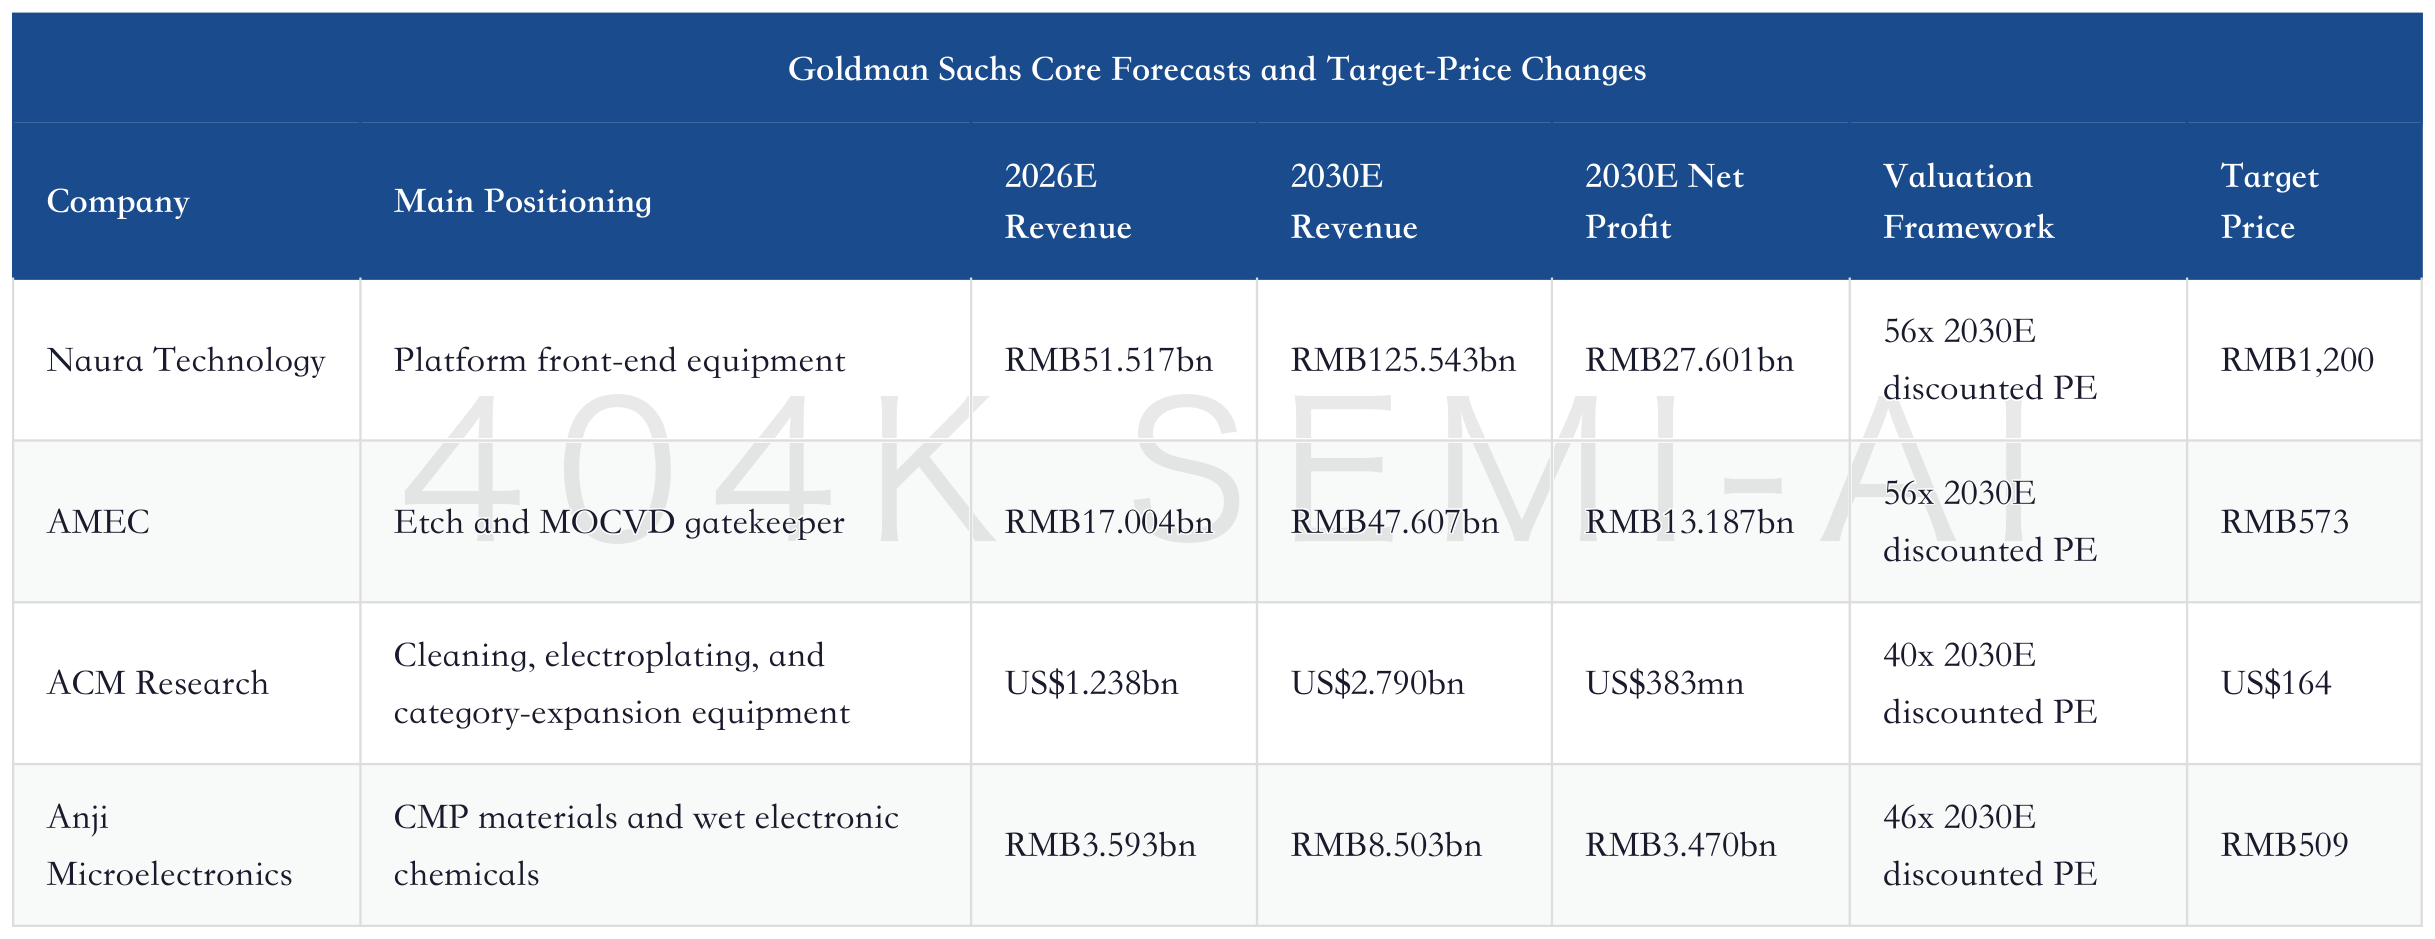
The research implication behind this table is not simply that all four companies have become more expensive. Rather, Goldman Sachs has shifted the core year for revenue and profit to 2030. In other words, the market is no longer asking only whether more tools can be sold in 2026; it is asking whether domestic advanced production lines have sufficiently continuous capex and materials consumption from 2026 to 2030.
From HBM to WFE: How AI Is Turning the Memory Cycle into an Equipment Supercycle, and How Much Longer Semiconductor Equipment Can Rise
Memory elasticity is especially important. DRAM, NAND, and HBM are not driven by a single equipment category, but by multiple process segments together. The higher the layer count, stacking complexity, linewidth requirements, and yield requirements for advanced memory, the more etch and thin-film deposition resemble “gatekeepers,” while cleaning and CMP materials resemble “amplifiers.” Gatekeepers determine whether the production line can run; amplifiers determine whether margins and repurchase intensity can be delivered after the line is running.
Therefore, the significance of CXMT’s server DRAM long-term order is not that “one company won an order,” but that it provides a demand anchor for the entire domestic advanced memory equipment chain. Once this demand anchor is continuously confirmed by more customer procurement, equipment tenders, and materials qualifications, valuation models will naturally migrate toward a longer cycle.
3. Why 2030E Discounted PE Has Become the Dividing Line for This Revaluation
Using forward PE for semiconductor equipment companies is not unusual. The question is which year to use. 2026E and 2027E look more like an order cycle; 2030E looks more like validation of industrial capability. Goldman Sachs’ move to 2030E discounted PE for target prices is essentially using a longer terminal year to answer one question: by 2030, will these companies have moved from single-step substitutes to foundational suppliers for China’s advanced production lines?
Naura Technology and AMEC use 56x 2030E discounted PE, the highest tier. This multiple is not because the two companies have the highest near-term margins, but because they occupy harder-to-substitute positions in front-end equipment and sit closer to the core of production-line capex. Naura Technology covers multiple front-end steps including etch, PVD, CVD, furnaces, thermal processing, and cleaning, and its platform breadth determines its revenue ceiling; AMEC is a more direct beneficiary of advanced memory and advanced logic through etch, and once margins recover, the elasticity will be released in a concentrated way.
ACM Research uses 40x 2030E discounted PE, with the discount mainly coming from several variables: it is a USD-listed stock, with strong exposure to domestic customers, but its valuation is also affected by overseas investor risk appetite, supply chain, and the competitive landscape; cleaning, electroplating, and PECVD category expansion can lift the ceiling, but the new-product introduction pace and gross-margin stability still need to be validated. Anji Microelectronics uses 46x 2030E discounted PE, between equipment platforms and single-tool companies. Materials companies have higher margins and stronger repeat purchases, but product-line concentration, customer qualification pace, and advanced-node volume growth will affect the valuation ceiling.
These multiples can be broken down into a simple framework: the stronger the production-line gatekeeper role, the higher the multiple; the broader the categories, the higher the ceiling; the more stable the repeat purchases, the better the profit quality; and the larger the supply-chain, customer-concentration, and external-restriction risks, the more visible the discount.
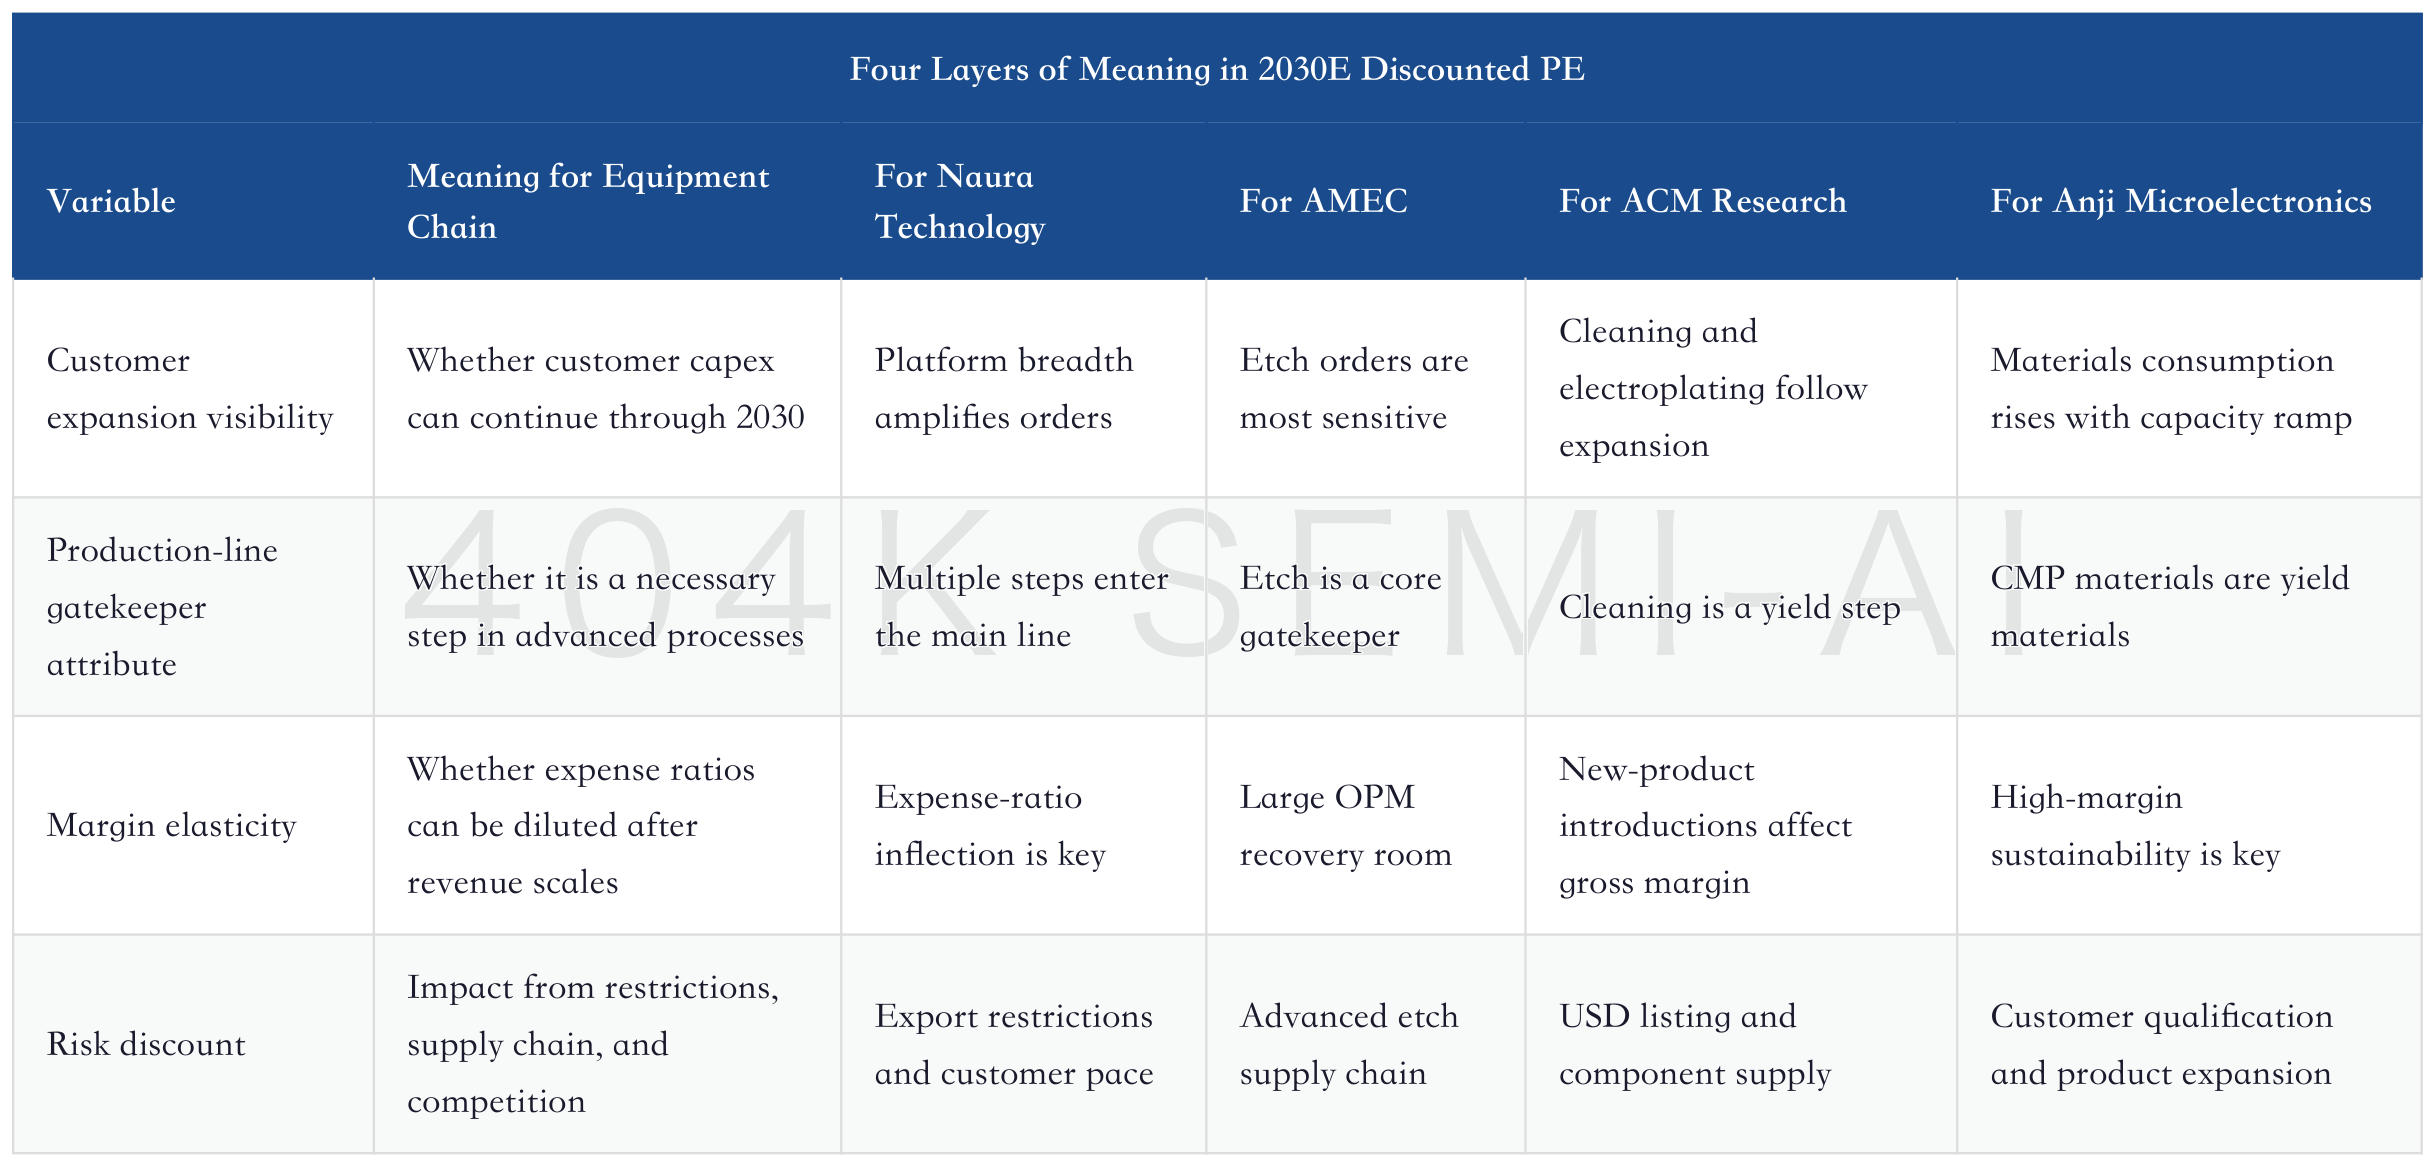
This framework offers readers a practical conclusion: do not look only at the percentage increase in target prices. After target-price increases, Naura Technology and AMEC may appear to have high valuations, but if advanced memory and advanced logic continue expanding through 2030, the revenue curves for platform equipment and etch gatekeepers will become steeper. ACM Research and Anji Microelectronics appear to have lower multiples, but their elasticity depends more on new category expansion, customer qualification, and materials consumption intensity.
Therefore, 2030E discounted PE is not an “optimistic multiple,” but a dividing line. The market will accept this valuation method only if it believes customer expansion visibility is sufficiently long. Once order validation breaks, the market will pull valuation back toward earnings over the next two years.
IV. Four-Company Ranking: Platform Equipment, Etch Gatekeeper, Cleaning Category Expansion, High-Margin Materials
This report is easiest to read as “Goldman Sachs is collectively bullish on China semiconductor equipment,” but the part that really deserves unpacking is the company ranking. The four companies are not the same type of asset; they have simply been pulled into the same supply-chain window by advanced memory and advanced logic capacity expansion.
NAURA’s core is not any single tool, but platform breadth. The company’s website discloses products spanning etch, PVD, CVD, cleaning, furnaces, rapid thermal processing, epitaxy, ion implantation, and other areas. This mix makes it look more like a domestic front-end equipment platform. If advanced memory and advanced logic capacity expansion proceed at the same time, a platform company can win orders across multiple process steps on the same production line, with revenue elasticity coming from more than single-point breakthroughs.
AMEC is more like an “advanced etch gatekeeper.” In logic and memory processes, etch difficulty rises rapidly as linewidths shrink, aspect ratios increase, and material systems become more complex. Etch equipment does not simply follow capacity expansion; it is critical equipment that determines whether customers’ advanced lines can reach target yields. AMEC’s advantage is concentrated elasticity; its drawback is also concentrated elasticity: if advanced-node customer capacity expansion slows, its valuation will be more sensitive than that of a platform company.
ACM Research’s focus is category expansion beyond cleaning equipment. The company discloses products spanning wet cleaning, front-end electroplating, Track, stress-free polishing, and PECVD. Cleaning itself is a yield-related step; the more process steps advanced nodes require, the greater the cleaning intensity. If electroplating and thin-film categories continue to be adopted, the company can move from a single cleaning-equipment supplier toward a broader process-equipment portfolio.
Anji Microelectronics is a high-margin asset on the materials side. The company discloses solutions covering CMP slurries, functional wet electronic chemicals, electroplating solutions, and additives. Equipment-company revenue usually fluctuates with capital expenditure, while materials-company revenue follows fab utilization and process consumption more closely. Advanced memory, advanced logic, and advanced packaging are more sensitive to material consistency, defect control, and yield contribution. Therefore, the key for Anji Microelectronics is not a one-off equipment tender, but repeat purchases and category expansion after qualification.
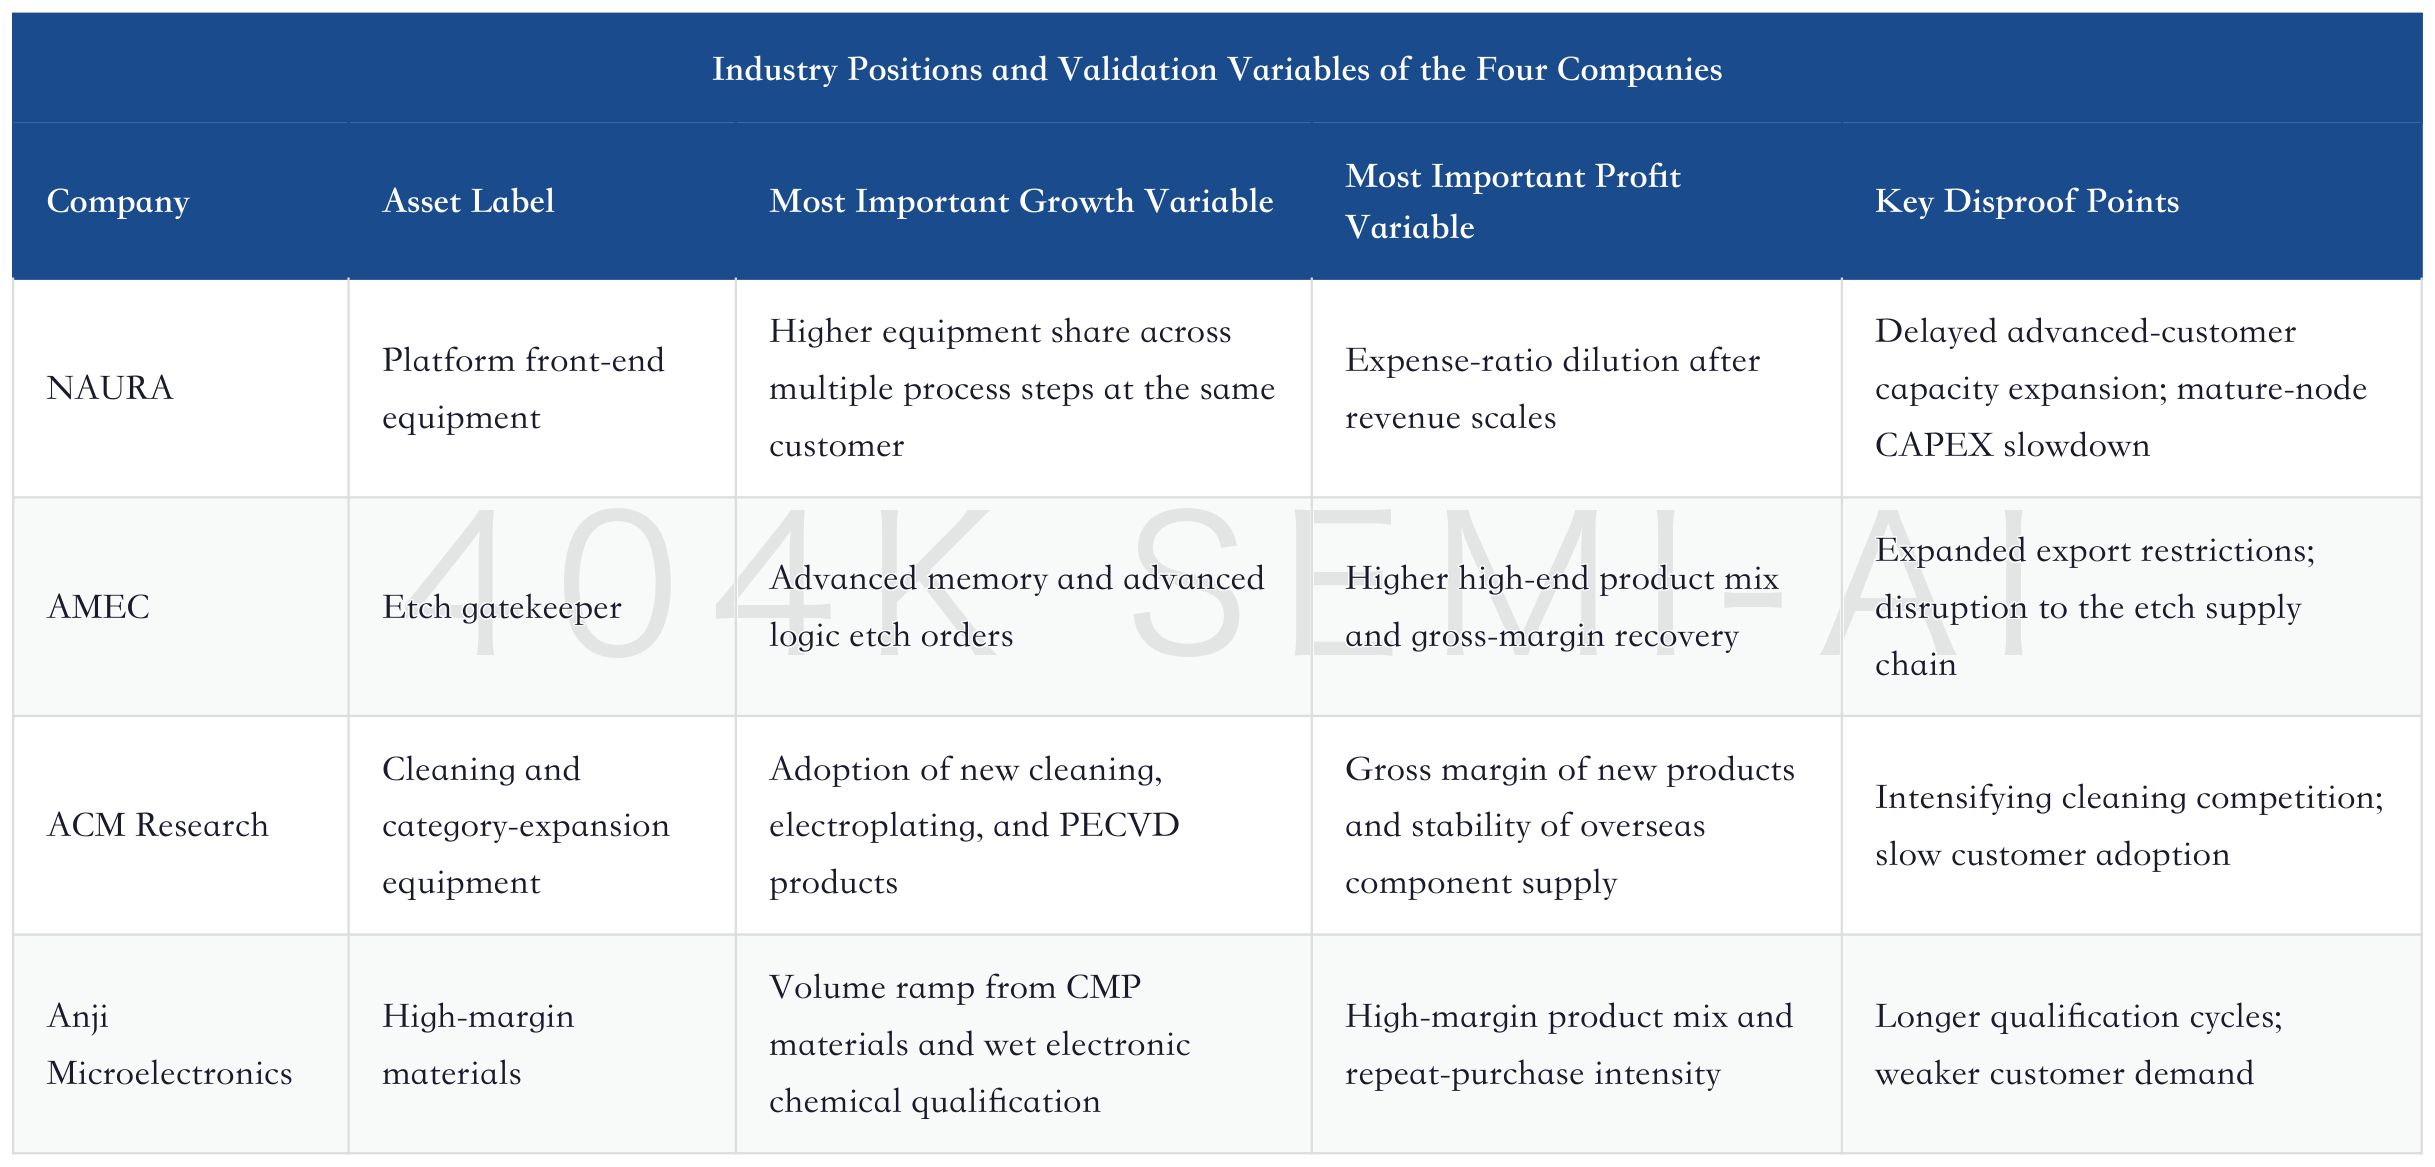
This ranking table is more important than the target-price table. Target prices are the result; industry position is the cause. NAURA and AMEC receive higher multiples because they are closer to core CAPEX for advanced production lines. ACM Research and Anji Microelectronics receive relatively lower multiples, which does not mean they lack elasticity; their elasticity is triggered differently. Cleaning and materials often release repeat-purchase value after production lines ramp. They may not be reflected in orders earliest in the short term, but once lines are operating stably, revenue quality improves.
This also explains why China’s equipment chain cannot simply be written up as “buy whoever has risen the most.” Under a 2030E framework, ranking should begin with three questions: first, whether the company is a necessary step in advanced production lines; second, whether it can expand from a single product into multiple categories; third, whether margins can improve after revenue scales. Only when all three questions have good answers does a long-term PE have support.
V. NAURA: Behind the RMB 1,200 Target Price Is the Revenue Slope of a Platform Equipment Company
NAURA remains the most typical platform asset in this round of re-rating. Goldman Sachs raised its target price from RMB 818 to RMB 1,200, corresponding to 56x 2030E discounted PE. On the surface, this is a 46.7% target-price increase; in substance, it reprices the company from a “domestic equipment leader” into a “domestic advanced-line platform supplier.”
NAURA Deep Dive: From Etch and Deposition to HBM Packaging Tools, How Advanced-Process Orders Move Through Expense Pressure
NAURA’s advantage lies in platform breadth. Advanced logic and advanced memory capacity expansion will not involve purchasing only one type of equipment. Fabs need coordination across etch, deposition, furnaces, cleaning, thermal processing, epitaxy, and multiple other steps. A single-equipment company must be excellent in one step; a platform company can continue to win share at the same customer, on the same production line, within the same capacity-expansion cycle. For the revenue model, this means customer CAPEX shifts from one point to multiple points.
Goldman Sachs’ model shows clear improvement in NAURA’s revenue, net profit, and operating margin from 2026E to 2030E. Profit grows faster than revenue, implying expense-ratio dilution and operating leverage release. In the past, the market worried that NAURA’s R&D; spending, headcount expansion, and category investment would pressure margins. But if advanced memory and advanced logic orders are continuously delivered, the platform company’s expense investment will be absorbed by a larger revenue pool.
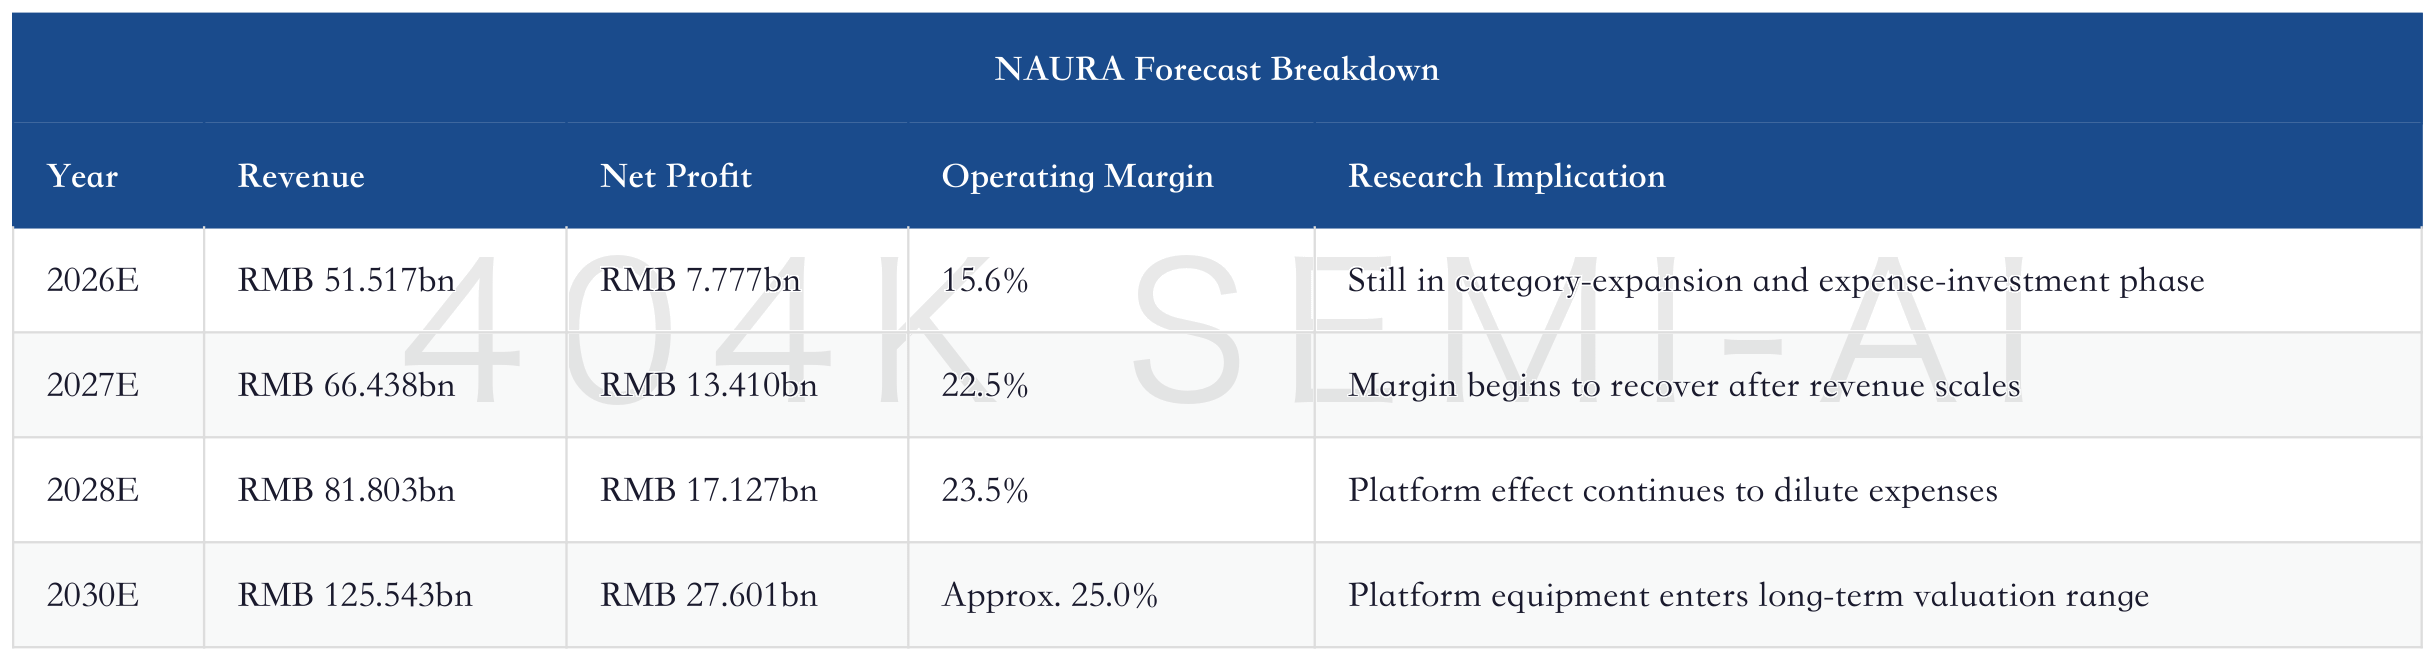
What NAURA most needs to validate is not one quarter of orders, but multi-step share at advanced customers. If the company only maintains substitution at mature nodes, the RMB 1,200 target price would look aggressive. If it continues to win multi-step orders in etch, deposition, furnaces, cleaning, thermal processing, and other areas at memory and advanced logic customers, the 2030E revenue curve becomes explainable.
The risks are also clear. First, if export restrictions continue to expand, they may affect customers’ advanced capacity buildout and may also affect some of the company’s upstream component supply. Second, if capital expenditure by mature-node customers slows, the platform company’s near-term revenue will come under pressure. Third, platform breadth is not a free lunch. Multi-category expansion requires sustained R&D; and delivery. If revenue realization is slower than expense investment, margin recovery will be delayed.
NAURA’s trading implication is therefore not as simple as “cheap” or “expensive.” It is more like a high-beta expression of long-term expansion in domestic advanced production lines. As long as the market believes advanced memory and advanced logic CAPEX can continue, platform equipment will sit at the front of the valuation table. Once customer capacity expansion loses speed, platform valuations will also de-rate faster.
VI. AMEC: High-End Etch Is the Clearest, Margin Recovery Is the Most Sensitive
AMEC has the strongest “gatekeeper” attribute among this group of companies. Goldman Sachs raised its target price from RMB 412.08 to RMB 573, also using 56x 2030E discounted PE. This multiple is the same as NAURA’s, but the logic is different: NAURA relies on platform breadth, while AMEC relies on etch position.
Etch is a core step in advanced processes that is very difficult to bypass. The deeper memory structures become, the smaller logic linewidths become, and the more complex material stacks become, the greater the impact of etch equipment on yield and capacity. If domestic advanced production lines are to ramp at more difficult nodes, equipment capability and process experience in etch will be repeatedly validated. AMEC’s valuation premium comes from the scarcity of this step.
Goldman Sachs’ model shows AMEC’s revenue, net profit, and operating margin all rising from 2026E to 2030E. This curve shows that the market is not only buying revenue growth, but also margin recovery after product-mix improvement.
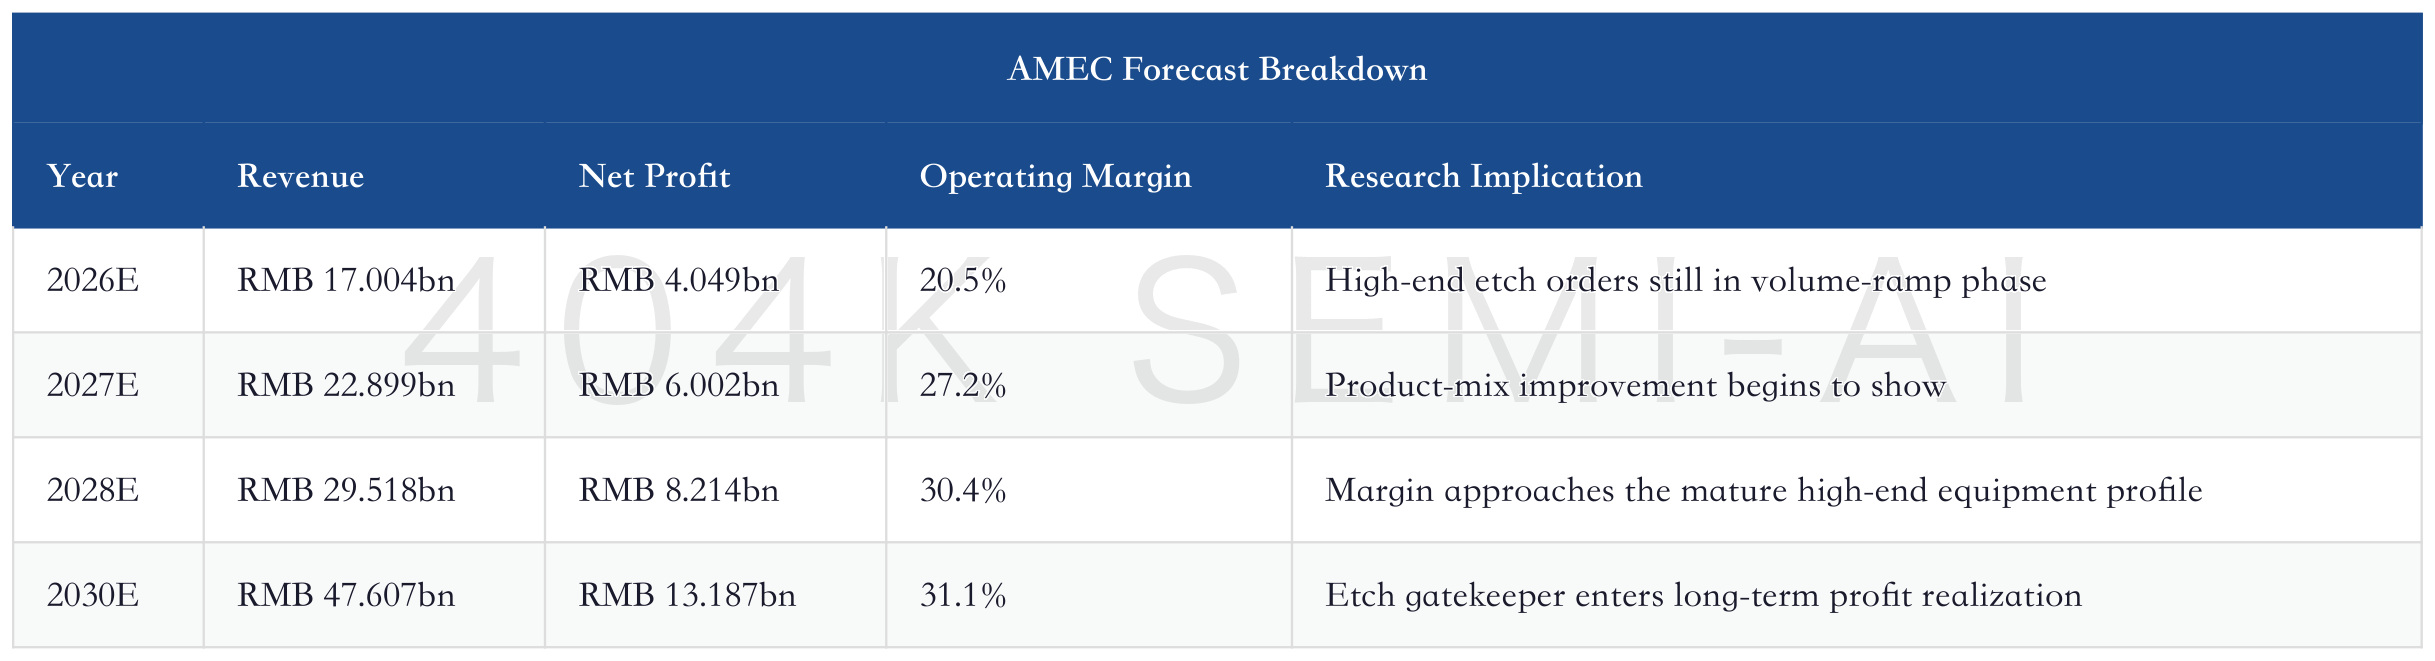
AMEC has three key validation points. First, whether advanced memory customers continue to expand capacity, especially etch demand related to high-aspect-ratio structures. Second, whether advanced logic customers expand the use of domestic equipment in more difficult processes. Third, whether gross margin and expense ratios can prove the company is not winning orders through low-price substitution, but building real competitiveness in critical process steps.
Japan SPE Turns Positive: How the WFE Upcycle Transmits from Billing Data to Test, Packaging, and Front-End Equipment
AMEC’s risks are also sharper. The more advanced etch becomes, the more vulnerable it is to external restrictions, upstream component supply, and the pace of customer adoption. If restrictions expand to more mature nodes, or if customers’ advanced expansion is delayed by equipment, yield, or market demand, AMEC’s revenue and valuation will be hit more directly than those of platform companies.
