
目录
TL;DR
1. Why UBS Raised 2027 Earnings by 84%: Pricing, Not Volume, Was Underestimated
2. RMB10.2 Is More Than a Routine Rebound: Prices Have Exceeded the Previous Cycle Peak
3. Why the Supply–Demand Gap Could Persist Through 2028: Nameplate Capacity Is Not Effective Supply
4. How Electronic Fabric Reshapes the Income Statement: A Three-Step Transmission from Revenue Mix to Cash Flow
5. The Value of AI Electronic Fabric: No Credit in the Base Case, but a RMB40 Billion Option in the Bull Case
6. Traditional Fiberglass Still Defines the Floor: Current Prices Do Not Discount a Full Recovery
7. RMB58, RMB83, and RMB22: Three Earnings-Duration Frameworks for the Same Company
8. How to Validate the Thesis Over the Next 12 Months: Four Sets of Trackable Indicators
9. Conclusion: The Electronic-Fabric Re-Rating Has Entered the Earnings-Delivery Phase, While the AI Option Remains Outside the Base Case
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
UBS raised its 2027 net profit forecast for China Jushi by 84%, while adopting a more conservative valuation of 15× 2027 P/E. E-cloth price increases are now flowing through to earnings, shifting the core debate to whether effective-supply bottlenecks can sustain elevated profitability beyond 2028.
TL;DR
Earnings forecasts have been revised sharply higher. UBS raised its 2026–2028 net profit forecasts by 22%, 84%, and 107% to RMB8.473 billion, RMB15.429 billion, and RMB19.99 billion, respectively, and lifted its price target from RMB43 to RMB58.
7628 prices have surpassed the previous cycle peak. The price reached RMB10.2/meter in August 2026, above the prior-cycle high of RMB8.8/meter; UBS expects the tax-inclusive price to approach RMB15/meter by end-2026.
The bottleneck is effective output, not nameplate capacity. Toyota Industries looms have lead times of 12–18 months, while domestic looms still struggle to meet standard 7628 requirements consistently. Thin, ultra-thin, and AI e-cloth also reduce output per loom.
E-cloth is reshaping the profit mix. UBS expects e-cloth revenue to rise from RMB3.673 billion in 2025 to RMB23.876 billion in 2028, surpassing conventional fiberglass revenue from 2027.
AI e-cloth remains an additional option. First-generation low-dielectric, low-thermal-expansion, and Q-glass products are already shipping in small volumes, but UBS’s base-case valuation assigns no net profit or valuation contribution to AI e-cloth.
The RMB58 target does not assume permanently elevated conditions. UBS applies 15× 2027 P/E and expects net profit to peak in 2028 before declining to RMB14.57 billion in 2029 and RMB12.143 billion in 2030.
Four indicators will determine the next leg: 7628 pricing versus the company’s blended ASP, e-cloth net profit per meter, conversion of AI product certifications into orders, and the actual effective output of new capacity after 2028.
1. Why UBS Raised 2027 Earnings by 84%: Pricing, Not Volume, Was Underestimated
The scale of this revision is unusual. UBS raised its China Jushi net profit forecasts for 2026, 2027, and 2028 from RMB6.936 billion, RMB8.403 billion, and RMB9.659 billion to RMB8.473 billion, RMB15.429 billion, and RMB19.99 billion, respectively. The 2027 forecast nearly doubled, while the 2028 forecast more than doubled. By contrast, assumed e-cloth sales volumes barely changed: 2026 and 2027 remain at 1.188 billion meters and 1.310 billion meters, while 2028 increased only from 1.587 billion meters to 1.682 billion meters. The model change is concentrated in blended e-cloth ASPs, with 2027 and 2028 assumptions raised from RMB7.1/meter and RMB7.4/meter to RMB13.5/meter and RMB14.2/meter.
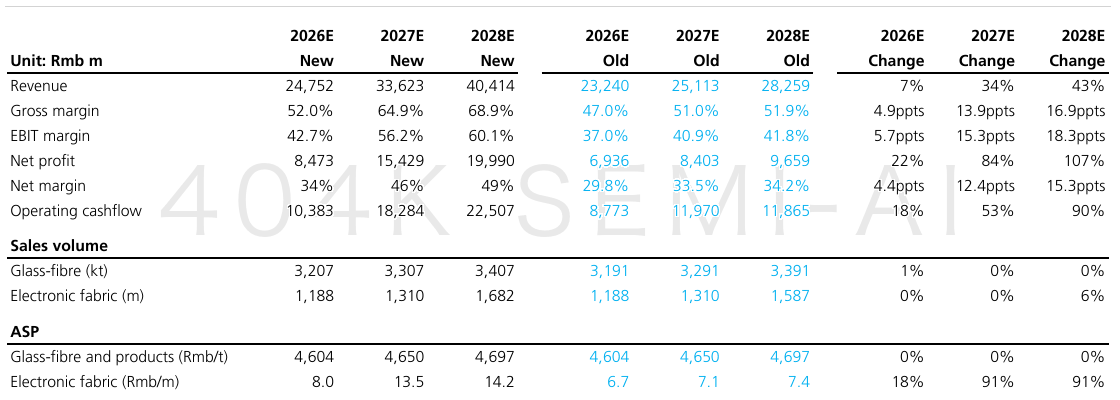
In other words, UBS is not generating higher earnings through more aggressive volume assumptions; it has reassessed pricing power. The 2027 e-cloth net profit assumption rises to RMB9/meter, implying approximately RMB11.7 billion of net profit on sales of 1.310 billion meters. Conventional fiberglass, based on sales of 3.30 million tonnes and net profit of RMB1,100/tonne, contributes approximately RMB3.6 billion. E-cloth has moved from an ancillary business to the dominant profit driver, explaining the sharp increase in the company-wide earnings forecast.
This also provides investors with a more effective monitoring framework. If volumes meet plan but the blended ASP falls below RMB13.5/meter, earnings will quickly revert toward the previous forecast. If spot-price increases feed smoothly into contract pricing, net profit per meter will become the primary determinant of 2027 results. Compared with announced additions of e-glass yarn tonnage or nominal e-cloth capacity, reported e-cloth revenue divided by sales volume, gross margin, and operating cash flow provide a more reliable read-through.
2. RMB10.2 Is More Than a Routine Rebound: Prices Have Exceeded the Previous Cycle Peak
Standard 7628 e-cloth reached RMB10.2/meter in August 2026, already above the previous cycle’s peak of approximately RMB8.8/meter in 2021. More importantly, prices remained near a trough of roughly RMB3–4/meter throughout 2022–2025 before rising rapidly in 2026, indicating that the supply chain has shifted from destocking to competing for effective supply. UBS expects the tax-inclusive 7628 price to approach RMB15/meter by end-2026 and has raised its tax-exclusive blended ASP forecasts for 2026–2028 to RMB8.0, RMB13.5, and RMB14.2.
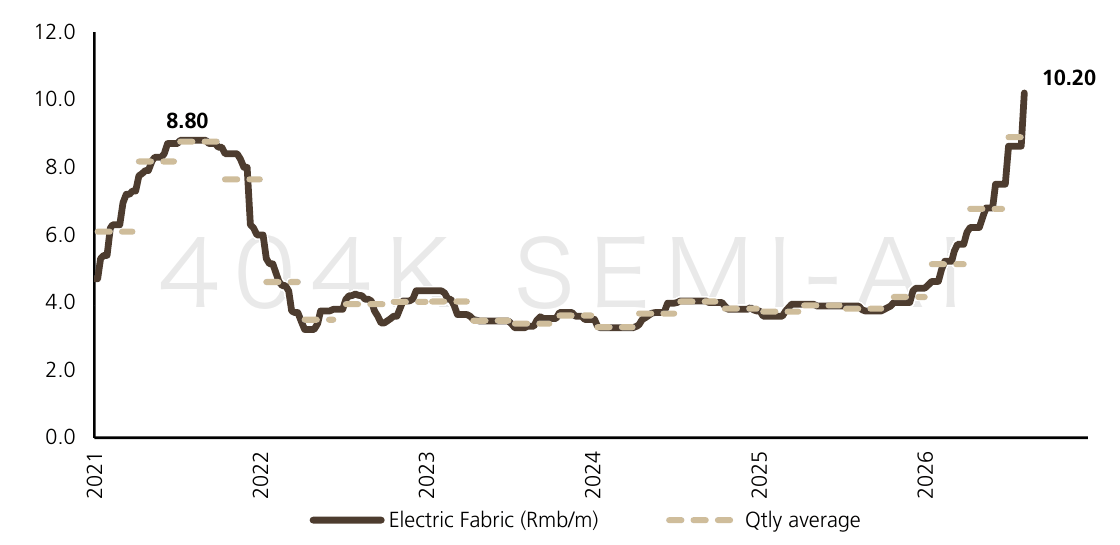
A spot price above the historical peak does not mean all company orders will immediately settle at RMB10.2. Customer mix, contract duration, and product specifications vary, so blended ASPs typically lag quoted market prices. The RMB15 year-end estimate should therefore be treated as a high-frequency directional indicator; quarterly ASP and product mix are what ultimately enter the income statement. UBS’s 2026 blended ASP assumption of only RMB8.0 already reflects low first-half pricing and contract repricing lags. Its RMB13.5 assumption for 2027 requires elevated prices to persist for a substantial period and cannot be supported by one or two year-end quotations alone.
Sustained price increases also require copper-clad laminate (CCL) and printed circuit board (PCB) customers to continue passing through costs. AI servers, high-speed switches, and high-layer-count boards have increased the importance of low-loss materials, making supply stability more critical than the per-meter price of e-cloth. For a full analysis of this material stack, see AI PCB and CCL Deep Dive: From GB300 to Rubin Ultra, Which Runs Short First—High-Layer-Count Boards, M9 Materials, or E-Cloth?. Upstream pricing power is more durable when downstream customers can absorb raw-material costs through product upgrades and price increases. If CCL spreads narrow and customer inventories rise, elevated 7628 prices will face the first test.
3. Why the Supply–Demand Gap Could Persist Through 2028: Nameplate Capacity Is Not Effective Supply
UBS forecasts supply deficits of 13%, 10%, and 6% for electronic-grade fiberglass cloth plus specialty/AI e-cloth in 2026, 2027, and 2028, respectively. The gap narrows each year but does not quickly disappear because e-cloth expansion is not simply a matter of having sufficient yarn. E-glass yarn furnaces, imported looms, upstream and downstream processing equipment, commissioning, yields, and customer certification form a series of interdependent constraints; a delay at any stage reduces effective capacity below nameplate levels.
