
CCL Price Hikes Enter the Profit Validation Phase: Elite Material and TUC Beat Q2 Expectations as Trainium 3 Ramps
目录
TL;DR
I. What Is Genuinely New in This Citi Report?
II. Q2 Beats: Pricing, Product Mix, and Utilization All Contributed
III. Why Another Price Increase May Be Possible in the Third Quarter
IV. Elite Material: The Earnings Base Has Been Reset, and M9 Is the Next Step
V. Taiwan Union Technology: Trainium 3 Provides Validation, While Thailand Capacity Determines the Ramp
VI. Choosing Between the Two Companies: Platform Versus Project
VII. Valuation: High Price Targets, High Hurdles
VIII. Cash Flow Is the Final Gate
IX. Validation Checklist for the Next Four Quarters
X. Conclusion: High Marks in Q2; the Test of Sustainability Begins in Q3
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The high-end copper-clad laminate market is moving beyond the narrative of “very strong demand and extremely tight supply” into an earnings validation phase focused on whether price increases can translate into lasting profits and capacity expansion into cash flow. Elite Material and Taiwan Union Technology Corporation delivered the first high-scoring results in the second quarter, but Citi’s 2027 growth assumptions also set a very high bar for subsequent performance.
TL;DR
Elite Material reported second-quarter 2026 revenue of NT$47.275 billion, up 43% QoQ, with gross margin rising to 33.9% and net profit reaching NT$9.873 billion. TUC reported revenue of NT$14.301 billion, up 42% QoQ, with gross margin of 29.7% and net profit of NT$2.342 billion. Both companies demonstrated that price increases, product-mix upgrades, and improved capacity utilization are translating into profits, although Elite Material’s beat was substantially larger.
The third quarter is the next hurdle. Citi expects the high-end CCL shortage to persist from the third quarter of 2026 through 2027, and Elite Material may raise prices again. If TUC follows with price increases while smoothly absorbing its Thailand capacity ramp beginning in July and demand from Amazon Trainium 3, its margins may have further upside.
The fundamental difference between Elite Material and TUC is already reflected in earnings revisions. Citi raised its 2026, 2027, and 2028 earnings forecasts for Elite Material by 37%, 20%, and 16%, respectively, and raised its price target from NT$5,100 to NT$6,000. For TUC, Citi raised its earnings forecasts for the same periods by only 3%, 1%, and 1%, respectively, while maintaining its price target at NT$1,950. The former represents a reset of the normalized earnings base; the latter looks more like confirmation of an existing growth thesis.
The price targets appear attractive but are based on aggressive 2027 profit assumptions and peak-cycle valuations. Elite Material’s price target applies 30x forecast 2027 EPS, while TUC’s applies 25x; both are near their respective historical highs. If M9, AI ASIC, 800G, and Trainium 3 deliver as expected, earnings can absorb the valuations. If market share, yields, or material supply encounter problems, both multiples and earnings will decline.
The final falsification test is cash flow. Citi expects Elite Material and TUC to generate free cash flow of -NT$17.848 billion and -NT$12.342 billion, respectively, in 2026, turning positive only in 2027. For now, this can be interpreted as capacity expansion and inventory building in exchange for growth. However, if receivables, inventories, and capital expenditures continue to consume profits, the market may still revert to valuing these purported “high-end materials platforms” as cyclical manufacturers.
I. What Is Genuinely New in This Citi Report?
The industry thesis for high-end CCLs has already been thoroughly discussed over the past several months: AI GPUs, hyperscalers’ in-house ASICs, and 800G/1.6T switches increase PCB layer counts and signal speeds, thereby increasing the value content of low-loss CCLs, high-end copper foil, fiberglass cloth, and resins. In our previous article, AI Interconnects Enter a Board-Level Revaluation, we discussed the demand denominator; in Shengyi Technology High-End CCL Update, we examined market share and effective capacity. The new evidence provided by today’s report is that Elite Material and TUC have already translated growth in the denominator into second-quarter profits.
This change cannot be summarized simply as “earnings beat expectations.” Elite Material’s second-quarter revenue was 21% above Citi’s forecast, but net profit was 41% higher. TUC’s revenue was broadly in line with the forecast, yet operating profit was 2% higher. The former indicates simultaneous upside in revenue, pricing, and product mix; the latter shows that margins can improve through price increases and higher utilization even without a revenue surprise. In other words, the sources of returns in high-end CCLs are shifting from volume expansion alone toward the combined leverage of volume, pricing, and product mix.
Under our previous framework, we used five indicators—pricing, lead times, yields, qualifications, and cash flow—to determine whether effective supply had begun to open up. This report provides interim answers for the first three: prices are still rising, supply remains tight, and the share of higher-grade products continues to increase. On qualifications, M9, Trainium 3, and CCLs for ABF substrates continue to advance. The only remaining item not yet completed is cash-flow confirmation of accounting profits. This is also the biggest difference between this article and our previous industry overviews: the focus is no longer on explaining why AI requires more CCLs, but on assessing who has converted price increases into profits and who can then convert those profits into cash.
II. Q2 Beats: Pricing, Product Mix, and Utilization All Contributed
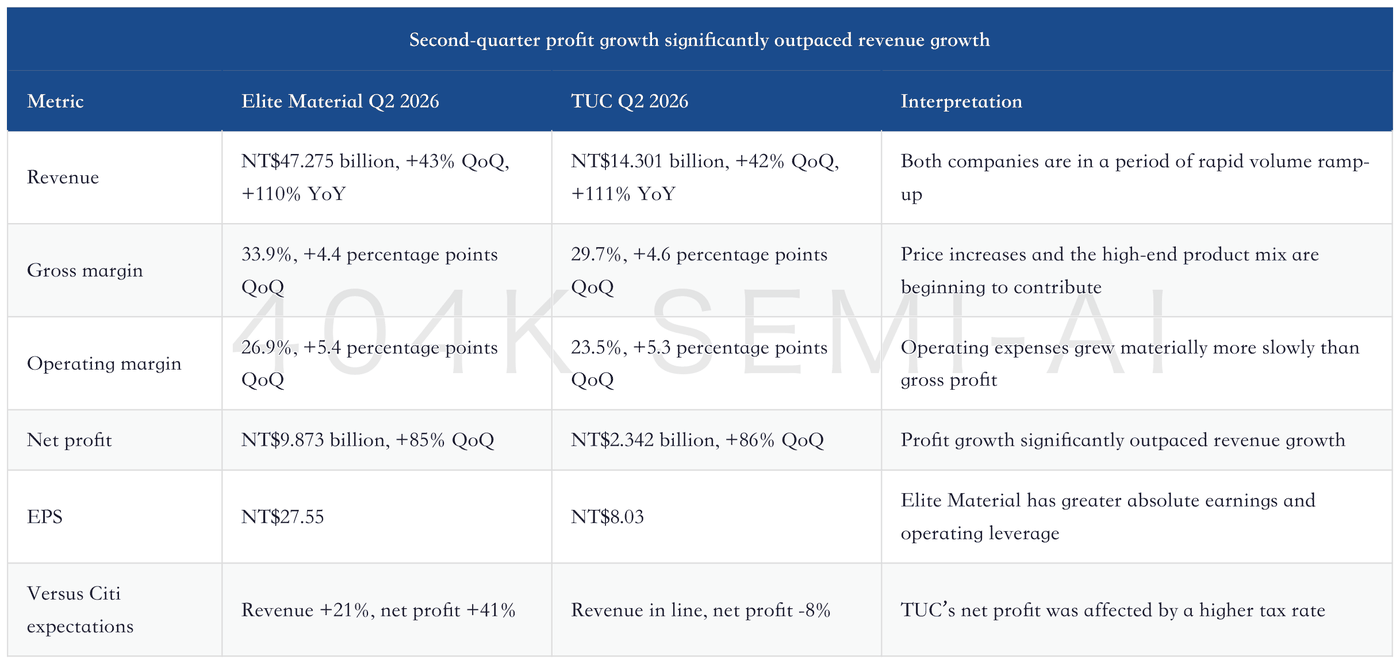
The key for Elite Material was the “high quality” of its beat. Second-quarter gross margin was 33.9%, up 3.5 percentage points YoY, while operating margin was 26.9%, up 6.3 percentage points YoY. The expense ratio declined as revenue expanded, indicating that incremental revenue was not generated by undercutting prices to secure volume. A higher share of advanced materials, price increases, and high utilization collectively converted incremental revenue into operating profit. The company disclosed that M7-and-above products now account for 60%–65% of its mix, enabling it to benefit more than conventional CCL manufacturers from specification upgrades rather than merely from industry restocking.
Elite Material’s official consolidated financial report directly confirmed the core figures cited by Citi: second-quarter revenue of NT$47.2752 billion, gross profit of NT$16.003 billion, operating profit of NT$12.7337 billion, net profit attributable to owners of the parent of NT$9.8734 billion, and basic EPS of NT$27.55. The accountants’ review found no material matters indicating that the financial statements had not been prepared in accordance with applicable standards or did not fairly present the company’s financial position and results. Citi’s assessment that results exceeded expectations is therefore not based on unconfirmed market estimates. The real issue is whether these margins can be sustained.
TUC’s results were also strong, but different in nature. Its second-quarter gross margin reached 29.7%, 8.5 percentage points higher than a year earlier, despite recognizing an approximately 1.9-percentage-point impact from inventory write-downs. The inventory impact resulted from a delay in the Trainium 3 ramp, indicating that second-quarter profit still included a one-off drag. If the project ramps as planned from the third quarter, margins may recover. However, TUC’s revenue was broadly in line with Citi’s forecast, while net profit was 8% below expectations because the tax rate was higher than expected. It demonstrated margin resilience but did not materially raise its revenue base in the way Elite Material did.
