
目录
TL;DR
The Debate Has Shifted: Strong Demand and Adequate Returns Are Two Different Questions
True ROI Is Jointly Determined by Utilization, Pricing, Asset Life, and Financing Costs
“Sold Out” Must Be Assessed Through Contract Quality, Not Just Nominal Scale
The Profit Pool Is Spilling Over, but “Picks-and-Shovels” Suppliers Must Also Undergo Utilization Audits
The Application Layer Has Already Provided the Answer: Cheaper Models Do Not Mean Demand Will Automatically Materialize
Financing Costs Are Entering the Denominator, and Cash Flow Will Define the Next Valuation Divide
Three Scenarios: AI Does Not Need to Lose Momentum for Valuations to Diverge Significantly
Four Pressure Gauges to Watch Next
Conclusion: AI Capex Has Not Lost Momentum, but the Market Has Changed Its Scorecard
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
AI demand continues to accelerate, but the valuation framework for capex has shifted: the market’s next focus is whether these GPUs can remain fully utilized over the long term, sustain pricing, and convert into cash.
TL;DR
AI capex is not cooling, but the margin for error is shrinking. TrendForce expects the nine largest global cloud service providers’ capex to grow about 90% year over year in 2026, exceeding $886.7 billion; UBS expects hyperscaler capex in its sample to grow about 85% and 45% in 2026 and 2027, respectively. Spending forecasts continue to rise, but capex as a share of operating cash flow may reach 107% and 113%, naturally shifting the market’s focus from “how much they bought” to “how much they earned back.”
GPU rental pricing is the most useful real-time pressure gauge, but for now it is only an indicator. One market sample that did not fully disclose platforms, regions, or contract durations shows that per-GPU hourly prices for A100, H100, and B200 have risen about 23%, 25%, and 27%, respectively, since the beginning of the year. Pricing and supply are rising simultaneously, supporting the view that demand remains tight; however, only concurrent improvements in pricing, utilization, service levels, and renewal rates can prove that data-center capacity is genuinely “fully sold.”
Orders, sold-out capacity, and remaining performance obligations cannot be equated directly with profit. Trainium capacity has reportedly been largely sold out through the end of 2027, while some memory capacity has also been reserved in advance; Palantir’s results provide a clearer illustration of contract-quality tiers: TCV and RDV indicate potential demand, RPO reflects more stringent non-cancellable obligations, while billings, deferred revenue, and free cash flow demonstrate actual conversion.
AI capex is shifting the profit pool toward power, memory, packaging, networking, and testing, but each segment has different realization conditions. onsemi estimates that its content per AI rack could rise from about $15,000 currently to $115,000 under an 800V architecture by 2030; meanwhile, CoWoS capacity expansion may initially depress utilization, and long-term HBM agreements may lock in volume without securing the highest prices. The “beneficiary” label must still pass four gates: qualification, yield, utilization, and cash flow.
Genuine commercialization divergence has already emerged at the application layer. Palantir’s second-quarter revenue grew 93%, with an adjusted free-cash-flow margin of 63%; Wix’s revenue grew 15%, and Base44’s gross-margin outlook improved, but the core business remained under pressure, while free cash flow excluding the effects of acquisitions and restructuring fell to $61 million. Lower model costs are only the starting point; whether customers expand usage and whether contracts convert into cash ultimately determine whether infrastructure ROI can close the loop.
The Debate Has Shifted: Strong Demand and Adequate Returns Are Two Different Questions
As of 15:20 Beijing time, growing evidence within today’s window points to the same issue: investment continues to accelerate, but the market is no longer willing to assign valuations based solely on the scale of capex.
TrendForce expects the nine largest global cloud service providers’ capex to grow about 90% year over year in 2026, exceeding $886.7 billion. For another group of hyperscalers, UBS forecasts capex growth of about 85% and 45% in 2026 and 2027, respectively, and server shipment growth of 19% and 17%, respectively. The two samples cannot simply be added together, but they point in the same direction: AI infrastructure expansion is not over, and the investment peak is extending into 2027.
The risk arises from the same set of figures. UBS estimates that capex as a share of revenue for the eight largest internet companies may rise from 17.2% in 2024 to 40.1% in 2026 and 47.7% in 2027; capex as a share of operating cash flow may increase from 54% to 107% and 113%. When investment exceeds current-period operating cash flow, revenue growth, bond financing, depreciation periods, and residual values are no longer minor modeling assumptions; they directly determine shareholder returns.
Semiconductor Momentum Trade Recedes: Morgan Stanley Sees Not the End of AI, but Capex Return Pressure Coming to the Fore
The easiest mistake today, therefore, is to translate “GPUs remain in short supply” directly into “returns on capital have been proven.” Shortages can demonstrate marginal demand, but cannot independently prove returns over an asset’s full life cycle. Once a data center is built, it must still progress through commissioning, ramp-up, customer migration, inference-volume growth, renewals, and hardware upgrades. If any step slows, apparent sold-out capacity may turn into underutilization, depreciation pressure, or low-priced long-term contracts.
True ROI Is Jointly Determined by Utilization, Pricing, Asset Life, and Financing Costs
The return on investment (ROI) of an AI data center can first be understood through a simple operating formula: realizable returns come from paid compute and application revenue, less power, networking, operations and maintenance, financing costs, and asset impairments, divided by actual invested capital. GPU count determines only the capacity ceiling; what actually generates revenue is “rentable GPU count × utilization × hourly price × billable hours.”
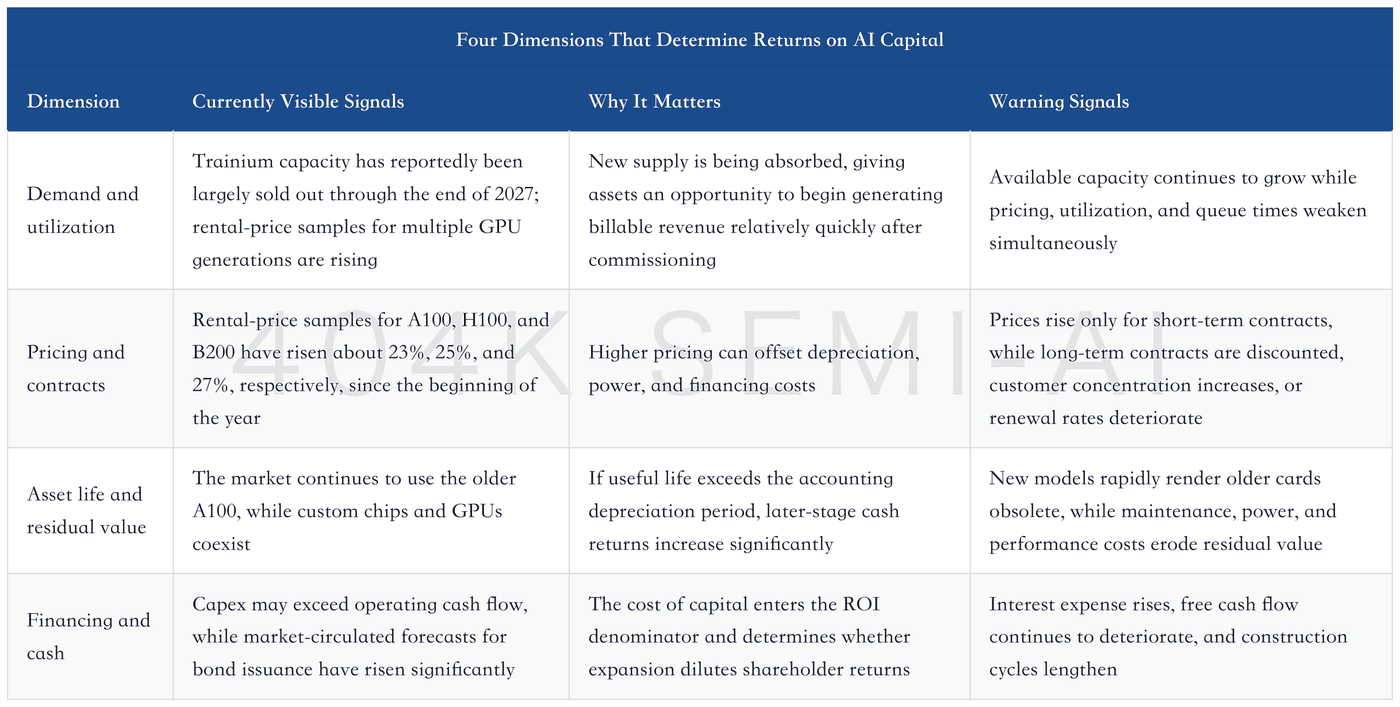
GPU rental pricing is today’s most eye-catching signal. One market sample states that the per-GPU hourly price for A100 increased from $1.30 at the beginning of the year to $1.60, H100 from $2.15 to $2.70, B200 from $4.40 to $5.60, and H200 from about $2.60 in May to about $3.00. If the methodology is consistent, this is indeed inconsistent with the claim that “supply is already materially excessive.”
However, this dataset cannot yet be incorporated directly into earnings models. It does not disclose differences in region, power costs, network configurations, minimum rental periods, service levels, or actual utilization, and it cannot rule out divergence between spot and long-term contract prices. The most valuable data are not quotes on a given day, but rental rates, utilization, and renewal rates over several consecutive quarters for the same platform, region, and service level. ROI genuinely improves only if all three curves move upward together; higher quoted prices alone may still reflect localized supply mismatches.
AI Compute ROIC Deep Dive: How 1GW of GB300, GPU Rentals, and Model APIs Could Deliver 25%-50% Returns
Hardware life can likewise change the outcome. Bulls often cite the fact that “the 6-year-old A100 is still in use” as proof that GPUs can continue generating revenue after depreciation. The direction of this argument is valid, but individual usable devices cannot be treated as representative of an entire asset pool’s residual value. Whether older cards can generate profits depends on performance per watt, software compatibility, failure rates, customer workloads, and electricity prices. Accounting lives may be long, but economic lives may be rapidly compressed by the lower unit inference costs of newer-generation chips.
“Sold Out” Must Be Assessed Through Contract Quality, Not Just Nominal Scale
AWS CEO Matt Garman said Trainium capacity is largely sold out through the end of 2027. This is a strong signal because customers are seeking not only absolute performance, but also lower unit compute costs and the flexibility to choose between custom chips and NVIDIA GPUs. It shows that cloud providers can improve margins through their chip mix rather than remain permanently locked into a single hardware cost structure.
The question remains: what exactly has been sold out? Are these non-cancellable, multi-year commitments or capacity reservations whose scale can be adjusted? Have customers prepaid? Do prices change with costs? Who bears responsibility if capacity does not come online on schedule? How much residual value will the assets retain after the contracts expire? The same nominal capacity can have a completely different contractual cash-payback period.
Palantir’s earnings provide a contract-quality framework that can be applied to cloud providers and AI infrastructure. U.S. commercial total contract value (TCV) reached $2.132 billion in the quarter, while remaining deal value (RDV) reached $6.238 billion. These figures indicate strong demand, but they typically assume that customers exercise all options and do not terminate early. The more stringent remaining performance obligations (RPO) increased from $2.42 billion to $4.9 billion; the next question is whether billings, deferred revenue, and cash flow can grow in tandem.
This framework can directly reshape AI infrastructure valuation: use nominal GW and total contract value to assess the upper bound, non-cancellable commitments to assess visibility, prepayments and billings to assess the customer’s share of the burden, and free cash flow to assess ultimate delivery. Looking only at the first layer will overstate the boom; looking only at the last may miss growth that is still in the construction phase.
The Profit Pool Is Spilling Over, but “Picks-and-Shovels” Suppliers Must Also Undergo Utilization Audits
As capital expenditure continues to grow, the profits will not remain confined to GPUs. As rack power rises, the value of power conversion, protection, backup power, liquid cooling, networking, optical interconnects, memory, advanced packaging, and testing all increases. What truly merits tracking is not who applies an AI label, but who can consistently convert system complexity into pricing, gross margin, and cash flow.
The AI power tree outlined by onsemi is illustrative. The company estimates that, in today’s 54V, 120 kW racks, serviceable content per rack is approximately $15,000. By 2030, if the architecture shifts to 800V high-voltage direct current and rack power rises to 600 kW–1 MW, content could reach $115,000, approximately 7.7 times the current level. The increase does not come from a single more expensive chip; high-voltage conversion, hot swapping, protection, backup power, and multi-stage voltage reduction all require more power semiconductors.
This remains an opportunity estimate, not revenue that has already been booked. 700V and 1200V vertical gallium nitride devices must complete sampling, qualification, mass production, and yield ramp-up; customer platforms must also transition to 800V as planned. onsemi’s second-quarter non-GAAP gross margin was 39.3%, with third-quarter guidance of 40%–42%. The strongest future evidence would be simultaneous improvement in AI revenue growth, capacity utilization, and gross margin—not the projected long-term content per rack itself.
Advanced packaging reveals the same issue. UBS expects monthly CoWoS capacity to increase from 66,000 wafers in 2025 to 133,000 in 2026 and 218,000 in 2027; utilization may initially decline from 86% to 82% before recovering to 95% in 2027. While capacity expansion resolves shortages, it will temporarily reduce utilization. Supply-chain revenue can still grow, but margins, depreciation absorption, and valuations may not move in tandem.
Memory offers a more direct counterexample. During the review window, reports indicated that the three leading manufacturers’ 2027 DRAM and HBM capacity had already been pre-allocated or sold out, and NAND capacity might also be locked in soon. Another market report, however, said that HBM3E prices declined after repricing and that long-term agreements signed earlier may carry lower prices than those secured by later buyers. These two signals are not contradictory: tight volumes do not mean every supplier achieves the same high pricing, and locking in volumes does not mean locking in the highest profits.
HBF, tiered storage, and more efficient model selection will further alter value distribution. On one hand, they ease inference-capacity and cost pressures, helping applications scale usage. On the other, they may reduce the amount of expensive HBM or GPU hours required for each task. This benefits the ecosystem as a whole, but unit demand for any single hardware category may not rise linearly forever.
The Application Layer Has Already Provided the Answer: Cheaper Models Do Not Mean Demand Will Automatically Materialize
Infrastructure ultimately must be funded by application revenue. The clearest comparison today is not between two model leaderboards, but between the cash-flow quality of Palantir and Wix.
Palantir’s second-quarter revenue was $1.935 billion, up 93% year over year; U.S. commercial revenue was $764 million, up 149%; and U.S. government revenue was $809 million, up 90%. The company signed 73 transactions worth more than $10 million during the quarter, with an adjusted operating margin of 62% and adjusted free cash flow of $1.22 billion, representing a 63% margin. These figures show that AIP has entered customers’ data, permissions, and execution workflows, ultimately converting into large contracts, billings, and cash.
Palantir CTO Shyam Sankar also noted that the standard version of Nemotron Ultra outperformed more expensive frontier models on five production tasks within 24 hours. This highlights that enterprise value depends on matching the model to the task. What customers are actually buying is lower cost, greater accuracy, and faster deployment into production workflows—not a model leaderboard position.
Wix presents the other side. Second-quarter revenue was $563 million, up 15% year over year. After BASE44 launched its internally developed model, management expected its non-GAAP gross margin to rise from nearly zero at the beginning of the year to approximately 60% in the second half, while AI costs as a percentage of BASE44 bookings could decline to 30%–40%. This demonstrates that there is room to improve model costs.
But the core business did not automatically become stronger as a result. The Partners business remained affected by weak demand from long-tail small designers, gross merchandise value increased only 3% to $3.6 billion, and free cash flow excluding the impact of acquisitions and restructuring was $61 million, reportedly the lowest quarterly level in 3 years. BASE44 customer acquisition still requires substantial sales investment, monthly subscriptions account for a relatively high share, and retention and monetization remain at an early stage. Lower costs improve unit economics, but they cannot replace customer demand, retention, and cash collection.
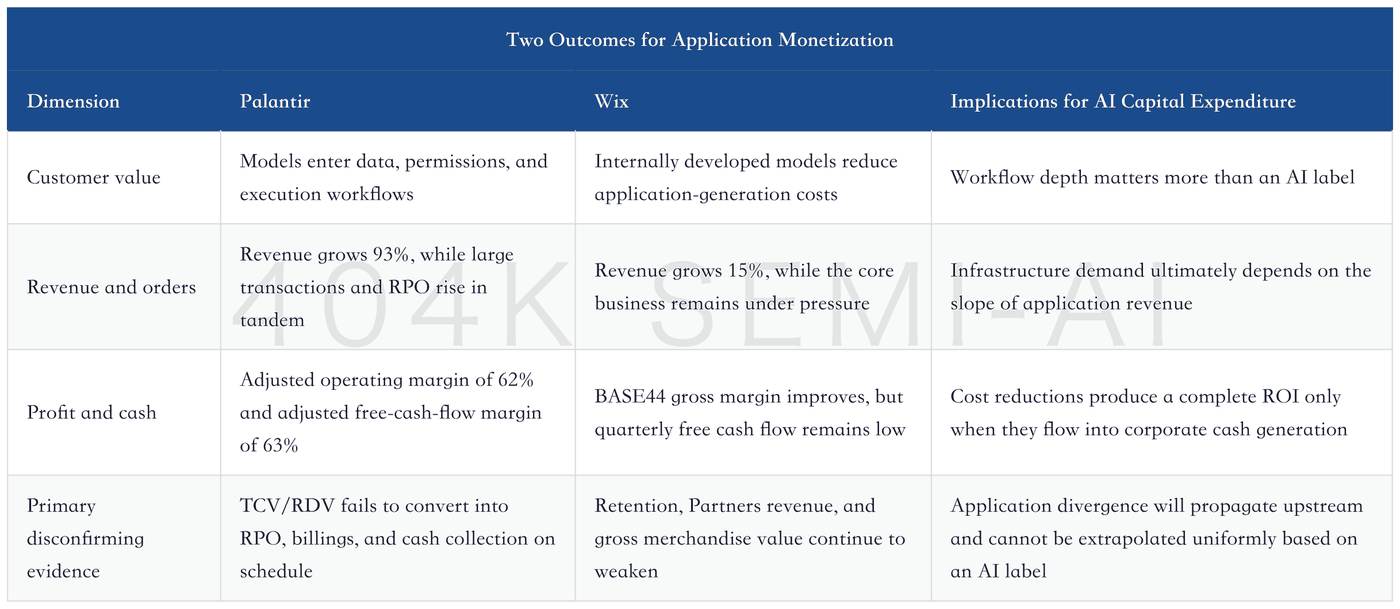
This also explains why enterprise AI adoption will remain uneven. A small number of model companies and successful applications consume substantial compute, some enterprises generate clear returns in customer service, workflow automation, and fraud prevention, while many traditional production workloads remain in the early stages of migration. Infrastructure demand can be strong even as application monetization diverges; this is not a logical contradiction, but a consequence of the construction cycle preceding the revenue cycle.
Financing Costs Are Entering the Denominator, and Cash Flow Will Define the Next Valuation Divide
When capital expenditure is below operating cash flow, cloud providers can use internal funding to absorb longer payback periods. When capital expenditure persistently exceeds operating cash flow, the use of bonds, leases, joint ventures, and project financing will increase. Market reports during the review window indicated that Amazon, Google, Meta, Microsoft, and Oracle could issue more than $250 billion of bonds in 2026. This figure has not yet been verified line by line against each company’s financing plans, but its direction is consistent with UBS’s assessment that capital expenditure is exceeding operating cash flow.
Financing does not automatically mean that risk is out of control. When credit quality is high, contract terms are long, and asset utilization is high, debt can reduce the cost of equity capital and align the construction period with the revenue period. The real danger arises when short-term financing funds long-term construction, floating costs are matched with fixed-price contracts, or data centers begin bearing full interest and depreciation before they are fully utilized.
Google, Meta, Microsoft, and Amazon Earnings Deep Dive: Diverging Capital-Expenditure Efficiency, Cloud Revenue, and Free Cash Flow
Therefore, over the next two quarters, investors should not focus solely on whether capital-expenditure guidance continues to rise. More important is whether cloud-revenue growth, RPO conversion, depreciation periods, interest expense, and free cash flow can improve together. Slower capital expenditure is not necessarily negative: if utilization and revenue remain unchanged, a slower construction pace would release free cash flow. Continued capital-expenditure growth is not necessarily positive either: if financing costs and construction timelines grow faster, marginal returns will decline.
Three Scenarios: AI Does Not Need to Lose Momentum for Valuations to Diverge Significantly
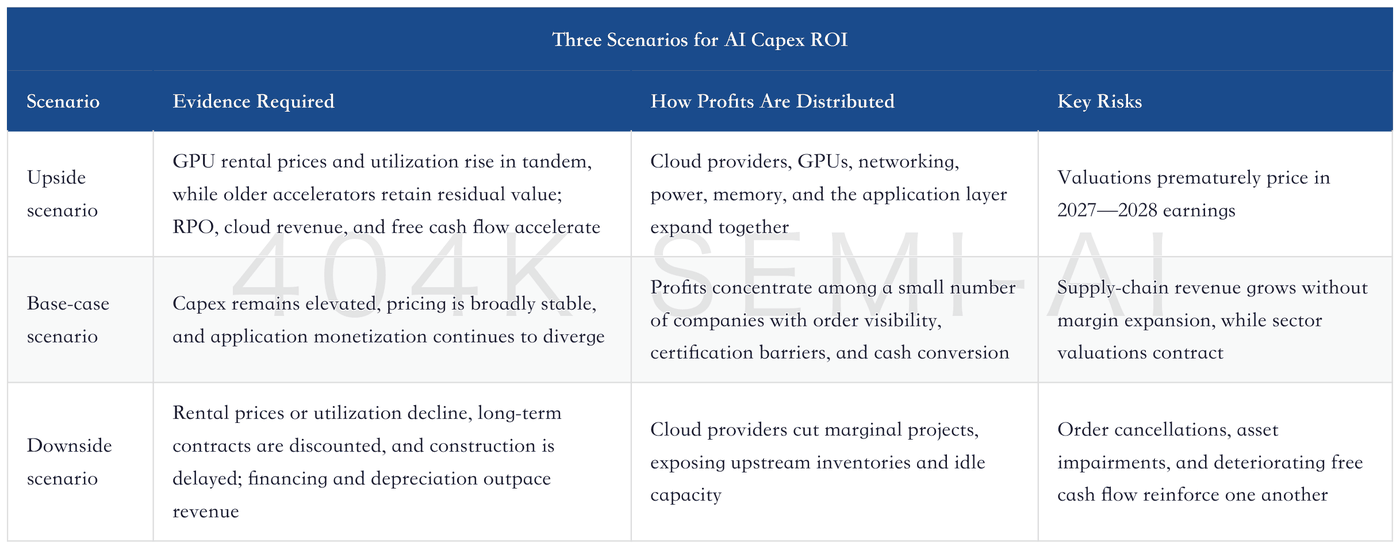
The current evidence is closer to the upper end of the base case. Tight Trainium capacity, rising rental prices across samples of multiple GPU generations, and continued upward revisions to cloud providers’ capex indicate that demand has not suddenly disappeared; Palantir’s cash flow demonstrates that some application-layer companies have already proven the model. However, the rising ratio of capex to operating cash flow, increasing financing needs, and weakness in Wix’s core business also show that returns will not accrue evenly across this value chain.
The strongest companies will no longer be merely those that “sell more AI,” but those that can increase the output generated by every $1 invested. Cloud providers must raise cluster utilization and service gross margins; chip and component companies must convert value per rack into actual revenue and gross margin; application companies must integrate models into workflows and collect cash. Any layer that expands scale without improving unit economics will pass the risk to the next layer.
Four Pressure Gauges to Watch Next
The first is GPU utilization and rental pricing. For fixed regions and service tiers, the prices, available capacity, queue times, and renewal rates of A100, H100, H200, and B200 need to be monitored continuously each month. A single day’s quotes cannot establish a trend.
The second is contract-to-cash conversion. Cloud providers’ and application companies’ remaining performance obligations, non-cancellable commitments, billings, deferred revenue, and operating cash flow should grow in the same direction. Rising contract value coupled with slower cash conversion is the earliest warning sign of deteriorating quality.
The third is the economic life of hardware. Depreciation periods, rental utilization of older accelerators, performance per watt, and second-hand residual values determine longer-term returns. If older accelerators can continue operating reliably, post-depreciation cash flow could be substantial; if software, power consumption, or customer demand forces early retirement, accounting profits will overstate actual returns.
The fourth is financing and free cash flow. The ratio of capex to operating cash flow, bond issuance, interest expense, project-financing maturities, and free cash flow need to be assessed together. Expanding financing volumes are not inherently concerning; rising financing costs combined with declining asset utilization are.
Conclusion: AI Capex Has Not Lost Momentum, but the Market Has Changed Its Scorecard
Today’s 55 items from the X monitoring window, the latest earnings reports, and industry research collectively point to a more specific conclusion: demand remains strong and the investment cycle continues to lengthen, but valuation criteria have shifted from the scale of equipment procurement to operating returns.
Whether GPUs are in short supply addresses only supply and demand; rental prices and utilization address revenue; contract terms and collections address quality; depreciation, residual values, and financing costs address shareholder returns. All four layers are essential.
Accordingly, the most important question in the next phase is not which company announces higher capex, but which can keep its purchased compute capacity fully monetized over the long term, convert system complexity into gross profit, turn contracts into cash, and recoup its investment before financing costs rise. Only companies capable of doing so will have truly closed the loop on AI capex ROI.