
目录
Executive Summary
July Data Raise the Prospect of Samsung Moving Ahead
Why Customs Proxies Work—and Why They Are Not Conclusive
Why One Month Can Move the Quarterly Regression So Sharply
Samsung Electronics’ US$12 Billion Scenario Reflects Both Volume and Mix
SK Hynix’s $5.6 Billion Estimate Looks More Like a Timing-Mismatch Stress Test
HBM4 Leadership Matters More Economically Than One Quarter of Market Share
Customer Diversification Amplifies the Value of a Second Supplier
The Malaysia Route Reveals an Expanding Packaging Network
The Implications for Revenue, Profit, and Market Expectations Are Asymmetric
How the Market Will Price a Temporary Overtake
Three Scenarios Will Determine Whether the “Overtake” Becomes a New Competitive Order
What Evidence Would Overturn the Current View
Public Data to Track Next
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
South Korea’s July export data offer the first quantitative indication that Samsung Electronics could overtake SK hynix in quarterly HBM revenue. However, the signal also reflects differences in shipment timing, packaging routes, and product generations. The direction of the share shift is becoming clearer, but its durability still requires confirmation from August and September data and customer-platform ramps.
Executive Summary
South Korean multi-chip memory exports to Taiwan and Malaysia fell 32% month over month in July, but remained 13% above April and 64% higher year over year. Seasonal cooling does not alter the robust demand picture; it simply underscores the need to assess monthly data within the quarterly shipment cycle.
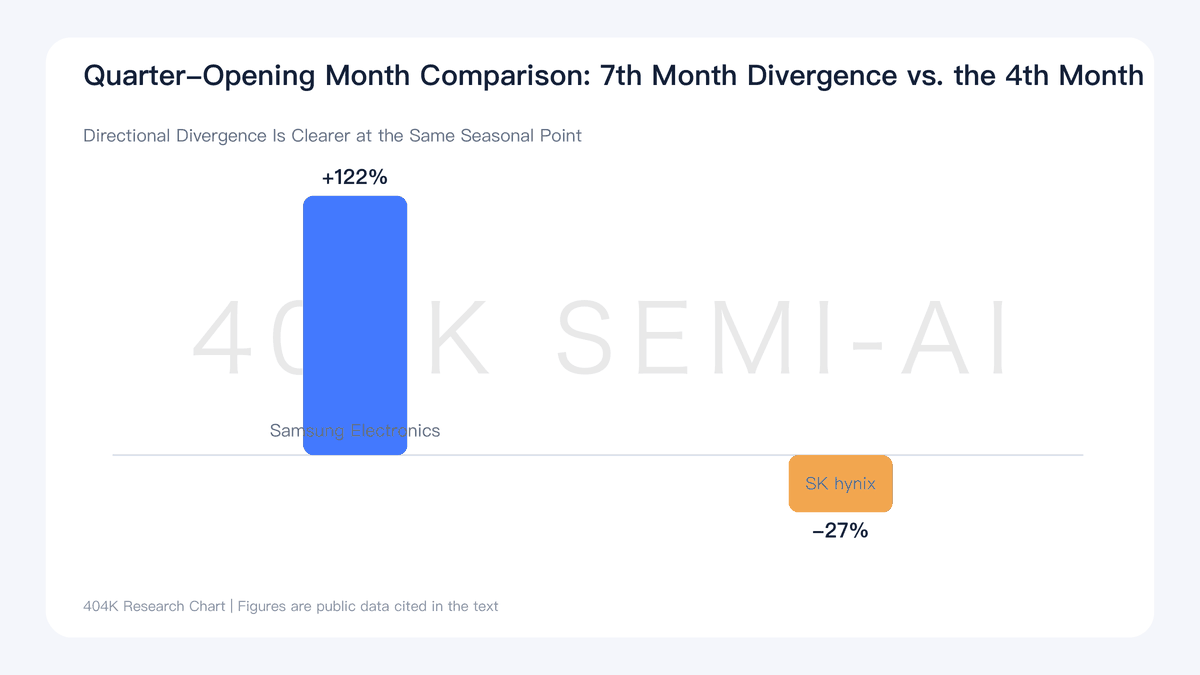
July exports from Samsung Electronics’ proxy region were approximately US$2.2 billion, down 35% month over month but 122% above April. Historical regressions imply approximately US$12 billion of HBM revenue in 3Q26, up approximately 80% from 2Q26 and above Bernstein’s US$9.3 billion forecast.
July exports from SK hynix’s proxy regions fell 28% month over month and 27% from April. The base-case regression implies approximately US$5.6 billion of HBM revenue in 3Q26, down approximately 20% from 2Q26. If SK hynix repeats an exceptionally back-end-loaded shipment pattern, the upside scenario could still approach US$12 billion.
Samsung Electronics’ export value per unit weight rose another 21% month over month, exceeding 2x the April level and approaching 4x SK hynix’s July figure. This is directional evidence of a higher HBM4 mix, not a direct measure of average chip selling prices.
Changes to the Rubin platform timeline could explain SK hynix’s near-term weakness, but do not by themselves prove lost orders. Samsung Electronics’ early shipments may also include customer inventory building, qualification lots, and earlier packaging milestones.
The July data shift the debate from whether Samsung Electronics is catching up to whether it can take a temporary lead in 3Q26. The more important questions concern 4Q26 and 2027: whether Samsung Electronics can sustain yields and delivery performance, and whether SK hynix can convert delays into catch-up volumes.
July Data Raise the Prospect of Samsung Moving Ahead
Before June, export data primarily showed that Samsung Electronics’ catch-up was accelerating. In the previous tracking update, Samsung Electronics’ regression-implied 2Q26 HBM revenue was approximately US$6.7 billion, up 89% from 1Q26, while SK hynix remained the clear volume leader at approximately US$7.6 billion. The July update changes the relative positioning: Samsung Electronics has now exceeded SK hynix in monthly proxy exports for the second consecutive month, while the two companies’ trajectories have diverged sharply since entering the same quarter.
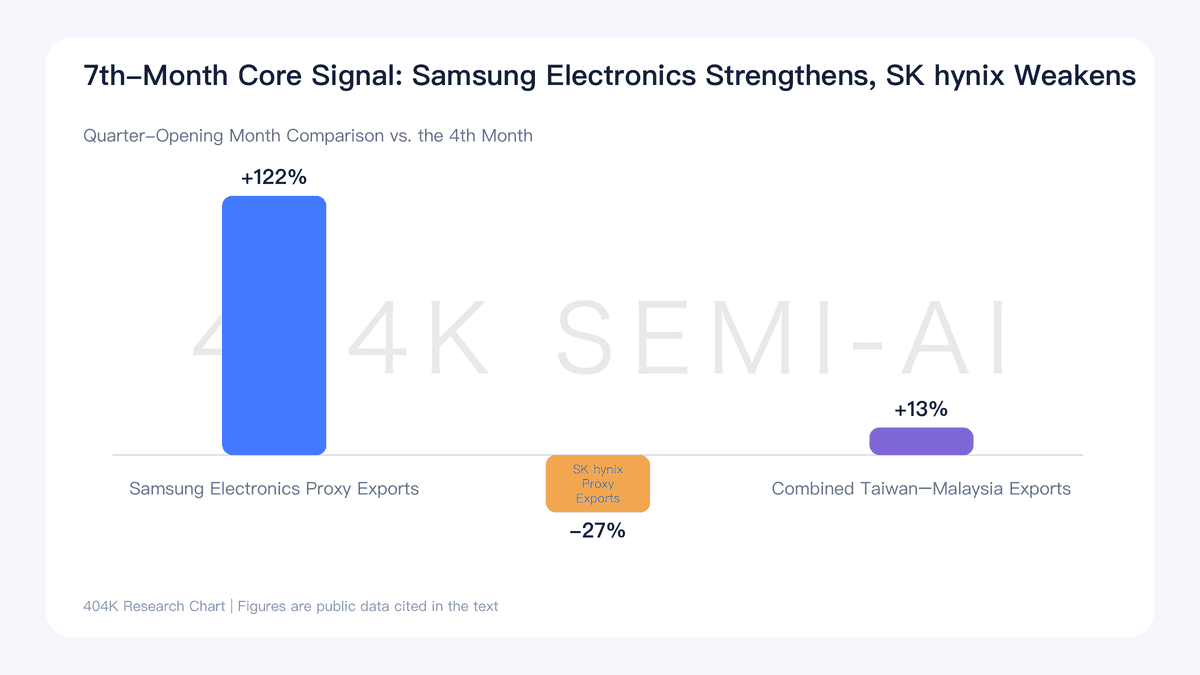
South Korean multi-chip memory exports to Taiwan and Malaysia fell 32% month over month in July. Viewed in isolation, that figure could suggest cooling demand, but July exports were still 13% above April and up 64% year over year. Because April and July are both the first month of a quarter, April is the more appropriate seasonal benchmark. Strong year-over-year growth in both July and the quarter-opening comparison indicates that HBM-related logistics remain on an expansionary trajectory.
Across all destinations, South Korea exported approximately US$10.1 billion of multi-chip memory in July, down 20% month over month but up 24% from April. Taiwan and Malaysia together accounted for 41%, below April’s 45%. The decline in the proxy destinations’ share indicates that price increases for conventional memory and shipments to other regions also lifted the total, so not all incremental exports can be attributed to HBM.
The direction of exports from each company’s proxy region is what materially changes the competitive narrative. July exports from South Chungcheong Province, Samsung Electronics’ proxy, totaled approximately US$2.2 billion, up 122% from April. Combined exports from North Chungcheong Province and Icheon, the proxies for SK hynix, fell 27% from April. One company expanded sharply in the quarter’s opening month while the other fell below the previous quarter’s opening level—a divergence more informative than aggregate export growth alone.
Why Customs Proxies Work—and Why They Are Not Conclusive
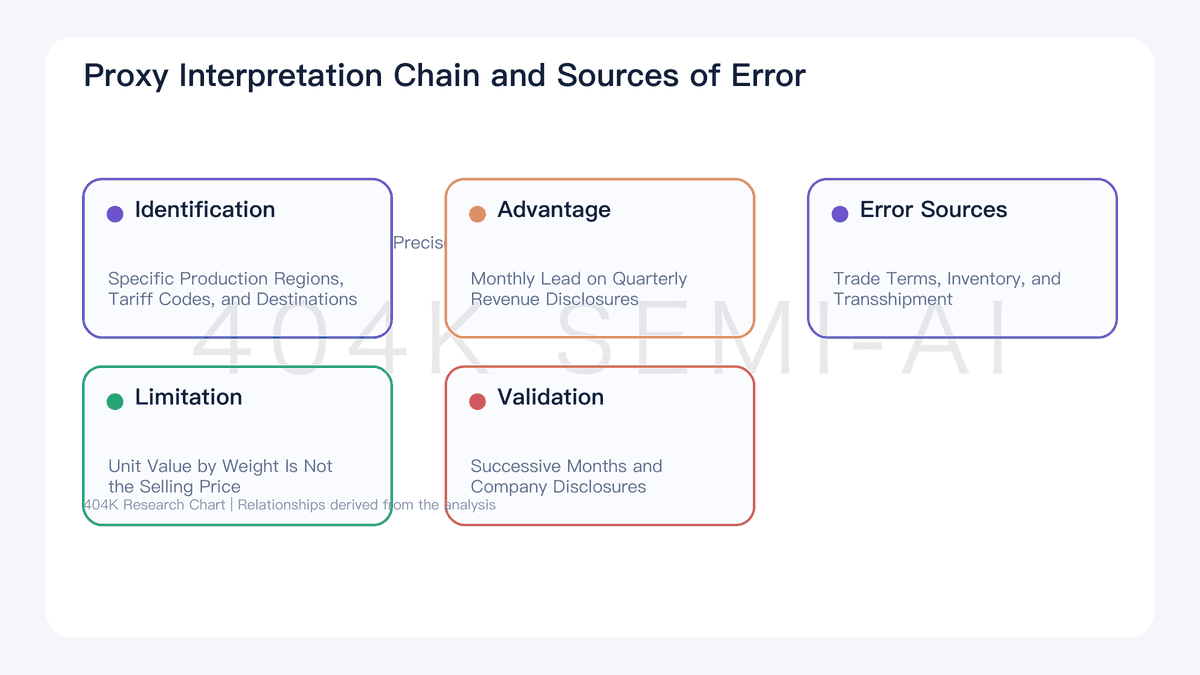
HBM is typically exported from South Korea as multi-chip memory to downstream packaging and system-integration locations. Taiwan is central to advanced packaging and the GPU supply chain, while Malaysia hosts high-end packaging facilities operated by companies including Intel. Exports from specific South Korean production regions, under designated customs codes and to these two destinations, have therefore shown a strong historical correlation with Samsung Electronics’ and SK hynix’s same-quarter HBM revenue.
The method’s principal advantage is timeliness. Companies typically disclose quarterly revenue after quarter-end, while monthly customs data provide an earlier view of volumes, product mix, and routing changes. Samsung Electronics has historically exhibited a back-end-loaded monthly shipment pattern, with the first month often accounting for less than 20% of the full quarter. If Samsung Electronics has already established a high base in what is normally a weak first month, the probability of further gains over the next two months naturally increases.
The limitations are equally specific. First, export value is not the same as recognized end-market revenue, as trade terms and delivery-recognition timing may differ. Second, value per unit weight is affected by chip generation, stack height, capacity, packaging format, and conventional-memory pricing. Third, domestic Korean integration, transshipment through third countries, and inventory changes are not fully captured. Fourth, customer qualification lots and high-volume production may appear under the same customs code.
Customs data are therefore useful for assessing direction, relative strength, and timing differences, but a single month’s regression estimate should not be treated as a precise earnings commitment. The base case should be presented alongside an extreme-seasonality scenario, with probabilities subsequently updated using August and September exports, company results, and customer-platform progress.
Why One Month Can Move the Quarterly Regression So Sharply
The importance of the quarter’s first month depends on each company’s historical shipment cadence. Samsung Electronics has shown back-end-loaded shipments in many prior quarters, with the first month contributing a relatively small share of quarterly exports. Because July already reached approximately US$2.2 billion in a typically low-weight month, the model also incorporates normal seasonal growth over the next two months, driving the quarterly estimate sharply higher.
SK hynix’s historical distribution is more balanced, so the first month typically contains more information about the full quarter. Because July was 27% below April, the model tends to extrapolate that weakness across the quarter. Although the two companies use similar customs codes and destinations, their seasonal parameters differ, precluding the use of a common extrapolation multiple.
Regression results also depend on the sample window. Samsung Electronics’ full historical sample implies approximately US$12 billion, while the sample since 1Q25 implies approximately US$12.6 billion—a relatively narrow difference that reinforces confidence in the direction of the signal. For SK hynix, including the exceptionally back-end-loaded 2Q24 observation expands the range from US$5.6 billion to approximately US$12 billion, leaving a much wider interval.
The model’s sharp swings highlight the variables that now require confirmation: whether Samsung Electronics can sustain July’s elevated level, and whether SK hynix’s weakness merely reflects a shift in customer-platform timing. August data will carry more incremental information than July for both companies because they can distinguish a genuine trend from a one-off anomaly.
