
BofA Flow Show Deep Dive: Are Funds Rotating Out of AI Megacaps and Into Small-Cap Cyclicals and Emerging Markets?
目录
TL;DR
1. What This Flow Show Is Really Trying to Answer
2. Why “Small Is Big” Is More Than a Slogan
3. BofA Has Not Abandoned AI, but It Is Asking for Stronger Proof
4. Three Risk Lines: MAGS, AUD/JPY, and the Yield Curve
5. Why Long-End Treasuries Are the Most Contrarian Trade
6. Emerging Markets Remain the Long-Term Theme, but Korea and Taiwan Are Already Hot
7. The Trading Framework From This Report
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core message of this BofA Flow Show is not to turn bearish on AI, but to warn that the market is rotating from giant AI stocks toward small caps, cyclicals, REITs, and emerging markets. Risk appetite has not disappeared; it is looking for the next assets to absorb capital. Fund flows, crowded valuations, and long-end rates are rewriting the trading sequence. The real task is to distinguish rotation, catch-up rallies, and a shift into risk-off hedges.
TL;DR
Capital is looking for new receiving assets. U.S. equity and technology funds have turned to outflows, but bonds, REITs, infrastructure, and some cyclical assets are taking in capital. This shows risk appetite has not disappeared; it is spreading out from the concentrated mega-cap AI trade.
BofA is not rejecting the AI theme. The real question in the report is how far cloud vendors and AI arms racers need to fall before the market starts trading capex cuts. The key issue is crowding, not a collapse in demand.
Small can become big for real reasons. Small caps, mid caps, housing, REITs, materials, and infrastructure benefit from low positioning, valuation repair, and affordability-policy expectations. In the short term this looks like a catch-up trade; in substance, capital is looking for a new pool.
Long-end Treasuries are insurance. Since the start of the new Fed chair’s term, Treasuries have risen and equities have pulled back. If long-end yields keep falling, that can support REITs and small caps while also compressing crowded equity valuations.
Emerging markets remain strong. Year to date, emerging markets, Korea, and Taiwan have significantly outperformed the U.S. BofA still favors EM versus U.S. equities, but the high deviation in Korea and Taiwan means chasing strength needs earnings validation.
Three lines define the risk. MAGS below 60, AUD/JPY below 110, and a renewed inversion of the yield curve are summer risk-off triggers. If they happen together, rotation becomes de-risking.
This is not a bearish report. The more accurate reading is that the AI trade has entered its second phase. The market is no longer paying only for megacap concentration; it is also starting to price small-cap cyclicals, semiconductor spillovers, and emerging markets.
1. What This Flow Show Is Really Trying to Answer
The title of this BofA report is “Small is Big.” The literal meaning is simple: small is becoming bigger. In the current market, it does not mean small caps have suddenly become more important than AI. It means that after mega-cap AI stocks, hyperscale cloud vendors, and the semiconductor theme have absorbed too much capital, the next question is where the next wave of money goes.
The report opens with a sharp question: how much further must hyperscale cloud vendors fall before the market starts trading capex cuts? This question is more valuable than a generic bearish call. It does not say AI capex is about to collapse. It says investors have begun to separate two things: AI demand is still there, but the phase of paying an unconditional premium for AI capex may be approaching its end.
The AI Trade Has Moved Ahead of Macro: Recalibrating Compute Capex, Earnings Expectations, and Market Pricing
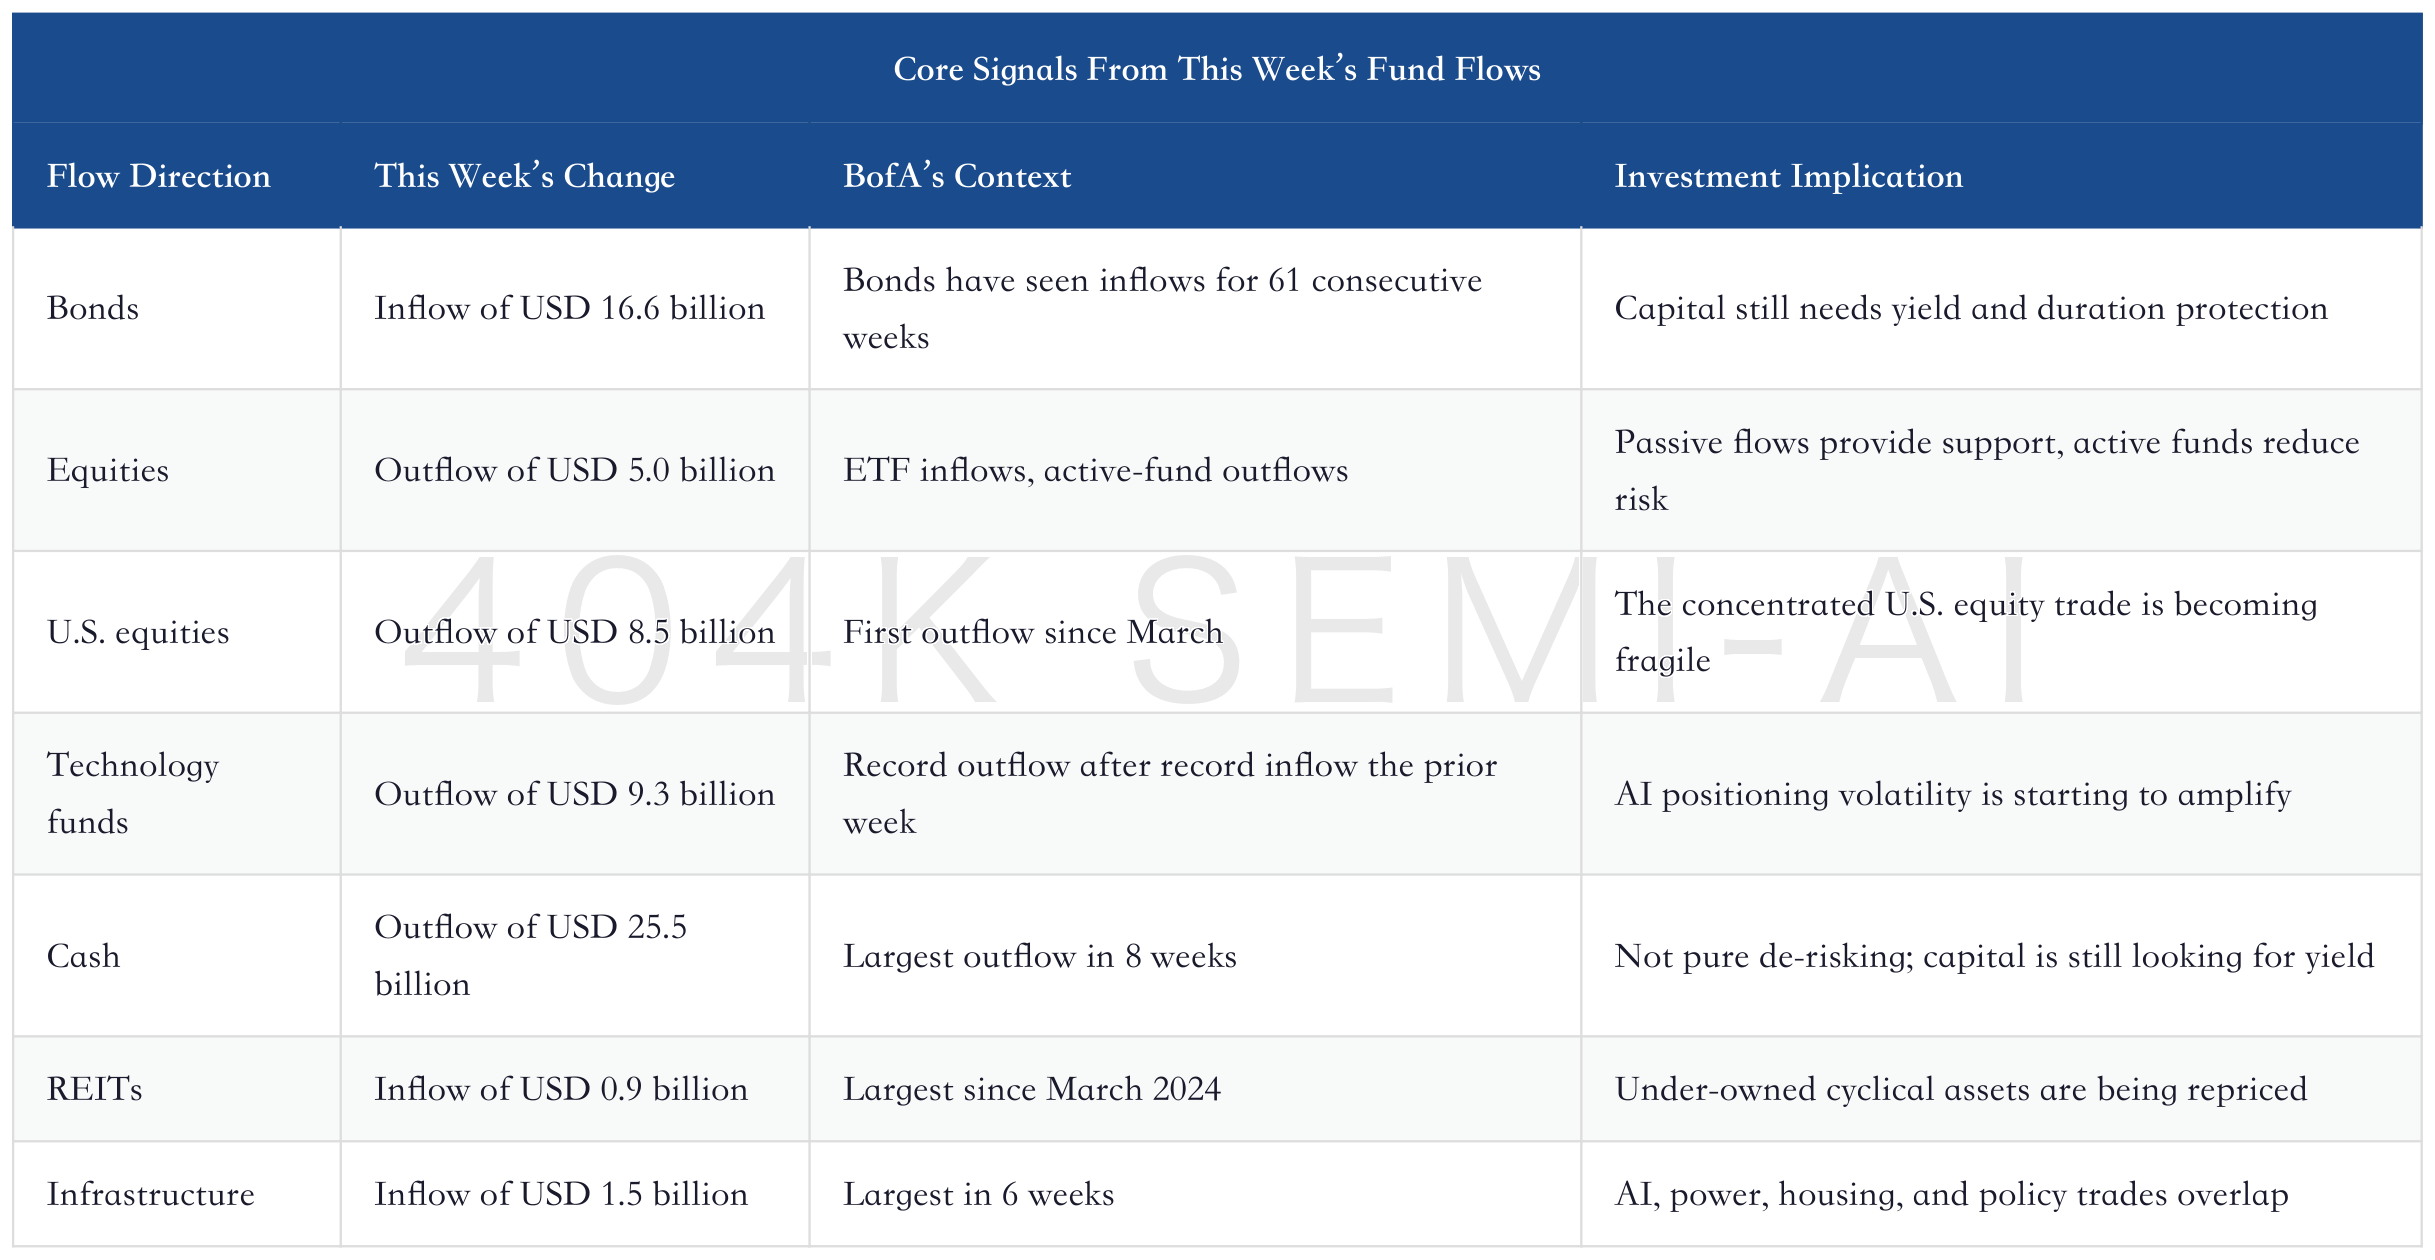
This explains why this week’s fund flows look somewhat contradictory. U.S. equity and technology funds started to see outflows, but REITs, infrastructure, materials, TIPS, parts of fixed income, and cyclical assets still had buyers. The market is not retreating from risk assets into cash. It is moving out of crowded assets into cheaper assets. Risk appetite remains; the receiving assets have changed.
BofA uses a very intuitive set of numbers: this week, bonds saw inflows of USD 16.6 billion, equities saw outflows of USD 5.0 billion, and cash saw outflows of USD 25.5 billion. U.S. equities saw outflows of USD 8.5 billion, the first since March 2026. Technology funds saw record outflows of USD 9.3 billion, immediately after record inflows of USD 19.2 billion the prior week. This contrast matters. It is not hard proof that the trend has reversed, but it shows AI and technology positioning has become so sensitive that one week of flows can change the market narrative.
2. Why “Small Is Big” Is More Than a Slogan
Small caps, mid caps, REITs, housing, materials, and infrastructure have been pushed into the corner by mega-cap technology stocks for the past several years. Their problem was not a lack of story, but that their stories were less concentrated, earnings were less stable, and capital capacity was not large enough. When AI leaders kept revising capex, cloud revenue, and chip demand higher, the market naturally preferred a small number of companies with high visibility.
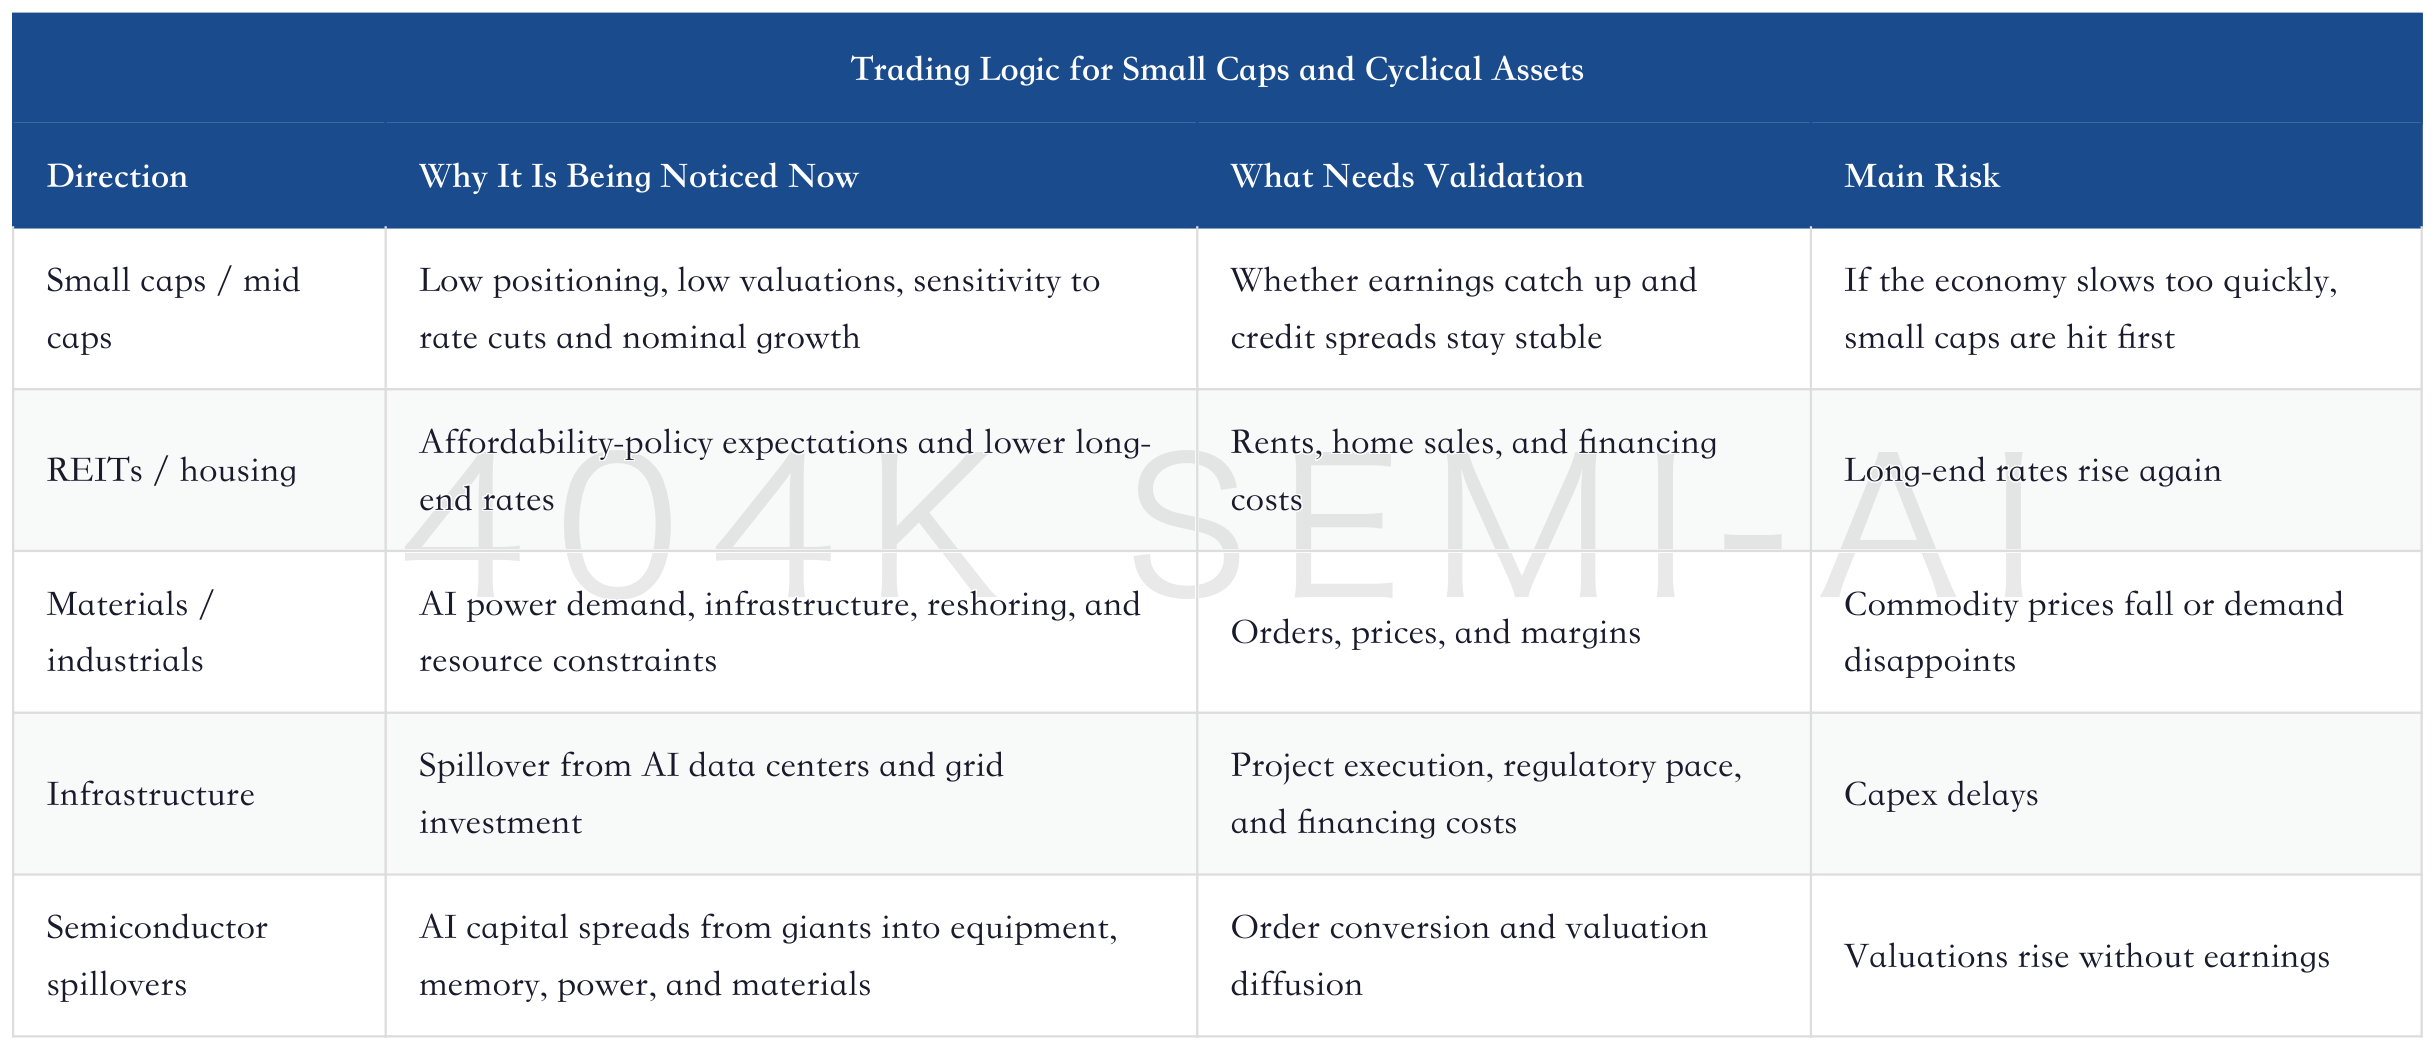
Now the marginal change has arrived. BofA believes liquidity flowing out of mega-cap AI arms racers is moving into semiconductors and less liquid cyclical assets such as small caps, mid caps, housing, and REITs. The key phrase is “less liquid.” Capital is not buying these assets because they have suddenly become perfect. It is buying them because positioning is low, valuations are low, and they are more sensitive to nominal growth and policy shifts.
Follow the Power: AI Data Centers Move From GPU Shortages to Grid, 800V, and Power Semiconductor Revaluation
There are three layers behind this rotation. The first is valuation. Mega-cap technology companies still have high earnings quality, but valuations and crowding have compressed the margin for error. The second is policy. The U.S. market is trading affordability, housing, infrastructure, and reindustrialization; REITs, building materials, materials, and small-cap cyclicals may all benefit. The third is nominal growth. As long as nominal GDP and corporate earnings do not fall rapidly, cyclical assets still have room to catch up.
BofA private-client data also supports this point. Its private-client assets are about USD 4.6 trillion, with current allocations of 65.8% to equities, 17.3% to bonds, and 9.6% to cash. Equity positioning is not low, but over the past four weeks private clients bought materials, munis, and TIPS through ETFs while selling Japan, consumer staples, and financials. In other words, private capital is not simply adding to the index. It is reselecting assets.
3. BofA Has Not Abandoned AI, but It Is Asking for Stronger Proof
This report is easily misread as “AI has peaked.” That is not the case. BofA’s real question is: after the market has fully priced AI capex and high margins, does the next step bring further diffusion, or does the market start trading capex cuts?
The report notes that S&P; 500 operating margins of about 16% still support an equity preference. This sentence is important. As long as margins do not collapse, it is difficult for U.S. equities to turn into a systemic bear market based on fund outflows alone. What is happening now is the cooling of a crowded trade, not a confirmed earnings-cycle recession.
Deep Dive on U.S. Semiconductors: AI Extends Visibility to 2028. After BofA Raises Estimates, Who Can Still Be Revalued?
But investors’ patience will shorten. In the past, the market was willing to pay for “the more AI capex, the better,” because capex meant demand for GPUs, networking, memory, optical modules, PCBs, power equipment, and data centers. Now the market will ask an additional question: when will these investments turn into revenue, when will they turn into free cash flow, and when will they stop pressuring the margins of cloud vendors and platform companies?
This is why the record outflow from technology funds this week deserves attention. A single week of outflows cannot prove a trend reversal, but it shows marginal buyers of AI exposure are starting to hesitate. Record inflows one week followed by record outflows the next show capital is not making a long-term retreat; it is trying to reduce exposure to the most crowded parts amid high volatility.
Deep Dive on AI’s Labor Shock: Why the Market Still Buys Only Compute Despite 15 Million Jobs at Risk of Replacement
A better interpretation is that the AI trade has entered its second phase. The first phase bought certainty: GPUs, cloud capex, AI servers, HBM, and optical modules. The second phase buys diffusion and earnings validation: semiconductor equipment, memory, power, electricity, materials, small-cap cyclicals, and Korean and Taiwanese supply chains. The second phase does not invalidate the first phase, but it weakens the valuation monopoly of a few giants.
4. Three Risk Lines: MAGS, AUD/JPY, and the Yield Curve
BofA’s risk trigger lines are specific: MAGS below 60, AUD/JPY below 110, and a yield-curve inversion could all become catalysts for a genuine summer risk-off move. The point is not that any single level is magical. It is that each represents a different market state.
MAGS is the thermometer for mega-cap technology risk appetite. If the Magnificent Seven ETF breaks below a key level, it means the market is not merely rotating but starting to exit the most crowded AI-weighted assets. AUD/JPY is the thermometer for global risk appetite and carry trades. A break below 110 often means growth expectations and risk assets are under pressure. A yield-curve inversion reflects the bond market repricing economic slowdown or policy error.
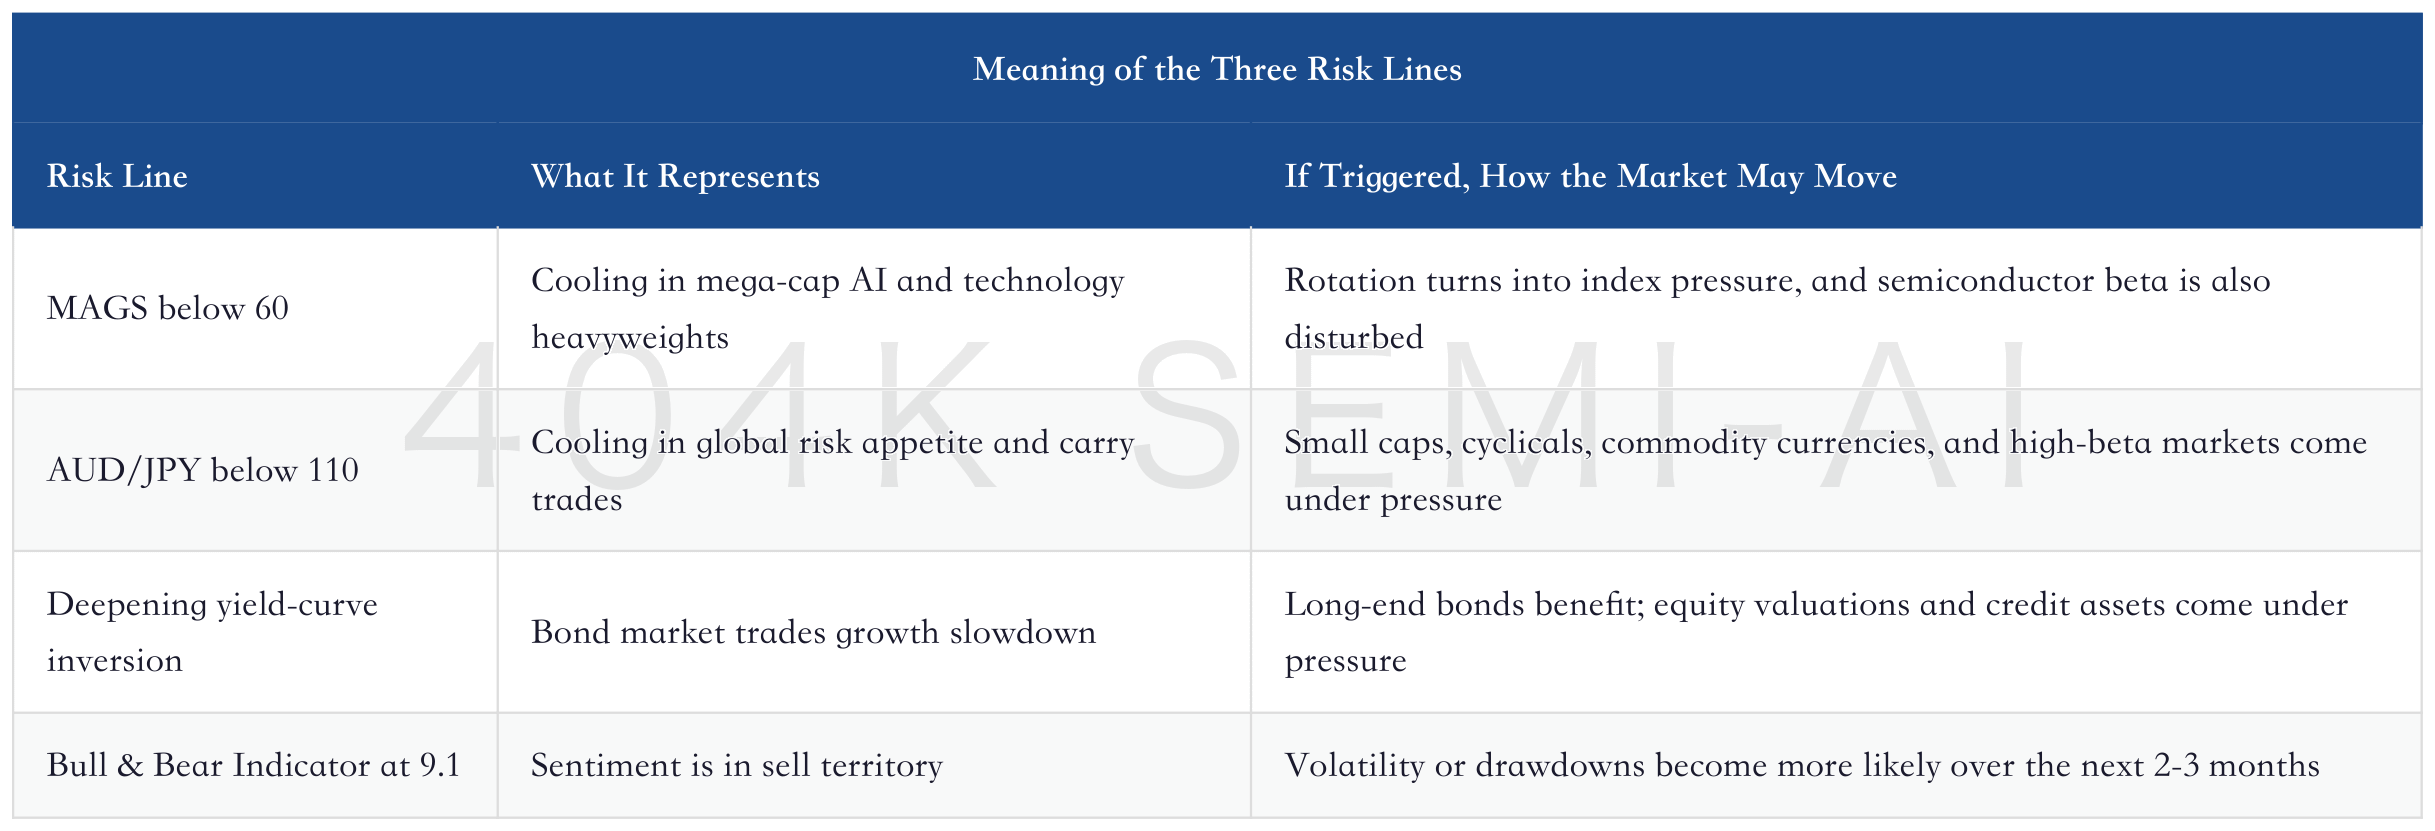
The Bull & Bear Indicator fell from 9.2 to 9.1, which looks like only a small decline, but it remains in high sell territory. BofA’s statistics show 17 similar sell signals since 2002, after which global equities lost an average of 2%-3% over the next 2-3 months, with a hit rate of about 60% and maximum drawdowns of 15%-20%. This is not a prediction that the market must crash. It says that when sentiment is overheated, credit technicals weaken, and flows become choppy, the odds of chasing strength deteriorate.
For investors, it is more important to distinguish two scenarios. The first is benign rotation: mega-cap technology consolidates, capital enters small caps, REITs, materials, emerging markets, and semiconductor spillover areas, and the index may not fall sharply. The second is genuine risk-off: MAGS, AUD/JPY, and the yield curve all deteriorate at the same time, capital rotates from equities into long bonds and cash, and small-cap cyclicals are also sold.
5. Why Long-End Treasuries Are the Most Contrarian Trade
In this report, BofA calls long-end Treasuries one of the most contrarian long-term trades. This looks inconsistent with “Small is Big,” but it is not. Small caps and cyclicals are trades in the diffusion of risk appetite. Long-end Treasuries are the hedge if crowded equity trades go wrong.
The report notes that since Warsh’s term began on May 22, U.S. Treasuries have risen 3.2%, equities have fallen 1.6%, and 10-year Treasury yields have fallen 17 basis points. BofA compares this period with several historical Fed chair tenures marked by falling yields. The core point is that if the next policy environment ultimately pushes long-end yields lower, long bonds will become one of the few assets not yet fully priced by crowding.
This is not a one-way positive for equities. A moderate decline in yields helps REITs, small caps, housing, and long-duration assets. But if yields fall because of growth concerns, credit, high-beta cyclicals, and small caps will instead come under pressure. Long bonds can therefore help the rotation trade, but they can also protect against risk drawdowns.
The logic for gold is similar. The report argues that gold below USD 4,000 is a good buying point, while emphasizing that the dollar is more something to “rent” than to “own.” In investment terms, this means the dollar may rebound in the short term because of easing Middle East tensions, changes in the sanctions cycle, and safe-haven inflows. But the 2020s remain an era of geopolitical fragmentation and populist political preference for growth over low inflation, so gold’s long-term allocation value has not disappeared.
The real conclusion here is portfolio structure. If one looks only at equities, it is easy to think BofA is calling for small caps to take over. If one looks only at long bonds and gold, it is easy to think BofA is calling for de-risking. The full reading is: within equities, rotate into diffusion; at the portfolio level, keep long-end bonds and gold as hedges. That is the only way to explain why BofA says “Small is Big” while also calling long-end Treasuries a contrarian long-term trade.
6. Emerging Markets Remain the Long-Term Theme, but Korea and Taiwan Are Already Hot
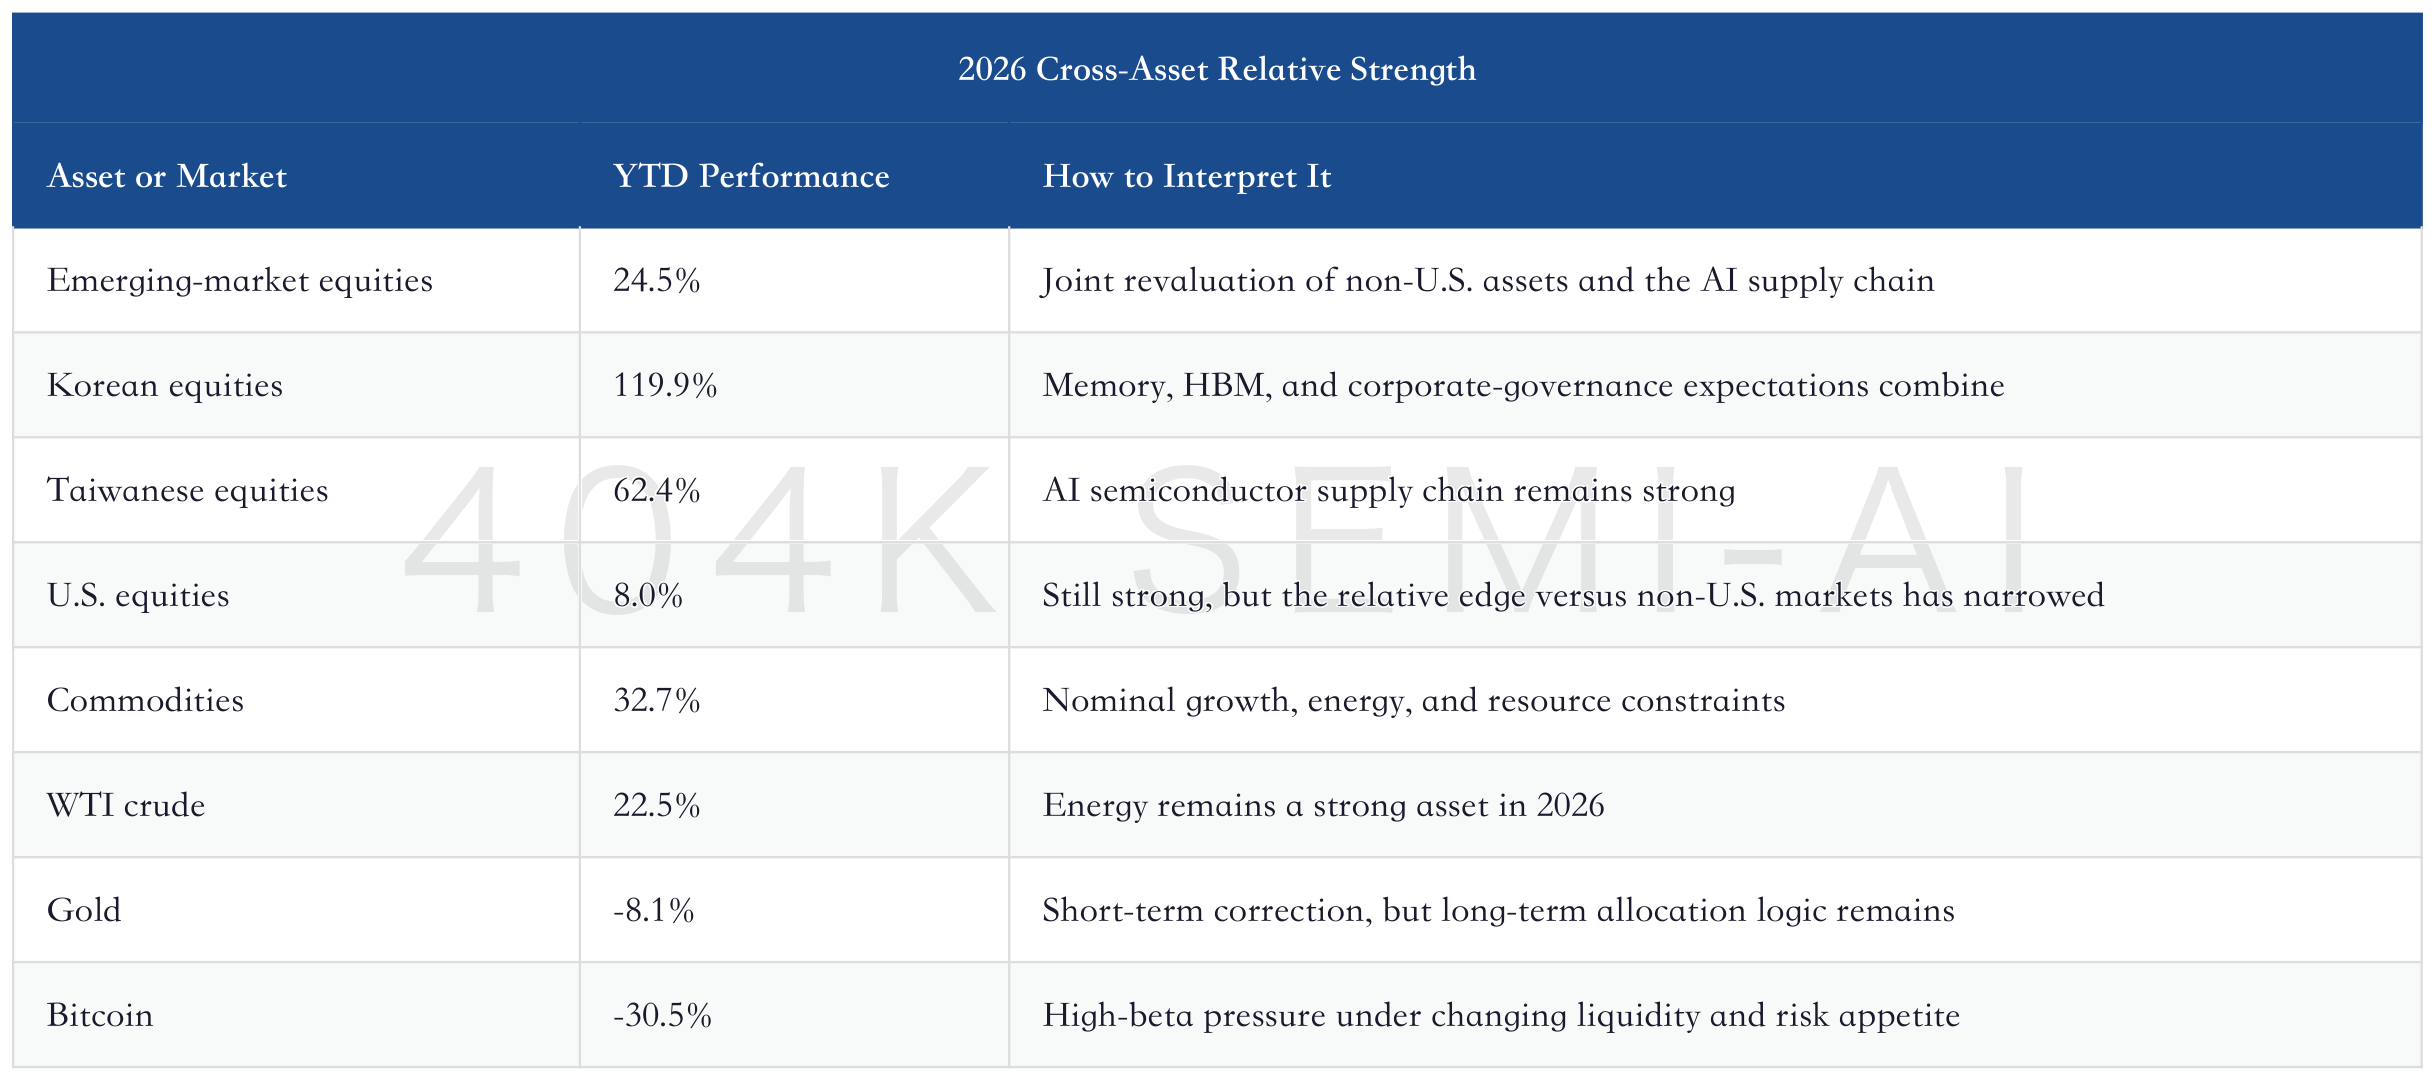
BofA continues to emphasize that the long-term trade is emerging markets outperforming U.S. equities. The annual performance table in the report is intuitive: the real winners this year are not simply U.S. technology stocks, but the AI supply chain and non-U.S. risk assets. Korea, Taiwan, emerging markets, and commodities are all already ahead of U.S. equities. The specific gains are shown in the table below; the text focuses on investment implications.
JPMorgan Sees the KOSPI at 15,000: Is Korea’s Rally an AI Bubble or a National Wealth Revaluation?
The strength in Korea and Taiwan is not mysterious. HBM, memory, wafer manufacturing, advanced packaging, AI servers, and electronic components are all driving upward revisions to earnings expectations, and foreign investors are willing to re-rate these markets. But the stronger they are, the less one can rely only on the long-term narrative. BofA’s table of deviations from the 200-day moving average shows Korean equities 68.4% above their 200-day average, Taiwan 39.7% above, and emerging markets as a whole 16.1% above. This is not a reason to sell immediately, but it is a signal that position management must be taken seriously.
Deep Dive on Korea’s AI Surplus: How the Memory Supercycle Revalues Fiscal Policy, Rates, and the Won
The best state for the emerging-market theme is continued earnings upgrades, no one-way dollar strength, a moderate decline in U.S. long-end rates, and continued conversion of AI supply-chain orders. The worst state is a rapid dollar rebound, AUD/JPY breaking below the key level, Korea and Taiwan correcting from overheated conditions, and U.S. technology heavyweights falling at the same time. The former is diffusion; the latter is de-risking.
7. The Trading Framework From This Report
The most useful part of this Flow Show is that it pulls the market out of the single question of “does AI rise or fall?” The real questions are threefold: whether the crowded trade in AI leaders is cooling; whether small caps, cyclicals, REITs, and emerging markets can absorb liquidity; and whether long-end Treasuries and gold can provide portfolio hedges.
First, AI remains the main theme, but investors can no longer simply buy megacap concentration. If capital flows out of mega-cap AI arms racers, it does not necessarily mean AI demand is weakening. It more likely means the market is starting to question returns on capex. Semiconductor spillovers, memory, power, materials, and small-cap cyclicals may instead absorb some of that capital.
Second, the rise in small caps and cyclicals needs earnings support. If it is only valuation repair, the rally will be fast. If orders, margins, stable credit spreads, and lower long-end rates can be seen, the move can shift from a catch-up trade into a trend.
Third, emerging markets can stay strong, but overheating cannot be ignored. Korea and Taiwan have already moved significantly above long-term moving averages. From here, earnings reports, foreign flows, exchange rates, and semiconductor orders are better validation tools than index momentum alone.
Fourth, long-end Treasuries are not opposed to equity diffusion; they are the insurance for this trade. If rotation works, a moderate decline in long-end rates will help small caps, REITs, and housing. If rotation fails, long bonds will hedge crowded equity drawdowns better than cash.
Finally, the four indicators most worth tracking are: whether technology funds continue to see outflows; whether REITs, small caps, and materials continue to receive capital; whether MAGS and AUD/JPY hold key levels; and whether the Bull & Bear Indicator continues to fall from extreme territory. As long as these indicators do not deteriorate together, this report looks more like an internal market rotation. If they all weaken at the same time, it should be read as a genuine summer risk-off warning.
Frozen Bulls: AI Crowding, Inflation Tail Risk, and Asia Rotation in the June Global and Asia Fund Manager Surveys
The conclusion is straightforward: BofA is not telling the market to abandon AI. It is warning that AI pricing power is beginning to diffuse from “a few giants” to “who can absorb capital, orders, and profits.” If technology outflows expand after July, MAGS breaks below the key line, and AUD/JPY weakens, this report will become a risk warning. If technology consolidates while small caps, cyclicals, REITs, and emerging markets continue to absorb capital, this report looks more like a roadmap for market rotation in the second half of 2026.BofA Flow Show Deep Dive: Are Funds Rotating Out of AI Megacaps and Into Small-Cap Cyclicals and Emerging Markets?
目录
TL;DR
1. What This Flow Show Is Really Trying to Answer
2. Why “Small Is Big” Is More Than a Slogan
3. BofA Has Not Abandoned AI, but It Is Asking for Stronger Proof
4. Three Risk Lines: MAGS, AUD/JPY, and the Yield Curve
5. Why Long-End Treasuries Are the Most Contrarian Trade
6. Emerging Markets Remain the Long-Term Theme, but Korea and Taiwan Are Already Hot
7. The Trading Framework From This Report
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core message of this BofA Flow Show is not to turn bearish on AI, but to warn that the market is rotating from giant AI stocks toward small caps, cyclicals, REITs, and emerging markets. Risk appetite has not disappeared; it is looking for the next assets to absorb capital. Fund flows, crowded valuations, and long-end rates are rewriting the trading sequence. The real task is to distinguish rotation, catch-up rallies, and a shift into risk-off hedges.
TL;DR
Capital is looking for new receiving assets. U.S. equity and technology funds have turned to outflows, but bonds, REITs, infrastructure, and some cyclical assets are taking in capital. This shows risk appetite has not disappeared; it is spreading out from the concentrated mega-cap AI trade.
BofA is not rejecting the AI theme. The real question in the report is how far cloud vendors and AI arms racers need to fall before the market starts trading capex cuts. The key issue is crowding, not a collapse in demand.
Small can become big for real reasons. Small caps, mid caps, housing, REITs, materials, and infrastructure benefit from low positioning, valuation repair, and affordability-policy expectations. In the short term this looks like a catch-up trade; in substance, capital is looking for a new pool.
Long-end Treasuries are insurance. Since the start of the new Fed chair’s term, Treasuries have risen and equities have pulled back. If long-end yields keep falling, that can support REITs and small caps while also compressing crowded equity valuations.
Emerging markets remain strong. Year to date, emerging markets, Korea, and Taiwan have significantly outperformed the U.S. BofA still favors EM versus U.S. equities, but the high deviation in Korea and Taiwan means chasing strength needs earnings validation.
Three lines define the risk. MAGS below 60, AUD/JPY below 110, and a renewed inversion of the yield curve are summer risk-off triggers. If they happen together, rotation becomes de-risking.
This is not a bearish report. The more accurate reading is that the AI trade has entered its second phase. The market is no longer paying only for megacap concentration; it is also starting to price small-cap cyclicals, semiconductor spillovers, and emerging markets.
1. What This Flow Show Is Really Trying to Answer
The title of this BofA report is “Small is Big.” The literal meaning is simple: small is becoming bigger. In the current market, it does not mean small caps have suddenly become more important than AI. It means that after mega-cap AI stocks, hyperscale cloud vendors, and the semiconductor theme have absorbed too much capital, the next question is where the next wave of money goes.
The report opens with a sharp question: how much further must hyperscale cloud vendors fall before the market starts trading capex cuts? This question is more valuable than a generic bearish call. It does not say AI capex is about to collapse. It says investors have begun to separate two things: AI demand is still there, but the phase of paying an unconditional premium for AI capex may be approaching its end.
The AI Trade Has Moved Ahead of Macro: Recalibrating Compute Capex, Earnings Expectations, and Market Pricing
This explains why this week’s fund flows look somewhat contradictory. U.S. equity and technology funds started to see outflows, but REITs, infrastructure, materials, TIPS, parts of fixed income, and cyclical assets still had buyers. The market is not retreating from risk assets into cash. It is moving out of crowded assets into cheaper assets. Risk appetite remains; the receiving assets have changed.
BofA uses a very intuitive set of numbers: this week, bonds saw inflows of USD 16.6 billion, equities saw outflows of USD 5.0 billion, and cash saw outflows of USD 25.5 billion. U.S. equities saw outflows of USD 8.5 billion, the first since March 2026. Technology funds saw record outflows of USD 9.3 billion, immediately after record inflows of USD 19.2 billion the prior week. This contrast matters. It is not hard proof that the trend has reversed, but it shows AI and technology positioning has become so sensitive that one week of flows can change the market narrative.
2. Why “Small Is Big” Is More Than a Slogan
Small caps, mid caps, REITs, housing, materials, and infrastructure have been pushed into the corner by mega-cap technology stocks for the past several years. Their problem was not a lack of story, but that their stories were less concentrated, earnings were less stable, and capital capacity was not large enough. When AI leaders kept revising capex, cloud revenue, and chip demand higher, the market naturally preferred a small number of companies with high visibility.
Now the marginal change has arrived. BofA believes liquidity flowing out of mega-cap AI arms racers is moving into semiconductors and less liquid cyclical assets such as small caps, mid caps, housing, and REITs. The key phrase is “less liquid.” Capital is not buying these assets because they have suddenly become perfect. It is buying them because positioning is low, valuations are low, and they are more sensitive to nominal growth and policy shifts.
Follow the Power: AI Data Centers Move From GPU Shortages to Grid, 800V, and Power Semiconductor Revaluation
There are three layers behind this rotation. The first is valuation. Mega-cap technology companies still have high earnings quality, but valuations and crowding have compressed the margin for error. The second is policy. The U.S. market is trading affordability, housing, infrastructure, and reindustrialization; REITs, building materials, materials, and small-cap cyclicals may all benefit. The third is nominal growth. As long as nominal GDP and corporate earnings do not fall rapidly, cyclical assets still have room to catch up.
BofA private-client data also supports this point. Its private-client assets are about USD 4.6 trillion, with current allocations of 65.8% to equities, 17.3% to bonds, and 9.6% to cash. Equity positioning is not low, but over the past four weeks private clients bought materials, munis, and TIPS through ETFs while selling Japan, consumer staples, and financials. In other words, private capital is not simply adding to the index. It is reselecting assets.
3. BofA Has Not Abandoned AI, but It Is Asking for Stronger Proof
This report is easily misread as “AI has peaked.” That is not the case. BofA’s real question is: after the market has fully priced AI capex and high margins, does the next step bring further diffusion, or does the market start trading capex cuts?
The report notes that S&P; 500 operating margins of about 16% still support an equity preference. This sentence is important. As long as margins do not collapse, it is difficult for U.S. equities to turn into a systemic bear market based on fund outflows alone. What is happening now is the cooling of a crowded trade, not a confirmed earnings-cycle recession.
Deep Dive on U.S. Semiconductors: AI Extends Visibility to 2028. After BofA Raises Estimates, Who Can Still Be Revalued?
But investors’ patience will shorten. In the past, the market was willing to pay for “the more AI capex, the better,” because capex meant demand for GPUs, networking, memory, optical modules, PCBs, power equipment, and data centers. Now the market will ask an additional question: when will these investments turn into revenue, when will they turn into free cash flow, and when will they stop pressuring the margins of cloud vendors and platform companies?
This is why the record outflow from technology funds this week deserves attention. A single week of outflows cannot prove a trend reversal, but it shows marginal buyers of AI exposure are starting to hesitate. Record inflows one week followed by record outflows the next show capital is not making a long-term retreat; it is trying to reduce exposure to the most crowded parts amid high volatility.
Deep Dive on AI’s Labor Shock: Why the Market Still Buys Only Compute Despite 15 Million Jobs at Risk of Replacement
A better interpretation is that the AI trade has entered its second phase. The first phase bought certainty: GPUs, cloud capex, AI servers, HBM, and optical modules. The second phase buys diffusion and earnings validation: semiconductor equipment, memory, power, electricity, materials, small-cap cyclicals, and Korean and Taiwanese supply chains. The second phase does not invalidate the first phase, but it weakens the valuation monopoly of a few giants.
4. Three Risk Lines: MAGS, AUD/JPY, and the Yield Curve
BofA’s risk trigger lines are specific: MAGS below 60, AUD/JPY below 110, and a yield-curve inversion could all become catalysts for a genuine summer risk-off move. The point is not that any single level is magical. It is that each represents a different market state.
MAGS is the thermometer for mega-cap technology risk appetite. If the Magnificent Seven ETF breaks below a key level, it means the market is not merely rotating but starting to exit the most crowded AI-weighted assets. AUD/JPY is the thermometer for global risk appetite and carry trades. A break below 110 often means growth expectations and risk assets are under pressure. A yield-curve inversion reflects the bond market repricing economic slowdown or policy error.
The Bull & Bear Indicator fell from 9.2 to 9.1, which looks like only a small decline, but it remains in high sell territory. BofA’s statistics show 17 similar sell signals since 2002, after which global equities lost an average of 2%-3% over the next 2-3 months, with a hit rate of about 60% and maximum drawdowns of 15%-20%. This is not a prediction that the market must crash. It says that when sentiment is overheated, credit technicals weaken, and flows become choppy, the odds of chasing strength deteriorate.
For investors, it is more important to distinguish two scenarios. The first is benign rotation: mega-cap technology consolidates, capital enters small caps, REITs, materials, emerging markets, and semiconductor spillover areas, and the index may not fall sharply. The second is genuine risk-off: MAGS, AUD/JPY, and the yield curve all deteriorate at the same time, capital rotates from equities into long bonds and cash, and small-cap cyclicals are also sold.
5. Why Long-End Treasuries Are the Most Contrarian Trade
In this report, BofA calls long-end Treasuries one of the most contrarian long-term trades. This looks inconsistent with “Small is Big,” but it is not. Small caps and cyclicals are trades in the diffusion of risk appetite. Long-end Treasuries are the hedge if crowded equity trades go wrong.
The report notes that since Warsh’s term began on May 22, U.S. Treasuries have risen 3.2%, equities have fallen 1.6%, and 10-year Treasury yields have fallen 17 basis points. BofA compares this period with several historical Fed chair tenures marked by falling yields. The core point is that if the next policy environment ultimately pushes long-end yields lower, long bonds will become one of the few assets not yet fully priced by crowding.
This is not a one-way positive for equities. A moderate decline in yields helps REITs, small caps, housing, and long-duration assets. But if yields fall because of growth concerns, credit, high-beta cyclicals, and small caps will instead come under pressure. Long bonds can therefore help the rotation trade, but they can also protect against risk drawdowns.
The logic for gold is similar. The report argues that gold below USD 4,000 is a good buying point, while emphasizing that the dollar is more something to “rent” than to “own.” In investment terms, this means the dollar may rebound in the short term because of easing Middle East tensions, changes in the sanctions cycle, and safe-haven inflows. But the 2020s remain an era of geopolitical fragmentation and populist political preference for growth over low inflation, so gold’s long-term allocation value has not disappeared.
The real conclusion here is portfolio structure. If one looks only at equities, it is easy to think BofA is calling for small caps to take over. If one looks only at long bonds and gold, it is easy to think BofA is calling for de-risking. The full reading is: within equities, rotate into diffusion; at the portfolio level, keep long-end bonds and gold as hedges. That is the only way to explain why BofA says “Small is Big” while also calling long-end Treasuries a contrarian long-term trade.
6. Emerging Markets Remain the Long-Term Theme, but Korea and Taiwan Are Already Hot
BofA continues to emphasize that the long-term trade is emerging markets outperforming U.S. equities. The annual performance table in the report is intuitive: the real winners this year are not simply U.S. technology stocks, but the AI supply chain and non-U.S. risk assets. Korea, Taiwan, emerging markets, and commodities are all already ahead of U.S. equities. The specific gains are shown in the table below; the text focuses on investment implications.
JPMorgan Sees the KOSPI at 15,000: Is Korea’s Rally an AI Bubble or a National Wealth Revaluation?
The strength in Korea and Taiwan is not mysterious. HBM, memory, wafer manufacturing, advanced packaging, AI servers, and electronic components are all driving upward revisions to earnings expectations, and foreign investors are willing to re-rate these markets. But the stronger they are, the less one can rely only on the long-term narrative. BofA’s table of deviations from the 200-day moving average shows Korean equities 68.4% above their 200-day average, Taiwan 39.7% above, and emerging markets as a whole 16.1% above. This is not a reason to sell immediately, but it is a signal that position management must be taken seriously.
Deep Dive on Korea’s AI Surplus: How the Memory Supercycle Revalues Fiscal Policy, Rates, and the Won
The best state for the emerging-market theme is continued earnings upgrades, no one-way dollar strength, a moderate decline in U.S. long-end rates, and continued conversion of AI supply-chain orders. The worst state is a rapid dollar rebound, AUD/JPY breaking below the key level, Korea and Taiwan correcting from overheated conditions, and U.S. technology heavyweights falling at the same time. The former is diffusion; the latter is de-risking.
7. The Trading Framework From This Report
The most useful part of this Flow Show is that it pulls the market out of the single question of “does AI rise or fall?” The real questions are threefold: whether the crowded trade in AI leaders is cooling; whether small caps, cyclicals, REITs, and emerging markets can absorb liquidity; and whether long-end Treasuries and gold can provide portfolio hedges.
First, AI remains the main theme, but investors can no longer simply buy megacap concentration. If capital flows out of mega-cap AI arms racers, it does not necessarily mean AI demand is weakening. It more likely means the market is starting to question returns on capex. Semiconductor spillovers, memory, power, materials, and small-cap cyclicals may instead absorb some of that capital.
Second, the rise in small caps and cyclicals needs earnings support. If it is only valuation repair, the rally will be fast. If orders, margins, stable credit spreads, and lower long-end rates can be seen, the move can shift from a catch-up trade into a trend.
Third, emerging markets can stay strong, but overheating cannot be ignored. Korea and Taiwan have already moved significantly above long-term moving averages. From here, earnings reports, foreign flows, exchange rates, and semiconductor orders are better validation tools than index momentum alone.
Fourth, long-end Treasuries are not opposed to equity diffusion; they are the insurance for this trade. If rotation works, a moderate decline in long-end rates will help small caps, REITs, and housing. If rotation fails, long bonds will hedge crowded equity drawdowns better than cash.
Finally, the four indicators most worth tracking are: whether technology funds continue to see outflows; whether REITs, small caps, and materials continue to receive capital; whether MAGS and AUD/JPY hold key levels; and whether the Bull & Bear Indicator continues to fall from extreme territory. As long as these indicators do not deteriorate together, this report looks more like an internal market rotation. If they all weaken at the same time, it should be read as a genuine summer risk-off warning.
Frozen Bulls: AI Crowding, Inflation Tail Risk, and Asia Rotation in the June Global and Asia Fund Manager Surveys
The conclusion is straightforward: BofA is not telling the market to abandon AI. It is warning that AI pricing power is beginning to diffuse from “a few giants” to “who can absorb capital, orders, and profits.” If technology outflows expand after July, MAGS breaks below the key line, and AUD/JPY weakens, this report will become a risk warning. If technology consolidates while small caps, cyclicals, REITs, and emerging markets continue to absorb capital, this report looks more like a roadmap for market rotation in the second half of 2026.