
目录
Executive Summary
I. July to August: Rising Optimism—and Greater Risk Awareness
II. AI Capital Expenditure: The Most Certain Source of Growth—and the Most Closely Watched Source of Credit Risk
III. The Real Foundation of “No Landing” Is Strong Nominal Growth
IV. The Portfolio’s True Shape: Heavy Equity Exposure, but Higher Quality Standards
V. Asset Allocation: The High Nominal Growth Trade Remains Concentrated
VI. Regional Divergence: Absolute Positioning and Historical Extremes Are Not the Same
VII. Sector Rotation: Energy and Consumer Are Rebounds; Technology and Banks Carry the Heavy Positions
VIII. Why Low Cash Amplifies Expectation Gaps Rather Than Automatically Causing a Sell-Off
IX. The Strongest Counterargument: Institutions May Simply Be Following Earnings Rationally
X. Six Sets of Indicators to Monitor Over the Next 1–3 Months
The August survey shows risk-asset positions are heavily loaded even as portfolios turn more defensive internally. The real danger is that thin cash buffers collide with a reversal in earnings, yields, or credit expectations.
Executive Summary
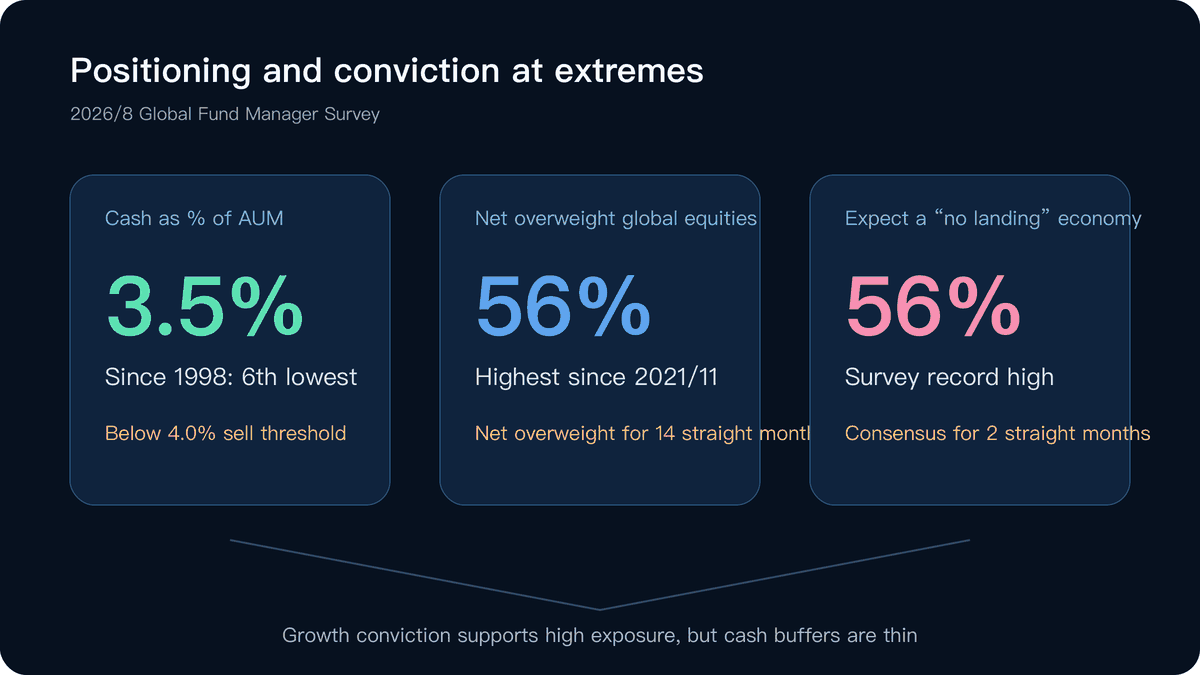
Global institutional risk exposure increased further. The net overweight in global equities rose from 42% in July to 56%, the highest since November 2021; cash as a share of assets under management fell from 3.6% to 3.5%, the 6th-lowest level since 1998. Both BofA’s Cash Rule and Bull & Bear Indicator have entered contrarian overbought territory.
High positioning is underpinned by fundamental conviction. A record 56% expect “no landing” for the economy over the next 12 months, a net 37% expect global corporate profits to grow by at least 10%, and 72% expect the Federal Reserve not to raise rates before the US midterm elections. Investors are betting that continued growth and earnings will absorb elevated valuations, not merely chasing market gains.
AI is both a growth engine and a credit risk. 71% expect no AI hyperscaler to cut capital expenditure in 2026, yet 38% believe such spending is the most likely source of a systemic credit event. The debate is not whether capacity will be built, but over the investment-payback period, cash flow, and financing structure.
Lower semiconductor crowding does not signal a wholesale retreat. Long global semiconductors remains the most crowded trade at 53%, although that is down 29 percentage points from 82% in July; meanwhile, the net technology overweight rose from 18% to 30%. The more plausible interpretation is that investors retained the trade after some crowding was unwound—not that institutions have exited technology.
Offense at the asset-class level, defense within equities. A net 71% favor high-quality over low-quality earnings, a net 36% prefer large caps, a net 17% favor value, and a net 16% prefer high-dividend stocks. On corporate cash deployment, 38% want companies to improve their balance sheets, while only 22% want higher capital expenditure.
Sector rotation includes substantial short covering. Energy improved by 17 percentage points from July, consumer staples by 13 percentage points, and consumer discretionary by 10 percentage points, but remained net underweight by 3%, 19%, and 12%, respectively, in August. Treating month-on-month increases as evidence that institutions have already turned bullish would overstate the signal.
The US is the most crowded; the UK is the coldest. US equities are net overweight by 27%, 1.5 standard deviations above their long-term average; UK equities are net underweight by 33%, 1.5 standard deviations below their long-term average. Emerging markets have a higher absolute net overweight than the US at 34%, but stand only 0.7 standard deviations above their own historical average.
Low cash is not a precise market-top signal. Heavy positioning can persist as long as corporate earnings deliver, bond yields remain orderly, and credit spreads stay stable. The real danger emerges when one of these 3 conditions reverses, causing redemptions, risk-limit triggers, and contracting risk budgets to turn deliberate bullish exposure into forced deleveraging.
I. July to August: Rising Optimism—and Greater Risk Awareness
The most important new development in August is that institutions increased risk-asset allocations while becoming more alert to corporate financing and balance-sheet risk. The net overweight in global equities rose from 42% to 56%, commodities from 11% to 24%, and US equities from 24% to 27%. Together, these are clear signals of stronger risk appetite.
At the same time, a net 19% viewed corporate balance sheets as overleveraged, up 12 percentage points from 7% in July. The share wanting companies to prioritize balance-sheet improvement reached 38%, above the 33% favoring shareholder distributions and the 22% favoring higher capital expenditure. Investors remain willing to hold risk assets, but increasingly demand more resilient funding and stronger cash returns from companies.
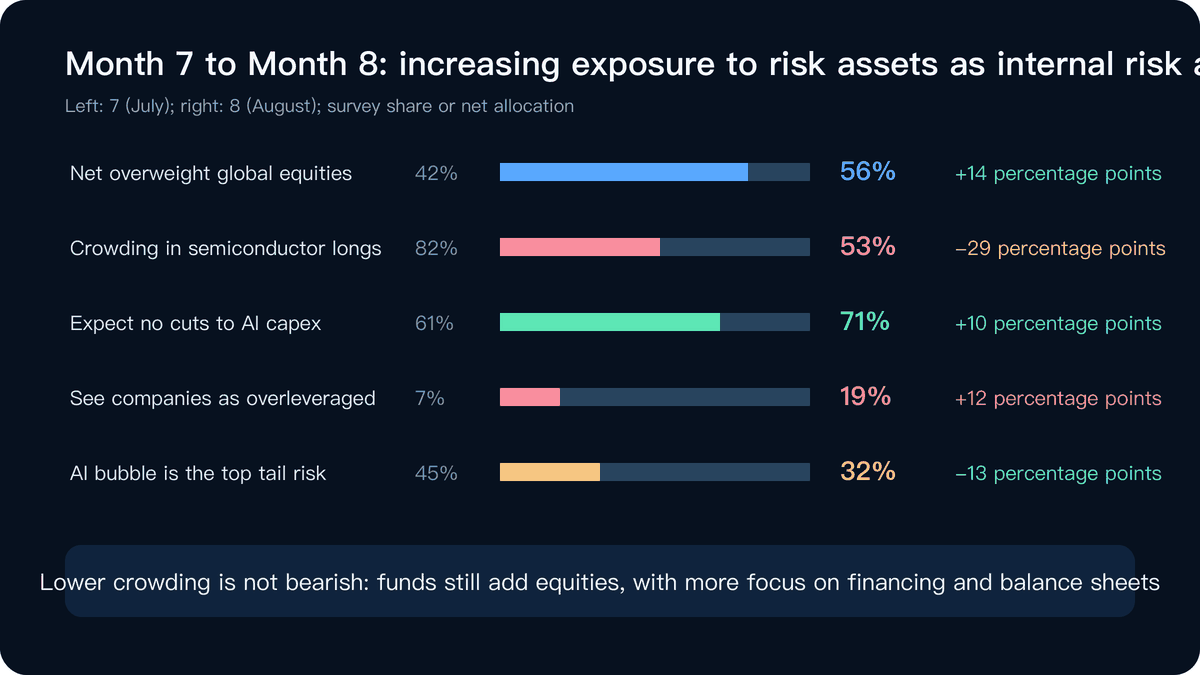
The decline in semiconductor crowding from 82% to 53%, alongside a drop in AI-bubble tail-risk concerns from 45% to 32%, could easily be read as evidence that technology risk has dissipated. That conclusion is premature. At 53%, long global semiconductors still exceeds the second-ranked trade, short the yen at 12%, by 41 percentage points and remains overwhelmingly crowded. Meanwhile, the net technology overweight actually rose from 18% to 30%. The shift looks more like an extreme consensus being partially unwound, with capital moving from indiscriminate buying toward preserving the structural theme while upgrading quality.
Cash fell further from 3.6% to 3.5%, indicating that the rotation occurred mainly within risk assets rather than through a substantial increase in cash. The portfolio’s directional stance has not reversed, but its buffer has become thinner.
II. AI Capital Expenditure: The Most Certain Source of Growth—and the Most Closely Watched Source of Credit Risk
71% of respondents expect no AI hyperscaler to announce capital-expenditure cuts in 2026, up 10 percentage points from July; only 21% expect cuts. Institutions have therefore become more confident—not more skeptical—about the near-term continuity of AI infrastructure investment.
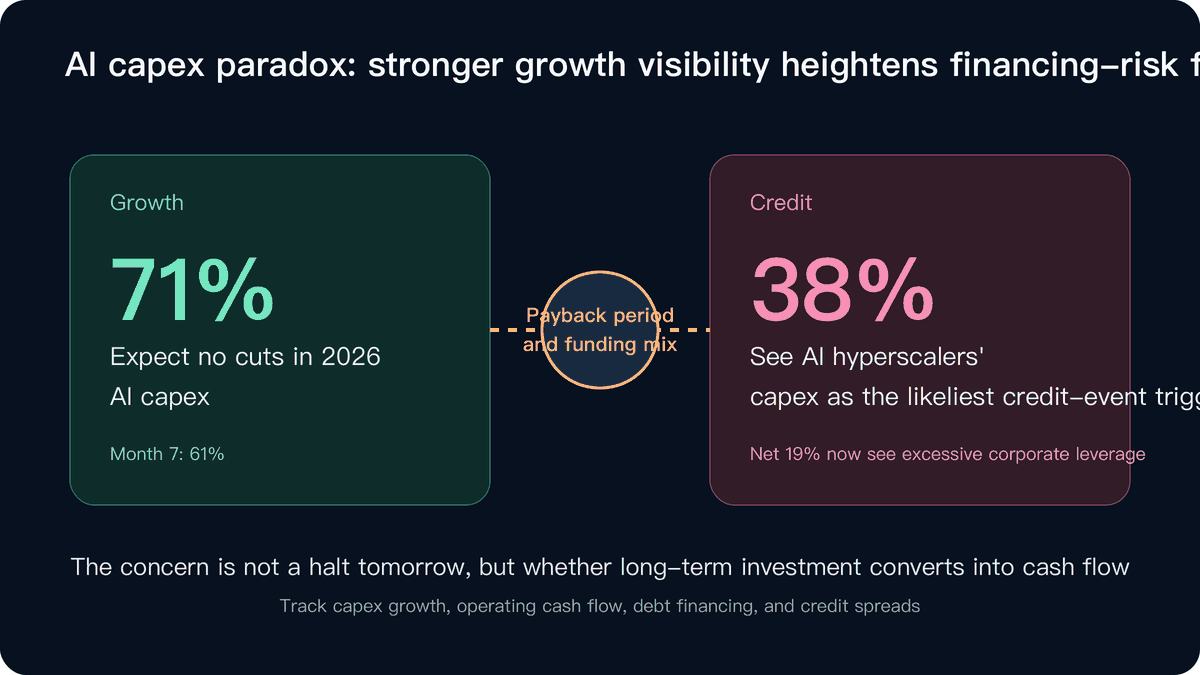
At the same time, 38% identify AI hyperscaler capital expenditure as the most likely source of a systemic credit event, well above private credit at 23% and government debt at 18%. These responses are not contradictory: capital expenditure can continue rising even as project payback periods lengthen, operating-cash-flow coverage weakens, and reliance on external financing increases. The risk has shifted from “will orders disappear?” to “who will fund the long-term investment, and when will the returns arrive?”
This also explains why preference for high-quality earnings rose to a net 71%. When funding costs are high and capital requirements are substantial, identical revenue growth can command very different valuations depending on cash-flow quality and balance-sheet strength. Companies able to fund investment through operating cash flow, sustain stable profits in their core businesses, and maintain well-structured debt maturities are better positioned to navigate peak capital expenditure. Companies dependent on continuous financing and distant returns may suffer valuation discounts even if their revenue continues to grow.
