
目录
Executive Summary
I. The Bottom Line: Technology Is Not Fading—Institutions Just No Longer Want to Run Unhedged
II. What the 59% Are Actually Doing: Moving from a Single AI Bet to Multiple Sources of Return
III. The AI Trade’s New Hurdle: Show Me Revenue, Not Just Budgets
IV. Why This Is Not a Wholesale Turn Bearish: Earnings, Undervaluation, and Return Expectations Still Support Asia
V. Semiconductors Remain Core, but the “Whole Sector Rises Together” Trade Is Breaking Down
VI. The AI Value Chain Broadens: Why Power, Networking, and Memory Are Drawing More Attention
VII. What Is Actually Happening to Sector Positioning: Defensive Exposure Is Recovering, but Technology Remains Near the Front
VIII. Regional Ranking: Taiwan and Japan Lead, While India Falls to Last Place
IX. Japan’s Dual Themes: Banks Benefit from Rates, Semiconductors from AI
10. The Strongest Alternative Interpretation: Healthy Broadening, Not a Prelude to Decline
Technology remains institutions’ highest-conviction theme, but a growing number of investors are no longer willing to rely solely on the AI narrative. The shift in August was to retain core positions while adding portfolio buffers.
Executive Summary
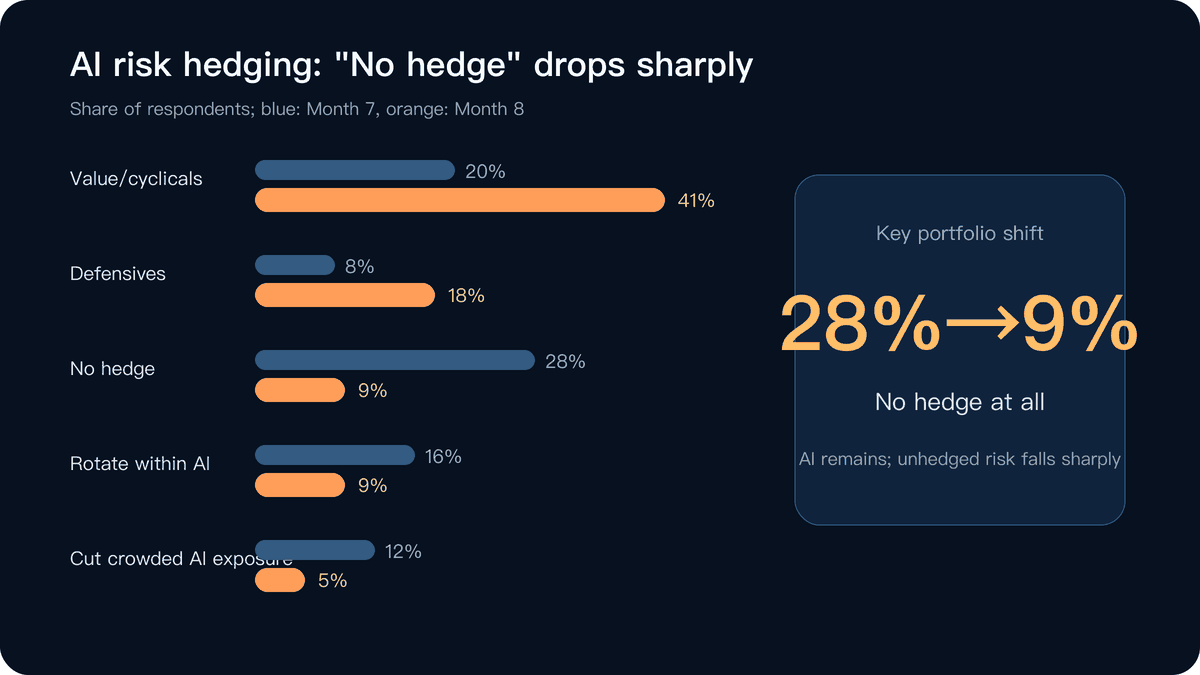
Technology remains No. 1, but portfolios have become markedly more cautious. 59% of respondents are using value, cyclical, or defensive sectors to cushion against an AI selloff—more than 2x the July level. The share rotating into value or cyclicals rose from 20% to 41%, while the share moving into defensives increased from 8% to 18%.
The clearest change is that the “completely unhedged” camp shrank from 28% to 9%. Institutions are neither abandoning AI en masse nor allowing portfolio outcomes to depend on a single theme. Technology exposure remains, but risk budgets are being diversified.
The AI trade has entered the revenue-validation phase. 64% of respondents need to see AI commercialization or revenue delivery before increasing exposure to AI-related equities. Renewed capex acceleration received only 18% support, while further earnings-estimate upgrades received 14%. Orders, revenue, and cash realization are replacing narrative momentum as the key tests.
Confidence in the broader Asian market remains strong. A net 45% expect corporate profits in Asia ex-Japan to improve over the next 12 months, lifting optimism to the 89th historical percentile; a net 18% view the region’s equities as undervalued. This does not resemble a wholesale turn bearish.
Signals within semiconductors are beginning to diverge. Net optimism on the semiconductor cycle fell to 27%, yet semiconductors and technology hardware remain the two most overweight sectors in Asia ex-Japan. Taiwan, China, at 28%, has re-emerged as the market viewed as the clearest beneficiary of the next phase of the AI cycle.
AI supply-chain preferences are broadening beyond chips themselves. Power and energy rank first at 23%; data-center infrastructure and connectivity/networking each stand at 18%; memory is at 14%; and AI compute receives only 5%. Institutions are increasingly focused on how the entire data center is powered, connected, and operated.
Rising defensive exposure does not mean these sectors are already broadly overweight. Monthly positioning in utilities and consumer staples improved by 19 and 15 percentage points, respectively, but absolute positions remain net underweight by 5% and 9%. This looks more like a correction from excessive neglect than a new one-way consensus.
Japan has two core themes: banks and semiconductors. 59% expect the Bank of Japan to raise rates again in September, while 55% see USD/JPY reaching 165 as a potential intervention trigger. Banks and semiconductors were each named by 64% of respondents as one of Japan’s two most overweight sectors.
I. The Bottom Line: Technology Is Not Fading—Institutions Just No Longer Want to Run Unhedged
The easiest misreading of this survey is that capital is rotating out of technology and into defensives. The reality is more nuanced. Semiconductors and technology hardware remain the top two sector preferences in Asia ex-Japan, with net overweight positions of 50% and 32%, respectively. Among China themes, AI and semiconductors lead by a wide margin, selected by 73% of respondents. Another 59% believe the positive impact of AI on equities is only partially priced in. Institutions have not rejected AI, nor have they removed technology from the core of their portfolios.
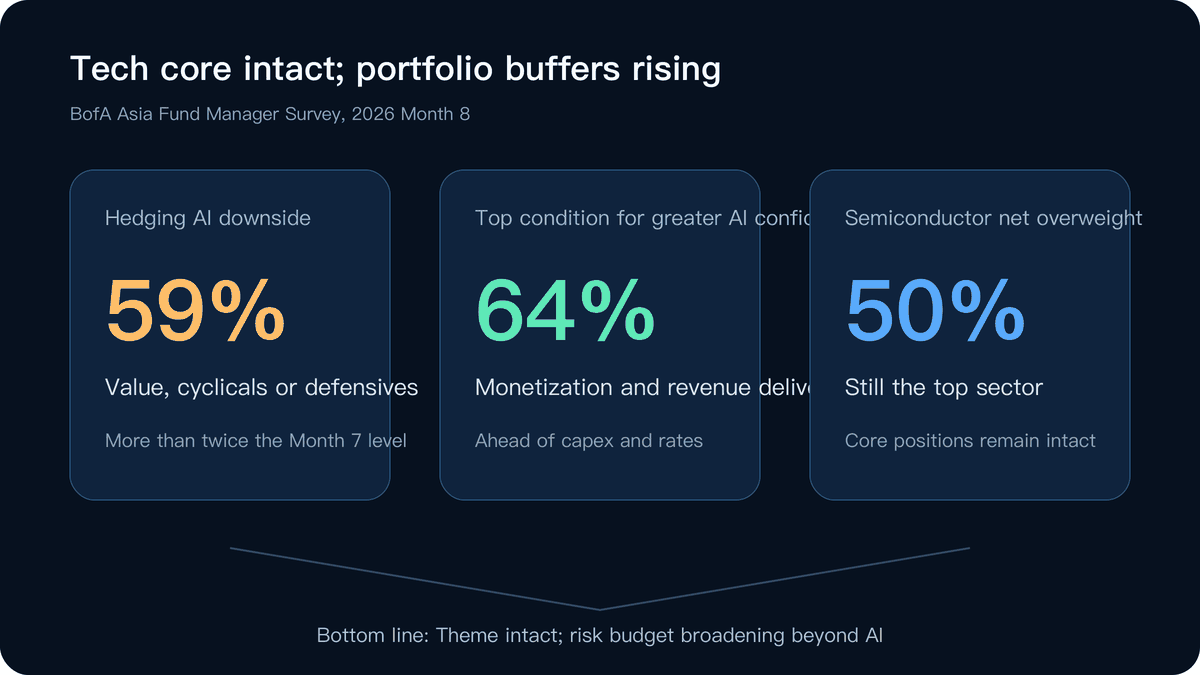
The shift is occurring at the portfolio-construction level: technology is no longer expected to carry returns on its own. The share using value or cyclical sectors to cushion against an AI selloff rose from 20% to 41%, while the share using defensives increased from 8% to 18%, taking the combined figure to 59%. Meanwhile, the proportion maintaining high AI exposure without any buffer fell from 28% to 9%. These changes reveal more about institutional behavior than technology’s continued No. 1 ranking: the core theme remains intact, but investors now demand a wider margin for error.
Nor should the rise in defensives be interpreted as a recession call. Respondents remain optimistic about Asian corporate profits, while their return expectations and assessment of undervaluation in Asian equities are also improving. More precisely, institutions are supplementing offensive positions with banks, healthcare, consumer staples, utilities, and telecommunications, ensuring that a single piece of AI news no longer determines the direction of the entire portfolio.
II. What the 59% Are Actually Doing: Moving from a Single AI Bet to Multiple Sources of Return
In July, 28% of respondents said they were not hedging the AI trade in any way; by August, that figure had fallen to just 9%, signaling a clear change in behavior. The share rotating into value or cyclical sectors increased by 21 percentage points, while the share moving into defensives rose by 10 percentage points. By contrast, the proportion repositioning within the AI supply chain fell from 16% to 9%, and the share maintaining low exposure to crowded AI beneficiaries declined from 12% to 5%.
Institutions are no longer confining the solution to the AI ecosystem itself. Switching from one type of chip to another would leave a portfolio exposed to the same capex cycle, earnings expectations, and market sentiment. Allocating part of the risk budget to banks, consumer sectors, healthcare, and utilities creates genuinely differentiated sources of return.
The fact that value, cyclicals, and defensives appear in the same response also means the 59% figure should not be read as uniformly bearish. Banks, energy, and certain cyclical sectors benefit from nominal growth, interest rates, and capital spending; they are not conventional safe-haven assets. Healthcare, consumer staples, and utilities provide the more traditional buffer of stable earnings. The August repositioning therefore reflects both an effort to reduce volatility and a broadening from a single AI theme toward multiple themes spanning growth, rates, and stable cash flows.
What has weakened is unconditional conviction. Institutions still endorse AI’s long-term trajectory, but they are no longer willing to accept the simplistic premise that rising capex should lift all AI assets in tandem.
III. The AI Trade’s New Hurdle: Show Me Revenue, Not Just Budgets
64% of respondents cited “AI commercialization or revenue delivery” as the primary condition for increasing confidence in AI-related equities. By comparison, renewed acceleration in hyperscaler AI capex received only 18% support, further earnings-estimate upgrades received 14%, lower market valuations just 5%, and lower interest rates 0%. The message is unequivocal: what institutions now lack most is evidence that investment is converting into revenue.
