
BOE A Deep Dive: Morgan Stanley Raises Target to Rmb9.30, Re-rating Logic from Display-Panel Cycle Leader to Glass-Substrate Option
目录
TL;DR
1. Why BOE A Was Suddenly Re-rated
2. What Exactly Is Being Adjusted in the Rmb9.30 Target Price
3. The Old Assets Have Not Disappeared: The LCD Cycle Still Determines the Base
4. Turning Cash Flow into an Asset: Why Depreciation and Capex Matter
5. OLED and MLED: Not the Main Line, but They Determine Valuation Quality
6. Glass-Substrate Advanced Packaging: Why the Market Is Willing to Price the Option
7. Model Breakdown: Low Revenue Growth, High Profit Elasticity
8. Compared with Other Parts of the Industry Chain, What Is BOE A Betting On?
9. Three Scenarios: How to Understand Rmb9.30, Rmb11.00, and Rmb3.50
10. The Most Important Things to Watch Are Not News, but Four Sets of Numbers
11. Main Risk: Valuation Has Moved Ahead of Performance
12. Sell-side Divergence: One Company, Two Valuation Languages
13. Asset History: From Scale Expansion to Efficiency Harvest
14. Data Framework: Which Numbers Can Be Viewed Precisely, and Which Can Only Be Viewed Probabilistically
15. Trading Cadence: First Look at the Panel Floor, Then at Glass-Substrate Realization
16. Conclusion: BOE A Has Begun to Have a Second Valuation Language
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
BOE A is being repriced not because near-term earnings have suddenly broken out, but because the market is starting to view it not as a single-cycle panel stock, but as an asset combining better cash flow, OLED repair, and an advanced-packaging glass-substrate option. The key question is how much of the Rmb9.30 target price comes from visibility, and how much from still-unrealized optionality.
TL;DR
This is not an earnings-upgrade story. Morgan Stanley raised BOE A's target price by nearly 80% while cutting its 2026E/2027E earnings forecasts. The real change is that the P/B multiple nearly doubled. In other words, the near-term income statement did not suddenly improve; the market is willing to pay a higher price because the asset profile has expanded from "LCD cycle" to "cash-flow improvement + advanced-packaging option."
The panel business remains the base. BOE A's 2028E display revenue is still around Rmb177.1bn, or 76.3% of modelled total revenue. Even if advanced-packaging glass substrates reach about Rmb5.1bn of revenue in 2028E under Morgan Stanley's model, they would account for only about 2.2% of total revenue. The share price can trade the glass-substrate beta, but fundamentals are still determined by LCD prices, capacity discipline, TV size migration, OLED yield, and depreciation cadence.
The re-rating lever is P/B, not P/E. Morgan Stanley sets its Rmb9.30 target price using 2.5x 2026E P/B, implying 2026E BVPS of about Rmb3.73, and cites 2026-2028E ROE of 5%-8% as support. This framework fits panel stocks better than P/E because BOE A's profit elasticity comes from balance-sheet utilization, lower depreciation, and supply discipline, not a single year's EPS.
Glass substrate is an option, not 2026 earnings. BOE A plans to build more complete glass-core substrate manufacturing from TGV glass cores to build-up layers. It may invest about Rmb5bn in 2027 to build monthly capacity of 15,000 510mm x 515mm substrates, with mass production targeted for 2028. This direction raises valuation imagination, but verification must at least track IC-design customer qualification, TGV yield, copper plating, warpage control, and coordination with packaging houses.
Cash-flow improvement makes the option more credible. Goldman Sachs' March materials show management emphasizing a future decline in depreciation and capex burden, with panel makers maintaining existing capacity and flexibly adjusting utilization, leading to healthier industry supply-demand. If LCD prices do not lose control again, BOE A can convert lower depreciation on older lines into profit and cash flow, while using lower capital intensity to place bets on MLED, OLED, and advanced packaging.
The disconfirmation points are specific. If TV-panel prices fall materially after 3Q26, OLED smartphone demand remains weak, advanced-packaging customer qualification stalls, or glass-substrate investment turns into high capex without orders, then 2.5x P/B will look too expensive. The four most important metrics to track are LCD TV panel prices, display-business gross margin, capex intensity, and glass-substrate customer validation milestones.
1. Why BOE A Was Suddenly Re-rated
This round of BOE A's re-rating is easy to misread as "glass-substrate concept speculation." That is only half right. The market is indeed trading new terms such as glass-core substrates, TGV, and panel-level packaging, but the move in the target price from Rmb5.20 to Rmb9.30 is not based on higher 2026 profit. It is based on a wider set of assets that can be discussed for the company.
Morgan Stanley's numbers are very direct: near-term earnings forecasts were cut, yet the target price was raised sharply. If this were a normal earnings upgrade, the target-price increase should come from higher EPS. That is not the case. The valuation method has shifted from the low P/B framework traditionally used for panel stocks to a higher book-value multiple. The core variable has become "whether book assets can earn a higher ROE, and whether this company can move from panel manufacturing capability into advanced-packaging manufacturing capability."
This distinction matters. The label BOE A has historically found hardest to escape is the LCD supply cycle. When the industry expands capacity, prices fall; when prices fall, earnings retrace; when earnings retrace, P/B valuation is pushed back to the low end. Two lines are now changing this narrative at the same time. The first is that older panel lines are entering a phase of lower depreciation and lower capex, while leading industry players are paying more attention to utilization discipline. The second is that AI compute packaging is turning glass substrates from an edge technology in the display industry into an underlying manufacturing capability that may participate in advanced packaging.
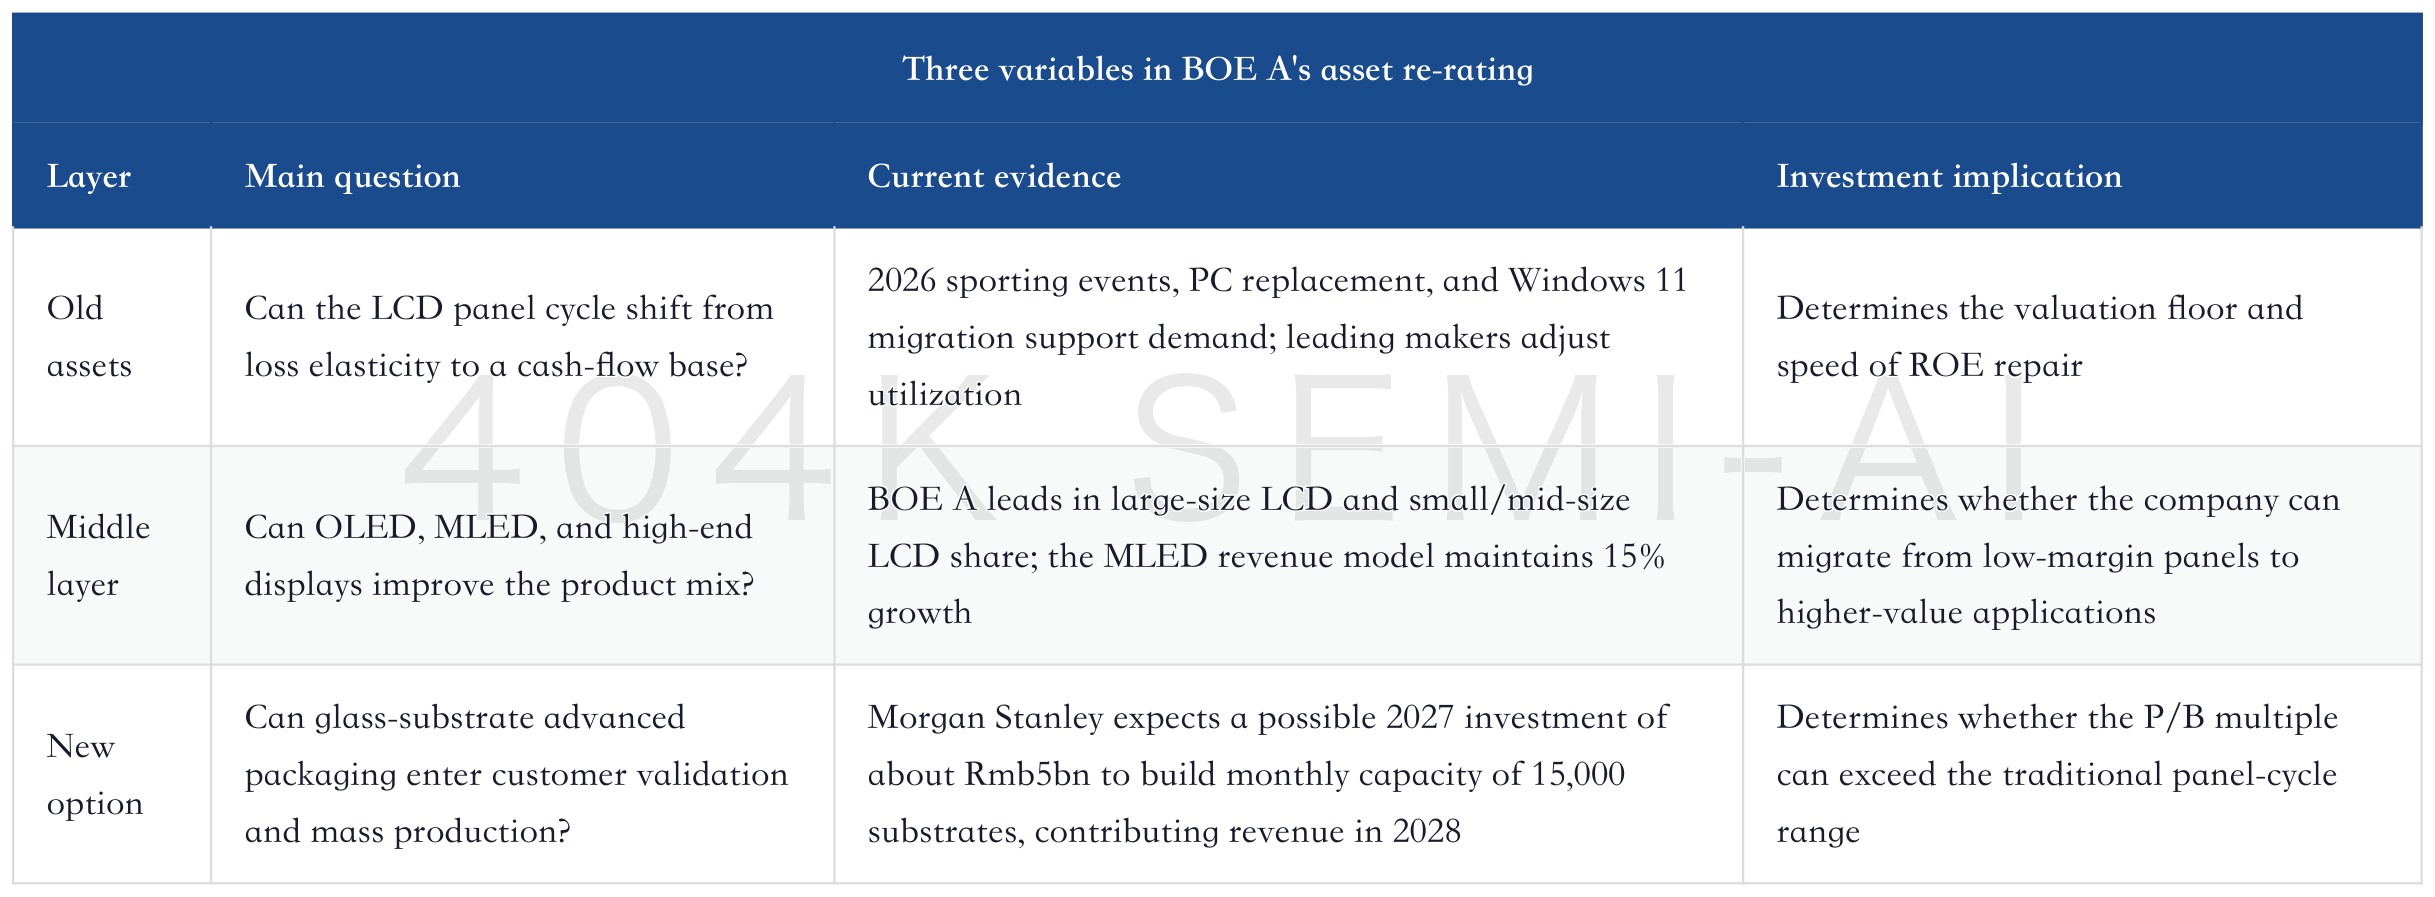
With these two lines layered together, BOE A's pricing question is no longer just "how many dollars will TV panels rise this year." It becomes three more fundamental questions: whether the profit floor of older LCD assets has been lifted, whether new display businesses such as OLED and MLED can stop consuming profit, and whether glass-substrate advanced packaging can open a second growth curve for the company.
This judgment should not be too aggressive. Morgan Stanley's text also acknowledges that revenue and profit contribution are more likely to appear only from 2028. In 2026/2027, commodity panels will still be the main driver. At present, 70%-80% of BOE A's revenue still comes from commodity panels, and 2028E display revenue still accounts for 76.3% in the model. So this is not "panels no longer matter"; it is "when the panel base does not collapse, new options can be priced by the market."
Glass substrates are not a materials story, but a process-integration battle
The core of BOE A's re-rating is not a single technology point, but the migration of process capability. Display-panel companies' historical advantages lie in large-area glass, thin-film deposition, lithography, yield ramping, cleanroom management, and large-scale manufacturing. Glass-core substrates in advanced packaging look like semiconductor-packaging materials, but they also test large glass panel handling, via formation, metallization, warpage, and interlayer structure control. Panel makers are not natural winners, but they at least have some transferable manufacturing muscle.
What truly deserves study at BOE A is that it does not want only to supply a glass core sheet, but to complete full glass-core substrate manufacturing, including the TGV glass core and build-up layers. That ambition is larger than simple slicing, drilling, or supplying materials, and it is also harder. If it succeeds, the company receives not low-value-added processing fees, but a key part of the value chain in advanced-packaging carriers. If it fails, the investment again becomes capex pressure.
2. What Exactly Is Being Adjusted in the Rmb9.30 Target Price
The most important part of this target-price change is the valuation bridge. The base, bull, and bear cases correspond to three different P/B worldviews: how much book-value multiple the recovery of the main business can support, how much probability should be assigned to the glass-substrate option, and whether industry supply discipline will lose control again in the bear case. The numbers themselves are not complicated. What is complicated is why the same company can suddenly move from being discussed at a low multiple for a traditional panel stock to a higher P/B.
The answer lies in ROE and the asset narrative. Morgan Stanley's base case prices BOE A into a higher ROE range instead of continuing to use the P/B center of the low-return years of the past. In other words, the logic behind the target-price increase is not "one-off profit jump," but "book assets are entering a higher-return range, and the market can assign a higher book-value multiple."
This type of valuation method is more reasonable for panel stocks. One-year P/E in the panel industry is often distorted: at cycle bottoms, profit is low and P/E looks high; at cycle peaks, profit is high and P/E looks low. What truly cuts through the cycle is asset utilization, depreciation cycle, capex discipline, supply structure, and ROE. If BOE A remains a high-capex, low-ROE panel company with severe price competition, P/B will struggle to rise for long. If it becomes an asset with lower depreciation, lower incremental capex, stable cash flow, and an advanced-packaging option, the P/B center has room to move up.
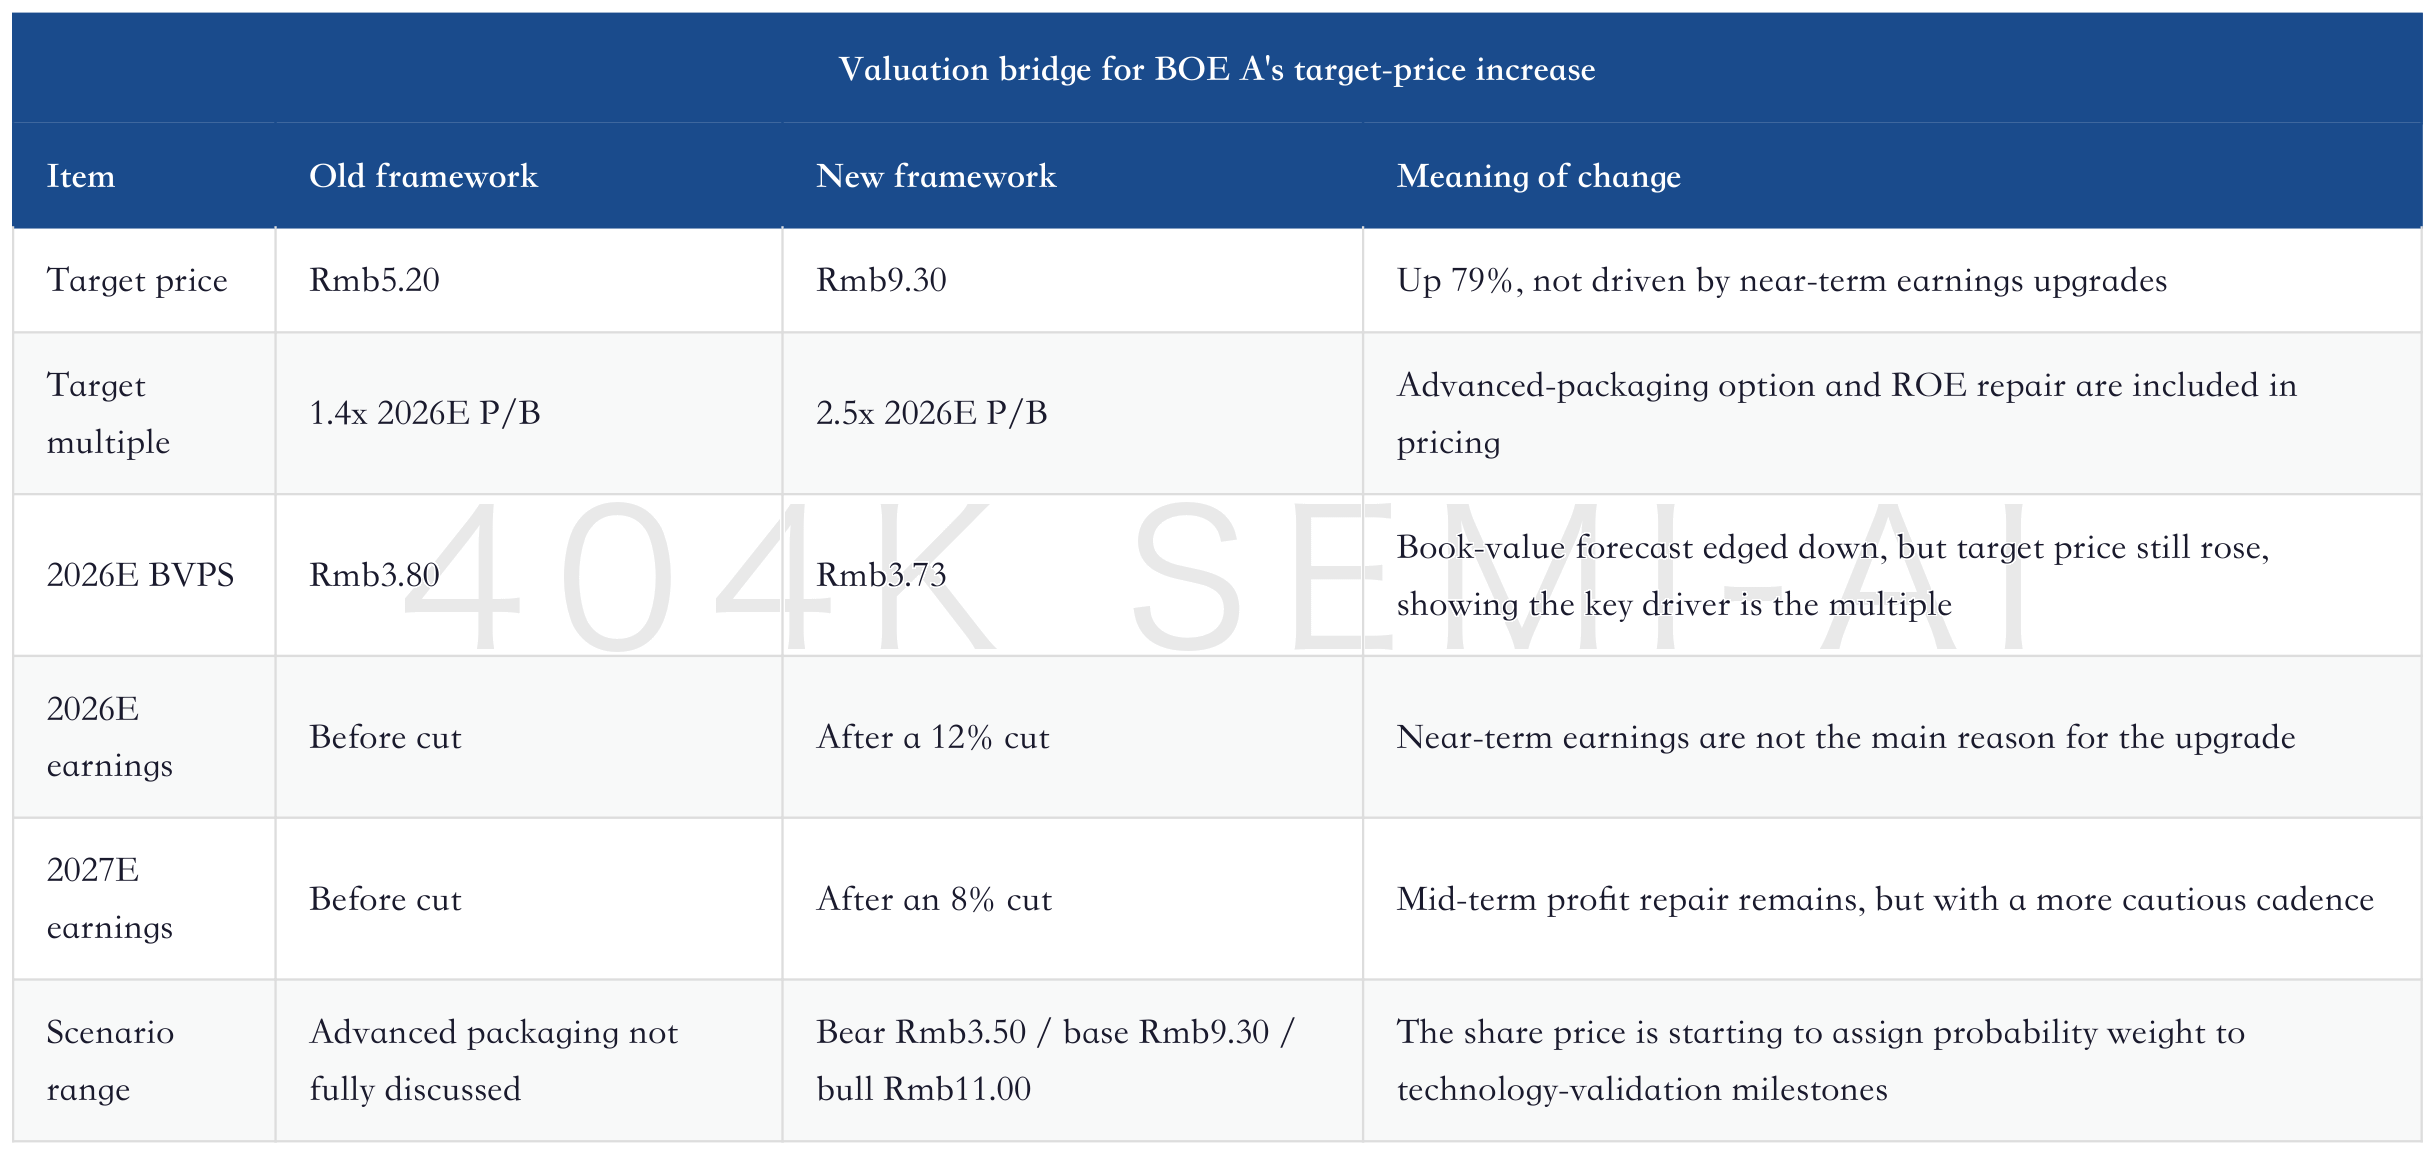
This table has a counterintuitive conclusion: if one looks only at the 2026E earnings cut, the stock should not become more expensive; if one looks at the P/B re-rating, it can. What investors really need to judge is whether the target multiple has enough asset-return support. If ROE can only stay at historical lows, high P/B is dangerous. If ROE repairs steadily while glass-substrate orders provide additional upside probability, high P/B is not just a concept trade.
The comparison between BOE A and Taiwanese panel makers also illustrates the point. In Morgan Stanley's Greater China display coverage, the ranking is BOE A, Innolux, and AUO. Innolux has stronger visibility in glass-core substrate projects, but its valuation has expanded further from levels near its peak of the past decade. AUO has LEO satellite and optical-module stories, but visibility for advanced-packaging contribution is lower. BOE A is distinctive because it has the largest main-business scale, valuation has rebounded but remains below the historical peak of 2.7x P/B, and the glass-substrate option has not yet been fully priced.
"Below the historical peak" should not be simplistically interpreted as cheap. The historical peak corresponded to a different cycle, different profit elasticity, and different market sentiment. A more prudent formulation is that BOE A's valuation has not, like Innolux's, fully capitalized advanced-packaging imagination in one step, leaving room for gradual realization through fundamental validation. Its risk-reward comes from "a relatively stable panel base + a new business not yet fully reflected," not from absolute undervaluation.
ABF substrates deep dive: the foundation of AI compute packaging, from entry framework to supply-demand and company ranking
Why can advanced packaging change the valuation of panel stocks? Because the bottleneck in AI compute is spreading from a single chip to connectivity between chips, packages, and substrates. GPU, HBM, ASIC, optical interconnect, advanced packaging, substrates, and materials are no longer isolated links. Thermal performance, warpage, signal loss, line/space, and manufacturable area of substrates all affect system-level compute cost. Glass substrates have entered the discussion because they may replace part of the bottleneck in organic materials through larger size, lower signal loss, lower warpage, and better dimensional stability.
BOE A's value does not lie in the statement "it also does AI." That is too crude. A more precise investment language is this: if AI packaging continues from silicon interposers and ABF substrates toward larger area, higher I/O, more layers, and lower warpage, glass-core substrates will become a potential route; as the world's largest panel manufacturer, BOE A has some large-glass manufacturing and clean-process experience, and therefore holds an option to enter this route. An option can support valuation, but it cannot replace orders.
3. The Old Assets Have Not Disappeared: The LCD Cycle Still Determines the Base
BOE A's first principle remains panels. In the model, total revenue rises only modestly. Although the share of the display business gradually declines, it is still the absolute majority by 2028E. If LCD prices fall sharply, the glass-substrate story will struggle to support valuation independently. Only if the display business stabilizes can the cash-flow base support the advanced-packaging option.
The good news is that the LCD supply-demand environment is healthier than in recent years. Goldman Sachs' February display-panel monthly report shows that prices for 32/43/55/65-inch LCD TV panels had risen 6%/3%/2%/2% since the start of 2026, reaching US$36/65/124/172. Although these prices remain far below their July 2021 peaks, the direction implies repair in industry demand and supply. More importantly, leading panel makers have learned to adjust utilization according to demand rather than expanding output without discipline.
BOE A also still has a dominant share position. Goldman Sachs materials show the company holds global leadership in large-size LCD, small/mid-size LCD, and LCD TV panels, with LCD TV panel share also rising year on year. For a heavy-asset manufacturer, share itself is not a profit guarantee. But share combined with industry concentration and utilization discipline can improve the stability of the price floor.
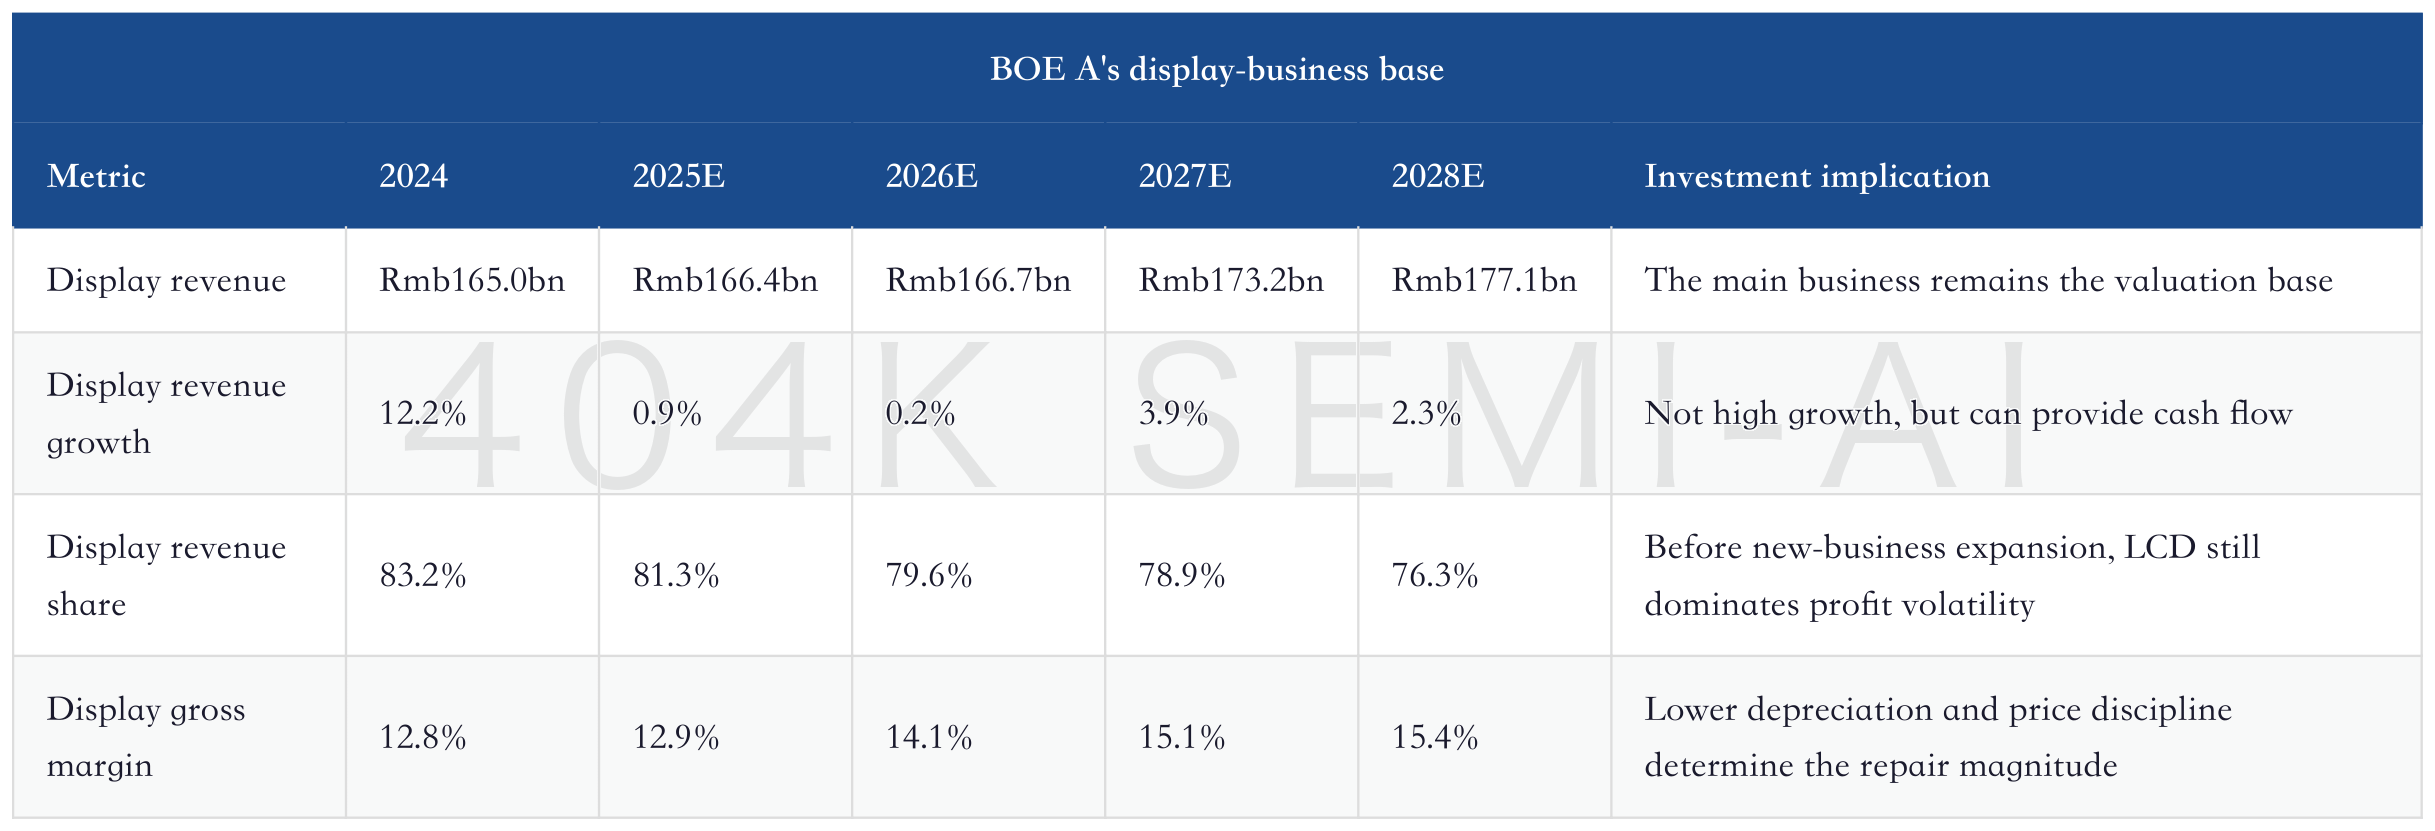
The key to the LCD business is not rapid growth, but "stop destroying value." The most damaging part of the panel industry in the past was that every time the cycle improved, capacity expanded and all manufacturers ultimately pushed prices down together. Leading makers now emphasize capacity control more, while larger TV sizes, sporting events, AI PCs, gaming monitors, and the Windows 11 replacement cycle all support 2026 demand. Demand is not exploding, but when supply is no longer expanding blindly, modest demand improvement can still feed into prices and gross margin.
This is also what separates BOE A from ordinary concept stocks. Glass substrates have not yet contributed profit, but LCD is already contributing revenue, share, and cash flow. As long as industry supply-demand does not deteriorate again, old assets can support the valuation floor. As long as depreciation and capex decline, old assets can release more free cash flow. The value of the new option must be built on old assets not becoming a drag.
The risk is equally clear. Morgan Stanley believes this round of TV-panel price increases may begin to fall back after 3Q26. If the price decline exceeds expectations and display-business gross margin cannot move from 14.1% in 2026E toward 15.1% in 2027E, ROE repair will be slower than valuation expansion. For BOE A, the biggest risk is not failure of glass substrates itself, but that before glass substrates begin to contribute, the LCD main business pushes profit and cash flow back down.
4. Turning Cash Flow into an Asset: Why Depreciation and Capex Matter
The variable most easily ignored in panel stocks is depreciation. LCD lines require huge capex during construction, and depreciation weighs on the income statement. Once lines enter maturity, depreciation pressure falls and capex slows, so the same revenue can release higher operating profit and cash flow. If BOE A is merely "low revenue growth," it does not look attractive. But if low revenue growth comes with lower depreciation, lower capex, and better industry supply discipline, it moves closer to a cash-flow asset rather than a cyclical stock.
Goldman Sachs' March meeting materials with BOE A management provide this clue. Management mentioned that 2026 growth catalysts include the World Cup and other sporting events, TV replacement, the end of Windows 10 support, and AI PC demand. It also expects future depreciation costs and capex to decline, with the goal of maintaining the current capacity level. This language corresponds not to expansionary growth, but to a harvest-phase asset.
This change is also visible in the BOE A model. The revenue curve is not steep, but the slopes of operating profit and net profit are larger, with margins repairing year by year. Behind this is not a sudden breakout in a single product, but the combined effect of gross margin, expense efficiency, lower depreciation, and product mix. For heavy-asset manufacturing, this kind of margin slope explains P/B re-rating better than revenue growth.
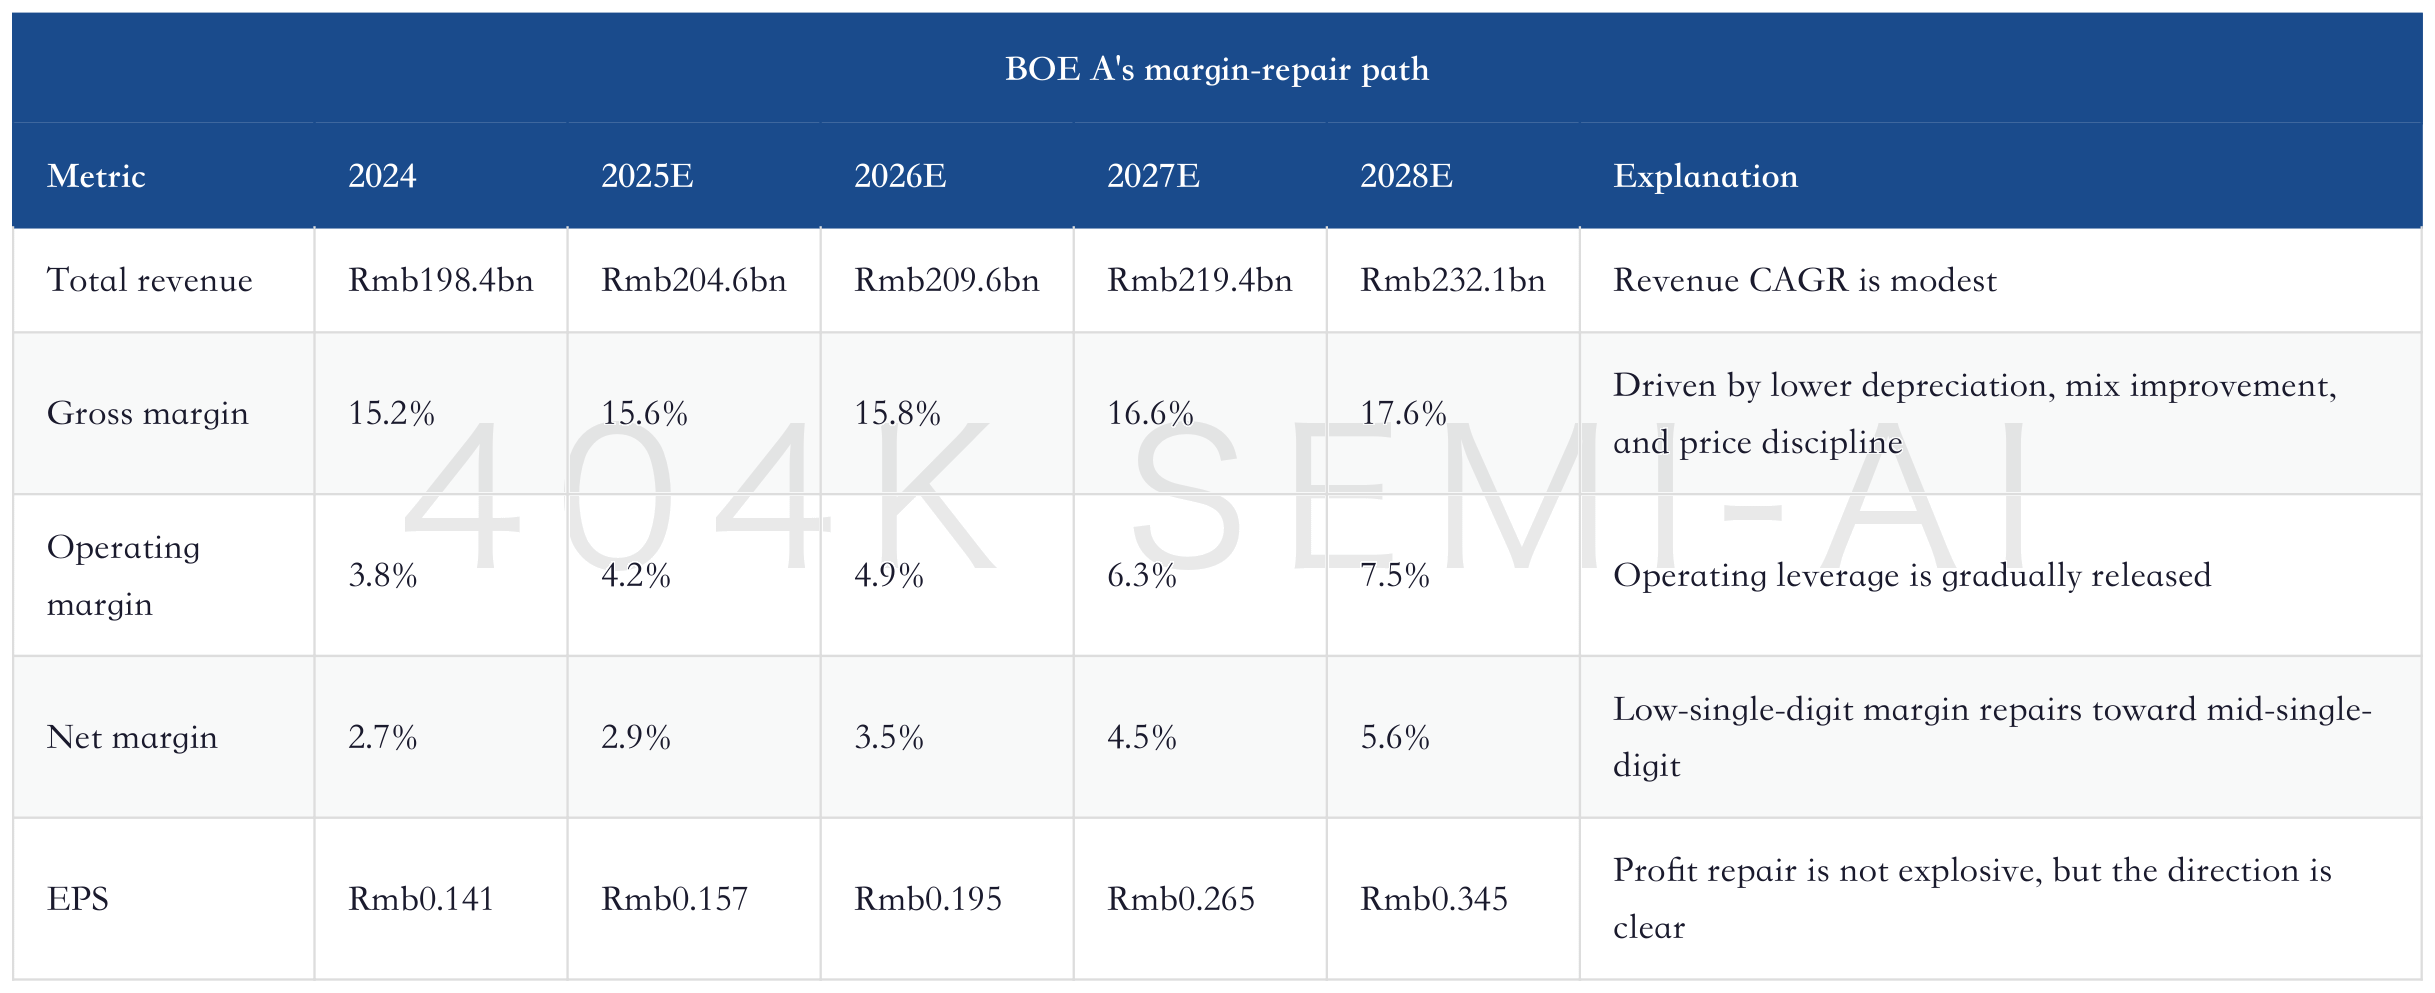
What matters most in this table is not how high 2028E net profit is, but the annual margin climb. Panel manufacturing is a large-scale fixed-cost industry. Every one percentage point of gross-margin and operating-margin improvement has a large impact on profit. BOE A's investment logic does not require revenue to grow 20% every year. As long as revenue maintains low-single-digit growth while gross margin and operating margin continue to improve, net profit can grow faster than revenue.
Cash-flow assetization also affects shareholder returns. In the model, the adjusted cash dividend rises from Rmb0.050 in 2024 to Rmb0.124 in 2028E. Although the absolute dividend yield is not the core of this note, it shows that if profit and cash flow improve steadily, the market can stop looking at the company only through "cycle-bottom P/B." The basis of the P/B re-rating is that book assets can generate more stable cash returns.
However, this path has limits. If BOE A re-enters a high-capex phase for advanced packaging, OLED, or MLED while new-business revenue realizes slowly, cash-flow assetization will be interrupted. The reason the glass-substrate option has value is that it appears able to borrow existing glass and panel-process experience. But once it requires large-scale new equipment, new fabs, new customer qualification, and a long payback period, it may again become a capex story.
5. OLED and MLED: Not the Main Line, but They Determine Valuation Quality
BOE A's second layer of assets is migration from LCD to OLED, MLED, and high-end displays. This should not be described as a grand narrative. OLED smartphone-panel demand has not been strong recently, and Goldman Sachs management-visit materials also mentioned that the smartphone market may be pressured by higher memory prices, weighing on the OLED business. MLED remains at an early stage with a small revenue base. They cannot replace LCD in the short term, but they will determine whether the company remains permanently trapped in low-margin commodity panels.
In the model, MLED revenue rises from Rmb8.5bn in 2024 to Rmb14.2bn in 2028E, growing by about 15% annually from 2026E to 2028E; gross margin rises from 5.8% to 8.0%. This business has low near-term profitability, but it represents BOE A's extension into automotive, commercial display, AR, smartwatches, high-end TVs, and special display scenarios. TCL/AUO third-quarter report readings also mentioned that future high-end panel applications include smartwatches, automotive displays, and AR glasses. BOE A plans to shift its Inner Mongolia B6 line from LCD/OLED toward Mini/Micro LED, reflecting the company's investment in high-end displays.
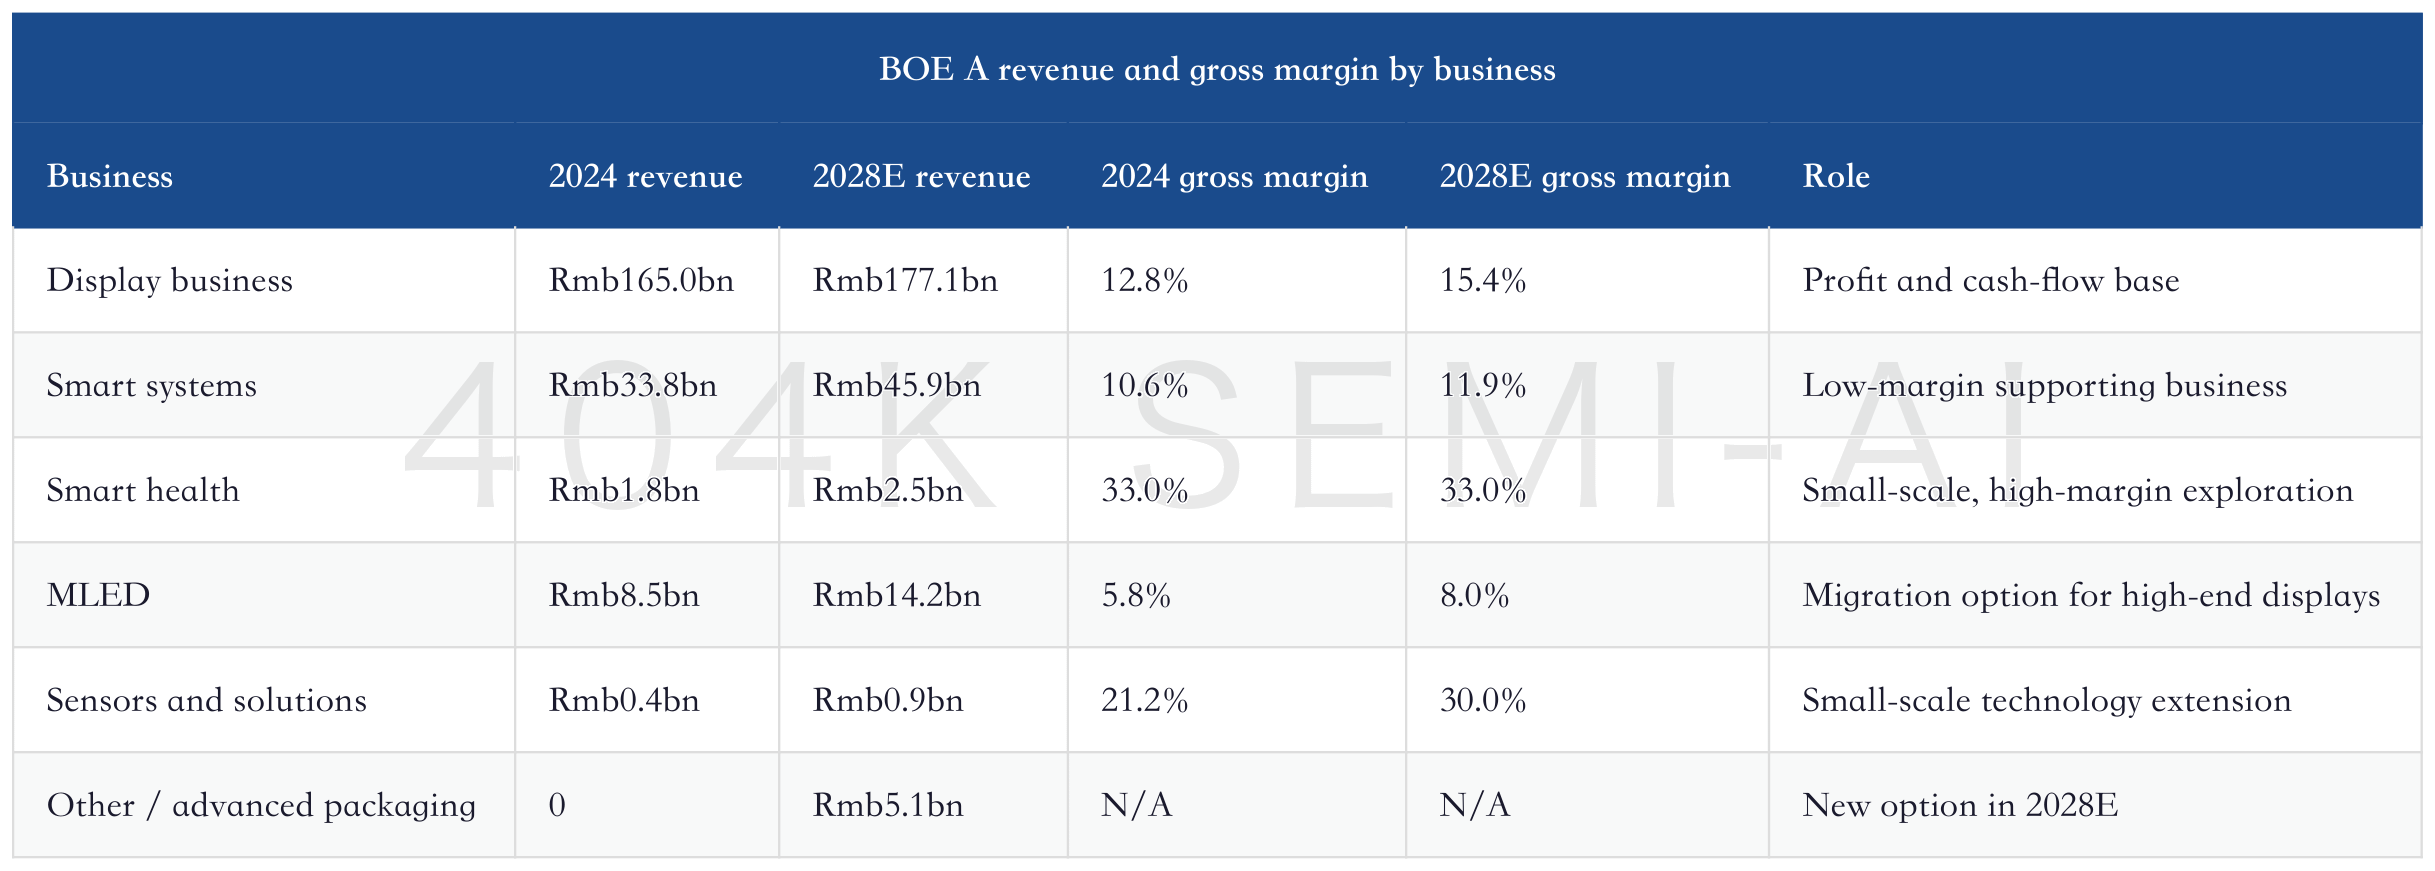
OLED/MLED affects valuation not through immediate profit contribution, but through improving the market's understanding of the company's capability boundary. If BOE A can only make LCD TV panels, it is a typical cyclical asset. If it can continue to find new applications in small/mid-size OLED, high-end automotive displays, Mini/Micro LED, and advanced-packaging glass substrates, it is not merely a capacity player, but a platform for large-area glass, thin films, lithography, and yield control.
This platform language also needs restraint. The display industry and semiconductor-packaging industry differ in customers, standards, qualification, yield curves, and cost structures. One cannot assume BOE A can naturally win simply because both use glass and clean processes. MLED has not yet proven high profitability, OLED is still affected by the smartphone cycle and competition, and advanced packaging requires trust from semiconductor customers. What truly deserves valuation is the "probability of capability migration," not the idea that "the transformation is already complete."
AI PCB Phase 3: capacity expansion is not the answer; glass-fiber looms, T-glass, HVLP copper foil, lamination, drilling, and qualification cycles decide who really unlocks supply
This is also why BOE A cannot talk only about capacity. Whether in MLED or glass-substrate advanced packaging, the end requirements are customer qualification, materials support, yield, and delivery stability. In the AI hardware chain, the most valuable link is often not "I can make it," but "I can make it stably, at low cost, and at scale, and customers are willing to hand me the next-generation platform." BOE A's panel-manufacturing experience gives it an entry ticket, not a finish-line ticket.
6. Glass-Substrate Advanced Packaging: Why the Market Is Willing to Price the Option
Glass substrates have drawn market attention because AI packaging is getting larger. As GPU, ASIC, HBM, and high-speed interconnects are stacked more densely, traditional organic substrates and silicon interposers all encounter issues in area, cost, warpage, heat, and signal integrity. Glass is attractive because of dimensional stability, low thermal-expansion matching, low signal loss, mechanical strength, and panel-level manufacturing potential. If future advanced packaging requires larger area, higher I/O density, and lower cost, glass-core substrates may become an optional route.
The path Morgan Stanley gives for BOE A is more specific than a pure concept. BOE A began researching glass-core substrate technology in 2020 and already has a pilot line. It is validating with domestic and overseas IC design companies. If progress is smooth, it may invest about Rmb5bn in 2027 to build capacity of 15,000 510mm x 515mm substrates per month, targeting mass production in 2028. The model assigns about Rmb5.1bn of advanced-packaging revenue in 2028E.
Two frameworks need to be separated here. Morgan Stanley has built a 2028 revenue assumption for glass-substrate advanced packaging, but under the company's total revenue framework, it is still small. This is not a contradiction, but a difference in framing: for total company revenue, advanced packaging is still small; for the valuation narrative, it may represent the start of a second curve. Investment judgment cannot describe small revenue as a decisive profit source, but it also cannot ignore its influence on the valuation multiple.
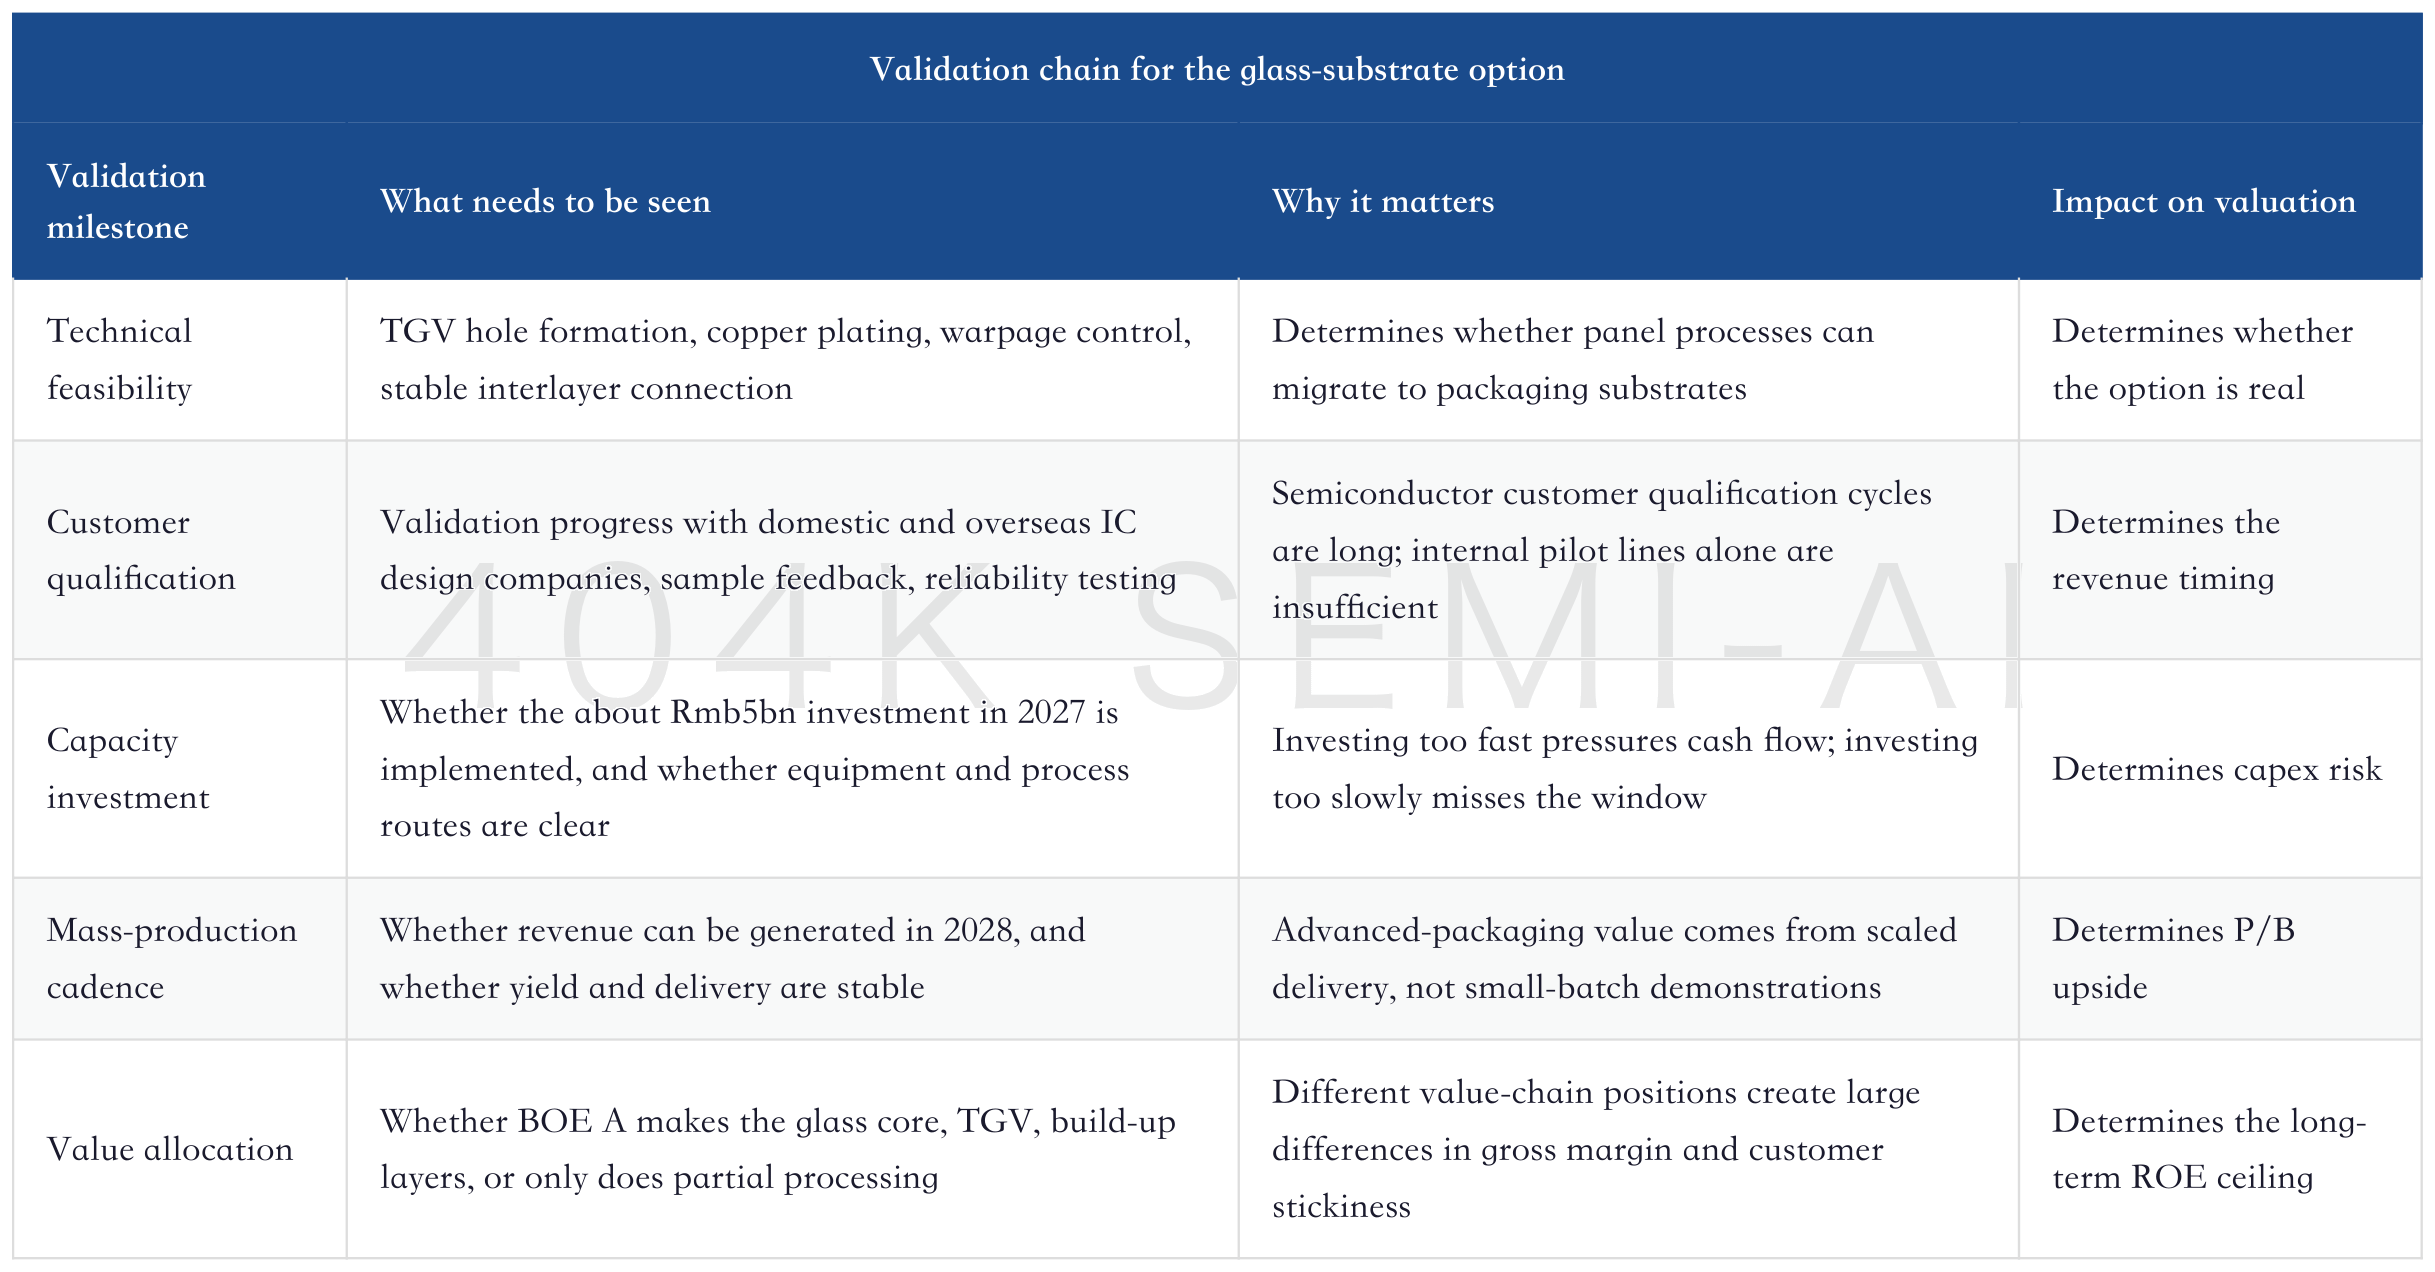
BOE A and Innolux have different paths. Innolux is believed to be participating in a leading foundry's glass-core substrate project, making TGV on 510mm x 515mm glass panels before handing them to Ibiden for the subsequent substrate process. Its visibility is stronger, but it needs to procure new equipment, and initial capex may reach NT$20bn-30bn. BOE A hopes to make more complete glass-core substrates, including the TGV glass core and build-up layers. The former looks more like entering one process in an existing supply chain; the latter looks more like pursuing broader manufacturing integration.
The benefit of complete manufacturing is a higher value-chain position. The drawback is higher difficulty. TGV is not an ordinary panel hole, and subsequent metallization, plating, insulation, interlayer connection, and reliability must all run to semiconductor-packaging standards. Build-up layers are not a routine display-panel process, and customers will not lower qualification standards simply because BOE A is a panel leader. BOE A's choice is to exchange higher difficulty for a larger value pool.
JCET deep dive: from cyclical assembly and test to AI advanced-packaging gatekeeper, how Chiplet, XDFOI, and domestic compute re-rate an OSAT leader
In the advanced-packaging industry chain, the boundaries among OSATs, substrate makers, material makers, equipment makers, and chip customers are being redistributed. If BOE A enters glass-core substrates, it will not be dealing with traditional display customers. It must enter joint validation with foundries, OSATs, substrate makers, and AI chip design companies. It must prove not only single-panel process capability, but system-level package usability.
This path has imagination, but also natural constraints. Morgan Stanley places revenue contribution in 2028, which already tells the market not to expect profit realization in 2026. If the share price over-trades advanced packaging in 2026 while fundamentals fail to catch up, volatility will be large. A healthier cadence is to watch validation milestones in 2026, capex and customer design-wins in 2027, and revenue recognition and the yield curve in 2028.
7. Model Breakdown: Low Revenue Growth, High Profit Elasticity
BOE A's model does not look like a typical growth stock. Revenue is not fast, while profit is faster. This is typical profit elasticity for heavy-asset manufacturing at a cycle bottom, during a decline in depreciation and a repair in gross margin. To read this company, one should not only ask whether revenue can grow quickly, but also whether asset utilization, depreciation cycle, and gross margin can convert low-growth revenue into higher profit.
This elasticity can be split into three parts. First, display-business revenue growth is low, but gross margin repairs from 12.8% to 15.4%, and the scale is large enough for a clear profit contribution. Second, smart systems, MLED, sensors, and other businesses contribute revenue growth; although gross margins vary widely, they help reduce the company's exposure to a single LCD cycle. Third, about Rmb5.1bn of other revenue is added in 2028E, used by the model to capture the advanced-packaging glass-substrate option.
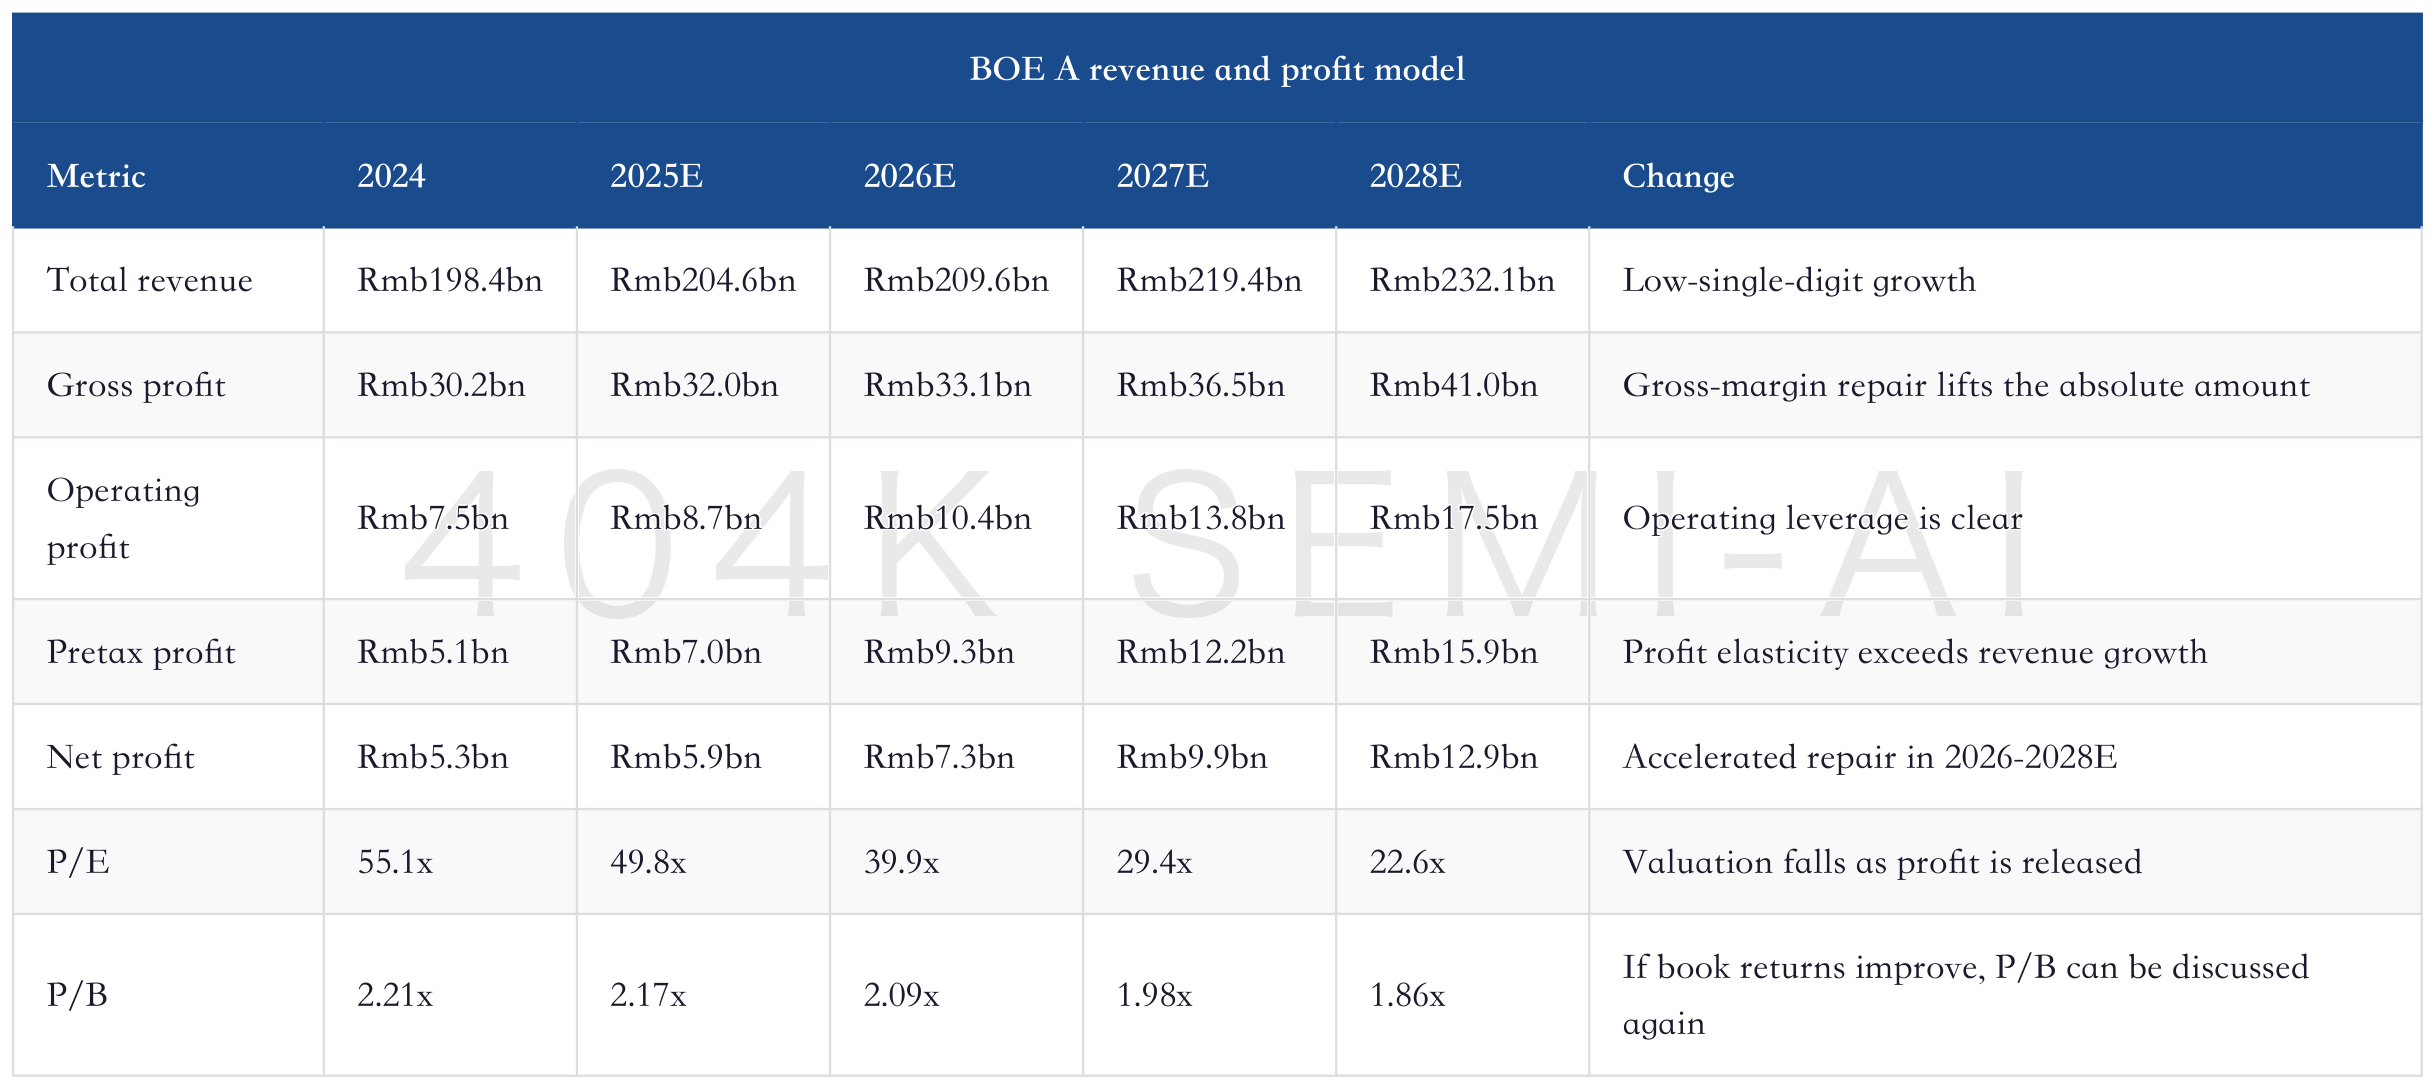
These data show that BOE A's attraction is not a steep revenue curve, but the slope of margins. 2026E net profit is Rmb7.3bn, corresponding to EPS of Rmb0.195; 2028E net profit is Rmb12.9bn, corresponding to EPS of Rmb0.345. If the market looks only at P/E, nearly 40x 2026E is not cheap. If it looks at P/B and ROE improvement, the valuation logic is different. Morgan Stanley chose P/B precisely because it sees BOE A as an asset-efficiency repair story rather than pure profit growth.
But the P/B framework does not mean profit can be ignored. The increase in the book-value multiple ultimately still requires ROE delivery. If 2028E net profit cannot approach Rmb12.9bn and ROE cannot enter the 5%-8% range, 2.5x P/B will be questioned again. BOE A must deliver every year: whether display gross margin can rise, whether OLED can stop dragging, whether MLED can improve revenue quality, and whether advanced packaging has customer validation.
The model's most sensitive variable is not advanced-packaging revenue itself, but display-business gross margin. Assuming 2028E advanced-packaging revenue of Rmb5.1bn, even with a high gross margin, its impact on total profit takes time. But display-business revenue is Rmb177.1bn, and every one percentage point change in gross margin is about Rmb1.8bn of gross profit. BOE A's short- to medium-term fundamentals are still the prices, utilization, and depreciation of LCD and high-end displays.
This also explains why the investment conclusion must be expressed in two layers. The first layer is that BOE A's main-business repair provides a valuation floor, with profit expected to repair from the 2024 trough toward 2028E. The second layer is that glass substrates provide valuation elasticity, but before 2028 it is mostly probability weight. If one discusses only the first layer, the Rmb9.30 target-price increase looks large. If one discusses only the second layer, it is easy to ignore main-business risk. Together, the two layers form the true structure of this re-rating.
8. Compared with Other Parts of the Industry Chain, What Is BOE A Betting On?
AI hardware investment has already expanded from chips to packaging, substrates, optical interconnect, PCB, glass fiber, copper foil, equipment, and materials. BOE A is not the most direct beneficiary in this chain. It does not sell compute chips directly like GPU companies, is not already sitting in high-end substrate orders like ABF leaders, and is not naturally positioned in advanced-packaging manufacturing like OSAT leaders. BOE A is betting on something else: whether large-glass manufacturing capability can cross over into packaging carriers.
This bet has two advantages. First, BOE A already handles large-size glass and is familiar with high-cleanliness, large-area, thin-film, and lithography-related manufacturing organization. If glass substrates move toward panel-level size, traditional packaging houses and substrate makers may not naturally have large-panel handling capability. Second, BOE A has a large asset scale. If advanced-packaging glass substrates require capex and engineering iteration, the company has the ability to invest.
It also has two disadvantages. First, qualification logic for semiconductor-packaging customers is stricter than for display customers, and reliability, yield, long-term supply, and ecosystem coordination all need to be re-proven. Second, BOE A's historical earnings quality has not been high, and investors will worry that the new business again becomes a high-capex, low-return expansion. In other words, it has capability clues for entering glass substrates, but has not yet formed a certain commercial loop.
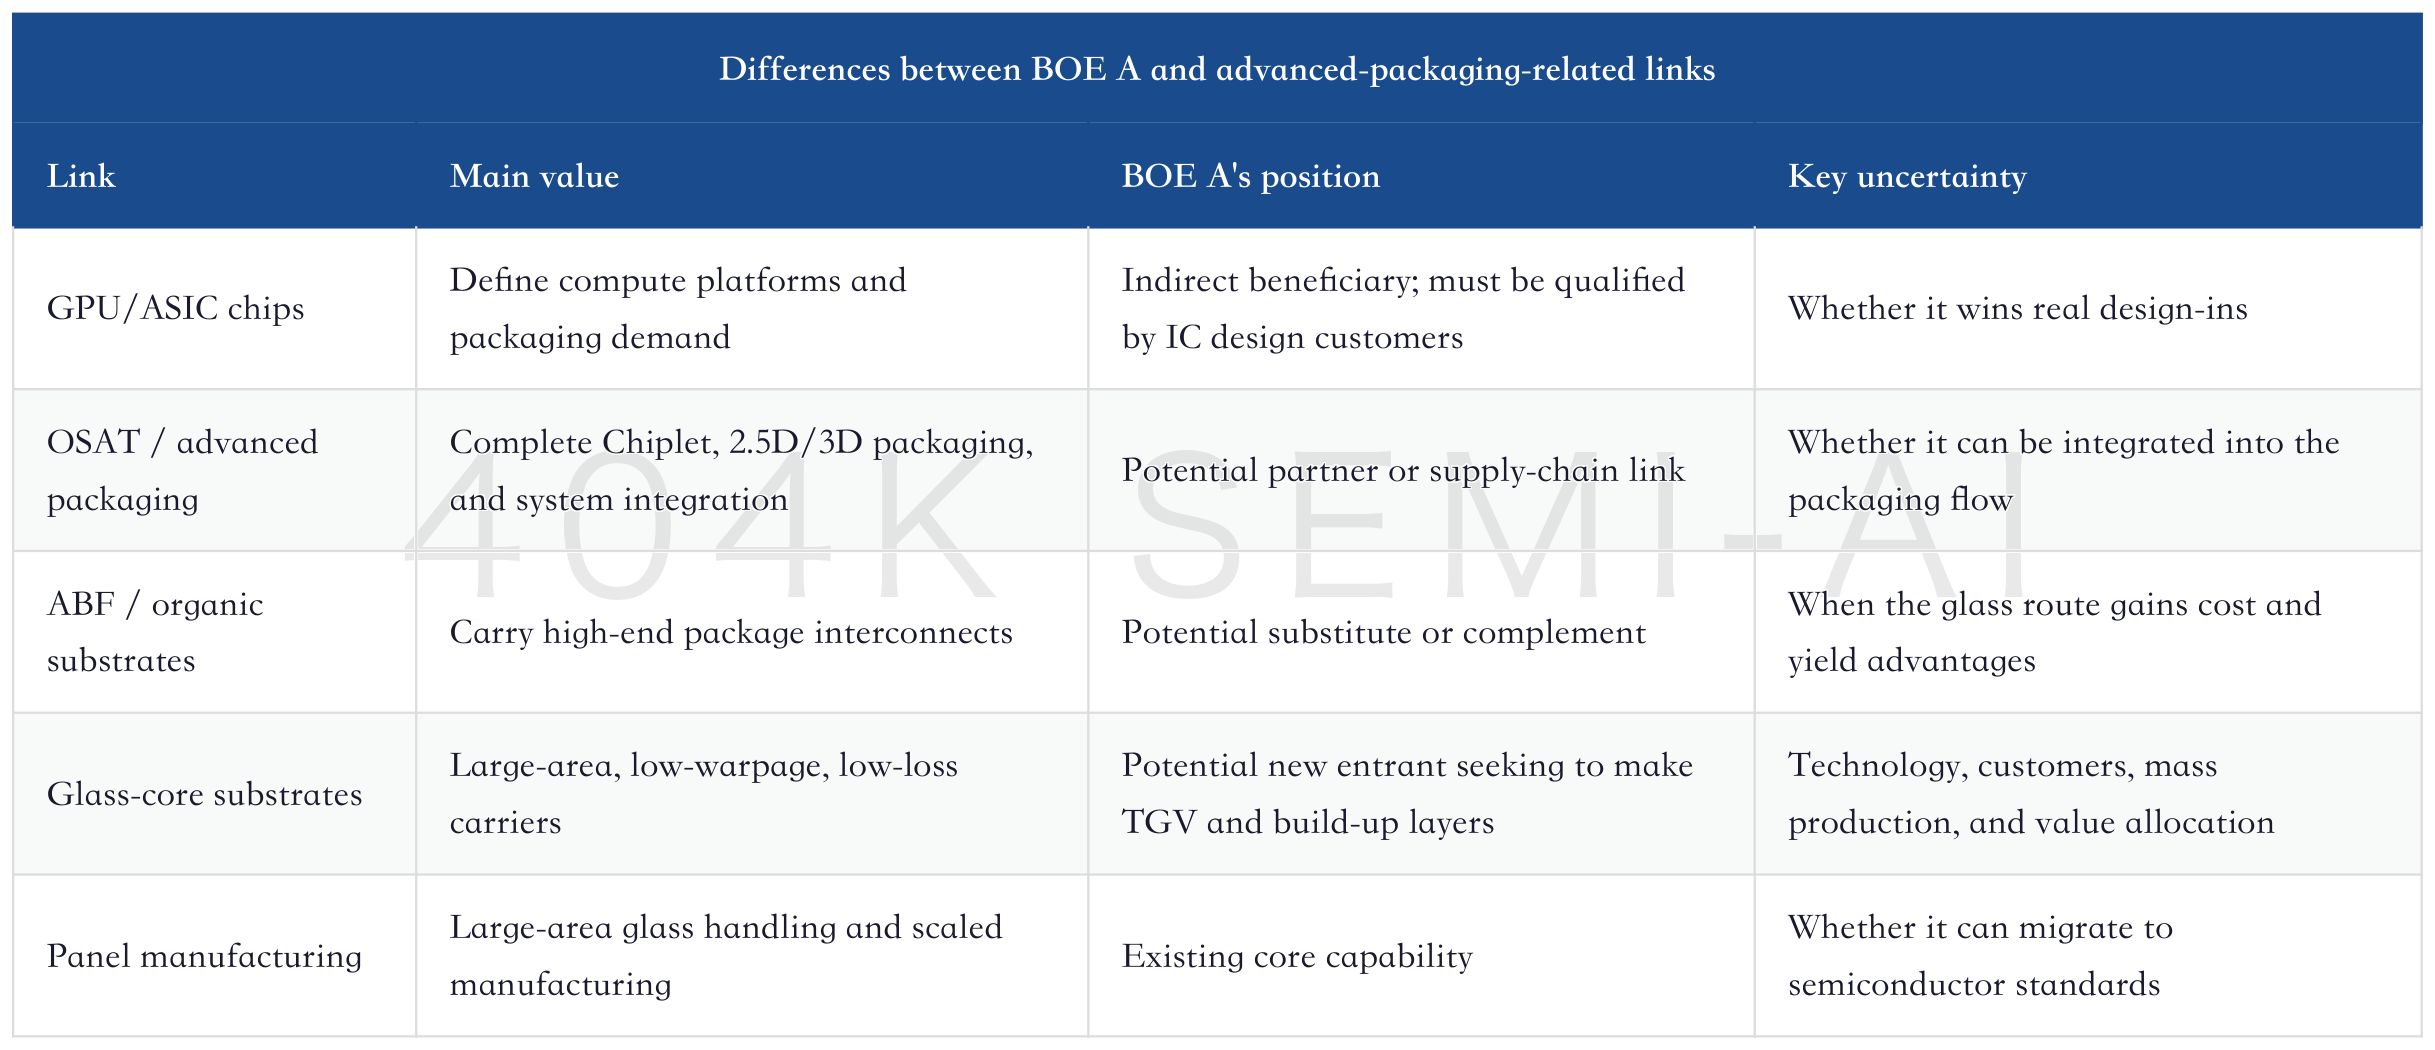
The conclusion from this table is that BOE A should not simply be compared with ABF substrate makers on orders, nor with OSATs on packaging capability. It is more like a "manufacturing-capability migration option": if advanced packaging truly requires panel-level glass manufacturing, it may move from the display industry into the semiconductor-packaging industry; if the glass route cannot scale for a long time, it still returns to being a panel-cycle stock.
Full re-rating map for AI PCB materials, from CCL price increases and glass-fiber looms to the ABF gap and rack upgrades
Over the past few months, the AI hardware chain has repeatedly proven one thing: the bottleneck is not always in the most visible chip link. Glass-fiber looms, T-glass, HVLP copper foil, ABF, CoWoS, optical modules, and power and thermal systems can all become profit-allocation gates at different stages. BOE A's glass-substrate story is easier to understand within this framework. It is not replacing GPUs; it is trying to enter the underlying manufacturing link of "compute cost per watt" and "packaging interconnect efficiency."
But precisely because of this, BOE A must be verified more strictly. The true bottlenecks in the AI chain eventually leave evidence in orders, price increases, capacity expansion, lead times, yield, and customer qualification. A concept without orders, a pilot line without customer design-wins, and capex without yield ramp are all insufficient to support a long-term re-rating.
9. Three Scenarios: How to Understand Rmb9.30, Rmb11.00, and Rmb3.50
For BOE A, scenario analysis should not look only at target prices, but at the worldview behind each price. The base case represents market partial recognition of ROE repair and advanced-packaging probability. The bull case represents full loading of new lines, improvement in product mix, and smooth advanced-packaging validation. The bear case represents weaker supply discipline, softer demand, slower OLED and advanced-packaging progress, and the market pressing it back into a low-P/B cyclical asset.
These three scenarios are not three random multiples, but three industrial paths. For BOE A to reach Rmb11.00, it cannot rely only on higher LCD prices, nor only on glass-substrate press releases. It needs healthy LCD profit, OLED/MLED not dragging, controlled capex, glass-substrate customer qualification progress, and investors believing that 2028E revenue is not one-off trial production. If only half of these are satisfied, Rmb9.30 can be discussed, but Rmb11.00 is hard to sustain.
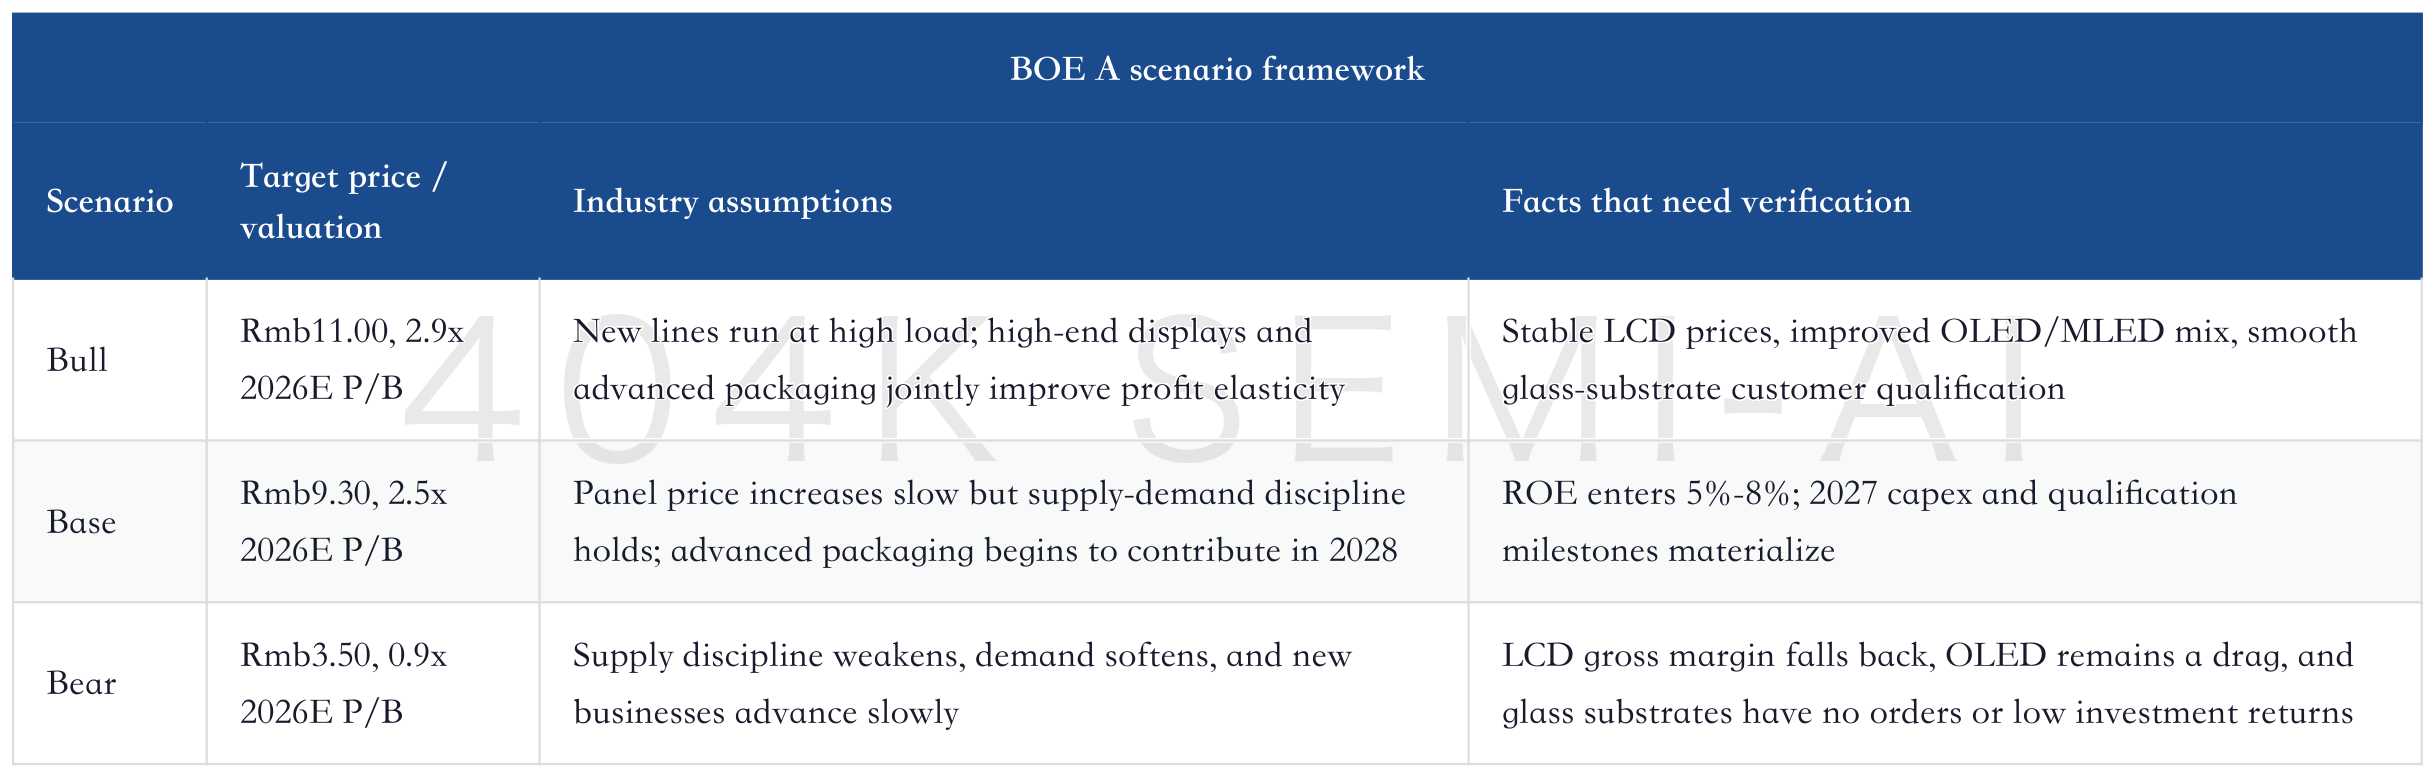
The operational implication of this framework is not to treat BOE A as a single-event trade. Upside requires multiple gears to mesh at the same time: LCD prices cannot be too weak, depreciation and capex need to fall, OLED/MLED need to improve product mix, and glass substrates need to show clear validation. If any gear slips, valuation will be discounted. But as long as old assets are stable and new options keep advancing, the market will be willing to keep assigning a higher P/B.
Investors also need to distinguish "how much is already reflected in the price." The current share price still has room to the base target, but the gap to the bull target does not mean there is no volatility risk, and the bear case also indicates material downside. This risk-reward is not one-way cheap. It is better suited to milestone tracking than to discounting all of the glass-substrate future in one step.
AI PCB Phase 6: capacity-expansion announcements do not equal effective capacity; a full read-through of 2026 equipment orders at Han's CNC, Shenghong Technology, and Shennan Circuits
The lesson from the AI hardware chain is that once the theme moves from "is there demand" to "who can deliver stably," valuations diverge. BOE A is the same. The first re-rating can rely on logic; the second must rely on validation. In coming quarters, if the company keeps releasing customer validation, samples, production-line, and mass-production plans, valuation can move along the option-value path. If only the concept sustains the heat, the share price will return to panel prices and mean P/B.
10. The Most Important Things to Watch Are Not News, but Four Sets of Numbers
Follow-up tracking for BOE A should be as quantitative as possible. The first group is LCD TV panel prices, especially mainstream 32/43/55/65-inch sizes. Prices do not need to keep rising sharply, but they cannot give back gains quickly after 3Q26. If prices fall modestly but remain above the start of the year, industry discipline is still in place. If prices fall back into a vicious-competition range, every re-rating must be discounted.
The second group is display-business gross margin. The model path is 14.1% in 2026E, 15.1% in 2027E, and 15.4% in 2028E. As long as display gross margin moves in this direction, the income statement can support a higher P/B. If gross margin is stuck around 13%, ROE repair will be insufficient. For BOE A, gross margin is more important than revenue growth.
The third group is capex and depreciation. Management's language emphasizes lower depreciation costs, lower capex, and maintaining the current capacity level. If financial reports show capex clearly rising again, and it is not tied to high-return new businesses, the market will question whether cash-flow assetization has been interrupted. If capex declines while profit improves, BOE A will look more like a mature manufacturing cash-flow asset.
The fourth group is glass-substrate validation milestones. These include whether customer validation is disclosed, whether domestic and overseas IC design companies have sample progress, whether TGV and build-up layers form a clear process route, whether the about Rmb5bn investment in 2027 is implemented, and whether the 2028 mass-production target is maintained. News heat is not important; customer qualification and production-line progress are.
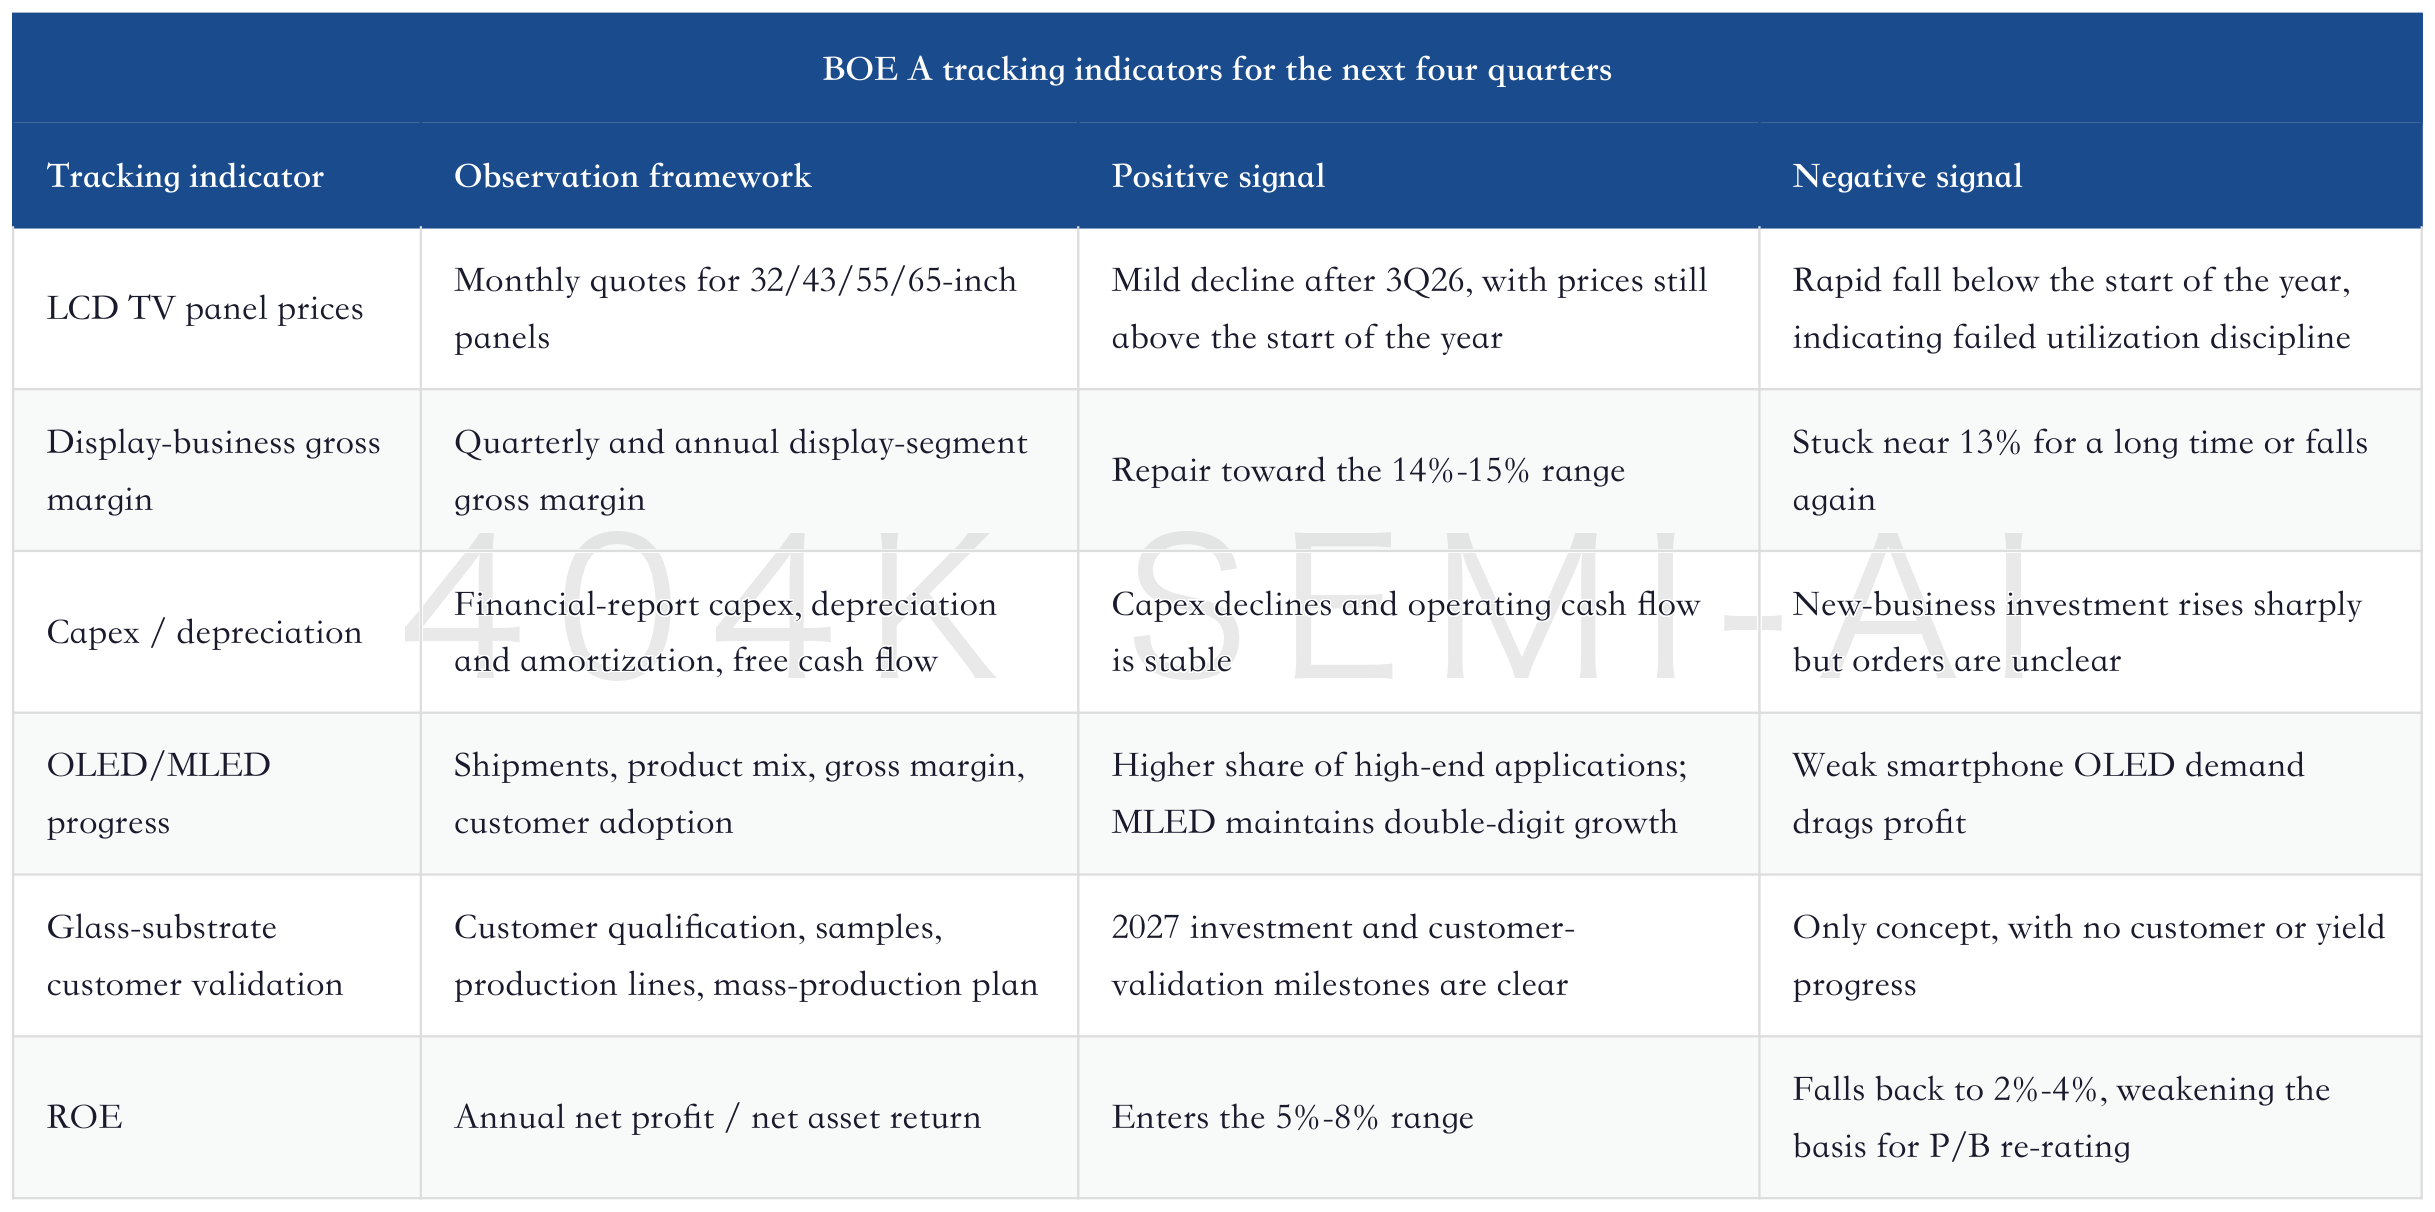
This table also helps distinguish short-term volatility from fundamental disconfirmation. Share-price increases or declines are not evidence; prices, gross margins, capex, and customer validation are. If LCD prices fall modestly but display gross margin continues to improve, one should not simply turn bearish. If there is a lot of glass-substrate news but capex loses control and customer qualification produces no result, one should not simply turn bullish.
11. Main Risk: Valuation Has Moved Ahead of Performance
BOE A's biggest risk is that valuation has already moved ahead of performance. 2.5x 2026E P/B is not a low valuation. It requires joint support from ROE repair and the advanced-packaging option. If 2026 earnings only improve modestly and advanced packaging lacks new validation, the market may conclude that the Rmb9.30 target price has pulled too much future value forward.
The second risk is the LCD price cycle. Sporting events, TV replacement, AI PCs, and Windows 11 replacement can support demand, but these are not unlimited sources of demand. If brands pull in orders early and demand weakens in the second half, or panel makers raise utilization again to seize share, prices will fall before profits. The panel industry's history has repeatedly shown that supply discipline matters more than the demand narrative.
The third risk is the return on investment in OLED and MLED. BOE A must invest in high-end displays, but investment does not equal profit. OLED smartphone panels are affected by smartphone demand, memory costs, customer mix, and competition. MLED has technical prospects, but revenue and gross margin are still ramping. If these businesses continue to consume capital and expenses, the main-business cash-flow improvement will be diluted.
The fourth risk is glass-substrate commercialization. TGV, copper plating, build-up layers, reliability testing, customer qualification, and mass-production yield can all become bottlenecks. Even if the technology is feasible, value allocation may not be ideal. If BOE A only wins low-value-added links, the valuation elasticity of advanced-packaging revenue will be lower than the market imagines. If investment is too large and orders are insufficient, cash flow will be hurt.
The fifth risk is cross-cycle target-price comparison. Rmb9.30 is Morgan Stanley's target price for BOE A in this note. It should not be directly ranked against other institutions' target prices with different dates, models, dividends, or ex-rights frameworks. If later corporate actions, share-capital changes, or report dates cross important events, target prices must be put on a consistent basis before comparison.
There is also a subtler risk: after BOE A is placed simultaneously into the baskets of "AI advanced packaging," "glass substrates," "panel recovery," and "A-share asset re-rating," the funding trade may become crowded. Once any basket fades, the share price may fall first and wait for fundamentals to explain later. For this type of stock, tracking fundamental milestones is more important than chasing concept labels.
12. Sell-side Divergence: One Company, Two Valuation Languages
The most research-worthy aspect of BOE A this time is that different institutions are effectively speaking two valuation languages. Goldman Sachs' March materials maintained a Neutral rating and a 12-month target price of Rmb4.79, based on 2026E EV/EBITDA, while emphasizing the industry cycle, OLED demand, and the fact that valuation had already reflected many positives. Morgan Stanley's June materials gave an Overweight rating, raised the target price from Rmb5.20 to Rmb9.30, based on 2.5x 2026E P/B, and incorporated advanced-packaging glass substrates into the valuation multiple. The difference is not simply who is right or wrong, but a difference in time horizon and asset attributes.
Goldman Sachs is closer to looking at "normalized profit for BOE A as a panel company." It cares whether 2026 sporting events, TV replacement, the end of Windows 10 support, and AI PCs can support demand. It also cares about the weakness in the OLED smartphone market and the impact of rising memory prices on terminal demand. It acknowledges lower depreciation and capex, but the valuation method still revolves around traditional-panel-industry EV/EBITDA. The advantage of this framework is conservatism; it does not discount unrealized new businesses too early. The disadvantage is that it may underestimate changes in the asset boundary.
Morgan Stanley is closer to looking at "the re-rating probability of BOE A as a glass-manufacturing platform." It did not raise the target price because of a near-term earnings upgrade. It actually cut near-term earnings, but lifted the P/B multiple. This shows a willingness to assign part of the option value in advance to advanced-packaging glass substrates and ROE repair. The advantage of this framework is that it captures industry-chain migration. The disadvantage is that if validation milestones do not arrive, the valuation will look premature.
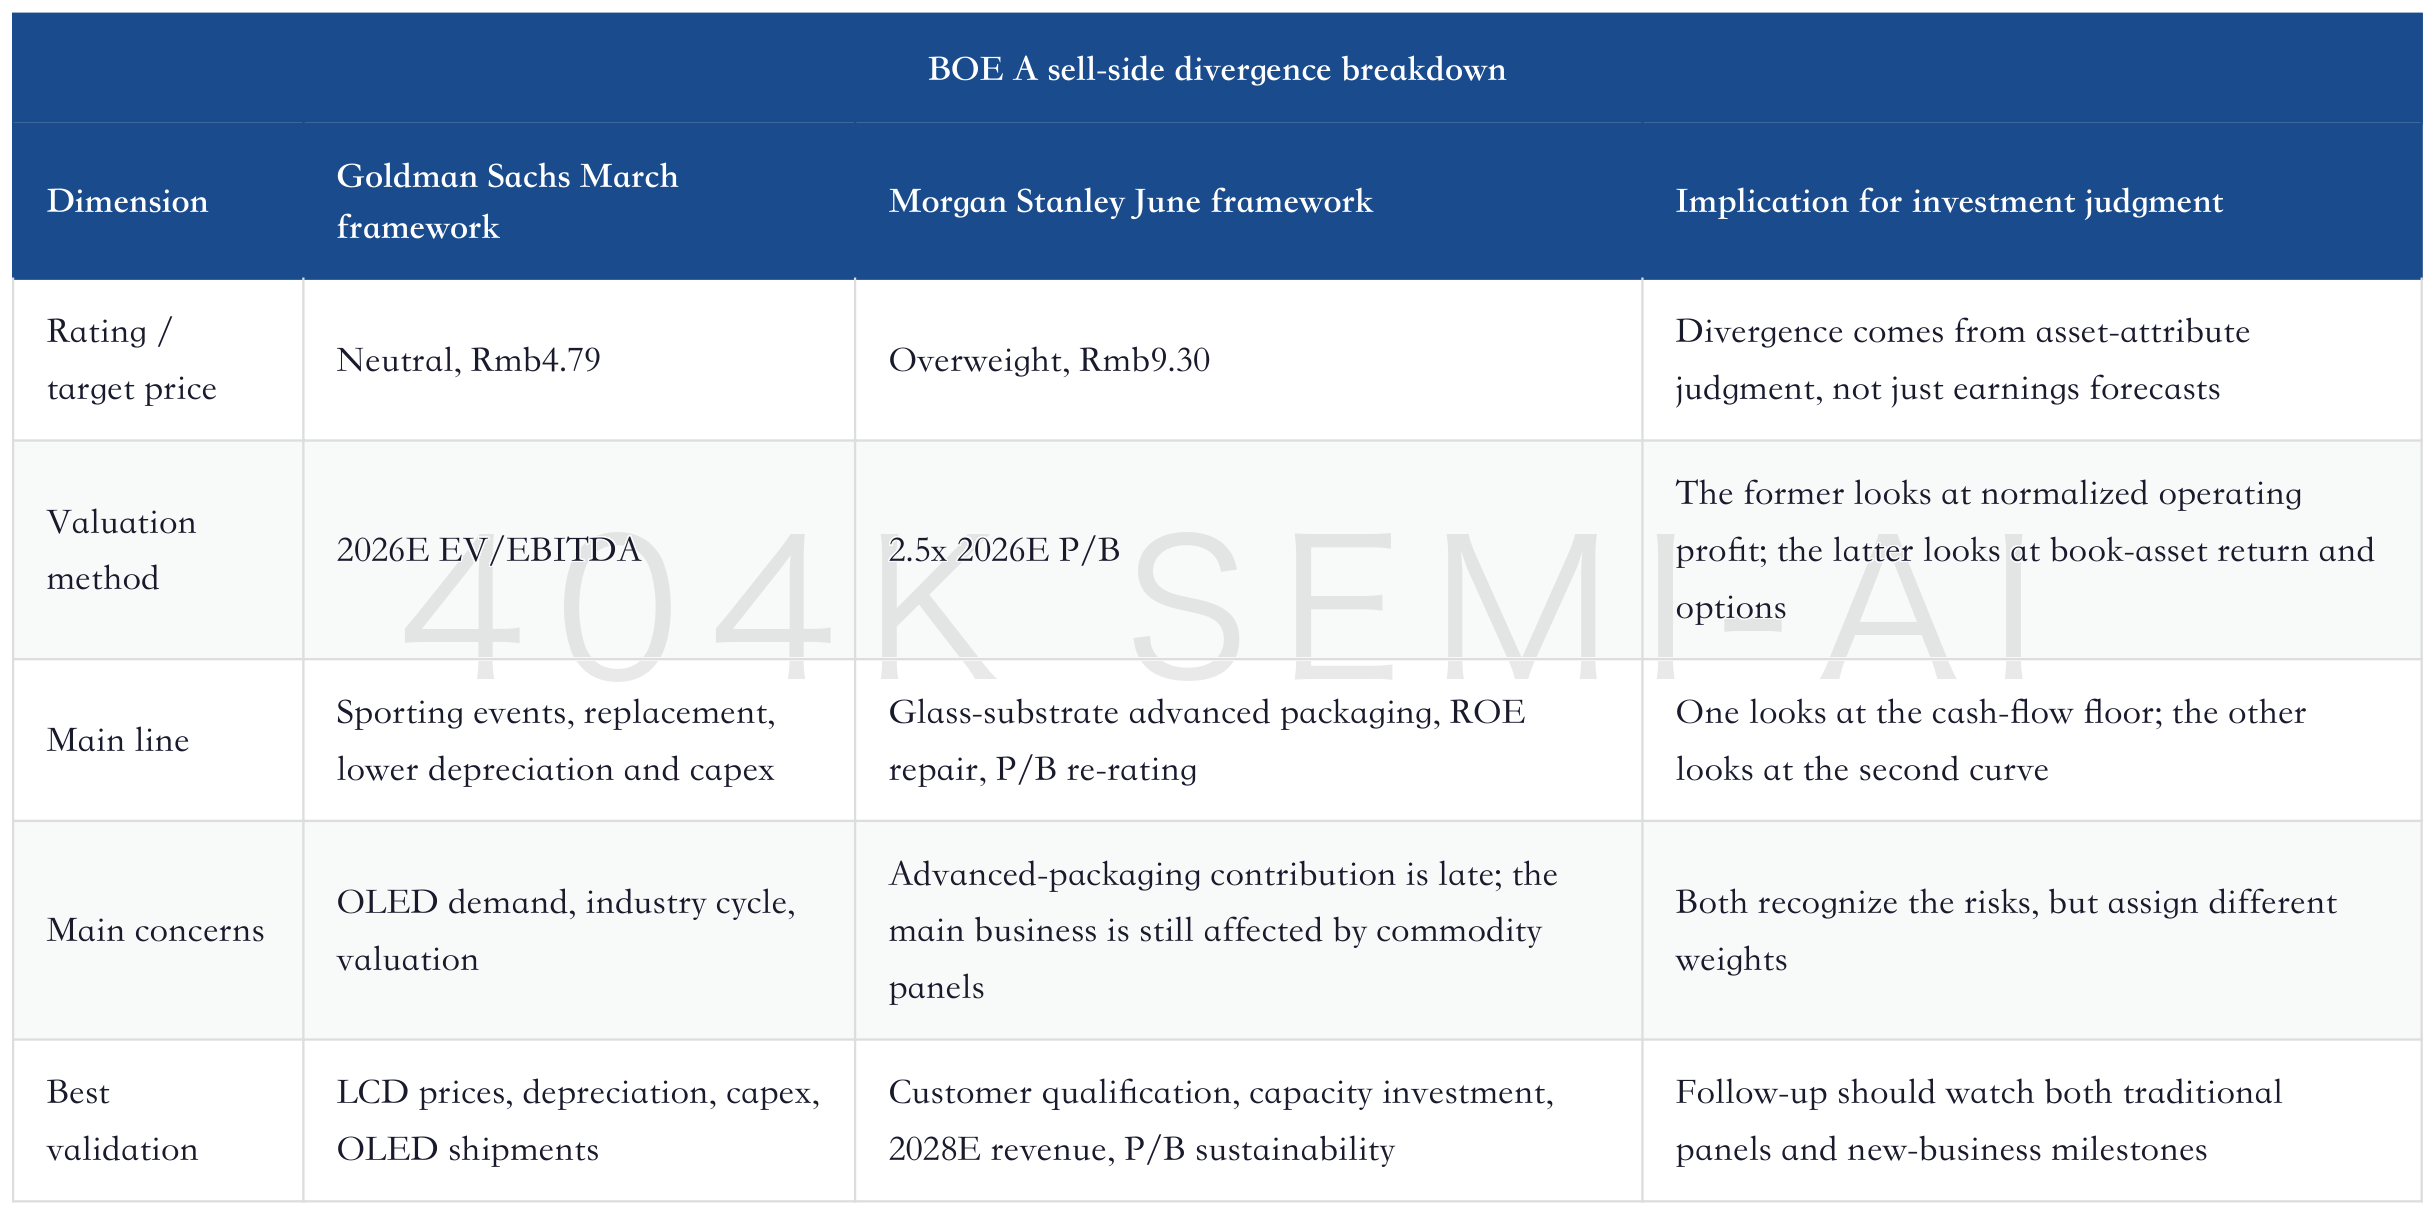
This divergence table is more useful than looking at target prices alone. If the next few quarters bring only improvements in LCD prices and depreciation, without glass-substrate customer validation, the Goldman Sachs framework will be closer to reality, and the stock should be valued on traditional-panel cash-flow repair. If LCD prices stabilize while BOE A discloses real customer validation, production-line investment, and mass-production targets, the Morgan Stanley framework will have more explanatory power, and the P/B multiple will have reasons to remain elevated or even expand.
Investors often make the mistake of treating target prices as static conclusions. Morgan Stanley's target price does not mean "BOE A is definitely worth this number." It is a set of conditions: book value, ROE repair, no deterioration in the panel main business, and progress in the advanced-packaging option. Goldman Sachs' more conservative target price does not mean "the company can only be worth this number." It is another set of conditions: mainly view BOE A as a cyclical panel company and value the traditional business using EV/EBITDA. Real research should not choose sides between target prices, but track which set of conditions is taking place.
This divergence also helps control position sizing and expectations. If the buying reason is only "the target price was raised," it is easy to lose the anchor during share-price volatility. If the buying reason is "the LCD main business provides a cash-flow floor, and glass substrates provide valuation optionality," then two types of data must be checked at the same time: traditional panel data determine whether the position can be held, and new-business milestones determine whether valuation can continue to rise. BOE A is not a single-variable trade. The more it is labeled as AI, the more it needs a multi-variable framework to discipline emotion.
13. Asset History: From Scale Expansion to Efficiency Harvest
For many years, BOE A's core action was to exchange large-scale capex for panel capacity and global share. The financial characteristics of this stage were typical: revenue scale kept expanding, book assets were heavy, depreciation pressure was high, and profit was easily swallowed during industry troughs. The market assigned a low P/B not simply because it disliked the panel industry, but because returns on book assets were not high enough for a long time.
When discussing re-rating now, this history cannot be forgotten. Without past large-scale line investment, BOE A would not have about 35% share in large-size LCD, nor would it have globally leading large-glass manufacturing experience. But because of those investments, the financial statements have long carried a heavy-asset burden. The key to asset re-rating is not to describe past expansion as a mistake, but to see whether these assets are entering a harvest phase.
The harvest phase has three signs. First, incremental capex no longer keeps expanding to capture low-end share, and management's target shifts toward maintaining the current capacity level. Second, profit elasticity from lower depreciation begins to appear, and low revenue growth can also bring operating-margin repair. Third, existing line capabilities can migrate to higher-value applications such as high-end displays, MLED, automotive, and advanced-packaging glass substrates. Only when all three hold can old assets shift from a drag to a base.
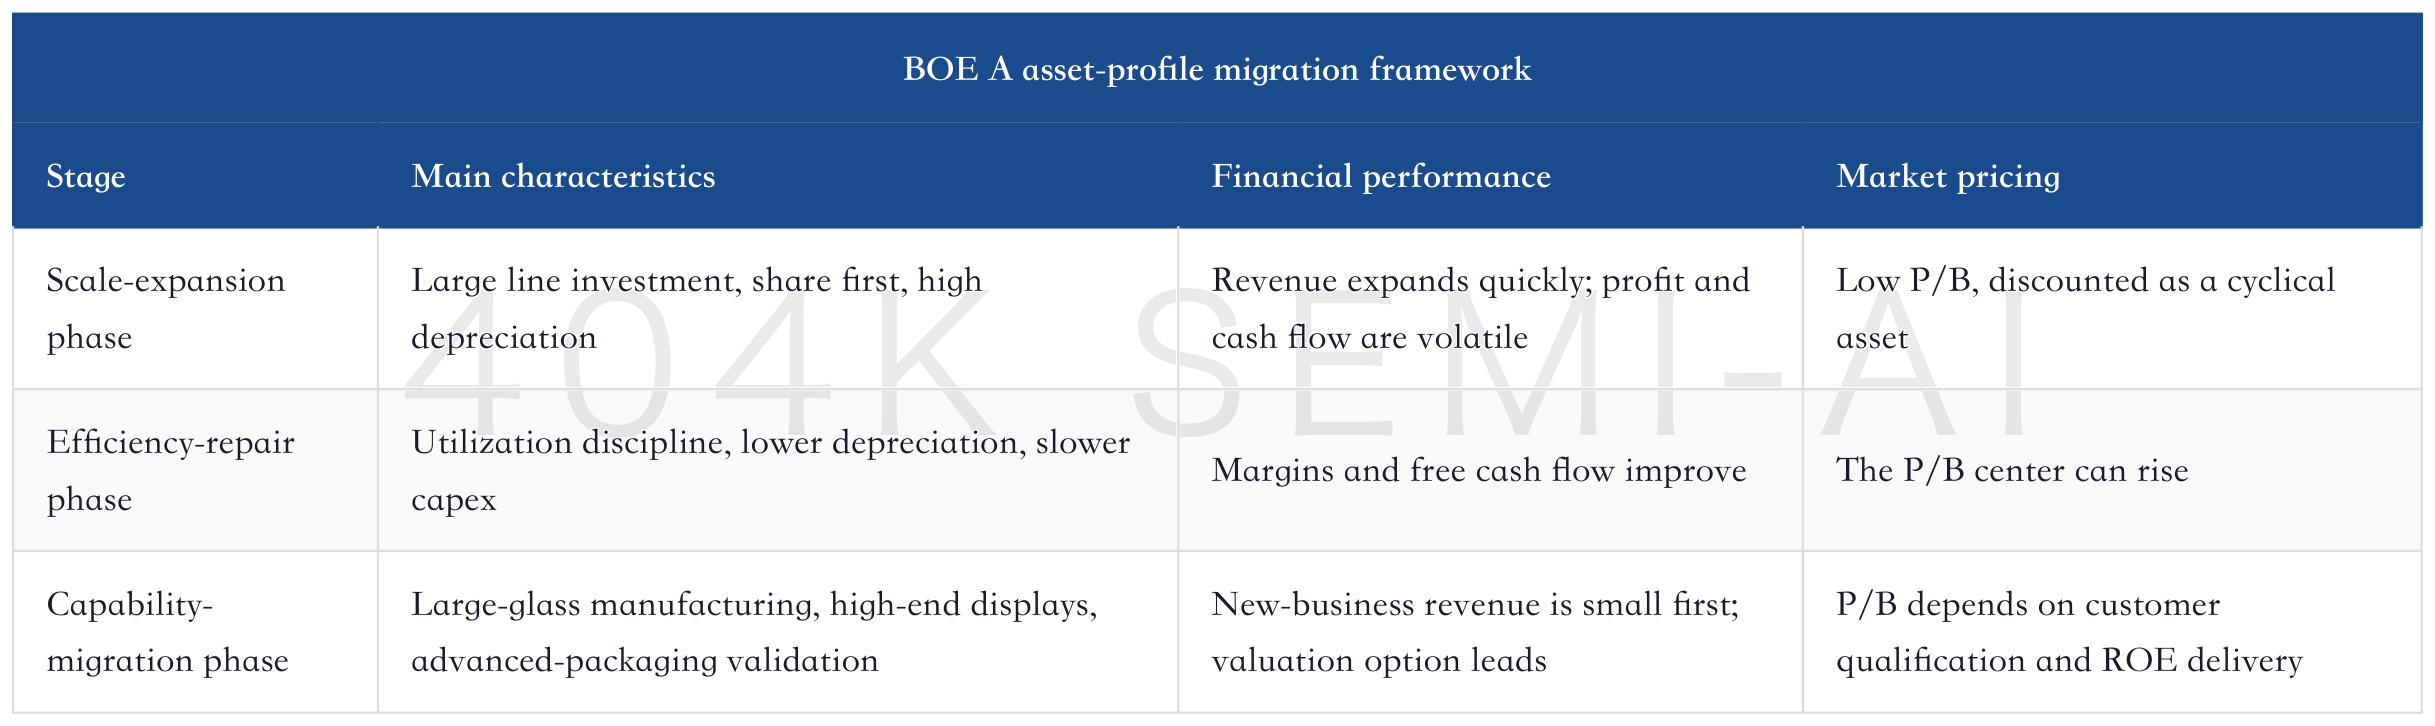
BOE A is now at the transition from the second stage to the third. If it stays only in the second stage, it can still become a better panel cash-flow asset, but the valuation ceiling is limited. If the third stage is validated successfully, it has the chance to be re-understood from "global panel leader" as a "large-area glass manufacturing platform." This platform may not serve only TVs and phones, but also AI packaging, automotive displays, industrial displays, and new interactive devices.
This asset history requires restrained writing. BOE A is not a sudden advanced-packaging upstart. Its advantages come from manufacturing capabilities left by years of heavy-asset investment, and its burden comes from the same heavy-asset base. Investment judgment must recognize both sides: without old assets, there is no glass-substrate option; if old-asset returns do not improve, the option will also be difficult to price for long.
14. Data Framework: Which Numbers Can Be Viewed Precisely, and Which Can Only Be Viewed Probabilistically
The number most easily confused for BOE A is the advanced-packaging revenue share. Morgan Stanley has already modelled glass-substrate advanced packaging, but the model's total-revenue framework shows it remains small in the company's overall revenue. A more rigorous expression is to separate the two: being modelled shows the new business has begun to enter valuation discussion; small size shows it has not yet become the main business. "Already modelled" cannot be interpreted as "already the main business."
Another distinction is between target price and earnings forecasts. The target price comes from P/B re-rating, not recent EPS upgrades. On P/E, BOE A does not look cheap. On P/B, if returns on book assets rise, there is still room to explain the valuation. Different valuation methods create completely different impressions, so the framework must be stated first.
The third distinction is between industry prices and company profit. Mainstream LCD TV panel sizes have risen together since the start of the year, which is an industry price signal. Whether BOE A's display-business gross margin can continue to repair is the company margin signal. Price signals do not necessarily pass fully into margins, because product mix, utilization, depreciation, customer mix, and costs also matter. If prices rise but gross margin does not, transmission is poor. If prices are moderate but gross margin rises, depreciation and mix improvement are working.
The fourth distinction is between lower capex and new-business investment. Management emphasizes a lower future capex burden, but if advanced-packaging glass substrates receive about Rmb5bn of investment in 2027, there will be localized new capex. The two do not necessarily conflict: the company can stop large expansions of traditional LCD lines while making targeted investment in new businesses. The key is whether investment returns are clear. Not all new capex should be treated as bad, and not all new-business investment should be treated as good.
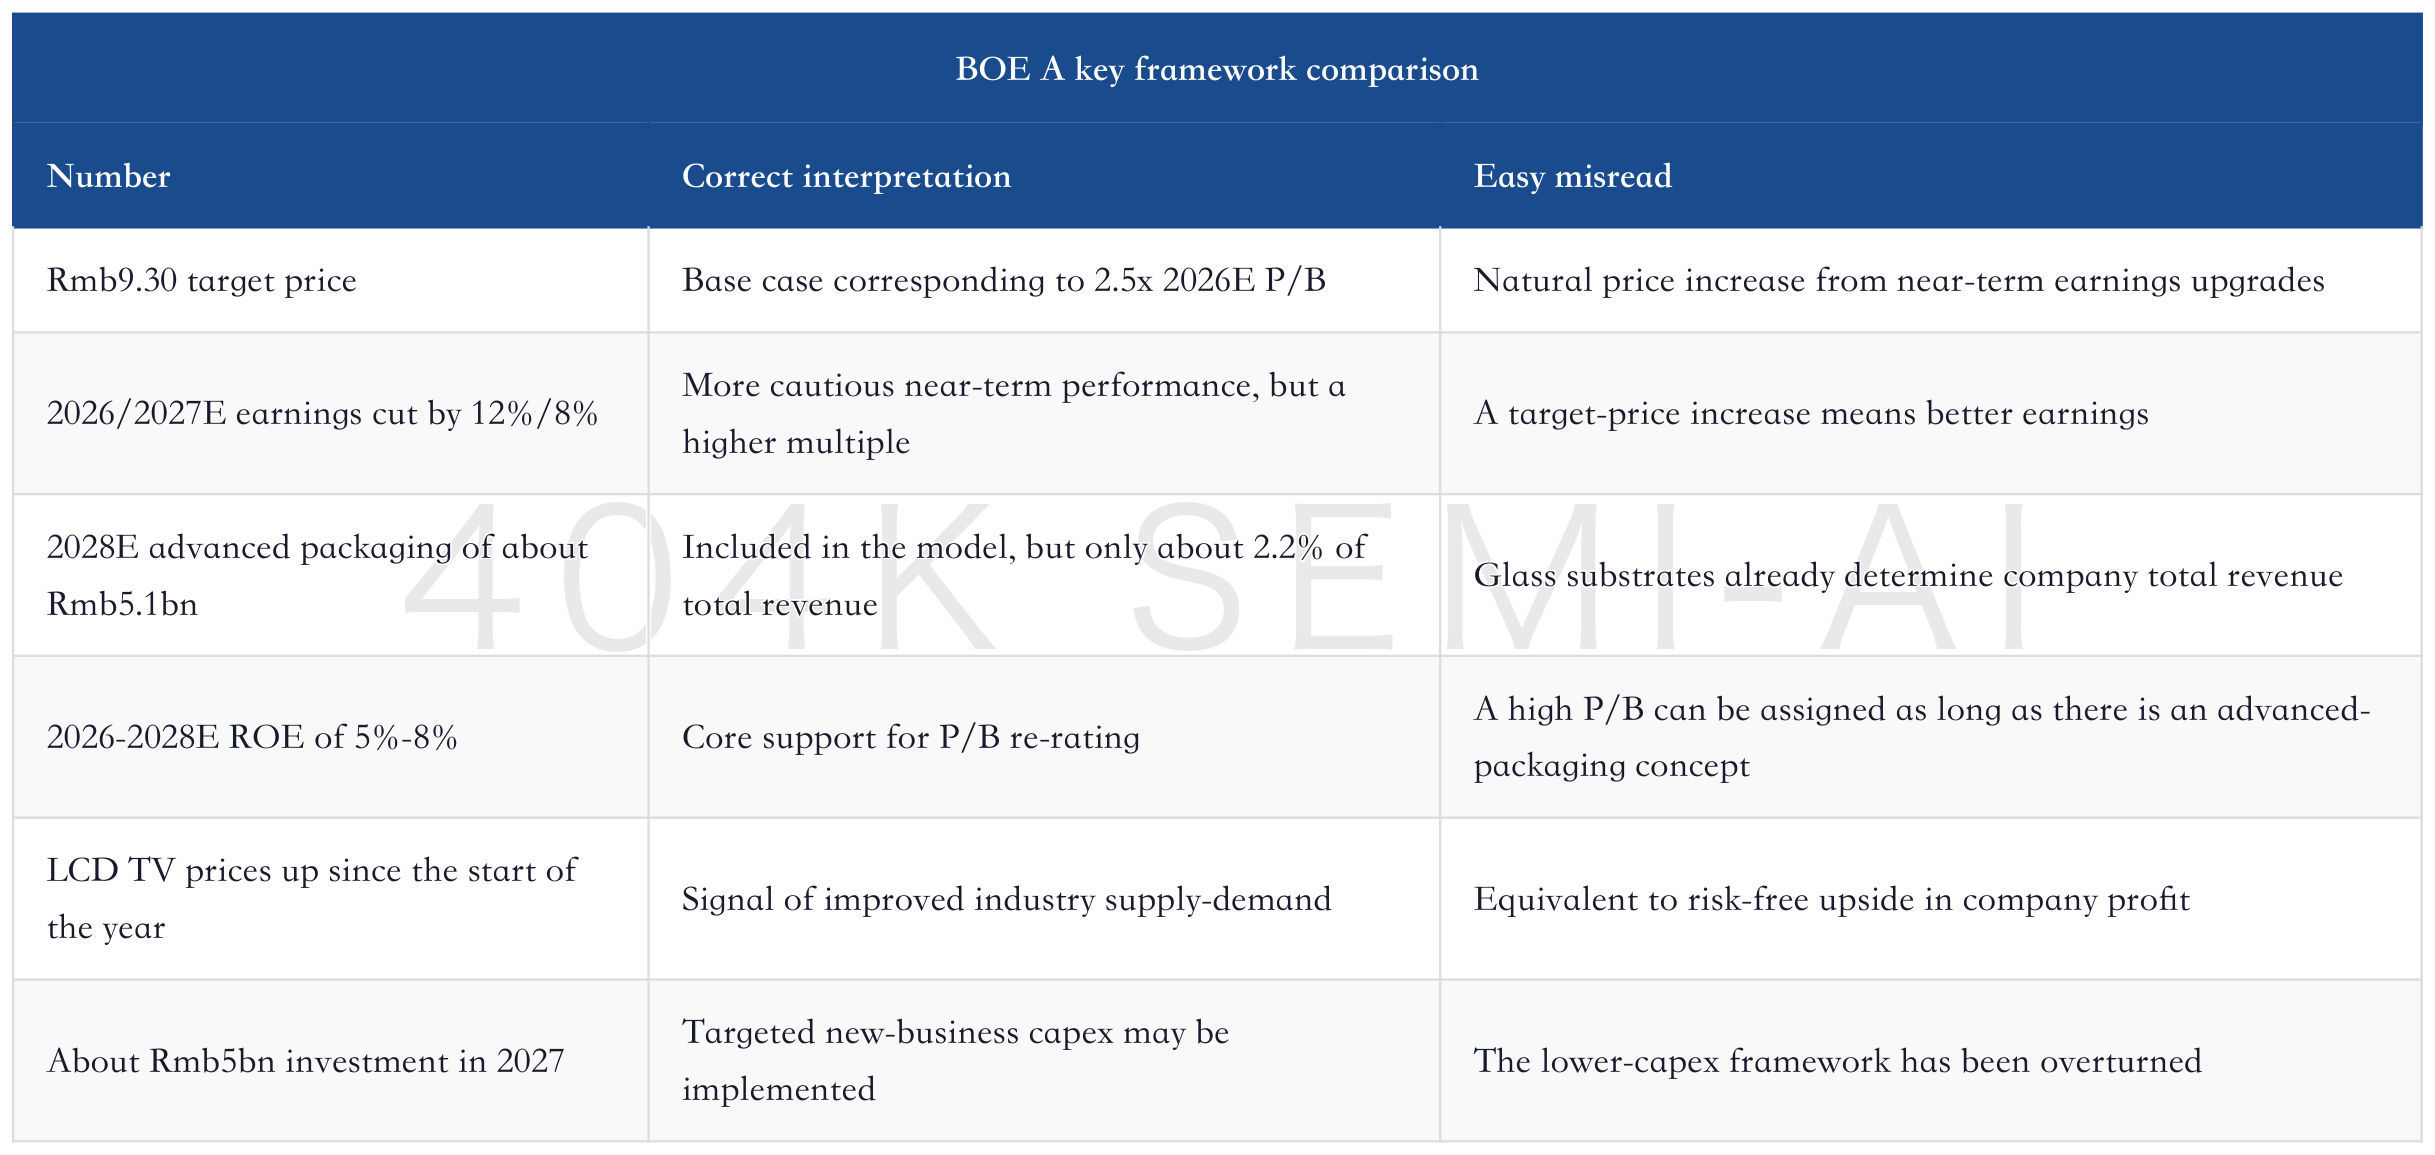
Once the data framework is clear, BOE A's investment judgment becomes steadier. One can acknowledge that advanced packaging provides valuation elasticity, while also acknowledging that revenue contribution before 2028 is limited. One can acknowledge that P/B re-rating is reasonable, while also acknowledging that it requires ROE delivery. One can acknowledge LCD price improvement, while still waiting for the company's gross-margin validation. Seen this way, BOE A is not a simple long or short, but an asset whose probabilities need to be calibrated continuously through time milestones.
15. Trading Cadence: First Look at the Panel Floor, Then at Glass-Substrate Realization
BOE A's cadence cannot be arranged around a single event. It has a traditional-panel path and an advanced-packaging path. The traditional-panel path determines "whether there is a floor when it falls," while the advanced-packaging path determines "whether there is room when it rises." Looking only at the former misses re-rating elasticity; looking only at the latter ignores the real constraints of the income statement and cash flow.
The first stage is to watch panel prices and margins from 1H26 to 3Q26. Pull-in demand from the World Cup, TV replacement, AI PCs, and the Windows 11 replacement cycle has already been partly reflected in panel prices at the start of the year. The key is not whether prices keep rising sharply, but whether they can fall mildly after 3Q26 rather than weakening quickly. If prices consolidate at high levels and BOE A's display gross margin realizes from 12.9% in 2025E toward 14.1% in 2026E, the market will be more willing to believe in the cash-flow base.
The second stage is to watch capex and depreciation. Management has already pointed to lower depreciation and slower capex, and subsequent financial reports need to prove this is not just verbal guidance. If capex intensity declines, operating cash flow remains stable, and net margin repairs from 2.9% toward 3.5%, BOE A will look more like a mature manufacturing asset, rather than a cyclical stock that earns only from price swings.
The third stage is to watch OLED/MLED and the high-end display mix. This stage will not immediately determine the valuation ceiling, but it will determine valuation quality. If MLED revenue continues to maintain double-digit growth, OLED improves in high-end customers and yield, and high-end displays gradually raise revenue quality, the market will believe BOE A's old manufacturing capability is migrating to higher-value applications. If these businesses remain low-profit and low-visibility, BOE A will still be forcibly pulled back into the LCD framework.
The fourth stage is to watch glass-substrate capex and customer qualification in 2027. Morgan Stanley's potential plan is about Rmb5bn of investment in 2027, monthly capacity of 15,000 510mm x 515mm substrates, and mass production in 2028. Validation of this line cannot rely only on announcements. It must look at who the customers are, what step validation has reached, how reliability testing is progressing, and how deep BOE A's value-chain role is. If only production-line investment is disclosed without customer qualification, the market will instead worry about rising capex.
The fifth stage is to watch revenue and yield in 2028. The about Rmb5.1bn of advanced-packaging revenue in 2028E is not a high share of total revenue, but it is highly meaningful for valuation. If it is revenue with customers, yield, and a replicable route, the market will view it as the starting point of a second curve. If it is only small-scale trial production or low-margin processing, option value will be revised down. The quality of advanced-packaging revenue matters more than the amount.
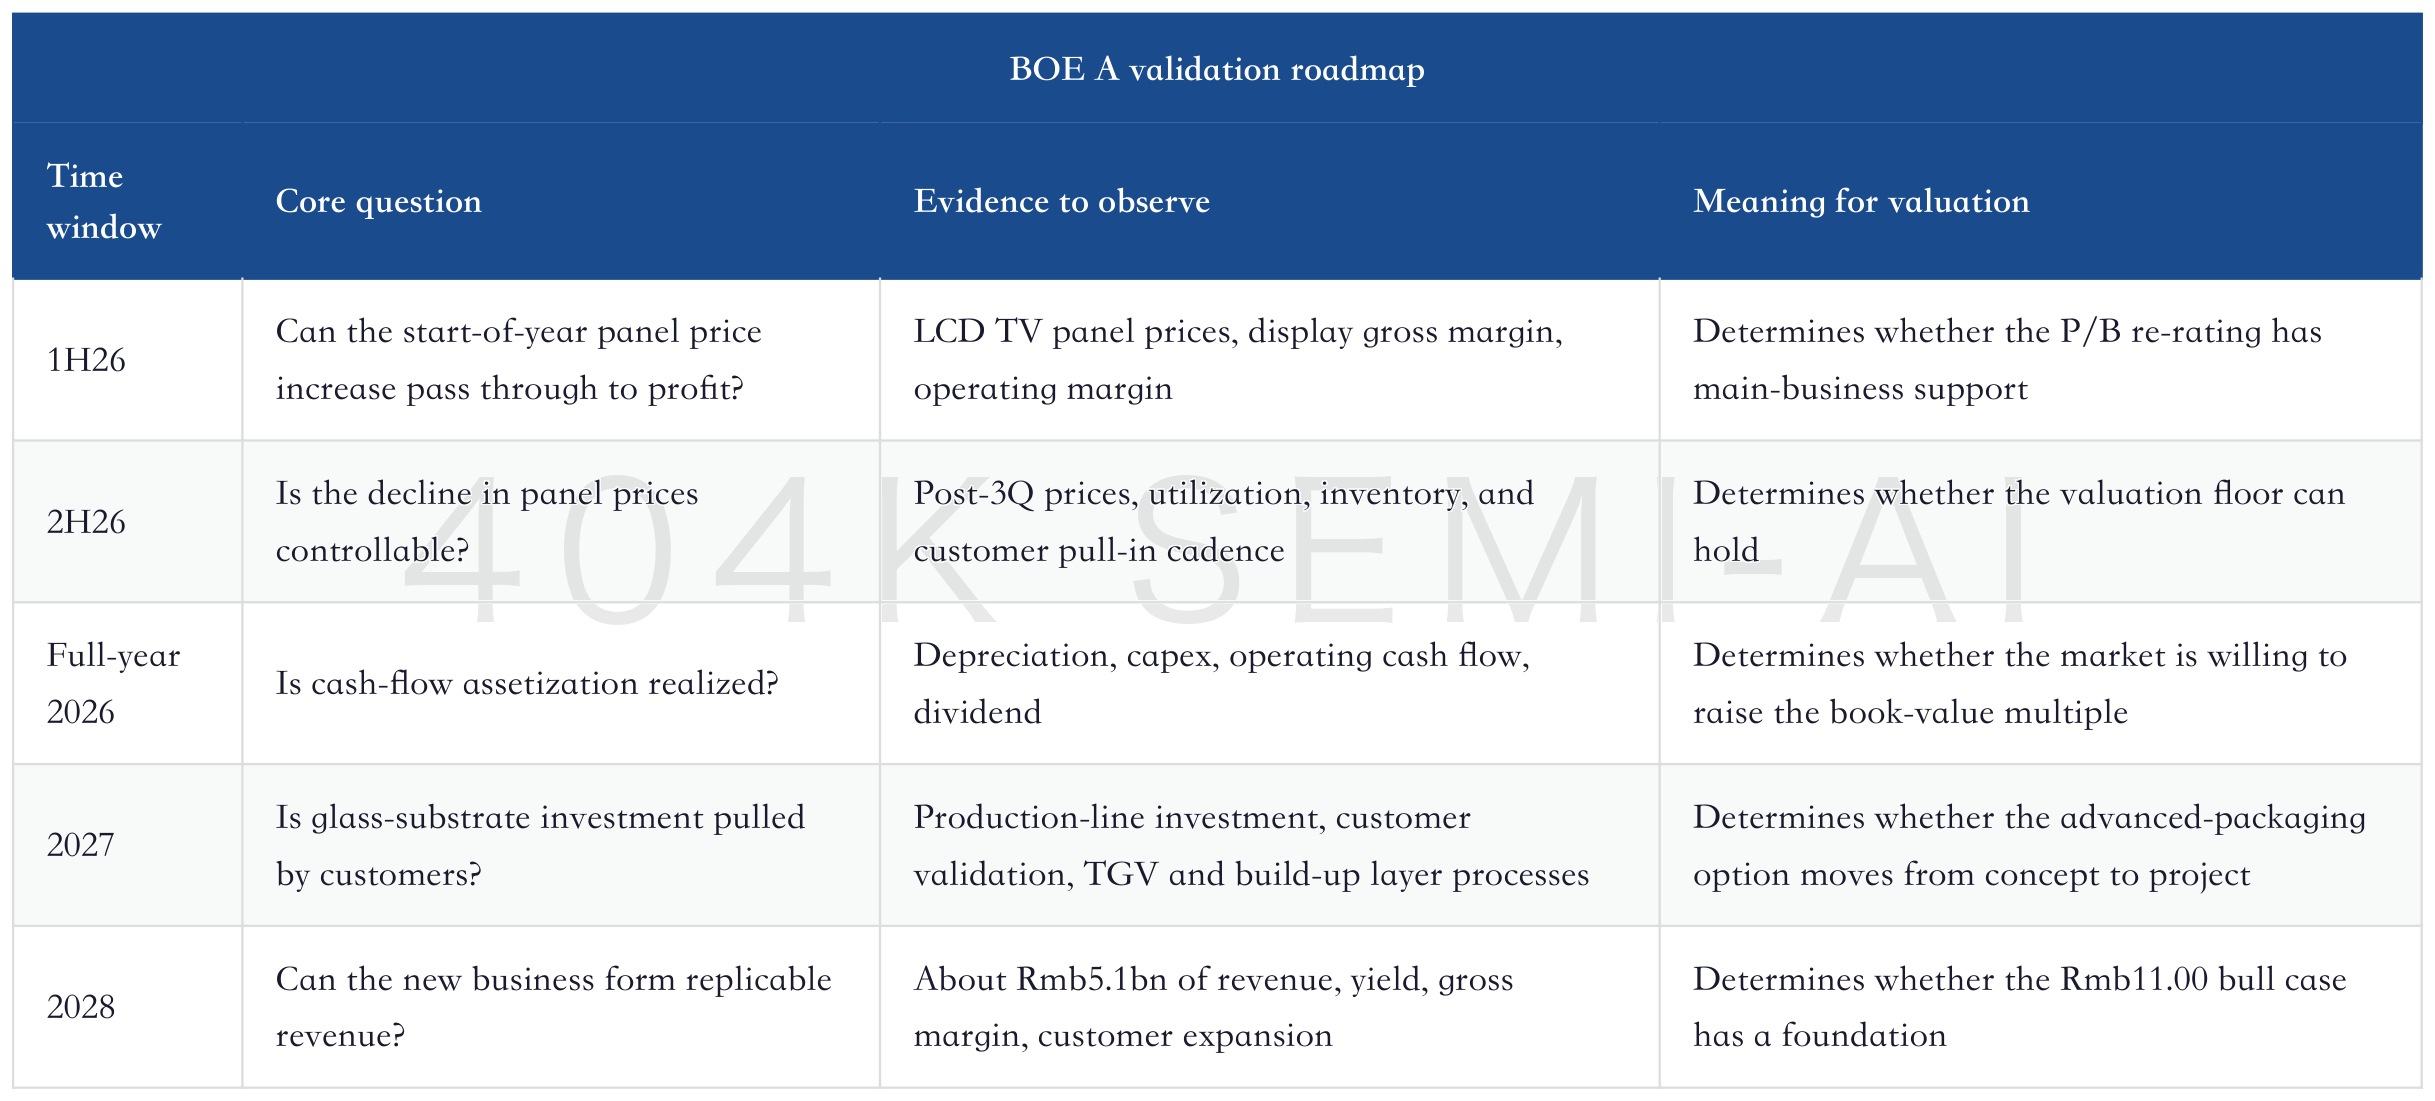
This roadmap gives a judgment sequence, not a trading instruction. Confirm the main-business floor first, then cash flow, then new business. If the order is reversed, investors can easily be led by the advanced-packaging story and still overvalue the option when the panel main business weakens. BOE A's advantage is that it has a real main business that can be checked. Its disadvantage is also that it has a real main business: once main-business data do not cooperate, the story has little cover.
Another cadence issue is the order of share price and fundamentals. The market usually trades the concept first and waits for data later. Glass substrate is a typical "valuation first, revenue later" asset: before customer validation, the share price may already assign probability; before revenue recognition, valuation may already fluctuate through several rounds. For this type of asset, position management cannot look only at long-term upside, but also at short-term validation density. If there are no new milestones over the next one to two quarters, the share price will need to rely more on LCD prices and financial-report performance.
From an industry perspective, BOE A's window is not unlimited. If the glass-substrate route is established, packaging houses, substrate makers, material makers, equipment makers, and panel makers will all compete for positions. Innolux already has relatively high visibility, and traditional substrate makers will not stand still. The earlier BOE A produces customer validation, the easier it is to prove that it is not a follower. If validation remains vague until after 2028, valuation optionality will be diluted by competition and uncertainty.
So BOE A's best current state is "the main business is not bad, and the new business is progressing." The worst state is not "glass substrates have no revenue yet," but "LCD prices weaken, capex rises, and the new business still has no customers." The former is simply option waiting; the latter damages both the base and the elasticity. All follow-up tracking should judge around these two states.
16. Conclusion: BOE A Has Begun to Have a Second Valuation Language
BOE A used to have only one valuation language: panel prices rise, earnings repair, P/B goes up; panel prices fall, earnings retrace, P/B goes down. This language has not failed, and it will still determine the share-price base over the next 12 months. But there is now a second valuation language: when depreciation on old lines declines, capex slows, industry supply discipline improves, and glass-substrate advanced packaging provides the probability of a second curve, the market can begin to value the company by asset efficiency and manufacturing-capability migration.
This is what the Rmb9.30 target price means. It does not say BOE A has already become an advanced-packaging company, nor does it say 2026 performance will explode. It says that if the company can turn its display-panel main business from a cyclical volatility asset into a more stable cash-flow base, while migrating large-glass manufacturing capability into advanced-packaging glass-core substrates, BOE A's reasonable P/B center can be higher than in recent years.
The most important judgment is that BOE A deserves to be researched again, but it cannot be oversimplified into a glass-substrate concept. Its core is still the panel main business, cash-flow improvement is the bridge, and glass substrate is the option. If the bridge is not stable, the option can easily become a bubble; once the bridge is stable, the option has capital-market value.
For investors, the more reasonable posture is not to ask "is BOE A an AI stock," but to ask four more basic questions: can LCD prices and gross margin hold, can depreciation and capex continue to decline, can OLED/MLED improve asset quality, and can glass substrates deliver customer validation and mass-production milestones. If the first two are true, the valuation floor is more stable. If the latter two continue to materialize, the market can discuss Rmb11.00 after Rmb9.30.
China Jushi deep dive: re-rating the electronic glass-fiber supply bottleneck, and how the glass-fiber leader can shift from cyclical stock to AI PCB materials asset
The re-rating of cyclical assets is never completed by changing a label. China Jushi's electronic glass fiber, PCB materials' T-glass, OSATs' advanced packaging, and BOE A's glass substrates are all essentially answering the same question: have old assets obtained higher-quality demand, stronger pricing power, and more stable capital returns because of new bottlenecks in AI hardware? If the answer is yes, valuation can be rewritten. If the answer is merely conceptual mapping, valuation will eventually return to the old cycle.
BOE A now stands on this dividing line. The main business already has clues of healthier supply-demand and cash-flow improvement, and glass substrates provide a direction for manufacturing-capability migration, but commercialization has not reached a stage where skepticism is no longer needed. The most restrained and most useful conclusion is this: BOE A should no longer be priced crudely only as a traditional LCD cyclical stock, but it has not yet completed the identity shift from display-panel leader to advanced-packaging asset. Over the next four quarters, it needs to turn this re-rating from story into numbers through prices, gross margin, cash flow, and customer validation.BOE A Deep Dive: Morgan Stanley Raises Target to Rmb9.30, Re-rating Logic from Display-Panel Cycle Leader to Glass-Substrate Option
目录
TL;DR
1. Why BOE A Was Suddenly Re-rated
2. What Exactly Is Being Adjusted in the Rmb9.30 Target Price
3. The Old Assets Have Not Disappeared: The LCD Cycle Still Determines the Base
4. Turning Cash Flow into an Asset: Why Depreciation and Capex Matter
5. OLED and MLED: Not the Main Line, but They Determine Valuation Quality
6. Glass-Substrate Advanced Packaging: Why the Market Is Willing to Price the Option
7. Model Breakdown: Low Revenue Growth, High Profit Elasticity
8. Compared with Other Parts of the Industry Chain, What Is BOE A Betting On?
9. Three Scenarios: How to Understand Rmb9.30, Rmb11.00, and Rmb3.50
10. The Most Important Things to Watch Are Not News, but Four Sets of Numbers
11. Main Risk: Valuation Has Moved Ahead of Performance
12. Sell-side Divergence: One Company, Two Valuation Languages
13. Asset History: From Scale Expansion to Efficiency Harvest
14. Data Framework: Which Numbers Can Be Viewed Precisely, and Which Can Only Be Viewed Probabilistically
15. Trading Cadence: First Look at the Panel Floor, Then at Glass-Substrate Realization
16. Conclusion: BOE A Has Begun to Have a Second Valuation Language
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
BOE A is being repriced not because near-term earnings have suddenly broken out, but because the market is starting to view it not as a single-cycle panel stock, but as an asset combining better cash flow, OLED repair, and an advanced-packaging glass-substrate option. The key question is how much of the Rmb9.30 target price comes from visibility, and how much from still-unrealized optionality.
TL;DR
This is not an earnings-upgrade story. Morgan Stanley raised BOE A’s target price by nearly 80% while cutting its 2026E/2027E earnings forecasts. The real change is that the P/B multiple nearly doubled. In other words, the near-term income statement did not suddenly improve; the market is willing to pay a higher price because the asset profile has expanded from “LCD cycle” to “cash-flow improvement + advanced-packaging option.”
The panel business remains the base. BOE A’s 2028E display revenue is still around Rmb177.1bn, or 76.3% of modelled total revenue. Even if advanced-packaging glass substrates reach about Rmb5.1bn of revenue in 2028E under Morgan Stanley’s model, they would account for only about 2.2% of total revenue. The share price can trade the glass-substrate beta, but fundamentals are still determined by LCD prices, capacity discipline, TV size migration, OLED yield, and depreciation cadence.
The re-rating lever is P/B, not P/E. Morgan Stanley sets its Rmb9.30 target price using 2.5x 2026E P/B, implying 2026E BVPS of about Rmb3.73, and cites 2026-2028E ROE of 5%-8% as support. This framework fits panel stocks better than P/E because BOE A’s profit elasticity comes from balance-sheet utilization, lower depreciation, and supply discipline, not a single year’s EPS.
Glass substrate is an option, not 2026 earnings. BOE A plans to build more complete glass-core substrate manufacturing from TGV glass cores to build-up layers. It may invest about Rmb5bn in 2027 to build monthly capacity of 15,000 510mm x 515mm substrates, with mass production targeted for 2028. This direction raises valuation imagination, but verification must at least track IC-design customer qualification, TGV yield, copper plating, warpage control, and coordination with packaging houses.
Cash-flow improvement makes the option more credible. Goldman Sachs’ March materials show management emphasizing a future decline in depreciation and capex burden, with panel makers maintaining existing capacity and flexibly adjusting utilization, leading to healthier industry supply-demand. If LCD prices do not lose control again, BOE A can convert lower depreciation on older lines into profit and cash flow, while using lower capital intensity to place bets on MLED, OLED, and advanced packaging.
The disconfirmation points are specific. If TV-panel prices fall materially after 3Q26, OLED smartphone demand remains weak, advanced-packaging customer qualification stalls, or glass-substrate investment turns into high capex without orders, then 2.5x P/B will look too expensive. The four most important metrics to track are LCD TV panel prices, display-business gross margin, capex intensity, and glass-substrate customer validation milestones.
1. Why BOE A Was Suddenly Re-rated
This round of BOE A’s re-rating is easy to misread as “glass-substrate concept speculation.” That is only half right. The market is indeed trading new terms such as glass-core substrates, TGV, and panel-level packaging, but the move in the target price from Rmb5.20 to Rmb9.30 is not based on higher 2026 profit. It is based on a wider set of assets that can be discussed for the company.
Morgan Stanley’s numbers are very direct: near-term earnings forecasts were cut, yet the target price was raised sharply. If this were a normal earnings upgrade, the target-price increase should come from higher EPS. That is not the case. The valuation method has shifted from the low P/B framework traditionally used for panel stocks to a higher book-value multiple. The core variable has become “whether book assets can earn a higher ROE, and whether this company can move from panel manufacturing capability into advanced-packaging manufacturing capability.”
This distinction matters. The label BOE A has historically found hardest to escape is the LCD supply cycle. When the industry expands capacity, prices fall; when prices fall, earnings retrace; when earnings retrace, P/B valuation is pushed back to the low end. Two lines are now changing this narrative at the same time. The first is that older panel lines are entering a phase of lower depreciation and lower capex, while leading industry players are paying more attention to utilization discipline. The second is that AI compute packaging is turning glass substrates from an edge technology in the display industry into an underlying manufacturing capability that may participate in advanced packaging.
With these two lines layered together, BOE A’s pricing question is no longer just “how many dollars will TV panels rise this year.” It becomes three more fundamental questions: whether the profit floor of older LCD assets has been lifted, whether new display businesses such as OLED and MLED can stop consuming profit, and whether glass-substrate advanced packaging can open a second growth curve for the company.
This judgment should not be too aggressive. Morgan Stanley’s text also acknowledges that revenue and profit contribution are more likely to appear only from 2028. In 2026/2027, commodity panels will still be the main driver. At present, 70%-80% of BOE A’s revenue still comes from commodity panels, and 2028E display revenue still accounts for 76.3% in the model. So this is not “panels no longer matter”; it is “when the panel base does not collapse, new options can be priced by the market.”
Glass substrates are not a materials story, but a process-integration battle
The core of BOE A’s re-rating is not a single technology point, but the migration of process capability. Display-panel companies’ historical advantages lie in large-area glass, thin-film deposition, lithography, yield ramping, cleanroom management, and large-scale manufacturing. Glass-core substrates in advanced packaging look like semiconductor-packaging materials, but they also test large glass panel handling, via formation, metallization, warpage, and interlayer structure control. Panel makers are not natural winners, but they at least have some transferable manufacturing muscle.
What truly deserves study at BOE A is that it does not want only to supply a glass core sheet, but to complete full glass-core substrate manufacturing, including the TGV glass core and build-up layers. That ambition is larger than simple slicing, drilling, or supplying materials, and it is also harder. If it succeeds, the company receives not low-value-added processing fees, but a key part of the value chain in advanced-packaging carriers. If it fails, the investment again becomes capex pressure.
2. What Exactly Is Being Adjusted in the Rmb9.30 Target Price
The most important part of this target-price change is the valuation bridge. The base, bull, and bear cases correspond to three different P/B worldviews: how much book-value multiple the recovery of the main business can support, how much probability should be assigned to the glass-substrate option, and whether industry supply discipline will lose control again in the bear case. The numbers themselves are not complicated. What is complicated is why the same company can suddenly move from being discussed at a low multiple for a traditional panel stock to a higher P/B.
The answer lies in ROE and the asset narrative. Morgan Stanley’s base case prices BOE A into a higher ROE range instead of continuing to use the P/B center of the low-return years of the past. In other words, the logic behind the target-price increase is not “one-off profit jump,” but “book assets are entering a higher-return range, and the market can assign a higher book-value multiple.”
This type of valuation method is more reasonable for panel stocks. One-year P/E in the panel industry is often distorted: at cycle bottoms, profit is low and P/E looks high; at cycle peaks, profit is high and P/E looks low. What truly cuts through the cycle is asset utilization, depreciation cycle, capex discipline, supply structure, and ROE. If BOE A remains a high-capex, low-ROE panel company with severe price competition, P/B will struggle to rise for long. If it becomes an asset with lower depreciation, lower incremental capex, stable cash flow, and an advanced-packaging option, the P/B center has room to move up.
This table has a counterintuitive conclusion: if one looks only at the 2026E earnings cut, the stock should not become more expensive; if one looks at the P/B re-rating, it can. What investors really need to judge is whether the target multiple has enough asset-return support. If ROE can only stay at historical lows, high P/B is dangerous. If ROE repairs steadily while glass-substrate orders provide additional upside probability, high P/B is not just a concept trade.
The comparison between BOE A and Taiwanese panel makers also illustrates the point. In Morgan Stanley’s Greater China display coverage, the ranking is BOE A, Innolux, and AUO. Innolux has stronger visibility in glass-core substrate projects, but its valuation has expanded further from levels near its peak of the past decade. AUO has LEO satellite and optical-module stories, but visibility for advanced-packaging contribution is lower. BOE A is distinctive because it has the largest main-business scale, valuation has rebounded but remains below the historical peak of 2.7x P/B, and the glass-substrate option has not yet been fully priced.
“Below the historical peak” should not be simplistically interpreted as cheap. The historical peak corresponded to a different cycle, different profit elasticity, and different market sentiment. A more prudent formulation is that BOE A’s valuation has not, like Innolux’s, fully capitalized advanced-packaging imagination in one step, leaving room for gradual realization through fundamental validation. Its risk-reward comes from “a relatively stable panel base + a new business not yet fully reflected,” not from absolute undervaluation.
ABF substrates deep dive: the foundation of AI compute packaging, from entry framework to supply-demand and company ranking
Why can advanced packaging change the valuation of panel stocks? Because the bottleneck in AI compute is spreading from a single chip to connectivity between chips, packages, and substrates. GPU, HBM, ASIC, optical interconnect, advanced packaging, substrates, and materials are no longer isolated links. Thermal performance, warpage, signal loss, line/space, and manufacturable area of substrates all affect system-level compute cost. Glass substrates have entered the discussion because they may replace part of the bottleneck in organic materials through larger size, lower signal loss, lower warpage, and better dimensional stability.
BOE A’s value does not lie in the statement “it also does AI.” That is too crude. A more precise investment language is this: if AI packaging continues from silicon interposers and ABF substrates toward larger area, higher I/O, more layers, and lower warpage, glass-core substrates will become a potential route; as the world’s largest panel manufacturer, BOE A has some large-glass manufacturing and clean-process experience, and therefore holds an option to enter this route. An option can support valuation, but it cannot replace orders.
3. The Old Assets Have Not Disappeared: The LCD Cycle Still Determines the Base
BOE A’s first principle remains panels. In the model, total revenue rises only modestly. Although the share of the display business gradually declines, it is still the absolute majority by 2028E. If LCD prices fall sharply, the glass-substrate story will struggle to support valuation independently. Only if the display business stabilizes can the cash-flow base support the advanced-packaging option.
The good news is that the LCD supply-demand environment is healthier than in recent years. Goldman Sachs’ February display-panel monthly report shows that prices for 32/43/55/65-inch LCD TV panels had risen 6%/3%/2%/2% since the start of 2026, reaching US$36/65/124/172. Although these prices remain far below their July 2021 peaks, the direction implies repair in industry demand and supply. More importantly, leading panel makers have learned to adjust utilization according to demand rather than expanding output without discipline.
BOE A also still has a dominant share position. Goldman Sachs materials show the company holds global leadership in large-size LCD, small/mid-size LCD, and LCD TV panels, with LCD TV panel share also rising year on year. For a heavy-asset manufacturer, share itself is not a profit guarantee. But share combined with industry concentration and utilization discipline can improve the stability of the price floor.
The key to the LCD business is not rapid growth, but “stop destroying value.” The most damaging part of the panel industry in the past was that every time the cycle improved, capacity expanded and all manufacturers ultimately pushed prices down together. Leading makers now emphasize capacity control more, while larger TV sizes, sporting events, AI PCs, gaming monitors, and the Windows 11 replacement cycle all support 2026 demand. Demand is not exploding, but when supply is no longer expanding blindly, modest demand improvement can still feed into prices and gross margin.
This is also what separates BOE A from ordinary concept stocks. Glass substrates have not yet contributed profit, but LCD is already contributing revenue, share, and cash flow. As long as industry supply-demand does not deteriorate again, old assets can support the valuation floor. As long as depreciation and capex decline, old assets can release more free cash flow. The value of the new option must be built on old assets not becoming a drag.
The risk is equally clear. Morgan Stanley believes this round of TV-panel price increases may begin to fall back after 3Q26. If the price decline exceeds expectations and display-business gross margin cannot move from 14.1% in 2026E toward 15.1% in 2027E, ROE repair will be slower than valuation expansion. For BOE A, the biggest risk is not failure of glass substrates itself, but that before glass substrates begin to contribute, the LCD main business pushes profit and cash flow back down.
4. Turning Cash Flow into an Asset: Why Depreciation and Capex Matter
The variable most easily ignored in panel stocks is depreciation. LCD lines require huge capex during construction, and depreciation weighs on the income statement. Once lines enter maturity, depreciation pressure falls and capex slows, so the same revenue can release higher operating profit and cash flow. If BOE A is merely “low revenue growth,” it does not look attractive. But if low revenue growth comes with lower depreciation, lower capex, and better industry supply discipline, it moves closer to a cash-flow asset rather than a cyclical stock.
Goldman Sachs’ March meeting materials with BOE A management provide this clue. Management mentioned that 2026 growth catalysts include the World Cup and other sporting events, TV replacement, the end of Windows 10 support, and AI PC demand. It also expects future depreciation costs and capex to decline, with the goal of maintaining the current capacity level. This language corresponds not to expansionary growth, but to a harvest-phase asset.
This change is also visible in the BOE A model. The revenue curve is not steep, but the slopes of operating profit and net profit are larger, with margins repairing year by year. Behind this is not a sudden breakout in a single product, but the combined effect of gross margin, expense efficiency, lower depreciation, and product mix. For heavy-asset manufacturing, this kind of margin slope explains P/B re-rating better than revenue growth.
What matters most in this table is not how high 2028E net profit is, but the annual margin climb. Panel manufacturing is a large-scale fixed-cost industry. Every one percentage point of gross-margin and operating-margin improvement has a large impact on profit. BOE A’s investment logic does not require revenue to grow 20% every year. As long as revenue maintains low-single-digit growth while gross margin and operating margin continue to improve, net profit can grow faster than revenue.
Cash-flow assetization also affects shareholder returns. In the model, the adjusted cash dividend rises from Rmb0.050 in 2024 to Rmb0.124 in 2028E. Although the absolute dividend yield is not the core of this note, it shows that if profit and cash flow improve steadily, the market can stop looking at the company only through “cycle-bottom P/B.” The basis of the P/B re-rating is that book assets can generate more stable cash returns.
However, this path has limits. If BOE A re-enters a high-capex phase for advanced packaging, OLED, or MLED while new-business revenue realizes slowly, cash-flow assetization will be interrupted. The reason the glass-substrate option has value is that it appears able to borrow existing glass and panel-process experience. But once it requires large-scale new equipment, new fabs, new customer qualification, and a long payback period, it may again become a capex story.
5. OLED and MLED: Not the Main Line, but They Determine Valuation Quality
BOE A’s second layer of assets is migration from LCD to OLED, MLED, and high-end displays. This should not be described as a grand narrative. OLED smartphone-panel demand has not been strong recently, and Goldman Sachs management-visit materials also mentioned that the smartphone market may be pressured by higher memory prices, weighing on the OLED business. MLED remains at an early stage with a small revenue base. They cannot replace LCD in the short term, but they will determine whether the company remains permanently trapped in low-margin commodity panels.
In the model, MLED revenue rises from Rmb8.5bn in 2024 to Rmb14.2bn in 2028E, growing by about 15% annually from 2026E to 2028E; gross margin rises from 5.8% to 8.0%. This business has low near-term profitability, but it represents BOE A’s extension into automotive, commercial display, AR, smartwatches, high-end TVs, and special display scenarios. TCL/AUO third-quarter report readings also mentioned that future high-end panel applications include smartwatches, automotive displays, and AR glasses. BOE A plans to shift its Inner Mongolia B6 line from LCD/OLED toward Mini/Micro LED, reflecting the company’s investment in high-end displays.
OLED/MLED affects valuation not through immediate profit contribution, but through improving the market’s understanding of the company’s capability boundary. If BOE A can only make LCD TV panels, it is a typical cyclical asset. If it can continue to find new applications in small/mid-size OLED, high-end automotive displays, Mini/Micro LED, and advanced-packaging glass substrates, it is not merely a capacity player, but a platform for large-area glass, thin films, lithography, and yield control.
This platform language also needs restraint. The display industry and semiconductor-packaging industry differ in customers, standards, qualification, yield curves, and cost structures. One cannot assume BOE A can naturally win simply because both use glass and clean processes. MLED has not yet proven high profitability, OLED is still affected by the smartphone cycle and competition, and advanced packaging requires trust from semiconductor customers. What truly deserves valuation is the “probability of capability migration,” not the idea that “the transformation is already complete.”
AI PCB Phase 3: capacity expansion is not the answer; glass-fiber looms, T-glass, HVLP copper foil, lamination, drilling, and qualification cycles decide who really unlocks supply
This is also why BOE A cannot talk only about capacity. Whether in MLED or glass-substrate advanced packaging, the end requirements are customer qualification, materials support, yield, and delivery stability. In the AI hardware chain, the most valuable link is often not “I can make it,” but “I can make it stably, at low cost, and at scale, and customers are willing to hand me the next-generation platform.” BOE A’s panel-manufacturing experience gives it an entry ticket, not a finish-line ticket.
6. Glass-Substrate Advanced Packaging: Why the Market Is Willing to Price the Option
Glass substrates have drawn market attention because AI packaging is getting larger. As GPU, ASIC, HBM, and high-speed interconnects are stacked more densely, traditional organic substrates and silicon interposers all encounter issues in area, cost, warpage, heat, and signal integrity. Glass is attractive because of dimensional stability, low thermal-expansion matching, low signal loss, mechanical strength, and panel-level manufacturing potential. If future advanced packaging requires larger area, higher I/O density, and lower cost, glass-core substrates may become an optional route.
The path Morgan Stanley gives for BOE A is more specific than a pure concept. BOE A began researching glass-core substrate technology in 2020 and already has a pilot line. It is validating with domestic and overseas IC design companies. If progress is smooth, it may invest about Rmb5bn in 2027 to build capacity of 15,000 510mm x 515mm substrates per month, targeting mass production in 2028. The model assigns about Rmb5.1bn of advanced-packaging revenue in 2028E.
Two frameworks need to be separated here. Morgan Stanley has built a 2028 revenue assumption for glass-substrate advanced packaging, but under the company’s total revenue framework, it is still small. This is not a contradiction, but a difference in framing: for total company revenue, advanced packaging is still small; for the valuation narrative, it may represent the start of a second curve. Investment judgment cannot describe small revenue as a decisive profit source, but it also cannot ignore its influence on the valuation multiple.
BOE A and Innolux have different paths. Innolux is believed to be participating in a leading foundry’s glass-core substrate project, making TGV on 510mm x 515mm glass panels before handing them to Ibiden for the subsequent substrate process. Its visibility is stronger, but it needs to procure new equipment, and initial capex may reach NT$20bn-30bn. BOE A hopes to make more complete glass-core substrates, including the TGV glass core and build-up layers. The former looks more like entering one process in an existing supply chain; the latter looks more like pursuing broader manufacturing integration.
The benefit of complete manufacturing is a higher value-chain position. The drawback is higher difficulty. TGV is not an ordinary panel hole, and subsequent metallization, plating, insulation, interlayer connection, and reliability must all run to semiconductor-packaging standards. Build-up layers are not a routine display-panel process, and customers will not lower qualification standards simply because BOE A is a panel leader. BOE A’s choice is to exchange higher difficulty for a larger value pool.
JCET deep dive: from cyclical assembly and test to AI advanced-packaging gatekeeper, how Chiplet, XDFOI, and domestic compute re-rate an OSAT leader
In the advanced-packaging industry chain, the boundaries among OSATs, substrate makers, material makers, equipment makers, and chip customers are being redistributed. If BOE A enters glass-core substrates, it will not be dealing with traditional display customers. It must enter joint validation with foundries, OSATs, substrate makers, and AI chip design companies. It must prove not only single-panel process capability, but system-level package usability.
This path has imagination, but also natural constraints. Morgan Stanley places revenue contribution in 2028, which already tells the market not to expect profit realization in 2026. If the share price over-trades advanced packaging in 2026 while fundamentals fail to catch up, volatility will be large. A healthier cadence is to watch validation milestones in 2026, capex and customer design-wins in 2027, and revenue recognition and the yield curve in 2028.
7. Model Breakdown: Low Revenue Growth, High Profit Elasticity
BOE A’s model does not look like a typical growth stock. Revenue is not fast, while profit is faster. This is typical profit elasticity for heavy-asset manufacturing at a cycle bottom, during a decline in depreciation and a repair in gross margin. To read this company, one should not only ask whether revenue can grow quickly, but also whether asset utilization, depreciation cycle, and gross margin can convert low-growth revenue into higher profit.
This elasticity can be split into three parts. First, display-business revenue growth is low, but gross margin repairs from 12.8% to 15.4%, and the scale is large enough for a clear profit contribution. Second, smart systems, MLED, sensors, and other businesses contribute revenue growth; although gross margins vary widely, they help reduce the company’s exposure to a single LCD cycle. Third, about Rmb5.1bn of other revenue is added in 2028E, used by the model to capture the advanced-packaging glass-substrate option.
These data show that BOE A’s attraction is not a steep revenue curve, but the slope of margins. 2026E net profit is Rmb7.3bn, corresponding to EPS of Rmb0.195; 2028E net profit is Rmb12.9bn, corresponding to EPS of Rmb0.345. If the market looks only at P/E, nearly 40x 2026E is not cheap. If it looks at P/B and ROE improvement, the valuation logic is different. Morgan Stanley chose P/B precisely because it sees BOE A as an asset-efficiency repair story rather than pure profit growth.
But the P/B framework does not mean profit can be ignored. The increase in the book-value multiple ultimately still requires ROE delivery. If 2028E net profit cannot approach Rmb12.9bn and ROE cannot enter the 5%-8% range, 2.5x P/B will be questioned again. BOE A must deliver every year: whether display gross margin can rise, whether OLED can stop dragging, whether MLED can improve revenue quality, and whether advanced packaging has customer validation.
The model’s most sensitive variable is not advanced-packaging revenue itself, but display-business gross margin. Assuming 2028E advanced-packaging revenue of Rmb5.1bn, even with a high gross margin, its impact on total profit takes time. But display-business revenue is Rmb177.1bn, and every one percentage point change in gross margin is about Rmb1.8bn of gross profit. BOE A’s short- to medium-term fundamentals are still the prices, utilization, and depreciation of LCD and high-end displays.
This also explains why the investment conclusion must be expressed in two layers. The first layer is that BOE A’s main-business repair provides a valuation floor, with profit expected to repair from the 2024 trough toward 2028E. The second layer is that glass substrates provide valuation elasticity, but before 2028 it is mostly probability weight. If one discusses only the first layer, the Rmb9.30 target-price increase looks large. If one discusses only the second layer, it is easy to ignore main-business risk. Together, the two layers form the true structure of this re-rating.
8. Compared with Other Parts of the Industry Chain, What Is BOE A Betting On?
AI hardware investment has already expanded from chips to packaging, substrates, optical interconnect, PCB, glass fiber, copper foil, equipment, and materials. BOE A is not the most direct beneficiary in this chain. It does not sell compute chips directly like GPU companies, is not already sitting in high-end substrate orders like ABF leaders, and is not naturally positioned in advanced-packaging manufacturing like OSAT leaders. BOE A is betting on something else: whether large-glass manufacturing capability can cross over into packaging carriers.
This bet has two advantages. First, BOE A already handles large-size glass and is familiar with high-cleanliness, large-area, thin-film, and lithography-related manufacturing organization. If glass substrates move toward panel-level size, traditional packaging houses and substrate makers may not naturally have large-panel handling capability. Second, BOE A has a large asset scale. If advanced-packaging glass substrates require capex and engineering iteration, the company has the ability to invest.
It also has two disadvantages. First, qualification logic for semiconductor-packaging customers is stricter than for display customers, and reliability, yield, long-term supply, and ecosystem coordination all need to be re-proven. Second, BOE A’s historical earnings quality has not been high, and investors will worry that the new business again becomes a high-capex, low-return expansion. In other words, it has capability clues for entering glass substrates, but has not yet formed a certain commercial loop.
The conclusion from this table is that BOE A should not simply be compared with ABF substrate makers on orders, nor with OSATs on packaging capability. It is more like a “manufacturing-capability migration option”: if advanced packaging truly requires panel-level glass manufacturing, it may move from the display industry into the semiconductor-packaging industry; if the glass route cannot scale for a long time, it still returns to being a panel-cycle stock.
Full re-rating map for AI PCB materials, from CCL price increases and glass-fiber looms to the ABF gap and rack upgrades
Over the past few months, the AI hardware chain has repeatedly proven one thing: the bottleneck is not always in the most visible chip link. Glass-fiber looms, T-glass, HVLP copper foil, ABF, CoWoS, optical modules, and power and thermal systems can all become profit-allocation gates at different stages. BOE A’s glass-substrate story is easier to understand within this framework. It is not replacing GPUs; it is trying to enter the underlying manufacturing link of “compute cost per watt” and “packaging interconnect efficiency.”
But precisely because of this, BOE A must be verified more strictly. The true bottlenecks in the AI chain eventually leave evidence in orders, price increases, capacity expansion, lead times, yield, and customer qualification. A concept without orders, a pilot line without customer design-wins, and capex without yield ramp are all insufficient to support a long-term re-rating.
9. Three Scenarios: How to Understand Rmb9.30, Rmb11.00, and Rmb3.50
For BOE A, scenario analysis should not look only at target prices, but at the worldview behind each price. The base case represents market partial recognition of ROE repair and advanced-packaging probability. The bull case represents full loading of new lines, improvement in product mix, and smooth advanced-packaging validation. The bear case represents weaker supply discipline, softer demand, slower OLED and advanced-packaging progress, and the market pressing it back into a low-P/B cyclical asset.
These three scenarios are not three random multiples, but three industrial paths. For BOE A to reach Rmb11.00, it cannot rely only on higher LCD prices, nor only on glass-substrate press releases. It needs healthy LCD profit, OLED/MLED not dragging, controlled capex, glass-substrate customer qualification progress, and investors believing that 2028E revenue is not one-off trial production. If only half of these are satisfied, Rmb9.30 can be discussed, but Rmb11.00 is hard to sustain.
The operational implication of this framework is not to treat BOE A as a single-event trade. Upside requires multiple gears to mesh at the same time: LCD prices cannot be too weak, depreciation and capex need to fall, OLED/MLED need to improve product mix, and glass substrates need to show clear validation. If any gear slips, valuation will be discounted. But as long as old assets are stable and new options keep advancing, the market will be willing to keep assigning a higher P/B.
Investors also need to distinguish “how much is already reflected in the price.” The current share price still has room to the base target, but the gap to the bull target does not mean there is no volatility risk, and the bear case also indicates material downside. This risk-reward is not one-way cheap. It is better suited to milestone tracking than to discounting all of the glass-substrate future in one step.
AI PCB Phase 6: capacity-expansion announcements do not equal effective capacity; a full read-through of 2026 equipment orders at Han’s CNC, Shenghong Technology, and Shennan Circuits
The lesson from the AI hardware chain is that once the theme moves from “is there demand” to “who can deliver stably,” valuations diverge. BOE A is the same. The first re-rating can rely on logic; the second must rely on validation. In coming quarters, if the company keeps releasing customer validation, samples, production-line, and mass-production plans, valuation can move along the option-value path. If only the concept sustains the heat, the share price will return to panel prices and mean P/B.
10. The Most Important Things to Watch Are Not News, but Four Sets of Numbers
Follow-up tracking for BOE A should be as quantitative as possible. The first group is LCD TV panel prices, especially mainstream 32/43/55/65-inch sizes. Prices do not need to keep rising sharply, but they cannot give back gains quickly after 3Q26. If prices fall modestly but remain above the start of the year, industry discipline is still in place. If prices fall back into a vicious-competition range, every re-rating must be discounted.
The second group is display-business gross margin. The model path is 14.1% in 2026E, 15.1% in 2027E, and 15.4% in 2028E. As long as display gross margin moves in this direction, the income statement can support a higher P/B. If gross margin is stuck around 13%, ROE repair will be insufficient. For BOE A, gross margin is more important than revenue growth.
The third group is capex and depreciation. Management’s language emphasizes lower depreciation costs, lower capex, and maintaining the current capacity level. If financial reports show capex clearly rising again, and it is not tied to high-return new businesses, the market will question whether cash-flow assetization has been interrupted. If capex declines while profit improves, BOE A will look more like a mature manufacturing cash-flow asset.
The fourth group is glass-substrate validation milestones. These include whether customer validation is disclosed, whether domestic and overseas IC design companies have sample progress, whether TGV and build-up layers form a clear process route, whether the about Rmb5bn investment in 2027 is implemented, and whether the 2028 mass-production target is maintained. News heat is not important; customer qualification and production-line progress are.
This table also helps distinguish short-term volatility from fundamental disconfirmation. Share-price increases or declines are not evidence; prices, gross margins, capex, and customer validation are. If LCD prices fall modestly but display gross margin continues to improve, one should not simply turn bearish. If there is a lot of glass-substrate news but capex loses control and customer qualification produces no result, one should not simply turn bullish.
11. Main Risk: Valuation Has Moved Ahead of Performance
BOE A’s biggest risk is that valuation has already moved ahead of performance. 2.5x 2026E P/B is not a low valuation. It requires joint support from ROE repair and the advanced-packaging option. If 2026 earnings only improve modestly and advanced packaging lacks new validation, the market may conclude that the Rmb9.30 target price has pulled too much future value forward.
The second risk is the LCD price cycle. Sporting events, TV replacement, AI PCs, and Windows 11 replacement can support demand, but these are not unlimited sources of demand. If brands pull in orders early and demand weakens in the second half, or panel makers raise utilization again to seize share, prices will fall before profits. The panel industry’s history has repeatedly shown that supply discipline matters more than the demand narrative.
The third risk is the return on investment in OLED and MLED. BOE A must invest in high-end displays, but investment does not equal profit. OLED smartphone panels are affected by smartphone demand, memory costs, customer mix, and competition. MLED has technical prospects, but revenue and gross margin are still ramping. If these businesses continue to consume capital and expenses, the main-business cash-flow improvement will be diluted.
The fourth risk is glass-substrate commercialization. TGV, copper plating, build-up layers, reliability testing, customer qualification, and mass-production yield can all become bottlenecks. Even if the technology is feasible, value allocation may not be ideal. If BOE A only wins low-value-added links, the valuation elasticity of advanced-packaging revenue will be lower than the market imagines. If investment is too large and orders are insufficient, cash flow will be hurt.
The fifth risk is cross-cycle target-price comparison. Rmb9.30 is Morgan Stanley’s target price for BOE A in this note. It should not be directly ranked against other institutions’ target prices with different dates, models, dividends, or ex-rights frameworks. If later corporate actions, share-capital changes, or report dates cross important events, target prices must be put on a consistent basis before comparison.
There is also a subtler risk: after BOE A is placed simultaneously into the baskets of “AI advanced packaging,” “glass substrates,” “panel recovery,” and “A-share asset re-rating,” the funding trade may become crowded. Once any basket fades, the share price may fall first and wait for fundamentals to explain later. For this type of stock, tracking fundamental milestones is more important than chasing concept labels.
12. Sell-side Divergence: One Company, Two Valuation Languages
The most research-worthy aspect of BOE A this time is that different institutions are effectively speaking two valuation languages. Goldman Sachs’ March materials maintained a Neutral rating and a 12-month target price of Rmb4.79, based on 2026E EV/EBITDA, while emphasizing the industry cycle, OLED demand, and the fact that valuation had already reflected many positives. Morgan Stanley’s June materials gave an Overweight rating, raised the target price from Rmb5.20 to Rmb9.30, based on 2.5x 2026E P/B, and incorporated advanced-packaging glass substrates into the valuation multiple. The difference is not simply who is right or wrong, but a difference in time horizon and asset attributes.
Goldman Sachs is closer to looking at “normalized profit for BOE A as a panel company.” It cares whether 2026 sporting events, TV replacement, the end of Windows 10 support, and AI PCs can support demand. It also cares about the weakness in the OLED smartphone market and the impact of rising memory prices on terminal demand. It acknowledges lower depreciation and capex, but the valuation method still revolves around traditional-panel-industry EV/EBITDA. The advantage of this framework is conservatism; it does not discount unrealized new businesses too early. The disadvantage is that it may underestimate changes in the asset boundary.
Morgan Stanley is closer to looking at “the re-rating probability of BOE A as a glass-manufacturing platform.” It did not raise the target price because of a near-term earnings upgrade. It actually cut near-term earnings, but lifted the P/B multiple. This shows a willingness to assign part of the option value in advance to advanced-packaging glass substrates and ROE repair. The advantage of this framework is that it captures industry-chain migration. The disadvantage is that if validation milestones do not arrive, the valuation will look premature.
This divergence table is more useful than looking at target prices alone. If the next few quarters bring only improvements in LCD prices and depreciation, without glass-substrate customer validation, the Goldman Sachs framework will be closer to reality, and the stock should be valued on traditional-panel cash-flow repair. If LCD prices stabilize while BOE A discloses real customer validation, production-line investment, and mass-production targets, the Morgan Stanley framework will have more explanatory power, and the P/B multiple will have reasons to remain elevated or even expand.
Investors often make the mistake of treating target prices as static conclusions. Morgan Stanley’s target price does not mean “BOE A is definitely worth this number.” It is a set of conditions: book value, ROE repair, no deterioration in the panel main business, and progress in the advanced-packaging option. Goldman Sachs’ more conservative target price does not mean “the company can only be worth this number.” It is another set of conditions: mainly view BOE A as a cyclical panel company and value the traditional business using EV/EBITDA. Real research should not choose sides between target prices, but track which set of conditions is taking place.
This divergence also helps control position sizing and expectations. If the buying reason is only “the target price was raised,” it is easy to lose the anchor during share-price volatility. If the buying reason is “the LCD main business provides a cash-flow floor, and glass substrates provide valuation optionality,” then two types of data must be checked at the same time: traditional panel data determine whether the position can be held, and new-business milestones determine whether valuation can continue to rise. BOE A is not a single-variable trade. The more it is labeled as AI, the more it needs a multi-variable framework to discipline emotion.
13. Asset History: From Scale Expansion to Efficiency Harvest
For many years, BOE A’s core action was to exchange large-scale capex for panel capacity and global share. The financial characteristics of this stage were typical: revenue scale kept expanding, book assets were heavy, depreciation pressure was high, and profit was easily swallowed during industry troughs. The market assigned a low P/B not simply because it disliked the panel industry, but because returns on book assets were not high enough for a long time.
When discussing re-rating now, this history cannot be forgotten. Without past large-scale line investment, BOE A would not have about 35% share in large-size LCD, nor would it have globally leading large-glass manufacturing experience. But because of those investments, the financial statements have long carried a heavy-asset burden. The key to asset re-rating is not to describe past expansion as a mistake, but to see whether these assets are entering a harvest phase.
The harvest phase has three signs. First, incremental capex no longer keeps expanding to capture low-end share, and management’s target shifts toward maintaining the current capacity level. Second, profit elasticity from lower depreciation begins to appear, and low revenue growth can also bring operating-margin repair. Third, existing line capabilities can migrate to higher-value applications such as high-end displays, MLED, automotive, and advanced-packaging glass substrates. Only when all three hold can old assets shift from a drag to a base.
BOE A is now at the transition from the second stage to the third. If it stays only in the second stage, it can still become a better panel cash-flow asset, but the valuation ceiling is limited. If the third stage is validated successfully, it has the chance to be re-understood from “global panel leader” as a “large-area glass manufacturing platform.” This platform may not serve only TVs and phones, but also AI packaging, automotive displays, industrial displays, and new interactive devices.
This asset history requires restrained writing. BOE A is not a sudden advanced-packaging upstart. Its advantages come from manufacturing capabilities left by years of heavy-asset investment, and its burden comes from the same heavy-asset base. Investment judgment must recognize both sides: without old assets, there is no glass-substrate option; if old-asset returns do not improve, the option will also be difficult to price for long.
14. Data Framework: Which Numbers Can Be Viewed Precisely, and Which Can Only Be Viewed Probabilistically
The number most easily confused for BOE A is the advanced-packaging revenue share. Morgan Stanley has already modelled glass-substrate advanced packaging, but the model’s total-revenue framework shows it remains small in the company’s overall revenue. A more rigorous expression is to separate the two: being modelled shows the new business has begun to enter valuation discussion; small size shows it has not yet become the main business. “Already modelled” cannot be interpreted as “already the main business.”
Another distinction is between target price and earnings forecasts. The target price comes from P/B re-rating, not recent EPS upgrades. On P/E, BOE A does not look cheap. On P/B, if returns on book assets rise, there is still room to explain the valuation. Different valuation methods create completely different impressions, so the framework must be stated first.
The third distinction is between industry prices and company profit. Mainstream LCD TV panel sizes have risen together since the start of the year, which is an industry price signal. Whether BOE A’s display-business gross margin can continue to repair is the company margin signal. Price signals do not necessarily pass fully into margins, because product mix, utilization, depreciation, customer mix, and costs also matter. If prices rise but gross margin does not, transmission is poor. If prices are moderate but gross margin rises, depreciation and mix improvement are working.
The fourth distinction is between lower capex and new-business investment. Management emphasizes a lower future capex burden, but if advanced-packaging glass substrates receive about Rmb5bn of investment in 2027, there will be localized new capex. The two do not necessarily conflict: the company can stop large expansions of traditional LCD lines while making targeted investment in new businesses. The key is whether investment returns are clear. Not all new capex should be treated as bad, and not all new-business investment should be treated as good.
Once the data framework is clear, BOE A’s investment judgment becomes steadier. One can acknowledge that advanced packaging provides valuation elasticity, while also acknowledging that revenue contribution before 2028 is limited. One can acknowledge that P/B re-rating is reasonable, while also acknowledging that it requires ROE delivery. One can acknowledge LCD price improvement, while still waiting for the company’s gross-margin validation. Seen this way, BOE A is not a simple long or short, but an asset whose probabilities need to be calibrated continuously through time milestones.
15. Trading Cadence: First Look at the Panel Floor, Then at Glass-Substrate Realization
BOE A’s cadence cannot be arranged around a single event. It has a traditional-panel path and an advanced-packaging path. The traditional-panel path determines “whether there is a floor when it falls,” while the advanced-packaging path determines “whether there is room when it rises.” Looking only at the former misses re-rating elasticity; looking only at the latter ignores the real constraints of the income statement and cash flow.
The first stage is to watch panel prices and margins from 1H26 to 3Q26. Pull-in demand from the World Cup, TV replacement, AI PCs, and the Windows 11 replacement cycle has already been partly reflected in panel prices at the start of the year. The key is not whether prices keep rising sharply, but whether they can fall mildly after 3Q26 rather than weakening quickly. If prices consolidate at high levels and BOE A’s display gross margin realizes from 12.9% in 2025E toward 14.1% in 2026E, the market will be more willing to believe in the cash-flow base.
The second stage is to watch capex and depreciation. Management has already pointed to lower depreciation and slower capex, and subsequent financial reports need to prove this is not just verbal guidance. If capex intensity declines, operating cash flow remains stable, and net margin repairs from 2.9% toward 3.5%, BOE A will look more like a mature manufacturing asset, rather than a cyclical stock that earns only from price swings.
The third stage is to watch OLED/MLED and the high-end display mix. This stage will not immediately determine the valuation ceiling, but it will determine valuation quality. If MLED revenue continues to maintain double-digit growth, OLED improves in high-end customers and yield, and high-end displays gradually raise revenue quality, the market will believe BOE A’s old manufacturing capability is migrating to higher-value applications. If these businesses remain low-profit and low-visibility, BOE A will still be forcibly pulled back into the LCD framework.
The fourth stage is to watch glass-substrate capex and customer qualification in 2027. Morgan Stanley’s potential plan is about Rmb5bn of investment in 2027, monthly capacity of 15,000 510mm x 515mm substrates, and mass production in 2028. Validation of this line cannot rely only on announcements. It must look at who the customers are, what step validation has reached, how reliability testing is progressing, and how deep BOE A’s value-chain role is. If only production-line investment is disclosed without customer qualification, the market will instead worry about rising capex.
The fifth stage is to watch revenue and yield in 2028. The about Rmb5.1bn of advanced-packaging revenue in 2028E is not a high share of total revenue, but it is highly meaningful for valuation. If it is revenue with customers, yield, and a replicable route, the market will view it as the starting point of a second curve. If it is only small-scale trial production or low-margin processing, option value will be revised down. The quality of advanced-packaging revenue matters more than the amount.
This roadmap gives a judgment sequence, not a trading instruction. Confirm the main-business floor first, then cash flow, then new business. If the order is reversed, investors can easily be led by the advanced-packaging story and still overvalue the option when the panel main business weakens. BOE A’s advantage is that it has a real main business that can be checked. Its disadvantage is also that it has a real main business: once main-business data do not cooperate, the story has little cover.
Another cadence issue is the order of share price and fundamentals. The market usually trades the concept first and waits for data later. Glass substrate is a typical “valuation first, revenue later” asset: before customer validation, the share price may already assign probability; before revenue recognition, valuation may already fluctuate through several rounds. For this type of asset, position management cannot look only at long-term upside, but also at short-term validation density. If there are no new milestones over the next one to two quarters, the share price will need to rely more on LCD prices and financial-report performance.
From an industry perspective, BOE A’s window is not unlimited. If the glass-substrate route is established, packaging houses, substrate makers, material makers, equipment makers, and panel makers will all compete for positions. Innolux already has relatively high visibility, and traditional substrate makers will not stand still. The earlier BOE A produces customer validation, the easier it is to prove that it is not a follower. If validation remains vague until after 2028, valuation optionality will be diluted by competition and uncertainty.
So BOE A’s best current state is “the main business is not bad, and the new business is progressing.” The worst state is not “glass substrates have no revenue yet,” but “LCD prices weaken, capex rises, and the new business still has no customers.” The former is simply option waiting; the latter damages both the base and the elasticity. All follow-up tracking should judge around these two states.
16. Conclusion: BOE A Has Begun to Have a Second Valuation Language
BOE A used to have only one valuation language: panel prices rise, earnings repair, P/B goes up; panel prices fall, earnings retrace, P/B goes down. This language has not failed, and it will still determine the share-price base over the next 12 months. But there is now a second valuation language: when depreciation on old lines declines, capex slows, industry supply discipline improves, and glass-substrate advanced packaging provides the probability of a second curve, the market can begin to value the company by asset efficiency and manufacturing-capability migration.
This is what the Rmb9.30 target price means. It does not say BOE A has already become an advanced-packaging company, nor does it say 2026 performance will explode. It says that if the company can turn its display-panel main business from a cyclical volatility asset into a more stable cash-flow base, while migrating large-glass manufacturing capability into advanced-packaging glass-core substrates, BOE A’s reasonable P/B center can be higher than in recent years.
The most important judgment is that BOE A deserves to be researched again, but it cannot be oversimplified into a glass-substrate concept. Its core is still the panel main business, cash-flow improvement is the bridge, and glass substrate is the option. If the bridge is not stable, the option can easily become a bubble; once the bridge is stable, the option has capital-market value.
For investors, the more reasonable posture is not to ask “is BOE A an AI stock,” but to ask four more basic questions: can LCD prices and gross margin hold, can depreciation and capex continue to decline, can OLED/MLED improve asset quality, and can glass substrates deliver customer validation and mass-production milestones. If the first two are true, the valuation floor is more stable. If the latter two continue to materialize, the market can discuss Rmb11.00 after Rmb9.30.
China Jushi deep dive: re-rating the electronic glass-fiber supply bottleneck, and how the glass-fiber leader can shift from cyclical stock to AI PCB materials asset
The re-rating of cyclical assets is never completed by changing a label. China Jushi’s electronic glass fiber, PCB materials’ T-glass, OSATs’ advanced packaging, and BOE A’s glass substrates are all essentially answering the same question: have old assets obtained higher-quality demand, stronger pricing power, and more stable capital returns because of new bottlenecks in AI hardware? If the answer is yes, valuation can be rewritten. If the answer is merely conceptual mapping, valuation will eventually return to the old cycle.
BOE A now stands on this dividing line. The main business already has clues of healthier supply-demand and cash-flow improvement, and glass substrates provide a direction for manufacturing-capability migration, but commercialization has not reached a stage where skepticism is no longer needed. The most restrained and most useful conclusion is this: BOE A should no longer be priced crudely only as a traditional LCD cyclical stock, but it has not yet completed the identity shift from display-panel leader to advanced-packaging asset. Over the next four quarters, it needs to turn this re-rating from story into numbers through prices, gross margin, cash flow, and customer validation.