
ASML Q2 Earnings Preview: Memory Capex, 90-Unit EUV Capacity, and a Recovery in China DUV
目录
TL;DR
Q2 Numbers Are Already Highly Transparent; Any Real Surprise Must Come from Guidance
Direct Investment-Bank Previews Diverge Entirely on 2027–2028
90 EUV Systems Must Be Broken Down into Capacity, Run Rate, and Revenue Recognition
Memory Provides the High-Conviction Base; Advanced Logic Determines the Scale of Upside
China DUV Could Recover, but Growth Is Not Unconditional
High-NA Is More of a Medium-Term Capacity Release Valve Than a Q2 Revenue Driver
Valuation Depends on Which Set of Forward Earnings Materializes
Three Earnings Scenarios: Replace Sentiment with Verifiable Signals
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
ASML will report 2Q26 results on July 15. Investment banks expect revenue of €8.7–9.03 billion and a gross margin of 51.7%–53.0%. Valuation will not hinge on a single quarter. The key questions are whether full-year guidance can approach the upper end of €40 billion, whether EUV capacity can rise to 90–100 units in 2027, and whether order visibility can extend into 2028.
TL;DR
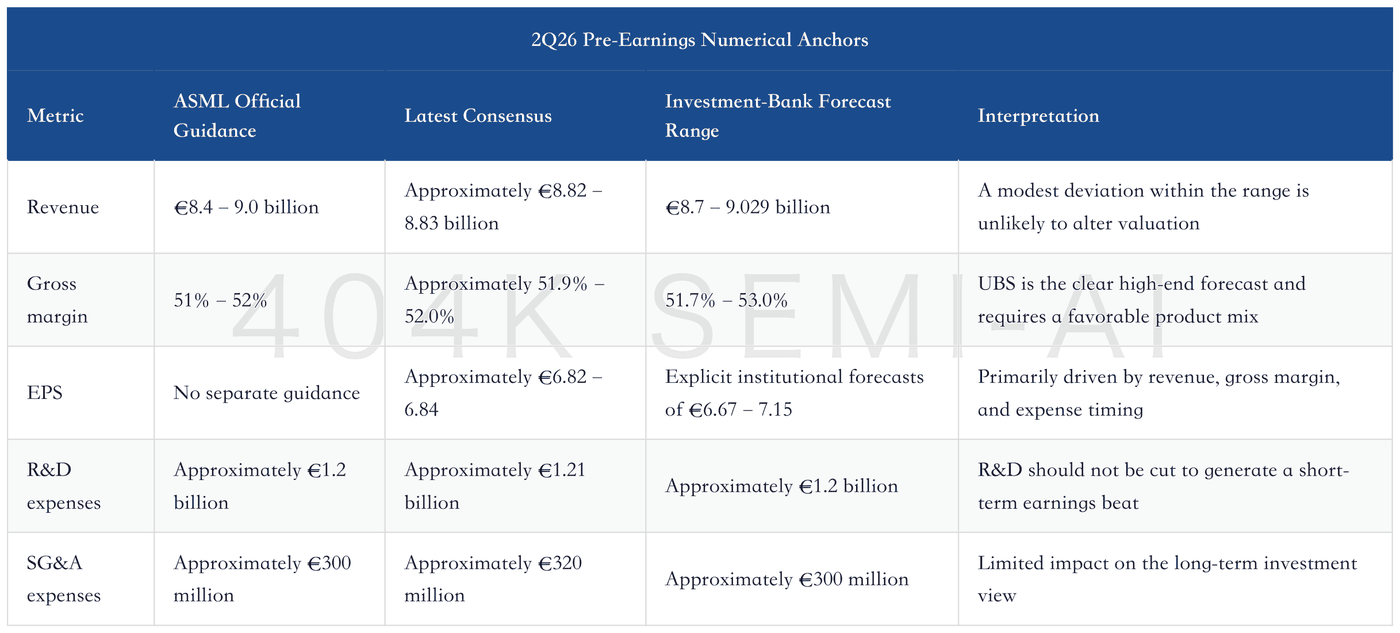
Q2 will most likely be merely in line. ASML’s official guidance calls for revenue of €8.4–9.0 billion and a gross margin of 51%–52%. The latest consensus is approximately €8.82–8.83 billion in revenue, a 51.9%–52.0% gross margin, and EPS of €6.82–6.84. JPMorgan, HSBC, and Morgan Stanley forecast revenue of €8.7 billion, €8.85 billion, and €9.029 billion, respectively, while UBS alone expects a 53% gross margin. These quarterly differences are still insufficient to alter the long-term valuation.
A genuine upgrade to full-year guidance is the first hurdle. The company currently guides to 2026 revenue of €36–40 billion and a gross margin of 51%–53%, while Goldman Sachs, UBS, and HSBC forecasts are already clustered at €39.4–39.8 billion. If management merely says revenue will be “near the upper end,” that would only confirm the base case. A formal increase in the lower bound or a narrowing of the range toward the high end would constitute an incremental gain that can be incorporated into earnings models.
The 90-unit figure refers to three different metrics. Investment-bank reports discuss annual supply-chain capacity, year-end run rate, and shipments recognized as revenue during the year. These cannot be treated as equivalent. JPMorgan views guidance of 90 units for 2027 as only a modest positive, while 90–100 units would be clearly positive. Morgan Stanley expects approximately 86 low-NA EUV systems and more than 90 including High-NA EUV. Bernstein and BNP Paribas forecast total 2027 shipments of 91 and 92 units, respectively.
Memory provides visibility, advanced logic determines the upside, and China DUV is a conditional source of potential upside surprise. HSBC expects DRAM wafer-fab equipment spending to grow 60% in 2027 and views higher capex at TSMC and Intel as a second growth driver for 2028. Goldman Sachs and UBS believe China DUV demand could recover in 2027 after digestion in 2026. None of these drivers can be booked directly into revenue without customer orders, fab readiness, and export licenses.
The post-earnings outcome will hinge on 2027–2028 EPS, not a few cents of quarterly upside. The five direct previews forecast 2027 EPS of €45.49–54.4 and 2028 EPS of €52.19–68.02, far wider ranges than the Q2 forecasting error. If management confirms 90–100 EUV systems in 2027, 2028 orders, and full-year guidance at the high end, valuation should continue converging toward the bullish models. If it confirms only shipments in the 80s and retains a wide range, the share price is more likely to digest its elevated valuation first.
Q2 Numbers Are Already Highly Transparent; Any Real Surprise Must Come from Guidance
ASML will issue its 2Q26 press release at 07:00 CEST on July 15, followed by a conference call at 15:00 with CEO Christophe Fouquet and CFO Roger Dassen. In 1Q26, the company already established the parameters for Q2 and the full year: Q2 revenue of €8.4–9.0 billion, a gross margin of 51%–52%, R&D; expenses of approximately €1.2 billion, and SG&A; expenses of approximately €300 million; full-year 2026 revenue of €36–40 billion and a gross margin of 51%–53%.
The 1Q26 comparison base was not weak. ASML reported quarterly revenue of €8.767 billion, a 53.0% gross margin, net income of €2.757 billion, and EPS of €7.15. Management said at the time that AI infrastructure investment was driving chip demand above supply and prompting customers to accelerate capacity expansion in 2026 and beyond, with order intake remaining strong. At the same time, the wide full-year guidance range was still needed to accommodate different potential outcomes from export-control discussions.
ASML Earnings Review — Memory Overtakes Logic for the First Time; Guidance Moves Higher
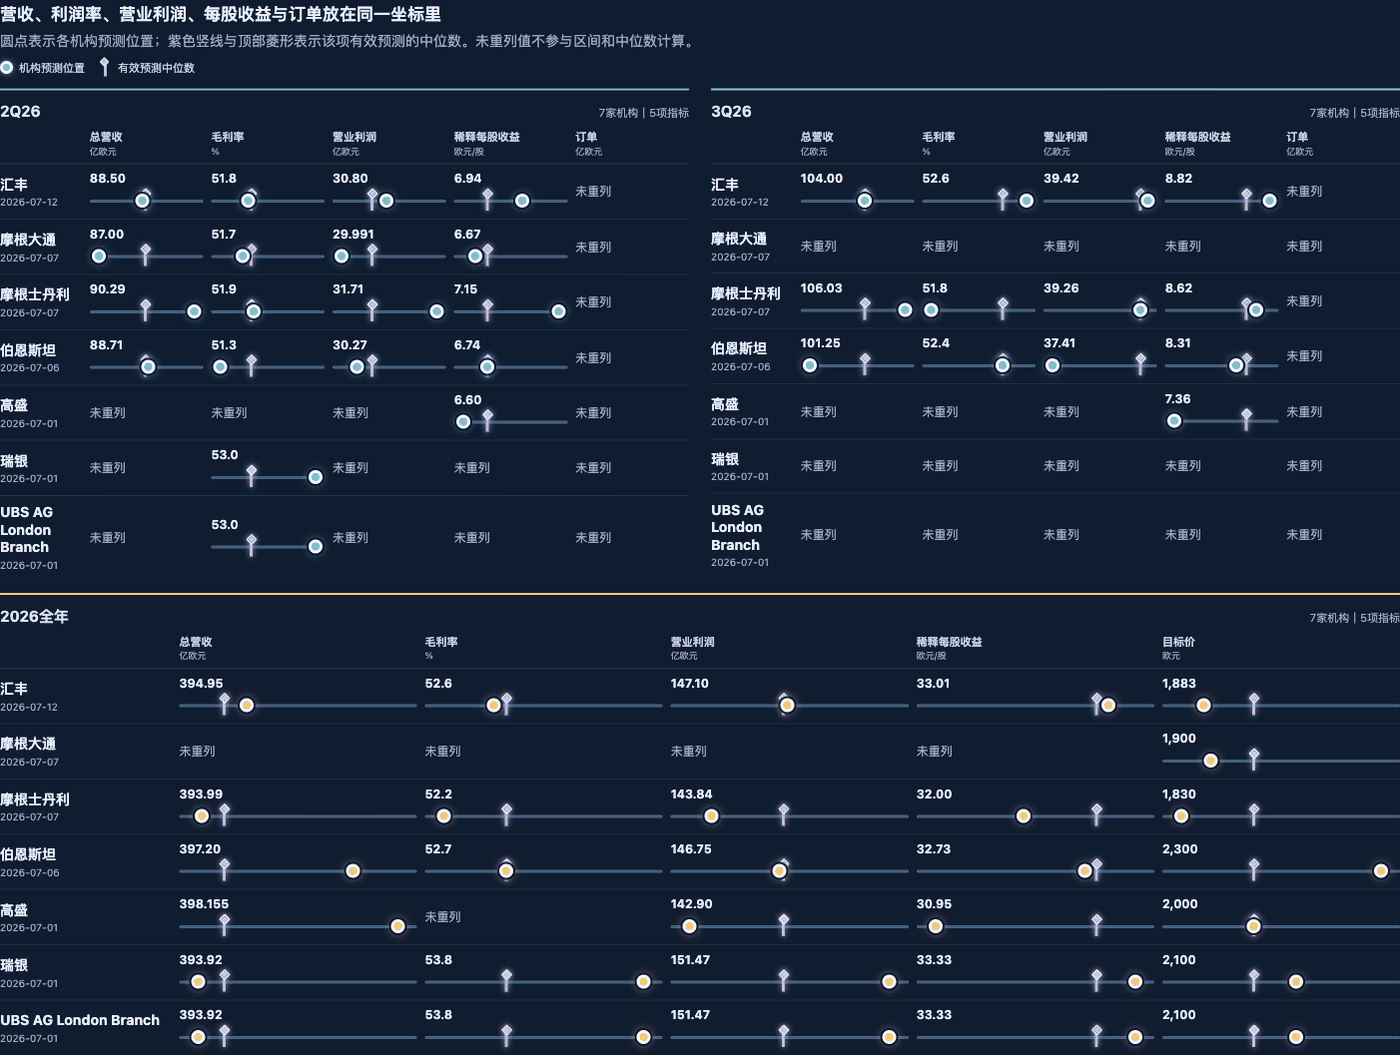
This chart places 2Q26, 3Q26, and full-year 2026 forecasts on the same scale. The dots show each institution’s position, while the purple markers indicate the median of valid forecasts. “UBS” and “UBS AG London Branch” in the chart are drawn from the same UBS model and should be treated as a single institution, not as additional consensus.
The key takeaway is that most Q2 revenue forecasts are clustered in the upper half of the company’s guidance range. The real outlier is UBS’s 53% gross-margin forecast. A modest quarterly revenue or EPS deviation would merely reflect delivery timing. Only a gross margin above the company’s range, a higher full-year lower bound, stronger 2027 EUV supply, and improved 2028 orders would indicate that the earnings anchor is continuing to move higher.
“Guidance upgrades” must also be distinguished by degree. If the company says it “expects to be near the upper end of the range,” that merely changes the probability distribution within the €36–40 billion range. Formally raising the lower bound or narrowing the range toward the high end would lift consensus estimates. Investment-bank full-year revenue forecasts in the chart are already clustered at €39.4–39.8 billion. The market needs a narrower, higher company forecast that can be directly incorporated into models.
Direct Investment-Bank Previews Diverge Entirely on 2027–2028
The metric ranking makes the divergence explicit: institutional ranges for Q2 revenue and EPS are not wide, only a few institutions provide updated 3Q26 figures, and dispersion in full-year 2026 price targets and earnings assumptions is materially greater. In other words, Q2 will confirm whether the company is keeping pace; 2027–2028 will determine how much further earnings can be upgraded.
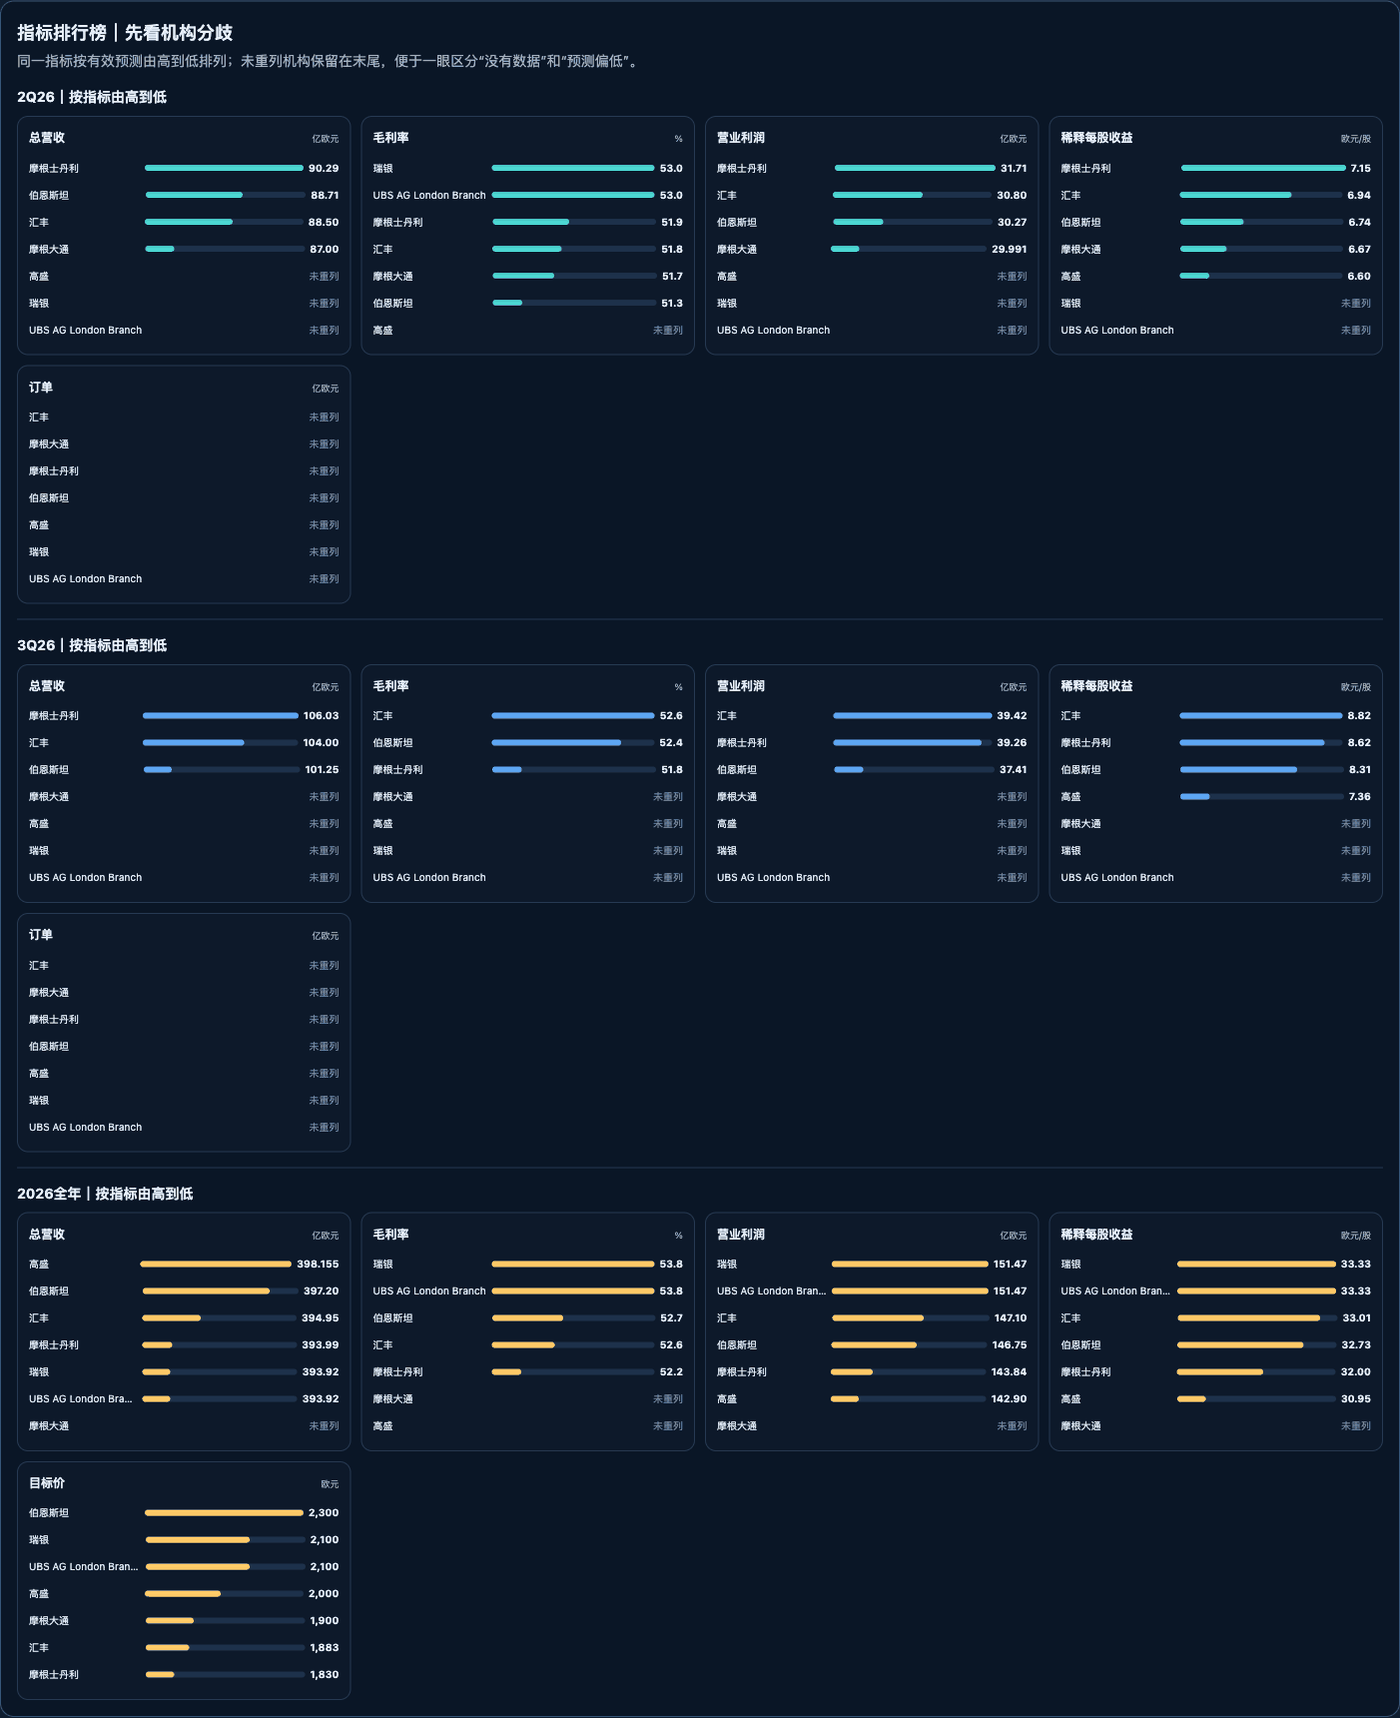
The divergence widens rapidly when the horizon extends to 2027–2028. The five institutions’ 2027 EPS forecasts differ by nearly €9, while their 2028 forecasts differ by nearly €16. The core debate is whether advanced-logic and memory capacity expansion will occur simultaneously, whether ASML can deliver enough EUV systems, and whether DUV and service revenue will expand alongside them.
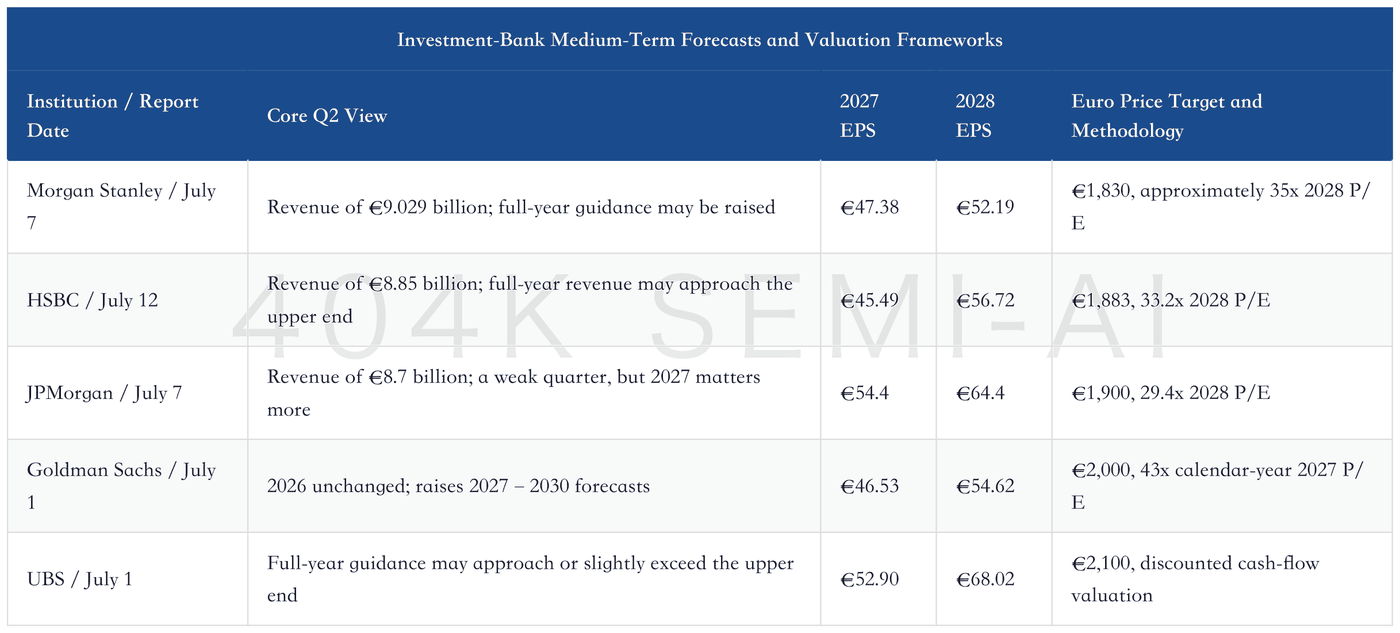
These price targets all refer to ASML’s Amsterdam-listed ordinary shares and are denominated in euros. The reports were published between July 1 and July 12. The ranking shows the high and low estimates, while the table explains the underlying reasons: HSBC and Morgan Stanley are relatively conservative on 2028 EPS; JPMorgan and UBS already incorporate higher EUV shipments, a strong memory cycle, and operating leverage into their models; Goldman Sachs has raised its 2027–2030 revenue, operating profit, and EPS forecasts by approximately 5%–9% overall.
This divergence provides the framework for assessing the earnings release. If management only confirms that 2026 will be near the high end while 2027 EUV shipments remain in the 80s and 2028 orders are not quantified, the lower-end earnings models will be more credible. If management explicitly states that it can deliver 90–100 units in 2027 and customers are beginning to lock in 2028 orders, the higher-end JPMorgan and UBS models will gain operational support. What the market is truly trading is which set of forward EPS estimates is closer to reality.
90 EUV Systems Must Be Broken Down into Capacity, Run Rate, and Revenue Recognition
Extreme ultraviolet lithography (EUV) is the most easily misinterpreted aspect of this earnings report. The “90 systems” cited by investment banks can mean at least three things: how many sets of critical components the supply chain can prepare annually, the annualized production run rate ASML’s factories can reach at a given point, and the number of systems actually shipped and recognized as revenue during the year. Assembly lead times, fast shipments, customer acceptance, and revenue recognition separate these metrics. “Capacity for 90 systems” cannot be equated directly with “90 systems sold that year.”
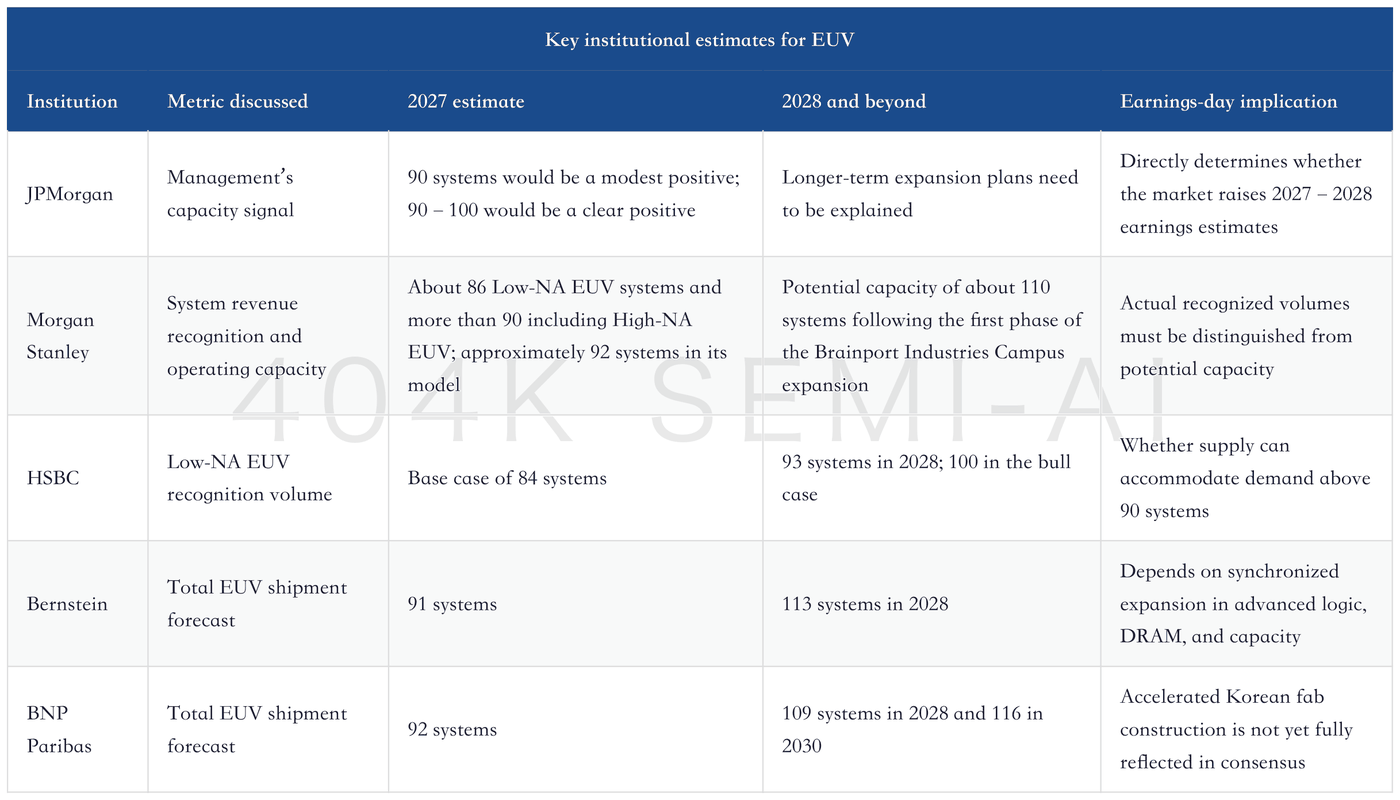
JPMorgan provides the clearest trading thresholds: if management merely says it can produce 90 systems in 2027, that is already broadly anticipated by the market. A clear indication of 90–100 systems, supported by an explanation of how light sources, lenses, cleanrooms, suppliers, and assembly lead times will align, would constitute a meaningful beat. Morgan Stanley further identifies the Brainport Industries Campus expansion as critical to capacity growth beyond 2028. If the first phase proceeds as planned, potential annual Low-NA EUV capacity could approach 110 systems.
The earnings call needs to answer four verifiable questions; simply stating “we will meet customer demand” provides no meaningful information: approximately how many systems will actually be recognized as revenue in 2027; whether the 90-system figure refers solely to Low-NA EUV or includes High-NA EUV; whether the fast-shipment mix and customer acceptance will create timing mismatches across quarters; and whether customers have already begun securing 2028 systems through long-term agreements or firm delivery slots. Only if all four answers improve will strong demand translate into realizable revenue.
Memory Provides the High-Conviction Base; Advanced Logic Determines the Scale of Upside
Memory has been the most consistently positive variable over the past month. Citing Micron’s latest capital expenditure plans, Goldman Sachs notes that Micron expects approximately $27 billion of capex in FY2026, with another significant increase in FY2027. Micron has also signed a multi-year EUV supply agreement with ASML for the 1-delta node and subsequent nodes. HSBC expects DRAM to account for approximately 40% of ASML’s 2026 system sales and forecasts DRAM wafer-fab equipment spending to rise 60% in 2027 to approximately $70.6 billion.
The primary value of memory capex lies in securing future capacity in advance; selling one additional system in Q2 affects only the near term. EUV delivery lead times exceed 12 months. If customers intend to expand high-bandwidth memory and advanced DRAM capacity in 2027, they must arrange equipment, facilities, and long-term agreements during 2026. BNP Paribas’ analysis of the Yongin projects in Korea indicates that SK Hynix’s Y2 fab could require approximately 30–45 EUV systems if equipment is installed during 2028–2031, while Samsung’s first Yongin fab could require approximately 35–50. These represent potential demand installed in phases over multiple years and cannot be recognized entirely in 2027, but they sufficiently explain why customers would compete for delivery slots earlier.
In-Depth Memory Update: How Korea’s $3.1 Trillion AI Investment Plan Revalues DRAM, NAND, and the Equipment Supply Chain
Advanced logic and foundry demand will determine the magnitude of the upside. HSBC has raised its global wafer-fab equipment (WFE) forecasts to $155.6 billion for 2026, $217.4 billion for 2027, and $261.1 billion for 2028. It expects advanced-foundry equipment spending to increase 31% in 2027 to $92.8 billion. Its thesis is that demand for TSMC’s advanced nodes will remain strong, while additional external customers for Intel and Samsung would mean global customers no longer rely on a single foundry, driving incremental fab construction and advanced-node lithography demand.
The evidence supporting this thesis is weaker than for the disclosed long-term memory agreements. HSBC’s base-case forecasts put TSMC’s capex at $80 billion in 2027 and $93 billion in 2028, with sensitivity analysis for higher spending. However, these remain investment-bank forecasts and require confirmation through TSMC’s, Intel’s, and Samsung’s own capex guidance. TSMC will report results the day after ASML, so ASML management’s commentary on advanced-logic demand will provide only the first point of validation; customer guidance will provide the second.
