
ASML Q2 Earnings Preview: Memory Capex, 90 EUV Units of Capacity, and China DUV Recovery
目录
Too Long; Didn’t Read
1. This Earnings Release Needs to Answer Not “Was Q2 Good?” but “Is 2027 Enough?”
II. Memory Capex Puts ASML Back in the Bottleneck Position
III. 2027 DUV and China Demand Are the Second Expectation Gap
IV. 90 EUV Units Is the Hard Threshold for Whether ASML Can Capture the Memory Cycle
V. High-NA Is Not the Near-Term Revenue Driver, but Memory Could Pull the Story Forward
VI. Valuation Framework: Behind the EUR 2,000 Target Price, the Market Is Buying FY27-28 EPS
VII. Three Earnings Scenarios: Orders in the Short Term, Capacity in the Medium Term, High-NA in the Long Term
VIII. Earnings-Day Checklist: Four Questions Determine the Quality of This Report
9. Disconfirmation Conditions and Tracking Indicators
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
ASML reports 2Q26 on July 15. What the market really needs to assess is not whether quarterly revenue lands near the EUR 8.4-9.0bn guide, but whether memory expansion, 2027 China DUV demand, 90 EUV units of capacity, and High-NA orders can keep lifting the 2027-2028 earnings anchor.
Too Long; Didn’t Read
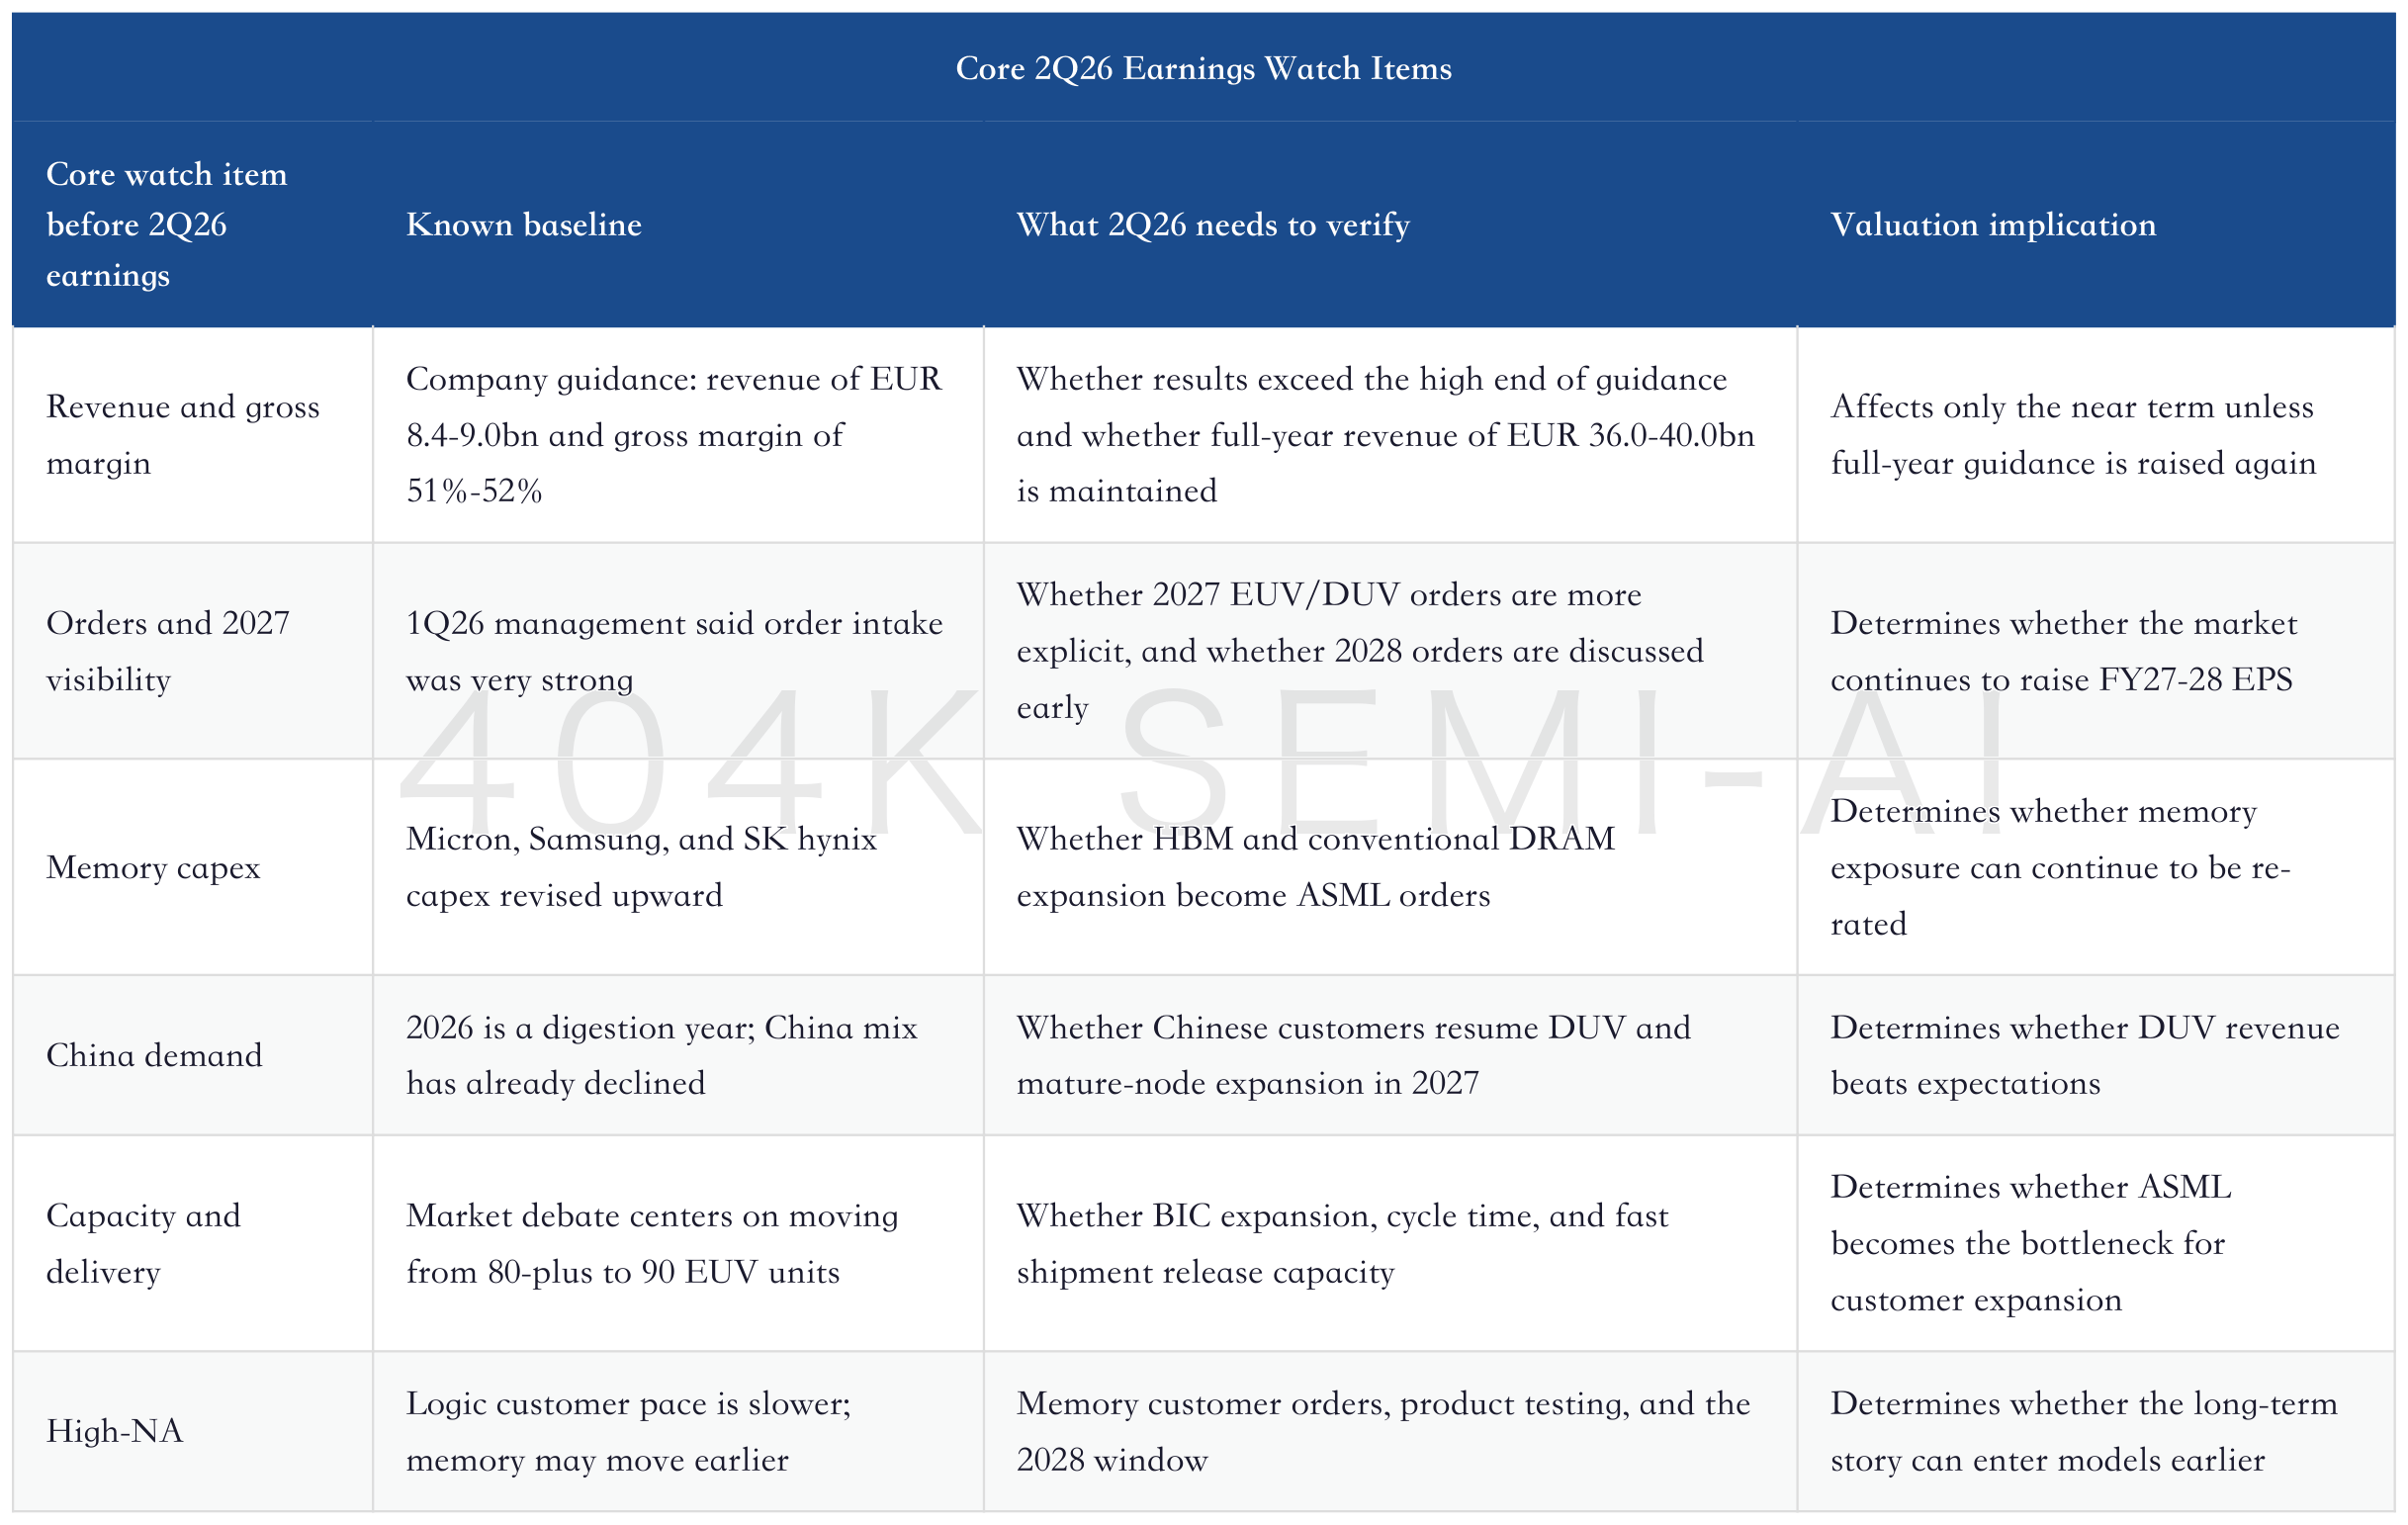
The quarterly numbers are not the main battlefield. As long as ASML’s 2Q26 lands within the company’s existing revenue and gross margin guidance, near-term disagreement should be limited. What can truly change valuation is whether management confirms 2027 order visibility, EUV capacity, and a DUV recovery. If the call merely repeats full-year guidance, the share-price reaction may be limited. If order and capacity commentary becomes more explicit, the market will continue to treat 2027, not 2026, as the main pricing year.
Memory is the first variable in this earnings release. Micron’s FY4Q26 capex is expected to be about USD 10bn, with full-year capex around USD 27bn, and FY2027 should rise materially again. In Samsung’s long-term 2026-2040 investment plan, about 76% is allocated to semiconductors. Lithography equipment has long delivery cycles, with EUV lead times exceeding 12 months. Memory makers’ capex today does not immediately become ASML revenue; it becomes 2027-2028 orders and capacity queues. That is exactly what matters most on the 2Q26 call.
China DUV is the second expectation gap. Chinese customers need to digest prior equipment purchases in 2026, and by the 2Q26 earnings release, the market has already treated a lower China mix as the base case. Goldman Sachs is more focused on whether 2027 demand for base memory, mature nodes, and DUV can re-expand. If management acknowledges that Chinese customers still have room for incremental equipment orders in 2027, ASML’s growth will not rely only on advanced logic and HBM; it will also regain underestimated DUV optionality.
Capacity for 90 EUV units defines the earnings ceiling. The prior debate was whether ASML can move from more than 80 EUV systems to about 90 or even higher. Morgan Stanley views the BIC cleanroom expansion and delivery-cycle improvement as key to resolving the bottleneck. 2Q26 needs to verify whether the company continues preparing the supply chain for 90 EUV units, and whether 2028 order discussions emerge early. As long as the market believes capacity constraints are easing, 2027-2028 revenue and EPS upgrades are not over.
Watch memory for High-NA adoption first. Logic customers, especially hyperscale AI chips, are more cautious on stitching, design rules, and yield. DRAM may adopt High-NA earlier because die sizes are smaller and the payoff is more direct. If the 2Q26 call includes clear comments on High-NA orders from memory customers, product testing, or a 2028 adoption window, High-NA will move from a long-dated story into the valuation sooner. If commentary remains limited to broad R&D; progress, the near term will still be driven mainly by Low-NA and DUV.
Valuation is no longer cheap, but the earnings anchor is still moving. Goldman Sachs raised its 12-month target price for ASML to EUR 2,000, effectively lifting its FY27-2030 earnings anchor rather than betting only on a 2Q26 quarterly beat. The risk is that the share price is already discounting a strong cycle. If 2Q26 orders, 2027 China demand, or High-NA evidence disappoint, valuation will compress first. But if memory capex continues turning into EUV and DUV orders, the market will keep shifting toward 2028 earnings.
1. This Earnings Release Needs to Answer Not “Was Q2 Good?” but “Is 2027 Enough?”
ASML will report 2Q26 earnings on July 15, 2026. The official schedule is to release the press statement first, followed by an investor call hosted by CEO Christophe Fouquet and CFO Roger Dassen. The company already provided clear 2Q26 and full-year guidance in 1Q26, so the market is well prepared for the quarterly revenue range.
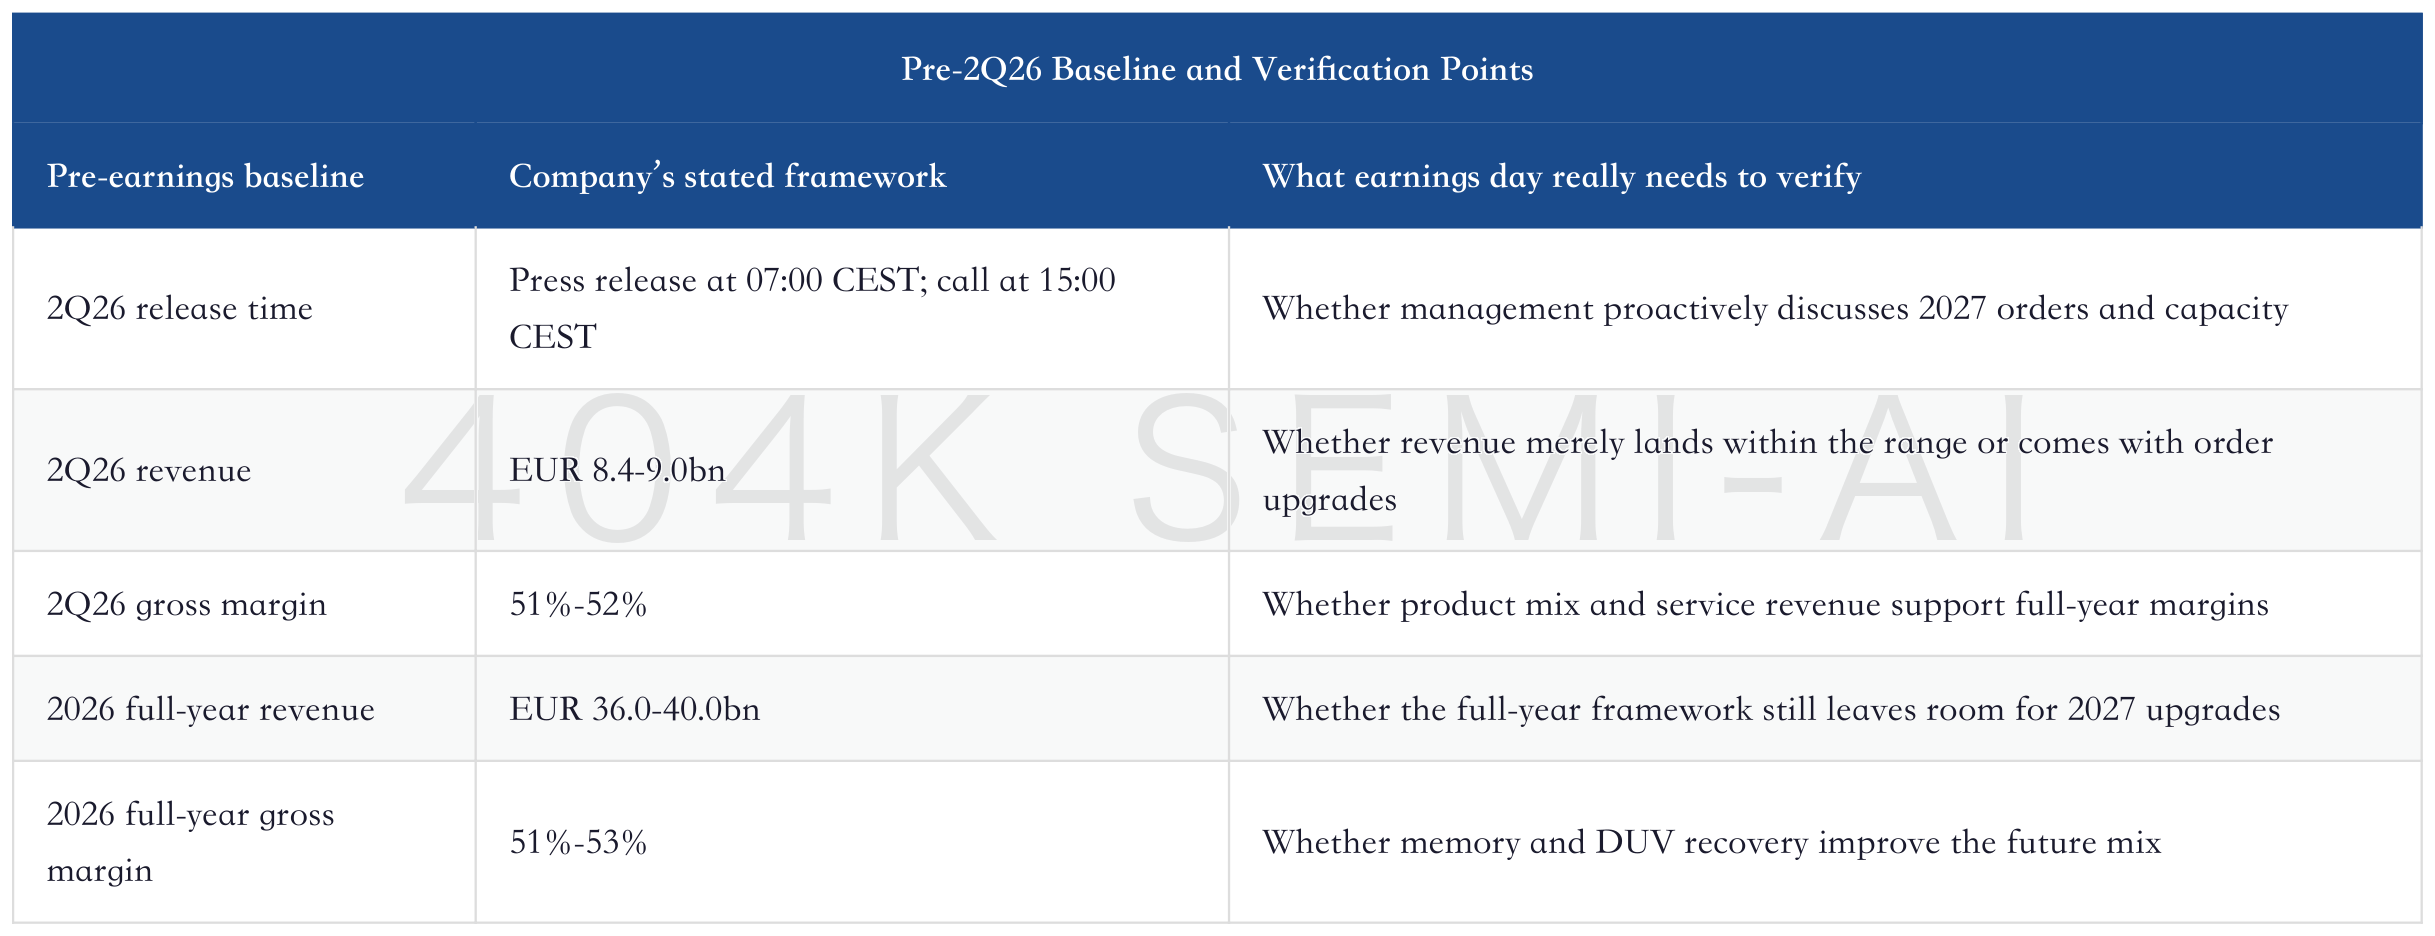
Therefore, the core question for 2Q26 is not whether the company can hit the midpoint of guidance. On the midpoint, ASML needs to deliver about EUR 8.7bn of revenue and a 51%-52% gross margin, which the market already expects. What really matters is how management describes 2027 orders, capacity, regional mix, and customer mix. The pricing anchor on earnings day will shift from “Is 2026 stable?” to “Is there still upside in 2027?”
1Q26 already answered half of the short-cycle questions. The company reported net sales of EUR 8.767bn, gross margin of 53.0%, net income of EUR 2.757bn, and EPS of EUR 7.15. More importantly, the company raised and narrowed its full-year revenue guidance to EUR 36.0-40.0bn from a wider range. Management emphasized at the time that AI-related infrastructure investment continued to drive chip demand above supply, and customers were accelerating capacity expansion plans for 2026 and beyond.
What 2Q26 needs to verify is whether that statement has moved from “demand is strong” to “orders are longer-dated.” If the story is only strong demand, ASML remains a high-quality equipment leader. If orders have already filled more of 2027 and part of 2028, it shifts again from an equipment cyclical into a long-term bottleneck asset in the AI capex cycle.
II. Memory Capex Puts ASML Back in the Bottleneck Position
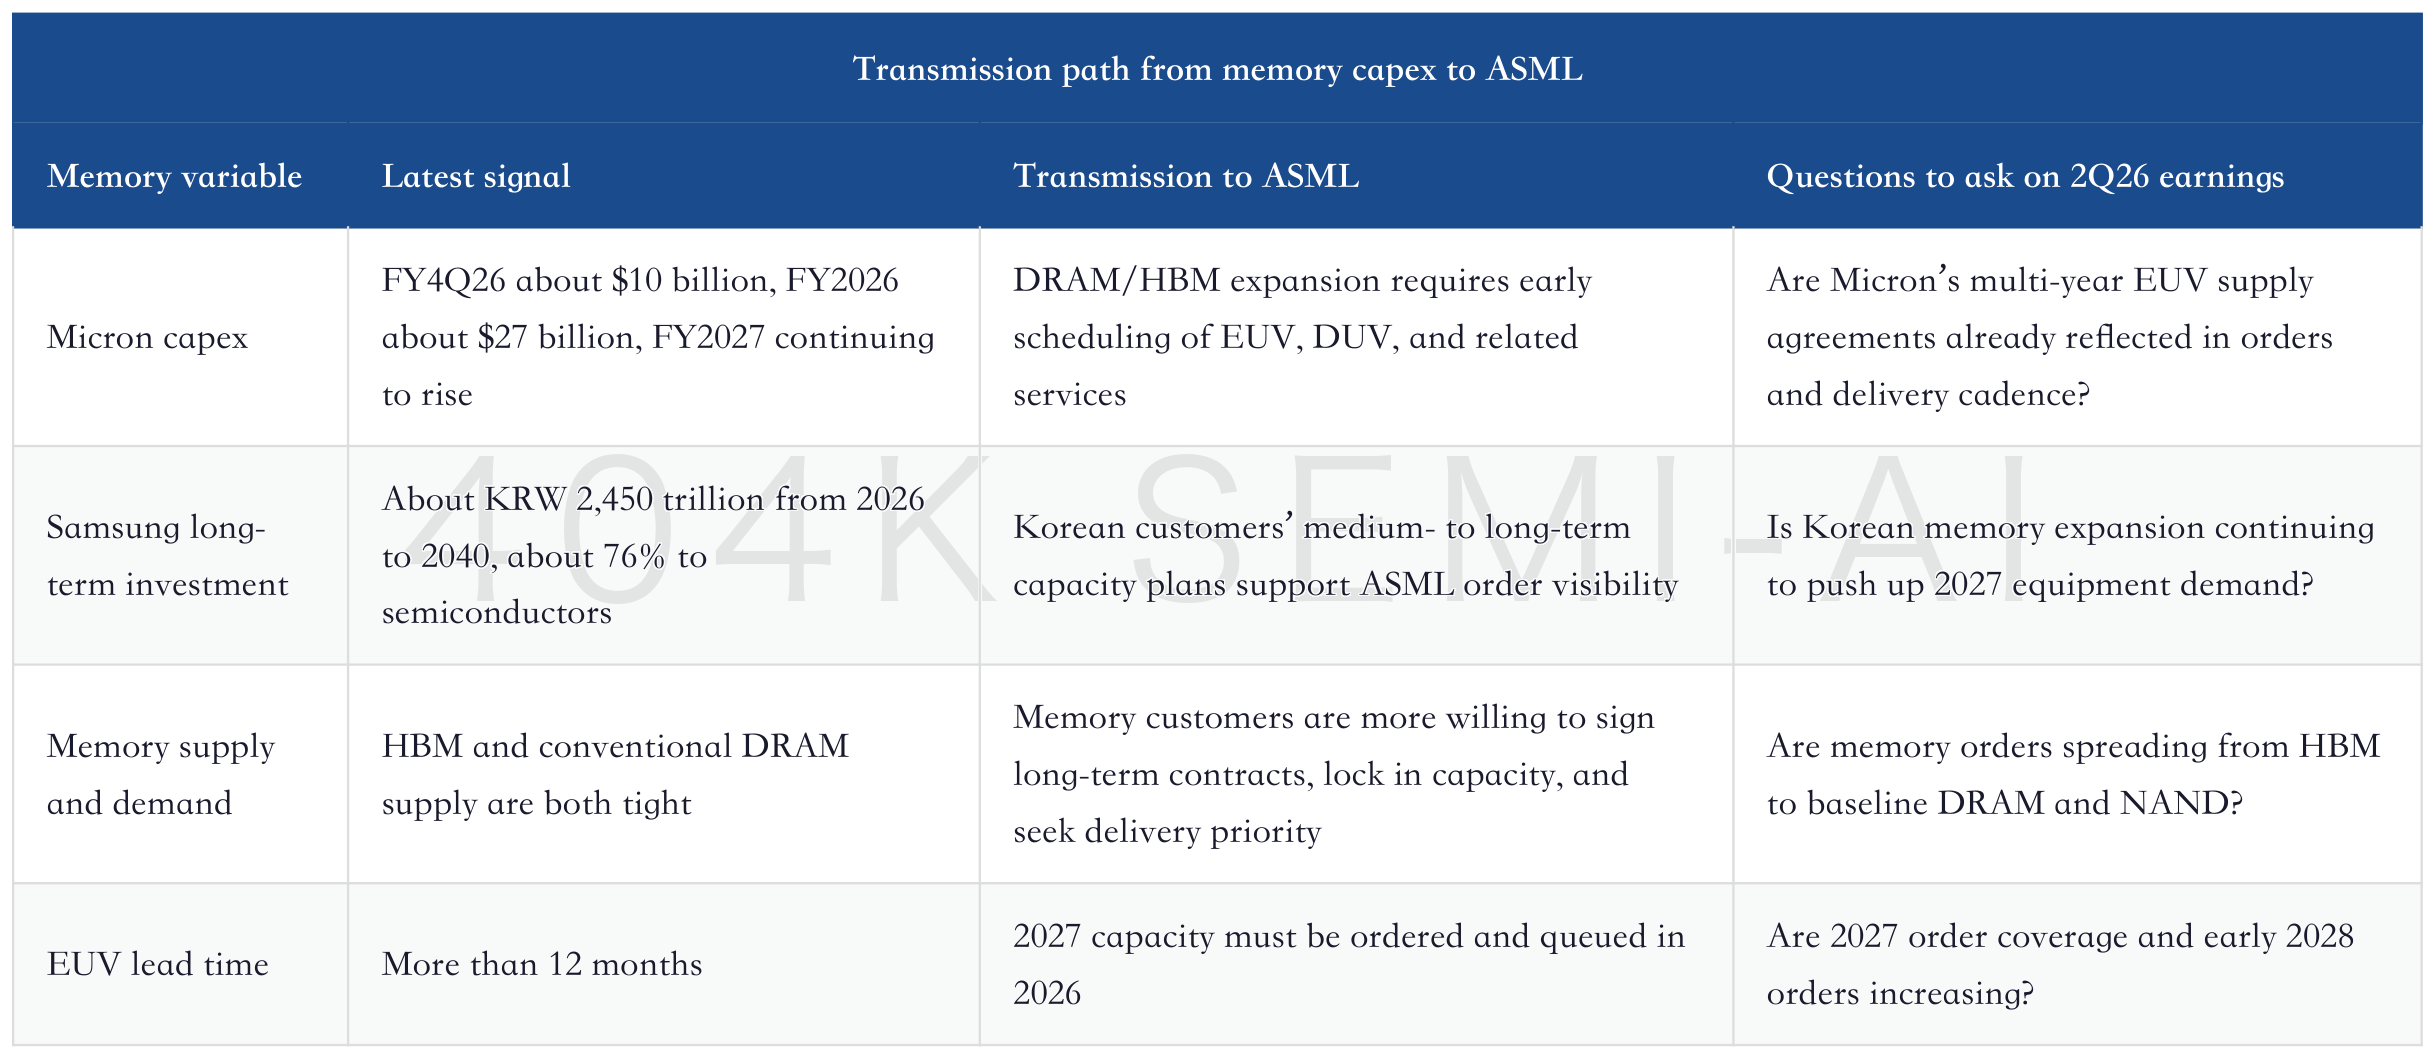
Before this 2Q26 earnings release, the strongest new variable comes from memory. The core of Goldman Sachs’ July 1 report update was not simply raising the target price, but reincorporating Micron, Samsung, and memory capex data into ASML’s revenue model. Micron’s capex cadence after FY3Q26 is critical: about $10 billion in FY4Q26, about $27 billion in FY2026, and another significant YoY increase in FY2027, with a large share of the incremental spending tied to cleanroom construction.
For ASML, the significance is not one quarter, but order lead time. EUV tool lead times exceed 12 months. If memory makers want to release 1-gamma, 1-delta, HBM, and conventional DRAM capacity in 2027, they must get key tools into the queue in 2H26. ASML does not benefit only after customers expand capacity; it begins locking in orders when customers decide their expansion roadmap.
Micron Technology FY2026 Third-Quarter Post-Earnings Analyst Call Notes
Samsung’s long-term investment plan further amplifies this signal. Based on the figures cited in Goldman Sachs’ report, Samsung plans to invest about KRW 2,450 trillion from 2026 to 2040, with roughly 76% going to semiconductors. Even though this figure includes both capex and R&D;, and is not equivalent to equipment orders that can be booked directly, it still shows that Korean memory manufacturers are treating the AI cycle as a multi-year supply-side restructuring.
ASML’s sensitivity to memory is more direct than that of most semiconductor equipment companies. In 1Q26, memory already rose from 30% of ASML system sales by end use in 4Q25 to 51%, surpassing logic for the first time. This shows memory expansion is not a thematic slogan, but has already entered the shipment mix. If management continues to confirm in 2Q26 that memory customers are extending orders, increasing prepayments, or seeking earlier delivery, the market will reinterpret this memory cycle from “price increases” to “an extended front-end equipment cycle.”
Memory also has an easily underestimated second-order effect on ASML: it will change the customer mix. Over the past two years, the market has been used to viewing ASML as a “shadow asset of TSMC advanced logic.” But after 1Q26, Korean and U.S. memory customers, as well as Chinese mature-node customers, are becoming important again. The more diversified the customer mix, the less ASML depends on the single roadmap of any one advanced logic customer, and the easier it is for valuation to move beyond a framework that only tracks TSMC’s 2nm cadence.
Deep Memory Update: Korea’s $3.1 Trillion AI Investment Plan and How to Revalue DRAM, NAND, and the Equipment Chain
III. 2027 DUV and China Demand Are the Second Expectation Gap
The second variable in ASML’s 2Q26 earnings is Chinese customers. After 1Q26, the market has already accepted that China demand is entering a digestion phase in 2026: some 2025 shipments need to be installed and absorbed, and export-control discussions have also made order cadence more cautious. This is no longer new. The real disagreement is about 2027.
Goldman Sachs’ view is that digestion in 2026 does not equal weakness in 2027. Chinese customers still have expansion plans in baseline memory, mature nodes, and certain non-advanced logic areas, while tight conventional memory supply and demand will create opportunities for Chinese manufacturers to gain overseas market share. As long as these expansion plans come with equipment orders, ASML’s DUV business has room to be revised upward again.
This view is corroborated by another change in 1Q26. ASML management had already changed its description of the non-EUV business from “roughly flat” to “expected to grow,” and noted that the prior slow start in DUV immersion had reversed. In other words, DUV is not an undervalued tail within mature nodes, but the second pillar of revenue elasticity in 2026-2027.
For investors, there are three sentences to listen for on the 2Q26 call. First, whether the company still describes China in 2026 as a digestion period. Second, whether the company hints that China demand has room to recover in 2027. Third, whether the company links China DUV demand with global memory expansion. If all three appear, ASML’s 2027 revenue model cannot be explained only by advanced logic and EUV.
The WFE Supercycle Has Just Begun: How AI Capex Is Driving Semiconductor Equipment Toward $250 Billion
The key to DUV is not technological appeal, but earnings elasticity and breadth of coverage. EUV has a high ASP and strong technical barriers, but DUV still has broad use cases in mature nodes, memory support, front-end steps related to advanced packaging, and Chinese customer demand. As long as customers add capacity for AI servers, HBM support, conventional DRAM, NAND, and mature logic, DUV orders will not simply fluctuate with the advanced logic cycle.
If 2Q26 only shows China’s share remaining low, it should not be interpreted directly as negative. A more reasonable view is that the low 2026 share is already known by the market. If management remains conservative, there is no new upside to valuation; if management says 2027 order discussions are beginning to recover, that is the expectation gap.
IV. 90 EUV Units Is the Hard Threshold for Whether ASML Can Capture the Memory Cycle
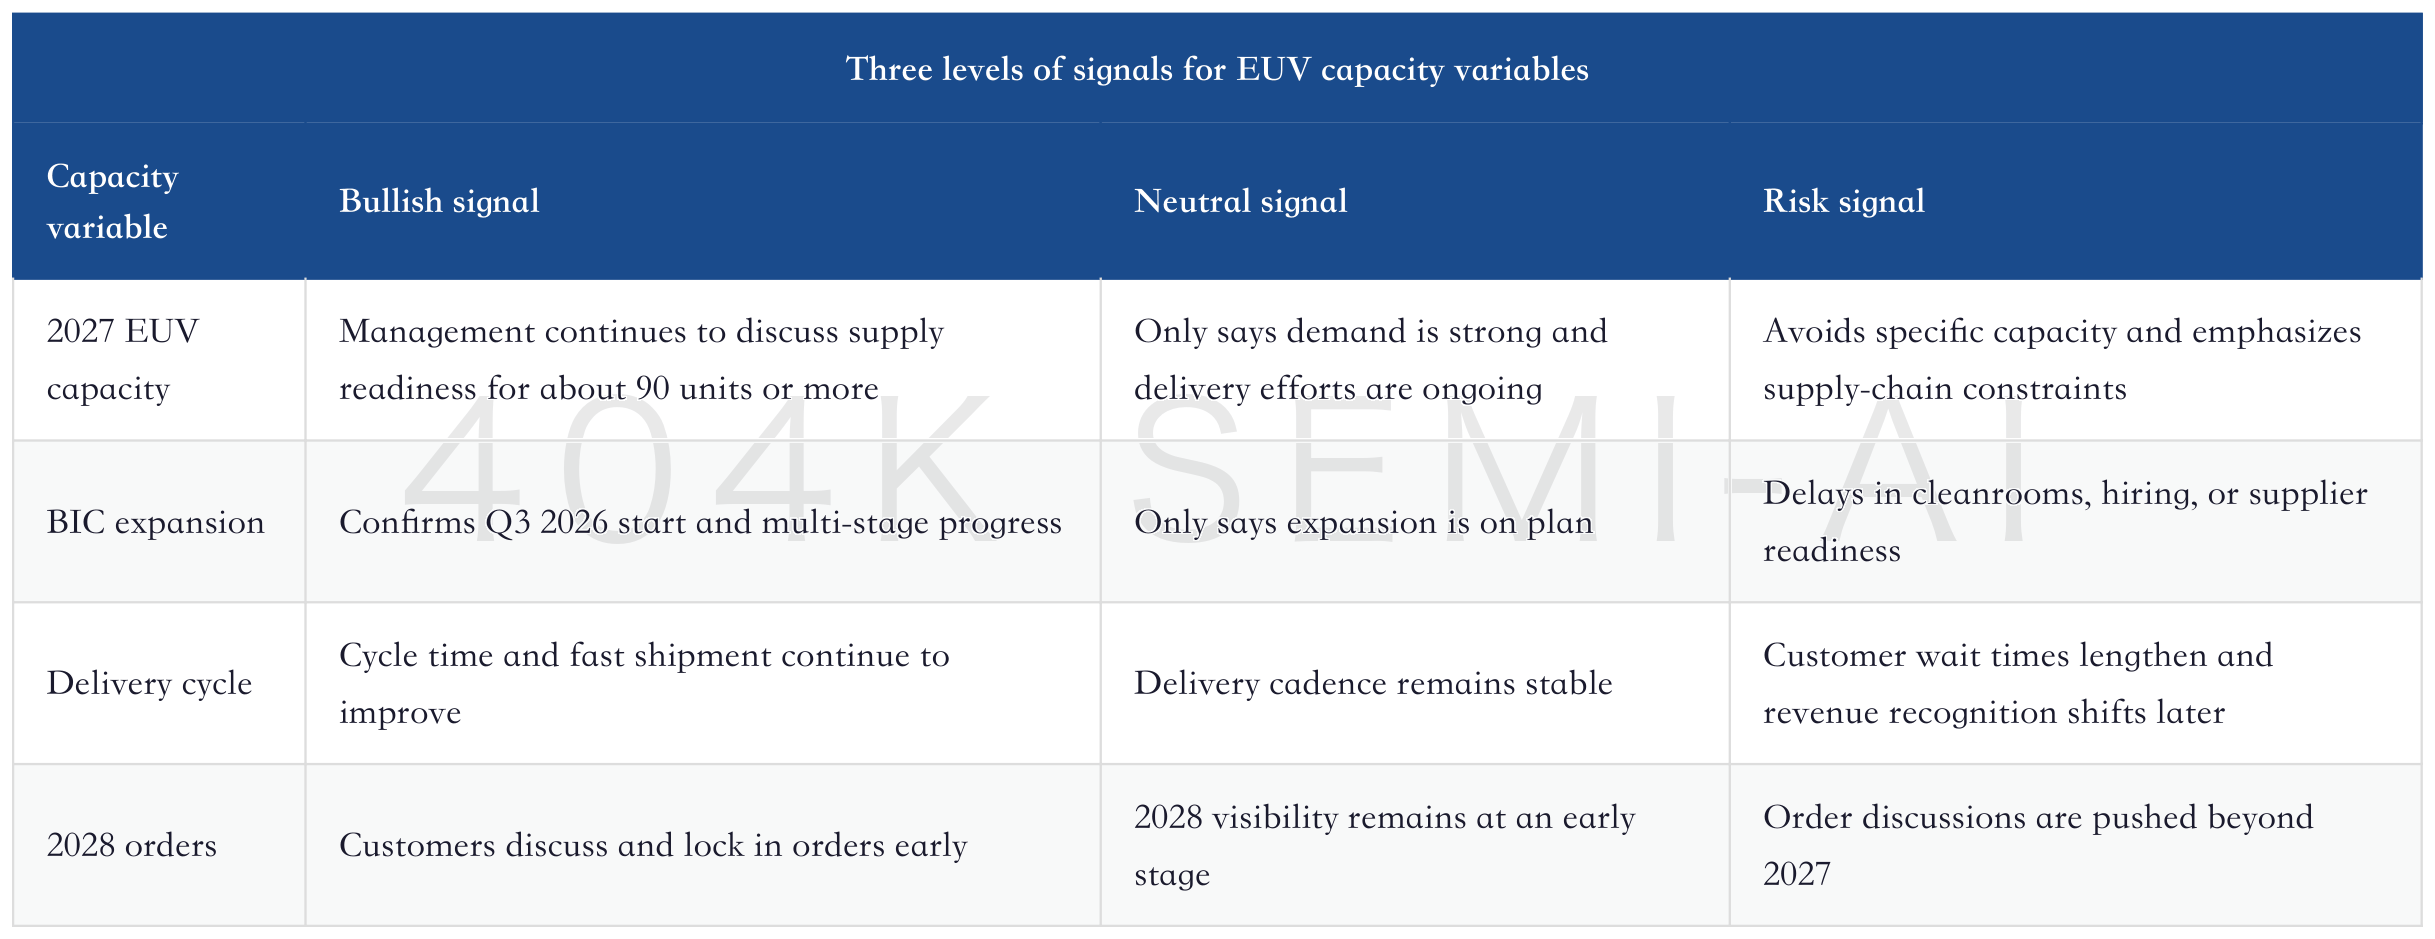
ASML’s biggest problem now is not whether there is demand, but whether it can deliver. After 1Q26, the market debate has centered on the 80-plus EUV unit capacity mentioned by management. Morgan Stanley’s June report focused on cleanroom expansion, hiring, and multi-stage capacity buildout at the Brainport Industries Campus, concluding that ASML has a chance to meet demand for about 90 EUV tools in 2027 and raise capacity further to more than 100 units in 2028.
This issue matters directly for earnings pricing. If ASML can only deliver 80-plus EUV units, even strong customer demand will become deferred orders, limiting revenue and EPS realization. If the company can push capacity close to 90 units through cycle-time improvement, fast shipment, supply-chain readiness, and BIC expansion, 2027 revenue and gross margin will both be supported.
Equipment Capex Ledger Update: AI Financing, $250 Billion WFE, and Semiconductor Equipment Repricing
The capacity issue will also affect customer behavior. If customers believe ASML capacity is tight, they will place orders earlier, pay earlier, and be more willing to sign long-term arrangements. This in turn improves ASML’s order visibility. This is especially true for memory customers, because as EUV layer counts increase in HBM and advanced DRAM nodes, tool demand is not a one-off inventory rebuild, but tied to node migration.
The 2Q26 call needs to focus on four details: whether 2027 EUV capacity preparation is still centered around about 90 units; whether BIC expansion is proceeding according to a Q3 2026 start and subsequent multi-stage path; whether supply-chain bottlenecks in light sources, lenses, cleanrooms, and assembly are easing; and whether customers have already begun locking in 2028 orders. A positive answer to any of these questions would lead the market to discount 2028 EPS earlier.
V. High-NA Is Not the Near-Term Revenue Driver, but Memory Could Pull the Story Forward
The market debate around High-NA has cooled somewhat over the past two months, mainly because logic customers are adopting it more cautiously. Large AI logic chips are typically close to reticle size, making stitching, design rules, random defects, and inspection challenges more complex. It is therefore not surprising that TSMC is in no rush to transition at the high-end logic node.
But this does not mean the High-NA story is over. The key reminder from Bank of America’s May report is that DRAM customers may adopt High-NA ahead of logic customers, because DRAM die are smaller and the benefits mainly come from lower critical-layer costs, simplified process steps, and yield improvement. UBS also emphasized that High-NA’s value is not only resolution, but also reducing multipatterning, lowering critical-layer costs, and freeing up capacity.
In ASML’s 2Q26 results, the most valuable High-NA signal is not that “the company remains positive on High-NA.” The market has heard that line many times. What matters is concrete customer activity: whether memory customers are starting to place orders, whether High-NA is being used for real product testing, whether it enters production nodes around 2028, and whether there is a clearer cadence related to Samsung, SK Hynix, or Intel.
If these signals appear, ASML’s long-term valuation will gain another layer of support. The market currently uses Low-NA EUV and DUV to explain 2027 upgrades, and High-NA to explain opportunities after 2030. If memory customers pull High-NA forward to 2028, the valuation horizon will move closer. Conversely, if the call still only discusses the technology roadmap without customer orders or production windows, High-NA should remain a long-term option in the near term and should not become the main trading line for 2Q26.
VI. Valuation Framework: Behind the EUR 2,000 Target Price, the Market Is Buying FY27-28 EPS
Goldman Sachs raised its 12-month target price for ASML to EUR 2,000. The core change is not a renewed bet on a single-quarter 2Q26 profit beat, but a broader upward shift in the earnings anchor for the coming years. The upgrades mainly come from memory capex, advanced-node demand, and a recovery in China DUV in 2027. The valuation multiple also reflects higher growth visibility.
This means Goldman is not buying a 2Q26 single-quarter beat, but an upward move in the FY27-28 earnings anchor. As long as the 2Q26 results can prove these upgrades are not a one-off sentiment move, the valuation will have a continued basis to hold. Conversely, if orders, capacity, and the China DUV commentary are not sufficiently solid, the target-price upgrade will look more like a sentiment peak.
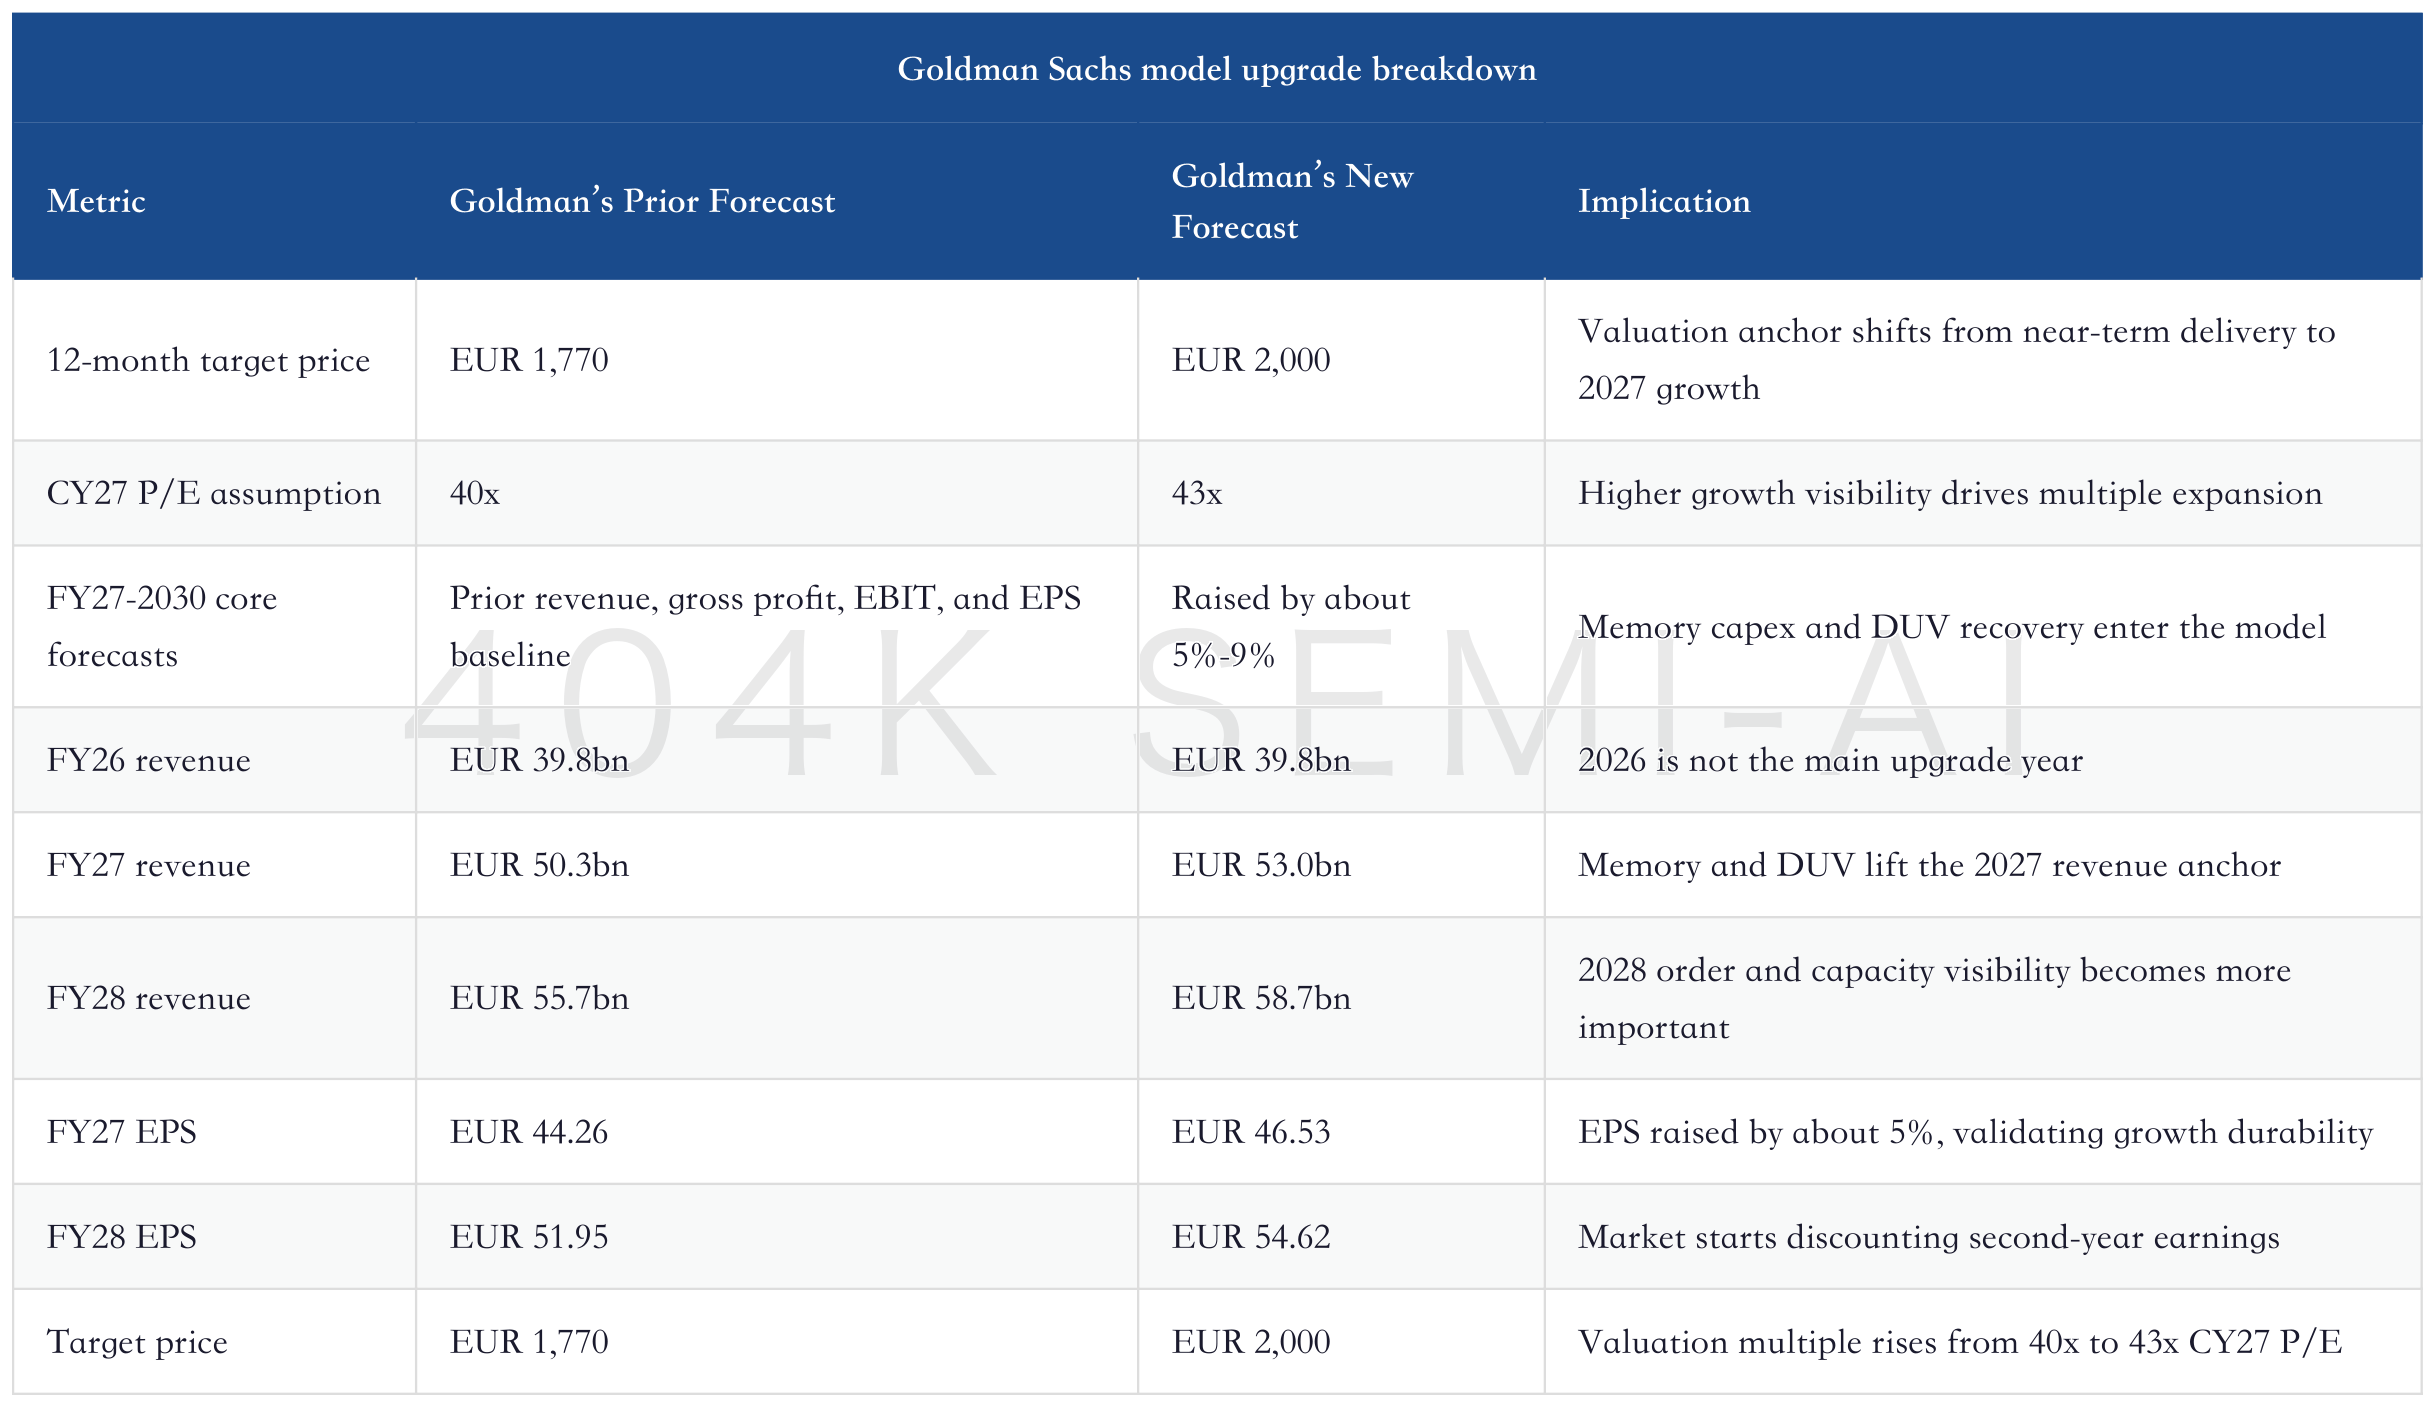
The valuation risk is also here. ASML is not a cheap stock. Under Goldman’s model, when the share price was around EUR 1,721 on June 30, it already implied roughly 32x two-year forward P/E, near the mid-to-high end of its long-term historical range. If the 2Q26 call lacks evidence on orders and capacity, the share price may first digest valuation rather than wait for FY27 delivery.
But if management provides three types of information, the market will still be willing to pay a premium: first, memory customer orders extending into 2027 and initial discussion of 2028; second, greater company confidence in 90 EUV units of capacity; third, China DUV demand moving from digestion in 2026 to recovery in 2027. ASML’s valuation has never been based only on current profits, but on whether the next round of customer capex is already lining up.
VII. Three Earnings Scenarios: Orders in the Short Term, Capacity in the Medium Term, High-NA in the Long Term
ASML’s 2Q26 is better assessed through a scenario framework than by only guessing revenue and EPS. Revenue and gross margin already have company guidance, and single-quarter variance may not change the long-term view. Orders, capacity, and 2027 commentary will determine whether the post-results share-price reaction is “good news already priced in” or “the earnings anchor continues to move higher.”
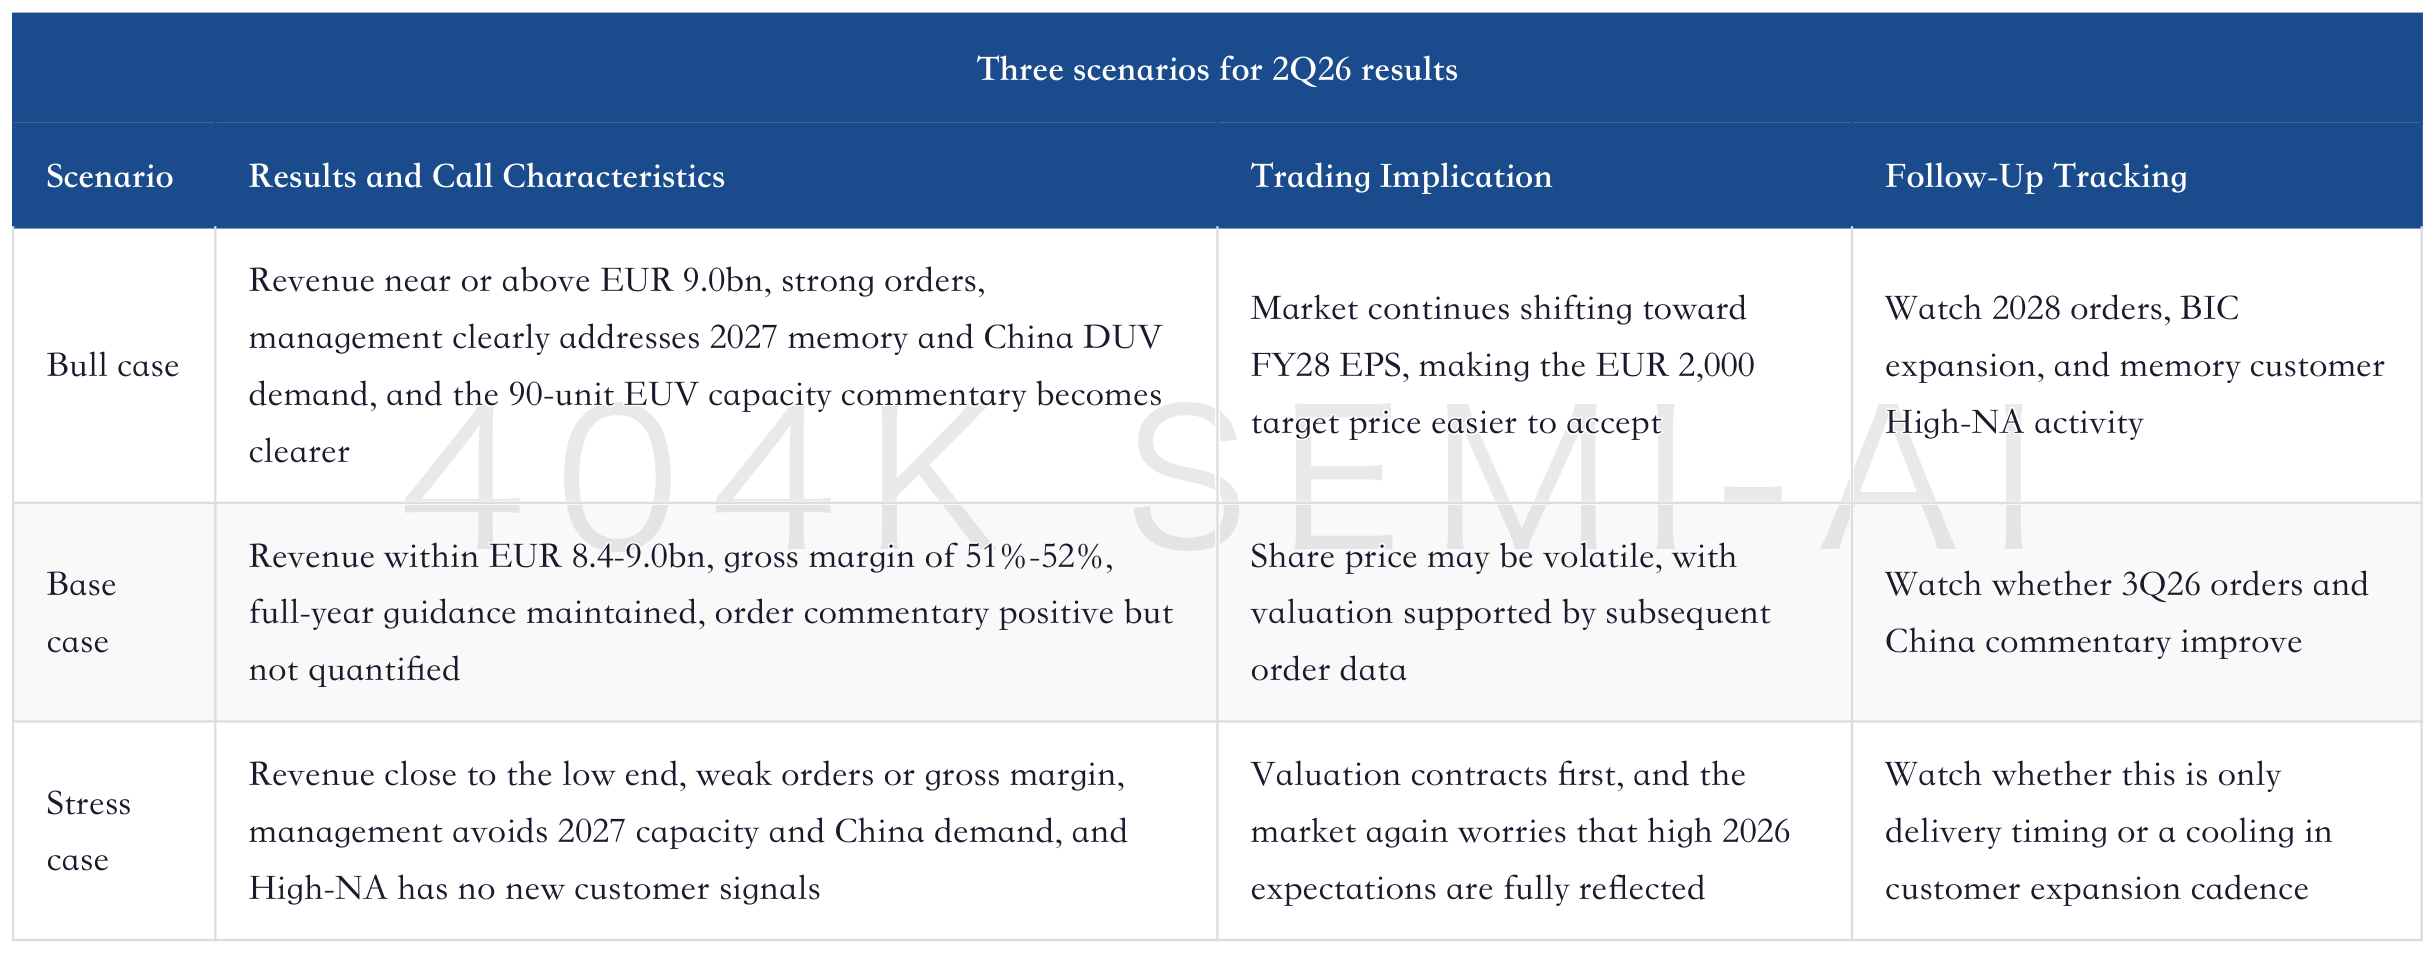
The biggest risk is “good numbers, weak commentary.” If 2Q26 revenue and EPS are slightly better, but answers on orders, 2027 demand, and capacity are vague, the share price may not respond positively. ASML’s current trading setup does not lack proof that “this quarter was good”; it lacks evidence that “next year will be even stronger.”
Conversely, if revenue merely meets guidance but the call clearly confirms 2027 memory expansion, EUV capacity readiness, and DUV recovery, the market may look past flat single-quarter revenue. The core of semiconductor equipment stocks is not current-quarter shipments, but visibility into orders and customer capex over the next four to eight quarters.
VIII. Earnings-Day Checklist: Four Questions Determine the Quality of This Report
First, watch orders rather than only revenue. Revenue is the recognition of past orders; orders are the shadow of future revenue. If 2Q26 orders are strong but revenue is flat, the quality of the report is still not poor. If revenue beats expectations but orders are ordinary, valuation will become more cautious.
Second, watch the 2027 China DUV commentary. The 2026 digestion period is already consensus; the real incremental upside is in 2027. As long as management acknowledges that Chinese customers still have room for recovery in mature-node, baseline memory, and DUV orders, the market will reassess the growth elasticity of the non-EUV business.
Third, watch the EUV capacity commentary. More than 80 units, 90 units, and more than 100 units are not three ordinary numbers; they represent three different earnings ceilings. 2Q26 needs to confirm whether ASML can convert customer demand into actual deliveries, rather than become the physical bottleneck in AI chip capacity expansion.
Fourth, watch whether High-NA moves from roadmap to orders. Caution among logic customers does not mean High-NA has failed; memory customers may move first. If the earnings call can link High-NA to DRAM nodes, real product testing, and 2028 orders, the long-term valuation will become more robust.
Together, these questions determine whether ASML is “the leader in the AI equipment cycle whose rally is already done” or “a bottleneck asset still undervalued as AI capex continues to broaden.” The answer for 2Q26 is not in a single income statement, but in management’s concrete description of 2027-2028 delivery capacity and customers’ willingness to expand.
9. Disconfirmation Conditions and Tracking Indicators
The long thesis for ASML is clear: AI infrastructure investment drives simultaneous capacity expansion in advanced logic, HBM, and conventional memory; customers lock in EUV and DUV capacity in advance; and ASML converts orders into FY27-28 revenue and EPS through capacity expansion and mix improvement. This thesis is most vulnerable to three things.
First, memory capex may not translate into lithography orders. If Micron, Samsung, and SK Hynix are only building cleanrooms, expanding packaging and testing, or delaying front-end equipment purchases, ASML’s benefit will be pushed out. After 2Q26, the key items to track are order disclosures, customer prepayments, memory-related EUV shipments, and the share of Korean customers.
Second, EUV capacity improvement may lag customer demand. If BIC expansion, supplier readiness, light-source availability, and assembly cycles do not improve meaningfully, strong demand will become a delivery bottleneck. Here, investors should watch the 2027 EUV shipment framework, the share of fast shipments, customer waiting times, and 2028 order visibility.
Third, a DUV recovery in China may not materialize. If Chinese customers continue digesting inventory in 2027 rather than placing new orders, the upside revision potential for Non-EUV will weaken, and ASML’s growth will again become overly dependent on advanced logic and memory. Here, investors should track China’s revenue share, DUV orders, mature-node customer capacity expansion, and the export-control framework.
Finally, High-NA needs empirical validation. Its long-term value remains intact, but in the near term, valuation cannot be supported by technology demonstrations alone. If the 2Q26 call and subsequent calls do not show memory customer orders, real product testing, or a 2028 adoption window, High-NA should still be treated as a long-dated option rather than an earnings driver for the next 12 months.
Memory deep dive: Memory stocks pulled back, but DRAM prices are surging, NAND is emerging from restocking, and KV cache is pushing AI demand toward SSDs
The conclusion from ASML’s earnings report can be compressed into one sentence: revenue and gross margin determine the day’s share-price volatility, while orders and capacity determine the direction of valuation. As long as memory capex continues turning into EUV/DUV orders, the path to 90 EUV units of capacity is not disproven, and the possibility of a China DUV recovery in 2027 remains alive, ASML remains the hardest-to-replace bottleneck asset in the AI capex chain, and the one customers are most likely to reserve in advance.ASML Q2 Earnings Preview: Memory Capex, 90 EUV Units of Capacity, and China DUV Recovery
目录
Too Long; Didn’t Read
1. This Earnings Release Needs to Answer Not “Was Q2 Good?” but “Is 2027 Enough?”
II. Memory Capex Puts ASML Back in the Bottleneck Position
III. 2027 DUV and China Demand Are the Second Expectation Gap
IV. 90 EUV Units Is the Hard Threshold for Whether ASML Can Capture the Memory Cycle
V. High-NA Is Not the Near-Term Revenue Driver, but Memory Could Pull the Story Forward
VI. Valuation Framework: Behind the EUR 2,000 Target Price, the Market Is Buying FY27-28 EPS
VII. Three Earnings Scenarios: Orders in the Short Term, Capacity in the Medium Term, High-NA in the Long Term
VIII. Earnings-Day Checklist: Four Questions Determine the Quality of This Report
9. Disconfirmation Conditions and Tracking Indicators
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
ASML reports 2Q26 on July 15. What the market really needs to assess is not whether quarterly revenue lands near the EUR 8.4-9.0bn guide, but whether memory expansion, 2027 China DUV demand, 90 EUV units of capacity, and High-NA orders can keep lifting the 2027-2028 earnings anchor.
Too Long; Didn’t Read
The quarterly numbers are not the main battlefield. As long as ASML’s 2Q26 lands within the company’s existing revenue and gross margin guidance, near-term disagreement should be limited. What can truly change valuation is whether management confirms 2027 order visibility, EUV capacity, and a DUV recovery. If the call merely repeats full-year guidance, the share-price reaction may be limited. If order and capacity commentary becomes more explicit, the market will continue to treat 2027, not 2026, as the main pricing year.
Memory is the first variable in this earnings release. Micron’s FY4Q26 capex is expected to be about USD 10bn, with full-year capex around USD 27bn, and FY2027 should rise materially again. In Samsung’s long-term 2026-2040 investment plan, about 76% is allocated to semiconductors. Lithography equipment has long delivery cycles, with EUV lead times exceeding 12 months. Memory makers’ capex today does not immediately become ASML revenue; it becomes 2027-2028 orders and capacity queues. That is exactly what matters most on the 2Q26 call.
China DUV is the second expectation gap. Chinese customers need to digest prior equipment purchases in 2026, and by the 2Q26 earnings release, the market has already treated a lower China mix as the base case. Goldman Sachs is more focused on whether 2027 demand for base memory, mature nodes, and DUV can re-expand. If management acknowledges that Chinese customers still have room for incremental equipment orders in 2027, ASML’s growth will not rely only on advanced logic and HBM; it will also regain underestimated DUV optionality.
Capacity for 90 EUV units defines the earnings ceiling. The prior debate was whether ASML can move from more than 80 EUV systems to about 90 or even higher. Morgan Stanley views the BIC cleanroom expansion and delivery-cycle improvement as key to resolving the bottleneck. 2Q26 needs to verify whether the company continues preparing the supply chain for 90 EUV units, and whether 2028 order discussions emerge early. As long as the market believes capacity constraints are easing, 2027-2028 revenue and EPS upgrades are not over.
Watch memory for High-NA adoption first. Logic customers, especially hyperscale AI chips, are more cautious on stitching, design rules, and yield. DRAM may adopt High-NA earlier because die sizes are smaller and the payoff is more direct. If the 2Q26 call includes clear comments on High-NA orders from memory customers, product testing, or a 2028 adoption window, High-NA will move from a long-dated story into the valuation sooner. If commentary remains limited to broad R&D; progress, the near term will still be driven mainly by Low-NA and DUV.
Valuation is no longer cheap, but the earnings anchor is still moving. Goldman Sachs raised its 12-month target price for ASML to EUR 2,000, effectively lifting its FY27-2030 earnings anchor rather than betting only on a 2Q26 quarterly beat. The risk is that the share price is already discounting a strong cycle. If 2Q26 orders, 2027 China demand, or High-NA evidence disappoint, valuation will compress first. But if memory capex continues turning into EUV and DUV orders, the market will keep shifting toward 2028 earnings.
1. This Earnings Release Needs to Answer Not “Was Q2 Good?” but “Is 2027 Enough?”
ASML will report 2Q26 earnings on July 15, 2026. The official schedule is to release the press statement first, followed by an investor call hosted by CEO Christophe Fouquet and CFO Roger Dassen. The company already provided clear 2Q26 and full-year guidance in 1Q26, so the market is well prepared for the quarterly revenue range.
Therefore, the core question for 2Q26 is not whether the company can hit the midpoint of guidance. On the midpoint, ASML needs to deliver about EUR 8.7bn of revenue and a 51%-52% gross margin, which the market already expects. What really matters is how management describes 2027 orders, capacity, regional mix, and customer mix. The pricing anchor on earnings day will shift from “Is 2026 stable?” to “Is there still upside in 2027?”
1Q26 already answered half of the short-cycle questions. The company reported net sales of EUR 8.767bn, gross margin of 53.0%, net income of EUR 2.757bn, and EPS of EUR 7.15. More importantly, the company raised and narrowed its full-year revenue guidance to EUR 36.0-40.0bn from a wider range. Management emphasized at the time that AI-related infrastructure investment continued to drive chip demand above supply, and customers were accelerating capacity expansion plans for 2026 and beyond.
What 2Q26 needs to verify is whether that statement has moved from “demand is strong” to “orders are longer-dated.” If the story is only strong demand, ASML remains a high-quality equipment leader. If orders have already filled more of 2027 and part of 2028, it shifts again from an equipment cyclical into a long-term bottleneck asset in the AI capex cycle.
II. Memory Capex Puts ASML Back in the Bottleneck Position
Before this 2Q26 earnings release, the strongest new variable comes from memory. The core of Goldman Sachs’ July 1 report update was not simply raising the target price, but reincorporating Micron, Samsung, and memory capex data into ASML’s revenue model. Micron’s capex cadence after FY3Q26 is critical: about $10 billion in FY4Q26, about $27 billion in FY2026, and another significant YoY increase in FY2027, with a large share of the incremental spending tied to cleanroom construction.
For ASML, the significance is not one quarter, but order lead time. EUV tool lead times exceed 12 months. If memory makers want to release 1-gamma, 1-delta, HBM, and conventional DRAM capacity in 2027, they must get key tools into the queue in 2H26. ASML does not benefit only after customers expand capacity; it begins locking in orders when customers decide their expansion roadmap.
Micron Technology FY2026 Third-Quarter Post-Earnings Analyst Call Notes
Samsung’s long-term investment plan further amplifies this signal. Based on the figures cited in Goldman Sachs’ report, Samsung plans to invest about KRW 2,450 trillion from 2026 to 2040, with roughly 76% going to semiconductors. Even though this figure includes both capex and R&D;, and is not equivalent to equipment orders that can be booked directly, it still shows that Korean memory manufacturers are treating the AI cycle as a multi-year supply-side restructuring.
ASML’s sensitivity to memory is more direct than that of most semiconductor equipment companies. In 1Q26, memory already rose from 30% of ASML system sales by end use in 4Q25 to 51%, surpassing logic for the first time. This shows memory expansion is not a thematic slogan, but has already entered the shipment mix. If management continues to confirm in 2Q26 that memory customers are extending orders, increasing prepayments, or seeking earlier delivery, the market will reinterpret this memory cycle from “price increases” to “an extended front-end equipment cycle.”
Memory also has an easily underestimated second-order effect on ASML: it will change the customer mix. Over the past two years, the market has been used to viewing ASML as a “shadow asset of TSMC advanced logic.” But after 1Q26, Korean and U.S. memory customers, as well as Chinese mature-node customers, are becoming important again. The more diversified the customer mix, the less ASML depends on the single roadmap of any one advanced logic customer, and the easier it is for valuation to move beyond a framework that only tracks TSMC’s 2nm cadence.
Deep Memory Update: Korea’s $3.1 Trillion AI Investment Plan and How to Revalue DRAM, NAND, and the Equipment Chain
III. 2027 DUV and China Demand Are the Second Expectation Gap
The second variable in ASML’s 2Q26 earnings is Chinese customers. After 1Q26, the market has already accepted that China demand is entering a digestion phase in 2026: some 2025 shipments need to be installed and absorbed, and export-control discussions have also made order cadence more cautious. This is no longer new. The real disagreement is about 2027.
Goldman Sachs’ view is that digestion in 2026 does not equal weakness in 2027. Chinese customers still have expansion plans in baseline memory, mature nodes, and certain non-advanced logic areas, while tight conventional memory supply and demand will create opportunities for Chinese manufacturers to gain overseas market share. As long as these expansion plans come with equipment orders, ASML’s DUV business has room to be revised upward again.
This view is corroborated by another change in 1Q26. ASML management had already changed its description of the non-EUV business from “roughly flat” to “expected to grow,” and noted that the prior slow start in DUV immersion had reversed. In other words, DUV is not an undervalued tail within mature nodes, but the second pillar of revenue elasticity in 2026-2027.
For investors, there are three sentences to listen for on the 2Q26 call. First, whether the company still describes China in 2026 as a digestion period. Second, whether the company hints that China demand has room to recover in 2027. Third, whether the company links China DUV demand with global memory expansion. If all three appear, ASML’s 2027 revenue model cannot be explained only by advanced logic and EUV.
The WFE Supercycle Has Just Begun: How AI Capex Is Driving Semiconductor Equipment Toward $250 Billion
The key to DUV is not technological appeal, but earnings elasticity and breadth of coverage. EUV has a high ASP and strong technical barriers, but DUV still has broad use cases in mature nodes, memory support, front-end steps related to advanced packaging, and Chinese customer demand. As long as customers add capacity for AI servers, HBM support, conventional DRAM, NAND, and mature logic, DUV orders will not simply fluctuate with the advanced logic cycle.
If 2Q26 only shows China’s share remaining low, it should not be interpreted directly as negative. A more reasonable view is that the low 2026 share is already known by the market. If management remains conservative, there is no new upside to valuation; if management says 2027 order discussions are beginning to recover, that is the expectation gap.
IV. 90 EUV Units Is the Hard Threshold for Whether ASML Can Capture the Memory Cycle
ASML’s biggest problem now is not whether there is demand, but whether it can deliver. After 1Q26, the market debate has centered on the 80-plus EUV unit capacity mentioned by management. Morgan Stanley’s June report focused on cleanroom expansion, hiring, and multi-stage capacity buildout at the Brainport Industries Campus, concluding that ASML has a chance to meet demand for about 90 EUV tools in 2027 and raise capacity further to more than 100 units in 2028.
This issue matters directly for earnings pricing. If ASML can only deliver 80-plus EUV units, even strong customer demand will become deferred orders, limiting revenue and EPS realization. If the company can push capacity close to 90 units through cycle-time improvement, fast shipment, supply-chain readiness, and BIC expansion, 2027 revenue and gross margin will both be supported.
Equipment Capex Ledger Update: AI Financing, $250 Billion WFE, and Semiconductor Equipment Repricing
The capacity issue will also affect customer behavior. If customers believe ASML capacity is tight, they will place orders earlier, pay earlier, and be more willing to sign long-term arrangements. This in turn improves ASML’s order visibility. This is especially true for memory customers, because as EUV layer counts increase in HBM and advanced DRAM nodes, tool demand is not a one-off inventory rebuild, but tied to node migration.
The 2Q26 call needs to focus on four details: whether 2027 EUV capacity preparation is still centered around about 90 units; whether BIC expansion is proceeding according to a Q3 2026 start and subsequent multi-stage path; whether supply-chain bottlenecks in light sources, lenses, cleanrooms, and assembly are easing; and whether customers have already begun locking in 2028 orders. A positive answer to any of these questions would lead the market to discount 2028 EPS earlier.
V. High-NA Is Not the Near-Term Revenue Driver, but Memory Could Pull the Story Forward
The market debate around High-NA has cooled somewhat over the past two months, mainly because logic customers are adopting it more cautiously. Large AI logic chips are typically close to reticle size, making stitching, design rules, random defects, and inspection challenges more complex. It is therefore not surprising that TSMC is in no rush to transition at the high-end logic node.
But this does not mean the High-NA story is over. The key reminder from Bank of America’s May report is that DRAM customers may adopt High-NA ahead of logic customers, because DRAM die are smaller and the benefits mainly come from lower critical-layer costs, simplified process steps, and yield improvement. UBS also emphasized that High-NA’s value is not only resolution, but also reducing multipatterning, lowering critical-layer costs, and freeing up capacity.
In ASML’s 2Q26 results, the most valuable High-NA signal is not that “the company remains positive on High-NA.” The market has heard that line many times. What matters is concrete customer activity: whether memory customers are starting to place orders, whether High-NA is being used for real product testing, whether it enters production nodes around 2028, and whether there is a clearer cadence related to Samsung, SK Hynix, or Intel.
If these signals appear, ASML’s long-term valuation will gain another layer of support. The market currently uses Low-NA EUV and DUV to explain 2027 upgrades, and High-NA to explain opportunities after 2030. If memory customers pull High-NA forward to 2028, the valuation horizon will move closer. Conversely, if the call still only discusses the technology roadmap without customer orders or production windows, High-NA should remain a long-term option in the near term and should not become the main trading line for 2Q26.
VI. Valuation Framework: Behind the EUR 2,000 Target Price, the Market Is Buying FY27-28 EPS
Goldman Sachs raised its 12-month target price for ASML to EUR 2,000. The core change is not a renewed bet on a single-quarter 2Q26 profit beat, but a broader upward shift in the earnings anchor for the coming years. The upgrades mainly come from memory capex, advanced-node demand, and a recovery in China DUV in 2027. The valuation multiple also reflects higher growth visibility.
This means Goldman is not buying a 2Q26 single-quarter beat, but an upward move in the FY27-28 earnings anchor. As long as the 2Q26 results can prove these upgrades are not a one-off sentiment move, the valuation will have a continued basis to hold. Conversely, if orders, capacity, and the China DUV commentary are not sufficiently solid, the target-price upgrade will look more like a sentiment peak.
The valuation risk is also here. ASML is not a cheap stock. Under Goldman’s model, when the share price was around EUR 1,721 on June 30, it already implied roughly 32x two-year forward P/E, near the mid-to-high end of its long-term historical range. If the 2Q26 call lacks evidence on orders and capacity, the share price may first digest valuation rather than wait for FY27 delivery.
But if management provides three types of information, the market will still be willing to pay a premium: first, memory customer orders extending into 2027 and initial discussion of 2028; second, greater company confidence in 90 EUV units of capacity; third, China DUV demand moving from digestion in 2026 to recovery in 2027. ASML’s valuation has never been based only on current profits, but on whether the next round of customer capex is already lining up.
VII. Three Earnings Scenarios: Orders in the Short Term, Capacity in the Medium Term, High-NA in the Long Term
ASML’s 2Q26 is better assessed through a scenario framework than by only guessing revenue and EPS. Revenue and gross margin already have company guidance, and single-quarter variance may not change the long-term view. Orders, capacity, and 2027 commentary will determine whether the post-results share-price reaction is “good news already priced in” or “the earnings anchor continues to move higher.”
The biggest risk is “good numbers, weak commentary.” If 2Q26 revenue and EPS are slightly better, but answers on orders, 2027 demand, and capacity are vague, the share price may not respond positively. ASML’s current trading setup does not lack proof that “this quarter was good”; it lacks evidence that “next year will be even stronger.”
Conversely, if revenue merely meets guidance but the call clearly confirms 2027 memory expansion, EUV capacity readiness, and DUV recovery, the market may look past flat single-quarter revenue. The core of semiconductor equipment stocks is not current-quarter shipments, but visibility into orders and customer capex over the next four to eight quarters.
VIII. Earnings-Day Checklist: Four Questions Determine the Quality of This Report
First, watch orders rather than only revenue. Revenue is the recognition of past orders; orders are the shadow of future revenue. If 2Q26 orders are strong but revenue is flat, the quality of the report is still not poor. If revenue beats expectations but orders are ordinary, valuation will become more cautious.
Second, watch the 2027 China DUV commentary. The 2026 digestion period is already consensus; the real incremental upside is in 2027. As long as management acknowledges that Chinese customers still have room for recovery in mature-node, baseline memory, and DUV orders, the market will reassess the growth elasticity of the non-EUV business.
Third, watch the EUV capacity commentary. More than 80 units, 90 units, and more than 100 units are not three ordinary numbers; they represent three different earnings ceilings. 2Q26 needs to confirm whether ASML can convert customer demand into actual deliveries, rather than become the physical bottleneck in AI chip capacity expansion.
Fourth, watch whether High-NA moves from roadmap to orders. Caution among logic customers does not mean High-NA has failed; memory customers may move first. If the earnings call can link High-NA to DRAM nodes, real product testing, and 2028 orders, the long-term valuation will become more robust.
Together, these questions determine whether ASML is “the leader in the AI equipment cycle whose rally is already done” or “a bottleneck asset still undervalued as AI capex continues to broaden.” The answer for 2Q26 is not in a single income statement, but in management’s concrete description of 2027-2028 delivery capacity and customers’ willingness to expand.
9. Disconfirmation Conditions and Tracking Indicators
The long thesis for ASML is clear: AI infrastructure investment drives simultaneous capacity expansion in advanced logic, HBM, and conventional memory; customers lock in EUV and DUV capacity in advance; and ASML converts orders into FY27-28 revenue and EPS through capacity expansion and mix improvement. This thesis is most vulnerable to three things.
First, memory capex may not translate into lithography orders. If Micron, Samsung, and SK Hynix are only building cleanrooms, expanding packaging and testing, or delaying front-end equipment purchases, ASML’s benefit will be pushed out. After 2Q26, the key items to track are order disclosures, customer prepayments, memory-related EUV shipments, and the share of Korean customers.
Second, EUV capacity improvement may lag customer demand. If BIC expansion, supplier readiness, light-source availability, and assembly cycles do not improve meaningfully, strong demand will become a delivery bottleneck. Here, investors should watch the 2027 EUV shipment framework, the share of fast shipments, customer waiting times, and 2028 order visibility.
Third, a DUV recovery in China may not materialize. If Chinese customers continue digesting inventory in 2027 rather than placing new orders, the upside revision potential for Non-EUV will weaken, and ASML’s growth will again become overly dependent on advanced logic and memory. Here, investors should track China’s revenue share, DUV orders, mature-node customer capacity expansion, and the export-control framework.
Finally, High-NA needs empirical validation. Its long-term value remains intact, but in the near term, valuation cannot be supported by technology demonstrations alone. If the 2Q26 call and subsequent calls do not show memory customer orders, real product testing, or a 2028 adoption window, High-NA should still be treated as a long-dated option rather than an earnings driver for the next 12 months.
Memory deep dive: Memory stocks pulled back, but DRAM prices are surging, NAND is emerging from restocking, and KV cache is pushing AI demand toward SSDs
The conclusion from ASML’s earnings report can be compressed into one sentence: revenue and gross margin determine the day’s share-price volatility, while orders and capacity determine the direction of valuation. As long as memory capex continues turning into EUV/DUV orders, the path to 90 EUV units of capacity is not disproven, and the possibility of a China DUV recovery in 2027 remains alive, ASML remains the hardest-to-replace bottleneck asset in the AI capex chain, and the one customers are most likely to reserve in advance.