
ASML Q2 Deep Dive: €9.326 Billion Revenue, 30% EUV Capacity Expansion in 2027, and a Sharp Increase in Full-Year Guidance
目录
TL;DR
1. This Was Not “Slightly Better Than Expected”—It Surpassed the Forward Bull Case
2. Quality of the Beat: Service and Upgrade Contributions Were Larger, While System Deliveries Also Expanded
3. H1 Mix: Memory Drives Incremental Growth, Logic Determines the Magnitude of H2 Upgrades
4. Full-Year Guidance Jumps: The Previous Bull Case Is Now the New Base Case
5. 2027 EUV: Orders Are Stronger Than Unit Guidance; 84–85 Units Is More Accurate Than 90–100
6. High-NA Has Crossed the Mass-Production Threshold, but Not Yet the Broad-Adoption Threshold
7. Cash Flow Recovered, but Rising Receivables Require Monitoring of Collections After Revenue Recognition
8. Review of Prior Expectations: What Was Validated, What Was Revised, and What Remains Unanswered
9. Earnings and Valuation: The High-End Model Has Gained Support, but the Most Bullish Assumptions Should Not Be Adopted Immediately
10. The Seven Numbers That Really Matter Next
Conclusion: The 2026 Upgrade Is Now Reflected; Supply Execution Becomes the Test in 2027
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This earnings report shifts the central debate from “whether growth is achievable in 2026” to “whether supply can keep pace with demand in 2027–2028”: the quarterly beat was driven primarily by upgrades, while the real valuation upside comes from sharply higher full-year guidance, near-fully booked 2027 EUV orders, and evidence of High-NA entering volume production.
TL;DR
ASML’s Q2 revenue of €9.3265 billion, 54.0% gross margin, and €7.59 EPS all exceeded the most optimistic mainstream pre-earnings thresholds. Revenue beat consensus by approximately 5.6%–5.7%, gross margin by 2.0–2.1 percentage points, and EPS by approximately 11%. However, the revenue and margin upside came primarily from Installed Base Management sales running approximately €300 million above the company’s initial expectations, rather than a sudden increase in EUV unit volumes.
The real change to the earnings anchor is the full-year guidance: 2026 revenue was raised from €36–40 billion to €43–45 billion, while gross-margin guidance increased from 51%–53% to 54%–56%. The revenue midpoint increased by €6 billion, or approximately 15.8%, while the gross-margin midpoint rose by 3 percentage points. This is no longer a move toward the upper end of the prior range; it effectively turns the previous bull case into the company’s new base case.
Q2 equipment demand was not weak, but the full €9.3265 billion of revenue should not be interpreted as an explosion in new-system demand. System sales reached €6.5648 billion, up 4.5% quarter on quarter, while Installed Base Management sales reached €2.7617 billion, up 11.0%. Lithography-system shipments increased from 79 to 91 units, but EUV remained at 16 units; the increase came primarily from immersion, dry, and KrF systems.
The debate over “90 EUV systems in 2027” has been partly resolved: orders are very strong, but absolute capacity is closer to 84–85 units. Using approximately 65 Low-NA EUV systems in 2026 as the baseline, ASML plans to expand capacity by approximately 30% in 2027, mathematically implying roughly 84.5 systems. This validates the previous base-case range of 84–90 units but falls short of the 90–100-unit bull-case threshold. However, the company said it has already received nearly all the EUV orders required for 2027, making demand visibility stronger than the absolute unit count suggests.
2028 and High-NA provide new evidence of longer-term upside. ASML has already received substantial EUV orders for 2028 and is studying a further capacity increase of approximately 30% following the 2027 expansion. On a compounded-growth basis, Low-NA EUV capacity could approach 110 units, but this is only a mathematical extrapolation, not company shipment guidance. Intel has deployed High-NA in certain process layers for 18A products now entering volume production, marking the first transition of High-NA from R&D; validation into actual high-volume products. However, this cannot yet be extrapolated to broad adoption by TSMC or memory customers.
The next step is not merely to chase revenue, but to monitor revenue quality and delivery constraints. The Q3 guidance midpoint of €11.5 billion and gross-margin midpoint of 56% imply that Q4 revenue would still need to reach approximately €14.4 billion to achieve the full-year revenue midpoint. Meanwhile, combined trade and finance receivables increased to €7.813 billion. The key factors to monitor are Q3 equipment-revenue conversion, the sustainability of service and upgrade demand, execution of the 2027 EUV capacity expansion, the emergence of a second High-NA volume-production customer, and cash collection following revenue recognition.
1. This Was Not “Slightly Better Than Expected”—It Surpassed the Forward Bull Case
The most important near-term questions before earnings were whether Q2 revenue could approach €9 billion, whether gross margin could reach approximately 52%, and whether the company would formally raise the lower end of full-year guidance. The actual results cleared those thresholds decisively: revenue reached €9.3265 billion, €326.5 million above the upper end of the company’s €8.4–9.0 billion guidance range; gross margin reached 54.0%, 2 percentage points above the top end of guidance; and basic EPS of €7.59 was also well above the €6.82–6.84 consensus range.
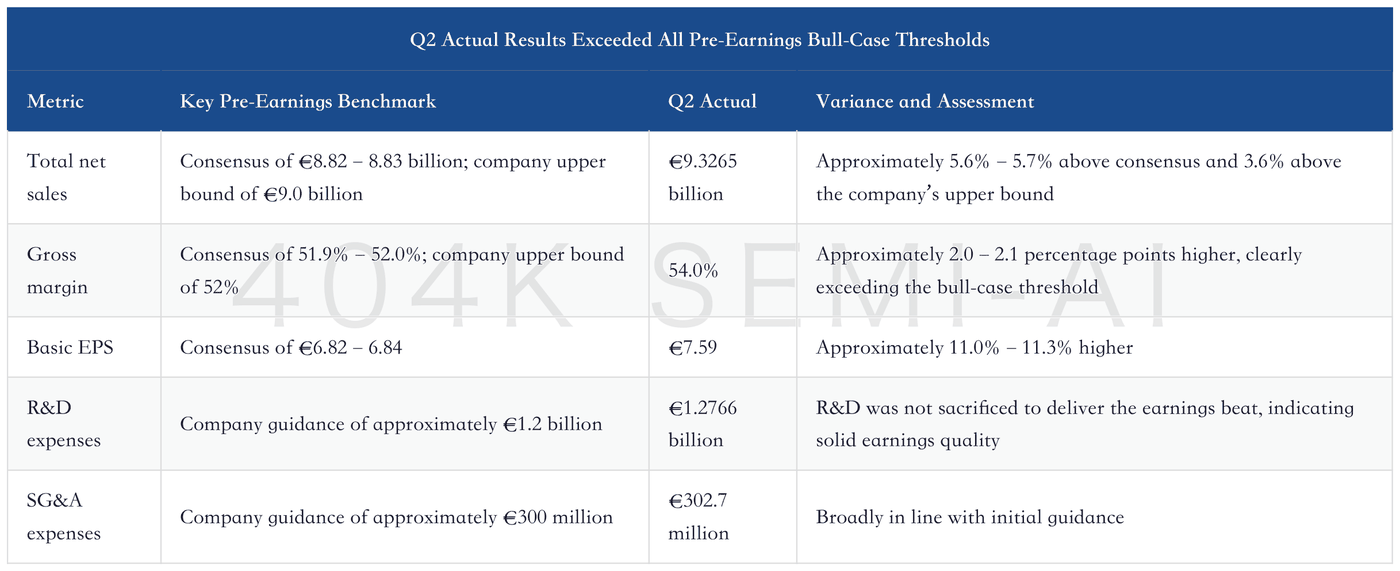
The quality of these results lies in the fact that the earnings beat was not achieved by cutting R&D; spending. Q2 R&D; expenses increased 9.4% year on year to €1.2766 billion, while SG&A; expenses remained broadly stable. Operating profit reached €3.4561 billion, up 29.7% year on year, while operating margin increased from 34.6% a year earlier to 37.1%. Revenue grew 21.3%, while operating profit increased by nearly 30%, demonstrating that operating leverage is now flowing through the income statement.
However, the broad-based beat should not be reduced to a broad-based upside surprise in new-system demand. Management explicitly stated that Installed Base Management sales came in approximately €300 million above expectations, driven primarily by software and upgrade projects that customers wanted to deploy immediately to improve the productivity of existing systems. These upgrades typically require shorter downtime and carry stronger margins, lifting both revenue and gross margin. Looking only at total revenue would therefore overstate the contribution of new-system deliveries to the quarterly beat.
ASML Q2 Earnings Preview: Memory Capex, 90-Unit EUV Capacity, and China DUV Recovery
2. Quality of the Beat: Service and Upgrade Contributions Were Larger, While System Deliveries Also Expanded
Q2 total revenue increased 6.4% quarter on quarter, with both system sales and Installed Base Management sales growing, although the latter expanded faster. System sales reached €6.5648 billion, up 4.5% quarter on quarter and 17.3% year on year. Installed Base Management sales reached €2.7617 billion, up 11.0% quarter on quarter and 31.8% year on year. Installed Base Management accounted for approximately 29.6% of total revenue, rising further from Q1. It is evolving from a “stabilizer” into an important driver of current-period growth and margins.
System volumes increased from 79 to 91 units, but the increase did not come from EUV. ASML shipped 16 EUV systems in Q2, unchanged from Q1. ArF immersion shipments increased from 17 to 23 units, ArF dry from 5 to 8, and KrF from 30 to 35, while I-line declined from 11 to 9. EUV’s share of system sales fell from 66% to 57%, while ArF immersion increased from 23% to 29%. This indicates that quarterly system-sales growth depended more heavily on the mix of mature lithography and immersion systems, rather than continued growth in shipments of the highest-value EUV systems.
The fact that gross margin increased to 54.0% even as EUV’s revenue contribution declined demonstrates the importance of service upgrades, volume absorption, and product mix. A single-variable framework in which a higher EUV mix automatically implies a higher gross margin cannot explain this quarter’s results. Management identified three drivers: a richer mix of high-margin upgrades, improved fixed-cost absorption from higher overall volumes, and a still-strong mix of EUV and immersion systems. Whether gross margin remains elevated in subsequent quarters will depend on all these factors continuing simultaneously, rather than EUV unit volumes alone.
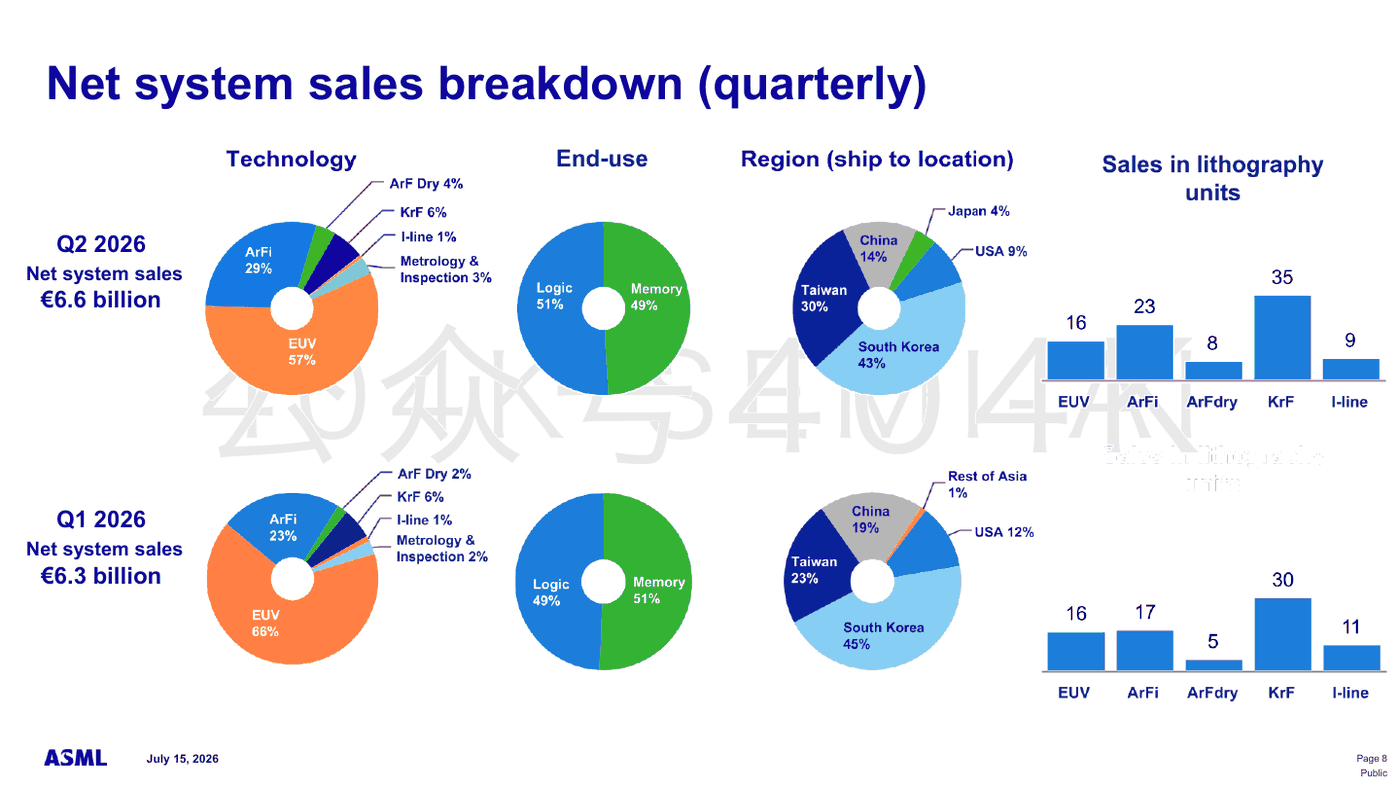
EUV accounted for 57% of ASML’s Q2 system sales, while logic and memory represented 51% and 49%, respectively. South Korea, Taiwan, China, the United States, and Japan accounted for 43%, 30%, 14%, 9%, and 4%, respectively. Source: ASML, “Q2 2026 Investor Relations Presentation,” p. 8.
The regional mix also indicates that Q1’s “sudden surge in memory and South Korea” is transitioning from an exceptional jump into sustained strength. South Korea still accounted for 43% of system sales in Q2, only 2 percentage points below Q1’s 45%. Taiwan increased from 23% to 30%, China declined from 19% to 14%, and the United States fell from 12% to 9%. This does not indicate a reversal in the memory cycle; rather, deliveries to advanced-logic customers accelerated again, shifting the end-market mix from 49% logic and 51% memory in Q1 to 51% logic and 49% memory in Q2.
3. H1 Mix: Memory Drives Incremental Growth, Logic Determines the Magnitude of H2 Upgrades
H1 total revenue was €18.0934 billion, up 17.2% year over year. Memory was the strongest source of incremental systems revenue, while logic will determine whether estimates continue to rise in H2. H1 systems revenue was €12.8442 billion, up 13.3% year over year; installed base management revenue was €5.2492 billion, up 28.1%. Within systems revenue, logic contributed €6.4427 billion, down 10.0%, while memory contributed €6.4015 billion, up 53.2%. The absolute figures were nearly identical, but their sources of growth were entirely different.
Memory strength is not merely a function of quarterly shipment volatility. Management expects memory revenue to grow approximately 75% in 2026, as demand for DDR and high-bandwidth memory prompts major customers to accelerate capacity expansion, while advanced memory nodes increase both EUV and advanced immersion lithography intensity. The investment implication is straightforward: ASML benefits both directly from high-bandwidth memory and from improving server-memory supply-demand conditions spreading into broader DRAM capital expenditure.
The year-over-year decline in H1 logic revenue does not imply weak logic demand. Management expects full-year advanced foundry logic revenue to grow approximately 25%, driven by capacity additions at existing 5nm, 4nm, and 3nm nodes, an accelerating 2nm ramp, and customers beginning to evaluate 1.4nm. Weak H1 logic revenue primarily reflects deferred deliveries and revenue recognition; the Q3 revenue guidance range of €11 billion–€12 billion is a direct signal that logic-equipment revenue is beginning to accelerate.
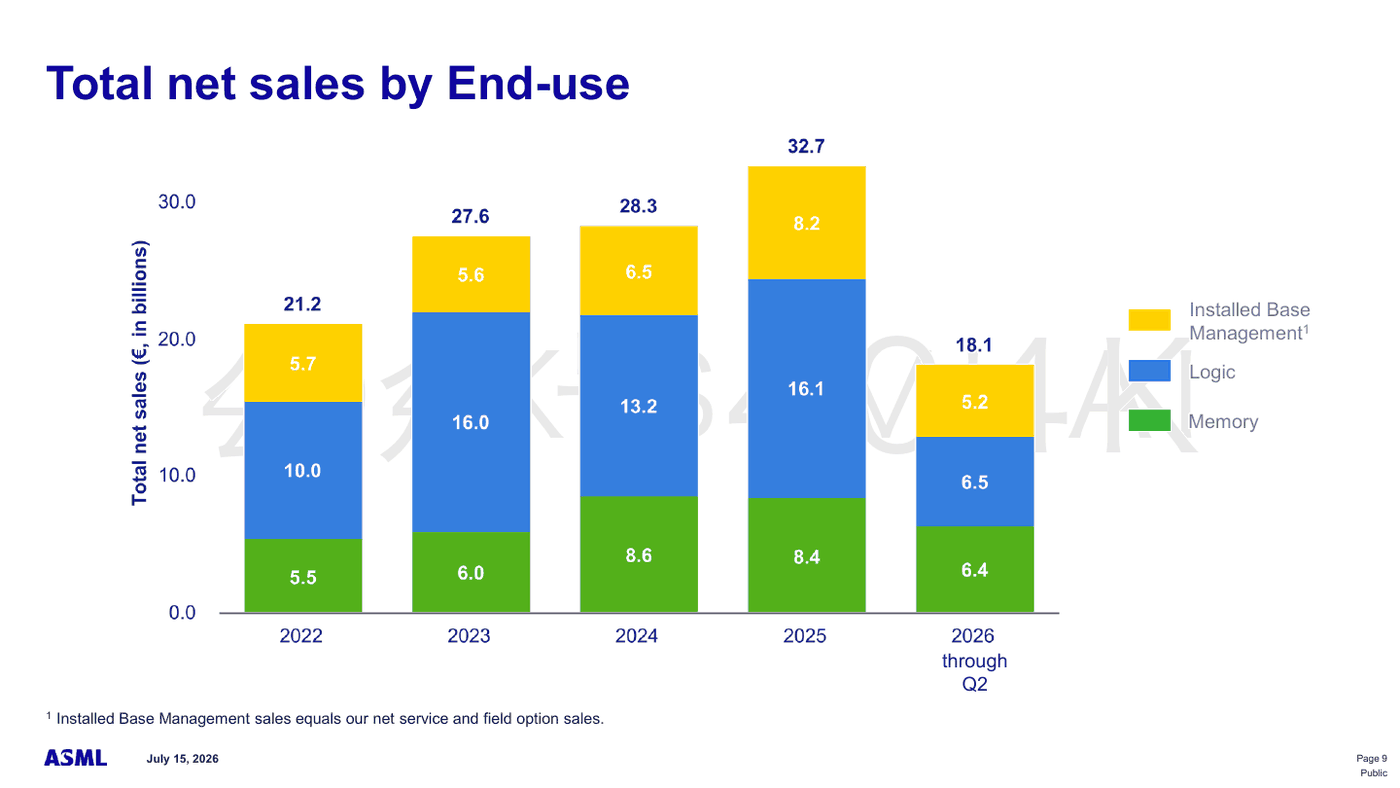
H1 2026 total revenue was €18.1 billion, comprising €6.4 billion from memory, €6.5 billion from logic, and €5.2 billion from installed base management. Source: ASML Q2 2026 Investor Relations Presentation, p. 9.
Product revenue further reveals a mix of accelerating advanced equipment and diverging mature-node equipment. H1 EXE revenue from High-NA EUV was €1.1889 billion, approximately 4.34 times the prior-year level; NXE revenue from Low-NA EUV was €6.7085 billion, up 19.9% year over year; KrF revenue was €772.6 million, up 55.9%; and dry ArF grew 90.0%. By contrast, ArF immersion revenue declined 22.5% year over year, although Q2 unit shipments recovered substantially, consistent with the company’s full-year plan of approximately 130 units, broadly flat with the prior year.
Geographically, South Korea contributed most of the incremental memory growth, while Taiwan began to capture the logic ramp. H1 total revenue from South Korea was €7.0855 billion, up 60.5% year over year; Taiwan contributed €5.1147 billion, up 17.3%; China contributed €2.8833 billion, down 22.3%; and the US contributed €1.9396 billion, broadly flat. Taiwan’s share of quarterly systems revenue rose to 30% in Q2, the first visible indication that deferred advanced-logic deliveries are beginning to alter the regional mix.
4. Full-Year Guidance Jumps: The Previous Bull Case Is Now the New Base Case
The strongest hard data point in this earnings report was not that Q2 revenue exceeded expectations by several hundred million euros, but that the company raised its entire 2026 revenue and gross-margin ranges. Full-year revenue guidance was raised from €36 billion–€40 billion to €43 billion–€45 billion. The midpoint increased by €6 billion, from €38 billion to €44 billion, or approximately 15.8%. Gross-margin guidance was raised from 51%–53% to 54%–56%, lifting the midpoint by three percentage points.
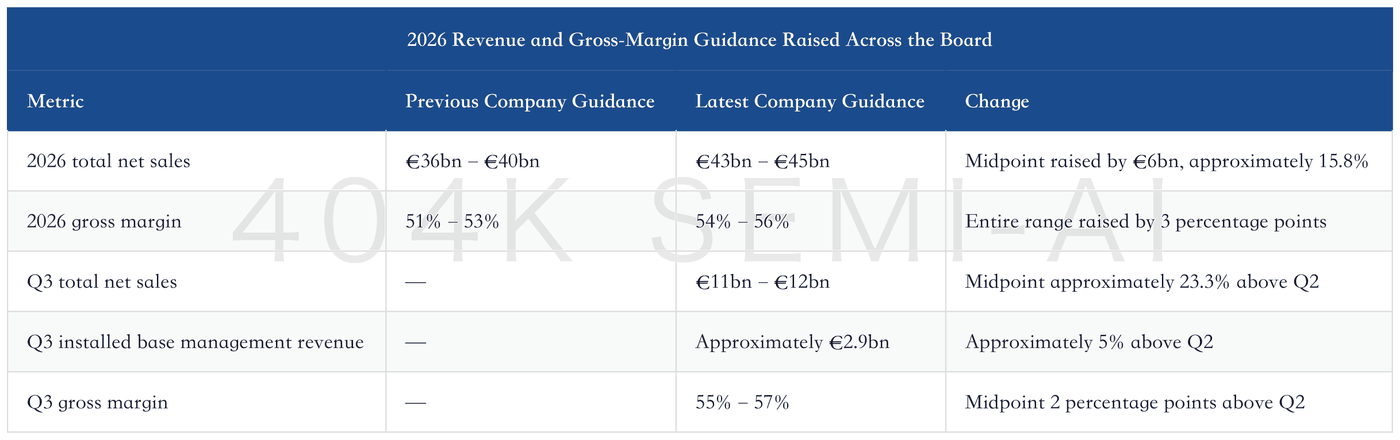
Most investment-bank forecasts had remained at €39.4 billion–€39.8 billion, and the low end of the company’s latest guidance now exceeds those estimates. This means earnings models require more than a modest upward adjustment within the old range; revenue scale, product mix, and fixed-cost absorption must be rebuilt. The simultaneous increase in the gross-margin range is particularly important: it indicates that the €6 billion revenue upgrade is not being driven by an accumulation of low-margin equipment, but by the combined effects of upgrades, the EUV/immersion mix, and improved volume absorption.
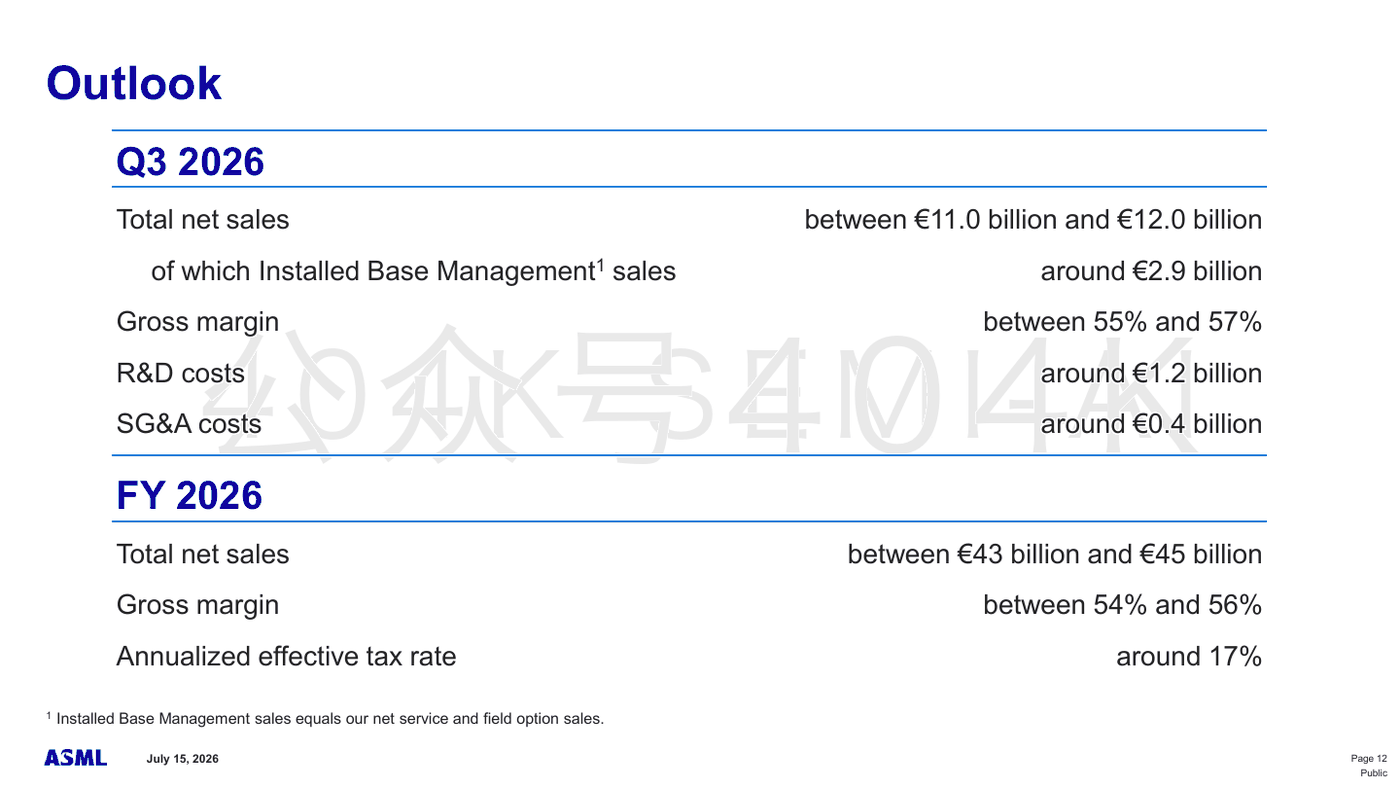
ASML guided to Q3 revenue of €11 billion–€12 billion and a gross margin of 55%–57%, while raising its 2026 revenue and gross-margin guidance to €43 billion–€45 billion and 54%–56%, respectively. Source: ASML Q2 2026 Investor Relations Presentation, p. 12.
However, the higher guidance also raises the execution threshold considerably. H1 revenue was €18.0934 billion. If Q3 reaches the €11.5 billion midpoint, Q4 would still need to contribute approximately €14.41 billion to achieve the full-year midpoint of €44 billion. This is not standalone Q4 guidance from the company, but a mathematical derivation. It indicates that revenue recognition is heavily weighted toward H2, and any delays in fast-shipment acceptance, customer fab readiness, or the supply chain could create substantial quarterly volatility.
5. 2027 EUV: Orders Are Stronger Than Unit Guidance; 84–85 Units Is More Accurate Than 90–100
The issue most easily conflated before the earnings release was whether “90 units” referred to capacity, shipments, or revenue recognition. Management’s latest wording is clearer: it expects to deliver approximately 65 Low-NA EUV systems in 2026, with EUV revenue growing approximately 45%; from this base, it plans to increase EUV capacity by approximately 30% in 2027. Multiplying 65 by 1.3 yields 84.5 units. It is therefore more accurate to describe 2027 Low-NA EUV capacity as approximately 84–85 units—not as a company commitment to ship 90 units, much less recognize revenue on 90 units.
These figures validate the previous base case but do not reach the bull-case threshold of 90–100 units. On absolute unit volumes alone, the earnings report provided no new evidence above the upper end of the prior outlook. Including High-NA separately could take total EUV system volumes above the Low-NA figure, but the company did not disclose an absolute 2027 High-NA unit count in these materials. The two categories therefore cannot be combined simply to produce a “90-unit” figure.
The order picture, however, is stronger than previously expected. ASML stated that it has already received nearly all the EUV orders required for 2027 and has also received a substantial number of EUV orders for 2028. The key phrase is “the orders the company believes are required to meet 2027 EUV demand.” This cannot be extrapolated to mean that the company’s entire 2027 order book is fully committed. It does, however, indicate that capacity expansion is being undertaken with support from customer long-term agreements and order visibility, rather than being built ahead of demand.
The 2028 upside comes from a second 30% capacity expansion. The company is assessing a further increase of approximately 30% in EUV capacity in 2028 from the 2027 base. On a compounded basis, multiplying 84.5 units by 1.3 yields approximately 109.9 units, or close to 110. This figure is only a mathematical indication of potential capacity scale and should not be presented as the company’s committed 2028 shipment volume. Revenue will also depend on the High-NA/Low-NA mix, fast-shipment acceptance, customer fab progress, and average selling prices.
DUV is also entering an expansion cycle, with larger absolute unit volumes. The company expects to deliver approximately 130 ArF immersion systems in 2026 and increase capacity by approximately 30% in 2027, implying around 169 units. It is also assessing a further increase of approximately 30% in 2028, which would bring compounded capacity close to 220 units. DUV and metrology and inspection revenue is expected to grow approximately 25% in 2026, meaning ASML’s growth is no longer reliant solely on leading-edge EUV. Mature nodes, memory capacity expansion, and upgrades to the installed base are collectively expanding the profit pool.
