
目录
Executive Summary
As Demand Broadens, Execution and Delivery Capacity Begin to Determine Revenue
Faster Capacity Expansion Shifts Bottlenecks to Equipment and Facilities
TSMC Retains Control of the Leading Edge; Mature-Node Pricing Will Rise Only Selectively
ASIC Volumes Are Set to Rise, but Profit Allocation Remains Uncertain
Substrates, CCL, and PCBs Capture More Board-Level Value
Tight Memory Supply Has Not Produced a Broad Consumer-Electronics Recovery
Profit Ranking Depends on Delivery, Cost Pass-Through, and Capital Returns
Testing the Next 3 Years Against 4 Sets of Metrics
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
AI hardware demand continues to expand, but the tightest constraints have extended beyond compute chips to cleanrooms, advanced-packaging equipment, substrates, and PCB delivery.
Executive Summary
JPMorgan’s August 25 Asia technology field trip covered 37 companies and 115 investors. Demand for GPUs, ASICs, and servers remains robust, while Neoclouds and large enterprises are emerging as new buyers alongside cloud service providers. Order visibility now extends into 2027.
Supply bottlenecks are moving downstream along the capacity-expansion sequence. Major Asian OSAT companies are increasing 2026 capital expenditure by more than 80% year over year. Lead times for CoW equipment have reached 12 months, while brownfield conversions require at least 6—9 months. Advanced-packaging capacity could remain tight through 2027—2028.
The ASIC revenue pool continues to expand, but supplier market shares and margins remain uncertain. Cloud service providers are increasingly adopting the CoT model and splitting individual projects among multiple design-service vendors. The final allocation of TPU v10 work remains undecided, with related revenue expected to begin contributing only in 2029.
Substrates, CCL, PCBs, liquid cooling, and memory are capturing greater content per system. HBM average selling prices are forecast to rise 43% year over year in 2027, while total memory content value per server is forecast to increase 28%. ASICs could also become the primary source of incremental liquid-cooling revenue from 2027.
Whether capacity expansion translates into profit will require continued validation through lead times, yields, price increases, gross margins, and cash returns. The focus in 2H26 will be on pricing and qualification, followed by revenue and profit delivery in 2027, and whether a wave of new supply depresses prices from 2028 onward.
As Demand Broadens, Execution and Delivery Capacity Begin to Determine Revenue
The most important shift in the current AI hardware upcycle is the simultaneous expansion of both the buyer base and the number of platforms. During its 11th Asia Technology Tour, JPMorgan met with 37 companies and 115 investors. The supply chain delivered a consistent message: GPU and ASIC demand remains elevated, cloud service providers continue to show strong purchasing appetite, and Neoclouds and large enterprises are beginning to procure or customize servers directly.
Changes in the order mix will amplify delivery pressure across the supply chain. Traditional cloud service providers have mature design, procurement, and supply-chain management capabilities. Neoclouds and enterprise customers place greater emphasis on delivery speed, customization, and total cost, with some already approaching server manufacturers such as Hon Hai and Quanta directly for bespoke systems. As compute demand broadens beyond a small number of major customers, the same component, packaging, and equipment capacity must support more platforms and a wider range of product configurations.
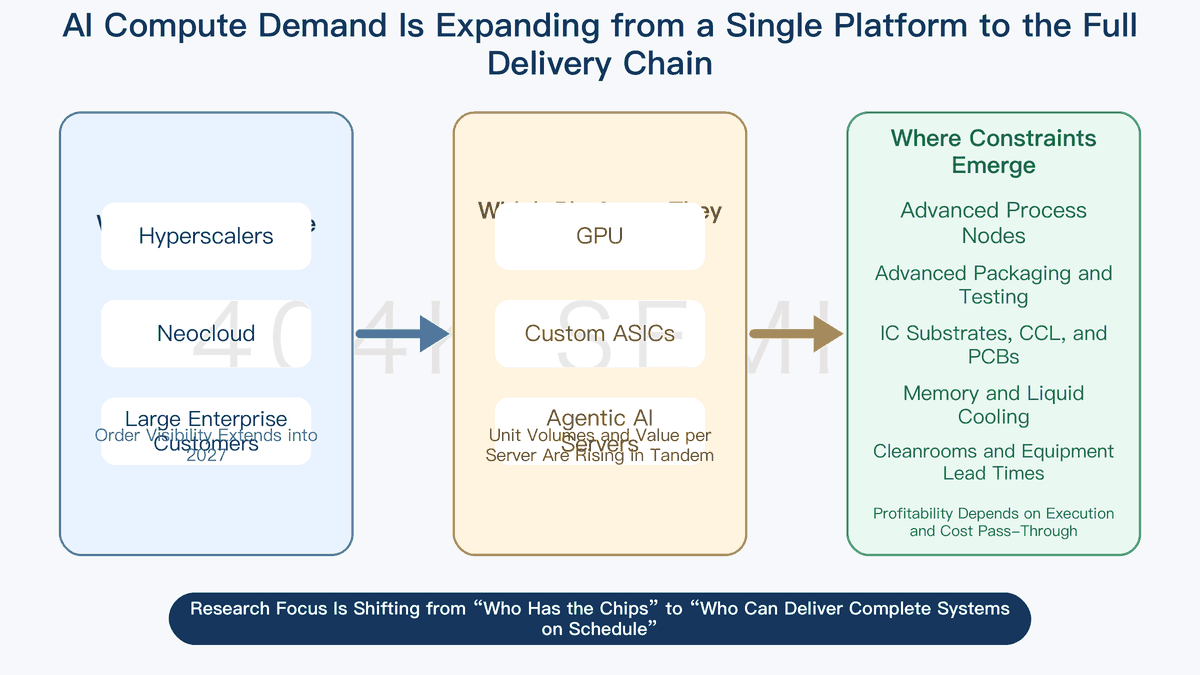
Earlier Asian hardware research had already shown that AI content value would spread beyond GPUs to PCBs, liquid cooling, power supplies, and optical interconnects. The August 25 update clarifies the sequence: the most immediate constraints are advanced nodes, advanced packaging, substrates, PCBs, and equipment lead times. Optical interconnects and longer-term power architectures remain important, but they cannot yet generate near-term revenue for every supplier.
End-market demand is not recovering in tandem. Industrial and automotive demand has begun to improve, PC demand has proved more resilient than the most bearish expectations, and smartphones remain the weakest segment. PCs weakened again in 2H26, with commercial demand outperforming the consumer market. AI servers and consumer electronics therefore need to be assessed separately: the former can sustain strong momentum, while the latter will continue to constrain pricing power for mature nodes and commodity components.
Faster Capacity Expansion Shifts Bottlenecks to Equipment and Facilities
The constraint in advanced packaging has moved from order availability to the availability of production space and equipment. Major Asian OSAT companies have raised 2026 capital expenditure to record levels, representing growth of more than 80% year over year. Manufacturers are searching for existing facilities to shorten construction timelines, but even brownfield conversions require at least 6—9 months, while new facilities typically take about 2 years.
Equipment lead times are becoming a new hard constraint. Lead times for CoW advanced-packaging tools have reached as long as 12 months, while traditional OSAT companies and TSMC are competing for similar equipment sets. Turning an announced expansion into deliverable output requires facilities, equipment installation, process tuning, customer qualification, and yield ramp-up. Any stage can delay revenue recognition.
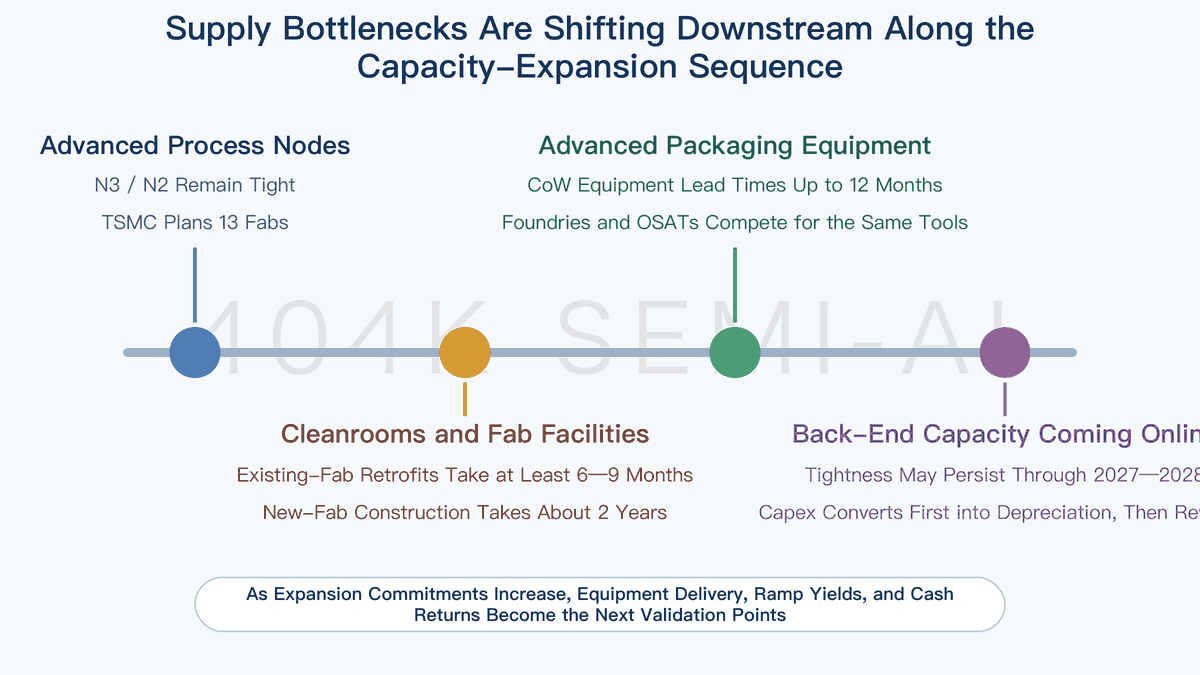
This is why advanced-packaging capacity could remain tight through 2027—2028. Current elevated capital expenditure will initially generate cash outflows, followed by depreciation once equipment enters production, and only then potentially translate into revenue and profit. If order momentum holds, higher utilization and a better product mix can absorb the depreciation burden. If projects are delayed or yields fall short, margin pressure will emerge before revenue pressure.
