
Arm FY2027 Q1 Deep Dive: Data Center Royalties More Than Double, AGI CPU Demand Exceeds $2 Billion
目录
Executive Summary
1. Revenue Growth Quality Matters More Than the Headline
2. Data Center Royalties More Than Double, Validating the Thesis That “CPUs Are Becoming Important Again”
3. AGI CPUs Move from Demand Validation to Supply Validation
4. Margins Appear to Be Improving, but Stock-Based Compensation Remains the Largest Reporting Discrepancy
5. Ample Cash, but This Quarter’s Free Cash Flow Should Not Be Annualized Directly
6. Q2 Guidance Maintains an Approximately 20% Growth Trajectory
7. Falsification Tests and a Validation Checklist for the Next Four Quarters
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This quarter validated the royalty thesis and moved AGI CPUs from a product concept into a capacity-constrained phase; what now requires closer examination is growth, earnings quality, and the pace of execution.
Executive Summary
Arm’s (ARM) strong quarter was not driven solely by large licensing deals. Revenue reached $1.289 billion, up 22% year over year; royalty revenue and license and other revenue increased 22% and 23%, respectively. Data center royalties more than doubled year over year, while ARMV9, CSS, and cloud deployments are simultaneously increasing per-chip value and the shipment base.
The AGI CPU demand estimate doubled, but it cannot yet be treated as revenue. Arm has delivered initial products to multiple customers and secured the manufacturing capacity required to support the previously identified $1 billion opportunity; customer demand for FY2027–FY2028 now exceeds $2 billion. The question has consequently shifted from “Are there customers?” to “Can Arm expand capacity, deliver on time, and recognize revenue at what gross margin?” The presentation still clearly identifies FY2028 as the first year of meaningful revenue.
Non-GAAP profitability is expanding, but GAAP earnings quality warrants caution. Non-GAAP operating margin increased from 39.1% to 41.2%, while GAAP operating margin declined from 10.8% to 7.1%. This quarter’s $343 million of stock-based compensation and $128 million of gains on equity investments inflated GAAP expenses and net income, respectively, so investors should not focus solely on net income doubling year over year to $270 million.
Cash flow was very strong, but clearly affected by timing. Operating cash flow was $902 million and non-GAAP free cash flow was $665 million, primarily driven by accounts receivable collections and an increase in other liabilities. Quarter-end cash and short-term investments of $3.888 billion are sufficient to support R&D; and capacity expansion, but the DreamBig acquisition completed the day after quarter-end, rising capital expenditures, and investments in manufacturing capacity will all consume cash.
Q2 guidance does not suggest that growth is losing momentum. The revenue midpoint of $1.38 billion implies approximately 7% sequential growth and approximately 22% year-over-year growth; the non-GAAP EPS midpoint is $0.47. The next priorities are whether data center royalties can continue growing materially faster than the company overall, whether AGI CPU demand can convert into orders and revenue, and whether expense growth can remain below revenue growth.
1. Revenue Growth Quality Matters More Than the Headline
Arm’s FY2027 Q1 revenue reached $1.289 billion, in the upper half of its prior guidance range of $1.210 billion–$1.31 billion. Non-GAAP diluted EPS was $0.45, above the high end of its prior guidance range of $0.36–$0.44. Both revenue and earnings exceeded the company’s original midpoint assumptions.
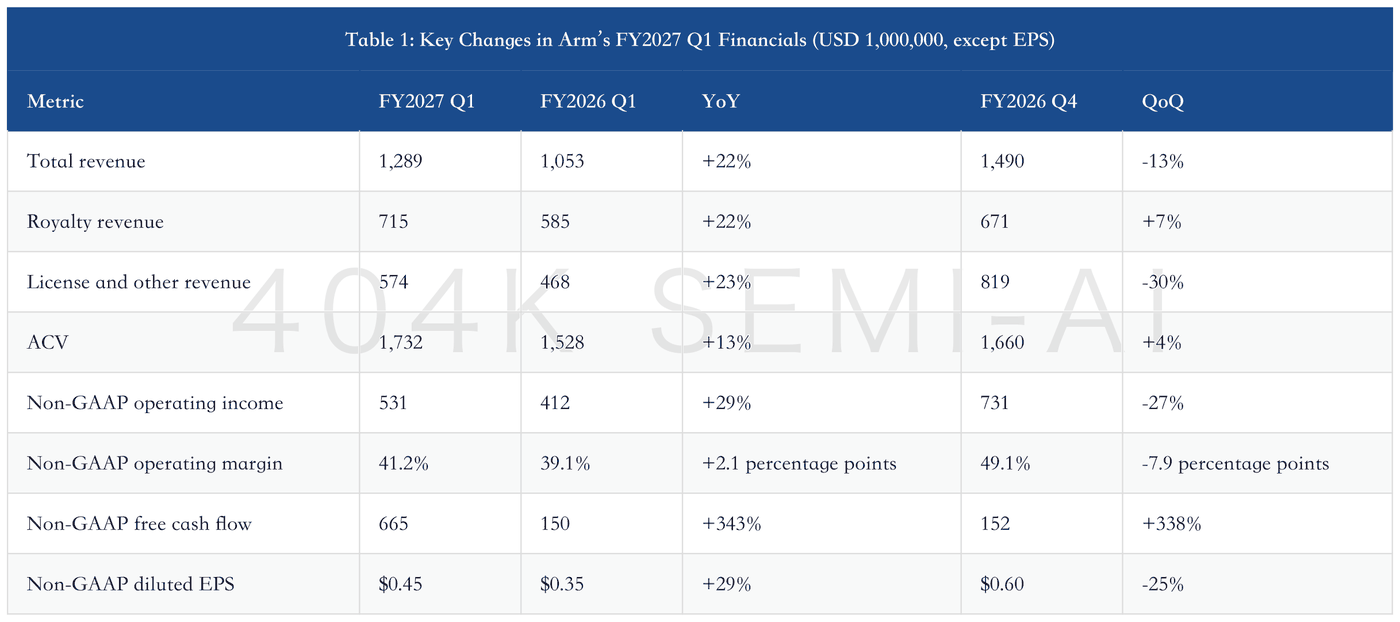
The sequential decline primarily reflected license revenue falling from $819 million in the prior quarter to $574 million. Licensing agreements are large and have uneven delivery milestones, so quarterly volatility is inherently high. More useful indicators are that royalties grew approximately 7% sequentially and ACV increased approximately 4%. In other words, both revenue from chips in mass production and the licensing-contract base are expanding; the underlying business continued to grow beyond Q4’s large deals.
The 6-K also provides a figure that is no longer highlighted in the shareholder letter: remaining performance obligations at quarter-end were $2.1226 billion, of which approximately 24% is expected to be recognized over the next 12 months, 23% over the subsequent 13–24 months, and the remainder thereafter. This figure excludes potential future royalties and therefore cannot represent the entire revenue pipeline; its significance is that it provides a degree of support for license revenue, rather than eliminating quarterly volatility.
