
目录
Executive Summary
What the Three Earnings Reports Changed
Understanding CPO: It Is Not Simply a New Module
Applied Optoelectronics: Order Upside Comes with a Capital and Manufacturing Test
Lumentum: A 50% Gross Margin Shows That Light-Source Scarcity Has Reached the Income Statement
Coherent: Turning Its 6-Inch Indium Phosphide Platform into a Supply Advantage
The Three Companies Are Not Interchangeable—they Represent Three Distinct Industry Factors
Scale-Out vs. Scale-Up Determines the Sequence of CPO Adoption
Why Pluggables Will Remain Dominant While CPO Re-Rates Light Sources First
What the Gross-Margin Gradient Really Indicates
Industry Competition Is Shifting from Module Share to Four Forms of Control
What Could Invalidate the Thesis That Supply Remains the Primary Constraint?
A More Practical Industry Scenario Framework
What to Validate Over the Next Four Quarters
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The three latest earnings reports point to the same conclusion: near-term AI optical-interconnect growth remains constrained by supply execution. CPO commercialization has begun, but it is not bypassing the 1.6T pluggable ramp.
Executive Summary
Demand has moved beyond the long-term roadmap. Applied Optoelectronics, Lumentum, and Coherent reported latest-quarter revenue of US$191.9 million, US$1.0063 billion, and US$2.0455 billion, respectively. The midpoints of their next-quarter guidance imply sequential growth of approximately 42.0%, 24.2%, and 12.4%. All 3 companies are accelerating deliveries, indicating that AI data-center optical demand has moved beyond sampling and qualification into a phase where capacity, component availability, and yields determine revenue.
CPO has begun, but 1.6T pluggables remain the most visible backbone of growth over the next 2 years. Coherent expects to begin recognizing CPO revenue in the December 2026 quarter. Lumentum has secured its first external laser source module order, while Applied Optoelectronics has also begun low-volume production of narrow-linewidth, high-power lasers. For all 3 companies, the largest near-term revenue opportunities still come from 800G, 1.6T, continuous-wave lasers, EMLs, and module capacity expansion. CPO adoption will progress layer by layer—from optical sources and external lasers to switching topologies and packaging architectures.
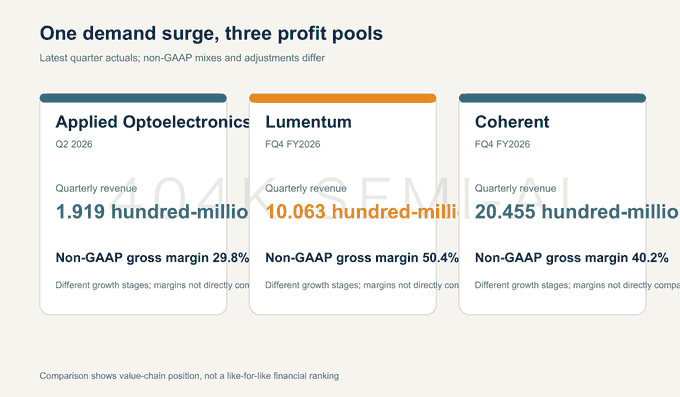
The profit pool is shifting toward hard-to-scale optical sources, yield, and system interfaces. Latest-quarter non-GAAP gross margins show a clear gradient: 29.8% at Applied Optoelectronics, 40.2% at Coherent, and 50.4% at Lumentum. The 3 companies’ business mixes are not fully comparable, but the spread still suggests that indium phosphide lasers, 6-inch wafers, pump lasers, OCS, and long-term customer agreements can generate higher returns than simply maximizing module volumes.
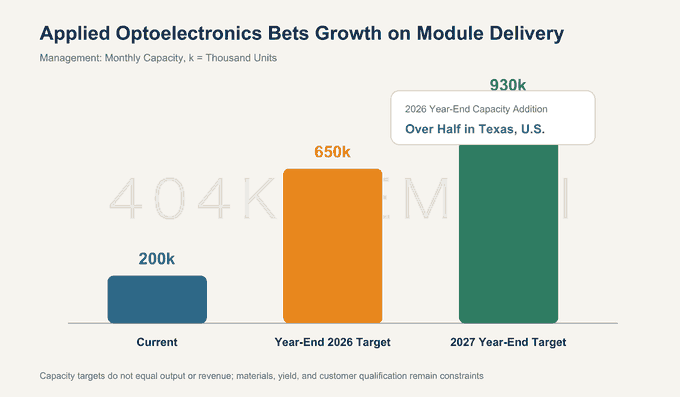
Applied Optoelectronics offers the greatest operating leverage—and faces the most difficult financial execution. The company plans to expand monthly module capacity from approximately 200,000 units to 650,000 by year-end 2026 and 930,000 by year-end 2027, and says its 1.6T backlog exceeds US$200 million. At the same time, operating cash flow was negative US$73.8 million in the first 6 months of 2026, purchases of property and equipment totaled US$335.1 million, and equipment prepayments reached US$289.7 million, funded primarily through financing. The central question is whether it can convert capacity into qualified shipments and gross margin without further material equity dilution.
The post-earnings debate on Lumentum centers on how long elevated margins can persist. Two post-earnings research reports dated August 12 raised their price assessments to US$1,000 and US$1,280, respectively. Both acknowledged that quarterly execution exceeded expectations; the key disagreement is whether OCS, pump lasers, 1.6T, and high-power CPO optical sources can sustain both revenue and gross margins at elevated levels. The market is no longer debating whether demand exists—it is pricing suppliers’ ability to control supply and the duration of that advantage.
Execution over the next 4 quarters is the most important variable. Investors should monitor Applied Optoelectronics’ 1.6T shipments and cash burn, Lumentum’s OCS revenue and high-power laser orders, Coherent’s 6-inch indium phosphide output and gross margin, and whether the 3 companies’ long-term agreements convert into cash. If these indicators deliver, the pace of CPO adoption will matter more as a difference in business mix. If they falter, perceived supply scarcity could quickly turn into overexpansion.
What the Three Earnings Reports Changed
Previous discussions of the optical-module industry often fell into 2 extremes. One treated AI-cluster network upgrades purely as a demand story, focusing on theoretical volumes for 800G, 1.6T, and 3.2T. The other viewed CPO as the end-state replacement for pluggable optics, assuming that traditional module value would rapidly disappear once CPO shipments began. All three latest earnings reports challenge this false choice.
Applied Optoelectronics reported second-quarter 2026 revenue of US$191.9 million, up 86% year over year and 27% sequentially. Data-center revenue reached US$107.7 million, up 140.4% year over year. Lumentum’s fiscal fourth-quarter 2026 revenue was US$1.0063 billion, up 109.3% year over year, while non-GAAP gross margin reached 50.4% for the first time. Coherent reported revenue of US$2.0455 billion, up 33.8% year over year; Data Center & Communications revenue was US$1.615 billion, representing 79% of total revenue and increasing 59% year over year. Despite differences in scale and business mix, all 3 companies delivered accelerating revenue and higher next-quarter guidance. That synchronized strength is more informative than an isolated earnings beat.
The companies, however, are not capturing the same profit pool. Applied Optoelectronics must convert 400G, 800G, and 1.6T orders into module capacity. Lumentum must determine whether scarce laser and OCS supply can extend its high-margin cycle. Coherent must prove that its 6-inch indium phosphide process advantage can span lasers, modules, CPO/NPO, and optical-switching systems—and translate into durable scale and profitability. Demand is moving in the same direction, but competitive positioning is increasingly differentiated.
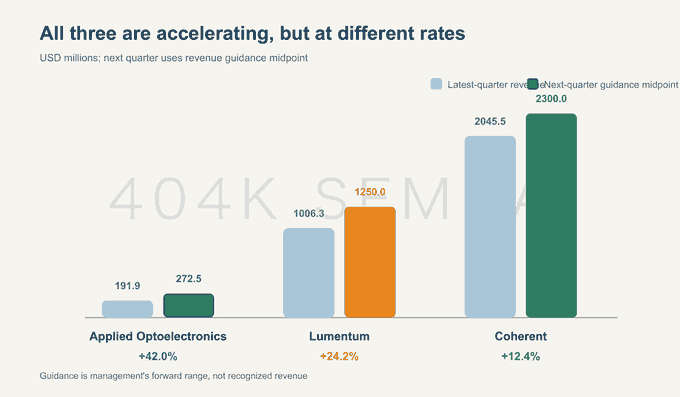
Next-quarter revenue guidance makes these differences clearer. Applied Optoelectronics guided to US$255 million to US$290 million, implying approximately 42.0% sequential growth at the midpoint. Lumentum guided to US$1.225 billion to US$1.275 billion, implying approximately 24.2% midpoint growth. Coherent guided to US$2.2 billion to US$2.4 billion, implying approximately 12.4% midpoint growth. Applied Optoelectronics has the steepest trajectory because it is starting from a smaller base and its module capacity is only beginning to come online. Coherent’s growth rate is lower, but it is built on quarterly revenue above US$2 billion and a non-GAAP gross margin above 40%. Looking only at growth rates overstates small-base operating leverage; looking only at margins understates module suppliers still in the early stages of capacity expansion.
The genuinely new development is that the industry has moved beyond asking whether customers have demand. The question is now whether suppliers can simultaneously solve optical-source availability, packaging, testing, thermal management, customer qualification, and returns on capital. Orders are no longer the only scarce resource; reliable delivery capability is.
Understanding CPO: It Is Not Simply a New Module
CPO, or co-packaged optics, places optical engines close to switching or compute chips, shortening the distance that high-speed electrical signals must travel across printed circuit boards to reduce power consumption and increase bandwidth density. It addresses the increasingly severe copper-trace losses, front-panel space constraints, and power requirements associated with higher switching capacity. Moving optics closer to high-power chips, however, introduces new challenges in thermal management, serviceability, yield, and optical-source reliability.
Traditional pluggable optical modules package optical components, drivers, and digital signal processors at the switch faceplate. Failed modules can be replaced directly, the supply chain is mature, and customer operating practices are well established. NPO, or near-packaged optics, moves optical engines closer to the switching chip while retaining some modularity. CPO goes further by deeply integrating optics with the chip package. ELS, or external laser sources, removes the lasers—among the most heat-sensitive and service-intensive components—from the package and delivers light to CPO optical engines through fiber. OCS, or optical circuit switching, changes connection topologies optically. It is not synonymous with CPO, but could work alongside CPO and NPO to reshape both intra-rack and inter-rack networks.
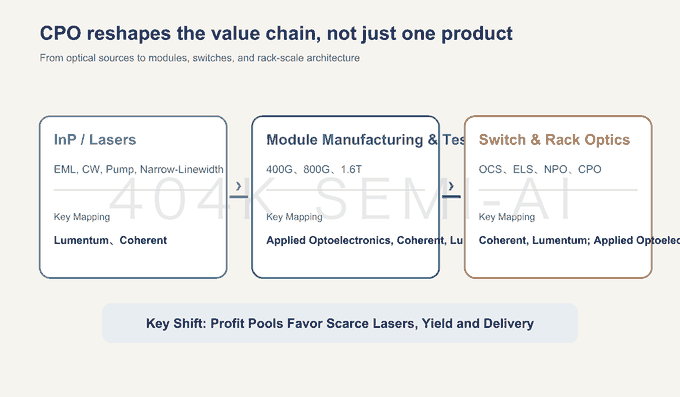
These distinctions are essential to understanding the 3 companies. Applied Optoelectronics produces pluggable modules while also developing the narrow-linewidth, high-power lasers required for CPO. Lumentum occupies multiple upstream and system-level positions across EMLs, continuous-wave lasers, pump lasers, ELS, and OCS. Coherent has exposure spanning indium phosphide wafers, lasers, detectors, modules, OCS, and CPO/NPO. CPO commercialization will preserve parts of the existing value chain while repricing optical-source, coupling, yield, and system-control capabilities that were previously embedded inside modules.
The next 2 years will therefore most likely feature 3 parallel market layers. First, 800G and 1.6T pluggables will continue to support large-scale deployments. Second, NPO and CPO will begin generating revenue with a limited number of customers and network topologies. Third, OCS, ELS, and high-power optical sources will benefit before complete CPO systems. Suppliers betting on only one packaging architecture may miss the transition, while those spanning both pluggables and new architectures are better positioned to turn customer migration into sustained revenue.
Applied Optoelectronics: Order Upside Comes with a Capital and Manufacturing Test
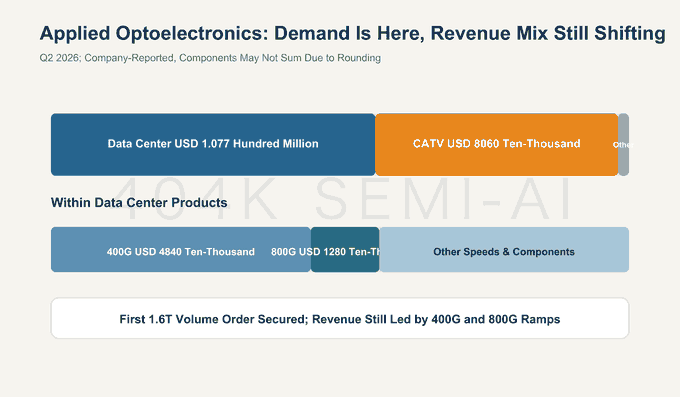
Applied Optoelectronics’ standout metric this quarter was not total revenue, but the speed transition within its data-center business. Data-center revenue reached $107.7 million, accounting for 56% of total revenue. 400G revenue was $48.4 million, or 45% of data-center revenue, up more than 4-fold year over year. 800G revenue reached $12.8 million, up more than 10-fold year over year and more than 2-fold sequentially. The company expects third-quarter 800G revenue to approach 5 times the second-quarter level. It has also secured its first volume 1.6T order, with a 1.6T backlog exceeding $200 million and shipments expected to begin late in the third quarter.
This indicates that customer demand is progressing through a continuous 400G–800G–1.6T upgrade cycle rather than hinging on a single generation. 400G continues to generate cash, 800G is driving near-term growth, and 1.6T has entered qualification and materials-procurement stages. Applied Optoelectronics also retains its cable-TV access business: second-quarter CATV revenue was $80.6 million and is expected to rise to $100 million–$110 million in the third quarter. CATV reduces the company’s dependence on a single data-center cycle, but it can also lead investors to misinterpret total revenue growth as pure AI optical-module growth. The two businesses therefore need to be assessed separately.
Applied Optoelectronics is particularly aggressive on capacity. Management said monthly module capacity is approximately 200,000 units and is planned to reach 650,000 by the end of 2026 and 930,000 by the end of 2027. More than half of the capacity added by the end of 2026 will be located in Texas. In unit terms, capacity will increase nearly 5-fold within two years; given the higher ASPs of 800G and 1.6T products, theoretical revenue upside is even greater. The company has even set an internal target of $471 million in monthly transceiver revenue by mid-2027. This target helps illustrate the scale of its expansion ambitions, but it should not be incorporated directly into a base-case forecast. It depends simultaneously on equipment installation, materials availability, yields, customer qualification, order pull-through, and pricing; delays at any stage would defer revenue recognition.
Management repeatedly highlighted materials constraints on the earnings call. Fourth-quarter 1.6T revenue could exceed $70 million, provided that optical components, chips, and equipment are available. Lead times for equipment used to produce high-power narrow-linewidth lasers can reach 21–24 months, while management described process losses for DWDM products at 40%–50%. High-power lasers are not simply existing products operated at higher wattage: the company said 800G lasers produce approximately 70 milliwatts, 1.6T lasers approximately 100 milliwatts, and CPO-related products could reach approximately 300 milliwatts while being approximately 6 times the size of standard devices. Power, thermal management, wavelength control, and yield collectively magnify the manufacturing challenge.
These disclosures point to Applied Optoelectronics’ potential position in the CPO value chain. It does not need to win the entire CPO system to supply lasers for external laser sources and optical engines. The company expects these products to ramp gradually from the second half of 2026 through 2027, with higher-volume production more likely after the third quarter of 2027, and has a longer-term target of approximately 400,000 units per month by 2028. The key issue is not the absolute volume but the timing mismatch: pluggable-module revenue must materialize now, while CPO light-source revenue may arrive more than a year later. Both production lines will compete for capital, equipment, and engineering resources.
The financial statements therefore warrant more scrutiny than the order book. During the first 6 months of 2026, Applied Optoelectronics reported negative operating cash flow of $73.8 million, purchases of property and equipment of $335.1 million, equipment prepayments of $289.7 million, and financing cash inflows of $980.3 million. Period-end cash and restricted cash totaled approximately $508.8 million, accounts receivable were $314 million, and inventory was $278.8 million. The company raised approximately $1.028 billion net through ATM issuances, while common shares outstanding increased from approximately 75 million at the end of 2025 to approximately 84.39 million at the end of June 2026.
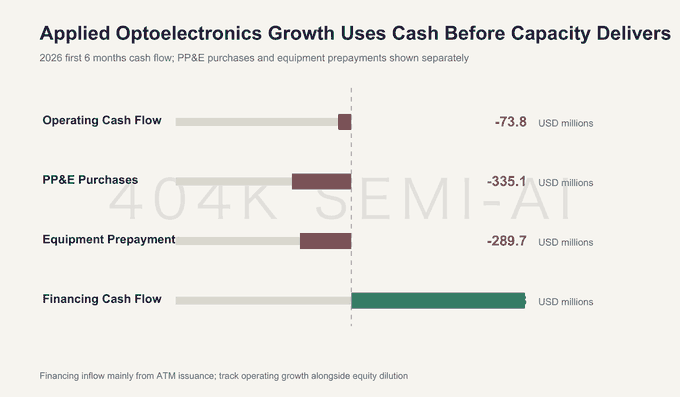
This is not simply a case of “weak cash flow.” Manufacturing expansions inherently create a timing mismatch: equipment is paid for first, capacity comes online next, and revenue is recognized last. The question is whether that mismatch remains contained. If 800G grows rapidly in the third quarter, 1.6T scales as planned in the fourth quarter, and higher utilization lifts gross margin, upfront investment will translate into scale advantages. If materials or customer qualification are delayed, however, inventory, equipment prepayments, and receivables could all rise together, requiring additional financing and further shareholder dilution.
