
Applied Materials Deep Dive: How the WFE Supercycle, DRAM Expansion, and Advanced Packaging Reprice the Profit Slope
目录
TL;DR
1. This Rerating Bets on AI Manufacturing Bottlenecks and a Multiyear Equipment Curve
2. WFE Total Upward Revisions: From US$145B to US$250B, the Equipment Cycle Is Being Extended by AI Capex
3. DRAM Is Applied Materials' First Ticket: 6F2, 4F2, and 3D DRAM Raise Unit-Capacity Value
4. Advanced Packaging Is the Second Ticket: Applied Materials Sells Back-End Process Density, Not Just the CoWoS Concept
5. AGS Service Revenue Improves Earnings Quality: Not the Flashiest Story, but Potentially the EPS Stabilizer
6. Peer Ranking: Applied Materials, LAM, and KLA Are Different AI Manufacturing Bottlenecks
7. Valuation Debate: Behind US$520, US$570, US$710, and US$770 Is a Tug-of-War Between 2027E and 2028E
8. Company Model: Applied Materials' Profit Slope Comes From Revenue, Gross Margin, and Services Rising Together
9. How Prior Work Connects: Applied Materials Is the Intersection of the "Memory Tax" and the "WFE Supercycle"
10. The Real Investment Judgment: Whether Applied Materials Is Worth Chasing Depends on Four Verification Points
11. Three Worldviews: Is Applied Materials Worth US$500, US$700, or a Return to Cyclical Valuation?
12. Risks and Disconfirmation: Where Growth Lands Determines Applied Materials' Valuation Resilience
13. Conclusion: Applied Materials Is an Integrated Platform for AI Manufacturing Expansion, but the Next Leg Requires Delivery, Not Storytelling
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Applied Materials is shifting from a traditional semiconductor equipment cyclical into a horizontal pick-and-shovel supplier for AI manufacturing bottlenecks. This rerating puts the WFE total, DRAM, advanced packaging, GAA, backside power delivery, and service revenue on the same profit slope. The key risk is whether orders, gross margin, and service revenue can continue to keep up after the market has pulled 2028 earnings into today's valuation.
TL;DR
Applied Materials is changing its asset profile. The market used to treat it as an equipment cyclical that moved with WFE. It now needs to be reconsidered as a materials engineering platform for AI wafers, AI memory, and advanced packaging expansion. The frameworks from Citi, UBS, and Jefferies all point to a continued rise in the 2027-2028 WFE midpoint. The only real difference is whether valuation should first anchor on 2027E EPS and a US$500-level stock, or move directly to 2028E EPS and a level above US$700.
WFE visibility is moving further out. 2027-2028 visibility is being extended simultaneously by customer orders, cleanroom capacity, and memory supply shortages, and the market is starting to price a multiyear fab delivery curve. Citi's bull-case framework puts WFE at about US$145B/US$200B/US$250B in 2026/2027/2028, while UBS also estimates 2028 WFE at about US$247.5B. This means Applied Materials' revenue ceiling is shifting from "single-year equipment orders" to a "multiyear fab delivery curve."
DRAM is the core ticket. Applied Materials benefits more from a DRAM upcycle than pure logic-equipment names because DRAM's transition from 6F2 to 4F2 and then to 3D DRAM should keep lifting the content intensity of deposition, etch, interconnect, metrology, and defect inspection. Jefferies estimates that Applied Materials' SAM per 100k wspm of DRAM can rise from about US$6.0B at 6F2 to about US$6.5B at 4F2, and then to about US$7.5B in the 3D DRAM phase.
Advanced packaging raises the quality of growth. The focus is on a process portfolio spanning wafer-level packaging, hybrid bonding, interconnect, plating, panel-level interposers, and eBeam inspection, not just the single CoWoS route. Jefferies expects Applied Materials' advanced-packaging-related business to exceed US$2B in 2026 and keep growing at more than 50%. If CoPoS and panel-level interposers scale, Applied Materials has a chance to capture higher equipment density in back-end expansion.
The bear case is a structural rotation. Morgan Stanley downgraded Applied Materials from overweight to equal-weight in May 2026. The core argument was that the 2027 NAND recovery is more favorable for LAM, while Applied Materials' DRAM advantage has already been priced in. This debate means the next leg for Applied Materials depends on the delivery of four numbers: DRAM orders, Semi Systems gross margin, AGS growth, and whether WFE share continues to recover.
The valuation debate comes from moving the earnings year out. The argument has already moved from "can it get near US$500" to "can the market discount 2028 earnings in advance." The question is whether investors are willing to believe Applied Materials' 2028E EPS can approach or exceed US$20 while maintaining AI-equipment valuation multiples.
The disconfirmation path is already clear. If DRAM WFE expansion is only one round of restocking, advanced-packaging revenue cannot exceed the high-growth path laid out by the company, Semi Systems gross margin falls back to old-cycle levels, or China restrictions and share losses at major customers push orders down again, Applied Materials will revert from an "AI manufacturing bottleneck asset" to traditional equipment beta. In that case, valuation would compress first, and earnings delivery would be revised down afterward.
1. This Rerating Bets on AI Manufacturing Bottlenecks and a Multiyear Equipment Curve
Applied Materials used to be easy to simplify as "WFE beta." What has really changed behind the 2026 sell-side upgrades is the label the market is willing to attach to the company. In the traditional framework, semiconductor equipment valuations followed fab capex, memory pricing, and China equipment demand. In the new framework, Applied Materials is placed upstream in the AI compute supply chain bottleneck, and earnings leverage depends on whether AI chips, HBM, DRAM, NAND, advanced packaging, and service revenue can all raise equipment content intensity at the same time.
This is also why several recent Applied Materials reports read less like ordinary earnings notes. Citi first raised its target price to US$520 in May, based on a 2026/2027 WFE bull-case framework derived from its capex model. After earnings, UBS wrote Applied Materials' 2028 EPS path toward nearly US$27. In its June DRAM and advanced packaging masterclass, Jefferies further decomposed Applied Materials' long-term SAM into DRAM unit capacity, advanced packaging platforms, and eBeam inspection. By mid-June, Citi directly pushed its WFE bull-case framework to about US$250B in 2028 and rolled Applied Materials' target price to US$710. The valuation year has moved out, which shows the market is no longer satisfied with asking whether 2026 earnings are high. It has started to price the equipment supply gap in 2028.
The WFE Supercycle Is Just Beginning: How AI Capex Pushes Semiconductor Equipment Toward US$250B
Applied Materials' business is, at its core, materials engineering. It combines thin-film deposition, etch, ion implantation, CMP, thermal processing, metrology, inspection, and packaging processes into production pathways. The larger AI chips become, the more complex process nodes become, and the denser memory hierarchies become, the more fabs need to refine how materials are deposited, etched, connected, and inspected for defects. In the old cycle, the value of materials engineering was easily viewed as equipment share. In the new cycle, it looks more like a gatekeeper for AI manufacturing: the players that can make more complex structures reliably capture more unit WFE content.
The Applied Materials narrative can be divided into three layers. The first is the total, with WFE moving out of the 2024-2025 normalization phase and back into an expansion cycle driven by AI capex and memory supply shortages. The second is structure, with DRAM, HBM, NAND, GAA, backside power delivery, and advanced packaging growing faster than traditional mature nodes. These areas happen to skew toward Applied Materials' deposition, etch, interconnect, and packaging capabilities. The third is quality, with AGS service revenue, subscription-style maintenance, spare parts, and process support making earnings less dependent on new equipment shipments alone while improving gross margin and cash-flow stability. The combination of total growth, structural mix, and quality is what constitutes the migration in asset profile.
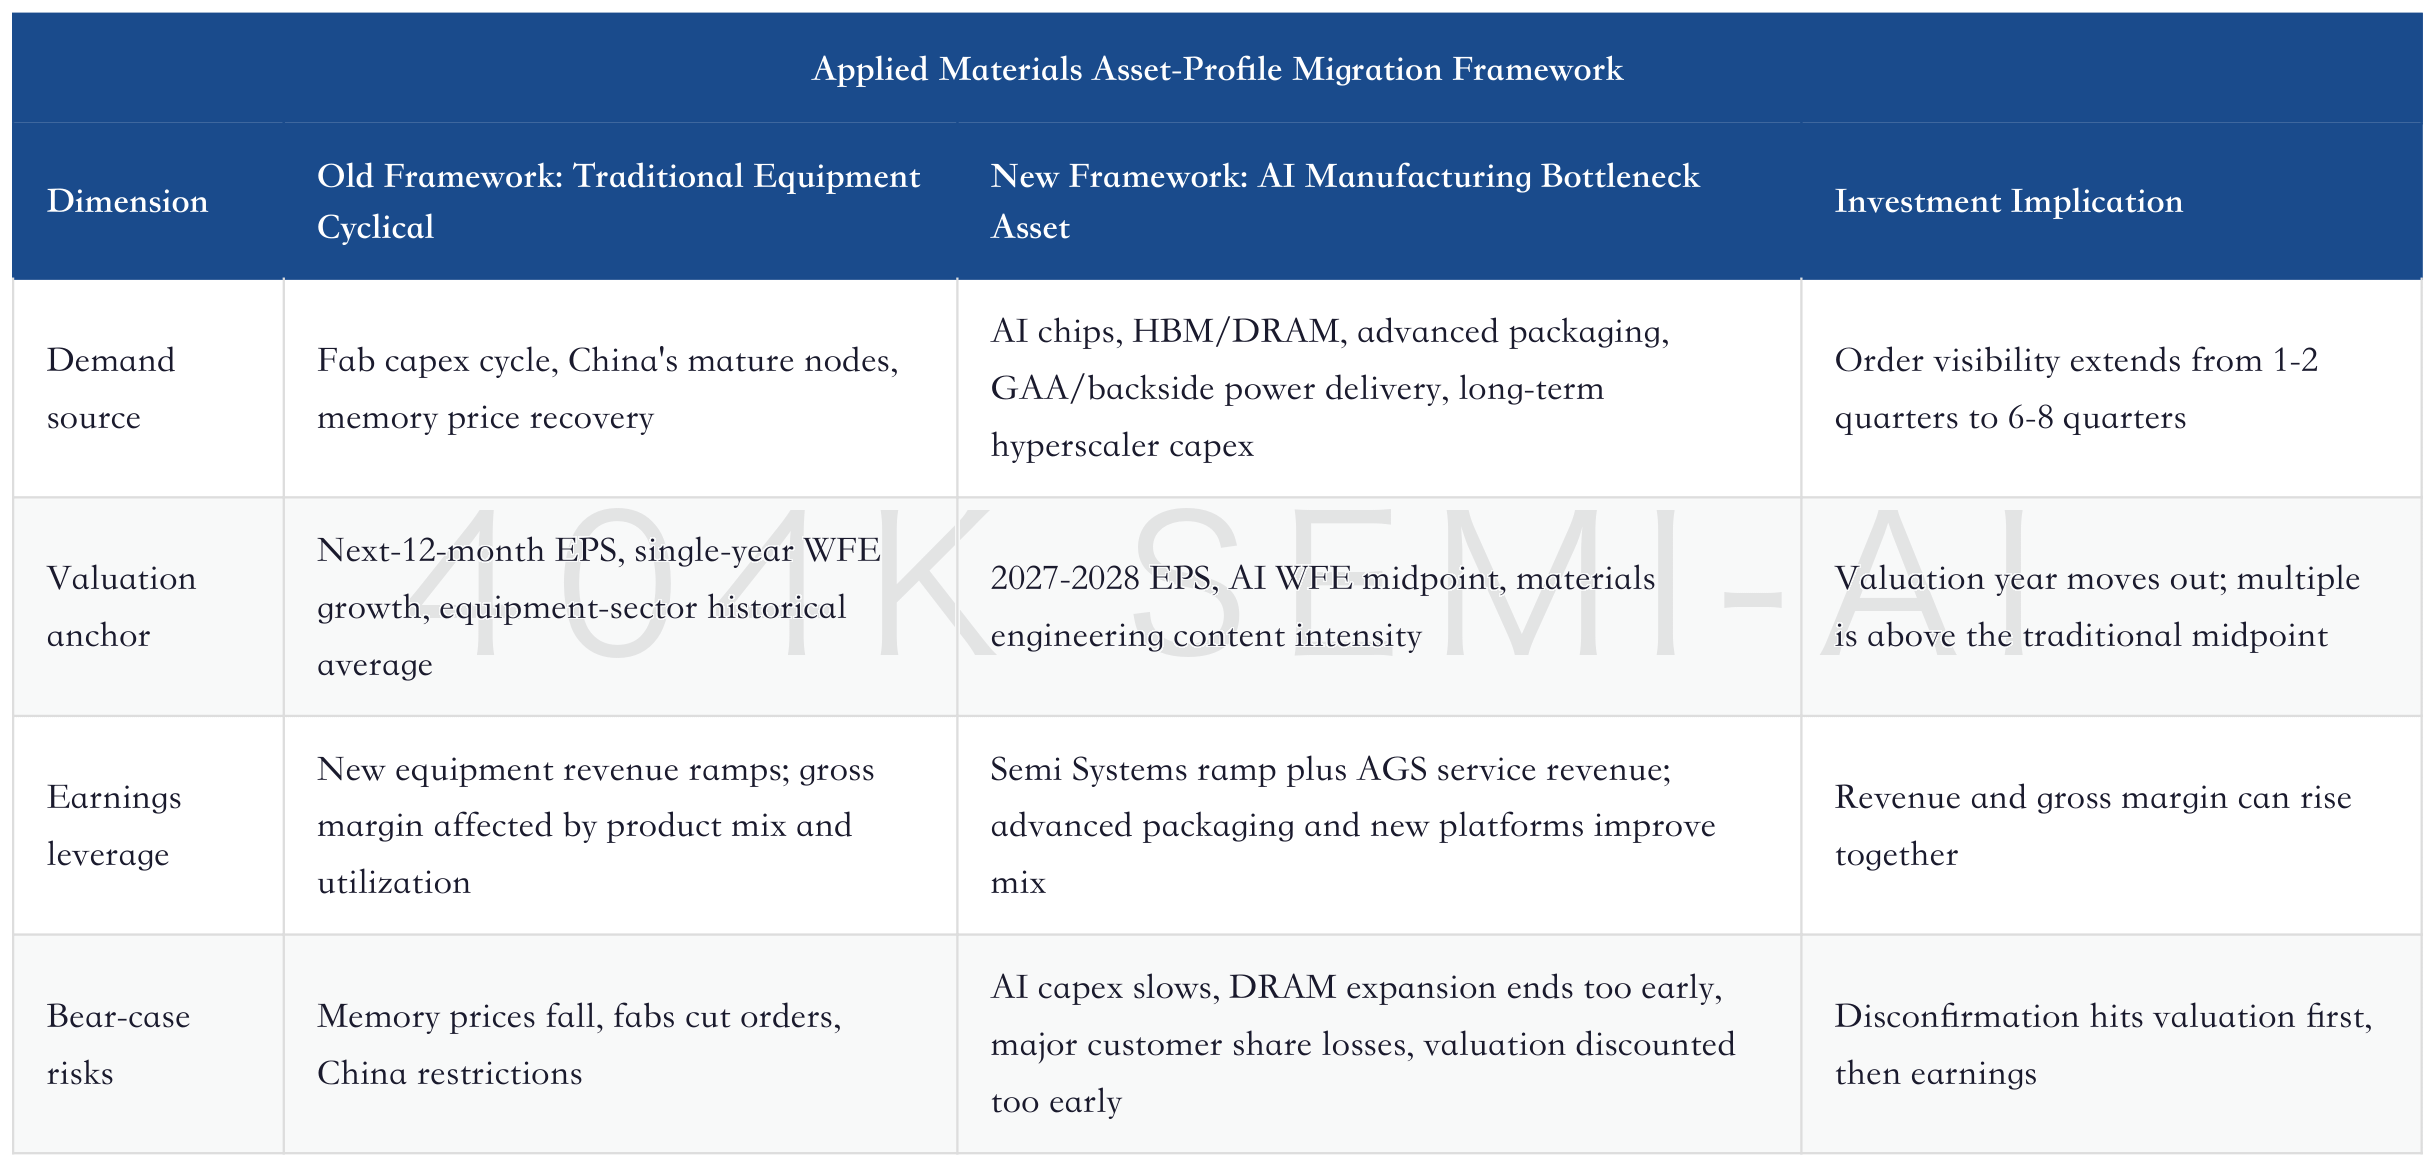
Understanding this framework makes it easier to see why the same group of reports is not fully aligned on Applied Materials, yet all acknowledge that the WFE cycle is getting larger. Bulls see incremental upside from DRAM, advanced packaging, and services. The more cautious camp sees more leverage for LAM in a NAND recovery and believes Applied Materials' DRAM advantage has already been traded by the market. The real debate is how much share Applied Materials can capture in the supercycle, and what multiple should be used to discount it.
2. WFE Total Upward Revisions: From US$145B to US$250B, the Equipment Cycle Is Being Extended by AI Capex
Applied Materials' first main line is the WFE total. Citi, UBS, and Morgan Stanley do not use exactly the same forecasting basis, but the direction is highly consistent: 2026 is not the endpoint; 2027-2028 is the core of market repricing. Citi and UBS push the bull-case framework further out, while Morgan Stanley, although more cautious, also acknowledges that the WFE midpoint has moved higher. The specific dollar differences are clearer in table form.
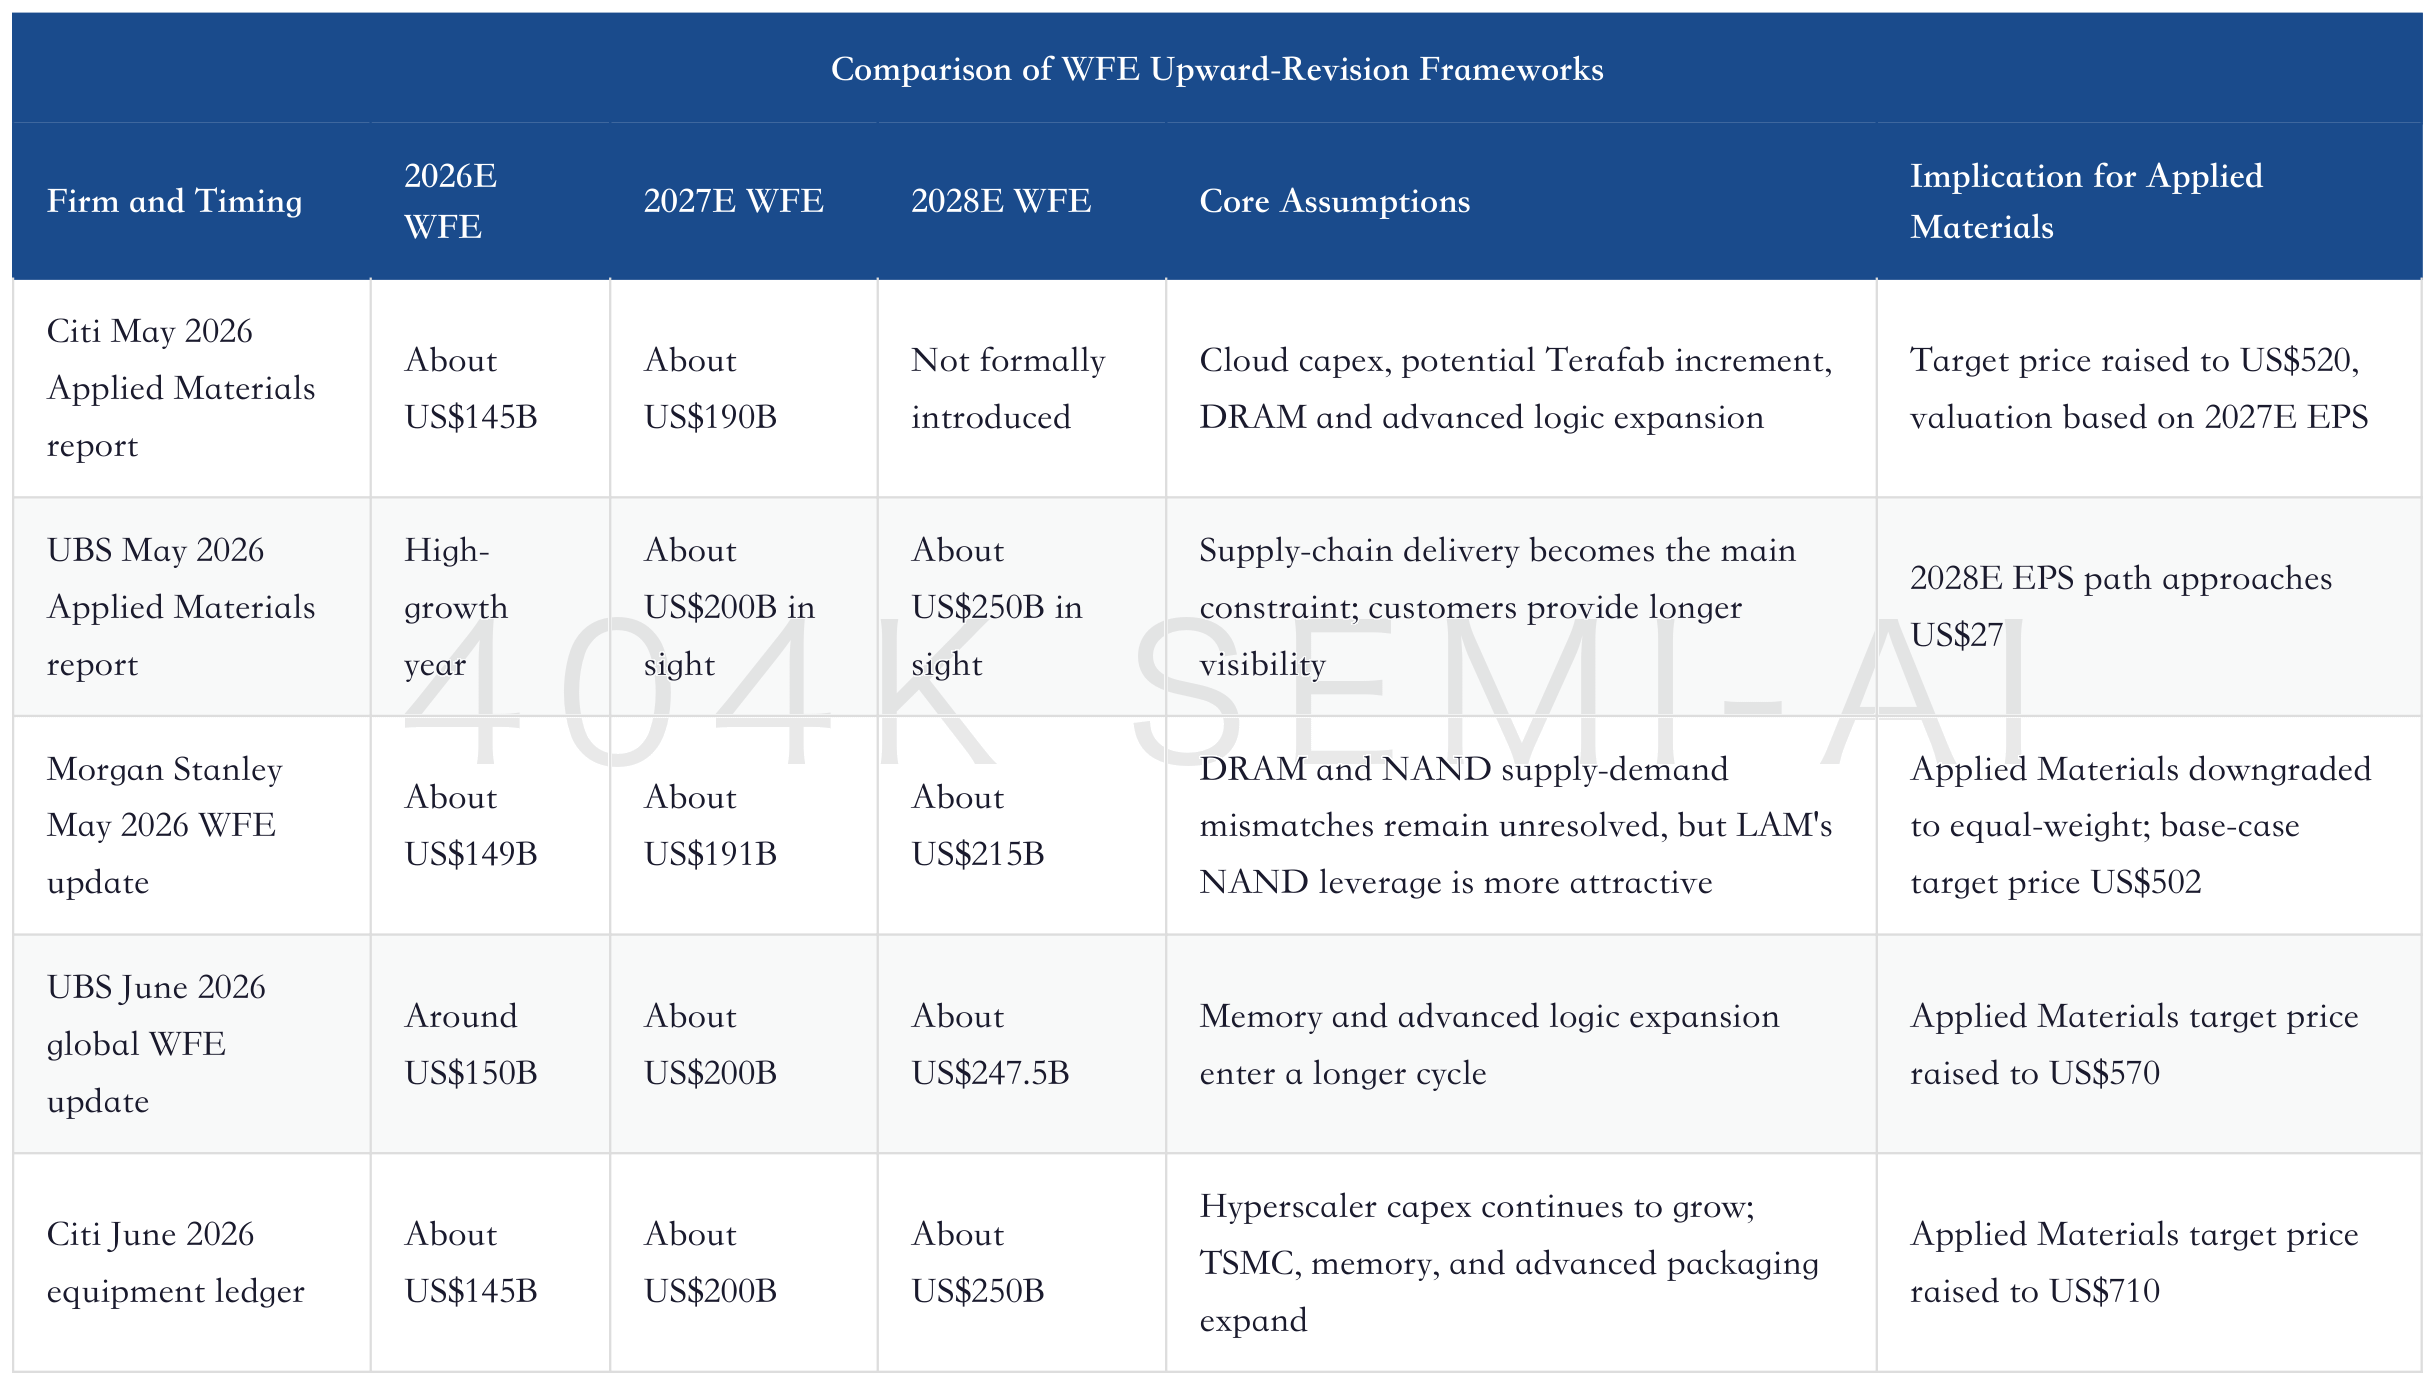
The most important number in this table is 2028. If we look only at 2026, Applied Materials is already trading on a high base. If we look at 2027, the market will debate whether DRAM or NAND is more advantaged. If we look at 2028, the question becomes whether AI compute expansion requires a longer semiconductor manufacturing capex curve. Citi's move to US$250B of WFE effectively changes Applied Materials' valuation anchor from "next-year profit" to "how far AI data centers need to expand wafer manufacturing."
Equipment Capex Ledger Update: AI Financing, US$250B WFE, and Semiconductor Equipment Repricing
WFE upward revisions come from multiple lines moving higher at the same time. Advanced logic needs to expand because GPUs, ASICs, CPUs, and networking chips are all competing for advanced nodes. DRAM needs to expand because HBM, DDR5, and server memory are pushing bit demand onto a steeper slope. NAND needs to expand because AI storage tiers, KV cache offloading, enterprise SSDs, and inference data flows consume more high-performance capacity. Advanced packaging needs to expand because compute chips increasingly rely on 2.5D, 3D, hybrid bonding, and interposers. In the past, these projects might have been treated as different cycles. Now they all point to the expansion of AI manufacturing infrastructure.
Applied Materials benefits most because incremental WFE dollars skew toward its strengths. Citi says Applied Materials is exposed over the next 2-3 years to GAA, advanced packaging, and ICAPS. UBS says Applied Materials is the biggest DRAM WFE supercycle beneficiary among US process-equipment companies. Jefferies says DRAM and advanced packaging will outgrow overall WFE. Behind the different wording is the same judgment: the marginal dollars in the new WFE cycle are more concentrated in equipment steps with more process steps, more complex materials stacks, and denser interconnect and inspection.
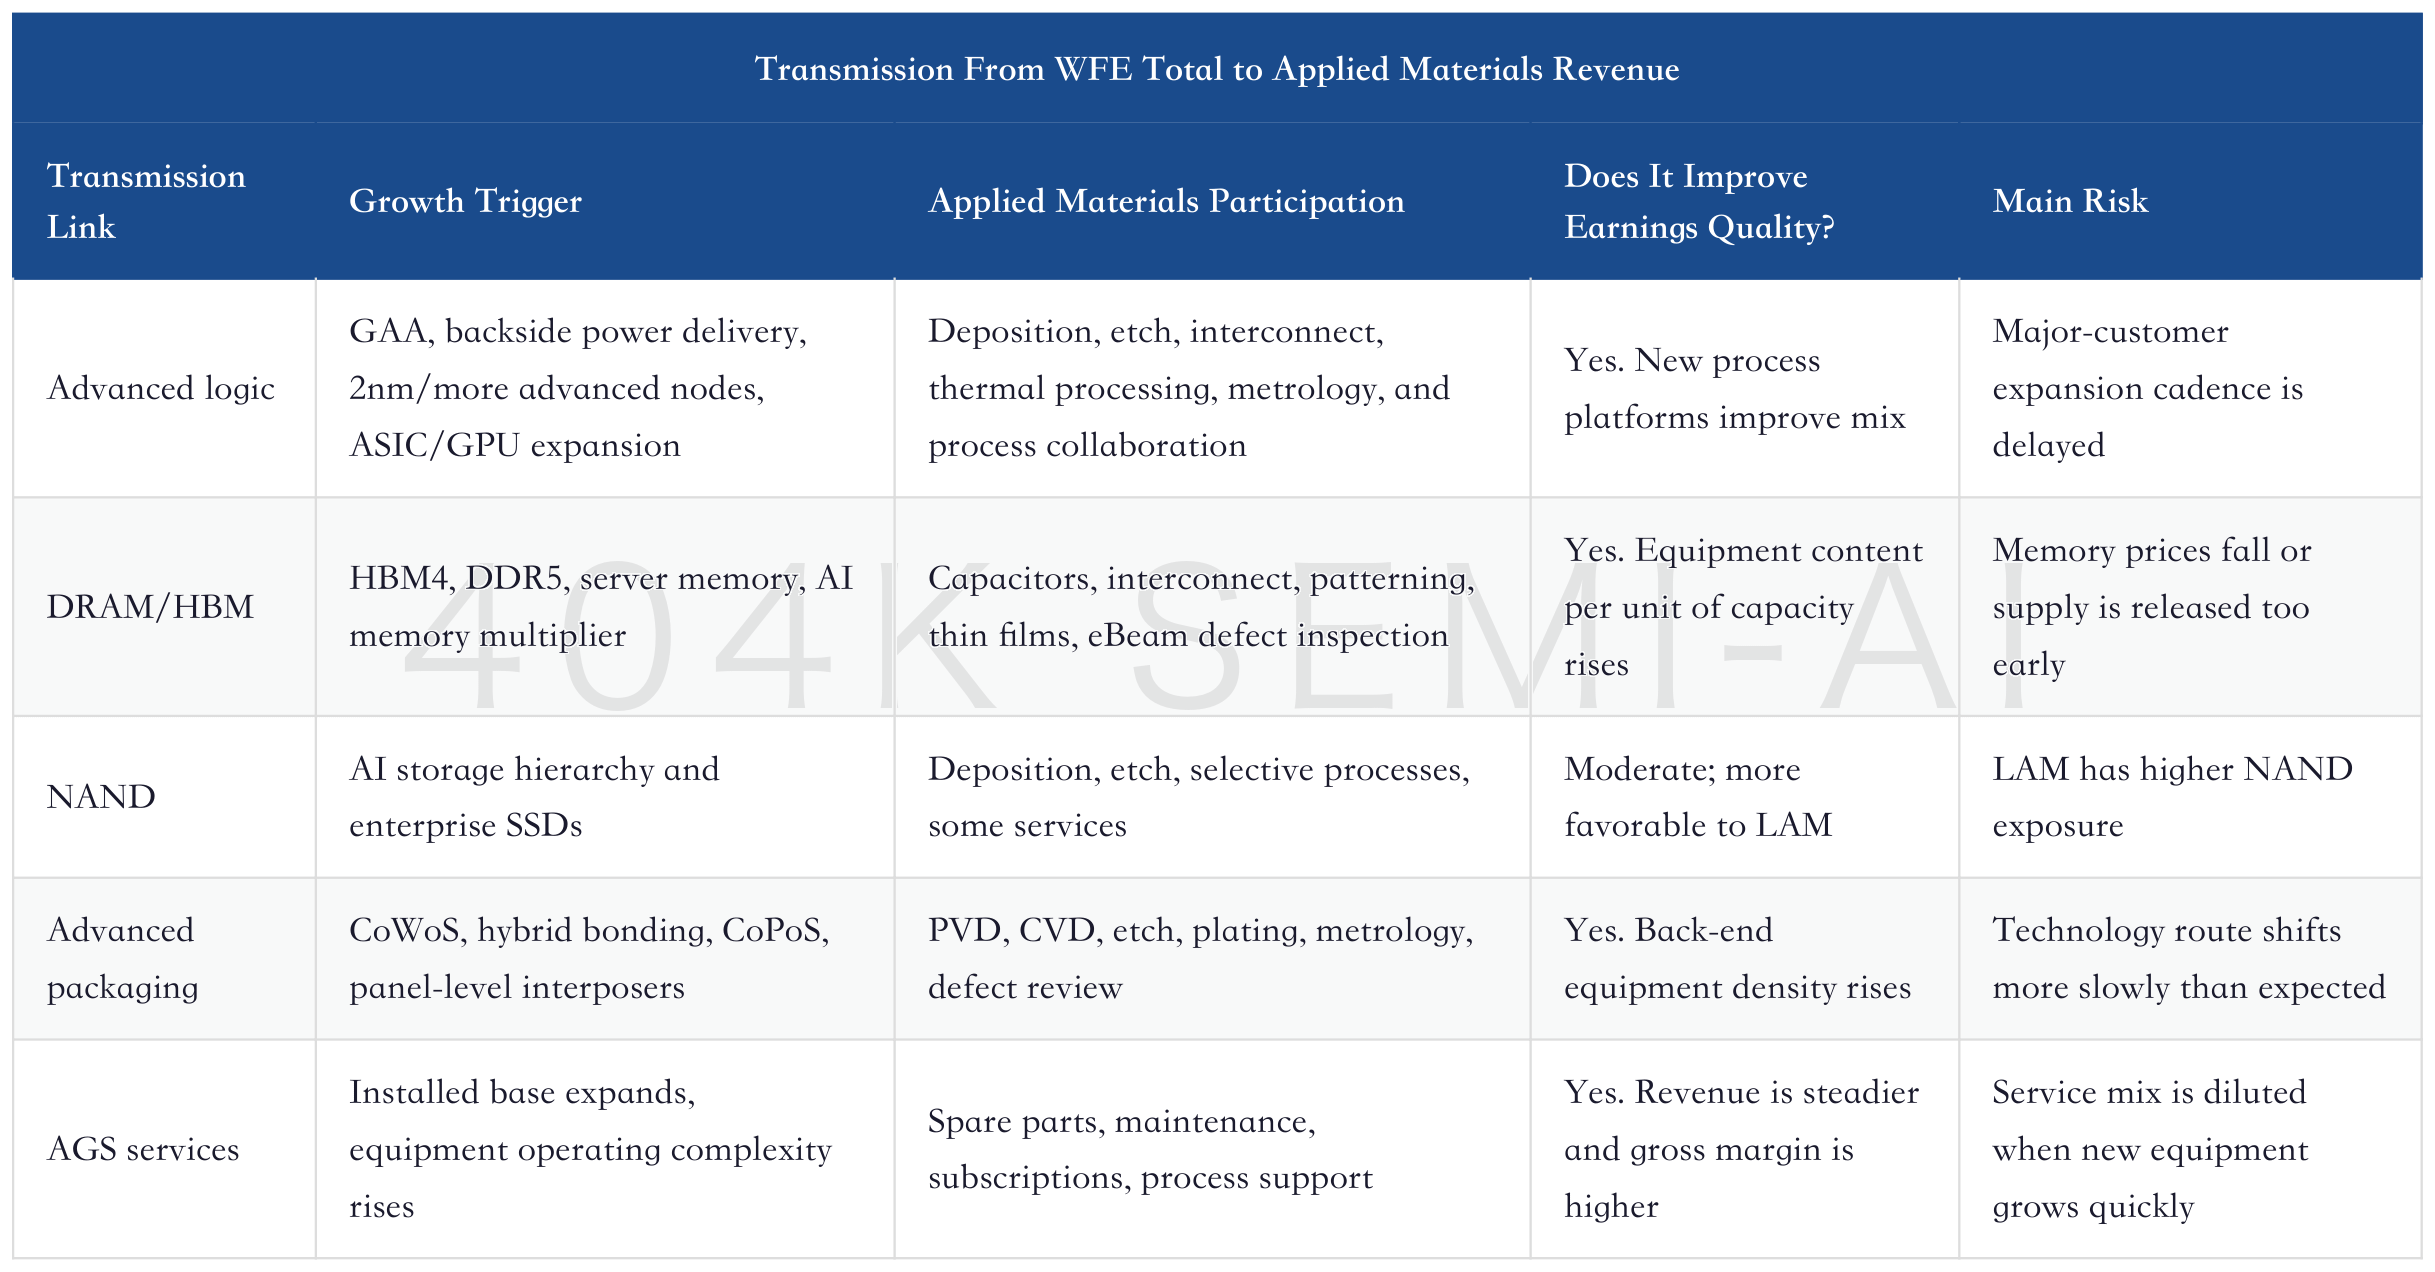
This transmission chain explains why Applied Materials' guidance is treated by the market as cycle confirmation. The April-quarter results and July-quarter guidance both show revenue, EPS, and gross margin avoiding a "volume growth with deteriorating earnings quality" combination. More importantly, the company raised its 2026 Semi Systems shipment growth target, leading the sell side to infer that Applied Materials is moving from following WFE upward to regaining share.
One easily overlooked detail is that Applied Materials' gross margin has remained around 50% even as revenue has been revised sharply higher. In traditional equipment cycles, revenue growth does not necessarily bring gross-margin expansion because supply chain, product mix, installation cadence, and regional structure can all weigh on profitability. But UBS and Evercore have repeatedly emphasized Applied Materials' gross-margin performance this time, suggesting that new platforms, advanced processes, and service revenue are offsetting part of the cost of scaling. If Semi Systems gross margin remains elevated, EPS revisions will move faster than revenue revisions.
3. DRAM Is Applied Materials' First Ticket: 6F2, 4F2, and 3D DRAM Raise Unit-Capacity Value
Applied Materials' first ticket is DRAM. Investors used to treat DRAM and NAND as a single "memory cycle" when looking at memory equipment. After 2026, that view is not precise enough. DRAM is becoming the main battlefield for equipment growth because of demand from HBM, DDR5, server memory, and AI inference memory. NAND also has upside leverage, but the allocation across equipment vendors is different. Applied Materials' advantage is in DRAM and advanced logic, LAM's advantage is more skewed toward NAND and etch, while KLA benefits from process control.
The Memory Tax Arrives: How AI Turns HBM, DRAM, and NAND Into a Global Macro Bottleneck
Jefferies' DRAM and advanced packaging report provides a very clear incremental logic for Applied Materials: DRAM expansion brings both more wafer starts and more materials-engineering steps. The 6F2 stage needs more deposition and patterning. The 4F2 stage introduces denser structures. 3D DRAM further raises structural complexity. Applied Materials participates in capacitors, interconnect, peripheral logic, thin films, etch, metrology, and defect inspection, so equipment SAM per unit of monthly capacity expands.
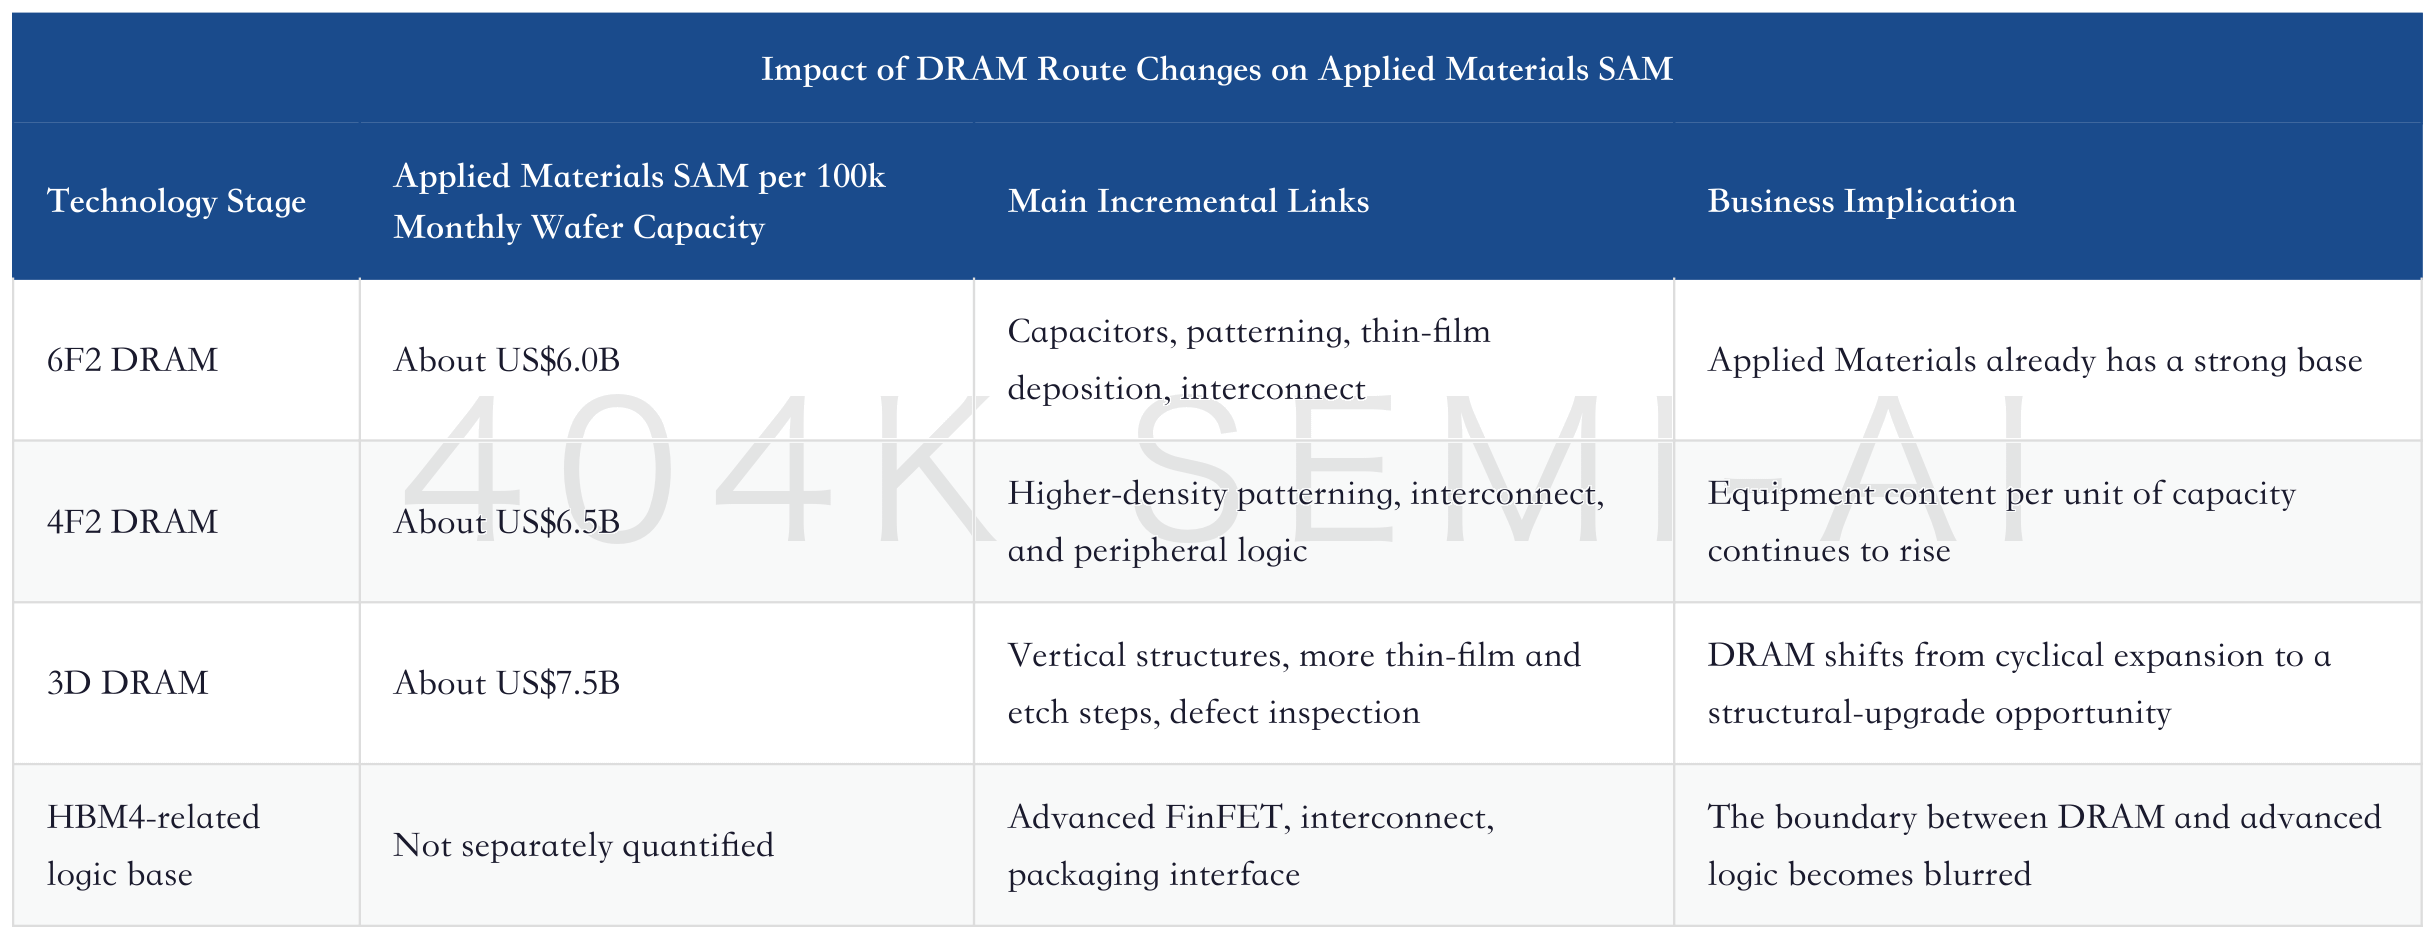
The value of this table is not precision to the nearest US$100M. The value is direction: for every additional 100k monthly wafer capacity, the equipment basket Applied Materials can sell becomes larger. If DRAM is only restocking after a price increase, the market will assign a low multiple. If the DRAM process roadmap raises unit-capacity SAM, the market will assign a longer earnings duration.
UBS's framework also supports this direction. In its June global WFE update, UBS argues that DRAM WFE will contribute more than 50% of total WFE growth in 2026 and more than two-thirds in 2027. This is an aggressive view, but it explains why UBS sees Applied Materials as the biggest DRAM WFE beneficiary among US equipment companies. A substantial portion of Applied Materials' 2026 Semi Systems growth comes from DRAM. If DRAM continues to outgrow overall WFE in 2027, Applied Materials' share recovery will not be a one-off rebound.
There is another important implication in the DRAM line: AI memory demand does not come only from HBM. HBM is the most visible high-end product, but AI servers, inference clusters, the return of CPUs, KV cache, DDR5 upgrades, and standard server capacity are all consuming DRAM. HBM needs more wafers to provide the same number of bits, while rising DDR5 prices stimulate general-purpose DRAM expansion. All of this ultimately returns to fab equipment demand. Because Applied Materials spans front-end and parts of packaging, it can benefit from both front-end expansion and rising back-end complexity.
The Second Engine of the Memory Supercycle: CPU Return, HBM Spillover, and a US$1.7T TAM Rerating
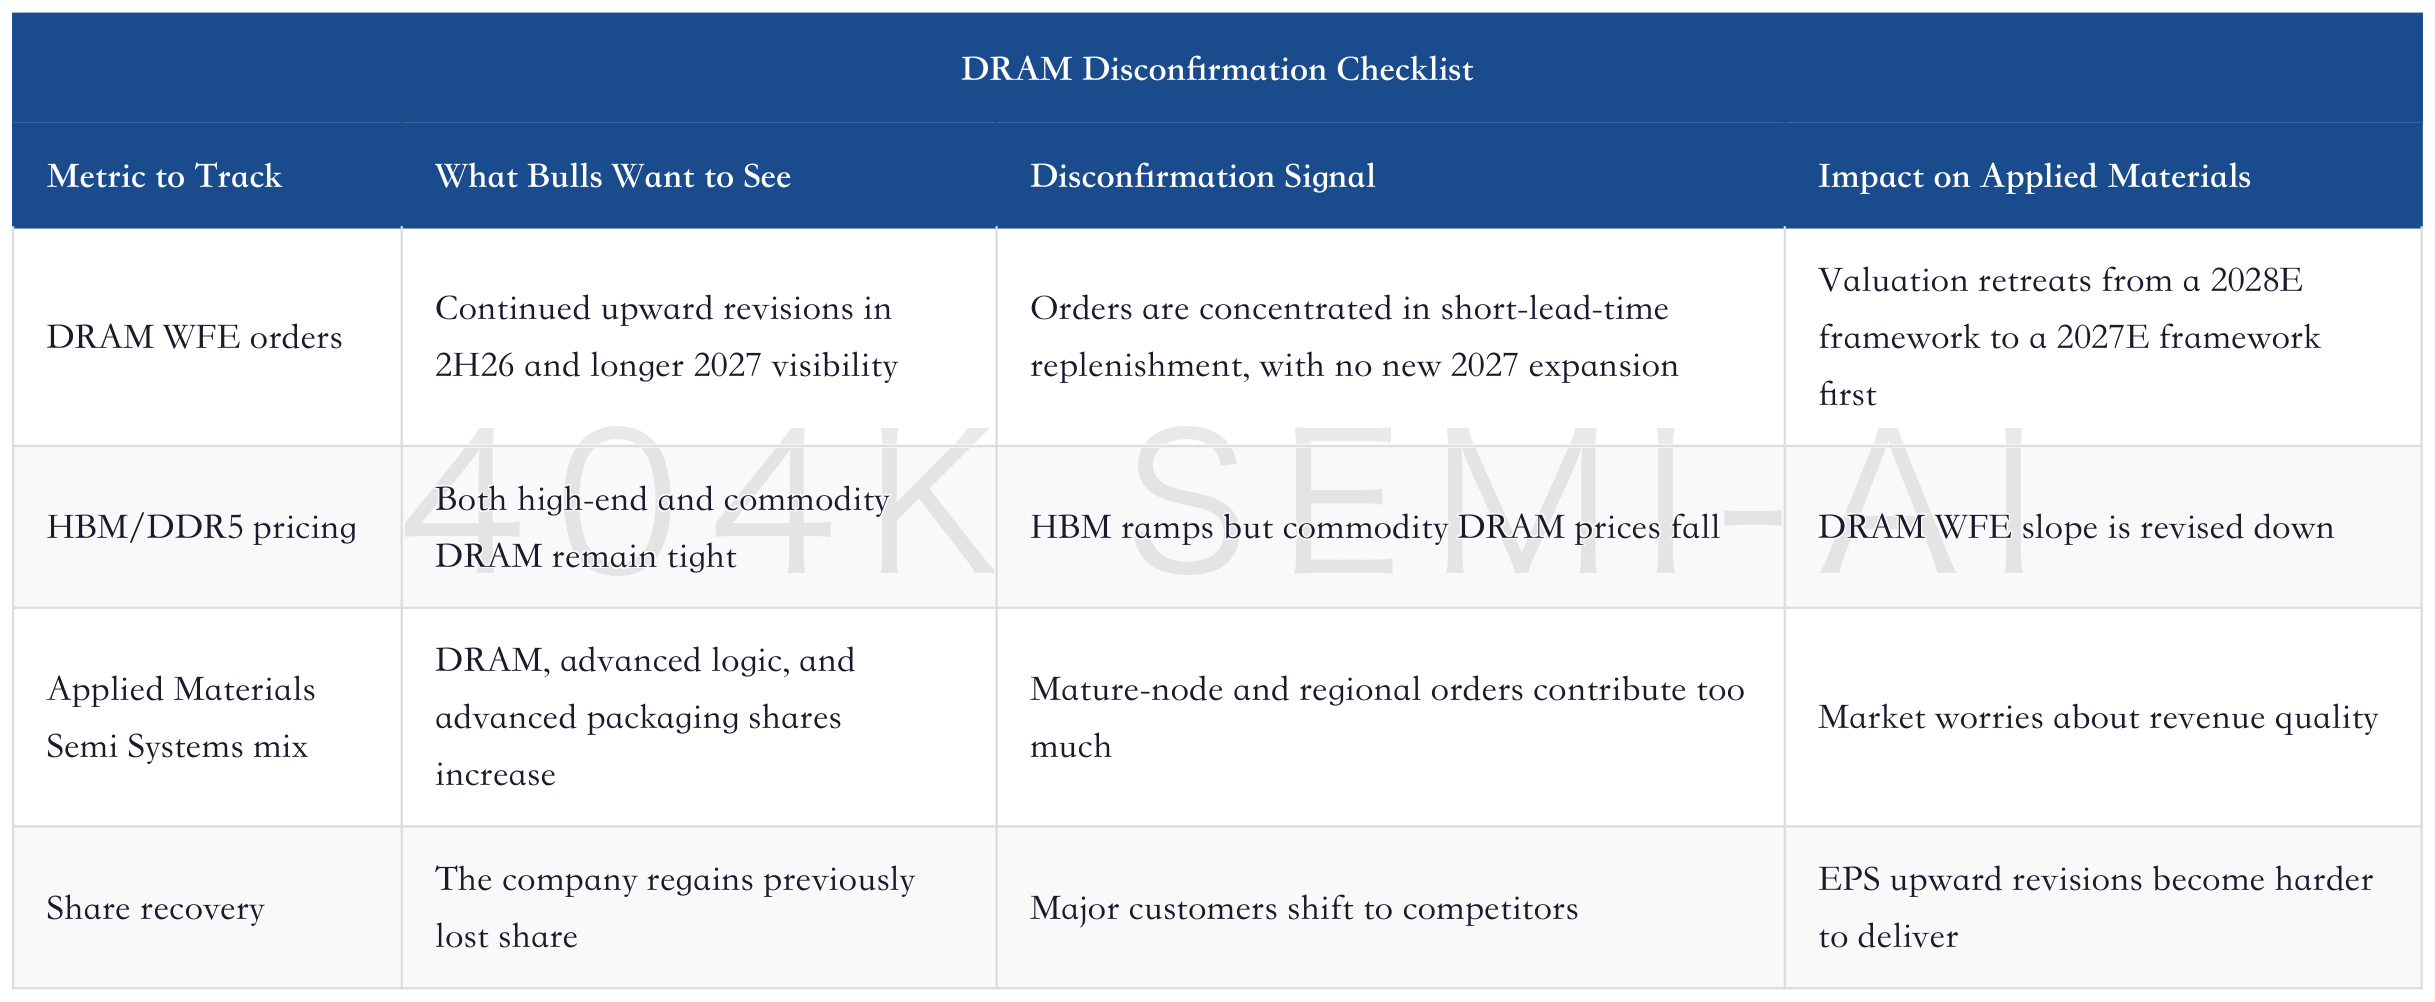
Conversely, DRAM is also Applied Materials' largest disconfirmation point. If DRAM WFE after 2026 is merely pull-forward demand, if customer expansion slows in 2027, or if HBM and commodity DRAM supply are released faster than demand, Applied Materials' share improvement will be viewed as a short-term benefit at the cyclical peak. Applied Materials bulls need to prove that the memory multiplier in AI servers is lifting DRAM equipment intensity to a new level.
4. Advanced Packaging Is the Second Ticket: Applied Materials Sells Back-End Process Density, Not Just the CoWoS Concept
Advanced packaging is Applied Materials' second ticket. The market is most familiar with CoWoS, but Applied Materials' opportunity does not come from a single packaging label. It comes from the front-end-like evolution of back-end processes. As chip area grows, die counts increase, and interconnect density rises, packaging is no longer just about sealing chips. It is rebuilding the interconnect architecture of the computing system. This shift brings deposition, etch, plating, metrology, eBeam inspection, and defect review into a larger back-end equipment market.
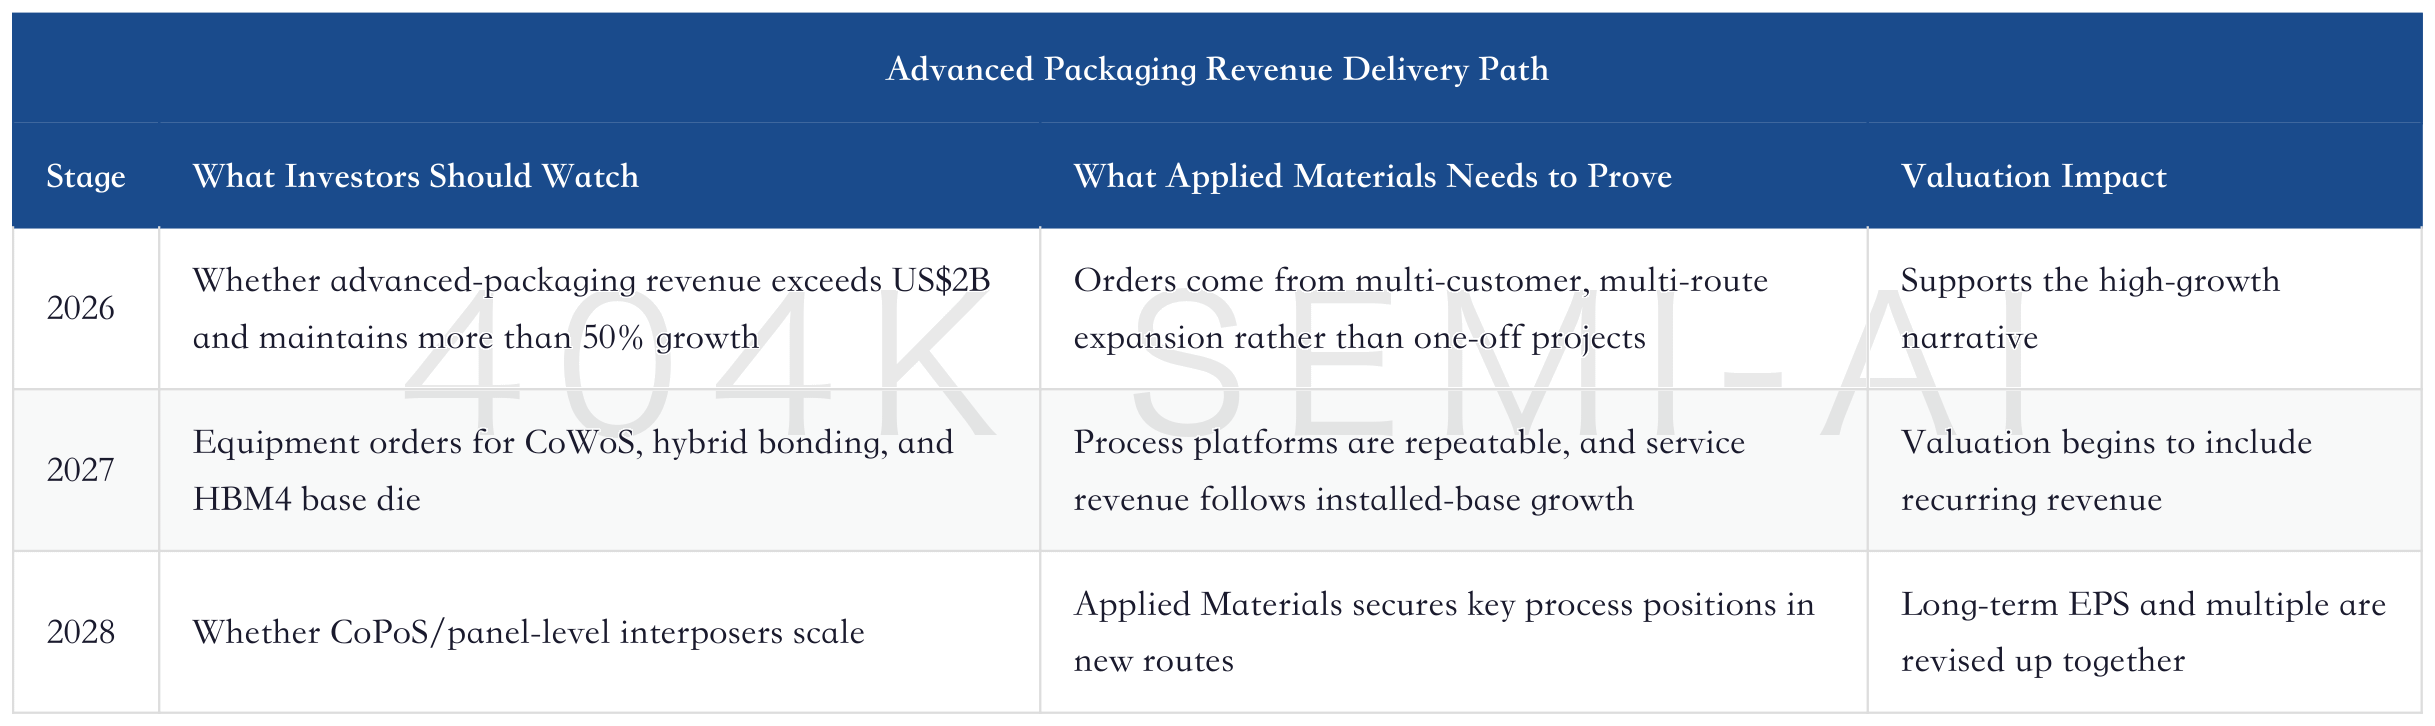
Jefferies expects Applied Materials' advanced-packaging-related revenue to exceed US$2B in 2026 and maintain growth above 50%. This is not yet the largest component of Applied Materials' total revenue, but its importance lies in growth rate and valuation narrative. Traditional semiconductor equipment is priced on front-end WFE. Advanced packaging gives Applied Materials an additional revenue curve based on "AI compute packaging density." As long as GPUs, ASICs, HBM, and interposers continue to expand, Applied Materials' back-end equipment basket will become larger.
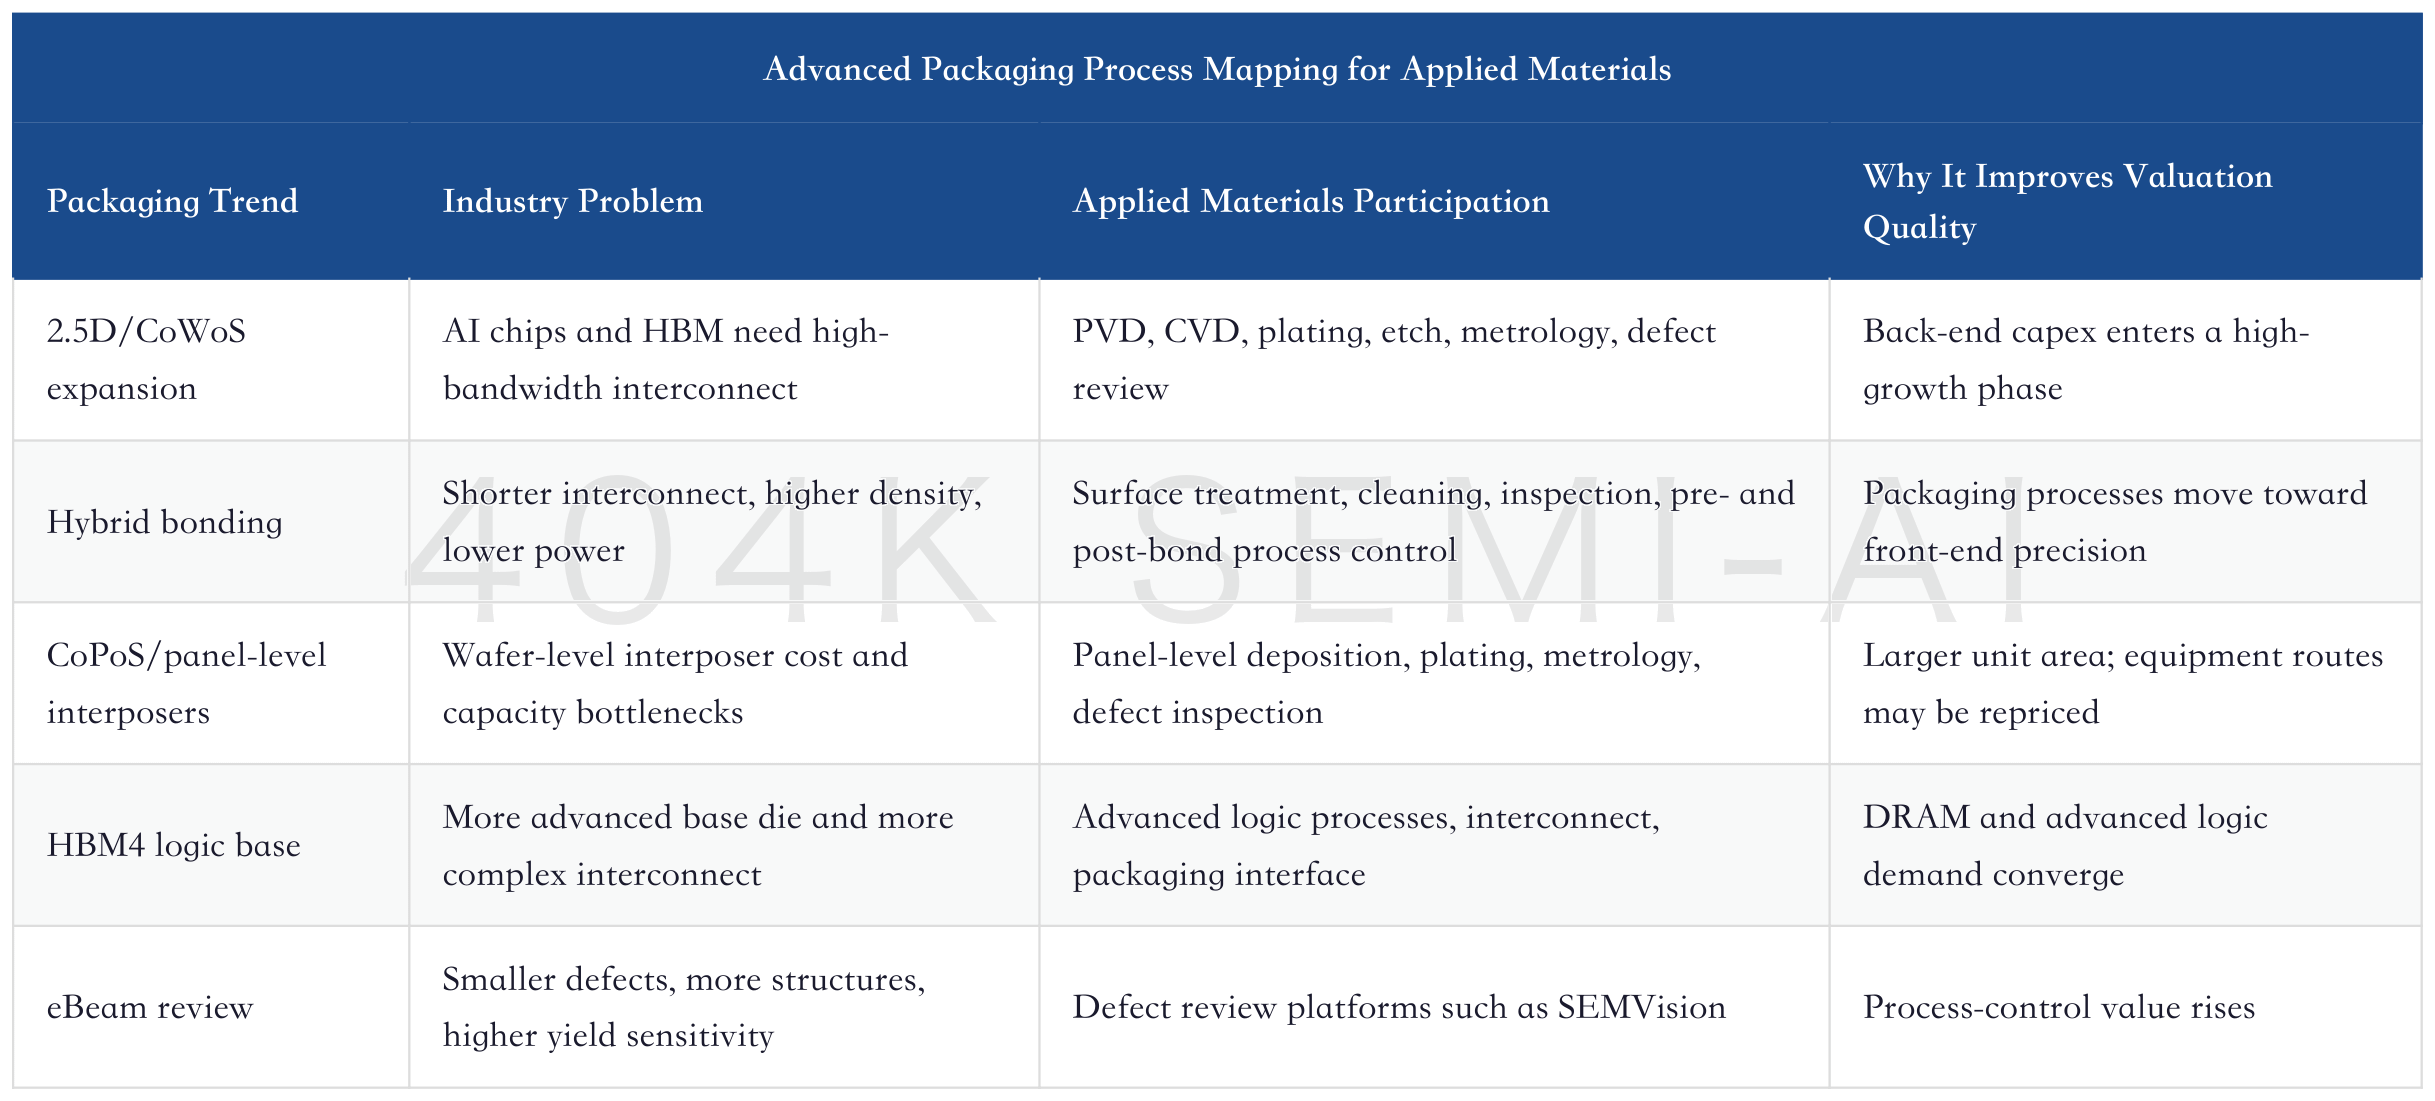
The focus of this line is "process density." The more complex advanced packaging becomes, the less it can be solved with traditional back-end equipment alone. AI chip packaging needs higher-precision thin films, interconnect, and inspection. HBM stacking needs more stable thermal management and yield control. If panel-level interposers work at scale, they could further enlarge packaging area and equipment value. Applied Materials' advantage is that it can migrate front-end materials engineering capabilities to the back end.
From HBM to WFE: How AI Turns the Memory Cycle Into an Equipment Supercycle, and How Much Runway Remains for Semiconductor Equipment?
Advanced packaging also explains why Applied Materials is not just DRAM beta. DRAM expansion benefits Applied Materials, but packaging extends the opportunity from memory makers to foundries, IDMs, OSATs, and system-level chip companies. Different roadmaps at TSMC, Samsung, Intel, memory makers, and cloud companies all eventually require more complex interconnect and inspection. If Applied Materials can bundle process opportunities across CoWoS, hybrid bonding, panel-level interposers, and HBM base die, its valuation should not be based only on the DRAM cycle.
That said, advanced packaging also has clear uncertainty. The timing of CoPoS and panel-level interposer scaling, who controls the equipment route, and whether yield and cost can meet targets are not yet settled. From an investment perspective, it is not prudent to fully capitalize all long-dated optionality at once. A more balanced view is that advanced packaging first gives Applied Materials a high-growth, small-base curve. If it exceeds US$2B in 2026 and continues to grow rapidly in 2027, investors can gradually upgrade it from "concept revenue" to a "valuation pillar."
5. AGS Service Revenue Improves Earnings Quality: Not the Flashiest Story, but Potentially the EPS Stabilizer
Applied Materials' third line is AGS service revenue. It is not as easy to narrate as DRAM or advanced packaging, but it matters a lot for valuation quality. The biggest risk for equipment companies is order volatility. The value of service revenue is that it turns the installed base into steadier maintenance, spare parts, process support, and subscription revenue. If the WFE supercycle holds, it first brings new equipment revenue and then a larger installed base. AGS then becomes an EPS stabilizer.
After earnings, UBS noted that Applied Materials raised its long-term AGS growth target from low double digits to roughly the mid-teens. Evercore also emphasized that AGS could grow at high double digits in 2026. This may look like a small change, but it helps valuation: if Applied Materials' revenue is only Semi Systems moving with WFE, the market assigns a cyclical multiple. If AGS share and growth rise at the same time, the market will be willing to treat part of revenue as higher quality.
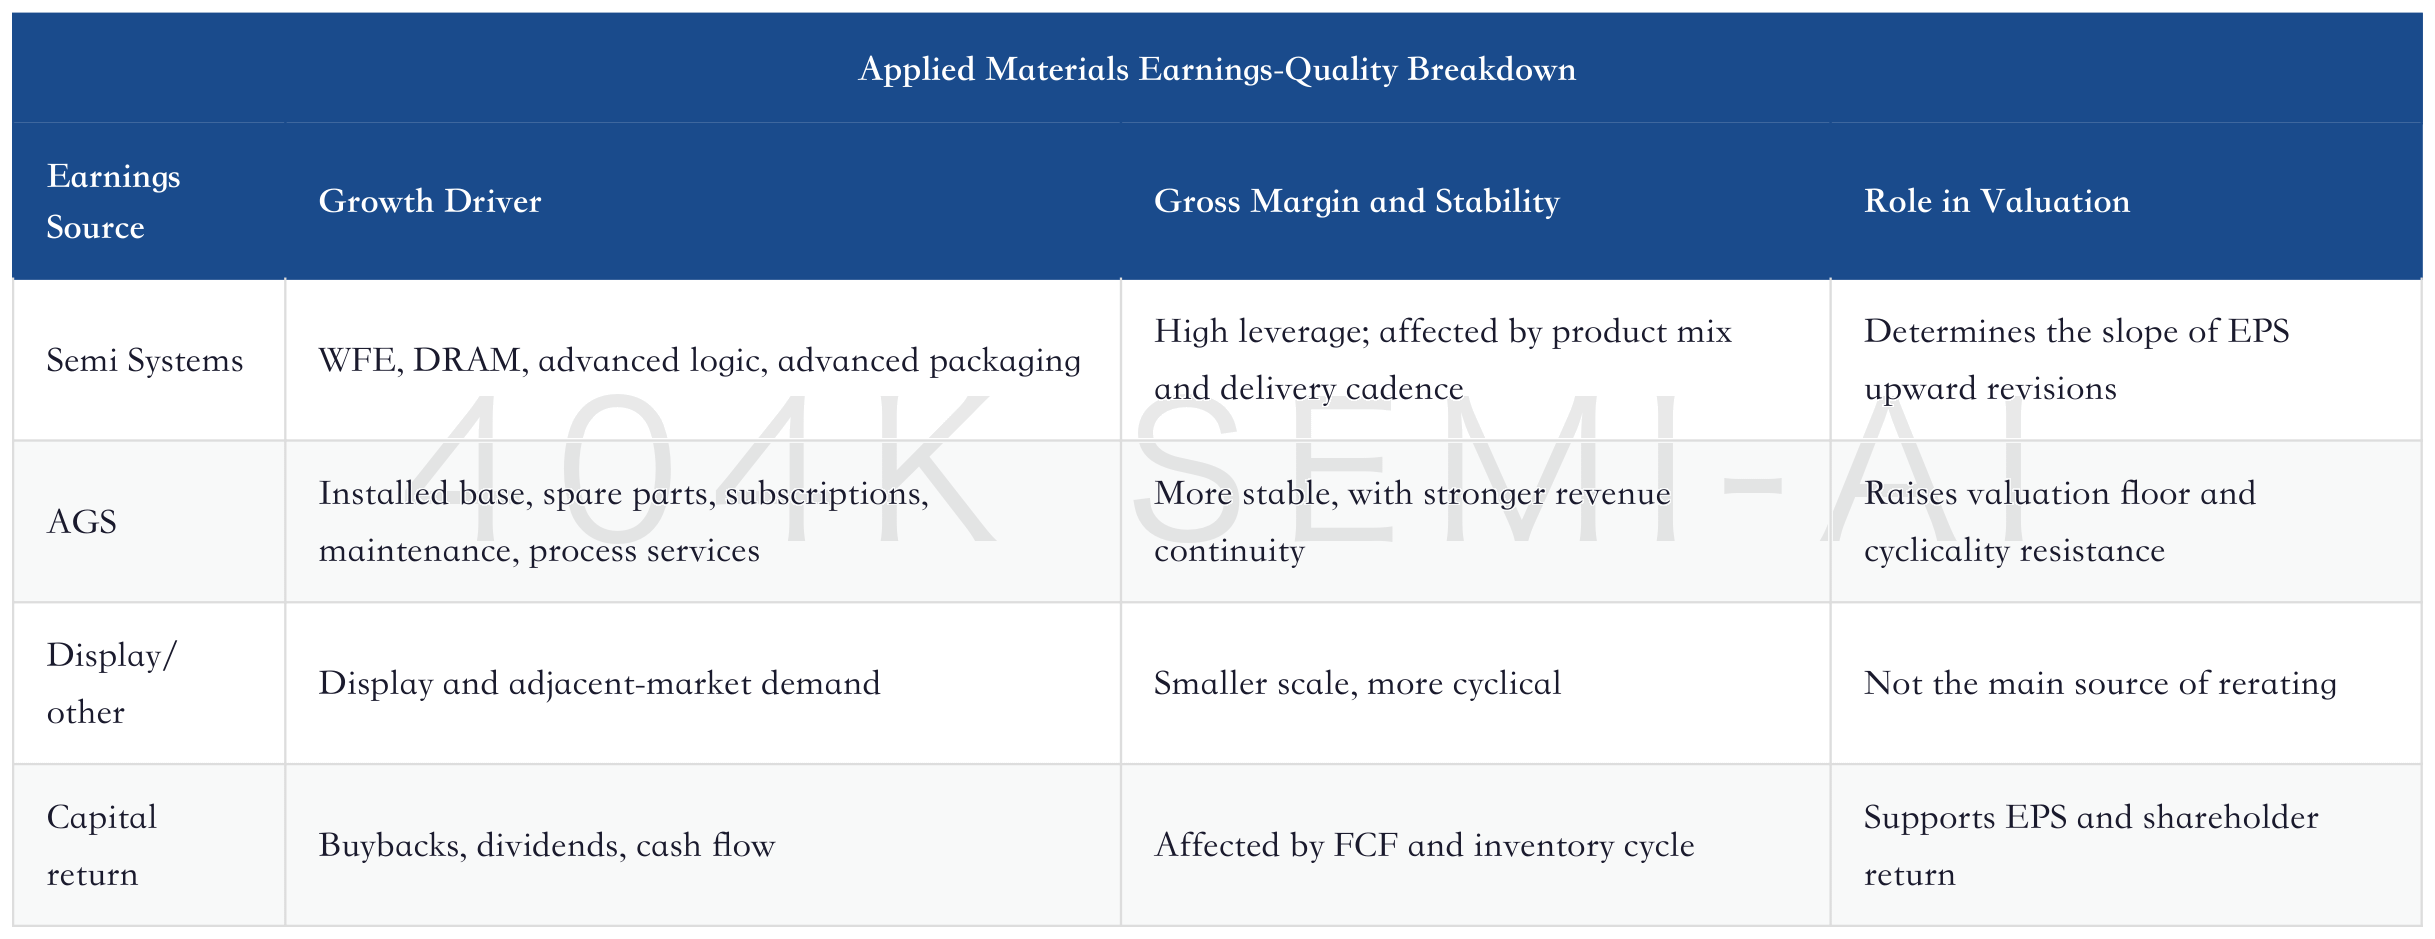
Service revenue also has a hidden advantage: the more complex advanced processes become, the more customers rely on continuous support from equipment vendors. GAA, backside power delivery, 3D DRAM, advanced packaging, and eBeam inspection all require ongoing tuning, maintenance, and yield optimization. The deeper Applied Materials' customer relationships become, the more AGS revenue looks like technical service rather than ordinary after-sales support. This is also why service revenue can help equipment companies move from "selling tools" to "selling process capability."
Of course, AGS has risks as well. When new equipment revenue grows rapidly, AGS share can be diluted. Inventory and supply-chain volatility can also affect near-term cash flow. Applied Materials' April-quarter free cash flow was very low, partly because of specific payments, M&A;, and inventory. If future WFE expansion requires Applied Materials to carry inventory continuously, cash flow may lag the income statement for a period. Bulls need to focus on whether AGS continues to deliver after the installed base expands; single-quarter FCF should be treated only as a supporting signal.
6. Peer Ranking: Applied Materials, LAM, and KLA Are Different AI Manufacturing Bottlenecks
Applied Materials is not an isolated asset. In US semiconductor equipment, Applied Materials, LAM, and KLA represent different AI manufacturing bottlenecks. Applied Materials is more skewed toward materials engineering, DRAM, advanced logic, packaging, and services. LAM is more skewed toward etch and NAND. KLA is more skewed toward process control, inspection, and metrology. A higher WFE total benefits all three companies, but structural differences determine relative outperformance by phase.
This is where Morgan Stanley's bear-case value lies. It upgraded LAM to overweight and downgraded Applied Materials to equal-weight, arguing that the 2027 NAND recovery gives LAM more leverage and that Applied Materials' DRAM advantage has already been partly reflected by the market. The report noted that Applied Materials' DRAM exposure is higher than LAM's in 2026, but LAM has higher NAND exposure, and 2027 NAND WFE upward revisions may become the new marginal variable. This is a very important counterargument: buying Applied Materials is effectively a bet that DRAM, advanced logic, and packaging content intensity will keep exceeding market expectations.
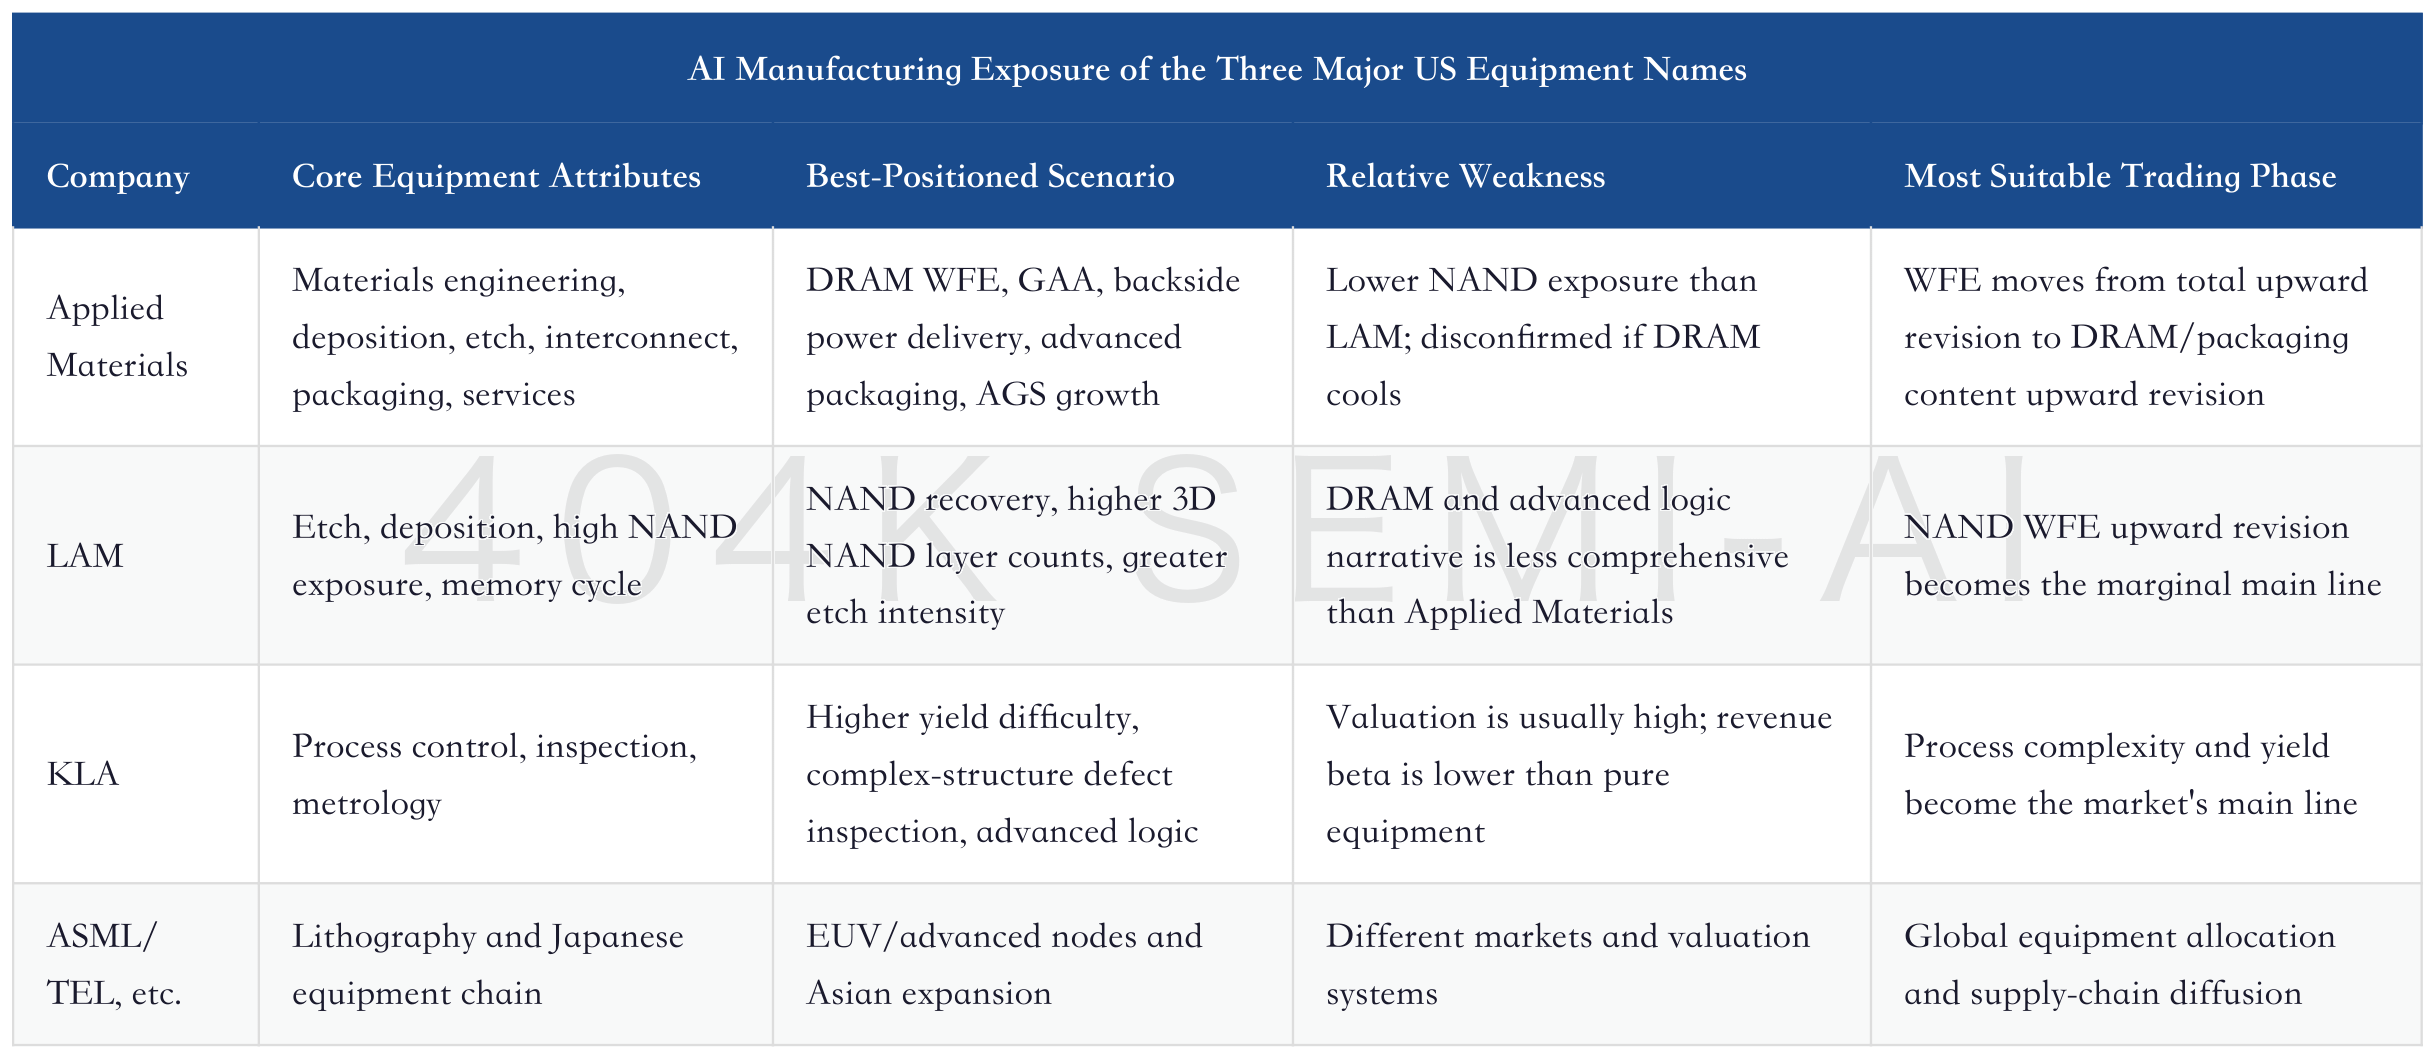
The conclusion for Applied Materials from this ranking is as follows: if investors believe 2027 is mainly about NAND recovery, LAM's leverage is more direct; if they believe 2027-2028 is mainly about continued increases in DRAM, advanced logic, and packaging complexity, Applied Materials' structure is more favorable; if they believe all equipment is entering a supercycle but are unsure who gains share, KLA's process-control profile is steadier. Applied Materials' advantage comes from having positions across multiple AI manufacturing processes.
Rerating Japan's Semiconductor Equipment and Materials: Physical Bottleneck Assets Behind AI Compute Expansion
From a valuation perspective, Citi's 2028 target-price framework for Applied Materials, LAM, and KLA also reflects these differences. Applied Materials is valued at 31x 2028E EPS to reach US$710. LAM and KLA are valued at 40x 2028E EPS, reflecting the market's willingness to give higher multiples to higher-growth or higher-quality links. Applied Materials' investment opportunity is this: if it can prove the DRAM/advanced packaging/AGS combination improves growth quality, a 31x or higher multiple has support; if it is only WFE beta, the multiple will be pushed back into the traditional range.
The peer debate also highlights one point: Applied Materials' story cannot be written only as "the industry is strong." A strong industry is a necessary condition, not a sufficient one. Applied Materials needs to prove in 2H26 and 2027 that it is gaining share, defending gross margin, expanding AGS, and turning advanced packaging revenue from small-base high growth into a long-term platform. Only if these metrics deliver does the valuation deserve to move from the US$500 level to above US$700.
7. Valuation Debate: Behind US$520, US$570, US$710, and US$770 Is a Tug-of-War Between 2027E and 2028E
The valuation debate around Applied Materials is already clear. Early target prices clustered around US$500, anchored on 2027E EPS and a premium to traditional equipment multiples. After June, some firms shifted the framework to 2028E EPS, quickly moving target prices above US$700. Morgan Stanley is relatively cautious, while Jefferies is more willing to assign a high-cycle scenario. The specific target prices and multiples are set out below.
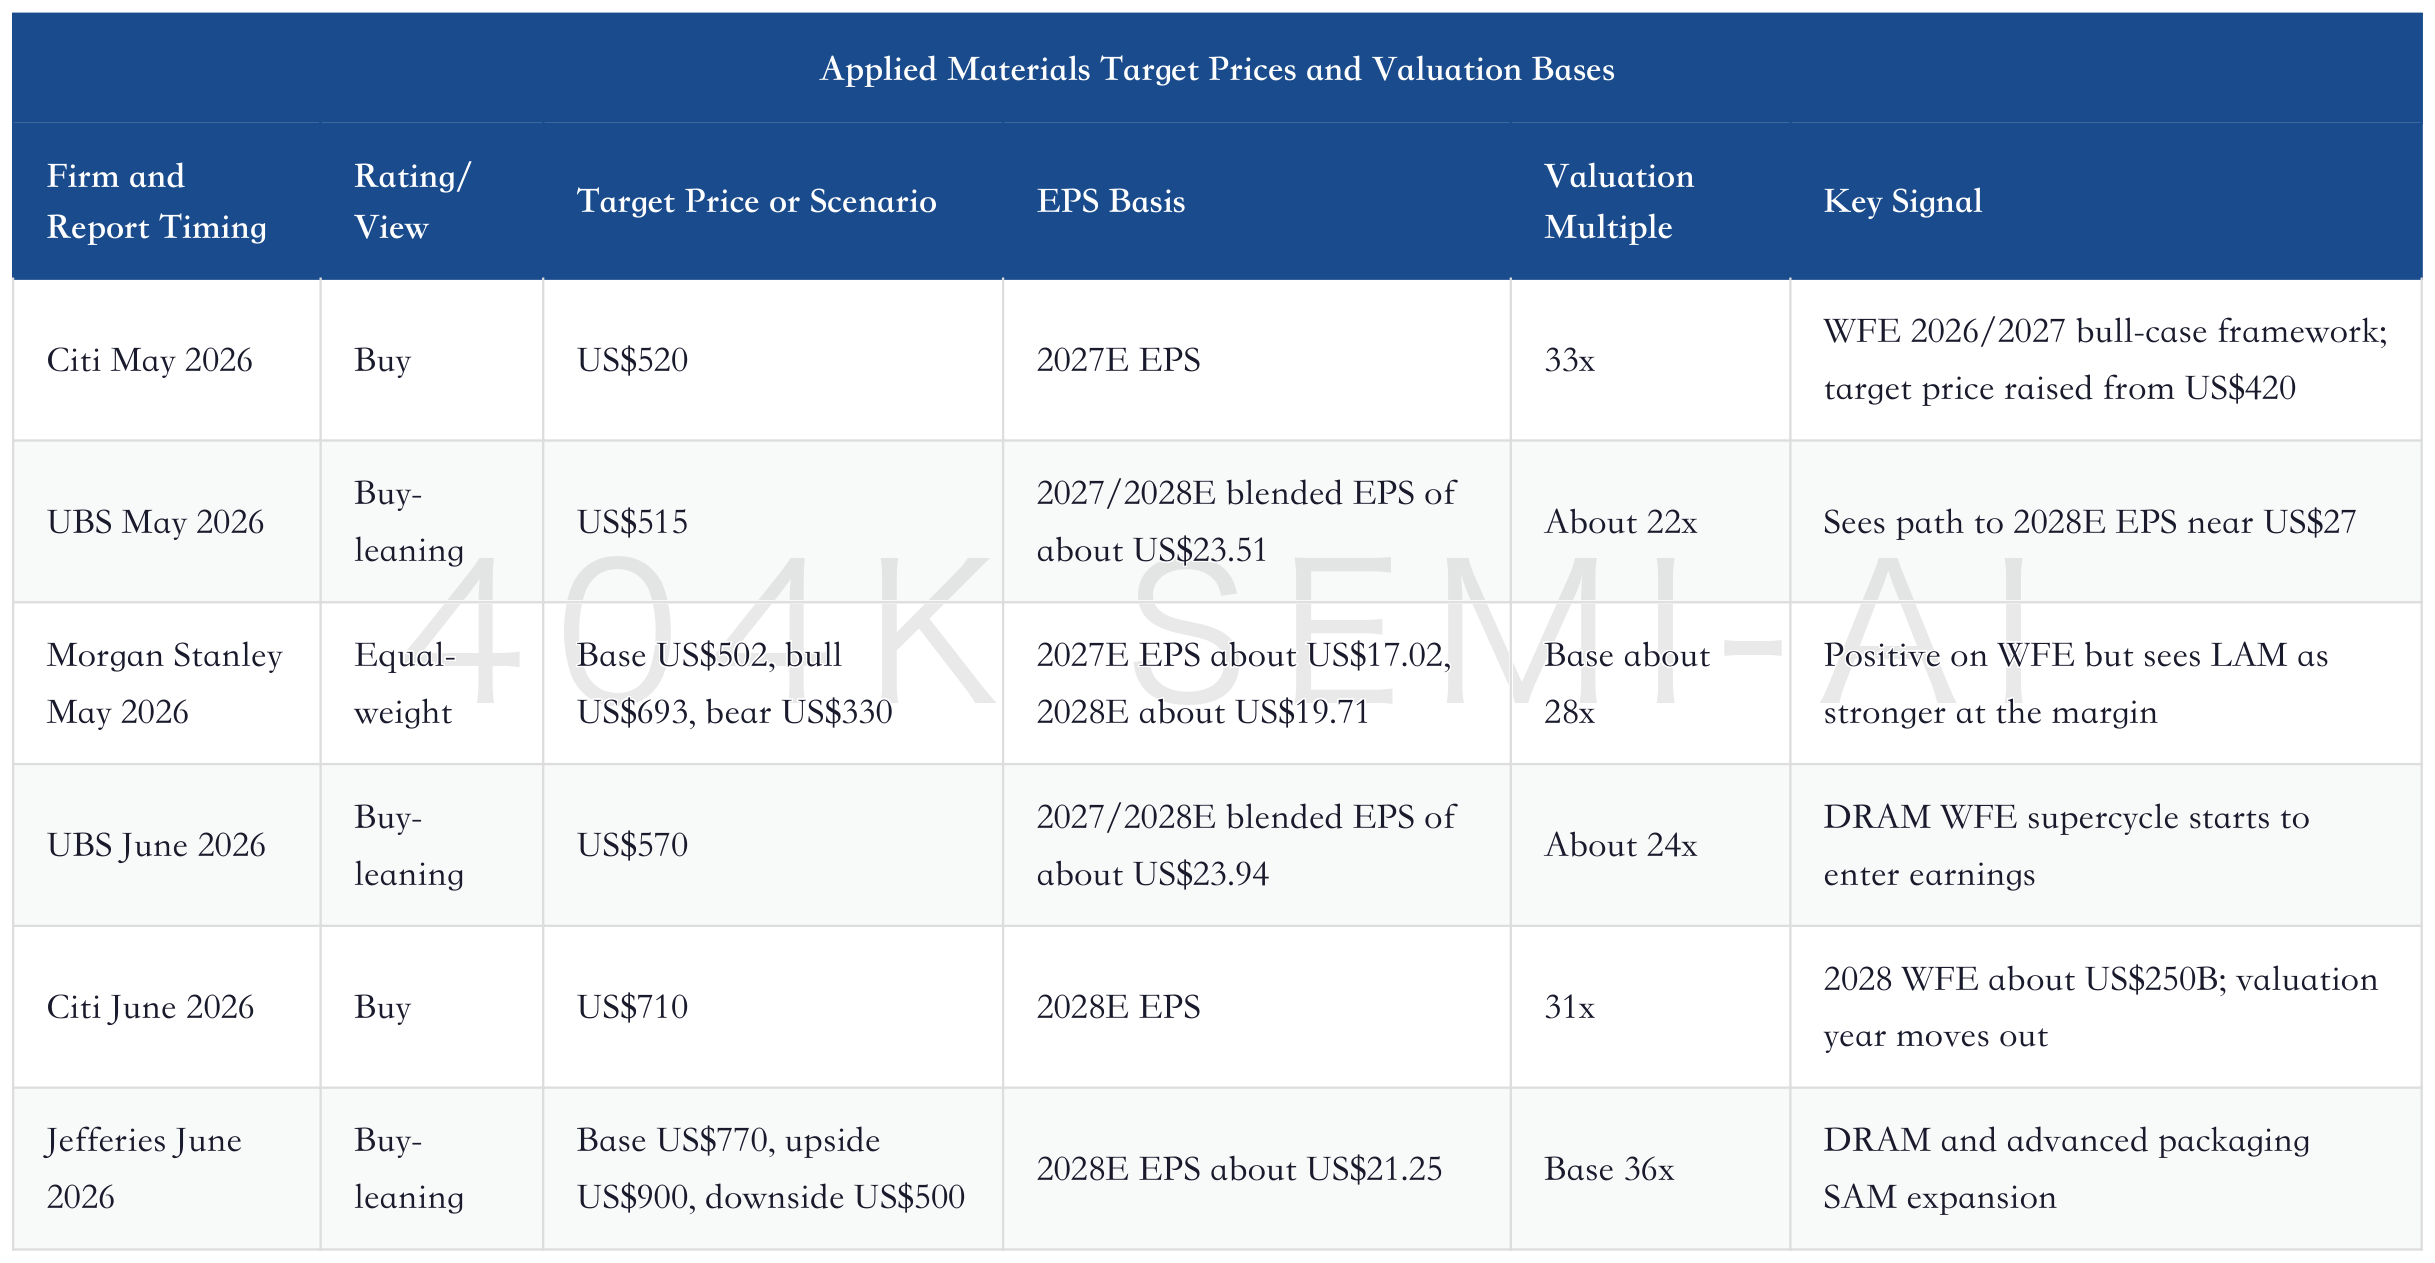
This table should not be read as "the highest target price is the most correct." It should be read as three variables: earnings year, EPS number, and valuation multiple. Morgan Stanley is more anchored on nearer-term earnings and a base multiple. UBS uses blended EPS. Citi and Jefferies push the lens to 2028, so the numbers look very different.
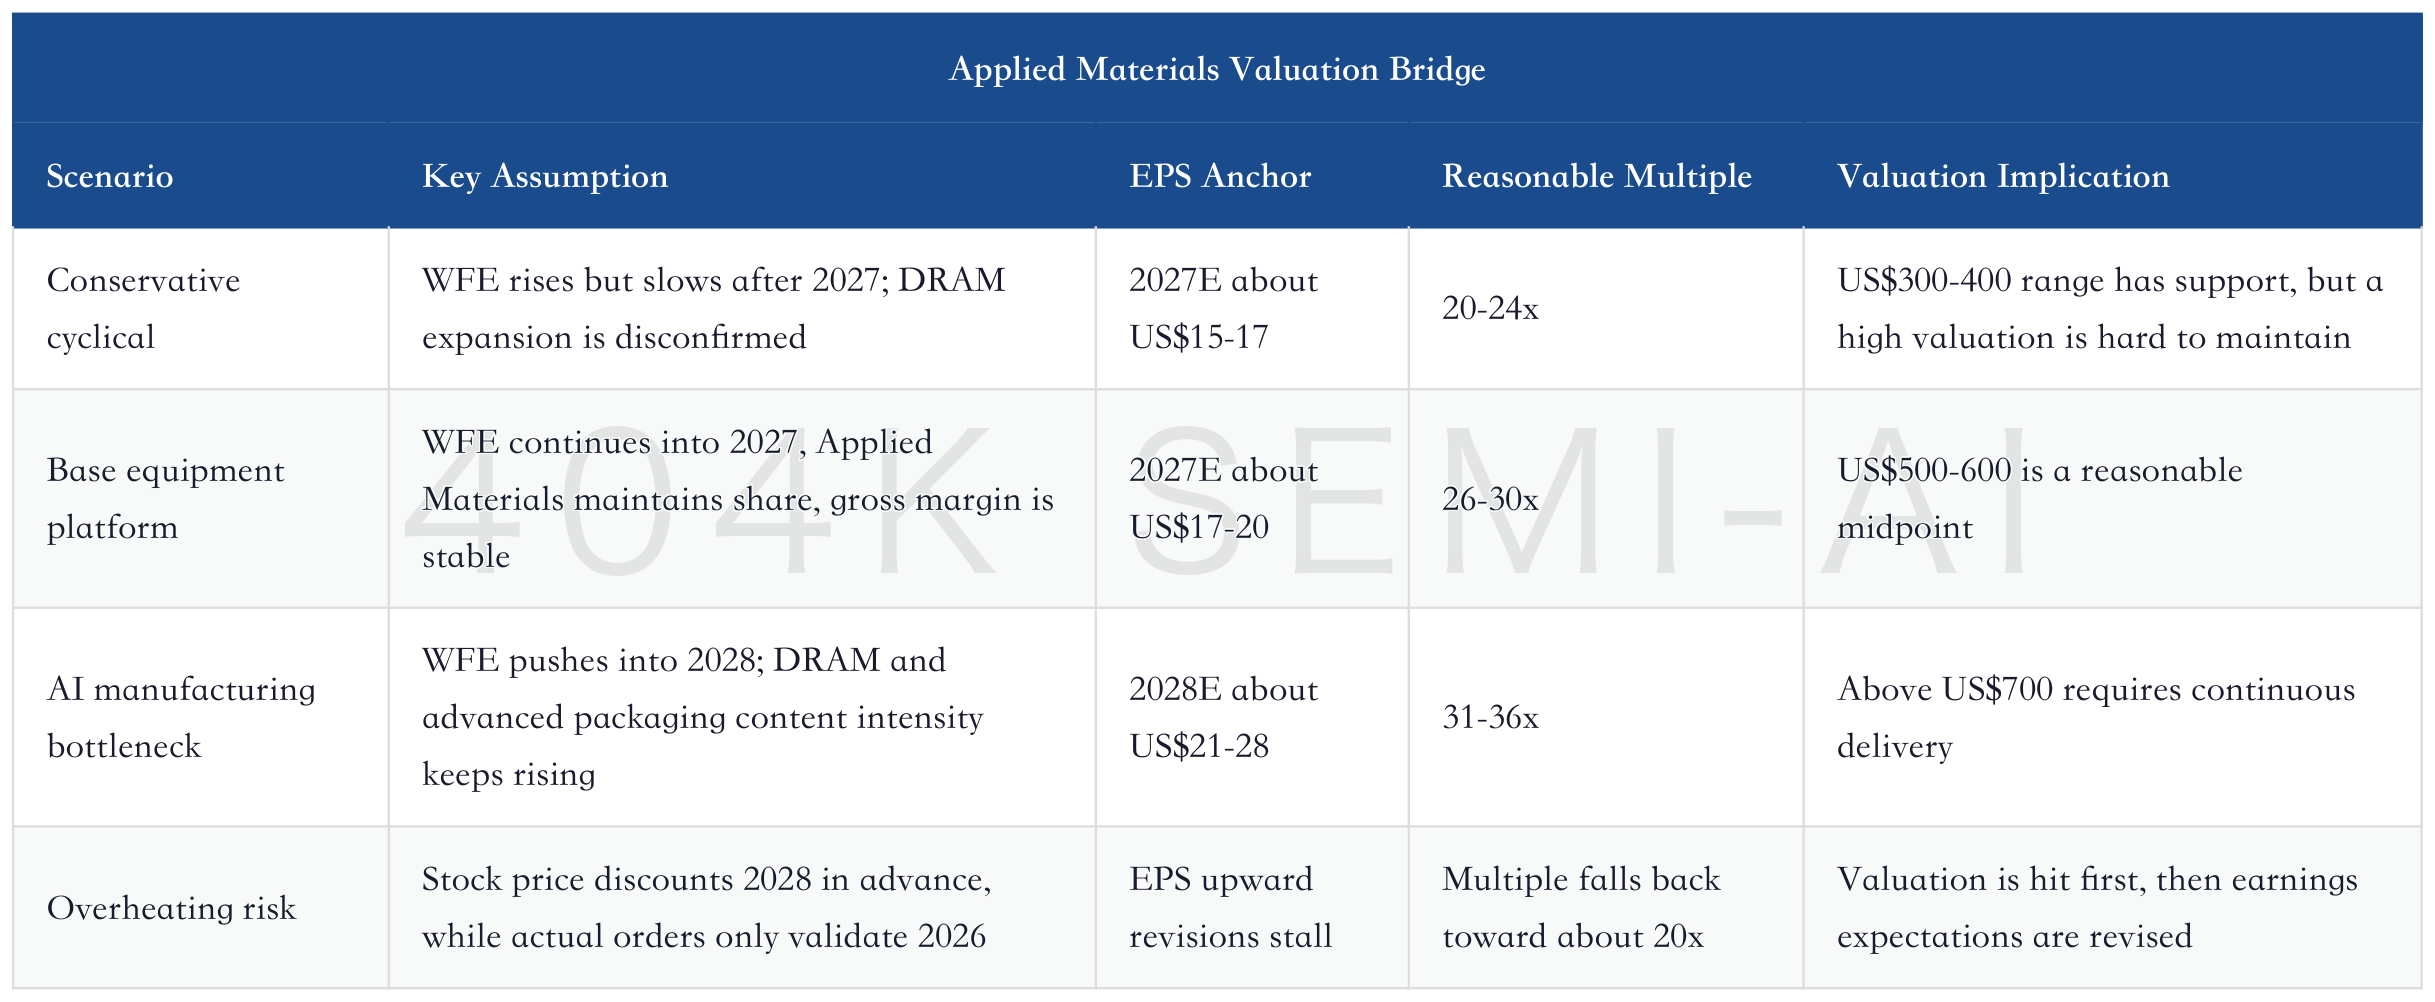
The most important valuation question for Applied Materials today is whether the market can pay for 2028 in mid-2026. If industry visibility really reaches eight quarters, customer production plans extend into 2028, and fab cleanrooms and equipment delivery become hard constraints, discounting 2028 earnings in advance is not unreasonable. Conversely, if this is simply the sell side linearly extrapolating AI capex excitement, the 2028 target price becomes a high-level narrative rather than a deliverable model.
Particular attention should be paid to the quality of the "valuation multiple." Citi's 31x 2028E P/E for Applied Materials is already meaningfully above the company's three-year average, and Jefferies' 36x is closer to a high-cycle scenario. To support this multiple, Applied Materials cannot simply grow revenue. It must prove the growth comes from higher-quality structure: DRAM content intensity, advanced packaging, service revenue, and stable gross margin. If revenue growth comes from low-margin, short-cycle, regional orders, the market will push the multiple back down.
Target prices also need to be read by formula, not by the headline number. Lower target prices are essentially near-term EPS plus a base multiple. Higher target prices have already built 2028 WFE and longer-dated EPS into the model. Sorting these numbers on one chart is not meaningful. What matters is identifying the unfulfilled conditions embedded in each target price.
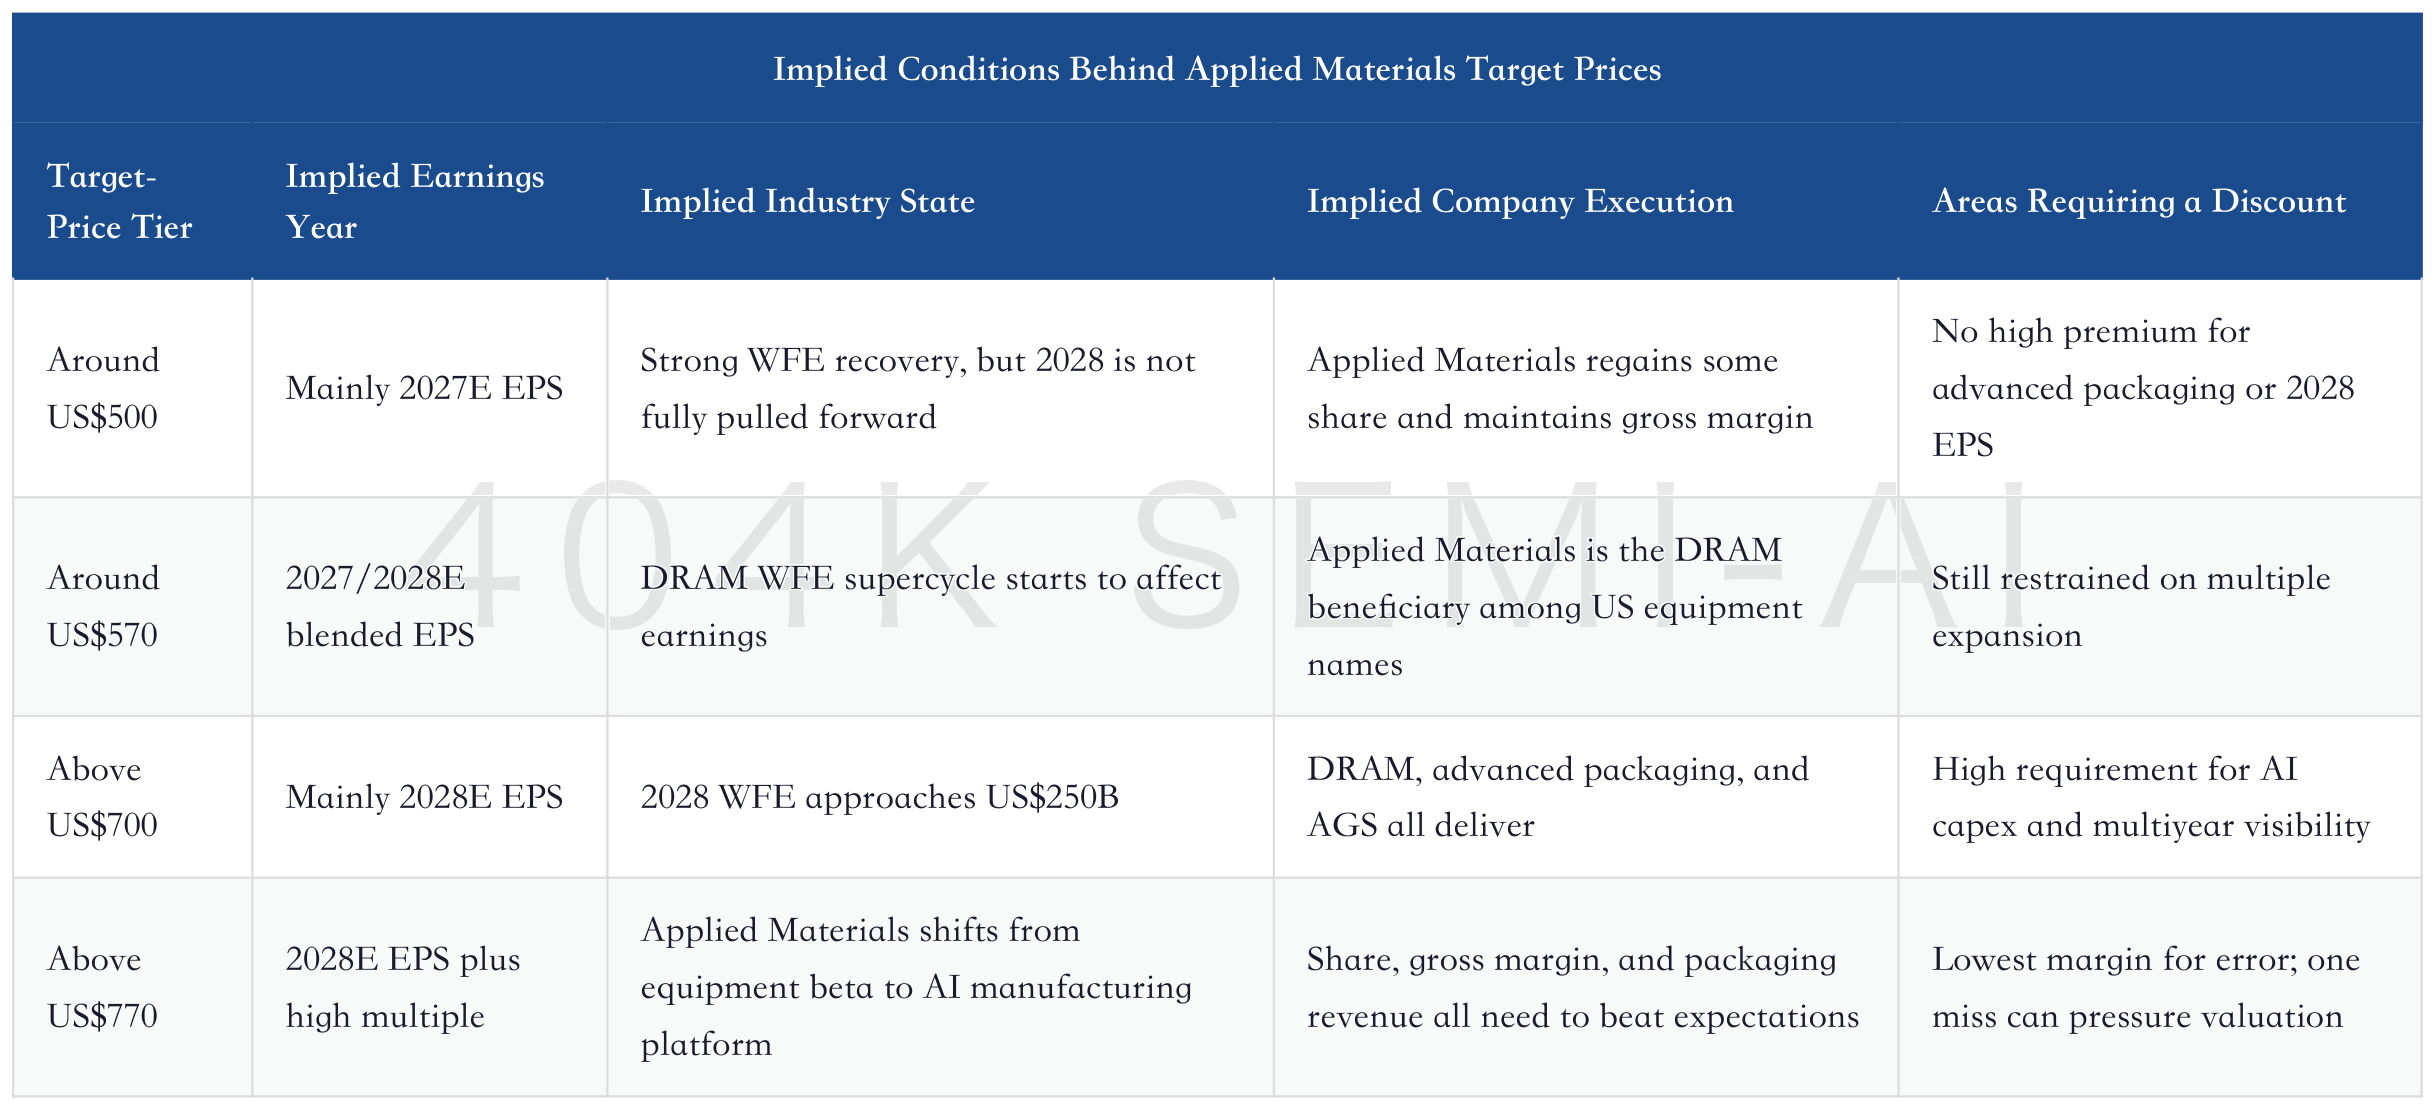
This breakdown is very useful for investing. If future Applied Materials earnings only prove that 2026 is strong, the market can at most sustain the first tier. If the company can prove that 2027 orders are still being revised upward, valuation can stabilize in the second tier. Only if customer scheduling, DRAM WFE, advanced packaging, and AGS all make the 2028 path more tangible will the market be willing to pay for the third and fourth tiers. The target-price increase itself is not the buy case; the verification conditions behind the target price are.
Applied Materials' valuation is therefore not as simple as "higher means more optimistic." High target prices often use further-out years and higher multiples, which also means higher risk. Low target prices are not necessarily bearish on the industry; they simply require pricing on nearer-term years. The more reasonable current reading is this: around US$500 is already supported by strong 2027 WFE and share recovery, US$570 is a neutral-to-positive framework that incorporates the DRAM supercycle into blended EPS, and above US$700 is a 2028 AI manufacturing platform option. Investors need to decide which layer of optionality they are willing to pay for.
8. Company Model: Applied Materials' Profit Slope Comes From Revenue, Gross Margin, and Services Rising Together
Applied Materials' company model can be understood through three variables: revenue scale, gross margin, and share count/EPS. Revenue scale is determined by WFE and share. Gross margin is determined by product mix, advanced process platforms, and service revenue. EPS is also affected by buybacks and operating leverage. The sell side's wide range of 2028 EPS estimates for Applied Materials essentially reflects different assumptions on these three variables.
UBS's June model lays out a very strong upside path, implying that Applied Materials continues to benefit from WFE upward revisions in 2026-2028 and that gross margin and expense leverage do not meaningfully slip. Morgan Stanley's base model is more conservative, mainly differing in revenue slope and longer-term EPS. Putting the revenue and EPS paths into a comparison table better shows the difference between the two worldviews.
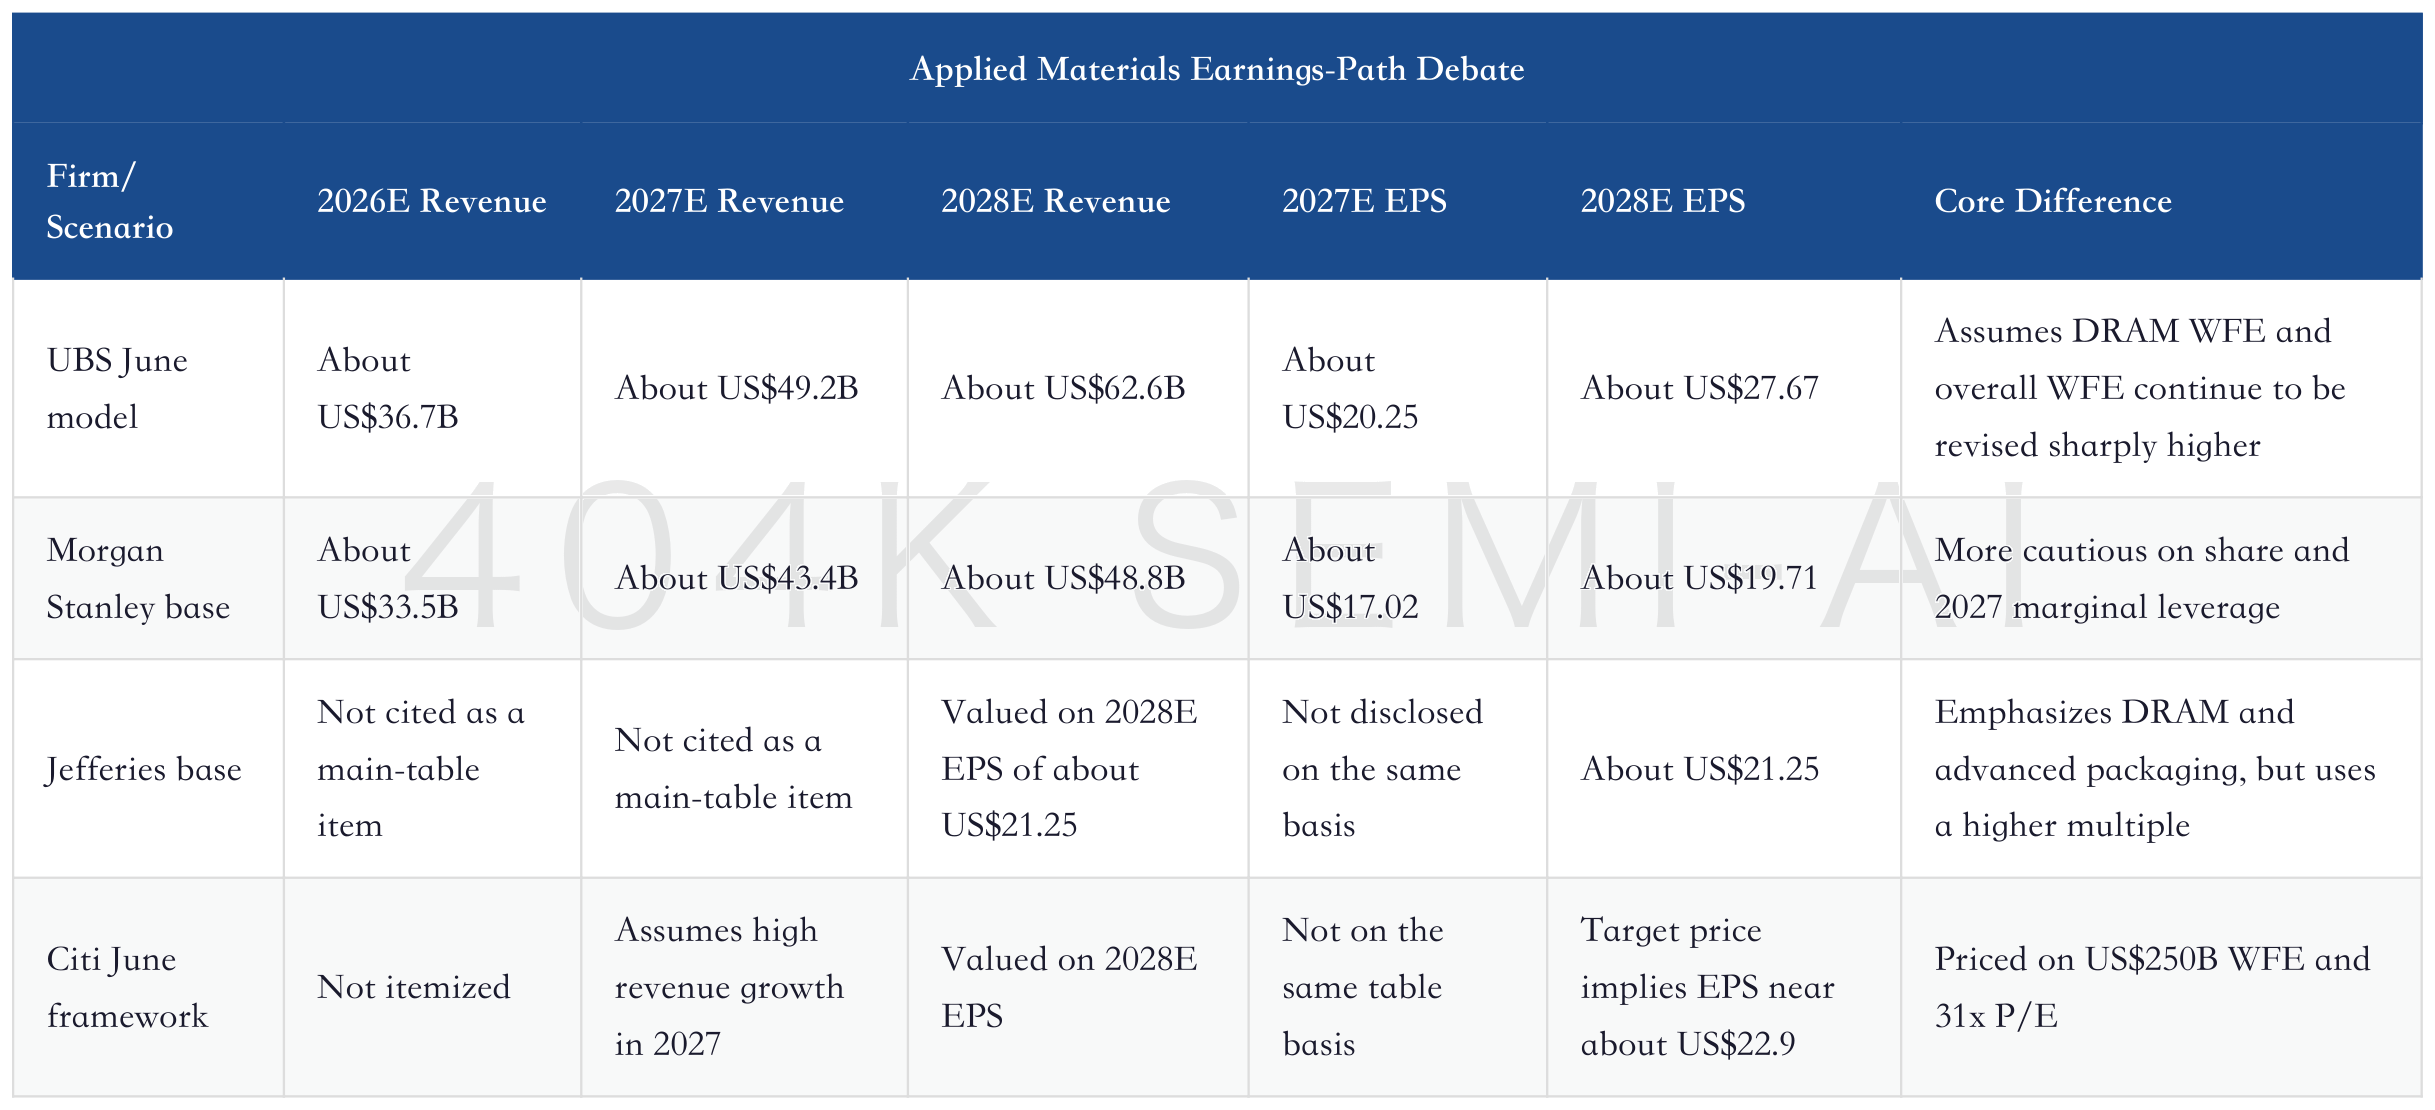
This table gives a practical judgment: a US$500-level valuation mainly needs 2027 EPS to deliver, while above US$700 mainly needs 2028 EPS to deliver. What investors really need to watch is whether revenue continues to be revised upward after 2027. If longer-term EPS lacks further upward evidence, the stock may only stay around the equipment-cycle midpoint. If the 2028 earnings path continues to become more concrete, the US$700 target has a real foundation.
Applied Materials' gross margin is the amplifier in this model. April-quarter gross margin was about 50%, and Semi Systems gross margin was near 55%, which UBS viewed as a rare high point over the past 25 years. While the company sharply raised July-quarter revenue guidance, gross-margin guidance still stayed around 50%, suggesting that higher revenue did not materially sacrifice earnings quality. If advanced packaging, new platforms, and AGS continue to improve mix, EPS leverage will exceed revenue leverage.
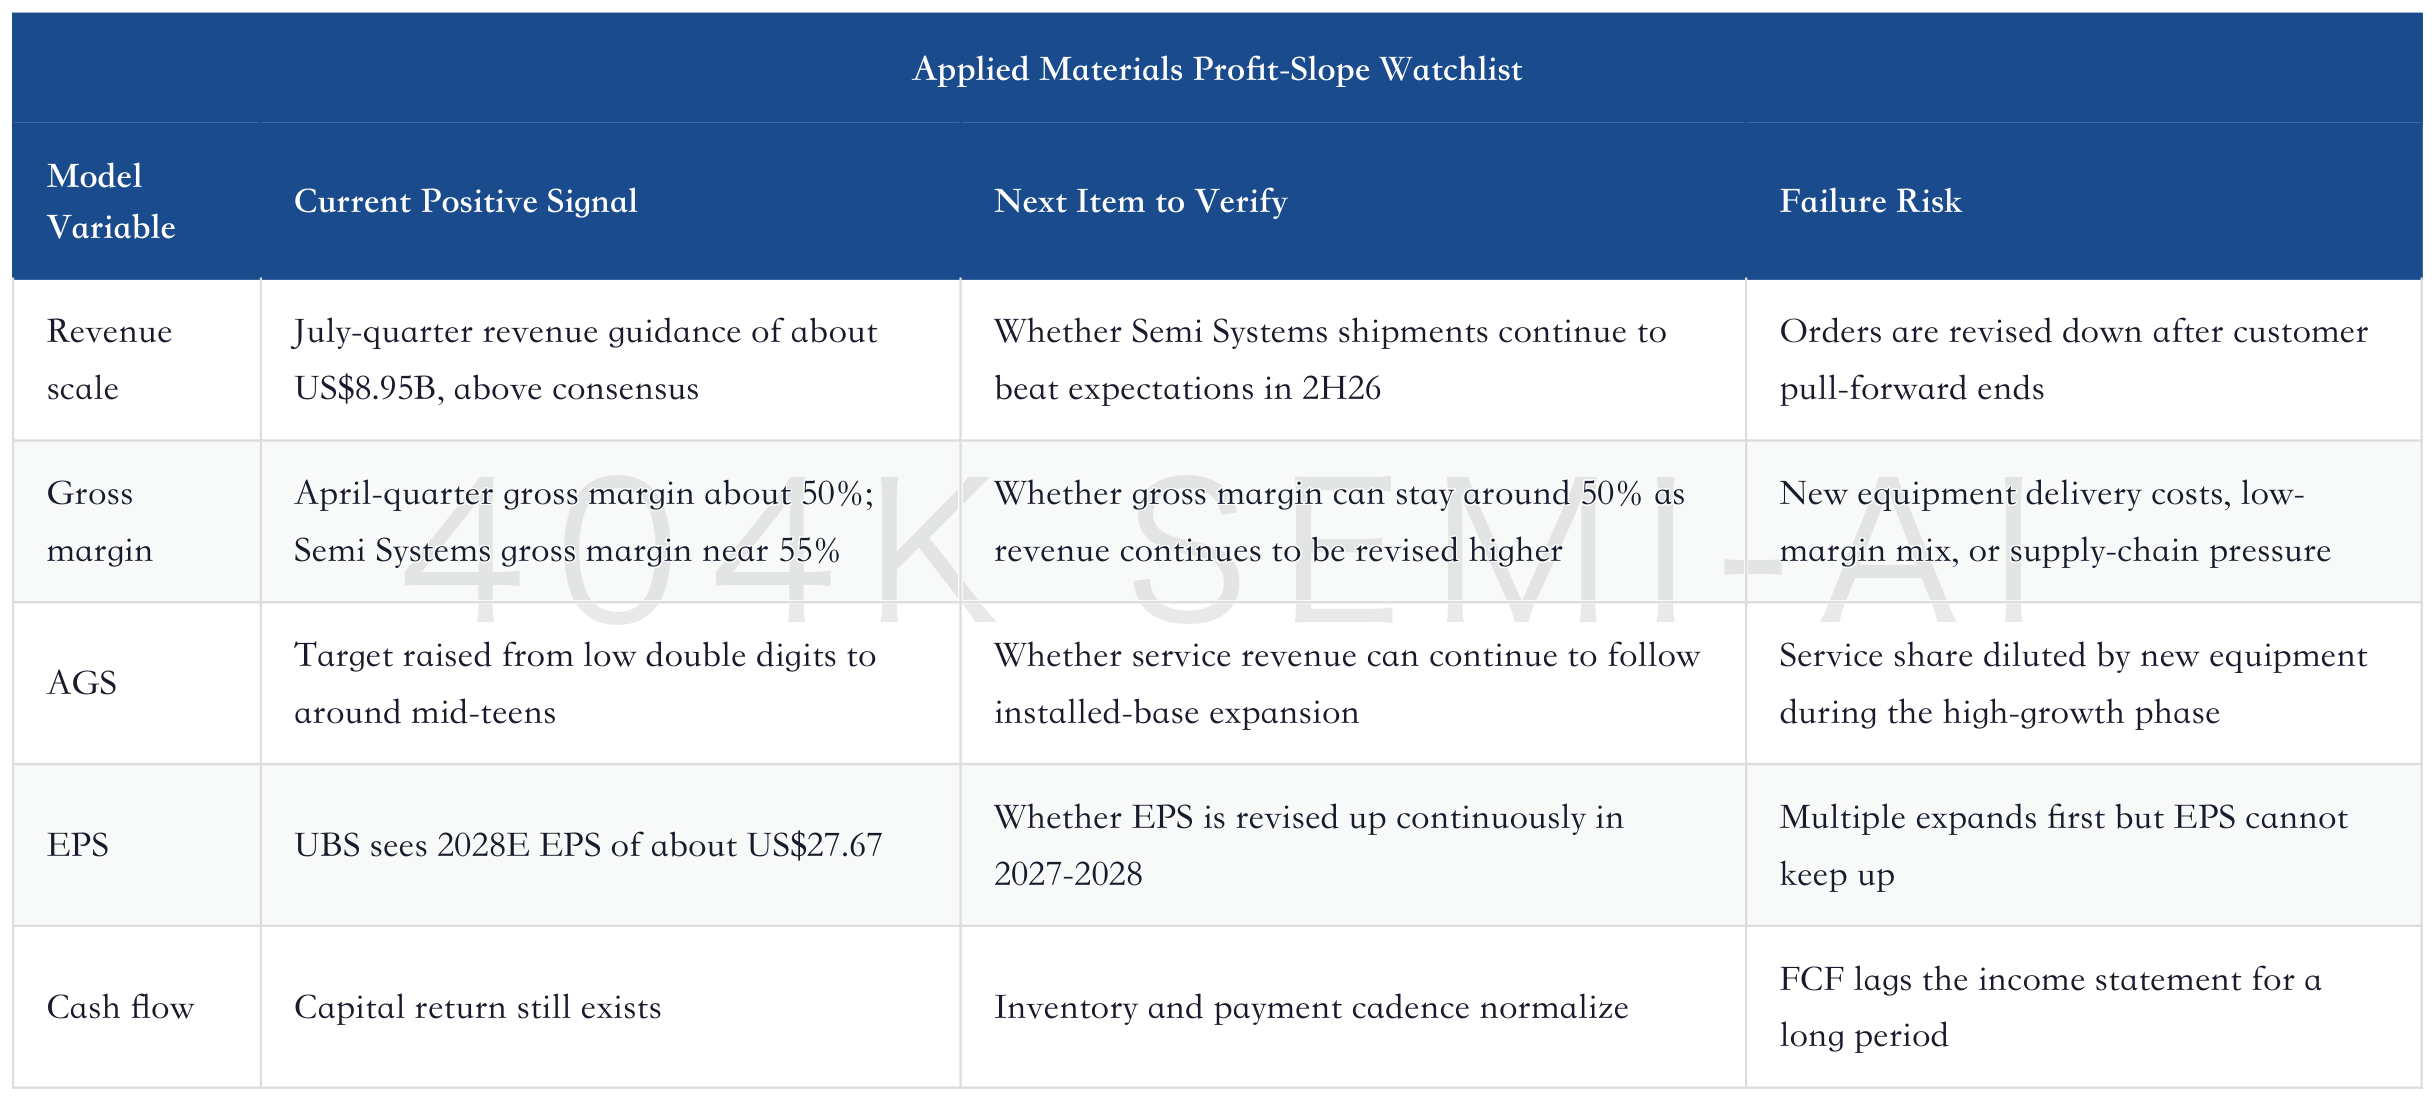
This is also why future Applied Materials earnings cannot be assessed only by revenue. Revenue beating expectations with falling gross margin indicates a problem in order quality. Stable gross margin with slowing AGS growth means the services story is not strong enough. AGS growth without Semi Systems share gains means the company is only monetizing the installed base rather than capturing new-cycle alpha. The truly favorable result is all three lines rising together: Semi Systems shipments revised up, gross margin stable or expanding, and AGS growth remaining elevated.
9. How Prior Work Connects: Applied Materials Is the Intersection of the "Memory Tax" and the "WFE Supercycle"
The AI hardware cycle has already been decomposed into multiple layers: GPUs and ASICs drive advanced logic, HBM and DRAM drive memory, NAND and SSDs absorb the inference data hierarchy, advanced packaging turns chip interconnect into a bottleneck, and every path ultimately returns to WFE and equipment. Applied Materials sits right at the intersection of these lines.
Semiconductor Industry Deep Dive: Memory-Tax Spillover, SanDisk, Applied Materials, and ON Semiconductor's Acquisition of Synaptics in AI Hardware Rerating
From the perspective of the "memory tax," Applied Materials sits upstream on the equipment side of rising memory prices. Higher DRAM prices, HBM shortages, and rising DDR5 long-term contract prices eventually force memory makers to expand capacity, upgrade processes, and improve yield. Applied Materials does not bear the full risk of memory price volatility, but it can sell materials engineering equipment into expansion and process upgrades. Its earnings leverage lags memory prices, but its duration may be better.
From the perspective of the "WFE supercycle," Applied Materials combines total growth and structure. A pure total-volume trade can buy the entire equipment group. A structural trade asks who is advantaged in DRAM, advanced logic, advanced packaging, and service revenue. Applied Materials' advantage is that it spans multiple incremental links. Its disadvantage is that it does not have NAND leverage as pure as LAM's, nor does it have KLA's higher-quality process-control label. Applied Materials is a more complex asset: it has cyclical leverage and platform potential.
From the perspective of "advanced packaging," Applied Materials represents the migration of front-end capabilities to the back end. CoWoS, HBM, and chiplets all point in the same direction: packaging is shifting from a cost center to a performance center. Applied Materials' opportunity comes from selling materials engineering and defect inspection into more complex packaging flows. If advanced packaging continues to move from small-base high growth into multiyear capex, Applied Materials' business boundary will be redefined.
This line also shows that Applied Materials' rerating should not be driven only by memory prices. Memory prices provide the motivation to expand capacity. Advanced packaging provides process density. Together, they shift equipment demand from "buying more capacity" to "buying more complex capability." If advanced packaging continues to become more front-end-like, Applied Materials' revenue quality will look more like a manufacturing platform rather than beta to memory prices.
From the perspective of the "global memory bottleneck," Applied Materials' key variable is delivery cadence. Memory makers' willingness to expand does not mean equipment arrives immediately. Cleanrooms, supply chains, installation, debugging, and yield ramp all take time. UBS noted that customers are providing equipment vendors with longer visibility, suggesting that the supply side is already scheduling production around multiyear projects. If Applied Materials can continue to gain share in this process, it can benefit from order visibility rather than just single-quarter pricing.
Goldman Sachs DRAM Deep Update: DDR5 Price Increases, 2027 HBM Repricing, and Samsung's KRW 2,450T Investment
Taken together, these prior judgments position Applied Materials as a key carrier through which the AI hardware cycle transmits from "chip demand" to "manufacturing capacity." GPUs and ASICs are the demand side. HBM and DRAM are the capacity constraint. Advanced packaging is the interconnect constraint. WFE is the manufacturing constraint. Applied Materials sells the materials engineering capability that resolves the manufacturing constraint. As long as AI hardware expansion continues to transmit from chip design to wafer manufacturing and packaging, Applied Materials' rerating has a foundation.
10. The Real Investment Judgment: Whether Applied Materials Is Worth Chasing Depends on Four Verification Points
Applied Materials is not a cheap stock now, nor is it a pure cycle-bottom stock. It is more like a repricing asset that is migrating from traditional equipment beta toward an AI manufacturing platform. The most dangerous part of this phase is that the story is smooth and the data are also being revised upward, but valuation has already moved ahead. The investment judgment cannot stop at "the industry is strong." It must land on four verification points: whether DRAM WFE continues to be revised up, whether advanced packaging moves from concept revenue to platform revenue, whether Semi Systems gross margin holds, and whether AGS proves the value of services.
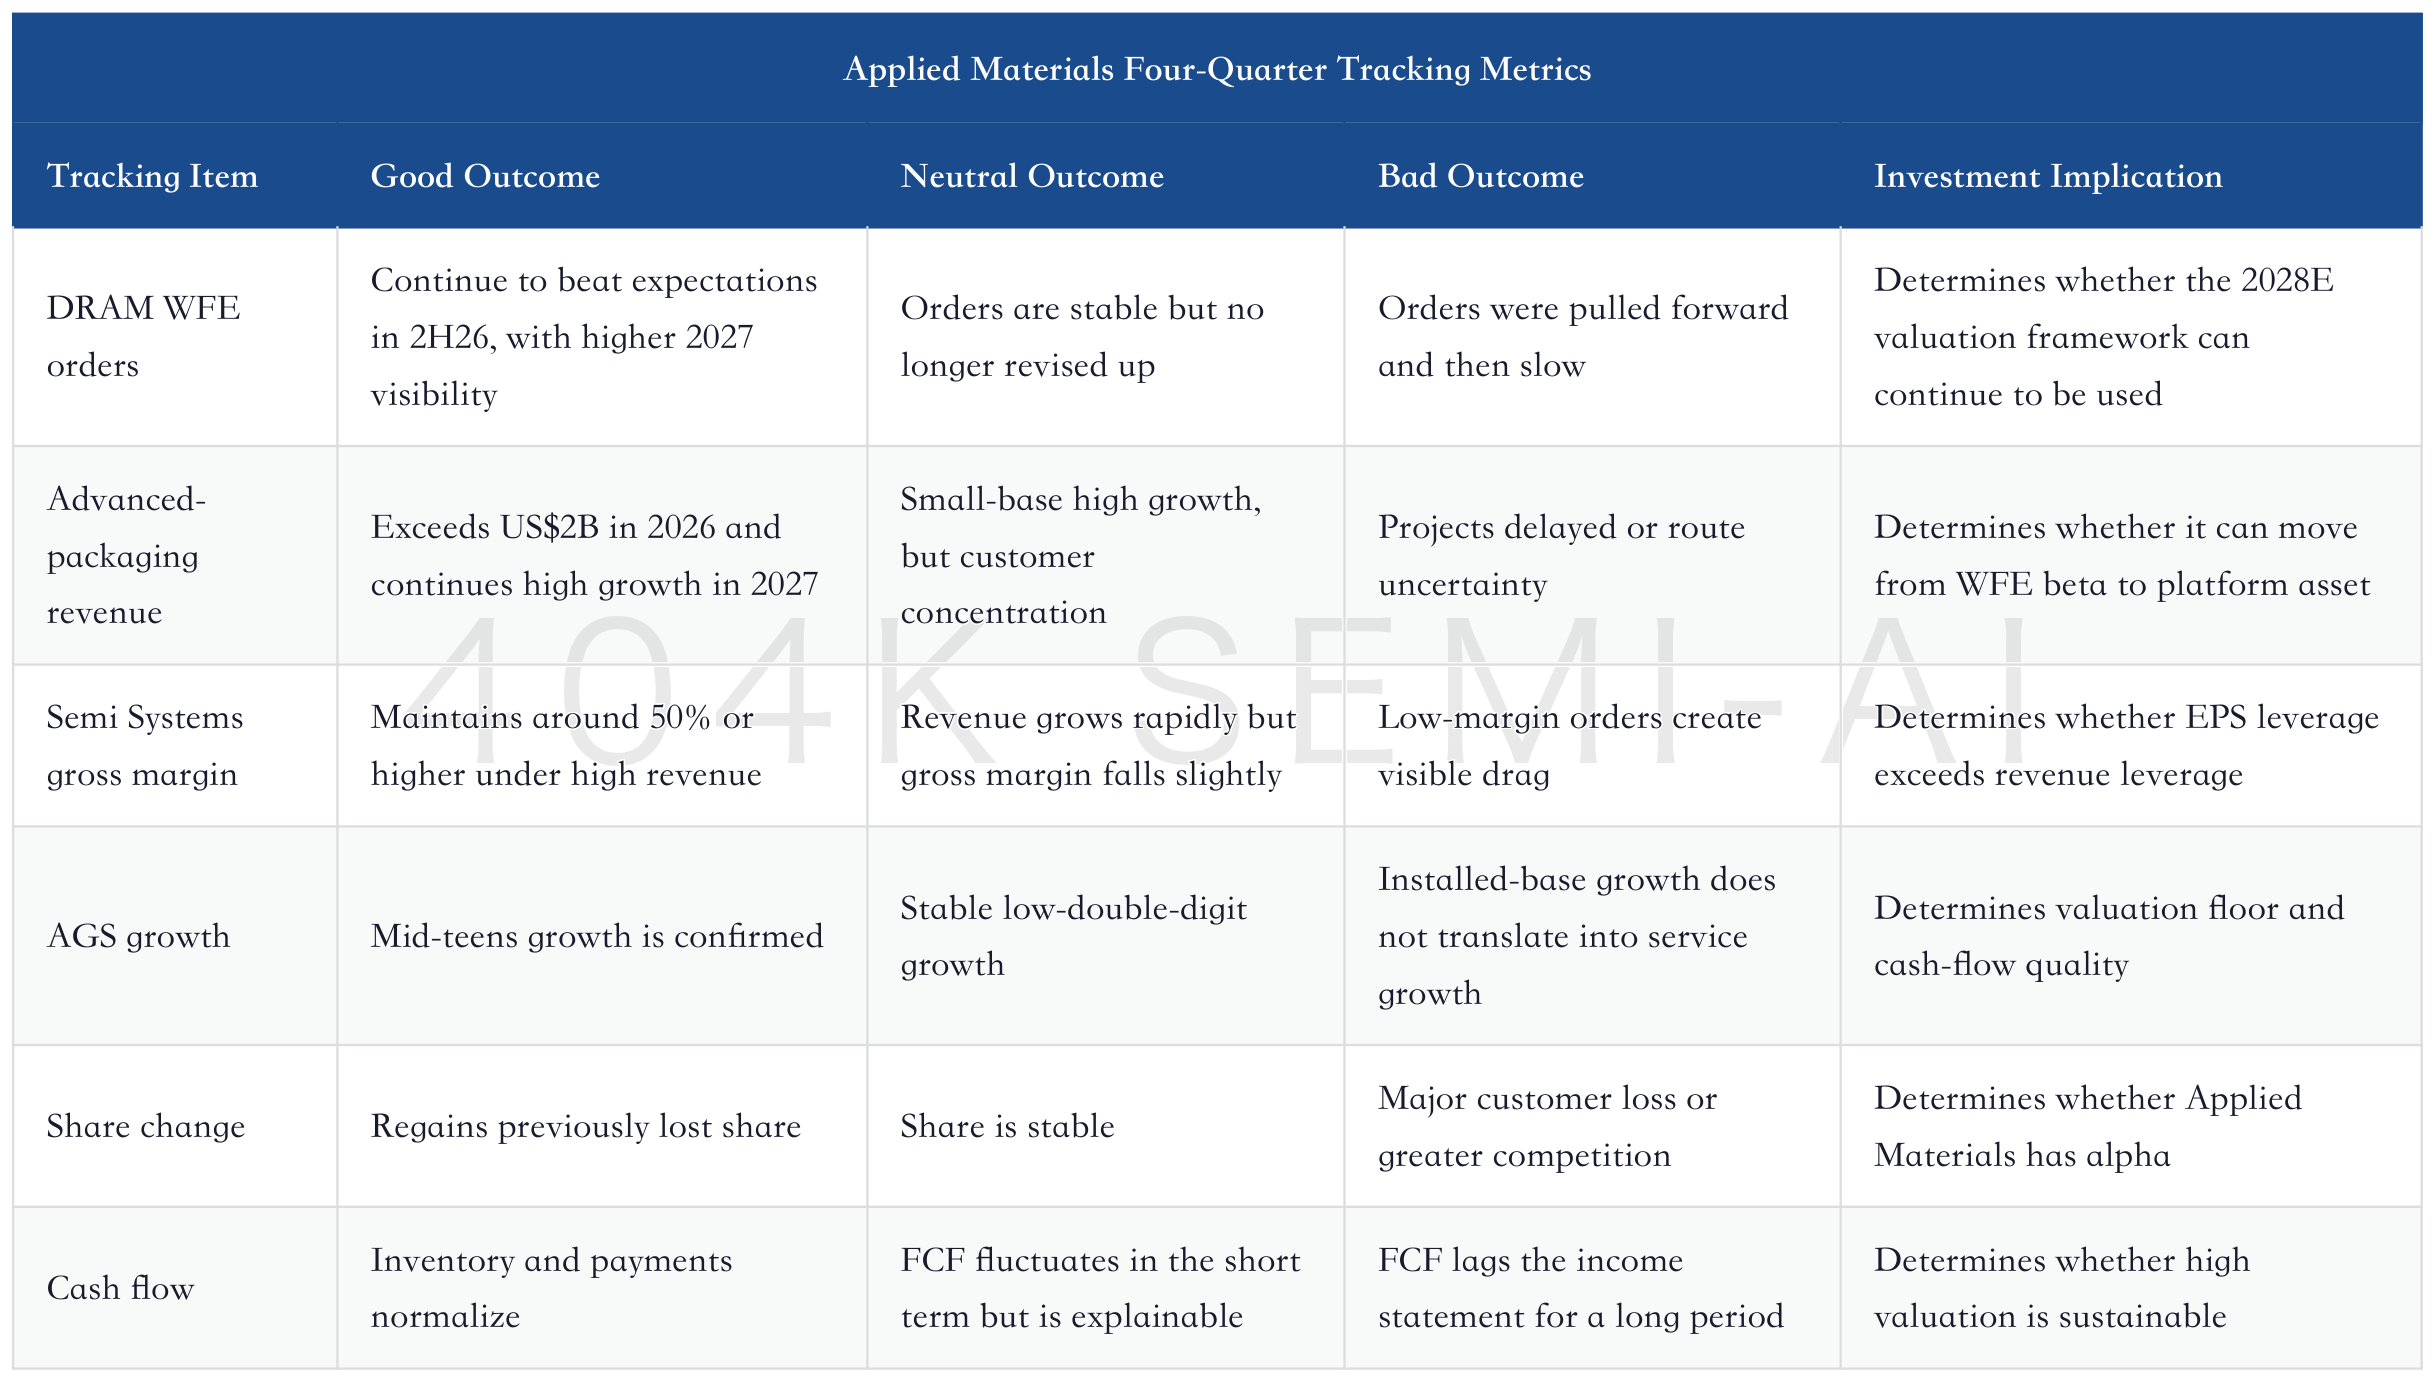
If these four verification points proceed smoothly, Applied Materials' upside comes from the market gradually believing 2028 EPS. Under UBS's path, 2028E EPS approaches US$28. Under Jefferies' base case, 2028E EPS is about US$21. Under Morgan Stanley's base case, 2028E EPS is about US$20. Even if the multiple does not expand further, as long as EPS moves from US$17 toward the US$25 range, the stock still has upside. The real risk is that EPS stops being revised up while the market has already assigned a high 2028 multiple.
From a portfolio construction perspective, Applied Materials belongs more in an "AI manufacturing capex" basket than as a single memory-price trade. If investors want to bet on NAND recovery, LAM may offer more direct leverage. If they want to bet on process control and yield, KLA has higher quality. If they want to bet on the combined expansion of AI wafer manufacturing from advanced logic and DRAM to advanced packaging, Applied Materials is the more balanced choice. The benefit of balance is that multiple lines provide support; the drawback is that every line needs verification.
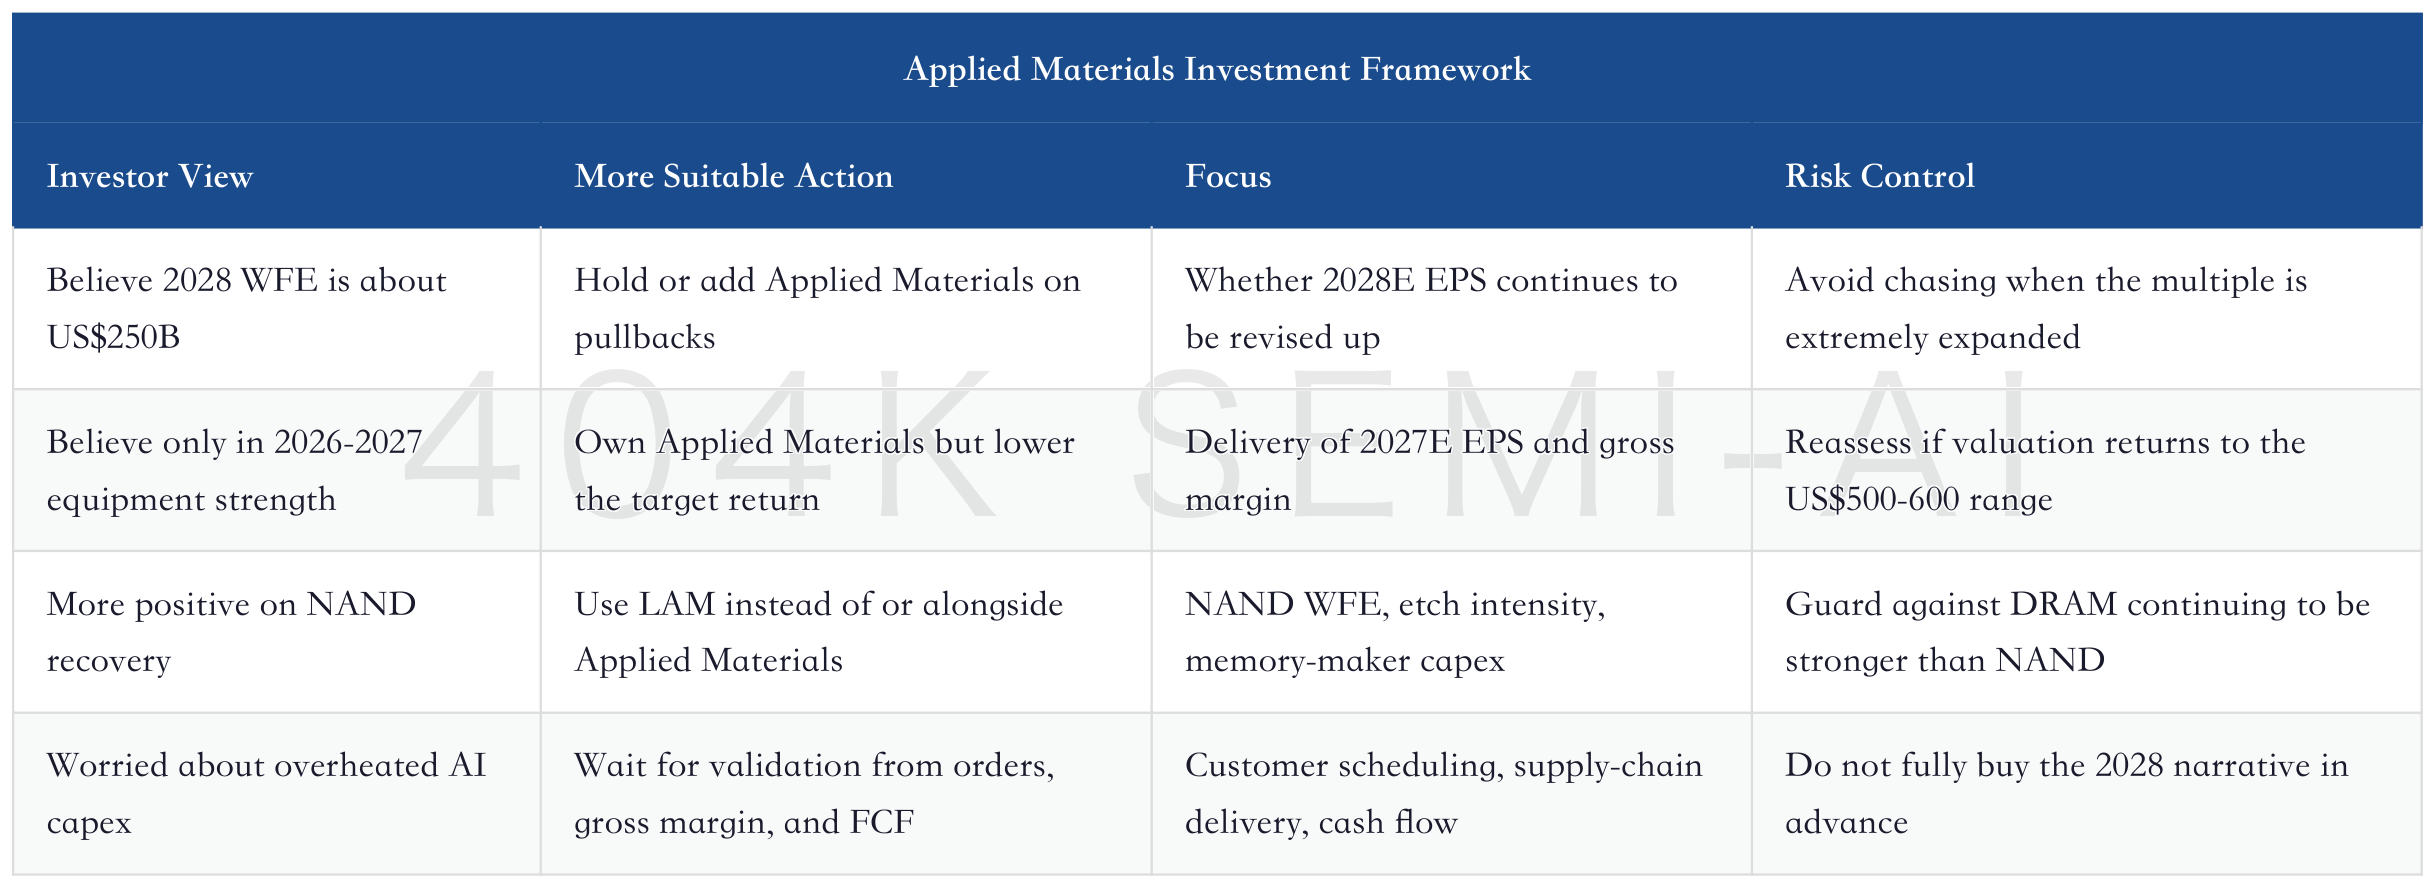
My judgment is that this rerating of Applied Materials has enough industrial foundation, but it should not be bought through linear extrapolation. The best holding window is the transition from "2026 earnings beat expectations" to "2027-2028 WFE visibility continues to improve." The most dangerous window is when target-price upgrades and stock-price appreciation have already discounted 2028 EPS, while the next earnings report only proves that 2026 is very strong. For Applied Materials to move from the US$500 level to above US$700, it must prove its AI manufacturing bottleneck platform attributes over several consecutive quarters, not merely deliver cyclical beta.
11. Three Worldviews: Is Applied Materials Worth US$500, US$700, or a Return to Cyclical Valuation?
The debate around Applied Materials now appears to be about target prices, but at its core it is a contest among three worldviews. The first views the company as a strong cyclical recovery stock, arguing that 2026-2027 WFE is very strong but that 2028 should not be discounted too early. The second views it as an AI manufacturing platform stock, arguing that WFE has already entered a supercycle visible into 2028, with DRAM, advanced packaging, and AGS permanently raising the EPS midpoint. The third argues that the market is linearly extrapolating AI capex and memory shortages, that the share price has already absorbed 2028 in advance, and that if orders are not revised up further, valuation will be hit first.
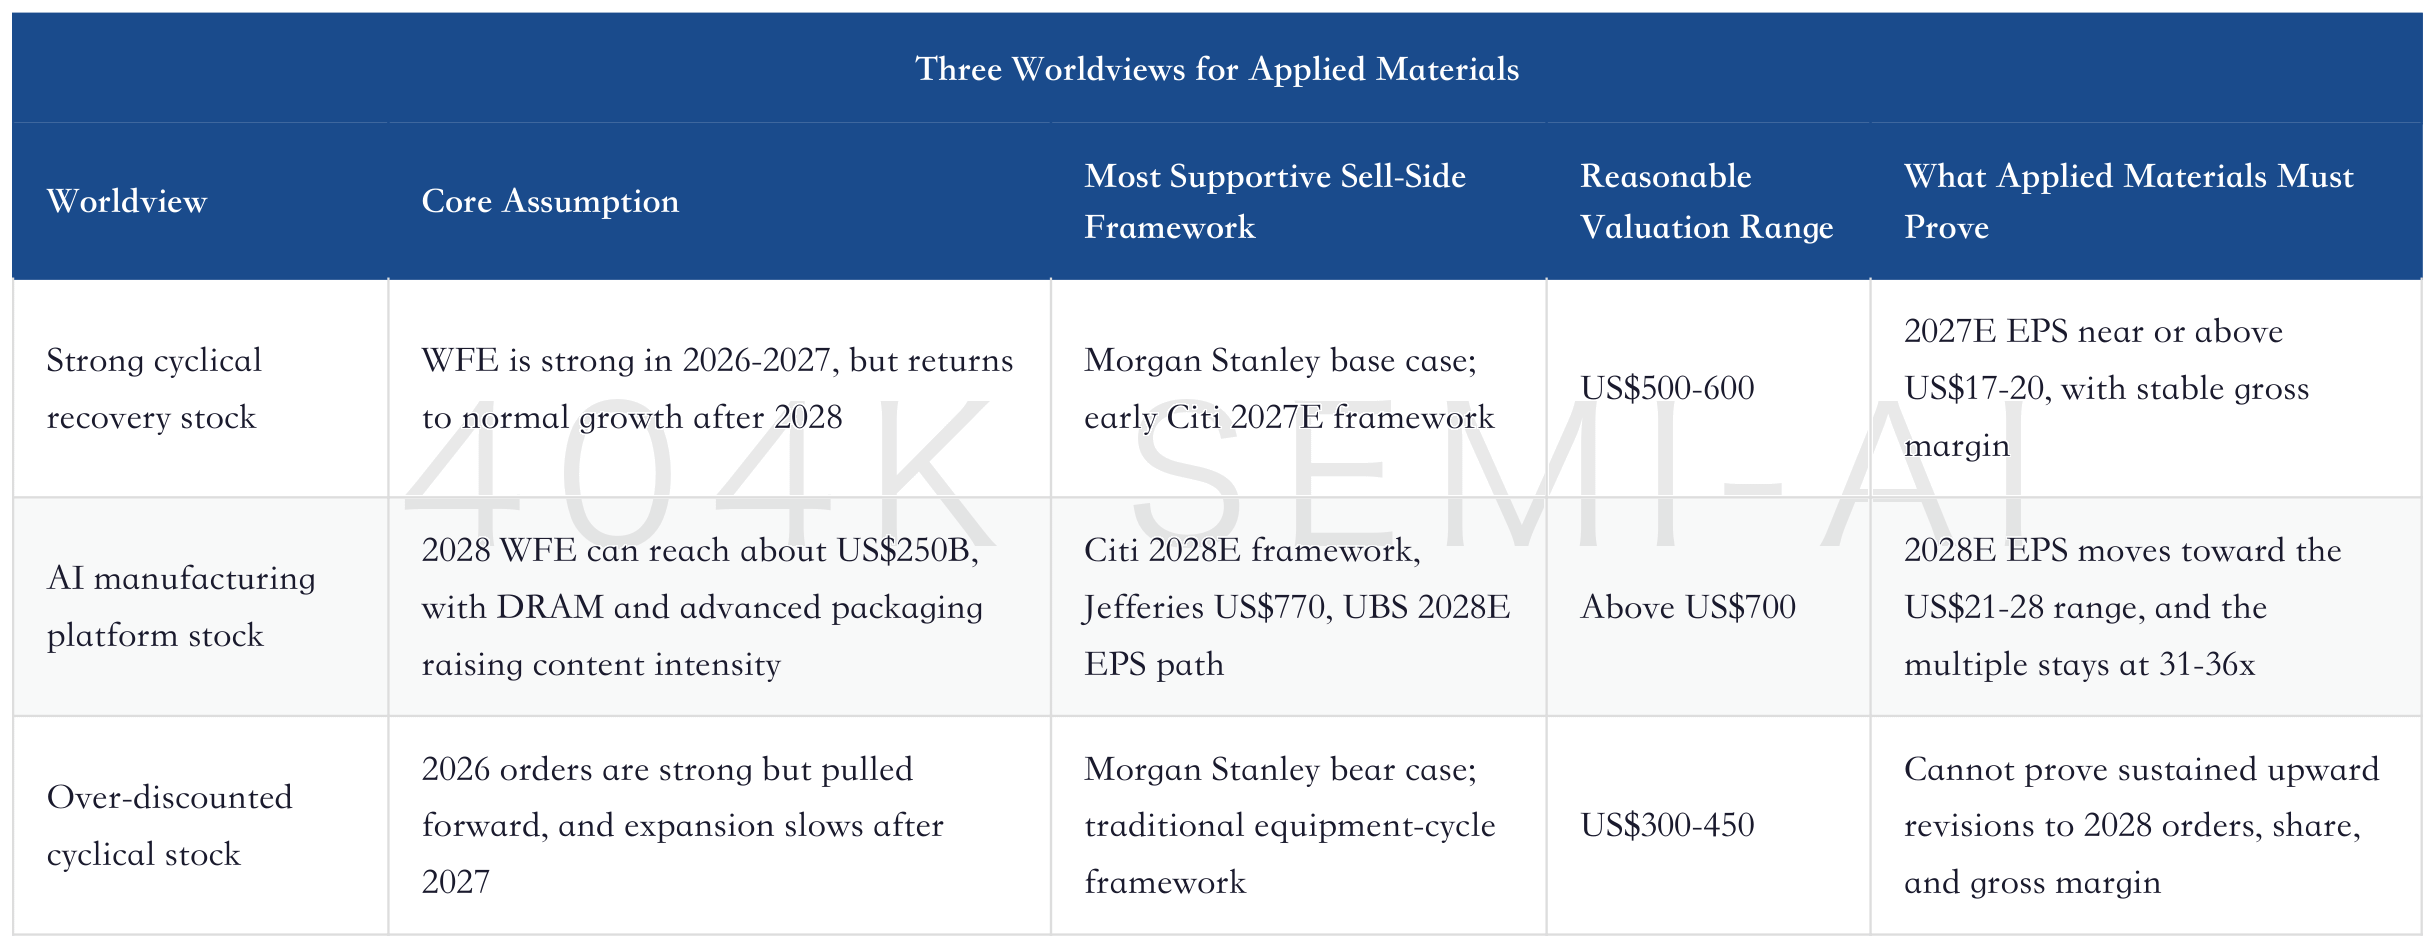
The first worldview is the steadiest and closest to traditional equipment-stock pricing. It acknowledges WFE upward revisions from AI and Applied Materials' advantages in DRAM and advanced logic, but it is unwilling to buy 2028 earnings too early. Under this framework, Applied Materials' reasonable anchor is 2027E EPS. As long as 2027 EPS can reach US$17-20, applying 26-30x can justify US$500-600. But moving beyond that range requires stronger evidence.
The second worldview has the most imagination, and it is what bulls most want to prove today. It shifts Applied Materials' valuation from "2027 equipment strength" to "insufficient AI manufacturing capacity in 2028." In this world, US$250B of WFE corresponds to a manufacturing capex midpoint supported jointly by cloud capex, advanced logic expansion, DRAM supply-demand mismatch, NAND capacity replenishment, advanced packaging, and service revenue. Applied Materials raises unit revenue quality through DRAM content intensity, packaging platforms, and AGS while also benefiting from total growth.
The third worldview is the one most worth watching because it does not require the industry to weaken; it only requires growth to fall short of what the market has already discounted. The stock is most vulnerable in a scenario where the company keeps growing but does not keep raising the 2028 path. High-cycle stocks often correct this way: revenue does not collapse, EPS does not collapse, but the market realizes it assigned too distant an earnings year and too high a multiple, so it compresses valuation first.
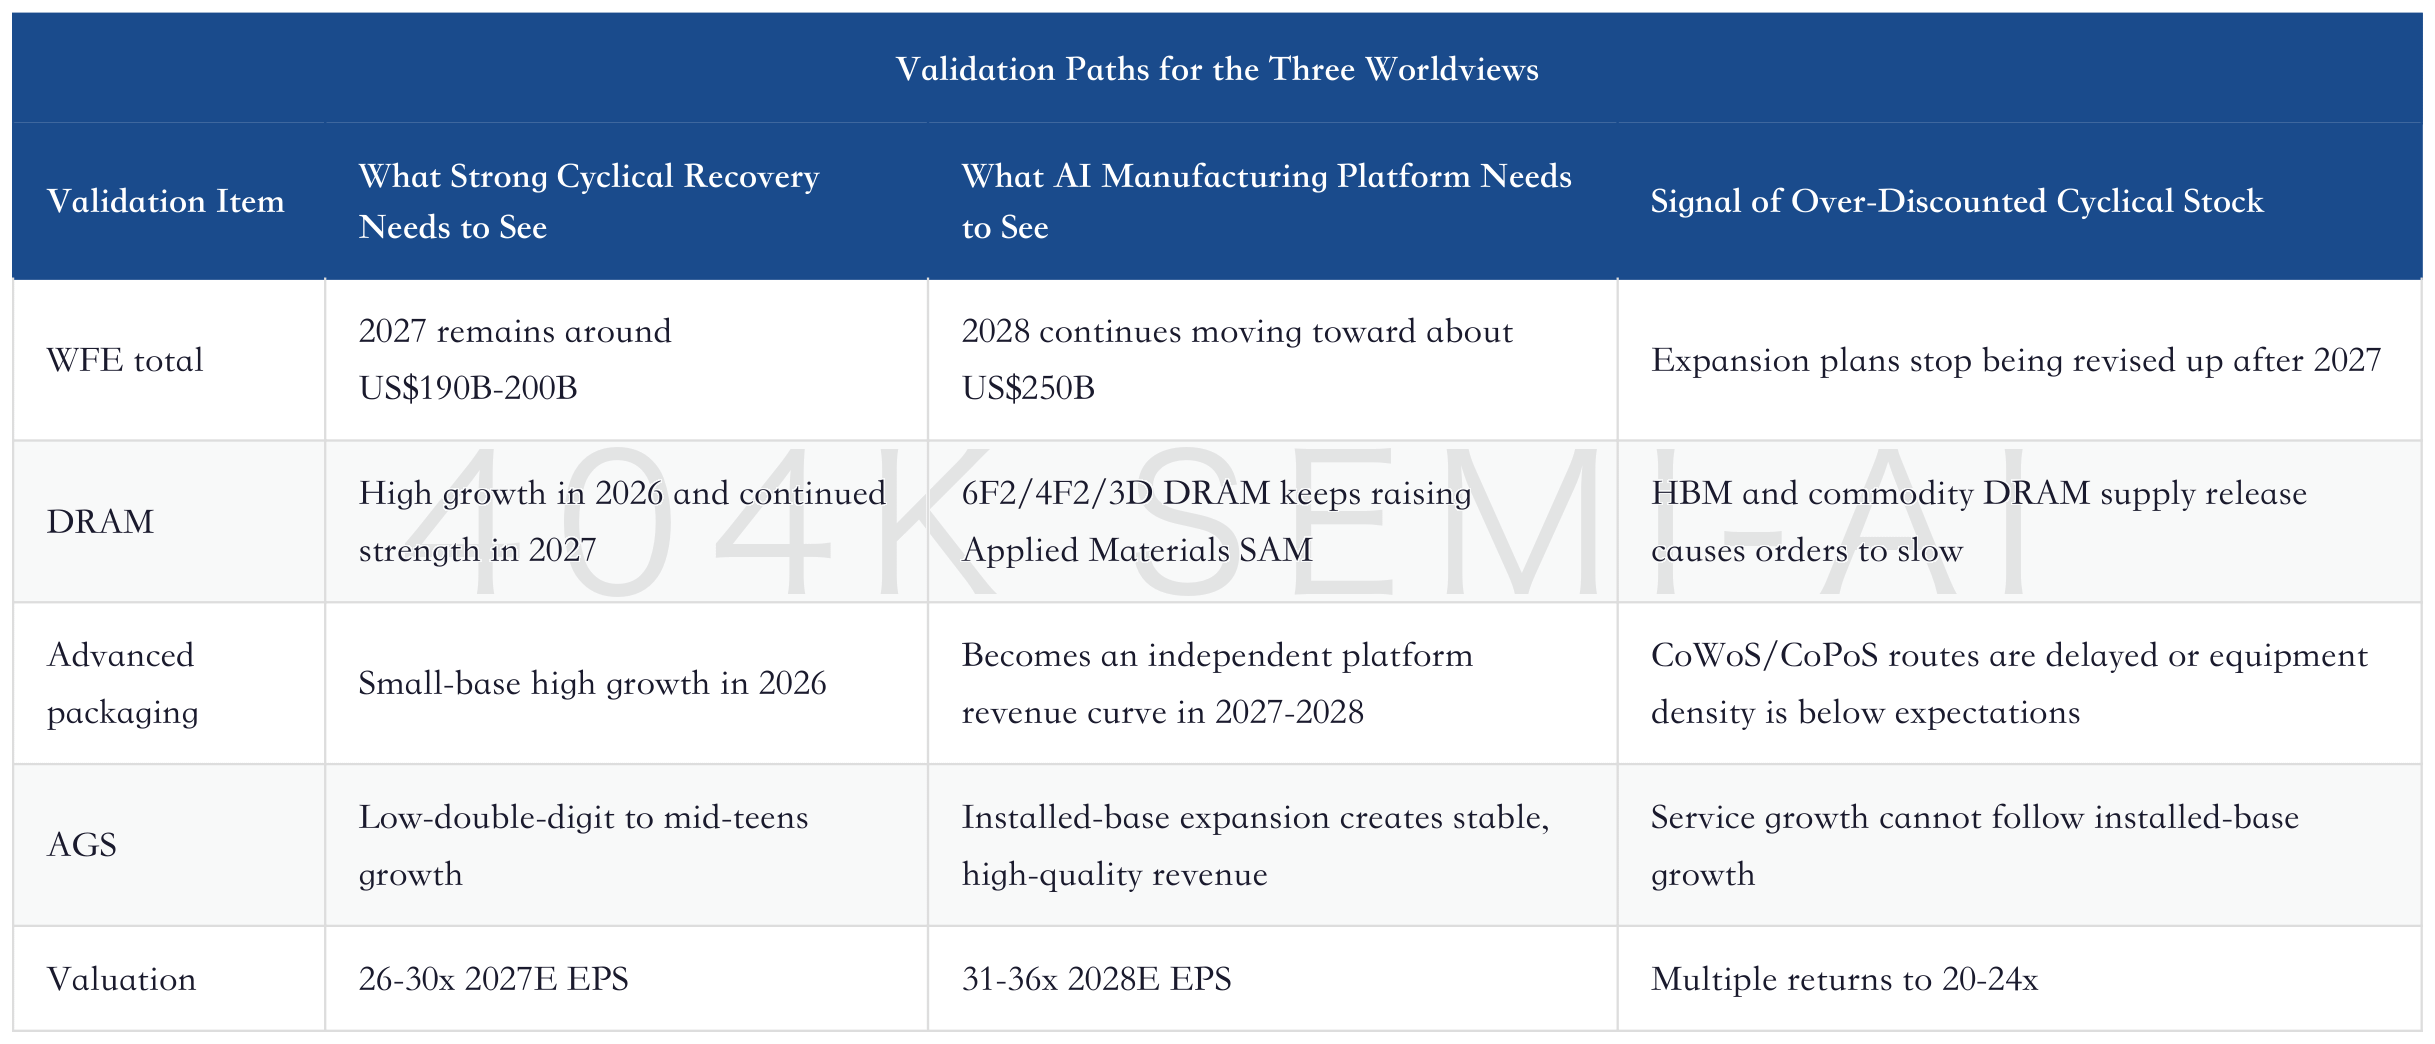
I am more inclined to place Applied Materials between the first and second worldviews: it is already more than an ordinary cyclical recovery, but it has not yet fully proven it can unconditionally enjoy a 2028 platform-stock valuation. Pushing it directly back into traditional equipment-stock valuation underestimates the structural changes in DRAM and advanced packaging. Treating it directly as an already-delivered AI manufacturing platform ignores the valuation risk after target prices have been raised sharply. A more reasonable approach is to treat US$500-600 as a midpoint already supported by 2027 strength and share recovery, and above US$700 as upside optionality that needs continuous validation.
This is also the difference between Applied Materials and memory stocks. Memory-stock earnings leverage comes more directly from prices, and price increases quickly transmit to profits. Applied Materials' earnings leverage comes from customer capex; the transmission is slower but visibility is longer. When memory prices surge in the short term, equipment stocks may not be the strongest at the same time. But when the market starts to believe that memory supply shortages will take 6-8 quarters or longer to resolve, equipment stocks look more like "pick-and-shovel suppliers for supply repair." The valuation key for Applied Materials is convincing the market that this transmission chain is long enough.
In terms of trading cadence, Applied Materials' best confirmation point usually appears when the industry begins to distinguish between "price leverage" and "equipment content leverage." If DRAM and HBM remain tight, memory-maker expansion plans are extended, and Applied Materials' orders and gross margin rise together, the market will be willing to push the target-price framework from 2027 to 2028. If memory prices rise but equipment orders are not revised up further, Applied Materials can easily underperform purer memory stocks. Buying Applied Materials is buying "the capex consequences of scarcity," not "scarcity itself."
12. Risks and Disconfirmation: Where Growth Lands Determines Applied Materials' Valuation Resilience
Applied Materials' biggest risk is that WFE growth lands elsewhere, or lands in lower-quality revenue. Given current AI capex, memory tightness, and advanced packaging demand, the equipment industry is likely still growing. What really affects valuation is the allocation of that growth. If NAND recovers faster than DRAM, LAM benefits more. If process-control intensity rises but Applied Materials' eBeam and metrology share does not expand meaningfully, KLA benefits more. If regional mature-node orders rebound but gross margin and sustainability are low, Applied Materials gets the revenue but not the multiple.
The risks can be compressed into seven watchpoints. Weaker-than-expected DRAM expansion would directly lower 2028E EPS through order cuts and insufficient HBM spillover. A stronger NAND recovery would give LAM more marginal leverage than Applied Materials. Weaker-than-expected advanced packaging would undermine the platform narrative. China restrictions would affect both equipment shipments and service revenue. Share loss at major customers would push Applied Materials from an alpha asset back to equipment beta. Cash flow lagging the income statement for a long period would compress a high multiple. A reversal after overheated AI capex would disconfirm the WFE supercycle at the root.
The risk that needs the most attention is "growth landing elsewhere." Morgan Stanley's cautious view already provides a path: if NAND recovery becomes the marginal main line in 2027, LAM may have more leverage than Applied Materials. If Applied Materials' DRAM advantage is already reflected in the stock price, the risk-reward of continuing to buy Applied Materials declines. Bulls cannot refute this simply by saying WFE is large. They need to prove that Applied Materials has excess growth in DRAM, advanced logic, packaging, and services.
The second risk is moving the valuation year out too early. Valuing the stock on 2028 EPS is not a problem in itself, provided customer orders, supply-chain delivery, and capacity construction offer enough visibility. If future earnings only show strong 2026 orders without visible 2027-2028 scheduling, the market will pull the valuation anchor back to 2027. Once the anchor retreats, the stock can correct first even if fundamentals have not collapsed.
The third risk is political and regional revenue. Applied Materials still has revenue exposure to China, and equipment export and service restrictions can affect some product lines and customer deliveries. This risk may not change the long-term AI manufacturing logic, but it affects revenue quality, gross margin, and the multiple the market is willing to pay. From an investment perspective, investors should avoid treating regional revenue as sustainable high-multiple revenue.
13. Conclusion: Applied Materials Is an Integrated Platform for AI Manufacturing Expansion, but the Next Leg Requires Delivery, Not Storytelling
The most worthwhile point in this Applied Materials rerating is that it connects several seemingly separate AI hardware clues. GPU and ASIC expansion raises advanced logic WFE. HBM and DDR5 raise DRAM WFE. Inference and storage tiers raise NAND and SSD demand. Advanced packaging turns chip interconnect into a performance bottleneck. Ultimately, all of these demands return to deposition, etch, interconnect, metrology, inspection, packaging, and services. Applied Materials does not own the end chips and does not directly enjoy memory price increases, but it sells the materials engineering capability that AI manufacturing expansion cannot bypass.
This is the core logic of Applied Materials' migration from cyclical stock to bottleneck asset. It does not mean there is no cycle, that valuation can rise without limit, or that every quarter will beat expectations. Its opportunity is that AI hardware expansion pushes wafer manufacturing and packaging complexity to a new level, creating upside for Applied Materials' unit-capacity value, service revenue, and longer-term EPS. As long as the WFE supercycle extends from 2026 to 2028, Applied Materials is not an equipment stock that can only be analyzed by near-term orders.
Execution requires more restraint. The market has already rediscovered Applied Materials' good-company attributes. What remains to earn is the "delivery gap," not the "discovery gap." If the next 2-3 quarters continue to validate orders, gross margin, AGS, and advanced-packaging revenue together, valuation can move from 2027 toward 2028. If only orders are strong while gross margin and service revenue do not keep up, the stock can only be paid like a cyclical. This difference determines whether Applied Materials remains in the US$500-600 equipment-strength midpoint or opens the platform space above US$700. When tracking the stock, investors should not look only at sell-side target prices. Each target-price increase should be decomposed back into four variables: WFE, share, gross margin, and EPS, and then checked against what earnings actually confirm.
The final judgment can be compressed into one sentence: what is most valuable about Applied Materials today is the possibility that it becomes the broadest materials engineering platform in the AI manufacturing supercycle. Bulls need to keep seeing DRAM WFE, advanced packaging, AGS, and gross margin deliver together. Bears need to prove that these growth drivers are merely pull-forward demand, or that incremental WFE mainly lands with LAM, KLA, and other equipment links. The focus of the next earnings report is whether Applied Materials can continue making the 2028 earnings path more credible, more verifiable, and easier to track.
If this stock is placed in a portfolio, its more reasonable role is the "core observation anchor for AI manufacturing capex," not a substitute for high-beta memory stocks. It can simultaneously test cloud capex, memory supply shortages, advanced logic expansion, and packaging complexity. If Applied Materials delivers several consecutive quarters of resonance across orders, gross margin, services, and advanced packaging, it will show that the AI hardware cycle has truly transmitted from chip design into manufacturing. If only target prices rise while operating data cannot keep up, the position should be managed as a cyclical stock rather than a platform stock.Applied Materials Deep Dive: How the WFE Supercycle, DRAM Expansion, and Advanced Packaging Reprice the Profit Slope
目录
TL;DR
1. This Rerating Bets on AI Manufacturing Bottlenecks and a Multiyear Equipment Curve
2. WFE Total Upward Revisions: From US$145B to US$250B, the Equipment Cycle Is Being Extended by AI Capex
3. DRAM Is Applied Materials’ First Ticket: 6F2, 4F2, and 3D DRAM Raise Unit-Capacity Value
4. Advanced Packaging Is the Second Ticket: Applied Materials Sells Back-End Process Density, Not Just the CoWoS Concept
5. AGS Service Revenue Improves Earnings Quality: Not the Flashiest Story, but Potentially the EPS Stabilizer
6. Peer Ranking: Applied Materials, LAM, and KLA Are Different AI Manufacturing Bottlenecks
7. Valuation Debate: Behind US$520, US$570, US$710, and US$770 Is a Tug-of-War Between 2027E and 2028E
8. Company Model: Applied Materials’ Profit Slope Comes From Revenue, Gross Margin, and Services Rising Together
9. How Prior Work Connects: Applied Materials Is the Intersection of the “Memory Tax” and the “WFE Supercycle”
10. The Real Investment Judgment: Whether Applied Materials Is Worth Chasing Depends on Four Verification Points
11. Three Worldviews: Is Applied Materials Worth US$500, US$700, or a Return to Cyclical Valuation?
12. Risks and Disconfirmation: Where Growth Lands Determines Applied Materials’ Valuation Resilience
13. Conclusion: Applied Materials Is an Integrated Platform for AI Manufacturing Expansion, but the Next Leg Requires Delivery, Not Storytelling
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Applied Materials is shifting from a traditional semiconductor equipment cyclical into a horizontal pick-and-shovel supplier for AI manufacturing bottlenecks. This rerating puts the WFE total, DRAM, advanced packaging, GAA, backside power delivery, and service revenue on the same profit slope. The key risk is whether orders, gross margin, and service revenue can continue to keep up after the market has pulled 2028 earnings into today’s valuation.
TL;DR
Applied Materials is changing its asset profile. The market used to treat it as an equipment cyclical that moved with WFE. It now needs to be reconsidered as a materials engineering platform for AI wafers, AI memory, and advanced packaging expansion. The frameworks from Citi, UBS, and Jefferies all point to a continued rise in the 2027-2028 WFE midpoint. The only real difference is whether valuation should first anchor on 2027E EPS and a US$500-level stock, or move directly to 2028E EPS and a level above US$700.
WFE visibility is moving further out. 2027-2028 visibility is being extended simultaneously by customer orders, cleanroom capacity, and memory supply shortages, and the market is starting to price a multiyear fab delivery curve. Citi’s bull-case framework puts WFE at about US$145B/US$200B/US$250B in 2026/2027/2028, while UBS also estimates 2028 WFE at about US$247.5B. This means Applied Materials’ revenue ceiling is shifting from “single-year equipment orders” to a “multiyear fab delivery curve.”
DRAM is the core ticket. Applied Materials benefits more from a DRAM upcycle than pure logic-equipment names because DRAM’s transition from 6F2 to 4F2 and then to 3D DRAM should keep lifting the content intensity of deposition, etch, interconnect, metrology, and defect inspection. Jefferies estimates that Applied Materials’ SAM per 100k wspm of DRAM can rise from about US$6.0B at 6F2 to about US$6.5B at 4F2, and then to about US$7.5B in the 3D DRAM phase.
Advanced packaging raises the quality of growth. The focus is on a process portfolio spanning wafer-level packaging, hybrid bonding, interconnect, plating, panel-level interposers, and eBeam inspection, not just the single CoWoS route. Jefferies expects Applied Materials’ advanced-packaging-related business to exceed US$2B in 2026 and keep growing at more than 50%. If CoPoS and panel-level interposers scale, Applied Materials has a chance to capture higher equipment density in back-end expansion.
The bear case is a structural rotation. Morgan Stanley downgraded Applied Materials from overweight to equal-weight in May 2026. The core argument was that the 2027 NAND recovery is more favorable for LAM, while Applied Materials’ DRAM advantage has already been priced in. This debate means the next leg for Applied Materials depends on the delivery of four numbers: DRAM orders, Semi Systems gross margin, AGS growth, and whether WFE share continues to recover.
The valuation debate comes from moving the earnings year out. The argument has already moved from “can it get near US$500” to “can the market discount 2028 earnings in advance.” The question is whether investors are willing to believe Applied Materials’ 2028E EPS can approach or exceed US$20 while maintaining AI-equipment valuation multiples.
The disconfirmation path is already clear. If DRAM WFE expansion is only one round of restocking, advanced-packaging revenue cannot exceed the high-growth path laid out by the company, Semi Systems gross margin falls back to old-cycle levels, or China restrictions and share losses at major customers push orders down again, Applied Materials will revert from an “AI manufacturing bottleneck asset” to traditional equipment beta. In that case, valuation would compress first, and earnings delivery would be revised down afterward.
1. This Rerating Bets on AI Manufacturing Bottlenecks and a Multiyear Equipment Curve
Applied Materials used to be easy to simplify as “WFE beta.” What has really changed behind the 2026 sell-side upgrades is the label the market is willing to attach to the company. In the traditional framework, semiconductor equipment valuations followed fab capex, memory pricing, and China equipment demand. In the new framework, Applied Materials is placed upstream in the AI compute supply chain bottleneck, and earnings leverage depends on whether AI chips, HBM, DRAM, NAND, advanced packaging, and service revenue can all raise equipment content intensity at the same time.
This is also why several recent Applied Materials reports read less like ordinary earnings notes. Citi first raised its target price to US$520 in May, based on a 2026/2027 WFE bull-case framework derived from its capex model. After earnings, UBS wrote Applied Materials’ 2028 EPS path toward nearly US$27. In its June DRAM and advanced packaging masterclass, Jefferies further decomposed Applied Materials’ long-term SAM into DRAM unit capacity, advanced packaging platforms, and eBeam inspection. By mid-June, Citi directly pushed its WFE bull-case framework to about US$250B in 2028 and rolled Applied Materials’ target price to US$710. The valuation year has moved out, which shows the market is no longer satisfied with asking whether 2026 earnings are high. It has started to price the equipment supply gap in 2028.
The WFE Supercycle Is Just Beginning: How AI Capex Pushes Semiconductor Equipment Toward US$250B
Applied Materials’ business is, at its core, materials engineering. It combines thin-film deposition, etch, ion implantation, CMP, thermal processing, metrology, inspection, and packaging processes into production pathways. The larger AI chips become, the more complex process nodes become, and the denser memory hierarchies become, the more fabs need to refine how materials are deposited, etched, connected, and inspected for defects. In the old cycle, the value of materials engineering was easily viewed as equipment share. In the new cycle, it looks more like a gatekeeper for AI manufacturing: the players that can make more complex structures reliably capture more unit WFE content.
The Applied Materials narrative can be divided into three layers. The first is the total, with WFE moving out of the 2024-2025 normalization phase and back into an expansion cycle driven by AI capex and memory supply shortages. The second is structure, with DRAM, HBM, NAND, GAA, backside power delivery, and advanced packaging growing faster than traditional mature nodes. These areas happen to skew toward Applied Materials’ deposition, etch, interconnect, and packaging capabilities. The third is quality, with AGS service revenue, subscription-style maintenance, spare parts, and process support making earnings less dependent on new equipment shipments alone while improving gross margin and cash-flow stability. The combination of total growth, structural mix, and quality is what constitutes the migration in asset profile.
Understanding this framework makes it easier to see why the same group of reports is not fully aligned on Applied Materials, yet all acknowledge that the WFE cycle is getting larger. Bulls see incremental upside from DRAM, advanced packaging, and services. The more cautious camp sees more leverage for LAM in a NAND recovery and believes Applied Materials’ DRAM advantage has already been traded by the market. The real debate is how much share Applied Materials can capture in the supercycle, and what multiple should be used to discount it.
2. WFE Total Upward Revisions: From US$145B to US$250B, the Equipment Cycle Is Being Extended by AI Capex
Applied Materials’ first main line is the WFE total. Citi, UBS, and Morgan Stanley do not use exactly the same forecasting basis, but the direction is highly consistent: 2026 is not the endpoint; 2027-2028 is the core of market repricing. Citi and UBS push the bull-case framework further out, while Morgan Stanley, although more cautious, also acknowledges that the WFE midpoint has moved higher. The specific dollar differences are clearer in table form.
The most important number in this table is 2028. If we look only at 2026, Applied Materials is already trading on a high base. If we look at 2027, the market will debate whether DRAM or NAND is more advantaged. If we look at 2028, the question becomes whether AI compute expansion requires a longer semiconductor manufacturing capex curve. Citi’s move to US$250B of WFE effectively changes Applied Materials’ valuation anchor from “next-year profit” to “how far AI data centers need to expand wafer manufacturing.”
Equipment Capex Ledger Update: AI Financing, US$250B WFE, and Semiconductor Equipment Repricing
WFE upward revisions come from multiple lines moving higher at the same time. Advanced logic needs to expand because GPUs, ASICs, CPUs, and networking chips are all competing for advanced nodes. DRAM needs to expand because HBM, DDR5, and server memory are pushing bit demand onto a steeper slope. NAND needs to expand because AI storage tiers, KV cache offloading, enterprise SSDs, and inference data flows consume more high-performance capacity. Advanced packaging needs to expand because compute chips increasingly rely on 2.5D, 3D, hybrid bonding, and interposers. In the past, these projects might have been treated as different cycles. Now they all point to the expansion of AI manufacturing infrastructure.
Applied Materials benefits most because incremental WFE dollars skew toward its strengths. Citi says Applied Materials is exposed over the next 2-3 years to GAA, advanced packaging, and ICAPS. UBS says Applied Materials is the biggest DRAM WFE supercycle beneficiary among US process-equipment companies. Jefferies says DRAM and advanced packaging will outgrow overall WFE. Behind the different wording is the same judgment: the marginal dollars in the new WFE cycle are more concentrated in equipment steps with more process steps, more complex materials stacks, and denser interconnect and inspection.
This transmission chain explains why Applied Materials’ guidance is treated by the market as cycle confirmation. The April-quarter results and July-quarter guidance both show revenue, EPS, and gross margin avoiding a “volume growth with deteriorating earnings quality” combination. More importantly, the company raised its 2026 Semi Systems shipment growth target, leading the sell side to infer that Applied Materials is moving from following WFE upward to regaining share.
One easily overlooked detail is that Applied Materials’ gross margin has remained around 50% even as revenue has been revised sharply higher. In traditional equipment cycles, revenue growth does not necessarily bring gross-margin expansion because supply chain, product mix, installation cadence, and regional structure can all weigh on profitability. But UBS and Evercore have repeatedly emphasized Applied Materials’ gross-margin performance this time, suggesting that new platforms, advanced processes, and service revenue are offsetting part of the cost of scaling. If Semi Systems gross margin remains elevated, EPS revisions will move faster than revenue revisions.
3. DRAM Is Applied Materials’ First Ticket: 6F2, 4F2, and 3D DRAM Raise Unit-Capacity Value
Applied Materials’ first ticket is DRAM. Investors used to treat DRAM and NAND as a single “memory cycle” when looking at memory equipment. After 2026, that view is not precise enough. DRAM is becoming the main battlefield for equipment growth because of demand from HBM, DDR5, server memory, and AI inference memory. NAND also has upside leverage, but the allocation across equipment vendors is different. Applied Materials’ advantage is in DRAM and advanced logic, LAM’s advantage is more skewed toward NAND and etch, while KLA benefits from process control.
The Memory Tax Arrives: How AI Turns HBM, DRAM, and NAND Into a Global Macro Bottleneck
Jefferies’ DRAM and advanced packaging report provides a very clear incremental logic for Applied Materials: DRAM expansion brings both more wafer starts and more materials-engineering steps. The 6F2 stage needs more deposition and patterning. The 4F2 stage introduces denser structures. 3D DRAM further raises structural complexity. Applied Materials participates in capacitors, interconnect, peripheral logic, thin films, etch, metrology, and defect inspection, so equipment SAM per unit of monthly capacity expands.
The value of this table is not precision to the nearest US$100M. The value is direction: for every additional 100k monthly wafer capacity, the equipment basket Applied Materials can sell becomes larger. If DRAM is only restocking after a price increase, the market will assign a low multiple. If the DRAM process roadmap raises unit-capacity SAM, the market will assign a longer earnings duration.
UBS’s framework also supports this direction. In its June global WFE update, UBS argues that DRAM WFE will contribute more than 50% of total WFE growth in 2026 and more than two-thirds in 2027. This is an aggressive view, but it explains why UBS sees Applied Materials as the biggest DRAM WFE beneficiary among US equipment companies. A substantial portion of Applied Materials’ 2026 Semi Systems growth comes from DRAM. If DRAM continues to outgrow overall WFE in 2027, Applied Materials’ share recovery will not be a one-off rebound.
There is another important implication in the DRAM line: AI memory demand does not come only from HBM. HBM is the most visible high-end product, but AI servers, inference clusters, the return of CPUs, KV cache, DDR5 upgrades, and standard server capacity are all consuming DRAM. HBM needs more wafers to provide the same number of bits, while rising DDR5 prices stimulate general-purpose DRAM expansion. All of this ultimately returns to fab equipment demand. Because Applied Materials spans front-end and parts of packaging, it can benefit from both front-end expansion and rising back-end complexity.
The Second Engine of the Memory Supercycle: CPU Return, HBM Spillover, and a US$1.7T TAM Rerating
Conversely, DRAM is also Applied Materials’ largest disconfirmation point. If DRAM WFE after 2026 is merely pull-forward demand, if customer expansion slows in 2027, or if HBM and commodity DRAM supply are released faster than demand, Applied Materials’ share improvement will be viewed as a short-term benefit at the cyclical peak. Applied Materials bulls need to prove that the memory multiplier in AI servers is lifting DRAM equipment intensity to a new level.
4. Advanced Packaging Is the Second Ticket: Applied Materials Sells Back-End Process Density, Not Just the CoWoS Concept
Advanced packaging is Applied Materials’ second ticket. The market is most familiar with CoWoS, but Applied Materials’ opportunity does not come from a single packaging label. It comes from the front-end-like evolution of back-end processes. As chip area grows, die counts increase, and interconnect density rises, packaging is no longer just about sealing chips. It is rebuilding the interconnect architecture of the computing system. This shift brings deposition, etch, plating, metrology, eBeam inspection, and defect review into a larger back-end equipment market.
Jefferies expects Applied Materials’ advanced-packaging-related revenue to exceed US$2B in 2026 and maintain growth above 50%. This is not yet the largest component of Applied Materials’ total revenue, but its importance lies in growth rate and valuation narrative. Traditional semiconductor equipment is priced on front-end WFE. Advanced packaging gives Applied Materials an additional revenue curve based on “AI compute packaging density.” As long as GPUs, ASICs, HBM, and interposers continue to expand, Applied Materials’ back-end equipment basket will become larger.
The focus of this line is “process density.” The more complex advanced packaging becomes, the less it can be solved with traditional back-end equipment alone. AI chip packaging needs higher-precision thin films, interconnect, and inspection. HBM stacking needs more stable thermal management and yield control. If panel-level interposers work at scale, they could further enlarge packaging area and equipment value. Applied Materials’ advantage is that it can migrate front-end materials engineering capabilities to the back end.
From HBM to WFE: How AI Turns the Memory Cycle Into an Equipment Supercycle, and How Much Runway Remains for Semiconductor Equipment?
Advanced packaging also explains why Applied Materials is not just DRAM beta. DRAM expansion benefits Applied Materials, but packaging extends the opportunity from memory makers to foundries, IDMs, OSATs, and system-level chip companies. Different roadmaps at TSMC, Samsung, Intel, memory makers, and cloud companies all eventually require more complex interconnect and inspection. If Applied Materials can bundle process opportunities across CoWoS, hybrid bonding, panel-level interposers, and HBM base die, its valuation should not be based only on the DRAM cycle.
That said, advanced packaging also has clear uncertainty. The timing of CoPoS and panel-level interposer scaling, who controls the equipment route, and whether yield and cost can meet targets are not yet settled. From an investment perspective, it is not prudent to fully capitalize all long-dated optionality at once. A more balanced view is that advanced packaging first gives Applied Materials a high-growth, small-base curve. If it exceeds US$2B in 2026 and continues to grow rapidly in 2027, investors can gradually upgrade it from “concept revenue” to a “valuation pillar.”
5. AGS Service Revenue Improves Earnings Quality: Not the Flashiest Story, but Potentially the EPS Stabilizer
Applied Materials’ third line is AGS service revenue. It is not as easy to narrate as DRAM or advanced packaging, but it matters a lot for valuation quality. The biggest risk for equipment companies is order volatility. The value of service revenue is that it turns the installed base into steadier maintenance, spare parts, process support, and subscription revenue. If the WFE supercycle holds, it first brings new equipment revenue and then a larger installed base. AGS then becomes an EPS stabilizer.
After earnings, UBS noted that Applied Materials raised its long-term AGS growth target from low double digits to roughly the mid-teens. Evercore also emphasized that AGS could grow at high double digits in 2026. This may look like a small change, but it helps valuation: if Applied Materials’ revenue is only Semi Systems moving with WFE, the market assigns a cyclical multiple. If AGS share and growth rise at the same time, the market will be willing to treat part of revenue as higher quality.
Service revenue also has a hidden advantage: the more complex advanced processes become, the more customers rely on continuous support from equipment vendors. GAA, backside power delivery, 3D DRAM, advanced packaging, and eBeam inspection all require ongoing tuning, maintenance, and yield optimization. The deeper Applied Materials’ customer relationships become, the more AGS revenue looks like technical service rather than ordinary after-sales support. This is also why service revenue can help equipment companies move from “selling tools” to “selling process capability.”
Of course, AGS has risks as well. When new equipment revenue grows rapidly, AGS share can be diluted. Inventory and supply-chain volatility can also affect near-term cash flow. Applied Materials’ April-quarter free cash flow was very low, partly because of specific payments, M&A;, and inventory. If future WFE expansion requires Applied Materials to carry inventory continuously, cash flow may lag the income statement for a period. Bulls need to focus on whether AGS continues to deliver after the installed base expands; single-quarter FCF should be treated only as a supporting signal.
6. Peer Ranking: Applied Materials, LAM, and KLA Are Different AI Manufacturing Bottlenecks
Applied Materials is not an isolated asset. In US semiconductor equipment, Applied Materials, LAM, and KLA represent different AI manufacturing bottlenecks. Applied Materials is more skewed toward materials engineering, DRAM, advanced logic, packaging, and services. LAM is more skewed toward etch and NAND. KLA is more skewed toward process control, inspection, and metrology. A higher WFE total benefits all three companies, but structural differences determine relative outperformance by phase.
This is where Morgan Stanley’s bear-case value lies. It upgraded LAM to overweight and downgraded Applied Materials to equal-weight, arguing that the 2027 NAND recovery gives LAM more leverage and that Applied Materials’ DRAM advantage has already been partly reflected by the market. The report noted that Applied Materials’ DRAM exposure is higher than LAM’s in 2026, but LAM has higher NAND exposure, and 2027 NAND WFE upward revisions may become the new marginal variable. This is a very important counterargument: buying Applied Materials is effectively a bet that DRAM, advanced logic, and packaging content intensity will keep exceeding market expectations.
The conclusion for Applied Materials from this ranking is as follows: if investors believe 2027 is mainly about NAND recovery, LAM’s leverage is more direct; if they believe 2027-2028 is mainly about continued increases in DRAM, advanced logic, and packaging complexity, Applied Materials’ structure is more favorable; if they believe all equipment is entering a supercycle but are unsure who gains share, KLA’s process-control profile is steadier. Applied Materials’ advantage comes from having positions across multiple AI manufacturing processes.
Rerating Japan’s Semiconductor Equipment and Materials: Physical Bottleneck Assets Behind AI Compute Expansion
From a valuation perspective, Citi’s 2028 target-price framework for Applied Materials, LAM, and KLA also reflects these differences. Applied Materials is valued at 31x 2028E EPS to reach US$710. LAM and KLA are valued at 40x 2028E EPS, reflecting the market’s willingness to give higher multiples to higher-growth or higher-quality links. Applied Materials’ investment opportunity is this: if it can prove the DRAM/advanced packaging/AGS combination improves growth quality, a 31x or higher multiple has support; if it is only WFE beta, the multiple will be pushed back into the traditional range.
The peer debate also highlights one point: Applied Materials’ story cannot be written only as “the industry is strong.” A strong industry is a necessary condition, not a sufficient one. Applied Materials needs to prove in 2H26 and 2027 that it is gaining share, defending gross margin, expanding AGS, and turning advanced packaging revenue from small-base high growth into a long-term platform. Only if these metrics deliver does the valuation deserve to move from the US$500 level to above US$700.
7. Valuation Debate: Behind US$520, US$570, US$710, and US$770 Is a Tug-of-War Between 2027E and 2028E
The valuation debate around Applied Materials is already clear. Early target prices clustered around US$500, anchored on 2027E EPS and a premium to traditional equipment multiples. After June, some firms shifted the framework to 2028E EPS, quickly moving target prices above US$700. Morgan Stanley is relatively cautious, while Jefferies is more willing to assign a high-cycle scenario. The specific target prices and multiples are set out below.
This table should not be read as “the highest target price is the most correct.” It should be read as three variables: earnings year, EPS number, and valuation multiple. Morgan Stanley is more anchored on nearer-term earnings and a base multiple. UBS uses blended EPS. Citi and Jefferies push the lens to 2028, so the numbers look very different.
The most important valuation question for Applied Materials today is whether the market can pay for 2028 in mid-2026. If industry visibility really reaches eight quarters, customer production plans extend into 2028, and fab cleanrooms and equipment delivery become hard constraints, discounting 2028 earnings in advance is not unreasonable. Conversely, if this is simply the sell side linearly extrapolating AI capex excitement, the 2028 target price becomes a high-level narrative rather than a deliverable model.
Particular attention should be paid to the quality of the “valuation multiple.” Citi’s 31x 2028E P/E for Applied Materials is already meaningfully above the company’s three-year average, and Jefferies’ 36x is closer to a high-cycle scenario. To support this multiple, Applied Materials cannot simply grow revenue. It must prove the growth comes from higher-quality structure: DRAM content intensity, advanced packaging, service revenue, and stable gross margin. If revenue growth comes from low-margin, short-cycle, regional orders, the market will push the multiple back down.
Target prices also need to be read by formula, not by the headline number. Lower target prices are essentially near-term EPS plus a base multiple. Higher target prices have already built 2028 WFE and longer-dated EPS into the model. Sorting these numbers on one chart is not meaningful. What matters is identifying the unfulfilled conditions embedded in each target price.
This breakdown is very useful for investing. If future Applied Materials earnings only prove that 2026 is strong, the market can at most sustain the first tier. If the company can prove that 2027 orders are still being revised upward, valuation can stabilize in the second tier. Only if customer scheduling, DRAM WFE, advanced packaging, and AGS all make the 2028 path more tangible will the market be willing to pay for the third and fourth tiers. The target-price increase itself is not the buy case; the verification conditions behind the target price are.
Applied Materials’ valuation is therefore not as simple as “higher means more optimistic.” High target prices often use further-out years and higher multiples, which also means higher risk. Low target prices are not necessarily bearish on the industry; they simply require pricing on nearer-term years. The more reasonable current reading is this: around US$500 is already supported by strong 2027 WFE and share recovery, US$570 is a neutral-to-positive framework that incorporates the DRAM supercycle into blended EPS, and above US$700 is a 2028 AI manufacturing platform option. Investors need to decide which layer of optionality they are willing to pay for.
8. Company Model: Applied Materials’ Profit Slope Comes From Revenue, Gross Margin, and Services Rising Together
Applied Materials’ company model can be understood through three variables: revenue scale, gross margin, and share count/EPS. Revenue scale is determined by WFE and share. Gross margin is determined by product mix, advanced process platforms, and service revenue. EPS is also affected by buybacks and operating leverage. The sell side’s wide range of 2028 EPS estimates for Applied Materials essentially reflects different assumptions on these three variables.
UBS’s June model lays out a very strong upside path, implying that Applied Materials continues to benefit from WFE upward revisions in 2026-2028 and that gross margin and expense leverage do not meaningfully slip. Morgan Stanley’s base model is more conservative, mainly differing in revenue slope and longer-term EPS. Putting the revenue and EPS paths into a comparison table better shows the difference between the two worldviews.
This table gives a practical judgment: a US$500-level valuation mainly needs 2027 EPS to deliver, while above US$700 mainly needs 2028 EPS to deliver. What investors really need to watch is whether revenue continues to be revised upward after 2027. If longer-term EPS lacks further upward evidence, the stock may only stay around the equipment-cycle midpoint. If the 2028 earnings path continues to become more concrete, the US$700 target has a real foundation.
Applied Materials’ gross margin is the amplifier in this model. April-quarter gross margin was about 50%, and Semi Systems gross margin was near 55%, which UBS viewed as a rare high point over the past 25 years. While the company sharply raised July-quarter revenue guidance, gross-margin guidance still stayed around 50%, suggesting that higher revenue did not materially sacrifice earnings quality. If advanced packaging, new platforms, and AGS continue to improve mix, EPS leverage will exceed revenue leverage.
This is also why future Applied Materials earnings cannot be assessed only by revenue. Revenue beating expectations with falling gross margin indicates a problem in order quality. Stable gross margin with slowing AGS growth means the services story is not strong enough. AGS growth without Semi Systems share gains means the company is only monetizing the installed base rather than capturing new-cycle alpha. The truly favorable result is all three lines rising together: Semi Systems shipments revised up, gross margin stable or expanding, and AGS growth remaining elevated.
9. How Prior Work Connects: Applied Materials Is the Intersection of the “Memory Tax” and the “WFE Supercycle”
The AI hardware cycle has already been decomposed into multiple layers: GPUs and ASICs drive advanced logic, HBM and DRAM drive memory, NAND and SSDs absorb the inference data hierarchy, advanced packaging turns chip interconnect into a bottleneck, and every path ultimately returns to WFE and equipment. Applied Materials sits right at the intersection of these lines.
Semiconductor Industry Deep Dive: Memory-Tax Spillover, SanDisk, Applied Materials, and ON Semiconductor’s Acquisition of Synaptics in AI Hardware Rerating
From the perspective of the “memory tax,” Applied Materials sits upstream on the equipment side of rising memory prices. Higher DRAM prices, HBM shortages, and rising DDR5 long-term contract prices eventually force memory makers to expand capacity, upgrade processes, and improve yield. Applied Materials does not bear the full risk of memory price volatility, but it can sell materials engineering equipment into expansion and process upgrades. Its earnings leverage lags memory prices, but its duration may be better.
From the perspective of the “WFE supercycle,” Applied Materials combines total growth and structure. A pure total-volume trade can buy the entire equipment group. A structural trade asks who is advantaged in DRAM, advanced logic, advanced packaging, and service revenue. Applied Materials’ advantage is that it spans multiple incremental links. Its disadvantage is that it does not have NAND leverage as pure as LAM’s, nor does it have KLA’s higher-quality process-control label. Applied Materials is a more complex asset: it has cyclical leverage and platform potential.
From the perspective of “advanced packaging,” Applied Materials represents the migration of front-end capabilities to the back end. CoWoS, HBM, and chiplets all point in the same direction: packaging is shifting from a cost center to a performance center. Applied Materials’ opportunity comes from selling materials engineering and defect inspection into more complex packaging flows. If advanced packaging continues to move from small-base high growth into multiyear capex, Applied Materials’ business boundary will be redefined.
This line also shows that Applied Materials’ rerating should not be driven only by memory prices. Memory prices provide the motivation to expand capacity. Advanced packaging provides process density. Together, they shift equipment demand from “buying more capacity” to “buying more complex capability.” If advanced packaging continues to become more front-end-like, Applied Materials’ revenue quality will look more like a manufacturing platform rather than beta to memory prices.
From the perspective of the “global memory bottleneck,” Applied Materials’ key variable is delivery cadence. Memory makers’ willingness to expand does not mean equipment arrives immediately. Cleanrooms, supply chains, installation, debugging, and yield ramp all take time. UBS noted that customers are providing equipment vendors with longer visibility, suggesting that the supply side is already scheduling production around multiyear projects. If Applied Materials can continue to gain share in this process, it can benefit from order visibility rather than just single-quarter pricing.
Goldman Sachs DRAM Deep Update: DDR5 Price Increases, 2027 HBM Repricing, and Samsung’s KRW 2,450T Investment
Taken together, these prior judgments position Applied Materials as a key carrier through which the AI hardware cycle transmits from “chip demand” to “manufacturing capacity.” GPUs and ASICs are the demand side. HBM and DRAM are the capacity constraint. Advanced packaging is the interconnect constraint. WFE is the manufacturing constraint. Applied Materials sells the materials engineering capability that resolves the manufacturing constraint. As long as AI hardware expansion continues to transmit from chip design to wafer manufacturing and packaging, Applied Materials’ rerating has a foundation.
10. The Real Investment Judgment: Whether Applied Materials Is Worth Chasing Depends on Four Verification Points
Applied Materials is not a cheap stock now, nor is it a pure cycle-bottom stock. It is more like a repricing asset that is migrating from traditional equipment beta toward an AI manufacturing platform. The most dangerous part of this phase is that the story is smooth and the data are also being revised upward, but valuation has already moved ahead. The investment judgment cannot stop at “the industry is strong.” It must land on four verification points: whether DRAM WFE continues to be revised up, whether advanced packaging moves from concept revenue to platform revenue, whether Semi Systems gross margin holds, and whether AGS proves the value of services.
If these four verification points proceed smoothly, Applied Materials’ upside comes from the market gradually believing 2028 EPS. Under UBS’s path, 2028E EPS approaches US$28. Under Jefferies’ base case, 2028E EPS is about US$21. Under Morgan Stanley’s base case, 2028E EPS is about US$20. Even if the multiple does not expand further, as long as EPS moves from US$17 toward the US$25 range, the stock still has upside. The real risk is that EPS stops being revised up while the market has already assigned a high 2028 multiple.
From a portfolio construction perspective, Applied Materials belongs more in an “AI manufacturing capex” basket than as a single memory-price trade. If investors want to bet on NAND recovery, LAM may offer more direct leverage. If they want to bet on process control and yield, KLA has higher quality. If they want to bet on the combined expansion of AI wafer manufacturing from advanced logic and DRAM to advanced packaging, Applied Materials is the more balanced choice. The benefit of balance is that multiple lines provide support; the drawback is that every line needs verification.
My judgment is that this rerating of Applied Materials has enough industrial foundation, but it should not be bought through linear extrapolation. The best holding window is the transition from “2026 earnings beat expectations” to “2027-2028 WFE visibility continues to improve.” The most dangerous window is when target-price upgrades and stock-price appreciation have already discounted 2028 EPS, while the next earnings report only proves that 2026 is very strong. For Applied Materials to move from the US$500 level to above US$700, it must prove its AI manufacturing bottleneck platform attributes over several consecutive quarters, not merely deliver cyclical beta.
11. Three Worldviews: Is Applied Materials Worth US$500, US$700, or a Return to Cyclical Valuation?
The debate around Applied Materials now appears to be about target prices, but at its core it is a contest among three worldviews. The first views the company as a strong cyclical recovery stock, arguing that 2026-2027 WFE is very strong but that 2028 should not be discounted too early. The second views it as an AI manufacturing platform stock, arguing that WFE has already entered a supercycle visible into 2028, with DRAM, advanced packaging, and AGS permanently raising the EPS midpoint. The third argues that the market is linearly extrapolating AI capex and memory shortages, that the share price has already absorbed 2028 in advance, and that if orders are not revised up further, valuation will be hit first.
The first worldview is the steadiest and closest to traditional equipment-stock pricing. It acknowledges WFE upward revisions from AI and Applied Materials’ advantages in DRAM and advanced logic, but it is unwilling to buy 2028 earnings too early. Under this framework, Applied Materials’ reasonable anchor is 2027E EPS. As long as 2027 EPS can reach US$17-20, applying 26-30x can justify US$500-600. But moving beyond that range requires stronger evidence.
The second worldview has the most imagination, and it is what bulls most want to prove today. It shifts Applied Materials’ valuation from “2027 equipment strength” to “insufficient AI manufacturing capacity in 2028.” In this world, US$250B of WFE corresponds to a manufacturing capex midpoint supported jointly by cloud capex, advanced logic expansion, DRAM supply-demand mismatch, NAND capacity replenishment, advanced packaging, and service revenue. Applied Materials raises unit revenue quality through DRAM content intensity, packaging platforms, and AGS while also benefiting from total growth.
The third worldview is the one most worth watching because it does not require the industry to weaken; it only requires growth to fall short of what the market has already discounted. The stock is most vulnerable in a scenario where the company keeps growing but does not keep raising the 2028 path. High-cycle stocks often correct this way: revenue does not collapse, EPS does not collapse, but the market realizes it assigned too distant an earnings year and too high a multiple, so it compresses valuation first.
I am more inclined to place Applied Materials between the first and second worldviews: it is already more than an ordinary cyclical recovery, but it has not yet fully proven it can unconditionally enjoy a 2028 platform-stock valuation. Pushing it directly back into traditional equipment-stock valuation underestimates the structural changes in DRAM and advanced packaging. Treating it directly as an already-delivered AI manufacturing platform ignores the valuation risk after target prices have been raised sharply. A more reasonable approach is to treat US$500-600 as a midpoint already supported by 2027 strength and share recovery, and above US$700 as upside optionality that needs continuous validation.
This is also the difference between Applied Materials and memory stocks. Memory-stock earnings leverage comes more directly from prices, and price increases quickly transmit to profits. Applied Materials’ earnings leverage comes from customer capex; the transmission is slower but visibility is longer. When memory prices surge in the short term, equipment stocks may not be the strongest at the same time. But when the market starts to believe that memory supply shortages will take 6-8 quarters or longer to resolve, equipment stocks look more like “pick-and-shovel suppliers for supply repair.” The valuation key for Applied Materials is convincing the market that this transmission chain is long enough.
In terms of trading cadence, Applied Materials’ best confirmation point usually appears when the industry begins to distinguish between “price leverage” and “equipment content leverage.” If DRAM and HBM remain tight, memory-maker expansion plans are extended, and Applied Materials’ orders and gross margin rise together, the market will be willing to push the target-price framework from 2027 to 2028. If memory prices rise but equipment orders are not revised up further, Applied Materials can easily underperform purer memory stocks. Buying Applied Materials is buying “the capex consequences of scarcity,” not “scarcity itself.”
12. Risks and Disconfirmation: Where Growth Lands Determines Applied Materials’ Valuation Resilience
Applied Materials’ biggest risk is that WFE growth lands elsewhere, or lands in lower-quality revenue. Given current AI capex, memory tightness, and advanced packaging demand, the equipment industry is likely still growing. What really affects valuation is the allocation of that growth. If NAND recovers faster than DRAM, LAM benefits more. If process-control intensity rises but Applied Materials’ eBeam and metrology share does not expand meaningfully, KLA benefits more. If regional mature-node orders rebound but gross margin and sustainability are low, Applied Materials gets the revenue but not the multiple.
The risks can be compressed into seven watchpoints. Weaker-than-expected DRAM expansion would directly lower 2028E EPS through order cuts and insufficient HBM spillover. A stronger NAND recovery would give LAM more marginal leverage than Applied Materials. Weaker-than-expected advanced packaging would undermine the platform narrative. China restrictions would affect both equipment shipments and service revenue. Share loss at major customers would push Applied Materials from an alpha asset back to equipment beta. Cash flow lagging the income statement for a long period would compress a high multiple. A reversal after overheated AI capex would disconfirm the WFE supercycle at the root.
The risk that needs the most attention is “growth landing elsewhere.” Morgan Stanley’s cautious view already provides a path: if NAND recovery becomes the marginal main line in 2027, LAM may have more leverage than Applied Materials. If Applied Materials’ DRAM advantage is already reflected in the stock price, the risk-reward of continuing to buy Applied Materials declines. Bulls cannot refute this simply by saying WFE is large. They need to prove that Applied Materials has excess growth in DRAM, advanced logic, packaging, and services.
The second risk is moving the valuation year out too early. Valuing the stock on 2028 EPS is not a problem in itself, provided customer orders, supply-chain delivery, and capacity construction offer enough visibility. If future earnings only show strong 2026 orders without visible 2027-2028 scheduling, the market will pull the valuation anchor back to 2027. Once the anchor retreats, the stock can correct first even if fundamentals have not collapsed.
The third risk is political and regional revenue. Applied Materials still has revenue exposure to China, and equipment export and service restrictions can affect some product lines and customer deliveries. This risk may not change the long-term AI manufacturing logic, but it affects revenue quality, gross margin, and the multiple the market is willing to pay. From an investment perspective, investors should avoid treating regional revenue as sustainable high-multiple revenue.
13. Conclusion: Applied Materials Is an Integrated Platform for AI Manufacturing Expansion, but the Next Leg Requires Delivery, Not Storytelling
The most worthwhile point in this Applied Materials rerating is that it connects several seemingly separate AI hardware clues. GPU and ASIC expansion raises advanced logic WFE. HBM and DDR5 raise DRAM WFE. Inference and storage tiers raise NAND and SSD demand. Advanced packaging turns chip interconnect into a performance bottleneck. Ultimately, all of these demands return to deposition, etch, interconnect, metrology, inspection, packaging, and services. Applied Materials does not own the end chips and does not directly enjoy memory price increases, but it sells the materials engineering capability that AI manufacturing expansion cannot bypass.
This is the core logic of Applied Materials’ migration from cyclical stock to bottleneck asset. It does not mean there is no cycle, that valuation can rise without limit, or that every quarter will beat expectations. Its opportunity is that AI hardware expansion pushes wafer manufacturing and packaging complexity to a new level, creating upside for Applied Materials’ unit-capacity value, service revenue, and longer-term EPS. As long as the WFE supercycle extends from 2026 to 2028, Applied Materials is not an equipment stock that can only be analyzed by near-term orders.
Execution requires more restraint. The market has already rediscovered Applied Materials’ good-company attributes. What remains to earn is the “delivery gap,” not the “discovery gap.” If the next 2-3 quarters continue to validate orders, gross margin, AGS, and advanced-packaging revenue together, valuation can move from 2027 toward 2028. If only orders are strong while gross margin and service revenue do not keep up, the stock can only be paid like a cyclical. This difference determines whether Applied Materials remains in the US$500-600 equipment-strength midpoint or opens the platform space above US$700. When tracking the stock, investors should not look only at sell-side target prices. Each target-price increase should be decomposed back into four variables: WFE, share, gross margin, and EPS, and then checked against what earnings actually confirm.
The final judgment can be compressed into one sentence: what is most valuable about Applied Materials today is the possibility that it becomes the broadest materials engineering platform in the AI manufacturing supercycle. Bulls need to keep seeing DRAM WFE, advanced packaging, AGS, and gross margin deliver together. Bears need to prove that these growth drivers are merely pull-forward demand, or that incremental WFE mainly lands with LAM, KLA, and other equipment links. The focus of the next earnings report is whether Applied Materials can continue making the 2028 earnings path more credible, more verifiable, and easier to track.
If this stock is placed in a portfolio, its more reasonable role is the “core observation anchor for AI manufacturing capex,” not a substitute for high-beta memory stocks. It can simultaneously test cloud capex, memory supply shortages, advanced logic expansion, and packaging complexity. If Applied Materials delivers several consecutive quarters of resonance across orders, gross margin, services, and advanced packaging, it will show that the AI hardware cycle has truly transmitted from chip design into manufacturing. If only target prices rise while operating data cannot keep up, the position should be managed as a cyclical stock rather than a platform stock.