
Analog Semiconductors Deep Dive: UBS Raises Texas Instruments Target Price to $350; How the Industrial Upcycle Re-rates the Analog Leader
目录
Too Long; Didn’t Read
1. What This UBS Report Really Changes
2. Why the Industrial Cycle Matters More Than Autos
III. What Distribution Inventory Is Saying: Units Are Down, Prices Have Not Fallen
IV. The Other Side of the Inventory Cycle: Whose Inventory Is Good, Whose Inventory Is Dangerous
V. Why Texas Instruments Became UBS’s Top Pick
VI. Analog Devices, Microchip Technology, ON Semiconductor: Who Is in the Second Tier
VII. Why 800V and AI Power Make Analog Valuations More Expensive
VIII. Valuation: Buy Cyclical Upside or Valuation Convergence?
IX. Where It Is Easiest to Be Wrong
X. What to Watch Over the Next Four Quarters
XI. Investment Conclusion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Analog semiconductors are moving from the tail end of destocking into the first half of an industrial restocking cycle. UBS raised its target price for Texas Instruments to $350, backed by a set of signals turning in sync: buy-side demand, distribution inventory, lead times, pricing, and free cash flow are all starting to point to a new industrial upcycle, while autos remain slow and data centers provide a second growth curve.
Too Long; Didn’t Read
Industrial restocking has already started. In UBS’s latest analog semiconductor update, order expectations from both distributors and direct buyers remain elevated. Improvement is no longer just long-dated optimism; it is already showing up in near-term orders, inventory, lead times, and pricing. Compared with the prior “recovery still on the way” phase, the change now is that industrial and data centers remain in high-momentum territory, inventories are starting to fall below target, lead times are extending again, and prices continue to rise.
In this cycle, buy Texas Instruments first. UBS raised its target price for Texas Instruments (TXN) from $295 to $350, lifting the valuation basis from 22x EV/FCF to 26x and applying it to average 2027/2028 free cash flow of US$12.6B. The Texas Instruments thesis sits simultaneously on price increases, finished-goods inventory, pricing execution, and the capex downcycle inflection, enabling the company to convert revenue elasticity into free cash flow more quickly as restocking begins.
Analog Devices has high certainty but slightly less torque. Analog Devices’ strengths lie in industrial, aerospace and defense, test and measurement, and high-end data converters. Its margins and customer quality remain among the best assets in analog semiconductors. The issue is that valuation is already not cheap, pricing elasticity is less pronounced than at Texas Instruments, and its inventory position is more conservative. It therefore looks more like a high-quality cyclical asset, but lacks the sharpest beta in the current restocking trade.
Microchip Technology and onsemi offer high upside but also high risk. Microchip’s exposure to industrial, data centers, aerospace and defense, and MCUs allows it to benefit from restocking, but its die bank remains heavy and it still needs demand recovery to absorb inventory and utilization headwinds. onsemi’s industrial and automotive businesses are indeed recovering, while 800V, SiC, GaN, and data-center power give it upside optionality. But UBS data show that some of its pricing remains under pressure and unit inventory is still building, leaving it with a heavier burden of proof than Texas Instruments.
Data centers are changing the valuation narrative for analog semiconductors. Traditional analog semiconductors move with industrial, automotive, and consumer electronics cycles, and valuations are usually treated as macro-cycle assets. 800V DC, AI rack power, GaN/SiC, connectors, and the power tree are pulling Texas Instruments, onsemi, Analog Devices, Infineon, Renesas, Monolithic Power, and others into the AI infrastructure diffusion chain. The market is starting to reprice the dual variables of “industrial recovery + rising AI power content.”
The risk is that restocking turns into a false upcycle. The four numbers to watch most closely are whether industrial and data-center net demand expectations remain elevated, whether lead times continue to extend, whether distribution unit inventories continue to decline, and whether Texas Instruments’ free cash flow is delivered on a 2027 cadence. If autos continue to decline, customers only pull orders forward without real consumption, or price pass-through is capped by second-source pressure, this analog semiconductor re-rating will shift from earnings upgrades to valuation overreach.
1. What This UBS Report Really Changes
The analog semiconductor debate has shifted from “is there a recovery?” to “who can capture pricing and cash flow in the early upcycle?” Over the past several quarters, the market has known that the analog semiconductor inventory cycle was approaching a bottom. But the debate was clear: has industrial demand really returned, are autos still a drag, and is customer restocking merely early ordering driven by tariff and supply anxiety? UBS’s 2Q26 update gives a clearer answer: the recovery has broadened from inventory-data improvement to a synchronized turn in demand, pricing, lead times, and corporate cash flow.
The evidence chain in this report has three layers. The first is purchaser surveys. UBS Evidence Lab’s semiconductor purchaser survey shows that the net share expecting demand to increase over the next six months reached 89%, the net share reporting demand increases over the past six months reached 87%, the net share reporting price increases reached 84%, and the net share expecting further price increases over the next six months reached 76%. These figures are already beyond ordinary marginal improvement and look closer to continuous diffusion in an early cycle.
The second layer is distribution inventory monitoring. UBS tracks more than 100 global distributors, around US$14B of inventory, and 48B catalog components. By 2Q26, unit inventories in true analog, power analog, and MCUs had each declined, while price indices remained elevated. True analog ASP had reached 141 versus 1Q24, power analog reached 136, and MCUs reached 120. Falling unit inventory with no price decline suggests the supply-demand relationship is shifting from “whoever has more inventory discounts” to “whoever can supply defends price.”
The third layer is company balance sheets. Analog companies’ 1Q26 revenue rose 3% quarter over quarter, while production fell 3% quarter over quarter, and total industry inventory was broadly flat. This combination is important: if the revenue rebound were coming from companies actively pushing supply into the channel, inventory should be rising with it. Revenue is now recovering while production remains restrained, indicating companies have not yet gone fully offensive. As long as orders continue to improve, capacity utilization, gross margin, and cash flow all have upside elasticity.
The main thread here is not a mindless industrywide upcycle. UBS repeatedly emphasizes that demand improvement is concentrated in industrial and data centers, while autos remain mixed and consumer and communications have not become new main drivers. What the market really wants to buy is the overlap of industrial restocking, AI data-center power diffusion, rising pricing, and improving free cash flow.
This is also why UBS ultimately puts Texas Instruments first. Many companies in analog semiconductors have recovery exposure, but only a few simultaneously offer pricing execution, supply capability, inventory position, utilization recovery, and capex decline. Texas Instruments now stands at that intersection.
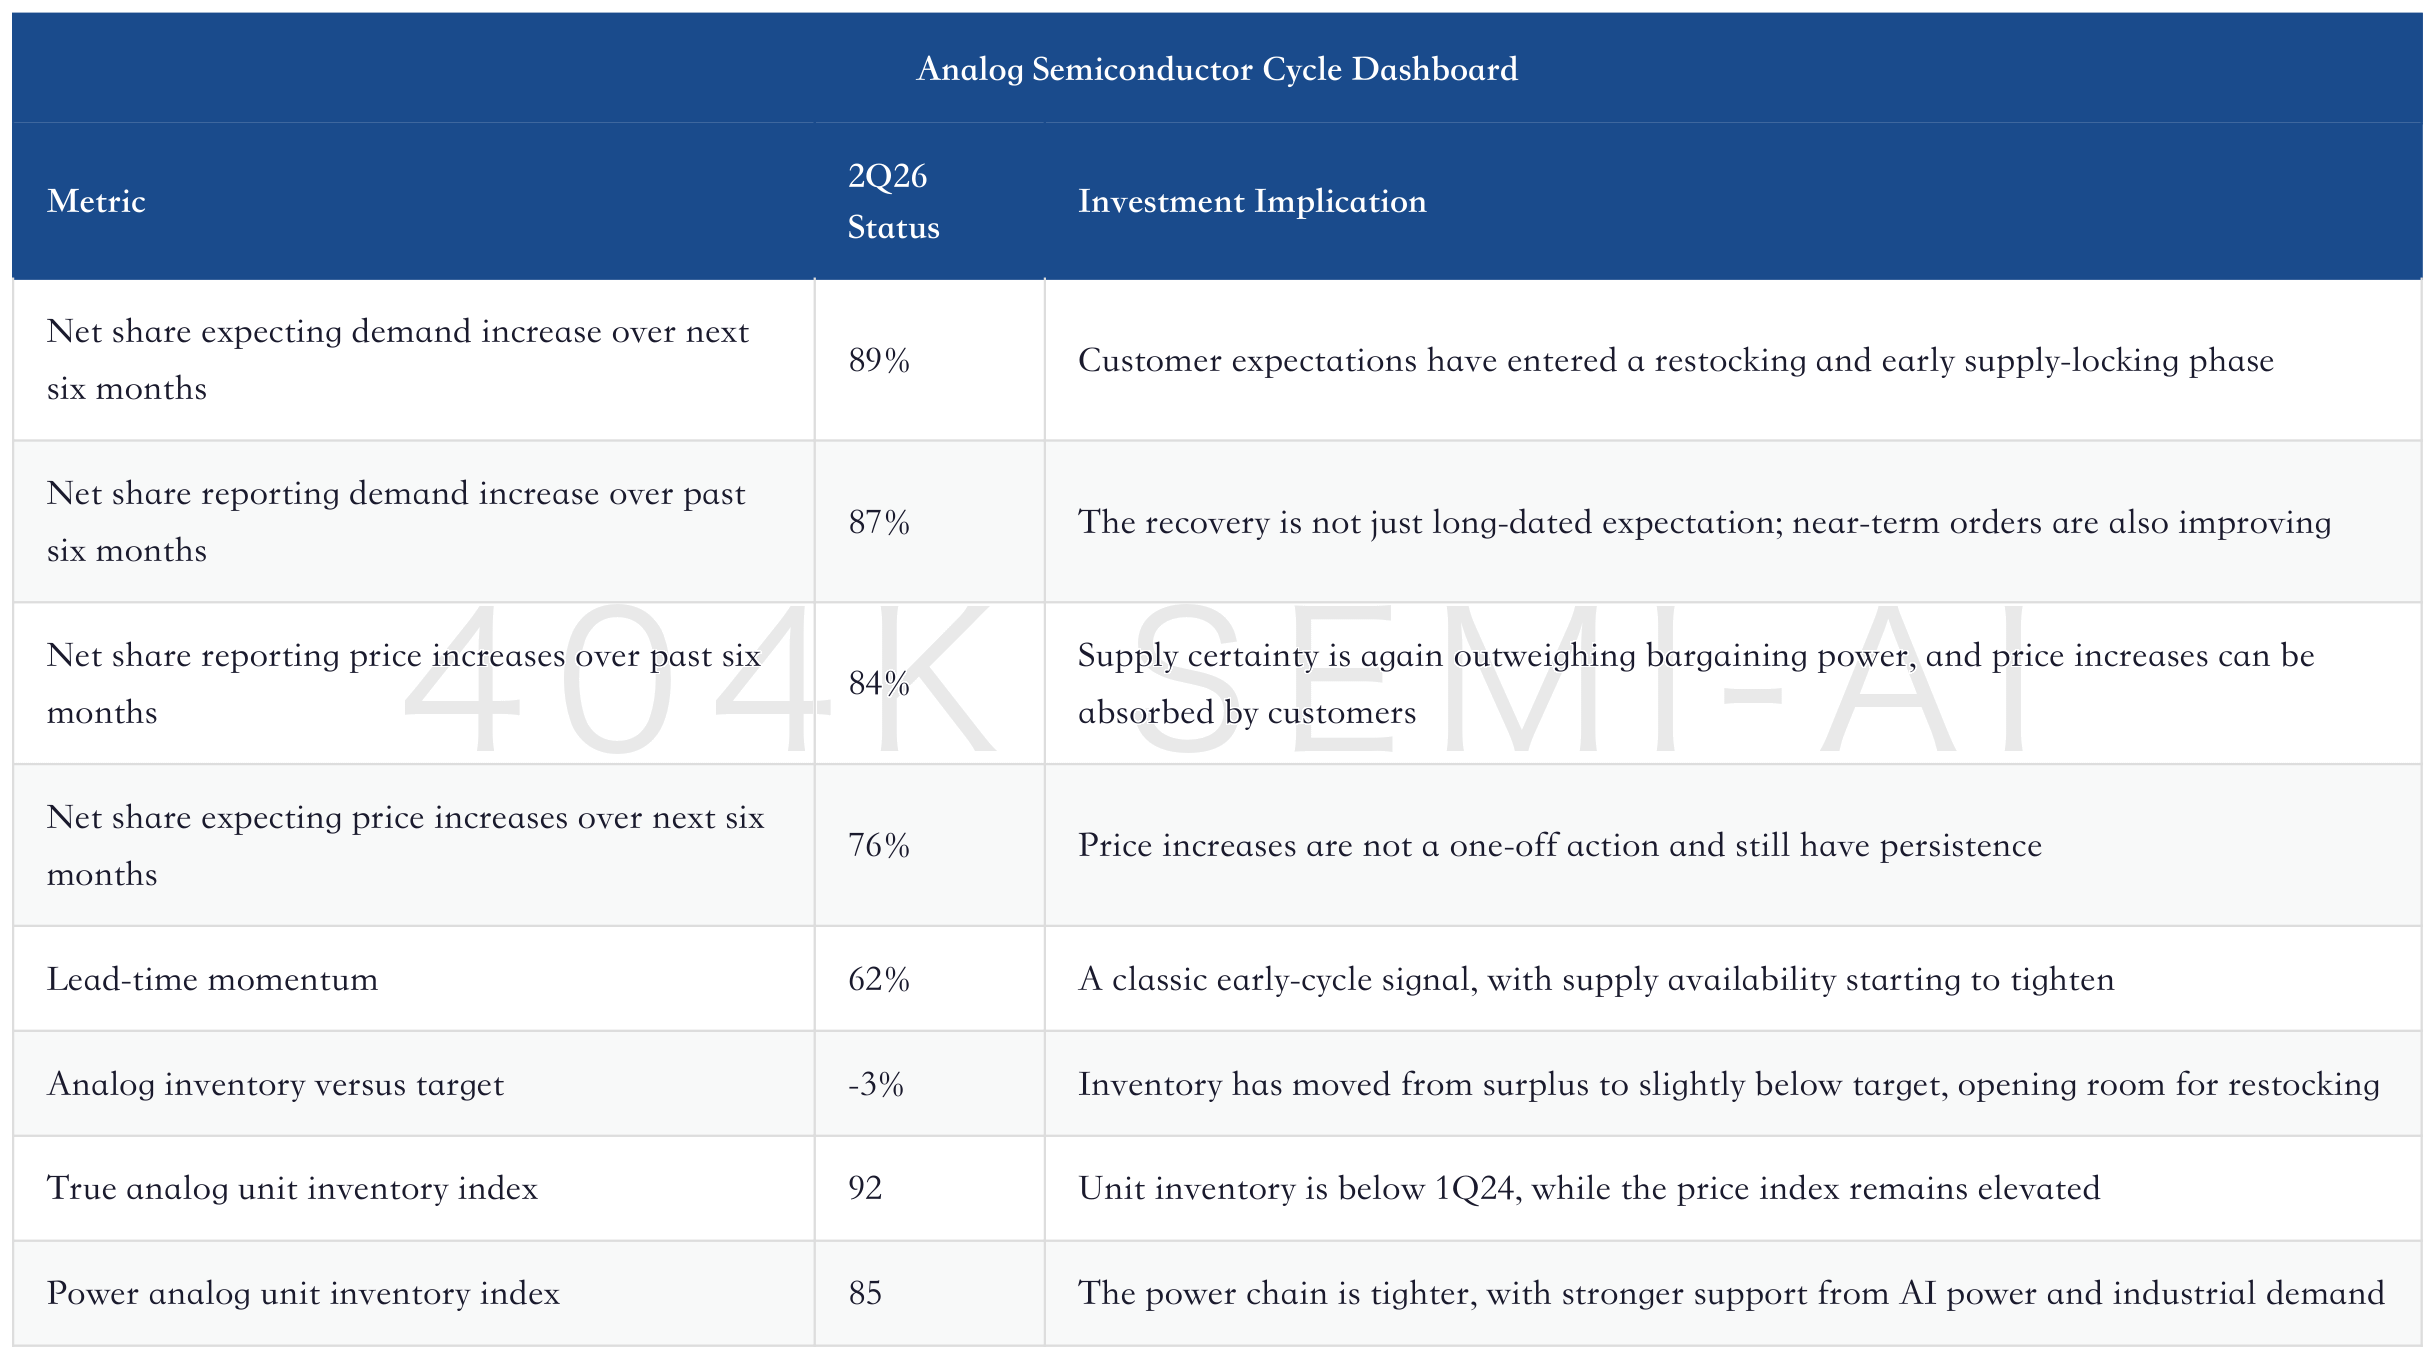
The implication of this table is straightforward: analog semiconductors are no longer just “done destocking.” Customers are starting to worry about supply, are willing to order early, are accepting price increases, and distribution inventories are not rebuilding in parallel. The market often grants valuation first at this stage, then waits for revenue and gross margin confirmation.
What makes this data more important is that three cycles are aligned in the same chart for the first time. The demand cycle is seen in orders and purchasing expectations; the pricing cycle is seen in whether customers accept price increases; and the cash-flow cycle is seen in whether vendors control production and capex while revenue recovers. Over the past year, the market could already see inventory digestion, but it could not be sure whether this was merely “low-level stabilization.” The combination UBS now presents is closer to “reacceleration after a low.” That changes how analog semiconductors are priced.
The demand cycle determines the revenue direction. Analog semiconductors are not driven by a single large customer order like GPUs, nor are they highly standardized like memory. Their revenue recovery often comes from simultaneous changes across many customers, many end markets, and many small part numbers. This is where purchaser surveys matter: when distributors and direct buyers turn at the same time, it means demand is not just one company’s order recovery; customer procurement teams have begun changing inventory strategy.
The pricing cycle determines the margin slope. What analog companies fear most is “revenue has returned, but only because discounts brought it back.” If demand recovery is stimulated by price cuts, revenue upgrades may not convert into earnings upgrades. What UBS sees this time is that the share reporting price increases remains high, customers are still worried about supply, and distribution unit inventories are falling while price indices have not dropped. This combination indicates that the industry still has some pricing power, at least in industrial, data-center power, and some high-reliability categories, where customers care more about delivery than haggling.
The cash-flow cycle determines the valuation multiple. The biggest controversy around Texas Instruments in recent years has not been company quality, but heavy capex, with the market worried that free cash flow would be consumed by fab investment. Now, if demand, pricing, and lead times are all moving upward while capex starts to enter a downward slope, investors will re-evaluate the company: it is no longer just a cyclical revenue recovery, but a conversion of prior heavy capital investment into future cash-flow leverage. This is the real meaning of UBS’s target-price increase.
So this report is not simply telling investors that “analog semiconductor conditions are getting better.” A more accurate reading is: industrial restocking provides the revenue base, rising prices provide earnings elasticity, Texas Instruments’ capex inflection provides the reason for multiple expansion, and AI data-center power adds a second layer of medium-term optionality to the story. Taken separately, none of these four variables feels new; taken together, they are the core of this analog semiconductor re-rating.
2. Why the Industrial Cycle Matters More Than Autos
Industrial is the main engine of this analog semiconductor recovery, while autos have not yet re-emerged as an industrywide accelerator. Historically, the most comfortable analog semiconductor rallies usually come when industrial and autos restock at the same time. This time, however, UBS data show autos remain mixed, while industrial and data centers are the clearer sources of incremental demand.
Industrial demand matters because it is naturally suited to analog semiconductors. Factory automation, energy, aerospace and defense, test and measurement, grid equipment, instrumentation, robotics, and data-center power all require large volumes of high-reliability, long-lifecycle, fragmented analog components. It is not highly standardized like smartphones or PCs, nor concentrated in a few high-priced chips like GPUs. Once industrial restocking starts, it spreads layer by layer across distributors, OEMs, foundries, EMS providers, and module makers, with pricing and lead times often moving ahead of end demand.
In UBS’s purchaser survey, industrial and data-center demand expectations remain elevated, while autos are declining more noticeably. This structure explains why Texas Instruments, Analog Devices, and Microchip Technology are better positioned than pure automotive or single EV-chain companies. Industrial customers do not only look at short-term pricing; they care more about supply certainty. Semiconductors often account for a small share of many industrial and automotive BOMs, but the cost of line stoppages is extremely high. Once customers worry that lead times are lengthening, procurement teams place orders early, sign long-term supply agreements, and raise safety stock.
This is also the basis for price pass-through. In the report, 51% of purchasers said they would pass semiconductor price increases on to downstream customers, while 38% said they would absorb the costs. This ratio shows that customers are indeed still under pressure, but price increases are no longer completely impossible to pass through. For analog semiconductor companies, as long as pricing can be defended, revenue recovery and utilization improvement will create greater gross-margin elasticity.
The difference between industrial and autos also appears in inventory reactions. The automotive chain experienced extreme shortages over the past several years, followed by slowing EV growth and component destocking, making customer behavior more prone to overshooting. Industrial-chain orders are more fragmented and product cycles are longer. The recovery may not be as sharp as an automotive rally, but its durability is better. By putting industrial at the center this time, UBS is reminding the market that the current analog semiconductor trade is a bet on broader industrial capex and the recovery of supply certainty, not merely an auto rebound.
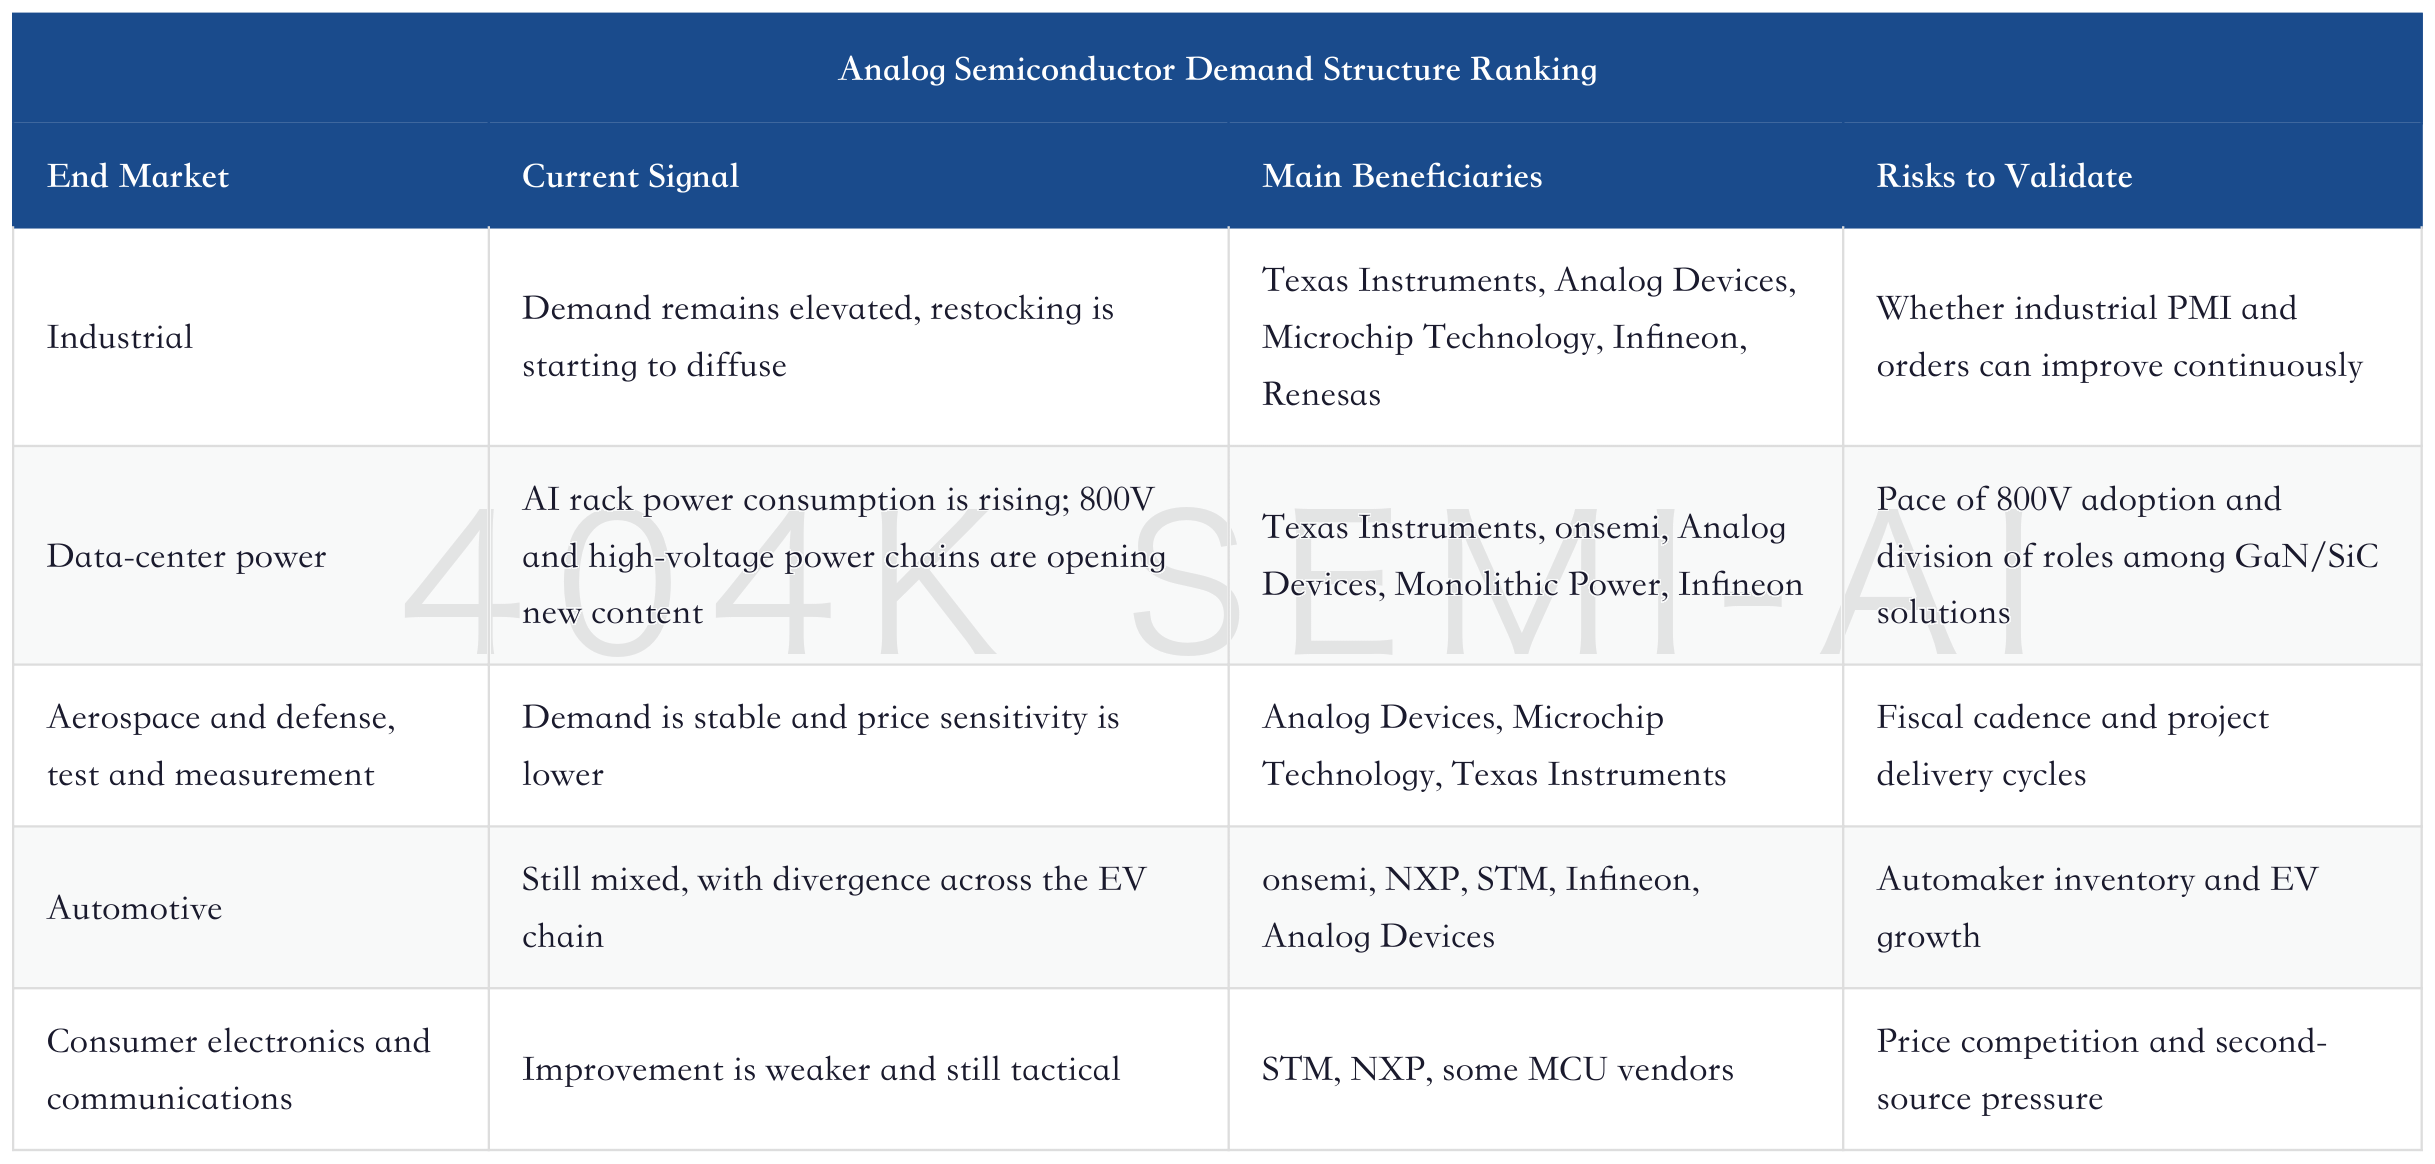
This ranking also explains stock selection. Texas Instruments has the broadest industrial and general-purpose analog distribution exposure; Analog Devices has high quality in high-performance industrial and data converters; Microchip Technology has greater elasticity in industrial, aerospace and defense, and MCUs; while onsemi depends more on whether its automotive, power-device, and data-center power narrative can offset legacy business exits and inventory pressure.
III. What Distribution Inventory Is Saying: Units Are Down, Prices Have Not Fallen
The core signal from distribution inventory is “lower volume, stable pricing,” which is more valuable than a simple inventory decline. If inventory falls alongside a sharp price decline, that is just forced destocking. If inventory falls while prices remain high, it means downstream digestion capacity is recovering and the supply side is not rushing to exchange price for volume.
UBS distribution inventory data divides analog chips into three categories: true analog, power analog, and MCUs. True analog includes data converters, sensors, amplifiers, and RF. Power analog includes power management ICs, transistors, diodes, and similar products. MCUs are core components for industrial, automotive, and embedded control. The common feature in 2Q26 is that unit inventory declined while prices remained materially above 1Q24 levels.
These three inventory measures are useful because they come from actual catalog-part data in distribution channels, making them closer to real customer purchasing behavior than disclosures from any single company. Looking at true analog, power analog, and MCU scale, unit inventory, and pricing signals together makes it easier to distinguish between “inventory clearance through price cuts” and “inventory falling while prices hold.”
The most notable divergence in 2Q26 is Texas Instruments. UBS data show Texas Instruments had strong pricing performance across true analog, power analog, and MCUs. In the true analog price index, Texas Instruments has risen to 201; in the power analog price index, it has risen to 170; and in the MCU price index, it has reached 143. By contrast, onsemi’s price index remains weak in some power analog categories, while Microchip Technology’s MCU inventory still needs further digestion.
This does not mean Texas Instruments will never face competitive risk. Analog chips are not GPUs. There are many product categories, customer qualification cycles are long, but substitution is not impossible. The real difference is that in the early-cycle upswing, the most valuable capability is being able to supply and having the confidence to raise prices. Texas Instruments absorbed pressure from capital spending and capacity expansion over the past few years. That is now turning into advantages in supply capability and cost position.
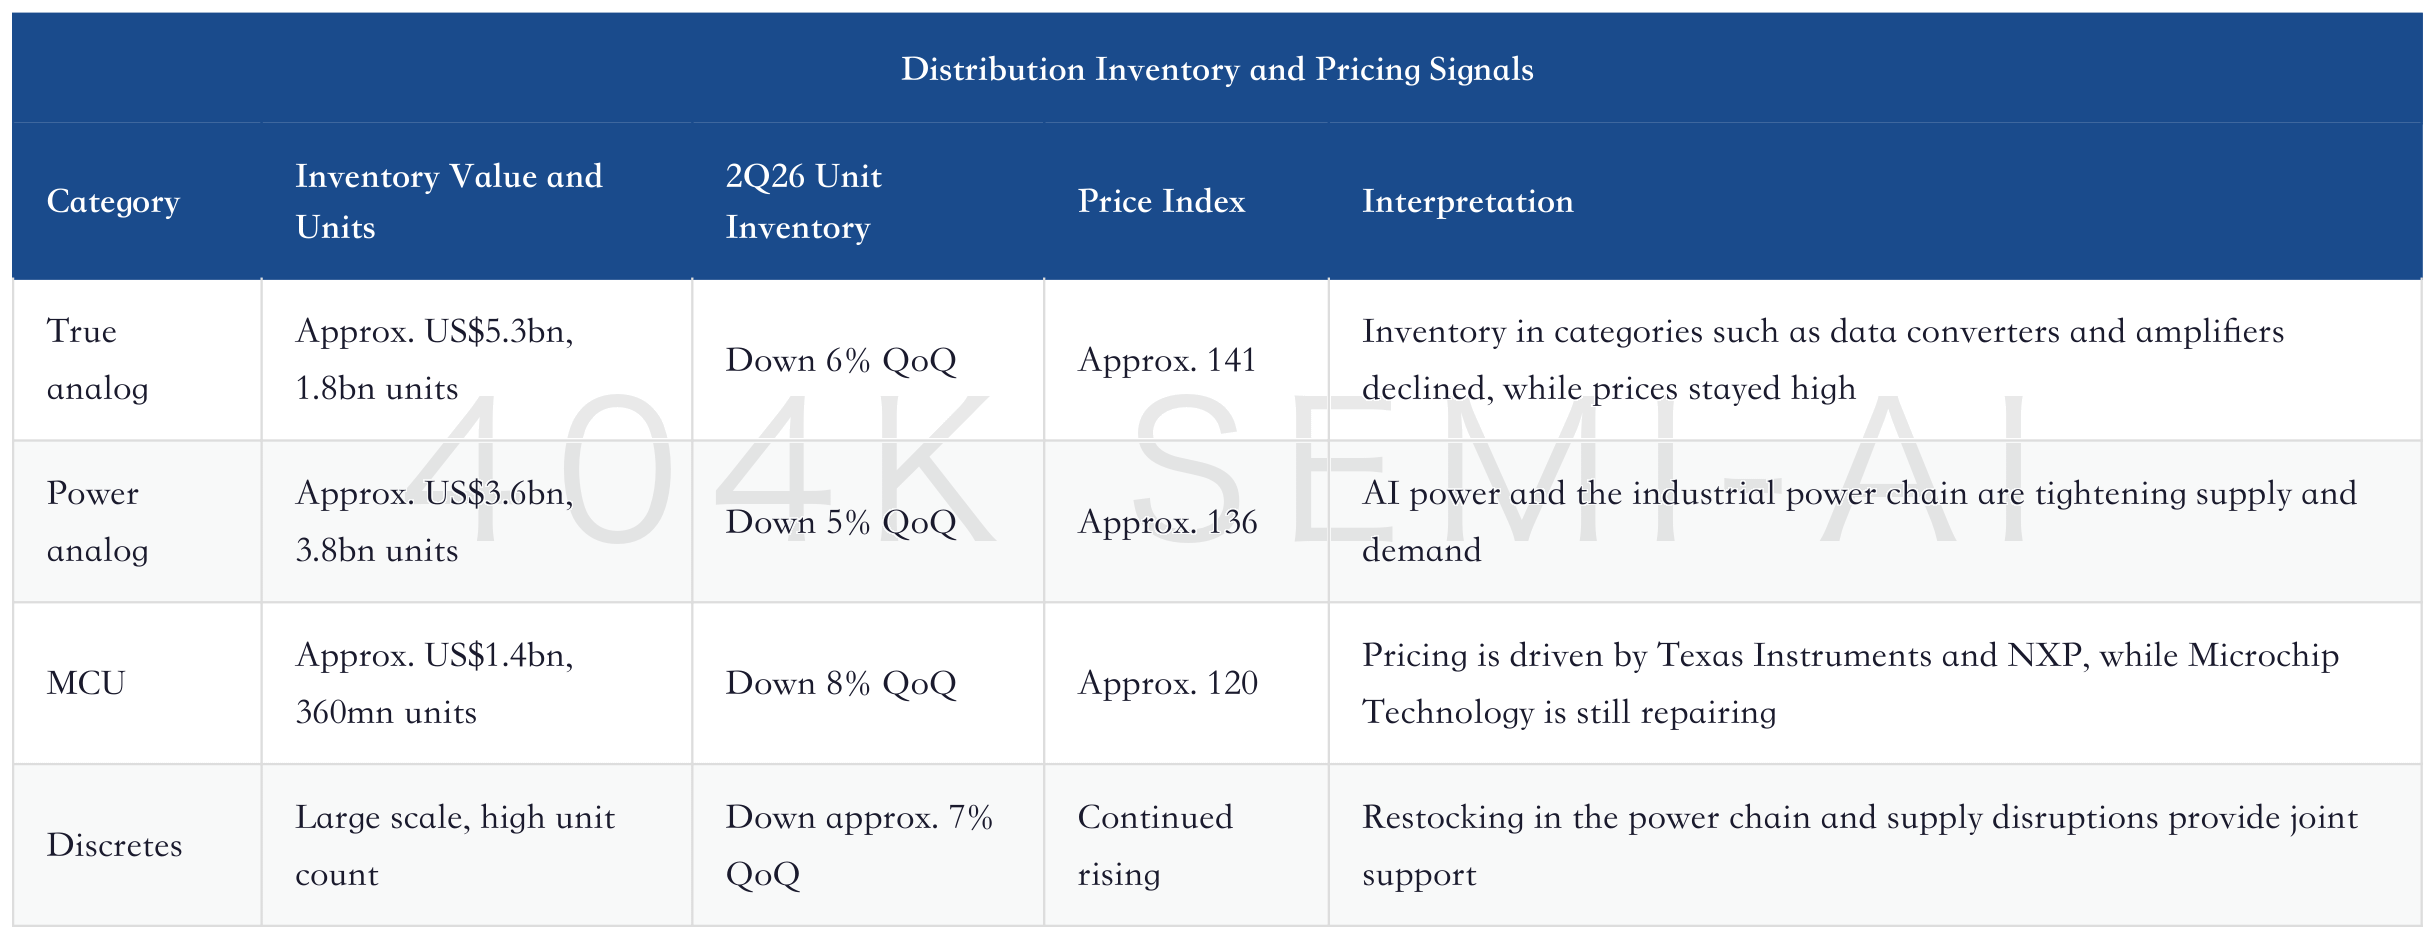
The investment implication of this table is that restocking usually appears first in catalog-part prices, lead times, unit inventory, and procurement budgets, and only later enters the income statement. By the time earnings fully reflect the revenue recovery, share prices have usually already moved some distance.
Data centers provide an additional lever here. In the past, analog cycles were mainly driven by industrial and automotive demand. Now, rising AI rack power density is turning power management, high-voltage GaN, SiC, isolation, thermal management, connectors, and sensors into part of the system bottleneck. Even if data centers are still not a large revenue share for companies such as Texas Instruments, their impact on the valuation narrative has already begun to exceed their revenue contribution.
Distribution catalog data also have an advantage that financial statements do not: they can reveal customer purchasing behavior earlier. When analog chip companies report revenue, investors are seeing the result of shipments already made and recognized. Changes in distribution inventory, pricing, and availability reflect what customers are doing when placing orders, modifying BOMs, looking for substitute parts, and locking in supply in advance. The most useful early-cycle signal is often not revenue growth year over year, but procurement teams starting to worry that they may not be able to get parts.
This is especially important in the industrial chain. Industrial customers do not frequently switch critical analog part numbers just because short-term prices are lower, because qualification, reliability, after-sales support, and line-stoppage risks are all high. Once a customer places an analog component into a long-term platform, supply stability becomes more important than unit price. When distribution inventory declines, customers are more likely to order in advance. When lead times lengthen, procurement teams switch from “buy as needed” to “lock in supply first.” When prices rise, as long as end-product gross margins can absorb it, customers typically will not redesign a system because a small number of analog components have become more expensive.
This is also why analog upcycles often last longer than they appear. Rising memory prices quickly stimulate supply expansion. GPU orders depend heavily on capital spending by a small number of major customers. Analog chips have fragmented part numbers, mature processes, and long qualification cycles, so both supply and demand move more slowly. Slowness has two effects: destocking drags on longer in downturns, while prices and lead times are also easier to sustain in upturns. Current UBS data do not show a one-off inventory replenishment. They show industrial customers once again assigning value to supply certainty.
Here it is necessary to distinguish between “ordering in advance” and “real restocking.” If customers are only pulling forward orders temporarily because of tariffs, geopolitics, or transportation disruptions, distribution inventory will quickly rise again and pricing momentum will weaken. If end demand and industrial capex improve at the same time, unit inventory will continue to decline, and supplier revenue and utilization will then follow. UBS combines buyer surveys, distribution catalog data, and balance sheets precisely to judge between these two scenarios. Current evidence leans more toward real restocking, but it still needs continuous confirmation from future earnings reports.
From an investment perspective, the conclusion from distribution catalog data is not “buy whoever has the least inventory,” but “buy whoever can deliver, raise prices, and hold share when customers are worried about supply.” Texas Instruments’ advantage is supply and pricing. Analog Devices’ advantage is high-end industrial quality. Microchip Technology and onsemi offer recovery elasticity and optionality. This difference will determine the sequence of share-price performance: early on, investors buy confirmation first; only later do they rotate into recovery elasticity and valuation convergence.
IV. The Other Side of the Inventory Cycle: Whose Inventory Is Good, Whose Inventory Is Dangerous
A company’s inventory position determines who can attack early in the upcycle and who must first repair the balance sheet. Analog chip inventory cannot be assessed only by total days of inventory. Die bank, finished goods, distribution inventory, internal capacity utilization, and customer inventory positions need to be viewed together to understand whether a company is preparing ammunition for the upcycle or still paying down the prior downturn.
UBS’s balance-sheet deep dive shows that industry headline inventory days were about 171 days in 1Q26. Rohm, Texas Instruments, onsemi, Microchip Technology, and Infineon are at higher levels; Analog Devices, STMicroelectronics, Allegro, and Renesas are relatively lower. Looking one level deeper, Texas Instruments’ finished-goods days were about 84 days, materially above the industry level of about 43 days. This looks like a risk, but UBS instead interprets it as an advantage, because Texas Instruments’ high finished-goods inventory can be delivered quickly when demand returns, preventing customers from switching to competitors because of lead times.
Microchip Technology and onsemi face different issues. Both companies have relatively heavy die banks, indicating that work-in-process and internal inventory burdens have not been fully removed. Microchip Technology’s management is already executing an inventory management plan, and demand recovery would help repair gross margins and utilization. onsemi must simultaneously address SiC, automotive, image sensors, exits from legacy businesses, and price divergence in power devices, making the proof path more complex.
Analog Devices is in a steadier position. Its industrial quality is high, inventory is relatively less aggressive, and margins are stronger. But the cost of stability is that elasticity may not be the greatest. For an analog company already trading at a high-quality premium, the market needs to see not only that things “will not be bad,” but also that pricing, orders, and the data-center power narrative can continue to revise upward.
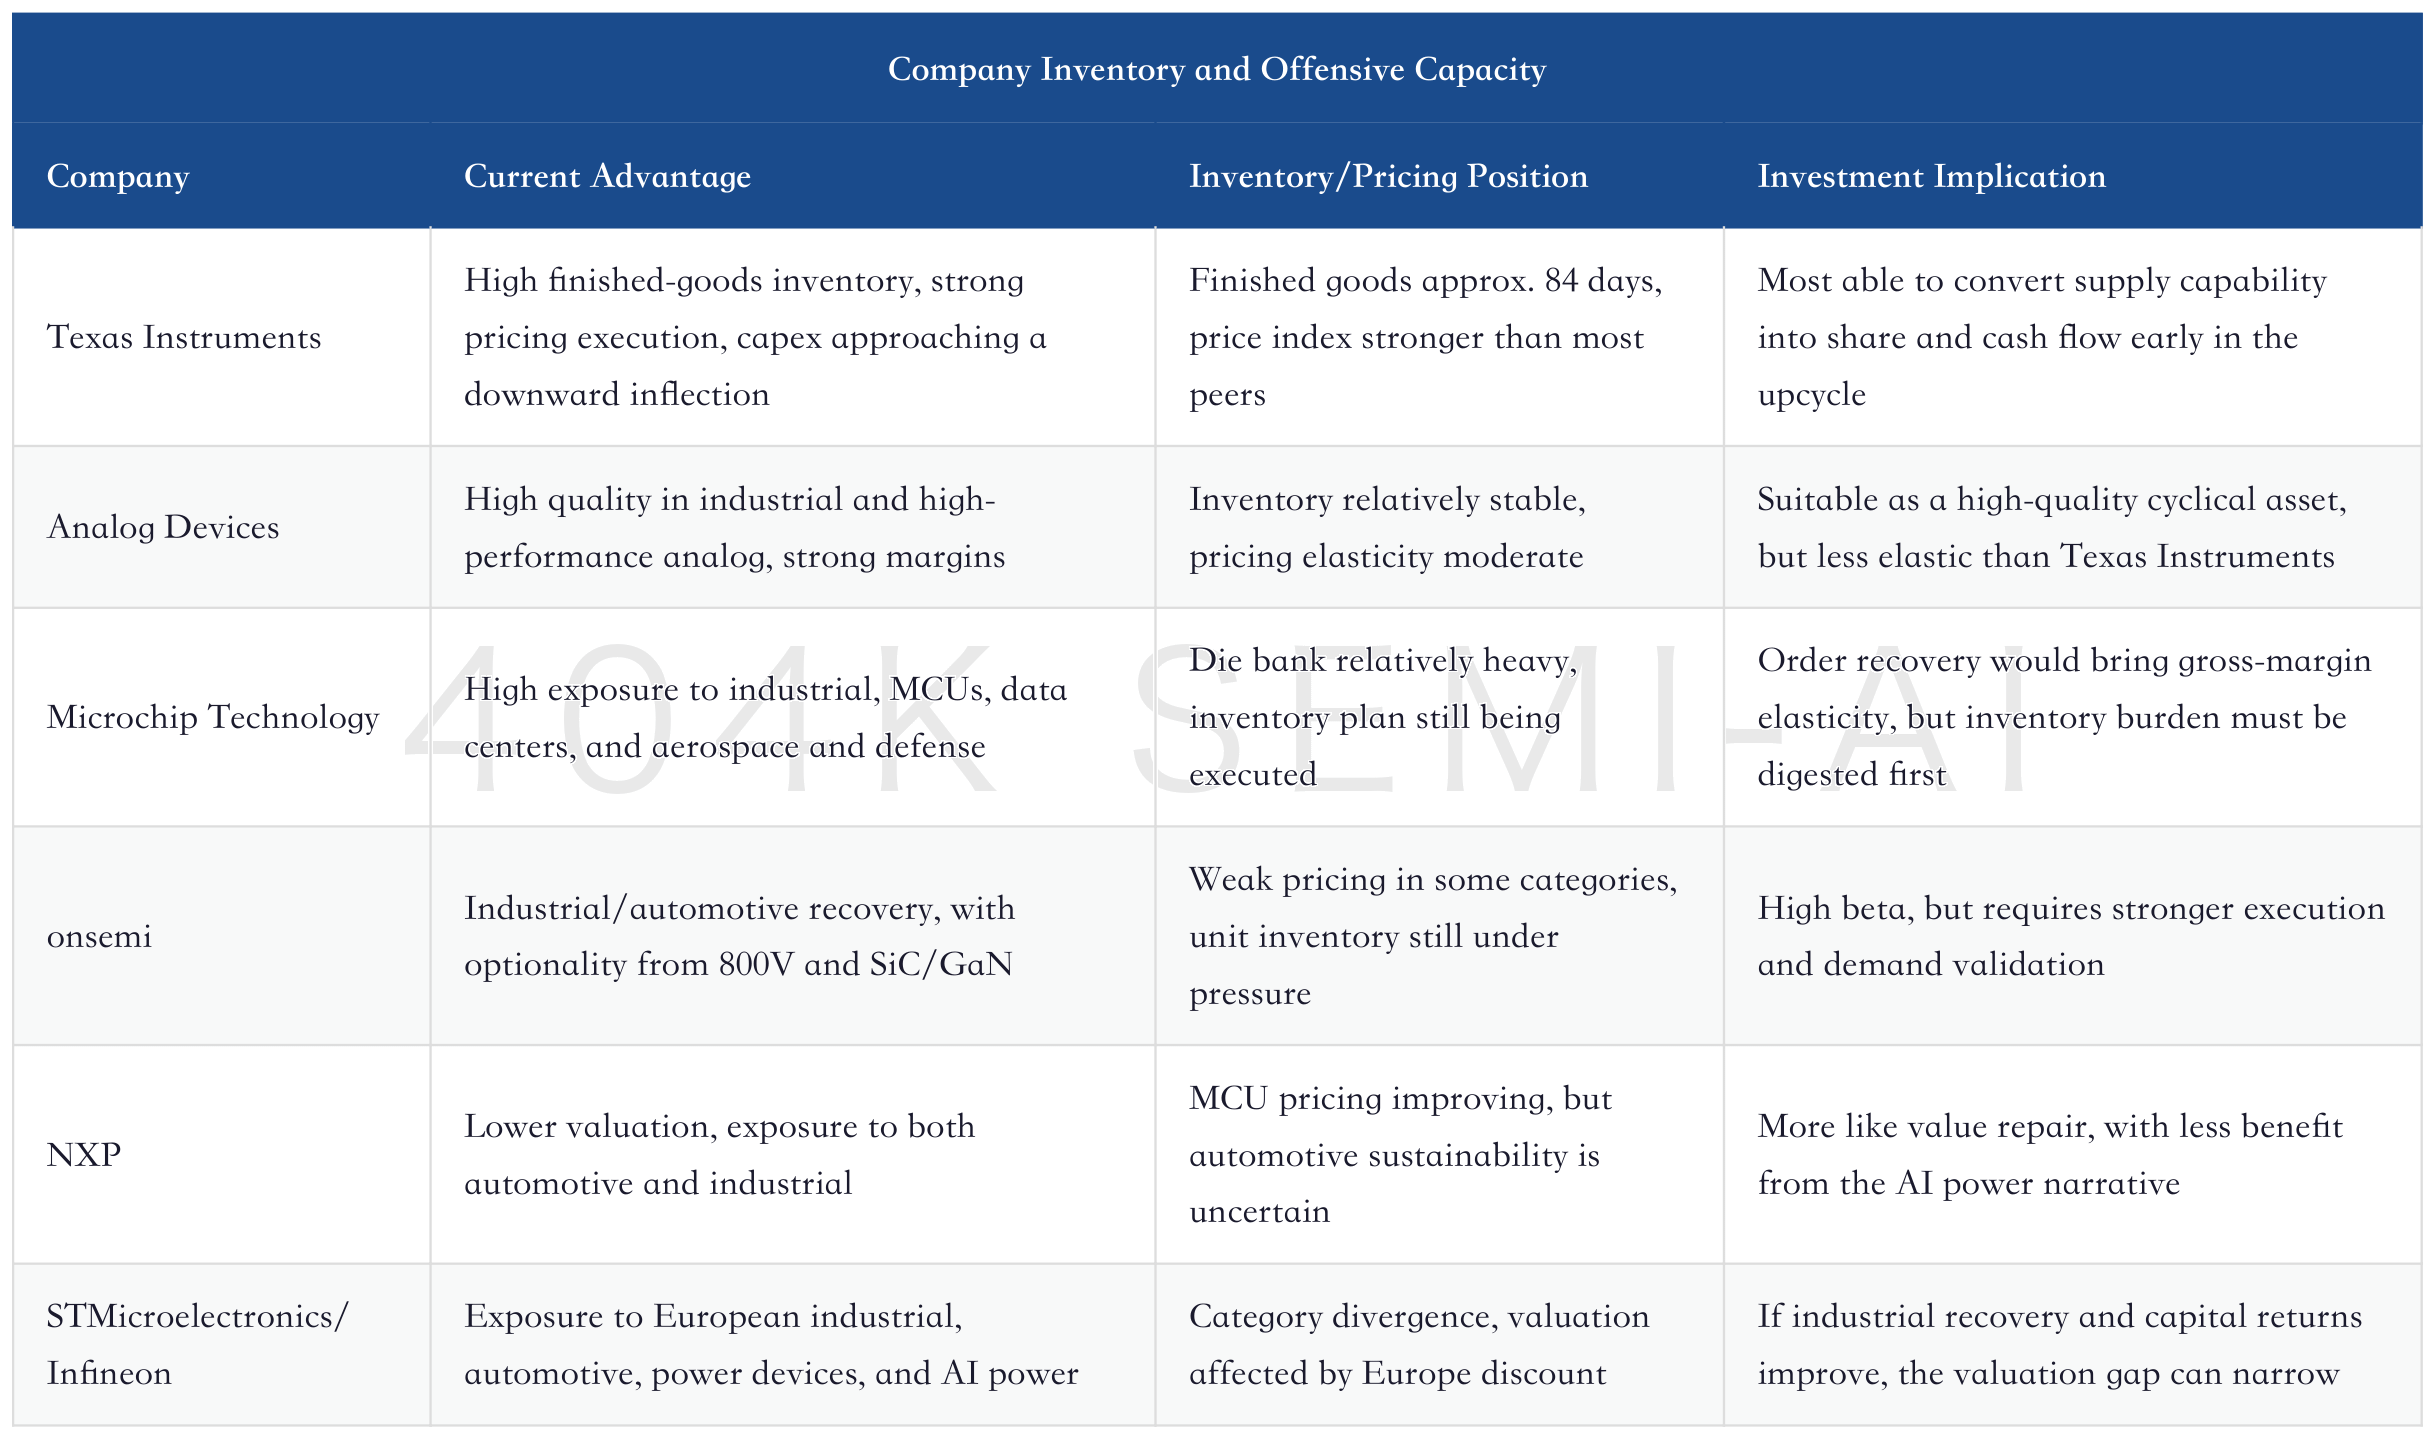
Inventory judgment cannot be static. High inventory combined with falling demand is a margin risk. High inventory combined with longer lead times and customer orders pulled forward is supply capability. Low inventory combined with demand recovery creates pricing elasticity. Low inventory combined with an inability to deliver leads to share loss. The most interesting part of Texas Instruments today is precisely that its high finished-goods inventory has turned from a point of controversy into a delivery option in the upcycle.
V. Why Texas Instruments Became UBS’s Top Pick
Texas Instruments is being re-rated this time because “pricing + inventory + FCF” are all turning at the same time. UBS raised its Texas Instruments price target from US$295 to US$350. On the surface, this reflects an increase in the valuation multiple from 22x EV/FCF to 26x. Underneath, it is a repricing of the company’s free-cash-flow quality.
Over the past two years, Texas Instruments’ valuation has been weighed down by one issue: it spent too much money building fabs. High capex, depreciation pressure, and slow gross-margin recovery meant that even if the market believed in a revenue recovery, investors still worried that free cash flow would be consumed. Now this issue is starting to reverse. As the capex cliff gradually arrives, as long as revenue maintains mid-teens growth, FCF per share will recover faster.
UBS’s model for Texas Instruments links revenue recovery, EPS repair, and the free-cash-flow inflection. The core of the valuation is not single-year EPS, but average 2027/2028 FCF and the target EV/FCF multiple. The base target price, upside case, and downside case all revolve around this set of cash-flow assumptions.
The most important variable in this model is FCF. In the past, analog investors often focused on gross margin, but Texas Instruments’ stock has historically been more easily priced around free cash flow. As long as capex comes down from elevated levels, revenue recovery and pricing improvement will flow through to cash flow more quickly. Texas Instruments’ cyclical elasticity comes from “after capacity investment is completed, each additional dollar of revenue leaves more cash behind.”
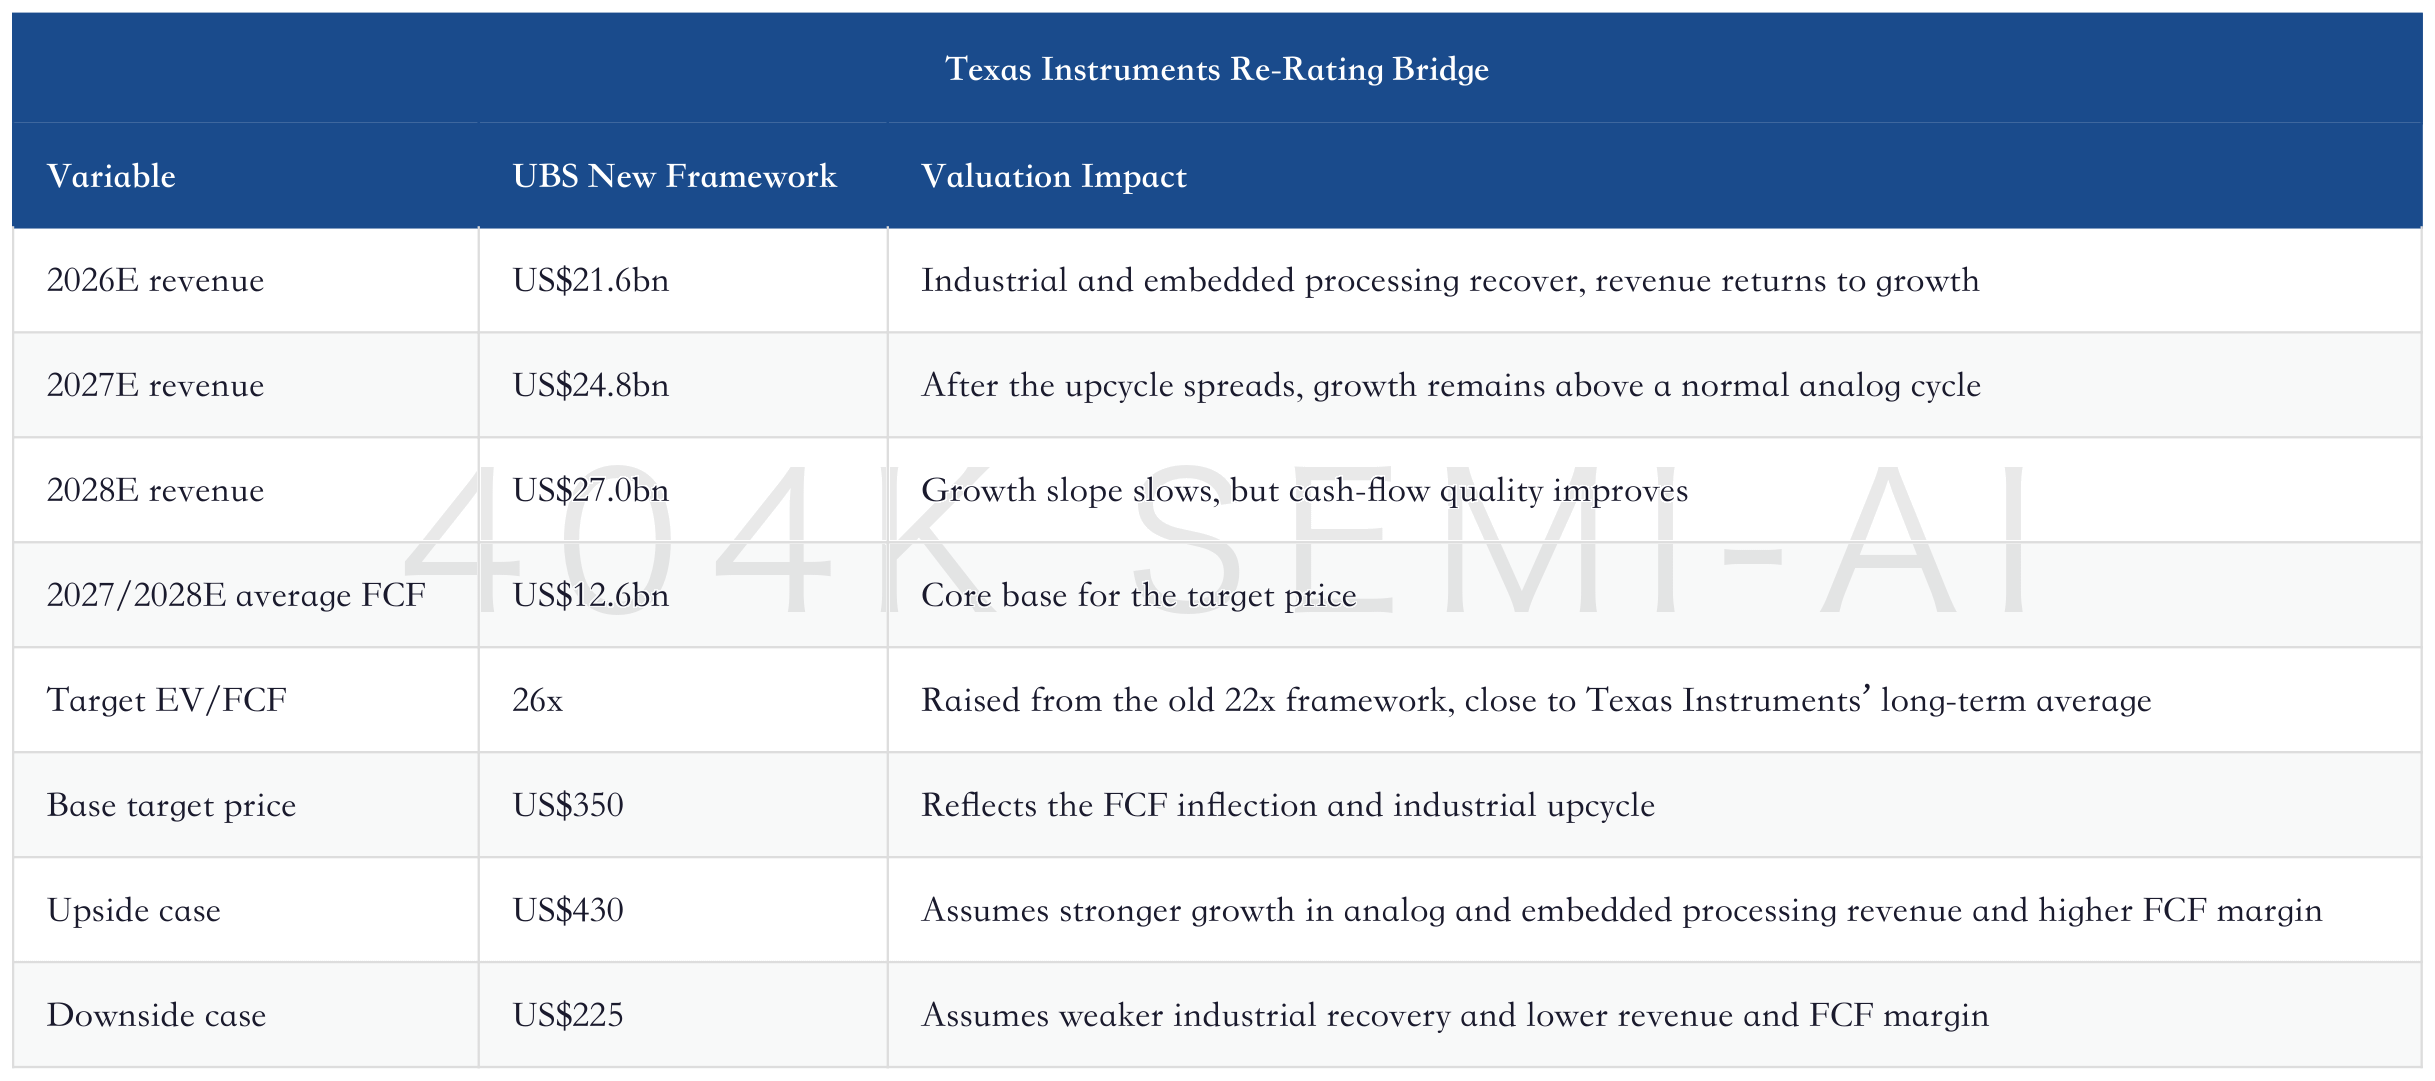
This bridge also highlights one risk: Texas Instruments is not a low-valuation stock. Its current valuation is already above its historical median and also above many traditional analog peers. Buying Texas Instruments means buying confirmation and the FCF inflection, not cheapness. If the industrial recovery does not continue, or if pricing execution is undermined by competition, the 26x FCF multiple implied by the US$350 target price will be difficult to expand further.
But in the analog chip industry, cheap is not necessarily the best early-cycle asset. What is truly scarce early in the cycle is a company that can secure price increases, deliver on time, and convert the capex peak into a downward slope in cash outflows. The capacity investment that Texas Instruments was questioned for over the past few years is now becoming the core option in this phase.
Texas Instruments’ asset attributes are changing. In the past, market discussion of Texas Instruments often focused on whether it had overinvested. The company’s commitment to internal manufacturing and long-term capacity expansion looked heavy during the downturn: depreciation pressure rose, capex consumed free cash flow, and revenue did not grow at the same time. Investors naturally worried that management was too optimistic about the industry cycle. Now the same asset base is being reinterpreted: if industrial and embedded demand recover, internal capacity, finished-goods inventory, and supply stability are not costs, but tools to gain share in the upcycle.
This is the difference between analog chips and foundry, memory, and GPU companies. In foundry, capacity utilization and advanced-node investment more directly affect industry supply and demand. In memory, supply discipline quickly transmits into pricing. GPU order visibility is more concentrated. Texas Instruments’ value lies in a large number of long-tail analog part numbers, mature processes, internal manufacturing, and long-term customer relationships. Its capacity is not a bet on one or two blockbuster products, but a way to provide certain delivery in a market with fragmented customers and complex part numbers. Industrial customers are willing to pay for certain delivery; that is when Texas Instruments’ internal manufacturing has economic value.
The decline in capex is the timing key for this re-rating. Revenue recovery alone is not enough to reprice Texas Instruments, because investors already know analog chips are cyclical. What truly changes the valuation is the simultaneous occurrence of revenue recovery and falling capex. At the current stage, each unit of incremental revenue is more likely to pass through to free cash flow, and capex no longer consumes the improvement in the income statement. UBS anchors its target price to free cash flow rather than single-year EPS because it recognizes this change.
Finished-goods inventory also needs to be repriced. In a downturn, high finished-goods inventory looks like a burden. Early in an upcycle, it looks like an option. It allows Texas Instruments to deliver quickly when customers resume orders, and it gives the company more pricing power when lead times lengthen. More importantly, it can reduce customers’ incentive to migrate to a second source. Once analog customers move a part number to a competitor because of shortages, share may take a long time to recover. The ability to deliver is itself both defense and offense.
Pricing execution is the third variable. In UBS distribution data, Texas Instruments’ price index is stronger across multiple analog and MCU measures, showing that it is not merely exchanging inventory and supply for volume. If pricing holds, revenue recovers, and capex declines at the same time, Texas Instruments’ operating leverage will be cleaner than that of a traditional cyclical stock. Investors are willing to pay a higher multiple because cash-flow quality is improving, not because the industry has suddenly become a high-growth track.
This also explains why Texas Instruments’ risk cannot be assessed only by whether its valuation is expensive. An expensive stock can still keep outperforming if the cash-flow inflection is clear. A cheap stock can still be a trap if inventory and pricing have not repaired. What Texas Instruments needs to prove now is not “whether the company is good,” but whether “cash-flow release after the capex peak can be delivered.” In every coming quarter, the market will cross-check revenue, inventory, capex, and free cash flow together.
VI. Analog Devices, Microchip Technology, ON Semiconductor: Who Is in the Second Tier
The ranking of the second tier depends on whether investors want certainty, cyclicality, or optionality. On quality alone, Analog Devices remains a premium asset in analog semiconductors. For cyclical torque, Microchip Technology has more room for inventory and utilization recovery. For AI power and power-device optionality, ON Semiconductor has higher upside, but the near-term evidence is also more complicated.
Analog Devices’ core strengths are customers and products. Industrial is its largest end market, and high-performance data converters, amplifiers, RF, test and measurement, aerospace and defense, and automation give it strong gross margins and customer stickiness. Bernstein’s global analog framework also views Analog Devices as one of the U.S. analog companies with the best industrial mix. The issue is that the market has already assigned a fairly high valuation to that quality. Analog Devices is better suited as a core allocation holding than as the sharpest restocking-beta trade.
Microchip Technology looks more like an “inventory-repair beta stock.” Goldman Sachs and Morgan Stanley have both previously noted that Microchip has attractive exposure to industrial, data center, computing, aerospace and defense markets, with orders and inventory-management plans improving, and gross-margin drag likely to decline as utilization improves. UBS’s 2Q data, however, is a reminder that Microchip’s die bank remains heavy and inventory digestion is not fully complete. Its upside depends more on continued order recovery and the company lifting utilization.
ON Semiconductor is harder to summarize in one sentence. Goldman Sachs believes ON’s industrial and automotive recovery is already under way, but legacy-business exits, SiC, and image sensors make headline revenue less clean. Citi is more positive on ON’s SiC/GaN optionality from the perspective of 800V data-center power. UBS’s distribution data offers a cooler reminder: ON’s pricing remains weak in some power analog categories, and unit inventory pressure has not been fully resolved. In other words, ON’s upside can be large, but it needs more execution evidence.
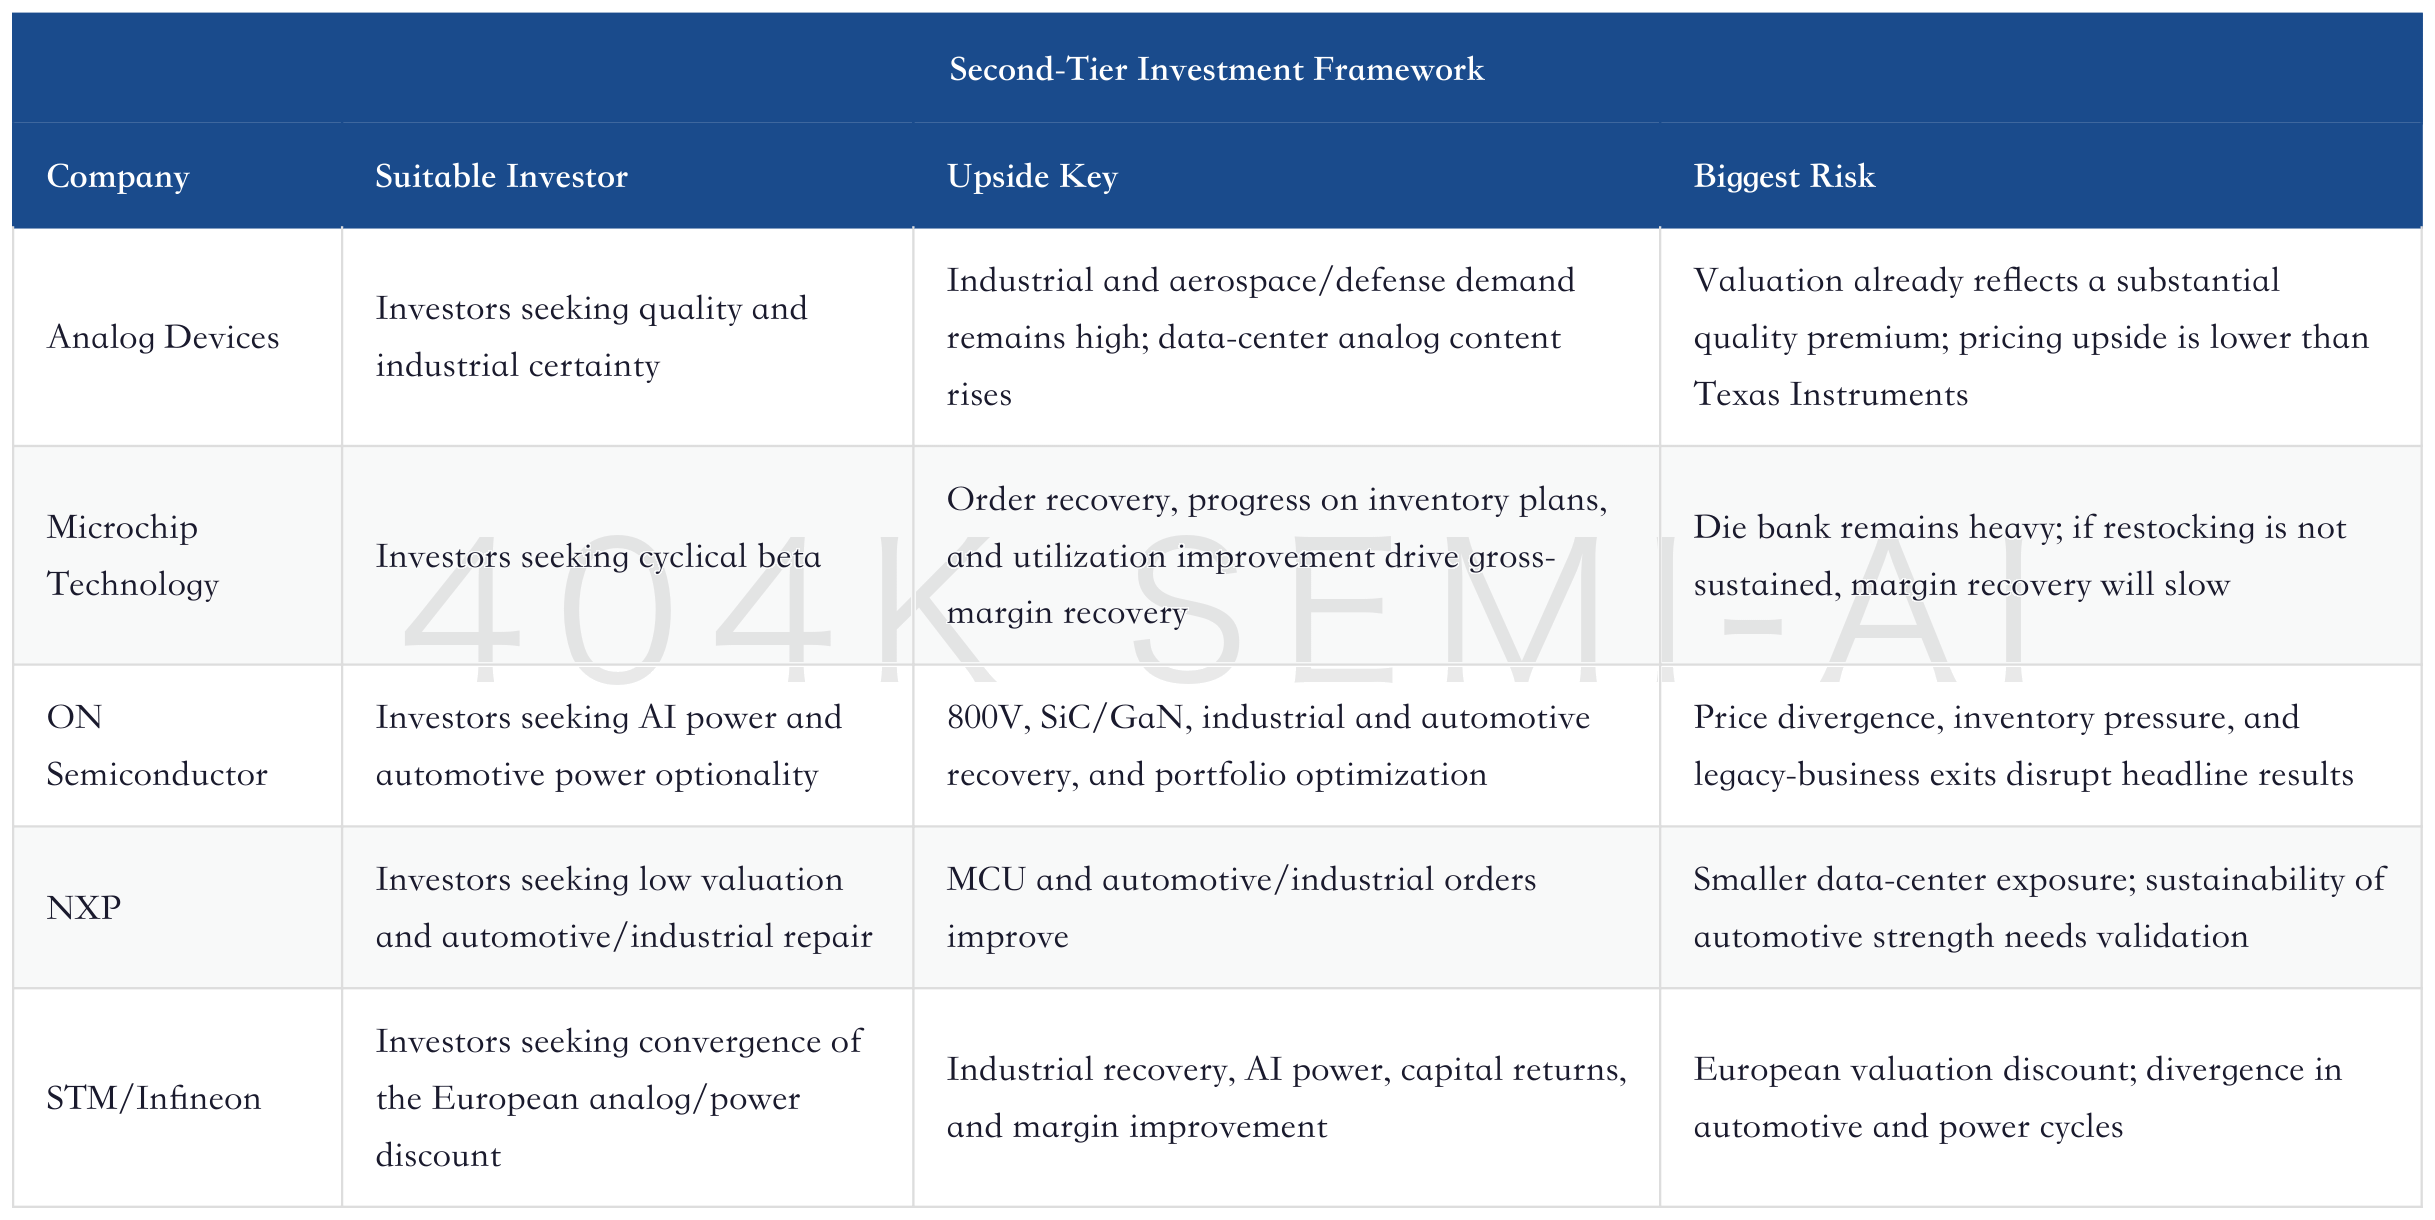
The core point of this table is that each company carries a different burden of proof. Texas Instruments needs to prove FCF. Analog Devices needs to prove high-quality growth is still there. Microchip Technology needs to convert inventory repair into gross margin. ON Semiconductor needs to prove that data-center power optionality can offset volatility in automotive and legacy businesses.
VII. Why 800V and AI Power Make Analog Valuations More Expensive
AI data centers have pulled analog semiconductors from a macro-cycle asset bucket into the system-bottleneck asset pool. This point matters because it explains why analog semiconductor companies can receive valuation rerating beyond a traditional industrial recovery.
The core change in AI racks is power density. GPUs, ASICs, HBM, switch chips, and optical modules are all increasing power consumption per rack. Power travels from the campus, transformers, distribution, racks, and power modules all the way to the chip side. This process requires a large number of analog and power devices: power-management ICs, high-voltage GaN, SiC, isolated drivers, sensors, thermal management, connectors, controllers, MCUs, and protection devices. Their unit prices are not necessarily high, but volumes are large, qualification is strict, and system value is high.
Citi’s 800V data-center power framework provides a more aggressive version: the 800V-to-1V power-delivery market could grow from about $2 billion in 2026 to about $12 billion in 2028, implying a CAGR above 70%. This type of estimate should not be applied mechanically, but the direction is worth taking seriously. Data-center power is moving from a “server power-supply chain” to an “AI compute-efficiency chain,” which gives some analog and power semiconductor companies a higher-valuation narrative than the traditional cycle.
Texas Instruments matters because of high-voltage GaN and internal manufacturing capability. ON Semiconductor matters because of SiC/GaN and high-power infrastructure. Analog Devices matters because of high-performance power, data conversion, and control. Monolithic Power matters because of modular power and high-end data-center customers. Infineon, Renesas, and STM connect to European industrial, automotive, and power devices. Different companies will not consume the same profit pool, but all will be re-screened by the AI power tree.
SemiAnalysis | 800VDC Delay and CPO Pushout: Powered Down, Lights Off Chinese-English Version
This thesis also carries risks. 800V will not become ubiquitous overnight. Nvidia and cloud-vendor architecture choices, the pace of green data-center construction, power-supply standards, GaN/SiC cost curves, and server OEM design cycles will all affect the pace of realization. In the near term, ±400V HVDC sidecars, rack-level power, and high-voltage conversion will land earlier. Broad adoption of true >1MW, SST, or higher-voltage architectures may require a longer cycle.
Therefore, in the final investment ranking, not every analog company should be labeled an AI asset. A more accurate approach is to split analog semiconductors into two categories: first, revenue and pricing repair from industrial-cycle recovery; second, valuation narrative and medium- to long-term content uplift from AI power. Texas Instruments, Analog Devices, ON Semiconductor, Monolithic Power, Infineon, and Renesas will carry different weights across these two lines, and the market will assign different valuations accordingly.
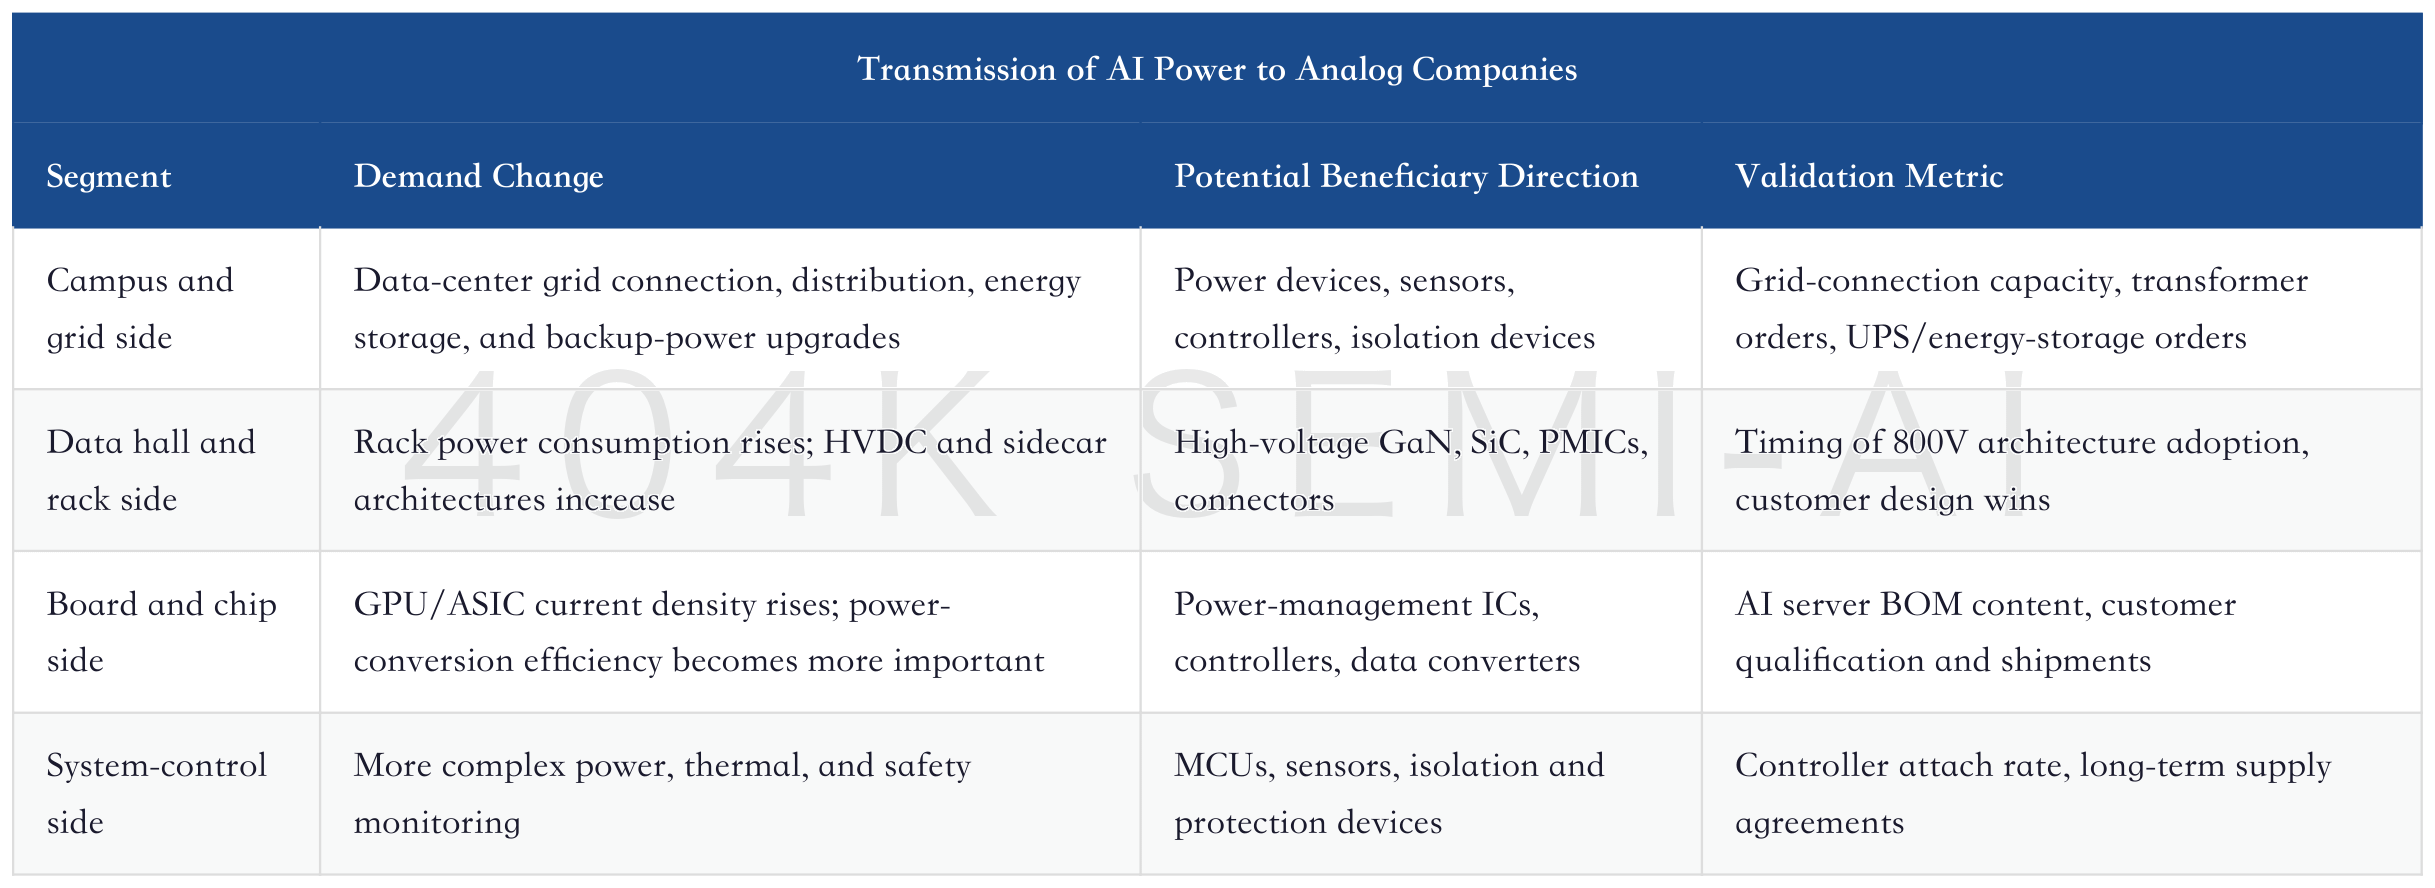
The investment implication of this chain is that AI does not only buy GPUs; it also buys power efficiency. Analog semiconductor companies were previously outside the center of the AI trade, but they are now entering the field of view as “second-order AI capex beneficiaries.” Valuation rerating may not be immediately realized through revenue mix, but as long as 800V, GaN/SiC, and data-center power orders keep appearing, the market will continue to assign higher narrative weight to relevant companies.
VIII. Valuation: Buy Cyclical Upside or Valuation Convergence?
Analog semiconductor valuations now fall into two types of trades: U.S. leaders are cash-flow confirmation trades, while European and Japanese leaders are discount-convergence trades. UBS’s report focuses on Texas Instruments, but Bernstein’s global analog valuation framework is a reminder that the analog industry is not limited to U.S. companies. Over the past 10 years, analog-company P/E multiples have been highly correlated with margins, ROIC, capital returns, and EPS growth. As long as the industry enters an upcycle, valuation gaps have room to narrow.
Among U.S. companies, Texas Instruments and Analog Devices already trade at higher valuations. Texas Instruments is justified by the FCF inflection and pricing execution. Analog Devices is justified by a high-quality industrial mix. Microchip Technology, ON Semiconductor, and NXP look cheaper, but lower valuation comes with a higher burden of proof: inventory, automotive, legacy-business exits, or insufficient data-center exposure.
Among European and Japanese companies, Infineon, Renesas, and STM have long carried valuation discounts. The market worries about automotive exposure, the power cycle, European macro, and insufficient capital returns. But if the industrial recovery continues, AI power content rises, and management teams improve shareholder returns or margin targets, those discounts can narrow. Bernstein explicitly noted that Infineon and Renesas have potential rerating opportunities in dividends/buybacks, margin improvement, and AI power/memory-interface ICs.
This creates two trading paths. The first is to buy certainty, such as Texas Instruments: expensive, but with simultaneous validation from pricing, inventory, and FCF. The second is to buy discount convergence: cheaper, but it requires margins, capital returns, and end demand to prove out at the same time. Which is better depends on investors’ confidence in the macro and industrial cycle.
Semiconductor Deep Dive: Memory-Tax Spillover, and How SanDisk, Applied Materials, and ON Semiconductor’s Acquisition of Synaptics Revalue AI Hardware
At the current point, a more reasonable portfolio approach is layered ownership. Core positions can be placed in companies such as Texas Instruments and Analog Devices, which are better positioned to benefit from industrial recovery and pricing execution. Beta positions can focus on Microchip Technology and ON Semiconductor. Valuation-convergence positions can focus on Infineon, Renesas, and STM. The benefit of this approach is that the portfolio does not need to place all bets on an automotive rebound, nor assign all valuation upside to the long-term AI power narrative.
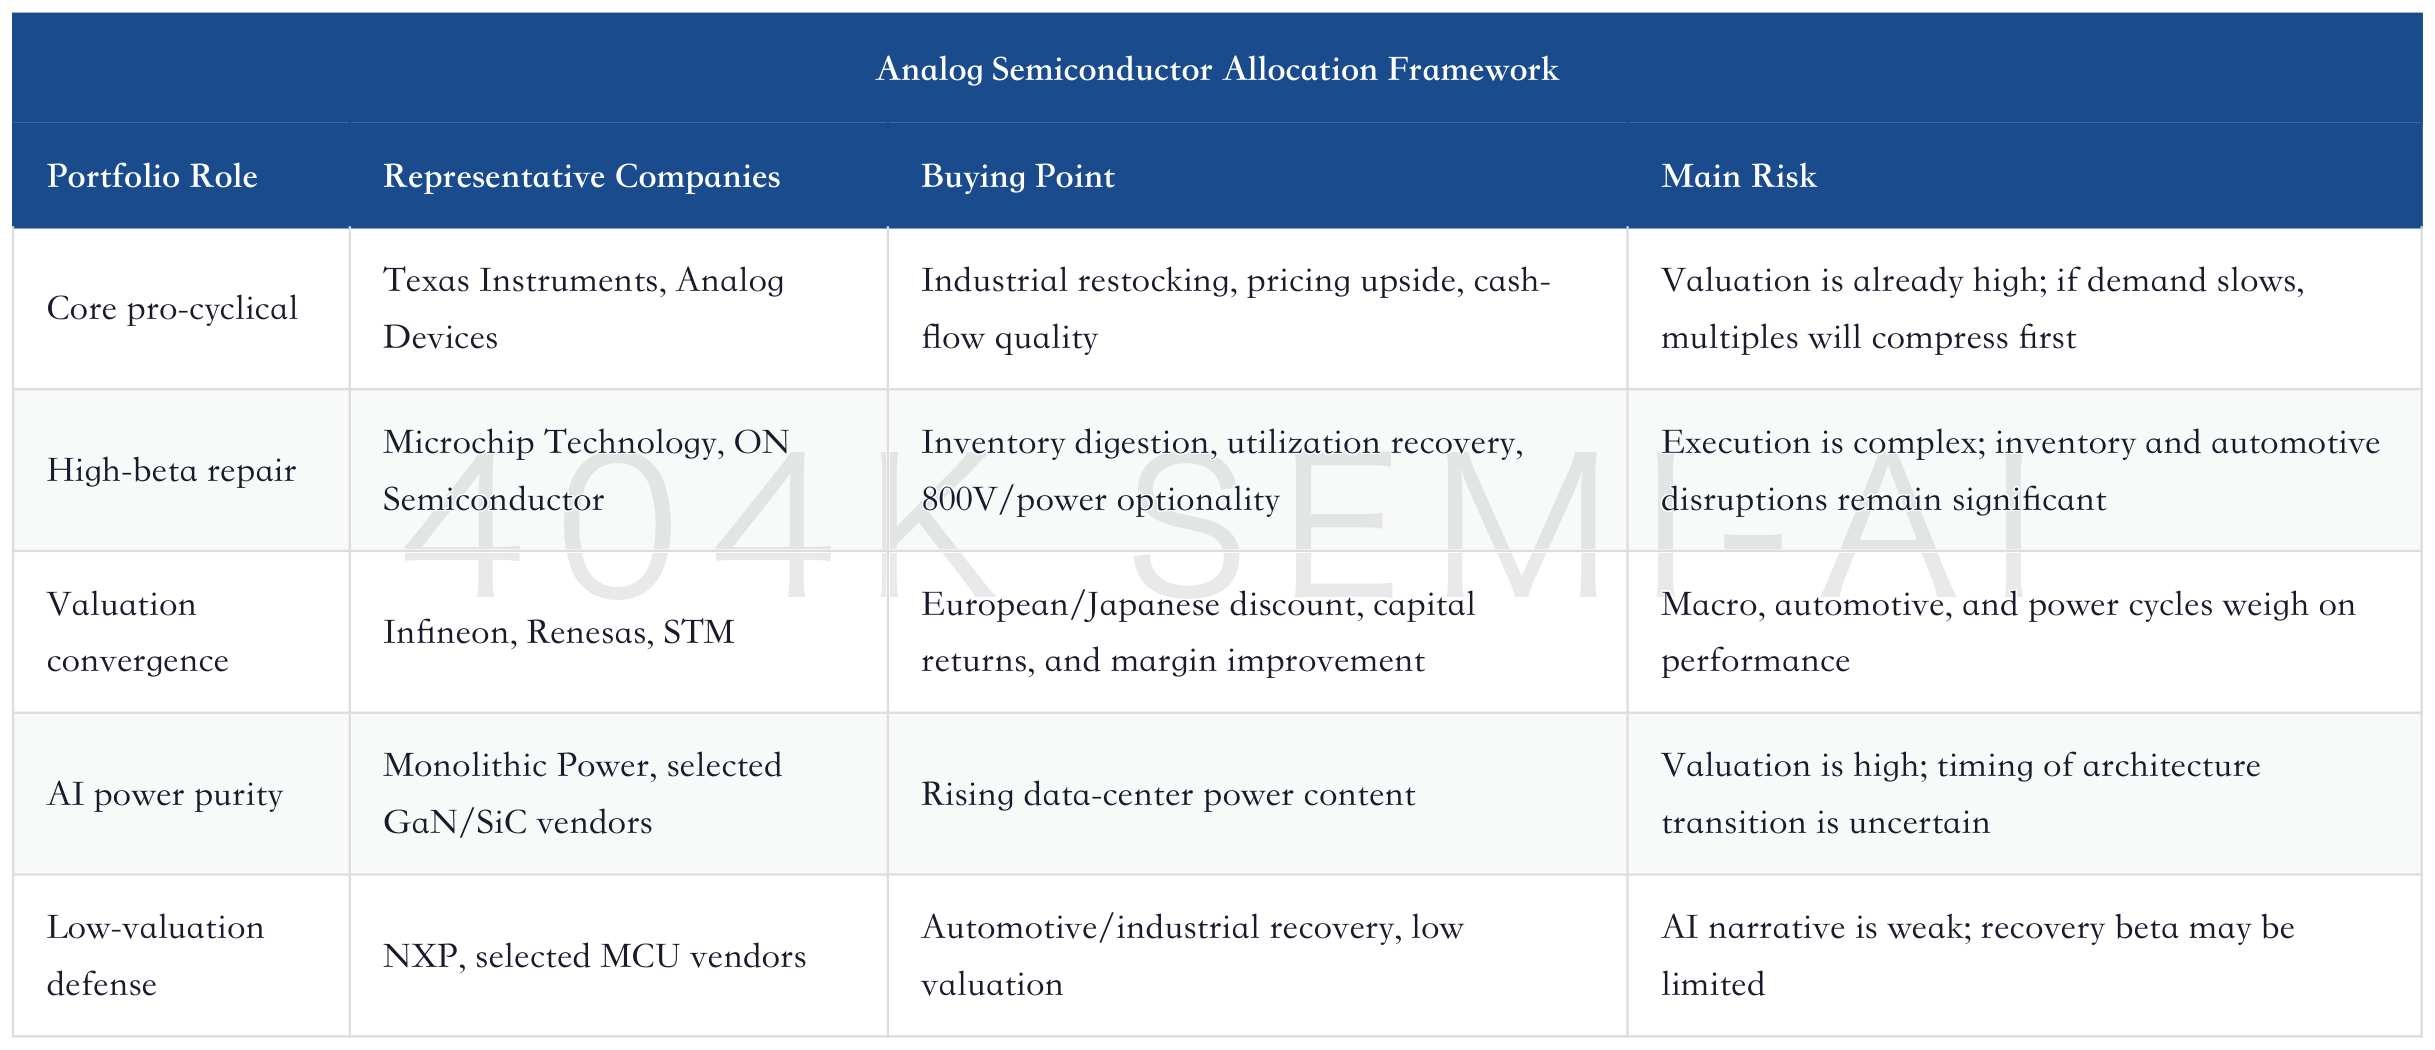
The underlying judgment behind this framework is that the analog semiconductor industry itself is entering an upcycle, but company share prices will not rise in sync. The market will first reward companies that can convert cyclical recovery into cash flow, then reward companies that can turn AI power into a new growth curve, and only later reward simple low-valuation repair.
Valuation switching usually has three steps. The first step is to buy confirmation, because when early-cycle signals first appear, investors are still unsure whether end demand is real. Capital will first go to companies with the clearest data, the best asset quality, and the most direct cash-flow path. Currently, that means Texas Instruments and Analog Devices. Texas Instruments’ confirmation comes from pricing, finished-goods inventory, and the free-cash-flow inflection. Analog Devices’ confirmation comes from high-end industrial exposure and margin quality.
The second step is to buy margin repair. Once the industry is confirmed to be entering an upcycle, the market will start looking for companies that were hurt more in the earlier phase and have steeper subsequent recovery potential. Microchip Technology and ON Semiconductor sit in this layer. They share higher beta and more problems. Microchip Technology needs to turn inventory and utilization repair into gross margin. ON Semiconductor needs to explain industrial and automotive recovery, SiC/GaN, and legacy-business exits at the same time. At this stage, cheap valuation becomes an advantage, provided operating data no longer deteriorates.
The third step is to buy valuation convergence. European and Japanese analog/power leaders have long traded at discounts, due to high automotive exposure, weak European macro, insufficient capital returns, and limited market confidence in management execution. If the industrial cycle continues to improve, AI power orders begin to spread, and management teams use buybacks, dividends, or margin targets to improve capital returns, the valuation discounts of Infineon, Renesas, and STM could narrow. This type of trade usually does not start earliest, but once confirmed, the beta can be meaningful.
These three steps are not a fixed sequence, nor are they a mechanical rotation instruction for investors. They are more like a checklist: when early-cycle evidence is still limited, the portfolio should lean toward confirmation; when revenue and pricing begin to show up in financial statements, the portfolio can add repair beta; when industry strength is fully confirmed, low-valuation and discounted assets become more likely to outperform. At the current point, UBS’s data moves the industry from step one toward the latter half of step one. Texas Instruments remains the clearest expression, while the second tier can already be watched.
The biggest valuation trap is treating “high-quality companies are expensive” and “low-quality companies are cheap” as the same kind of opportunity. After Texas Instruments’ price target was raised to $350, it is indeed not cheap, but it is expensive because the cash-flow path is clearer. Microchip Technology, ON Semiconductor, and European companies are relatively cheap, but that cheapness comes from uncertainty around inventory, automotive, business mix, and execution. Portfolios need to bind valuation to burden of proof, not simply compare high and low multiples.
If subsequent industrial PMI, distribution inventory, and price indices continue to support UBS’s judgment, portfolios can expand from Texas Instruments and Analog Devices into beta assets such as Microchip Technology, ON Semiconductor, and Infineon. If the data begins to diverge, portfolios should return to the companies with the clearest cash flow, or even reduce overall analog semiconductor exposure. Analog semiconductor rerating is not a one-time conclusion; it is a process that must be repeatedly tested every quarter through orders, pricing, inventory, and free cash flow.
IX. Where It Is Easiest to Be Wrong
The biggest risk in this round of analog-chip re-rating is misreading inventory replenishment as broad end-demand prosperity. Purchasing managers placing orders earlier, increasing safety stock, and signing long-term supply agreements can all move orders and prices first. But if end demand does not follow, replenishment can turn into another round of channel inventory pressure after 2-3 quarters.
The first risk is automotive. In UBS’s 2Q data, automotive demand expectations deteriorated more noticeably. Slowing EV growth, inventory adjustments at traditional automakers, and competition in SiC and power devices will all affect companies such as onsemi, NXP, STMicroelectronics, and Infineon. If automotive remains weak, industrial and data centers will need to shoulder more of the growth burden.
The second risk is pricing. Current price increases are coming from supply certainty, lead times, and capacity reallocation at mature nodes. If customers successfully execute second-source strategies, distributor inventory rises again, or mature-node foundry capacity is released, prices may weaken before orders do. Profit sensitivity in analog chips is highly price-sensitive, especially for companies still carrying heavy inventory.
The third risk is inventory. Texas Instruments’ high finished-goods inventory is now viewed as a delivery advantage, but if demand turns down, it will again become an inventory burden that worries investors. Microchip Technology’s and onsemi’s die banks require even more continuous validation. Once inventory days stop falling while production starts rising again, the market will suspect companies are pulling the recovery forward onto the balance sheet.
The fourth risk is the pace of 800V adoption. The long-term direction for AI power is clear, but adoption of 800V, GaN, SiC, SST, sidecar, and rack-level power architectures will not be linear. Architecture delays do not mean demand disappears, but they will affect the near-term valuation the market assigns to related companies. Option-like assets such as onsemi are more exposed.
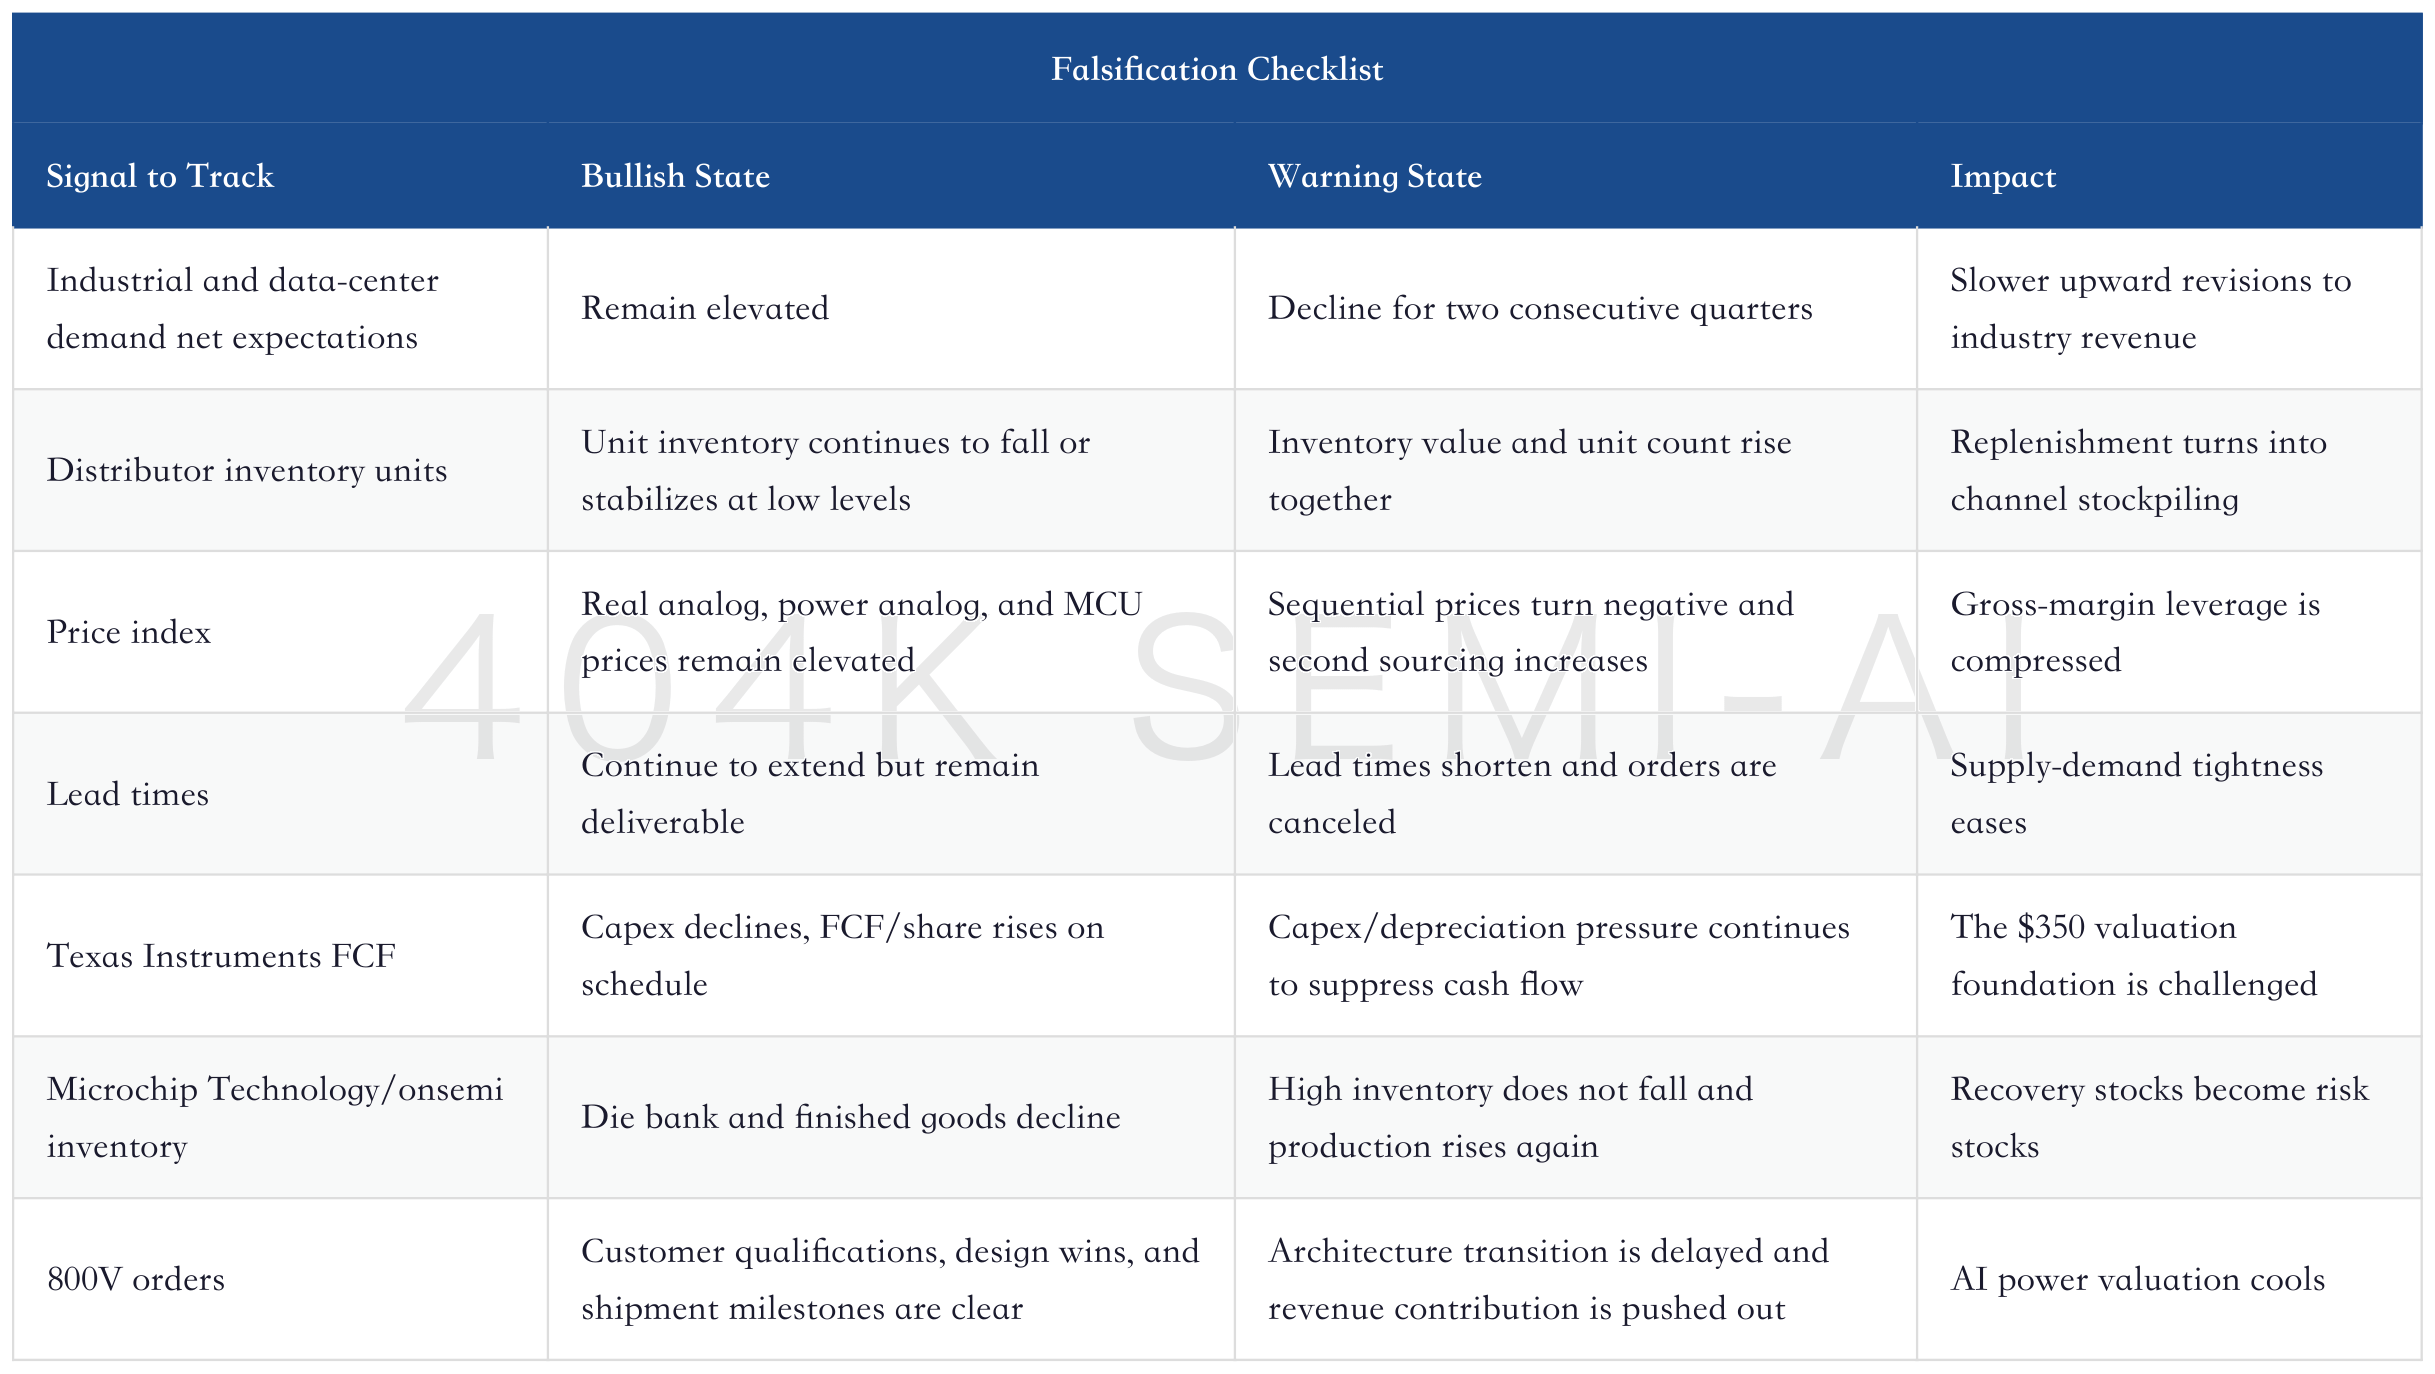
This falsification checklist is more important than looking at stock prices alone. Analog chips are a slow-variable industry, with time lags among orders, inventory, pricing, lead times, utilization, and cash flow. The real buying points usually appear when these variables improve simultaneously but the income statement has not yet fully reflected them; the real risks also appear first when these variables diverge.
Another easily overlooked issue: UBS’s data are not company guidance and cannot be directly equated with revenue forecasts. Buyer surveys reflect purchasing intent and supply perception; distributor catalog data reflect channel availability and pricing; balance sheets reflect company inventory and production cadence. Together, the three have strong leading value, but any one of them in isolation can mislead investors.
Buyer surveys can be affected by sentiment. Customers have just lived through a shortage cycle, and their memory of tight supply can make them more inclined to lock in supply early. If macro uncertainty, tariff disruptions, or transportation issues rise, procurement departments may also temporarily increase safety stock. This behavior can make order expectations look very strong, but it does not necessarily mean end sales are rising in parallel. Therefore, demand net expectations need to be assessed together with distributor inventory units, prices, and company revenue, not by looking only at survey curves.
Distributor catalog data also have blind spots. Distribution channels cover a large number of catalog parts and are good at capturing marginal changes in industrial, general-purpose analog, MCU, and power devices, but they are not equivalent to all direct-sales customers, major-customer long-term supply agreements, or full coverage of more customized high-end products. Texas Instruments, Analog Devices, Microchip Technology, and onsemi have different exposures to direct sales and distribution, so channel data also have different explanatory power for each company. They can tell investors that supply and demand are tightening, but they cannot replace company-level judgment on order quality.
Inventory days require even more segmentation. High headline inventory days are not necessarily bad. High finished goods can be a supply advantage when demand recovers; a high die bank often means work-in-process and internal inventory still need to be digested; high distributor inventory can suppress pricing. Texas Instruments’ high finished goods and Microchip Technology’s and onsemi’s die banks should not be placed in the same risk bucket. One is delivery ammunition in an upcycle; the other is closer to an internal burden that must be addressed before margin repair.
Price indices also cannot be directly extrapolated into gross margin. Distributor prices remaining high indicates the channel is not clearing inventory through steep discounts, but company gross margins will also be affected by utilization, product mix, depreciation, long-term contracts, production location, and FX. Strong pricing at Texas Instruments does not automatically mean short-term gross margin will immediately jump; it also needs capex and depreciation pressure to ease at the margin. Analog Devices’ more moderate price leverage does not mean quality is deteriorating, because its margins are already high and its customer structure is more stable.
Therefore, the best use of this report is not to linearly extrapolate every UBS number, but to treat it as a cycle dashboard. Demand expectations show direction, inventory units show channel health, price indices show supply-demand strength, lead times show customer anxiety, and balance sheets show whether companies can convert demand into profit and cash flow. As long as these indicators move in the same direction, the analog-chip re-rating has a foundation. Once more than two begin to diverge, investors should reduce their assumptions for cycle slope.
This is also why portfolio ranking must remain dynamic. Current evidence supports buying higher-conviction assets such as Texas Instruments and Analog Devices first, while monitoring the recovery progress at Microchip Technology and onsemi. If subsequent data prove that replenishment is flowing into revenue and margins, weightings in higher-beta assets can be increased. If the data remain limited to procurement sentiment, the portfolio should return to cash-flow and margin certainty. The analog-chip opportunity is not a single-point bet, but a process of adjusting positions along the strength of evidence.
X. What to Watch Over the Next Four Quarters
Over the next four quarters, analog chips need to validate a transition from “prices and orders” to “revenue, gross margin, and cash flow.” Buyer surveys and distributor inventory have already provided early-cycle signals; the next step must show up in company financials.
First, watch Texas Instruments’ revenue and FCF. If 2Q and 3Q continue to show recovery in industrial and embedded processing, and lower capex allows free cash flow to improve along UBS’s projected path, Texas Instruments’ valuation has reason to keep rolling upward. If revenue is revised up but FCF does not move, it means depreciation, inventory, or gross margin is still a drag.
Second, watch Analog Devices’ industrial orders and margins. Analog Devices does not need to tell many new stories. It needs to prove that high-quality industrial demand remains intact, and that data centers and high-performance power are not just small-percentage narratives. As long as margins remain strong, Analog Devices will continue to enjoy a quality premium.
Third, watch Microchip Technology’s inventory plan and utilization. Microchip Technology’s upside comes from gross-margin recovery. If inventory charges, low utilization, and the die bank continue to drag, the market will not give it a higher multiple just because orders improve.
Fourth, watch onsemi’s AI power and automotive businesses. onsemi has the greatest valuation leverage, but also the most variables. Its September analyst day, 800V-related customer progress, SiC/GaN orders, automotive demand, and exits from legacy businesses will determine whether it can move from a “recovery stock” to an “AI power option stock.”
Fifth, watch capital returns at European and Japanese companies. For the valuation discounts at Infineon, Renesas, and STMicroelectronics to narrow, industry recovery alone is not enough; they also need margin targets, shareholder returns, and AI power/industrial structure upgrades. If management teams still talk only about cycle recovery and not cash returns, the discount will remain.
The final judgment can be compressed into one sentence: analog chips have entered an investable stage of the upcycle, but this is not an indiscriminate industry-wide trade. The current top priority is Texas Instruments, because it simultaneously satisfies industrial recovery, price execution, inventory delivery, and an FCF inflection; the second layer is Analog Devices’ quality, Microchip Technology’s recovery, and onsemi’s AI power option; only the third layer is valuation convergence in Europe and Japan.
If this rally plays out correctly, the market will first broaden from “AI only buys accelerators” to “AI power and industrial automation also need to be re-rated,” and then from “analog-chip inventories have bottomed” to “cash flow and capital returns are improving.” If it goes wrong, the earliest problems will appear in the four hard indicators of orders, lead times, prices, and inventory.
Breaking the next year into three scenarios makes the investment actions clearer. The base case is a moderate industrial upturn, continued diffusion of data-center power, and automotive remaining a drag but no longer worsening. In this scenario, Texas Instruments deserves the core position most, because its price execution, finished-goods inventory, and capex decline can all be realized at the same time. Analog Devices is suitable as a high-quality cyclical asset. Microchip Technology and onsemi are higher-beta watch positions, with weights to be increased only after inventory and margin evidence becomes clearer.
The bullish scenario is sustained broadening of industrial orders, continued lead-time extension, customer acceptance of price increases, and AI data-center power moving from thematic investment into real orders. In this scenario, the analog-chip rally would broaden from Texas Instruments to a wider power and MCU chain. Microchip Technology’s utilization recovery would be repriced by the market, onsemi’s SiC/GaN and 800V options would become more valuable, and Infineon, Renesas, and STMicroelectronics would also have room for valuation-discount convergence. The portfolio can gradually shift from “core conviction” to “recovery beta + AI power options.”
The bearish scenario is that buyer surveys turn into early pull-ins, distributor inventory rises again, price indices weaken, automotive continues to drag, and Texas Instruments’ free cash flow is again held down by capex and depreciation. In this scenario, analog chips would revert to ordinary cyclicals. High-valuation companies would see multiples compressed first, inventory-heavy companies would see margins pressured, and AI power options would cool because of architecture delays and order uncertainty. The portfolio should contract back to companies with the highest cash-flow certainty, or even wait for the next round of signals.
The dividing line among these three scenarios is not macro slogans, but several very specific operating indicators. As long as distributor inventory units continue to fall, prices hold, lead times do not shorten quickly, company inventory does not rebuild, and Texas Instruments’ free cash flow is released on schedule, the base case can hold. Only if these indicators strengthen simultaneously does the bullish scenario have a foundation. If more than two reverse, the market will begin to question whether this is merely a short replenishment cycle.
This also means the investment conclusion of this report will not be “buy all analog chips.” Analog chips are improving, but the improvement path has a sequence: first supply capability and pricing power, then gross-margin and inventory repair, then long-term AI power content, and only finally low-valuation convergence. Investors need to track evidence along this path, rather than raise valuations for all companies together just because one industry cycle indicator improves.
Over the longer cycle, the value of analog chips will increasingly move toward the “intersection of industrial and AI infrastructure.” AI data centers need power, thermal management, sensing, isolation, control, and reliable supply; industrial automation needs long lifecycles, high reliability, and large volumes of mature-process devices. The differences among Texas Instruments, Analog Devices, Microchip Technology, onsemi, Infineon, Renesas, and STMicroelectronics lie in where each stands along this intersection. The companies that can capture both industrial recovery and AI power upgrades will earn higher valuations.
XI. Investment Conclusion
Analog chips now deserve to be written as a standalone second-order AI hardware theme. They are not as direct as GPUs, nor as tight as HBM and advanced packaging, but they connect industrial recovery, data-center power, mature-node supply and demand, and a cash-flow inflection. UBS raising its Texas Instruments target price is essentially pricing these variables together.
For portfolios, the better approach now is layering, not chasing a single label. The first layer is Texas Instruments, where the trade is industrial restocking and an FCF inflection. The second layer is Analog Devices, Microchip Technology, and onsemi, corresponding respectively to quality, recovery, and optionality. The third layer is Infineon, Renesas, and STMicroelectronics, where the trade is convergence in global analog valuation discounts. The fourth layer is Monolithic Power, GaN/SiC, connectors, and other AI power-chain names, where the trade is architecture upgrade.
This layering has one practical benefit: it avoids mixing cycle, quality, and optionality into one trade. Texas Instruments is suitable as a core position because the evidence is the most direct; Analog Devices is suitable as a quality position because its customers and margins are steadier; Microchip Technology and onsemi are suitable as higher-beta positions because the repair space is larger but the variables are more numerous; European and Japanese leaders are suitable as discount-convergence positions because they need industry conditions and capital returns to improve together. Stop-loss points also differ by position type, and they cannot be managed with the same valuation multiple.
For Texas Instruments, the real stop-loss point is not near-term valuation appearing expensive, but failure to deliver free cash flow. If capex does not come down, revenue recovery is insufficient, and inventory turns from a delivery advantage back into a burden, the logic behind the target-price increase will weaken. For Analog Devices, the stop-loss point is a softening in high-quality industrial demand and margins. For Microchip Technology, the key is inventory planning and utilization; for onsemi, the key is whether automotive, SiC/GaN, and AI power orders can all validate the thesis. For Infineon, Renesas, and STMicroelectronics, the key is that the discount cannot rely only on industry recovery; investors must see improvements in capital returns and margins.
Therefore, the analog-chip theme is best added to through “evidence upgrades,” not by chasing a good story. In the early stage, use Texas Instruments and Analog Devices to build confirmation. In the middle stage, expand weights into Microchip Technology, onsemi, and European/Japanese leaders based on inventory, pricing, and margins. Over the long run, use progress in AI power architecture to screen for companies that can genuinely gain new content. This cadence is steadier than simply betting on industry beta, and it is more consistent with the signal in UBS’s latest data.
More broadly, the investment challenge in analog chips is that, unlike leading-edge process nodes or memory, there is no single highly transparent price. One company may sell data converters, power management, amplifiers, MCUs, isolation devices, sensors, and discretes at the same time. Within the same end market, industrial, automotive, data-center, and consumer-electronics cycles also differ. If investors summarize everything as “analog-chip demand is improving,” they can easily mix strong categories with weak ones, strong customers with weak ones, and strong pricing with weak pricing.
Texas Instruments’ burden of proof is to turn “broad coverage” into “cash flow.” The company has many part numbers, many customers, and strong internal manufacturing, giving it a natural advantage when industrial demand recovers. But the market ultimately looks at free cash flow. If revenue recovery only shows up on the income statement while capex and depreciation continue to weigh on FCF, valuation expansion will be capped. Conversely, once FCF improvement is confirmed, Texas Instruments’ high valuation becomes a justified premium rather than a cycle-top risk.
Analog Devices’ burden of proof is to maintain the scarcity value of a high-quality industrial asset. It does not need to prove a capex inflection like Texas Instruments, nor does it need to prove AI power optionality like onsemi. But it does need to show that industrial, aerospace and defense, test and measurement, and high-performance analog customers are still willing to pay for quality. If margins are stable and order quality is good, Analog Devices can continue to enjoy a quality premium. If industrial demand is only short-cycle restocking, its valuation upside will be limited.
Microchip Technology’s burden of proof is to rewrite “inventory pressure” into “margin repair.” It has exposure to industrial, aerospace and defense, data centers, and MCUs, as well as stronger cyclical leverage. But die-bank and utilization issues mean it cannot rely on demand improvement alone. Investors need to see inventory plans advance, gross margin recover, and orders improve together. If those three developments occur in sequence, Microchip Technology can move from a restocking trade into a margin-repair trade. If orders improve but inventory does not decline, the upside will be discounted.
onsemi’s burden of proof is the most complex. It has traditional industrial and automotive recovery, as well as multiple variables including SiC, GaN, 800V data-center power, and image sensors. The advantage is abundant optionality; the drawback is that each variable can drag on the headline. For onsemi, the most important point is not to tell every story, but to prove that incremental AI power and power-device demand can offset the noise from automotive, exits from legacy businesses, and pricing divergence.
For European and Japanese companies, the burden of proof is capital returns and margins. Infineon, Renesas, and STMicroelectronics do not lack industrial, automotive, and power-semiconductor exposure, nor do they lack long-term technology positioning. The market has assigned them discounts for a long time because investors worry about cyclicality, capital allocation, and the European macro backdrop. If management teams can convert industry recovery into margin improvement and shareholder returns, the discounts can narrow. If they only follow the industry recovery, valuation gaps may persist for a long time.
This burden-of-proof framework determines the order of adding exposure. First buy companies that already have evidence, then buy companies where evidence is forming, and finally buy companies where evidence still requires patience but valuations are cheap. The current UBS report makes the first layer of evidence clearer and gives the second and third layers more monitoring value, but it does not yet justify an indiscriminate sector-wide re-rating. This restraint is the most important point to retain from the report.
Finally, portfolios need room for rebalancing. Once an analog upcycle is confirmed, the market will quickly spread from Texas Instruments to lower-valuation peers. But if confirmation fails, the drawdown will also begin with the higher-beta names. The steadier approach is to use Texas Instruments as the cycle-confirmation anchor, Analog Devices as the quality anchor, Microchip Technology and onsemi as higher-beta observations, and European and Japanese leaders as discount-convergence candidates. Each layer should be triggered by different evidence, not bought on the same day using the same conclusion.
This framework also explains why UBS raised the target price on Texas Instruments rather than re-rating the entire analog industry. Industry signals have improved, but company-level delivery paths differ. Texas Instruments has the shortest path to delivery, Analog Devices has the steadiest quality, Microchip Technology and onsemi have greater upside beta, and discount convergence for Infineon, Renesas, and STMicroelectronics requires more evidence on governance and capital returns. Making these differences clear is more valuable for investment than simply saying “analog chips are recovering.”
In the short term, the easiest trade for the market is Texas Instruments’ target-price increase to $350. In the medium term, the real tests are whether industrial demand is continuous, distribution inventory keeps falling, pricing remains resilient, and capex converts into free cash flow. If all four hold at the same time, analog chips will move from the periphery of the AI hardware trade into the core industrial semiconductor asset pool.
The most valuable aspect of this report is that it turns “recovery” into trackable hard indicators. Demand expectations, pricing, lead times, inventory, and FCF are no longer scattered stories. They now point in the same direction: the industrial upcycle has begun, the analog-chip re-rating window has opened, but the winners will concentrate among companies that can deliver supply capability, pricing power, and cash flow at the same time.
Analog Semiconductors Deep Dive: UBS Raises Texas Instruments Target Price to $350; How the Industrial Upcycle Re-rates the Analog Leader
目录
Too Long; Didn’t Read
1. What This UBS Report Really Changes
2. Why the Industrial Cycle Matters More Than Autos
III. What Distribution Inventory Is Saying: Units Are Down, Prices Have Not Fallen
IV. The Other Side of the Inventory Cycle: Whose Inventory Is Good, Whose Inventory Is Dangerous
V. Why Texas Instruments Became UBS’s Top Pick
VI. Analog Devices, Microchip Technology, ON Semiconductor: Who Is in the Second Tier
VII. Why 800V and AI Power Make Analog Valuations More Expensive
VIII. Valuation: Buy Cyclical Upside or Valuation Convergence?
IX. Where It Is Easiest to Be Wrong
X. What to Watch Over the Next Four Quarters
XI. Investment Conclusion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Analog semiconductors are moving from the tail end of destocking into the first half of an industrial restocking cycle. UBS raised its target price for Texas Instruments to $350, backed by a set of signals turning in sync: buy-side demand, distribution inventory, lead times, pricing, and free cash flow are all starting to point to a new industrial upcycle, while autos remain slow and data centers provide a second growth curve.
Too Long; Didn’t Read
Industrial restocking has already started. In UBS’s latest analog semiconductor update, order expectations from both distributors and direct buyers remain elevated. Improvement is no longer just long-dated optimism; it is already showing up in near-term orders, inventory, lead times, and pricing. Compared with the prior “recovery still on the way” phase, the change now is that industrial and data centers remain in high-momentum territory, inventories are starting to fall below target, lead times are extending again, and prices continue to rise.
In this cycle, buy Texas Instruments first. UBS raised its target price for Texas Instruments (TXN) from $295 to $350, lifting the valuation basis from 22x EV/FCF to 26x and applying it to average 2027/2028 free cash flow of US$12.6B. The Texas Instruments thesis sits simultaneously on price increases, finished-goods inventory, pricing execution, and the capex downcycle inflection, enabling the company to convert revenue elasticity into free cash flow more quickly as restocking begins.
Analog Devices has high certainty but slightly less torque. Analog Devices’ strengths lie in industrial, aerospace and defense, test and measurement, and high-end data converters. Its margins and customer quality remain among the best assets in analog semiconductors. The issue is that valuation is already not cheap, pricing elasticity is less pronounced than at Texas Instruments, and its inventory position is more conservative. It therefore looks more like a high-quality cyclical asset, but lacks the sharpest beta in the current restocking trade.
Microchip Technology and onsemi offer high upside but also high risk. Microchip’s exposure to industrial, data centers, aerospace and defense, and MCUs allows it to benefit from restocking, but its die bank remains heavy and it still needs demand recovery to absorb inventory and utilization headwinds. onsemi’s industrial and automotive businesses are indeed recovering, while 800V, SiC, GaN, and data-center power give it upside optionality. But UBS data show that some of its pricing remains under pressure and unit inventory is still building, leaving it with a heavier burden of proof than Texas Instruments.
Data centers are changing the valuation narrative for analog semiconductors. Traditional analog semiconductors move with industrial, automotive, and consumer electronics cycles, and valuations are usually treated as macro-cycle assets. 800V DC, AI rack power, GaN/SiC, connectors, and the power tree are pulling Texas Instruments, onsemi, Analog Devices, Infineon, Renesas, Monolithic Power, and others into the AI infrastructure diffusion chain. The market is starting to reprice the dual variables of “industrial recovery + rising AI power content.”
The risk is that restocking turns into a false upcycle. The four numbers to watch most closely are whether industrial and data-center net demand expectations remain elevated, whether lead times continue to extend, whether distribution unit inventories continue to decline, and whether Texas Instruments’ free cash flow is delivered on a 2027 cadence. If autos continue to decline, customers only pull orders forward without real consumption, or price pass-through is capped by second-source pressure, this analog semiconductor re-rating will shift from earnings upgrades to valuation overreach.
1. What This UBS Report Really Changes
The analog semiconductor debate has shifted from “is there a recovery?” to “who can capture pricing and cash flow in the early upcycle?” Over the past several quarters, the market has known that the analog semiconductor inventory cycle was approaching a bottom. But the debate was clear: has industrial demand really returned, are autos still a drag, and is customer restocking merely early ordering driven by tariff and supply anxiety? UBS’s 2Q26 update gives a clearer answer: the recovery has broadened from inventory-data improvement to a synchronized turn in demand, pricing, lead times, and corporate cash flow.
The evidence chain in this report has three layers. The first is purchaser surveys. UBS Evidence Lab’s semiconductor purchaser survey shows that the net share expecting demand to increase over the next six months reached 89%, the net share reporting demand increases over the past six months reached 87%, the net share reporting price increases reached 84%, and the net share expecting further price increases over the next six months reached 76%. These figures are already beyond ordinary marginal improvement and look closer to continuous diffusion in an early cycle.
The second layer is distribution inventory monitoring. UBS tracks more than 100 global distributors, around US$14B of inventory, and 48B catalog components. By 2Q26, unit inventories in true analog, power analog, and MCUs had each declined, while price indices remained elevated. True analog ASP had reached 141 versus 1Q24, power analog reached 136, and MCUs reached 120. Falling unit inventory with no price decline suggests the supply-demand relationship is shifting from “whoever has more inventory discounts” to “whoever can supply defends price.”
The third layer is company balance sheets. Analog companies’ 1Q26 revenue rose 3% quarter over quarter, while production fell 3% quarter over quarter, and total industry inventory was broadly flat. This combination is important: if the revenue rebound were coming from companies actively pushing supply into the channel, inventory should be rising with it. Revenue is now recovering while production remains restrained, indicating companies have not yet gone fully offensive. As long as orders continue to improve, capacity utilization, gross margin, and cash flow all have upside elasticity.
The main thread here is not a mindless industrywide upcycle. UBS repeatedly emphasizes that demand improvement is concentrated in industrial and data centers, while autos remain mixed and consumer and communications have not become new main drivers. What the market really wants to buy is the overlap of industrial restocking, AI data-center power diffusion, rising pricing, and improving free cash flow.
This is also why UBS ultimately puts Texas Instruments first. Many companies in analog semiconductors have recovery exposure, but only a few simultaneously offer pricing execution, supply capability, inventory position, utilization recovery, and capex decline. Texas Instruments now stands at that intersection.
The implication of this table is straightforward: analog semiconductors are no longer just “done destocking.” Customers are starting to worry about supply, are willing to order early, are accepting price increases, and distribution inventories are not rebuilding in parallel. The market often grants valuation first at this stage, then waits for revenue and gross margin confirmation.
What makes this data more important is that three cycles are aligned in the same chart for the first time. The demand cycle is seen in orders and purchasing expectations; the pricing cycle is seen in whether customers accept price increases; and the cash-flow cycle is seen in whether vendors control production and capex while revenue recovers. Over the past year, the market could already see inventory digestion, but it could not be sure whether this was merely “low-level stabilization.” The combination UBS now presents is closer to “reacceleration after a low.” That changes how analog semiconductors are priced.
The demand cycle determines the revenue direction. Analog semiconductors are not driven by a single large customer order like GPUs, nor are they highly standardized like memory. Their revenue recovery often comes from simultaneous changes across many customers, many end markets, and many small part numbers. This is where purchaser surveys matter: when distributors and direct buyers turn at the same time, it means demand is not just one company’s order recovery; customer procurement teams have begun changing inventory strategy.
The pricing cycle determines the margin slope. What analog companies fear most is “revenue has returned, but only because discounts brought it back.” If demand recovery is stimulated by price cuts, revenue upgrades may not convert into earnings upgrades. What UBS sees this time is that the share reporting price increases remains high, customers are still worried about supply, and distribution unit inventories are falling while price indices have not dropped. This combination indicates that the industry still has some pricing power, at least in industrial, data-center power, and some high-reliability categories, where customers care more about delivery than haggling.
The cash-flow cycle determines the valuation multiple. The biggest controversy around Texas Instruments in recent years has not been company quality, but heavy capex, with the market worried that free cash flow would be consumed by fab investment. Now, if demand, pricing, and lead times are all moving upward while capex starts to enter a downward slope, investors will re-evaluate the company: it is no longer just a cyclical revenue recovery, but a conversion of prior heavy capital investment into future cash-flow leverage. This is the real meaning of UBS’s target-price increase.
So this report is not simply telling investors that “analog semiconductor conditions are getting better.” A more accurate reading is: industrial restocking provides the revenue base, rising prices provide earnings elasticity, Texas Instruments’ capex inflection provides the reason for multiple expansion, and AI data-center power adds a second layer of medium-term optionality to the story. Taken separately, none of these four variables feels new; taken together, they are the core of this analog semiconductor re-rating.
2. Why the Industrial Cycle Matters More Than Autos
Industrial is the main engine of this analog semiconductor recovery, while autos have not yet re-emerged as an industrywide accelerator. Historically, the most comfortable analog semiconductor rallies usually come when industrial and autos restock at the same time. This time, however, UBS data show autos remain mixed, while industrial and data centers are the clearer sources of incremental demand.
Industrial demand matters because it is naturally suited to analog semiconductors. Factory automation, energy, aerospace and defense, test and measurement, grid equipment, instrumentation, robotics, and data-center power all require large volumes of high-reliability, long-lifecycle, fragmented analog components. It is not highly standardized like smartphones or PCs, nor concentrated in a few high-priced chips like GPUs. Once industrial restocking starts, it spreads layer by layer across distributors, OEMs, foundries, EMS providers, and module makers, with pricing and lead times often moving ahead of end demand.
In UBS’s purchaser survey, industrial and data-center demand expectations remain elevated, while autos are declining more noticeably. This structure explains why Texas Instruments, Analog Devices, and Microchip Technology are better positioned than pure automotive or single EV-chain companies. Industrial customers do not only look at short-term pricing; they care more about supply certainty. Semiconductors often account for a small share of many industrial and automotive BOMs, but the cost of line stoppages is extremely high. Once customers worry that lead times are lengthening, procurement teams place orders early, sign long-term supply agreements, and raise safety stock.
This is also the basis for price pass-through. In the report, 51% of purchasers said they would pass semiconductor price increases on to downstream customers, while 38% said they would absorb the costs. This ratio shows that customers are indeed still under pressure, but price increases are no longer completely impossible to pass through. For analog semiconductor companies, as long as pricing can be defended, revenue recovery and utilization improvement will create greater gross-margin elasticity.
The difference between industrial and autos also appears in inventory reactions. The automotive chain experienced extreme shortages over the past several years, followed by slowing EV growth and component destocking, making customer behavior more prone to overshooting. Industrial-chain orders are more fragmented and product cycles are longer. The recovery may not be as sharp as an automotive rally, but its durability is better. By putting industrial at the center this time, UBS is reminding the market that the current analog semiconductor trade is a bet on broader industrial capex and the recovery of supply certainty, not merely an auto rebound.
This ranking also explains stock selection. Texas Instruments has the broadest industrial and general-purpose analog distribution exposure; Analog Devices has high quality in high-performance industrial and data converters; Microchip Technology has greater elasticity in industrial, aerospace and defense, and MCUs; while onsemi depends more on whether its automotive, power-device, and data-center power narrative can offset legacy business exits and inventory pressure.
III. What Distribution Inventory Is Saying: Units Are Down, Prices Have Not Fallen
The core signal from distribution inventory is “lower volume, stable pricing,” which is more valuable than a simple inventory decline. If inventory falls alongside a sharp price decline, that is just forced destocking. If inventory falls while prices remain high, it means downstream digestion capacity is recovering and the supply side is not rushing to exchange price for volume.
UBS distribution inventory data divides analog chips into three categories: true analog, power analog, and MCUs. True analog includes data converters, sensors, amplifiers, and RF. Power analog includes power management ICs, transistors, diodes, and similar products. MCUs are core components for industrial, automotive, and embedded control. The common feature in 2Q26 is that unit inventory declined while prices remained materially above 1Q24 levels.
These three inventory measures are useful because they come from actual catalog-part data in distribution channels, making them closer to real customer purchasing behavior than disclosures from any single company. Looking at true analog, power analog, and MCU scale, unit inventory, and pricing signals together makes it easier to distinguish between “inventory clearance through price cuts” and “inventory falling while prices hold.”
The most notable divergence in 2Q26 is Texas Instruments. UBS data show Texas Instruments had strong pricing performance across true analog, power analog, and MCUs. In the true analog price index, Texas Instruments has risen to 201; in the power analog price index, it has risen to 170; and in the MCU price index, it has reached 143. By contrast, onsemi’s price index remains weak in some power analog categories, while Microchip Technology’s MCU inventory still needs further digestion.
This does not mean Texas Instruments will never face competitive risk. Analog chips are not GPUs. There are many product categories, customer qualification cycles are long, but substitution is not impossible. The real difference is that in the early-cycle upswing, the most valuable capability is being able to supply and having the confidence to raise prices. Texas Instruments absorbed pressure from capital spending and capacity expansion over the past few years. That is now turning into advantages in supply capability and cost position.
The investment implication of this table is that restocking usually appears first in catalog-part prices, lead times, unit inventory, and procurement budgets, and only later enters the income statement. By the time earnings fully reflect the revenue recovery, share prices have usually already moved some distance.
Data centers provide an additional lever here. In the past, analog cycles were mainly driven by industrial and automotive demand. Now, rising AI rack power density is turning power management, high-voltage GaN, SiC, isolation, thermal management, connectors, and sensors into part of the system bottleneck. Even if data centers are still not a large revenue share for companies such as Texas Instruments, their impact on the valuation narrative has already begun to exceed their revenue contribution.
Distribution catalog data also have an advantage that financial statements do not: they can reveal customer purchasing behavior earlier. When analog chip companies report revenue, investors are seeing the result of shipments already made and recognized. Changes in distribution inventory, pricing, and availability reflect what customers are doing when placing orders, modifying BOMs, looking for substitute parts, and locking in supply in advance. The most useful early-cycle signal is often not revenue growth year over year, but procurement teams starting to worry that they may not be able to get parts.
This is especially important in the industrial chain. Industrial customers do not frequently switch critical analog part numbers just because short-term prices are lower, because qualification, reliability, after-sales support, and line-stoppage risks are all high. Once a customer places an analog component into a long-term platform, supply stability becomes more important than unit price. When distribution inventory declines, customers are more likely to order in advance. When lead times lengthen, procurement teams switch from “buy as needed” to “lock in supply first.” When prices rise, as long as end-product gross margins can absorb it, customers typically will not redesign a system because a small number of analog components have become more expensive.
This is also why analog upcycles often last longer than they appear. Rising memory prices quickly stimulate supply expansion. GPU orders depend heavily on capital spending by a small number of major customers. Analog chips have fragmented part numbers, mature processes, and long qualification cycles, so both supply and demand move more slowly. Slowness has two effects: destocking drags on longer in downturns, while prices and lead times are also easier to sustain in upturns. Current UBS data do not show a one-off inventory replenishment. They show industrial customers once again assigning value to supply certainty.
Here it is necessary to distinguish between “ordering in advance” and “real restocking.” If customers are only pulling forward orders temporarily because of tariffs, geopolitics, or transportation disruptions, distribution inventory will quickly rise again and pricing momentum will weaken. If end demand and industrial capex improve at the same time, unit inventory will continue to decline, and supplier revenue and utilization will then follow. UBS combines buyer surveys, distribution catalog data, and balance sheets precisely to judge between these two scenarios. Current evidence leans more toward real restocking, but it still needs continuous confirmation from future earnings reports.
From an investment perspective, the conclusion from distribution catalog data is not “buy whoever has the least inventory,” but “buy whoever can deliver, raise prices, and hold share when customers are worried about supply.” Texas Instruments’ advantage is supply and pricing. Analog Devices’ advantage is high-end industrial quality. Microchip Technology and onsemi offer recovery elasticity and optionality. This difference will determine the sequence of share-price performance: early on, investors buy confirmation first; only later do they rotate into recovery elasticity and valuation convergence.
IV. The Other Side of the Inventory Cycle: Whose Inventory Is Good, Whose Inventory Is Dangerous
A company’s inventory position determines who can attack early in the upcycle and who must first repair the balance sheet. Analog chip inventory cannot be assessed only by total days of inventory. Die bank, finished goods, distribution inventory, internal capacity utilization, and customer inventory positions need to be viewed together to understand whether a company is preparing ammunition for the upcycle or still paying down the prior downturn.
UBS’s balance-sheet deep dive shows that industry headline inventory days were about 171 days in 1Q26. Rohm, Texas Instruments, onsemi, Microchip Technology, and Infineon are at higher levels; Analog Devices, STMicroelectronics, Allegro, and Renesas are relatively lower. Looking one level deeper, Texas Instruments’ finished-goods days were about 84 days, materially above the industry level of about 43 days. This looks like a risk, but UBS instead interprets it as an advantage, because Texas Instruments’ high finished-goods inventory can be delivered quickly when demand returns, preventing customers from switching to competitors because of lead times.
Microchip Technology and onsemi face different issues. Both companies have relatively heavy die banks, indicating that work-in-process and internal inventory burdens have not been fully removed. Microchip Technology’s management is already executing an inventory management plan, and demand recovery would help repair gross margins and utilization. onsemi must simultaneously address SiC, automotive, image sensors, exits from legacy businesses, and price divergence in power devices, making the proof path more complex.
Analog Devices is in a steadier position. Its industrial quality is high, inventory is relatively less aggressive, and margins are stronger. But the cost of stability is that elasticity may not be the greatest. For an analog company already trading at a high-quality premium, the market needs to see not only that things “will not be bad,” but also that pricing, orders, and the data-center power narrative can continue to revise upward.
Inventory judgment cannot be static. High inventory combined with falling demand is a margin risk. High inventory combined with longer lead times and customer orders pulled forward is supply capability. Low inventory combined with demand recovery creates pricing elasticity. Low inventory combined with an inability to deliver leads to share loss. The most interesting part of Texas Instruments today is precisely that its high finished-goods inventory has turned from a point of controversy into a delivery option in the upcycle.
V. Why Texas Instruments Became UBS’s Top Pick
Texas Instruments is being re-rated this time because “pricing + inventory + FCF” are all turning at the same time. UBS raised its Texas Instruments price target from US$295 to US$350. On the surface, this reflects an increase in the valuation multiple from 22x EV/FCF to 26x. Underneath, it is a repricing of the company’s free-cash-flow quality.
Over the past two years, Texas Instruments’ valuation has been weighed down by one issue: it spent too much money building fabs. High capex, depreciation pressure, and slow gross-margin recovery meant that even if the market believed in a revenue recovery, investors still worried that free cash flow would be consumed. Now this issue is starting to reverse. As the capex cliff gradually arrives, as long as revenue maintains mid-teens growth, FCF per share will recover faster.
UBS’s model for Texas Instruments links revenue recovery, EPS repair, and the free-cash-flow inflection. The core of the valuation is not single-year EPS, but average 2027/2028 FCF and the target EV/FCF multiple. The base target price, upside case, and downside case all revolve around this set of cash-flow assumptions.
The most important variable in this model is FCF. In the past, analog investors often focused on gross margin, but Texas Instruments’ stock has historically been more easily priced around free cash flow. As long as capex comes down from elevated levels, revenue recovery and pricing improvement will flow through to cash flow more quickly. Texas Instruments’ cyclical elasticity comes from “after capacity investment is completed, each additional dollar of revenue leaves more cash behind.”
This bridge also highlights one risk: Texas Instruments is not a low-valuation stock. Its current valuation is already above its historical median and also above many traditional analog peers. Buying Texas Instruments means buying confirmation and the FCF inflection, not cheapness. If the industrial recovery does not continue, or if pricing execution is undermined by competition, the 26x FCF multiple implied by the US$350 target price will be difficult to expand further.
But in the analog chip industry, cheap is not necessarily the best early-cycle asset. What is truly scarce early in the cycle is a company that can secure price increases, deliver on time, and convert the capex peak into a downward slope in cash outflows. The capacity investment that Texas Instruments was questioned for over the past few years is now becoming the core option in this phase.
Texas Instruments’ asset attributes are changing. In the past, market discussion of Texas Instruments often focused on whether it had overinvested. The company’s commitment to internal manufacturing and long-term capacity expansion looked heavy during the downturn: depreciation pressure rose, capex consumed free cash flow, and revenue did not grow at the same time. Investors naturally worried that management was too optimistic about the industry cycle. Now the same asset base is being reinterpreted: if industrial and embedded demand recover, internal capacity, finished-goods inventory, and supply stability are not costs, but tools to gain share in the upcycle.
This is the difference between analog chips and foundry, memory, and GPU companies. In foundry, capacity utilization and advanced-node investment more directly affect industry supply and demand. In memory, supply discipline quickly transmits into pricing. GPU order visibility is more concentrated. Texas Instruments’ value lies in a large number of long-tail analog part numbers, mature processes, internal manufacturing, and long-term customer relationships. Its capacity is not a bet on one or two blockbuster products, but a way to provide certain delivery in a market with fragmented customers and complex part numbers. Industrial customers are willing to pay for certain delivery; that is when Texas Instruments’ internal manufacturing has economic value.
The decline in capex is the timing key for this re-rating. Revenue recovery alone is not enough to reprice Texas Instruments, because investors already know analog chips are cyclical. What truly changes the valuation is the simultaneous occurrence of revenue recovery and falling capex. At the current stage, each unit of incremental revenue is more likely to pass through to free cash flow, and capex no longer consumes the improvement in the income statement. UBS anchors its target price to free cash flow rather than single-year EPS because it recognizes this change.
Finished-goods inventory also needs to be repriced. In a downturn, high finished-goods inventory looks like a burden. Early in an upcycle, it looks like an option. It allows Texas Instruments to deliver quickly when customers resume orders, and it gives the company more pricing power when lead times lengthen. More importantly, it can reduce customers’ incentive to migrate to a second source. Once analog customers move a part number to a competitor because of shortages, share may take a long time to recover. The ability to deliver is itself both defense and offense.
Pricing execution is the third variable. In UBS distribution data, Texas Instruments’ price index is stronger across multiple analog and MCU measures, showing that it is not merely exchanging inventory and supply for volume. If pricing holds, revenue recovers, and capex declines at the same time, Texas Instruments’ operating leverage will be cleaner than that of a traditional cyclical stock. Investors are willing to pay a higher multiple because cash-flow quality is improving, not because the industry has suddenly become a high-growth track.
This also explains why Texas Instruments’ risk cannot be assessed only by whether its valuation is expensive. An expensive stock can still keep outperforming if the cash-flow inflection is clear. A cheap stock can still be a trap if inventory and pricing have not repaired. What Texas Instruments needs to prove now is not “whether the company is good,” but whether “cash-flow release after the capex peak can be delivered.” In every coming quarter, the market will cross-check revenue, inventory, capex, and free cash flow together.
VI. Analog Devices, Microchip Technology, ON Semiconductor: Who Is in the Second Tier
The ranking of the second tier depends on whether investors want certainty, cyclicality, or optionality. On quality alone, Analog Devices remains a premium asset in analog semiconductors. For cyclical torque, Microchip Technology has more room for inventory and utilization recovery. For AI power and power-device optionality, ON Semiconductor has higher upside, but the near-term evidence is also more complicated.
Analog Devices’ core strengths are customers and products. Industrial is its largest end market, and high-performance data converters, amplifiers, RF, test and measurement, aerospace and defense, and automation give it strong gross margins and customer stickiness. Bernstein’s global analog framework also views Analog Devices as one of the U.S. analog companies with the best industrial mix. The issue is that the market has already assigned a fairly high valuation to that quality. Analog Devices is better suited as a core allocation holding than as the sharpest restocking-beta trade.
Microchip Technology looks more like an “inventory-repair beta stock.” Goldman Sachs and Morgan Stanley have both previously noted that Microchip has attractive exposure to industrial, data center, computing, aerospace and defense markets, with orders and inventory-management plans improving, and gross-margin drag likely to decline as utilization improves. UBS’s 2Q data, however, is a reminder that Microchip’s die bank remains heavy and inventory digestion is not fully complete. Its upside depends more on continued order recovery and the company lifting utilization.
ON Semiconductor is harder to summarize in one sentence. Goldman Sachs believes ON’s industrial and automotive recovery is already under way, but legacy-business exits, SiC, and image sensors make headline revenue less clean. Citi is more positive on ON’s SiC/GaN optionality from the perspective of 800V data-center power. UBS’s distribution data offers a cooler reminder: ON’s pricing remains weak in some power analog categories, and unit inventory pressure has not been fully resolved. In other words, ON’s upside can be large, but it needs more execution evidence.
The core point of this table is that each company carries a different burden of proof. Texas Instruments needs to prove FCF. Analog Devices needs to prove high-quality growth is still there. Microchip Technology needs to convert inventory repair into gross margin. ON Semiconductor needs to prove that data-center power optionality can offset volatility in automotive and legacy businesses.
VII. Why 800V and AI Power Make Analog Valuations More Expensive
AI data centers have pulled analog semiconductors from a macro-cycle asset bucket into the system-bottleneck asset pool. This point matters because it explains why analog semiconductor companies can receive valuation rerating beyond a traditional industrial recovery.
The core change in AI racks is power density. GPUs, ASICs, HBM, switch chips, and optical modules are all increasing power consumption per rack. Power travels from the campus, transformers, distribution, racks, and power modules all the way to the chip side. This process requires a large number of analog and power devices: power-management ICs, high-voltage GaN, SiC, isolated drivers, sensors, thermal management, connectors, controllers, MCUs, and protection devices. Their unit prices are not necessarily high, but volumes are large, qualification is strict, and system value is high.
Citi’s 800V data-center power framework provides a more aggressive version: the 800V-to-1V power-delivery market could grow from about $2 billion in 2026 to about $12 billion in 2028, implying a CAGR above 70%. This type of estimate should not be applied mechanically, but the direction is worth taking seriously. Data-center power is moving from a “server power-supply chain” to an “AI compute-efficiency chain,” which gives some analog and power semiconductor companies a higher-valuation narrative than the traditional cycle.
Texas Instruments matters because of high-voltage GaN and internal manufacturing capability. ON Semiconductor matters because of SiC/GaN and high-power infrastructure. Analog Devices matters because of high-performance power, data conversion, and control. Monolithic Power matters because of modular power and high-end data-center customers. Infineon, Renesas, and STM connect to European industrial, automotive, and power devices. Different companies will not consume the same profit pool, but all will be re-screened by the AI power tree.
SemiAnalysis | 800VDC Delay and CPO Pushout: Powered Down, Lights Off Chinese-English Version
This thesis also carries risks. 800V will not become ubiquitous overnight. Nvidia and cloud-vendor architecture choices, the pace of green data-center construction, power-supply standards, GaN/SiC cost curves, and server OEM design cycles will all affect the pace of realization. In the near term, ±400V HVDC sidecars, rack-level power, and high-voltage conversion will land earlier. Broad adoption of true >1MW, SST, or higher-voltage architectures may require a longer cycle.
Therefore, in the final investment ranking, not every analog company should be labeled an AI asset. A more accurate approach is to split analog semiconductors into two categories: first, revenue and pricing repair from industrial-cycle recovery; second, valuation narrative and medium- to long-term content uplift from AI power. Texas Instruments, Analog Devices, ON Semiconductor, Monolithic Power, Infineon, and Renesas will carry different weights across these two lines, and the market will assign different valuations accordingly.
The investment implication of this chain is that AI does not only buy GPUs; it also buys power efficiency. Analog semiconductor companies were previously outside the center of the AI trade, but they are now entering the field of view as “second-order AI capex beneficiaries.” Valuation rerating may not be immediately realized through revenue mix, but as long as 800V, GaN/SiC, and data-center power orders keep appearing, the market will continue to assign higher narrative weight to relevant companies.
VIII. Valuation: Buy Cyclical Upside or Valuation Convergence?
Analog semiconductor valuations now fall into two types of trades: U.S. leaders are cash-flow confirmation trades, while European and Japanese leaders are discount-convergence trades. UBS’s report focuses on Texas Instruments, but Bernstein’s global analog valuation framework is a reminder that the analog industry is not limited to U.S. companies. Over the past 10 years, analog-company P/E multiples have been highly correlated with margins, ROIC, capital returns, and EPS growth. As long as the industry enters an upcycle, valuation gaps have room to narrow.
Among U.S. companies, Texas Instruments and Analog Devices already trade at higher valuations. Texas Instruments is justified by the FCF inflection and pricing execution. Analog Devices is justified by a high-quality industrial mix. Microchip Technology, ON Semiconductor, and NXP look cheaper, but lower valuation comes with a higher burden of proof: inventory, automotive, legacy-business exits, or insufficient data-center exposure.
Among European and Japanese companies, Infineon, Renesas, and STM have long carried valuation discounts. The market worries about automotive exposure, the power cycle, European macro, and insufficient capital returns. But if the industrial recovery continues, AI power content rises, and management teams improve shareholder returns or margin targets, those discounts can narrow. Bernstein explicitly noted that Infineon and Renesas have potential rerating opportunities in dividends/buybacks, margin improvement, and AI power/memory-interface ICs.
This creates two trading paths. The first is to buy certainty, such as Texas Instruments: expensive, but with simultaneous validation from pricing, inventory, and FCF. The second is to buy discount convergence: cheaper, but it requires margins, capital returns, and end demand to prove out at the same time. Which is better depends on investors’ confidence in the macro and industrial cycle.
Semiconductor Deep Dive: Memory-Tax Spillover, and How SanDisk, Applied Materials, and ON Semiconductor’s Acquisition of Synaptics Revalue AI Hardware
At the current point, a more reasonable portfolio approach is layered ownership. Core positions can be placed in companies such as Texas Instruments and Analog Devices, which are better positioned to benefit from industrial recovery and pricing execution. Beta positions can focus on Microchip Technology and ON Semiconductor. Valuation-convergence positions can focus on Infineon, Renesas, and STM. The benefit of this approach is that the portfolio does not need to place all bets on an automotive rebound, nor assign all valuation upside to the long-term AI power narrative.
The underlying judgment behind this framework is that the analog semiconductor industry itself is entering an upcycle, but company share prices will not rise in sync. The market will first reward companies that can convert cyclical recovery into cash flow, then reward companies that can turn AI power into a new growth curve, and only later reward simple low-valuation repair.
Valuation switching usually has three steps. The first step is to buy confirmation, because when early-cycle signals first appear, investors are still unsure whether end demand is real. Capital will first go to companies with the clearest data, the best asset quality, and the most direct cash-flow path. Currently, that means Texas Instruments and Analog Devices. Texas Instruments’ confirmation comes from pricing, finished-goods inventory, and the free-cash-flow inflection. Analog Devices’ confirmation comes from high-end industrial exposure and margin quality.
The second step is to buy margin repair. Once the industry is confirmed to be entering an upcycle, the market will start looking for companies that were hurt more in the earlier phase and have steeper subsequent recovery potential. Microchip Technology and ON Semiconductor sit in this layer. They share higher beta and more problems. Microchip Technology needs to turn inventory and utilization repair into gross margin. ON Semiconductor needs to explain industrial and automotive recovery, SiC/GaN, and legacy-business exits at the same time. At this stage, cheap valuation becomes an advantage, provided operating data no longer deteriorates.
The third step is to buy valuation convergence. European and Japanese analog/power leaders have long traded at discounts, due to high automotive exposure, weak European macro, insufficient capital returns, and limited market confidence in management execution. If the industrial cycle continues to improve, AI power orders begin to spread, and management teams use buybacks, dividends, or margin targets to improve capital returns, the valuation discounts of Infineon, Renesas, and STM could narrow. This type of trade usually does not start earliest, but once confirmed, the beta can be meaningful.
These three steps are not a fixed sequence, nor are they a mechanical rotation instruction for investors. They are more like a checklist: when early-cycle evidence is still limited, the portfolio should lean toward confirmation; when revenue and pricing begin to show up in financial statements, the portfolio can add repair beta; when industry strength is fully confirmed, low-valuation and discounted assets become more likely to outperform. At the current point, UBS’s data moves the industry from step one toward the latter half of step one. Texas Instruments remains the clearest expression, while the second tier can already be watched.
The biggest valuation trap is treating “high-quality companies are expensive” and “low-quality companies are cheap” as the same kind of opportunity. After Texas Instruments’ price target was raised to $350, it is indeed not cheap, but it is expensive because the cash-flow path is clearer. Microchip Technology, ON Semiconductor, and European companies are relatively cheap, but that cheapness comes from uncertainty around inventory, automotive, business mix, and execution. Portfolios need to bind valuation to burden of proof, not simply compare high and low multiples.
If subsequent industrial PMI, distribution inventory, and price indices continue to support UBS’s judgment, portfolios can expand from Texas Instruments and Analog Devices into beta assets such as Microchip Technology, ON Semiconductor, and Infineon. If the data begins to diverge, portfolios should return to the companies with the clearest cash flow, or even reduce overall analog semiconductor exposure. Analog semiconductor rerating is not a one-time conclusion; it is a process that must be repeatedly tested every quarter through orders, pricing, inventory, and free cash flow.
IX. Where It Is Easiest to Be Wrong
The biggest risk in this round of analog-chip re-rating is misreading inventory replenishment as broad end-demand prosperity. Purchasing managers placing orders earlier, increasing safety stock, and signing long-term supply agreements can all move orders and prices first. But if end demand does not follow, replenishment can turn into another round of channel inventory pressure after 2-3 quarters.
The first risk is automotive. In UBS’s 2Q data, automotive demand expectations deteriorated more noticeably. Slowing EV growth, inventory adjustments at traditional automakers, and competition in SiC and power devices will all affect companies such as onsemi, NXP, STMicroelectronics, and Infineon. If automotive remains weak, industrial and data centers will need to shoulder more of the growth burden.
The second risk is pricing. Current price increases are coming from supply certainty, lead times, and capacity reallocation at mature nodes. If customers successfully execute second-source strategies, distributor inventory rises again, or mature-node foundry capacity is released, prices may weaken before orders do. Profit sensitivity in analog chips is highly price-sensitive, especially for companies still carrying heavy inventory.
The third risk is inventory. Texas Instruments’ high finished-goods inventory is now viewed as a delivery advantage, but if demand turns down, it will again become an inventory burden that worries investors. Microchip Technology’s and onsemi’s die banks require even more continuous validation. Once inventory days stop falling while production starts rising again, the market will suspect companies are pulling the recovery forward onto the balance sheet.
The fourth risk is the pace of 800V adoption. The long-term direction for AI power is clear, but adoption of 800V, GaN, SiC, SST, sidecar, and rack-level power architectures will not be linear. Architecture delays do not mean demand disappears, but they will affect the near-term valuation the market assigns to related companies. Option-like assets such as onsemi are more exposed.
This falsification checklist is more important than looking at stock prices alone. Analog chips are a slow-variable industry, with time lags among orders, inventory, pricing, lead times, utilization, and cash flow. The real buying points usually appear when these variables improve simultaneously but the income statement has not yet fully reflected them; the real risks also appear first when these variables diverge.
Another easily overlooked issue: UBS’s data are not company guidance and cannot be directly equated with revenue forecasts. Buyer surveys reflect purchasing intent and supply perception; distributor catalog data reflect channel availability and pricing; balance sheets reflect company inventory and production cadence. Together, the three have strong leading value, but any one of them in isolation can mislead investors.
Buyer surveys can be affected by sentiment. Customers have just lived through a shortage cycle, and their memory of tight supply can make them more inclined to lock in supply early. If macro uncertainty, tariff disruptions, or transportation issues rise, procurement departments may also temporarily increase safety stock. This behavior can make order expectations look very strong, but it does not necessarily mean end sales are rising in parallel. Therefore, demand net expectations need to be assessed together with distributor inventory units, prices, and company revenue, not by looking only at survey curves.
Distributor catalog data also have blind spots. Distribution channels cover a large number of catalog parts and are good at capturing marginal changes in industrial, general-purpose analog, MCU, and power devices, but they are not equivalent to all direct-sales customers, major-customer long-term supply agreements, or full coverage of more customized high-end products. Texas Instruments, Analog Devices, Microchip Technology, and onsemi have different exposures to direct sales and distribution, so channel data also have different explanatory power for each company. They can tell investors that supply and demand are tightening, but they cannot replace company-level judgment on order quality.
Inventory days require even more segmentation. High headline inventory days are not necessarily bad. High finished goods can be a supply advantage when demand recovers; a high die bank often means work-in-process and internal inventory still need to be digested; high distributor inventory can suppress pricing. Texas Instruments’ high finished goods and Microchip Technology’s and onsemi’s die banks should not be placed in the same risk bucket. One is delivery ammunition in an upcycle; the other is closer to an internal burden that must be addressed before margin repair.
Price indices also cannot be directly extrapolated into gross margin. Distributor prices remaining high indicates the channel is not clearing inventory through steep discounts, but company gross margins will also be affected by utilization, product mix, depreciation, long-term contracts, production location, and FX. Strong pricing at Texas Instruments does not automatically mean short-term gross margin will immediately jump; it also needs capex and depreciation pressure to ease at the margin. Analog Devices’ more moderate price leverage does not mean quality is deteriorating, because its margins are already high and its customer structure is more stable.
Therefore, the best use of this report is not to linearly extrapolate every UBS number, but to treat it as a cycle dashboard. Demand expectations show direction, inventory units show channel health, price indices show supply-demand strength, lead times show customer anxiety, and balance sheets show whether companies can convert demand into profit and cash flow. As long as these indicators move in the same direction, the analog-chip re-rating has a foundation. Once more than two begin to diverge, investors should reduce their assumptions for cycle slope.
This is also why portfolio ranking must remain dynamic. Current evidence supports buying higher-conviction assets such as Texas Instruments and Analog Devices first, while monitoring the recovery progress at Microchip Technology and onsemi. If subsequent data prove that replenishment is flowing into revenue and margins, weightings in higher-beta assets can be increased. If the data remain limited to procurement sentiment, the portfolio should return to cash-flow and margin certainty. The analog-chip opportunity is not a single-point bet, but a process of adjusting positions along the strength of evidence.
X. What to Watch Over the Next Four Quarters
Over the next four quarters, analog chips need to validate a transition from “prices and orders” to “revenue, gross margin, and cash flow.” Buyer surveys and distributor inventory have already provided early-cycle signals; the next step must show up in company financials.
First, watch Texas Instruments’ revenue and FCF. If 2Q and 3Q continue to show recovery in industrial and embedded processing, and lower capex allows free cash flow to improve along UBS’s projected path, Texas Instruments’ valuation has reason to keep rolling upward. If revenue is revised up but FCF does not move, it means depreciation, inventory, or gross margin is still a drag.
Second, watch Analog Devices’ industrial orders and margins. Analog Devices does not need to tell many new stories. It needs to prove that high-quality industrial demand remains intact, and that data centers and high-performance power are not just small-percentage narratives. As long as margins remain strong, Analog Devices will continue to enjoy a quality premium.
Third, watch Microchip Technology’s inventory plan and utilization. Microchip Technology’s upside comes from gross-margin recovery. If inventory charges, low utilization, and the die bank continue to drag, the market will not give it a higher multiple just because orders improve.
Fourth, watch onsemi’s AI power and automotive businesses. onsemi has the greatest valuation leverage, but also the most variables. Its September analyst day, 800V-related customer progress, SiC/GaN orders, automotive demand, and exits from legacy businesses will determine whether it can move from a “recovery stock” to an “AI power option stock.”
Fifth, watch capital returns at European and Japanese companies. For the valuation discounts at Infineon, Renesas, and STMicroelectronics to narrow, industry recovery alone is not enough; they also need margin targets, shareholder returns, and AI power/industrial structure upgrades. If management teams still talk only about cycle recovery and not cash returns, the discount will remain.
The final judgment can be compressed into one sentence: analog chips have entered an investable stage of the upcycle, but this is not an indiscriminate industry-wide trade. The current top priority is Texas Instruments, because it simultaneously satisfies industrial recovery, price execution, inventory delivery, and an FCF inflection; the second layer is Analog Devices’ quality, Microchip Technology’s recovery, and onsemi’s AI power option; only the third layer is valuation convergence in Europe and Japan.
If this rally plays out correctly, the market will first broaden from “AI only buys accelerators” to “AI power and industrial automation also need to be re-rated,” and then from “analog-chip inventories have bottomed” to “cash flow and capital returns are improving.” If it goes wrong, the earliest problems will appear in the four hard indicators of orders, lead times, prices, and inventory.
Breaking the next year into three scenarios makes the investment actions clearer. The base case is a moderate industrial upturn, continued diffusion of data-center power, and automotive remaining a drag but no longer worsening. In this scenario, Texas Instruments deserves the core position most, because its price execution, finished-goods inventory, and capex decline can all be realized at the same time. Analog Devices is suitable as a high-quality cyclical asset. Microchip Technology and onsemi are higher-beta watch positions, with weights to be increased only after inventory and margin evidence becomes clearer.
The bullish scenario is sustained broadening of industrial orders, continued lead-time extension, customer acceptance of price increases, and AI data-center power moving from thematic investment into real orders. In this scenario, the analog-chip rally would broaden from Texas Instruments to a wider power and MCU chain. Microchip Technology’s utilization recovery would be repriced by the market, onsemi’s SiC/GaN and 800V options would become more valuable, and Infineon, Renesas, and STMicroelectronics would also have room for valuation-discount convergence. The portfolio can gradually shift from “core conviction” to “recovery beta + AI power options.”
The bearish scenario is that buyer surveys turn into early pull-ins, distributor inventory rises again, price indices weaken, automotive continues to drag, and Texas Instruments’ free cash flow is again held down by capex and depreciation. In this scenario, analog chips would revert to ordinary cyclicals. High-valuation companies would see multiples compressed first, inventory-heavy companies would see margins pressured, and AI power options would cool because of architecture delays and order uncertainty. The portfolio should contract back to companies with the highest cash-flow certainty, or even wait for the next round of signals.
The dividing line among these three scenarios is not macro slogans, but several very specific operating indicators. As long as distributor inventory units continue to fall, prices hold, lead times do not shorten quickly, company inventory does not rebuild, and Texas Instruments’ free cash flow is released on schedule, the base case can hold. Only if these indicators strengthen simultaneously does the bullish scenario have a foundation. If more than two reverse, the market will begin to question whether this is merely a short replenishment cycle.
This also means the investment conclusion of this report will not be “buy all analog chips.” Analog chips are improving, but the improvement path has a sequence: first supply capability and pricing power, then gross-margin and inventory repair, then long-term AI power content, and only finally low-valuation convergence. Investors need to track evidence along this path, rather than raise valuations for all companies together just because one industry cycle indicator improves.
Over the longer cycle, the value of analog chips will increasingly move toward the “intersection of industrial and AI infrastructure.” AI data centers need power, thermal management, sensing, isolation, control, and reliable supply; industrial automation needs long lifecycles, high reliability, and large volumes of mature-process devices. The differences among Texas Instruments, Analog Devices, Microchip Technology, onsemi, Infineon, Renesas, and STMicroelectronics lie in where each stands along this intersection. The companies that can capture both industrial recovery and AI power upgrades will earn higher valuations.
XI. Investment Conclusion
Analog chips now deserve to be written as a standalone second-order AI hardware theme. They are not as direct as GPUs, nor as tight as HBM and advanced packaging, but they connect industrial recovery, data-center power, mature-node supply and demand, and a cash-flow inflection. UBS raising its Texas Instruments target price is essentially pricing these variables together.
For portfolios, the better approach now is layering, not chasing a single label. The first layer is Texas Instruments, where the trade is industrial restocking and an FCF inflection. The second layer is Analog Devices, Microchip Technology, and onsemi, corresponding respectively to quality, recovery, and optionality. The third layer is Infineon, Renesas, and STMicroelectronics, where the trade is convergence in global analog valuation discounts. The fourth layer is Monolithic Power, GaN/SiC, connectors, and other AI power-chain names, where the trade is architecture upgrade.
This layering has one practical benefit: it avoids mixing cycle, quality, and optionality into one trade. Texas Instruments is suitable as a core position because the evidence is the most direct; Analog Devices is suitable as a quality position because its customers and margins are steadier; Microchip Technology and onsemi are suitable as higher-beta positions because the repair space is larger but the variables are more numerous; European and Japanese leaders are suitable as discount-convergence positions because they need industry conditions and capital returns to improve together. Stop-loss points also differ by position type, and they cannot be managed with the same valuation multiple.
For Texas Instruments, the real stop-loss point is not near-term valuation appearing expensive, but failure to deliver free cash flow. If capex does not come down, revenue recovery is insufficient, and inventory turns from a delivery advantage back into a burden, the logic behind the target-price increase will weaken. For Analog Devices, the stop-loss point is a softening in high-quality industrial demand and margins. For Microchip Technology, the key is inventory planning and utilization; for onsemi, the key is whether automotive, SiC/GaN, and AI power orders can all validate the thesis. For Infineon, Renesas, and STMicroelectronics, the key is that the discount cannot rely only on industry recovery; investors must see improvements in capital returns and margins.
Therefore, the analog-chip theme is best added to through “evidence upgrades,” not by chasing a good story. In the early stage, use Texas Instruments and Analog Devices to build confirmation. In the middle stage, expand weights into Microchip Technology, onsemi, and European/Japanese leaders based on inventory, pricing, and margins. Over the long run, use progress in AI power architecture to screen for companies that can genuinely gain new content. This cadence is steadier than simply betting on industry beta, and it is more consistent with the signal in UBS’s latest data.
More broadly, the investment challenge in analog chips is that, unlike leading-edge process nodes or memory, there is no single highly transparent price. One company may sell data converters, power management, amplifiers, MCUs, isolation devices, sensors, and discretes at the same time. Within the same end market, industrial, automotive, data-center, and consumer-electronics cycles also differ. If investors summarize everything as “analog-chip demand is improving,” they can easily mix strong categories with weak ones, strong customers with weak ones, and strong pricing with weak pricing.
Texas Instruments’ burden of proof is to turn “broad coverage” into “cash flow.” The company has many part numbers, many customers, and strong internal manufacturing, giving it a natural advantage when industrial demand recovers. But the market ultimately looks at free cash flow. If revenue recovery only shows up on the income statement while capex and depreciation continue to weigh on FCF, valuation expansion will be capped. Conversely, once FCF improvement is confirmed, Texas Instruments’ high valuation becomes a justified premium rather than a cycle-top risk.
Analog Devices’ burden of proof is to maintain the scarcity value of a high-quality industrial asset. It does not need to prove a capex inflection like Texas Instruments, nor does it need to prove AI power optionality like onsemi. But it does need to show that industrial, aerospace and defense, test and measurement, and high-performance analog customers are still willing to pay for quality. If margins are stable and order quality is good, Analog Devices can continue to enjoy a quality premium. If industrial demand is only short-cycle restocking, its valuation upside will be limited.
Microchip Technology’s burden of proof is to rewrite “inventory pressure” into “margin repair.” It has exposure to industrial, aerospace and defense, data centers, and MCUs, as well as stronger cyclical leverage. But die-bank and utilization issues mean it cannot rely on demand improvement alone. Investors need to see inventory plans advance, gross margin recover, and orders improve together. If those three developments occur in sequence, Microchip Technology can move from a restocking trade into a margin-repair trade. If orders improve but inventory does not decline, the upside will be discounted.
onsemi’s burden of proof is the most complex. It has traditional industrial and automotive recovery, as well as multiple variables including SiC, GaN, 800V data-center power, and image sensors. The advantage is abundant optionality; the drawback is that each variable can drag on the headline. For onsemi, the most important point is not to tell every story, but to prove that incremental AI power and power-device demand can offset the noise from automotive, exits from legacy businesses, and pricing divergence.
For European and Japanese companies, the burden of proof is capital returns and margins. Infineon, Renesas, and STMicroelectronics do not lack industrial, automotive, and power-semiconductor exposure, nor do they lack long-term technology positioning. The market has assigned them discounts for a long time because investors worry about cyclicality, capital allocation, and the European macro backdrop. If management teams can convert industry recovery into margin improvement and shareholder returns, the discounts can narrow. If they only follow the industry recovery, valuation gaps may persist for a long time.
This burden-of-proof framework determines the order of adding exposure. First buy companies that already have evidence, then buy companies where evidence is forming, and finally buy companies where evidence still requires patience but valuations are cheap. The current UBS report makes the first layer of evidence clearer and gives the second and third layers more monitoring value, but it does not yet justify an indiscriminate sector-wide re-rating. This restraint is the most important point to retain from the report.
Finally, portfolios need room for rebalancing. Once an analog upcycle is confirmed, the market will quickly spread from Texas Instruments to lower-valuation peers. But if confirmation fails, the drawdown will also begin with the higher-beta names. The steadier approach is to use Texas Instruments as the cycle-confirmation anchor, Analog Devices as the quality anchor, Microchip Technology and onsemi as higher-beta observations, and European and Japanese leaders as discount-convergence candidates. Each layer should be triggered by different evidence, not bought on the same day using the same conclusion.
This framework also explains why UBS raised the target price on Texas Instruments rather than re-rating the entire analog industry. Industry signals have improved, but company-level delivery paths differ. Texas Instruments has the shortest path to delivery, Analog Devices has the steadiest quality, Microchip Technology and onsemi have greater upside beta, and discount convergence for Infineon, Renesas, and STMicroelectronics requires more evidence on governance and capital returns. Making these differences clear is more valuable for investment than simply saying “analog chips are recovering.”
In the short term, the easiest trade for the market is Texas Instruments’ target-price increase to $350. In the medium term, the real tests are whether industrial demand is continuous, distribution inventory keeps falling, pricing remains resilient, and capex converts into free cash flow. If all four hold at the same time, analog chips will move from the periphery of the AI hardware trade into the core industrial semiconductor asset pool.
The most valuable aspect of this report is that it turns “recovery” into trackable hard indicators. Demand expectations, pricing, lead times, inventory, and FCF are no longer scattered stories. They now point in the same direction: the industrial upcycle has begun, the analog-chip re-rating window has opened, but the winners will concentrate among companies that can deliver supply capability, pricing power, and cash flow at the same time.