
目录
Too Long; Didn't Read
1. Why Did $11.536 Billion Still Disappoint the Market?
2. Data Center Revenue Doubled, and the Core Business Is Still Accelerating
3. The Real Gap in the $13 Billion Outlook Is the Pace of MI450 Delivery
4. Free Cash Flow Margin Fell from 25% to 14% as Growth Began to Absorb Capital
5. Non-Data-Center Businesses Did Not Sink Revenue, but They Weakened Profit Quality
6. What Was the Roughly 9% Decline Pricing In?
7. Which Parts of the Prior View Were Completed from Q1 to Q2?
8. Do Not Watch Only One Revenue Number Next Quarter
Conclusion: A Good Company Did Not Deliver a Large Enough Expectations Gap
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Advanced Micro Devices (AMD) posted record revenue and profit, yet the roughly 9% after-hours decline exposed the expectations gap directly: operating results beat the sell-side consensus but failed to clear a higher buy-side bar.
Too Long; Didn't Read
The quarter beat the sell-side consensus but missed the buy-side hurdle. Q2 2026 revenue of $11.536 billion and non-GAAP earnings per share of $1.66 both exceeded the pre-earnings sell-side consensus of roughly $11.3 billion and $1.63. Revenue, however, fell short of the approximately $11.9 billion buy-side bar, while the 56% gross margin was below the buy side's 56.5% expectation.
The data center fundamentals did not deteriorate; they were the strongest part of the report. Segment revenue reached $6.718 billion, up 107% year over year and 16% quarter over quarter, and represented 58% of total revenue. Segment operating margin rose from approximately 28% in the prior quarter to 31%. The combined ramp of EPYC and Instinct shows that AMD now has its most dependable growth engine at a quarterly revenue scale above $10 billion.
The $13 billion Q3 outlook was good, but it did not deliver a sufficiently large new surprise. The midpoint implies roughly 13% sequential growth but remained below the approximately $13.2 billion buy-side threshold. A flat 56% gross margin also left unanswered how much revenue, profit, and cash MI450 and Helios will contribute in Q4 and 2027.
Cash flow is the part of the quarter that warrants the most restraint. Free cash flow fell from $2.566 billion in Q1 to $1.558 billion, and the free cash flow margin declined from 25% to 14%. Accounts receivable, inventory, and capital expenditure all rose at the same time. Growth remains healthy, but the ramp of new products and systems is consuming more working capital.
The roughly 9% after-hours drop looks more like an expectations and positioning reset than a disproof of the data center thesis. Long positioning was crowded before earnings, while options priced only about a 7.9% move. The larger realized decline indicates that the market is reassessing the pace of delivery in 2027. MI450 must ramp on schedule, gross margin must clear 56.5%, and free cash flow must recover before the valuation ceiling can rise again.
1. Why Did $11.536 Billion Still Disappoint the Market?
Judged only by the headlines, the quarter had few obvious flaws. AMD's Q2 revenue was $11.536 billion, up 50% year over year and 13% sequentially. Non-GAAP operating income was $3.094 billion, up 75%, with a 27% operating margin. Non-GAAP net income was $2.76 billion, or $1.66 per share. The midpoint of the company's prior revenue guidance was $11.2 billion, so the actual result was $336 million higher, while gross margin also reached the approximately 56% guide.
The problem is that a share price never competes with company guidance; it competes with the expectations already embedded in the price. Two pre-earnings buy-side surveys supplied by market participants used different positioning scales but pointed in the same direction: longs were crowded. The sell-side consensus was approximately $11.3 billion of revenue, a gross margin near 56%, and earnings per share of $1.63. The buy-side thresholds that actually shaped after-hours trading had already risen to approximately $11.9 billion of revenue, a 56.5% gross margin, and earnings per share of $1.73. The reported results cleared the first hurdle but not the second.
Actual results beat the sell-side consensus but did not clear the buy-side threshold
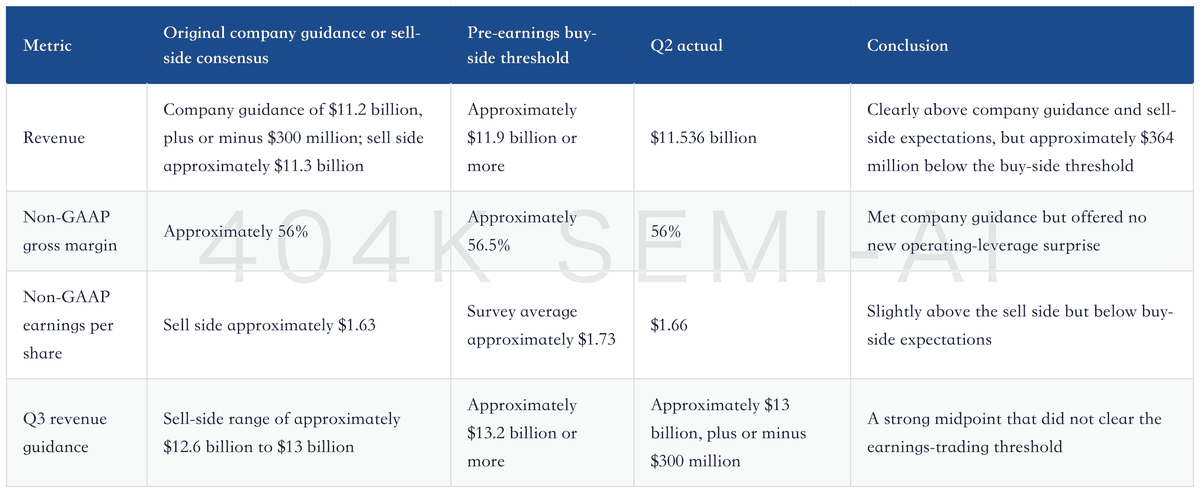
This table explains most of the roughly 9% decline. Revenue of $11.536 billion was about 2% above the sell-side estimate but roughly 3% below the buy-side threshold. The midpoint of Q3 guidance still implies approximately 13% sequential growth, yet it was also about $200 million below buy-side expectations. For a stock that had already risen substantially during the year and whose positioning was near crowded territory before earnings, "good but not good enough" was sufficient to trigger profit-taking.
The earnings definition also matters. GAAP net income was $2.297 billion, or $1.38 per share, including a $483 million gain on long-term investments. The company excluded that gain from its adjusted results, making $1.66 the more useful measure of core operating performance. Conversely, investors should not attribute all of the GAAP earnings-per-share growth to operating leverage in the chip business.
2. Data Center Revenue Doubled, and the Core Business Is Still Accelerating
Data center performance is the hard fact that should not be obscured by the share-price reaction. Q2 segment revenue reached $6.718 billion, up 107% year over year and 16% sequentially, or $943 million more than in Q1. Segment operating income was $2.103 billion, up 163%, while operating margin reached approximately 31.3%, about 3.6 percentage points above Q1's 27.7%. Data center represented 58.2% of total revenue but contributed roughly 68% of segment operating income, so both its revenue and profit weights increased.
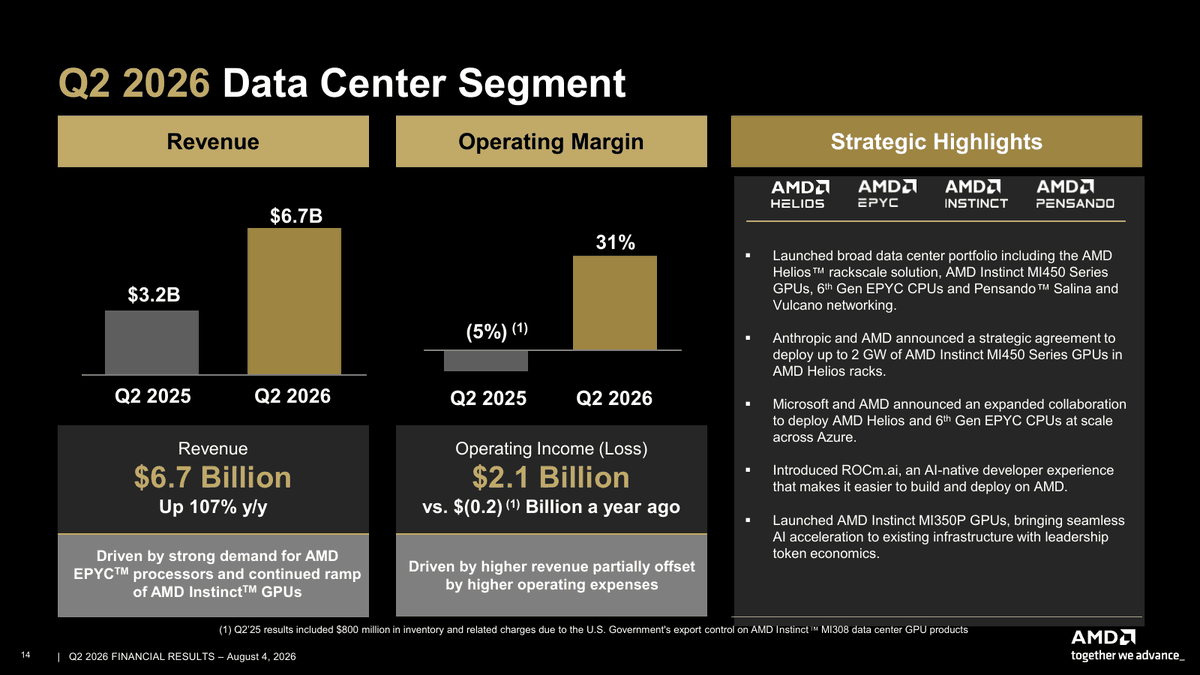
Chart: Page 14 of AMD's Q2 2026 earnings presentation. The page shows data center revenue growth of 107% and operating income growth of 163%, supporting the conclusion that volume growth also produced segment operating leverage.
The figures validate two points. First, EPYC server CPUs continue to gain high-value share. Agentic AI has not made host CPUs less valuable; instead, it has increased demand for orchestration, data preparation, networking, and general-purpose computing. Second, Instinct GPUs have moved from a concept to a revenue source at scale. The company did not disclose the exact CPU and GPU split within the data center segment, so the entire $6.718 billion cannot be attributed to AI accelerators. Still, the simultaneous surge in revenue and profit at least shows that the product mix is not simply relying on low-margin system volume.
The next-generation roadmap in the official materials is also more complete. Anthropic plans to adopt MI450-based Helios systems at deployments of up to 2 GW. Microsoft plans to deploy Helios and sixth-generation EPYC in Azure. ROCm.ai is opening more models, kernels, and optimization assets to developers. Customers, CPUs, GPUs, networking, software, and racks are beginning to appear in one picture. That is the structure AMD needs to evolve from "the second chip source behind Nvidia" into a second platform that customers can deploy at scale.
Investors should not, however, treat customer plans as current-quarter revenue. According to the official presentation, AMD supplied no revenue bridge for MI450 in Q3, Q4, or 2027, and it did not disclose recognized revenue per GW, system-delivery timing, or customer acceptance conditions. This quarter's strong data center result proves that the current products and the EPYC base are growing. The presentation has not confirmed that the 2027 AI revenue embedded in bullish market models has already been locked in.
3. The Real Gap in the $13 Billion Outlook Is the Pace of MI450 Delivery
Q3 revenue guidance was approximately $13 billion, plus or minus $300 million. At the midpoint, both year-over-year and sequential growth remain high. Non-GAAP gross margin was guided to approximately 56%, with operating expenses of about $3.65 billion. A simple mechanical calculation using $13 billion of revenue multiplied by a 56% gross margin, less $3.65 billion of operating expenses, implies approximately $3.63 billion of operating income and an operating margin near 28%, slightly above Q2's 27%.
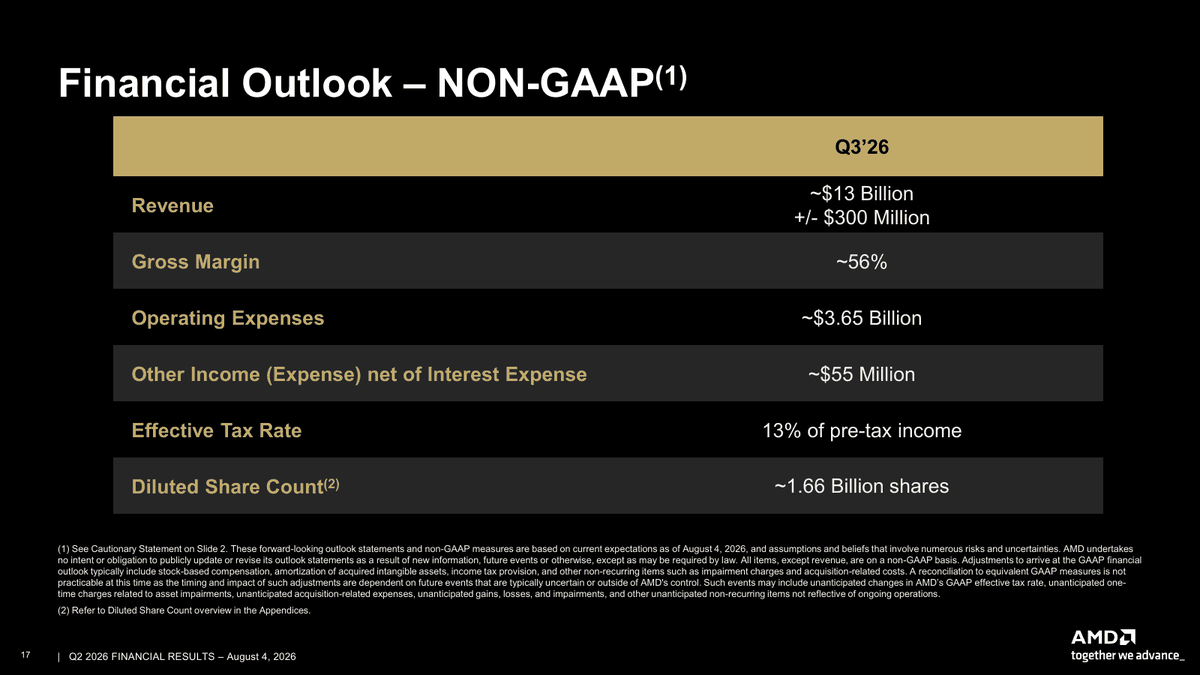
Chart: Page 17 of AMD's Q2 2026 earnings presentation. The page provides Q3 guidance of approximately $13 billion in revenue, a 56% non-GAAP gross margin, and $3.65 billion of operating expenses, supporting the estimate of next-quarter growth and operating leverage.
If AMD were in an ordinary industry upcycle, this would already be sufficiently strong guidance. The current valuation, however, is wagering that MI450 and Helios will create a much steeper revenue step after Q4. The buy side therefore wanted Q3 guidance of at least approximately $13.2 billion and hoped gross margin would rise to 56.5%. The combination of $13 billion and 56% says that growth is continuing, but it does not prove that the slope has been revised upward again.
Four steps must be kept separate. MI450 chips shipping on schedule does not mean that complete Helios racks have passed customer acceptance. Completed system delivery does not mean that all revenue is recognized in the same quarter. Revenue recognition does not mean that AI accelerator gross margin has approached the corporate average. Gross profit also does not mean that working capital will quickly convert into free cash flow. A timing mismatch in HBM, advanced packaging, networking, liquid cooling, power, software, or large-customer customization terms can create gaps among orders, revenue, profit, and cash.
The market therefore wants quantities that can be placed in a model: how many MI450 samples or initial units ship in Q3, how much revenue can be recognized in Q4, how many systems and how much supply have been committed for 2027, and when AI accelerator gross margin will no longer dilute the corporate average. The customer list is already long enough, but the earnings presentation did not quantify all of those questions. The valuation naturally retreated to a level that waits for the next evidence point.
4. Free Cash Flow Margin Fell from 25% to 14% as Growth Began to Absorb Capital
Q2 operating cash flow was $2.366 billion, capital expenditure was $808 million, and free cash flow was $1.558 billion, for a 14% free cash flow margin. Compared with Q1, free cash flow fell by $1.008 billion, or approximately 39%, while capital expenditure more than doubled from $389 million to $808 million. AMD remains free-cash-flow positive, but for a fabless company the direction is clearly weaker than the income statement.
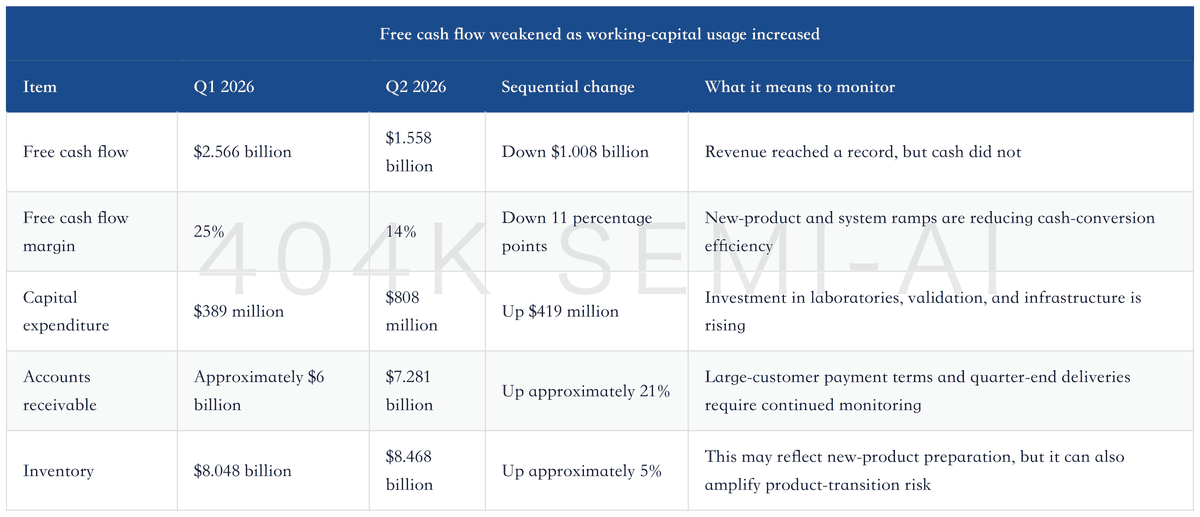
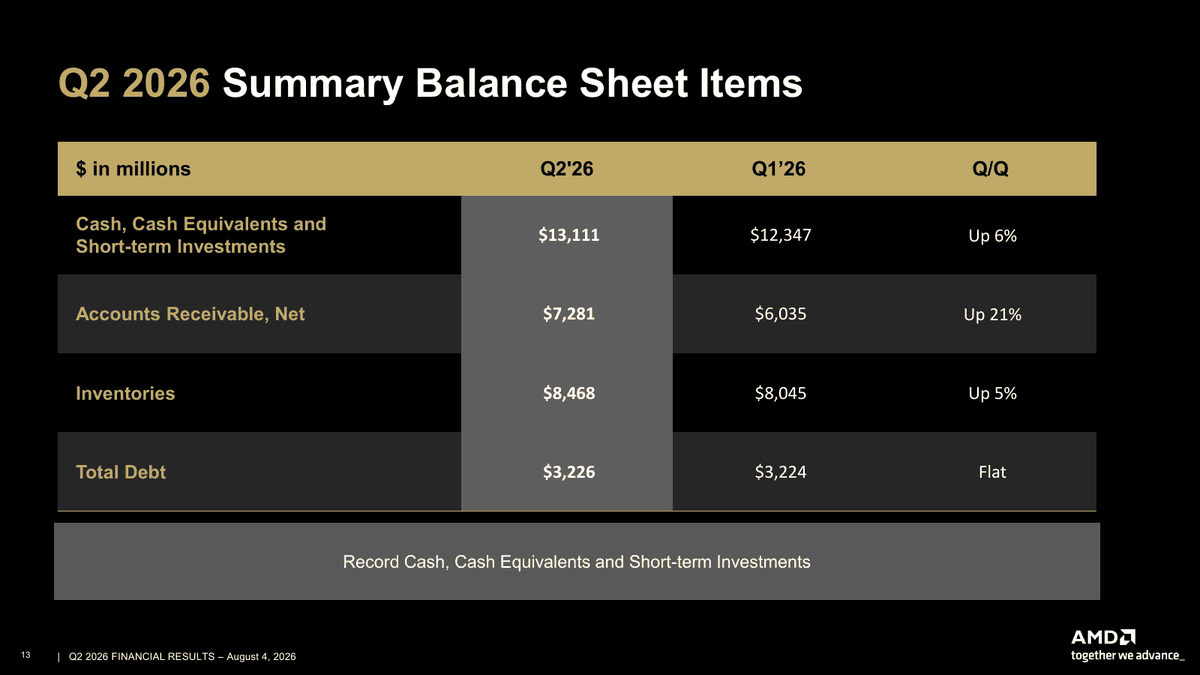
Chart: Page 13 of AMD's Q2 2026 earnings presentation. The page shows a 6% sequential increase in cash and short-term investments, a 21% increase in accounts receivable, and a 5% increase in inventory, supporting the conclusion that liquidity is ample but growth is consuming more working capital.
The cash-flow statement provides more detail. The increase in accounts receivable consumed $1.246 billion of cash, the increase in inventory consumed $423 million, and higher prepayments and other items consumed $683 million. An increase of $2.274 billion in accounts payable offset a substantial portion of that pressure. In other words, operating cash flow did not improve entirely through natural customer collections; growth in supplier balances also provided a cushion.
This does not mean demand is deteriorating. Before AI systems reach volume production, AMD must prepare GPUs, HBM, packaging, networking, and complete-system materials, while accounts receivable naturally rises with revenue. AMD ended the quarter with $13.111 billion in cash and short-term investments against only $3.226 billion of debt, so liquidity is not a problem. The trend is what matters: if Q3 revenue continues to grow while accounts receivable and inventory keep rising faster than revenue and the free cash flow margin remains in the low-to-mid teens, "high growth with weak cash conversion" will turn from a ramping phenomenon into a valuation discount.
5. Non-Data-Center Businesses Did Not Sink Revenue, but They Weakened Profit Quality
Client and gaming revenue totaled $3.841 billion, up 6% year over year and 7% sequentially. Segment operating income was $582 million, down 24%, for an operating margin of approximately 15%. Revenue growth alongside profit contraction indicates that product mix, the game-console cycle, or spending reduced operating leverage. Client products can support the base through Ryzen and commercial-PC share gains, but they cannot explain the current valuation or independently support profit when data center results fall short of expectations.
Embedded performed better. Revenue was $977 million, up 19% year over year and 12% sequentially. Operating income was $386 million, up 40%, for an operating margin close to 40%. This shows that the Xilinx assets are again contributing high-margin profit. Embedded, however, represents only about 8% of total revenue, making it more useful as a source of earnings stability than as the driver of the stock.
The year-over-year gross-margin comparison also requires removal of a one-time base effect. Q2 2025 included approximately $800 million of inventory charges related to MI308 export restrictions. Directly comparing that quarter's 44% non-GAAP gross margin with this quarter's 56% would produce an exaggerated 12-percentage-point improvement. The company disclosed an adjusted Q2 2025 gross margin of approximately 54%, making the true comparable improvement closer to 2 percentage points. That is still respectable, but it shows that margin expansion is gradual rather than a massive immediate profit windfall from doubled revenue.
Research and development spending is also accelerating. Q2 GAAP research and development expense was $2.528 billion, approximately 22% of revenue, while selling, general, and administrative expense was $1.401 billion. Building a platform requires software, networking, systems, and customer support, so higher spending has a strategic rationale. It also means investors cannot mechanically extrapolate earnings per share from the data center revenue growth rate alone.
6. What Was the Roughly 9% Decline Pricing In?
The first layer is the expectations gap. Actual results beat published sell-side expectations but fell short of the buy-side thresholds for current-quarter revenue, gross margin, and next-quarter guidance. The market is not saying that $11.536 billion was poor; it is saying the result was insufficient to keep raising already aggressive 2027 models.
The second layer is the timing gap. The quarter validated EPYC and current Instinct products, while the official materials also laid out the Anthropic, Microsoft, and Helios roadmap. Yet they did not provide a sufficiently precise quarterly revenue bridge for MI450. Investors positioned for a Q4 and 2027 ramp require a higher discount rate when the timing remains uncertain.
The third layer is the quality gap. Data center segment margin improved, but companywide gross margin remained 56%, the free cash flow margin fell to 14%, and accounts receivable and inventory continued to rise. Revenue delivery is moving faster than profit quality, so the market will demand cash evidence in subsequent quarters.
The fourth layer is the positioning gap. Both pre-earnings surveys showed crowded long positioning, while implied options volatility was approximately 7.9%. The roughly 9% after-hours decline exceeded the pre-event pricing by about 1.1 percentage points. Such a move usually reflects not just new short positions but also de-risking by high-expectation longs. The price reaction magnified the disappointment, but it cannot be used to infer that the 107% year-over-year growth in data center demand was unreal.
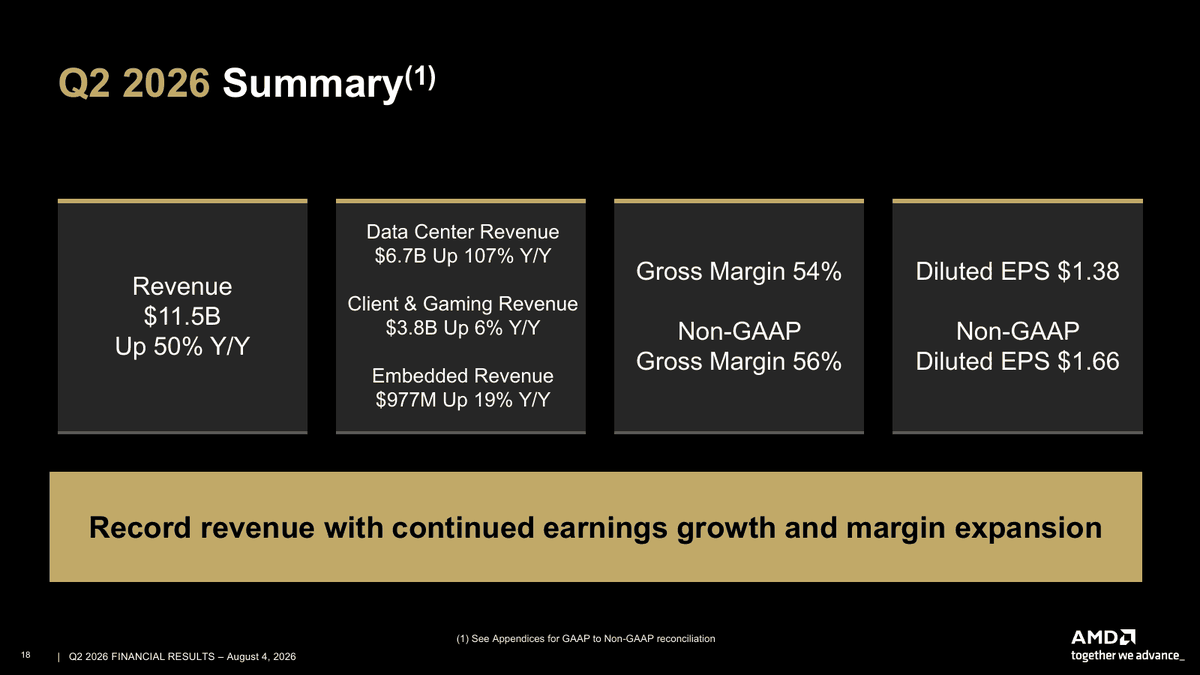
Chart: Page 18 of AMD's Q2 2026 earnings presentation. The official summary highlights record revenue, data center growth, gross margin, and earnings per share. Set against the after-hours decline, it makes clear that the trading conflict arose from the forward hurdle rather than a broad collapse in current-quarter results.
This decline is therefore closer to the valuation clock being pushed back than to a reversal of the industry direction. If MI450 shipments and Helios acceptance proceed smoothly and some revenue merely shifts from Q3 to Q4, the after-hours adjustment will be an expectations reset. If system delivery, customer power availability, or advanced packaging pushes scale revenue out again while gross margin and free cash flow fail to improve, the market will then reduce 2027 earnings forecasts rather than merely compress the near-term multiple.
7. Which Parts of the Prior View Were Completed from Q1 to Q2?
The earlier review of AMD's Q1 2026 results argued that the company was evolving from "a second-source AI GPU supplier" into a second platform spanning CPUs, GPUs, networking, software, and racks. This quarter, data center revenue rose from $5.775 billion to $6.718 billion, segment margin increased to 31%, and Anthropic and Microsoft entered the Helios customer map. That part of the thesis received further validation.
The Q2 preview, however, also established a stricter acceptance standard: MI450 cannot be judged only by orders; investors must examine revenue timing, system delivery, gross margin, and free cash flow together. This quarter cleared only the test that the existing data center business continues to accelerate. The MI450 revenue bridge remains incomplete, gross margin merely met the original guidance, and free cash flow declined sequentially. The long-term platform thesis is therefore stronger than it was last quarter, while near-term valuation tolerance is lower. That is how improving fundamentals and a falling share price can coexist.
8. Do Not Watch Only One Revenue Number Next Quarter
Q3 and subsequent quarters should be assessed through a mutually constraining set of indicators rather than summarized again with the words "beat expectations."
Can the revenue midpoint clear $13.2 billion? $13 billion represents strong growth, but more than $13.2 billion would be closer to the current buy-side threshold. If the result lands at the $12.7 billion low end, management must explain whether the issue is delivery timing or a change in demand.
Can data center revenue keep growing faster than the company overall? If segment growth slows, investors should separate EPYC, current Instinct products, and the MI450 transition rather than mistake a product changeover for disappearing total demand.
Will MI450 and Helios disclose recognizable quarterly revenue and system volumes? Customer lists, GW plans, and shipment language must remain separate from acceptance and revenue recognition.
Can gross margin sustainably clear 56.5%? If AI revenue surges while gross margin remains at 56% or declines, investors should ask about HBM, system content, customer discounts, and ramp costs.
Can the free cash flow margin return above 20%? Accounts receivable and inventory should be monitored at the same time to determine whether they continue to grow faster than revenue and keep the income statement and cash flow statement apart.
Can client and gaming profit stop declining? Data center sets the valuation ceiling, but non-data-center businesses must at least protect the profit base rather than let deteriorating mix offset revenue growth.
Taken together, the bullish scenario has MI450 ramping materially in Q4, Helios entering customer production deployments, gross margin rising above 56.5%, and the free cash flow margin returning above 20%. The base scenario has revenue sustaining high growth while most MI450 contribution remains deferred and margins and cash flow improve gradually. The downside scenario combines lower revenue guidance, delayed system delivery, and simultaneous deterioration in gross margin and cash conversion. Only the third scenario would be sufficient to disprove the current framework of AMD as a second AI platform.
Conclusion: A Good Company Did Not Deliver a Large Enough Expectations Gap
The contradiction in AMD's Q2 report can be compressed into one sentence: the company delivered a very strong operating result, but not a trading result strong enough to raise already crowded expectations again. Data center revenue doubled year over year and segment margin reached 31%, showing that the competitiveness of EPYC and Instinct did not disappear with the after-hours decline. The $13 billion guidance, 56% gross margin, and 14% free cash flow margin show that turning MI450 and Helios orders into high-quality profit will still take time.
The roughly 9% decline first reset expectations. The most important validation from here is whether AMD can translate its Q4 and 2027 platform narrative, in sequence, into revenue, gross margin, and free cash flow. If all three arrive together, the current correction is a valuation reset after crowded positioning. If only revenue grows while margins and cash persistently lag, even rapid data center growth will struggle to prevent further multiple compression.
Related Reading
Arm FY2027 Q1 Deep Dive: Data Center Royalties More Than Double, AGI CPU Demand Exceeds $2 Billion