
Amazon Q2 2026 Deep Dive: AWS Growth Accelerates to 37%, AI Capex Pushes Free Cash Flow Negative
目录
In Brief
From Q1’s “Inflection” to Q2’s “Confirmation”
Profit Growth Has Two Layers: Operating Leverage Is Real, but the Net-Income Surge Cannot Be Extrapolated
Why AWS Suddenly Accelerated: Large-Customer Capacity, Internally Developed Chips, and the Platform Layer All Scaled Together
Negative Free Cash Flow Does Not Mean the Business Is Hemorrhaging Cash
Prime Day Timing Creates the Greatest Risk of Misreading Guidance
The Four Issues the Market Is Most Likely to Misread
Disconfirming Evidence and Validation Metrics for the Next Two Quarters
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Amazon’s core change this quarter was the simultaneous acceleration in AWS revenue and profit; AI infrastructure investment pushed trailing-12-month free cash flow negative for the first time.
In Brief
The AWS growth inflection received a second—and stronger—confirmation. Revenue reached $42.232 billion, up 37% year over year and accelerating by 9 percentage points from Q1’s 28%; operating income reached $16.621 billion, up 64%, with operating margin rising to 39.4%. AWS accounts for only about 21% of group revenue but contributes about 61% of operating income, remaining the core of Amazon’s operating value.
The group’s operating improvement is real, but net income of $62.647 billion cannot be directly annualized. Amazon recognized $53.415 billion of other income this quarter, mainly from its Anthropic investment; by comparison, operating income of $27.461 billion is the more comparable operating anchor. Unrealized investment gains do not negate the improvement in AWS and retail, but they inflated reported EPS to $5.75.
Last quarter’s tension between “very strong operating cash flow” and “free cash flow approaching zero” worsened further this quarter. Trailing-12-month operating cash flow rose 33% to $161.403 billion, but net cash investment in property and equipment increased 64% to $169.007 billion, while free cash flow fell from positive $18.184 billion to negative $7.604 billion. Demand continues to grow, but returns on AI capital are clearly lagging revenue and profit recognition.
Q3 revenue guidance is $197.0 billion to $202.0 billion, representing 9% to 12% year-over-year growth. This appears to be a marked slowdown from this quarter’s 20%, but Prime Day fell in Q3 in 2025 and shifted to Q2 in 2026. The company explicitly stated that, if Prime Day were excluded from both years, Q3 growth would be nearly 4 percentage points higher. The real questions are not about the event-timing mismatch, but whether AWS can continue growing above 30% and whether capex growth can begin to fall below operating cash-flow growth.
From Q1’s “Inflection” to Q2’s “Confirmation”
The prior report’s assessment of Amazon was that “AWS growth is back, but AI infrastructure is consuming free cash flow.” Q2 did not overturn this framework; instead, it pushed both sides to greater extremes: AWS revenue growth accelerated from 28% to 37%, while trailing-12-month free cash flow fell from $1.232 billion to negative $7.604 billion. Demand, profit, and adoption of internally developed chips all strengthened in the cloud business, but group cash returns were pushed out further.
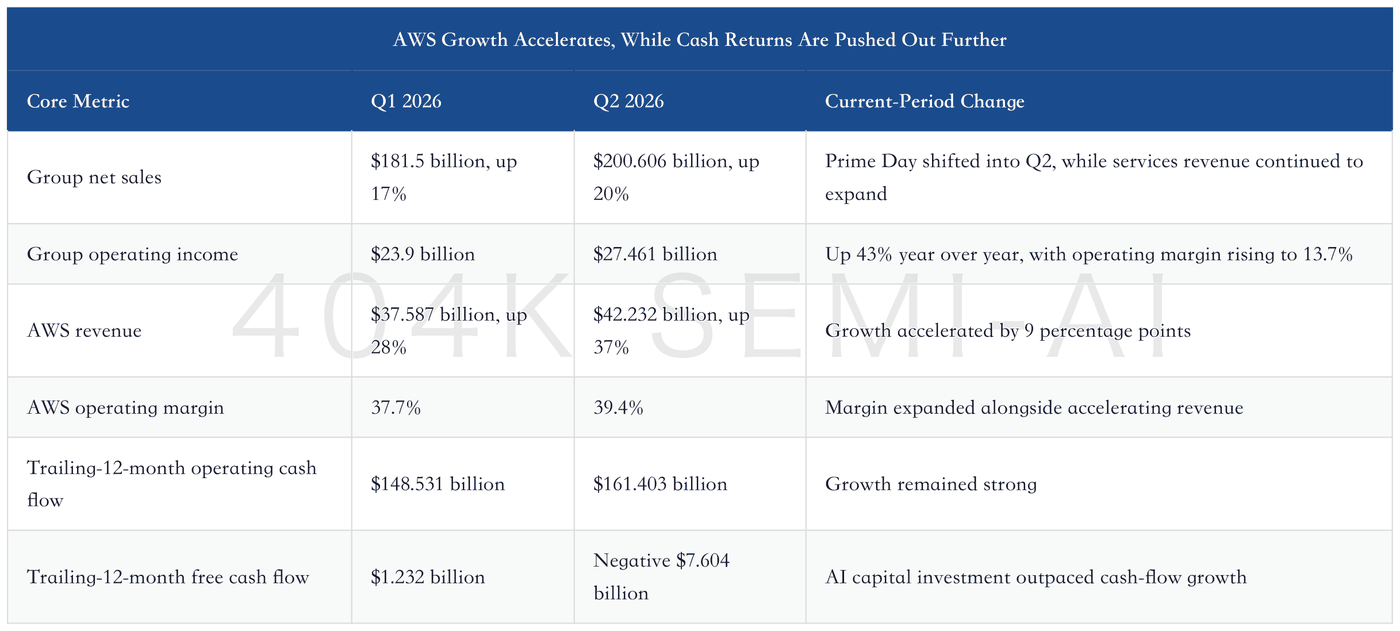
The most important point in this table is not the scale of revenue, but that AWS margin continued to rise during a period of high growth. Cloud providers typically absorb rising equipment depreciation, energy, and networking costs as they compete for AI training and inference demand; AWS nevertheless delivered 37% revenue growth, 64% operating-income growth, and a 39.4% margin this quarter. This indicates that incremental demand is not limited to low-cost compute capacity, but also includes scale benefits from platforms, databases, model services, and internally developed chips.
Profit Growth Has Two Layers: Operating Leverage Is Real, but the Net-Income Surge Cannot Be Extrapolated
Amazon’s Q2 net sales reached $200.606 billion, up 20% year over year. Services sales were $123.004 billion, while product sales were $77.602 billion; services revenue now accounts for more than 60% of group revenue, with AWS, third-party seller services, advertising, and subscriptions jointly increasing the profit density of the business mix.
Segment performance was also more balanced than the view that “everything depends on AWS” would suggest. North America revenue reached $116.177 billion, up 16% year over year, with operating income of $9.123 billion; International revenue reached $42.197 billion, up 15%, with operating income of $1.717 billion, a marked improvement from $747 million a year earlier. AWS operating income was $16.621 billion, accounting for about 60.5% of group operating income, but North America and International contributed a combined $10.84 billion, indicating that fulfillment efficiency, delivery density, and retail-services revenue are also improving.
By revenue source, online stores grew 15% to $70.432 billion, third-party seller services rose 16% to $46.78 billion, advertising services increased 26% to $19.809 billion, and subscription services grew 12% to $13.73 billion. Advertising remains the high-growth services revenue stream closest to a closed-loop transaction model. Amazon disclosed that advertisers using Ads Agent achieved an average 8% reduction in cost per thousand impressions and a 6% reduction in customer-acquisition cost, providing a more verifiable commercial result than generic claims that “AI improves advertising efficiency.”
However, analysis of the income statement must stop at operating income rather than simply multiplying net income by four. Within net income of $62.647 billion, separately reported other income reached $53.415 billion, mainly from the Anthropic investment. Because taxes and other items mean this income cannot simply be subtracted from net income on a one-for-one basis, the most prudent approach is to use operating income of $27.461 billion as the operating baseline and then assess AWS, North America, and International separately. Changes in Anthropic’s valuation may increase asset value, but they are not sustainable cloud-services gross profit and do not generate an equivalent amount of operating cash flow.
The expense structure shows that this operating leverage did not result from broad-based retrenchment. Technology and infrastructure expense reached $33.158 billion, up 22% year over year; fulfillment expense was $29.633 billion, up 14%; transportation costs increased 19%, while paid units grew 17%. The first continued to grow slightly faster than revenue, while the latter two broadly expanded with transaction volumes. Group operating income grew 43%, materially faster than revenue growth of 20%, driven primarily by AWS profit, improvement in the International business, and the services-revenue mix—not by ceasing investment in AI and fulfillment.
Depreciation and amortization also need to be tracked separately. Depreciation and amortization reached $19.988 billion this quarter, up 31% year over year and already growing faster than group revenue. This figure includes property and equipment, capitalized content, and operating-lease assets, so it cannot all be treated as data-center depreciation; however, it clearly shows that prior capital investment is entering the income statement at a faster pace. As long as AWS profit growth remains above depreciation growth, operating leverage can continue to absorb the shift toward a more asset-intensive model; if the two cross over, the capex debate will migrate from the cash-flow statement to the income statement.
Why AWS Suddenly Accelerated: Large-Customer Capacity, Internally Developed Chips, and the Platform Layer All Scaled Together
Management described AWS’s 36.7% growth as its fastest in 18 quarters and disclosed that AWS’s AI business and chip business have each surpassed $25 billion in annualized revenue, with both maintaining triple-digit growth. This metric indicates that Amazon’s AI revenue no longer depends solely on renting individual GPUs: infrastructure capacity, internally developed chips, model hosting, and enterprise-development tools are forming a multilayered revenue pool.
The infrastructure layer is the most direct. Anthropic and OpenAI have both signed multiyear, multi-gigawatt capacity commitments with AWS, making Trainium both a cost tool and a contractual vehicle for securing long-term workloads. In general-purpose computing, GRAVITON5 delivers up to 25% more compute performance than the prior generation, while the Graviton family offers a 30% to 40% price-performance improvement over comparable x86 instances; 98% of the top 1,000 EC2 customers already use Graviton, and related commitments increased by nearly 2x quarter over quarter.
Evidence for the platform layer comes from Bedrock. It added more customers over the past six months than during the preceding two years combined, while Q2 customer spending exceeded the total for all prior quarters combined; Bedrock now offers more than 10 hosted models. If this growth remains confined to training clusters, AWS will increasingly resemble an asset-intensive compute-capacity supplier; if customers also adopt model hosting, databases, permissions, security, and agent tools, revenue durability and margins will more closely resemble those of a platform business. AWS’s 39.4% margin this quarter temporarily supports the latter possibility, but the company has not yet disclosed the respective revenue and gross margins of Trainium and Bedrock, so it cannot be concluded from this evidence that capital returns have already been realized.
Amazon is also using AI on the retail side to increase traffic and fulfillment density. The company stated that the number of products available for same-day or overnight delivery increased by more than 40% year over year; Amazon Now product sales and unit volumes both grew by more than 80% quarter over quarter. Active shopping-AI users nearly doubled, while the number of interactions increased by more than 5x. The positive feedback loop is as follows: faster delivery increases purchase frequency, more transaction data improves recommendations and advertising, and profits from advertising and third-party services then subsidize further fulfillment investment. The counterevidence is that delivery costs increased 19%, still above the 17% growth in paid units; if this gap continues to widen, growth may be driven more by costly investments in delivery speed than by improving unit economics.
Negative Free Cash Flow Does Not Mean the Business Is Hemorrhaging Cash
Operating cash flow over the past twelve months was $161.403 billion, up 33% year over year, indicating that the core business’s cash-generating capacity has not deteriorated. However, cash purchases of property and equipment, net of proceeds from disposals and incentives, reached $169.007 billion over the same period, up 64% year over year, turning Amazon-defined free cash flow negative at $7.604 billion. Amazon explicitly stated that this net investment increased by $66.054 billion year over year, primarily reflecting AI investment.
Looking only at the past twelve months would still understate the intensity of current investment. Second-quarter operating cash flow was $45.387 billion, while cash purchases of property and equipment were $54.208 billion. After deducting $1.132 billion of proceeds from disposals and incentives, implied quarterly free cash flow was approximately negative $7.689 billion. First-half operating cash flow was $71.419 billion, while net cash capital investment on the same basis was $96.31 billion, indicating that cash investment was materially front-loaded.
Cash spending does not tell the whole story. During the quarter, Amazon added $10.7 billion of property and equipment that had been acquired but not yet paid for, $563 million of assets acquired under finance leases, and $7.67 billion of assets acquired under operating leases. These figures remind investors that current-period asset investment may initially take the form of payables or lease obligations before appearing in future cash flows. However, Amazon did not disclose standalone AWS capital expenditures or update its full-year capital expenditure guidance in this earnings release. Therefore, not all group investment can be attributed to AWS, much less can spending on logistics, satellites, content, and retail automation all be characterized as AI investment.
The balance sheet continues to provide a buffer: period-end cash and cash equivalents were $78.213 billion, while marketable securities were $44.775 billion, totaling approximately $122.988 billion. Meanwhile, long-term debt increased from $65.648 billion at the end of 2025 to $128.894 billion. The company did not attribute the increase in debt to AI on a line-by-line basis in these materials, but the simultaneous increases in cash, debt, and capital investment at least indicate that Amazon is using a more leveraged balance sheet to support growth.
This investment cycle cannot be assessed using the simplistic ratio of “current-quarter capital expenditures divided by current-quarter AWS revenue.” Data centers face lead times from procurement, construction, and power-up to customer deployment, while pre-committed Trainium capacity will also be converted over multiple years. A more reliable validation chain should be assessed sequentially: whether multi-year capacity commitments convert into actual usage; whether customer spending on Bedrock and chips expands; whether AWS operating income can absorb higher depreciation; and, finally, whether group operating cash flow can once again exceed net capital investment. There is positive evidence for the first 2 items, the third currently holds, and the fourth has not yet been achieved.
Prime Day Timing Creates the Greatest Risk of Misreading Guidance
Amazon guided to third-quarter net sales of $197.0 billion to $202.0 billion, representing year-over-year growth of 9% to 12%; operating income was guided to $22.5 billion to $26.5 billion, versus $17.4 billion in the year-earlier period. At the midpoint, revenue would be approximately $199.5 billion, representing growth of approximately 10.5%, while operating income would be approximately $24.5 billion, up approximately 41% year over year. Profit guidance remains resilient, but headline revenue growth falls to the low double digits.
The quarterly shift in Prime Day timing cannot be ignored. Prime Day occurred in the third quarter of 2025 but in the second quarter of 2026. The company explicitly stated that, if Prime Day were excluded from both years, third-quarter revenue growth would be nearly 4 percentage points above the guided range; foreign exchange is also expected to create an approximately 0.8-percentage-point headwind. Therefore, interpreting third-quarter guidance of 9% to 12% as a sharp decline in consumer or cloud demand would conflate the event calendar with the underlying trend. Conversely, the current quarter’s 20% growth also benefited from the event being brought forward and cannot be extrapolated mechanically.
The Four Issues the Market Is Most Likely to Misread
First, treating earnings per share of $5.75 as sustainable earnings power. Gains on the Anthropic investment boosted net income; operating income and segment profit provide more reliable bases for comparison.
Second, interpreting negative free cash flow as a deterioration in the core business. Operating cash flow still grew 33%; free cash flow turned negative because net capital investment grew faster. The real risk is the payback period, not a collapse in current demand.
Third, attributing all capital expenditures to AWS and AI. The company only stated that the increase primarily reflected AI investment and did not disclose standalone AWS capital expenditures; the group also operates fulfillment networks, devices, content, satellites, and automation businesses.
Fourth, focusing only on AWS revenue growth while ignoring profitability and platformization. Growth of 37% is strong, but more important is the increase in margin to 39.4% and whether Bedrock and Amazon’s in-house chips can convert large-customer capacity into recurring software and services revenue. If revenue continues to grow rapidly in the future while margins decline materially, it may indicate that lower-margin infrastructure accounts for a greater share of the business.
Disconfirming Evidence and Validation Metrics for the Next Two Quarters
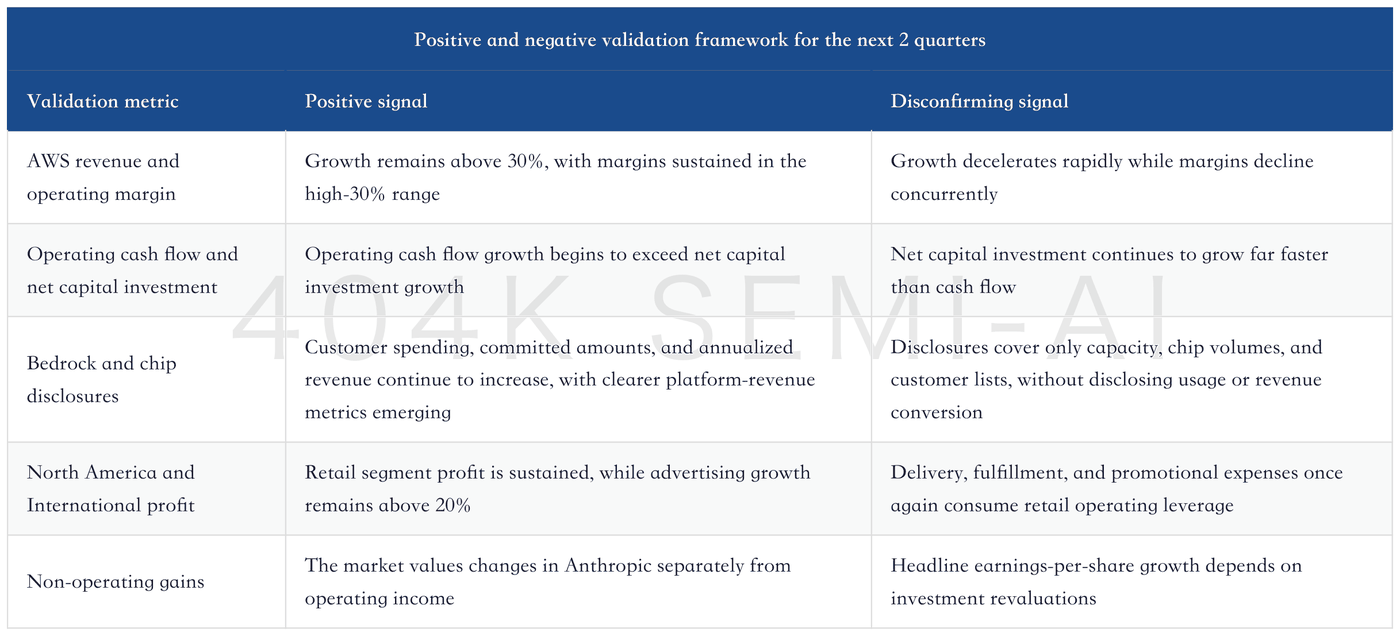
The conclusion from this quarter is clear: the AWS turnaround seen last quarter has advanced into dual confirmation from both growth and profitability, but the return on AI capital has completed only the income-statement half of the case and has yet to complete the cash-flow half. Amazon is demonstrating that it can convert large-customer capacity, in-house chips, and Bedrock into revenue, but it must also demonstrate over the next several quarters that these assets can ultimately enable operating cash flow growth to exceed capital investment growth. The most effective sequence for assessing the quality of Amazon’s current AI cycle is not net income, revenue, and narrative, but AWS operating income, operating cash flow, net capital investment, and free cash flow.
Related Reading
Microsoft FY2026 Q4 Deep Dive: Azure Growth Rises to 43%, Cloud Gross Margin Falls to 65%