
Amazon 2026 Q2 Earnings Deep Dive: AWS Growth Accelerates to 37%, While AI Capex Pushes Free Cash Flow Negative
目录
TL;DR
From Q1’s “Turnaround” to Q2’s “Confirmation”
Profit Growth Has Two Layers: Operating Leverage Is Real, but the Surge in Net Income Cannot Be Extrapolated
Why AWS Suddenly Accelerated: Large-Customer Capacity, Proprietary Chips, and the Platform Layer All Scaled Together
Negative Free Cash Flow Does Not Mean the Business Is Bleeding Cash
Prime Day Timing Creates the Greatest Risk of Misreading Guidance
The Four Things the Market Is Most Likely to Misread
Disconfirming and Validating Indicators for the Next Two Quarters
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Amazon’s key development this quarter was the simultaneous acceleration of AWS revenue and profit; meanwhile, AI infrastructure investment pushed trailing-12-month free cash flow negative for the first time.
TL;DR
AWS’s growth inflection received a second—and stronger—confirmation. Revenue reached $42.232 billion, up 37% year over year, accelerating by another 9 percentage points from Q1’s 28%; operating income reached $16.621 billion, up 64%, with operating margin rising to 39.4%. AWS accounts for only approximately 21% of group revenue but contributes approximately 61% of operating income, remaining the core of Amazon’s operating value.
The improvement in group operations is real, but the $62.647 billion in net income cannot be directly annualized. Amazon recognized $53.415 billion in other income this quarter, primarily from its investment in Anthropic; by comparison, the $27.461 billion in operating income is the more comparable operating anchor. Unrealized investment gains do not negate the improvements in AWS and retail, but they inflated reported earnings per share to $5.75.
Last quarter’s tension between “strong operating cash flow” and “free cash flow approaching zero” deteriorated further this quarter. Trailing-12-month operating cash flow increased 33% to $161.403 billion, but net cash expenditures on property and equipment rose 64% to $169.007 billion, sending free cash flow down from positive $18.184 billion to negative $7.604 billion. Demand continues to grow, but cash returns on AI capital are clearly lagging revenue and profit recognition.
Q3 revenue guidance is $197 billion to $202 billion, representing year-over-year growth of 9% to 12%. On the surface, this is a marked slowdown from this quarter’s 20%, but Prime Day fell in Q3 in 2025 and shifted to Q2 in 2026. The company explicitly stated that, if Prime Day were excluded from both years, Q3 growth would be nearly 4 percentage points higher. The real issues to validate are not the timing shift in the event, but whether AWS can sustain growth above 30% and whether capex growth can begin to fall below operating cash flow growth.
From Q1’s “Turnaround” to Q2’s “Confirmation”
The prior report’s view on Amazon was: “AWS growth has returned, but AI infrastructure is consuming free cash flow.” Q2 did not overturn this framework; instead, it pushed both sides to greater extremes: AWS revenue growth rose from 28% to 37%, while trailing-12-month free cash flow fell from $1.232 billion to negative $7.604 billion. Demand, profit, and adoption of proprietary chips in the cloud business all strengthened, while cash realization at the group level was pushed further out.
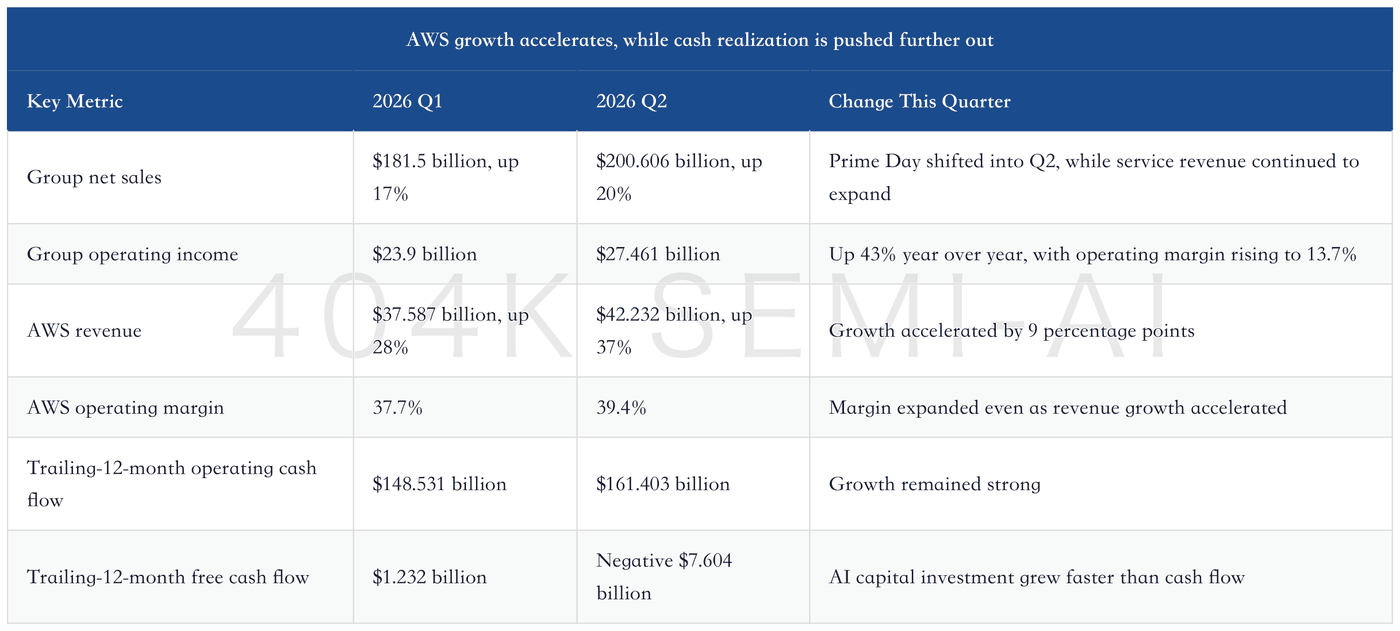
The most important point in this table is not the scale of revenue, but that AWS margins continued to rise during a period of rapid growth. Cloud providers typically face higher equipment depreciation, energy, and network costs as they compete for AI training and inference demand; yet AWS delivered 37% revenue growth, 64% operating income growth, and a 39.4% margin this quarter. This indicates that incremental demand is not limited to low-priced compute capacity, but also includes scale benefits from platforms, databases, model services, and proprietary chips.
Profit Growth Has Two Layers: Operating Leverage Is Real, but the Surge in Net Income Cannot Be Extrapolated
Amazon’s second-quarter net sales reached $200.606 billion, up 20% year over year. Service sales were $123.004 billion, while product sales were $77.602 billion; services now account for more than 60% of group revenue, with AWS, third-party seller services, advertising, and subscriptions collectively increasing the profit density of the business mix.
Segment performance was also more balanced than the characterization that “it is all AWS.” North America revenue was $116.177 billion, up 16% year over year, with operating income of $9.123 billion; International revenue was $42.197 billion, up 15%, with operating income of $1.717 billion, a significant improvement from $747 million in the prior-year period. AWS operating income was $16.621 billion, accounting for approximately 60.5% of group operating income, but North America and International contributed a combined $10.84 billion, indicating that fulfillment efficiency, delivery density, and retail service revenue are also improving.
By revenue source, online stores grew 15% to $70.432 billion, third-party seller services grew 16% to $46.78 billion, advertising services grew 26% to $19.809 billion, and subscription services grew 12% to $13.73 billion. Advertising remains the high-growth service revenue stream closest to a closed transaction loop; Amazon disclosed that advertisers using Ads Agent reduced average cost per thousand impressions by 8% and customer acquisition costs by 6%, a more verifiable commercial outcome than generic claims that “AI improves advertising efficiency.”
