
Alphabet Q2 2026 Deep Dive: Cloud Revenue Surges 82%, While AI Capex Pushes Free Cash Flow Negative
目录
TL;DR
The Most Important Pre-Earnings Question Now Has Its First Answer
Dissecting the Forecast Variance: Cloud Revenue Beat by $1.812 Billion, While Group Costs Ran $3.159 Billion Higher
EPS Was Approximately $2.85 After Mechanically Excluding Gains on Equity Securities
Search Has Not Been Cannibalized by AI and Is Still Accelerating, but Unit Economics Remain a Black Box
Cloud Once Again Demonstrated Both Growth and Margin Expansion—and by a Wider Margin
Capital Expenditures Did Not Exceed Pre-Earnings Expectations, but Investment Intensity Continues to Rise
From $112.193 Billion in Net Income to $39.069 Billion in Operating Cash Flow: What Explains the Gap?
The $49.6 Billion Equity Financing Is the Most Easily Overlooked Change in This Earnings Report
Gemini Has Achieved Scale; It Must Now Prove Revenue and Cost Economics
Which Forward-Looking Views Were Validated, and Which Need to Be Rewritten?
Valuation Requires More Than Earnings Upgrades; the Cash Content of Earnings Must Also Be Reassessed
The Next Six Sets of Numbers Matter More Than a Single Day’s Share-Price Move
The Risk Is Not That AI Fails, but That Success Becomes Too Expensive
Conclusion: Revenue Has Delivered; Cash Flow Still Has More to Prove
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Alphabet’s earnings offer two answers at once: Cloud and Search demonstrate that AI can generate revenue and profit, while negative free cash flow shows that returns on capital remain unproven.
TL;DR
Alphabet’s Q2 2026 revenue reached $119.796 billion, up 24% year over year and 2.0% above Citi’s pre-earnings forecast. Search revenue landed almost exactly in line with expectations, while most of the upside versus Citi came from Cloud: revenue rose 82% to $24.768 billion, 7.9% above Citi’s forecast; Cloud operating income reached $8.814 billion, 14.6% above forecast, with the margin expanding to 35.6%. AI demand has moved beyond product enthusiasm and into the income statement.
EPS of $9.11 should not be treated as a direct measure of operating performance. The company recorded $99.031 billion in gains on equity securities during the quarter, adding $77.1 billion to net income after tax and $6.26 to EPS. Mechanically excluding this impact, EPS was approximately $2.85, slightly below Citi’s $2.90 forecast. The 30% year-over-year increase in operating income reflects genuine improvement, while the 298% increase in net income was primarily driven by investment revaluation.
Google Search remains the most dependable cash cow. Search and other advertising revenue rose 17% to $63.271 billion, just $4 million away from Citi’s forecast; YouTube advertising revenue increased 13% to $11.055 billion, 2.6% above forecast. Total traffic acquisition costs grew 10%, slower than advertising revenue, indicating no deterioration in traffic distribution costs. However, the company still does not disclose ad load on AI queries, cost per query, or revenue per query.
The sharpest contrast was in cash flow. Capital expenditure doubled year over year to $44.924 billion, broadly in line with Citi’s $45.1 billion estimate. However, operating cash flow was only $39.069 billion, resulting in quarterly free cash flow of negative $5.855 billion, versus Citi’s forecast of positive $5.931 billion. The main source of the discrepancy was an approximately $12 billion shortfall in operating cash flow; inventories, accounts receivable, and other assets absorbed a combined $20.827 billion of cash.
Alphabet is changing its capital structure. In June, the company completed $49.6 billion of equity financing and issued $20.3 billion of senior unsecured notes. It conducted no share repurchases during the quarter and retained capacity for up to $40 billion of at-the-market equity issuance. With $242.474 billion in cash, cash equivalents, and marketable securities, the company is not short of liquidity. The financing coincided with funding needs related to AI infrastructure, M&A;, and employee equity-tax obligations, creating a capital buffer for expansion. Assessments of shareholder returns must now account for depreciation, free cash flow, and dilution together.
These results validate half of the earlier outlook: Cloud demand, Search resilience, and capex intensity were all stronger than the market feared. The other half remains unresolved. A $514 billion Cloud backlog, 950 million monthly active Gemini App users, and 22 billion API tokens processed per minute demonstrate that demand exists. But this AI investment cycle will only prove capable of generating sustainable returns if Cloud margins hold, operating cash flow once again covers capex, and equity-issuance pressure declines.
The Most Important Pre-Earnings Question Now Has Its First Answer
Ahead of the release, the market’s focus on Alphabet had shifted from “Will generative AI replace Search?” to “Can Cloud revenue absorb the capex burden?” In its July 16 North American Internet preview, Citi raised its Q2 revenue forecast for Alphabet to $117.42 billion and projected Cloud revenue of $22.956 billion and capital expenditure of $45.1 billion. The central issue in this framework was not whether a single quarter would beat expectations, but whether revenue growth, margins, and the pace of cash recovery could all hold simultaneously.
North American Internet Giants Deep Dive: Higher Cloud Demand, AI Monetization, and the Test of $801 Billion in Capital Expenditure
The actual results split these questions in two. Revenue was clearly ahead of the preview, capex was almost exactly in line, operating income was slightly below forecast, and free cash flow missed in the opposite direction. In other words, Alphabet has succeeded in turning AI into revenue, but has not yet fully converted that revenue growth into distributable cash.
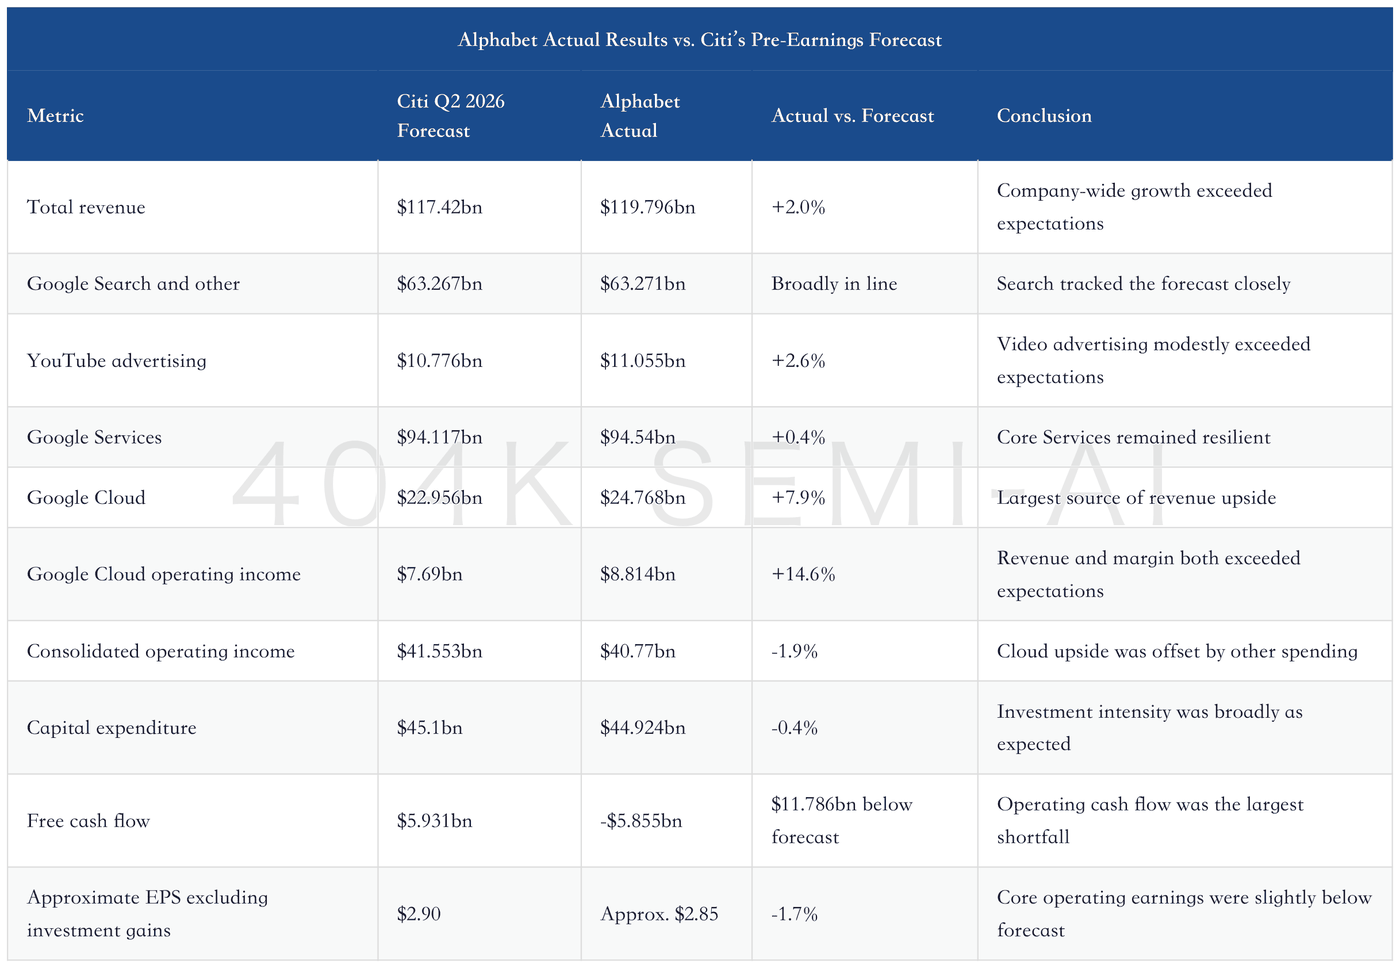
The key takeaway from this table is not simply that there were more beats than misses. The upside in Google Cloud revenue and profit demonstrates that AI demand is already flowing into the financial statements; the substantial free-cash-flow miss reminds investors that revenue growth cannot be translated directly into shareholder returns. The fact that both are true simultaneously is the central challenge in interpreting these results.
Dissecting the Forecast Variance: Cloud Revenue Beat by $1.812 Billion, While Group Costs Ran $3.159 Billion Higher
Alphabet’s total revenue exceeded Citi’s forecast by $2.376 billion, of which Cloud contributed $1.812 billion, or 76.3% of the total upside. Search was only $4 million above forecast, YouTube advertising was $279 million higher, and Google Services exceeded expectations by $423 million in aggregate. Strictly speaking, Services still contributed slightly more year-over-year incremental revenue than Cloud, but Cloud accounted for nearly all of the quarter’s revenue upside versus expectations. Cloud revenue grew 23.7% sequentially, well above the 14.6% implied by Citi’s model. Cloud operating income also exceeded forecast by $1.124 billion, indicating that demand converted into recognized revenue and segment profit faster than investment-bank models had anticipated.
This upside did not fully flow through to consolidated operating income. Google Services operating income came in $1.397 billion below Citi’s forecast, offsetting the $1.124 billion of Cloud upside. Other Bets and Alphabet-level activities then fell a combined $510 million short of the model, leaving consolidated operating income $783 million below forecast. Citi’s model implied total costs and expenses of approximately $75.867 billion, compared with the actual $79.026 billion—a difference of $3.159 billion.
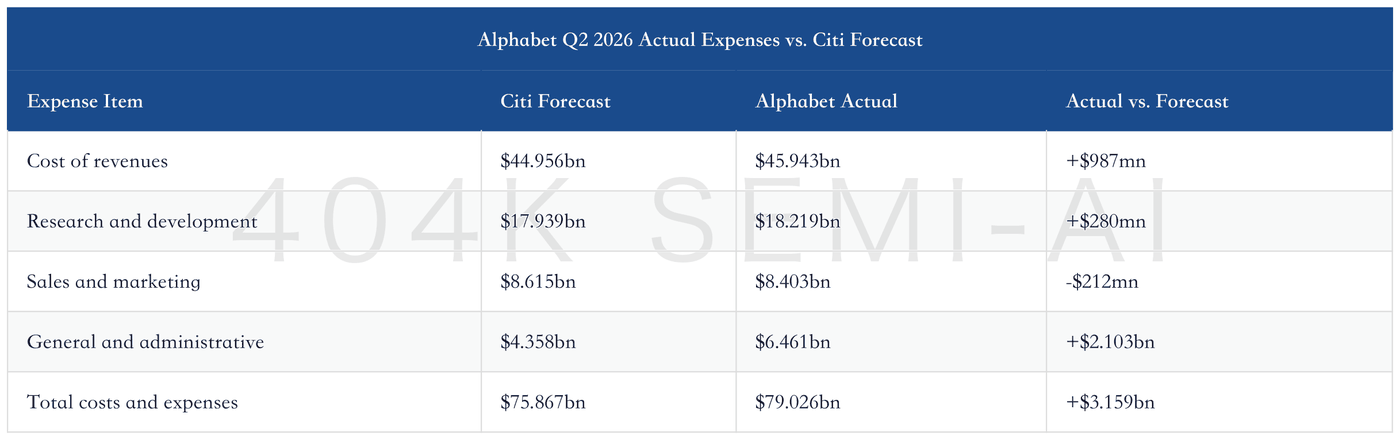
The official earnings materials did not explain how much of the $2.103 billion variance in general and administrative expenses came from one-off items, acquisition integration, legal expenses, or ongoing investment. The confirmed positive variance this quarter was therefore Cloud revenue recognition and segment profit, while the negative variance in corporate-level expenses still requires clarification. Revenue has already exceeded expectations, but until the nature of the additional costs is fully understood, Cloud’s upside should not be extrapolated directly to consolidated EPS at the same magnitude.
EPS Was Approximately $2.85 After Mechanically Excluding Gains on Equity Securities
Google reported quarterly net income of $112.193 billion, with $112.107 billion attributable to common shareholders and diluted EPS of $9.11. At face value, net income increased 298% year over year, far outpacing revenue growth of 24% and operating income growth of 30%.
The explanation lies almost entirely below operating income. The company recorded $99.031 billion in net gains on equity securities, lifting net other income to $97.983 billion. It explicitly disclosed that these equity-security gains increased income tax expense by $21.9 billion, net income by $77.1 billion, and diluted EPS by $6.26.
For assessing operating trends, the $9.11 can therefore be split into two components: approximately $6.26 from investment revaluation in the quarter, with the remaining roughly $2.85 more closely reflecting earnings from advertising, cloud, subscriptions, and other operations. This $2.85 figure is not an official non-GAAP measure reported by Google; it is simply a mechanical deduction based on the disclosed after-tax impact. It still includes interest, foreign-exchange effects, and other non-operating items, and therefore should not be treated as strictly defined core EPS.
On this basis, Google’s core operations did not deteriorate. Operating income rose 30% year over year to $40.77 billion, while operating margin increased from 32.4% to 34.0%. However, the core business did not suddenly nearly triple, as the headline EPS figure of $9.11 might suggest. Citi’s pre-earnings EPS estimate was $2.90, close to the approximate operating figure of $2.85. This indicates that the market’s assessment of core earnings was broadly accurate; the genuine surprise was the magnitude of the portfolio revaluation.
This distinction also affects valuation methodology. Unrealized equity gains could reverse in future quarters and should not be capitalized into a sustainable earnings multiple. Operating income, segment profit, operating cash flow, and free cash flow after capital expenditures are more reliable indicators. Unless all four improve concurrently, a one-quarter surge in net income should not be extrapolated.
Search Has Not Been Cannibalized by AI and Is Still Accelerating, but Unit Economics Remain a Black Box
Google Services revenue rose 15% year over year to $94.54 billion. Operating income increased 19.6% to $39.544 billion, with margin expanding from 40.1% to 41.8%. Search and other advertising revenue grew 17% to $63.271 billion, making it the largest source of growth within Services. YouTube advertising revenue rose 13% to $11.055 billion, while subscriptions, platforms, and devices revenue increased 15% to $12.911 billion. Only Google Network advertising revenue declined, falling approximately 1% to $7.303 billion.
Search revenue was almost exactly in line with Citi’s forecast. At a minimum, this result disproves the most bearish near-term view: AI search features have not immediately eroded query volumes or advertising revenue. Management stated in its official earnings materials that popular AI features are driving growth in Search queries. Meanwhile, total traffic acquisition costs rose 10% to $16.179 billion, slower than the approximately 14% growth in Google advertising revenue. Traffic acquisition costs as a percentage of advertising revenue declined from 20.6% to 19.8%, indicating that distribution costs did not absorb the incremental revenue.
Revenue growth alone, however, does not prove that AI search has achieved a complete monetization loop. The official materials did not disclose ad load for AI Overviews, conversational search, or agentic queries, nor did they provide per-query serving costs for traditional versus AI queries. Generating longer answers requires more inference compute. If usage grows faster than revenue per query, Search revenue could continue to increase while margins come under pressure in subsequent quarters.
Google Services margin improved year over year this quarter, suggesting that such pressure has not yet outweighed the scale benefits from advertising and subscriptions. However, Citi’s model implied a Services margin of approximately 43.5%, compared with the actual 41.8%. This explains why Search and YouTube revenue met or exceeded forecasts while consolidated operating income still fell short: revenue delivered, but costs did not fully meet the most optimistic expectations.
The most valuable indicators going forward are not another Gemini user figure, but three sets of unit metrics: the share and growth of AI queries, ad clicks or conversion performance, and inference cost per query. If the company discloses usage without monetization efficiency, AI’s success in Search remains a product victory rather than a complete financial victory.
Cloud Once Again Demonstrated Both Growth and Margin Expansion—and by a Wider Margin
Cloud was the strongest business this quarter. Revenue rose 82% year over year to $24.768 billion; operating income increased approximately 212% to $8.814 billion; and operating margin expanded from 20.7% to 35.6%. Cloud’s share of Google’s total revenue increased from 14.1% a year earlier to 20.7%, while its operating income was equivalent to 21.6% of consolidated operating income. Cloud is no longer merely a small growth option outside Search; it has become a second pillar capable of materially changing the group’s revenue and profit mix.
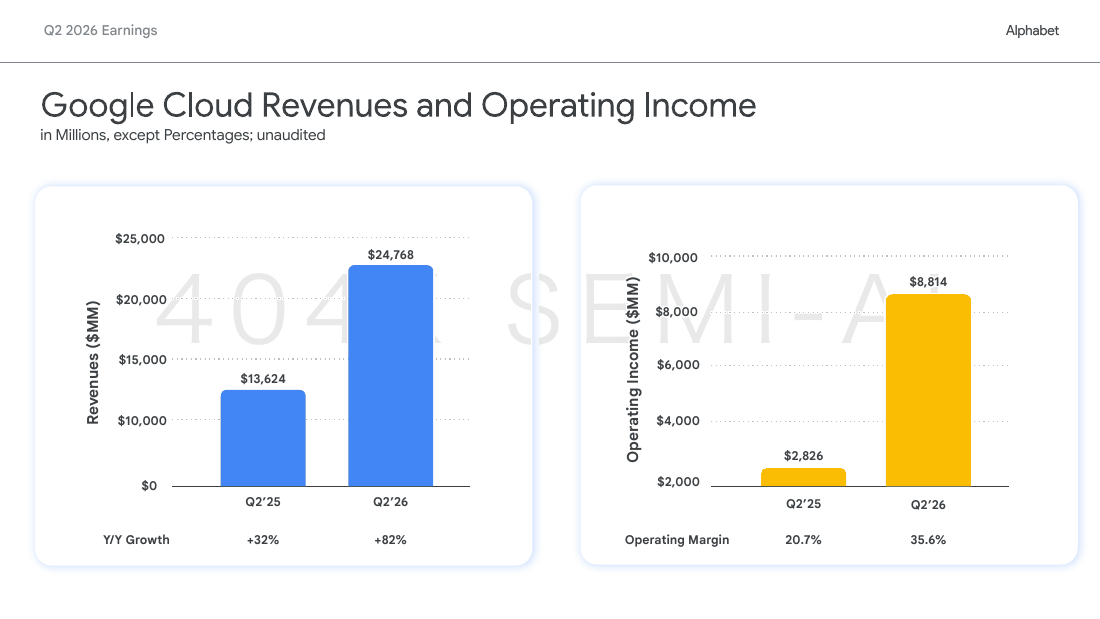
The most important aspect of these results is that revenue growth and margin expansion did not come at each other’s expense. Citi had forecast Cloud revenue growth of 68.5% and an operating margin of 33.5%. Actual revenue growth was 13.5 percentage points higher, while margin exceeded the estimate by 2.1 percentage points. If growth had depended primarily on low-margin hardware or substantial discounts, margins would typically have come under pressure. Instead, margins improved significantly, indicating that incremental revenue generated strong economies of scale during the quarter.
The demand evidence was also more concrete. The official presentation disclosed a Google Cloud backlog of $514 billion, while Gemini Enterprise has been adopted by nearly 90% of the Fortune 100. API processing volume for Gemini models reached approximately 22 billion tokens per minute, up from more than 16 billion in the prior quarter. Using 16 billion as the lower-bound base implies growth of approximately 37.5%; because the actual base was above 16 billion, the true growth rate was lower. These figures advance the narrative from “enterprises are testing AI” to “enterprises are signing contracts and continuously using AI.”
However, the $514 billion backlog cannot mechanically be treated as one year of revenue. It is equivalent to approximately 20.8 times this quarter’s Cloud revenue and about 5.2 times the current quarterly revenue run rate on an annualized basis. Contract durations, minimum commitments, actual customer consumption, and revenue-recognition schedules may all differ. Backlog demonstrates demand visibility; it does not mean that revenue of the same magnitude can be recognized over the next four quarters.
Revenue quality requires another layer of disaggregation. Google’s segment disclosure states that Cloud product revenue primarily comes from sales of TPU systems. Meanwhile, net cash outflows for acquisitions and purchases of intangible assets totaled $33.697 billion in the first half of 2026. Goodwill increased by $24.448 billion from year-end 2025, while intangible assets increased by $7.822 billion. These two official disclosures alone do not allow a precise breakdown of how much of the 82% growth came from the existing cloud-services business, hardware sales, or acquisitions.
This does not negate Cloud’s strength; it prevents different revenue streams from being placed within the same valuation framework. Consumption-based cloud services, long-term subscriptions, usage-based computing, TPU hardware, and acquired revenue have different gross margins, renewal rates, and cash-conversion cycles. A clearer disclosure of organic growth, hardware mix, and backlog conversion in the next Form 10-Q or subsequent management commentary would be necessary to assess how long this quarter’s 82% growth can persist.
Capital Expenditures Did Not Exceed Pre-Earnings Expectations, but Investment Intensity Continues to Rise
Google’s quarterly capital expenditures rose 100% year over year to $44.924 billion, representing 37.5% of revenue, compared with 23.3% a year earlier. Over the past five quarters, quarterly capital expenditures increased from $22.446 billion to $23.953 billion, $27.851 billion, $35.674 billion, and finally $44.924 billion. The growth rate was rapid, but the amount was almost exactly in line with Citi’s $45.1 billion forecast. The quarter’s negative free cash flow therefore cannot be attributed to the company suddenly purchasing an unexpected batch of servers.
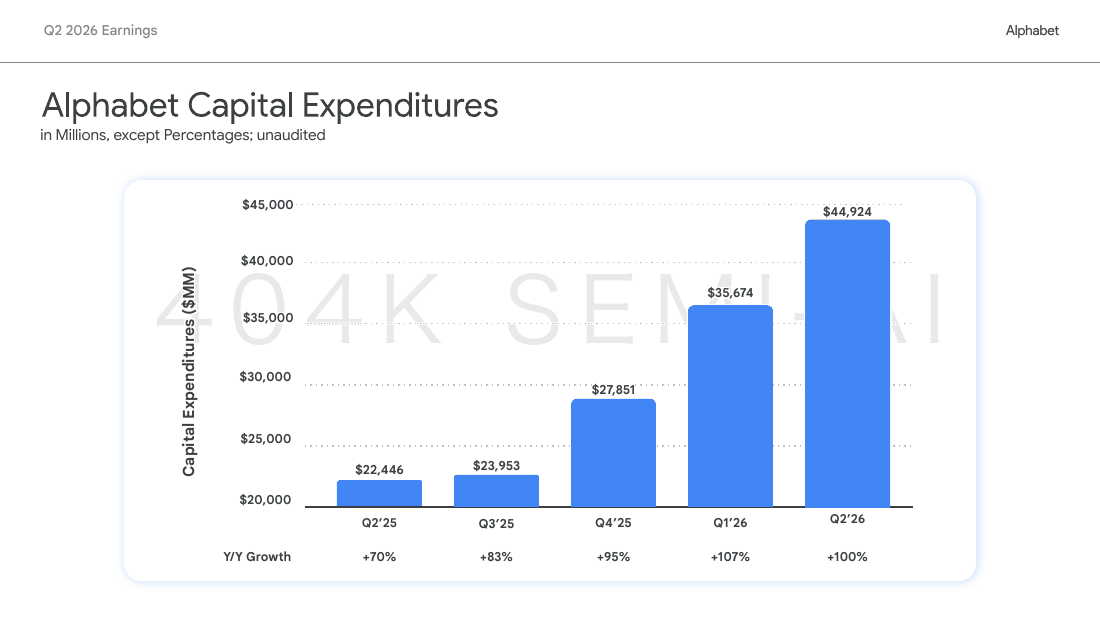
The actual variance came from operating cash flow. Google generated $39.069 billion in quarterly operating cash flow, up 41% year over year, but still below capital expenditures, resulting in negative quarterly free cash flow of $5.855 billion. Free cash flow over the past 12 months was $53.273 billion, down 20% year over year and another 17.3% from $64.429 billion at the end of the first quarter of 2026.
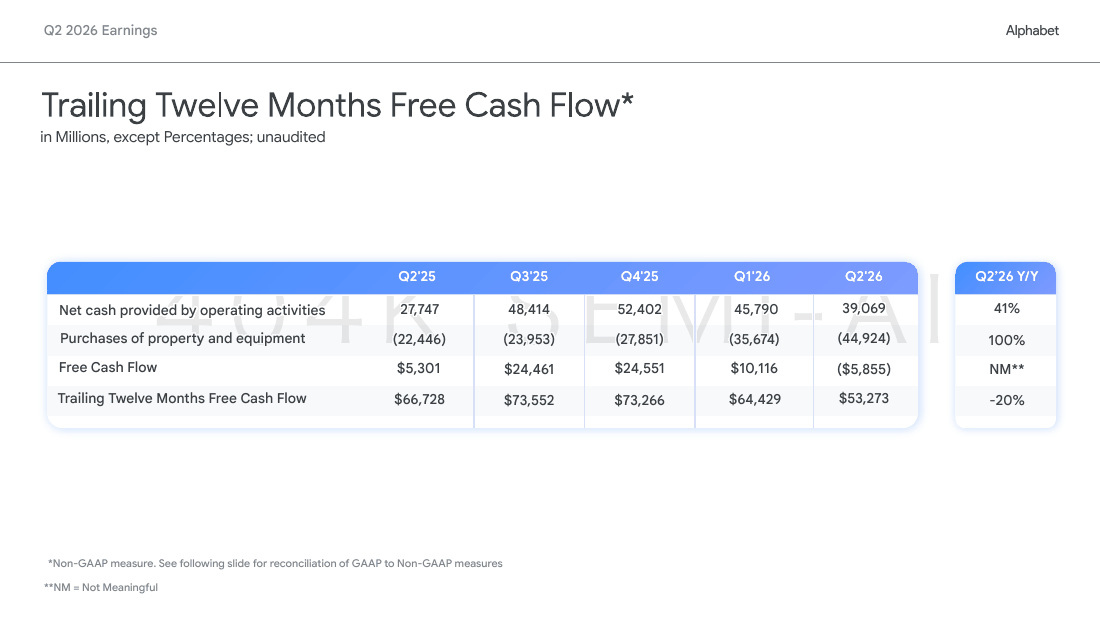
Citi forecast capital expenditures of $45.1 billion and positive free cash flow of $5.931 billion, implying operating cash flow of approximately $51.031 billion. Actual operating cash flow was approximately $11.962 billion below this implied figure, explaining nearly all of the directional variance in free cash flow.
The cash flow statement provides clues. Increases in accounts receivable, inventory, and other assets consumed $6.541 billion, $6.696 billion, and $7.59 billion, respectively, for a combined working-capital use of $20.827 billion. Inventory rose from $2.439 billion at year-end 2025 to $9.991 billion, more than tripling in six months. Given that Google Cloud now also sells TPU systems, the inventory increase may be related to hardware and infrastructure supply preparation. However, the two official disclosures do not provide an inventory breakdown, so this remains an inference requiring verification.
This means Google’s current AI investment extends beyond capital expenditures. Equipment, data centers under construction, and network infrastructure enter fixed assets; chip or system preparation enters inventory; settlement with major customers affects accounts receivable; and acquisitions create goodwill and intangible assets. Focusing solely on capital expenditures understates the total balance-sheet and working-capital requirements of the AI expansion.
Negative free cash flow also does not mean the core business has lost its cash-generation capacity. Operating cash flow still reached $39.069 billion, while free cash flow over the past 12 months remained $53.273 billion. The issue is that investment is now progressing faster than quarterly operating cash generation, lengthening the validation period for cash returns. If inventory and accounts receivable decline in subsequent quarters, cash flow could recover relatively quickly. If both continue rising alongside capital expenditures, negative free cash flow could evolve from a one-quarter fluctuation into a more persistent capital-structure issue.
From $112.193 Billion in Net Income to $39.069 Billion in Operating Cash Flow: What Explains the Gap?
Comparing the income statement with the cash flow statement explains why net income was nearly three times operating cash flow. Net income was first boosted substantially by $99.031 billion in gains on equity securities, but these gains did not generate an equivalent amount of cash during the quarter. The cash flow statement therefore deducted $98.999 billion in net securities gains, while adding back $7.104 billion in depreciation, $7.957 billion in stock-based compensation, and $20.618 billion in deferred income taxes. These adjustments alone bring the sharp increase in net income back toward a measure more representative of operating activity.
Working capital then absorbed additional cash. Accounts receivable, inventory, and other assets consumed a combined $20.827 billion, while accounts payable, accrued expenses, deferred revenue, income taxes, and other items provided a net offset of approximately $9.127 billion. As a result, $112.193 billion in net income translated into $39.069 billion in operating cash flow. This reconciliation shows that the gap between earnings and cash flow this quarter had two components: non-cash gains from investment revaluations and genuine working-capital requirements during a period of expansion.
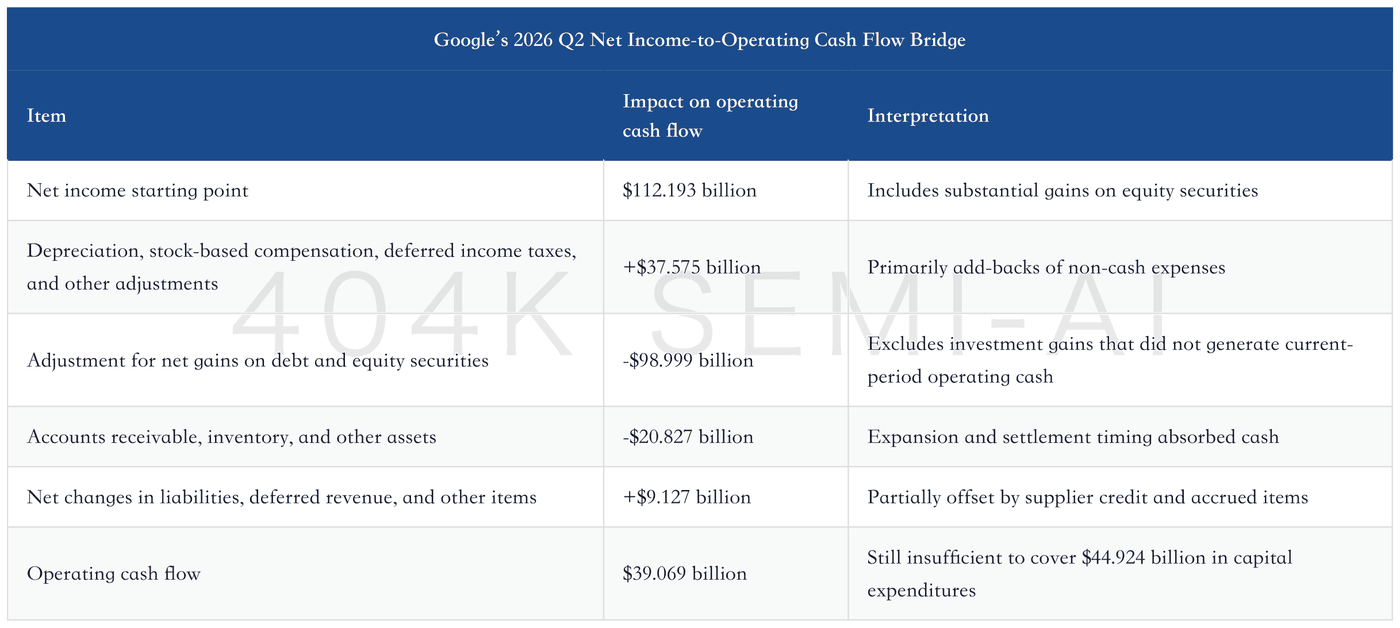
The operating cash flow-to-capital expenditure coverage ratio declined from approximately 1.24x a year earlier to roughly 0.87x this quarter. This is a more useful metric for continuous monitoring than simply noting that free cash flow turned negative. If the ratio returns above 1x while inventory and accounts receivable decline, this quarter can be viewed as a timing mismatch at the peak of the investment cycle. If the ratio continues to fall, capital-return risk will deepen even if Cloud revenue maintains strong growth.
The balance sheet also confirms that the company has entered a more capital-intensive expansion phase. From year-end 2025 to the end of June 2026, net property and equipment increased by $74.615 billion, goodwill by $24.448 billion, intangible assets by $7.822 billion, and inventory by $7.552 billion. Total assets increased by $326.702 billion over the six-month period. Cash, cash equivalents, and marketable securities rose by $115.631 billion over the same period, supported both by higher securities valuations and new equity and debt financing. Greater balance-sheet liquidity does not mean that all newly added assets have begun generating cash returns.
The $49.6 Billion Equity Financing Is the Most Easily Overlooked Change in This Earnings Report
In June, Google issued Class A and Class C common shares and mandatory convertible preferred stock, raising combined net proceeds of $49.6 billion. It also issued senior unsecured notes during the second quarter, raising net proceeds of $20.3 billion. The company further established an at-the-market equity offering program of up to $40 billion, primarily to fund tax payments related to employee equity compensation; the program remained unused as of June 30.
Historically, Google typically relied on cash flow from advertising while repurchasing shares. In both the second quarter and first half of 2026, share repurchases were zero, compared with $13.238 billion and $28.306 billion, respectively, in the corresponding periods a year earlier. Meanwhile, Google raised $30.499 billion through common equity and $19.063 billion through mandatory convertible preferred stock in the first half of 2026. Capital allocation has clearly shifted from “operating cash flow plus buybacks” toward “operating cash flow plus external financing.”
This is not a liquidity crisis. At the end of June, Google held $242.474 billion in cash, cash equivalents, and marketable securities, versus $98.165 billion in long-term debt—a surplus of $144.309 billion. The financing appears intended to preserve capacity for concurrent investments in AI infrastructure, acquisitions, inventory buildout, and tax payments associated with employee equity compensation.
However, the financing still carries costs for common shareholders. Common-share issuance increases the share count, preferred stock requires dividends and may convert into common equity, debt adds interest expense, and the at-the-market offering program creates potential dilution. Second-quarter interest expense increased from $261 million a year earlier to $1.278 billion, while the company also accrued $86 million in dividends on mandatory convertible preferred stock. The amounts remain modest for now, but the direction has changed.
Assessing returns on AI capital expenditure therefore requires asking not only whether revenue can grow, but also whether value per share can increase. If Cloud profit expands rapidly and free cash flow recovers, external financing merely accelerates investment in high-return projects. If capital expenditure continues rising while cash flow remains persistently below investment, financing will progressively transfer project risk to common shareholders.
Gemini Has Achieved Scale; It Must Now Prove Revenue and Cost Economics
Google disclosed an unusually broad set of AI usage metrics this quarter: the Gemini App reached 950 million monthly active users, model APIs processed approximately 22 billion tokens per minute, and Gemini Enterprise was deployed at nearly 90% of Fortune 100 companies. Product iteration accelerated markedly, extending from Gemini 3 in November 2025 to Gemini 3.5 Flash, Gemini Omni, Chrome updates, and Genie 3 for subscribers.
These figures are sufficient to show that Google is doing more than merely building computing capacity. Consumers, developers, and enterprise customers are actively using its products, while Cloud revenue and backlog provide evidence of financial conversion. Compared with a year ago, the question has shifted from “Is anyone using Gemini?” to “How much gross profit can each user, token, and enterprise contract generate?”
Official disclosures still omit three critical metrics. First, the number of paying Gemini App users and revenue per user; second, the inference costs and pricing changes associated with token growth; and third, Gemini Enterprise contract values, active seats, and renewal rates. Monthly active users and API volumes can expand rapidly through free features; only conversion rates, depth of usage, and gross margins can demonstrate commercial quality.
R&D; expenses increased 32% year over year to $18.219 billion, outpacing revenue growth of 24%. Losses from unallocated Alphabet-level activities widened from $3.372 billion to $5.789 billion, an increase of 71.7%, primarily reflecting shared AI research, foundation-model development, and technology infrastructure usage costs. Growth in Cloud profit indicates that some investment is already being monetized, while the acceleration in Alphabet-level expenses shows that frontier-model development remains in a highly investment-intensive phase.
The best validation of Gemini’s scale is therefore not another increase in user numbers, but the combined trajectory of Cloud profit and shared AI costs. Cloud operating income increased by $5.988 billion year over year in the second quarter of 2026, while losses from Alphabet-level activities widened by $2.417 billion. This rough segment-level bridge suggests that incremental commercialization profit currently exceeds the increase in shared expenses. However, segment cost allocation is not equivalent to economic attribution, and it cannot support the conclusion that Cloud profit already directly covers all shared AI costs.
Which Forward-Looking Views Were Validated, and Which Need to Be Rewritten?
Citi’s earlier preview argued that Google’s growth resilience would come primarily from Cloud and TPUs, rather than from Search suddenly returning to exceptionally high growth. Second-quarter results support this view: Search grew 17%, Cloud grew 82%, and Cloud’s revenue contribution increased to 20.7%. Cloud’s 35.6% operating margin also exceeded Citi’s 33.5% forecast, indicating that TPU investment and enterprise AI demand did not materially dilute segment margins during the quarter.
The preview’s capital expenditure forecast was similarly accurate. Actual capital expenditure of $44.924 billion was only 0.4% below the $45.1 billion forecast, meaning the AI infrastructure expansion was not a post-earnings surprise. What does need to be rewritten is the cash flow trajectory: Citi expected positive free cash flow, but the actual figure was negative. The company also raised approximately $69.9 billion through equity and debt while suspending share repurchases during the quarter. This indicates that capital requirements extend beyond capital expenditure alone, with working capital and acquisitions also absorbing cash.
The preview also identified Cloud backlog and external TPU sales as key future growth drivers. This quarter’s $514 billion backlog confirms very strong demand, while official segment disclosures confirm that Cloud product revenue primarily comes from TPU systems. However, the company did not disclose TPU unit sales, pricing, customer concentration, or the split between service and hardware revenue, preventing direct validation of a longer-term TPU sales model.
Finally, Citi previously set a $447 price target based on 2027 earnings per share of $15.90 and a 28x P/E multiple. The second-quarter results have one positive and one negative implication for this valuation framework. Stronger-than-forecast Cloud revenue and margins support earnings upgrades, while negative free cash flow, external financing, and potential dilution warrant a higher discount for capital-return risk. Without subsequent guidance and a breakdown of organic Cloud growth, this quarter’s results justify raising expectations for underlying demand rather than simply annualizing quarterly earnings per share of $9.11.
Valuation Requires More Than Earnings Upgrades; the Cash Content of Earnings Must Also Be Reassessed
Citi’s $447 price target is based on 2027 EPS of $15.90 and a 28x P/E multiple. This framework incorporates two independent judgments: whether future earnings can reach $15.90 per share, and whether the market will still pay $28 for every $1 of earnings. Q2 Cloud revenue and profit exceeded expectations, strengthening the first judgment; below-consensus operating cash flow, negative free cash flow, and potential dilution raise the bar for the second.
This quarter’s $9.11 EPS cannot be used directly in the valuation model. Mechanically excluding the company-disclosed $6.26 per-share impact from investment gains yields comparable EPS of approximately $2.85, slightly below Citi’s $2.90 forecast. This indicates that core earnings did not rise nearly as dramatically as the headline figure suggests. Meanwhile, Cloud operating income of $8.814 billion significantly exceeded expectations but was partly offset by other businesses and shared investments: Google Services generated $39.544 billion in operating income, bringing the total with Cloud to $48.358 billion. After deducting a $1.799 billion loss from Other Bets and a $5.789 billion loss from Alphabet-level activities, consolidated operating income was $40.77 billion.
This profit bridge means the valuation should not reward Cloud growth alone. For every additional $1 of Cloud profit, the increase in free cash flow attributable to each common share will be smaller than the increase in segment profit if it also requires greater shared model R&D;, depreciation, working capital, and external financing. Conversely, if Cloud sustains a margin of approximately 35%, the growth of Alphabet-level AI expenses slows, and inventories and receivables release cash, this quarter’s investment could translate into higher-quality group earnings.
Changes in the share count also have a lagged impact. Common shares outstanding reached 12.23 billion at the end of June, up 142 million from year-end 2025; diluted EPS this quarter was calculated using 12.309 billion weighted-average shares, up approximately 0.9% year over year. Not all of this increase can be attributed to the June financing, but the June issuance entered the weighted-average calculation only partially near quarter-end. The potential impact of future preferred-share conversions and the $40 billion at-the-market offering program is also not fully reflected in this quarter’s EPS. Therefore, even if analysts raise group net-income estimates, they must also review diluted-share-count assumptions rather than treating incremental profit as an equivalent increase in EPS.
A more practical valuation approach is to divide outcomes into three scenarios. The first is continued high Cloud growth and margins, operating cash flow once again covering capital expenditures, and no further expansion of equity issuance. In this case, earnings upgrades and a stable valuation multiple can coexist. The second is continued upgrades to revenue and segment profit, but slow cash conversion and ongoing financing. EPS may still grow, but the valuation multiple would come under pressure as capital intensity rises. The third is Cloud growth driven increasingly by hardware or acquisitions, declining margins, and rising unit costs in Search. In that case, both earnings forecasts and the valuation multiple would be revised downward. The key task after the earnings release is not to select an optimistic figure, but to determine which scenario the company is moving toward.
The Next Six Sets of Numbers Matter More Than a Single Day’s Share-Price Move
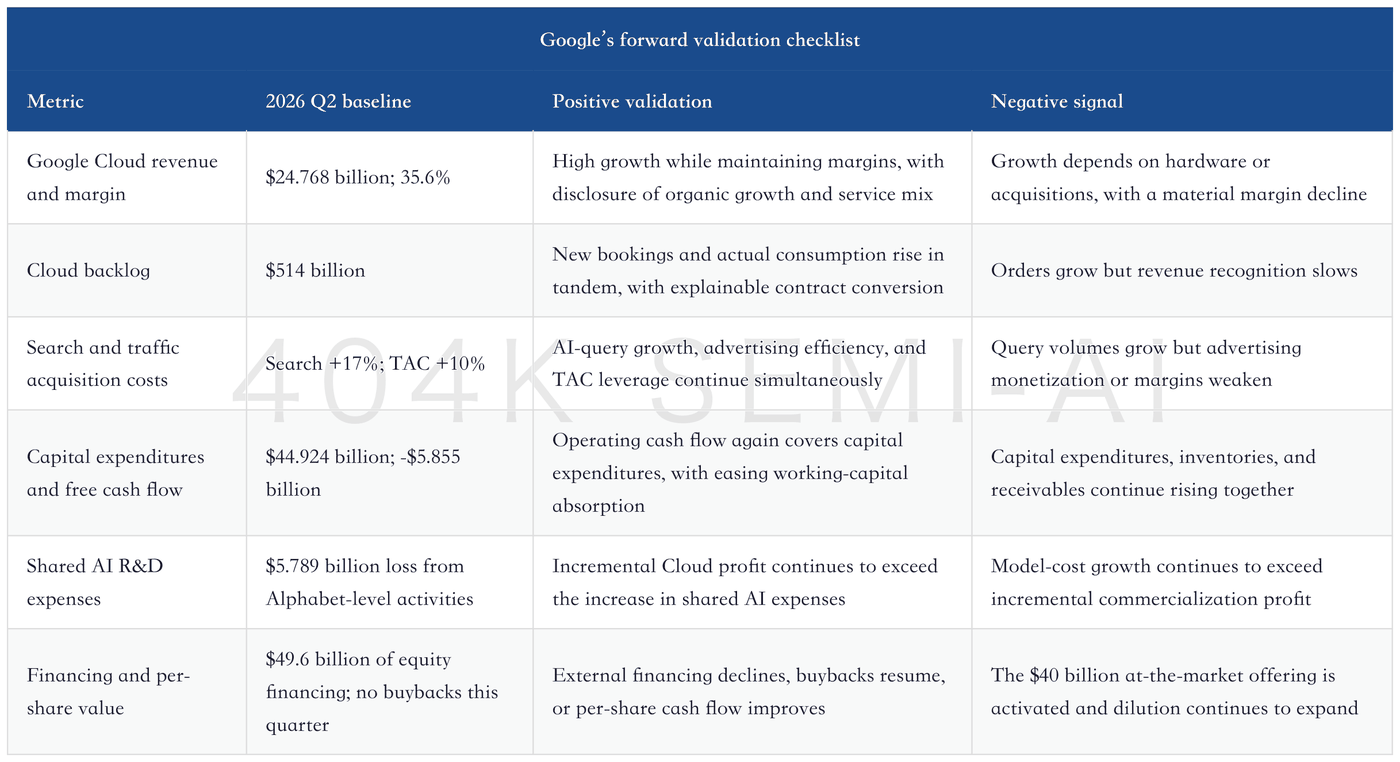
These six sets of numbers form a simple sequence: first assess whether demand continues to grow, then whether that demand converts into high-quality revenue; next determine whether profit can cover R&D;, and finally whether cash can cover capital expenditures. Any growth that clears only the first two hurdles but not the latter two may raise revenue forecasts while reducing cash-flow-based valuations.
The Risk Is Not That AI Fails, but That Success Becomes Too Expensive
The first risk is earnings quality. The $99.031 billion gain on equity securities makes net income and EPS incomparable, and future adverse market-price movements could generate losses. Simply annualizing the $9.11 EPS would overstate operating earnings power.
The second risk is the composition of Cloud growth. The 82% growth rate may include contributions from cloud services, TPU systems, and acquisitions. Margins were strong this quarter, but hardware cycles, customer concentration, and acquisition integration could make growth more volatile than in a traditional subscription business.
The third risk is cash conversion. Capital expenditures were already largely anticipated by the market; operating cash flow and working capital were the quarter’s real surprises. If inventories and receivables do not convert into revenue and cash in subsequent quarters, negative free cash flow will persist longer.
The fourth risk is dilution. The simultaneous issuance of common shares, mandatory convertible preferred shares, and debt, together with the potential at-the-market offering, indicates that Google is willing to use its capital structure to accelerate AI expansion. If project returns are sufficiently high, this approach can create value; if returns fall short, common shareholders will face both valuation compression and a reduced ownership percentage.
The fifth risk is reliance on mature businesses for funding. Google Services still generated $39.544 billion in operating income and remains the primary source of cash for AI expansion. If Search advertising slows because of competition, regulation, or rising AI-query costs, Cloud will need to assume responsibility for profit and cash flow more quickly.
The sixth risk is insufficient disclosure. The two official materials did not provide Q3 revenue guidance, a full-year capital-expenditure target, organic Cloud growth, TPU sales, Gemini’s paid conversion rate, or the unit cost of AI queries. The earnings release presented the results but did not fully lay out the path to future returns. Missing information is itself part of the valuation uncertainty.
Conclusion: Revenue Has Delivered; Cash Flow Still Has More to Prove
The strongest evidence from Google’s 2026 Q2 results is not the 298% increase in net income, but the combination of 82% Cloud revenue growth, a Cloud margin of 35.6%, and continued 17% growth in Search. This indicates that Google’s AI investment is simultaneously supporting consumer products, enterprise cloud, and core Search, with no near-term substitution effect in which the new business grows while the legacy business collapses.
The most important warning sign is also not the $44.924 billion in capital expenditures itself. That figure was almost entirely in line with pre-earnings expectations. The real change was that operating cash flow failed to keep pace, quarterly free cash flow turned negative, the company raised approximately $69.9 billion through equity and debt financing, and buybacks ceased. Google is using a heavier balance sheet and a longer cash-conversion cycle to secure faster AI expansion.
Therefore, these results cannot simply be categorized as a comprehensive beat, nor should negative free cash flow be interpreted as evidence that AI spending has failed. A more accurate assessment is that demand and profit have already provided strong validation, while the return on capital has completed only the first half of the journey. If Cloud continues to sustain high margins, Search unit economics do not deteriorate, and operating cash flow once again covers capital expenditures, this financing and expansion could prove to be a high-return investment. If revenue estimates continue rising while cash flow and dilution keep deteriorating, the market will ultimately reprice the same growth from high-quality cloud revenue into an expensive capital race.