
AI Storage Deep Dive Update: Morgan Stanley’s May HDD and SSD Data Confirm Data Center Capacity Demand Remains Elevated
目录
Too Long; Didn’t Read
1. What the May Data Answers: Has AI Storage Demand Fallen?
2. HDDs and SSDs Are Not a Zero-Sum Replacement Cycle, but Tiered Expansion of the AI Data Stack
3. Why Capacity Growth Matters More Than Unit Growth
4. HDD Chain: High-Capacity Nearline Drives Are More Worth Tracking Than Total HDD Units
V. Enterprise SSDs: NAND’s Real Strength Is Data Centers, Not Consumer SSDs
VI. Putting HDD and eSSD in the Same Ranking Table
7. Three Worldviews: Cyclical Peak, Structural Re-Rating, Extreme Shortage
8. Falsification Checklist: What to Watch Over the Next Four Quarters
9. From Monthly Data to the Model: How Profit Transmits
10. Risks: Strong Data Can Still Be Offset by Valuation and Supply Response
11. Conclusion: May Data Moves AI Storage from Narrative Back to Physical Validation
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Morgan Stanley’s May HDD and SSD monthly data adds hard evidence to the storage trade: data center capacity demand remains elevated, and nearline HDDs and enterprise SSDs are not cannibalizing each other. Instead, each is becoming scarcer in the AI data stack. The key metrics to track are not monthly unit shipments, but EB capacity, drive capacity, customer visibility, and pricing discipline.
Too Long; Didn’t Read
Data center storage has not weakened. May nearline HDD production reached 7.07mn units, +14.8% YoY and +4.0% MoM; enterprise SSD capacity shipments reached 41.35EB, +138.8% YoY and +9.7% MoM. The read-through is direct: cloud vendors are still taking capacity, and AI training, inference, video, logs, and object storage have not seen a demand cliff.
HDDs and SSDs coexist in tiers. Morgan Stanley divides data center storage into three layers: SSD, HDD, and tape. This is closer to reality than the old “SSD replaces HDD” narrative. Enterprise SSDs handle high throughput, low latency, and hot data; nearline HDDs handle large capacity, low cost, and cold/warm data; tape handles long-term archival. The larger AI data volumes become, the more all three layers are pulled higher.
Capacity matters more than units. 2026 data center enterprise SSD capacity shipments are forecast at 509.33EB, +94.0% YoY; data center nearline HDD capacity shipments are forecast at 1,841EB, +30.1% YoY. Unit shipments do not look as dramatic, but higher drive capacity, a rising helium drive mix, and higher average enterprise SSD capacity drive EB growth far above unit growth.
The HDD re-rating remains supported by data. Total HDD production rose +6.9% YoY in May, but nearline HDDs rose +14.8% YoY and helium nearline drives rose +22.5% YoY. Growth is coming from high-capacity cloud drives, not traditional PC and consumer drives. The value of HDD suppliers is not only in price increases, but also in the industry’s ability to use limited supply to serve a more durable long-term capacity demand base.
Enterprise SSDs validate NAND upside. Total SSD unit shipments fell -0.5% YoY in May, but enterprise SSD unit shipments rose +45.8% YoY and capacity shipments rose +138.8% YoY. This shows sharp divergence within NAND demand. Consumer SSDs and PC SSDs cannot represent data center eSSD demand. Valuation divergence across SanDisk, Kioxia, Micron, and Samsung should center on enterprise SSD share and the quality of long-term agreements.
The component chain has extension optionality. Japanese electronics component companies such as TDK, Nidec, Minebea Mitsumi, HOYA, and Resonac do not sell complete HDD systems directly, but they benefit from demand for heads, motors, glass substrates, and media in high-capacity drives. The key is not total HDD units, but the fact that each HDD needs more heads and platters. The high-capacity roadmap raises component value content.
The falsification points are clear. If enterprise SSD capacity growth later falls back to ordinary SSD levels, helium nearline HDD growth slows, cloud customer inventory rises quickly from 1-2 weeks, or price/TB can no longer rise sequentially by quarter, the storage re-rating will revert to a traditional cycle. If EB capacity continues to grow strongly and suppliers avoid expanding greenfield capacity, the market will continue to reduce the cyclical discount applied to HDD and eSSD earnings.
1. What the May Data Answers: Has AI Storage Demand Fallen?
The most valuable part of the May HDD and SSD data is that it pulls the statement “AI storage remains very strong” back from company guidance into monthly shipments. Company calls can be emotional, and target-price increases can lag. Monthly industry data is better suited to verifying whether the trend is still intact. Morgan Stanley’s conclusion is clear: data center storage continues to grow in tiers, with both nearline HDDs and enterprise SSDs still at elevated levels.
This is not a grand narrative report. Its value lies in the granularity of the monthly data: total HDDs, nearline HDDs, helium drives, total SSD shipments, enterprise SSD units, enterprise SSD capacity, HDD heads, motors, media, and supplier share are all updated. For investors, this is more useful than a simple statement that “AI demand is strong,” because it shows which layer is strong, which layer is merely stable, and which layer is already declining.
The May data first gives an overall outline: total HDD production is still growing moderately, with nearline HDDs the strongest segment; total SSD unit shipments are slightly weak, but enterprise SSDs are the strongest segment within SSDs. In other words, end-consumer storage is not seeing a broad synchronized recovery. The real strength is in the data center capacity layer.
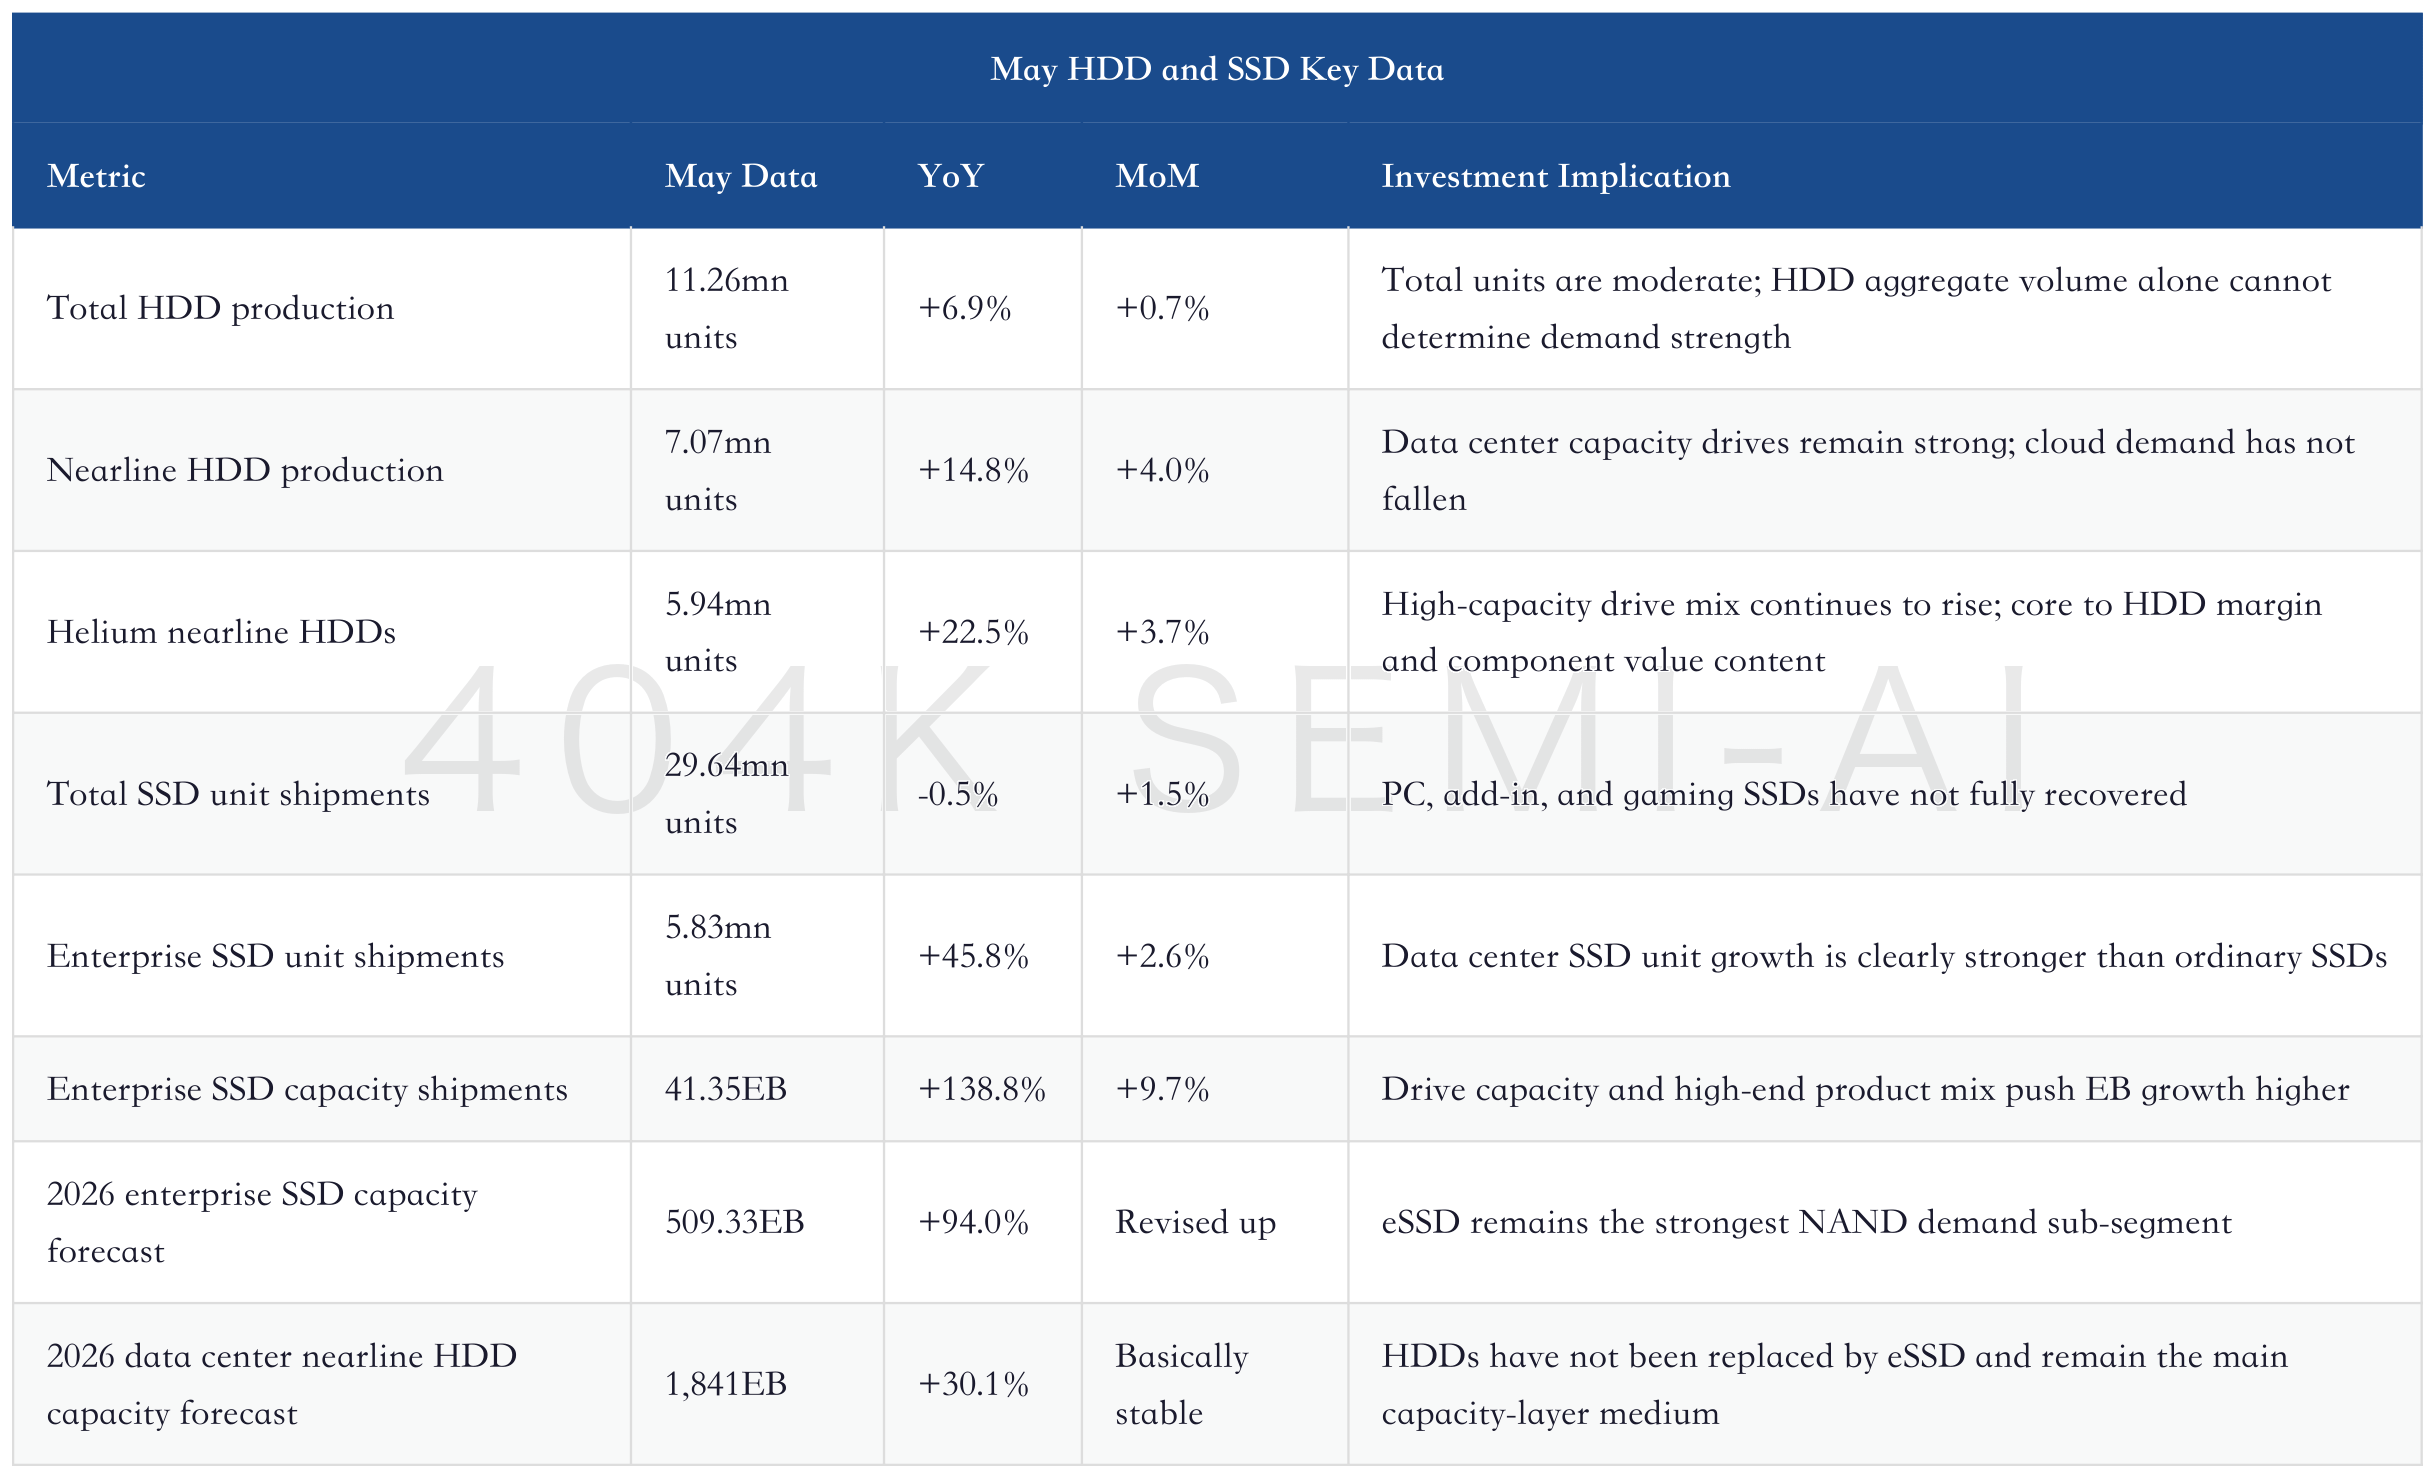
The most easily overlooked point is the difference between units and capacity. Both HDDs and SSDs are entering a phase in which units look flat while capacity rises quickly. HDDs rely on drive capacity, helium drives, more platters, and higher areal density; SSDs rely on higher average enterprise product capacity. Investors who only look at units will underestimate the real revenue and earnings elasticity of this storage cycle.
AI Is Driving a Storage Industry Re-rating: Who Has the Most Pricing Power Across DRAM, NAND, SSD, and HDD, as Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Results Cross-Validate Each Other
This also explains why the May data does not overturn the earlier storage-series framework. The AI data stack is pulling not only HBM, nor is it simply driving a single NAND price increase. The real change is happening in the data itself: model training requires checkpoint storage, inference requires context caching, video and multimodal data create larger cold/warm data pools, and enterprise applications turn logs, vectors, retrieval, and permission states into persistent assets. The more data there is, the more systems need to place data with different access frequencies into different tiers.
Morgan Stanley’s monthly data validates exactly this point. Nearline HDDs did not lose momentum because enterprise SSDs were strong, and enterprise SSDs did not lose momentum because HDDs were strong. Both are growing together, showing that cloud vendors are not simply replacing one medium with another, but expanding the entire storage pyramid.
2. HDDs and SSDs Are Not a Zero-Sum Replacement Cycle, but Tiered Expansion of the AI Data Stack
The storage bottleneck in AI data centers is not “HDD or SSD,” but the need to expand every data tier. The market used to like the SSD-replaces-HDD story because in PCs and consumer electronics, the user-experience gap was obvious enough. Data centers do not follow that logic. A hyperscale cloud platform simultaneously needs high performance, low latency, high capacity, low cost, low power, and long-term retention. A single medium struggles to satisfy all of these at once.
Enterprise SSDs are advantaged in hot and warm data. Model weights, vector databases, caches, RAG retrieval, online inference state, training intermediate files, database logs, and high-frequency access data all require higher throughput and lower latency. Here, NAND’s value shifts from “cheap capacity” to a “system performance variable.” This is why enterprise SSD unit shipments rose only 45.8%, while capacity rose 138.8%: customers are buying larger and higher-value drives.
Nearline HDDs are advantaged in large capacity and cost. Not all AI-generated data needs low-latency access. Training corpora, video, images, logs, synthetic data, archived objects, infrequently accessed data lakes, and backups all require storage at scale. HDDs still have a TCO advantage, especially when NAND prices are also rising. That makes HDD’s capacity-layer value even clearer.
Tape is the longer-duration archival layer. It does not directly determine the listed-company upside in this report, but Morgan Stanley’s inclusion of tape in data center storage tiering is an important reminder: AI data centers will not be dominated by a single medium. Data access frequency and retention period determine medium selection.
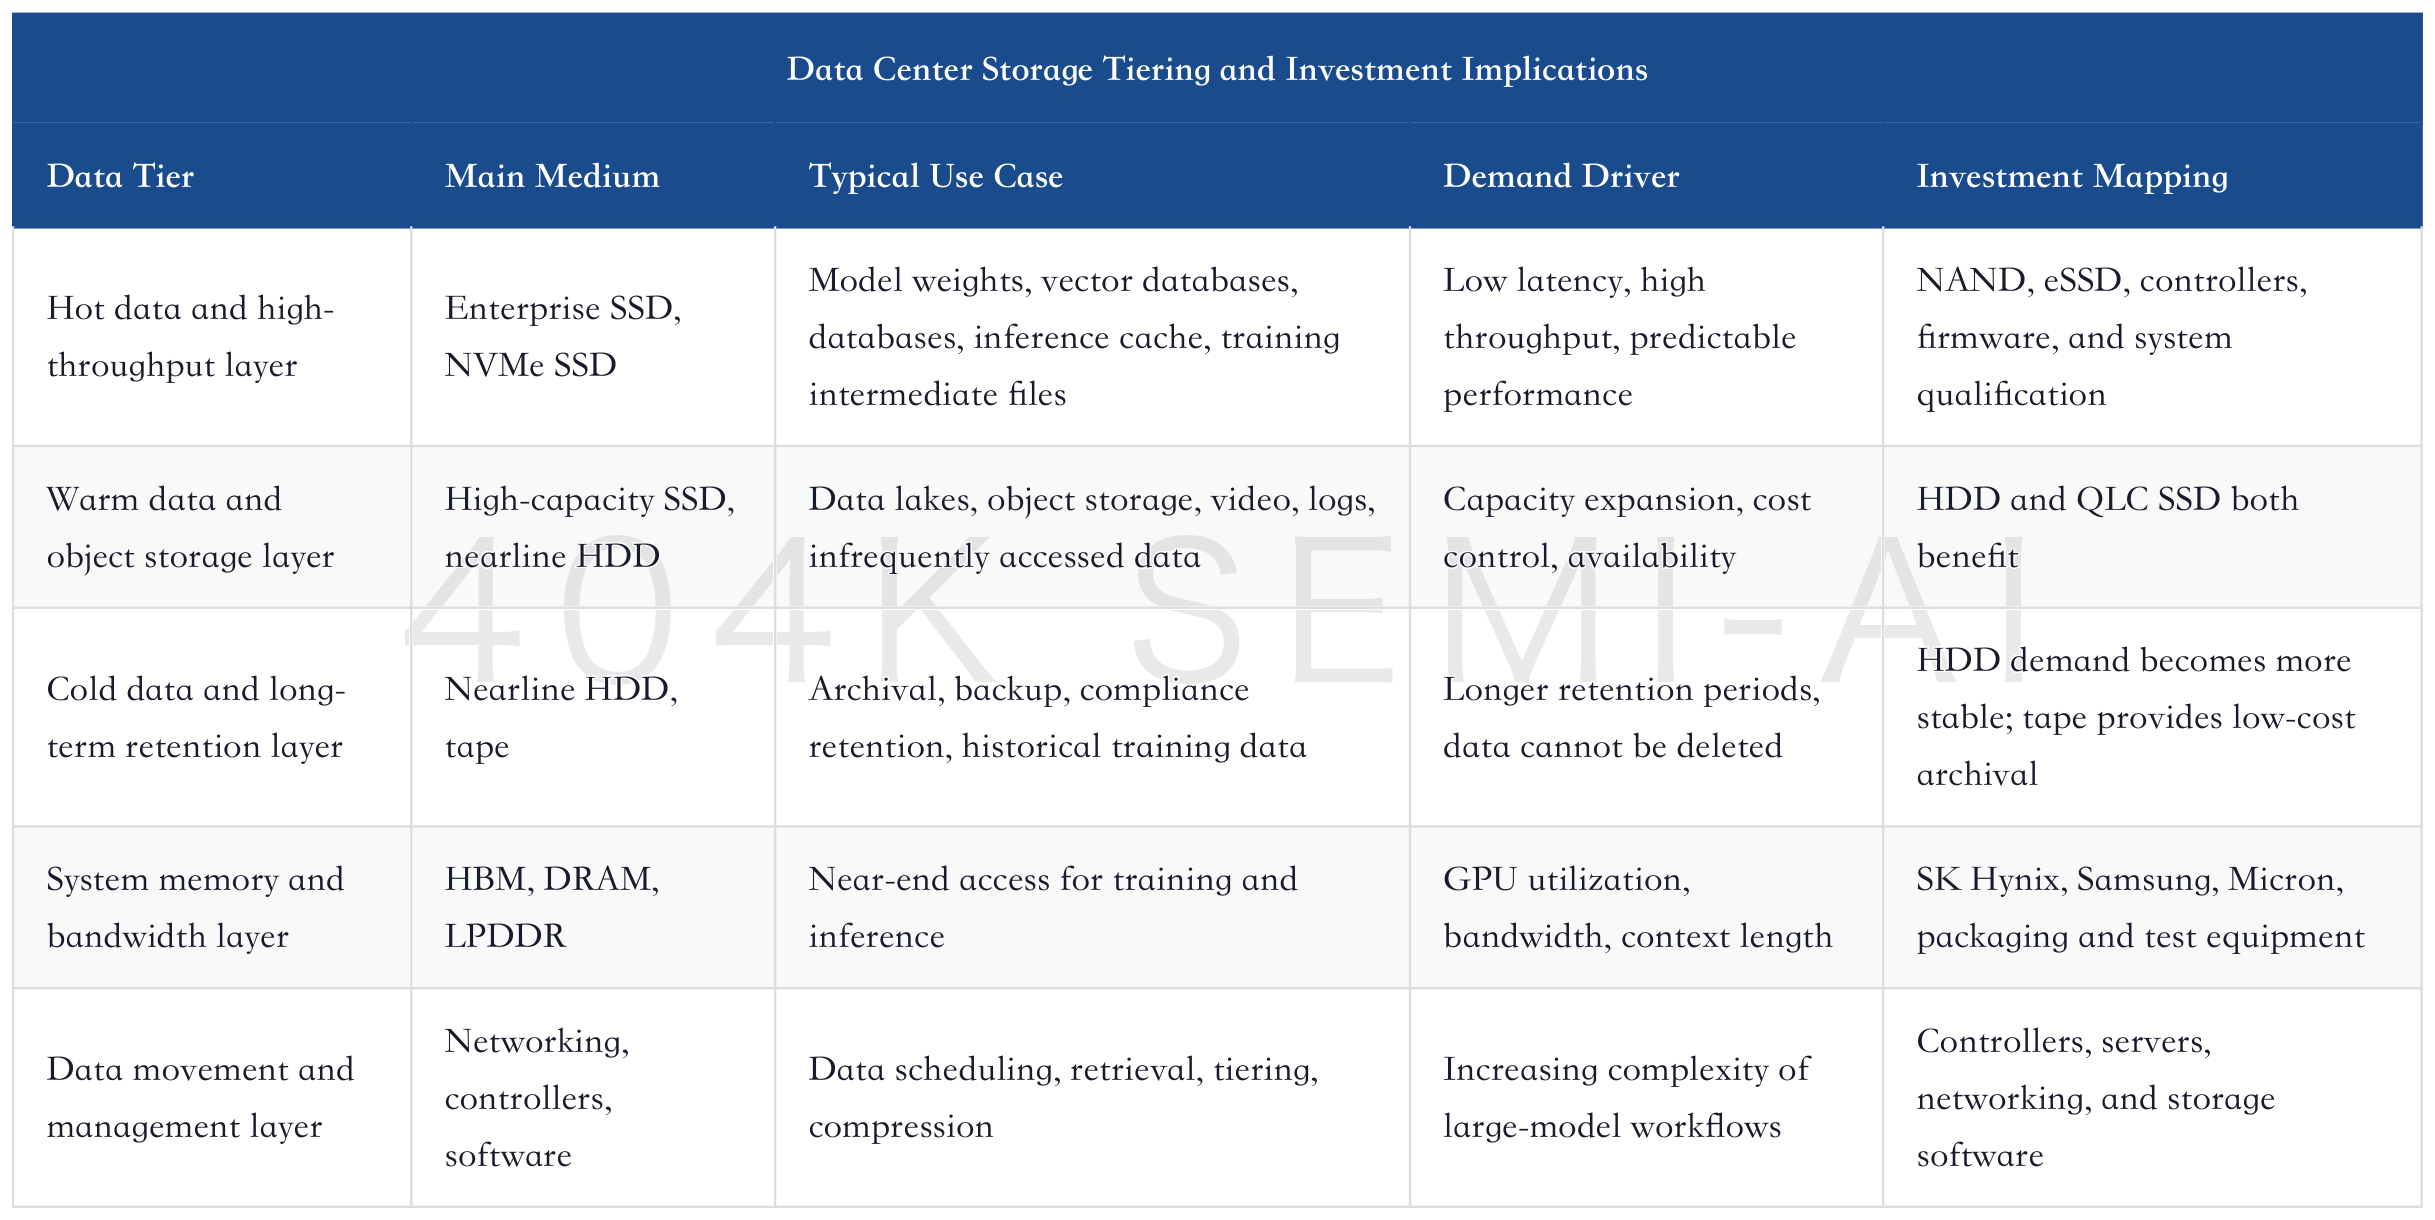
The key in this table is not to label every medium a beneficiary, but to distinguish the logic of each benefit. HBM and DRAM are closer to compute bandwidth, enterprise SSDs are closer to performance storage, HDDs are closer to low-cost capacity, and tape is closer to archival insurance. They all belong to the AI data stack, but their valuations and falsification points are different.
This is also the fundamental reason why HDDs and eSSDs can both be strong right now. SSDs entering data centers do not mean HDD demand must disappear; tight HDD supply does not mean enterprise SSDs have no room. The real demand in AI data centers is expansion of the total capacity pool, not share-grabbing within the same pool. As long as data generation grows faster than medium substitution, multiple storage media will remain tight at the same time.
This view is consistent with Morgan Stanley’s April data. The April report had already pointed in the same direction: data center demand remained strong, with 2026 enterprise SSD capacity shipments then forecast at 476.1EB and data center nearline HDD capacity at 1,844EB. The May report raises the enterprise SSD capacity forecast to 509.33EB, while nearline HDDs still maintain roughly 30% growth. The incremental change comes from another upward revision to eSSD forecasts, not an HDD collapse.
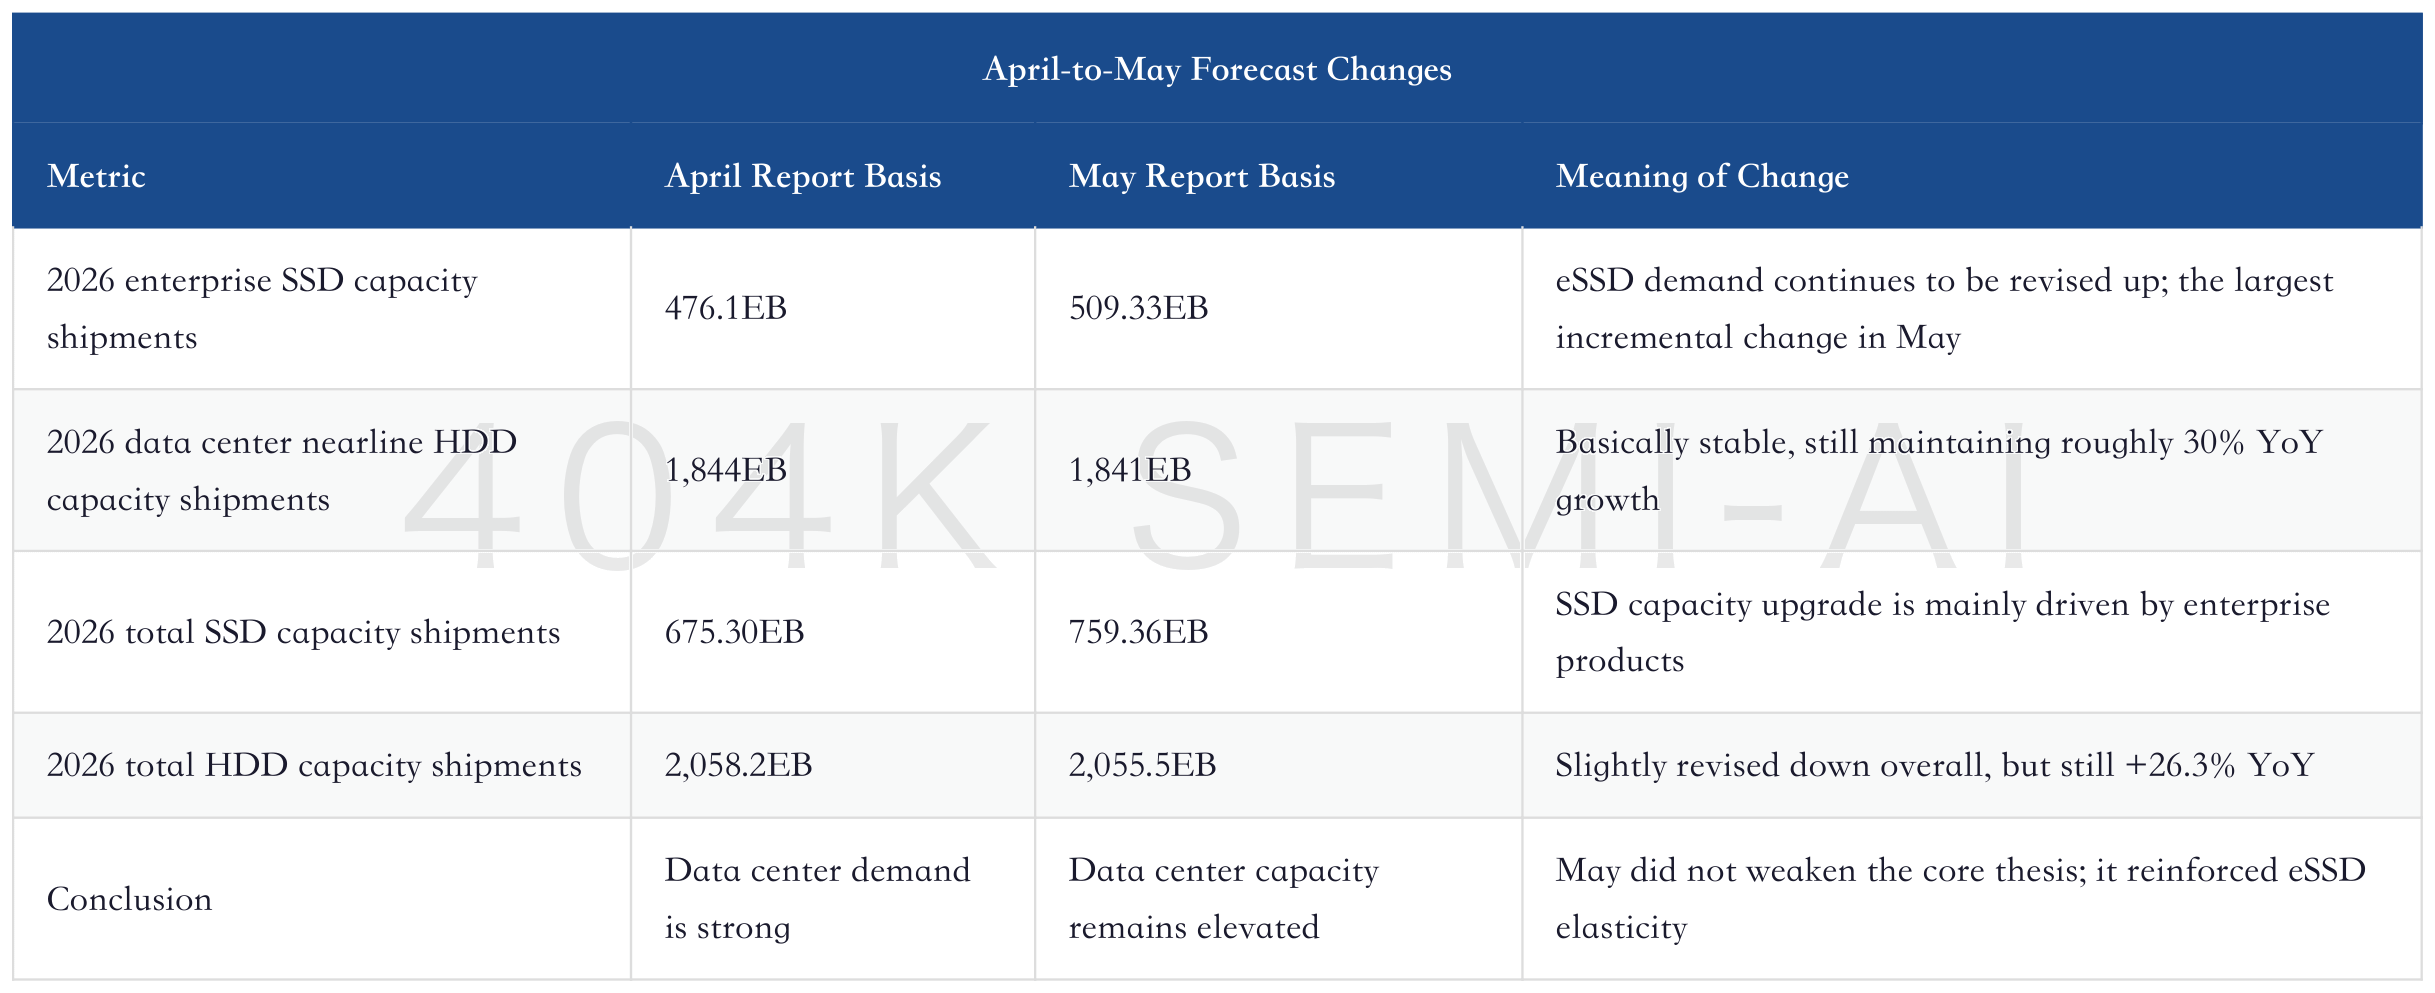
This set of changes is important. The fact that nearline HDD forecasts were not revised up sharply again may mean near-term supply is already relatively locked in. The continued upward revision to enterprise SSD forecasts shows that the slope of AI-driven NAND demand is still being re-understood by the market. HDDs reflect scarcity and pricing more, while eSSDs reflect capacity and share more.
3. Why Capacity Growth Matters More Than Unit Growth
What storage companies really sell is EB and value, not simply units. Traditional hardware analysis tends to start with shipment units, which is useful for PCs, smartphones, and ordinary consumer electronics. But for HDDs and enterprise SSDs, unit shipments can no longer explain revenue. A higher mix of high-capacity drives, rising average capacity for enterprise SSDs, and the expansion of helium drives and multi-platter architectures all allow capacity growth to far exceed unit growth.
Total HDD production in May increased only 6.9% YoY, which does not look particularly impressive. But nearline HDDs grew 14.8% YoY, and helium nearline HDDs grew 22.5% YoY. More importantly, Morgan Stanley’s HDD capacity shipment forecast shows total HDD capacity at 1,627.9EB in 2025, above 2,000EB in 2026, and continuing to rise in 2027 and 2028. In other words, HDD industry units can be close to stable, while capacity and price/TB can still drive revenue and profit.
The same logic applies to enterprise SSDs. Enterprise SSD unit shipments in May were already strong at +45.8% YoY; capacity shipments were even stronger at +138.8% YoY. This embeds two variables: data center customers are buying more enterprise drives, and average capacity is rising significantly. The latter is critical for NAND vendors, because high-capacity enterprise SSDs usually have higher qualification barriers, more complex firmware, stronger controller requirements, and higher customer stickiness.
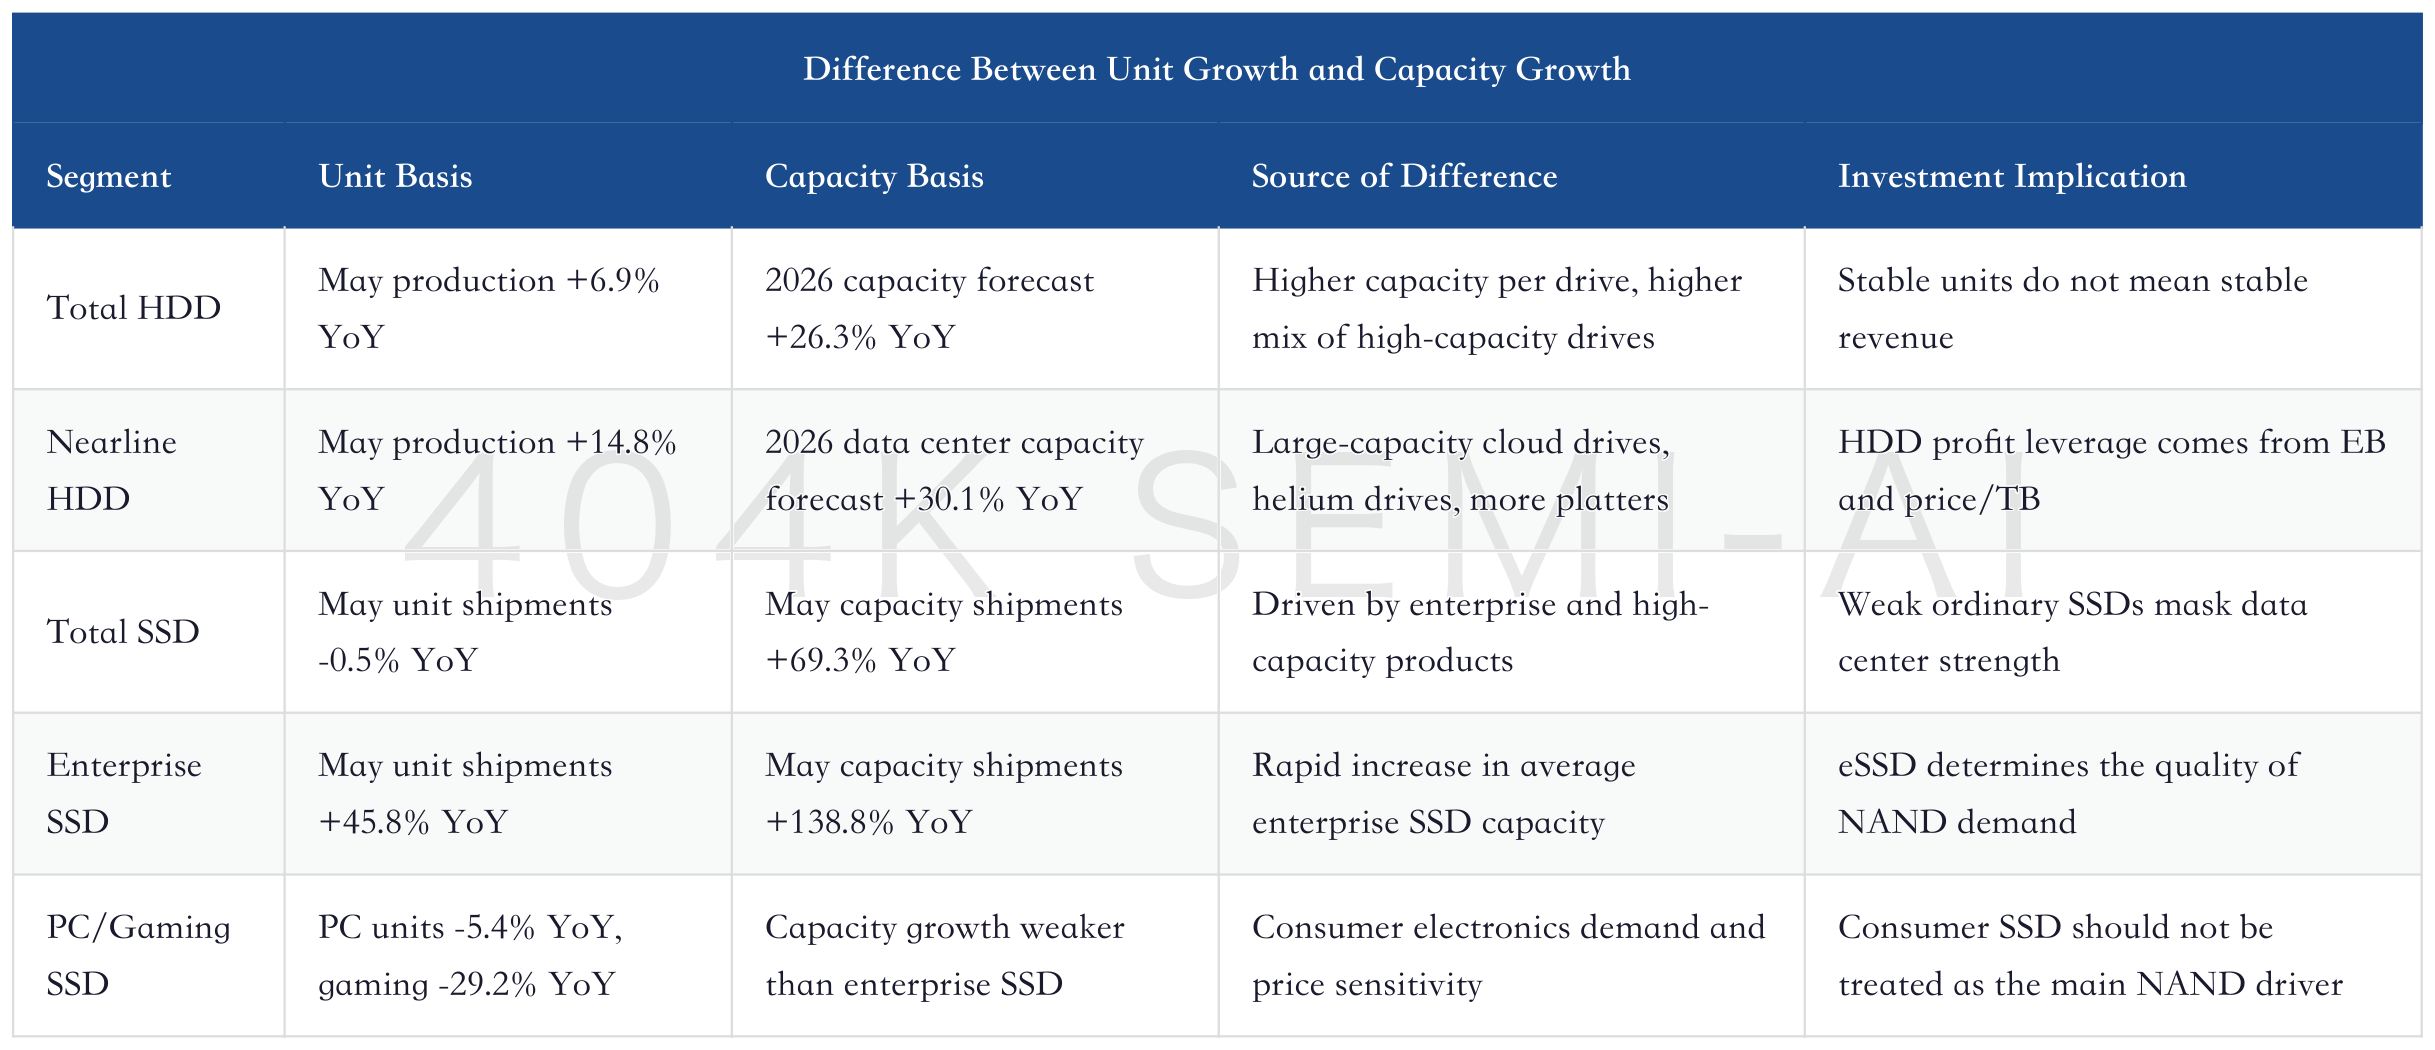
This table shows that after storage enters the AI cycle, investors need to shift the analytical unit from “units” to “capacity, pricing, and profit quality.” HDD units are unlikely to recover to levels seen ten years ago, but that does not stop HDDs from becoming scarce capacity assets in AI data centers. Total SSD units can even decline, while enterprise SSDs still lift the slope of NAND demand.
Global Storage Deep Dive: 2Q26 Earnings Divergence, and Whether 3Q Pricing Improvement Can Restart Storage Stock Re-Rating
This also affects valuation. Traditional cyclical valuations focus on the pricing cycle: estimates are revised up when prices rise and revised down when prices fall. AI storage valuation needs one additional layer: whether customers are buying higher-capacity, higher-value products with longer qualification cycles. If so, profit volatility still exists, but the cyclical discount can decline.
4. HDD Chain: High-Capacity Nearline Drives Are More Worth Tracking Than Total HDD Units
The core of this HDD re-rating is not a recovery in PC hard drives, but the transformation of nearline capacity drives into long-duration capacity assets for cloud customers. Total HDD production in May was 11.26 million units, +6.9% YoY, of which nearline HDD production was 7.07 million units, +14.8% YoY. This means nearline drives have already become the most important growth source for the HDD industry.
Looking one level deeper, nearline HDDs are also upgrading internally. Helium nearline drives reached 5.94 million units in May, +22.5% YoY; air drives were 1.13 million units, -13.7% YoY. This shows industry growth is coming from higher-capacity, higher-value products. For the supply chain, helium drives and high-capacity drives typically mean more heads, more platters, more complex structures, and higher reliability requirements, lifting component value content accordingly.
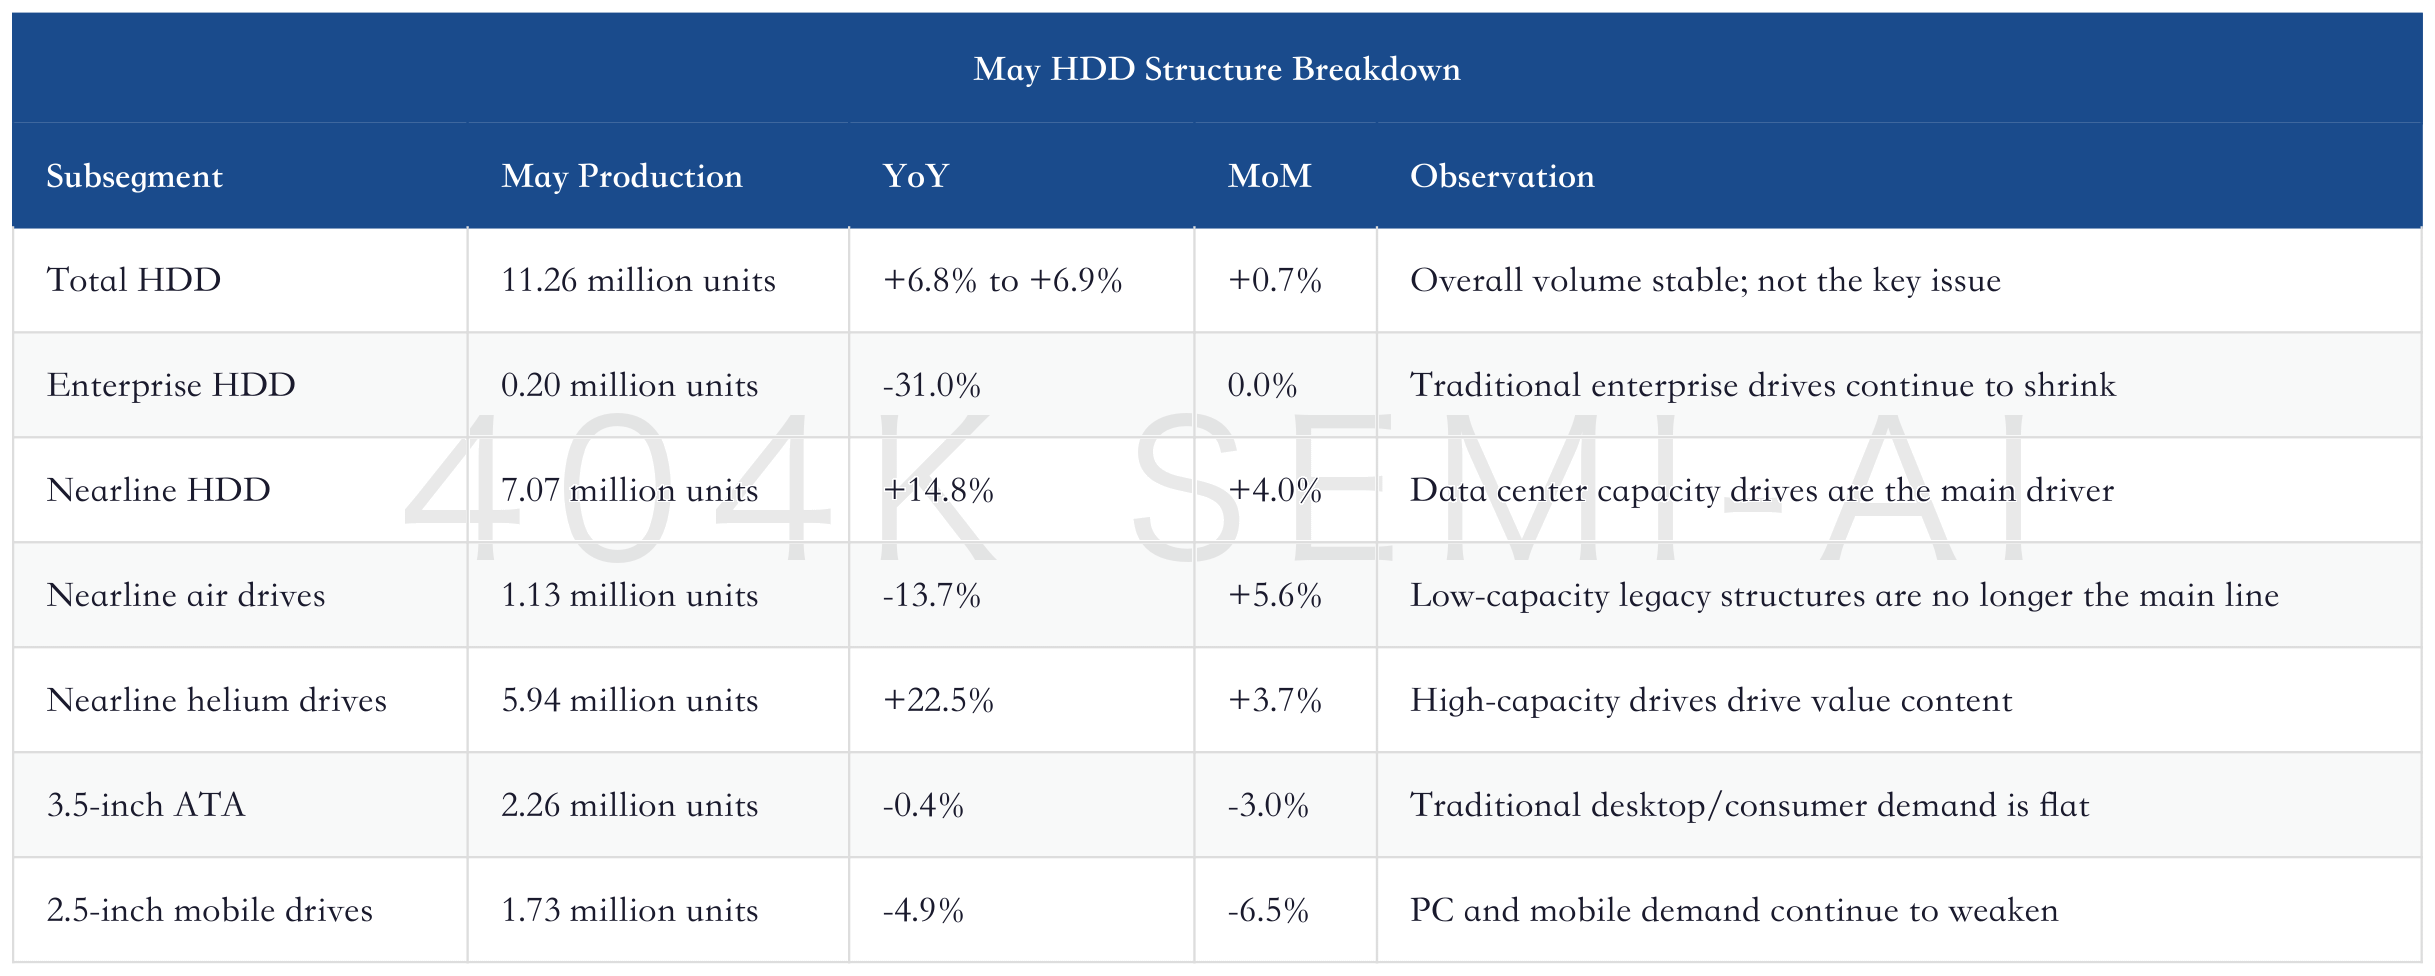
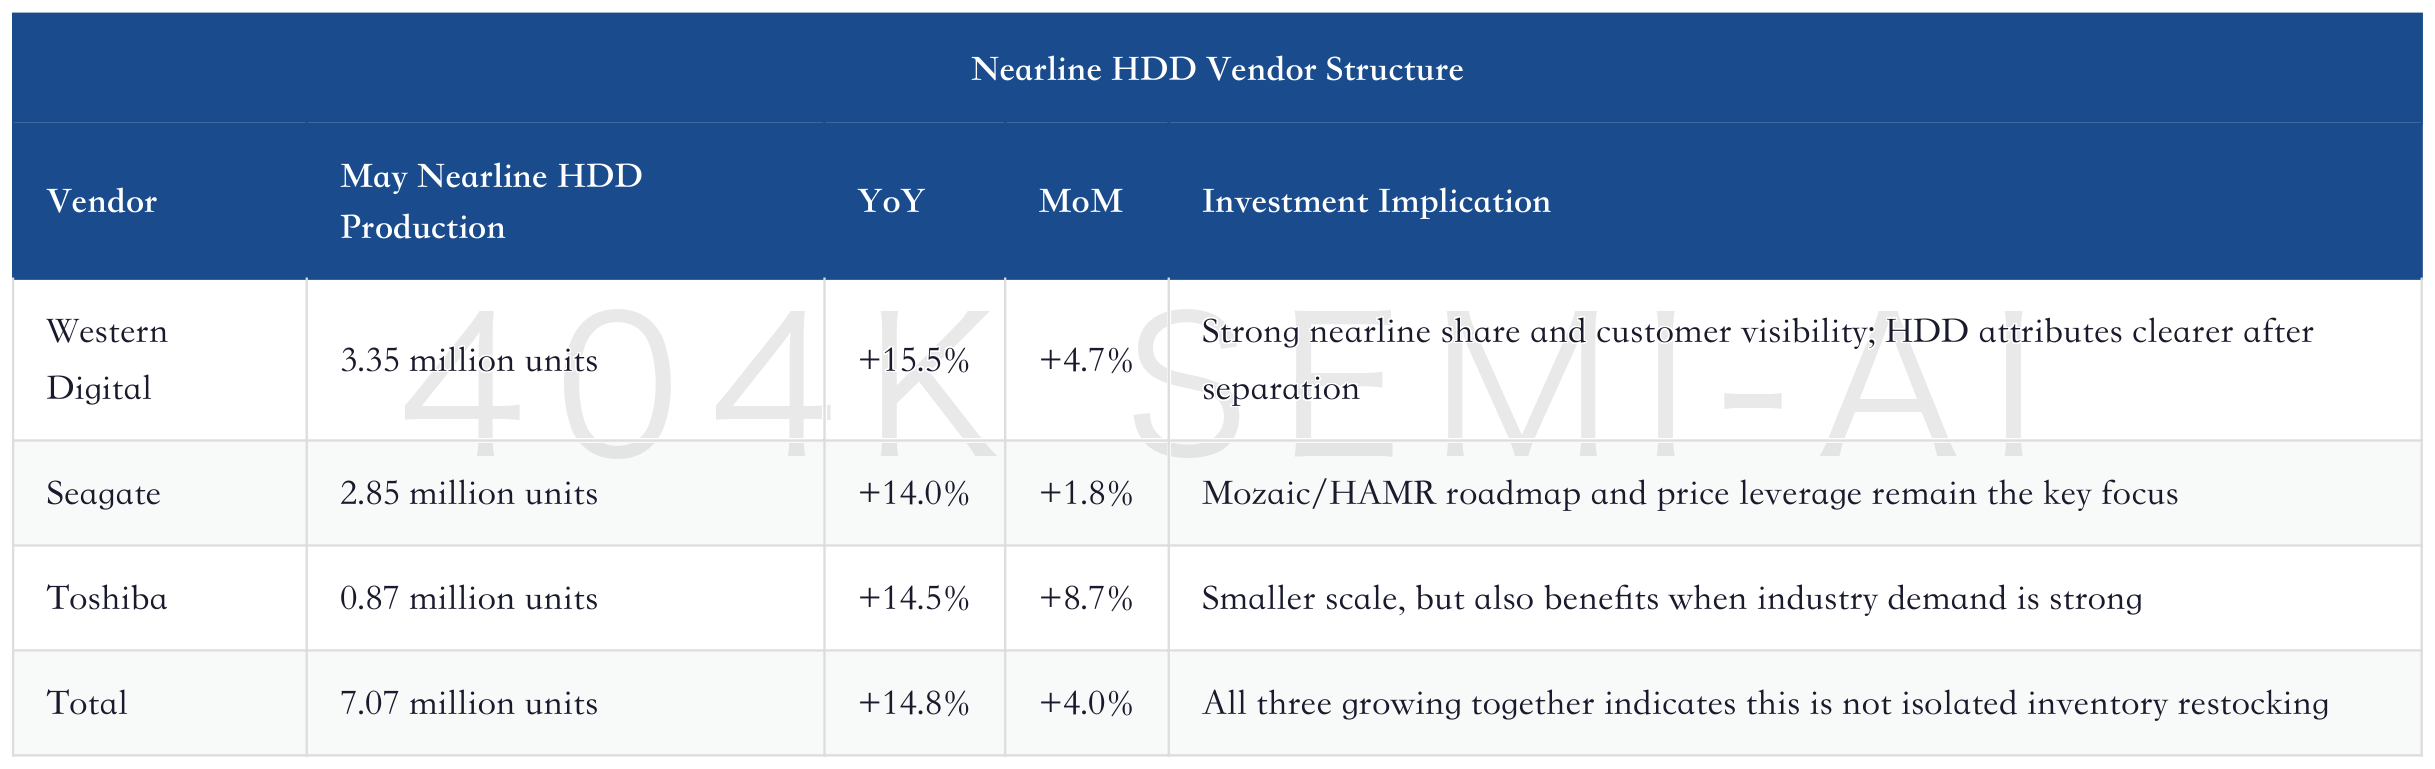
Vendor structure also points to synchronized growth. Western Digital, Seagate, and Toshiba all expanded nearline HDD production in May, indicating this is not a share fluctuation at a single company but broad industry demand at a high level. The specific figures are shown in the table below.
Western Digital Deep Dive: From 2032 Visibility to Re-Rating as a Scarce HDD Asset
HDD pricing power comes from supply discipline and customer visibility. Morgan Stanley’s U.S. hardware team previously noted in its HDD report that Asian channel checks suggested nearline HDD demand could grow close to 40%-50% annually, while supply EB growth was closer to 30%-35%; customers want to see capacity visibility out to 2032, but suppliers are not rushing to lock in long-term commercial terms. Western Digital management also noted during roadshows that customers are providing longer visibility, ODM inventory is only 1-2 weeks, and supply will not be solved through new greenfield capacity.
Japan’s May electronic components data provided monthly validation of this theme. Nearline HDD production is still growing, high-capacity helium drives are stronger, and HDD head, media, and motor data do not show a demand cliff. For the HDD chain, this is not a simple story of “cyclical stocks raising prices,” but a change in cash-flow quality as limited supply serves longer-duration demand.
HDD Price Hike Again: AI Data Retention, 2032 Visibility, and the Upgrade Logic for Seagate and Western Digital
This point is most direct for Seagate and Western Digital. Seagate looks more like a high-purity HDD cash-flow asset, with its technology roadmap and price/TB leverage as the core. Western Digital is also purer after the spin-off, but its investment narrative emphasizes customer visibility, the dual-track UltraSMR/HAMR roadmap, and capital returns. Neither company should still be viewed only through the PC hard-drive cycle.
For the Japanese component chain, the mapping is more granular. TDK still has an important share in HDD heads, Nidec and Minebea Mitsumi dominate motors, and HOYA and Resonac have exposure to glass substrates and media. Morgan Stanley’s report also breaks down the HDD supply chain in detail, because high-capacity drives do not only change the profit profile of system vendors; they also change the component value per drive.
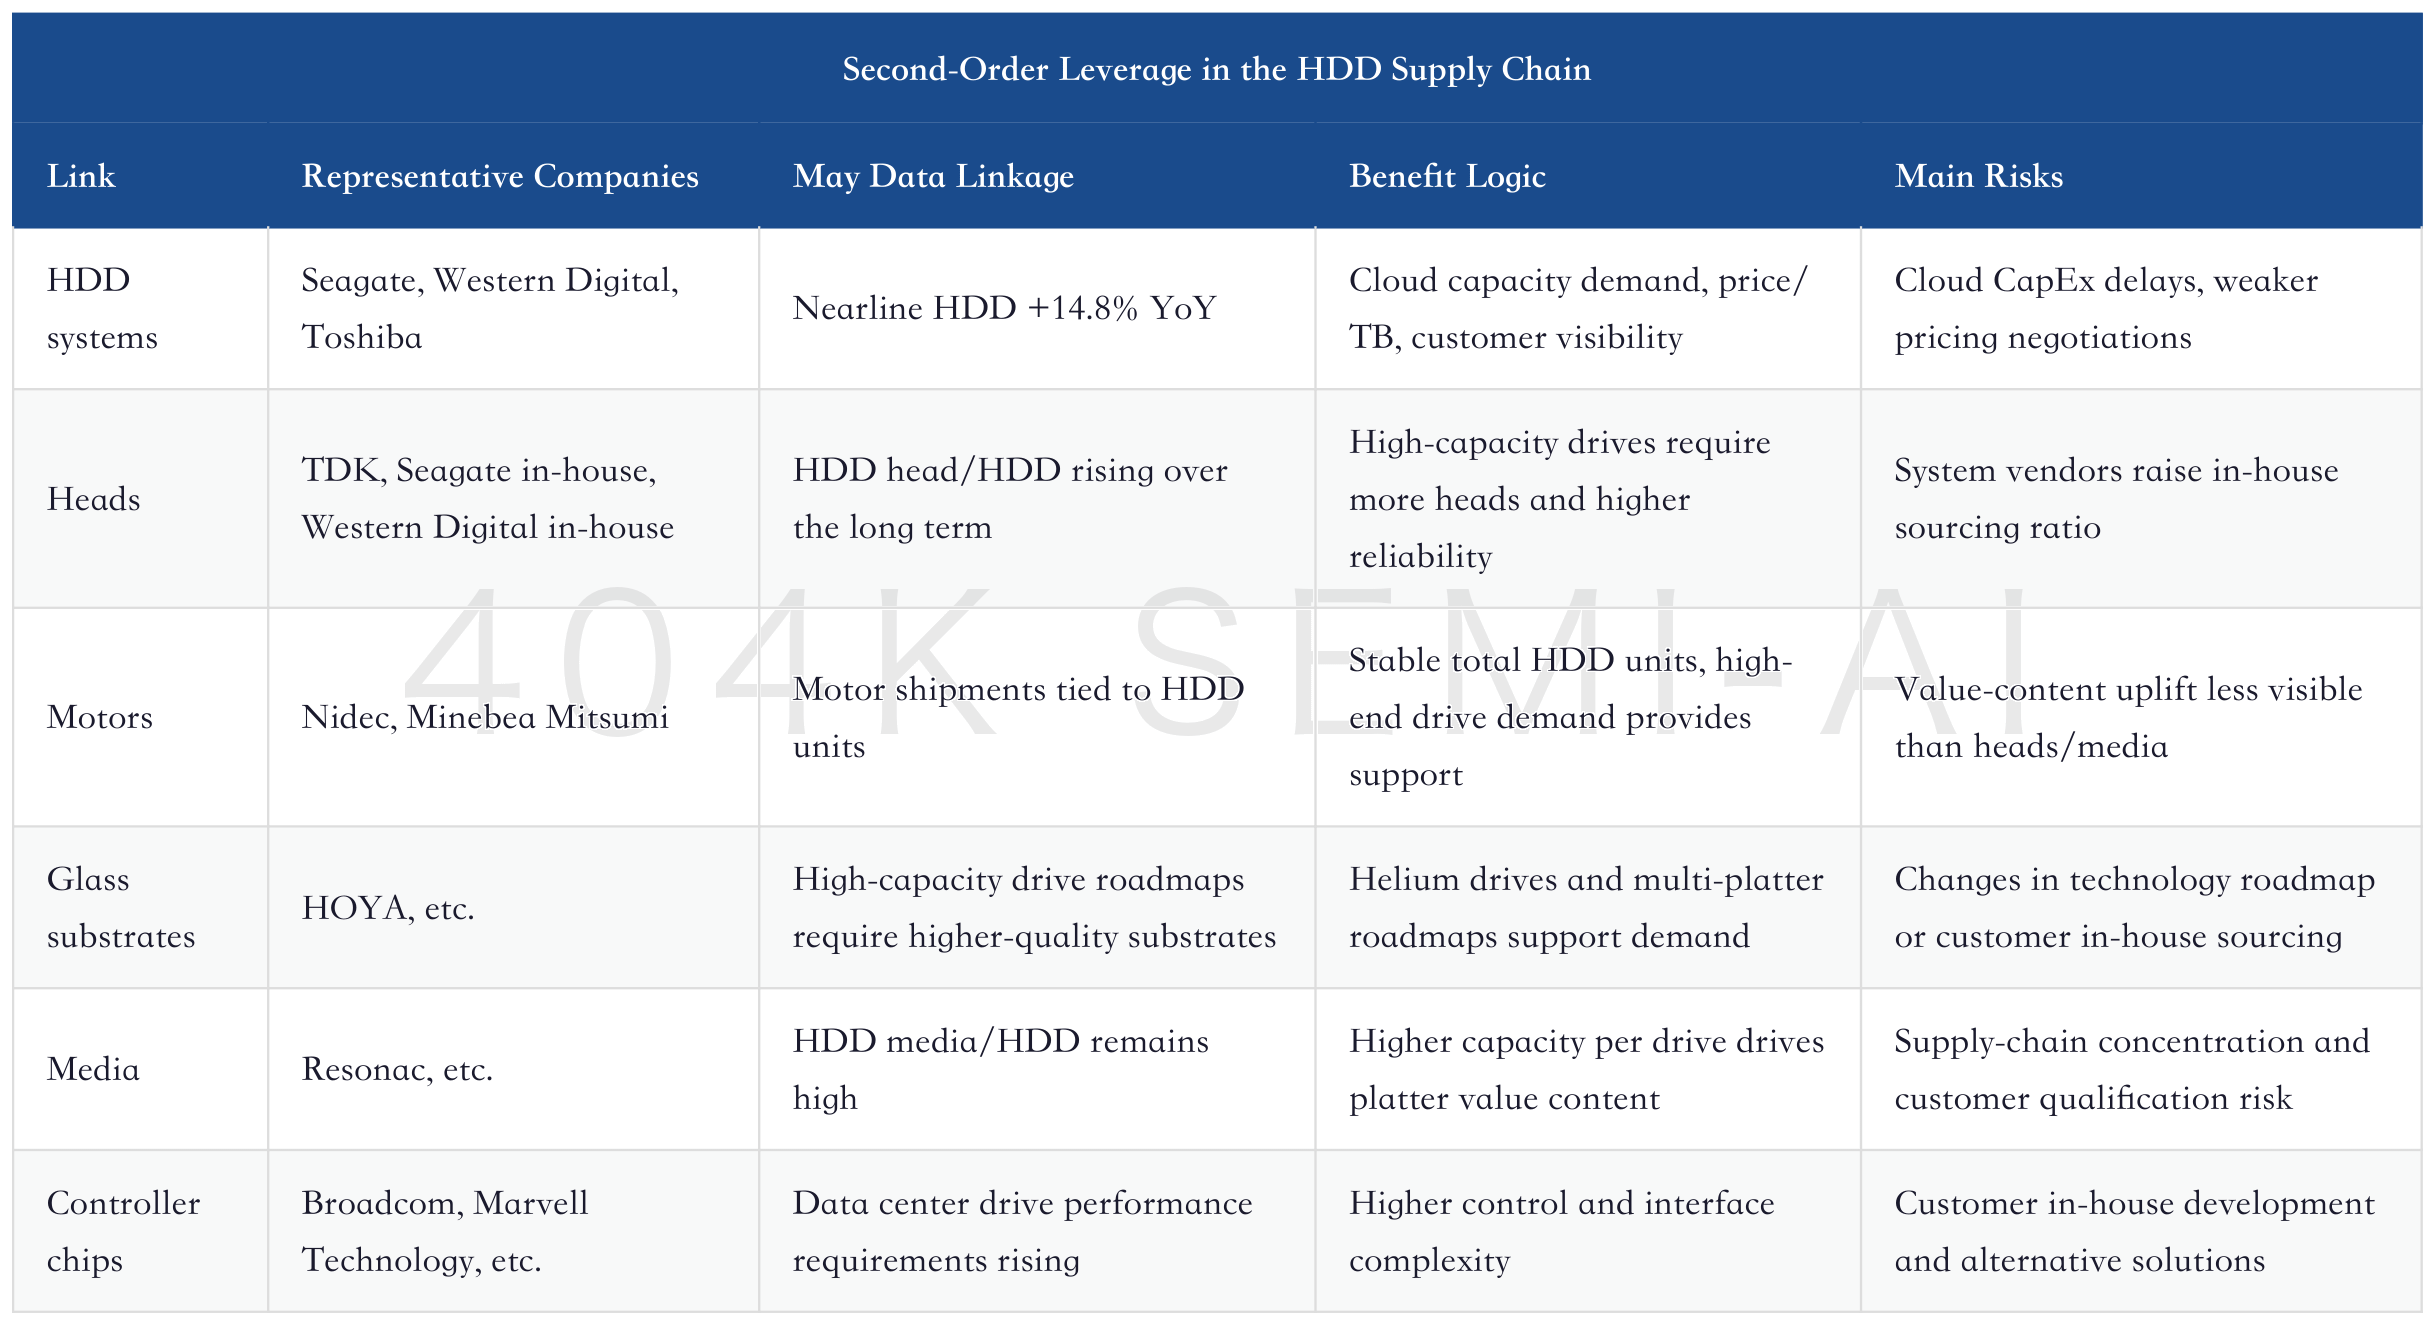
Some restraint is needed here: the component chain is not necessarily more levered than system vendors. High-capacity drives will lift value content, but system vendors control pricing and customer relationships, while component vendors depend on share, qualification, and bargaining power. Companies such as TDK and Nidec are better used as confirmation signals for HDD strength, rather than simple substitutes for core exposure to Seagate and Western Digital.
V. Enterprise SSDs: NAND’s Real Strength Is Data Centers, Not Consumer SSDs
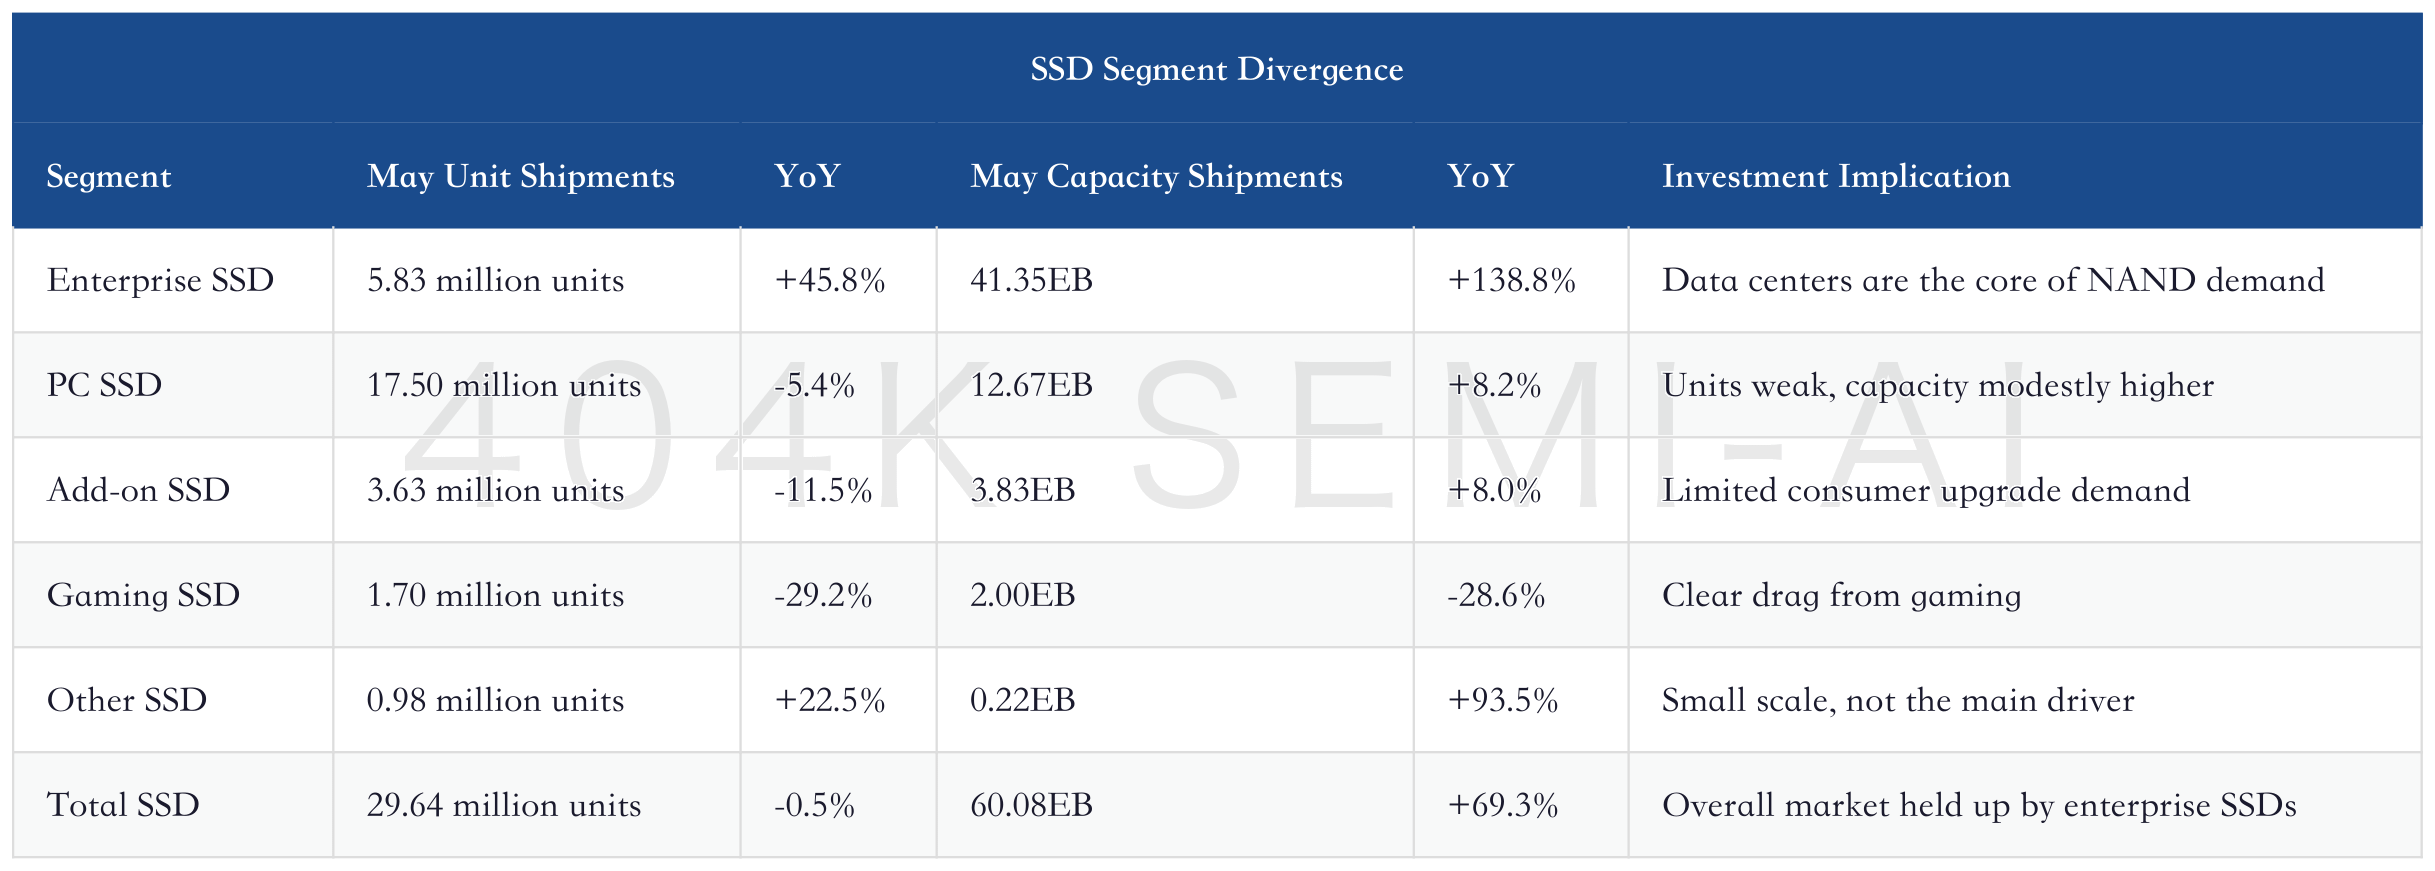
Enterprise SSDs are the strongest data point in this report, and the clearest monthly validation for a NAND re-rating. Total SSD unit shipments in May were down 0.5% YoY. Looking only at that number could lead to the mistaken view that NAND demand is merely average. But enterprise SSD unit shipments rose 45.8% YoY, while capacity shipments rose 138.8% YoY. Taken together, these two figures show that a structural migration is taking place within NAND.
Demand for ordinary SSDs is tied to PCs, gaming, and consumer electronics. It is price-sensitive and easily disrupted by end-market inventory. Demand for enterprise SSDs is tied to cloud CapEx, AI training and inference, databases, search, object storage, RAG, vector databases, content delivery, and video data. Procurement cycles are longer, qualification is more complex, and customers care more about performance stability and delivery certainty.
The SSD segment data captures this divergence. Consumer-related SSDs remain weak, while enterprise SSDs are clearly stronger than the overall market on both unit and capacity metrics. What NAND suppliers most need to win is not a recovery in ordinary SSDs, but enterprise SSD share and qualification for high-capacity products. The detailed breakdown is below.
SanDisk Deep Dive Update: Jefferies Raises Target Price to $3,000; How eSSD Share Recovery and NAND Long-Term Agreements Re-rate Earnings Durability
The implications differ for SanDisk, Kioxia, Micron, and Samsung. For SanDisk, the key points are data center SSD share, NBM long-term agreements, and QLC product ramp. For Kioxia, they are the eSSD revenue mix, BiCS8 cost declines, and scale effects from joint manufacturing with SanDisk. For Micron, the question is whether NAND and data center SSDs can contribute a second profit line beyond DRAM/HBM. For Samsung, the focus is its full-category breadth and whether it can benefit from NAND and eSSD recovery alongside its HBM catch-up.
NAND prices alone are not enough here. Price increases are certainly useful, but what can truly reduce the valuation discount is customer quality and product mix. If eSSD growth is merely ordinary cyclical restocking, the market will assign a low multiple. If eSSD growth comes from hyperscaler qualifications, long-term contracts, controller and firmware capabilities, and a high-capacity QLC roadmap, the market will view part of the profit pool as more stable infrastructure cash flow.
Kioxia Deep Dive Update: Goldman Sachs Raises Target Price to ¥116,000; How NAND Tightness Re-rates the AI Storage Cycle
Morgan Stanley’s May data is especially important for pure NAND names such as Kioxia. Kioxia has no HDD business. Its re-rating must rely on NAND supply-demand, enterprise SSD share, data center customer qualifications, and the cost curve. Enterprise SSD capacity shipments rose 138.8% YoY in May, showing that the overall market is still creating opportunities for pure NAND suppliers. But total SSD unit shipments were down 0.5% YoY, which also reminds the market not to value all NAND products at the same level of strength.
The same applies to SanDisk. SanDisk’s valuation debate has long centered on two questions: whether NAND prices are at a cyclical peak, and whether eSSD and NBM long-term agreements can make earnings more visible. The May data does not directly prove SanDisk’s own share gains, but it does prove that the enterprise SSD market is strong enough. If SanDisk subsequently delivers on share, long-term agreements, and high-capacity QLC products together, its earnings quality will be better than that of an ordinary NAND cycle.
Micron Earnings Deep Dive: Q3 Results Far Exceed Expectations; The AI Storage Supercycle Enters the Delivery Phase, How Much Profit Can Long-Term Agreements Lock In?
VI. Putting HDD and eSSD in the Same Ranking Table
The May data makes the ranking of storage companies clearer: HDD is about scarce cash flow, eSSD is about share and customer qualification, and DRAM/HBM is about bandwidth and profit purity. All are driven by AI, but their valuation anchors differ. Saying “all storage is good” loses the most important distinctions.
Seagate and Western Digital are the most direct beneficiaries of nearline HDDs. Their core questions are: can price/TB continue to rise, can long-term customer visibility translate into harder contracts, and will suppliers continue to avoid greenfield capacity expansion? If these conditions hold, HDD profits should not be fully discounted as a traditional cyclical peak.
SanDisk and Kioxia are the most direct beneficiaries of enterprise SSDs. Their core questions are: can eSSD share improve, can QLC/TLC products pass more hyperscaler qualifications, will NAND capital spending remain disciplined, and can long-term agreements lock in profits? If these conditions hold, NAND earnings are not just spot price volatility.
Micron, Samsung, and SK hynix have broader frameworks. They are of course driven by DRAM, HBM, and server memory, but eSSD and NAND also reinforce full-category breadth. Micron’s mapping to U.S. AI storage, Samsung’s breadth assets, and SK hynix’s HBM purity all need to be assessed alongside marginal changes in NAND/eSSD.
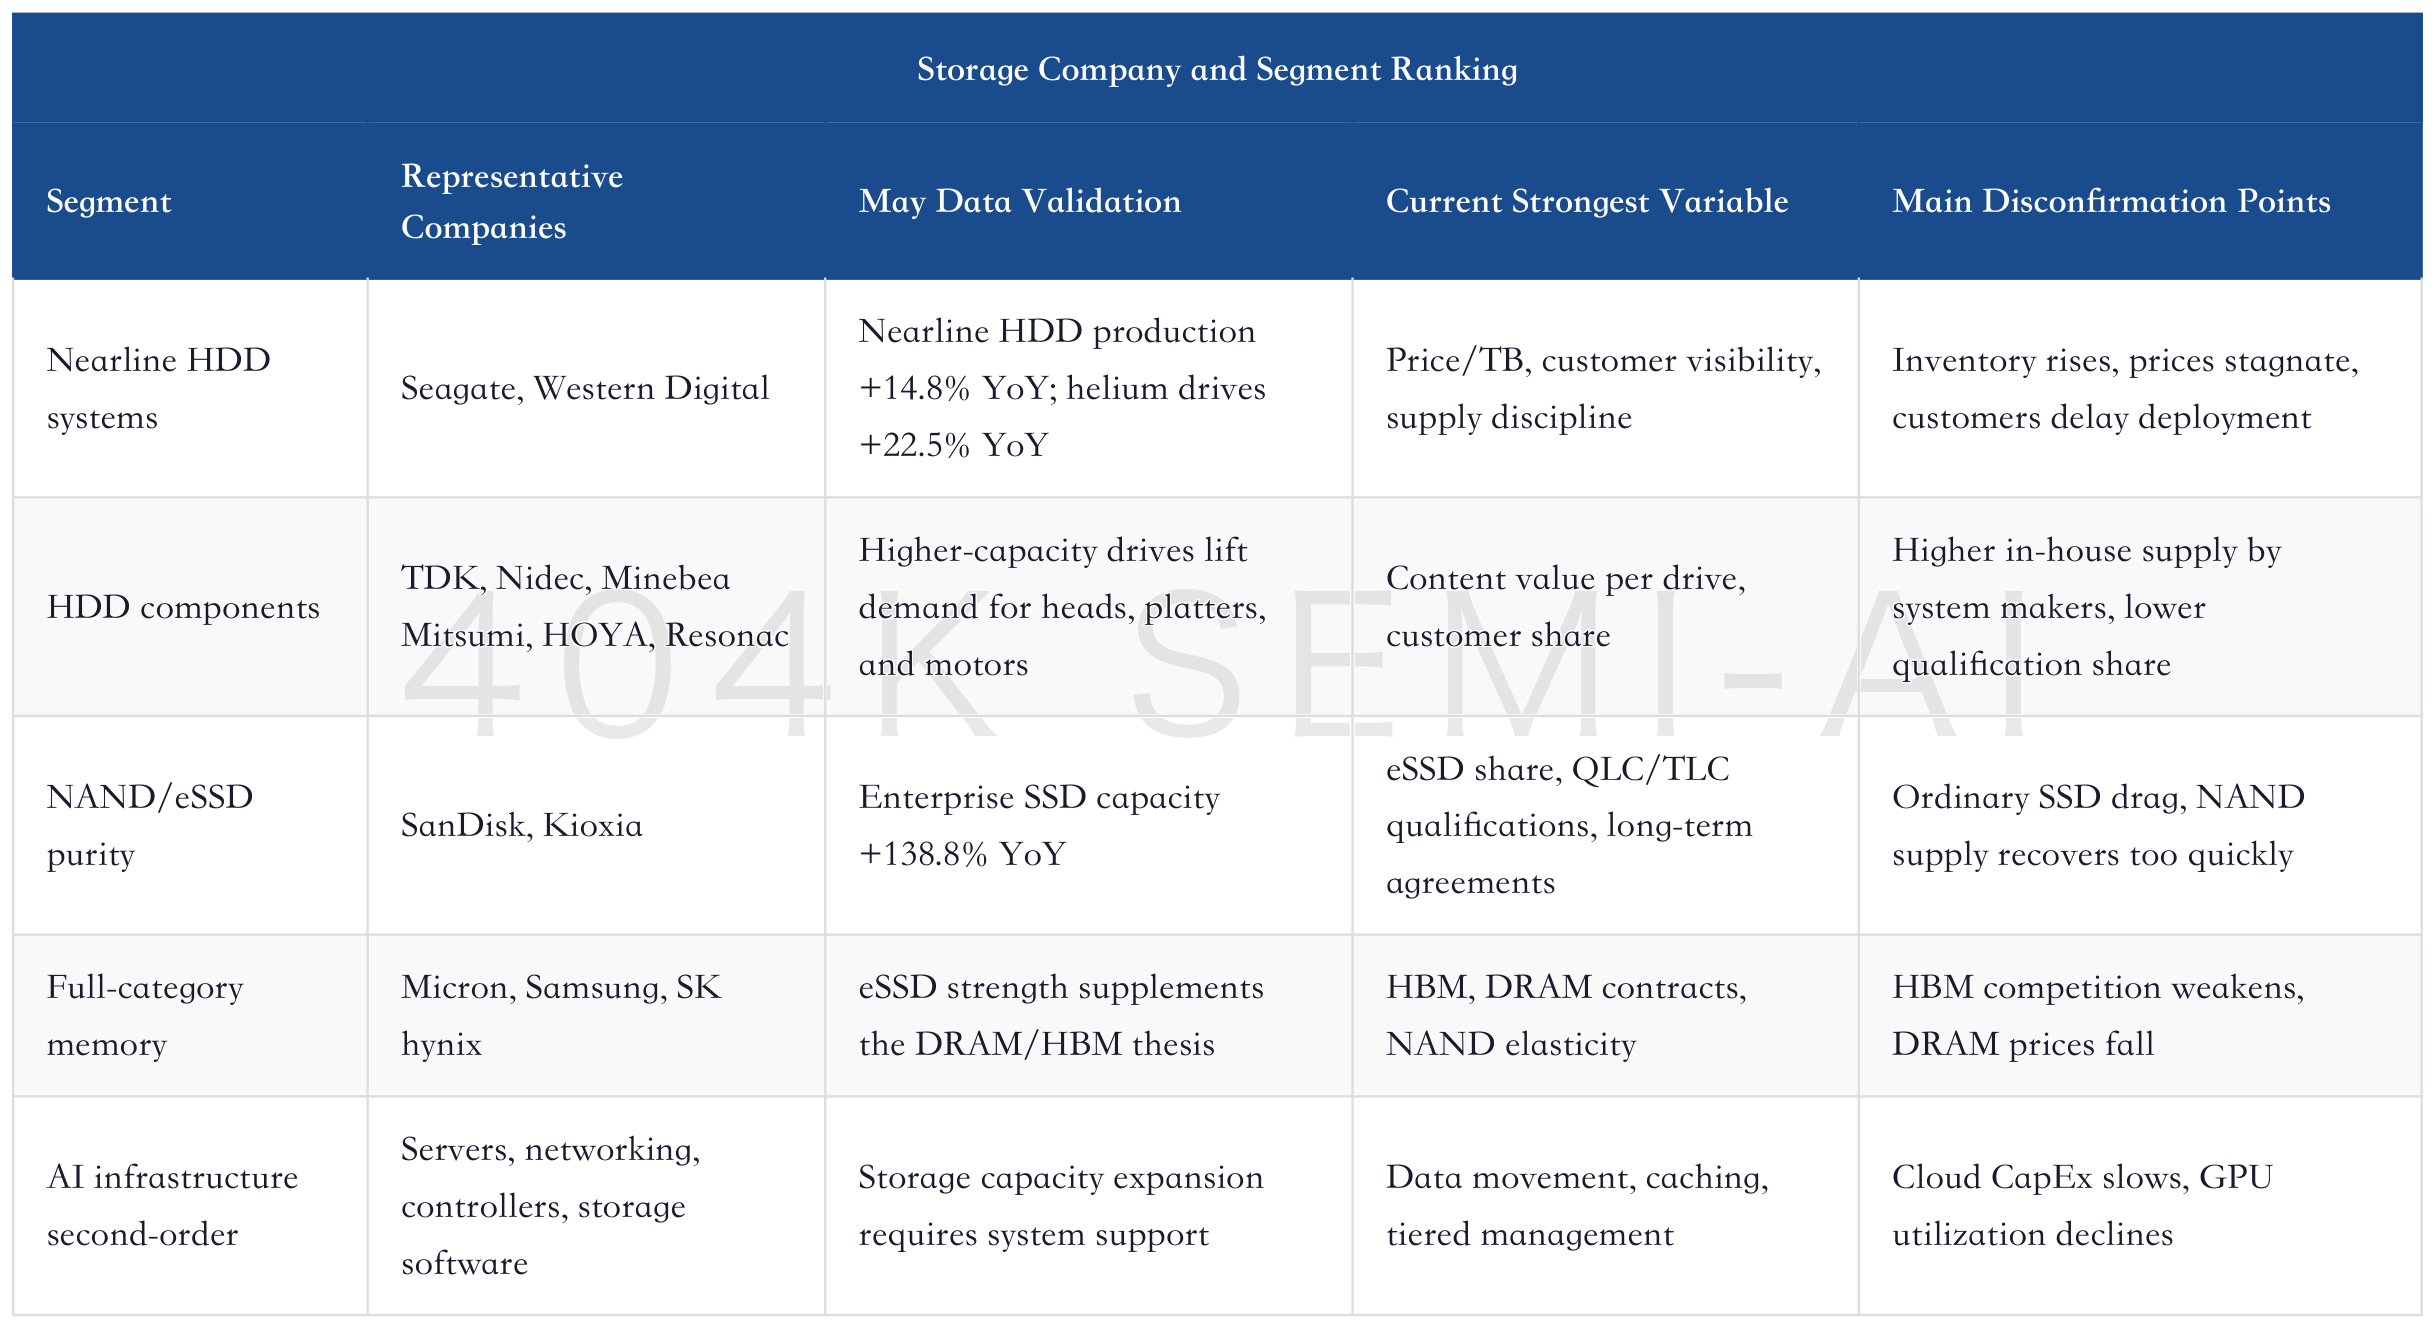
This ranking has an important implication: HDD is not necessarily more “backward” than NAND, and NAND is not necessarily more “advanced” than HDD. In an investment framework, being advanced does not determine valuation; scarcity position does. HDD is scarce in the low-cost capacity tier, eSSD is scarce in the high-performance capacity tier, and HBM is scarce in the bandwidth tier. Different forms of scarcity map to different companies and different risks.
Storage Deep Dive Update: Morgan Stanley Calls for Buying Old Storage; Why DDR4, SLC NAND, and NOR Are Still Rising
There is a common thread between price increases in legacy storage and strong demand for HDD/eSSD: AI is absorbing high-end supply and capital spending priority, making traditional products tighter because supply is insufficient. HDD has not been quickly supplemented by new greenfield capacity, and suppliers have not prioritized expansion for legacy DRAM, SLC NAND, or NOR either. The market used to treat these products as mature, low-growth, low-valuation assets. It is now discovering that maturity can also mean stronger supply discipline.
This does not mean all legacy assets can be re-rated. A re-rating requires three conditions: demand has not disappeared, supply is not easy to expand, and customers are willing to pay for availability. The May HDD and SSD data satisfy the first two conditions for nearline HDDs and enterprise SSDs. The third condition still needs to be tracked through pricing and contracts.
7. Three Worldviews: Cyclical Peak, Structural Re-Rating, Extreme Shortage
The biggest debate in this memory cycle is not whether the data is strong, but what valuation strong data deserves. Strong May data does not automatically mean all memory stocks are cheap. Share prices have already discounted a large amount of optimism. The real question is how much of current profit can be capitalized.
The market can be divided into three worldviews.
The first is the traditional cyclical peak. This framework acknowledges that HDD and enterprise SSD are very strong, but argues customers are over-ordering, suppliers will eventually add supply, and both NAND and HDD prices will fall back. In this world, May data only proves the cycle is not over; it does not prove valuation multiples should rise.
The second is structural re-rating. This framework argues that AI data centers make storage demand more resilient, longer-lasting, and less substitutable, while suppliers also have more supply discipline than in the past. In this world, May data is not just strong for the month. It indicates storage is moving from a short-cycle component into a bottleneck in AI infrastructure, allowing part of the profit pool to be discounted at a higher quality.
The third is extreme shortage. This framework argues that AI inference, agents, video, and physical AI will keep data growth ahead of expectations, with both HDD and enterprise SSD supply insufficient, price/TB, NAND contract prices, and customer long-term agreements continuing to move higher. In this world, current earnings forecasts are still too low, and the valuation ceiling may continue to expand.
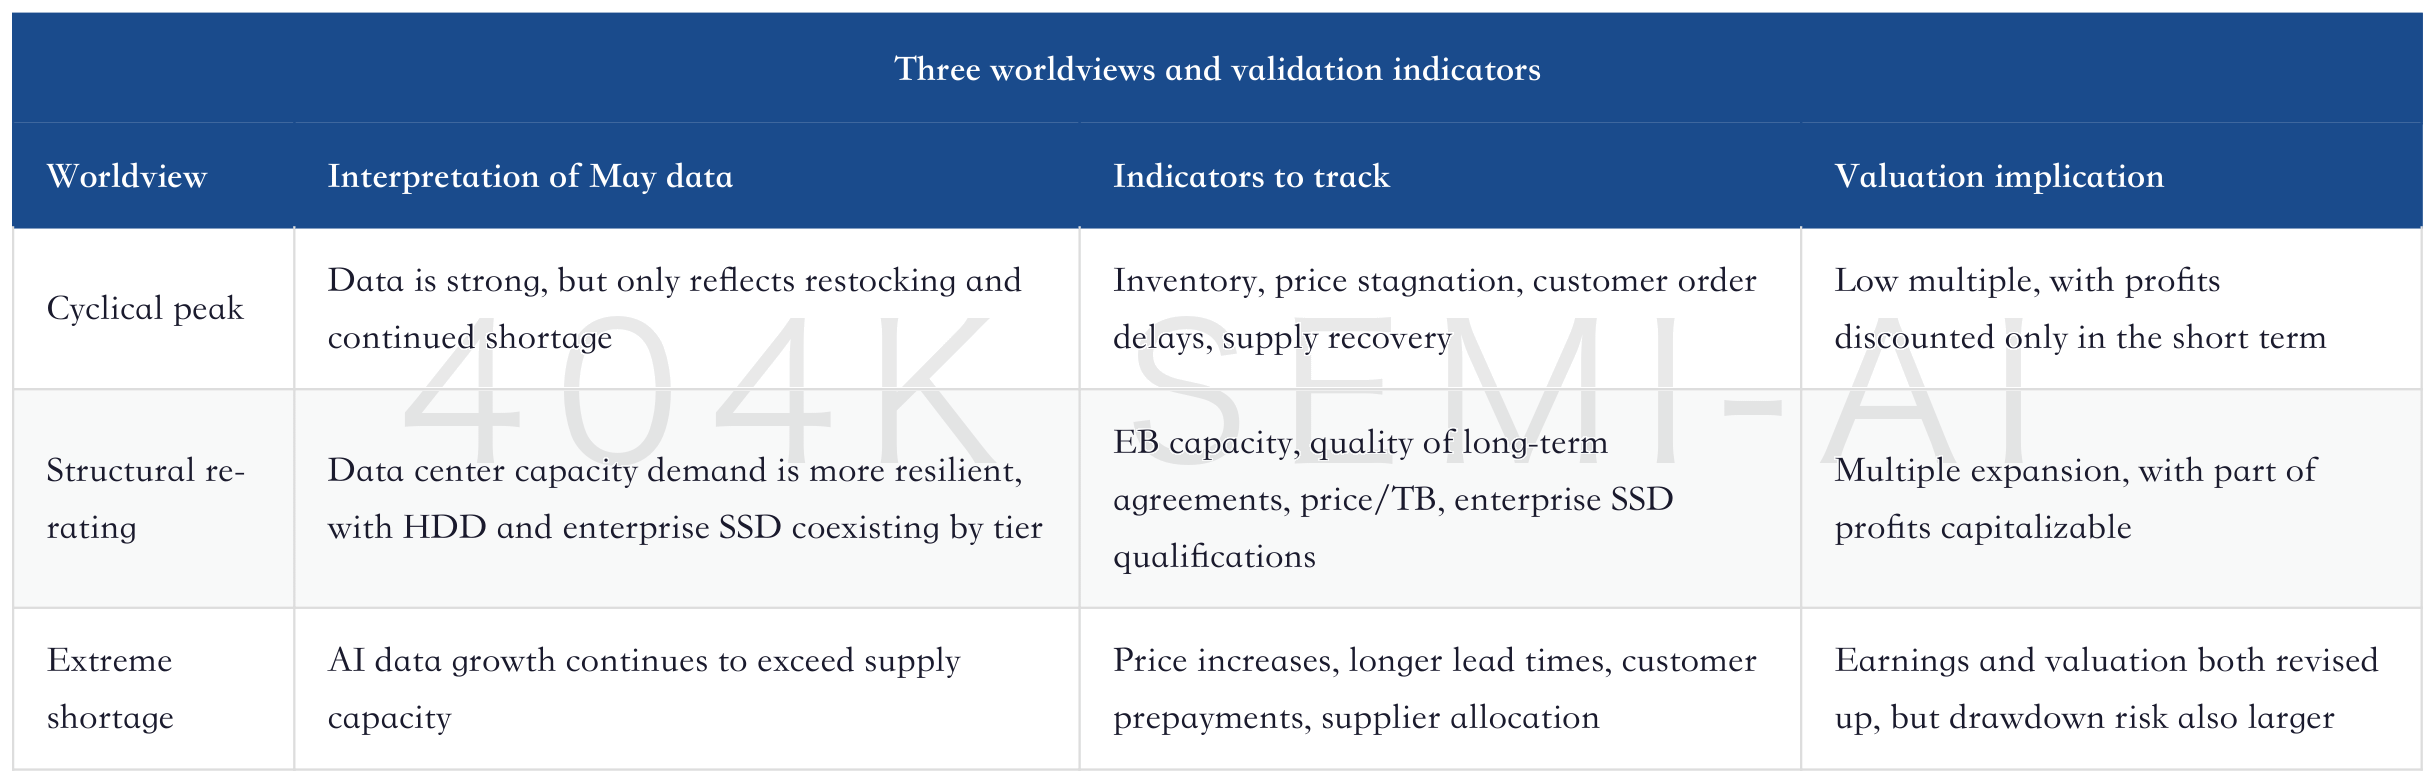
The May data currently supports the second worldview more, while there is not yet enough evidence to prove the third. The reason is simple: enterprise SSD capacity was revised up significantly, and nearline HDD maintained high growth, supporting the structural re-rating case. But the forecast for total HDD capacity has not been revised up sharply again, while HDD prices and contract terms are not directly disclosed in this Japan electronic components monthly report. Extreme shortage therefore cannot yet be treated as the base case.
This judgment also matters for positioning. If all strong data is treated as extreme shortage, the research conclusion becomes target-price chasing. If strong data is treated only as a normal cycle, investors will miss the change in the asset attributes of AI storage. A steadier approach is to use structural re-rating as the base case, retain upside optionality from extreme shortage, and clearly list the indicators that would falsify the thesis.
8. Falsification Checklist: What to Watch Over the Next Four Quarters
Whether the storage re-rating can continue depends on whether data keeps moving along the path of “EB growth, pricing discipline, long-term agreement quality, and no supply expansion.” May data is one confirmation, not the final answer. Each subsequent month and quarter should return to the same set of indicators.
First, watch enterprise SSD capacity shipments. As long as enterprise SSD capacity continues to grow far faster than unit shipments, customers are buying higher-capacity, higher-value products, and NAND demand quality remains strong. If enterprise SSD capacity growth falls back to ordinary SSD levels, valuation for pure NAND names should become more conservative.
Second, watch nearline HDD capacity and helium drives. Total HDD unit shipments have limited significance. Nearline EB and the share of high-capacity drives matter more. If helium drives, heads/HDD, and media/HDD continue to rise, the high-capacity roadmap is still advancing.
Third, watch price/TB and contract terms. If HDD vendors can continue raising price/TB by quarter, while avoiding locking in commercial terms beyond 2030 too early, they can retain more profit flexibility. If enterprise SSD vendors can secure long-term customer commitments, prepayments, capacity locks, or a higher qualification share, the NAND cycle discount will decline.
Fourth, watch supply discipline. The biggest risk for HDD is new greenfield capacity undermining scarcity. The biggest risk for NAND is prices stimulating a rapid recovery in capital expenditure. As long as suppliers meet demand through technology migration and higher capacity per drive rather than large-scale new capacity, profit quality will be higher.
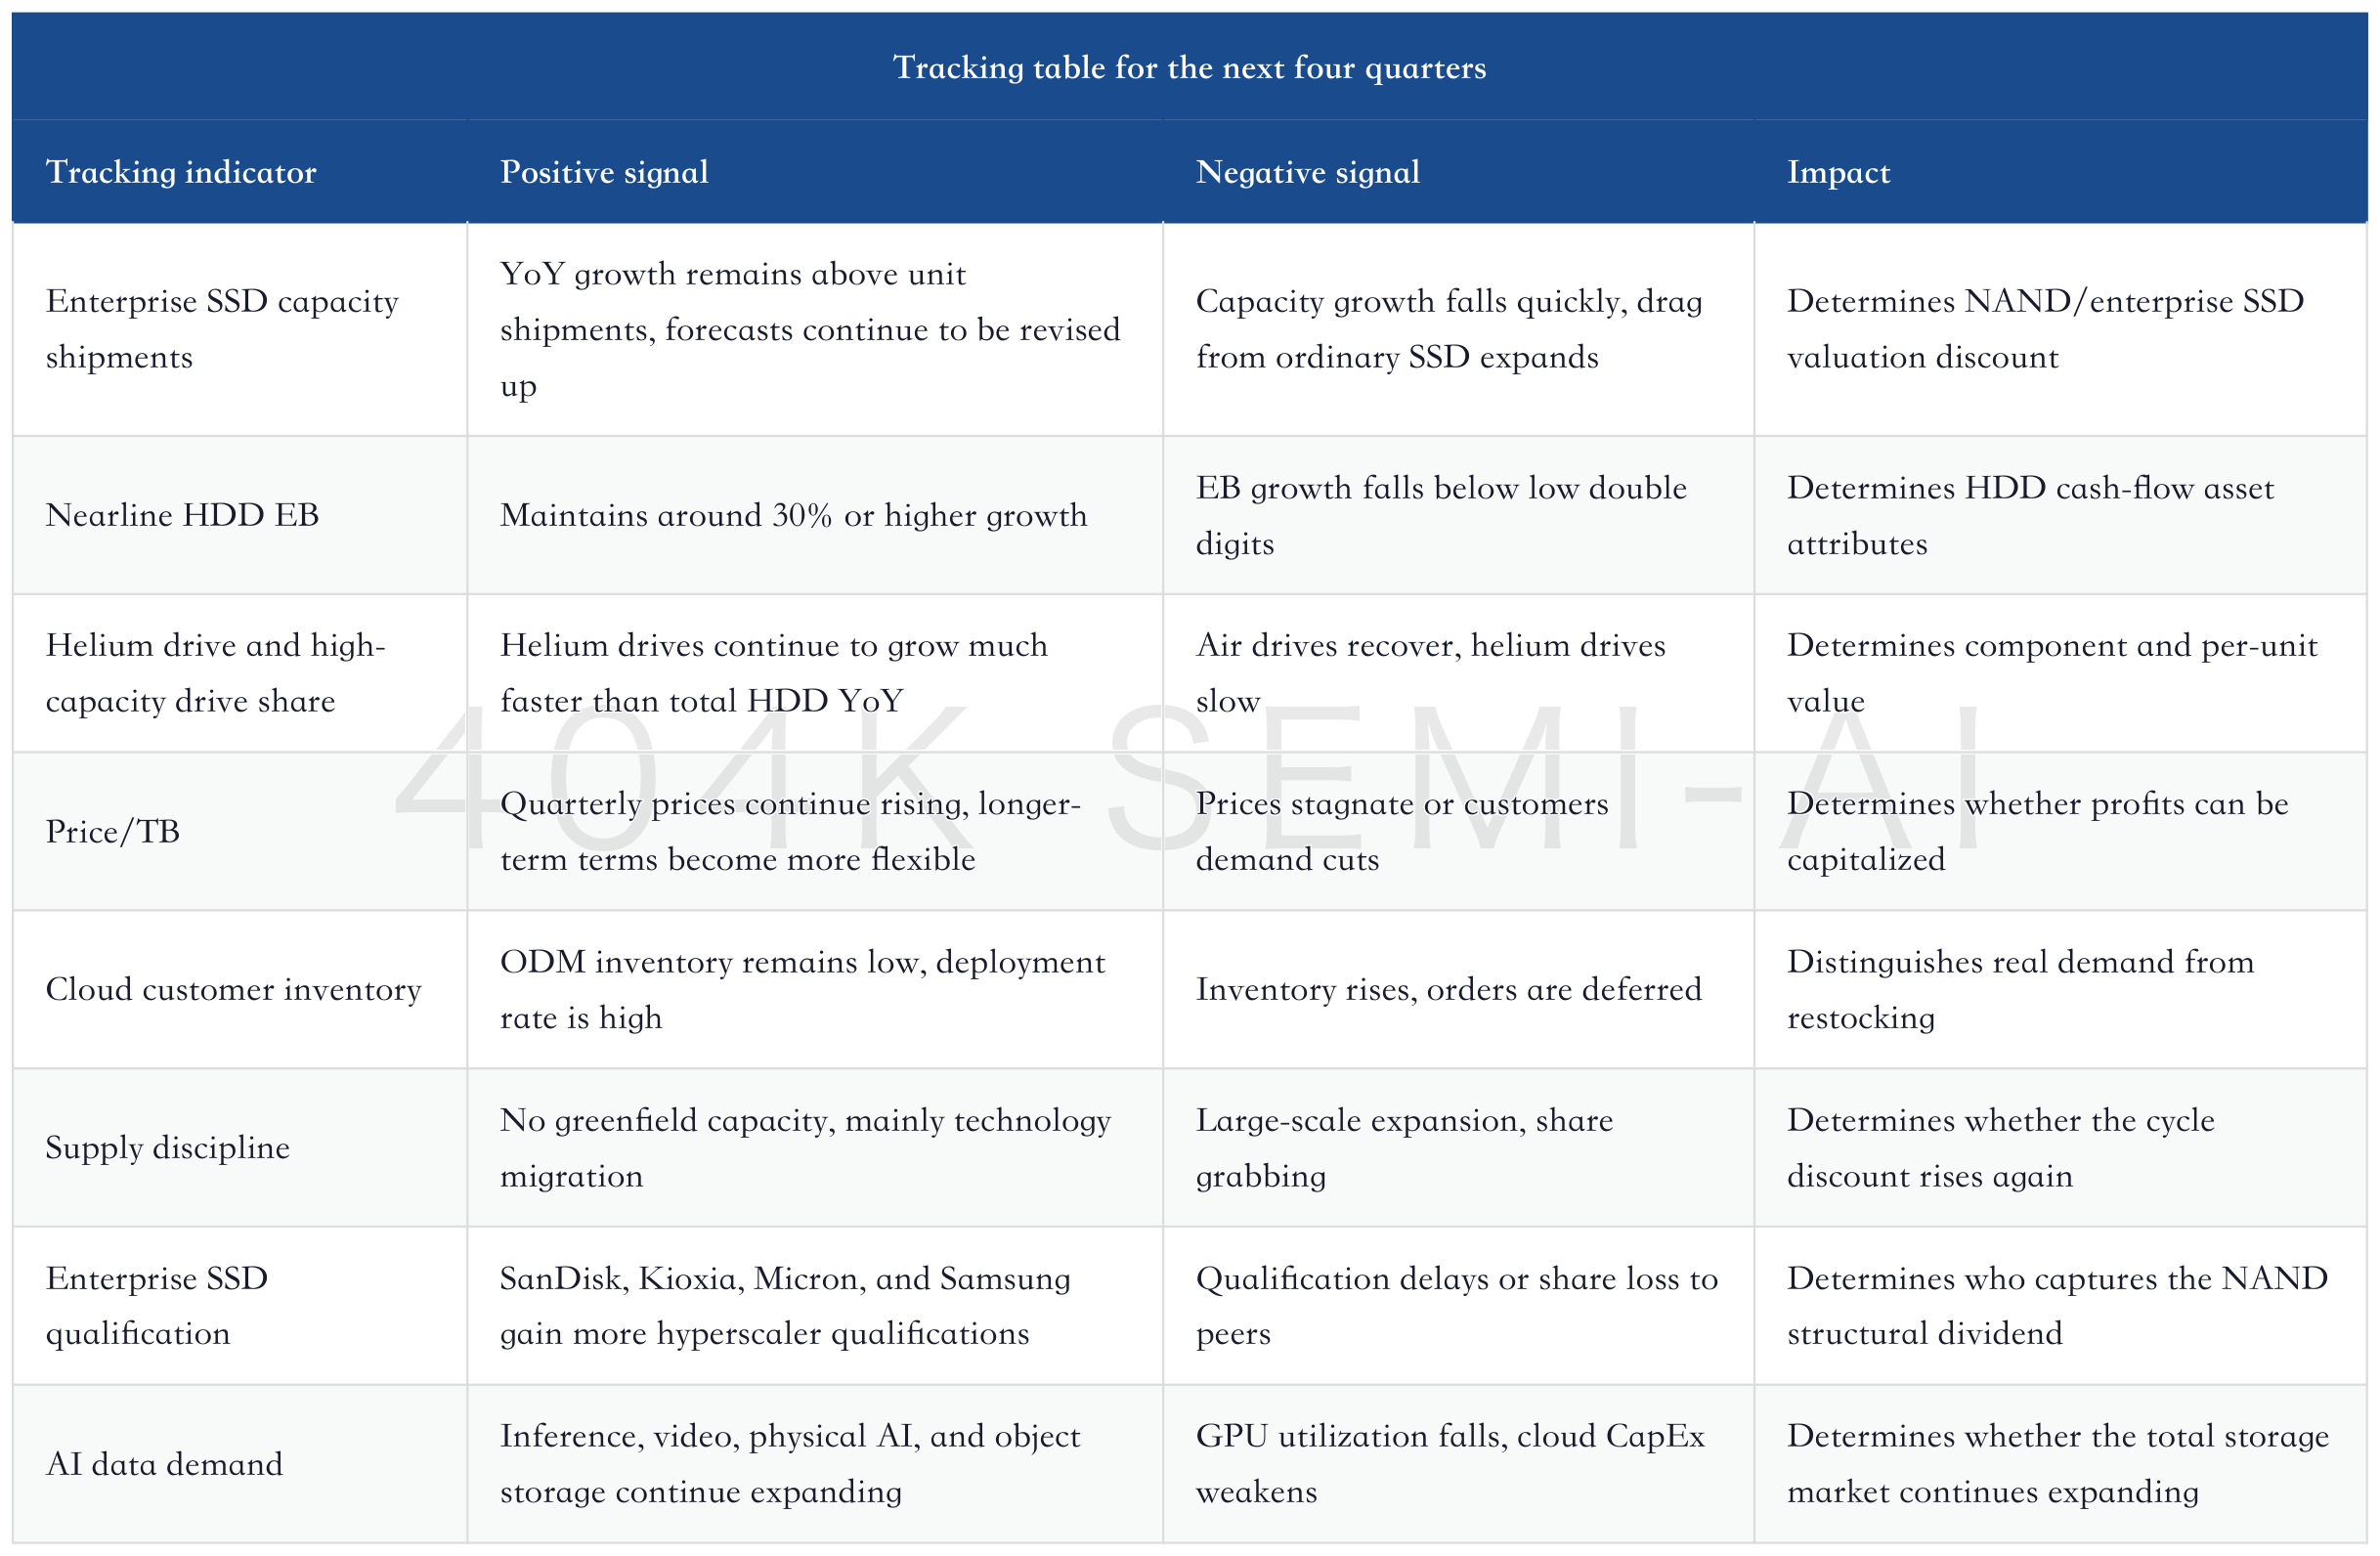
This tracking table also helps distinguish companies. For Seagate and Western Digital, first watch price/TB, nearline EB, and customer inventory. For SanDisk and Kioxia, first watch enterprise SSD capacity, qualifications, and long-term agreements. For Micron and Samsung, DRAM, HBM, and server memory must also be layered in. For TDK, Nidec, HOYA, and Resonac, watch high-capacity HDD component share.
9. From Monthly Data to the Model: How Profit Transmits
May data cannot be converted directly into a target price, but it can clearly flow into revenue, gross margin, valuation multiples, and risk discounting. If an in-depth report only says “May data was strong,” the information density is still insufficient. A more useful approach is to break the monthly data into four transmission chains: HDD price/TB, high-capacity HDD components, enterprise SSD capacity, and NAND supply discipline.
The first chain is HDD price/TB. Nearline HDD production and capacity demand are strong, while suppliers are unwilling to add supply quickly through greenfield capacity, so price/TB has room to continue rising. Price/TB has high profit leverage for Seagate and Western Digital, because much of the cost is already embedded in the fixed manufacturing system, and incremental pricing tends to flow more directly into gross margin expansion. Morgan Stanley’s U.S. hardware team previously estimated that if nearline HDD prices migrate from the low-teens dollars/TB toward above $20/TB, EPS leverage would be substantial. The May Japan electronic components data cannot prove where pricing already is, but it does prove the demand side has not weakened this price transmission.
The second chain is high-capacity HDD components. Helium drives grew +22.5% YoY, stronger than total HDD, indicating the high-capacity roadmap is still progressing. High-capacity drives bring demand for more heads, more platters, higher-precision motors, higher-quality glass substrates, and media. Component company leverage does not necessarily come from HDD unit growth, but from per-unit value and customer share. TDK, Nidec, Minebea Mitsumi, HOYA, and Resonac need to be analyzed by segment, rather than simply bundled as “HDD concept stocks.”
The third chain is enterprise SSD capacity. Enterprise SSD capacity grew +138.8% YoY, far above unit growth, indicating customers are buying larger-capacity, higher-value enterprise drives. This transmission chain is most important for NAND companies: if the share of high-capacity enterprise SSD rises, NAND suppliers’ product mix, customer stickiness, and long-term agreement quality all improve. Pure NAND or high-NAND-purity names such as SanDisk and Kioxia will benefit more directly than consumer SSD companies.
The fourth chain is NAND supply discipline. Enterprise SSD demand is strong. If suppliers immediately expand capacity aggressively, profits are only short-cycle. If capital expenditure remains restrained, and AI customers are willing to secure supply through long-term contracts and more stringent qualification, profit quality improves. Whether memory stock valuations can continue to expand depends largely on which supply response the market believes in.
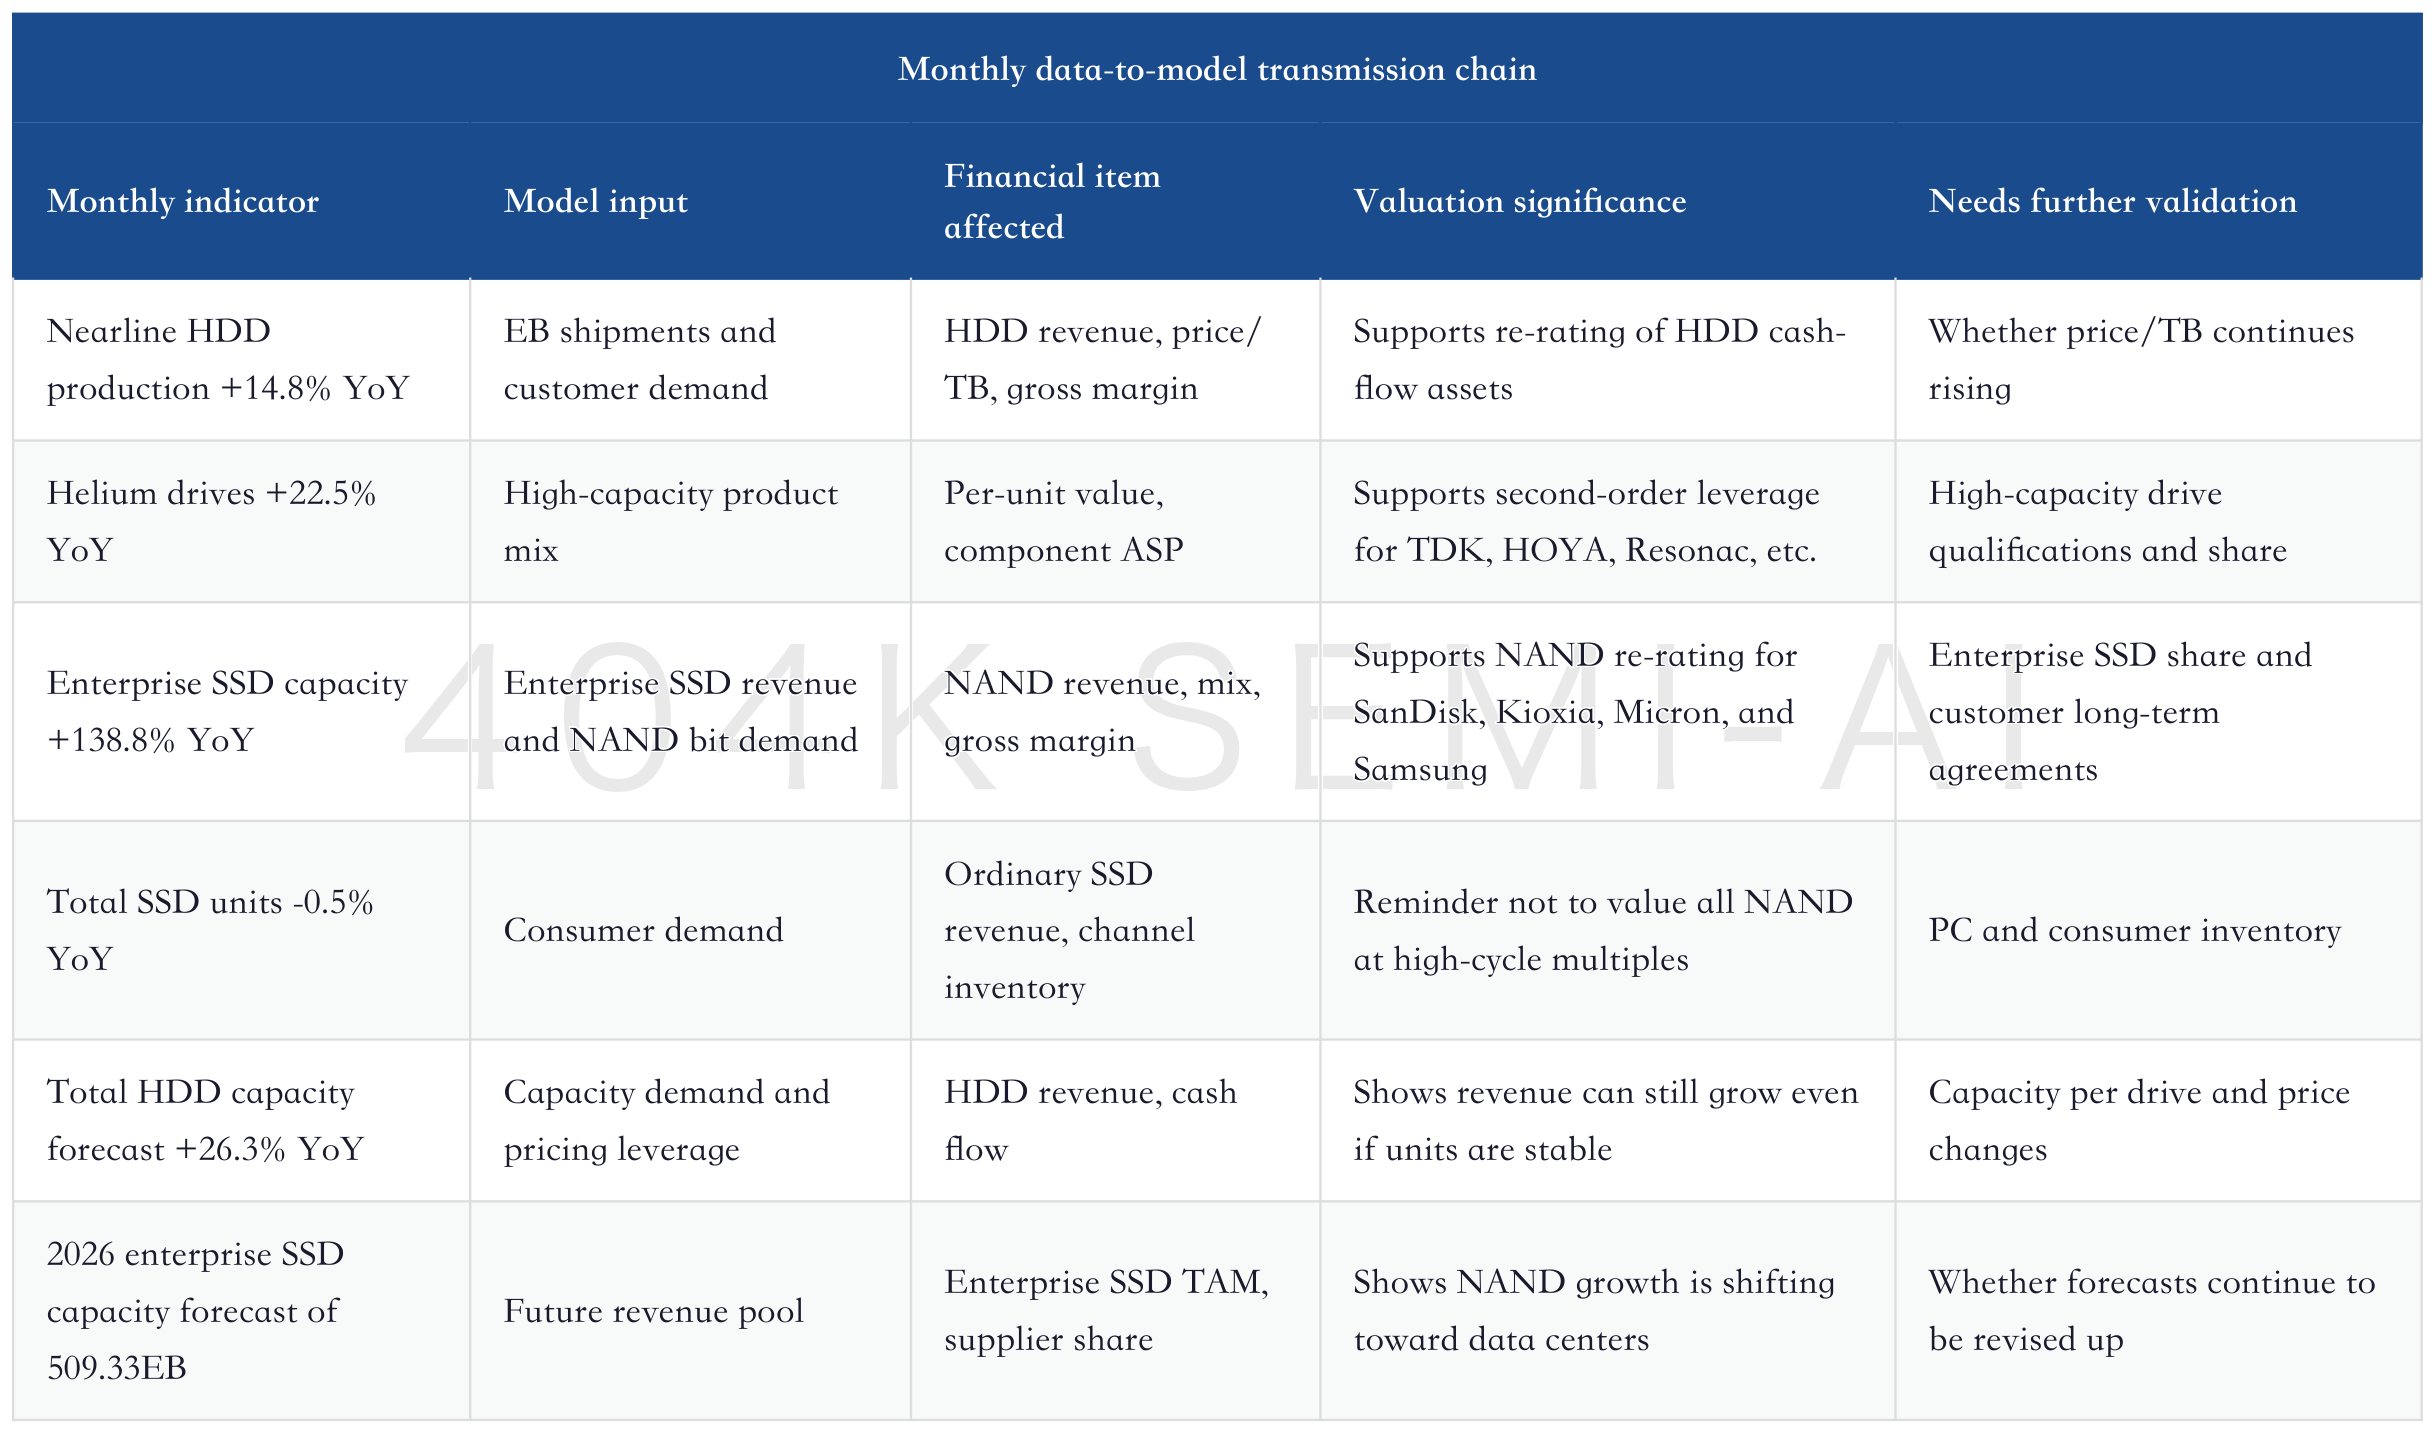
This transmission table moves the investment judgment from “demand is strong” to “whose profits are more likely to be capitalized.” Capitalization for HDD OEMs comes from pricing and supply discipline. Capitalization for NAND vendors comes from enterprise SSD share and long-term agreements. Capitalization for component vendors comes from value content and share. For full-category memory vendors, HBM and DRAM must also be layered in.
A simple but useful judgment is that May data is positive for both HDD and enterprise SSD, but for different reasons across companies. Seagate and Western Digital get evidence of resilient demand, tight supply, and pricing flexibility. SanDisk and Kioxia get evidence that the enterprise SSD market continues to be revised up. TDK and Nidec get evidence that the high-capacity HDD chain has not broken down. Micron and Samsung get evidence that NAND is not purely a drag.
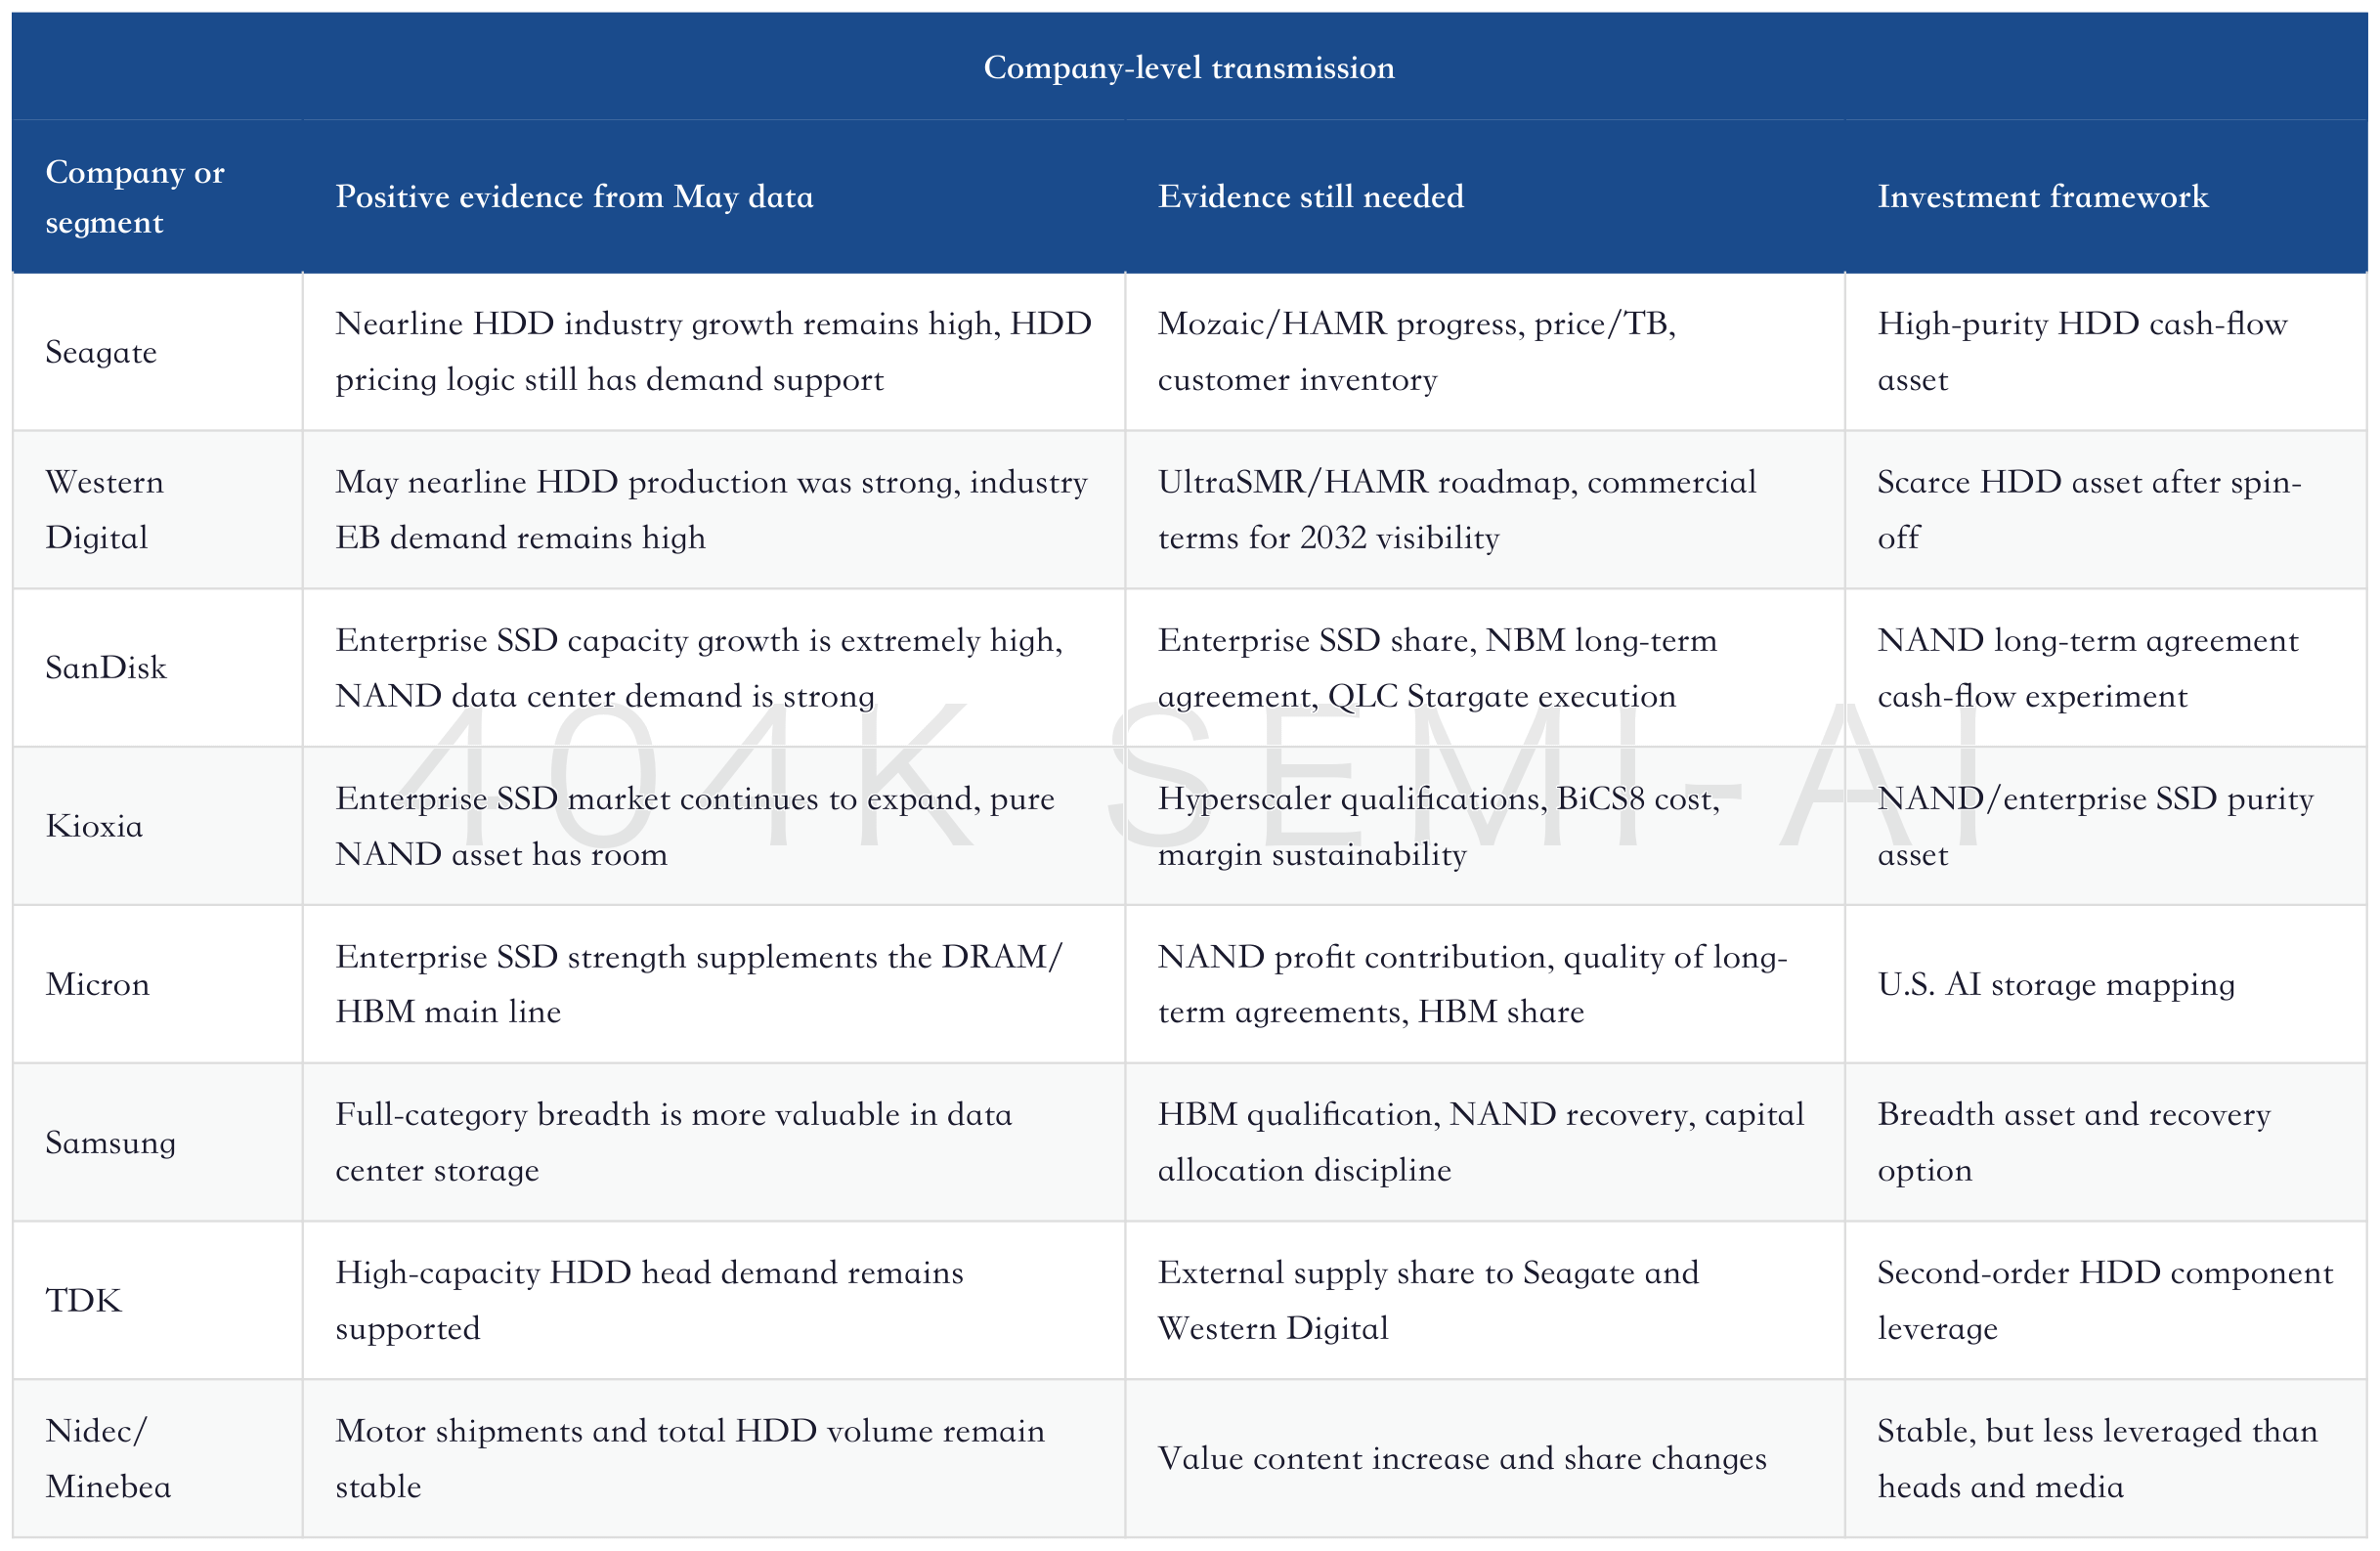
The real valuation question is which profits can be treated as “more durable profits.” Traditional memory stocks usually do not receive high multiples because prices, inventory, and supply response move too quickly, and earnings peaks are often cyclical peaks. The difference in this AI storage cycle is that data center customers are starting to buy longer-cycle capacity visibility, while suppliers are more willing to protect profits through long-term agreements, technology cadence, and capacity discipline. If this holds, the discount rate applied to the same $1 of profit for HDD and enterprise SSD companies should fall.
This is also why the investment implication of May data is more than “one month of upward revisions.” Strong monthly shipments are only the first layer of evidence. The second layer is capacity growth exceeding unit growth. The third layer is high-capacity products driving per-system value. The fourth layer is customers being willing to write this demand into longer-term commercial arrangements. Seeing only the first layer makes it easy to chase short-term momentum. Seeing the fourth layer is what justifies using asset re-rating as the base case.
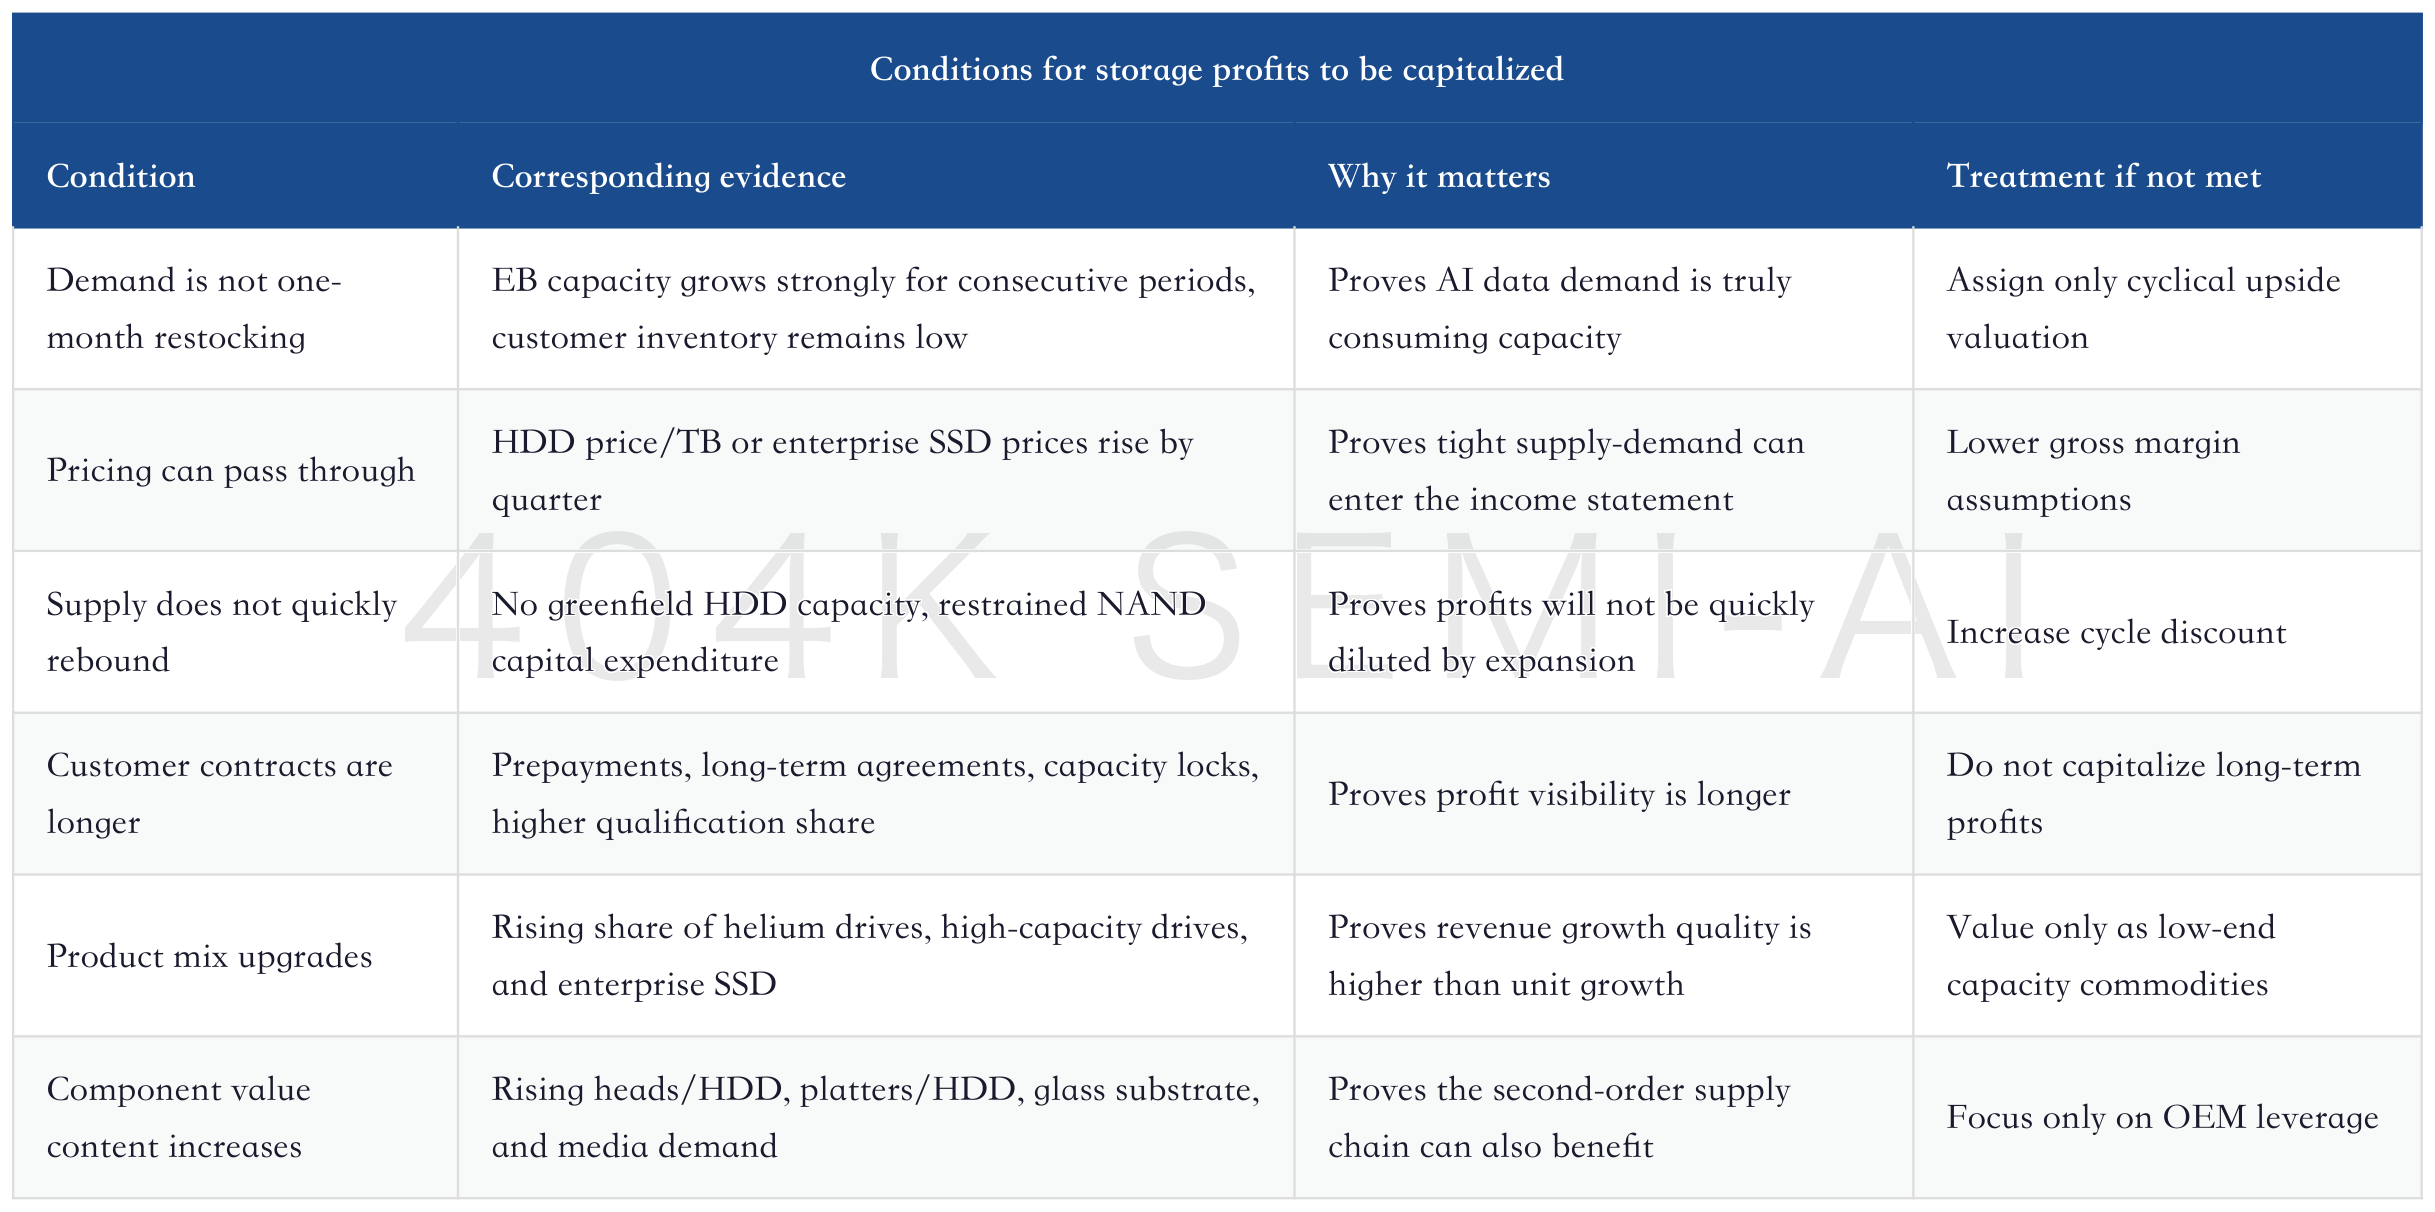
The constraint from this table is strict: if only monthly data is strong, but pricing, contracts, and supply discipline are absent, memory stocks remain cyclical stocks. If monthly data is strong, while pricing, contracts, and supply discipline also begin to materialize, the market will discount part of future profits into more stable cash flow. May data currently strengthens demand and product mix. Pricing and contracts still need confirmation through future company earnings and management commentary.
One detail should not be overlooked: strong data for enterprise SSD and nearline HDD are not mutually exclusive within the same customer wallet. After cloud customers procure GPU servers, they must simultaneously expand hot data, warm data, cold data, and backup tiers. Enterprise SSD captures online services and high-frequency access budgets. HDD captures data lakes, object storage, and archive budgets. As long as AI applications lengthen data retention cycles, both will absorb cloud capital expenditure at the same time, rather than simply competing for the same hard-drive budget.
Therefore, the biggest place not to cut corners in models is avoiding treating “unit shipments” as the only volume variable. For HDD, investors should watch units, EB, price/TB, capacity per drive, and platter/head value content at the same time. For enterprise SSD, investors should watch units, EB, average capacity, enterprise mix, qualified customers, and NAND bit cost at the same time. If the model only contains one shipment volume and one ASP, it will force this AI storage re-rating back into a traditional electronic components cycle.
For portfolio allocation, this means the storage chain should not be rotated only based on “which stock has risen less.” A more reasonable sequence is to first confirm which data layer is closest to the income statement, then confirm which company is most sensitive to that data layer, and only then assess whether valuation already reflects it. HDD OEMs are closest to pricing and cash flow. NAND vendors are closest to enterprise SSD capacity and product mix. Component vendors are closest to the value content increase in high-capacity drives. All three asset classes benefit from AI storage, but the realization cadence differs.
In a simplified framework, HDD OEMs are “capacity scarcity + pricing discipline,” enterprise SSD is “AI hot data + NAND supply discipline,” and components are “per-drive complexity + share stability.” May data provided positive validation for all three lines, but with different intensity: HDD validated nearline demand and helium drives, enterprise SSD validated capacity shipments, and components validated that the upstream high-capacity roadmap has not been falsified. If subsequent earnings can convert these monthly signals into orders, gross margins, and cash flow, the storage chain still has room for further re-rating.
This also explains why storage stocks cannot be ranked as a simple leaderboard of share-price gains. HDD companies, NAND companies, DRAM/HBM companies, and component companies are driven by different variables, and their share-price reactions will also unfold in phases. The first phase usually prices in spot/contract pricing and target-price upgrades; the second phase prices in earnings delivery; the third phase prices in changes in earnings quality and valuation discounts. The May data is more of a validation point between the second and third phases.
10. Risks: Strong Data Can Still Be Offset by Valuation and Supply Response
Strong May data does not mean the storage trade is risk-free. The real risk is not that demand immediately disappears, but that the market extrapolates strong data too far, or that suppliers restart capacity expansion under the stimulus of high prices. The most dangerous point in the storage cycle is often not when data is poor, but when data is strong and capital expenditure begins to turn aggressive with it.
The first risk is valuation crowding. Storage stocks have already gone through multiple rounds of target-price upgrades, and many share prices have moved ahead of fundamentals. Strong monthly data can support the direction of the trade, but it does not necessarily support continued multiple expansion for every company. The higher the purity and the larger the prior gains, the more the valuation needs to be supported by harder evidence from contracts, pricing, and customers.
The second risk is supply response. The HDD industry currently has stronger supply discipline, and adding new greenfield capacity is difficult. This is the core of the HDD rerating. But the NAND industry has historically been more susceptible to price-driven capital expenditure. If NAND pricing and eSSD demand are too strong, and suppliers pull forward expansion plans, price assumptions for 2027-2028 will be pressured lower.
The third risk is changes in TCO across media. HDD and eSSD currently coexist in a tiered architecture, but marginal use cases will be affected by cost changes. If NAND costs fall faster than expected, some warm data may migrate to QLC SSDs; if NAND prices remain high, HDD’s TCO advantage will become more evident. This is not a binary choice, but marginal share and price negotiations will change.
The fourth risk is the pace of cloud capital expenditure. AI data-center storage demand is ultimately constrained by data-center ramp-up, server deployment, GPU utilization, and commercialization of inference applications. If power, racks, networking, or GPU deliveries slow down, storage orders may also be deferred in phases. The May data does not show this problem, but it must be tracked going forward.
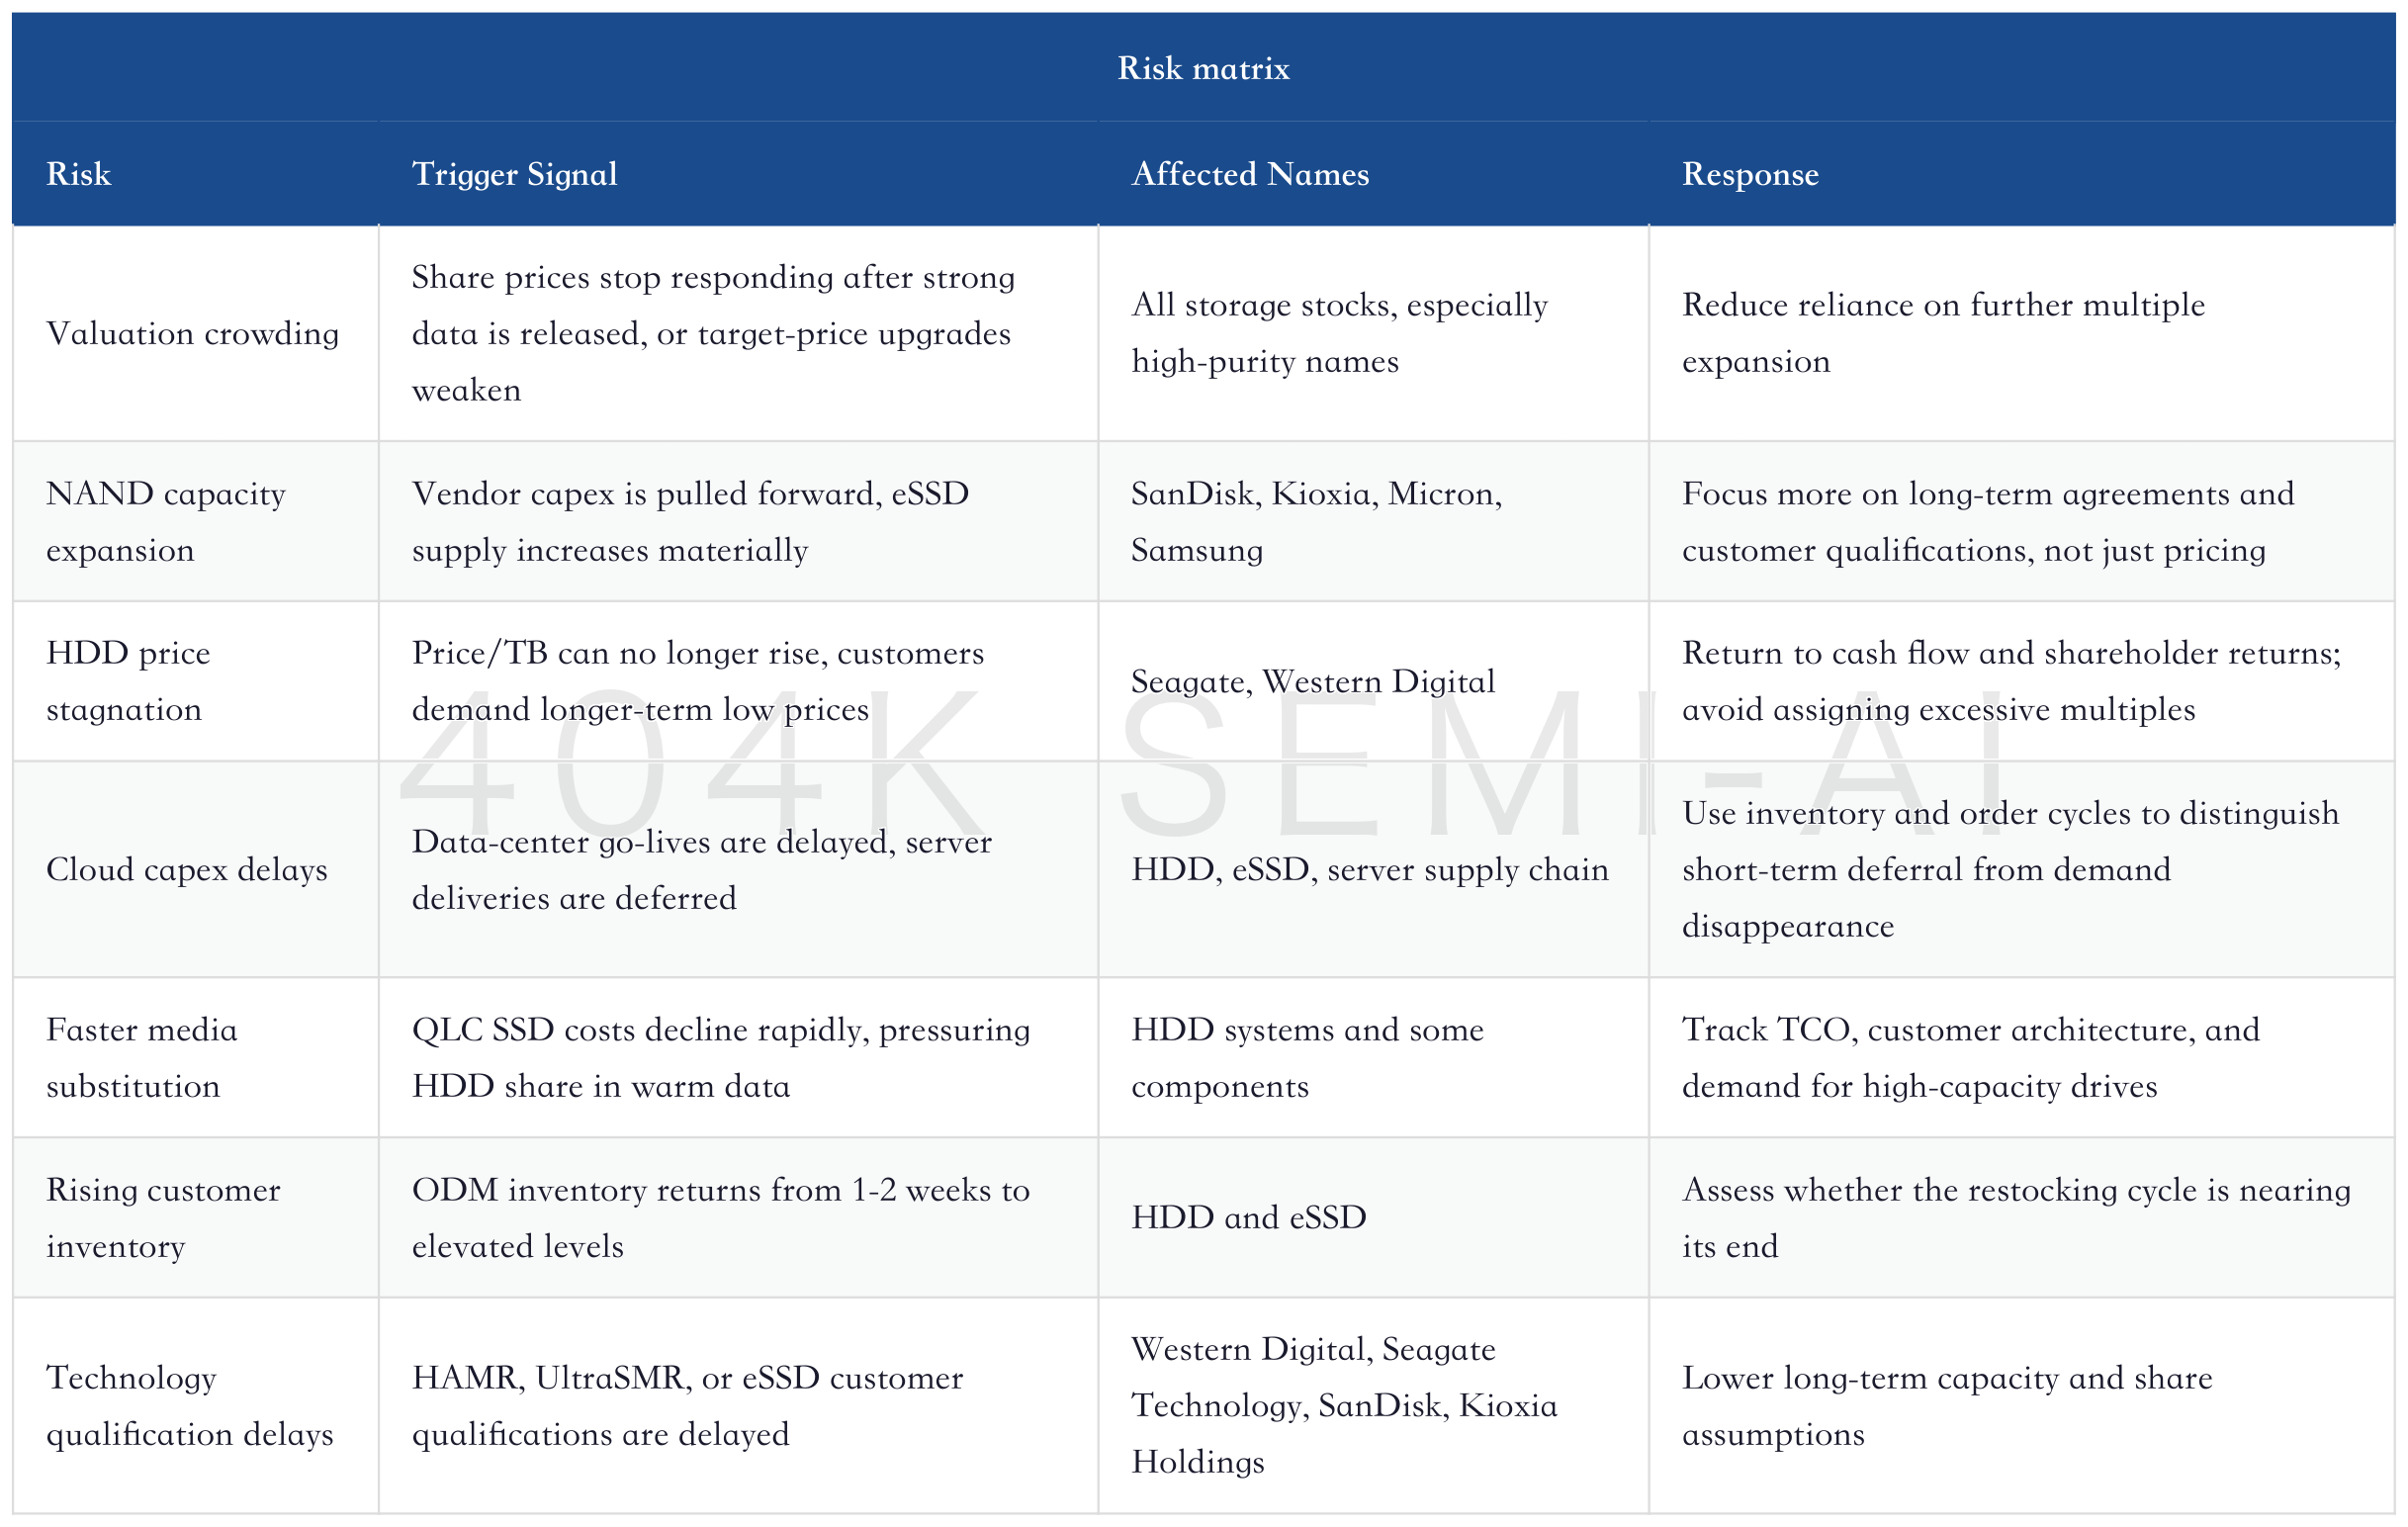
The purpose of this risk table is to avoid turning strong May data into a one-sided conclusion. A deep-dive report needs to provide a judgment, but also the conditions under which that judgment fails. The current base case remains positive, but if more than two negative signals appear together, such as a reversal in eSSD capacity growth, HDD price stagnation, and rising customer inventory, then the market should acknowledge that the trade has shifted from structural rerating back to cyclical trading.
11. Conclusion: May Data Moves AI Storage from Narrative Back to Physical Validation
The most important conclusion from Morgan Stanley’s May HDD and SSD data is that data-center capacity demand remains high, and its strength comes from structure rather than one-month noise. Nearline HDD year-on-year growth, enterprise SSD capacity doubling, flat total SSD unit shipments but strong enterprise SSD performance, and rising shares of helium drives and high-capacity products together show that AI data centers are extending the entire storage hierarchy.
From an investment perspective, this cannot be resolved with a simple statement that “storage remains attractive.” HDD and eSSD have different valuation anchors. HDD depends on supply discipline, price/TB, and long-term capacity visibility; eSSD depends on enterprise share, customer qualification, long-term agreement quality, and NAND capex discipline; full-category memory vendors also need to be assessed on capital allocation across HBM, DRAM, and NAND.
A more practical reading is to treat the May data as a stress-test sheet. It does not prove that every company is cheap, but it can show whether the main demand line has broken, which segments are still delivering, and which segments are merely rising in sympathy. As long as this tiered validation continues, the research focus for the storage chain should move upstream from “whether prices have risen” to “who can turn strong demand into more durable cash flow.”
The strongest core view remains: the AI storage trade is moving from a pricing cycle into a validation cycle. The prior phase relied on price increases and target-price upgrades; the next phase must rely on monthly data, earnings, customer contracts, and supply discipline to prove that profits are not a short peak. The May data is on the bulls’ side, but it also makes the future disconfirmation points clearer.
If enterprise SSD capacity continues to be revised upward over the next few months, nearline HDD helium drives maintain high growth, and price/TB continues to rise, valuation discounts for storage stocks still have room to decline. If these indicators begin to diverge, especially if enterprise SSD capacity growth reverses, cloud customer inventory rises, and HDD prices stagnate, then this rerating should be downgraded from “structural scarcity” back to “strong cyclical upturn.” The advantage of this conclusion is that it can be continuously falsified by monthly data.
The main sources are Morgan Stanley Japan Electronic Components team’s May HDD/SSD Data: DC Volumes Remain High, Morgan Stanley U.S. Hardware team reports on HDD demand and Western Digital management meetings, and the archived AI storage deep-dive report series.AI Storage Deep Dive Update: Morgan Stanley’s May HDD and SSD Data Confirm Data Center Capacity Demand Remains Elevated
目录
Too Long; Didn’t Read
1. What the May Data Answers: Has AI Storage Demand Fallen?
2. HDDs and SSDs Are Not a Zero-Sum Replacement Cycle, but Tiered Expansion of the AI Data Stack
3. Why Capacity Growth Matters More Than Unit Growth
4. HDD Chain: High-Capacity Nearline Drives Are More Worth Tracking Than Total HDD Units
V. Enterprise SSDs: NAND’s Real Strength Is Data Centers, Not Consumer SSDs
VI. Putting HDD and eSSD in the Same Ranking Table
7. Three Worldviews: Cyclical Peak, Structural Re-Rating, Extreme Shortage
8. Falsification Checklist: What to Watch Over the Next Four Quarters
9. From Monthly Data to the Model: How Profit Transmits
10. Risks: Strong Data Can Still Be Offset by Valuation and Supply Response
11. Conclusion: May Data Moves AI Storage from Narrative Back to Physical Validation
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Morgan Stanley’s May HDD and SSD monthly data adds hard evidence to the storage trade: data center capacity demand remains elevated, and nearline HDDs and enterprise SSDs are not cannibalizing each other. Instead, each is becoming scarcer in the AI data stack. The key metrics to track are not monthly unit shipments, but EB capacity, drive capacity, customer visibility, and pricing discipline.
Too Long; Didn’t Read
Data center storage has not weakened. May nearline HDD production reached 7.07mn units, +14.8% YoY and +4.0% MoM; enterprise SSD capacity shipments reached 41.35EB, +138.8% YoY and +9.7% MoM. The read-through is direct: cloud vendors are still taking capacity, and AI training, inference, video, logs, and object storage have not seen a demand cliff.
HDDs and SSDs coexist in tiers. Morgan Stanley divides data center storage into three layers: SSD, HDD, and tape. This is closer to reality than the old “SSD replaces HDD” narrative. Enterprise SSDs handle high throughput, low latency, and hot data; nearline HDDs handle large capacity, low cost, and cold/warm data; tape handles long-term archival. The larger AI data volumes become, the more all three layers are pulled higher.
Capacity matters more than units. 2026 data center enterprise SSD capacity shipments are forecast at 509.33EB, +94.0% YoY; data center nearline HDD capacity shipments are forecast at 1,841EB, +30.1% YoY. Unit shipments do not look as dramatic, but higher drive capacity, a rising helium drive mix, and higher average enterprise SSD capacity drive EB growth far above unit growth.
The HDD re-rating remains supported by data. Total HDD production rose +6.9% YoY in May, but nearline HDDs rose +14.8% YoY and helium nearline drives rose +22.5% YoY. Growth is coming from high-capacity cloud drives, not traditional PC and consumer drives. The value of HDD suppliers is not only in price increases, but also in the industry’s ability to use limited supply to serve a more durable long-term capacity demand base.
Enterprise SSDs validate NAND upside. Total SSD unit shipments fell -0.5% YoY in May, but enterprise SSD unit shipments rose +45.8% YoY and capacity shipments rose +138.8% YoY. This shows sharp divergence within NAND demand. Consumer SSDs and PC SSDs cannot represent data center eSSD demand. Valuation divergence across SanDisk, Kioxia, Micron, and Samsung should center on enterprise SSD share and the quality of long-term agreements.
The component chain has extension optionality. Japanese electronics component companies such as TDK, Nidec, Minebea Mitsumi, HOYA, and Resonac do not sell complete HDD systems directly, but they benefit from demand for heads, motors, glass substrates, and media in high-capacity drives. The key is not total HDD units, but the fact that each HDD needs more heads and platters. The high-capacity roadmap raises component value content.
The falsification points are clear. If enterprise SSD capacity growth later falls back to ordinary SSD levels, helium nearline HDD growth slows, cloud customer inventory rises quickly from 1-2 weeks, or price/TB can no longer rise sequentially by quarter, the storage re-rating will revert to a traditional cycle. If EB capacity continues to grow strongly and suppliers avoid expanding greenfield capacity, the market will continue to reduce the cyclical discount applied to HDD and eSSD earnings.
1. What the May Data Answers: Has AI Storage Demand Fallen?
The most valuable part of the May HDD and SSD data is that it pulls the statement “AI storage remains very strong” back from company guidance into monthly shipments. Company calls can be emotional, and target-price increases can lag. Monthly industry data is better suited to verifying whether the trend is still intact. Morgan Stanley’s conclusion is clear: data center storage continues to grow in tiers, with both nearline HDDs and enterprise SSDs still at elevated levels.
This is not a grand narrative report. Its value lies in the granularity of the monthly data: total HDDs, nearline HDDs, helium drives, total SSD shipments, enterprise SSD units, enterprise SSD capacity, HDD heads, motors, media, and supplier share are all updated. For investors, this is more useful than a simple statement that “AI demand is strong,” because it shows which layer is strong, which layer is merely stable, and which layer is already declining.
The May data first gives an overall outline: total HDD production is still growing moderately, with nearline HDDs the strongest segment; total SSD unit shipments are slightly weak, but enterprise SSDs are the strongest segment within SSDs. In other words, end-consumer storage is not seeing a broad synchronized recovery. The real strength is in the data center capacity layer.
The most easily overlooked point is the difference between units and capacity. Both HDDs and SSDs are entering a phase in which units look flat while capacity rises quickly. HDDs rely on drive capacity, helium drives, more platters, and higher areal density; SSDs rely on higher average enterprise product capacity. Investors who only look at units will underestimate the real revenue and earnings elasticity of this storage cycle.
AI Is Driving a Storage Industry Re-rating: Who Has the Most Pricing Power Across DRAM, NAND, SSD, and HDD, as Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Results Cross-Validate Each Other
This also explains why the May data does not overturn the earlier storage-series framework. The AI data stack is pulling not only HBM, nor is it simply driving a single NAND price increase. The real change is happening in the data itself: model training requires checkpoint storage, inference requires context caching, video and multimodal data create larger cold/warm data pools, and enterprise applications turn logs, vectors, retrieval, and permission states into persistent assets. The more data there is, the more systems need to place data with different access frequencies into different tiers.
Morgan Stanley’s monthly data validates exactly this point. Nearline HDDs did not lose momentum because enterprise SSDs were strong, and enterprise SSDs did not lose momentum because HDDs were strong. Both are growing together, showing that cloud vendors are not simply replacing one medium with another, but expanding the entire storage pyramid.
2. HDDs and SSDs Are Not a Zero-Sum Replacement Cycle, but Tiered Expansion of the AI Data Stack
The storage bottleneck in AI data centers is not “HDD or SSD,” but the need to expand every data tier. The market used to like the SSD-replaces-HDD story because in PCs and consumer electronics, the user-experience gap was obvious enough. Data centers do not follow that logic. A hyperscale cloud platform simultaneously needs high performance, low latency, high capacity, low cost, low power, and long-term retention. A single medium struggles to satisfy all of these at once.
Enterprise SSDs are advantaged in hot and warm data. Model weights, vector databases, caches, RAG retrieval, online inference state, training intermediate files, database logs, and high-frequency access data all require higher throughput and lower latency. Here, NAND’s value shifts from “cheap capacity” to a “system performance variable.” This is why enterprise SSD unit shipments rose only 45.8%, while capacity rose 138.8%: customers are buying larger and higher-value drives.
Nearline HDDs are advantaged in large capacity and cost. Not all AI-generated data needs low-latency access. Training corpora, video, images, logs, synthetic data, archived objects, infrequently accessed data lakes, and backups all require storage at scale. HDDs still have a TCO advantage, especially when NAND prices are also rising. That makes HDD’s capacity-layer value even clearer.
Tape is the longer-duration archival layer. It does not directly determine the listed-company upside in this report, but Morgan Stanley’s inclusion of tape in data center storage tiering is an important reminder: AI data centers will not be dominated by a single medium. Data access frequency and retention period determine medium selection.
The key in this table is not to label every medium a beneficiary, but to distinguish the logic of each benefit. HBM and DRAM are closer to compute bandwidth, enterprise SSDs are closer to performance storage, HDDs are closer to low-cost capacity, and tape is closer to archival insurance. They all belong to the AI data stack, but their valuations and falsification points are different.
This is also the fundamental reason why HDDs and eSSDs can both be strong right now. SSDs entering data centers do not mean HDD demand must disappear; tight HDD supply does not mean enterprise SSDs have no room. The real demand in AI data centers is expansion of the total capacity pool, not share-grabbing within the same pool. As long as data generation grows faster than medium substitution, multiple storage media will remain tight at the same time.
This view is consistent with Morgan Stanley’s April data. The April report had already pointed in the same direction: data center demand remained strong, with 2026 enterprise SSD capacity shipments then forecast at 476.1EB and data center nearline HDD capacity at 1,844EB. The May report raises the enterprise SSD capacity forecast to 509.33EB, while nearline HDDs still maintain roughly 30% growth. The incremental change comes from another upward revision to eSSD forecasts, not an HDD collapse.
This set of changes is important. The fact that nearline HDD forecasts were not revised up sharply again may mean near-term supply is already relatively locked in. The continued upward revision to enterprise SSD forecasts shows that the slope of AI-driven NAND demand is still being re-understood by the market. HDDs reflect scarcity and pricing more, while eSSDs reflect capacity and share more.
3. Why Capacity Growth Matters More Than Unit Growth
What storage companies really sell is EB and value, not simply units. Traditional hardware analysis tends to start with shipment units, which is useful for PCs, smartphones, and ordinary consumer electronics. But for HDDs and enterprise SSDs, unit shipments can no longer explain revenue. A higher mix of high-capacity drives, rising average capacity for enterprise SSDs, and the expansion of helium drives and multi-platter architectures all allow capacity growth to far exceed unit growth.
Total HDD production in May increased only 6.9% YoY, which does not look particularly impressive. But nearline HDDs grew 14.8% YoY, and helium nearline HDDs grew 22.5% YoY. More importantly, Morgan Stanley’s HDD capacity shipment forecast shows total HDD capacity at 1,627.9EB in 2025, above 2,000EB in 2026, and continuing to rise in 2027 and 2028. In other words, HDD industry units can be close to stable, while capacity and price/TB can still drive revenue and profit.
The same logic applies to enterprise SSDs. Enterprise SSD unit shipments in May were already strong at +45.8% YoY; capacity shipments were even stronger at +138.8% YoY. This embeds two variables: data center customers are buying more enterprise drives, and average capacity is rising significantly. The latter is critical for NAND vendors, because high-capacity enterprise SSDs usually have higher qualification barriers, more complex firmware, stronger controller requirements, and higher customer stickiness.
This table shows that after storage enters the AI cycle, investors need to shift the analytical unit from “units” to “capacity, pricing, and profit quality.” HDD units are unlikely to recover to levels seen ten years ago, but that does not stop HDDs from becoming scarce capacity assets in AI data centers. Total SSD units can even decline, while enterprise SSDs still lift the slope of NAND demand.
Global Storage Deep Dive: 2Q26 Earnings Divergence, and Whether 3Q Pricing Improvement Can Restart Storage Stock Re-Rating
This also affects valuation. Traditional cyclical valuations focus on the pricing cycle: estimates are revised up when prices rise and revised down when prices fall. AI storage valuation needs one additional layer: whether customers are buying higher-capacity, higher-value products with longer qualification cycles. If so, profit volatility still exists, but the cyclical discount can decline.
4. HDD Chain: High-Capacity Nearline Drives Are More Worth Tracking Than Total HDD Units
The core of this HDD re-rating is not a recovery in PC hard drives, but the transformation of nearline capacity drives into long-duration capacity assets for cloud customers. Total HDD production in May was 11.26 million units, +6.9% YoY, of which nearline HDD production was 7.07 million units, +14.8% YoY. This means nearline drives have already become the most important growth source for the HDD industry.
Looking one level deeper, nearline HDDs are also upgrading internally. Helium nearline drives reached 5.94 million units in May, +22.5% YoY; air drives were 1.13 million units, -13.7% YoY. This shows industry growth is coming from higher-capacity, higher-value products. For the supply chain, helium drives and high-capacity drives typically mean more heads, more platters, more complex structures, and higher reliability requirements, lifting component value content accordingly.
Vendor structure also points to synchronized growth. Western Digital, Seagate, and Toshiba all expanded nearline HDD production in May, indicating this is not a share fluctuation at a single company but broad industry demand at a high level. The specific figures are shown in the table below.
Western Digital Deep Dive: From 2032 Visibility to Re-Rating as a Scarce HDD Asset
HDD pricing power comes from supply discipline and customer visibility. Morgan Stanley’s U.S. hardware team previously noted in its HDD report that Asian channel checks suggested nearline HDD demand could grow close to 40%-50% annually, while supply EB growth was closer to 30%-35%; customers want to see capacity visibility out to 2032, but suppliers are not rushing to lock in long-term commercial terms. Western Digital management also noted during roadshows that customers are providing longer visibility, ODM inventory is only 1-2 weeks, and supply will not be solved through new greenfield capacity.
Japan’s May electronic components data provided monthly validation of this theme. Nearline HDD production is still growing, high-capacity helium drives are stronger, and HDD head, media, and motor data do not show a demand cliff. For the HDD chain, this is not a simple story of “cyclical stocks raising prices,” but a change in cash-flow quality as limited supply serves longer-duration demand.
HDD Price Hike Again: AI Data Retention, 2032 Visibility, and the Upgrade Logic for Seagate and Western Digital
This point is most direct for Seagate and Western Digital. Seagate looks more like a high-purity HDD cash-flow asset, with its technology roadmap and price/TB leverage as the core. Western Digital is also purer after the spin-off, but its investment narrative emphasizes customer visibility, the dual-track UltraSMR/HAMR roadmap, and capital returns. Neither company should still be viewed only through the PC hard-drive cycle.
For the Japanese component chain, the mapping is more granular. TDK still has an important share in HDD heads, Nidec and Minebea Mitsumi dominate motors, and HOYA and Resonac have exposure to glass substrates and media. Morgan Stanley’s report also breaks down the HDD supply chain in detail, because high-capacity drives do not only change the profit profile of system vendors; they also change the component value per drive.
Some restraint is needed here: the component chain is not necessarily more levered than system vendors. High-capacity drives will lift value content, but system vendors control pricing and customer relationships, while component vendors depend on share, qualification, and bargaining power. Companies such as TDK and Nidec are better used as confirmation signals for HDD strength, rather than simple substitutes for core exposure to Seagate and Western Digital.
V. Enterprise SSDs: NAND’s Real Strength Is Data Centers, Not Consumer SSDs
Enterprise SSDs are the strongest data point in this report, and the clearest monthly validation for a NAND re-rating. Total SSD unit shipments in May were down 0.5% YoY. Looking only at that number could lead to the mistaken view that NAND demand is merely average. But enterprise SSD unit shipments rose 45.8% YoY, while capacity shipments rose 138.8% YoY. Taken together, these two figures show that a structural migration is taking place within NAND.
Demand for ordinary SSDs is tied to PCs, gaming, and consumer electronics. It is price-sensitive and easily disrupted by end-market inventory. Demand for enterprise SSDs is tied to cloud CapEx, AI training and inference, databases, search, object storage, RAG, vector databases, content delivery, and video data. Procurement cycles are longer, qualification is more complex, and customers care more about performance stability and delivery certainty.
The SSD segment data captures this divergence. Consumer-related SSDs remain weak, while enterprise SSDs are clearly stronger than the overall market on both unit and capacity metrics. What NAND suppliers most need to win is not a recovery in ordinary SSDs, but enterprise SSD share and qualification for high-capacity products. The detailed breakdown is below.
SanDisk Deep Dive Update: Jefferies Raises Target Price to $3,000; How eSSD Share Recovery and NAND Long-Term Agreements Re-rate Earnings Durability
The implications differ for SanDisk, Kioxia, Micron, and Samsung. For SanDisk, the key points are data center SSD share, NBM long-term agreements, and QLC product ramp. For Kioxia, they are the eSSD revenue mix, BiCS8 cost declines, and scale effects from joint manufacturing with SanDisk. For Micron, the question is whether NAND and data center SSDs can contribute a second profit line beyond DRAM/HBM. For Samsung, the focus is its full-category breadth and whether it can benefit from NAND and eSSD recovery alongside its HBM catch-up.
NAND prices alone are not enough here. Price increases are certainly useful, but what can truly reduce the valuation discount is customer quality and product mix. If eSSD growth is merely ordinary cyclical restocking, the market will assign a low multiple. If eSSD growth comes from hyperscaler qualifications, long-term contracts, controller and firmware capabilities, and a high-capacity QLC roadmap, the market will view part of the profit pool as more stable infrastructure cash flow.
Kioxia Deep Dive Update: Goldman Sachs Raises Target Price to ¥116,000; How NAND Tightness Re-rates the AI Storage Cycle
Morgan Stanley’s May data is especially important for pure NAND names such as Kioxia. Kioxia has no HDD business. Its re-rating must rely on NAND supply-demand, enterprise SSD share, data center customer qualifications, and the cost curve. Enterprise SSD capacity shipments rose 138.8% YoY in May, showing that the overall market is still creating opportunities for pure NAND suppliers. But total SSD unit shipments were down 0.5% YoY, which also reminds the market not to value all NAND products at the same level of strength.
The same applies to SanDisk. SanDisk’s valuation debate has long centered on two questions: whether NAND prices are at a cyclical peak, and whether eSSD and NBM long-term agreements can make earnings more visible. The May data does not directly prove SanDisk’s own share gains, but it does prove that the enterprise SSD market is strong enough. If SanDisk subsequently delivers on share, long-term agreements, and high-capacity QLC products together, its earnings quality will be better than that of an ordinary NAND cycle.
Micron Earnings Deep Dive: Q3 Results Far Exceed Expectations; The AI Storage Supercycle Enters the Delivery Phase, How Much Profit Can Long-Term Agreements Lock In?
VI. Putting HDD and eSSD in the Same Ranking Table
The May data makes the ranking of storage companies clearer: HDD is about scarce cash flow, eSSD is about share and customer qualification, and DRAM/HBM is about bandwidth and profit purity. All are driven by AI, but their valuation anchors differ. Saying “all storage is good” loses the most important distinctions.
Seagate and Western Digital are the most direct beneficiaries of nearline HDDs. Their core questions are: can price/TB continue to rise, can long-term customer visibility translate into harder contracts, and will suppliers continue to avoid greenfield capacity expansion? If these conditions hold, HDD profits should not be fully discounted as a traditional cyclical peak.
SanDisk and Kioxia are the most direct beneficiaries of enterprise SSDs. Their core questions are: can eSSD share improve, can QLC/TLC products pass more hyperscaler qualifications, will NAND capital spending remain disciplined, and can long-term agreements lock in profits? If these conditions hold, NAND earnings are not just spot price volatility.
Micron, Samsung, and SK hynix have broader frameworks. They are of course driven by DRAM, HBM, and server memory, but eSSD and NAND also reinforce full-category breadth. Micron’s mapping to U.S. AI storage, Samsung’s breadth assets, and SK hynix’s HBM purity all need to be assessed alongside marginal changes in NAND/eSSD.
This ranking has an important implication: HDD is not necessarily more “backward” than NAND, and NAND is not necessarily more “advanced” than HDD. In an investment framework, being advanced does not determine valuation; scarcity position does. HDD is scarce in the low-cost capacity tier, eSSD is scarce in the high-performance capacity tier, and HBM is scarce in the bandwidth tier. Different forms of scarcity map to different companies and different risks.
Storage Deep Dive Update: Morgan Stanley Calls for Buying Old Storage; Why DDR4, SLC NAND, and NOR Are Still Rising
There is a common thread between price increases in legacy storage and strong demand for HDD/eSSD: AI is absorbing high-end supply and capital spending priority, making traditional products tighter because supply is insufficient. HDD has not been quickly supplemented by new greenfield capacity, and suppliers have not prioritized expansion for legacy DRAM, SLC NAND, or NOR either. The market used to treat these products as mature, low-growth, low-valuation assets. It is now discovering that maturity can also mean stronger supply discipline.
This does not mean all legacy assets can be re-rated. A re-rating requires three conditions: demand has not disappeared, supply is not easy to expand, and customers are willing to pay for availability. The May HDD and SSD data satisfy the first two conditions for nearline HDDs and enterprise SSDs. The third condition still needs to be tracked through pricing and contracts.
7. Three Worldviews: Cyclical Peak, Structural Re-Rating, Extreme Shortage
The biggest debate in this memory cycle is not whether the data is strong, but what valuation strong data deserves. Strong May data does not automatically mean all memory stocks are cheap. Share prices have already discounted a large amount of optimism. The real question is how much of current profit can be capitalized.
The market can be divided into three worldviews.
The first is the traditional cyclical peak. This framework acknowledges that HDD and enterprise SSD are very strong, but argues customers are over-ordering, suppliers will eventually add supply, and both NAND and HDD prices will fall back. In this world, May data only proves the cycle is not over; it does not prove valuation multiples should rise.
The second is structural re-rating. This framework argues that AI data centers make storage demand more resilient, longer-lasting, and less substitutable, while suppliers also have more supply discipline than in the past. In this world, May data is not just strong for the month. It indicates storage is moving from a short-cycle component into a bottleneck in AI infrastructure, allowing part of the profit pool to be discounted at a higher quality.
The third is extreme shortage. This framework argues that AI inference, agents, video, and physical AI will keep data growth ahead of expectations, with both HDD and enterprise SSD supply insufficient, price/TB, NAND contract prices, and customer long-term agreements continuing to move higher. In this world, current earnings forecasts are still too low, and the valuation ceiling may continue to expand.
The May data currently supports the second worldview more, while there is not yet enough evidence to prove the third. The reason is simple: enterprise SSD capacity was revised up significantly, and nearline HDD maintained high growth, supporting the structural re-rating case. But the forecast for total HDD capacity has not been revised up sharply again, while HDD prices and contract terms are not directly disclosed in this Japan electronic components monthly report. Extreme shortage therefore cannot yet be treated as the base case.
This judgment also matters for positioning. If all strong data is treated as extreme shortage, the research conclusion becomes target-price chasing. If strong data is treated only as a normal cycle, investors will miss the change in the asset attributes of AI storage. A steadier approach is to use structural re-rating as the base case, retain upside optionality from extreme shortage, and clearly list the indicators that would falsify the thesis.
8. Falsification Checklist: What to Watch Over the Next Four Quarters
Whether the storage re-rating can continue depends on whether data keeps moving along the path of “EB growth, pricing discipline, long-term agreement quality, and no supply expansion.” May data is one confirmation, not the final answer. Each subsequent month and quarter should return to the same set of indicators.
First, watch enterprise SSD capacity shipments. As long as enterprise SSD capacity continues to grow far faster than unit shipments, customers are buying higher-capacity, higher-value products, and NAND demand quality remains strong. If enterprise SSD capacity growth falls back to ordinary SSD levels, valuation for pure NAND names should become more conservative.
Second, watch nearline HDD capacity and helium drives. Total HDD unit shipments have limited significance. Nearline EB and the share of high-capacity drives matter more. If helium drives, heads/HDD, and media/HDD continue to rise, the high-capacity roadmap is still advancing.
Third, watch price/TB and contract terms. If HDD vendors can continue raising price/TB by quarter, while avoiding locking in commercial terms beyond 2030 too early, they can retain more profit flexibility. If enterprise SSD vendors can secure long-term customer commitments, prepayments, capacity locks, or a higher qualification share, the NAND cycle discount will decline.
Fourth, watch supply discipline. The biggest risk for HDD is new greenfield capacity undermining scarcity. The biggest risk for NAND is prices stimulating a rapid recovery in capital expenditure. As long as suppliers meet demand through technology migration and higher capacity per drive rather than large-scale new capacity, profit quality will be higher.
This tracking table also helps distinguish companies. For Seagate and Western Digital, first watch price/TB, nearline EB, and customer inventory. For SanDisk and Kioxia, first watch enterprise SSD capacity, qualifications, and long-term agreements. For Micron and Samsung, DRAM, HBM, and server memory must also be layered in. For TDK, Nidec, HOYA, and Resonac, watch high-capacity HDD component share.
9. From Monthly Data to the Model: How Profit Transmits
May data cannot be converted directly into a target price, but it can clearly flow into revenue, gross margin, valuation multiples, and risk discounting. If an in-depth report only says “May data was strong,” the information density is still insufficient. A more useful approach is to break the monthly data into four transmission chains: HDD price/TB, high-capacity HDD components, enterprise SSD capacity, and NAND supply discipline.
The first chain is HDD price/TB. Nearline HDD production and capacity demand are strong, while suppliers are unwilling to add supply quickly through greenfield capacity, so price/TB has room to continue rising. Price/TB has high profit leverage for Seagate and Western Digital, because much of the cost is already embedded in the fixed manufacturing system, and incremental pricing tends to flow more directly into gross margin expansion. Morgan Stanley’s U.S. hardware team previously estimated that if nearline HDD prices migrate from the low-teens dollars/TB toward above $20/TB, EPS leverage would be substantial. The May Japan electronic components data cannot prove where pricing already is, but it does prove the demand side has not weakened this price transmission.
The second chain is high-capacity HDD components. Helium drives grew +22.5% YoY, stronger than total HDD, indicating the high-capacity roadmap is still progressing. High-capacity drives bring demand for more heads, more platters, higher-precision motors, higher-quality glass substrates, and media. Component company leverage does not necessarily come from HDD unit growth, but from per-unit value and customer share. TDK, Nidec, Minebea Mitsumi, HOYA, and Resonac need to be analyzed by segment, rather than simply bundled as “HDD concept stocks.”
The third chain is enterprise SSD capacity. Enterprise SSD capacity grew +138.8% YoY, far above unit growth, indicating customers are buying larger-capacity, higher-value enterprise drives. This transmission chain is most important for NAND companies: if the share of high-capacity enterprise SSD rises, NAND suppliers’ product mix, customer stickiness, and long-term agreement quality all improve. Pure NAND or high-NAND-purity names such as SanDisk and Kioxia will benefit more directly than consumer SSD companies.
The fourth chain is NAND supply discipline. Enterprise SSD demand is strong. If suppliers immediately expand capacity aggressively, profits are only short-cycle. If capital expenditure remains restrained, and AI customers are willing to secure supply through long-term contracts and more stringent qualification, profit quality improves. Whether memory stock valuations can continue to expand depends largely on which supply response the market believes in.
This transmission table moves the investment judgment from “demand is strong” to “whose profits are more likely to be capitalized.” Capitalization for HDD OEMs comes from pricing and supply discipline. Capitalization for NAND vendors comes from enterprise SSD share and long-term agreements. Capitalization for component vendors comes from value content and share. For full-category memory vendors, HBM and DRAM must also be layered in.
A simple but useful judgment is that May data is positive for both HDD and enterprise SSD, but for different reasons across companies. Seagate and Western Digital get evidence of resilient demand, tight supply, and pricing flexibility. SanDisk and Kioxia get evidence that the enterprise SSD market continues to be revised up. TDK and Nidec get evidence that the high-capacity HDD chain has not broken down. Micron and Samsung get evidence that NAND is not purely a drag.
The real valuation question is which profits can be treated as “more durable profits.” Traditional memory stocks usually do not receive high multiples because prices, inventory, and supply response move too quickly, and earnings peaks are often cyclical peaks. The difference in this AI storage cycle is that data center customers are starting to buy longer-cycle capacity visibility, while suppliers are more willing to protect profits through long-term agreements, technology cadence, and capacity discipline. If this holds, the discount rate applied to the same $1 of profit for HDD and enterprise SSD companies should fall.
This is also why the investment implication of May data is more than “one month of upward revisions.” Strong monthly shipments are only the first layer of evidence. The second layer is capacity growth exceeding unit growth. The third layer is high-capacity products driving per-system value. The fourth layer is customers being willing to write this demand into longer-term commercial arrangements. Seeing only the first layer makes it easy to chase short-term momentum. Seeing the fourth layer is what justifies using asset re-rating as the base case.
The constraint from this table is strict: if only monthly data is strong, but pricing, contracts, and supply discipline are absent, memory stocks remain cyclical stocks. If monthly data is strong, while pricing, contracts, and supply discipline also begin to materialize, the market will discount part of future profits into more stable cash flow. May data currently strengthens demand and product mix. Pricing and contracts still need confirmation through future company earnings and management commentary.
One detail should not be overlooked: strong data for enterprise SSD and nearline HDD are not mutually exclusive within the same customer wallet. After cloud customers procure GPU servers, they must simultaneously expand hot data, warm data, cold data, and backup tiers. Enterprise SSD captures online services and high-frequency access budgets. HDD captures data lakes, object storage, and archive budgets. As long as AI applications lengthen data retention cycles, both will absorb cloud capital expenditure at the same time, rather than simply competing for the same hard-drive budget.
Therefore, the biggest place not to cut corners in models is avoiding treating “unit shipments” as the only volume variable. For HDD, investors should watch units, EB, price/TB, capacity per drive, and platter/head value content at the same time. For enterprise SSD, investors should watch units, EB, average capacity, enterprise mix, qualified customers, and NAND bit cost at the same time. If the model only contains one shipment volume and one ASP, it will force this AI storage re-rating back into a traditional electronic components cycle.
For portfolio allocation, this means the storage chain should not be rotated only based on “which stock has risen less.” A more reasonable sequence is to first confirm which data layer is closest to the income statement, then confirm which company is most sensitive to that data layer, and only then assess whether valuation already reflects it. HDD OEMs are closest to pricing and cash flow. NAND vendors are closest to enterprise SSD capacity and product mix. Component vendors are closest to the value content increase in high-capacity drives. All three asset classes benefit from AI storage, but the realization cadence differs.
In a simplified framework, HDD OEMs are “capacity scarcity + pricing discipline,” enterprise SSD is “AI hot data + NAND supply discipline,” and components are “per-drive complexity + share stability.” May data provided positive validation for all three lines, but with different intensity: HDD validated nearline demand and helium drives, enterprise SSD validated capacity shipments, and components validated that the upstream high-capacity roadmap has not been falsified. If subsequent earnings can convert these monthly signals into orders, gross margins, and cash flow, the storage chain still has room for further re-rating.
This also explains why storage stocks cannot be ranked as a simple leaderboard of share-price gains. HDD companies, NAND companies, DRAM/HBM companies, and component companies are driven by different variables, and their share-price reactions will also unfold in phases. The first phase usually prices in spot/contract pricing and target-price upgrades; the second phase prices in earnings delivery; the third phase prices in changes in earnings quality and valuation discounts. The May data is more of a validation point between the second and third phases.
10. Risks: Strong Data Can Still Be Offset by Valuation and Supply Response
Strong May data does not mean the storage trade is risk-free. The real risk is not that demand immediately disappears, but that the market extrapolates strong data too far, or that suppliers restart capacity expansion under the stimulus of high prices. The most dangerous point in the storage cycle is often not when data is poor, but when data is strong and capital expenditure begins to turn aggressive with it.
The first risk is valuation crowding. Storage stocks have already gone through multiple rounds of target-price upgrades, and many share prices have moved ahead of fundamentals. Strong monthly data can support the direction of the trade, but it does not necessarily support continued multiple expansion for every company. The higher the purity and the larger the prior gains, the more the valuation needs to be supported by harder evidence from contracts, pricing, and customers.
The second risk is supply response. The HDD industry currently has stronger supply discipline, and adding new greenfield capacity is difficult. This is the core of the HDD rerating. But the NAND industry has historically been more susceptible to price-driven capital expenditure. If NAND pricing and eSSD demand are too strong, and suppliers pull forward expansion plans, price assumptions for 2027-2028 will be pressured lower.
The third risk is changes in TCO across media. HDD and eSSD currently coexist in a tiered architecture, but marginal use cases will be affected by cost changes. If NAND costs fall faster than expected, some warm data may migrate to QLC SSDs; if NAND prices remain high, HDD’s TCO advantage will become more evident. This is not a binary choice, but marginal share and price negotiations will change.
The fourth risk is the pace of cloud capital expenditure. AI data-center storage demand is ultimately constrained by data-center ramp-up, server deployment, GPU utilization, and commercialization of inference applications. If power, racks, networking, or GPU deliveries slow down, storage orders may also be deferred in phases. The May data does not show this problem, but it must be tracked going forward.
The purpose of this risk table is to avoid turning strong May data into a one-sided conclusion. A deep-dive report needs to provide a judgment, but also the conditions under which that judgment fails. The current base case remains positive, but if more than two negative signals appear together, such as a reversal in eSSD capacity growth, HDD price stagnation, and rising customer inventory, then the market should acknowledge that the trade has shifted from structural rerating back to cyclical trading.
11. Conclusion: May Data Moves AI Storage from Narrative Back to Physical Validation
The most important conclusion from Morgan Stanley’s May HDD and SSD data is that data-center capacity demand remains high, and its strength comes from structure rather than one-month noise. Nearline HDD year-on-year growth, enterprise SSD capacity doubling, flat total SSD unit shipments but strong enterprise SSD performance, and rising shares of helium drives and high-capacity products together show that AI data centers are extending the entire storage hierarchy.
From an investment perspective, this cannot be resolved with a simple statement that “storage remains attractive.” HDD and eSSD have different valuation anchors. HDD depends on supply discipline, price/TB, and long-term capacity visibility; eSSD depends on enterprise share, customer qualification, long-term agreement quality, and NAND capex discipline; full-category memory vendors also need to be assessed on capital allocation across HBM, DRAM, and NAND.
A more practical reading is to treat the May data as a stress-test sheet. It does not prove that every company is cheap, but it can show whether the main demand line has broken, which segments are still delivering, and which segments are merely rising in sympathy. As long as this tiered validation continues, the research focus for the storage chain should move upstream from “whether prices have risen” to “who can turn strong demand into more durable cash flow.”
The strongest core view remains: the AI storage trade is moving from a pricing cycle into a validation cycle. The prior phase relied on price increases and target-price upgrades; the next phase must rely on monthly data, earnings, customer contracts, and supply discipline to prove that profits are not a short peak. The May data is on the bulls’ side, but it also makes the future disconfirmation points clearer.
If enterprise SSD capacity continues to be revised upward over the next few months, nearline HDD helium drives maintain high growth, and price/TB continues to rise, valuation discounts for storage stocks still have room to decline. If these indicators begin to diverge, especially if enterprise SSD capacity growth reverses, cloud customer inventory rises, and HDD prices stagnate, then this rerating should be downgraded from “structural scarcity” back to “strong cyclical upturn.” The advantage of this conclusion is that it can be continuously falsified by monthly data.
The main sources are Morgan Stanley Japan Electronic Components team’s May HDD/SSD Data: DC Volumes Remain High, Morgan Stanley U.S. Hardware team reports on HDD demand and Western Digital management meetings, and the archived AI storage deep-dive report series.