
AI PCB and CCL Deep Dive: From GB300 to Rubin Ultra, What Runs Short First: High-Layer PCBs, M9 Materials, or Electronic Glass Fabric?
目录
Too Long; Didn't Read
I. AI Servers Enter Board-Level Shortage: PCB and CCL Move From Peripheral Materials to Delivery Gates
II. Demand Side: AI-PCB TAM Expands From GPU Boards to ASICs, CPUs, Switches, and Optical Modules
III. Specification Side: From GB300 to Rubin, TPU, and Trainium, How Board-Level Content Value Rises
IV. Supply Side: PCB Expands Fastest, CCL Next, Electronic Glass Fabric Slowest; Pricing Power Is the Reverse
V. Pricing Power: PCB Makers Earn Orders, CCL and Electronic Glass Fabric Earn Scarcity; Who Turns Price Hikes Into Profit?
VI. Company Ranking: WUS Printed Circuit, Victory Giant Technology, Shengyi Technology, Shennan Circuits, Guanghe Technology, and the Taiwan Material Chain Are Not the Same Opportunity
VII. Value-Chain Pass-Through: Five Profit Pools Behind One AI Board
VIII. From Orders to Cash Flow: Five Tables to Verify in AI PCB Phase Two
IX. Three Scenarios: Continued Price Hikes, Effective Supply Opening, and Platform Timing Delays
X. Valuation and Target Prices: Do Not Reduce a High-Prosperity Industry to One Multiple
XI. What to Track Over the Next Four Quarters: Do Not Wait for Financial Reports to Decide
XII. Falsification Checklist: When Board-Level Interconnect Enters the Second Half
XIII. Conclusion: The Main Line for AI PCB and CCL Is Not Expansion, but Qualified Capacity and Profit Delivery
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The bottleneck in AI servers is spilling over from GPUs and CoWoS into board-level interconnect. PCBs, CCLs, electronic glass fabric, copper foil, and HDI are no longer peripheral materials. They are the small gates that determine whether Rubin, Google TPU, and 1.6T switches can come online on schedule. The real investment debate is who can turn price hikes into profit.
Too Long; Didn't Read
The bottleneck has already spilled over. In the first phase of AI hardware, investors bought GPUs and advanced packaging. In the second phase, they are buying the ability to actually bring complete servers, switches, and ASIC clusters online. The value of PCB, CCL, HDI, mSAP, electronic glass fabric, and copper foil is not that they are "also AI." It is that without them, expensive chips cannot become operating racks.
Demand does not only come from NVIDIA. AI-PCB demand is expanding from GPU motherboards to Google TPU, CPU boards, switches, optical modules, and ASIC servers. The 1.6T networking upgrade will make switch and optical-module PCBs one of the fastest-growing branches. By 2028E, Google TPU-related PCB procurement could exceed the NVIDIA GPU chain, changing the customer mix for board-level interconnect.
CCL has more pricing power than PCB. PCB makers are expanding most aggressively, but many price increases are pass-throughs of material costs. CCL, electronic glass fabric, and high-end copper foil are expanding more slowly, customer qualification takes longer, and price elasticity is more direct. Industry-chain profit will continue to shift from simple PCB capacity expansion toward M8/M9 materials, Low Dk electronic glass fabric, HVLP copper foil, and high-end CCL suppliers.
Specification upgrades matter more than unit growth. The move from GB300 to VR200, Rubin Ultra, TPU 8t/8i, and Trainium 3 is not just about selling a few more boards. Layer count, low-loss materials, HDI, mSAP, and lamination yield all step up together. Commodity capacity cannot directly replace high-end capacity. The real supply question is customer qualification, yield, and material lock-in.
Company ranking depends on profit quality. WUS Printed Circuit wins on execution in switches and high-end communications PCBs. Victory Giant Technology wins on AI-server PCB capacity expansion and overseas customer elasticity. Shengyi Technology and Kingboard Laminates sit closer to upstream material pricing power. Elite Material and Taiwan Union Technology are Taiwan-listed high-end CCL representatives. Zhen Ding Technology ties together HDI, mSAP, substrates, and optical-module boards.
The biggest risk is effective supply opening up. If CCL expansion, electronic glass fabric supply, M9 qualification, and PCB capacity ramp all proceed smoothly from 2H26 to 2027, the price-hike thesis will cool. If cloud capex slows, Rubin or TPU platforms are delayed, or customers renegotiate, board-level interconnect stocks will bear valuation drawdown first. The key metrics to track are gross margin, order lock-in, and cash flow.
I. AI Servers Enter Board-Level Shortage: PCB and CCL Move From Peripheral Materials to Delivery Gates
The easiest mistake in AI hardware investing is putting every component into the same "AI server beneficiary" basket. When GPUs were short, the strongest assets were NVIDIA, HBM, TSMC advanced nodes, and CoWoS. After CoWoS targets were revised up, the market moved on to WoS, substrates, OSAT, and testing. Looking further out, what really determines whether racks can ship is the less conspicuous world of board-level interconnect and materials.
PCBs and CCLs used to be understood by the market as cyclical materials, with demand coming from communications, automotive, consumer electronics, and ordinary servers. AI servers have changed this business. The question is no longer "there are more servers, so there are more PCBs." It is that AI racks increasingly resemble high-power, high-bandwidth, high-density electrical systems. GPU boards, CPU boards, UBBs, switch trays, all-to-all switch boards, backplanes, optical-module boards, mSAP boards, and HDI boards together determine signal integrity and system yield.
This is why board-level interconnect is moving from peripheral material to a small delivery gate. GPUs, TPUs, ASICs, and CPUs all require higher bandwidth, lower loss, and more reliable power integrity. Data-center customers are buying delivered compute, not standalone chips. If one high-layer-count PCB, one low-loss CCL material, or one copper-foil supply step cannot keep up, complete-system shipment is delayed. The value chain is shifting from "chips are expensive enough" to "systems are hard enough."
In the previous phase, PCB discussions often centered on how large the TAM was and whether a company had AI orders. The better questions now are: what type of board is the company making, is the material grade moving up, has customer qualification penetrated the platform, is expansion locked by customers, and can price hikes show up in gross margin? Without those conditions, AI PCB is only a theme. With them, it becomes a delivery asset.
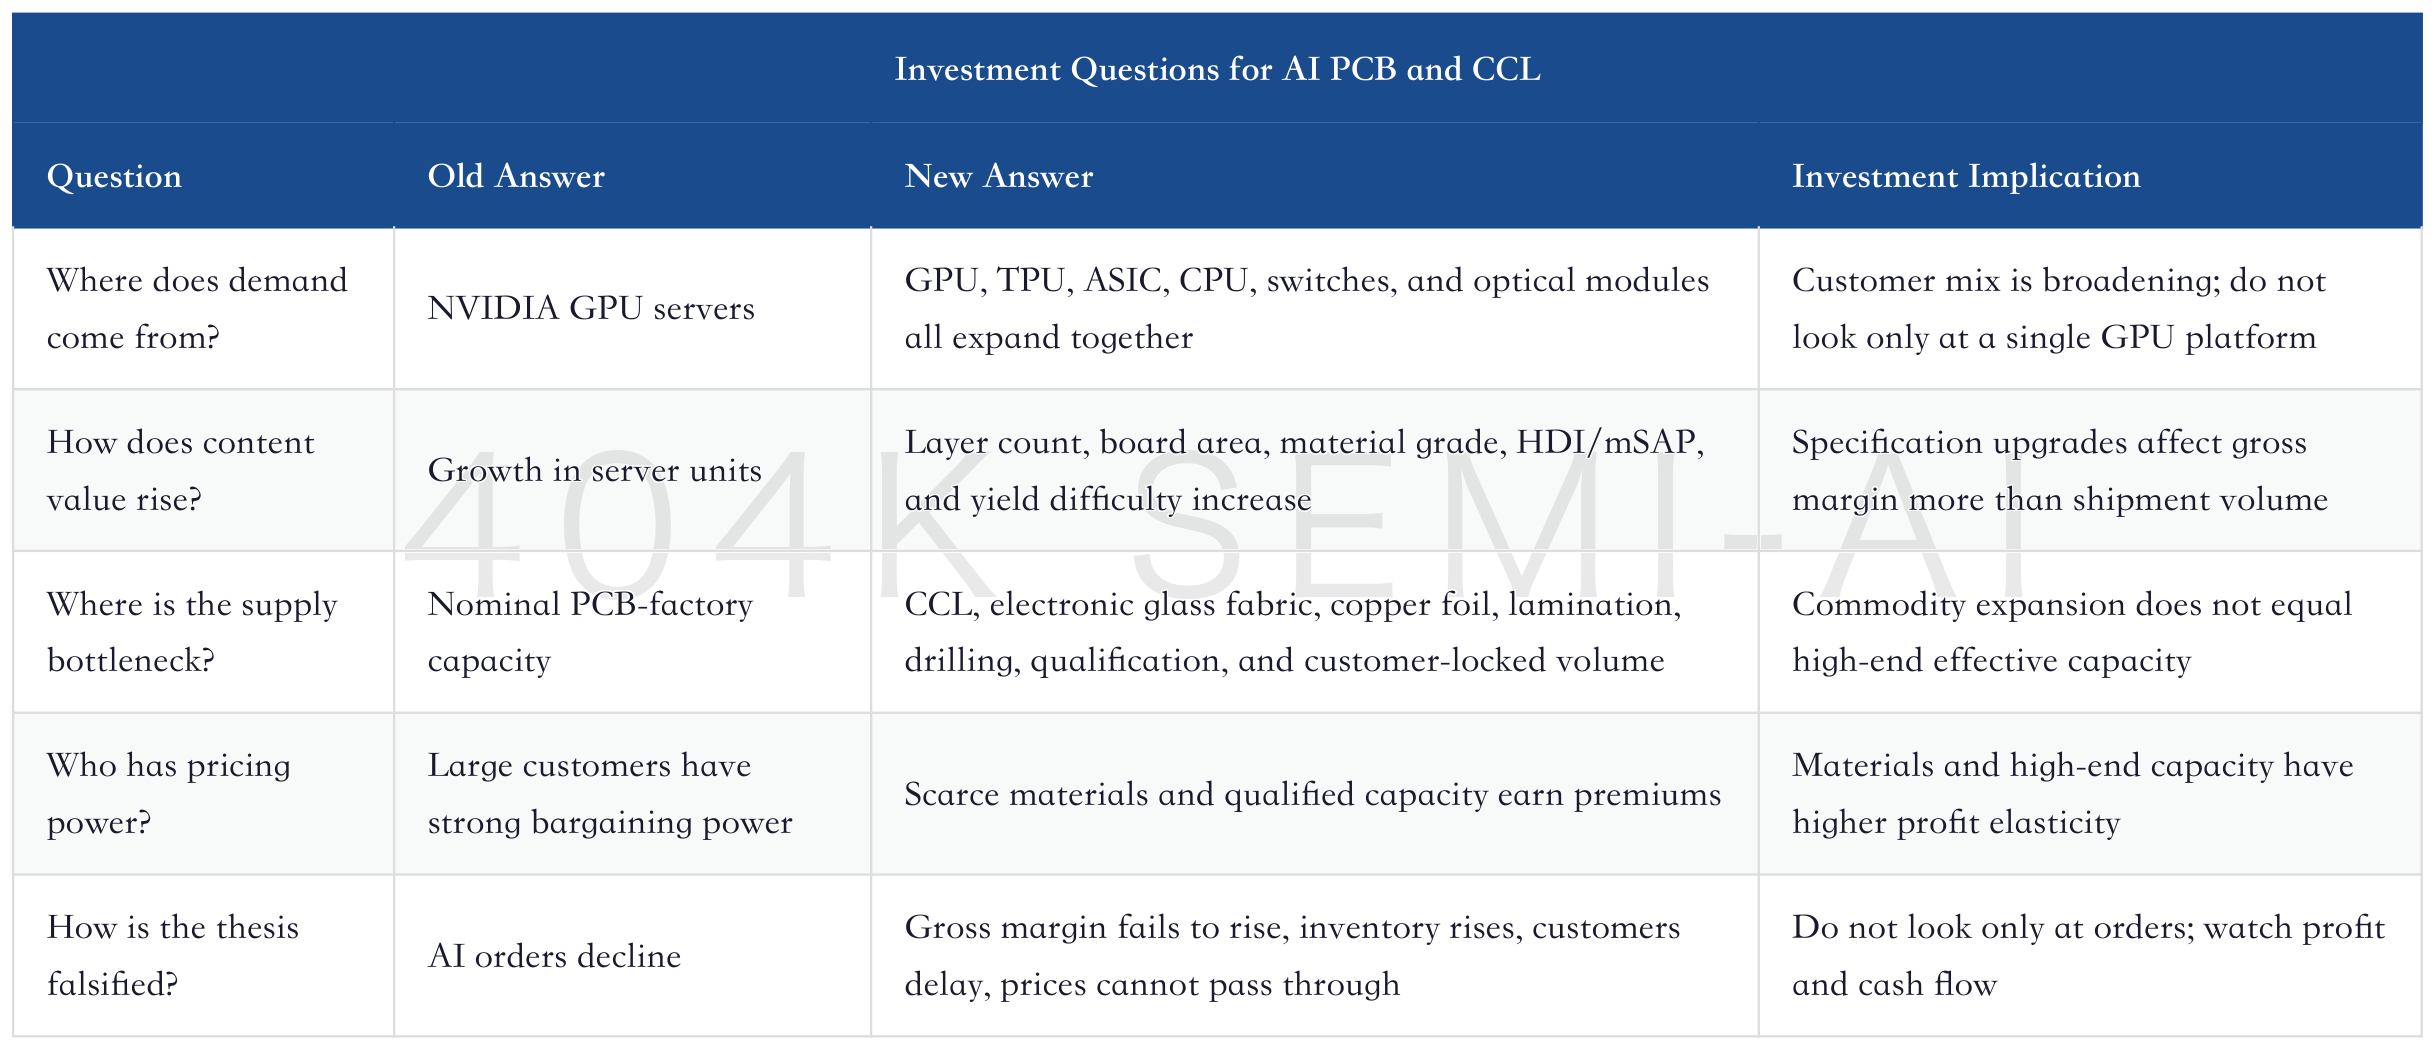
The main conclusion of this report is simple: the AI PCB and CCL cycle is not over, but the crude "buy every PCB maker" phase is over. Future excess returns will come from three types of companies. The first are PCB makers that can lock in leading AI customers and turn high-end board volume into cash flow. The second are CCL and upstream material suppliers that control M8/M9, high-end electronic glass fabric, and copper-foil materials and can raise prices directly. The third are platform suppliers that connect HDI, mSAP, substrates, optical-module boards, and other capabilities.
Full Reappraisal of AI PCB Materials: From CCL Price Hikes and Glass-Fabric Looms to the ABF Gap and Rack Upgrades
Compared with the material reappraisal in early May, two new variables have emerged. The first is the sharply increased weight of Google TPU and the ASIC chain, which means PCB/CCL is no longer just a shadow of the NVIDIA chain. The second is that supply pre-locking from 2H26 to 2027 is becoming a valuation anchor. Customers are starting to lock future capacity in advance, and material suppliers are beginning to choose AI projects with better profit.
II. Demand Side: AI-PCB TAM Expands From GPU Boards to ASICs, CPUs, Switches, and Optical Modules
The biggest change in AI-PCB demand is the broader definition. Early models mainly looked at compute boards and switch boards in GPU servers. Now CPU, ASIC servers, 1.6T switches, optical-module boards, and the future 3.2T networking upgrade all need to be included. After Citi added CPU and optical-module PCB demand into its model, the AI-PCB TAM curve was revised up materially. This is not a minor adjustment; it is a redrawing of the demand boundary.
From 2026E to 2028E, AI-PCB TAM rises from about RMB152 billion to RMB562 billion, implying a very high three-year CAGR. More important is the structure. ASIC remains the largest application in 2027E, and NVIDIA GPU remains important, but the shares of CPU, switches, and optical modules rise. This shows that PCB content value is starting to migrate with network and system architecture. By 2028E, Google TPU-related PCB procurement could exceed the NVIDIA GPU chain, and the "No. 1 customer" for board-level interconnect will no longer naturally be NVIDIA.
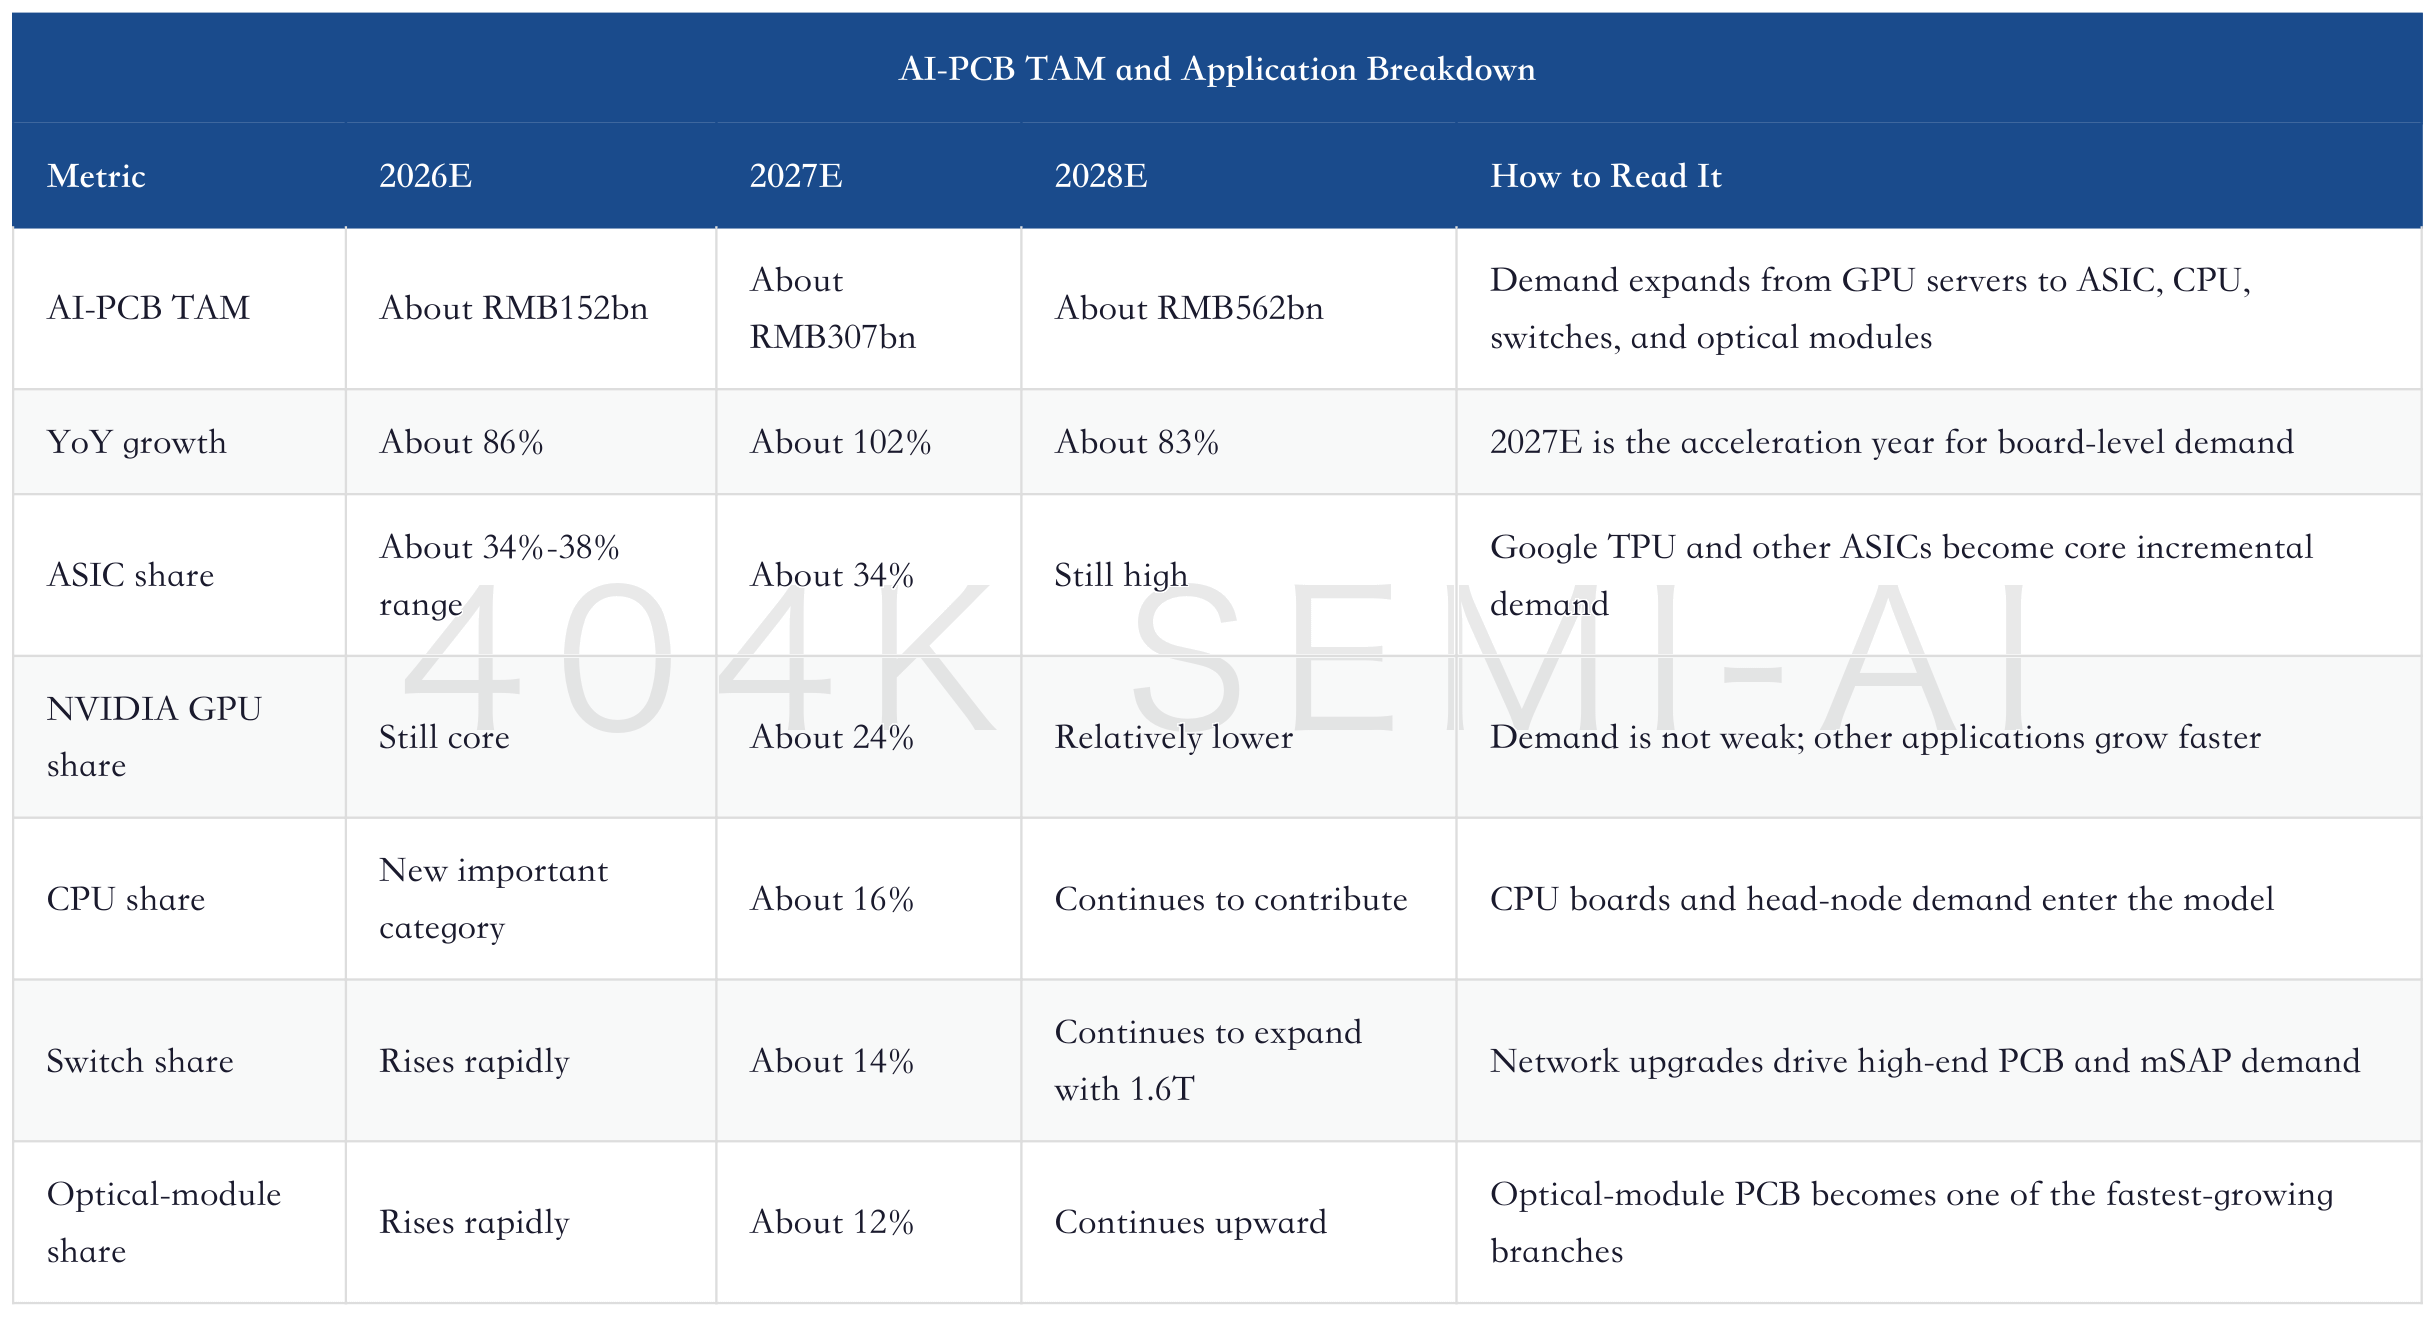
This table explains a fact that is often overlooked: AI PCB is not a single product. GPU boards, TPU UBBs, CPU boards, switch boards, optical-module boards, and HDI/mSAP boards correspond to different suppliers, material grades, and profit quality. Aggregating them into one TAM is useful, but investors must disaggregate them.
Google TPU is the core of the structural change. The PCB content value of Google TPU is high. The PCB content value per TPU v8/v9 is estimated at about US$1,000, and incremental demand expands rapidly in 2027E and 2028E. By 2028E, Google TPU PCB procurement could reach about US$16 billion, exceeding the NVIDIA GPU chain. This is not the old story of "ASIC replacing GPU." It is the reshuffling of PCB/CCL profit distribution after AI clusters expand from a single GPU platform to multi-architecture platforms.
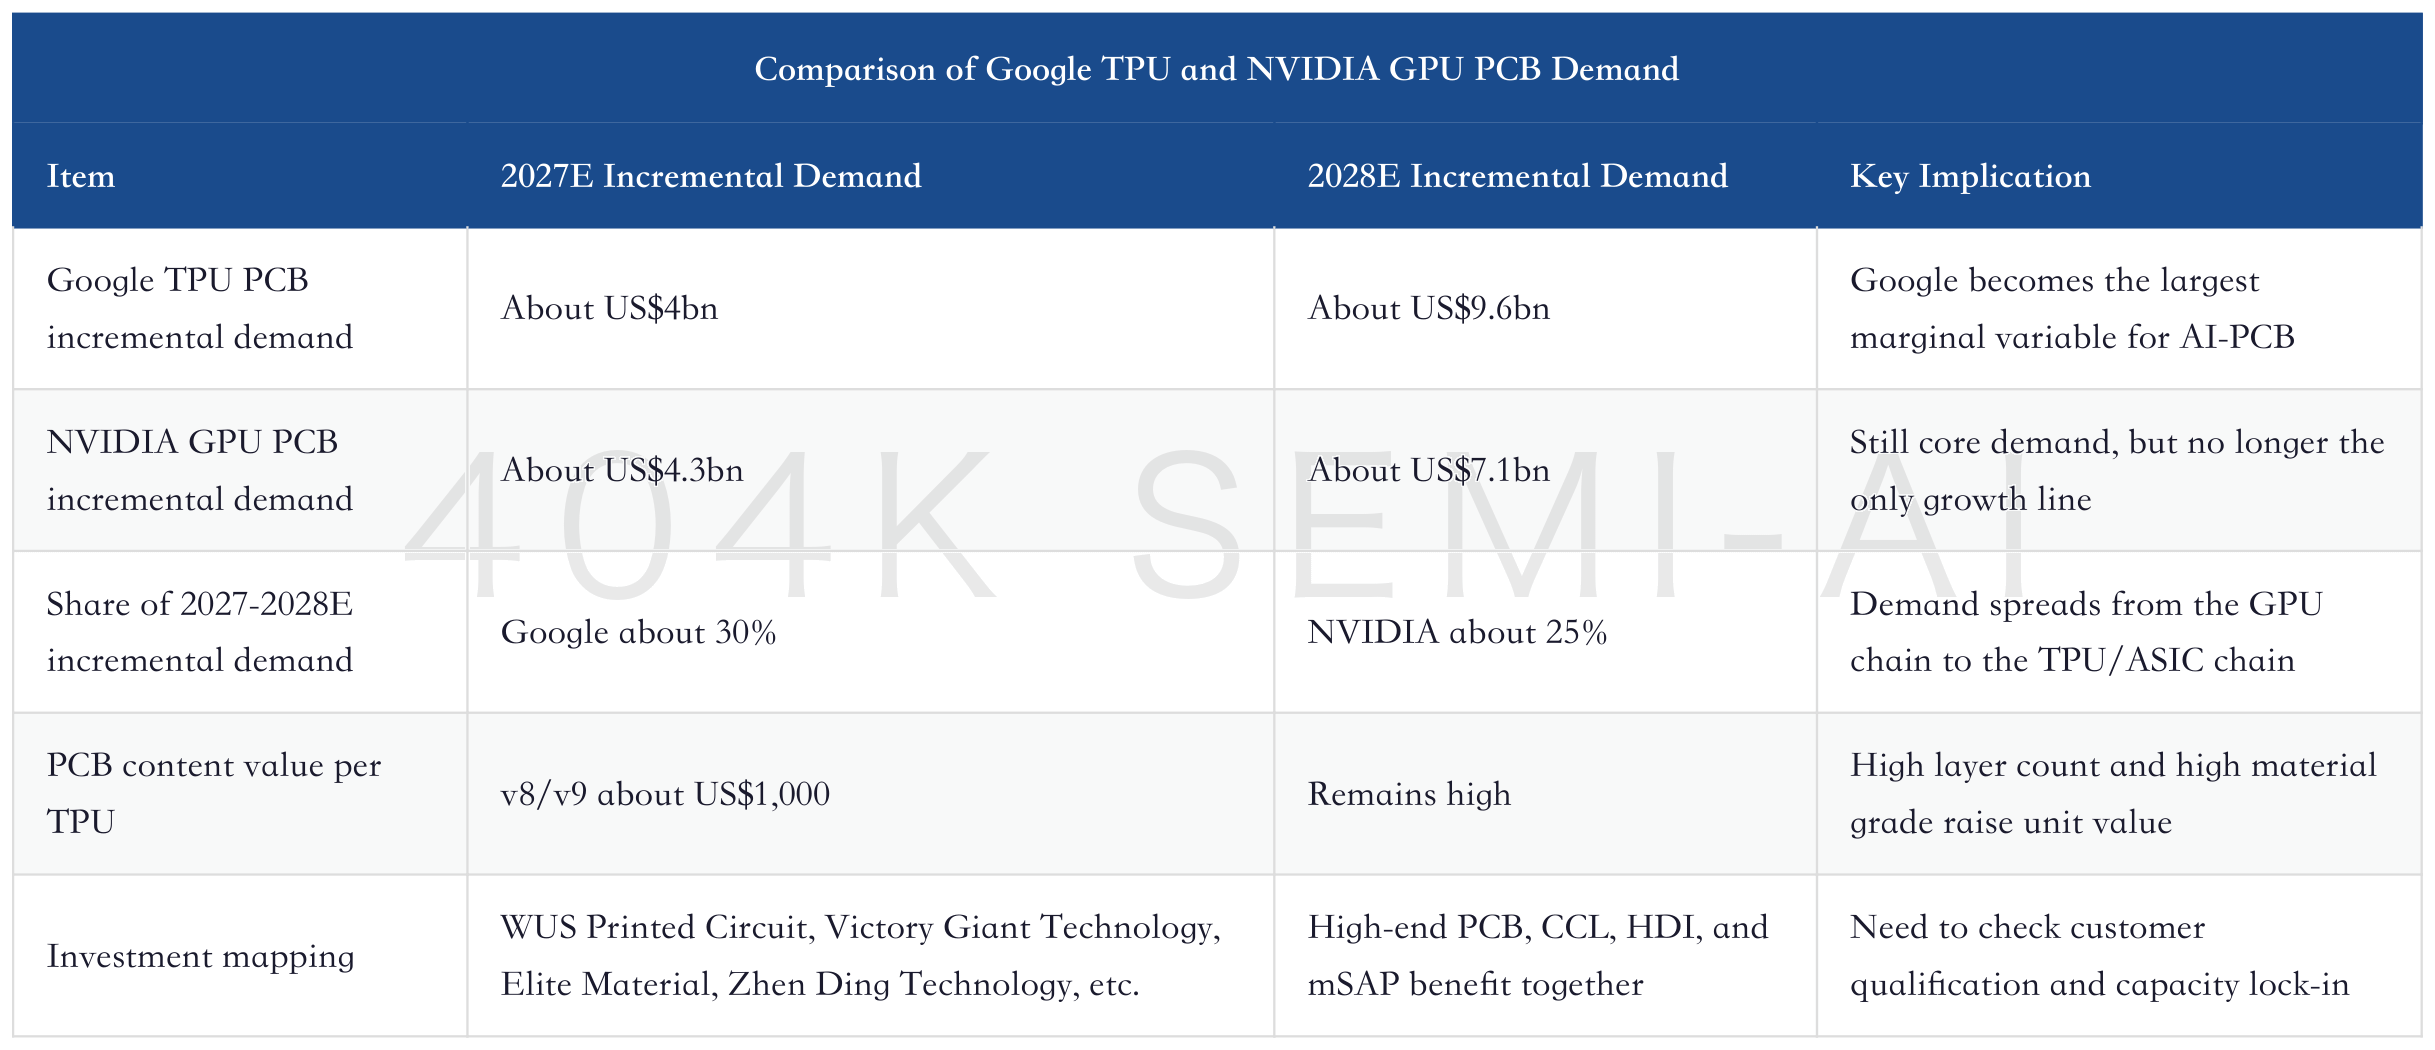
Network upgrades are another high-elasticity branch. After 1.6T optical modules and switches start, optical-module PCBs and switch PCBs may grow faster than GPU boards. The reason is simple: the larger the AI cluster, the heavier the east-west traffic. The number of switches and optical modules does not merely grow linearly with GPU count; it rises with network topology, port speed, and rack density. Board-level interconnect is moving from inside the server to the rack, the switching layer, and optical modules.
AI Network Interconnect Hardware Part I: The Value Migration Behind 1.6T/3.2T, and Who Benefits Most Across Switching, Copper Interconnect, Optical Interconnect, and the Physical Layer
This matters for A-share mapping. The core thesis for WUS Printed Circuit is not simply "AI server boards"; it is the joint driver of data-center switches, high-speed communications boards, and AI-server boards. The core thesis for Victory Giant Technology is not simple expansion, but high-layer-count multilayer boards and HDI capability entering overseas AI customers. Shennan Circuits, Guanghe Technology, Kinwong Electronic, DSBJ, and others also need to be analyzed by product category. Only by separating "GPU boards, switch boards, optical-module boards, ASIC boards, and CPU boards" can investors avoid treating all PCB companies as the same asset.
The demand-side conclusion is that AI PCB has enough room, but room does not equal profit. TAM expansion shows incremental growth in the track. Profit distribution depends on who wins customers, who locks materials, who ramps quickly, and who maintains stable yield. Before 2027E, customer competition for capacity may rerate PCB makers. After 2027E, the market will begin asking more practical questions: at what gross margin are these orders delivered, and can post-expansion cash flow materialize?
III. Specification Side: From GB300 to Rubin, TPU, and Trainium, How Board-Level Content Value Rises
The second change in AI PCB is that specification upgrades are more valuable than quantity growth. Traditional server PCBs focus on balancing layer count, materials, and cost. AI servers also need high-speed signal integrity, power integrity, thermal density, lamination yield, and system reliability. After platform upgrades, board content value does not rise evenly; it jumps on key boards.
The NVIDIA chain is a typical example. GB200/GB300 have already pushed Bianca boards, switch trays, mid-planes, and other structures toward higher layer counts and higher material grades. VR200 further raises requirements for Bianca boards and switch trays. A potential Rubin Ultra backplane could push layer count to a more extreme level. What really matters is not the number of layers itself, but that high layer count makes lamination, drilling, impedance control, low-loss materials, and yield harder at the same time.
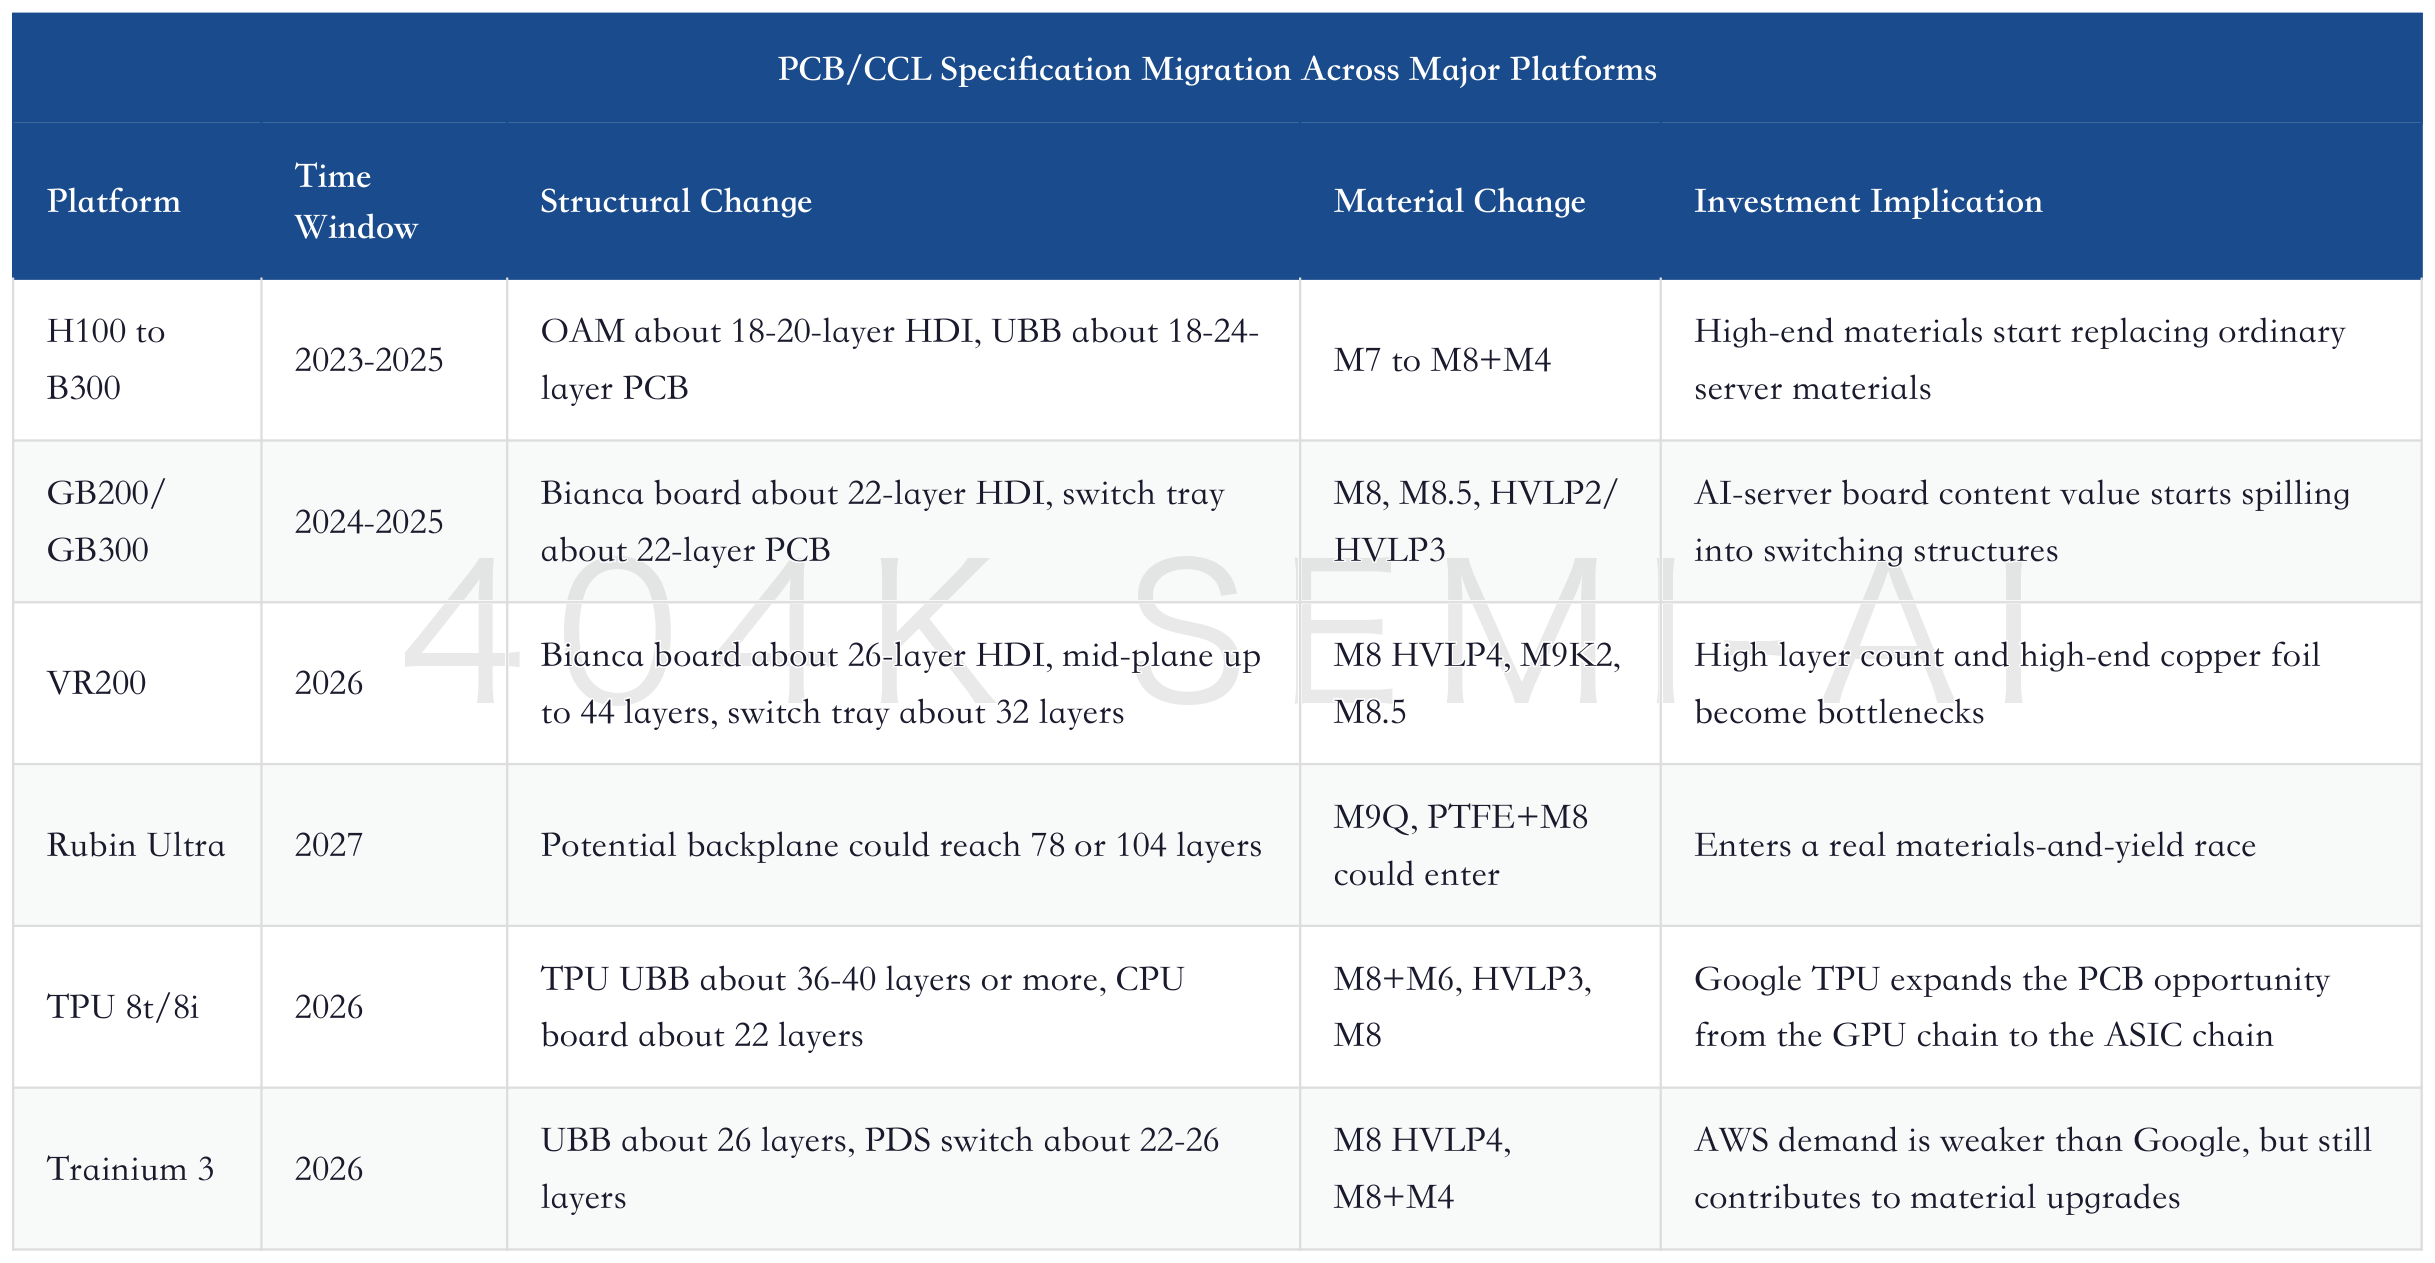
Google TPU's specification upgrade is more aggressive than many investors imagine. TPU v8 may move from about 22-24 layers in the prior generation to 36-44 layers, with materials moving from M7 to M8 and glass fabric also migrating toward Low Dk Gen 2. TPU v9 may also introduce more complex materials such as quartz fabric. TPU is not synonymous with "cheap ASIC," at least in board-level interconnect. It is becoming an important driver of high-end PCB and high-end CCL.
The AWS Trainium logic is more moderate, but cannot be ignored. Trainium 2 and Trainium 3 have limited changes in area and layer count, with more of the upgrade coming from copper-foil grade. Trainium 4 is more of a longer-dated item. Its significance for PCB/CCL is less sharp than Google TPU's, but as part of multi-ASIC customers, it proves that AI board-level demand is not a single-customer story. As long as cloud vendors continue investing across multiple paths, board-level interconnect suppliers have the opportunity to diversify risk across platforms.
CPU servers are the third line. Agentic AI and inference workloads make ordinary CPU-server demand stronger than the market originally expected. Materials are migrating from M6 to M7, but layer-count increases are less aggressive than in GPU/TPU. CPU servers act more like a base-business recovery for PCB and CCL. They may not deliver the highest gross margin, but they can absorb standard electronic glass fabric, ordinary CCL, and server-board capacity, indirectly squeezing high-end material supply.
Therefore, the specification side should be understood in three layers. The first is compute-board upgrades, centered on GPU and TPU. The second is network-board upgrades, centered on switches, optical modules, mSAP, and 1.6T. The third is CPU and general-server recovery, centered on standard materials and capacity utilization. Only when all three happen together does the situation become "high-end materials rise in price, and ordinary materials are not loose either."
The Second Reappraisal of the AI Server Materials Chain: From Passive Components to PCB/CCL, ABF Substrates, and Test Equipment
For companies, the value of specification upgrades lies in the customer-qualification barriers they create. Ordinary PCB capacity can be expanded, but high-end AI-server boards cannot be copied immediately. Ordinary CCL can see price increases, but high-end M8/M9 materials depend on customer relationships, formulations, yield, and stable supply. The higher the product moves, the less willing customers are to switch suppliers frequently, because one board issue can affect whole-system yield and delivery.
This also explains why the market assigns higher valuations to leaders. The valuation rerating of companies such as WUS Printed Circuit, Victory Giant Technology, Elite Material, Taiwan Union Technology, and Zhen Ding Technology is not because they have "more capacity." It is because they are more likely to obtain qualification on high-end platforms. What is truly valuable is staying on the BOM for the next-generation platform, not filling capacity on the previous-generation platform.
IV. Supply Side: PCB Expands Fastest, CCL Next, Electronic Glass Fabric Slowest; Pricing Power Is the Reverse
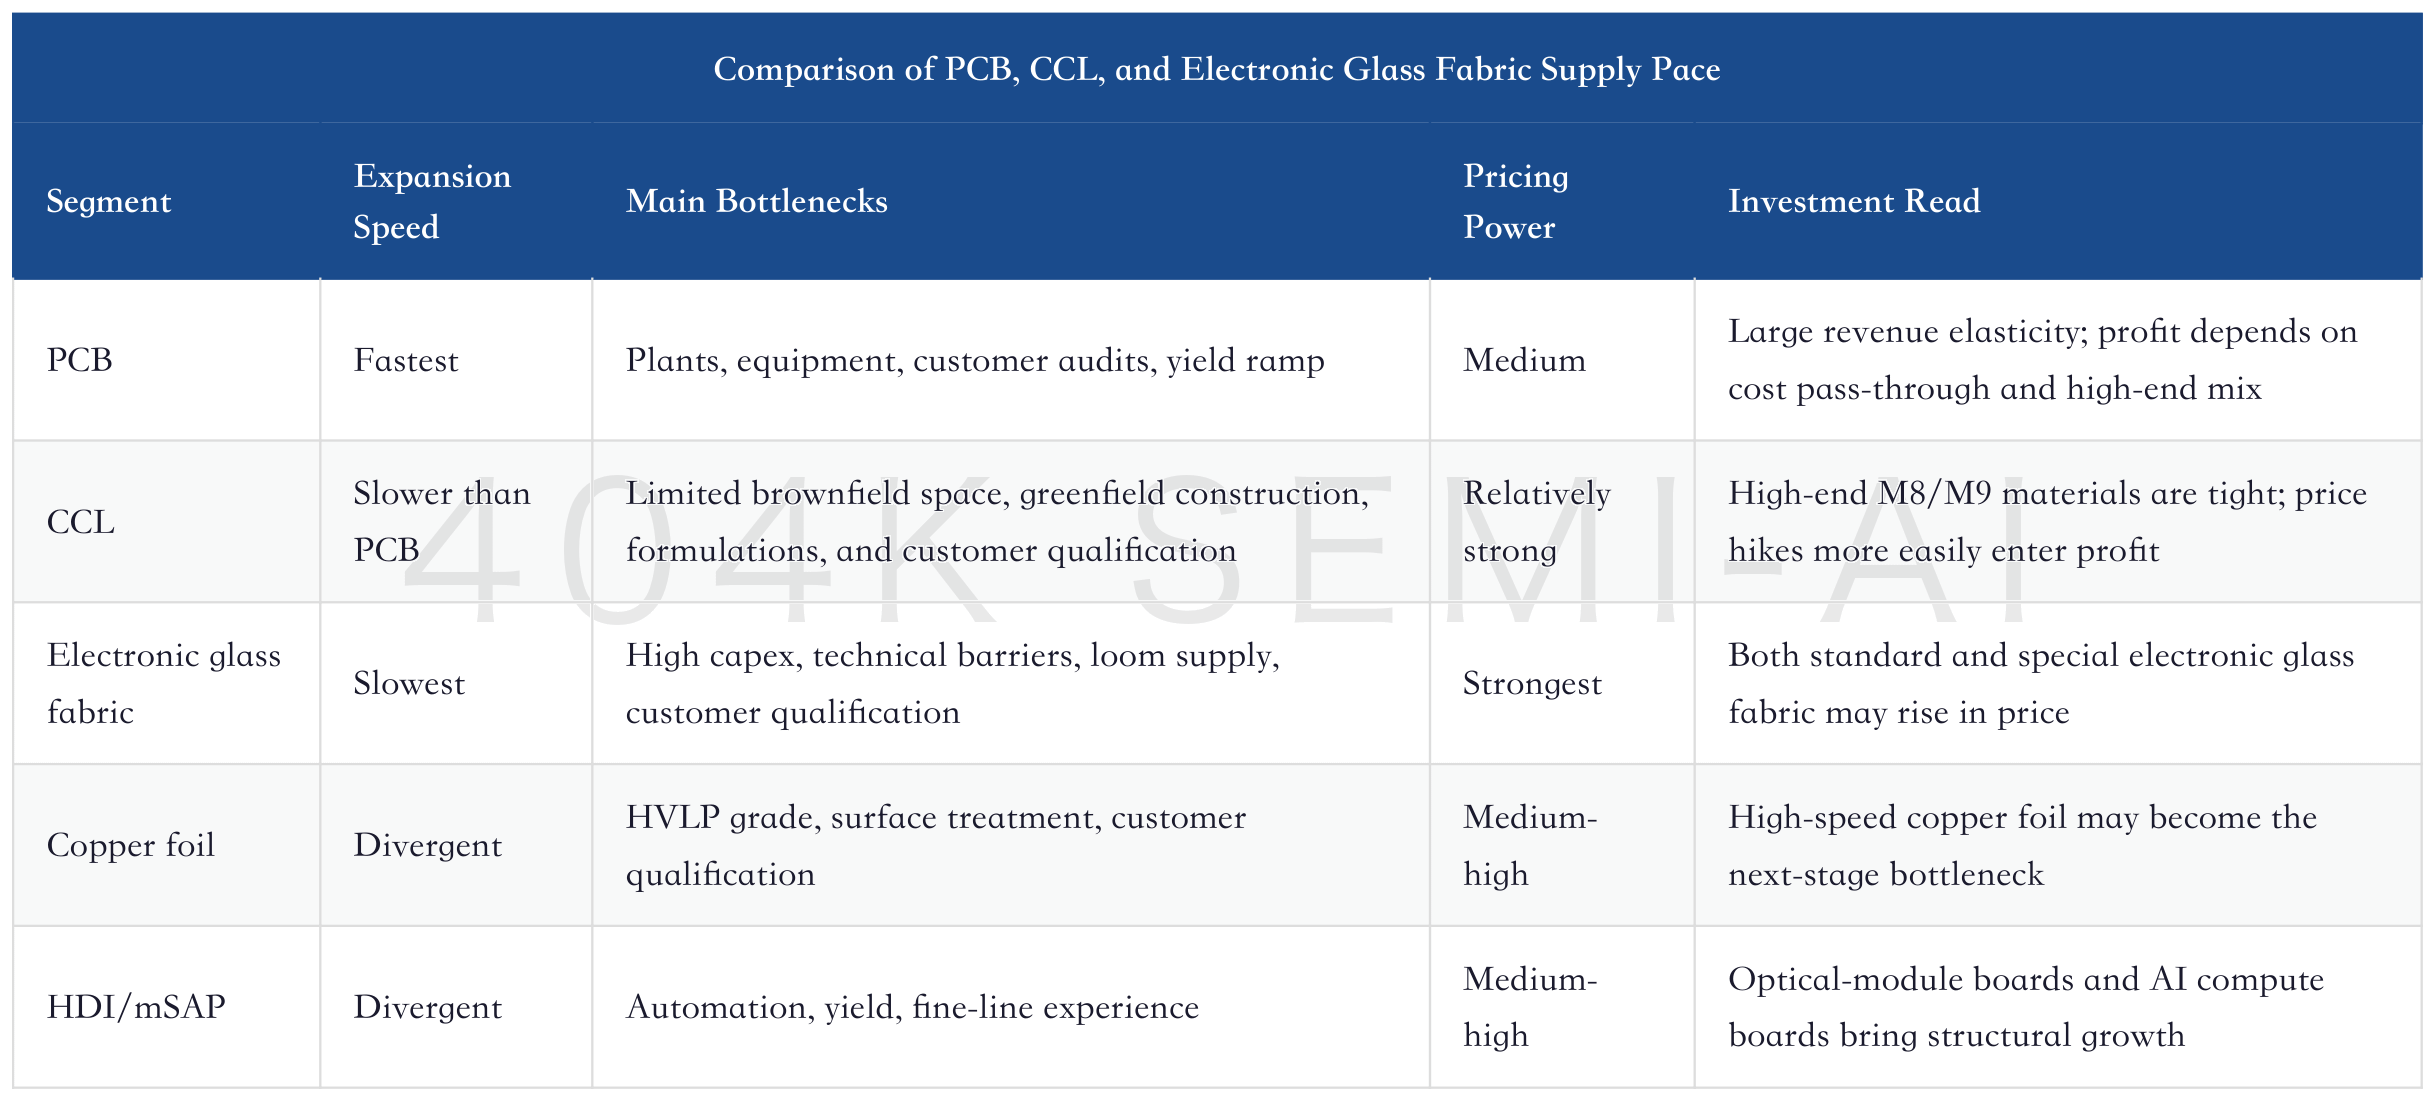
Strong demand does not mean every segment can raise prices. The most important supply contradiction in the PCB/CCL chain is that different segments expand at different speeds. PCB makers are the most aggressive and find it easiest to announce new plants. CCL expansion is slower, and existing sites have limited space. Electronic glass fabric and special glass fabric have longer expansion cycles and are constrained by looms, technology, and qualification. The slower the supply, the stronger the pricing power.
Citi China Materials' conclusion is direct: supply growth is fastest in PCB, followed by CCL, while electronic glass fabric is slowest. Pricing power is the reverse, with electronic glass fabric and CCL stronger, while PCB is more about cost pass-through. This judgment is important for investing. PCB makers have large revenue elasticity, but rising material costs can erode gross margin. If CCL and electronic glass fabric suppliers can raise prices directly, their earnings elasticity may be higher than that of PCB makers.
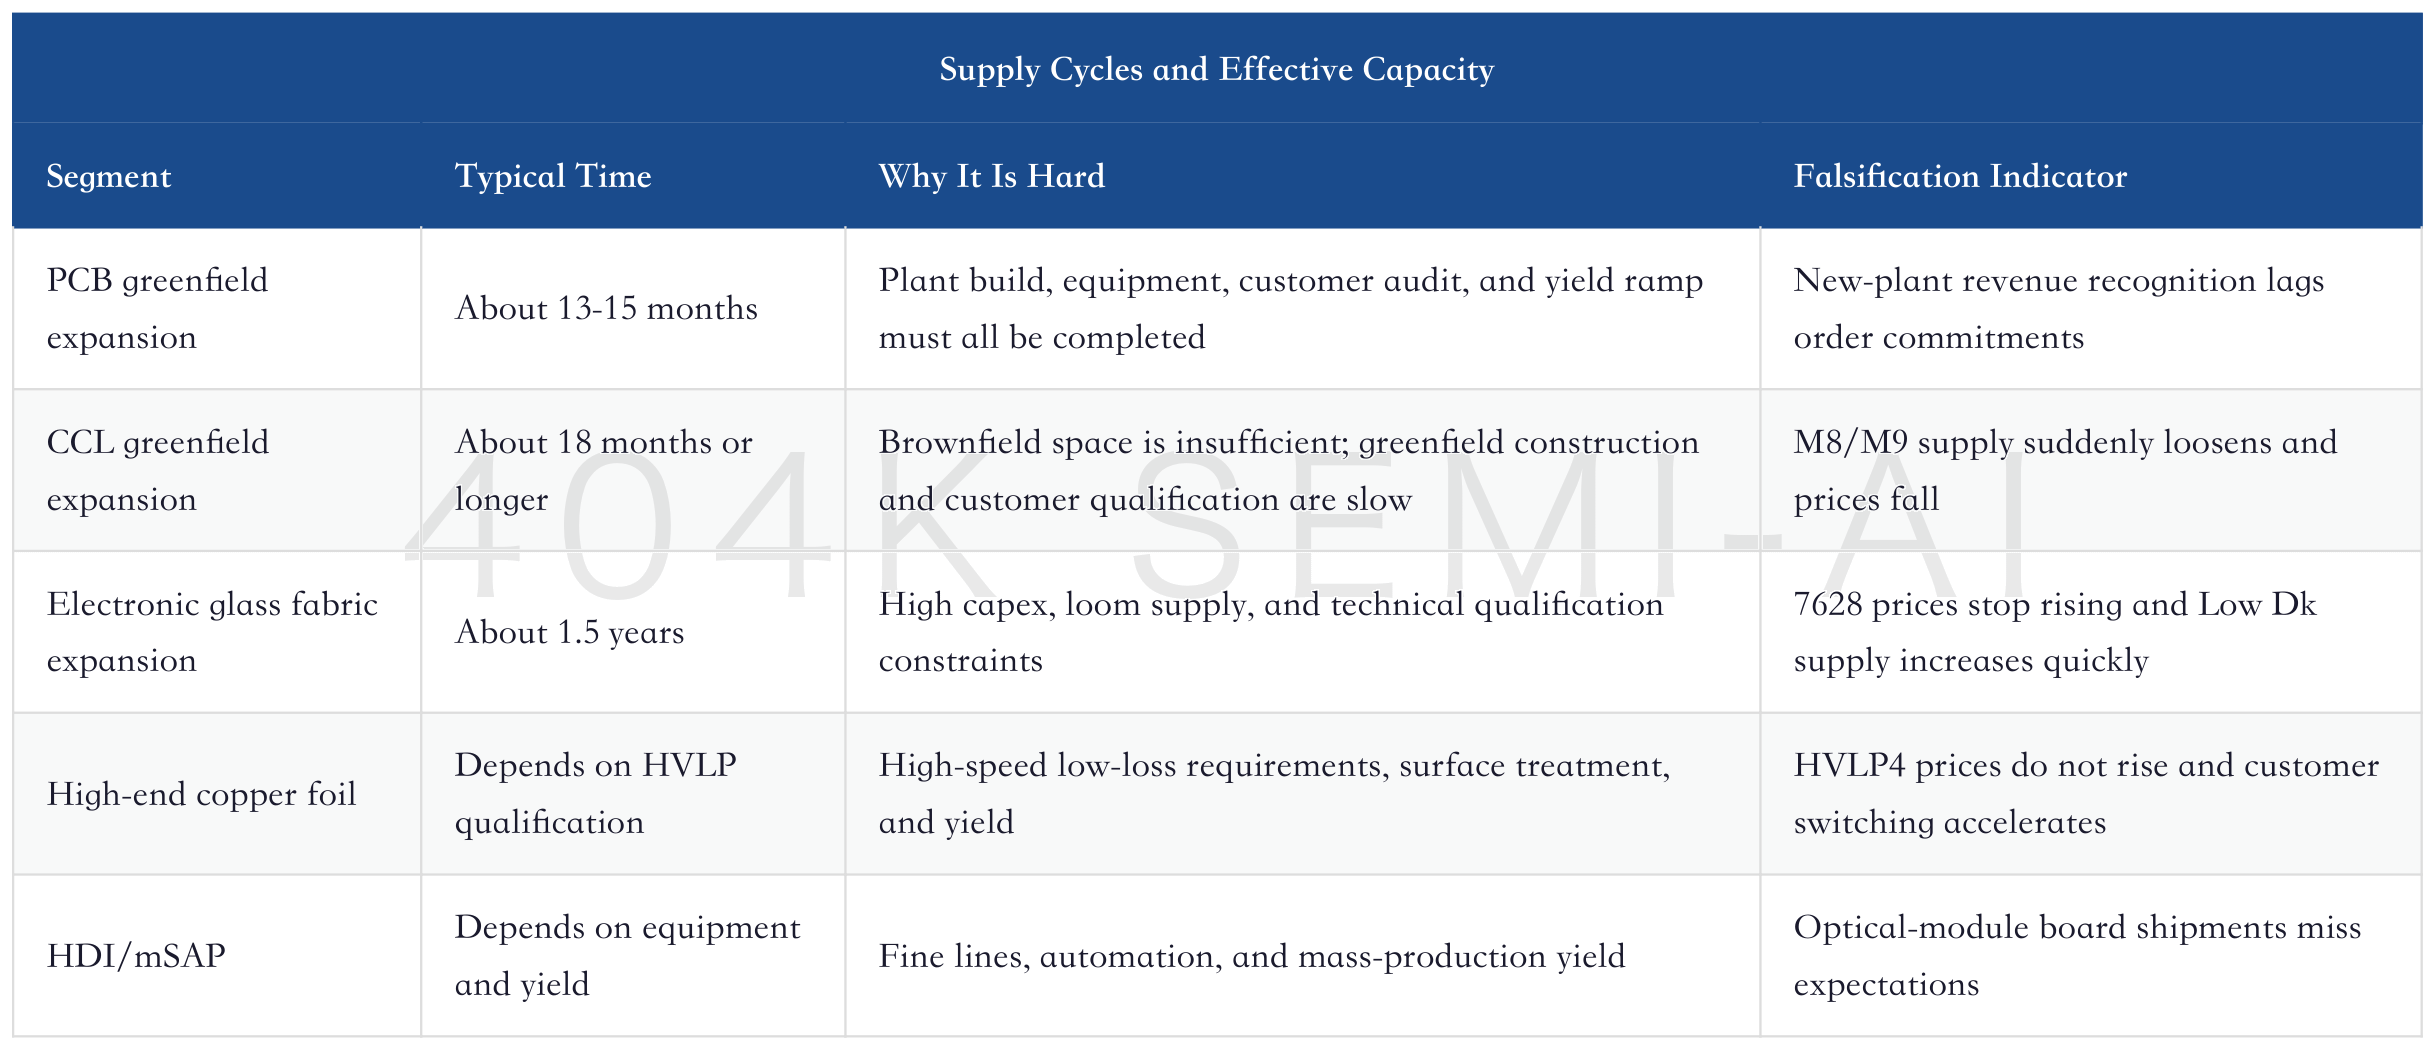
PCB greenfield expansion usually takes about 13-15 months, from land acquisition, construction, equipment installation, and customer audit to revenue recognition. CCL greenfield projects may take about 18 months in China and longer in Southeast Asia. New electronic glass fabric capacity also takes about 1.5 years and is constrained by high-end loom supply. A 100,000-ton electronic yarn/electronic glass fabric project may require about RMB3.7 billion of investment, far higher capital intensity than ordinary roving projects.
This means that from 2H26 to 2027, the industry is not without expansion; it is that expansion is hard to arrive simultaneously. PCB makers can announce new capacity first, and customers can lock volume in advance, but if CCL, electronic glass fabric, and copper foil cannot supply in parallel, nominal PCB capacity cannot be fully converted into effective capacity. The market is now giving high-end materials higher valuations for exactly this reason.
Electronic glass fabric is the most easily underestimated segment in this round of material reappraisal. High-end special electronic glass fabric occupies more loom efficiency, squeezing ordinary 7628 electronic glass fabric capacity. At the same time, recovery in general-server demand also pulls standard electronic glass fabric. As a result, ordinary electronic glass fabric may also become tight. This structure of "high-end product consuming capacity, low-end product also rising in price" can make material-company earnings more elastic than in a traditional cycle.
The logic of tight electronic glass fabric is not that AI servers directly consume all standard fabric. It is that high-end special fabric lowers effective loom efficiency. If a Toyota loom produces standard 7628 thick fabric, annual output is high. If it is used for AI special electronic glass fabric, efficiency can fall sharply. Capacity is not the number of machines; it is effective meters. This detail is crucial because it shows that expansion announcements cannot be equated directly with supply release.
CCL supply is also close to tight balance. Major suppliers such as Elite Material, Taiwan Union Technology, Panasonic, Doosan, and Shengyi Technology have not added large amounts of effective capacity this year. Elite Material and Taiwan Union Technology output increases also depend on tool installation and ramp pace. Downstream PCB makers believe they have locked supply through the forecasts they provided last year, but if AI projects ramp intensively after 3Q, actual allocation may still be tight.
Kingboard Laminates Deep-Dive Update: AI-Fabric Pushes CCL Cyclicals Toward a Materials Bottleneck, and the Earnings Reappraisal Behind the HK$100 Target Price
The supply-side investment conclusion is: do not treat expansion as bearish, and do not treat shortage as eternal. In the short term, expansion announcements show that customers are willing to lock volume and may improve 2028E visibility. In the medium term, concentrated expansion will test prices. In the long term, only companies that can maintain gross margin and customer share after expansion are true platform assets.
V. Pricing Power: PCB Makers Earn Orders, CCL and Electronic Glass Fabric Earn Scarcity; Who Turns Price Hikes Into Profit?
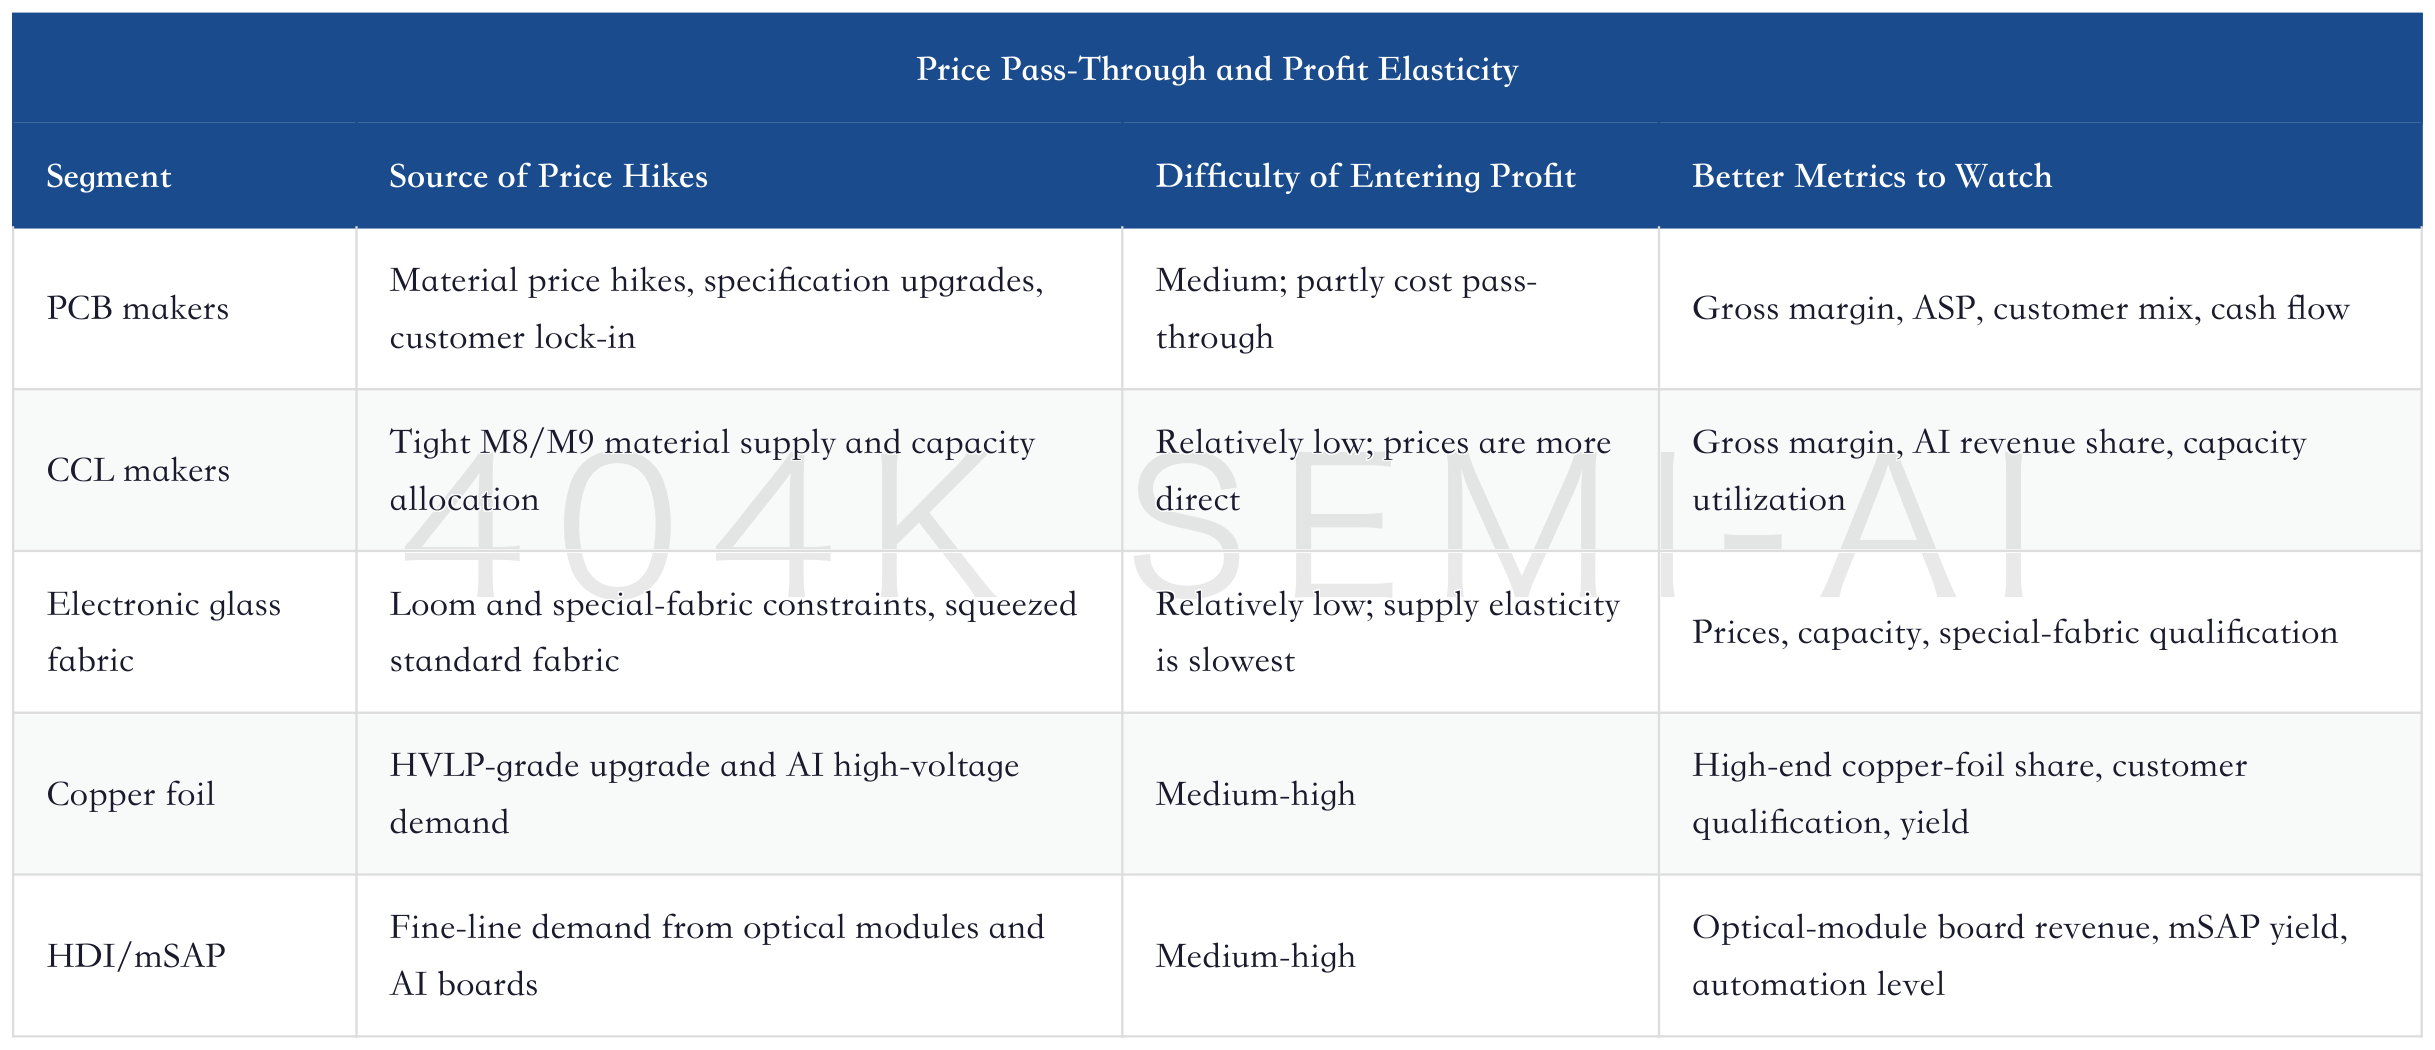
This cycle requires investors to separate profit quality from "price hikes." PCB makers can indeed raise prices, but often by passing CCL, copper foil, and electronic glass fabric price increases on to customers. Gross margin may not expand sharply. Price increases at CCL and electronic glass fabric suppliers are more direct. If supply is truly tight, their gross-margin improvement will be more visible than revenue growth.
Price signals have already appeared. M7 and below products have generally seen clear increases, low-end M4 products have risen even more, while AI-related M8 materials have risen more moderately because CCL makers still need to maintain long-term customer relationships. If supply tightens further in 2H, customers may be willing to pay premiums to secure supply, and high-end CCL pricing power will become more direct.
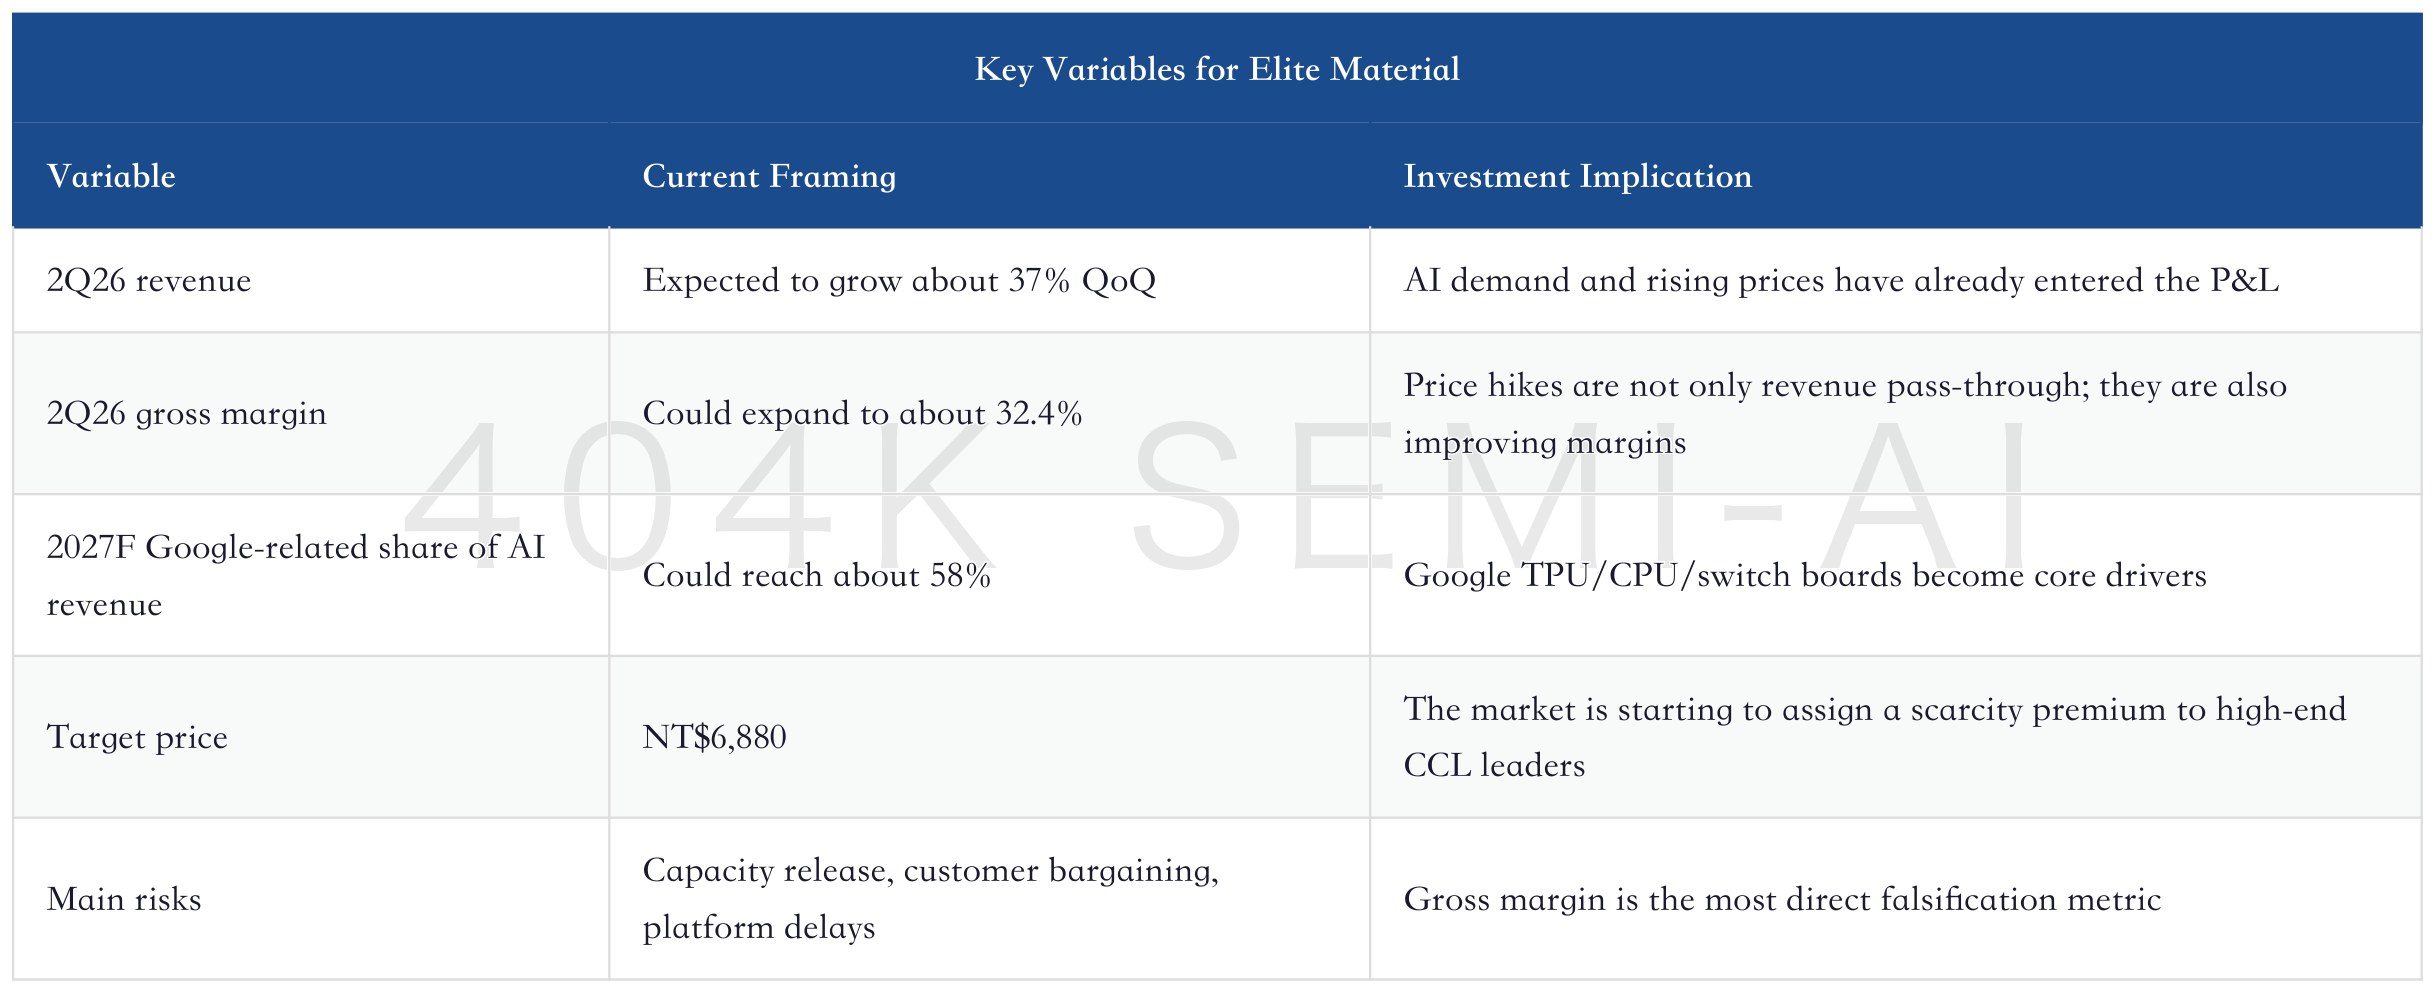
Elite Material is a representative of high-end CCL pricing power. Nomura expects Elite Material's 2Q26 revenue to grow about 37% QoQ, with gross margin potentially expanding to 32.4%, while raising its target price to NT$6,880. More importantly, the CCL content opportunity from Google TPU/CPU boards and switches could account for 58% of Elite Material's AI revenue by 2027F, up from 38% in 2026F. This shows that Elite Material is not merely following NVIDIA; it is gaining greater weight in the Google TPU chain.
Elite Material's earnings elasticity comes from three points. First, it has large capacity and can obtain customer resources first when the industry is tight. Second, its high-end product mix is improving as the M8/M9 material share rises. Third, a multi-customer structure across Google, AWS, and NVIDIA means it is not fully dependent on a single platform. The risks are also clear: if new capacity arrives faster than expected, or if customer bargaining caps price increases, gross-margin expansion will slow.
Shengyi Technology and Kingboard Laminates represent the China material mapping. Shengyi Technology is the A-share CCL leader. The key factors are the share of high-end copper-clad laminates, AI customer qualification, sustainability of price hikes, and gross margin. Kingboard Laminates is the Hong Kong-listed representative of CCL and electronic glass fabric integration and is more able to convert upstream scarcity into profit during a material upcycle. Together they verify one question: is CCL merely a normal cyclical price hike, or is it an asset reappraisal driven by AI-server material bottlenecks?
Electronic glass fabric companies such as China Jushi provide more upstream validation. If 7628 electronic glass fabric continues to rise in price, special electronic glass fabric qualification progresses, and demand for Low CTE, Low Dk Gen 2, and quartz fabric gradually expands, it means board-level interconnect material bottlenecks are still spreading upstream. If electronic glass fabric prices stop rising, or if new entrants pass qualification quickly, the material-chain elasticity will cool.
Pricing power ultimately has to land in financial metrics. Revenue growth is the first step. Gross-margin expansion is the second. Operating cash flow and accounts-receivable control are the third. If a PCB company sees revenue surge but gross margin does not rise, receivables rise significantly, and inventory piles up, it means it merely took orders. If a material company raises prices but volume is constrained, it may only be a short-term supply squeeze. Investors should not buy just the words "price hike"; they should buy whether price hikes can penetrate the income statement and cash-flow statement.
VI. Company Ranking: WUS Printed Circuit, Victory Giant Technology, Shengyi Technology, Shennan Circuits, Guanghe Technology, and the Taiwan Material Chain Are Not the Same Opportunity
The PCB/CCL industry chain is long. Without ranking, it easily becomes a list of companies. A better approach is to stratify by "bottleneck position" and "profit quality." For PCB makers, focus on customers and effective capacity. For material suppliers, focus on pricing power and qualification. For HDI/mSAP, focus on fine lines and optical-module boards. For equipment makers, focus on whether expansion orders are truly pulled forward. For electronic glass fabric and copper foil, focus on upstream supply constraints.
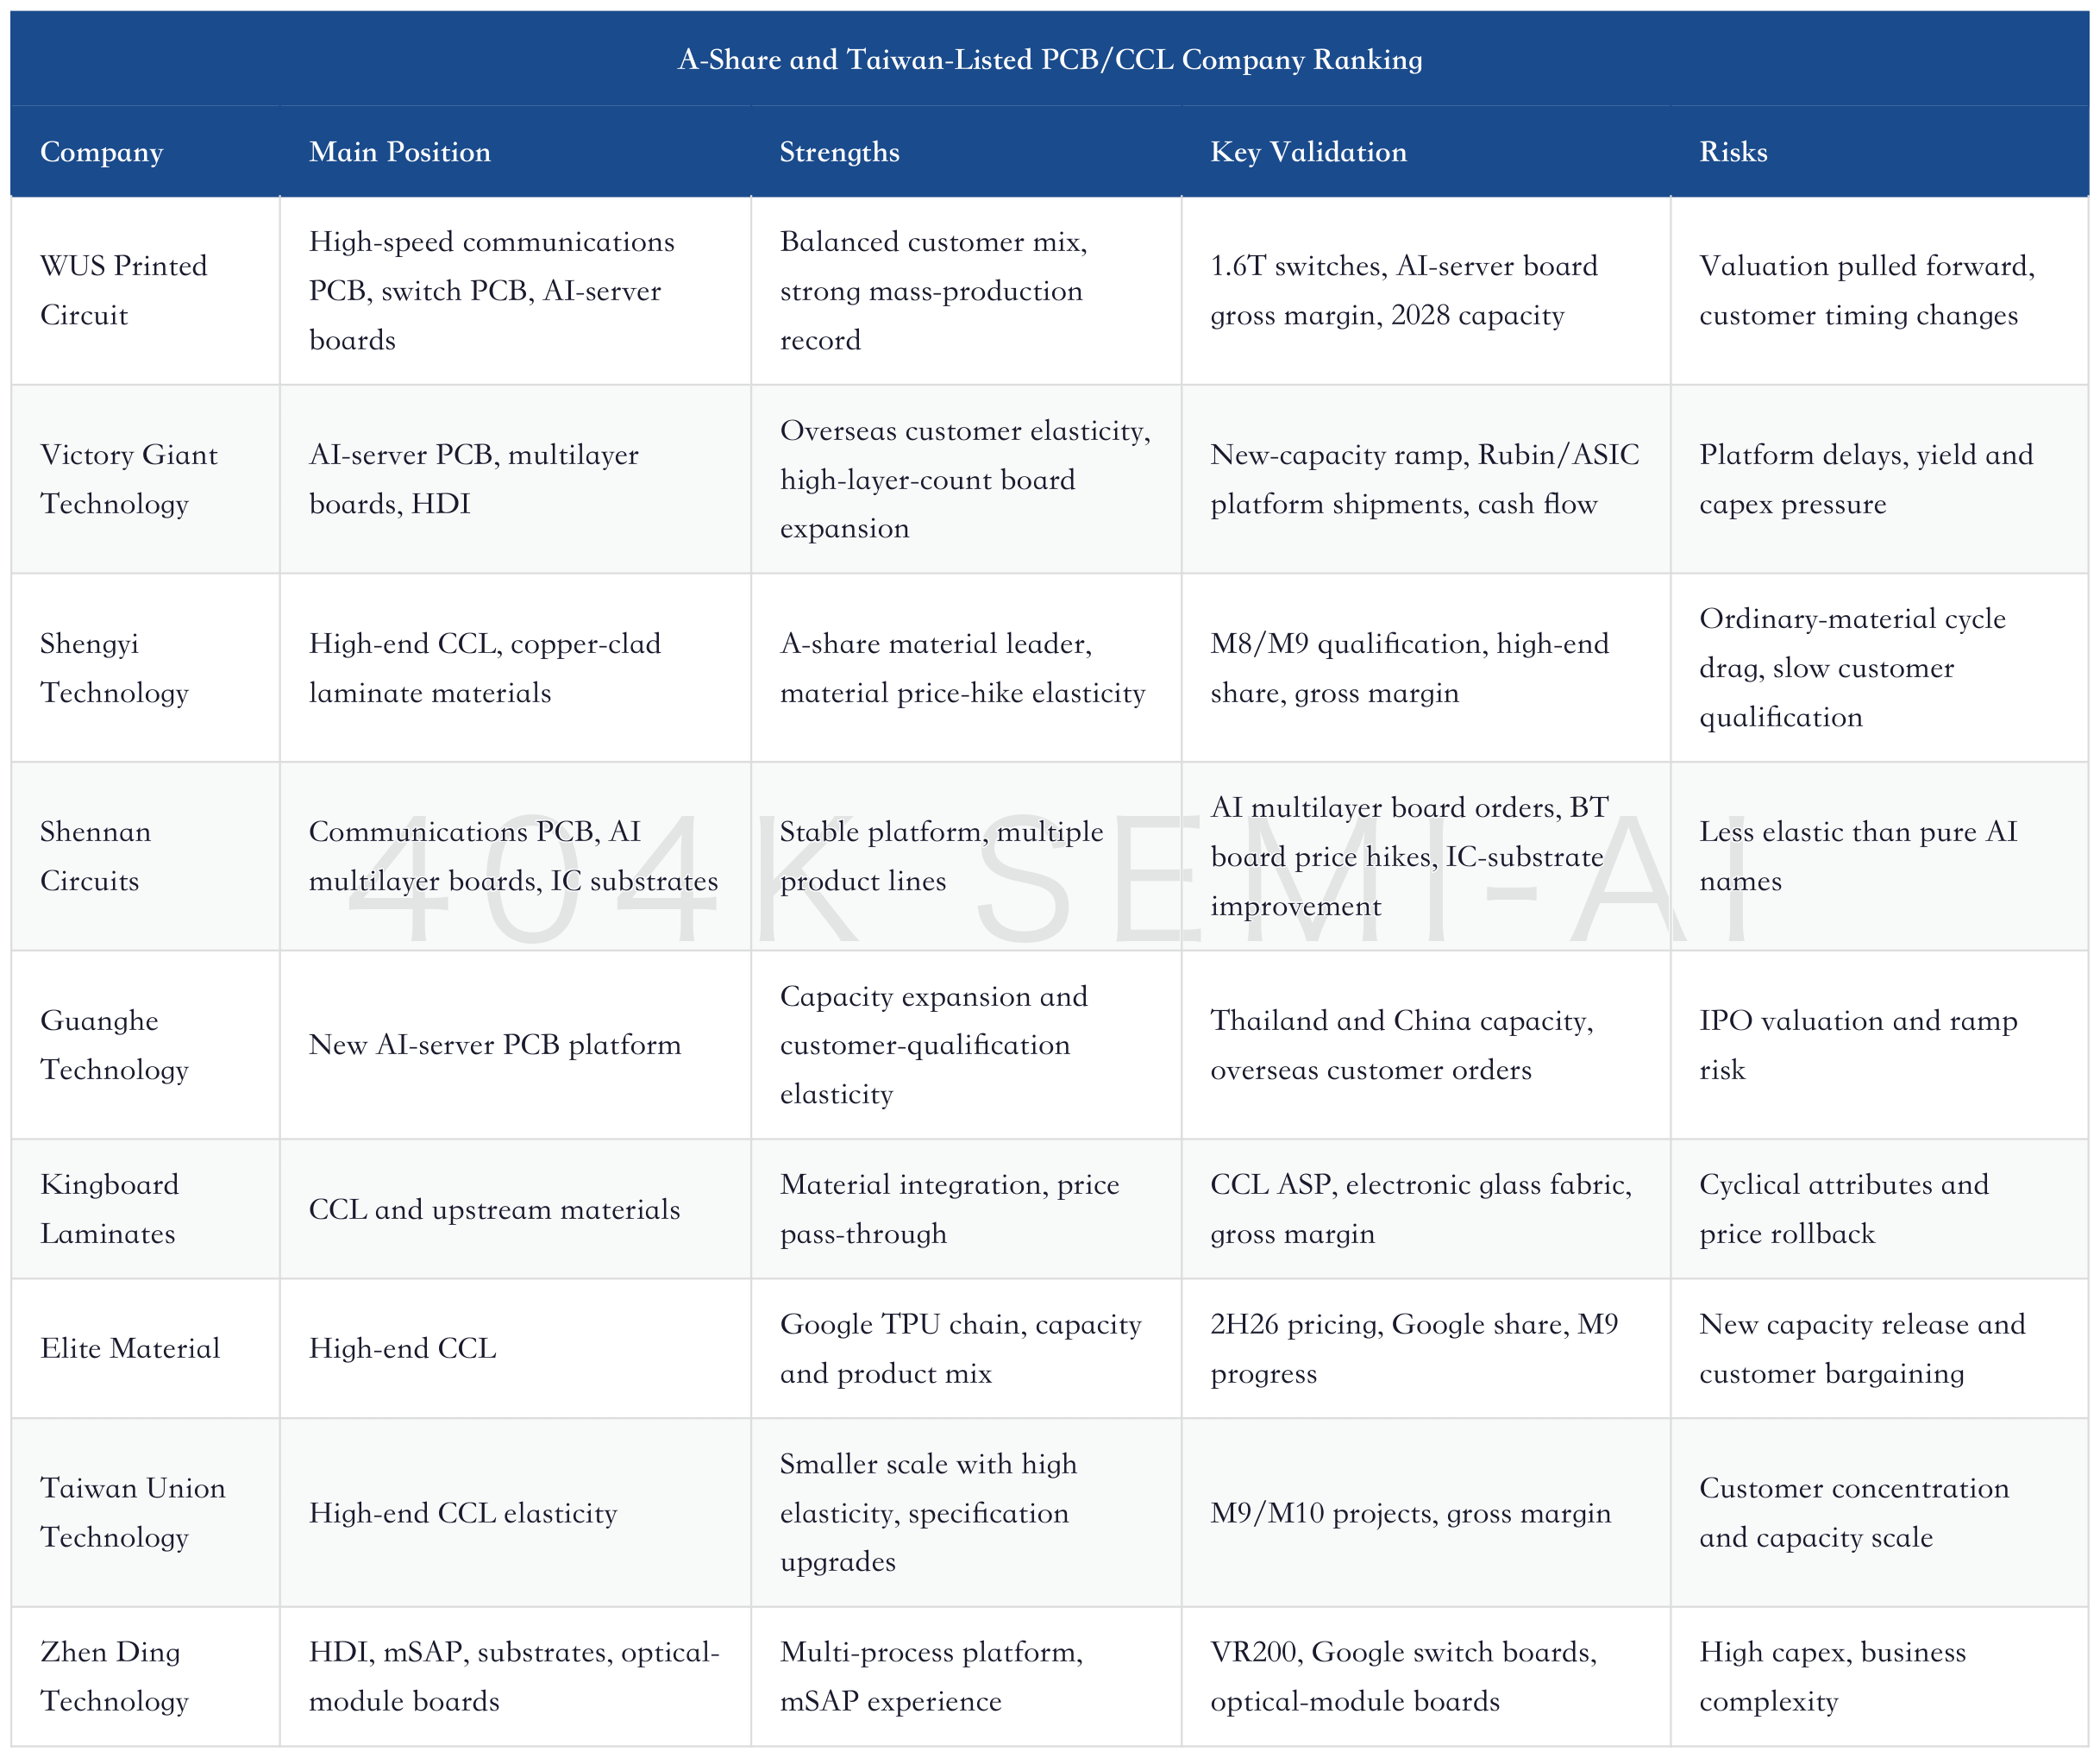
WUS Printed Circuit represents high-end communications and data-center switch PCBs. Foreign reports often refer to WUS Printed Circuit by the listed-company name; this report uses its formal securities abbreviation in English as WUS Printed Circuit. Its advantages are a solid base in data-center switches, communications boards, and AI-server-related products, a relatively balanced customer mix, and a delivery record that more easily earns a valuation premium. Citi raised its target price for WUS Printed Circuit to RMB189, driven by 1.6T switches, Google and switch demand, and 2028E capacity visibility.
Victory Giant Technology represents effective-capacity elasticity in AI-server PCBs. Its strengths are high-layer-count multilayer boards, HDI capability, and overseas customer expansion elasticity. Its valuation is more sensitive to AI-server platform timing. Citi raised its target price for Victory Giant Technology to RMB456, while also cutting part of its 2026E net-profit forecast because Rubin timing could delay some revenue. This point is important: Victory Giant Technology does not lack growth, but its growth is more dependent on customer platform timing and new-capacity ramp.
Shengyi Technology is the core A-share CCL mapping. Compared with PCB makers, Shengyi Technology is closer to the material bottleneck. The key variables are M8/M9, high-frequency high-speed copper-clad laminates, customer qualification, and gross margin. Its advantage is that material tightness can directly enter prices. The risk is that high-end share and qualification at leading overseas customers still need continuous verification. If AI-related high-end CCL price increases continue, Shengyi Technology will be reappraised from an ordinary material cyclical into a high-end material platform.
Shennan Circuits is characterized by both multilayer PCB and IC-substrate capabilities. It has a base in communications PCBs and server PCBs, as well as packaging-substrate extensions. Investors need to distinguish its profit structure across AI-server boards, BT boards, IC substrates, and traditional communications. Shennan Circuits is better viewed as a "steady platform" and should not simply be assigned the highest-elasticity PCB-maker valuation.
Guanghe Technology is a newly listed high-end PCB elasticity stock. Foreign reports often refer to Guanghe Technology by the listed-company name; this report uses its formal securities abbreviation in English as Guanghe Technology. Its opportunity lies in higher AI-server PCB dollar content and capacity expansion in Thailand/China. The risks are new-capacity ramp, customer concentration, and valuation already reflecting expectations. Guanghe Technology is more of a "new platform validation case" than a fully proven leader case.
DSBJ and Avary Holding have more integrated mappings. DSBJ has optical-module, consumer-electronics, and AI-PCB angles and cannot be valued only on PCB. Avary Holding is a consumer-electronics PCB leader migrating toward SLP, ABF, server boards, and other high-end interconnect. The core questions are whether the depreciation cycle, customer mix, and AI-business share can change its asset attributes.
Victory Giant Technology Deep Dive: AI PCB Enters the Era of Effective Capacity, and How Victory Giant Moves From PCB Maker to Server Delivery Asset
In ranking terms, WUS Printed Circuit and Victory Giant Technology represent two paths for A-share PCB makers. WUS Printed Circuit is more like an "execution asset for high-end switches and AI-server boards." Victory Giant Technology is more like an "effective-capacity elasticity asset for AI-server PCB." The former depends more on stable delivery and customer mix. The latter depends more on capacity-expansion execution and platform timing. Both benefit from AI PCB TAM expansion, but their entry points and risks differ.
Shengyi Technology, Kingboard Laminates, Elite Material, and Taiwan Union Technology represent four paths on the material side. Shengyi Technology is an A-share high-end CCL platform. Kingboard Laminates is Hong Kong-listed material integration. Elite Material is the Taiwan-listed high-end CCL leader. Taiwan Union Technology is a higher-elasticity high-end CCL name. The common question for the material side is whether price increases can continue, whether customers will accept premiums, and whether new capacity will quickly dilute scarcity.
Zhen Ding Technology offers another platform opportunity. It is neither a pure CCL maker nor a single PCB maker, but combines ABF substrates, AI PCB/HDI, mSAP, and optical-module boards. Nomura raised its target price for Zhen Ding Technology to NT$720, citing IC-substrate sales growth, a doubling of server/optical-communications sales, 2026E capex guidance raised above NT$80 billion, and ramps in VR200 Bianca HDI boards and Google switch boards. Its value lies in multiple board-level bottlenecks materializing together. Its risk is also higher capex and execution complexity.
VII. Value-Chain Pass-Through: Five Profit Pools Behind One AI Board
The most underestimated aspect of AI PCB/CCL is that profit does not stop with PCB makers. Customers procure deliverable AI servers, switches, and optical modules, but this chain allocates value to five segments: PCB makers earn premiums from area, layer count, and yield; CCL makers earn premiums from low-loss materials; electronic glass fabric and copper foil earn premiums from upstream scarcity; HDI/mSAP makers earn premiums from fine lines; and equipment makers receive front-loaded expansion orders. Every segment benefits from AI, but financial elasticity is completely different.
The first profit pool is PCB makers. Its revenue elasticity is the most visible because customer orders ultimately land at PCB makers, and expansion announcements are easiest for the market to see. WUS Printed Circuit, Victory Giant Technology, Shennan Circuits, Guanghe Technology, Kinwong Electronic, DSBJ, and Avary Holding can all capture this demand from different angles. The issue is that PCB makers bear material price hikes, yield ramp, and capex pressure, so revenue growth does not necessarily mean margin expansion. To earn a high valuation, a PCB maker must prove that it has obtained high-end qualified capacity, not low-margin contract-manufacturing capacity.
The second profit pool is CCL makers. CCL is not an ordinary material; it is the foundation for high-speed signal transmission. As AI servers move from M7 to M8, M9, and even higher-end combinations such as PTFE and M9Q, material formulations, loss control, stability, and customer qualification all become barriers. The value of companies such as Elite Material, Taiwan Union Technology, Shengyi Technology, and Kingboard Laminates comes from whether they can translate material-grade upgrades into ASP and gross margin. PCB makers can expand faster, but if high-end CCL is insufficient, the capacity they expand is only partially effective.
The third profit pool is electronic glass fabric and copper foil. Electronic glass fabric determines the CCL skeleton, while copper foil determines high-speed signal and power integrity. Neither is short-cycle capacity. The special feature of electronic glass fabric is that high-end Low Dk, Low CTE, quartz fabric, and other products reduce effective loom efficiency and squeeze standard 7628 electronic glass fabric. The special feature of copper foil is that HVLP3, HVLP4, and higher-grade products must pass customer qualification and yield validation. If electronic glass fabric and copper foil remain tight from 2H26 to 2027, material-side profit will be harder than PCB-maker profit.
The fourth profit pool is HDI and mSAP. AI servers appear to be a large-board business, but 1.6T optical modules, switch boards, Bianca HDI boards, and high-density connections are bringing fine-line capability into the data center. The core reason Zhen Ding Technology is back in focus is not that it suddenly became a single AI-board maker. It is that it has put HDI, mSAP, substrates, optical-module boards, and automation experience into one delivery capability. As future AI servers move further toward high-density systems, HDI/mSAP is more likely to migrate from a consumer-electronics capability into a data-center capability.
The fifth profit pool is equipment and process capability. PCB equipment, drilling, lamination, exposure, electroplating, inspection, automation, and yield control will all be pulled forward by expansion. China PCB-equipment materials repeatedly emphasize that capacity squeeze and high-end penetration will support fundamentals. The reason is here: customers lock capacity first, manufacturers then lock equipment, and equipment and process companies receive expansion orders early. But the equipment-side risk is also clearer. Once expansion slows, order visibility changes faster than material prices.
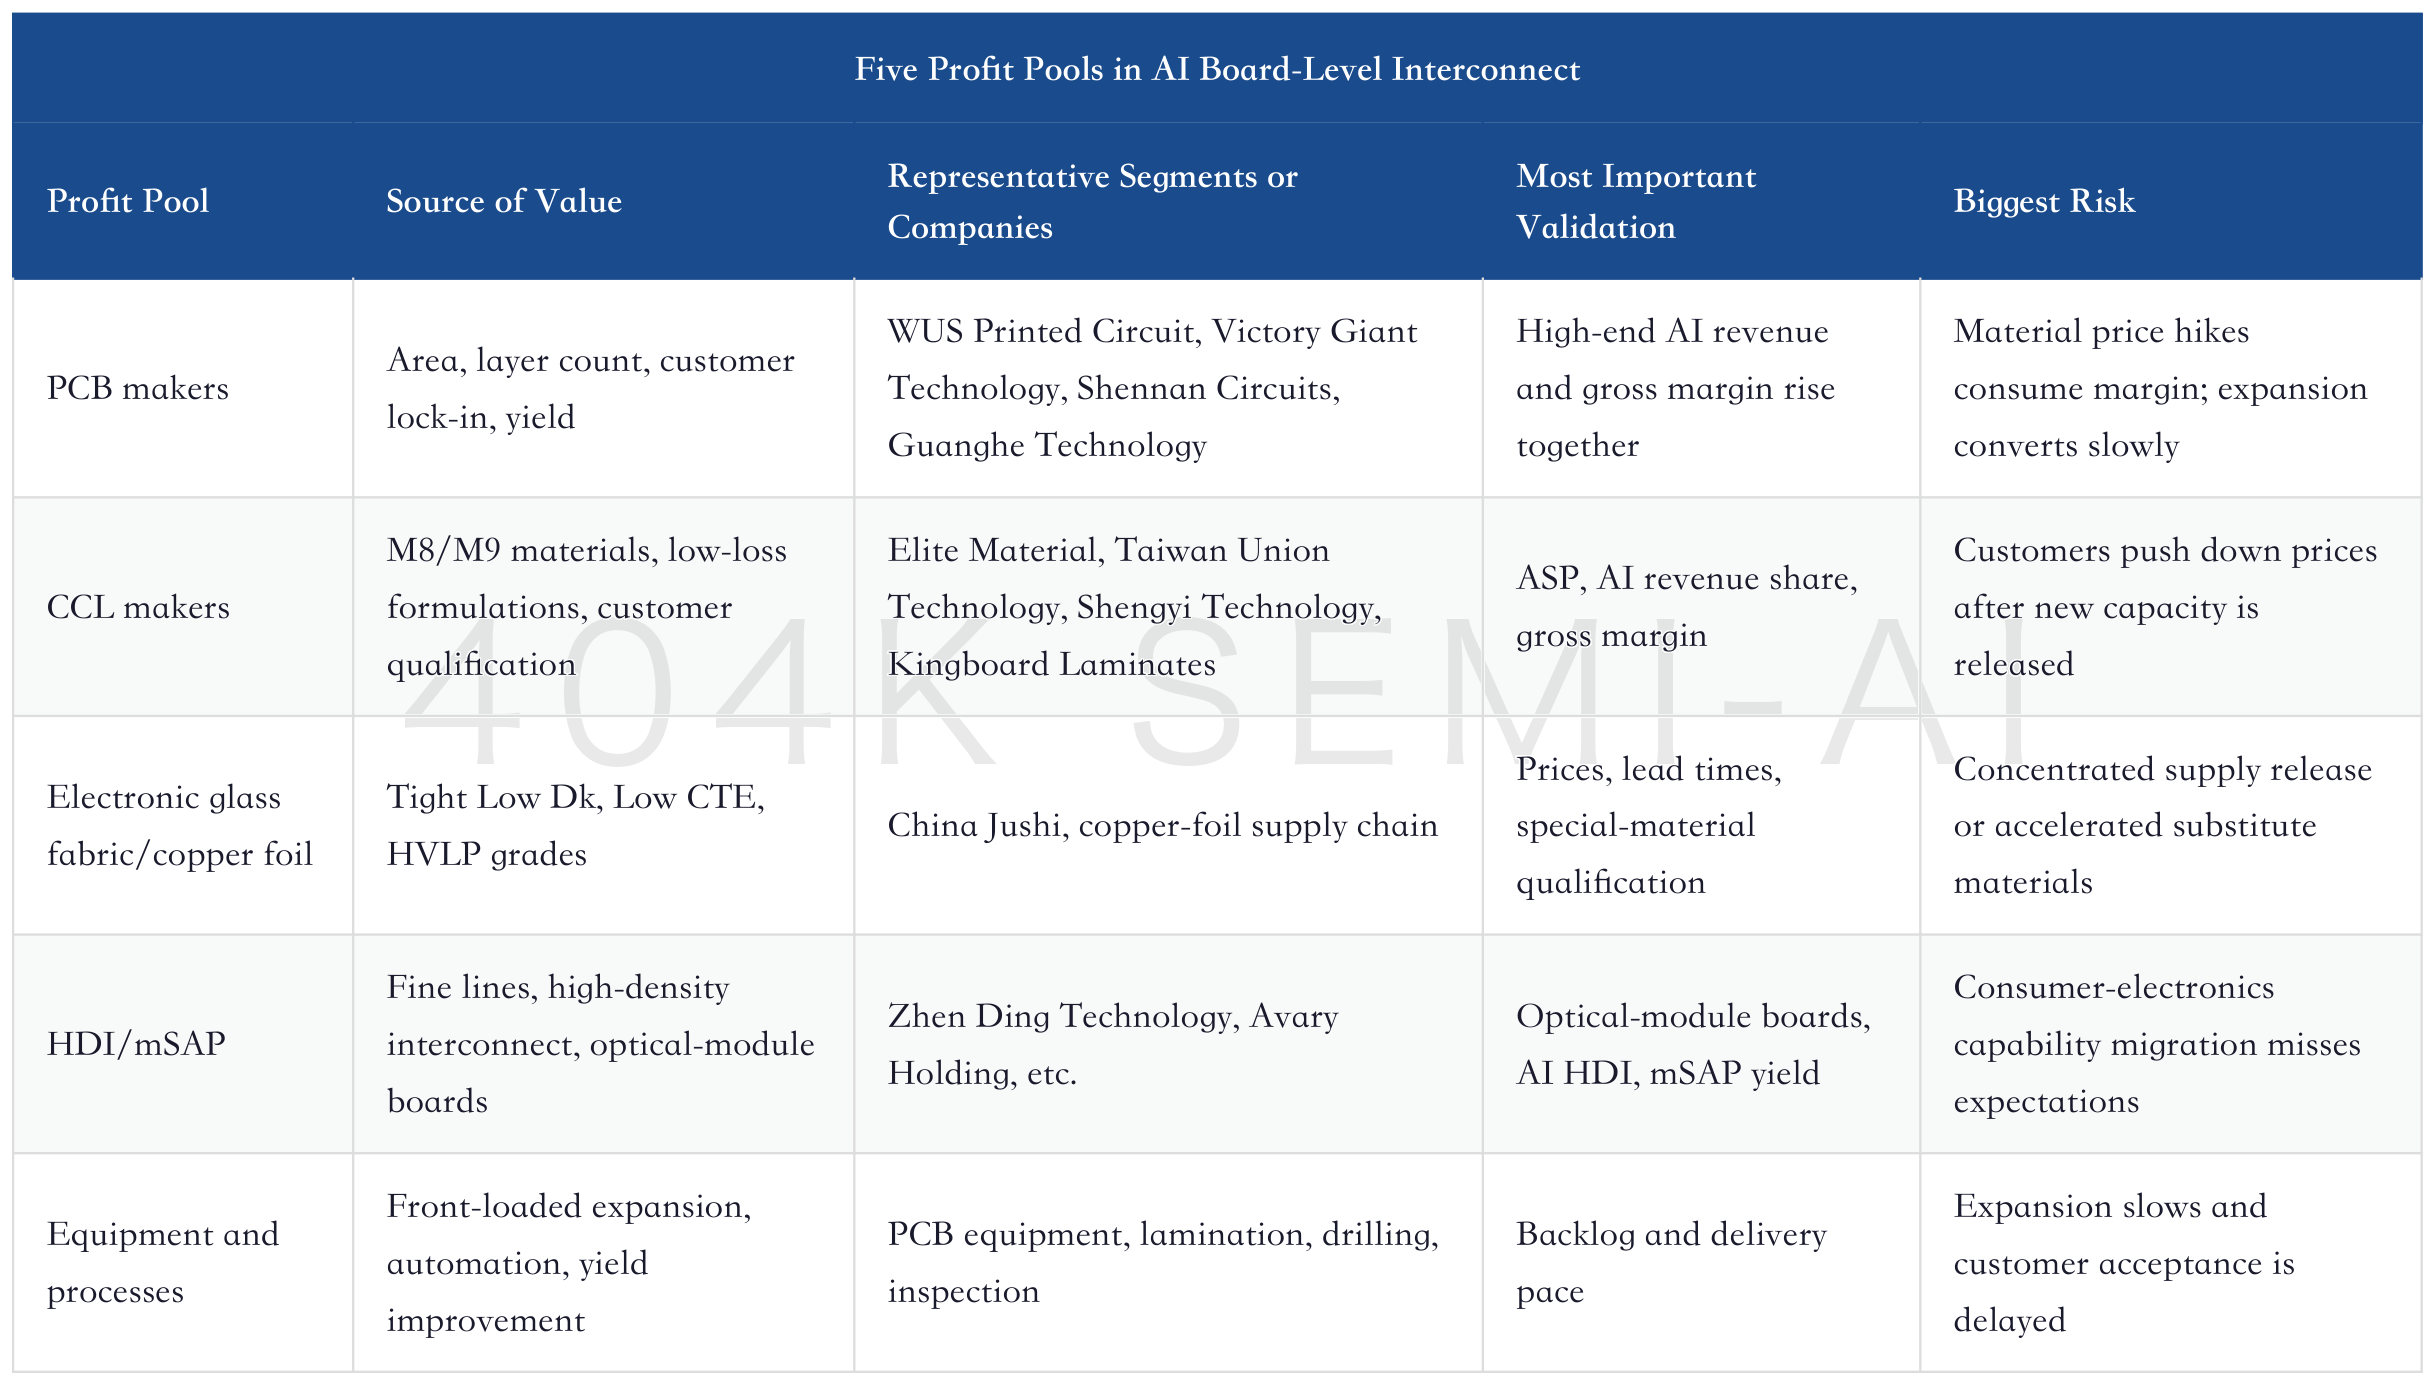
This table also explains why valuation methods cannot be the same even though all of this is called AI PCB. PCB makers should be validated through revenue, orders, gross margin, and cash flow. CCL makers should be validated through ASP, high-end mix, and capacity utilization. Electronic glass fabric and copper foil should be validated through prices, lead times, and special-material qualification. HDI/mSAP should be validated through optical-module boards, fine-line yield, and customer migration. If all these segments are compared using one PE multiple, investors can easily buy the hottest stock while missing the area with the hardest profit.
Value-chain pass-through has another implication: PCB makers and material suppliers are not simply upstream and downstream players bargaining against each other. They jointly participate in customer delivery. To ensure platforms come online, leading cloud vendors will care simultaneously about PCB, CCL, electronic glass fabric, copper foil, and key equipment. They may directly participate in supply-chain capacity lock-in, and even book 2027-2028 capacity in advance. This reduces some cyclical volatility, but also makes suppliers more dependent on a small number of large customers. The stronger the lock-in, the steadier near-term earnings; the more concentrated the customer base, the higher the medium-term bargaining risk.
Therefore, AI PCB/CCL investing should not only ask "which company raises prices the most." Better questions are: are price increases coming from specification upgrades or short-term squeezes, how much capex is covered by customer lock-in, for how many quarters can gross-margin improvement continue, can high-end share be maintained after expansion, and does cash flow improve along with profit? Companies that can answer all these questions will move from cyclical manufacturing into AI infrastructure assets.
VIII. From Orders to Cash Flow: Five Tables to Verify in AI PCB Phase Two
In the first phase of AI PCB, investors looked at orders. In the second phase, they must look at cash flow. The reason is simple: high-end PCB and CCL expansion require capital. Customer lock-in is not the same as profit in hand, and price increases are not the same as improved cash flow. If investors only look at orders, a company can become a manufacturing asset with "revenue growth but cash-flow pressure." Only when orders, gross margin, receivables, inventory, and capex efficiency improve together does it become a real platform asset.
The first table is the customer lock-in table. Investors need to see whether customers are moving from forecasts to LTAs, whether they are booking 2027-2028 capacity in advance, and whether they are willing to pay premiums for material supply. The clearer the customer volume lock, the lower the expansion risk. If expansion is only announced by the company without customer commitment, valuation should be discounted.
The second table is the product-mix table. Investors need to see the revenue share of M8/M9, HVLP4, HDI, mSAP, high-layer-count boards, optical-module boards, and AI-server boards. Ordinary server boards and high-end AI boards can both be called "AI-related," but their gross margins are completely different. When product mix is unclear, investors should not assign high-end bottleneck valuations.
The third table is the gross-margin table. Price hikes ultimately need to be judged by gross margin. If material price increases are only cost pass-through, PCB-maker revenue will grow, but gross margin may not expand. If the share of high-end materials and high-end boards rises, gross margin should improve. Elite Material, Zhen Ding Technology, Shengyi Technology, Victory Giant Technology, and WUS Printed Circuit all need to be tested by gross margin.
The fourth table is the capex and effective-capacity table. AI PCB expansion is not only about the capex amount. Investors also need to track construction cycle, equipment arrival, customer audit, yield ramp, and revenue recognition. Zhen Ding Technology raised its 2026E capex guidance to more than NT$80 billion, showing the industry's willingness to invest. But the market ultimately needs to see whether this capex becomes high-margin revenue.
The fifth table is the receivables and inventory table. AI customers are powerful, orders are large, and delivery is complex, all of which can easily create receivables and inventory pressure. If revenue and profit both grow but operating cash flow does not improve in step, order quality needs to be questioned. A truly high-quality AI hardware asset should deliver customer lock-in, price pass-through, and cash flow together.
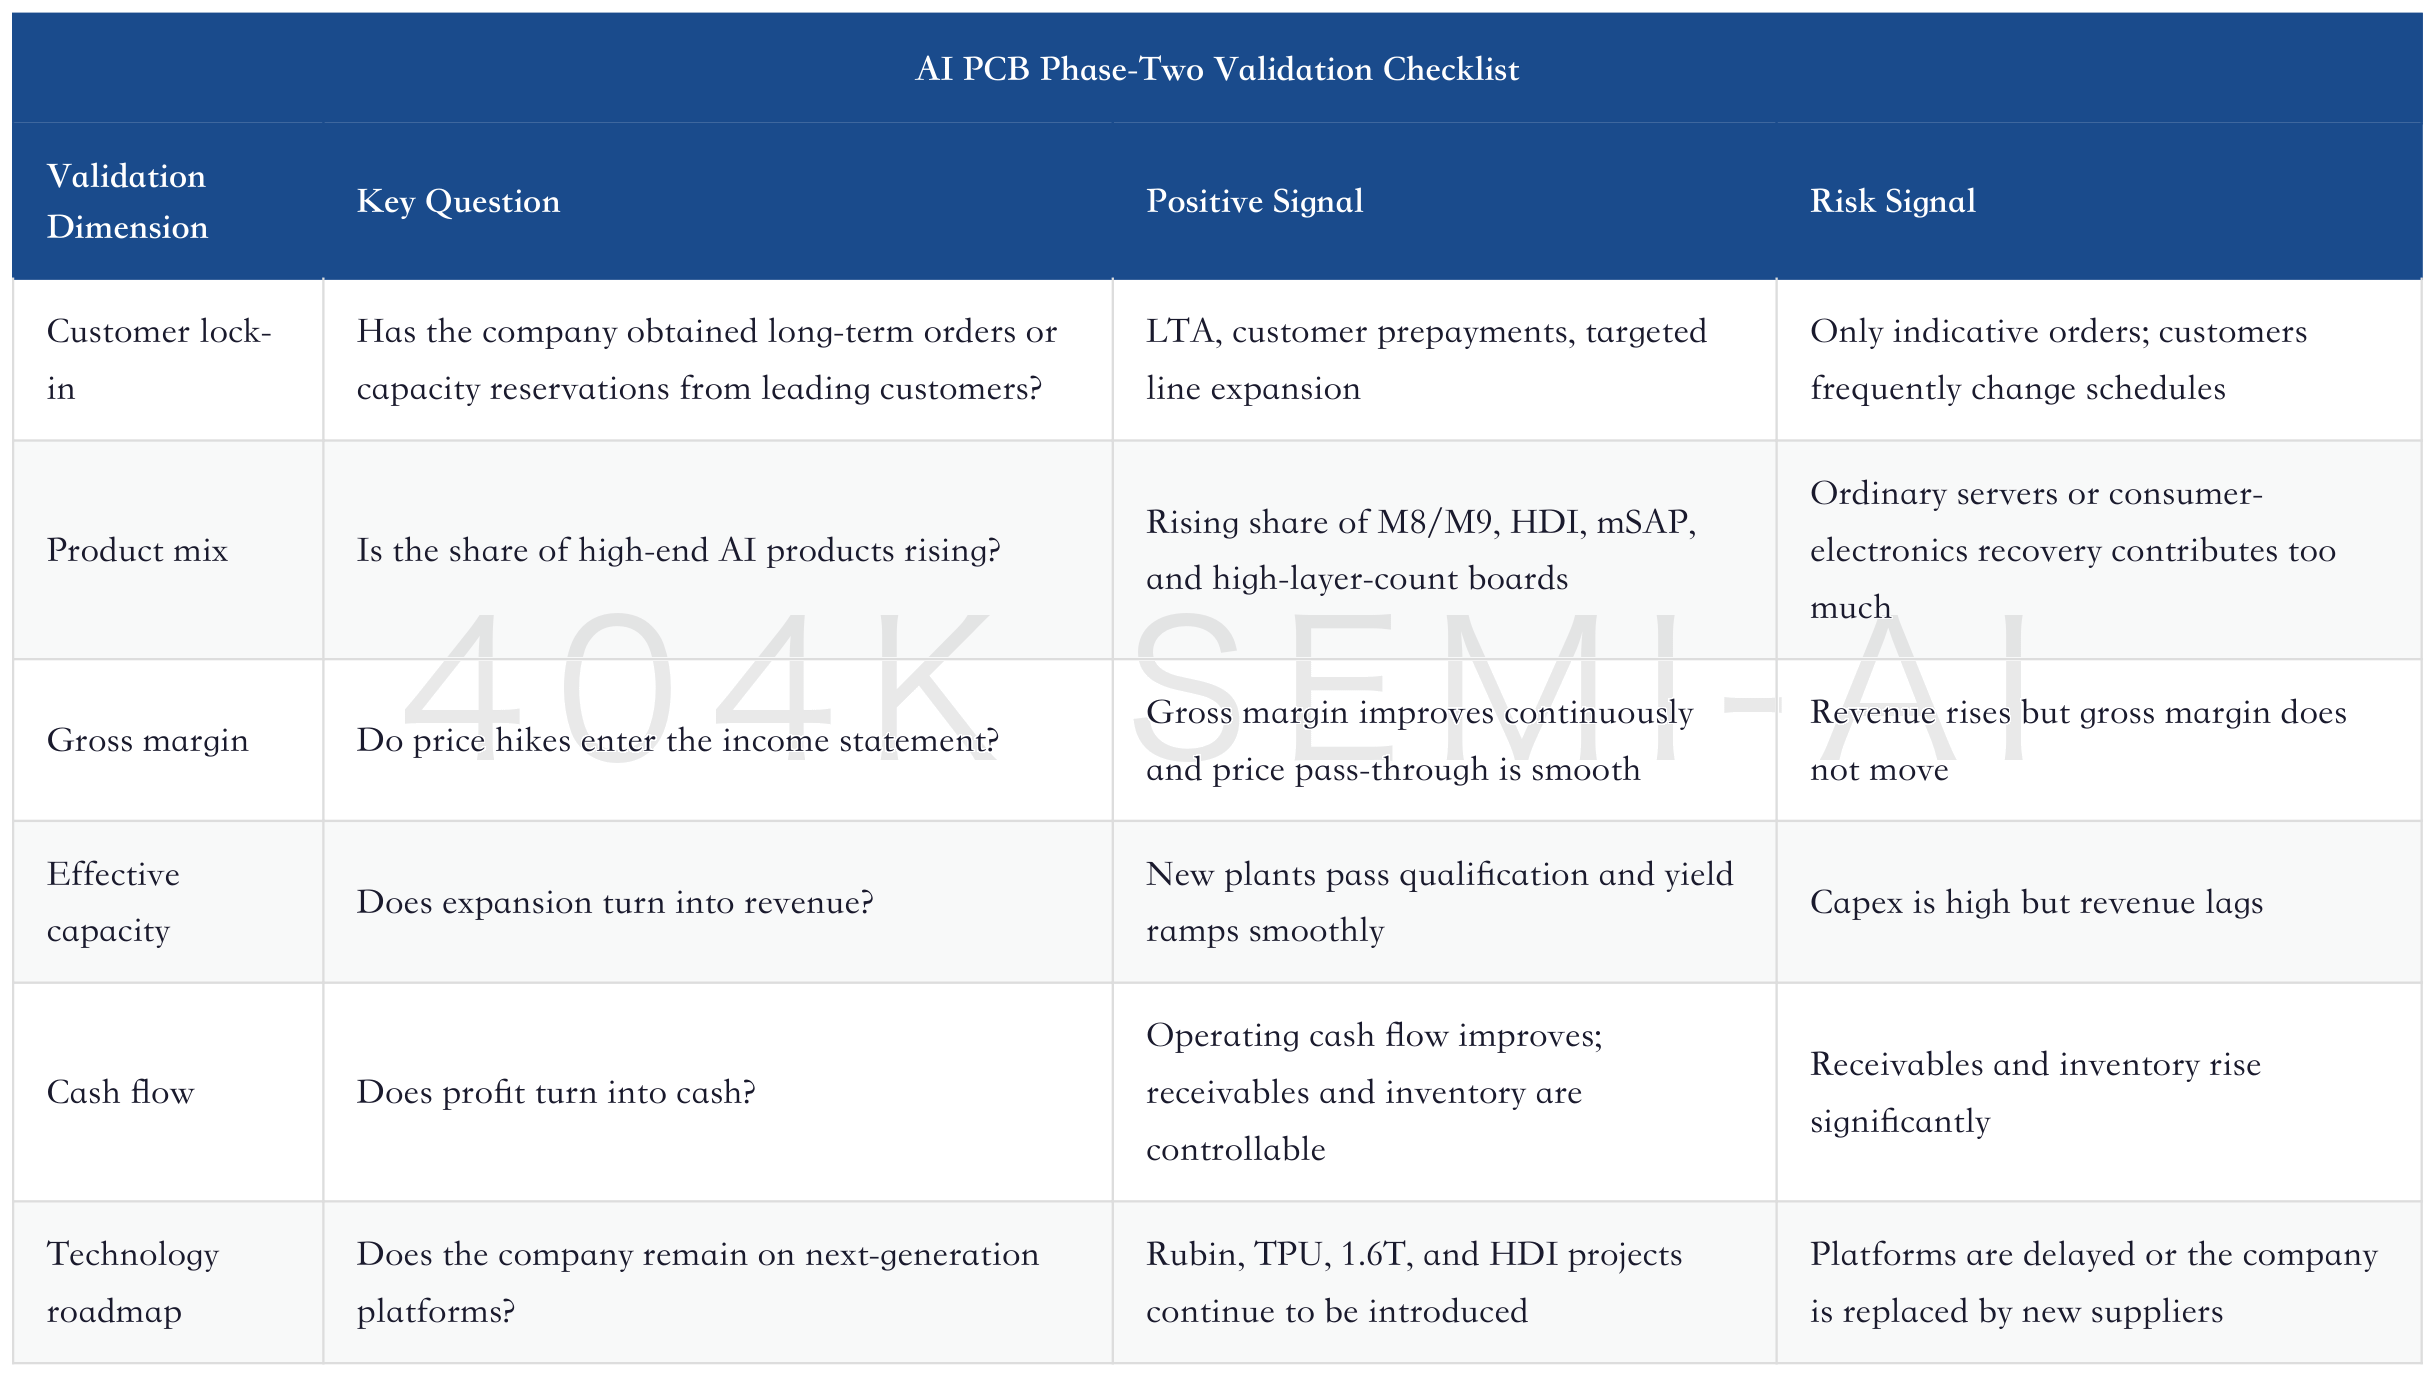
This validation checklist also explains why the trading cadence differs by stock. WUS Printed Circuit is better tracked through quarterly gross margin and switch/AI-server orders. Victory Giant Technology is better tracked through effective capacity and customer-platform ramp. Shengyi Technology is better tracked through high-end CCL prices and product mix. Kingboard Laminates is better tracked through ASP and electronic glass fabric. Zhen Ding Technology is better tracked through capex conversion, HDI, and mSAP revenue.
AI PCB From Material Reappraisal to Profit Delivery: Shennan 30+ Layer MLPCB, Taiwan Union High-End CCL, Kingboard Material Integration, Nan Ya PCB and Unimicron ABF Substrates, and Who Books Price Hikes First
The phase-two market will not reward "having a story" alone. If a company says it has AI orders, but product mix is unclear, gross margin does not improve, capex is heavy, and customer concentration is high, share-price gains will be hard to sustain. Conversely, if a company does not tell many stories but gross margin, customer qualification, and cash flow continue improving, the market will rerate it.
IX. Three Scenarios: Continued Price Hikes, Effective Supply Opening, and Platform Timing Delays
The future AI PCB/CCL cycle can be divided into three scenarios. The first is continued price hikes, where demand remains strong, materials remain tight, customers are willing to pay premiums, and both PCB makers and material suppliers continue revising earnings upward. The second is effective supply opening, where PCB, CCL, electronic glass fabric, and copper-foil expansion proceed better than expected, price hikes slow, and profit elasticity falls. The third is platform timing delays, where Rubin, TPU, Trainium, or 1.6T switch ramps miss expectations, orders are delayed, and valuations retreat first.
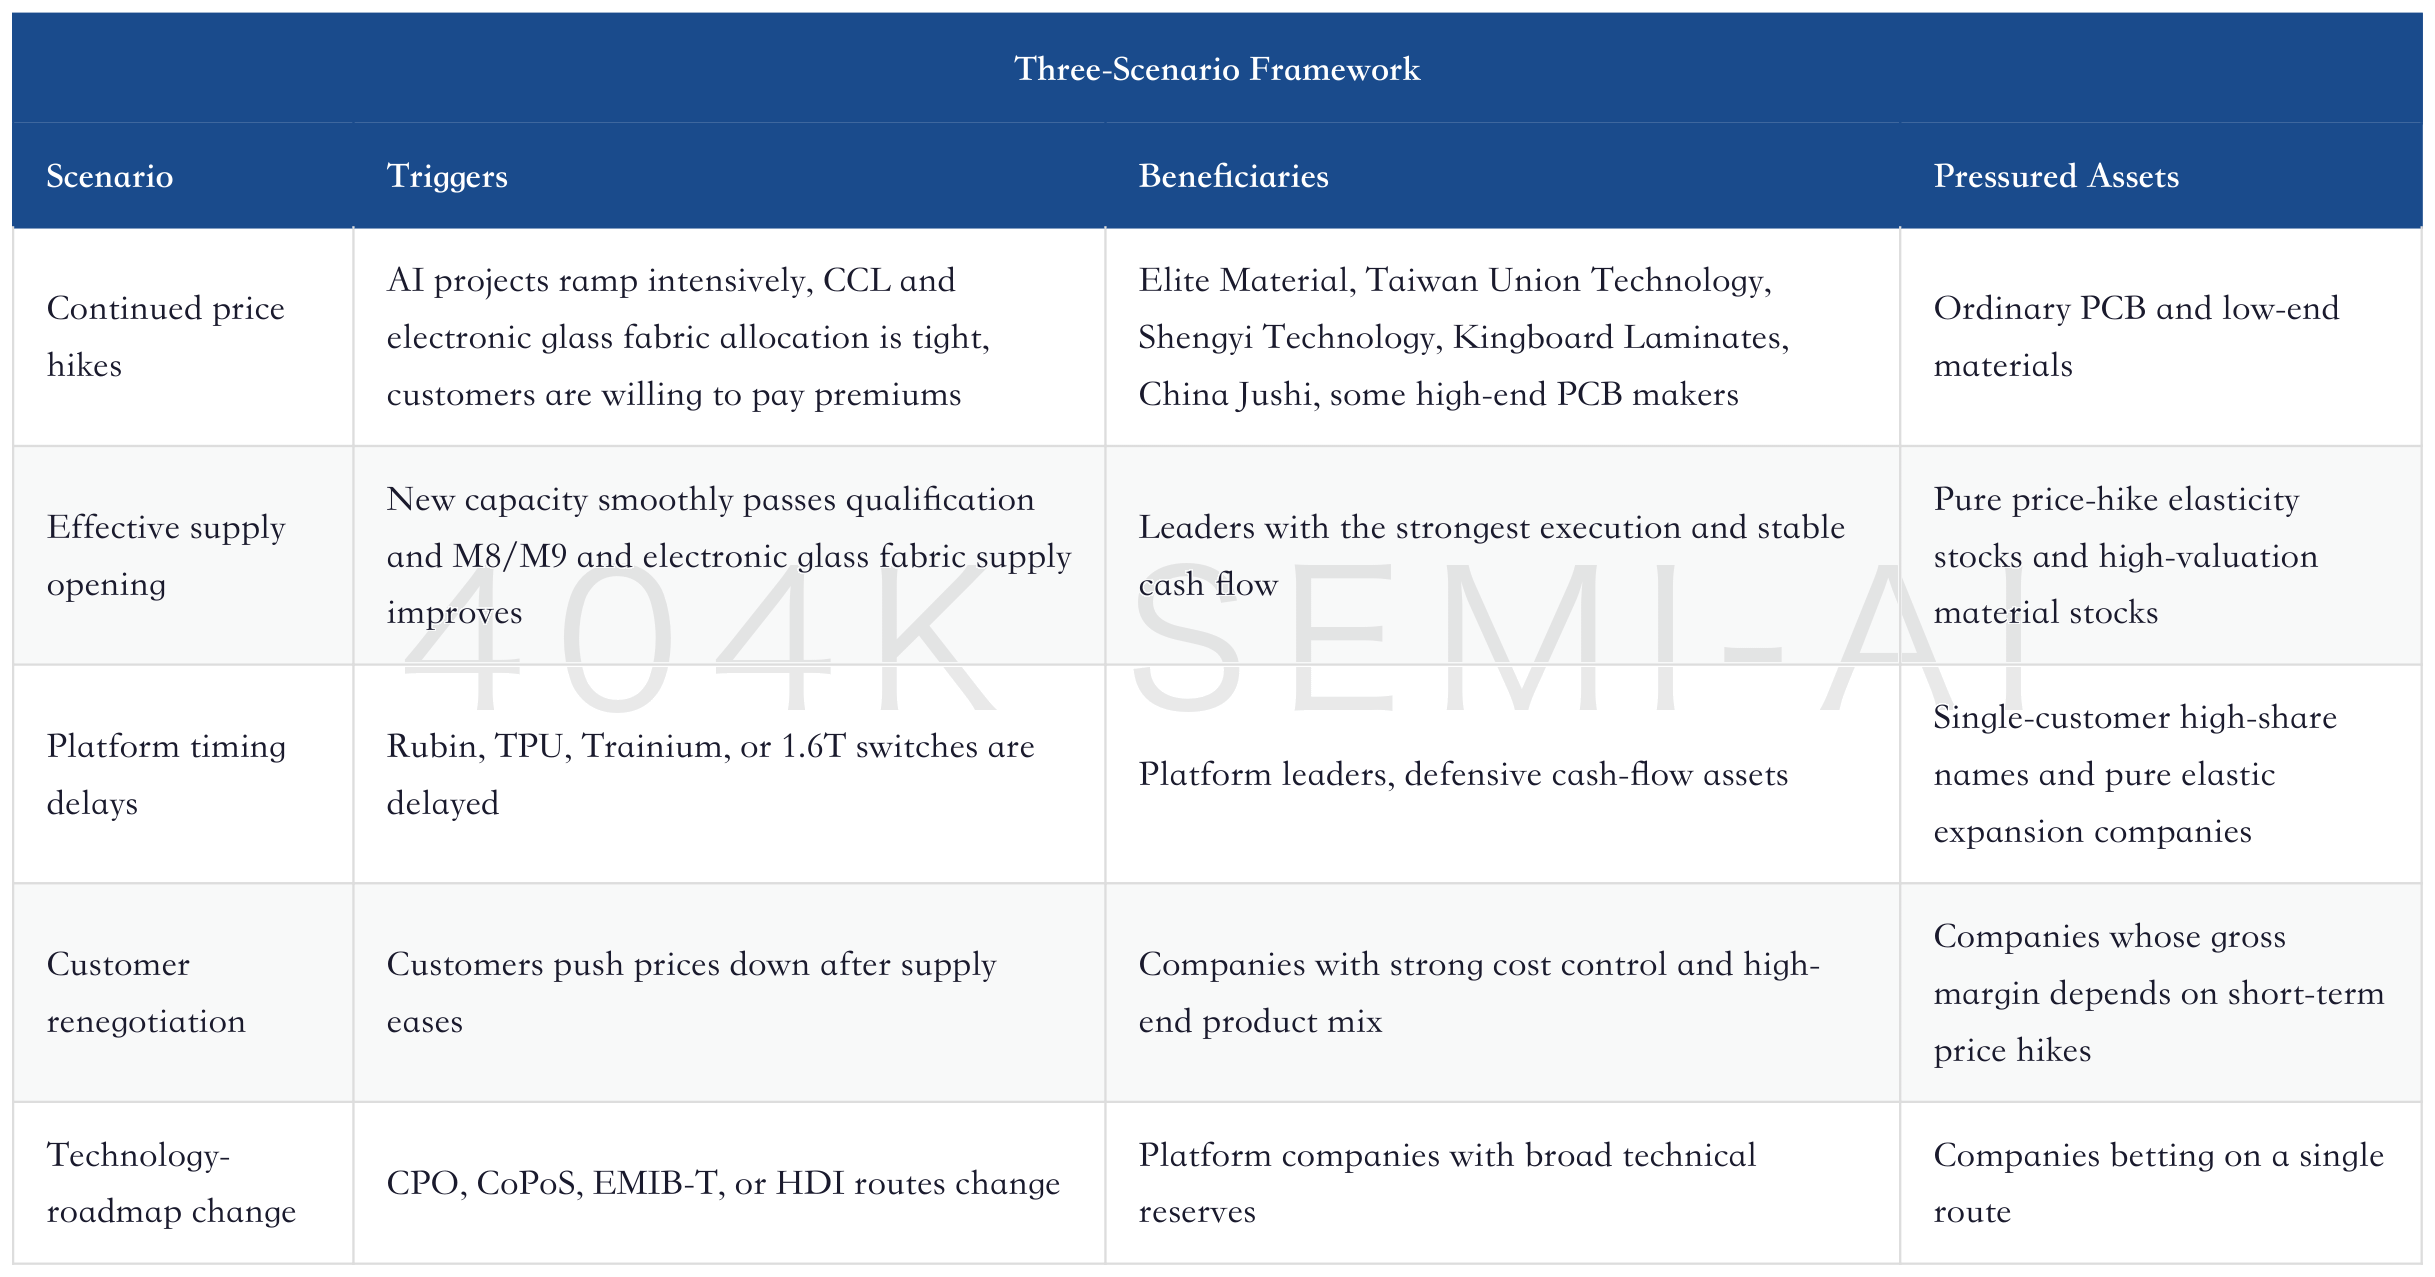
The base case still leans toward continued price hikes. The reason is not infinite demand strength, but the simultaneous pull from multiple platforms from 2H26 to 2027: Google TPU 8t/8i, NVIDIA VR200/Rubin, AWS Trainium 3, 1.6T switches, optical-module boards, and CPU-server recovery. Demand presses on PCB, CCL, electronic glass fabric, copper foil, and HDI at the same time, while supply is hard to release in an orderly way.
But the second scenario cannot be ignored. As long as customers lock volume in advance, suppliers will expand. As long as valuations are high enough, new capacity and new entrants will accelerate. AI PCB and CCL are not natural monopolies that cannot expand. They simply have long expansion cycles, slow qualification, and difficult yield. Investors should watch one timing point carefully: when the market shifts from "supply will always be tight" to "effective supply is being released," high-valuation material stocks will be compressed first.
The third scenario is platform timing delay. If Rubin is delayed further, revenue recognition for some PCB makers will move later. If Google TPU production plans change, chains including Elite Material, WUS Printed Circuit, Victory Giant Technology, and Zhen Ding Technology will be affected. If 1.6T switch deployment misses expectations, elasticity in optical-module boards and mSAP will decline. Platform delays do not mean demand disappears, but they change the timing of earnings recognition.
Therefore, the best portfolio is not a one-way bet. High-certainty assets such as WUS Printed Circuit and Elite Material can form the base. Elastic assets such as Victory Giant Technology, Zhen Ding Technology, and Guanghe Technology can provide offense. Material-side assets such as Shengyi Technology, Kingboard Laminates, and China Jushi can express upstream scarcity. Platform companies such as Shennan Circuits, DSBJ, and Avary Holding can capture broader interconnect migration.
X. Valuation and Target Prices: Do Not Reduce a High-Prosperity Industry to One Multiple
The valuation challenge for AI PCB/CCL is that different segments all look like beneficiaries, but the market gives them multiples for different reasons. PCB-maker multiples come from high-end customers and order certainty. Material-supplier multiples come from price pass-through and supply scarcity. HDI/mSAP platform multiples come from capability migration. Equipment-side multiples come from the expansion cycle. Ranking companies only by "AI-related revenue share" misreads both risk and return.
The valuation core for WUS Printed Circuit, Victory Giant Technology, and Guanghe Technology is whether AI revenue can continue being revised upward. Foreign target-price upgrades show that the market is starting to incorporate 2027-2028 board-level demand into models, but these target prices cannot be compared directly across companies. Report dates, customer definitions, profit assumptions, capacity ramps, and risk premiums all differ. A more reasonable approach is to ask where the earnings upgrade behind the target price comes from: revenue revision, gross-margin revision, or valuation-multiple revision.
Material-stock valuation is more like a margin-sensitivity question. The upgrade to Elite Material's target price is centered on 2027F EPS and repriced high-end CCL demand. The reappraisal of Kingboard Laminates and Shengyi Technology also depends on whether AI-material price hikes enter gross margin. If only low-end CCL and ordinary electronic glass fabric are rising in price, valuation should remain more cyclical. If M8/M9, Low Dk, Low CTE, and high-end copper foil form sustained qualification barriers, valuation has room to become more platform-like.
Zhen Ding Technology's valuation is more of a platform reappraisal. Nomura raised Zhen Ding Technology's target price not only because of AI PCB, but also because of IC substrates, optical-module boards, HDI/mSAP, and long-term customer agreements. Its risks are also more complex: capex is large, product lines are numerous, and any ramp issue in one segment can affect profit delivery. The greatest risk for platform companies is "many narratives, dispersed profit." The best validation is multiple new businesses contributing gross margin and cash flow at the same time.
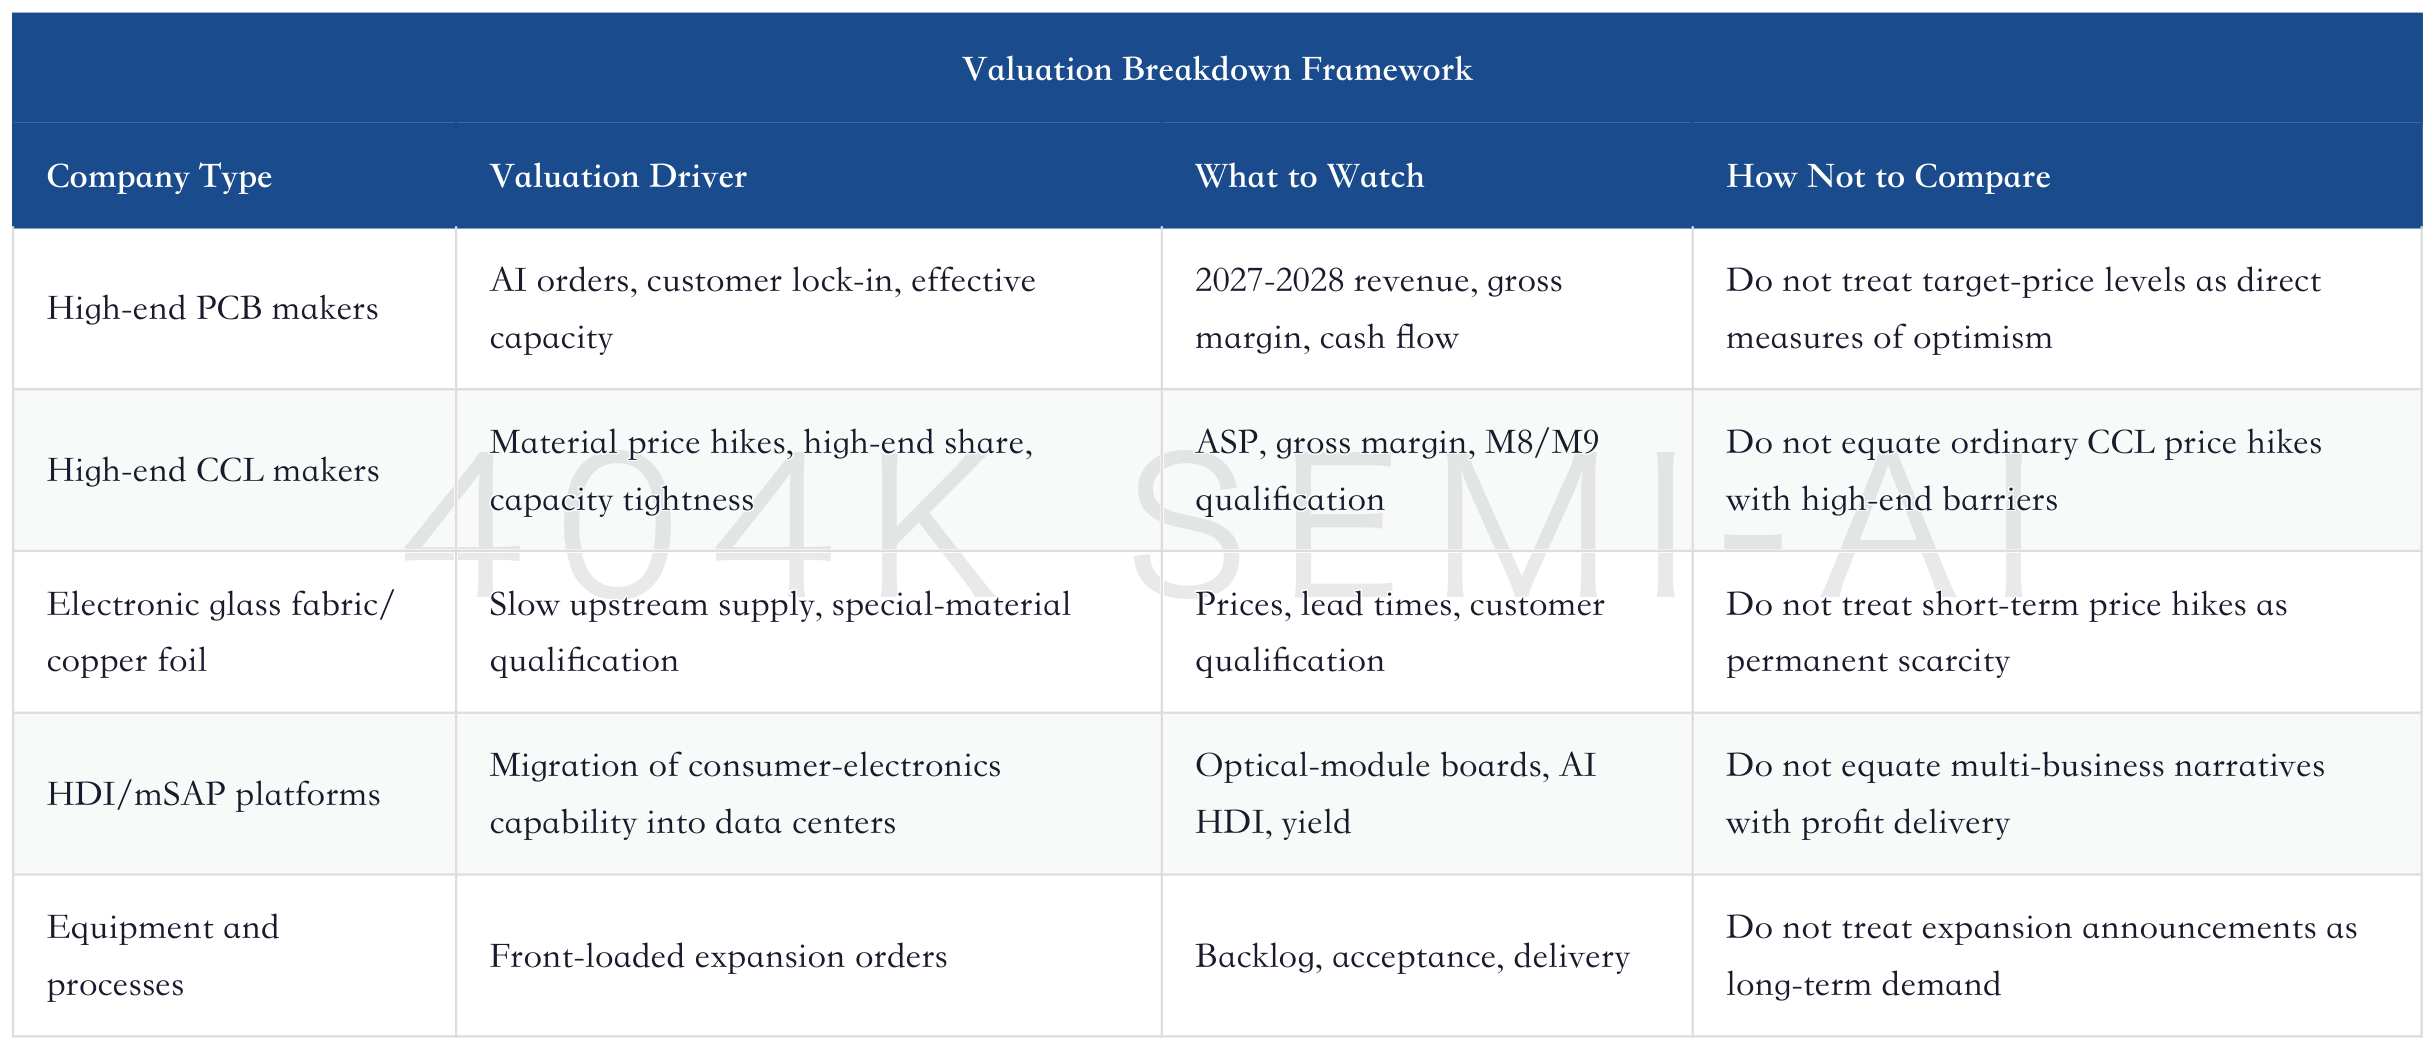
The most important valuation dividing line is when the market moves from "valuing orders" to "valuing profit delivery." In 2025-2026, orders, customers, capacity, and target-price upgrades are enough to push share prices. Starting in 2027, the market will increasingly care about gross margin, cash flow, and utilization of new capacity. Companies that can continue revising profit upward after this turning point will be able to maintain high valuations.
This is also why this report emphasizes ranking rather than only listing beneficiaries. WUS Printed Circuit and Victory Giant Technology both benefit from AI PCB, but the former depends more on stable delivery of switches and high-end communications boards, while the latter depends more on AI-server boards and new-capacity ramp. Shengyi Technology and Kingboard Laminates both benefit from CCL price hikes, but the former is an A-share high-end material platform and the latter is material integration with Hong Kong-listed valuation recovery. Elite Material and Taiwan Union Technology both benefit from high-end CCL, but the former has stronger capacity and customer mix, while the latter has higher elasticity.
Valuation risks also need to be written clearly in advance. First, if effective supply of high-end CCL and electronic glass fabric is released in 2027, material-stock gross-margin assumptions will be revised down. Second, if Rubin, Google TPU, or 1.6T switches are delayed, revenue recognition for PCB makers will move later. Third, if cloud capex shifts from "rushing for supply" to "pressing costs," customer bargaining power will strengthen again. Fourth, if company capex is too fast, depreciation and cash-flow pressure will arrive before revenue release.
Therefore, AI PCB/CCL is not a sector that can be explained indefinitely by high multiples alone. Its valuation rerating comes from real bottlenecks, and its valuation pullback will also come from real supply. Good investment judgment should acknowledge two things at the same time: near-term scarcity remains real, and the long-term cycle has not disappeared. Only by putting both into the model can investors avoid treating cyclicals as perpetual growth stocks at the hottest point of the cycle, or missing high-end platforms that can truly cross the cycle during corrections.
XI. What to Track Over the Next Four Quarters: Do Not Wait for Financial Reports to Decide
AI PCB/CCL tracking cannot rely only on annual reports. Over the next four quarters, each quarter has different validation points. In 3Q26, watch whether Google TPU, VR200, and Trainium 3 truly drive material allocation. In 4Q26, watch whether price pass-through continues and whether high-end CCL gross margin improves. In 1H27, watch whether new capacity can pass customer qualification. In 2H27, watch whether supply opening suppresses prices.
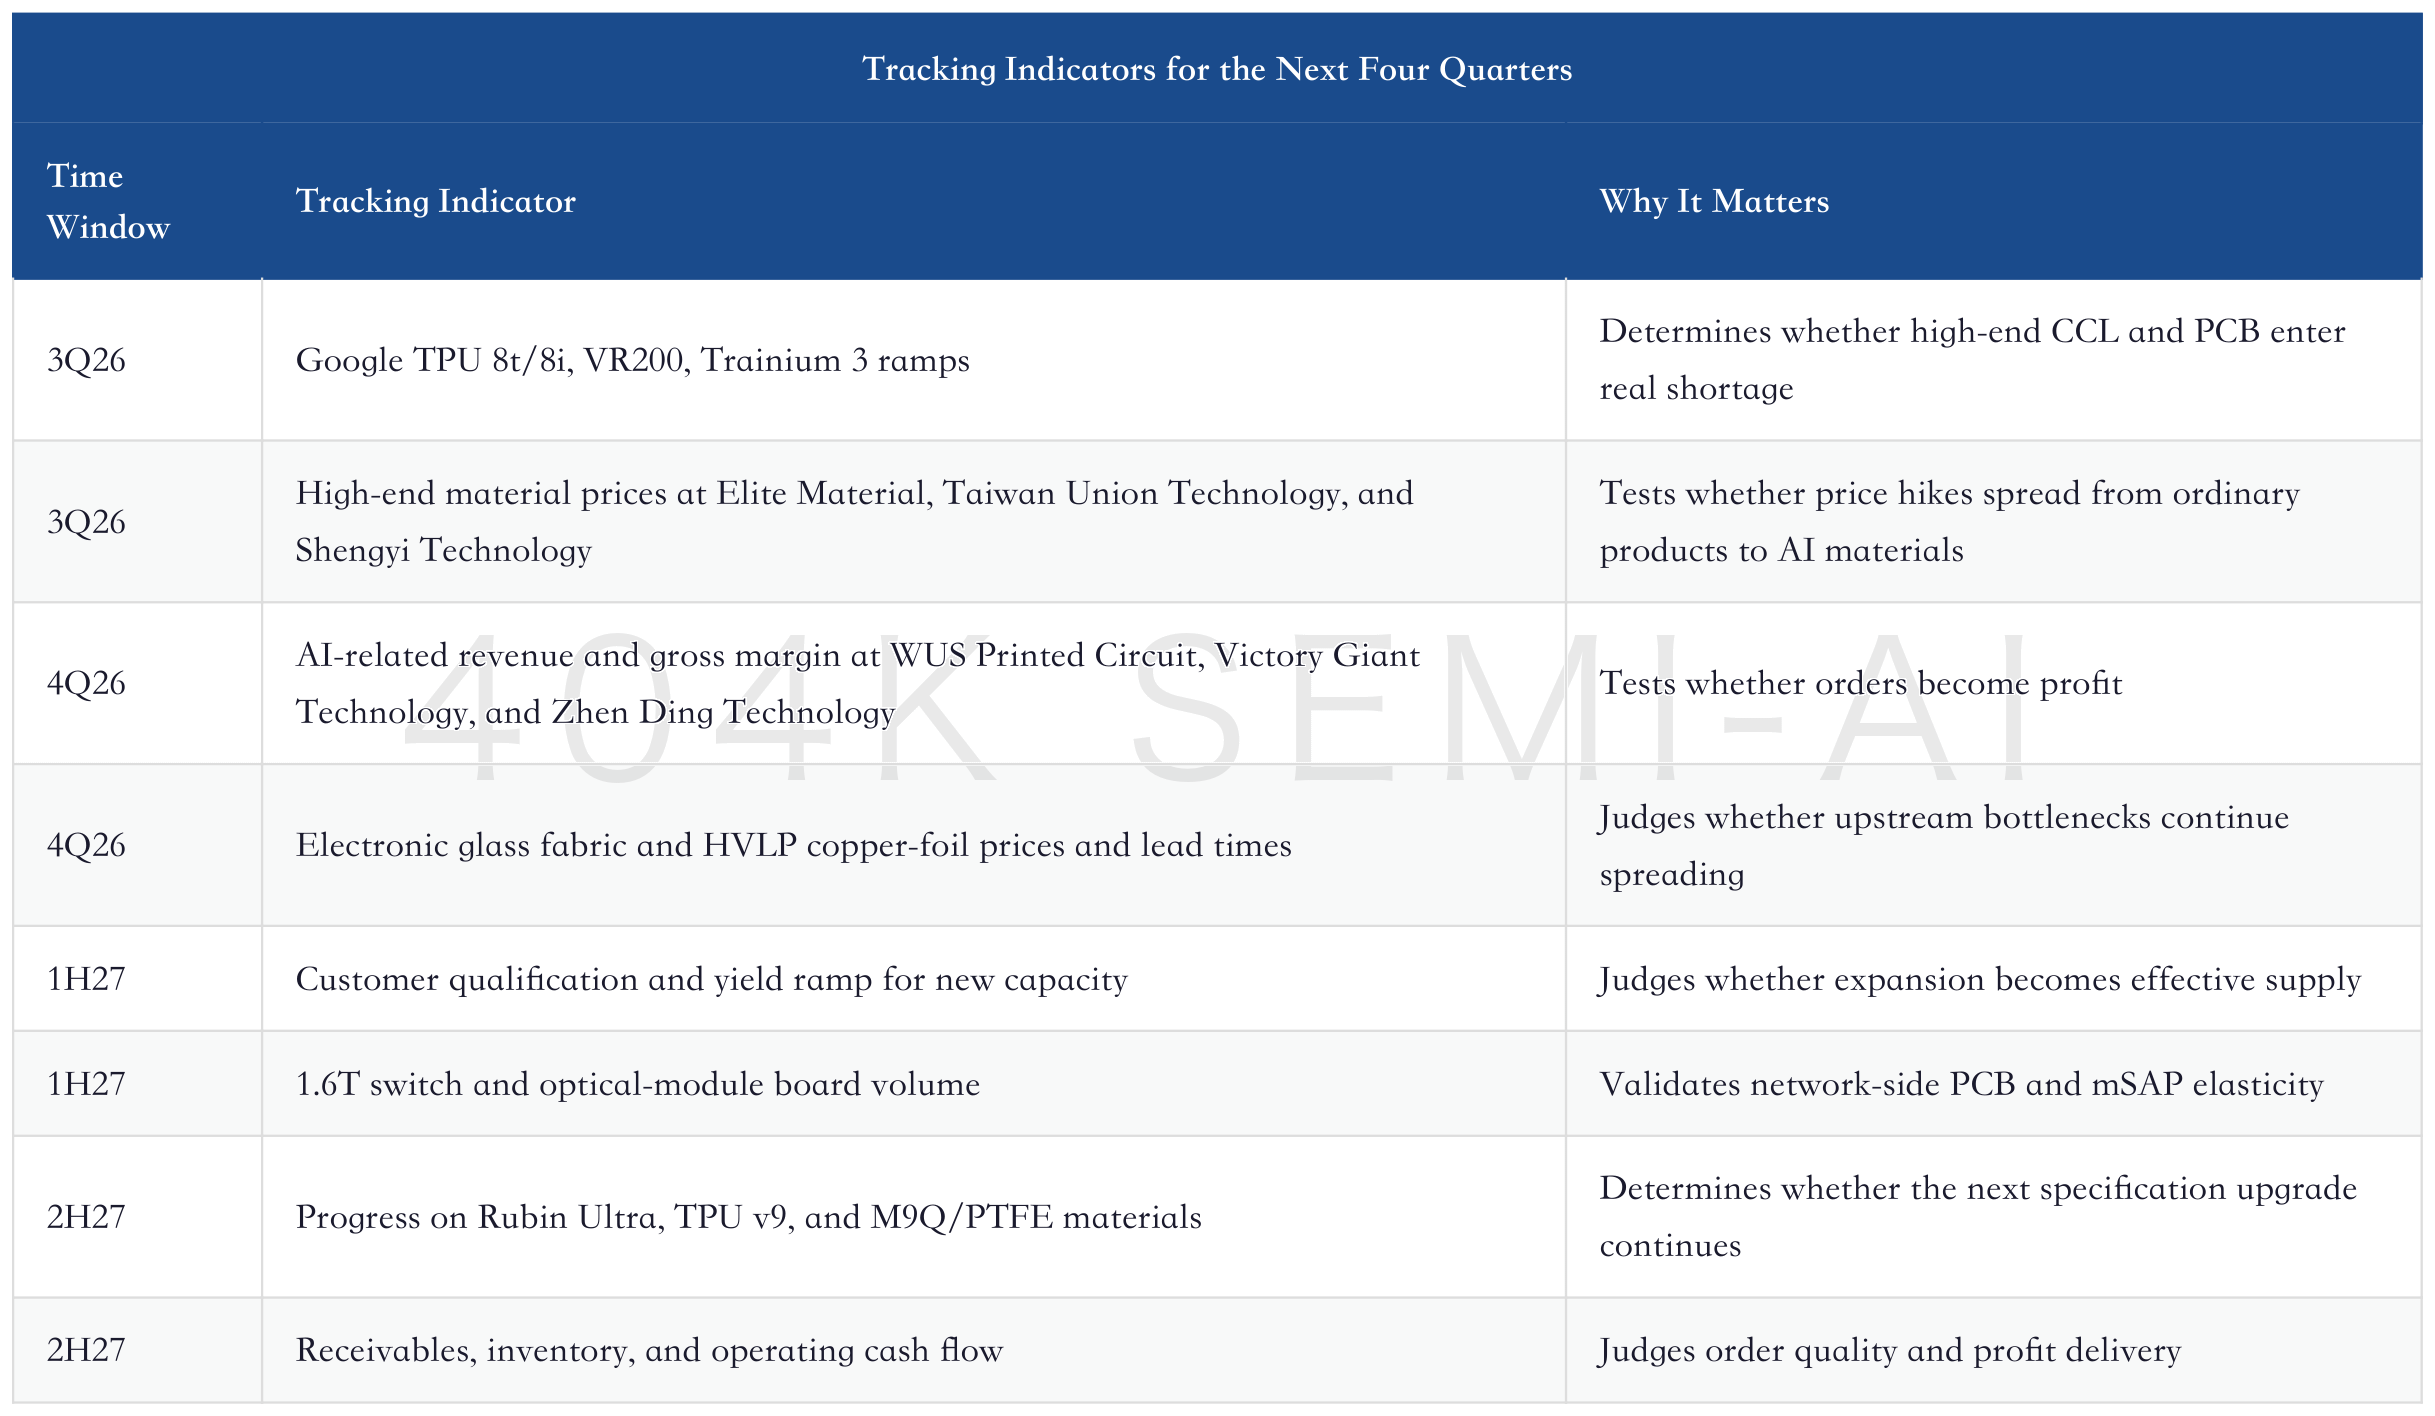
Several indicators are easy to misread. First, upward capex revisions are not necessarily positive. Without customer lock-in, capex becomes depreciation pressure. Second, gross margin failing to rise is not necessarily immediately negative. If a company is in a new-capacity ramp phase, investors need to watch subsequent utilization. Third, inventory increases are not necessarily bad. High-end material stocking and customer lock-in may create phased inventory increases, but if receivables rise at the same time and cash flow deteriorates, investors need to be alert.
Historically, PCB and CCL have both been cyclical industries prone to overheating. AI changes demand quality and specification thresholds, but it does not eliminate the manufacturing cycle. The real differences are that the upcycle driver this time comes from data-center infrastructure, not phone or PC inventory; supply constraints come from customer qualification and high-end materials, not insufficient ordinary capacity; and valuation divergence comes from profit quality, not simple revenue growth.
This is also why investors need to separate "AI demand is strong" from "share prices can keep rising." Strong demand is an industry judgment. Continued share-price gains require companies to deliver profit, the market to keep revising upward, and valuation to still have room. If any one of the three is missing, share prices may correct first even if the industry trend has not changed.
XII. Falsification Checklist: When Board-Level Interconnect Enters the Second Half
The most important falsification signal for AI PCB/CCL is not a one-day share-price decline, nor one institution cutting a target price. It is the industry chain moving from "scrambling for supply" to "competing on cost." As long as customers are still scrambling for qualified capacity, M8/M9 materials, electronic glass fabric, and high-end copper foil, the industry is still in the profit-upgrade phase. Once customers start pressing prices again, suppliers start competing for orders, and expanded capacity starts proactively searching for demand, the cycle enters the second half.
The first falsification signal is prices failing to rise. CCL and electronic glass fabric prices are the most direct thermometers. If prices for M7 and below stop rising, M8/M9 price hikes cannot land, Low Dk and Low CTE electronic glass fabric lead times shorten, and customers no longer accept premiums for HVLP copper foil, material tightness is easing. PCB makers may still see revenue growth, but material-side valuations need to be revised down, and PCB-maker gross margins will face customer renegotiation.
The second falsification signal is gross margin no longer expanding. If AI orders are truly moving high-end, gross margin should at least stabilize or improve. If PCB-maker revenue grows quickly but gross margin declines continuously, order quality may be weaker than headline revenue suggests. If CCL ASP rises but gross margin does not, raw materials, capacity utilization, or price concessions are eating profit. If HDI/mSAP platform revenue rises but depreciation pressure arrives faster, capability migration has not yet entered profit delivery.
The third falsification signal is weakening customer lock-in. Current optimistic expectations are built on 2027-2028 capacity being booked in advance and leading customers being willing to participate in supply-chain lock-in. If customers change long-term orders into short orders, convert dedicated lines into flexible procurement, or delay previously committed capacity occupancy, supply-demand conditions are loosening. PCB makers and material suppliers may continue shipping, but valuation should move from bottleneck-asset valuation back toward manufacturing-asset valuation.
The fourth falsification signal is repeated platform delays. A delay in one platform can be offset by others, but multiple platforms slowing at the same time requires a reassessment of the demand curve. Delays in Rubin Ultra, Google TPU v9, subsequent Trainium platforms, 1.6T switches, or optical-module boards are not fatal individually. If these lines all move later at the same time, the annual cadence of AI-PCB TAM will flatten, and both PCB-maker expansion and material-supplier price hikes will face delivery pressure.
The fifth falsification signal is capex becoming depreciation pressure. In this AI PCB/CCL cycle, higher capex is itself evidence of strong supply-demand conditions, but capex also becomes future cost. If new plants pass customer qualification slowly, yield ramps slowly, and utilization is low, depreciation enters costs before revenue and profit arrive. At that point, the most dangerous setup is valuation already pricing full utilization and high gross margin, while the financial statements deliver only depreciation.
The sixth falsification signal is deteriorating cash-flow quality. The value of high-end manufacturing orders ultimately depends on operating cash flow. If a company stocks up early for delivery to large customers, a phased inventory increase is understandable. If receivables, inventory, and capex all rise while operating cash flow clearly lags profit, pricing power is weaker than imagined. The biggest risk for AI hardware companies is strong accounting profit and slow cash collection, because the market will reapply a manufacturing discount.
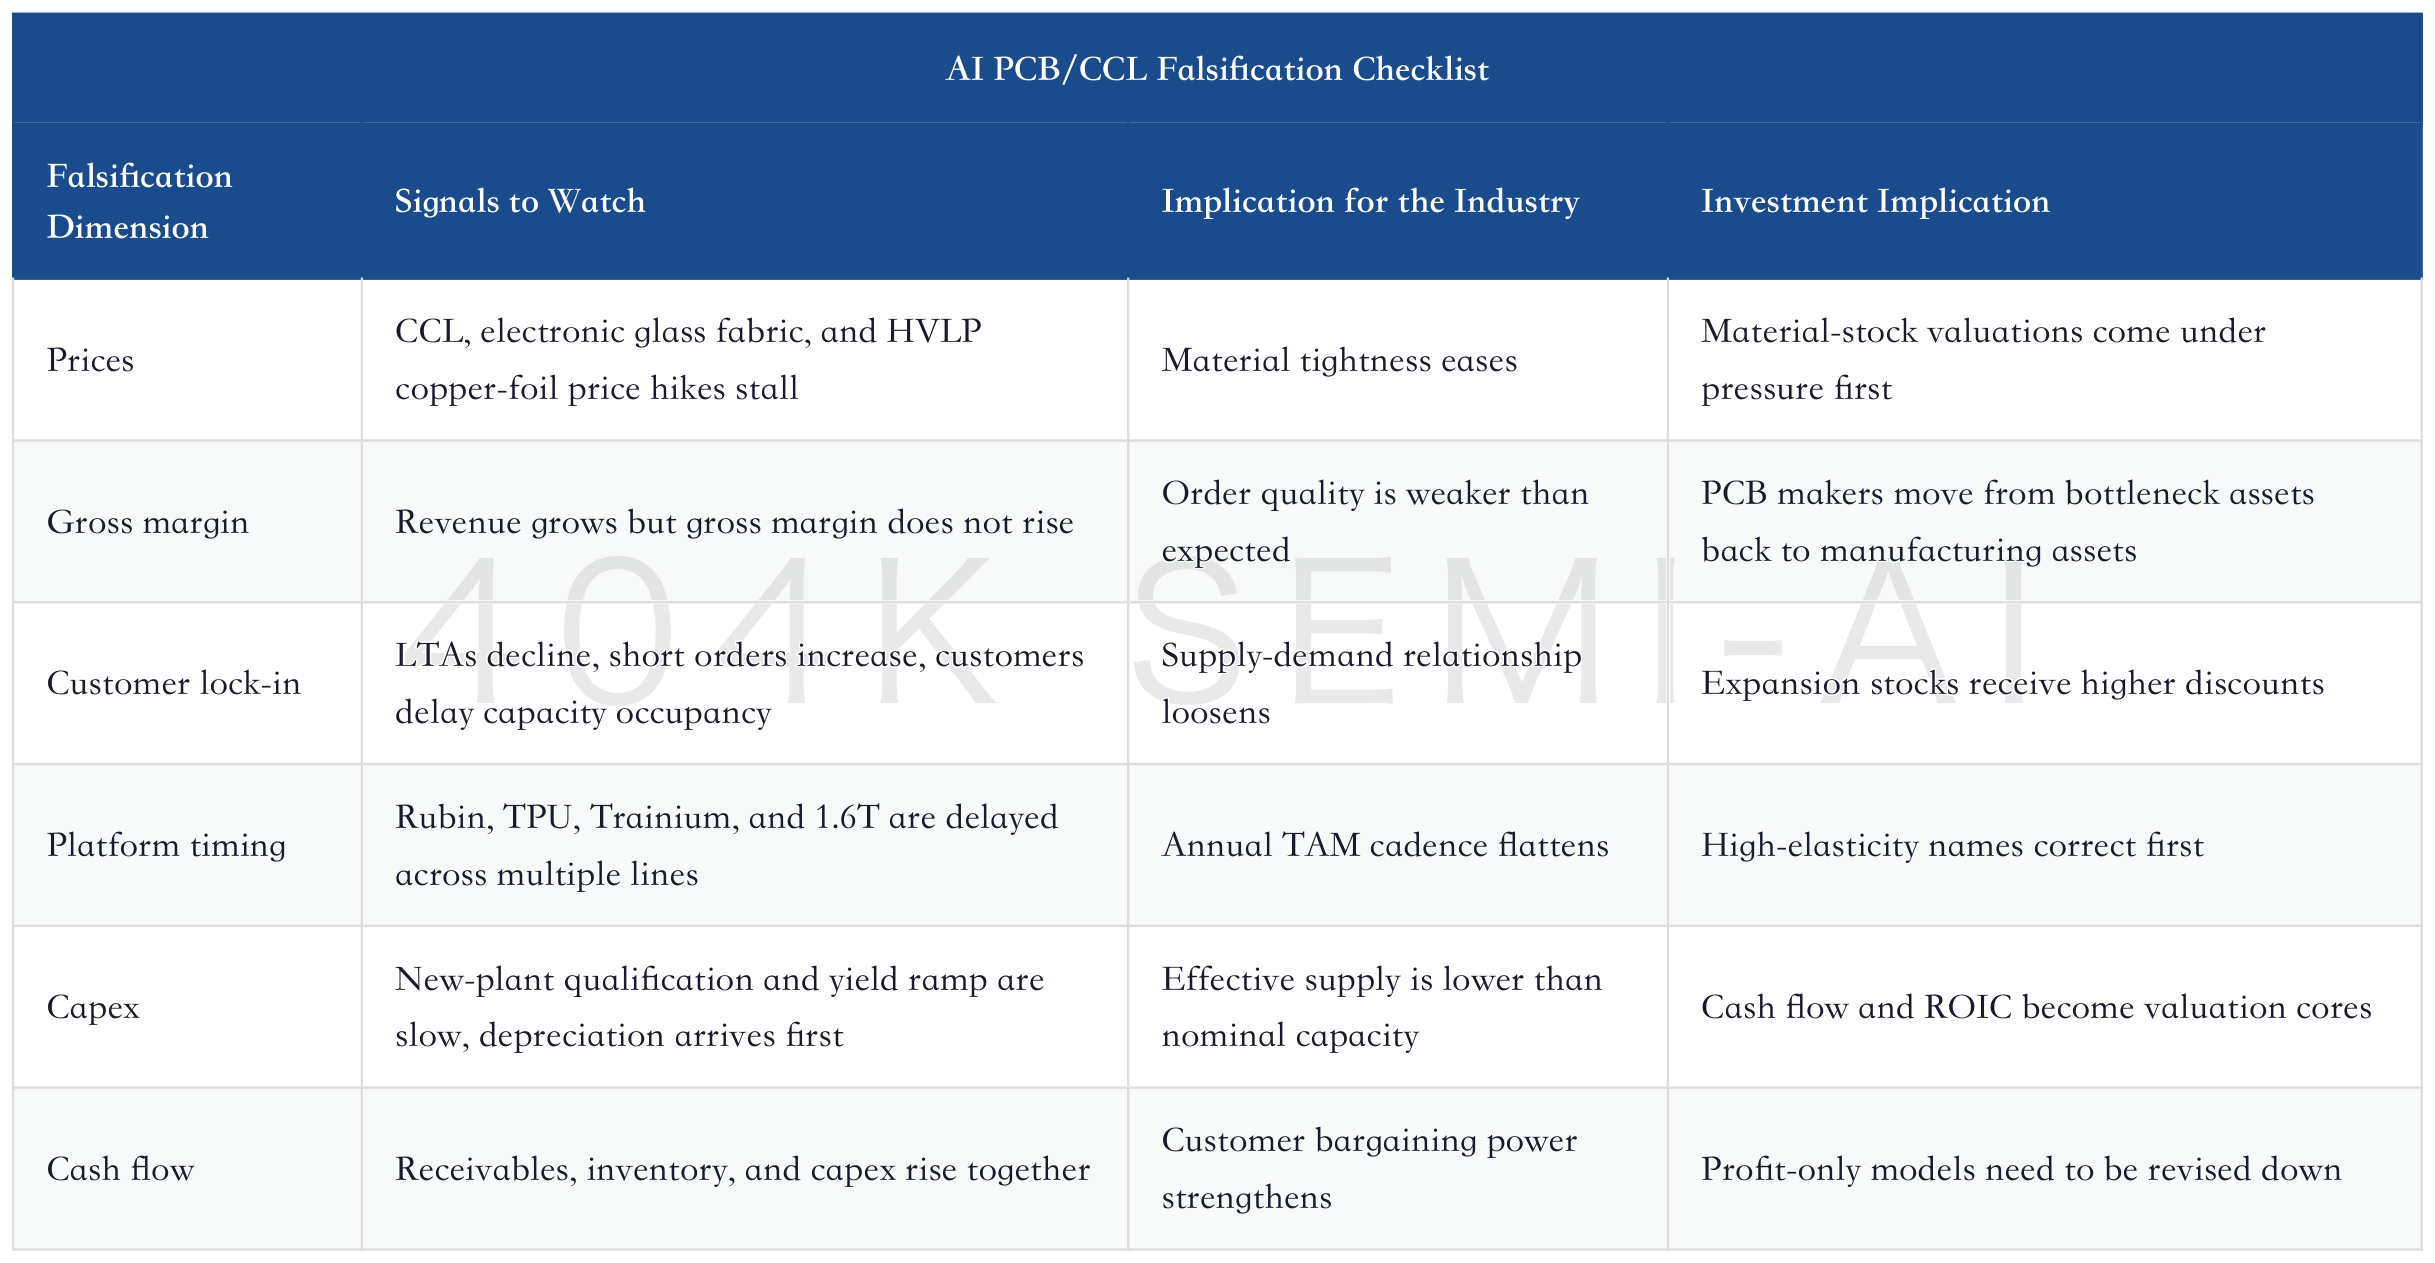
Conversely, if these falsification signals do not appear, the cycle should not end too early. As long as high-end material allocation remains tight, customers continue locking capacity in advance, material-side gross margins continue improving at Elite Material, Shengyi Technology, Kingboard Laminates, and others, and board-level suppliers such as WUS Printed Circuit, Victory Giant Technology, and Zhen Ding Technology continue turning orders into cash flow, the market will continue assigning higher valuations to AI PCB/CCL. The real question is not whether the industry has room, but whether each company can capture profit within that room.
In trading cadence, this theme can be divided into three phases. The first is TAM and order revisions, where share prices mainly reflect "how much demand exists." The second is price and gross-margin validation, where share prices mainly reflect "who turns demand into profit." The third is expansion delivery and supply release, where share prices mainly reflect "who can cross the cycle." The industry is now moving from the first phase toward the second. Some companies have already been priced for the second phase, but third-phase risks have not been fully incorporated into models.
This is why this report prefers a framework of "qualified capacity and profit delivery." Discussing only demand underestimates material-side price hikes. Discussing only price hikes overestimates cycle durability. Listing only company names ignores customer mix and yield. Valuable research connects demand, specifications, supply, pricing, financials, and falsification into one chain. AI PCB and CCL still deserve a standalone deep dive precisely because they are no longer fringe items in the larger AI-server chain, but have begun to develop their own investment cadence.
XIII. Conclusion: The Main Line for AI PCB and CCL Is Not Expansion, but Qualified Capacity and Profit Delivery
The main line for AI PCB and CCL can be summarized in one sentence: the more concentrated compute becomes, the more board-level interconnect looks like infrastructure; the more complex racks become, the more high-end materials look like delivery rights. GPUs, TPUs, CPUs, switches, optical modules, power, and cooling all require higher-quality boards and materials, turning PCB and CCL from cyclical supporting roles into small gates determining whether AI servers can come online.
But this main line is not simple expansion. What is truly valuable is qualified capacity, customer lock-in, yield, material grade, and price pass-through. Ordinary capacity can be expanded, but high-end effective capacity has to pass customer audits. Ordinary price hikes can pass through, but high-end material price hikes need to enter gross margin. Ordinary orders can be canceled, while long-term locked volume is what supports capex. Investors must see these differences clearly.
For A-shares, WUS Printed Circuit, Victory Giant Technology, Shengyi Technology, Shennan Circuits, Guanghe Technology, DSBJ, Avary Holding, and others all map to AI PCB, but in completely different ways. WUS Printed Circuit leans toward switches and high-end communications PCBs. Victory Giant Technology leans toward effective capacity in AI-server PCBs. Shengyi Technology leans toward high-end CCL materials. Shennan Circuits leans toward a steady platform and IC substrates. Guanghe Technology leans toward new-capacity elasticity. DSBJ and Avary Holding lean toward integrated interconnect platforms. Treating them as the same sector misses the most important profit differences.
For Hong Kong and Taiwan equities, Kingboard Laminates, Elite Material, Taiwan Union Technology, Zhen Ding Technology, China Jushi, and others provide more upstream or more platform-oriented perspectives. Elite Material and Taiwan Union Technology validate high-end CCL price hikes. Kingboard Laminates validates material integration. China Jushi validates electronic glass fabric supply. Zhen Ding Technology validates platformization across HDI, mSAP, optical-module boards, and substrates. They are important references for understanding A-share mapping.
The real risk is treating every bottleneck as permanently scarce. As long as customers are willing to pay premiums, suppliers will expand. As long as valuations are high enough, new entrants will accelerate qualification. As long as platform timing is delayed, orders will be re-ranked. The good business in AI PCB and CCL is that near-term tightness is real. The difficulty is that companies must keep proving over the long term that they are not ordinary cyclicals.
The best question for the next phase is not "who has AI orders," but "whose AI orders can pass through material lock-in, customer qualification, yield ramp, gross-margin improvement, and cash recovery." Companies that can pass through this chain will move from PCB makers or material suppliers into AI infrastructure delivery assets. Companies that cannot will only shine briefly in theme-driven rallies. AI servers are still expanding, but the market has already started rewarding finer research.
At the tracking level, investors should divide this main line into four accounts: the order account, the material account, the capacity account, and the cash-flow account. The order account tracks cloud-platform production schedules and long-term lock-in. The material account tracks M8/M9, electronic glass fabric, and HVLP copper-foil prices. The capacity account tracks new-plant qualification and yield. The cash-flow account tracks receivables, inventory, and operating cash flow. When all four accounts improve together, the reappraisal continues. If only orders improve while the other accounts do not keep up, share prices will behave more like theme volatility.
This is also why this report separates PCB, CCL, electronic glass fabric, copper foil, HDI, and mSAP for a standalone discussion. They are no longer small attachments to the AI-server theme, but important variables for judging the quality of compute delivery in 2027. GPUs and advanced packaging answer the question, "Are there enough compute chips?" PCB and CCL answer the question, "Can complete systems come online on time?" As the market moves from buying chip shortages to buying system delivery, board-level interconnect must be priced separately.
The final conclusion remains measured: AI PCB and CCL are still in the middle of an upward cycle, with tight near-term supply, rapid specification upgrades, strong customer lock-in, and room for further profit revisions. But this is not perpetual scarcity. Expansion, platform timing, and customer bargaining will eventually re-enter the model. The companies that can cross the second half are not those that tell the best AI story, but those that can deliver qualified capacity, material barriers, and cash flow together.AI PCB and CCL Deep Dive: From GB300 to Rubin Ultra, What Runs Short First: High-Layer PCBs, M9 Materials, or Electronic Glass Fabric?
目录
Too Long; Didn’t Read
I. AI Servers Enter Board-Level Shortage: PCB and CCL Move From Peripheral Materials to Delivery Gates
II. Demand Side: AI-PCB TAM Expands From GPU Boards to ASICs, CPUs, Switches, and Optical Modules
III. Specification Side: From GB300 to Rubin, TPU, and Trainium, How Board-Level Content Value Rises
IV. Supply Side: PCB Expands Fastest, CCL Next, Electronic Glass Fabric Slowest; Pricing Power Is the Reverse
V. Pricing Power: PCB Makers Earn Orders, CCL and Electronic Glass Fabric Earn Scarcity; Who Turns Price Hikes Into Profit?
VI. Company Ranking: WUS Printed Circuit, Victory Giant Technology, Shengyi Technology, Shennan Circuits, Guanghe Technology, and the Taiwan Material Chain Are Not the Same Opportunity
VII. Value-Chain Pass-Through: Five Profit Pools Behind One AI Board
VIII. From Orders to Cash Flow: Five Tables to Verify in AI PCB Phase Two
IX. Three Scenarios: Continued Price Hikes, Effective Supply Opening, and Platform Timing Delays
X. Valuation and Target Prices: Do Not Reduce a High-Prosperity Industry to One Multiple
XI. What to Track Over the Next Four Quarters: Do Not Wait for Financial Reports to Decide
XII. Falsification Checklist: When Board-Level Interconnect Enters the Second Half
XIII. Conclusion: The Main Line for AI PCB and CCL Is Not Expansion, but Qualified Capacity and Profit Delivery
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The bottleneck in AI servers is spilling over from GPUs and CoWoS into board-level interconnect. PCBs, CCLs, electronic glass fabric, copper foil, and HDI are no longer peripheral materials. They are the small gates that determine whether Rubin, Google TPU, and 1.6T switches can come online on schedule. The real investment debate is who can turn price hikes into profit.
Too Long; Didn’t Read
The bottleneck has already spilled over. In the first phase of AI hardware, investors bought GPUs and advanced packaging. In the second phase, they are buying the ability to actually bring complete servers, switches, and ASIC clusters online. The value of PCB, CCL, HDI, mSAP, electronic glass fabric, and copper foil is not that they are “also AI.” It is that without them, expensive chips cannot become operating racks.
Demand does not only come from NVIDIA. AI-PCB demand is expanding from GPU motherboards to Google TPU, CPU boards, switches, optical modules, and ASIC servers. The 1.6T networking upgrade will make switch and optical-module PCBs one of the fastest-growing branches. By 2028E, Google TPU-related PCB procurement could exceed the NVIDIA GPU chain, changing the customer mix for board-level interconnect.
CCL has more pricing power than PCB. PCB makers are expanding most aggressively, but many price increases are pass-throughs of material costs. CCL, electronic glass fabric, and high-end copper foil are expanding more slowly, customer qualification takes longer, and price elasticity is more direct. Industry-chain profit will continue to shift from simple PCB capacity expansion toward M8/M9 materials, Low Dk electronic glass fabric, HVLP copper foil, and high-end CCL suppliers.
Specification upgrades matter more than unit growth. The move from GB300 to VR200, Rubin Ultra, TPU 8t/8i, and Trainium 3 is not just about selling a few more boards. Layer count, low-loss materials, HDI, mSAP, and lamination yield all step up together. Commodity capacity cannot directly replace high-end capacity. The real supply question is customer qualification, yield, and material lock-in.
Company ranking depends on profit quality. WUS Printed Circuit wins on execution in switches and high-end communications PCBs. Victory Giant Technology wins on AI-server PCB capacity expansion and overseas customer elasticity. Shengyi Technology and Kingboard Laminates sit closer to upstream material pricing power. Elite Material and Taiwan Union Technology are Taiwan-listed high-end CCL representatives. Zhen Ding Technology ties together HDI, mSAP, substrates, and optical-module boards.
The biggest risk is effective supply opening up. If CCL expansion, electronic glass fabric supply, M9 qualification, and PCB capacity ramp all proceed smoothly from 2H26 to 2027, the price-hike thesis will cool. If cloud capex slows, Rubin or TPU platforms are delayed, or customers renegotiate, board-level interconnect stocks will bear valuation drawdown first. The key metrics to track are gross margin, order lock-in, and cash flow.
I. AI Servers Enter Board-Level Shortage: PCB and CCL Move From Peripheral Materials to Delivery Gates
The easiest mistake in AI hardware investing is putting every component into the same “AI server beneficiary” basket. When GPUs were short, the strongest assets were NVIDIA, HBM, TSMC advanced nodes, and CoWoS. After CoWoS targets were revised up, the market moved on to WoS, substrates, OSAT, and testing. Looking further out, what really determines whether racks can ship is the less conspicuous world of board-level interconnect and materials.
PCBs and CCLs used to be understood by the market as cyclical materials, with demand coming from communications, automotive, consumer electronics, and ordinary servers. AI servers have changed this business. The question is no longer “there are more servers, so there are more PCBs.” It is that AI racks increasingly resemble high-power, high-bandwidth, high-density electrical systems. GPU boards, CPU boards, UBBs, switch trays, all-to-all switch boards, backplanes, optical-module boards, mSAP boards, and HDI boards together determine signal integrity and system yield.
This is why board-level interconnect is moving from peripheral material to a small delivery gate. GPUs, TPUs, ASICs, and CPUs all require higher bandwidth, lower loss, and more reliable power integrity. Data-center customers are buying delivered compute, not standalone chips. If one high-layer-count PCB, one low-loss CCL material, or one copper-foil supply step cannot keep up, complete-system shipment is delayed. The value chain is shifting from “chips are expensive enough” to “systems are hard enough.”
In the previous phase, PCB discussions often centered on how large the TAM was and whether a company had AI orders. The better questions now are: what type of board is the company making, is the material grade moving up, has customer qualification penetrated the platform, is expansion locked by customers, and can price hikes show up in gross margin? Without those conditions, AI PCB is only a theme. With them, it becomes a delivery asset.
The main conclusion of this report is simple: the AI PCB and CCL cycle is not over, but the crude “buy every PCB maker” phase is over. Future excess returns will come from three types of companies. The first are PCB makers that can lock in leading AI customers and turn high-end board volume into cash flow. The second are CCL and upstream material suppliers that control M8/M9, high-end electronic glass fabric, and copper-foil materials and can raise prices directly. The third are platform suppliers that connect HDI, mSAP, substrates, optical-module boards, and other capabilities.
Full Reappraisal of AI PCB Materials: From CCL Price Hikes and Glass-Fabric Looms to the ABF Gap and Rack Upgrades
Compared with the material reappraisal in early May, two new variables have emerged. The first is the sharply increased weight of Google TPU and the ASIC chain, which means PCB/CCL is no longer just a shadow of the NVIDIA chain. The second is that supply pre-locking from 2H26 to 2027 is becoming a valuation anchor. Customers are starting to lock future capacity in advance, and material suppliers are beginning to choose AI projects with better profit.
II. Demand Side: AI-PCB TAM Expands From GPU Boards to ASICs, CPUs, Switches, and Optical Modules
The biggest change in AI-PCB demand is the broader definition. Early models mainly looked at compute boards and switch boards in GPU servers. Now CPU, ASIC servers, 1.6T switches, optical-module boards, and the future 3.2T networking upgrade all need to be included. After Citi added CPU and optical-module PCB demand into its model, the AI-PCB TAM curve was revised up materially. This is not a minor adjustment; it is a redrawing of the demand boundary.
From 2026E to 2028E, AI-PCB TAM rises from about RMB152 billion to RMB562 billion, implying a very high three-year CAGR. More important is the structure. ASIC remains the largest application in 2027E, and NVIDIA GPU remains important, but the shares of CPU, switches, and optical modules rise. This shows that PCB content value is starting to migrate with network and system architecture. By 2028E, Google TPU-related PCB procurement could exceed the NVIDIA GPU chain, and the “No. 1 customer” for board-level interconnect will no longer naturally be NVIDIA.
This table explains a fact that is often overlooked: AI PCB is not a single product. GPU boards, TPU UBBs, CPU boards, switch boards, optical-module boards, and HDI/mSAP boards correspond to different suppliers, material grades, and profit quality. Aggregating them into one TAM is useful, but investors must disaggregate them.
Google TPU is the core of the structural change. The PCB content value of Google TPU is high. The PCB content value per TPU v8/v9 is estimated at about US$1,000, and incremental demand expands rapidly in 2027E and 2028E. By 2028E, Google TPU PCB procurement could reach about US$16 billion, exceeding the NVIDIA GPU chain. This is not the old story of “ASIC replacing GPU.” It is the reshuffling of PCB/CCL profit distribution after AI clusters expand from a single GPU platform to multi-architecture platforms.
Network upgrades are another high-elasticity branch. After 1.6T optical modules and switches start, optical-module PCBs and switch PCBs may grow faster than GPU boards. The reason is simple: the larger the AI cluster, the heavier the east-west traffic. The number of switches and optical modules does not merely grow linearly with GPU count; it rises with network topology, port speed, and rack density. Board-level interconnect is moving from inside the server to the rack, the switching layer, and optical modules.
AI Network Interconnect Hardware Part I: The Value Migration Behind 1.6T/3.2T, and Who Benefits Most Across Switching, Copper Interconnect, Optical Interconnect, and the Physical Layer
This matters for A-share mapping. The core thesis for WUS Printed Circuit is not simply “AI server boards”; it is the joint driver of data-center switches, high-speed communications boards, and AI-server boards. The core thesis for Victory Giant Technology is not simple expansion, but high-layer-count multilayer boards and HDI capability entering overseas AI customers. Shennan Circuits, Guanghe Technology, Kinwong Electronic, DSBJ, and others also need to be analyzed by product category. Only by separating “GPU boards, switch boards, optical-module boards, ASIC boards, and CPU boards” can investors avoid treating all PCB companies as the same asset.
The demand-side conclusion is that AI PCB has enough room, but room does not equal profit. TAM expansion shows incremental growth in the track. Profit distribution depends on who wins customers, who locks materials, who ramps quickly, and who maintains stable yield. Before 2027E, customer competition for capacity may rerate PCB makers. After 2027E, the market will begin asking more practical questions: at what gross margin are these orders delivered, and can post-expansion cash flow materialize?
III. Specification Side: From GB300 to Rubin, TPU, and Trainium, How Board-Level Content Value Rises
The second change in AI PCB is that specification upgrades are more valuable than quantity growth. Traditional server PCBs focus on balancing layer count, materials, and cost. AI servers also need high-speed signal integrity, power integrity, thermal density, lamination yield, and system reliability. After platform upgrades, board content value does not rise evenly; it jumps on key boards.
The NVIDIA chain is a typical example. GB200/GB300 have already pushed Bianca boards, switch trays, mid-planes, and other structures toward higher layer counts and higher material grades. VR200 further raises requirements for Bianca boards and switch trays. A potential Rubin Ultra backplane could push layer count to a more extreme level. What really matters is not the number of layers itself, but that high layer count makes lamination, drilling, impedance control, low-loss materials, and yield harder at the same time.
Google TPU’s specification upgrade is more aggressive than many investors imagine. TPU v8 may move from about 22-24 layers in the prior generation to 36-44 layers, with materials moving from M7 to M8 and glass fabric also migrating toward Low Dk Gen 2. TPU v9 may also introduce more complex materials such as quartz fabric. TPU is not synonymous with “cheap ASIC,” at least in board-level interconnect. It is becoming an important driver of high-end PCB and high-end CCL.
The AWS Trainium logic is more moderate, but cannot be ignored. Trainium 2 and Trainium 3 have limited changes in area and layer count, with more of the upgrade coming from copper-foil grade. Trainium 4 is more of a longer-dated item. Its significance for PCB/CCL is less sharp than Google TPU’s, but as part of multi-ASIC customers, it proves that AI board-level demand is not a single-customer story. As long as cloud vendors continue investing across multiple paths, board-level interconnect suppliers have the opportunity to diversify risk across platforms.
CPU servers are the third line. Agentic AI and inference workloads make ordinary CPU-server demand stronger than the market originally expected. Materials are migrating from M6 to M7, but layer-count increases are less aggressive than in GPU/TPU. CPU servers act more like a base-business recovery for PCB and CCL. They may not deliver the highest gross margin, but they can absorb standard electronic glass fabric, ordinary CCL, and server-board capacity, indirectly squeezing high-end material supply.
Therefore, the specification side should be understood in three layers. The first is compute-board upgrades, centered on GPU and TPU. The second is network-board upgrades, centered on switches, optical modules, mSAP, and 1.6T. The third is CPU and general-server recovery, centered on standard materials and capacity utilization. Only when all three happen together does the situation become “high-end materials rise in price, and ordinary materials are not loose either.”
The Second Reappraisal of the AI Server Materials Chain: From Passive Components to PCB/CCL, ABF Substrates, and Test Equipment
For companies, the value of specification upgrades lies in the customer-qualification barriers they create. Ordinary PCB capacity can be expanded, but high-end AI-server boards cannot be copied immediately. Ordinary CCL can see price increases, but high-end M8/M9 materials depend on customer relationships, formulations, yield, and stable supply. The higher the product moves, the less willing customers are to switch suppliers frequently, because one board issue can affect whole-system yield and delivery.
This also explains why the market assigns higher valuations to leaders. The valuation rerating of companies such as WUS Printed Circuit, Victory Giant Technology, Elite Material, Taiwan Union Technology, and Zhen Ding Technology is not because they have “more capacity.” It is because they are more likely to obtain qualification on high-end platforms. What is truly valuable is staying on the BOM for the next-generation platform, not filling capacity on the previous-generation platform.
IV. Supply Side: PCB Expands Fastest, CCL Next, Electronic Glass Fabric Slowest; Pricing Power Is the Reverse
Strong demand does not mean every segment can raise prices. The most important supply contradiction in the PCB/CCL chain is that different segments expand at different speeds. PCB makers are the most aggressive and find it easiest to announce new plants. CCL expansion is slower, and existing sites have limited space. Electronic glass fabric and special glass fabric have longer expansion cycles and are constrained by looms, technology, and qualification. The slower the supply, the stronger the pricing power.
Citi China Materials’ conclusion is direct: supply growth is fastest in PCB, followed by CCL, while electronic glass fabric is slowest. Pricing power is the reverse, with electronic glass fabric and CCL stronger, while PCB is more about cost pass-through. This judgment is important for investing. PCB makers have large revenue elasticity, but rising material costs can erode gross margin. If CCL and electronic glass fabric suppliers can raise prices directly, their earnings elasticity may be higher than that of PCB makers.
PCB greenfield expansion usually takes about 13-15 months, from land acquisition, construction, equipment installation, and customer audit to revenue recognition. CCL greenfield projects may take about 18 months in China and longer in Southeast Asia. New electronic glass fabric capacity also takes about 1.5 years and is constrained by high-end loom supply. A 100,000-ton electronic yarn/electronic glass fabric project may require about RMB3.7 billion of investment, far higher capital intensity than ordinary roving projects.
This means that from 2H26 to 2027, the industry is not without expansion; it is that expansion is hard to arrive simultaneously. PCB makers can announce new capacity first, and customers can lock volume in advance, but if CCL, electronic glass fabric, and copper foil cannot supply in parallel, nominal PCB capacity cannot be fully converted into effective capacity. The market is now giving high-end materials higher valuations for exactly this reason.
Electronic glass fabric is the most easily underestimated segment in this round of material reappraisal. High-end special electronic glass fabric occupies more loom efficiency, squeezing ordinary 7628 electronic glass fabric capacity. At the same time, recovery in general-server demand also pulls standard electronic glass fabric. As a result, ordinary electronic glass fabric may also become tight. This structure of “high-end product consuming capacity, low-end product also rising in price” can make material-company earnings more elastic than in a traditional cycle.
The logic of tight electronic glass fabric is not that AI servers directly consume all standard fabric. It is that high-end special fabric lowers effective loom efficiency. If a Toyota loom produces standard 7628 thick fabric, annual output is high. If it is used for AI special electronic glass fabric, efficiency can fall sharply. Capacity is not the number of machines; it is effective meters. This detail is crucial because it shows that expansion announcements cannot be equated directly with supply release.
CCL supply is also close to tight balance. Major suppliers such as Elite Material, Taiwan Union Technology, Panasonic, Doosan, and Shengyi Technology have not added large amounts of effective capacity this year. Elite Material and Taiwan Union Technology output increases also depend on tool installation and ramp pace. Downstream PCB makers believe they have locked supply through the forecasts they provided last year, but if AI projects ramp intensively after 3Q, actual allocation may still be tight.
Kingboard Laminates Deep-Dive Update: AI-Fabric Pushes CCL Cyclicals Toward a Materials Bottleneck, and the Earnings Reappraisal Behind the HK$100 Target Price
The supply-side investment conclusion is: do not treat expansion as bearish, and do not treat shortage as eternal. In the short term, expansion announcements show that customers are willing to lock volume and may improve 2028E visibility. In the medium term, concentrated expansion will test prices. In the long term, only companies that can maintain gross margin and customer share after expansion are true platform assets.
V. Pricing Power: PCB Makers Earn Orders, CCL and Electronic Glass Fabric Earn Scarcity; Who Turns Price Hikes Into Profit?
This cycle requires investors to separate profit quality from “price hikes.” PCB makers can indeed raise prices, but often by passing CCL, copper foil, and electronic glass fabric price increases on to customers. Gross margin may not expand sharply. Price increases at CCL and electronic glass fabric suppliers are more direct. If supply is truly tight, their gross-margin improvement will be more visible than revenue growth.
Price signals have already appeared. M7 and below products have generally seen clear increases, low-end M4 products have risen even more, while AI-related M8 materials have risen more moderately because CCL makers still need to maintain long-term customer relationships. If supply tightens further in 2H, customers may be willing to pay premiums to secure supply, and high-end CCL pricing power will become more direct.
Elite Material is a representative of high-end CCL pricing power. Nomura expects Elite Material’s 2Q26 revenue to grow about 37% QoQ, with gross margin potentially expanding to 32.4%, while raising its target price to NT$6,880. More importantly, the CCL content opportunity from Google TPU/CPU boards and switches could account for 58% of Elite Material’s AI revenue by 2027F, up from 38% in 2026F. This shows that Elite Material is not merely following NVIDIA; it is gaining greater weight in the Google TPU chain.
Elite Material’s earnings elasticity comes from three points. First, it has large capacity and can obtain customer resources first when the industry is tight. Second, its high-end product mix is improving as the M8/M9 material share rises. Third, a multi-customer structure across Google, AWS, and NVIDIA means it is not fully dependent on a single platform. The risks are also clear: if new capacity arrives faster than expected, or if customer bargaining caps price increases, gross-margin expansion will slow.
Shengyi Technology and Kingboard Laminates represent the China material mapping. Shengyi Technology is the A-share CCL leader. The key factors are the share of high-end copper-clad laminates, AI customer qualification, sustainability of price hikes, and gross margin. Kingboard Laminates is the Hong Kong-listed representative of CCL and electronic glass fabric integration and is more able to convert upstream scarcity into profit during a material upcycle. Together they verify one question: is CCL merely a normal cyclical price hike, or is it an asset reappraisal driven by AI-server material bottlenecks?
Electronic glass fabric companies such as China Jushi provide more upstream validation. If 7628 electronic glass fabric continues to rise in price, special electronic glass fabric qualification progresses, and demand for Low CTE, Low Dk Gen 2, and quartz fabric gradually expands, it means board-level interconnect material bottlenecks are still spreading upstream. If electronic glass fabric prices stop rising, or if new entrants pass qualification quickly, the material-chain elasticity will cool.
Pricing power ultimately has to land in financial metrics. Revenue growth is the first step. Gross-margin expansion is the second. Operating cash flow and accounts-receivable control are the third. If a PCB company sees revenue surge but gross margin does not rise, receivables rise significantly, and inventory piles up, it means it merely took orders. If a material company raises prices but volume is constrained, it may only be a short-term supply squeeze. Investors should not buy just the words “price hike”; they should buy whether price hikes can penetrate the income statement and cash-flow statement.
VI. Company Ranking: WUS Printed Circuit, Victory Giant Technology, Shengyi Technology, Shennan Circuits, Guanghe Technology, and the Taiwan Material Chain Are Not the Same Opportunity
The PCB/CCL industry chain is long. Without ranking, it easily becomes a list of companies. A better approach is to stratify by “bottleneck position” and “profit quality.” For PCB makers, focus on customers and effective capacity. For material suppliers, focus on pricing power and qualification. For HDI/mSAP, focus on fine lines and optical-module boards. For equipment makers, focus on whether expansion orders are truly pulled forward. For electronic glass fabric and copper foil, focus on upstream supply constraints.
WUS Printed Circuit represents high-end communications and data-center switch PCBs. Foreign reports often refer to WUS Printed Circuit by the listed-company name; this report uses its formal securities abbreviation in English as WUS Printed Circuit. Its advantages are a solid base in data-center switches, communications boards, and AI-server-related products, a relatively balanced customer mix, and a delivery record that more easily earns a valuation premium. Citi raised its target price for WUS Printed Circuit to RMB189, driven by 1.6T switches, Google and switch demand, and 2028E capacity visibility.
Victory Giant Technology represents effective-capacity elasticity in AI-server PCBs. Its strengths are high-layer-count multilayer boards, HDI capability, and overseas customer expansion elasticity. Its valuation is more sensitive to AI-server platform timing. Citi raised its target price for Victory Giant Technology to RMB456, while also cutting part of its 2026E net-profit forecast because Rubin timing could delay some revenue. This point is important: Victory Giant Technology does not lack growth, but its growth is more dependent on customer platform timing and new-capacity ramp.
Shengyi Technology is the core A-share CCL mapping. Compared with PCB makers, Shengyi Technology is closer to the material bottleneck. The key variables are M8/M9, high-frequency high-speed copper-clad laminates, customer qualification, and gross margin. Its advantage is that material tightness can directly enter prices. The risk is that high-end share and qualification at leading overseas customers still need continuous verification. If AI-related high-end CCL price increases continue, Shengyi Technology will be reappraised from an ordinary material cyclical into a high-end material platform.
Shennan Circuits is characterized by both multilayer PCB and IC-substrate capabilities. It has a base in communications PCBs and server PCBs, as well as packaging-substrate extensions. Investors need to distinguish its profit structure across AI-server boards, BT boards, IC substrates, and traditional communications. Shennan Circuits is better viewed as a “steady platform” and should not simply be assigned the highest-elasticity PCB-maker valuation.
Guanghe Technology is a newly listed high-end PCB elasticity stock. Foreign reports often refer to Guanghe Technology by the listed-company name; this report uses its formal securities abbreviation in English as Guanghe Technology. Its opportunity lies in higher AI-server PCB dollar content and capacity expansion in Thailand/China. The risks are new-capacity ramp, customer concentration, and valuation already reflecting expectations. Guanghe Technology is more of a “new platform validation case” than a fully proven leader case.
DSBJ and Avary Holding have more integrated mappings. DSBJ has optical-module, consumer-electronics, and AI-PCB angles and cannot be valued only on PCB. Avary Holding is a consumer-electronics PCB leader migrating toward SLP, ABF, server boards, and other high-end interconnect. The core questions are whether the depreciation cycle, customer mix, and AI-business share can change its asset attributes.
Victory Giant Technology Deep Dive: AI PCB Enters the Era of Effective Capacity, and How Victory Giant Moves From PCB Maker to Server Delivery Asset
In ranking terms, WUS Printed Circuit and Victory Giant Technology represent two paths for A-share PCB makers. WUS Printed Circuit is more like an “execution asset for high-end switches and AI-server boards.” Victory Giant Technology is more like an “effective-capacity elasticity asset for AI-server PCB.” The former depends more on stable delivery and customer mix. The latter depends more on capacity-expansion execution and platform timing. Both benefit from AI PCB TAM expansion, but their entry points and risks differ.
Shengyi Technology, Kingboard Laminates, Elite Material, and Taiwan Union Technology represent four paths on the material side. Shengyi Technology is an A-share high-end CCL platform. Kingboard Laminates is Hong Kong-listed material integration. Elite Material is the Taiwan-listed high-end CCL leader. Taiwan Union Technology is a higher-elasticity high-end CCL name. The common question for the material side is whether price increases can continue, whether customers will accept premiums, and whether new capacity will quickly dilute scarcity.
Zhen Ding Technology offers another platform opportunity. It is neither a pure CCL maker nor a single PCB maker, but combines ABF substrates, AI PCB/HDI, mSAP, and optical-module boards. Nomura raised its target price for Zhen Ding Technology to NT$720, citing IC-substrate sales growth, a doubling of server/optical-communications sales, 2026E capex guidance raised above NT$80 billion, and ramps in VR200 Bianca HDI boards and Google switch boards. Its value lies in multiple board-level bottlenecks materializing together. Its risk is also higher capex and execution complexity.
VII. Value-Chain Pass-Through: Five Profit Pools Behind One AI Board
The most underestimated aspect of AI PCB/CCL is that profit does not stop with PCB makers. Customers procure deliverable AI servers, switches, and optical modules, but this chain allocates value to five segments: PCB makers earn premiums from area, layer count, and yield; CCL makers earn premiums from low-loss materials; electronic glass fabric and copper foil earn premiums from upstream scarcity; HDI/mSAP makers earn premiums from fine lines; and equipment makers receive front-loaded expansion orders. Every segment benefits from AI, but financial elasticity is completely different.
The first profit pool is PCB makers. Its revenue elasticity is the most visible because customer orders ultimately land at PCB makers, and expansion announcements are easiest for the market to see. WUS Printed Circuit, Victory Giant Technology, Shennan Circuits, Guanghe Technology, Kinwong Electronic, DSBJ, and Avary Holding can all capture this demand from different angles. The issue is that PCB makers bear material price hikes, yield ramp, and capex pressure, so revenue growth does not necessarily mean margin expansion. To earn a high valuation, a PCB maker must prove that it has obtained high-end qualified capacity, not low-margin contract-manufacturing capacity.
The second profit pool is CCL makers. CCL is not an ordinary material; it is the foundation for high-speed signal transmission. As AI servers move from M7 to M8, M9, and even higher-end combinations such as PTFE and M9Q, material formulations, loss control, stability, and customer qualification all become barriers. The value of companies such as Elite Material, Taiwan Union Technology, Shengyi Technology, and Kingboard Laminates comes from whether they can translate material-grade upgrades into ASP and gross margin. PCB makers can expand faster, but if high-end CCL is insufficient, the capacity they expand is only partially effective.
The third profit pool is electronic glass fabric and copper foil. Electronic glass fabric determines the CCL skeleton, while copper foil determines high-speed signal and power integrity. Neither is short-cycle capacity. The special feature of electronic glass fabric is that high-end Low Dk, Low CTE, quartz fabric, and other products reduce effective loom efficiency and squeeze standard 7628 electronic glass fabric. The special feature of copper foil is that HVLP3, HVLP4, and higher-grade products must pass customer qualification and yield validation. If electronic glass fabric and copper foil remain tight from 2H26 to 2027, material-side profit will be harder than PCB-maker profit.
The fourth profit pool is HDI and mSAP. AI servers appear to be a large-board business, but 1.6T optical modules, switch boards, Bianca HDI boards, and high-density connections are bringing fine-line capability into the data center. The core reason Zhen Ding Technology is back in focus is not that it suddenly became a single AI-board maker. It is that it has put HDI, mSAP, substrates, optical-module boards, and automation experience into one delivery capability. As future AI servers move further toward high-density systems, HDI/mSAP is more likely to migrate from a consumer-electronics capability into a data-center capability.
The fifth profit pool is equipment and process capability. PCB equipment, drilling, lamination, exposure, electroplating, inspection, automation, and yield control will all be pulled forward by expansion. China PCB-equipment materials repeatedly emphasize that capacity squeeze and high-end penetration will support fundamentals. The reason is here: customers lock capacity first, manufacturers then lock equipment, and equipment and process companies receive expansion orders early. But the equipment-side risk is also clearer. Once expansion slows, order visibility changes faster than material prices.
This table also explains why valuation methods cannot be the same even though all of this is called AI PCB. PCB makers should be validated through revenue, orders, gross margin, and cash flow. CCL makers should be validated through ASP, high-end mix, and capacity utilization. Electronic glass fabric and copper foil should be validated through prices, lead times, and special-material qualification. HDI/mSAP should be validated through optical-module boards, fine-line yield, and customer migration. If all these segments are compared using one PE multiple, investors can easily buy the hottest stock while missing the area with the hardest profit.
Value-chain pass-through has another implication: PCB makers and material suppliers are not simply upstream and downstream players bargaining against each other. They jointly participate in customer delivery. To ensure platforms come online, leading cloud vendors will care simultaneously about PCB, CCL, electronic glass fabric, copper foil, and key equipment. They may directly participate in supply-chain capacity lock-in, and even book 2027-2028 capacity in advance. This reduces some cyclical volatility, but also makes suppliers more dependent on a small number of large customers. The stronger the lock-in, the steadier near-term earnings; the more concentrated the customer base, the higher the medium-term bargaining risk.
Therefore, AI PCB/CCL investing should not only ask “which company raises prices the most.” Better questions are: are price increases coming from specification upgrades or short-term squeezes, how much capex is covered by customer lock-in, for how many quarters can gross-margin improvement continue, can high-end share be maintained after expansion, and does cash flow improve along with profit? Companies that can answer all these questions will move from cyclical manufacturing into AI infrastructure assets.
VIII. From Orders to Cash Flow: Five Tables to Verify in AI PCB Phase Two
In the first phase of AI PCB, investors looked at orders. In the second phase, they must look at cash flow. The reason is simple: high-end PCB and CCL expansion require capital. Customer lock-in is not the same as profit in hand, and price increases are not the same as improved cash flow. If investors only look at orders, a company can become a manufacturing asset with “revenue growth but cash-flow pressure.” Only when orders, gross margin, receivables, inventory, and capex efficiency improve together does it become a real platform asset.
The first table is the customer lock-in table. Investors need to see whether customers are moving from forecasts to LTAs, whether they are booking 2027-2028 capacity in advance, and whether they are willing to pay premiums for material supply. The clearer the customer volume lock, the lower the expansion risk. If expansion is only announced by the company without customer commitment, valuation should be discounted.
The second table is the product-mix table. Investors need to see the revenue share of M8/M9, HVLP4, HDI, mSAP, high-layer-count boards, optical-module boards, and AI-server boards. Ordinary server boards and high-end AI boards can both be called “AI-related,” but their gross margins are completely different. When product mix is unclear, investors should not assign high-end bottleneck valuations.
The third table is the gross-margin table. Price hikes ultimately need to be judged by gross margin. If material price increases are only cost pass-through, PCB-maker revenue will grow, but gross margin may not expand. If the share of high-end materials and high-end boards rises, gross margin should improve. Elite Material, Zhen Ding Technology, Shengyi Technology, Victory Giant Technology, and WUS Printed Circuit all need to be tested by gross margin.
The fourth table is the capex and effective-capacity table. AI PCB expansion is not only about the capex amount. Investors also need to track construction cycle, equipment arrival, customer audit, yield ramp, and revenue recognition. Zhen Ding Technology raised its 2026E capex guidance to more than NT$80 billion, showing the industry’s willingness to invest. But the market ultimately needs to see whether this capex becomes high-margin revenue.
The fifth table is the receivables and inventory table. AI customers are powerful, orders are large, and delivery is complex, all of which can easily create receivables and inventory pressure. If revenue and profit both grow but operating cash flow does not improve in step, order quality needs to be questioned. A truly high-quality AI hardware asset should deliver customer lock-in, price pass-through, and cash flow together.
This validation checklist also explains why the trading cadence differs by stock. WUS Printed Circuit is better tracked through quarterly gross margin and switch/AI-server orders. Victory Giant Technology is better tracked through effective capacity and customer-platform ramp. Shengyi Technology is better tracked through high-end CCL prices and product mix. Kingboard Laminates is better tracked through ASP and electronic glass fabric. Zhen Ding Technology is better tracked through capex conversion, HDI, and mSAP revenue.
AI PCB From Material Reappraisal to Profit Delivery: Shennan 30+ Layer MLPCB, Taiwan Union High-End CCL, Kingboard Material Integration, Nan Ya PCB and Unimicron ABF Substrates, and Who Books Price Hikes First
The phase-two market will not reward “having a story” alone. If a company says it has AI orders, but product mix is unclear, gross margin does not improve, capex is heavy, and customer concentration is high, share-price gains will be hard to sustain. Conversely, if a company does not tell many stories but gross margin, customer qualification, and cash flow continue improving, the market will rerate it.
IX. Three Scenarios: Continued Price Hikes, Effective Supply Opening, and Platform Timing Delays
The future AI PCB/CCL cycle can be divided into three scenarios. The first is continued price hikes, where demand remains strong, materials remain tight, customers are willing to pay premiums, and both PCB makers and material suppliers continue revising earnings upward. The second is effective supply opening, where PCB, CCL, electronic glass fabric, and copper-foil expansion proceed better than expected, price hikes slow, and profit elasticity falls. The third is platform timing delays, where Rubin, TPU, Trainium, or 1.6T switch ramps miss expectations, orders are delayed, and valuations retreat first.
The base case still leans toward continued price hikes. The reason is not infinite demand strength, but the simultaneous pull from multiple platforms from 2H26 to 2027: Google TPU 8t/8i, NVIDIA VR200/Rubin, AWS Trainium 3, 1.6T switches, optical-module boards, and CPU-server recovery. Demand presses on PCB, CCL, electronic glass fabric, copper foil, and HDI at the same time, while supply is hard to release in an orderly way.
But the second scenario cannot be ignored. As long as customers lock volume in advance, suppliers will expand. As long as valuations are high enough, new capacity and new entrants will accelerate. AI PCB and CCL are not natural monopolies that cannot expand. They simply have long expansion cycles, slow qualification, and difficult yield. Investors should watch one timing point carefully: when the market shifts from “supply will always be tight” to “effective supply is being released,” high-valuation material stocks will be compressed first.
The third scenario is platform timing delay. If Rubin is delayed further, revenue recognition for some PCB makers will move later. If Google TPU production plans change, chains including Elite Material, WUS Printed Circuit, Victory Giant Technology, and Zhen Ding Technology will be affected. If 1.6T switch deployment misses expectations, elasticity in optical-module boards and mSAP will decline. Platform delays do not mean demand disappears, but they change the timing of earnings recognition.
Therefore, the best portfolio is not a one-way bet. High-certainty assets such as WUS Printed Circuit and Elite Material can form the base. Elastic assets such as Victory Giant Technology, Zhen Ding Technology, and Guanghe Technology can provide offense. Material-side assets such as Shengyi Technology, Kingboard Laminates, and China Jushi can express upstream scarcity. Platform companies such as Shennan Circuits, DSBJ, and Avary Holding can capture broader interconnect migration.
X. Valuation and Target Prices: Do Not Reduce a High-Prosperity Industry to One Multiple
The valuation challenge for AI PCB/CCL is that different segments all look like beneficiaries, but the market gives them multiples for different reasons. PCB-maker multiples come from high-end customers and order certainty. Material-supplier multiples come from price pass-through and supply scarcity. HDI/mSAP platform multiples come from capability migration. Equipment-side multiples come from the expansion cycle. Ranking companies only by “AI-related revenue share” misreads both risk and return.
The valuation core for WUS Printed Circuit, Victory Giant Technology, and Guanghe Technology is whether AI revenue can continue being revised upward. Foreign target-price upgrades show that the market is starting to incorporate 2027-2028 board-level demand into models, but these target prices cannot be compared directly across companies. Report dates, customer definitions, profit assumptions, capacity ramps, and risk premiums all differ. A more reasonable approach is to ask where the earnings upgrade behind the target price comes from: revenue revision, gross-margin revision, or valuation-multiple revision.
Material-stock valuation is more like a margin-sensitivity question. The upgrade to Elite Material’s target price is centered on 2027F EPS and repriced high-end CCL demand. The reappraisal of Kingboard Laminates and Shengyi Technology also depends on whether AI-material price hikes enter gross margin. If only low-end CCL and ordinary electronic glass fabric are rising in price, valuation should remain more cyclical. If M8/M9, Low Dk, Low CTE, and high-end copper foil form sustained qualification barriers, valuation has room to become more platform-like.
Zhen Ding Technology’s valuation is more of a platform reappraisal. Nomura raised Zhen Ding Technology’s target price not only because of AI PCB, but also because of IC substrates, optical-module boards, HDI/mSAP, and long-term customer agreements. Its risks are also more complex: capex is large, product lines are numerous, and any ramp issue in one segment can affect profit delivery. The greatest risk for platform companies is “many narratives, dispersed profit.” The best validation is multiple new businesses contributing gross margin and cash flow at the same time.
The most important valuation dividing line is when the market moves from “valuing orders” to “valuing profit delivery.” In 2025-2026, orders, customers, capacity, and target-price upgrades are enough to push share prices. Starting in 2027, the market will increasingly care about gross margin, cash flow, and utilization of new capacity. Companies that can continue revising profit upward after this turning point will be able to maintain high valuations.
This is also why this report emphasizes ranking rather than only listing beneficiaries. WUS Printed Circuit and Victory Giant Technology both benefit from AI PCB, but the former depends more on stable delivery of switches and high-end communications boards, while the latter depends more on AI-server boards and new-capacity ramp. Shengyi Technology and Kingboard Laminates both benefit from CCL price hikes, but the former is an A-share high-end material platform and the latter is material integration with Hong Kong-listed valuation recovery. Elite Material and Taiwan Union Technology both benefit from high-end CCL, but the former has stronger capacity and customer mix, while the latter has higher elasticity.
Valuation risks also need to be written clearly in advance. First, if effective supply of high-end CCL and electronic glass fabric is released in 2027, material-stock gross-margin assumptions will be revised down. Second, if Rubin, Google TPU, or 1.6T switches are delayed, revenue recognition for PCB makers will move later. Third, if cloud capex shifts from “rushing for supply” to “pressing costs,” customer bargaining power will strengthen again. Fourth, if company capex is too fast, depreciation and cash-flow pressure will arrive before revenue release.
Therefore, AI PCB/CCL is not a sector that can be explained indefinitely by high multiples alone. Its valuation rerating comes from real bottlenecks, and its valuation pullback will also come from real supply. Good investment judgment should acknowledge two things at the same time: near-term scarcity remains real, and the long-term cycle has not disappeared. Only by putting both into the model can investors avoid treating cyclicals as perpetual growth stocks at the hottest point of the cycle, or missing high-end platforms that can truly cross the cycle during corrections.
XI. What to Track Over the Next Four Quarters: Do Not Wait for Financial Reports to Decide
AI PCB/CCL tracking cannot rely only on annual reports. Over the next four quarters, each quarter has different validation points. In 3Q26, watch whether Google TPU, VR200, and Trainium 3 truly drive material allocation. In 4Q26, watch whether price pass-through continues and whether high-end CCL gross margin improves. In 1H27, watch whether new capacity can pass customer qualification. In 2H27, watch whether supply opening suppresses prices.
Several indicators are easy to misread. First, upward capex revisions are not necessarily positive. Without customer lock-in, capex becomes depreciation pressure. Second, gross margin failing to rise is not necessarily immediately negative. If a company is in a new-capacity ramp phase, investors need to watch subsequent utilization. Third, inventory increases are not necessarily bad. High-end material stocking and customer lock-in may create phased inventory increases, but if receivables rise at the same time and cash flow deteriorates, investors need to be alert.
Historically, PCB and CCL have both been cyclical industries prone to overheating. AI changes demand quality and specification thresholds, but it does not eliminate the manufacturing cycle. The real differences are that the upcycle driver this time comes from data-center infrastructure, not phone or PC inventory; supply constraints come from customer qualification and high-end materials, not insufficient ordinary capacity; and valuation divergence comes from profit quality, not simple revenue growth.
This is also why investors need to separate “AI demand is strong” from “share prices can keep rising.” Strong demand is an industry judgment. Continued share-price gains require companies to deliver profit, the market to keep revising upward, and valuation to still have room. If any one of the three is missing, share prices may correct first even if the industry trend has not changed.
XII. Falsification Checklist: When Board-Level Interconnect Enters the Second Half
The most important falsification signal for AI PCB/CCL is not a one-day share-price decline, nor one institution cutting a target price. It is the industry chain moving from “scrambling for supply” to “competing on cost.” As long as customers are still scrambling for qualified capacity, M8/M9 materials, electronic glass fabric, and high-end copper foil, the industry is still in the profit-upgrade phase. Once customers start pressing prices again, suppliers start competing for orders, and expanded capacity starts proactively searching for demand, the cycle enters the second half.
The first falsification signal is prices failing to rise. CCL and electronic glass fabric prices are the most direct thermometers. If prices for M7 and below stop rising, M8/M9 price hikes cannot land, Low Dk and Low CTE electronic glass fabric lead times shorten, and customers no longer accept premiums for HVLP copper foil, material tightness is easing. PCB makers may still see revenue growth, but material-side valuations need to be revised down, and PCB-maker gross margins will face customer renegotiation.
The second falsification signal is gross margin no longer expanding. If AI orders are truly moving high-end, gross margin should at least stabilize or improve. If PCB-maker revenue grows quickly but gross margin declines continuously, order quality may be weaker than headline revenue suggests. If CCL ASP rises but gross margin does not, raw materials, capacity utilization, or price concessions are eating profit. If HDI/mSAP platform revenue rises but depreciation pressure arrives faster, capability migration has not yet entered profit delivery.
The third falsification signal is weakening customer lock-in. Current optimistic expectations are built on 2027-2028 capacity being booked in advance and leading customers being willing to participate in supply-chain lock-in. If customers change long-term orders into short orders, convert dedicated lines into flexible procurement, or delay previously committed capacity occupancy, supply-demand conditions are loosening. PCB makers and material suppliers may continue shipping, but valuation should move from bottleneck-asset valuation back toward manufacturing-asset valuation.
The fourth falsification signal is repeated platform delays. A delay in one platform can be offset by others, but multiple platforms slowing at the same time requires a reassessment of the demand curve. Delays in Rubin Ultra, Google TPU v9, subsequent Trainium platforms, 1.6T switches, or optical-module boards are not fatal individually. If these lines all move later at the same time, the annual cadence of AI-PCB TAM will flatten, and both PCB-maker expansion and material-supplier price hikes will face delivery pressure.
The fifth falsification signal is capex becoming depreciation pressure. In this AI PCB/CCL cycle, higher capex is itself evidence of strong supply-demand conditions, but capex also becomes future cost. If new plants pass customer qualification slowly, yield ramps slowly, and utilization is low, depreciation enters costs before revenue and profit arrive. At that point, the most dangerous setup is valuation already pricing full utilization and high gross margin, while the financial statements deliver only depreciation.
The sixth falsification signal is deteriorating cash-flow quality. The value of high-end manufacturing orders ultimately depends on operating cash flow. If a company stocks up early for delivery to large customers, a phased inventory increase is understandable. If receivables, inventory, and capex all rise while operating cash flow clearly lags profit, pricing power is weaker than imagined. The biggest risk for AI hardware companies is strong accounting profit and slow cash collection, because the market will reapply a manufacturing discount.
Conversely, if these falsification signals do not appear, the cycle should not end too early. As long as high-end material allocation remains tight, customers continue locking capacity in advance, material-side gross margins continue improving at Elite Material, Shengyi Technology, Kingboard Laminates, and others, and board-level suppliers such as WUS Printed Circuit, Victory Giant Technology, and Zhen Ding Technology continue turning orders into cash flow, the market will continue assigning higher valuations to AI PCB/CCL. The real question is not whether the industry has room, but whether each company can capture profit within that room.
In trading cadence, this theme can be divided into three phases. The first is TAM and order revisions, where share prices mainly reflect “how much demand exists.” The second is price and gross-margin validation, where share prices mainly reflect “who turns demand into profit.” The third is expansion delivery and supply release, where share prices mainly reflect “who can cross the cycle.” The industry is now moving from the first phase toward the second. Some companies have already been priced for the second phase, but third-phase risks have not been fully incorporated into models.
This is why this report prefers a framework of “qualified capacity and profit delivery.” Discussing only demand underestimates material-side price hikes. Discussing only price hikes overestimates cycle durability. Listing only company names ignores customer mix and yield. Valuable research connects demand, specifications, supply, pricing, financials, and falsification into one chain. AI PCB and CCL still deserve a standalone deep dive precisely because they are no longer fringe items in the larger AI-server chain, but have begun to develop their own investment cadence.
XIII. Conclusion: The Main Line for AI PCB and CCL Is Not Expansion, but Qualified Capacity and Profit Delivery
The main line for AI PCB and CCL can be summarized in one sentence: the more concentrated compute becomes, the more board-level interconnect looks like infrastructure; the more complex racks become, the more high-end materials look like delivery rights. GPUs, TPUs, CPUs, switches, optical modules, power, and cooling all require higher-quality boards and materials, turning PCB and CCL from cyclical supporting roles into small gates determining whether AI servers can come online.
But this main line is not simple expansion. What is truly valuable is qualified capacity, customer lock-in, yield, material grade, and price pass-through. Ordinary capacity can be expanded, but high-end effective capacity has to pass customer audits. Ordinary price hikes can pass through, but high-end material price hikes need to enter gross margin. Ordinary orders can be canceled, while long-term locked volume is what supports capex. Investors must see these differences clearly.
For A-shares, WUS Printed Circuit, Victory Giant Technology, Shengyi Technology, Shennan Circuits, Guanghe Technology, DSBJ, Avary Holding, and others all map to AI PCB, but in completely different ways. WUS Printed Circuit leans toward switches and high-end communications PCBs. Victory Giant Technology leans toward effective capacity in AI-server PCBs. Shengyi Technology leans toward high-end CCL materials. Shennan Circuits leans toward a steady platform and IC substrates. Guanghe Technology leans toward new-capacity elasticity. DSBJ and Avary Holding lean toward integrated interconnect platforms. Treating them as the same sector misses the most important profit differences.
For Hong Kong and Taiwan equities, Kingboard Laminates, Elite Material, Taiwan Union Technology, Zhen Ding Technology, China Jushi, and others provide more upstream or more platform-oriented perspectives. Elite Material and Taiwan Union Technology validate high-end CCL price hikes. Kingboard Laminates validates material integration. China Jushi validates electronic glass fabric supply. Zhen Ding Technology validates platformization across HDI, mSAP, optical-module boards, and substrates. They are important references for understanding A-share mapping.
The real risk is treating every bottleneck as permanently scarce. As long as customers are willing to pay premiums, suppliers will expand. As long as valuations are high enough, new entrants will accelerate qualification. As long as platform timing is delayed, orders will be re-ranked. The good business in AI PCB and CCL is that near-term tightness is real. The difficulty is that companies must keep proving over the long term that they are not ordinary cyclicals.
The best question for the next phase is not “who has AI orders,” but “whose AI orders can pass through material lock-in, customer qualification, yield ramp, gross-margin improvement, and cash recovery.” Companies that can pass through this chain will move from PCB makers or material suppliers into AI infrastructure delivery assets. Companies that cannot will only shine briefly in theme-driven rallies. AI servers are still expanding, but the market has already started rewarding finer research.
At the tracking level, investors should divide this main line into four accounts: the order account, the material account, the capacity account, and the cash-flow account. The order account tracks cloud-platform production schedules and long-term lock-in. The material account tracks M8/M9, electronic glass fabric, and HVLP copper-foil prices. The capacity account tracks new-plant qualification and yield. The cash-flow account tracks receivables, inventory, and operating cash flow. When all four accounts improve together, the reappraisal continues. If only orders improve while the other accounts do not keep up, share prices will behave more like theme volatility.
This is also why this report separates PCB, CCL, electronic glass fabric, copper foil, HDI, and mSAP for a standalone discussion. They are no longer small attachments to the AI-server theme, but important variables for judging the quality of compute delivery in 2027. GPUs and advanced packaging answer the question, “Are there enough compute chips?“ PCB and CCL answer the question, “Can complete systems come online on time?” As the market moves from buying chip shortages to buying system delivery, board-level interconnect must be priced separately.
The final conclusion remains measured: AI PCB and CCL are still in the middle of an upward cycle, with tight near-term supply, rapid specification upgrades, strong customer lock-in, and room for further profit revisions. But this is not perpetual scarcity. Expansion, platform timing, and customer bargaining will eventually re-enter the model. The companies that can cross the second half are not those that tell the best AI story, but those that can deliver qualified capacity, material barriers, and cash flow together.