
AI Hardware Restocking Deep Dive: Capacitors Hit New Highs, Nearline HDD Capacity +31% YoY, Enterprise SSD Capacity +139%, and How Data-Center Demand Is Spreading Into Components and Storage
目录
Too Long; Didn't Read
1. This Restocking Is Not a Broad Demand Rebound, but AI Hardware Spreading Into Second-Line Bottlenecks
2. Record-High Capacitors Show AI Servers Are Starting to Pressure High-Value-Added Passive Components
3. Connectors Are Not Yet the Main Line, but They Are the Thermometer for Whether AI Server Diffusion Is Real
4. On the Storage Side, Capacity Matters More Than Units
5. TDK's Logic Is Stability, Not the Fastest Beta
6. Why HDD and SSD Can Both Be Strong
7. Regional Signal: This Is Not a Normal Consumer-Electronics Recovery, but China and the Data-Center Chain Moving First
8. The Core Tension in MLCC: Not Whether Capacitors Exist, but Who Can Supply High-Reliability Part Numbers
9. TDK and the HDD Chain: Slow Variables May Matter More Than Fast Beta
10. The Change in Enterprise SSD: QLC Is Not Low-End Substitution, but a Rewrite of Capacity Economics
11. Three Worldviews: What Is This Trade Really Betting On?
12. Valuation Discipline: After Strong Data, the Biggest Risk Is Buying Every Company as the Same AI Asset
13. How to Validate Over the Next Four Quarters
14. Company and Link Breakdown: Which Looks Like Beta, Which Looks Scarce, and Which Is Only Cycle Repair
15. Risks and Falsification: Which Signals Would Show This Is Not AI Second-Line Diffusion
16. The Right Way to Read These Two Reports: Do Not Look Only at YoY, Look at Where the Bottlenecks Are
17. Data Definitions: Why the Same Numbers Can Lead to Different Conclusions
18. The Investment Framework From This Report: Data First, Valuation Second
19. Three Judgments: Second-Line AI Hardware Diffusion Is Not Over
20. Conclusion: AI Capex Is Moving From "Buying Chips" to "Building Out Systems"
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This AI hardware restocking cycle has continued to spill over from GPUs, HBM, and PCBs into lower-level electronic components and storage capacity. April capacitor shipments reached another record, while May nearline HDD and enterprise SSD capacity both accelerated, showing that data-center demand is still spreading along three links: power delivery, interconnect, and data retention.
Too Long; Didn't Read
AI demand is moving down the stack. In April, Japanese suppliers' global electronic-component market was not broadly hot, but capacitor shipments reached JPY 167.6bn, up 20% YoY. The real strength is the component mix upgrade driven by servers, AI power, and high-density computing.
Capacitors are stronger than the overall market. Total electronic-component shipments weakened MoM, but passive components, capacitors, connectors, and inductors jointly supported structural growth. MLCC ceramic electrode materials recovered 8% MoM, meaning the debate has shifted from destocking to whether supply tightness is widening.
For storage, watch capacity, not unit volumes. HDD units recovered only modestly in May, but nearline HDD capacity output rose 31% YoY. Cloud vendors are buying larger capacity and longer data retention, not simply more drives. The next variable to watch is whether nearline average capacity can stay above 23TB.
Enterprise SSD is stronger. Enterprise/data-center SSD capacity output rose 139% YoY, and high-capacity SSD demand was described as unprecedented. QLC is entering higher-capacity tiers, and NAND value is being repriced by AI inference and data retention.
Company ranking needs layers. Murata Manufacturing and Taiyo Yuden map more directly to AI server MLCCs; Hirose Electric benefits from a mild connector recovery; TDK is exposed at the same time to HDD heads/suspensions, aluminum capacitors, and medium-sized batteries. In the short term, share prices may rotate between high-beta MLCC and steady-growth TDK, but in the medium term the key question is who controls high-value-added capacity.
The falsification points are clear. Watch four numbers: whether capacitor shipments keep growing on a dollar basis, whether connectors move from mild recovery into a trend upturn, whether nearline HDD average capacity remains above 23TB, and whether the enterprise/data-center SSD capacity share keeps rising from 20.3%. If all of these slow at the same time, the second-line AI hardware diffusion trade should cool.
1. This Restocking Is Not a Broad Demand Rebound, but AI Hardware Spreading Into Second-Line Bottlenecks
Putting monthly electronic-component and storage data side by side makes the conclusion clearer than looking at either report alone: the AI hardware trade is moving from "who sells GPUs and HBM" to "who supports the long-term operation of GPU racks."
April electronic-component data was not perfect. Total shipments from major Japanese electronic-component suppliers weakened MoM, and the dollar-basis series did not expand in tandem. Looking only at the aggregate, this was not a broadly hot electronics cycle.
But the structure was completely different. Passive components, capacitors, and connectors all clearly outperformed the overall market. The real drag came from other items within connection components, conversion components, and other electronic components, not from the high-value-added components most sensitive to AI servers.
That is the biggest difference between this hardware cycle and a traditional consumer-electronics restocking cycle. Traditional restocking usually starts with simultaneous improvement in smartphones, PCs, and consumer-electronics end devices, then spreads upstream into components. The AI hardware cycle is the opposite: it starts with compute chips, HBM, CoWoS, PCBs, and power systems, then transmits order pressure to MLCCs, inductors, connectors, HDD heads, SSD capacity, and NAND supply.
Second Upward Revision in the AI Hardware Cycle: Repricing Asian Tech Across Storage, HBM, PCB, and MLCC
In other words, not every electronic component has suddenly improved. Instead, AI data centers are pushing a group of formerly "supporting-role" components to the front. Capacitors support high-density power stability, connectors support high-speed interconnect reliability, and HDDs and SSDs support training data, inference logs, enterprise data, and cold/warm data retention. They are not the same product, but they answer the same question: after compute capex is deployed, where do system bottlenecks continue to emerge?
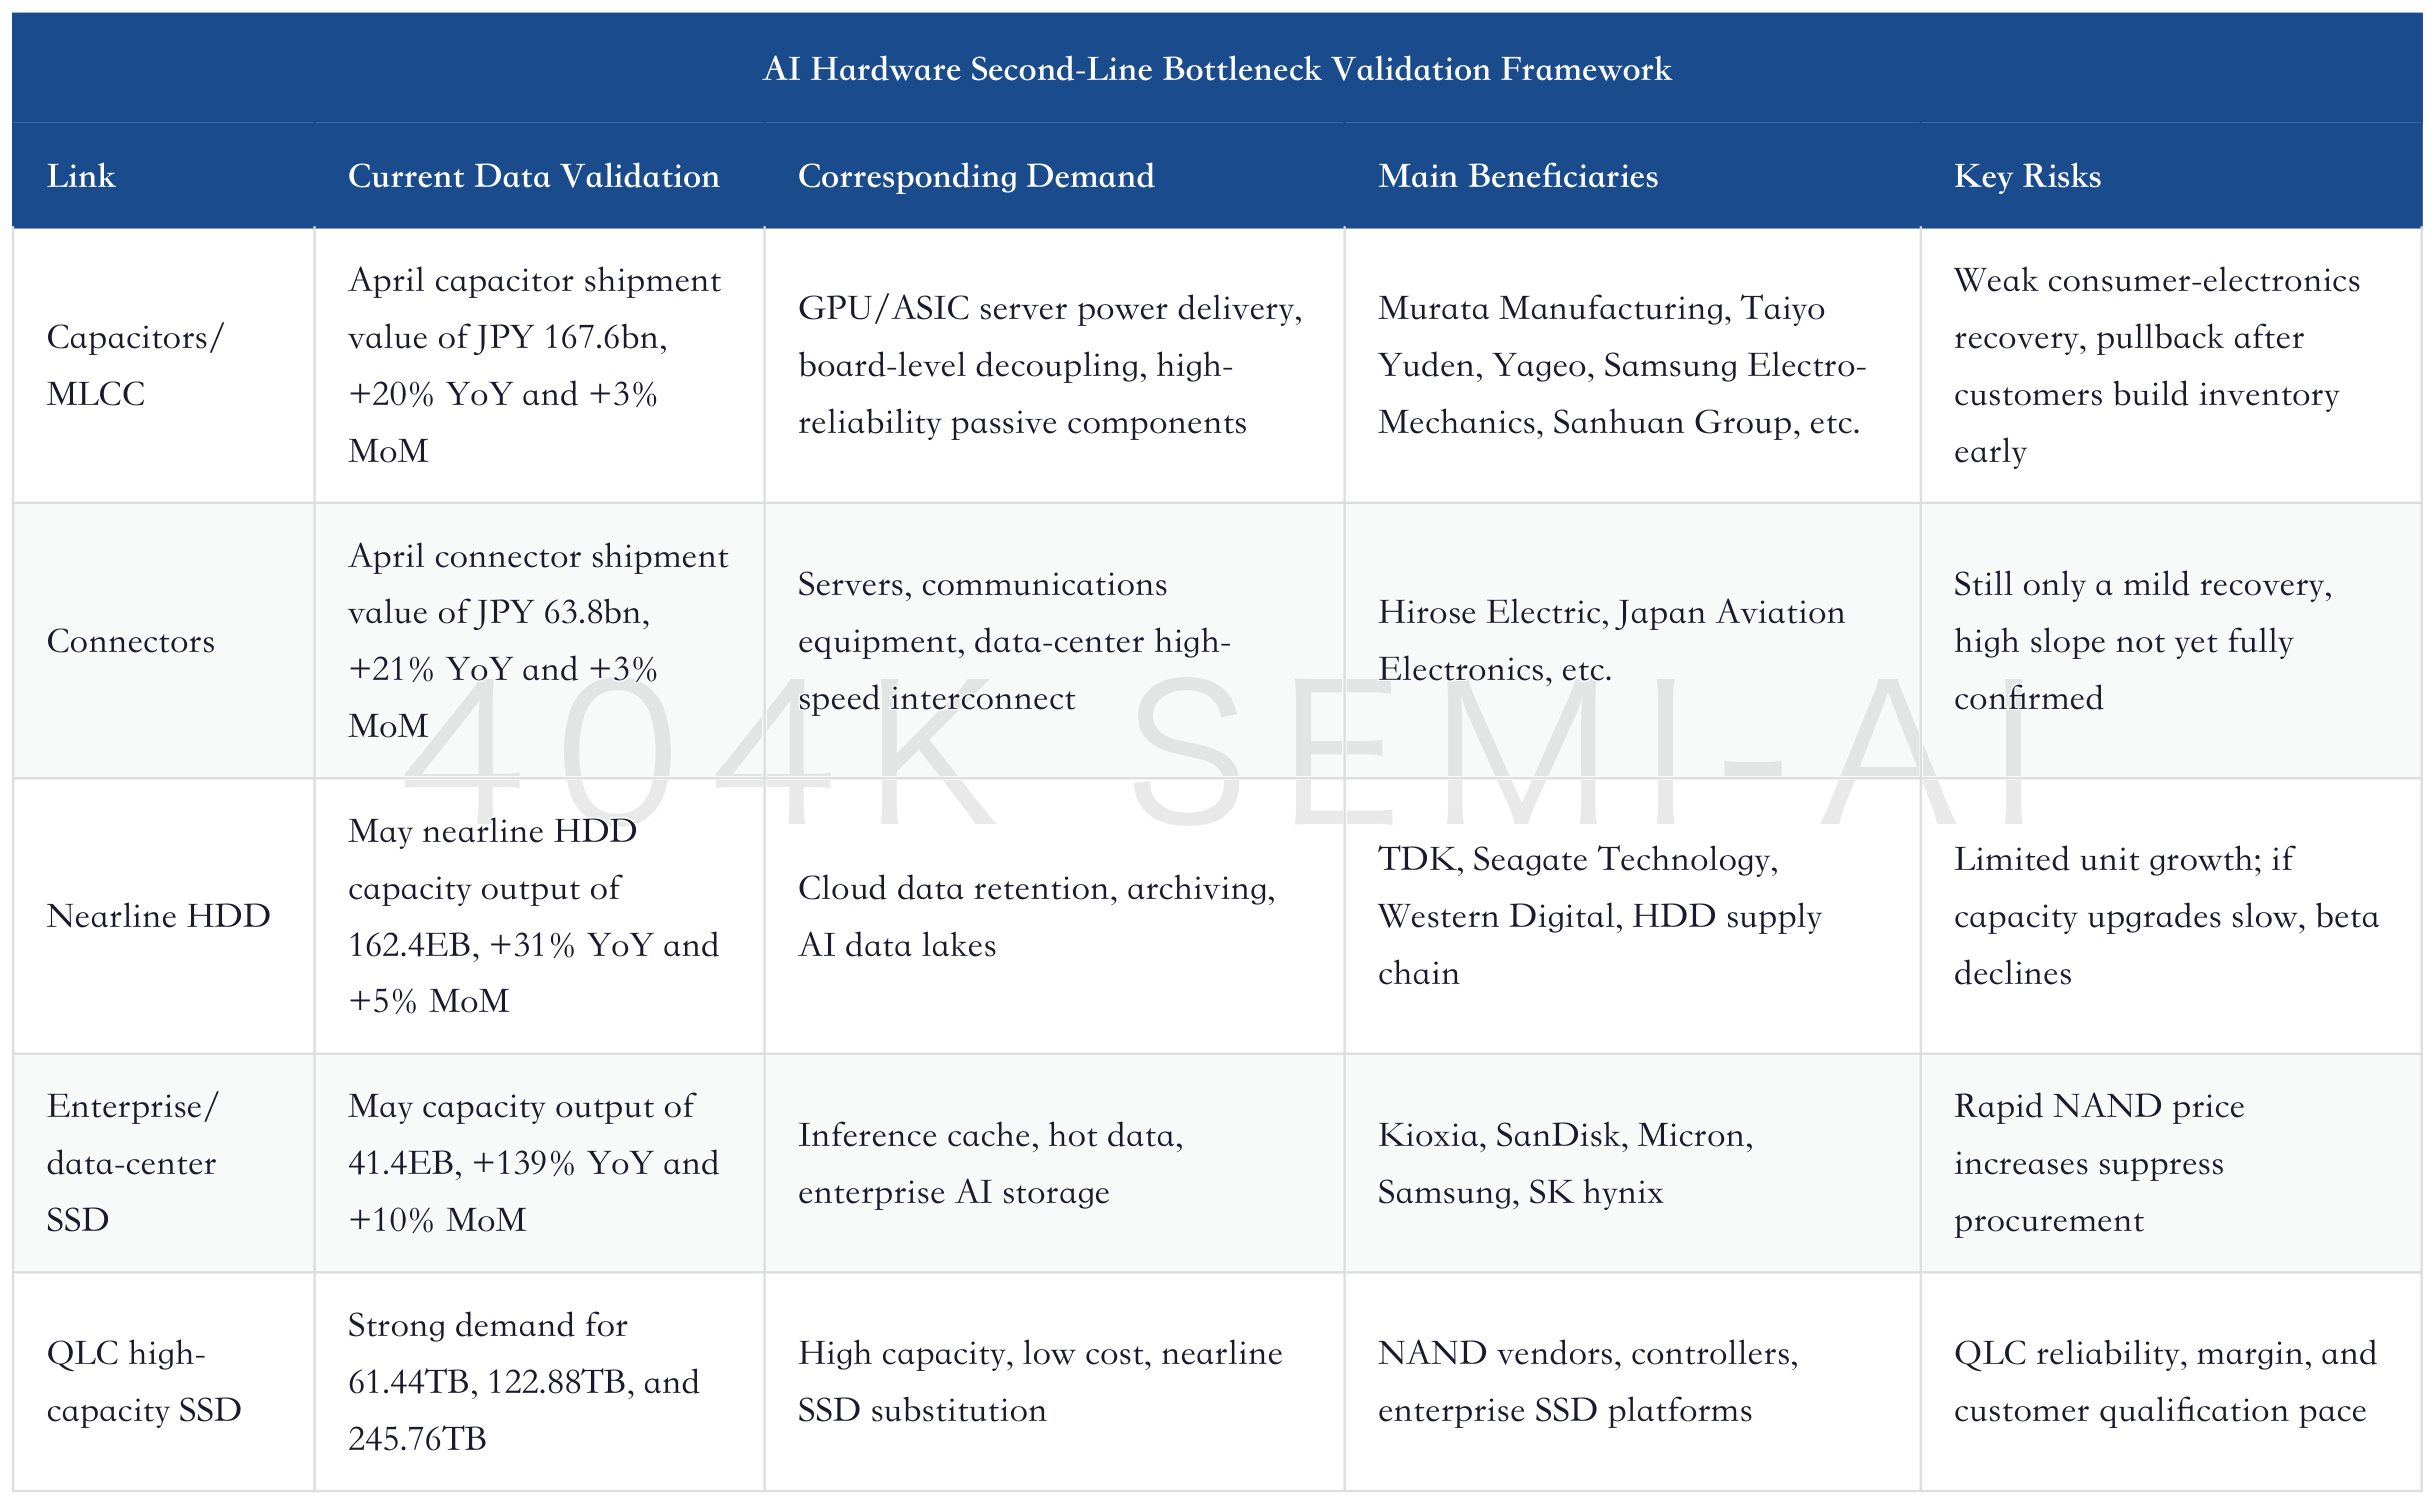
The point of this table is not to argue that every link is equally strong. It is to clarify the validation sequence. MLCCs and capacitors are the strongest line in the current data; nearline HDD and enterprise SSD are the clearest line in capacity growth; connectors are recovering, but their slope still needs confirmation from more months of data.
2. Record-High Capacitors Show AI Servers Are Starting to Pressure High-Value-Added Passive Components
Capacitor data deserves the most attention because it continued to make new highs even as total electronic components declined MoM.
In April, capacitors continued to reach a record high on a yen basis and also maintained growth on a dollar basis. That means the strength was not purely caused by yen depreciation; real demand was improving as well.
Inductors within passive components also recovered MoM. Among resistors, capacitors, and inductors, resistors and capacitors were stronger, inductors warmed up, and high-frequency components remained weak. This mix shows improvement in high-end computing and power-related demand, while ordinary communications, RF, and traditional end devices have not yet entered a synchronized strong cycle.
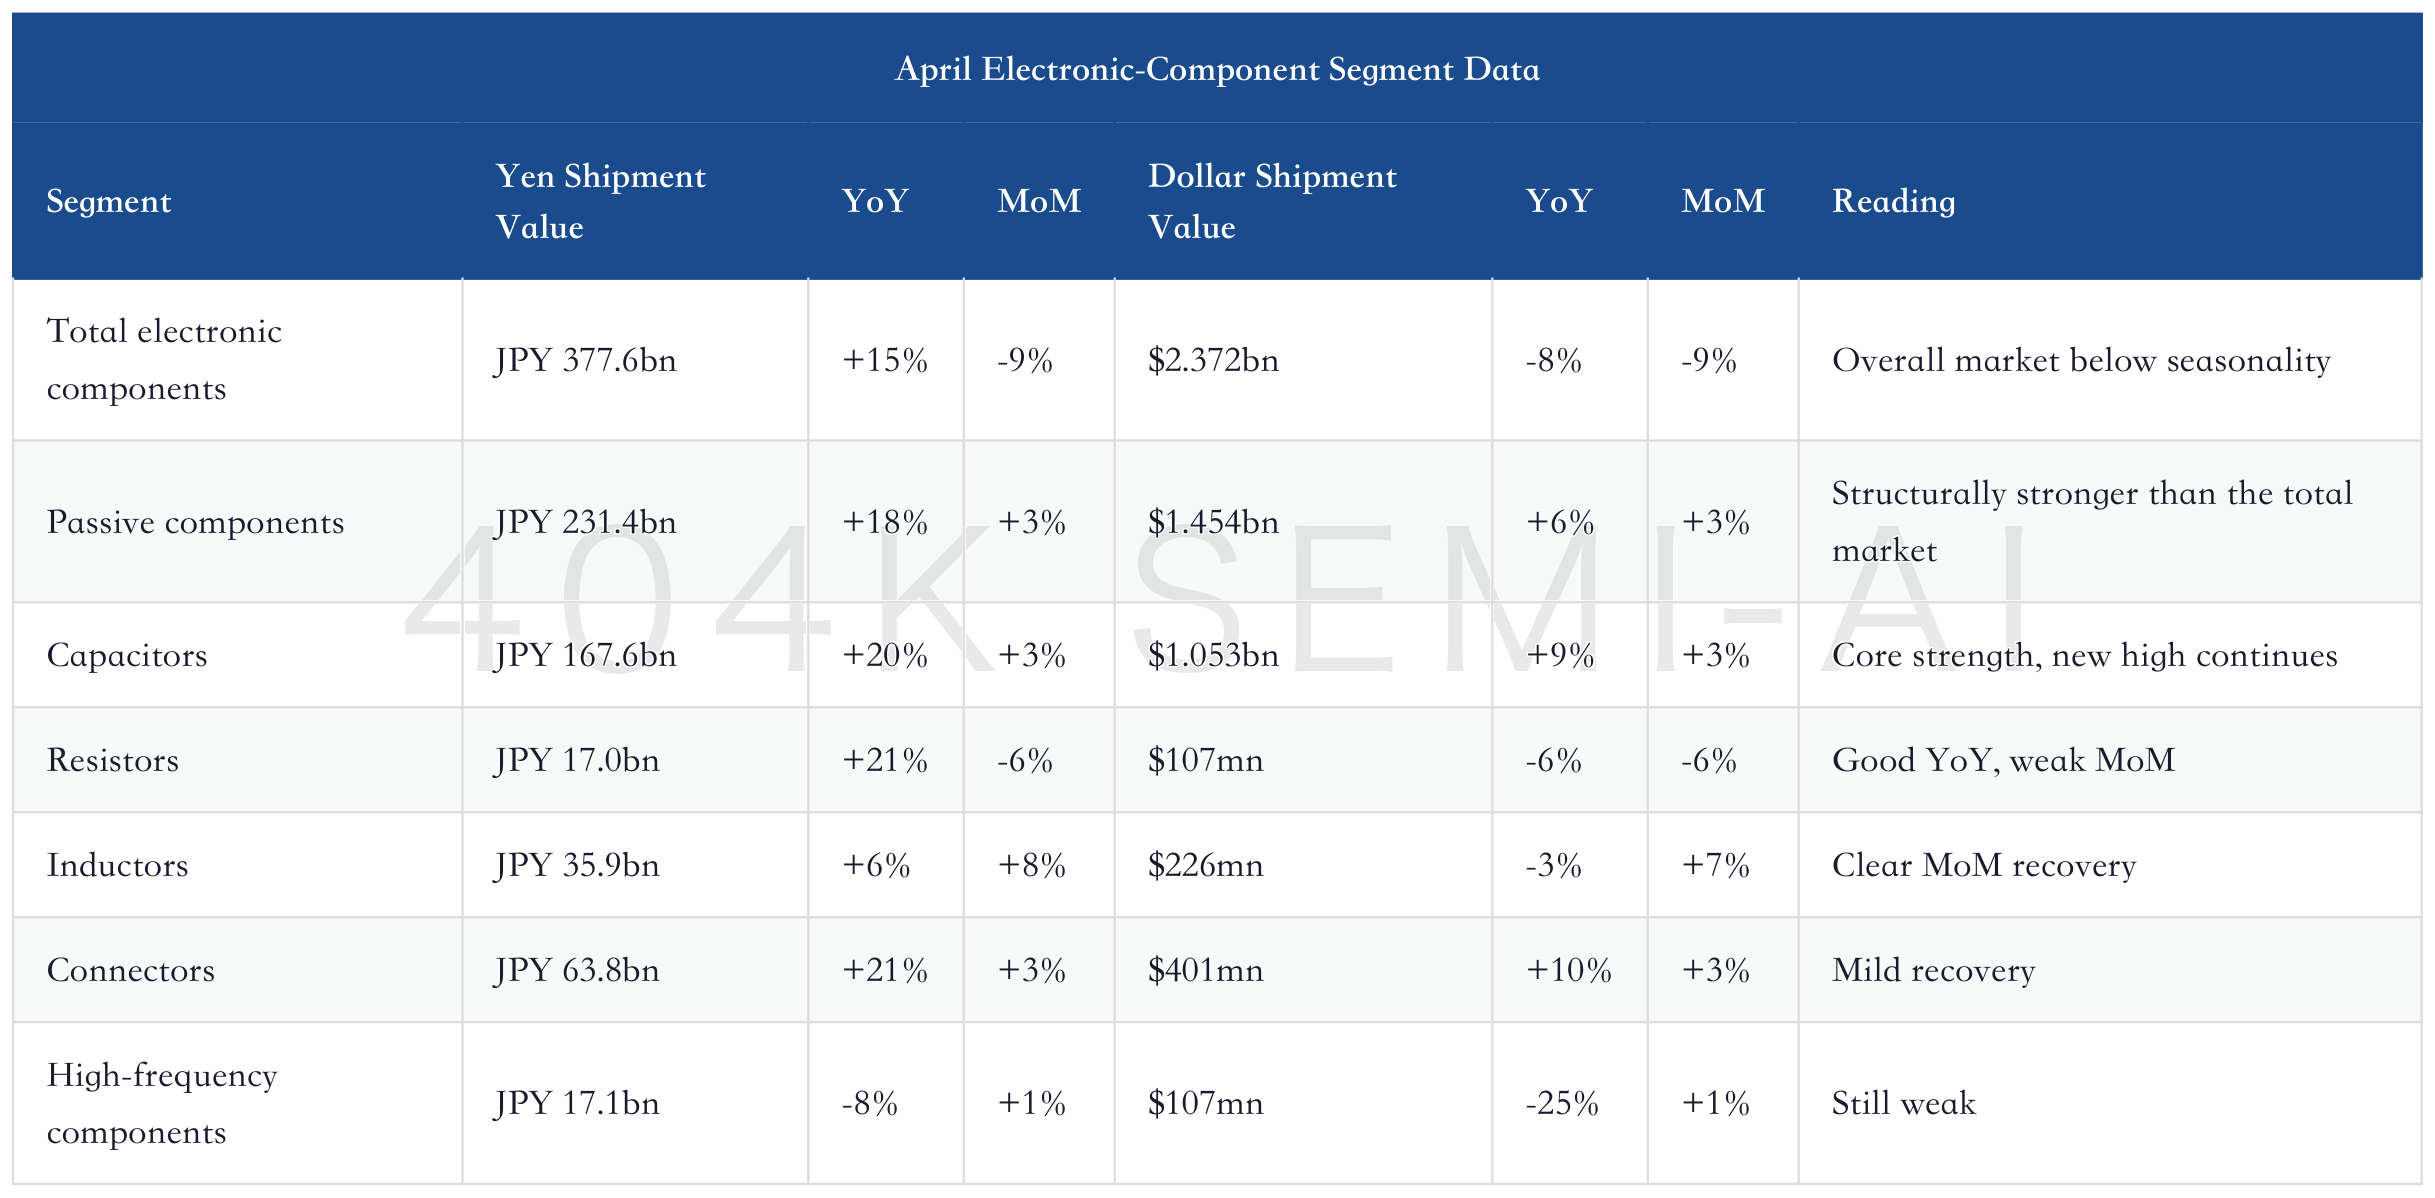
The key to MLCC is not simply "growth in total capacitors," but an upward shift in product mix. AI servers and high-power accelerator cards need more board-level decoupling, higher capacitance, higher reliability, and more complex power-integrity design. Once GPUs, ASICs, HBM, and high-speed networks raise power consumption and transient current, low-end commodity MLCCs cannot simply replace high-end part numbers.
This shifts the investment question from "is MLCC restocking" to "can high-capacitance, high-reliability part numbers raise prices, expand capacity, and be stably qualified by server customers." April ceramic electrode material output was still down 15% YoY, but recovered 8% MoM. That number matters: the YoY decline shows the industry is not yet broadly overheating, while the MoM recovery shows downstream restocking or production scheduling is turning.
If ceramic electrode material output continues to improve MoM over the next few months while capacitor shipment value keeps growing on a dollar basis, it would more strongly support the view that AI servers are pressuring high-end MLCC supply. Conversely, if electrode-material output was only a one-month rebound and dollar-basis capacitor shipments weaken, the current trade would look more like early inventory building and FX disturbance.
3. Connectors Are Not Yet the Main Line, but They Are the Thermometer for Whether AI Server Diffusion Is Real
Connector data is better than market perception, but not yet strong enough to become a standalone main line.
In April, connectors improved both YoY and MoM, and the dollar-basis series also showed recovery. This has two implications. First, connectors have indeed recovered from a weak cycle, and the recovery is not purely an FX contribution. Second, the slope is still mild, unlike capacitors, which have already reached consecutive new highs.
Why do connectors matter? Because an AI server is not a single chip, but a full system. GPUs, ASICs, switch chips, backplanes, cables, optical modules, storage, and power all require reliable connections. The more complex rack-level systems become, the more connector and high-speed interconnect quality affects stability, maintenance cost, and system deployment speed.
For companies such as Hirose Electric, a mild connector recovery is a positive signal, but it still needs two follow-up confirmations: first, whether the dollar-basis series can grow for several consecutive months; second, whether growth can spread from general connectors to high-value-added server, communications, automotive, and industrial applications. If this is only a one-month recovery in April, the market will not be willing to assign a very high valuation. If connectors rise together with AI servers, optical interconnects, and high-speed backplanes, they will move from cycle repair to part of the system bottleneck.
This is also why this report cannot focus only on MLCCs. AI server "peripheral components" are not isolated. Power stability depends on capacitors; data and control signals depend on connectors; high-speed networking depends on optical-electrical interconnects; persistent data depends on HDDs and SSDs. Strength in a single link may only be restocking. Simultaneous data improvement across multiple links looks more like second-order diffusion after capex is actually deployed.
Deep Update on Japanese Electronic Components: High-Value-Added Component Expansion in AI Data Centers, and Valuation Discipline for Murata, TDK, and Ibiden
4. On the Storage Side, Capacity Matters More Than Units
May HDD and SSD data gives a more direct conclusion: when data centers buy storage, they buy capacity and data-retention capability, not simply more devices.
May HDD unit growth was not dramatic, and nearline HDD was not supported by pure unit expansion in the investment logic. The real difference was capacity output: capacity per drive bay continued to rise, and cloud vendors were buying larger capacity, longer data retention, and higher data density.
This shows nearline HDD growth is coming from two directions: unit recovery and higher capacity per drive. In May, average nearline HDD capacity reached 23.0TB, up 14% YoY and 1% MoM. The gradual increase in 24TB, 28TB, 30TB, and 32TB-plus products means demand has moved from "are there drives" to "how much data can each drive bay hold."
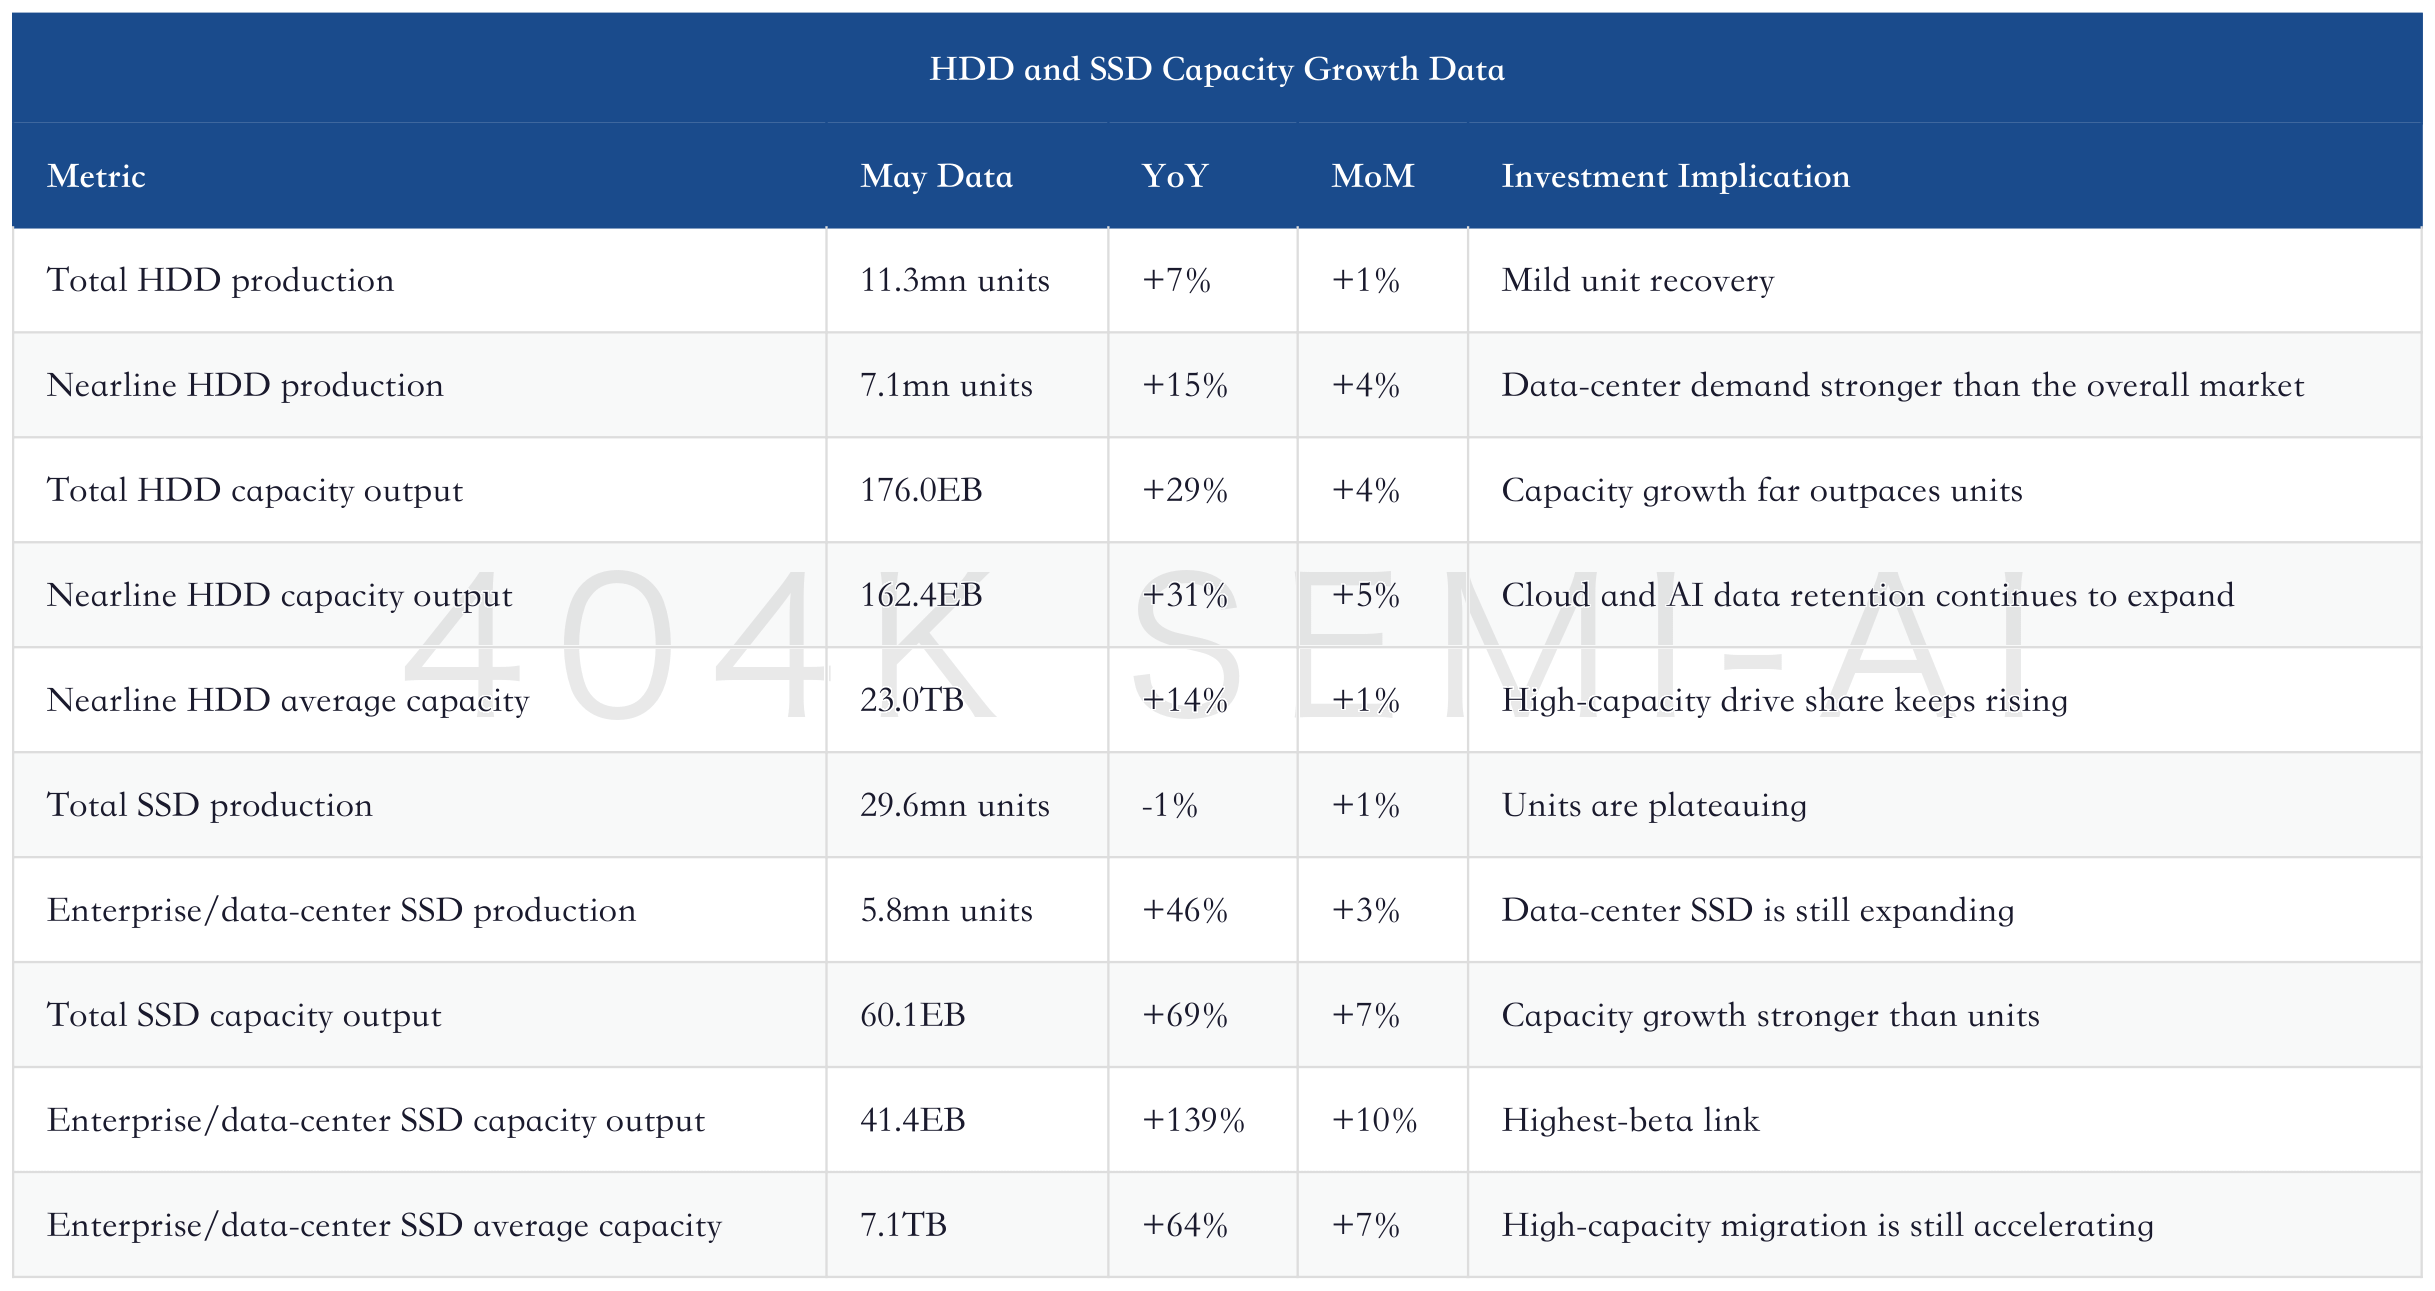
The investment implication of nearline HDD is straightforward: AI training and inference generate more and more data, and that data will not live only in HBM and DRAM. Cold data, warm data, logs, samples, model versions, enterprise knowledge bases, and compliance retention all require low-cost, large-capacity storage. HDD has not become a "high-growth chip" again, but it has become a scarce and priceable capacity asset in cloud capex.
Western Digital Deep Dive: From 2032 Visibility to the Re-Rating of HDD as a Scarce Asset
Enterprise/data-center SSD has even greater beta. In May, enterprise/data-center SSD capacity output rose 139% YoY and 10% MoM, with average capacity per drive reaching 7.1TB, up 64% YoY and 7% MoM. The report also mentioned unprecedented demand for 61.44TB, 122.88TB, and 245.76TB SSDs, with QLC designs becoming increasingly common in these capacity tiers.
This pulls NAND value out of the consumer-electronics pricing cycle and back into the capacity cycle of AI infrastructure. Historically, the market's biggest concerns around NAND were weak consumer end demand, easy oversupply, and limited product differentiation. Now enterprise SSDs are rebuilding barriers through higher capacity, lower cost per unit of capacity, more complex controllers, and longer customer qualification cycles. If price increases appear alongside product-mix improvement, NAND companies' profit beta will be more durable than in a pure price-up cycle.
AI Storage Deep Update: Morgan Stanley's May HDD and SSD Data Confirms Data-Center Capacity Demand Remains Elevated
5. TDK's Logic Is Stability, Not the Fastest Beta
TDK appears in both data lines, but its trading logic differs from Murata Manufacturing and Taiyo Yuden.
Murata Manufacturing and Taiyo Yuden are more like MLCC beta names. The core question for AI server MLCCs is whether high-value-added part numbers can keep raising prices, whether capacity can remain constrained, and whether customer qualification can protect margins. If MLCC supply/demand tightness continues, Murata Manufacturing, with its more complete product line, customer relationships, and high-end part-number capabilities, should generally be better positioned to receive a valuation premium than ordinary electronic-component companies.
Murata Manufacturing Deep Update: The Profit Gate and Valuation Discipline of AI Server MLCCs
TDK's path is more diversified. It is not being re-rated purely on AI server MLCCs, but benefits from several lines at once: higher value-add in HDD heads and suspensions, the transition of nearline HDDs toward HAMR, AI server aluminum capacitors and passive components, and demand related to medium-sized batteries and BBUs. This mix may have less short-term beta than a pure MLCC story, but it is more resilient to single-product volatility.
JPMorgan listed TDK as its top pick among HDD electronic-component suppliers in the storage data report. The core reason was that HDD vendors' internal capacity expansion is constrained, while existing capacity is being shifted to HAMR, giving TDK an opportunity to keep increasing its share in the external supply chain. Citi also recently divided TDK's AI server-related profit contribution into MLCCs, capacitors, HDD heads/suspensions, and medium-sized batteries, emphasizing that the company should not be viewed only as a mobile-phone battery company.
TDK Deep Update: Citi's JPY 4,500 Target Price and How AI Servers Re-Rate Batteries, HDD, and Passive Components
So company ranking cannot simply be written as "the one that rises more is better." A more reasonable framework is to examine the pairing of beta and certainty.
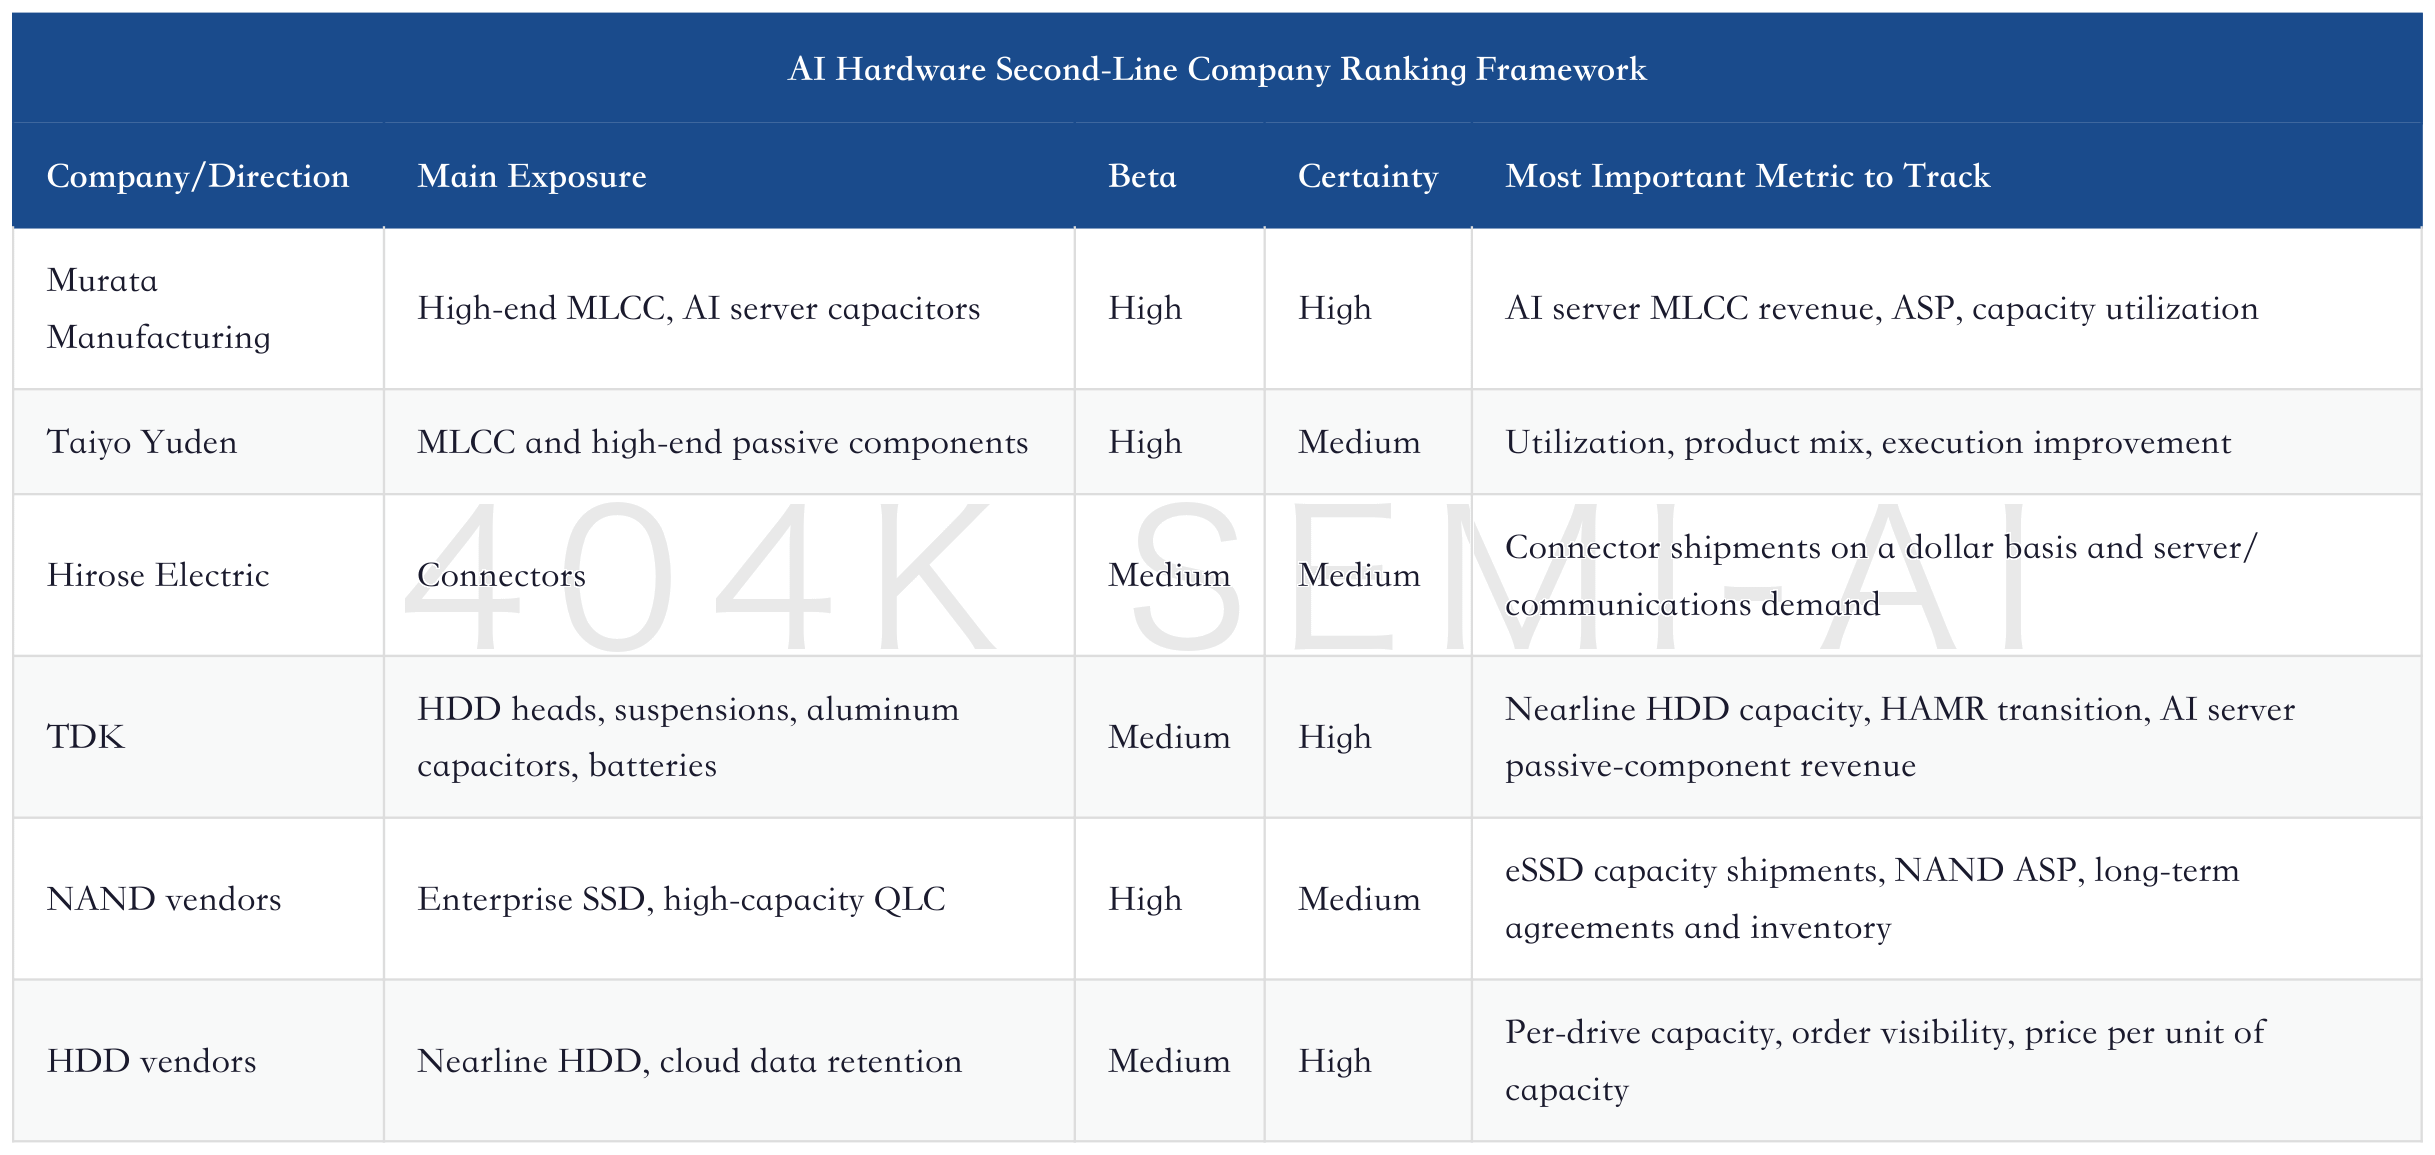
The investment judgment behind this ranking table is as follows: if the market is trading "AI server MLCC shortage," Murata Manufacturing and Taiyo Yuden are more direct; if it is trading "sustained data-center capacity expansion," TDK, HDD vendors, and NAND vendors are more direct; if it is trading "AI hardware spreading from chips into system components," these lines will together lift the valuation center of Japanese electronic components and the storage chain.
6. Why HDD and SSD Can Both Be Strong
The market often understands HDD and SSD as substitutes. In data centers, the more accurate description is tiering.
HDD is suitable for low-cost, long-term, massive data retention. SSD is suitable for higher-performance, higher-throughput, lower-latency data access. As the AI-era data pool expands, both can grow: training and inference require a faster hot-data layer and also a cheaper, larger data lake and archive layer. HDD delivers cost per capacity, while SSD delivers performance and density.
May data validates exactly this point. The combined capacity of enterprise HDD, nearline HDD, and enterprise/data-center SSD continued to expand, and SSD's share of total capacity continued to rise.
This shows SSD is taking more of the incremental capacity, but HDD is not being squeezed out. On the contrary, nearline HDD capacity is also growing. What is really happening is that total data-center storage demand is expanding, while the internal structure is being tiered by hot/cold data, cost, and performance.
AI Is Driving a Sector-Wide Storage Re-Rating: DRAM, NAND, SSD, and HDD Pricing Power Across Samsung, SK hynix, SanDisk, Western Digital, and Seagate Earnings
This matters a lot for NAND. In the past, enterprise SSD growth was often understood as part of the server cycle. Now it looks more like part of the AI data stack. Strong demand for 61.44TB, 122.88TB, and 245.76TB SSDs means customers are not just buying more standard-capacity SSDs, but are rebuilding data-center storage tiers with higher-density SSDs. QLC is entering high-capacity tiers, which also means cost, endurance, controllers, and firmware capability will jointly decide who captures the profit.
Kioxia Deep Update: JPY 155,000 Target Price, NAND Cash Flow, and AI SSD Re-Rating
7. Regional Signal: This Is Not a Normal Consumer-Electronics Recovery, but China and the Data-Center Chain Moving First
The most easily overlooked point in the electronic-component data is regional structure. Overall MoM weakness does not mean every region is weak. The real questions are which regions can resist seasonality, which still look like a traditional cycle, and which have started to reflect restocking in server and industrial chains.
The direction of April regional data is clear: China was the main MoM bright spot, while other major regions mostly improved YoY but were under MoM pressure. This mix is not a typical synchronized global consumer-electronics restocking. If smartphones, PCs, and general end devices were recovering broadly, the regional data would usually be more balanced. What we see now looks more like servers, power, industrial, and some automotive-related chains recovering first, while traditional end devices have not fully caught up.
This matters for investment judgment. If this were only a consumer-electronics cycle rebound, the market would be more willing to buy low-valuation, low-end part numbers and inventory repair. If it is AI data-center diffusion, the market will continue to reward component companies with high reliability, high capacitance, wide temperature range, high current, and harder customer qualification. The valuation implications are completely different.
China's strength should not be simply interpreted as "domestic demand suddenly improving across the board." A more reasonable explanation is that China's supply chain contains many servers, power supplies, industrial control, communications equipment, and system assembly links. Once global cloud vendors and the AI server chain pull production schedules, orders show up in regional statistics as more resilient China-related shipments. This explanation also cross-checks with storage data: capacity demand comes from cloud and enterprise data centers, not from a single consumer end device.
Conversely, MoM pressure in the United States, Europe, and Japan should not be directly read as demand collapse. Monthly electronic-component data is heavily affected by customer pull-ins, inventory timing, FX, and seasonality. What really needs to be watched is continuity: if China and the rest of Asia remain strong while the United States and Europe also start to recover MoM, it would show AI hardware diffusion moving from the supply-chain side to the end-demand side. If only China is strong while other regions remain weak, investors should beware of localized inventory building or order transfer.
This is why the report discusses "region" in the middle. Region itself is not a buy reason. It is a filter for judging demand quality. Strong demand needs to meet two conditions at the same time: alignment with high-value-added categories and alignment with data-center capacity expansion. As long as both appear together, second-line AI hardware diffusion is more credible than ordinary restocking.
8. The Core Tension in MLCC: Not Whether Capacitors Exist, but Who Can Supply High-Reliability Part Numbers
MLCC is not a simple aggregate-volume story. The difference between low-end capacitors and high-end AI server MLCCs is like the difference between ordinary steel and aerospace materials: both are called materials, but reliability, specifications, qualification, customer stickiness, and margins are entirely different.
Why do AI servers drive more high-end MLCC demand? The reason is not mysterious. GPU and ASIC power consumption keeps rising, board-card transient current keeps increasing, and HBM, power modules, switch chips, and high-speed interconnects all require stricter power integrity. High-end MLCCs stabilize voltage, filter noise, and support power-module response in extremely short time windows. If capacitor specifications cannot keep up, the system is not merely slower; stability, yield, and maintenance cost are all affected.
This changes the competitive ranking of MLCC companies. In a normal cycle, investors look at overall utilization, inventory days, and price beta. In an AI server cycle, they should look more at server qualification, product mix, automotive and industrial capabilities, high-end part-number capacity, customer concentration, and expansion discipline. Murata Manufacturing's advantages come from high-end part-number coverage, customer relationships, and accumulated R&D; Taiyo Yuden's beta comes from product-mix improvement and utilization recovery; Taiwanese and Korean suppliers can also benefit, but certainty in the highest-end server part numbers needs to be verified company by company.
"we prefer Murata Manufacturing"
The meaning behind this short quote is not simply that one company is better. It means JPMorgan is prioritizing certainty over beta among MLCC stocks. High-end part numbers have long customer qualification cycles, and customers do not easily switch suppliers only because short-term prices are lower. Once AI servers enter volume production, customers care more about stable delivery and quality risk, so price sensitivity can be lower than in consumer electronics.
This is also why record-high capacitor shipment value matters. It does not by itself prove that MLCC has entered broad shortage. Rather, it shows that the revenue mix of high-value-added components is improving. If the dollar-basis series continues to grow and ceramic electrode material output continues to recover, it would further confirm that high-end MLCC is moving from an expectations trade to order realization. If only the yen-basis series is strong while the dollar-basis series and upstream materials do not follow, the market should give some of the move back to FX and inventory-building noise.
MLCC investment judgment can be split into three layers. The first layer is volume, which determines whether the industry is repairing from the bottom. The second layer is structure, which determines whether high-end part numbers can drive margin improvement. The third layer is customers, which determines whether orders can turn from one-off restocking into long-term specification upgrades. Current data already supports the first layer and part of the second, but the third still needs validation through company orders, server revenue, and customer qualification pace.
This line's biggest risk is also here. If AI servers merely increase the usage of certain specifications without creating real supply constraints, MLCC companies will struggle to earn a long-term excess valuation. If capacity expands too quickly, consumer-electronics recovery remains too weak, or customers reduce purchasing after pre-building inventory, short-term shipment strength will become inventory pressure over the next few quarters. Good research does not linearly extrapolate strong data; it continuously checks whether strong data is translating into prices, margins, and order visibility.
9. TDK and the HDD Chain: Slow Variables May Matter More Than Fast Beta
The biggest difference between the TDK line and the MLCC line is that it behaves more like a slow variable. MLCC trading is more easily driven by monthly shipments, part-number shortages, and price expectations; TDK's logic depends more on nearline HDD capacity upgrades, the HAMR transition, the value of heads and suspensions, and the combined contribution of AI server passive components.
Such companies do not necessarily run fastest in the short term. If the market only chases names that most resemble "AI shortage," TDK may underperform purer MLCC beta companies. The storage report also directly flagged this short-term comparison: investors may pair-trade TDK against Murata Manufacturing and Taiyo Yuden in the near term. But that does not mean TDK's medium- to long-term story is weakening.
"TDK is our top pick"
The key to this view is that the HDD supply chain is not a simple shipment-volume story. As nearline HDDs move to higher capacity, platters, heads, suspensions, precision processing, and yield all become more important. Especially during the HAMR transition, HDD vendors may not want to quickly expand all internal capacity because the capex and yield risk of a technology transition are higher. If external core-component suppliers can deliver stably, they may win higher share.
TDK's value content comes from two directions. One is HDD itself: cloud vendors still need low-cost, large-capacity data retention, and the higher nearline HDD capacity goes, the higher the technical barrier for key components. The other is AI server system components: aluminum capacitors, passive components, medium-sized batteries, and BBU-related products mean the company is not dependent only on mobile-phone batteries and the traditional electronics cycle.
This is why TDK's valuation should shift from "mobile-phone battery plus cyclical components" to "data-center capacity plus power reliability plus complex electronic components." The asset attribute has changed, so the market's valuation method should change as well. The old framework focused on the phone replacement cycle, consumer-electronics inventory, and battery prices; the new framework focuses on cloud capex, data retention, HAMR yield, server power delivery, and customer order visibility.
Of course, slow variables also have drawbacks. HDD capacity upgrades do not accelerate linearly every month, and HAMR cannot replace everything overnight. If cloud capex slows, or customers shift more data tiering toward SSDs and object-storage optimization, the HDD chain's beta will weaken. TDK is not an AI name that "only goes up." It is more like an asset re-rating line that needs quarterly validation.
For this line, the most effective tracking is not the monthly share price, but four questions. Is nearline HDD average capacity still rising? Does HAMR conversion lift the value of key components? Is external supplier share really increasing? Can AI server-related passive components and medium-sized batteries form identifiable revenue in financial results? As long as these questions get continuous answers, TDK is not merely a side branch of the storage chain.
10. The Change in Enterprise SSD: QLC Is Not Low-End Substitution, but a Rewrite of Capacity Economics
Enterprise SSD is the line most easily misread. In the past, many investors understood QLC as a "cheaper, shorter-life, lower-end" NAND technology path. That interpretation makes sense in a consumer-electronics context, but it is insufficient in an AI data-center context. The real question is not whether QLC is low-end, but whether it can lower cost per unit of capacity enough to reconstruct storage tiers while keeping endurance acceptable.
AI training, inference, and enterprise knowledge bases generate large amounts of hot and warm data. Hot data needs low latency, high throughput, and fast access; warm data needs to be faster than HDD, but cannot use overly expensive media. High-capacity enterprise SSD sits exactly in this middle layer: it does not replace HBM and DRAM, nor does it fully replace HDD. It migrates part of the data from slower storage to a faster, denser, more schedulable medium.
"unprecedented demand"
The report used this phrase to describe high-capacity enterprise SSD demand. What truly deserves attention is the product mix behind it. Customers are not only buying a bit more standard-capacity SSD; they are qualifying higher-capacity enterprise platforms with more complex controllers and higher density. For NAND vendors, this is more important than a simple spot-price increase. Price increases can quickly be capped by supply response, but high-capacity enterprise SSDs require customer qualification, firmware, controllers, thermal management, and reliability data, so the barriers are thicker.
This line has different implications for Kioxia, SanDisk, Micron, Samsung, and SK hynix. Companies with more complete enterprise customers, controller capability, QLC yield, and long-term supply ability are more likely to turn capacity demand into profit. Companies that only have wafer capacity but skew lower-end in product mix may capture only part of the pricing cycle. In other words, NAND companies should not be evaluated only by bit shipments and ASP; the share of high-capacity enterprise SSD matters as well.
The simultaneous strength of enterprise SSD and nearline HDD also explains why "substitution" is not the main line today. AI data centers are not replacing HDD with SSD within a fixed storage pool; they are building a larger data hierarchy. HDD absorbs low-cost massive retention, while SSD absorbs higher-performance and higher-density access. When both are strong, the data pool is expanding. Only if SSD is strong while HDD is weak would it look more like substitution.
The risk in this line is supply discipline. The NAND industry's most common historical mistake is to expand capacity quickly after seeing price recovery, then drive the profit cycle back down. If high-capacity enterprise SSD demand is strong enough and supply discipline remains restrained, profits will be more durable. If the consumer side remains weak and enterprise strength is not enough to absorb incremental supply, the market will return to traditional cycle volatility.
11. Three Worldviews: What Is This Trade Really Betting On?
This report cannot offer only one linear conclusion, because when electronic components and storage improve at the same time, the market may be trading three different worldviews. Splitting the worldviews makes it clear what to watch next.
The first worldview is "ordinary cycle repair." In this framework, the April improvement in capacitors and connectors is merely normal restocking after inventory clearance, and the May storage-capacity improvement is staged procurement by cloud vendors. Under this worldview, the market should not assign a very high valuation. The best trade is to buy low-valuation cyclical stocks and reduce exposure after inventory repair is realized. Its evidence is that the overall market is not strong enough, some regions are weak MoM, and dollar-basis data is still divergent.
The second worldview is "AI server second-line bottlenecks." In this framework, what is strong is not all electronic components, but high-value-added links related to power delivery, interconnect, capacity, and data retention. Under this worldview, Murata Manufacturing, Taiyo Yuden, TDK, enterprise SSD, and the nearline HDD chain can receive higher valuations because they are not ordinary restocking, but system constraints after AI capex is deployed. Its evidence is record-high capacitors, storage-capacity growth clearly outpacing unit growth, and strong high-capacity enterprise SSD demand.
The third worldview is "data-center capacity economics re-rating." In this framework, the most important factor is not one month of component data, but cloud vendors redesigning storage tiers for future inference, data lakes, model versions, enterprise knowledge bases, and log retention. HDD, SSD, QLC, controllers, NAND long-term agreements, HDD heads, and suspensions all benefit. Under this worldview, the storage chain moves from traditional cyclical equities to part of AI infrastructure, but also becomes more dependent on the capex cycle and customer concentration.
The three worldviews are not mutually exclusive. The market may initially value the names as ordinary cycle repair, then gradually shift to AI server second-line bottlenecks as more monthly data confirms the trend, and then shift to capacity economics re-rating if enterprise SSD and nearline HDD remain strong. Real excess return often comes from worldview switching, not from a single data point itself.
Current data is closer to the second worldview and has started to provide evidence for the third. The reason is that capacitors, nearline HDD, and enterprise SSD are not products driven by the same consumer end device. Their simultaneous strength looks more like AI system buildout spreading into lower-level hardware. Connectors are still only in a mild recovery, so system-level diffusion has not been fully confirmed. Once connectors, optical interconnects, and the server power chain continue to follow, the second worldview will be more solid.
This framework also explains why the title puts capacitors, nearline HDD, and enterprise SSD together. They represent power stability, low-cost capacity, and high-performance capacity, respectively. If AI capex stopped at the chip layer, capacitors and storage capacity should not improve at the same time. Now that they are improving together, capex is moving from "buying chips" to "keeping the full system running for the long term."
12. Valuation Discipline: After Strong Data, the Biggest Risk Is Buying Every Company as the Same AI Asset
The easiest mistake in second-line AI hardware diffusion is to buy all beneficiaries as the same type of asset. MLCCs, connectors, HDD components, NAND, HDD vendors, and SSD platforms have very different business models, and they should not be valued the same way.
The key for MLCC companies is high-end part numbers and margins. If the server part-number mix rises, price and gross-margin improvement can matter more than revenue growth. For these companies, valuation should revolve around high-end capacity, ASP, customer qualification, and expansion discipline. Looking only at total capacitor shipment value can easily mix low-end and high-end demand together.
The key for connector companies is sustainability. Connector recovery shows improvement in system interconnect demand, but a mild one-month improvement is not enough to support a large valuation re-rating. For these companies, investors should wait for more continuous order evidence from servers, communications equipment, automotive, and industrial chains. If connectors are only ordinary cycle repair, valuation expansion will be smaller than for MLCCs.
The key for TDK is compound exposure. It is neither the highest-beta MLCC name nor a pure HDD component company. Valuation should look at HDD capacity upgrades, the HAMR transition, AI server passive components, and medium-sized batteries at the same time. If the market only compares it with pure MLCC companies, it may underappreciate slow variables in the short term. If it values TDK only as a mobile-phone battery company, it may miss an asset-attribute migration in the medium term.
The key for NAND companies is product mix and supply discipline. Strong enterprise SSD demand does not mean all NAND capacity is equally valuable. High-capacity SSDs, QLC, controllers, customer qualification, and long-term agreement capability determine profit quality. If the industry expands capacity too quickly in response to price increases, profits will return to cyclical volatility. If supply discipline holds, high-capacity enterprise SSD will lengthen the profit cycle.
The key for HDD vendors is order visibility and price per unit of capacity. Strong nearline HDD capacity growth shows that cloud data-retention demand remains. But HDD is still a mature industry, so valuation cannot be fully assigned like a growth stock. It is more like a scarce capacity asset: when cloud customers need long-term data retention and supply expansion is constrained by technology and capex, profits and cash flow become more stable.
This is the valuation discipline of this report: do not assign the same multiple simply because all are AI-related; do not look only at the aggregate cycle simply because all are electronic components; and do not ignore structural changes from data-center capacity demand simply because storage has historically been cyclical. The best portfolio is not betting on one slogan, but layering by beta, certainty, valuation, and tracking metrics.
13. How to Validate Over the Next Four Quarters
Over the next four quarters, this line should be validated through three layers: monthly data, company earnings, and customer capex. Monthly data discovers the trend, earnings confirm profits, and customer capex judges sustainability.
For monthly data, first watch capacitors and upstream MLCC materials. If capacitor shipments continue to grow on a dollar basis and ceramic electrode material output continues to recover, high-end MLCC demand is not a one-off inventory build. If the dollar-basis series weakens while the yen-basis series remains strong, FX and product mix need to be separated, rather than extrapolated directly.
Second, watch connectors. If connectors recover continuously, AI servers are diffusing from chips, power, and storage into system interconnect. If connectors stay in a mild recovery, system-level diffusion is still incomplete, and the market will prefer the two harder lines: MLCC and storage capacity.
Third, watch average nearline HDD capacity. Unit volumes themselves are not the most important variable; average capacity and capacity output better reflect cloud-customer demand. If average capacity keeps rising, the share of high-capacity drives is rising. If average capacity stagnates, orders may be only unit repair, and the investment implication will be much weaker.
Fourth, watch the enterprise/data-center SSD capacity share. If high-capacity SSD continues to raise its share, NAND is shifting from a consumer pricing cycle to a data-center product-mix cycle. If the share falls back, then even if total SSD units look fine, investors should beware of enterprise demand being pulled forward.
At the earnings layer, watch margins. Electronic components and storage are both industries where companies can have "revenue but no profit." If a company delivers shipment growth but no gross-margin improvement, product mix or price discipline is insufficient. If revenue growth is not fast, but margins and order visibility improve, that may actually be a higher-quality signal.
At the customer capex layer, watch actual delivery across cloud vendors and the AI server chain. GPU cluster deployment speed, rack power, networks, storage, and data-center construction pace will decide whether second-line bottlenecks can persist. If cloud vendors are only locking in supply early, second-line components may stay strong for only a few quarters. If real deployment and inference traffic continue to grow, storage and system-component demand will last longer.
The benefit of this validation framework is that it is not thrown off by one-month volatility. AI hardware diffusion is not a straight line. Any link can be disturbed in the short term by inventory, FX, customer scheduling, or supply constraints. As long as multiple links give positive signals at the same time, the theme remains intact. If only one link is still strong, the portfolio should shrink from a broad diffusion trade to a single-point cycle trade.
14. Company and Link Breakdown: Which Looks Like Beta, Which Looks Scarce, and Which Is Only Cycle Repair
When electronic components and storage are viewed together, it is easy to reach an overly broad conclusion: AI drives both components and storage. That conclusion is too crude to guide follow-up tracking. The real task is to separate asset attributes.
Murata Manufacturing looks more like a high-end MLCC certainty asset. Its advantage is not that one month's shipment value rose the most, but that high-end part numbers, customer relationships, and quality qualification form a moat. AI servers need stability, and customers are more willing to pay for reliability and delivery certainty. As long as server MLCC demand continues, Murata Manufacturing is best positioned to translate industry strength into margins and a valuation premium.
