
AI Hardware 2Q26 Earnings Preview: A Several-Hundred-EB Storage Shortfall and the Profit Relay from Agentic-AI CPUs to Optical Interconnects
目录
TL;DR
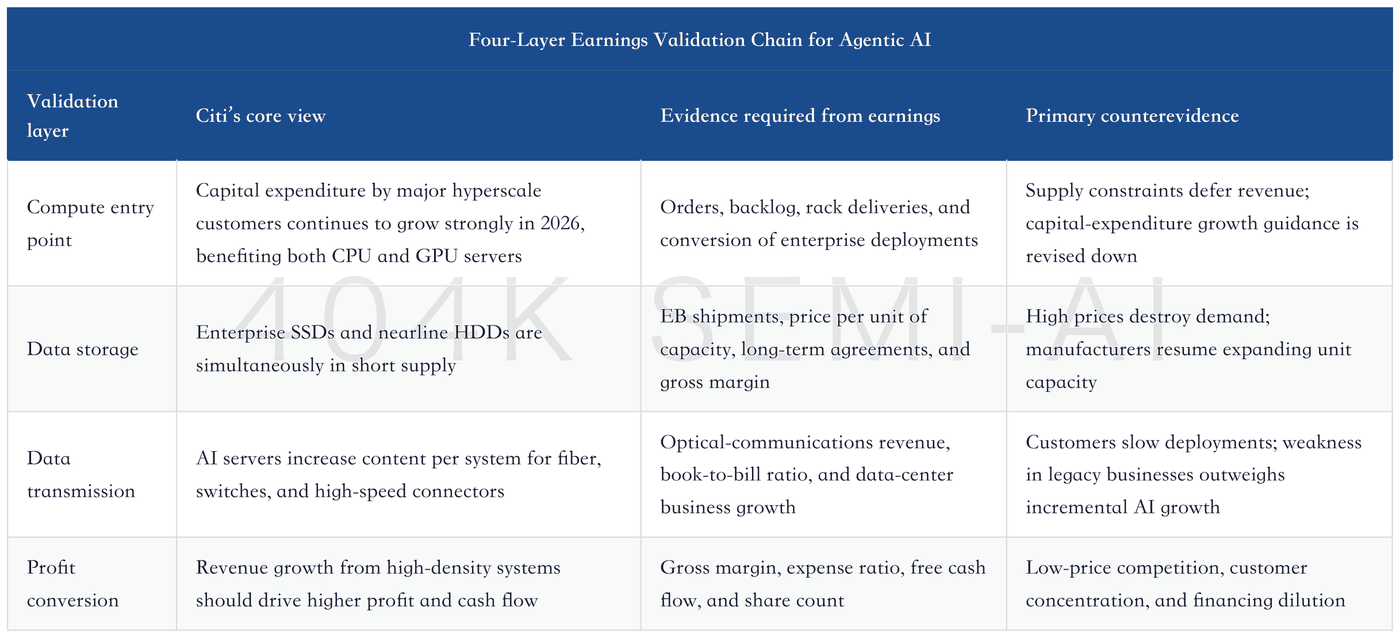
What the Market Actually Needs to Validate This Earnings Season
CPUs Are Not a Substitute for Storage, but a Demand Amplifier
Why Storage Ranks First: Supply Cannot Keep Pace
SanDisk: The Greatest Pricing Leverage in Enterprise SSDs
Seagate Technology: The Purest “Capacity, Pricing, and Cost Reduction” Play
Western Digital: An Additional Capital-Allocation Catalyst Beyond the HDD Cycle
Optical Interconnects and Connectors: The Second Layer of Growth, with Margins as the Key
Corning: Revenue Is Not the Main Story—Margins Are
Amphenol: End-Market Diversification Makes AI Growth More Sustainable
TE Connectivity: AI Growth Must First Offset the Automotive Shortfall
OEM Divergence: Revenue, Gross Margin, and EPS Are Not Interchangeable
Consumer Electronics and the Industrial Cycle: Pricing Can Support Revenue, but Not Necessarily Demand
Earnings Calendar and Company-by-Company Scorecard
Valuations Already Discount a Distant Future; Risk-Reward Must Be Recalculated Through Earnings
Final View: Start With CPUs, but Allocate Capital Where Supply Is Tightest
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The most important question this earnings season is not whether AI capital expenditure remains elevated, but whether incremental compute capacity can translate into pricing, margins, and cash flow across CPU servers, storage, and optical interconnects.
TL;DR
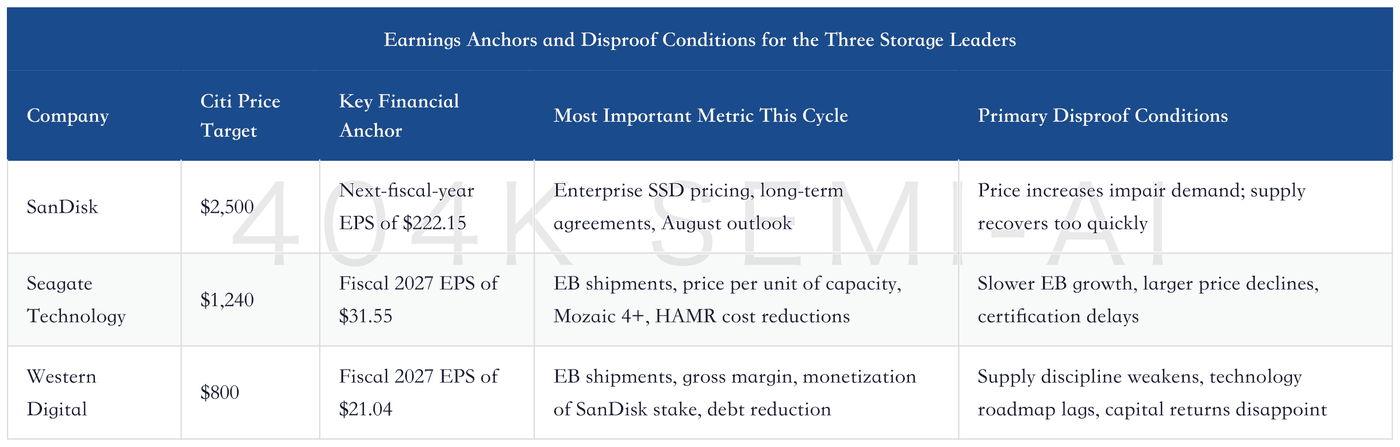
Storage remains the highest-conviction segment this earnings season. Citi expects enterprise HDD demand in exabytes to enter a roughly 25% CAGR phase, with 2026 demand exceeding supply by several hundred EB and tightness potentially persisting through 2028. SanDisk, Seagate Technology, and Western Digital therefore rank as Citi’s top three component picks. After earnings, the key issue will not be whether management says “AI demand is strong,” but whether EB shipments, price per unit of capacity, gross margin, and supply discipline all deliver simultaneously.
CPUs are the entry point for data creation, while storage is the recurring bill for long-running agents. BofA previously raised its estimate for the 2030 server CPU total addressable market to more than $170 billion, primarily because inference and agentic workloads are returning to general-purpose servers. Citi’s preview completes the second half of the thesis: agents operating around the clock will continuously generate, replicate, and version data, driving simultaneous growth in local SSDs, enterprise SSDs, object storage, and nearline HDDs.
Optical interconnects and high-speed connectors represent the second layer of the profit relay. AI servers are expected to account for only about 24.3% of server shipments in 2026 but approximately 71.4% of server spending. These high-density systems require more high-speed connectors, fiber, and switches. For Corning, the focus is optical communications and margins; for Amphenol, it is AI connector content and M&A; integration; and TE Connectivity must demonstrate that data-center growth can offset weakness in automotive.
AI revenue does not necessarily translate into shareholder earnings, and Super Micro Computer is the clearest counterexample. Citi forecasts FY2027 revenue of $63.613 billion, well above the consensus estimate of $51.374 billion, yet its EPS estimate of $3.15 remains slightly below the market’s $3.17. Low margins, customer concentration, and equity dilution will determine how much revenue ultimately reaches earnings per share.
The greatest risk is not that AI suddenly disappears, but that high prices, elevated valuations, and crowded positioning reinforce one another. Citi’s assumptions for 2026 blended NAND ASPs and enterprise SSD pricing are highly aggressive, while PC and smartphone shipments face declines of approximately 15% and 17%, respectively. If price increases destroy end demand, HDD manufacturers relax capacity discipline, or earnings merely meet expectations, popular storage and optical-interconnect names could see valuation compression first.
What the Market Actually Needs to Validate This Earnings Season
Over the past two years, the market has focused on whether there were enough graphics processing units (GPUs); the next question is whether the rest of the AI system can keep pace. Citi’s covered hardware and component companies have risen by an average of 110% year to date, versus a 10% gain for the S&P; 500. Such substantial outperformance means that “AI capital expenditure growth” is no longer new information. The next round of earnings upgrades must come from more specific supply-demand shortfalls, pricing power, and profit conversion.
Citi’s priorities are clear: storage ranks first, followed by original equipment manufacturers benefiting from AI deployments and enterprise server refreshes, then connectors and optical networking. While this ranking still appears to be about AI hardware, the underlying focus has shifted from “how many machines are sold” to “how much recurring consumption each machine generates.” Agentic AI is not a model that stops after a single training run. It operates continuously, performs repeated inference, calls external tools, and leaves behind large volumes of intermediate state. More compute events create more key-value cache, logs, vector data, user context, model checkpoints, and output versions. Servers are no longer merely compute devices; they are also data-production systems.
This is where BofA’s CPU report and Citi’s latest preview are most valuable when read together. BofA raised its estimate for the 2030 server central processing unit (CPU) market to more than $170 billion, arguing that inference, agentic AI, and enterprise modernization will restore the CPU’s importance within servers. Citi, meanwhile, notes that server spending continues to be driven not only by GPUs, but also by growing demand for CPU-based agentic servers. CPUs are the entry point that brings more enterprise workloads into the AI era, while storage, networking, and connectors determine whether those workloads can run continuously.
The Second Engine of the Storage Supercycle: CPU Resurgence, HBM Spillover, and a $1.7 Trillion TAM Revaluation
Morgan Stanley’s July 13 feedback from its Nvidia roadshow provides another cross-check: constraints in power supply, data-center space, and critical components remain, while storage shortages could persist for years. This suggests that the most important issue to track in 2H26 is not whether an individual cloud provider makes a modest adjustment to capital expenditure, but whether constrained segments can expand capacity, sustain pricing, and secure customer commitments under long-term agreements. Aggregate demand remains strong, but value will concentrate in areas where supply is hardest to increase.
CPUs Are Not a Substitute for Storage, but a Demand Amplifier
The easiest mistake when incorporating the CPU report into this earnings preview is to interpret it as simply meaning that “CPU stocks will also rise.” A more useful approach is to view CPUs as the starting point of the entire data-production chain. Workloads in traditional training clusters are relatively concentrated, making data-write patterns easier to plan. Once agents are deployed within enterprises, however, large numbers of tasks will be distributed across general-purpose servers, where they must call models while also accessing databases, enterprise software, and user files. Every additional inference event requires not only more computation, but also another round of reading, caching, writing, backup, and archiving.
Citi’s server model illustrates this shift in value density. AI servers are expected to represent approximately 24.3% of total server shipments in 2026 but roughly 71.4% of total server spending. By 2028, their shipment share could rise to 34.3%, while their spending share reaches 78.1%. The average selling price of an AI server in 2026 is estimated at approximately $112,000, versus about $14,400 for a non-AI server. The higher price does not come solely from GPUs; it also reflects higher-specification CPUs, memory, local SSDs, network interface cards, switching connections, power delivery, and cooling.
More importantly, CPU-server expansion will extend AI demand into enterprises that have not previously deployed large-scale GPU infrastructure. Customer service, code generation, data analysis, and workflow automation do not require every step to run on expensive GPUs. CPUs handle orchestration, retrieval, and post-processing for many tasks. Dell Technologies and Hewlett Packard Enterprise rank first and second, respectively, in Citi’s OEM rankings precisely because they can also attach enterprise storage, networking, and services.
The real implication of stronger CPU demand is therefore the broader diffusion of data infrastructure, not the replacement of one chip by another. Even if CPU market share shifts among vendors, the storage and connectivity demand generated by enterprise agent deployments will not disappear. CPU-server orders and the transition of enterprise projects into production are important leading indicators of whether the storage upcycle can broaden into a wider market.
Why Storage Ranks First: Supply Cannot Keep Pace
Storage has emerged as the strongest theme because demand growth and supply discipline are occurring simultaneously. Citi’s industry checks indicate that demand for NAND flash, enterprise SSDs, and hard disk drives (HDDs) significantly exceeds supply. Hyperscalers are receiving priority allocation, crowding out consumer, PC, and channel customers. If AI merely generated more data while manufacturers could rapidly expand capacity, margins might not improve. The difference today is that HDD vendors have explicitly ruled out increasing unit capacity and are relying primarily on higher areal density, while NAND vendors are placing greater emphasis on profitability, long-term agreements, and disciplined capital expenditure.
Citi expects HDD industry demand, measured in exabytes (EB), to enter a roughly 25% compound growth cycle. An exabyte is a unit used to measure massive storage capacity. Demand is expected to exceed supply by several hundred EB in 2026, with tight conditions potentially persisting through 2028. Elevated NAND prices also make SSD substitution for HDDs less economical, meaning the two storage architectures are not engaged in a zero-sum competition: enterprise SSDs benefit from low-latency inference, key-value cache offloading, and high-performance data access, while nearline HDDs support large-scale object storage, data replicas, and long-term archiving.
The most important metrics in this thesis are not HDD unit shipments, but EB shipments, price per EB, and gross margin. High-capacity products can increase total capacity while unit volumes remain relatively stable, while heat-assisted magnetic recording (HAMR) and higher areal density reduce cost per unit of capacity. If vendors can increase EB deliveries, maintain pricing discipline, and lower costs through new technologies, revenue, gross margin, and free cash flow can all rise together. If EB growth depends on steep price cuts or yield ramp-ups disappoint, the cycle narrative will quickly lose its earnings support.
SanDisk: The Greatest Pricing Leverage in Enterprise SSDs
The core SanDisk thesis is not a recovery in consumer flash, but the higher-value role of enterprise SSDs in inference architectures. Offloading key-value caches from expensive memory tiers to SSDs can alleviate inference memory bottlenecks, while hyperscalers’ training and inference services require high-speed access to massive datasets. Citi expects tight NAND supply and demand to persist through 2028 and believes vendors will improve profitability through price increases, long-term agreements, and capital-expenditure discipline.
Citi forecasts SanDisk’s fiscal fourth-quarter revenue at $8.695 billion, above the consensus estimate of $8.322 billion and the upper end of company guidance of $7.75–8.25 billion; its EPS forecast of $36.64 is also above the $34.10 consensus. For the following quarter, Citi forecasts revenue of $12.275 billion and EPS of $51.40, indicating exceptionally strong pricing leverage. This is also the key risk: Citi expects blended NAND ASPs to rise 236% year over year in 2026 and enterprise SSD ASPs to rise 330%. Increases of this magnitude cannot be assessed solely from the supply side; order volumes, customer acceptance, and long-term agreement coverage must also be validated.
Seagate Technology: The Purest “Capacity, Pricing, and Cost Reduction” Play
Seagate Technology is the clearest HDD supply-demand trade. Citi raised its price target from $1,150 to $1,240, increased its valuation multiple from 23x to 24x fiscal 2028 EPS, and lifted its fiscal 2027 revenue and EPS forecasts to $17.712 billion and $31.55, respectively, both above consensus. The bull case rests on higher EB shipments, smaller price declines, and greater cost savings from HAMR; the bear case is the exact opposite.
Mozaic 4+ began ramping in the March quarter and will scale further in fiscal 2027, making it a product metric that must be assessed separately in the earnings report. Citi believes the company is still “shipping below industry demand,” which supports pricing but also means that any certification, yield, or supply-chain issue could delay revenue realization. Under Citi’s scenarios, Seagate’s bull-case price target is $1,618, its base case is $1,240, and its bear case is $740—a very wide range. The same variables that create high upside leverage also mean that misjudging EB growth or HAMR cost reductions could produce a double hit.
Western Digital: An Additional Capital-Allocation Catalyst Beyond the HDD Cycle
Western Digital’s HDD thesis resembles Seagate’s, but it also offers catalysts from monetizing its SanDisk stake, reducing debt, and increasing shareholder returns. Citi raised its price target from $685 to $800 and forecasts fiscal 2027 revenue of $19.236 billion and EPS of $21.04, above consensus estimates of $17.569 billion and $17.80, respectively. If the stake is monetized successfully, balance-sheet improvement could translate industry strength into shareholder returns more quickly.
This does not make Western Digital a low-risk investment. Citi’s bull-, base-, and bear-case price targets are $1,064, $800, and $495, respectively. The key variables remain enterprise HDD EB shipments, price declines, and margins. The company must also catch up in HAMR: if Seagate continues to extend its first-mover advantage, Western Digital could lag in product mix and cost improvement. Following earnings, investors should assess capital allocation separately from operating execution; proceeds from stake sales and debt reduction should not obscure pricing or technology issues in the HDD business.
Global Storage Deep Dive: Diverging Earnings in 2Q26—Can Better 3Q Pricing Restart the Storage-Sector Re-Rating?
Optical Interconnects and Connectors: The Second Layer of Growth, with Margins as the Key
Growth in AI server volumes is only the first step; connection density within and between racks is increasing even faster. High-density systems must connect more CPUs, GPUs, memory, and storage, potentially expanding the data-center switch market from $41 billion in 2025 to $60 billion in 2026, $84 billion in 2027, and $111 billion in 2028. Connectors and optical fiber are not optional accessories; they are the physical foundation enabling compute resources to achieve cluster-level efficiency.
AI Networking and Interconnect Hardware, Part I: Value Migration Behind 1.6T/3.2T—Who Benefits Most Across Switching, Copper Interconnects, Optical Interconnects, and the Physical Layer?
Corning: Revenue Is Not the Main Story—Margins Are
Corning’s most notable feature is the combination of below-consensus revenue and above-consensus profitability. Citi forecasts fiscal 2027 core revenue of $21.529 billion, below the $22.368 billion consensus. However, it expects a gross margin of 41.8%, well above the market’s 39.1%, while its EPS forecast of $4.30 also exceeds the $4.21 consensus. This indicates that Corning’s valuation thesis is not simply about chasing optical-fiber revenue; it rests on margin expansion driven by the optical communications product mix, a recovery in the solar business, and improved utilization.
Citi raised Corning’s price target from $225 to $240, based on approximately 35x 2028 EPS discounted back one year. Using 2028 earnings suggests that the AI optical-communications cycle could be prolonged, but also that the valuation is highly sensitive to execution. Key metrics to assess in the earnings report include optical-communications revenue, order visibility, solar capacity utilization, gross margin, and free cash flow. If optical communications remain strong but margins fail to improve, the market will question whether incremental revenue is being absorbed by capacity expansion, product transitions, or higher costs. Conversely, slightly weaker revenue accompanied by sustained margin outperformance would provide stronger evidence of earnings quality.
