
AI Compute ROIC Deep Dive: How 1GW GB300, GPU Leasing, and Model APIs Can Deliver 25%–50% Returns
目录
TL;DR
I. Capex Is Not the Answer; Revenue per 1GW Is
II. Three Business Models: All Appear Profitable, but the Quality of Returns Differs Significantly
III. GPU Leasing’s 31% ROIC Depends on Pricing Discipline and Full Utilization
IV. Model APIs on Owned Compute Offer a 46% Return—the Most Attractive Path, but Also the Hardest to Defend
V. Renting Compute Is Not Inherently Easy—the Cloud Provider May Capture Most of the Profit First
VI. Returns of 25%–50% Are Ultimately Determined by Six Variables
VII. Why Model Margins Are High but Cloud Providers’ Financial Statements Are Not Yet as Attractive
VIII. The Four Major Platforms Have Different Return Pathways
IX. Where the Market May Actually Be Wrong
X. How to Falsify This Framework Over the Next Four Quarters
XI. Conclusion: AI Infrastructure Has Entered a Capital-Returns Trade
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The next phase of AI infrastructure will no longer be about who spends more, but who can convert every 1GW of compute into revenue, profit, and free cash flow faster.
TL;DR
The central debate over this AI capex cycle has shifted from “Does demand exist?” to “When will returns materialize?” Using a 1GW GB300 data center as a common basis, Morgan Stanley outlines three paths: hyperscalers leasing GPUs generate an approximately 31% return on invested capital (ROIC); model companies selling APIs using owned compute generate approximately 46% ROIC; and model companies selling APIs using third-party rented compute generate an illustrative after-tax margin of approximately 25%. For the first two, after-tax operating profit can be divided by the $39.0 billion capital investment. The third lacks a comparable capital denominator and cannot be compared mechanically.
The base case is not conservative. GPU leasing requires approximately 75% utilization and pricing of $8.5 per hour. Model APIs running on owned compute require 65% of capacity to be allocated to inference, throughput of 2,750 tokens per GPU per second, and pricing of $1.75 per million tokens. Returns decline rapidly if any variable weakens. Moreover, more expensive models often have lower throughput, so token pricing and revenue per GW are not simply proportional.
Infrastructure ownership determines how profits are distributed. Self-built compute is capital-intensive, but keeps rental payments in-house and generates higher profits once capacity is fully utilized. Renting compute appears asset-light, but requires most revenue to be paid to the cloud provider first. In the report’s third-party compute scenario, revenue is $40.5 billion and compute rental expense is $27.9 billion. If revenue is also discounted for utilization while rent remains fixed, the profit buffer becomes very thin.
Recent company disclosures show that neither demand nor returns are merely theoretical: Microsoft’s AI business has exceeded $37.0 billion in annualized revenue, Amazon AWS generated $37.6 billion in quarterly revenue, Google Cloud has surpassed $70.0 billion in annualized revenue, and Meta’s advertising revenue continues to grow rapidly. However, all four companies have also taken capex to a new level, bringing depreciation, financing, and free-cash-flow pressure onto their financial statements. Revenue growth must continue to outpace incremental depreciation to validate the high-ROIC path.
Six core metrics warrant monitoring: GPU and accelerator utilization, compute pricing per unit, token throughput, the share of capacity allocated to inference, depreciation and electricity costs per unit of revenue, and AI revenue growth relative to capex growth. If pricing and utilization decline simultaneously, or depreciation consistently grows faster than AI revenue, the 25%–50% return path will be disproven.
I. Capex Is Not the Answer; Revenue per 1GW Is
Over the past two years, the analytical framework for AI infrastructure has focused primarily on supply: whoever can secure GPUs, lock in power, and connect data centers to the grid earlier is more likely to generate revenue. Morgan Stanley previously estimated that cumulative capex by major hyperscalers could exceed $1.4 trillion, with compute capacity expanding approximately 4-fold from 2025 to 2028 to reach approximately 120GW. This explains why orders for chips, power equipment, networking, and data centers continue to grow, but it does not answer shareholders’ most important question: how much money will these assets ultimately earn?
From an accounting perspective, capex first enters the balance sheet and subsequently flows through the income statement as depreciation. The faster servers and GPUs enter service, the sooner depreciation begins. If customer usage, model calls, and application revenue ramp more slowly, margins will come under pressure first. Conversely, if capacity remains undersupplied for an extended period, with stable pricing and high utilization, capital-intensive assets can generate high returns. In other words, capex itself is neither bullish nor bearish; what matters is the race between revenue realization and the cost of capital.
Our previous analysis of the 138GW data-center expansion plan examined “where the money is being invested.” This 1GW model goes one step further and begins to answer “how every dollar invested is earned back.” It condenses complex AI infrastructure economics into three layers: first, an asset cost of $39.0 billion/GW; second, revenue generated from GPU-hours or tokens; and third, returns after depreciation, electricity, operations and maintenance, compute rent, and taxes.
II. Three Business Models: All Appear Profitable, but the Quality of Returns Differs Significantly
The report compares three business models using the same GB300 generation and the same GW basis. Its greatest advantage is that it enables the profit pools to be compared side by side for the first time. Its biggest pitfall is that the three “ROIC” figures are not calculated on fully comparable bases.
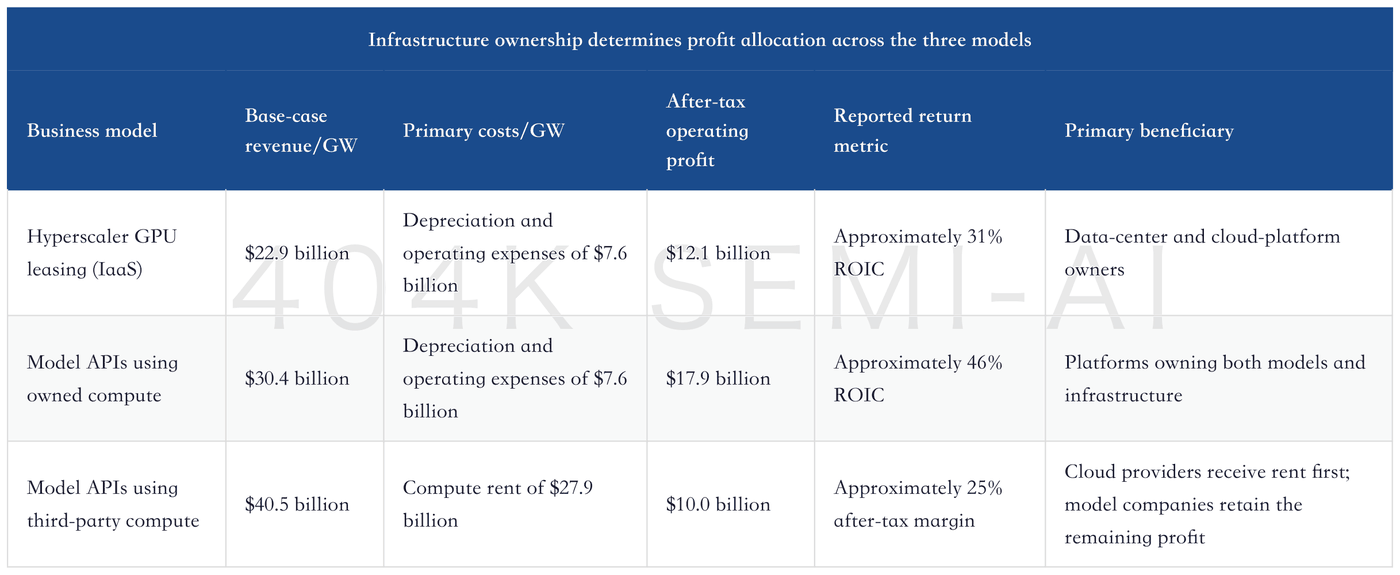
The first and second models both assume a $39.0 billion investment to build 1GW of GB300 capacity. Their respective after-tax operating profits of $12.1 billion and $17.9 billion can therefore be divided directly by invested capital, producing ROICs of 31% and 46%. The third model does not purchase the $39.0 billion asset, and the report labels its after-tax margin as an illustrative “ROIC.” This is useful for assessing operating profitability, but it neither proves that an asset-light model company earns only a 25% return on invested capital nor permits direct ranking against the first two models.
The third-party compute scenario does not apply the same 75% utilization treatment used for owned infrastructure, causing revenue/GW to rise from $30.4 billion to $40.5 billion. A purely mechanical stress test illustrates the sensitivity: discounting $40.5 billion of revenue to 75%, or approximately $30.4 billion, while holding rent unchanged at $27.9 billion would reduce pre-tax profit from $12.6 billion to approximately $2.5 billion. After-tax profit would be approximately $2.0 billion, leaving an after-tax margin of only approximately 6.5%. This is not the report’s original forecast, but it clearly exposes the asset-light model’s vulnerability—revenue fluctuates with usage, while rent and reserved-capacity commitments may be more rigid.
III. GPU Leasing’s 31% ROIC Depends on Pricing Discipline and Full Utilization
The economics of GPU infrastructure as a service (IaaS) are the most straightforward. A 1GW data center can accommodate approximately 410,256 GB300 GPUs, theoretically generating approximately 3.6 billion GPU-hours annually. At 75% utilization and pricing of $8.5 per hour, revenue would be approximately $22.9 billion. Costs include $4.6 billion of IT-equipment depreciation, $1.1 billion of non-IT depreciation, and approximately $2.0 billion of electricity, maintenance, and other operating expenses, totaling approximately $7.6 billion. After-tax operating profit would be approximately $12.1 billion, generating an approximately 31% return on $39.0 billion of invested capital.
