
目录
Executive Summary
I. A New Constraint Layer Is Emerging in Compute Expansion
II. Broadcom: Near-Term Acceleration and a Fiscal 2027 Downgrade Can Coexist
III. $100 Billion of Financing Takes Chip Competition into the Capital Layer
IV. Broadcom Valuation: Growth Remains Intact, but the Margin for Error Is Narrowing
V. NVIDIA: Extending Control Both Downstream and Upstream of Compute
VI. The Poolside Transaction Fills a Gap in the Model-Development Toolchain
VII. Terafab: Job Openings Show Ambition; Satellite Images Show the Stage of Development
VIII. Industry Value Will Be Reallocated According to “Project Control”
IX. Five Milestones to Track Over the Next 12 Months
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
AI chip companies are extending competition into financing, land, power, data-center facilities, model development, and wafer fabrication—shifting both industry value and risk in the process.
Executive Summary
Broadcom’s (AVGO) AI revenue continues to accelerate in the near term. The report forecasts approximately $16 billion in fiscal Q3 2026 and $21 billion to $22 billion in fiscal Q4. However, its fiscal 2027 forecast was cut by approximately $5 billion to approximately $130 billion, with tensor processor shipments reduced to approximately 6.4 million units.
The downgrade does not alter the fiscal 2028 expansion trajectory. The report expects Broadcom’s fiscal 2028 AI revenue to approach $200 billion, with powered-shell readiness emerging as the principal constraint on timing.
Broadcom’s proposed participation in approximately $100 billion of financing would support roughly 2 GW of deployment. As chip suppliers begin helping customers secure long-term capital, financing capacity is becoming another determinant of success in custom-compute projects.
Nvidia is participating in land, power, and facility investments while providing credit support. Its initial projects are planned at 4.25 GW, expandable to approximately 8 GW. Nvidia has also secured Poolside’s model-development platform and team through a $6 billion licensing fee and a $1 billion investment, extending its vertical reach downstream into infrastructure and upstream into the model toolchain.
Terafab’s 44 job openings span lithography, deposition, etching, epitaxy, integration, and memory design. Cleanroom-construction roles have increased from 9% to 39% of openings. Satellite imagery still shows only limited site clearing: organizational build-out has begun, but physical construction remains at an early stage.
Future valuation dispersion will increasingly depend on 3 capabilities: securing infrastructure, controlling financing risk, and converting engineering plans into billable compute capacity. Announced investment figures and hiring volumes provide only evidence of progress; revenue, cash flow, and equipment installation are the ultimate proof points.
I. A New Constraint Layer Is Emerging in Compute Expansion
Over the past 2 years, the central issues in AI have been GPUs, custom chips, high-bandwidth memory, and advanced packaging. Chip supply remains critical, but the report’s 3 sets of evidence indicate that compute expansion is encountering upstream constraints: whether customers can secure long-term capital, campuses can obtain power, facilities can be delivered on schedule, and operating organizations can support multi-GW clusters.
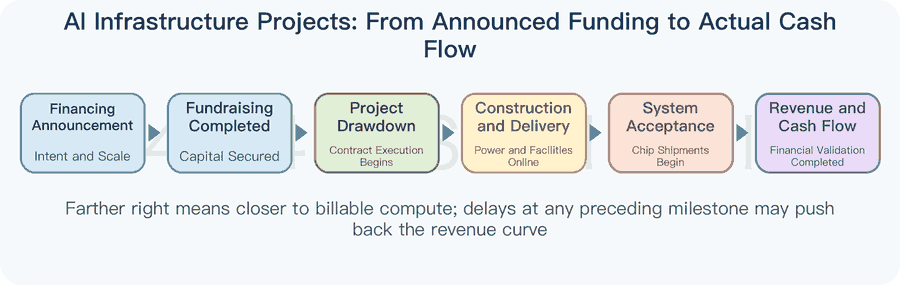
A single multi-GW project typically must pass through 5 stages: customer commitment, financing close, land acquisition and grid connection, delivery of powered facilities, and system acceptance. Capital and infrastructure determine the first 3 stages; large-scale chip shipments occur during the final 2.
This shift will reshape chip companies’ revenue functions. Even when chips and systems are ready, delays in land, power, or facilities will still defer shipments and revenue recognition. The report therefore links Broadcom’s AI revenue ramp to powered-shell readiness, rather than chip availability alone.
The supply chain is also shifting from linear procurement toward project-based delivery. Beyond supplying chips, vendors may participate in capital arrangements, credit support, project development, and long-term upgrades. This can extend order visibility, but also increases balance-sheet commitments, customer concentration, and execution risk.
Earlier supplier involvement in project planning can lock in technology choices, system specifications, and upgrade cycles. The tradeoff is a longer sales cycle, requiring revenue quality to be assessed alongside financing closure, customer creditworthiness, and campus utilization. The larger the contract, the more important project-level verification becomes.
II. Broadcom: Near-Term Acceleration and a Fiscal 2027 Downgrade Can Coexist
The report expects Broadcom’s fiscal Q3 2026 total revenue to come in slightly above expectations, with fiscal Q4 guidance of approximately $34 billion. AI revenue is projected at approximately $16 billion in fiscal Q3 and between $21 billion and $22 billion in fiscal Q4, with custom compute continuing to grow faster than AI networking.
Anthropic is the clearest source of near-term upside. The report estimates that its tensor processors will contribute approximately $2.5 billion in fiscal Q3 and $3.3 billion in fiscal Q4, totaling approximately $9.3 billion in calendar 2026. Google Cloud-related AI revenue is expected to increase by approximately $2 billion quarter over quarter in fiscal Q3 and by another approximately $1.5 billion in fiscal Q4.
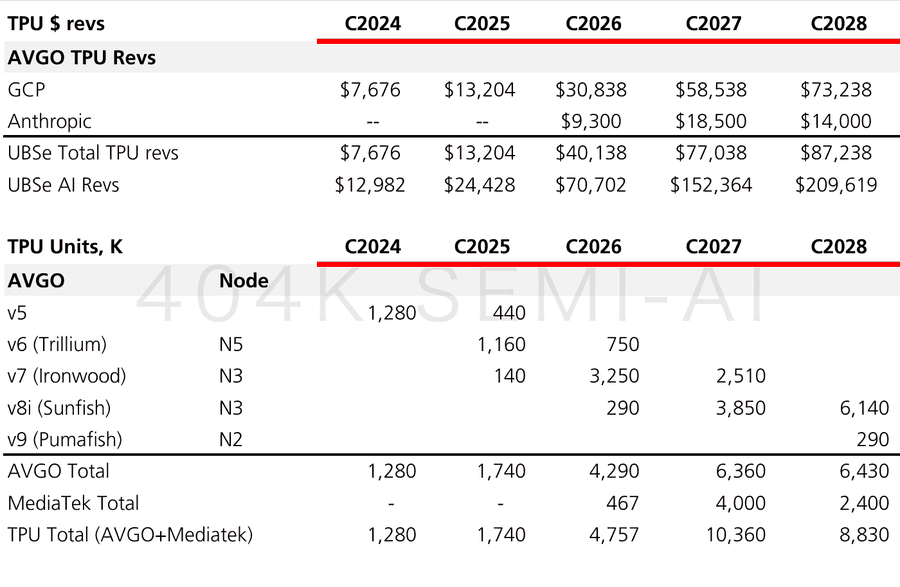
The growth curve is still being recalibrated. The report cut its fiscal 2027 Broadcom AI revenue forecast by approximately $5 billion to approximately $130 billion and reduced its calendar 2027 estimate for Broadcom tensor processor shipments to approximately 6.36 million units. The adjustment reflects shipment timing, particularly an earlier unit-volume assumption that proved too aggressive.
Customer mix provides some cushion. The report expects OpenAI to contribute approximately $1.25 billion and $12 billion in calendar 2026 and 2027, respectively, while Apple ramps more slowly. Meta custom compute is expected to remain broadly flat in fiscal 2026 before accelerating materially in fiscal 2027. Google remains the largest individual program, but greater customer diversification is beginning to improve the longer-term growth trajectory.
Approximately $200 billion of fiscal 2028 AI revenue is the next major anchor. Achieving it requires simultaneous progress across next-generation tensor processors, Anthropic, OpenAI, and additional custom-chip customers. A delay in any single project may not undermine the overall trend, but simultaneous delays across multiple powered facilities would directly depress the revenue curve.
III. $100 Billion of Financing Takes Chip Competition into the Capital Layer
The headline size of the Broadcom-related financing proposal is approximately $100 billion, comprising between $60 billion and $70 billion of senior secured debt and approximately $30 billion of subordinated debt, with Broadcom potentially providing partial guarantees. Blackstone and Apollo are expected to participate. The report estimates that this financing would support roughly 2 GW of deployment.
The arrangement is linked to the AI XPV framework launched in June 2026. XPV aims to support more than 20 GW of AI compute capacity by 2028, with initial projects including an Anthropic deployment exceeding 1 GW. Although $100 billion sounds enormous, it would fund only approximately one-tenth of the capacity contemplated by the 20 GW framework.
The economics have 3 layers. First, access to capital can influence which custom chips customers adopt. Second, suppliers can use financing commitments to increase project lock-in. Third, credit support can bring some customer and infrastructure risk back onto the supplier’s balance sheet.
Based on the report’s rough conversion, $100 billion for 2 GW implies approximately $50 billion of total financing per GW. This is not the value of the chip bill of materials: the capital must also fund land, power, facilities, networking, cooling, energy storage, and long-term operations and maintenance. Dividing the financing amount directly by chip volumes would materially overstate semiconductor revenue.
Senior secured and subordinated debt create a layered risk structure. When project cash flows perform as expected, long-duration capital expands customers’ deployment capacity. If utilization, construction progress, or customer credit deteriorates, subordinated capital absorbs losses first, while partial guarantees could transmit some losses back to Broadcom. The larger the financing package, the greater the need for separate disclosure of guarantee caps, collateral, drawdown conditions, and recourse provisions.
Financing commitments cannot be recognized directly as chip revenue. The debt must first be structured, backed by deployed assets, and drawn down, while campuses must still secure power and facilities. Financing translates into chip shipments only when deployment advances into equipment procurement and cluster acceptance.
IV. Broadcom Valuation: Growth Remains Intact, but the Margin for Error Is Narrowing
The report lowered its Broadcom price target from $485 to $470. The valuation is based on a sum-of-the-parts free-cash-flow model: approximately $35.1 billion of calendar 2027 infrastructure software free cash flow valued at approximately 12x enterprise value/free cash flow, and approximately $65.6 billion of semiconductor free cash flow valued at approximately 30x.
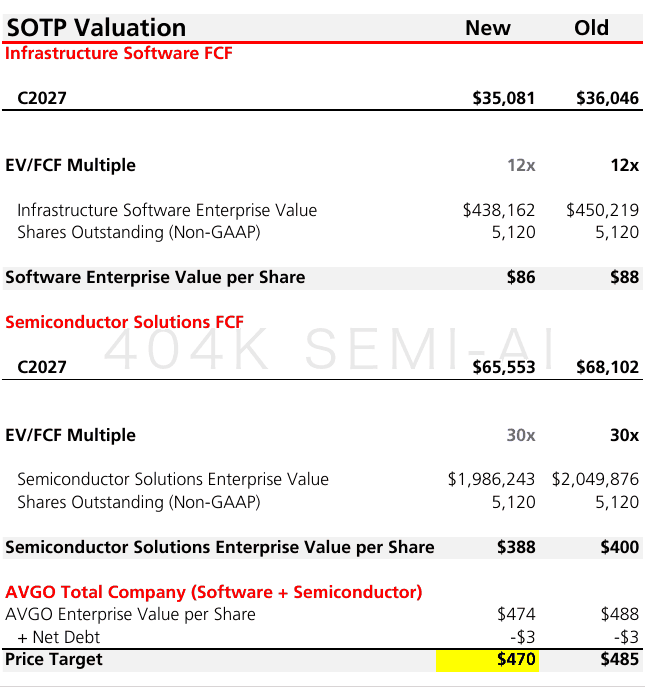
The model’s key sensitivity lies in the semiconductor segment. Changes to software cash flow and its valuation multiple are limited; the lower price target primarily reflects adjustments to AI revenue and semiconductor free cash flow. Custom-chip growth remains strong, but the market has already priced in a substantial portion of the anticipated fiscal 2027-fiscal 2028 expansion.
Broadcom trades at approximately 21x next-12-month earnings, above its approximately 18x 10-year average. This remains below the semiconductor index median of approximately 35x, but materially above Broadcom’s own longer-term valuation midpoint.
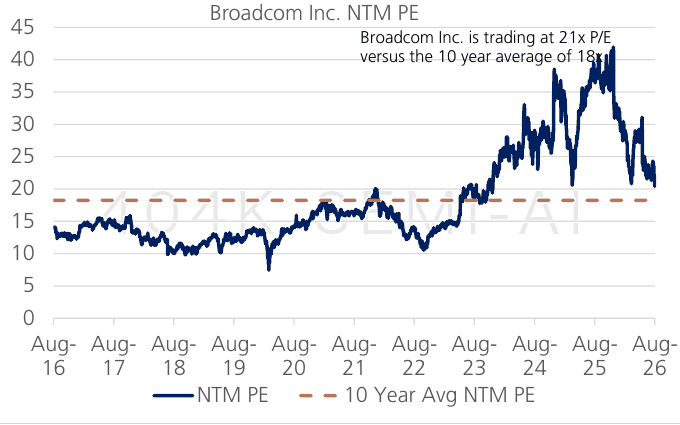
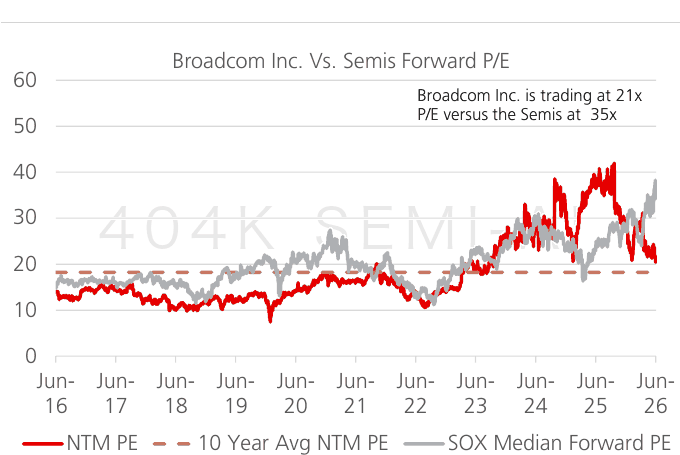
The discount to the industry suggests that investors still have reservations about Broadcom’s diversified business mix, while the premium to its own history shows that an AI-driven rerating has already occurred. Further valuation upside will depend more on revenue conversion and free cash flow than on reiterating the custom-chip market opportunity.
Signals that would weaken the model include further reductions in tensor processor unit estimates, delays to powered facilities, rising guarantee risk, and slower-than-expected production ramps among new customers. Supportive signals include earlier realization of fiscal 2028 revenue, financing projects converting into firm orders, and a rising contribution from customers other than Google.
The $470 price target is not independent of the operating assumptions. Every 10% change in software or semiconductor free cash flow—or any adjustment to the semiconductor segment’s 30x valuation multiple—would materially affect the target. The key variables to monitor are the pace at which revenue converts into cash and whether financing support consumes more capital.
V. NVIDIA: Extending Control Both Downstream and Upstream of Compute
The PORTS-Pike project illustrates NVIDIA’s expansion into infrastructure. OpenAI remains the tenant and operator, while NVIDIA, SB Energy, and other partners are helping secure land, power, and facilities through a $1.5 billion investment and up to $105 billion of residual-value or credit support.
Initial capacity is 4.25 GW, with an option to expand to approximately 8 GW. NVIDIA estimates that each generation of AI factory systems deployed at the campus could represent approximately 1.5 million GPUs and $150 billion–$200 billion in revenue, with multiple upgrades over the campus lifecycle.
These figures imply system revenue of approximately $100,000–$133,000 per GPU. This metric covers the entire AI factory system and should not be interpreted as the average selling price of a standalone GPU. It shows that the value of controlling the campus lies in recurring upgrades and system revenue, not a one-time chip sale.
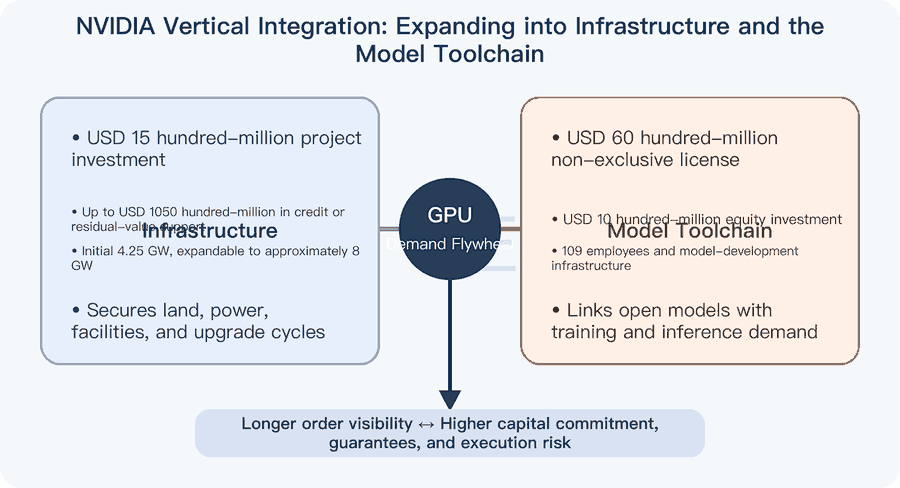
The maximum $105 billion of support should not be equated with an immediate cash outlay. Residual-value or credit support typically depends on project structure and specific triggers; cash exposure, guarantee risk, and asset-recovery risk must be assessed separately. NVIDIA’s scale and cash flow allow it to support a longer investment cycle, but capital efficiency will still determine valuation quality.
NVIDIA’s recent investments in SB Energy, Lancium, and Cloverleaf Infrastructure can be viewed as building compute-capacity corridors. If these corridors reliably provide land, power, and facilities, visibility into GPU demand will improve. Changes in project development, financing, or customer demand, however, would make vertical integration more complex to manage.
This model has 3 levels of involvement. The lightest is supplying chips and systems, with risk concentrated in the product. The middle tier involves arranging financing, securing resources, and providing credit support. The heaviest entails developing or operating AI factory assets. NVIDIA is currently moving primarily into the middle tier; the report identifies the possibility that it could eventually become a developer or operator, but does not present that as a foregone conclusion.
Deeper involvement increases customer switching costs and makes upgrade revenue more visible, but also raises depreciation, construction, financing, and utilization risks. Whether returns on capital remain intact will depend on how much of the asset burden partners assume, lease duration, when credit support is triggered, and whether successive GPU upgrades generate sufficient cash flow.
VI. The Poolside Transaction Fills a Gap in the Model-Development Toolchain
NVIDIA paid $6 billion for a non-exclusive license to Poolside’s Model Factory platform and recruited 109 employees; it also invested $1 billion at a $12 billion pre-money valuation. The transaction focuses on model-development infrastructure, training systems, engineering workflows, and talent—not the acquisition of a single model.
Model Factory develops open-weight mixture-of-experts models for agentic workloads. Integrating these capabilities could give NVIDIA an end-to-end loop spanning foundation-model development, GPU training, and GPU inference. As open models improve, more developers and enterprises may choose NVIDIA’s platform for both training and deployment.
The size of the $6 billion licensing fee also raises the bar for scrutiny. The platform must deliver verifiable incremental gains in model quality, training efficiency, developer adoption, and inference demand. If talent integration and the open-model ecosystem make limited progress, the license will look more like an expensive purchase of time. If it accelerates model iteration and drives compute demand, the software investment will reinforce hardware demand.
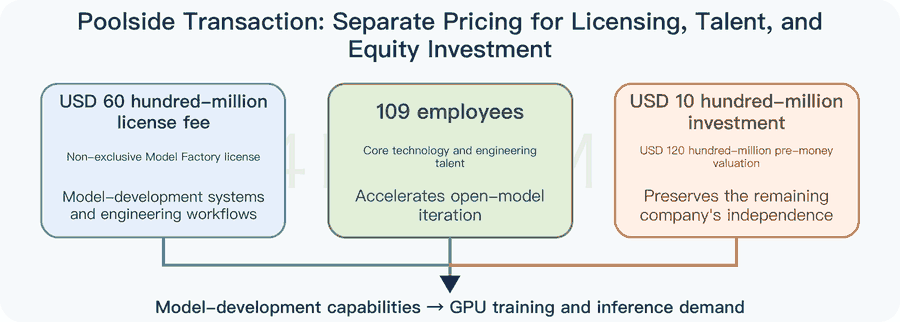
The non-exclusive license preserves the independence of Poolside’s remaining business and means NVIDIA did not obtain full exclusivity. Returns must come from faster model iteration, talent retention, and platform synergies rather than preventing competitors from using the relevant technology. Retention of the 109 employees—and their actual responsibilities—will affect the success of the integration.
NVIDIA is extending control in two directions at once: downstream into land, power, and facilities, and upstream into model-development tools and talent. Both support GPU demand, but the middle of the chain still requires cooperation from cloud providers, AI labs, and capital providers. A more complete platform also brings greater responsibility across the value chain.
VII. Terafab: Job Openings Show Ambition; Satellite Images Show the Stage of Development
Terafab-related job openings reached 44 in July 2026, mostly targeting senior engineers with high-volume manufacturing and fab-operations experience. Roles span lithography, deposition, dry etch, wet etch, epitaxy, implantation, integration, testing, and thin films. The organizational design resembles a full-scale fab rather than a limited set of process modules.
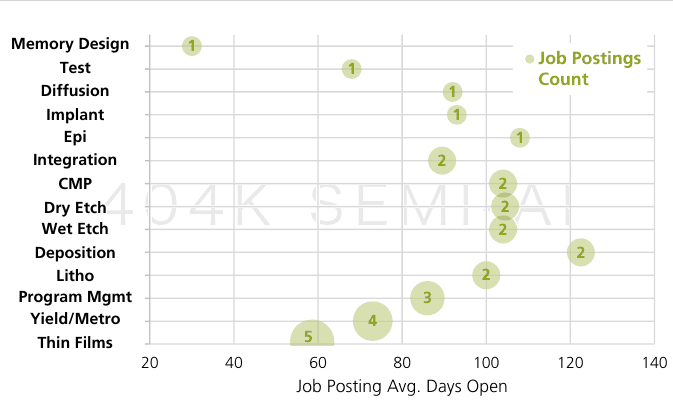
Hiring locations provide another clue. Several roles were posted in both Austin, Texas, and Hsinchu, indicating that the project aims to attract experienced wafer-manufacturing talent. It remains unclear how the Hsinchu positions will directly support the ramp-up of the Texas fab. The geographic distribution demonstrates hiring intent, but not that technology transfer has been completed.
Memory-design and memory-integration roles are more revealing. They indicate that Terafab is exploring in-house memory-manufacturing capabilities. The source of the required memory IP remains a major gap, as incumbent suppliers have limited incentive to license core IP to a potential new competitor.
Job postings are a point-in-time inventory affected by duplicate listings, positions left open for long periods, and reuse across locations. They are more useful for assessing organizational scope and urgency than for directly estimating headcount, capital expenditure, or the start of mass production. The recruitment data has been screened for anomalies, but there will still be attrition between job postings and completed hires.
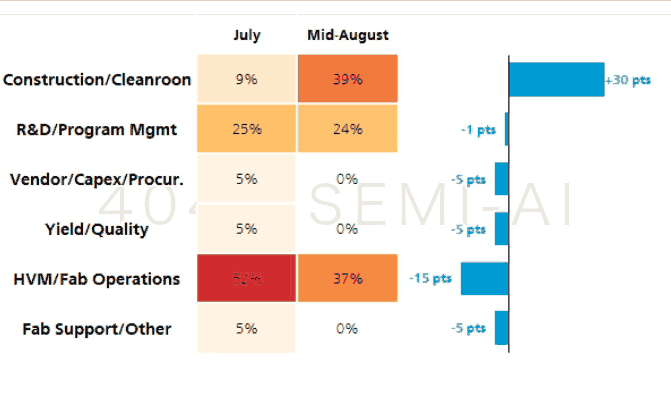
Cleanroom-construction roles increased from 9% of openings in July to 39% by mid-August, a rise of 30 percentage points that made them the largest category. High-volume manufacturing and fab-operations roles declined from 52% to 37%, while R&D; and project management remained at approximately 24%. The hiring mix is shifting from operational preparation toward construction readiness.
Satellite imagery provides a necessary cross-check. The Grimes County campus remains at a very early stage, with mainly limited forest clearing and site preparation visible. Signs of temporary equipment or machinery storage appear near A15, but several engineering milestones remain before cleanroom completion, equipment move-in, and mass production.
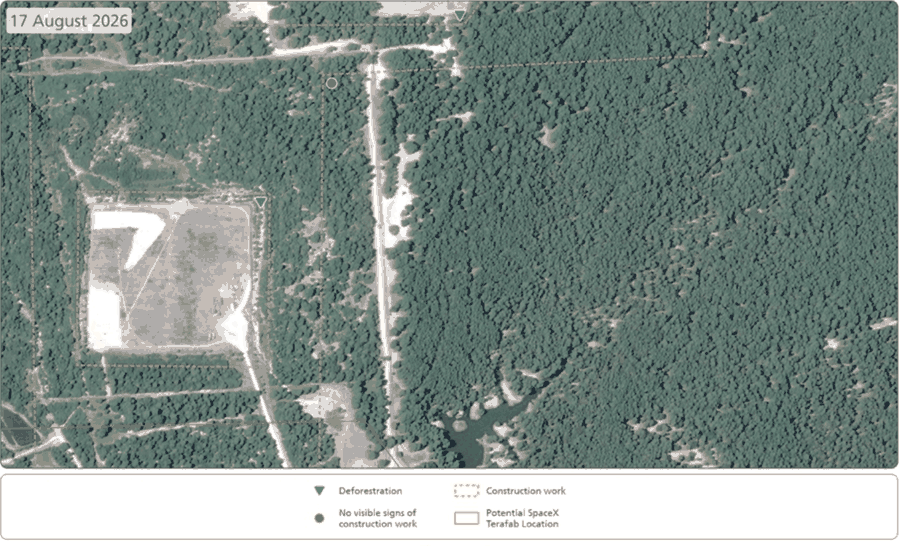
Job postings and satellite imagery must be interpreted together. The broader the functional coverage of hiring, the more credible the project’s intent; the more limited the visible construction, the more cautiously the revenue timeline should be assessed. Directly extrapolating 44 openings into equipment orders would overstate near-term progress, while ignoring the rapid increase in cleanroom roles would understate the shift toward construction readiness.
Evidence for a manufacturing project can be divided into 5 levels: hiring and organization, permitting and civil works, cleanroom and MEP systems, equipment move-in, and pilot production and yields. Terafab is currently positioned mainly between the first 2 levels. Semiconductor-equipment demand and capacity scale will have a more reliable quantitative basis only after equipment lists, move-in schedules, and pilot-line results emerge.
VIII. Industry Value Will Be Reallocated According to “Project Control”
Broadcom, NVIDIA, and Terafab represent three paths to control. Broadcom binds customers to deployments through custom silicon and financing platforms; NVIDIA connects GPUs, infrastructure, and the model-development toolchain; Terafab is attempting to extend design requirements into manufacturing and memory capabilities.
This shift introduces new dimensions for comparing semiconductor companies. Technical performance remains the price of admission, but financing structures determine whether projects can break ground, power and facilities determine when systems come online, and manufacturing and software organizations determine the pace of upgrades. Companies controlling more points in the chain can secure longer order visibility, but are also more exposed to project delays and tied-up capital.
For semiconductor-equipment companies, Terafab’s significance lies in the potential addition of a new fab with broad process coverage. Current openings already span the principal front-end steps, but equipment procurement still depends on project budgets, the selected process flow, cleanroom development, and equipment tenders. Equipment move-in would provide stronger evidence of revenue than hiring.
For cloud providers and AI labs, additional financing and infrastructure partners expand deployment options. Customers can gain access to more dedicated, long-duration compute capacity, but may also assume longer leases, greater concentration in a single technology roadmap, and more complex financing obligations. Better demand visibility does not mean end-market returns have already been proven.
Project control will appear across 3 financial statements. The income statement captures chip, system, and software revenue; the cash flow statement captures prepayments, capital expenditure, and free cash flow; and the balance sheet captures investments, guarantees, and long-term obligations. Focusing only on revenue overlooks financing and asset risk, while focusing only on capital expenditure understates the value of locking in long-term orders.
The sequence of benefits for semiconductor-equipment companies also varies. The site and cleanroom stages first affect construction and facility-support supply chains. Only after the process flow is frozen does demand advance to lithography, deposition, etch, cleaning, metrology, and packaging equipment. Job coverage can indicate the direction of demand, but equipment orders determine the revenue cadence.
IX. Five Milestones to Track Over the Next 12 Months
Verify whether Broadcom’s AI revenue approaches $16 billion and $21 billion–$22 billion in fiscal Q3 and Q4 2026, respectively. Quarterly growth from Anthropic and Google Cloud should explain most of the change.
Monitor whether Broadcom’s approximately $130 billion fiscal 2027 AI revenue estimate is revised down further. Key components are tensor processor unit volumes, OpenAI’s production ramp, Apple’s progress, and revenue from customers beyond Google.
Distinguish among financing announcements, completed fundraising, project drawdowns, infrastructure construction starts, and chip orders. The approximately $100 billion financing plan will provide greater revenue visibility only after clearing the latter four milestones.
Track land, power, facility delivery, and credit-support terms for Nvidia’s infrastructure projects. Whether the initial 4.25 GW of capacity proceeds on schedule will be a more meaningful validation of the business model than the longer-term 8 GW option.
Track Terafab’s transition from hiring to equipment deployment. Cleanroom construction, environmental and building permits, equipment tenders, process IP, pilot-line installation, and yield validation form a sequential chain of evidence. If hiring increases while physical construction remains stalled for an extended period, the project timeline will need to be pushed back.
The three threads ultimately converge on cash flow. Broadcom must convert custom silicon and financed projects into semiconductor free cash flow; Nvidia must demonstrate that vertical investment strengthens GPU demand without diluting capital efficiency; and Terafab must translate organizational ambition into an operational production line. AI chip competition has entered the balance-sheet phase, but the winners will still be determined by billable compute, actual cash flow, and engineering execution.