
目录
Executive Summary
I. ABF Has Entered a Seller’s Market
II. Server CPUs Re-Emerge as the Main Driver of Demand Upgrades
III. Concentrated Capacity Does Not Mean Supply Can Ramp Quickly
IV. Pricing Power Is Flowing Through to Gross Margin; Pass-Through Speed Determines the Ranking
V. All Three Companies Are Growing Rapidly, but Their Earnings Drivers Differ
VI. Two 2030 Models Produce Different Winners
VII. Why BofA’s 19% Shortfall Is Not Directly Comparable with Goldman Sachs’s 51%
8. Higher Price Targets Show the Market Has Already Priced In Part of the Upside
9. What Could End the Sellers’ Market Early
10. Ten Public Data Points to Test the Thesis
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
BofA has raised its forecasts for both the ABF supply shortfall and server CPU demand. Industry pricing power is now moving beyond quotations and into gross margins. The ultimate earnings upside will depend on qualified high-end capacity, customer share, and the pace of price pass-through.
Executive Summary
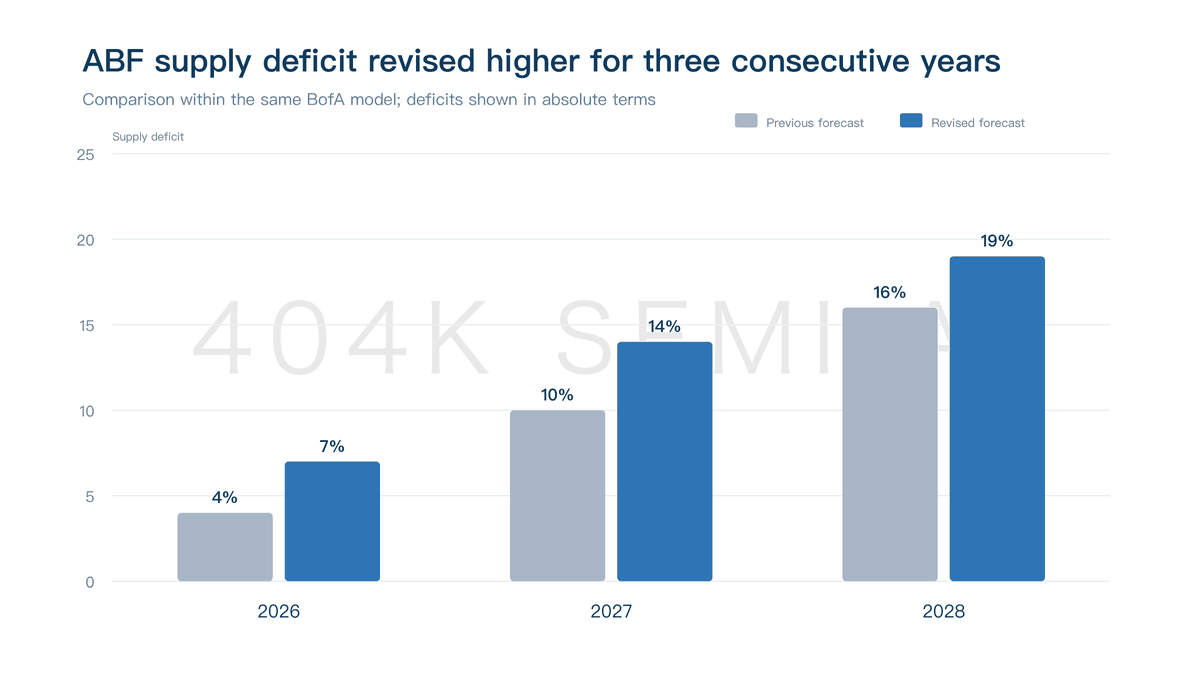
BofA raised its ABF supply-gap forecasts to 7% in 2026, 14% in 2027, and 19% in 2028. Its previous forecasts were 4%, 10%, and 16%, respectively. The widening shortfall across all 3 years indicates that incremental demand continues to outpace the ramp-up of qualified capacity, strengthening the industry’s pricing power.
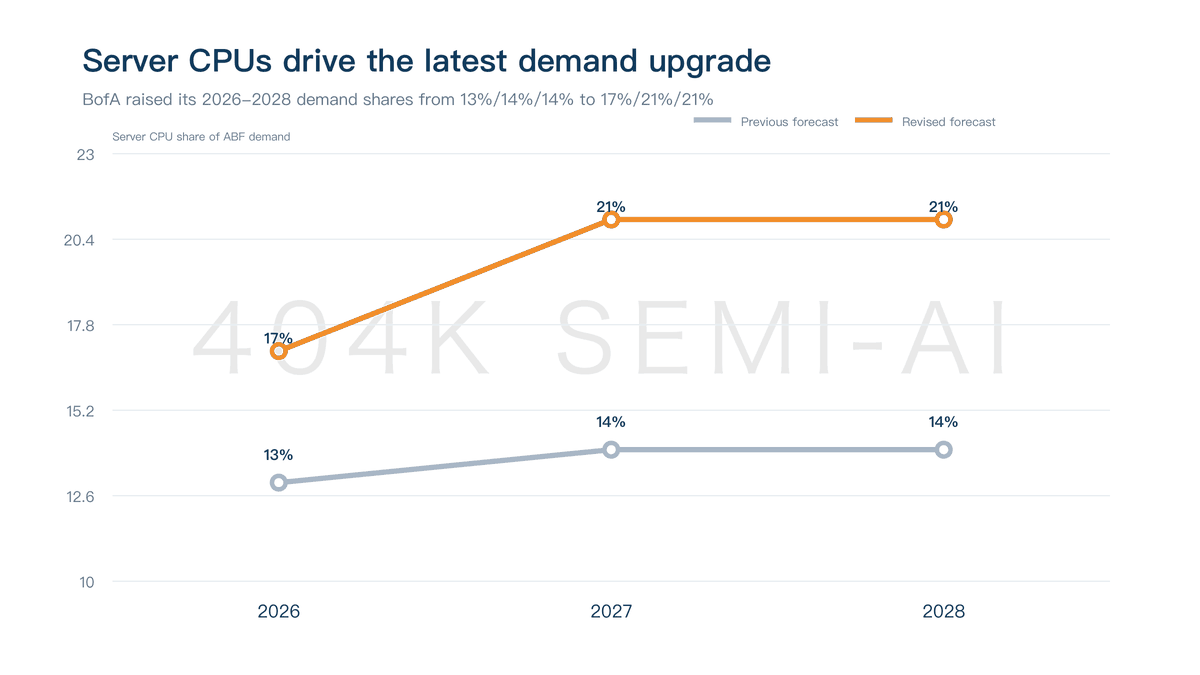
Server CPUs are the most important new source of demand. BofA increased its estimates for server CPUs’ share of ABF demand from 13%/14%/14% in 2026/2027/2028 to 17%/21%/21%. GPUs and custom ASICs continue to grow, while CPU platform upgrades are increasing substrate area, layer count, and content value, creating a more diversified demand base.
Price increases are already flowing through the income statement. In 2Q26, gross margins at Nan Ya PCB, Unimicron, and Kinsus improved sequentially by 890, 680, and 490 basis points, respectively. Nan Ya PCB has the strongest share and pricing leverage in high-end switch chips; Unimicron benefits from scale and high-end product expansion; and Kinsus offers longer-term upside through AI CPUs, GPUs, ASICs, and BT substrates.
All 3 companies can grow, but their earnings drivers differ materially. BofA expects revenue at Unimicron, Nan Ya PCB, and Kinsus to expand rapidly over 2025-2028, with gross margins reaching 39.8%, 41.3%, and 37.0%, respectively, in 2028. Scale, pricing, customer share, and operating leverage will collectively determine the ultimate profit outcome.
There is still substantial upside through 2030, and no single scenario fully captures the outlook. The top-down model is more bullish on share gains at Kinsus, while the bottom-up model favors compound average-selling-price growth at Unimicron and Nan Ya PCB. The models identify different winners, underscoring that demand, market share, and pricing are all essential.
The elevated price targets already embed demanding execution requirements. BofA raised its price targets for Unimicron, Nan Ya PCB, and Kinsus to NT$1,400, NT$1,700, and NT$1,250, respectively, all based on 35 times 2H27-1H28E earnings per share. Its 2027-2028 earnings forecasts for Nan Ya PCB and Unimicron remain below consensus, making sustained delivery on gross margins, lead times, and customer share essential.
I. ABF Has Entered a Seller’s Market
BofA’s August 19 report highlights a clear shift: ABF demand growth is once again outpacing supply growth, with the gap widening in each of the next 3 years. BofA now forecasts supply shortfalls of 7%, 14%, and 19% in 2026, 2027, and 2028, respectively—up 3, 4, and 3 percentage points from its previous model.
These figures imply more than simply “shortages.” A seller’s market requires high utilization, lengthening lead times, customers locking in volumes earlier, rising prices, and improving supplier margins. Quotation headlines can be driven by channel sentiment, but gross margins and customer bookings are harder to inflate for long. BofA’s report already identifies the first evidence in profitability, with all 3 Taiwanese substrate manufacturers posting material gross-margin improvement in 2Q26.
The higher shortfall forecasts also bring the industry debate forward. Previously, investors focused on whether AI substrates would become scarce after 2027; pricing and earnings are now testable as early as 2026. If high-end product lead times continue to lengthen, long-term contracts are repriced, and gross margins rise over the next 2 quarters, the seller’s market will move from forecast to operating reality.
ABF substrates sit between chip packages and motherboards, providing high-density interconnects, power delivery, signal transmission, and mechanical support. As AI chips grow larger, add more I/O, and consume more power, substrates require greater area, more layers, and finer circuitry. As product complexity rises, the qualified output area delivered by the same equipment may actually decline. Demand growth and lower effective capacity per unit of equipment are occurring simultaneously, making the shortfall steeper than chip shipment growth alone would suggest.
ABF Substrates In Depth: The Packaging Foundation of AI Compute—from Technical Fundamentals to Supply-Demand Dynamics and Company Rankings
The previous industry overview covered ABF’s technical role, qualification cycles, and effective capacity. The essential conclusion is that factory construction, equipment installation, and qualified output are 3 distinct stages. Capacity-expansion announcements address nominal capacity; customers need high-end capacity that has passed qualification and can sustain stable mass production.
II. Server CPUs Re-Emerge as the Main Driver of Demand Upgrades
Server CPUs are the most easily underestimated change in BofA’s latest revisions. BofA raised its estimates for server CPUs’ share of ABF demand to 17%, 21%, and 21% in 2026, 2027, and 2028, respectively, from previous forecasts of 13%, 14%, and 14%. By 2027, the server CPU share is 7 percentage points above the prior model.
This revision broadens the demand base underpinning the ABF cycle. GPUs and server accelerators continue to drive demand for large, high-layer-count substrates; custom ASICs developed by cloud providers increase the number of platforms; and server CPU upgrades add another growth vector. AI systems still require CPUs for orchestration, general-purpose computing, data preprocessing, and control tasks, so growth in GPU volumes does not eliminate CPU demand. The more complex the platform architecture, the more specialized the division of labor among chips—and the more projects substrate suppliers can address.
Substrate content per server CPU is also increasing. New platforms require more high-speed I/O, stronger power delivery, and more complex packaging, driving greater substrate area, layer counts, and circuit density. On the first page of its report, BofA explicitly identifies stronger server CPU demand as the leading reason for the renewed widening of the supply-demand gap. It also places this demand alongside AI CPUs, GPUs, ASICs, and network switch chips within the same industry framework, indicating that growth is being driven by upgrades across multiple compute-chip categories.
A more diversified demand base reduces the impact of delays to any single platform. A postponed GPU may affect related substrate orders, while server CPUs, switch chips, and other ASICs could continue to grow. Supplier upside will depend on customer and product mix. Nan Ya PCB holds more than 50% share in high-end network-switch substrates; Kinsus is increasing revenue from AI CPUs, GPUs, and ASICs; and Unimicron’s advantages lie in scale, high-end technology, and relationships with major customers.
The demand model still has limitations. The higher server CPU share assumes sustained AI-infrastructure investment, on-schedule CPU platform ramps, and rising content per chip. If cloud providers delay server deployments, CPU platform transitions proceed more slowly than expected, or packaging designs reduce ABF area, the 21% share assumption would need to be revised downward.
III. Concentrated Capacity Does Not Mean Supply Can Ramp Quickly
Nominal ABF capacity is highly concentrated in 2026. BofA estimates that Ibiden and Unimicron account for 21% and 20%, respectively; Kyocera for approximately 16%; Shinko Electric Industries and Nan Ya PCB for approximately 11% each; and Kinsus and Samsung Electro-Mechanics for approximately 9% each. The top 2 suppliers collectively account for approximately 41%, and the top 7 for approximately 97%.
