
ABF Substrate Deep-Dive Update: 25% Shortfall by 2030, 20-30% BT Price Hikes, and AI ASIC Proliferation: Which of Unimicron, Nan Ya PCB, and Zhen Ding Can Deliver Most
目录
Too Long; Didn’t Read
1. The Key Point of This Upgrade Is Not Price Hikes, but the Cycle Endpoint Moving Later
2. Supply-Demand Ledger: Roughly 25% Shortfall by 2030, and the Price-Hike Cycle Is Not Just About 2026
III. Demand Side: AI Diffusion Is Turning ABF from a PC Cyclical into a System-Level Base Material
IV. Pricing Model: BT Rises First, ABF Follows, and Profit Elasticity Starts Flowing into Gross Margin
V. Company Ranking: Unimicron Is the Steadiest, Nan Ya PCB Has the Most Leverage, Zhen Ding Looks Most Like an Execution Option
VI. Global Peers: High-End Substrates Are Not Only a Taiwan Story; Ibiden and Samsung Electro-Mechanics Define the Technology Ceiling
VII. A-Share Mapping: Do Not Treat Every PCB Company as an ABF Proxy
VIII. Valuation: Why 25x 2028 P/E Is Not Necessarily Expensive
9. Risks: Watch Four Lines: Capacity Expansion, T-glass, CoWoP, and Weaker Demand
10. What to Track Over the Next Four Quarters
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The ABF trade is shifting from validation of 2026 price hikes to a re-rating of effective capacity through 2030. A 25% shortfall, BT moving up first, and AI ASIC proliferation show that substrates have moved from a PC cyclical product to a foundational compute material. The key question is no longer who announces capacity expansion, but who can convert pricing, customer lock-in, and yield into profit.
Too Long; Didn’t Read
The ABF pricing logic has shifted gears. Morgan Stanley raised its 2030 ABF demand/supply ratio from 122.3% in its prior model to 124.6%, implying roughly a 25% supply shortfall. This is not a normal quarterly price hike. It pushes the cycle endpoint from 2027 to 2030 and leads the market to start pricing high-end effective capacity, customer qualification, and materials lock-in.
BT rises first, ABF follows, and Nan Ya PCB has the most direct torque. Supply-chain checks show Nan Ya PCB’s 2Q26 BT substrate prices have already risen by roughly 20-30%, while ABF prices are up about 10%, with further price hikes still possible in the second half. Nan Ya PCB is the most aggressive on pricing execution; the 2028 ABF ASP growth assumption reaches 38.6% YoY, while the gross margin assumption rises to 53.0%.
Unimicron is the most stable core asset. Morgan Stanley raised its target price for Unimicron from NT$1,285 to NT$1,465 and lifted 2026-2028 EPS by 25%, 33%, and 14%, respectively. Its advantage is not short-term spot pricing, but scale profit driven jointly by AI ASICs, server CPUs, major customers, and high-end ABF specification upgrades.
Zhen Ding Tech is a qualification-breakthrough option. Zhen Ding’s target price was raised only from NT$666 to NT$690, and EPS was revised up by just 4%. But the focus is its Shenzhen ABF plant, Google TPU, Chinese AI chips, and AI server PCBs. If TPU substrates and AI PCB yields are delivered, Zhen Ding’s valuation torque will come from execution rather than price hikes.
For A-share mapping, distinguish PCB, CCL, and substrates. WUS Printed Circuit, Victory Giant Technology, Shennan Circuits, Goworld Technology, and Kinwong Electronic are more direct beneficiaries of AI server PCB and switch upgrades, while Shengyi Technology and Shengyi Electronics are more exposed to the CCL and electronic materials chain. The ABF shortfall will lift the industry’s valuation baseline, but not every PCB company should be treated simply as an ABF name.
The biggest counterevidence is not just capacity expansion. New capacity takes at least two years to alter supply-demand. In the near term, what really matters is 2Q gross margin, 3Q revenue guidance, T-glass constraints, customer LTA renewals, spillover from BT pricing, and alternative routes such as CoWoP. If demand weakens simultaneously across AI servers, general-purpose servers, or PCs, the price-hike trade will first pressure valuation multiples.
1. The Key Point of This Upgrade Is Not Price Hikes, but the Cycle Endpoint Moving Later
Morgan Stanley’s ABF substrate report is easily misread as “prices are rising faster than expected.” Pricing is indeed the near-term trigger, but the more important change is in the supply-demand model: the 2030 ABF demand/supply ratio is raised from 122.3% in the old model to 124.6%, implying roughly a 25% supply shortfall. This turns ABF from a 2026-2027 price-hike trade into a 2026-2030 effective-capacity scarcity trade.
Under the old framework, the market asked how much prices rose in 2Q this year, whether they could continue rising in the second half, and whether price hikes could flow into gross margins. Under the new framework, the market needs to ask who still has customer-recognized high-end capacity after 2028, who can secure qualifications for AI ASICs, server CPUs, networking chips, and TPUs, and who can preserve pricing power amid materials constraints, yield ramp, and customer LTAs.
ABF is not a standardized bulk material. It is the packaging foundation between high-performance chips and motherboards. Area, layer count, line density, warpage control, material stability, and qualification cycles all affect effective capacity. Nominal capacity expansion is not the same as deliverable capacity, and customers do not decide who carries next-generation large chips based only on quotes.
This explains why Morgan Stanley raised Unimicron, Nan Ya PCB, and Zhen Ding Tech at the same time, but not in exactly the same order. Unimicron ranks first because its customer position in AI ASICs and server CPUs is the most stable, and it still has 50% upside after the target-price increase. Nan Ya PCB ranks second because it has the most direct pricing leverage in BT and ABF, with strong pricing execution. Zhen Ding Tech ranks third because near-term EPS upgrades are limited, but Google TPU, Chinese AI chips, and AI server PCB add a qualification-breakthrough option.
ABF Substrate Deep Dive: The Packaging Foundation of AI Compute, from Introductory Framework to Supply-Demand Structure and Company Ranking
That historical thesis already made clear that ABF is the packaging foundation of AI compute. The incremental point in this update is that the duration of the foundation shortage has been extended, and profit allocation has also upgraded from “who has capacity” to “who has high-end effective capacity accepted by major customers.”
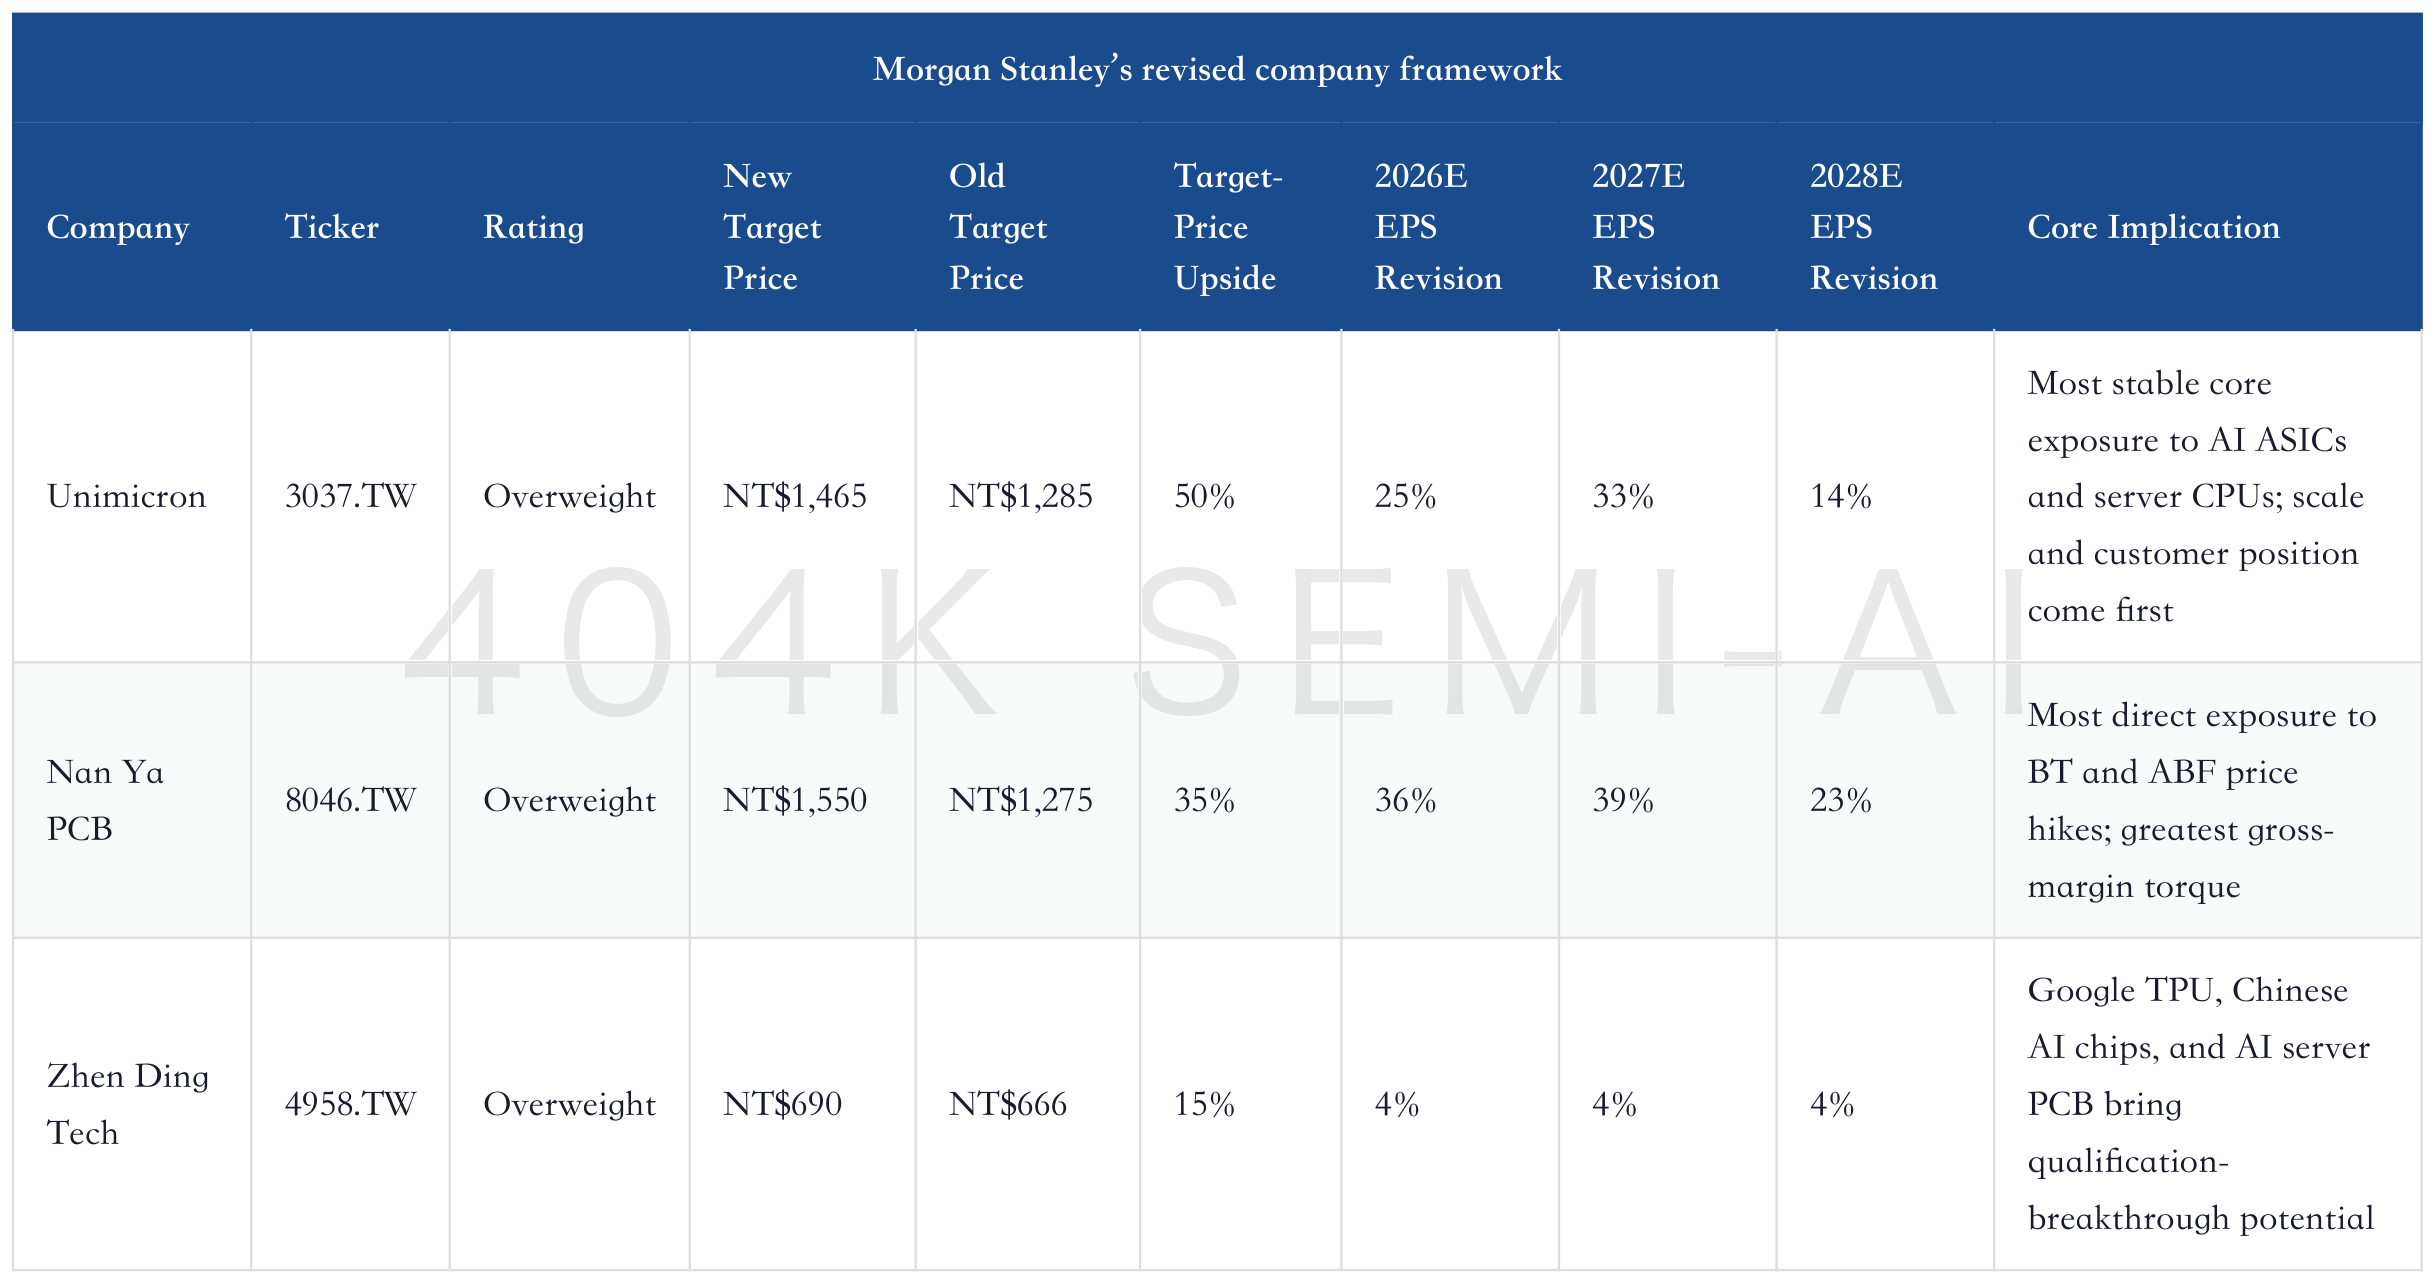
The key point in this table is not the target prices themselves, but the EPS revision structure. Nan Ya PCB has the largest revisions, showing that its price hikes are most sensitive to the income statement. Unimicron’s revisions are more medium- to long-term, indicating that the high-end ABF shortfall and major-customer structure should release profit year by year. Zhen Ding Tech has the smallest revisions, indicating it remains in a capability-validation phase and should not be placed in the same profit-delivery tier as Unimicron and Nan Ya PCB.
2. Supply-Demand Ledger: Roughly 25% Shortfall by 2030, and the Price-Hike Cycle Is Not Just About 2026
The most important line in the supply-demand model is the new 2030 demand/supply ratio of 124.6%. A demand/supply ratio above 100% means demand exceeds supply. Morgan Stanley’s model implies that 2030 ABF demand will be about one-quarter higher than supply. Compared with the old model, 2026-2028 is already tighter, and the shortfall continues to widen in 2029-2030.
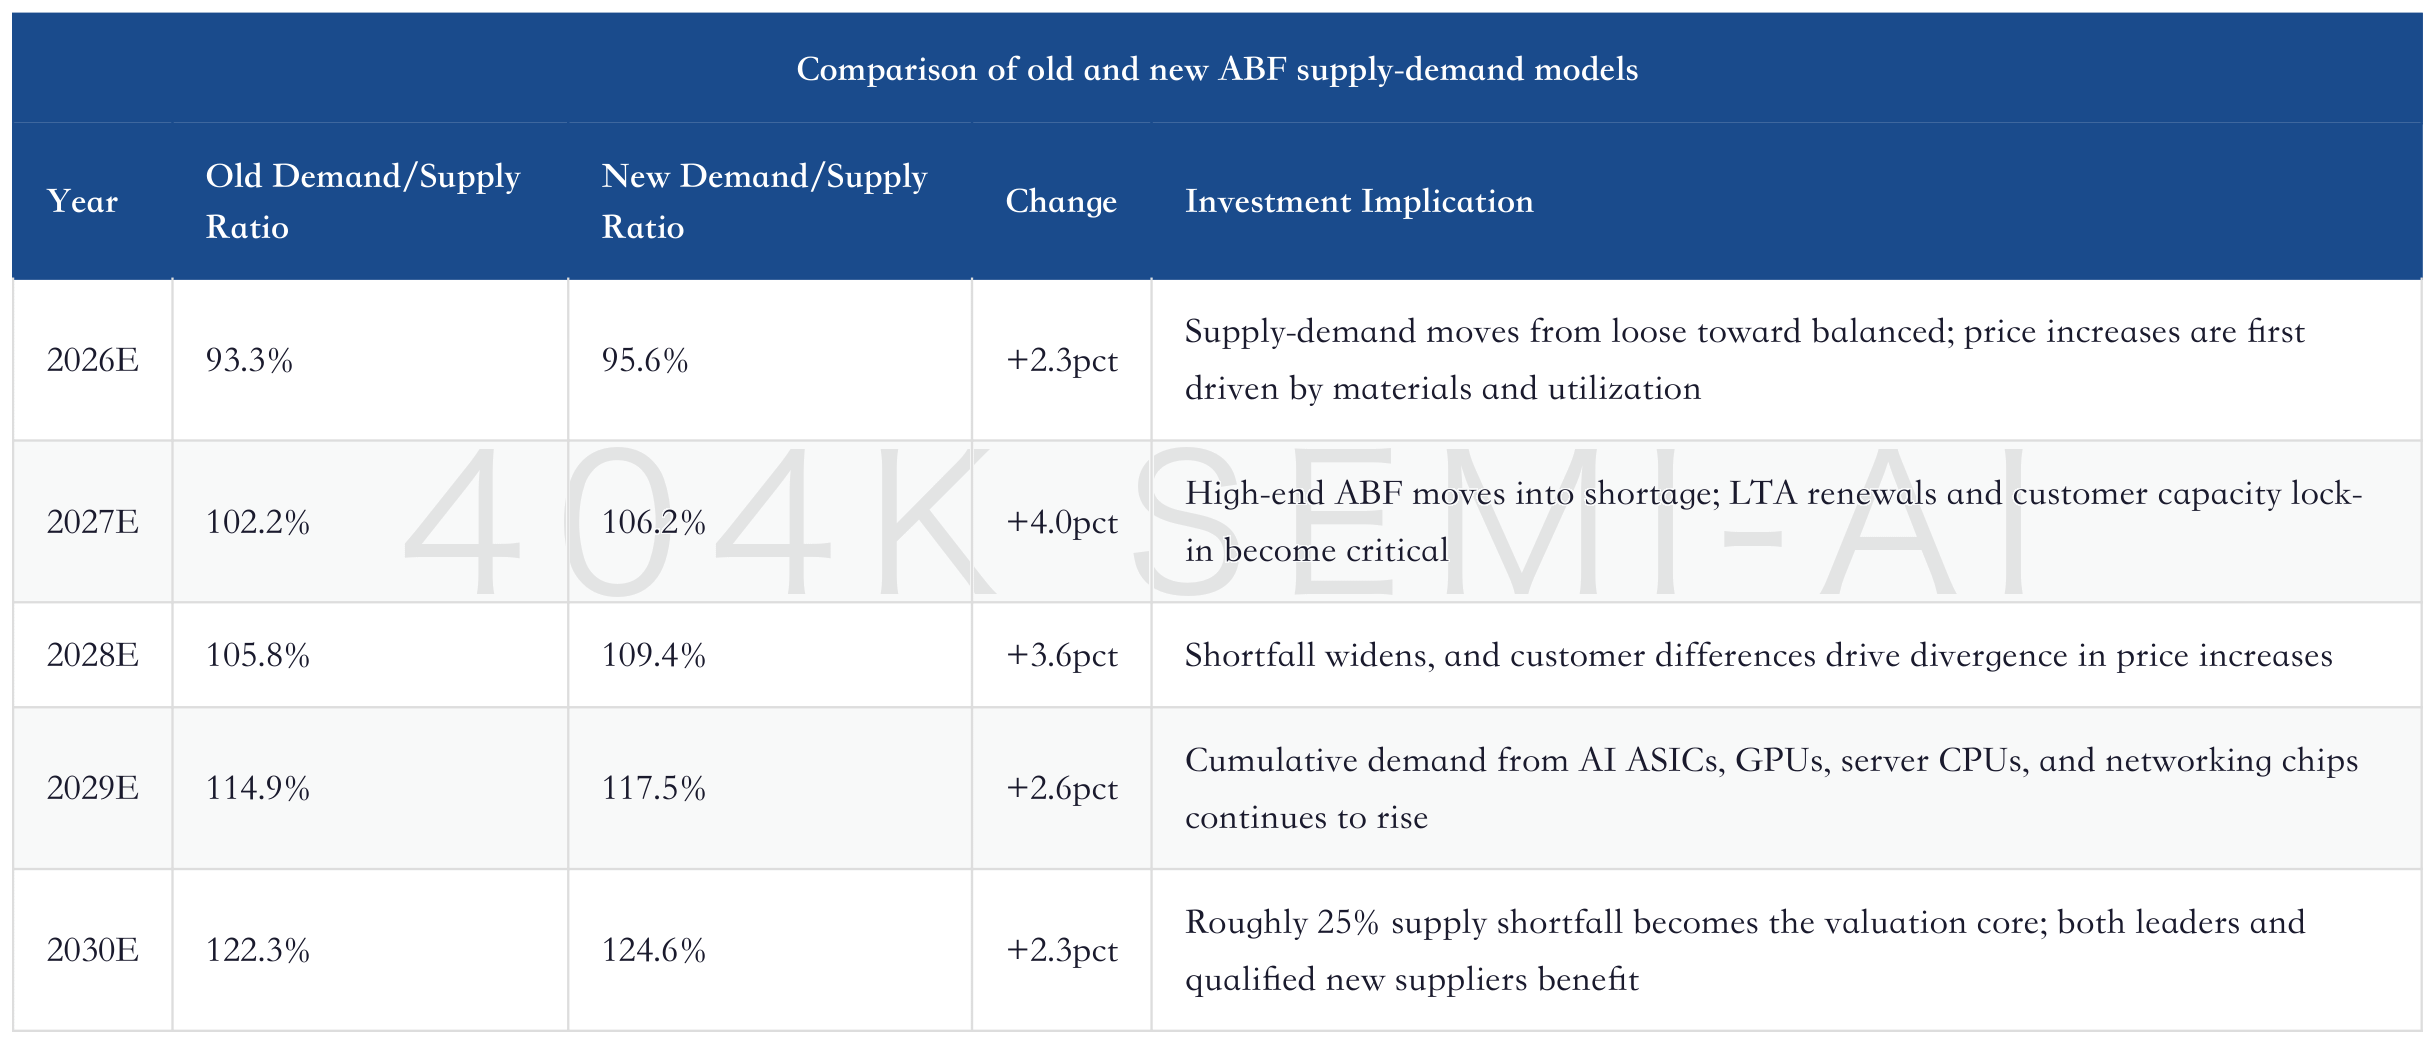
This model imposes two constraints on investment judgment. First, capacity-expansion announcements should not be treated as a simple bearish signal. Morgan Stanley explicitly includes AT&S;’s AI/HPC IC substrate expansion plan in Kulim, Malaysia in its model, yet still sees the 2030 shortfall widening. The reason is that new expansion typically takes at least two years from announcement, equipment, facilities, customer qualification, and yield stabilization, and its real impact on supply-demand usually comes after 2029.
Second, investors should not look only at 2026 price hikes. The 2026 price increases are driven more by materials costs, utilization recovery, and a low base. After 2027, pricing power comes from AI chip specification upgrades and high-end capacity shortages. If 2026 price hikes do not enter gross margins, the trade will be discounted. If high-end capacity lock-in and customer qualifications continue to be delivered in 2027, valuations should not be handled merely as traditional cyclical stocks.
ABF went through a shortage cycle in 2020-2022, then returned to oversupply in 2023-2024 as PCs normalized and new capacity came online. The difference now is that the source of demand has changed. The previous round was driven jointly by work-from-home, PCs, general-purpose servers, and cloud computing. This time, demand is being driven jointly by AI GPUs, ASICs, server CPUs, networking chips, and in-house accelerators. Demand sources are more concentrated in high-end chips, with higher value content and greater manufacturing difficulty.
This is why “effective capacity” matters more than “nominal capacity.” Being able to produce general PC CPU substrates does not mean a supplier can stably produce large-size, high-layer-count, low-warpage ABF compatible with AI ASICs and networking chips. Customer qualification and yield ramp will keep part of nominal capacity outside the income statement.
III. Demand Side: AI Diffusion Is Turning ABF from a PC Cyclical into a System-Level Base Material
ABF used to be a PC cyclical. The demand center has now shifted to servers, AI GPUs, AI ASICs, and networking chips. The mix shift is shown in the table below. The core conclusion is that PCs are rapidly losing explanatory power for ABF, while AI system-level chips are increasingly determining industry pricing and margins.
This structural migration matters more than aggregate growth. PC chips are highly cyclical, face heavy pricing pressure, and offer suppliers limited long-term certainty from customers. AI GPUs, ASICs, server CPUs, and networking chips are different: die sizes are larger, layer counts are higher, packaging complexity is greater, and customers are more willing to pay for delivery certainty, yield, and stable supply.
ABF demand is no longer about “a PC recovery driving a substrate recovery.” It is about “every high-performance logic chip in the AI system becoming larger, more complex, and more expensive.” From GPUs to TPUs, from Trainium to network switch chips, from general-purpose server CPUs to AI orchestration CPUs, substrates are upgrading alongside the chip system.
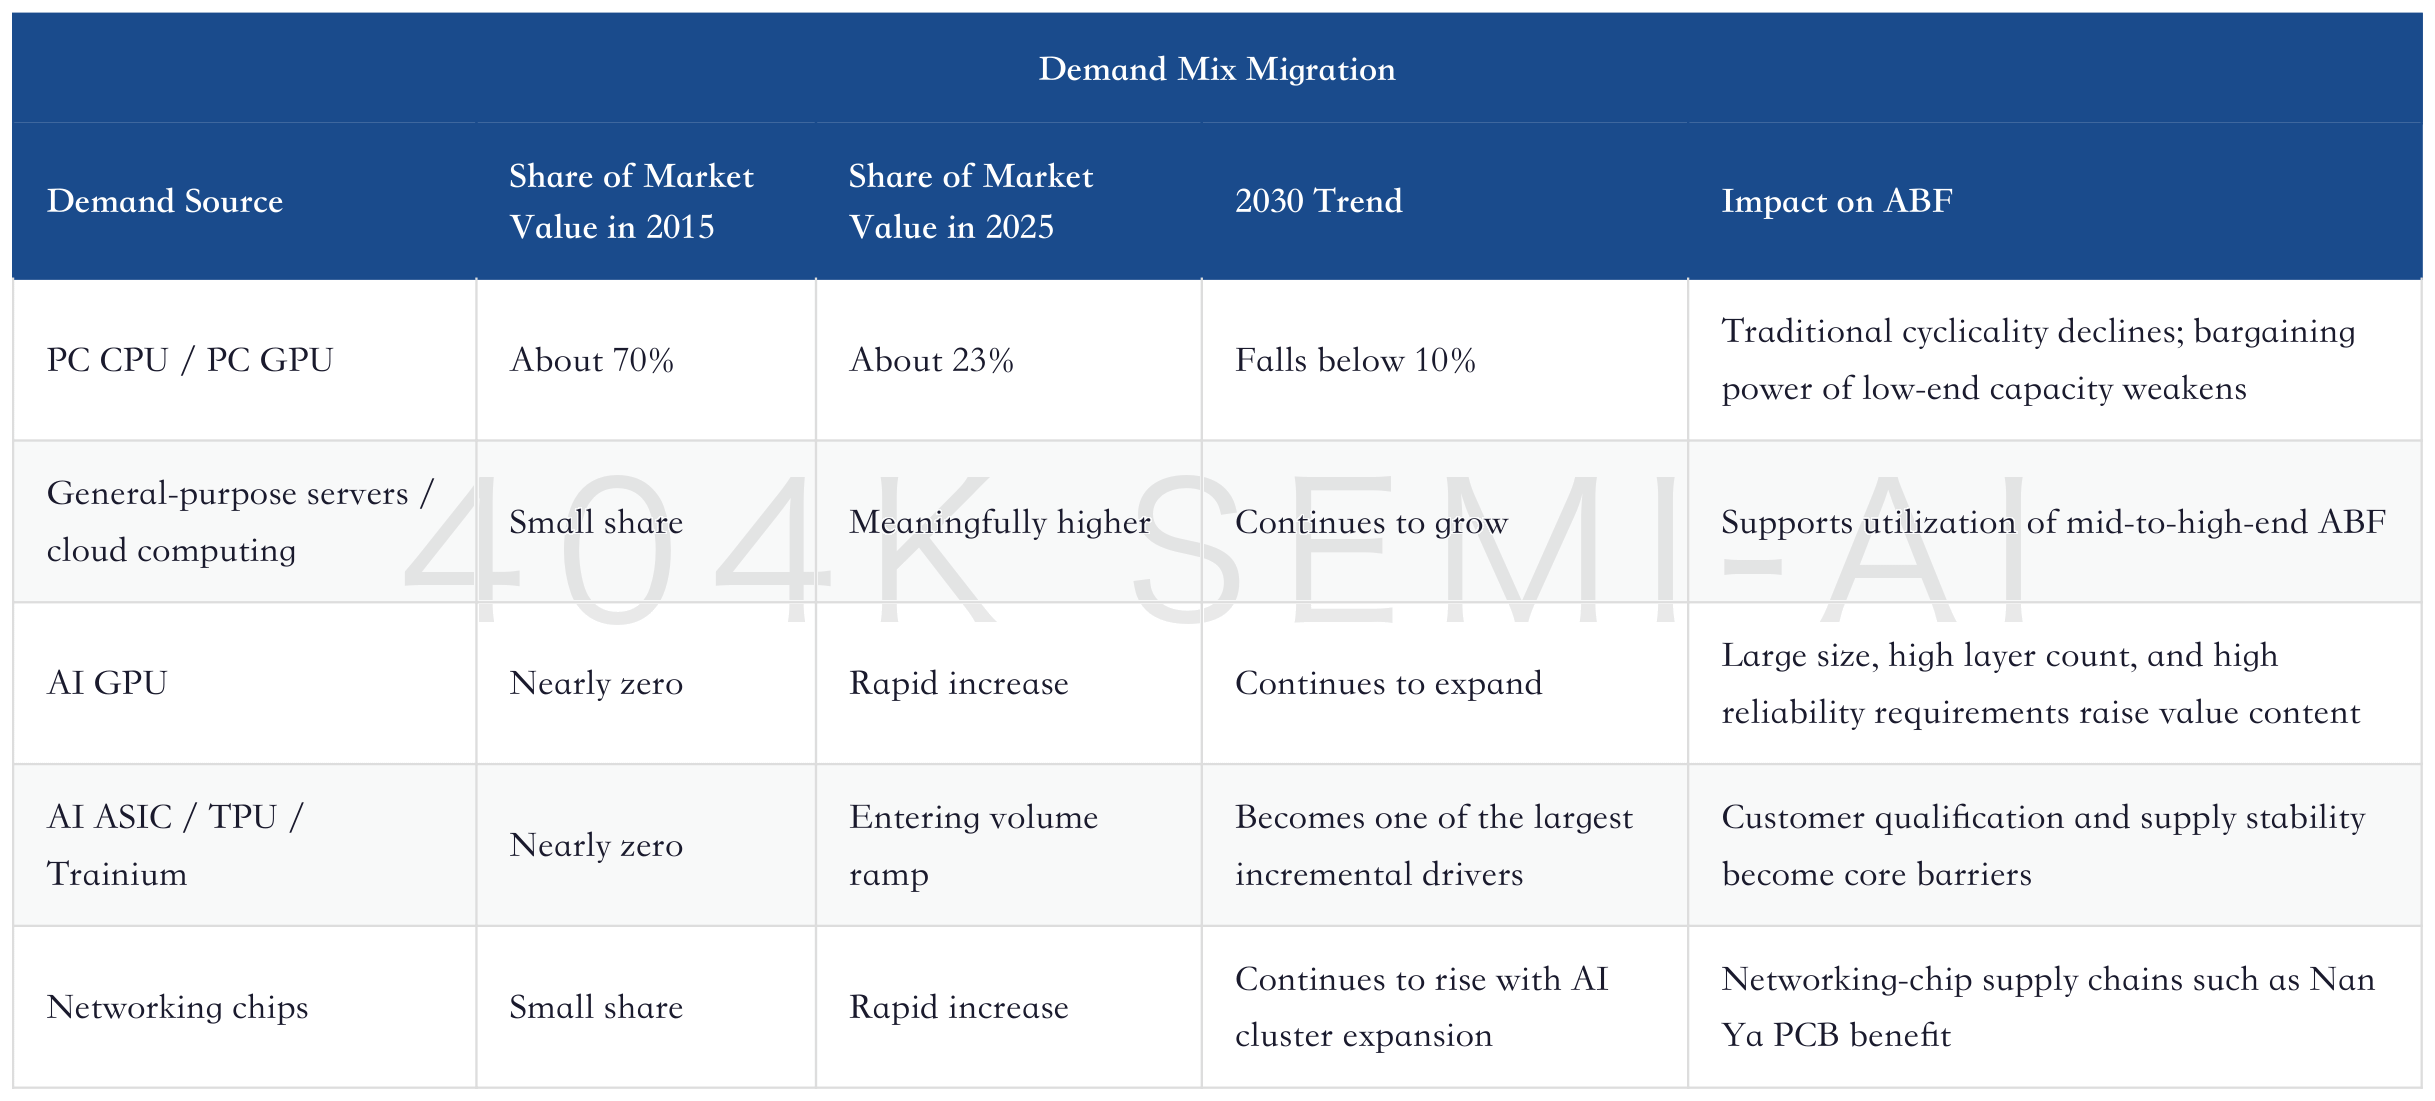
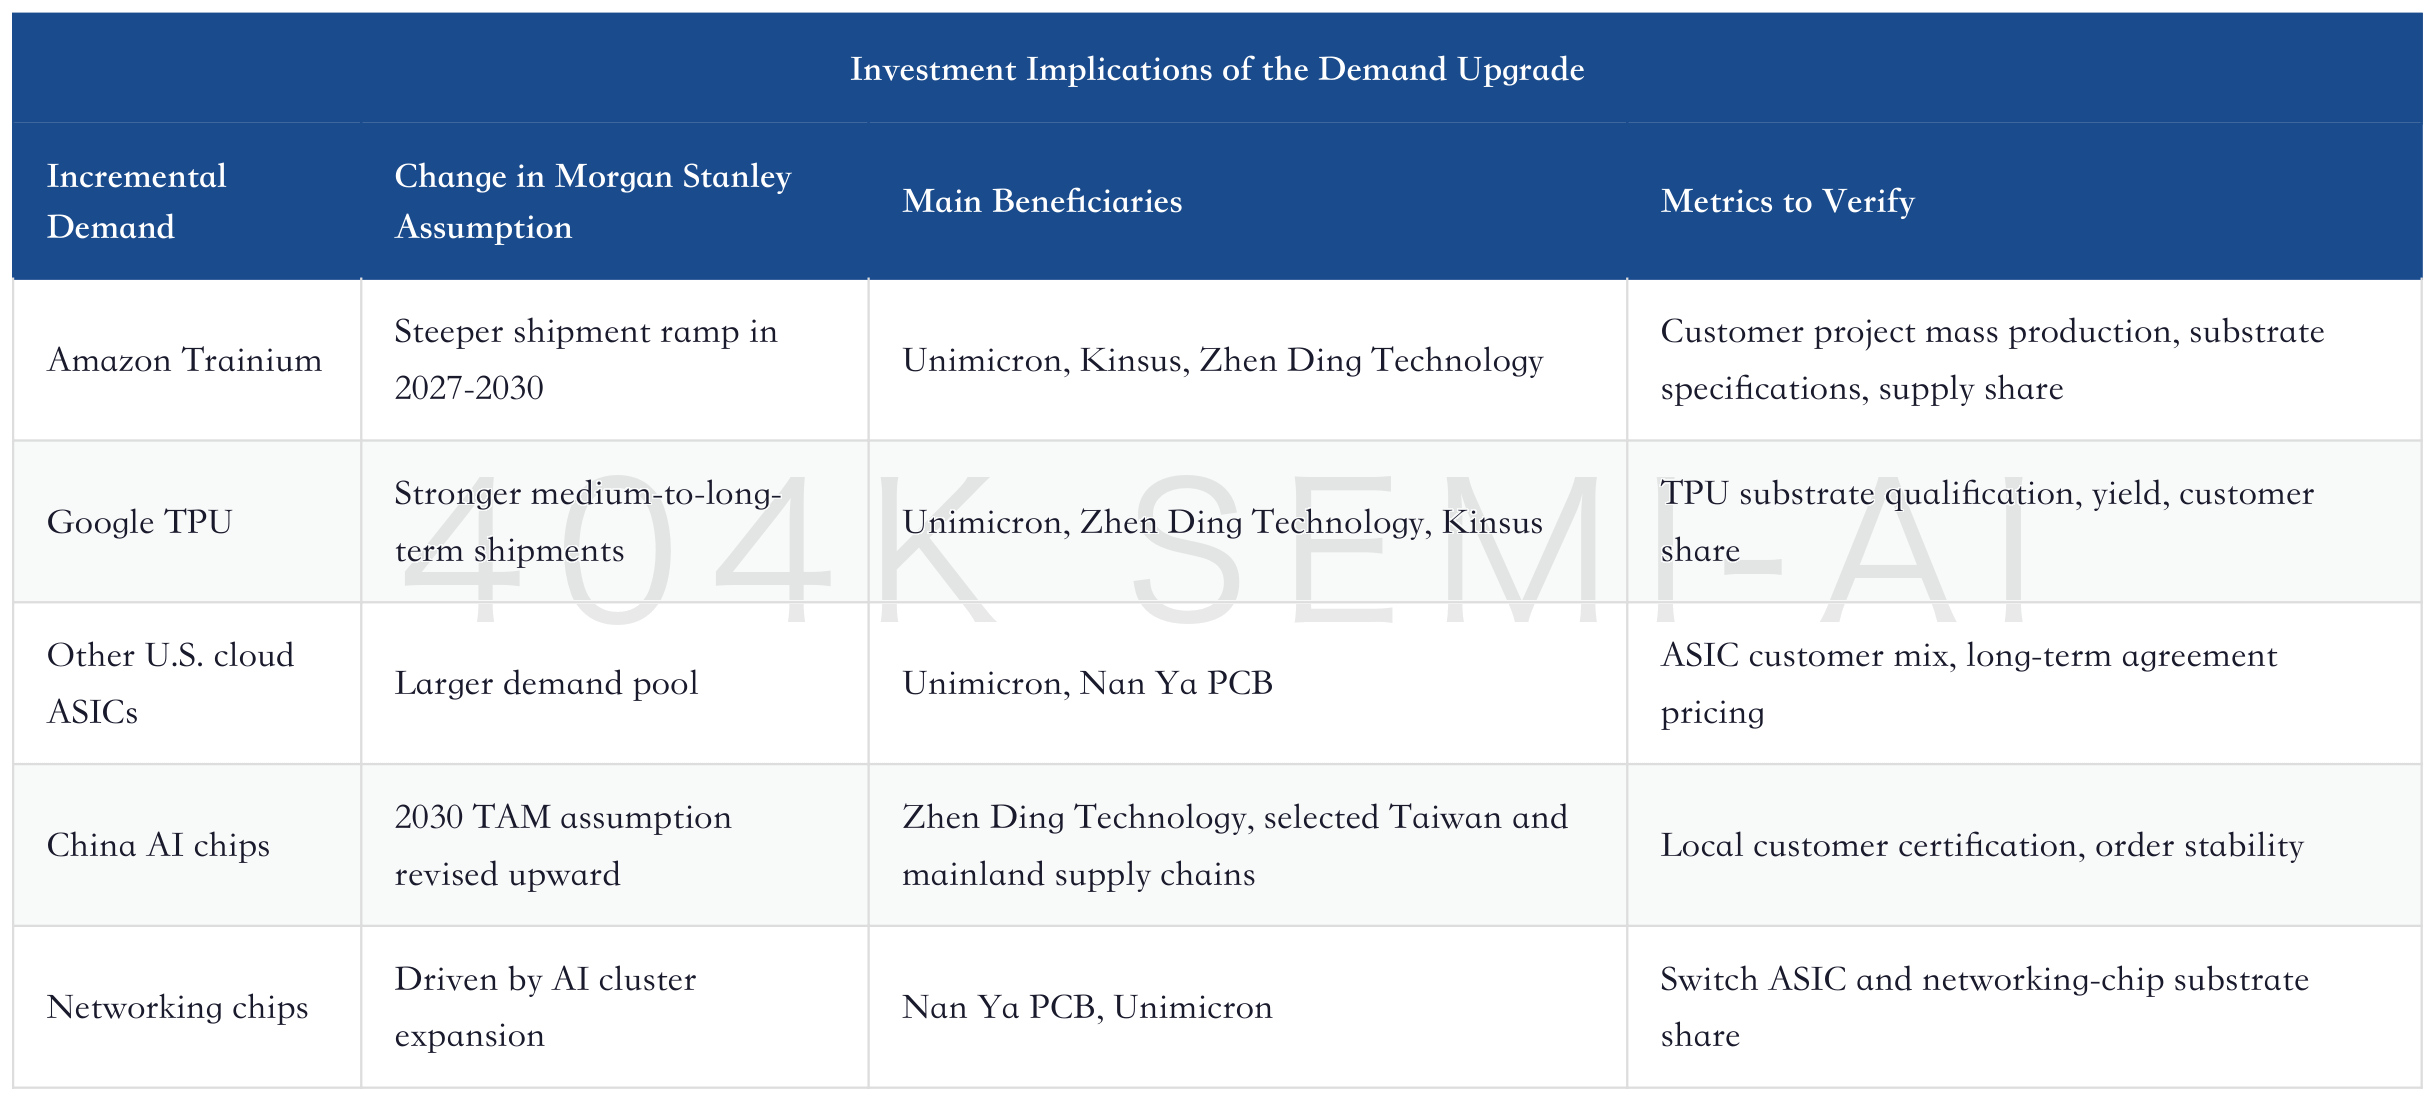
Morgan Stanley’s demand upgrade mainly comes from three lines. First is the volume ramp of Amazon Trainium and Google TPU. Cloud vendors’ self-developed ASICs are not a small GPU-substitution story, but a new source of ABF area demand. Second is “China AI chips” and other ASICs, where the 2030 assumption has been raised meaningfully, implying local accelerators are also consuming high-end substrates. Third is the networking layer of AI systems, where switch ASICs and high-end networking chips are spreading ABF demand from compute chips to the interconnect layer.
For ABF, the essence of the spillover in the AI server materials chain is that compute systems need not only more GPUs, but also more expensive packaging, interconnects, substrates, PCBs, CCL, electronic glass cloth, MLCCs, and test equipment. ABF is the layer closest to the chip, so pricing and qualification elasticity are the first to be traded by the market.
IV. Pricing Model: BT Rises First, ABF Follows, and Profit Elasticity Starts Flowing into Gross Margin
The hardest short-term evidence is in pricing and gross margin. Morgan Stanley supply-chain checks show Nan Ya PCB’s 2Q26 BT substrate prices rose about 20-30%, while ABF substrate prices rose about 10%, with further increases expected in 2H26. This cadence shows that price hikes are not only sitting in long-term supply-demand models, but have already started to enter quarterly income statements.
BT rising first has two implications. First, supply-demand for low-end or mid-range substrates is also tightening. Memory customers have not pushed prices down; instead, lead times continue to extend. Second, BT price increases will transmit to ABF because materials, equipment, customer scheduling, and supplier resource allocation are connected. If suppliers can raise prices in BT, they have even stronger grounds to demand higher prices for high-end ABF.
Morgan Stanley’s medium-term ABF pricing assumptions have also become meaningfully steeper: ABF pricing is assumed to grow 20-25% YoY in 2026 and more than 25% in 2027; prices continue to rise in 2028, but with wider customer dispersion. Because Unimicron has higher exposure to major customers and long-term agreements, its 2028 price-growth assumption is above 20%; because Nan Ya PCB has tighter supply-demand and more aggressive price execution, its 2028 ABF price-growth assumption reaches more than 40%.
ABF and BT Substrate Price Hikes Revised Up Again: From T-glass Constraints to BT Spillover, Why the AI Substrate Price-Hike Cycle Is Not Over Yet
The linkage between BT and ABF is the short-term main line of this price-hike trade. BT price increases show the market that substrate supply-demand tightness is not limited to high-end AI ABF. ABF price increases confirm that major customers are also paying for certainty in high-end packaging. Together, these two lines are the fundamental reason Nan Ya PCB’s second-quarter earnings exceeded expectations.
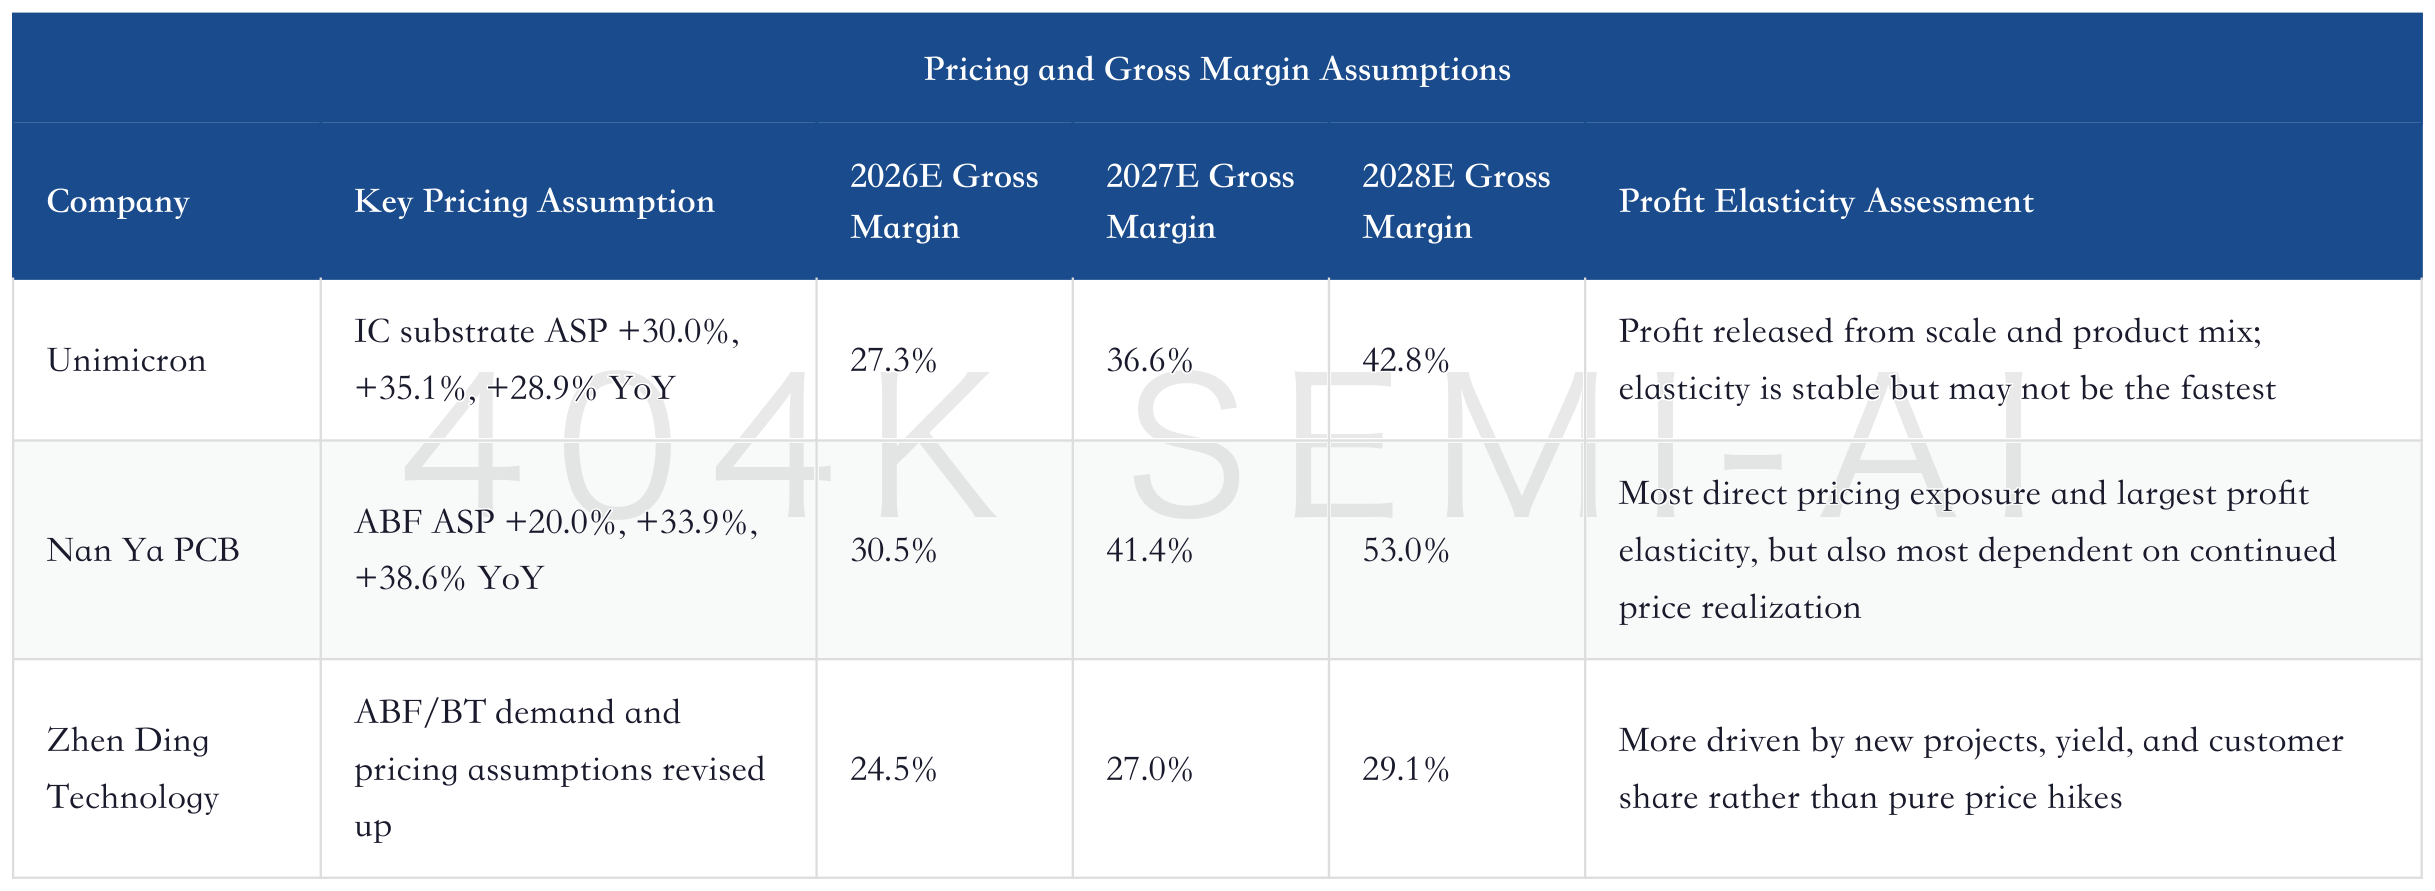
This table separates the three companies. Unimicron looks like the core asset in high-end ABF, with profits coming from customer structure, scale, and high-end product mix. Nan Ya PCB looks like the price-hike beta, with the largest profit elasticity when BT and ABF rise at the same time. Zhen Ding Technology looks like a new-qualification option: price hikes help, but the ceiling on valuation depends on whether Google TPU, AI server PCB, and China AI chip projects can be executed successfully.
The short-term verification points are also clear. For Unimicron, watch whether 2Q26 gross margin can reach 22.1%, and whether 3Q revenue guidance proves volume ramp in AI ASIC and server CPU projects. For Nan Ya PCB, watch whether 2Q26 EPS can reach NT$3.35, and whether 3Q gross margin continues to expand. For Zhen Ding Technology, watch 2Q26 gross margin and 3Q margin, but Morgan Stanley believes its EPS may still come in below consensus because expenses and taxes will offset part of the operating improvement.
V. Company Ranking: Unimicron Is the Steadiest, Nan Ya PCB Has the Most Leverage, Zhen Ding Looks Most Like an Execution Option
Unimicron, Nan Ya Printed Circuit Board, and Zhen Ding Technology are all maintained at Overweight, but their payoff profiles come from different sources. Putting them in the same “ABF price hike” basket would miss the real differences.
Unimicron’s keywords are major customers, high-end ABF, AI ASICs, and server CPUs. Morgan Stanley raised its 2026-2028 EPS estimates by 25%, 33%, and 14%, respectively, and lifted its gross margin assumption from 23.1% in 2026 to 38.3% in 2028. Its target price implies 25x 2028 P/E, so it is not cheap. But if high-end ABF remains in shortage from 2027 onward, the leader’s pricing framework could shift from cyclical stock to effective-capacity asset.
Unimicron also has one point that is easily underestimated: it may not be the fastest company to raise prices, but it is the best positioned to take on long-term projects from major customers. If AI ASICs, server CPUs, and next-generation large-scale packaging keep upgrading, customers will want stable supply, not the lowest quotation every quarter. LTAs may suppress price-hike leverage in the short term, but over the long term they could become a source of customer lock-in and capacity-expansion visibility.
Nan Ya PCB’s keywords are price execution, BT spillover, and networking chips. In 2Q26, BT substrate prices rose 20-30% and ABF prices rose about 10%; the second-quarter earnings beat mainly came from pricing and gross margin. Morgan Stanley raised Nan Ya PCB’s 2026-2028 EPS estimates by 36%, 39%, and 23%, respectively, and lifted its target price from NT$1,275 to NT$1,550.
Nan Ya PCB’s advantage is that price hikes flow into the income statement faster. The drawback is the same thing: when the market is trading price leverage, it shines the most; when the market starts worrying about demand, capacity expansion, or substitute technologies, its valuation will also be pressured first. Nan Ya PCB is better viewed as the sharpest earnings-leverage play in the ABF and BT price-hike cycle, rather than the steadiest long-term asset.
Zhen Ding Technology’s keyword is qualification breakthrough. It is not a pure ABF company. iPhone F-PCB, SLP, AI server PCB, optical module PCB, and ABF/BT substrates are all in the model. Morgan Stanley raised Zhen Ding’s 2026-2028 EPS estimates by only 4% and lifted its target price from NT$666 to NT$690, showing that near-term price hikes have limited impact on its income statement.
But Zhen Ding should not be judged only by that 4%. The key is that its Shenzhen ABF fab 1 turned profitable in 1Q26, its Kaohsiung plant is planned for mass production in 2H26, and Shenzhen fab 2 is also under construction. At the same time, it is viewed as one of the key ABF suppliers for Chinese AI chips and is increasing its ABF exposure to international customers, with Google TPU being the most important validation point. If TPU substrates execute well and help it get closer to more ASIC/GPU customers, Zhen Ding’s valuation could shift from “consumer electronics PCB company” to “AI interconnect and substrate platform.”
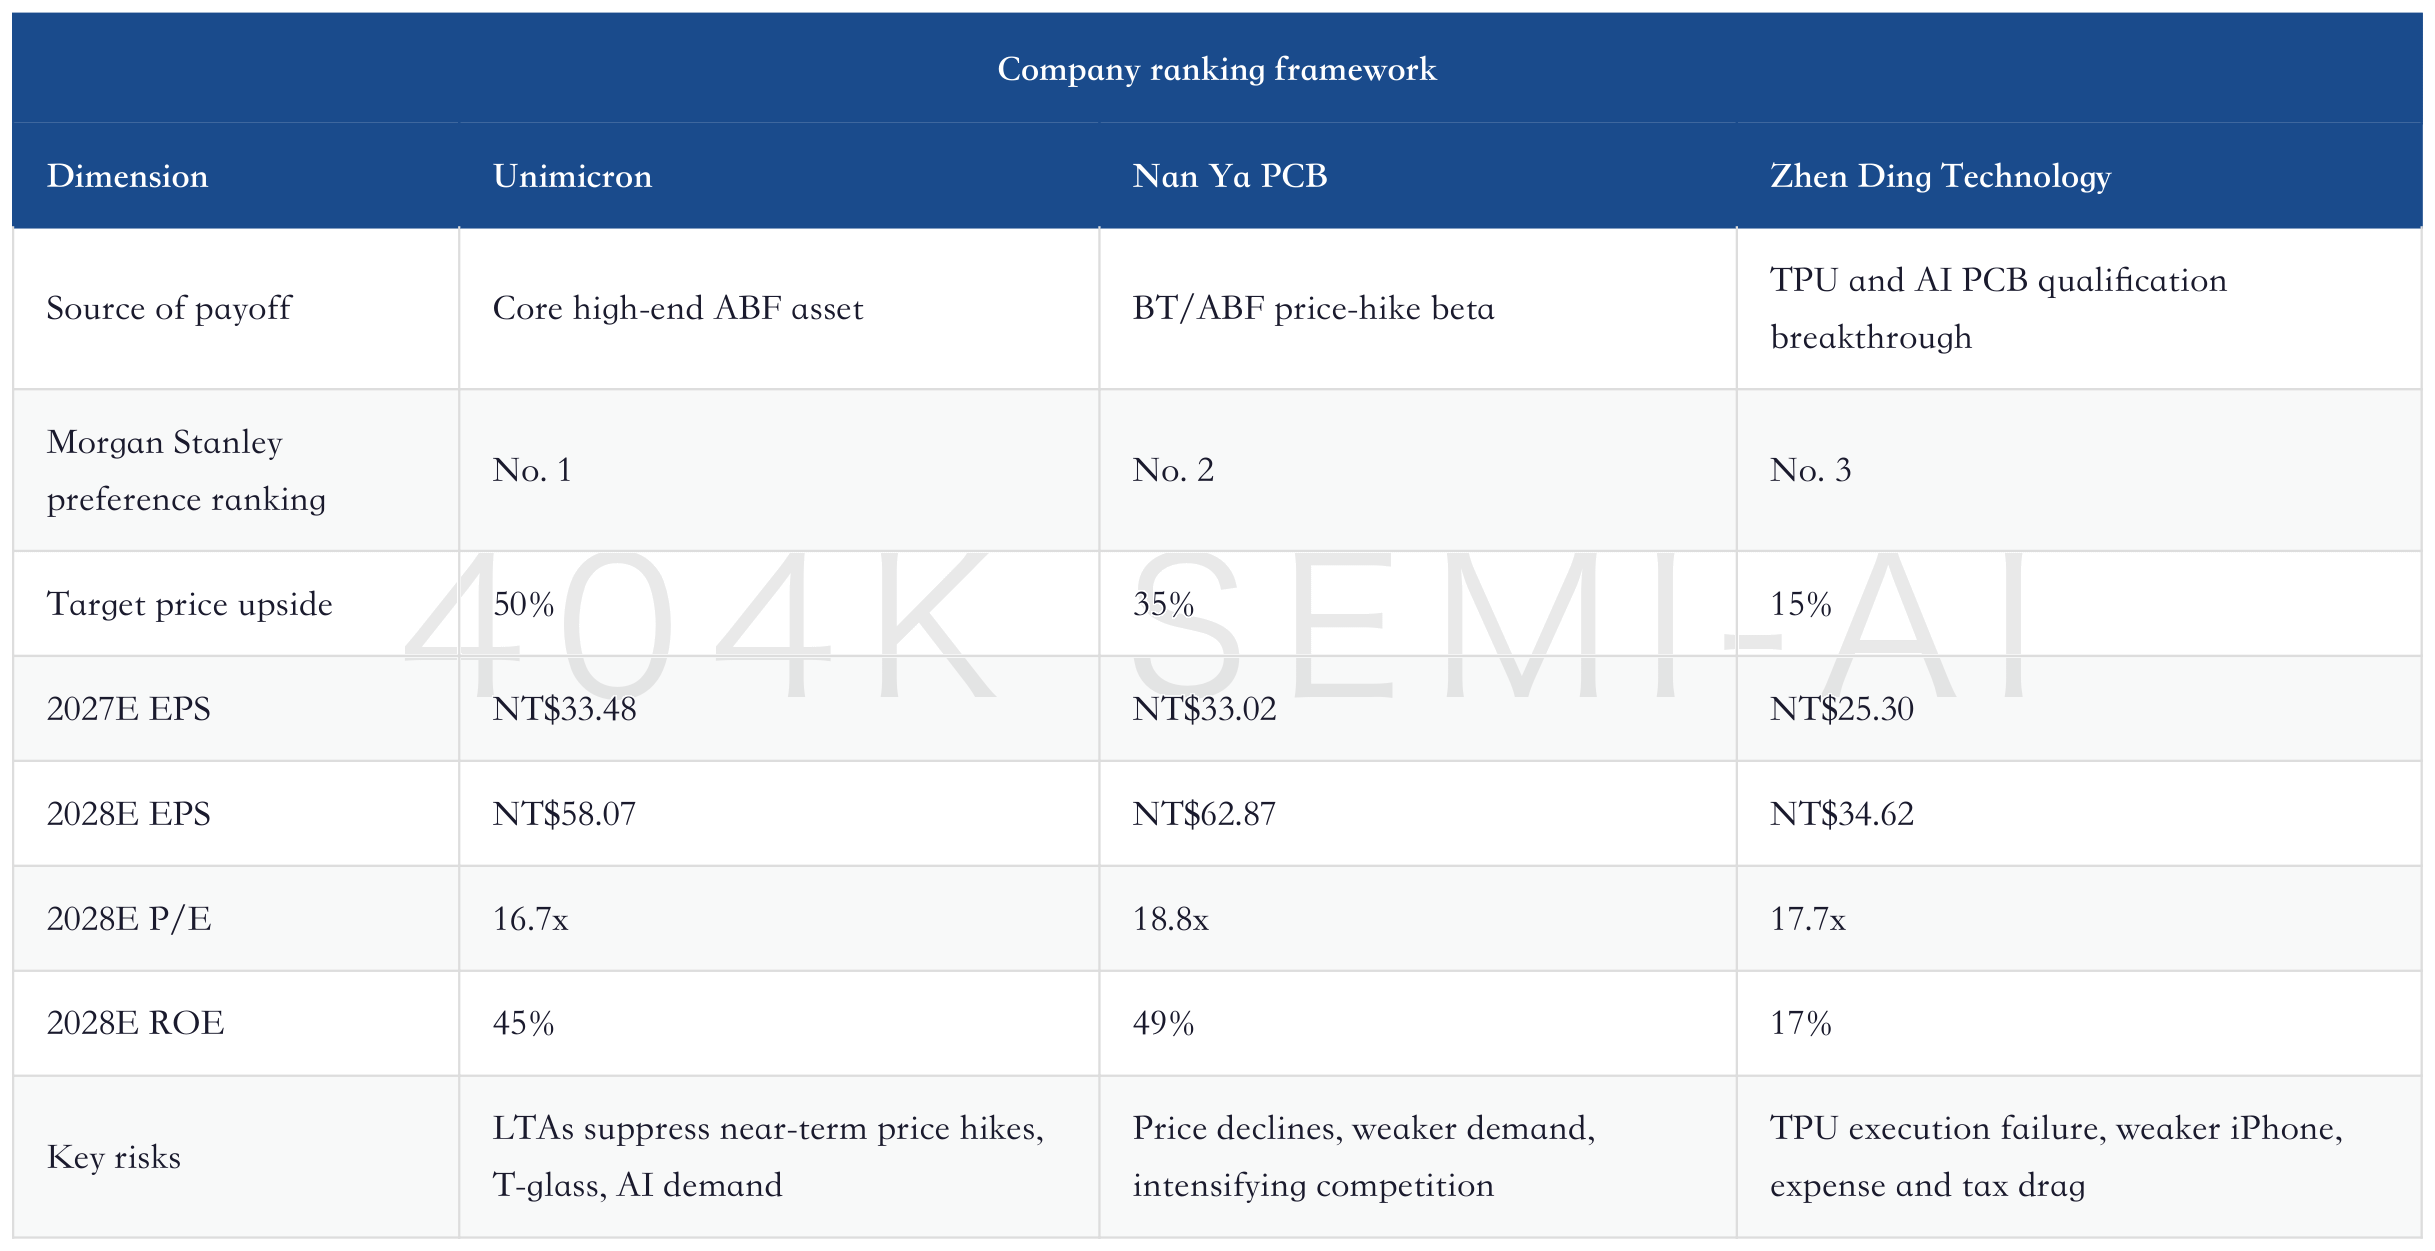
Put more simply: for certainty, look first at Unimicron; for price-hike leverage, look at Nan Ya PCB; for new qualification breakthroughs, look at Zhen Ding Technology. All three benefit from the ABF gap, but the market values them for different reasons.
VI. Global Peers: High-End Substrates Are Not Only a Taiwan Story; Ibiden and Samsung Electro-Mechanics Define the Technology Ceiling
ABF is not a single-region supply chain. In Morgan Stanley’s peer table, in addition to Unimicron, Nan Ya PCB, and Zhen Ding Technology, the companies include Ibiden, Samsung Electro-Mechanics, AT&S;, and Kinsus. These companies occupy different positions, and the market assigns them different valuations.
Ibiden is the technology-ceiling asset in high-end ABF. It has strong customer relationships in high-end server CPUs, GPUs, and advanced packaging, but its current valuation is already very high, and Morgan Stanley rates it Underweight. Samsung Electro-Mechanics is a broad electronic components leader. ABF, MLCCs, silicon capacitors, and other AI data center materials all enter its income statement, so its valuation logic is not a single ABF shortage, but the re-rating of a “high-value-added electronic components portfolio.”
Kinsus is another type of asset. It has ABF capacity and customer-sponsored expansion signals, and also benefits from tight supply in T-glass and high-end substrates, but it is not a core covered name in this Morgan Stanley report. AT&S; enters the model through AI/HPC substrate expansion in Kulim, Malaysia, showing that customers are willing to support new capacity with long-term commitments, though the capacity ramp is still after 2029.
Ibiden Deep Dive: Citi Sees ¥30,000; How AI CPU Package Substrates Re-rate the ABF Leader
Samsung Electro-Mechanics Deep-Dive Update: Goldman Sachs Raises Estimates Sharply as AI Servers Push MLCCs, Silicon Capacitors, and ABF into the Income Statement
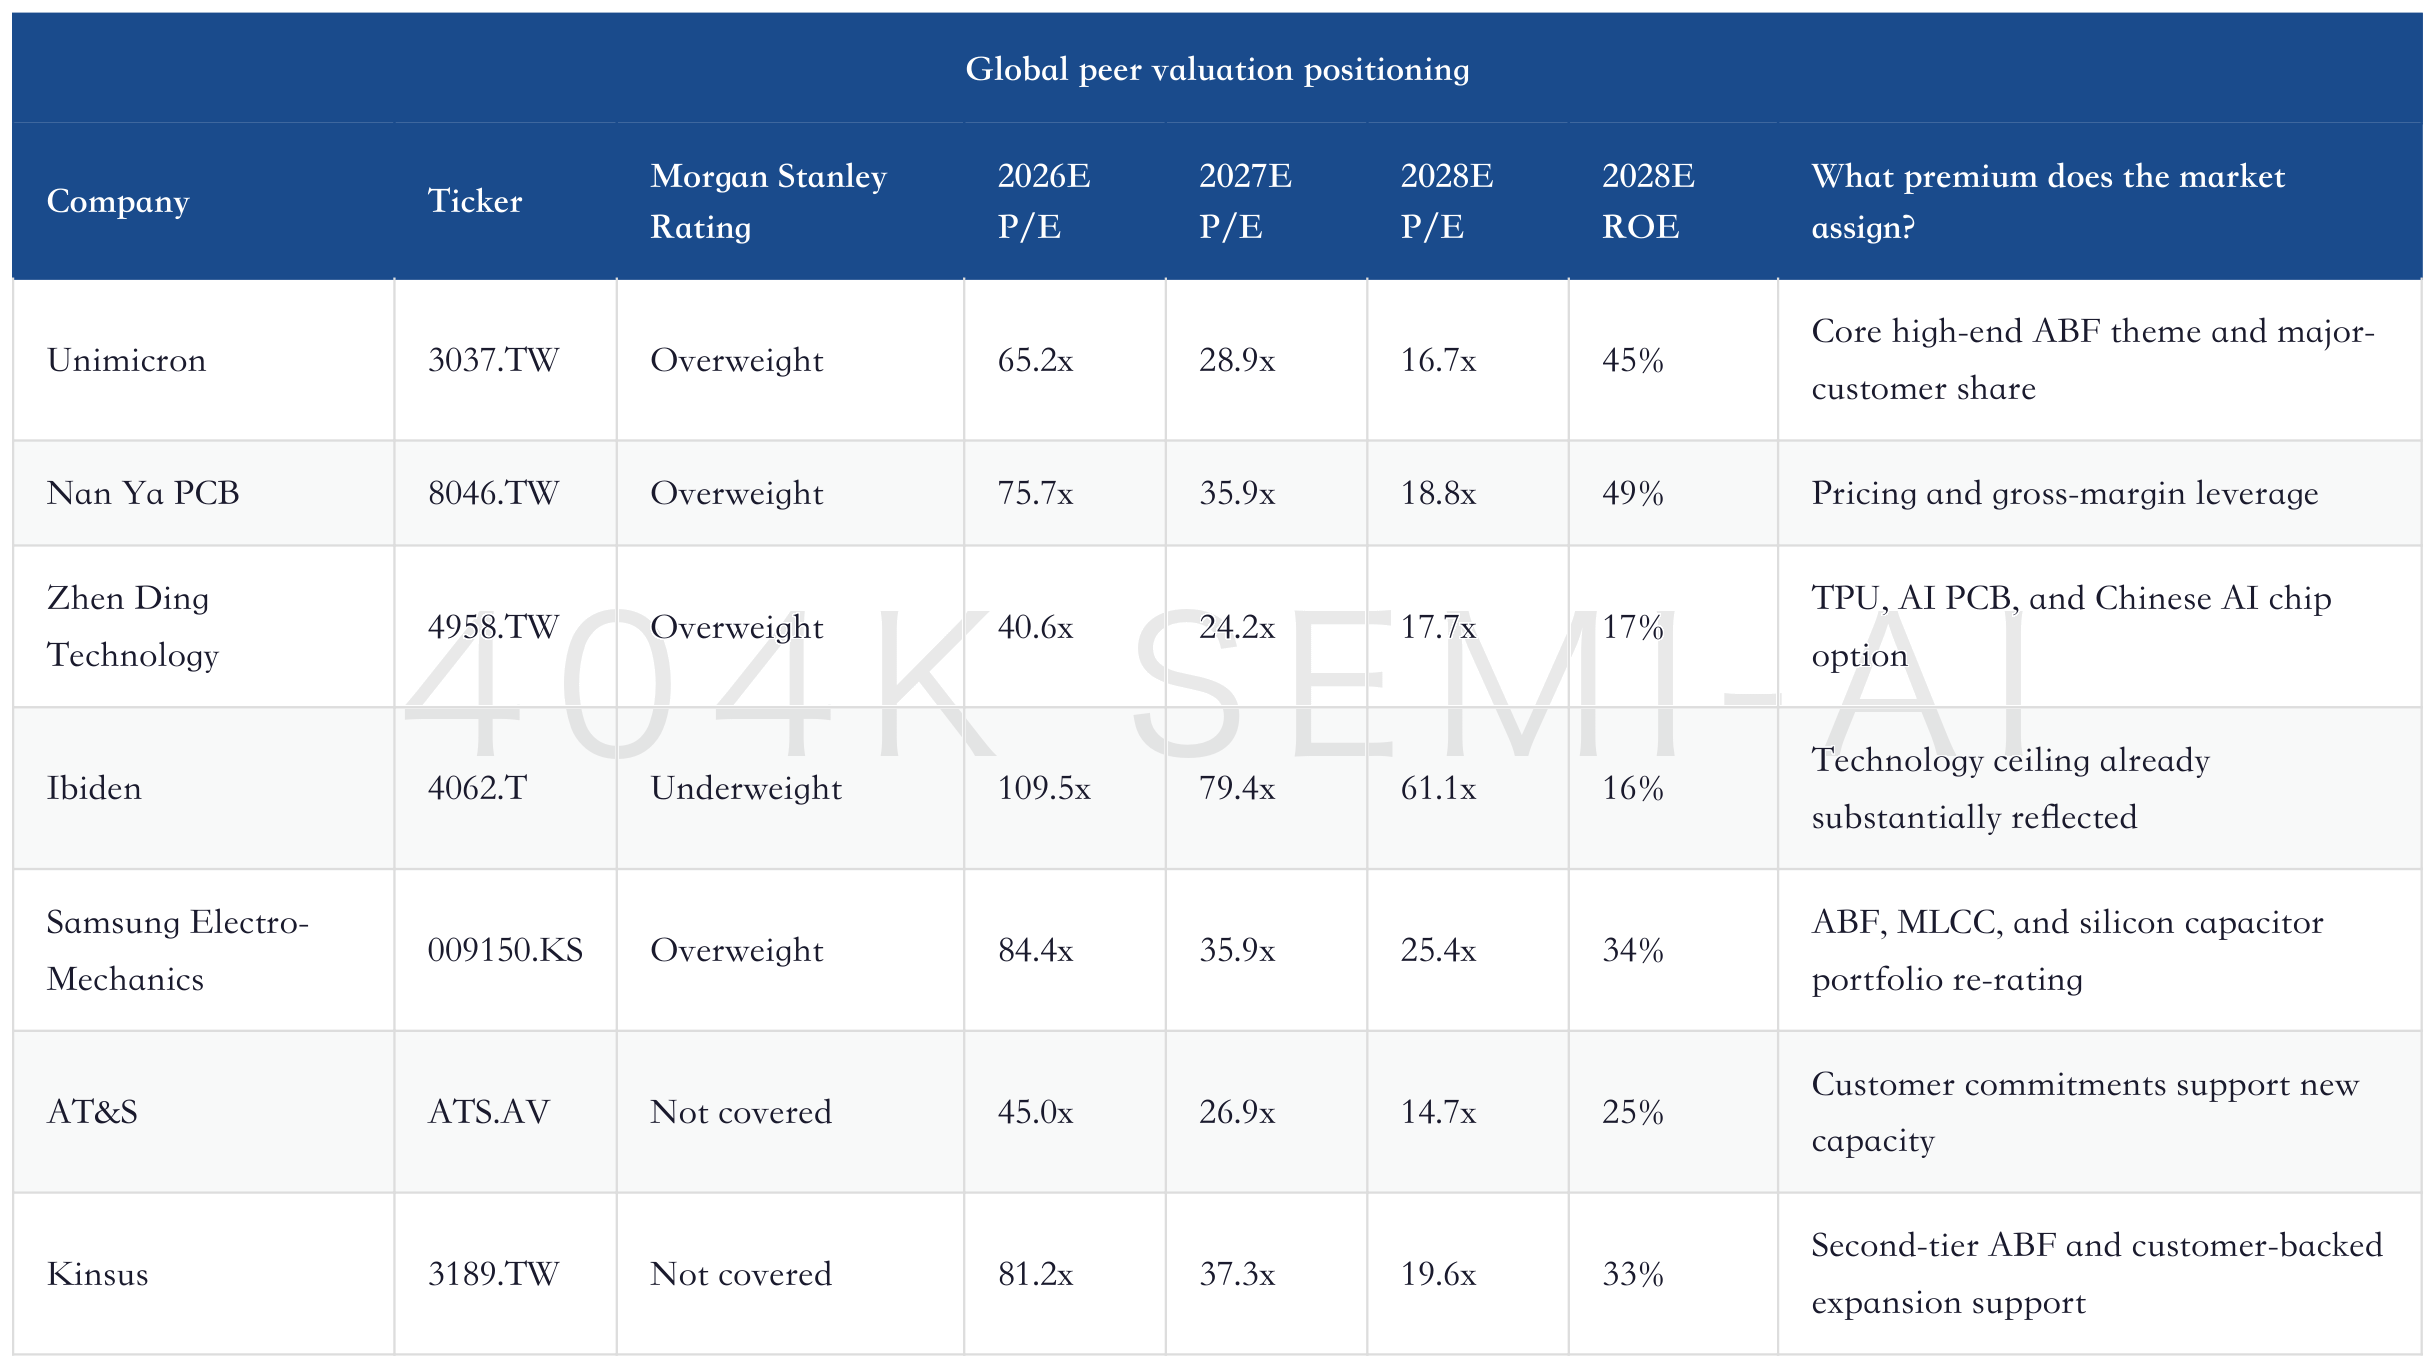
This table has a counterintuitive conclusion: cheaper is not always better for ABF stocks. Ibiden is expensive because its technology ceiling and customer position are extremely strong. Unimicron looks expensive, but its valuation will fall quickly after earnings scale in 2028. Nan Ya PCB has the highest 2028 ROE, proving that earnings leverage is very steep once price hikes flow into gross margin. Zhen Ding Technology’s valuation is not expensive, but ROE has not yet fully reflected the potential of new businesses, and execution risk is also higher.
VII. A-Share Mapping: Do Not Treat Every PCB Company as an ABF Proxy
The most important implication of this report for A-shares is not “buy all PCB names,” but to separate the value chain into three layers: first, ABF substrates themselves; second, AI server PCBs and switch PCBs; third, CCL, electronic cloth, glass fiber cloth, and copper foil materials. All three layers benefit from AI hardware upgrades, but their earnings elasticity, validation metrics, and valuation anchors are completely different.
WUS Printed Circuit is closer to AI server PCBs and switch PCBs. The core variables are 1.6T/3.2T switches, high-layer-count boards, customer mix, and pricing discipline. Victory Giant Technology is more like an effective-capacity asset in AI PCBs; the market needs to track high-layer-count MLPCBs, HDI, overseas capacity, and joint development with customers. Shennan Circuits has packaging substrates, communications PCBs, and server-related capabilities, but investors need to distinguish margin profiles and customer timing across businesses. Guanghe Technology, Kinwong Electronic, and DSBJ correspond respectively to AI PCBs, automotive/server PCBs, optical interconnects, and the migration from consumer electronics to AI.
WUS Printed Circuit deep-dive update: Citi’s RMB189 target price, 1.6T switches, 3.2T R&D;, and AI PCB pricing discipline
Victory Giant Technology deep-dive update: Rubin high-layer-board delays, new TPU orders, and how RMB20bn capex validates effective AI PCB capacity
Guanghe Technology deep dive: Citi’s RMB241 target price and why AI servers need more expensive PCBs
Shengyi Technology and Shengyi Electronics sit more in CCL, electronic materials, and the PCB supply chain. An ABF shortage will raise the market’s valuation tolerance for high-end interconnect materials, but Shengyi Technology is not an ABF leader, and Taiwan ABF pricing assumptions cannot simply be copied into its income statement. A more reasonable read is that the overall AI server materials chain is upgrading, which strengthens pricing discipline for high-end CCL, electronic cloth, glass fiber, copper foil, and high-layer-count PCBs.
AI PCBs and ABF substrates both benefit from the same underlying trend: chips are becoming larger, systems are becoming more complex, and the interconnect value per rack is rising. But they show up differently in the income statement. ABF is closer to chip packaging, where customer qualification and high-end materials are harder. AI PCBs are closer to server and switch systems, and are more affected by layer count, material grade, yield, drilling and lamination, and customer delivery cadence.
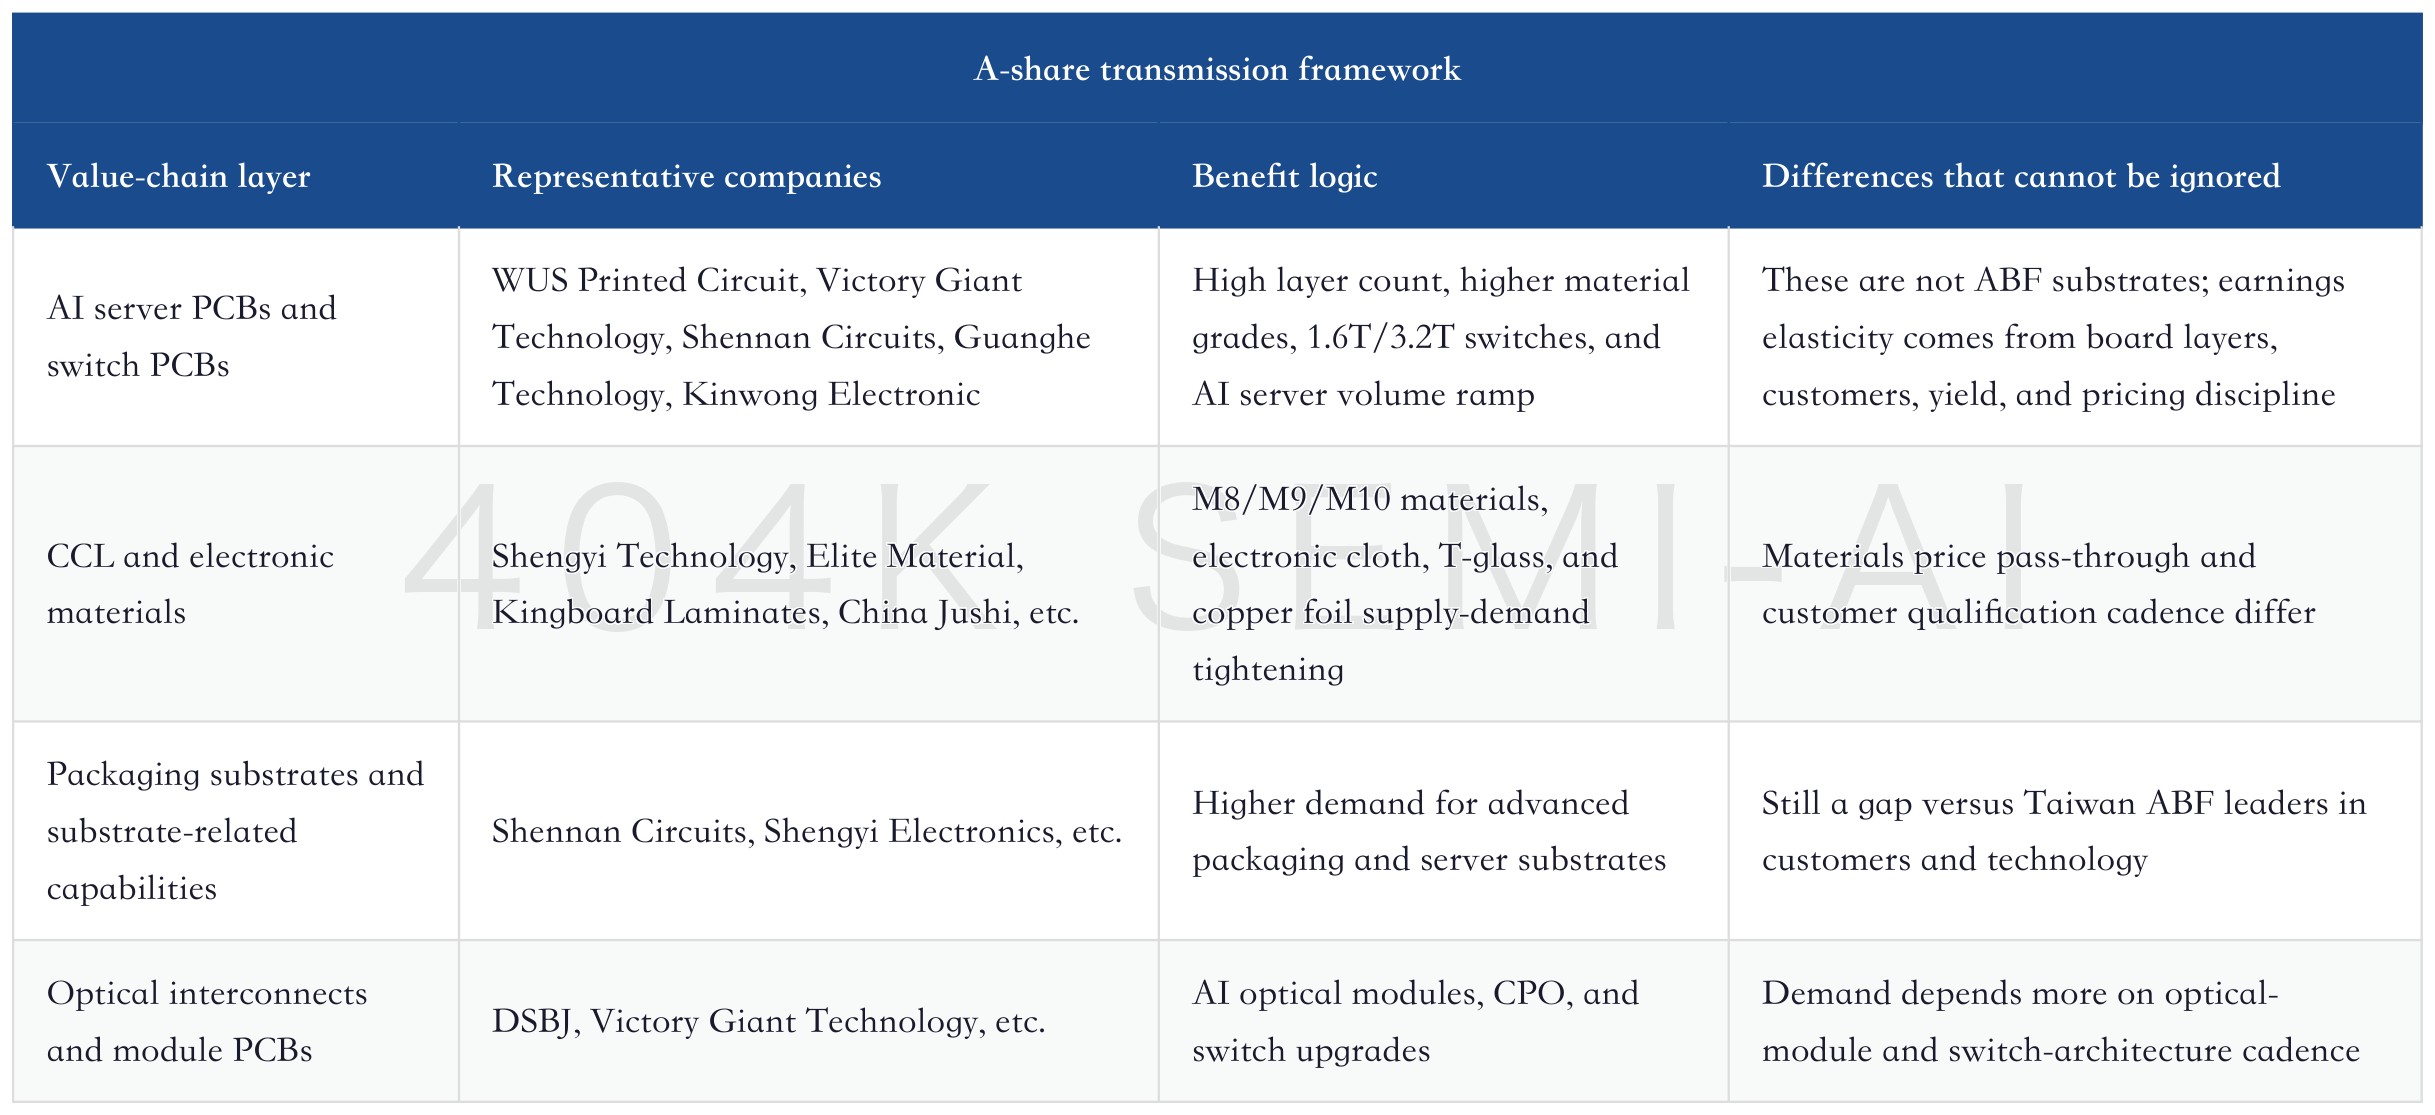
Therefore, the real way to trade A-shares is not to copy Morgan Stanley’s target prices for the three companies, but to treat the ABF shortage as an upstream signal for the high-end interconnect value chain. As long as ABF continues to rise in price, the physical bottleneck in AI hardware has not been resolved. As long as BT, CCL, electronic cloth, and PCBs all show pricing discipline at the same time, this is not a single-point shortage, but a system-level revaluation of the materials chain.
AI PCB and CCL deep dive: From GB300 to Rubin Ultra, which becomes scarce first: high-layer boards, M9 materials, or electronic cloth?
The role of these earlier pieces is to place ABF back into the overall AI server value chain. ABF is not an isolated shortage. Together with PCBs, CCL, electronic cloth, T-glass, MLCCs, silicon capacitors, and test equipment, it forms the physical gate for AI hardware. When screening stocks, it is better to move layer by layer along “chip packaging - materials - PCB - server/switch delivery,” rather than simply buying by industry label.
VIII. Valuation: Why 25x 2028 P/E Is Not Necessarily Expensive
Morgan Stanley uses 25x 2028 P/E as the target-price framework for both Unimicron and Nan Ya PCB, and 20x 2028 P/E for Zhen Ding Technology. For traditional substrate cyclical stocks, this valuation does not look low. But if high-end ABF remains in shortage through 2027-2030, the valuation anchor cannot be limited to the historical 10-20x range.
The core difference is earnings quality. For traditional cyclical stocks, price increases come from short-term supply-demand mismatches; once supply comes online, prices and margins fall back. High-end ABF price increases come from customer qualification, technical specifications, effective capacity, and materials constraints. Even with new capacity additions, truly usable capacity still has to go through customer certification, yield ramp-up, and product iteration. Suppliers are not only selling capacity; they are also selling delivery certainty.
Unimicron’s target price implies 44x 2027 P/E and 25x 2028 P/E; Nan Ya PCB’s implies 47x 2027 P/E and 25x 2028 P/E; Zhen Ding Technology’s implies 27x 2027 P/E and 20x 2028 P/E. High multiples are not risk-free, but if 2028 earnings continue to be revised up, valuation will be absorbed quickly by earnings.
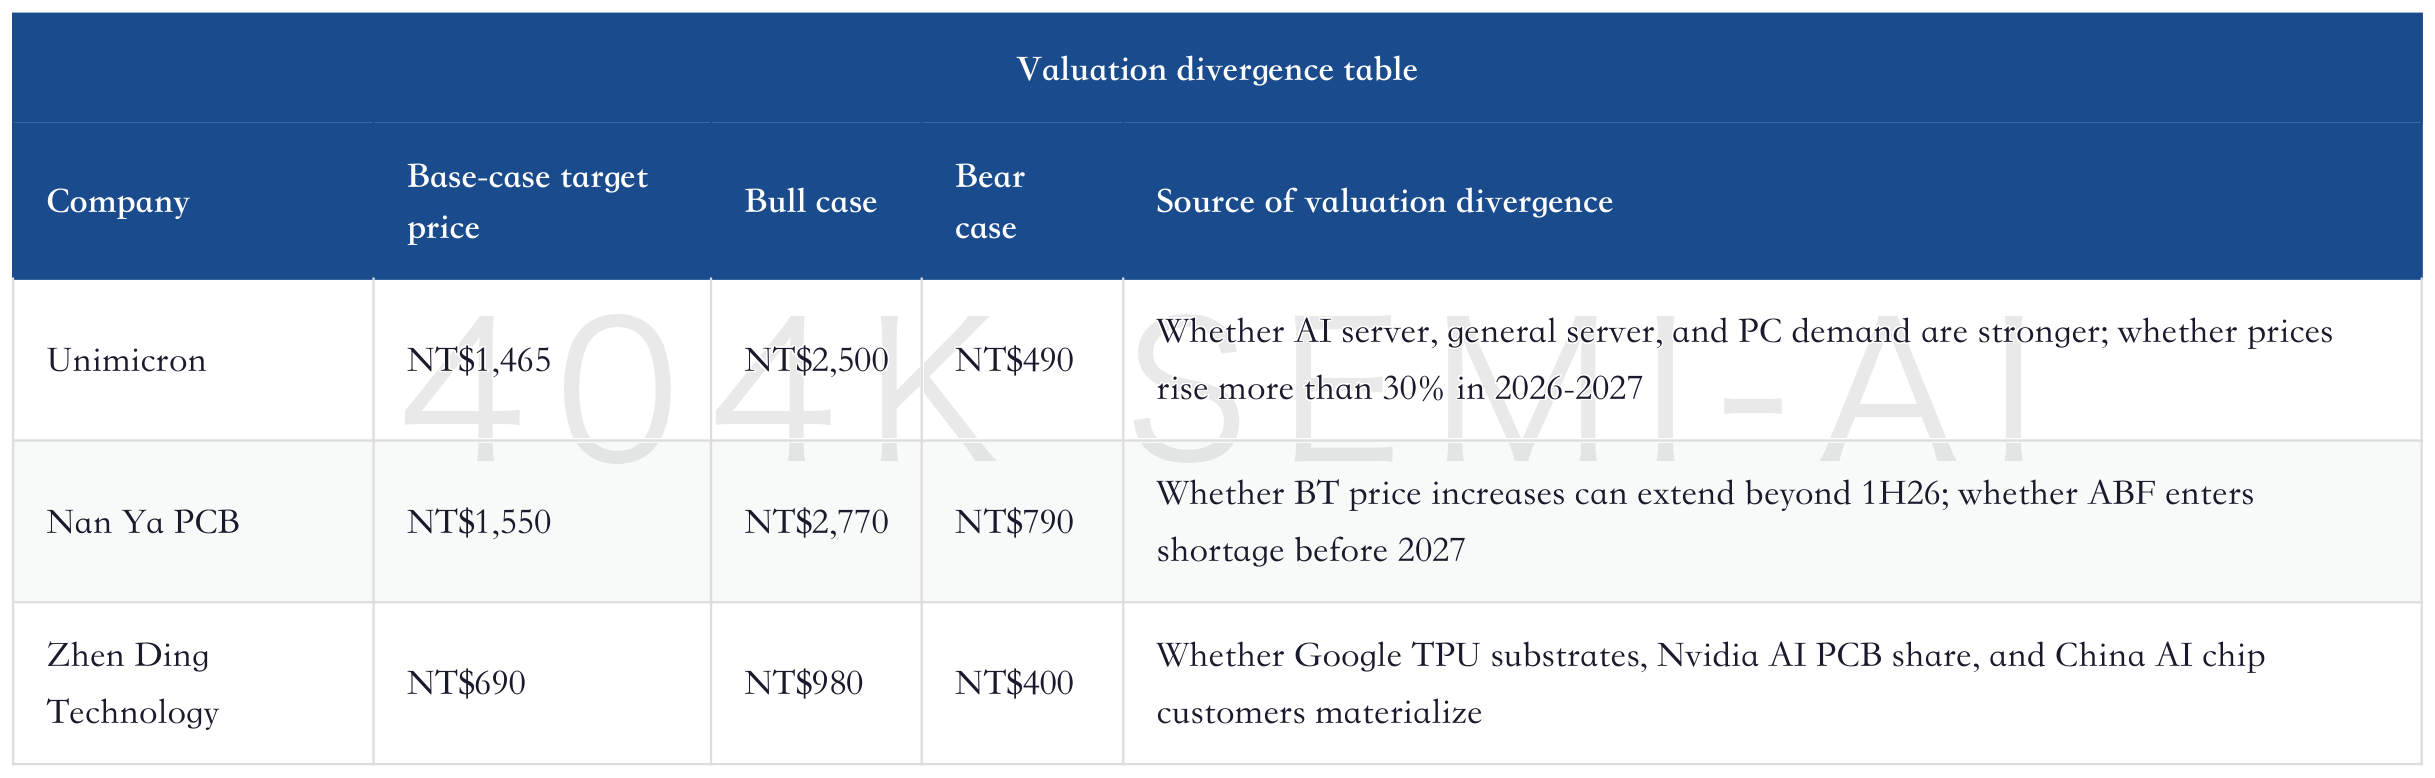
The bear cases are most worth noting. The bear-case assumptions for both Unimicron and Nan Ya PCB include ABF prices falling 15-20% or more than 20% in 2026-2027, which shows the market is not assigning an unconditional premium to ABF. As long as demand weakens, capacity additions exceed expectations, alternative routes prove effective, or prices fail to pass through, valuation will compress first, followed by earnings downgrades.
But the base case still has support. Morgan Stanley believes weak PC demand does not affect the high-end ABF theme, because demand from servers, AI GPUs, AI ASICs, and networking chips is strong enough; general servers should still see double-digit unit growth in 2026; ASP has already bottomed and begun to recover; and raw-material price increases plus specification upgrades are jointly pushing up prices. As long as this combination holds, the 2028 income statement will look better than the 2026 income statement.
9. Risks: Watch Four Lines: Capacity Expansion, T-glass, CoWoP, and Weaker Demand
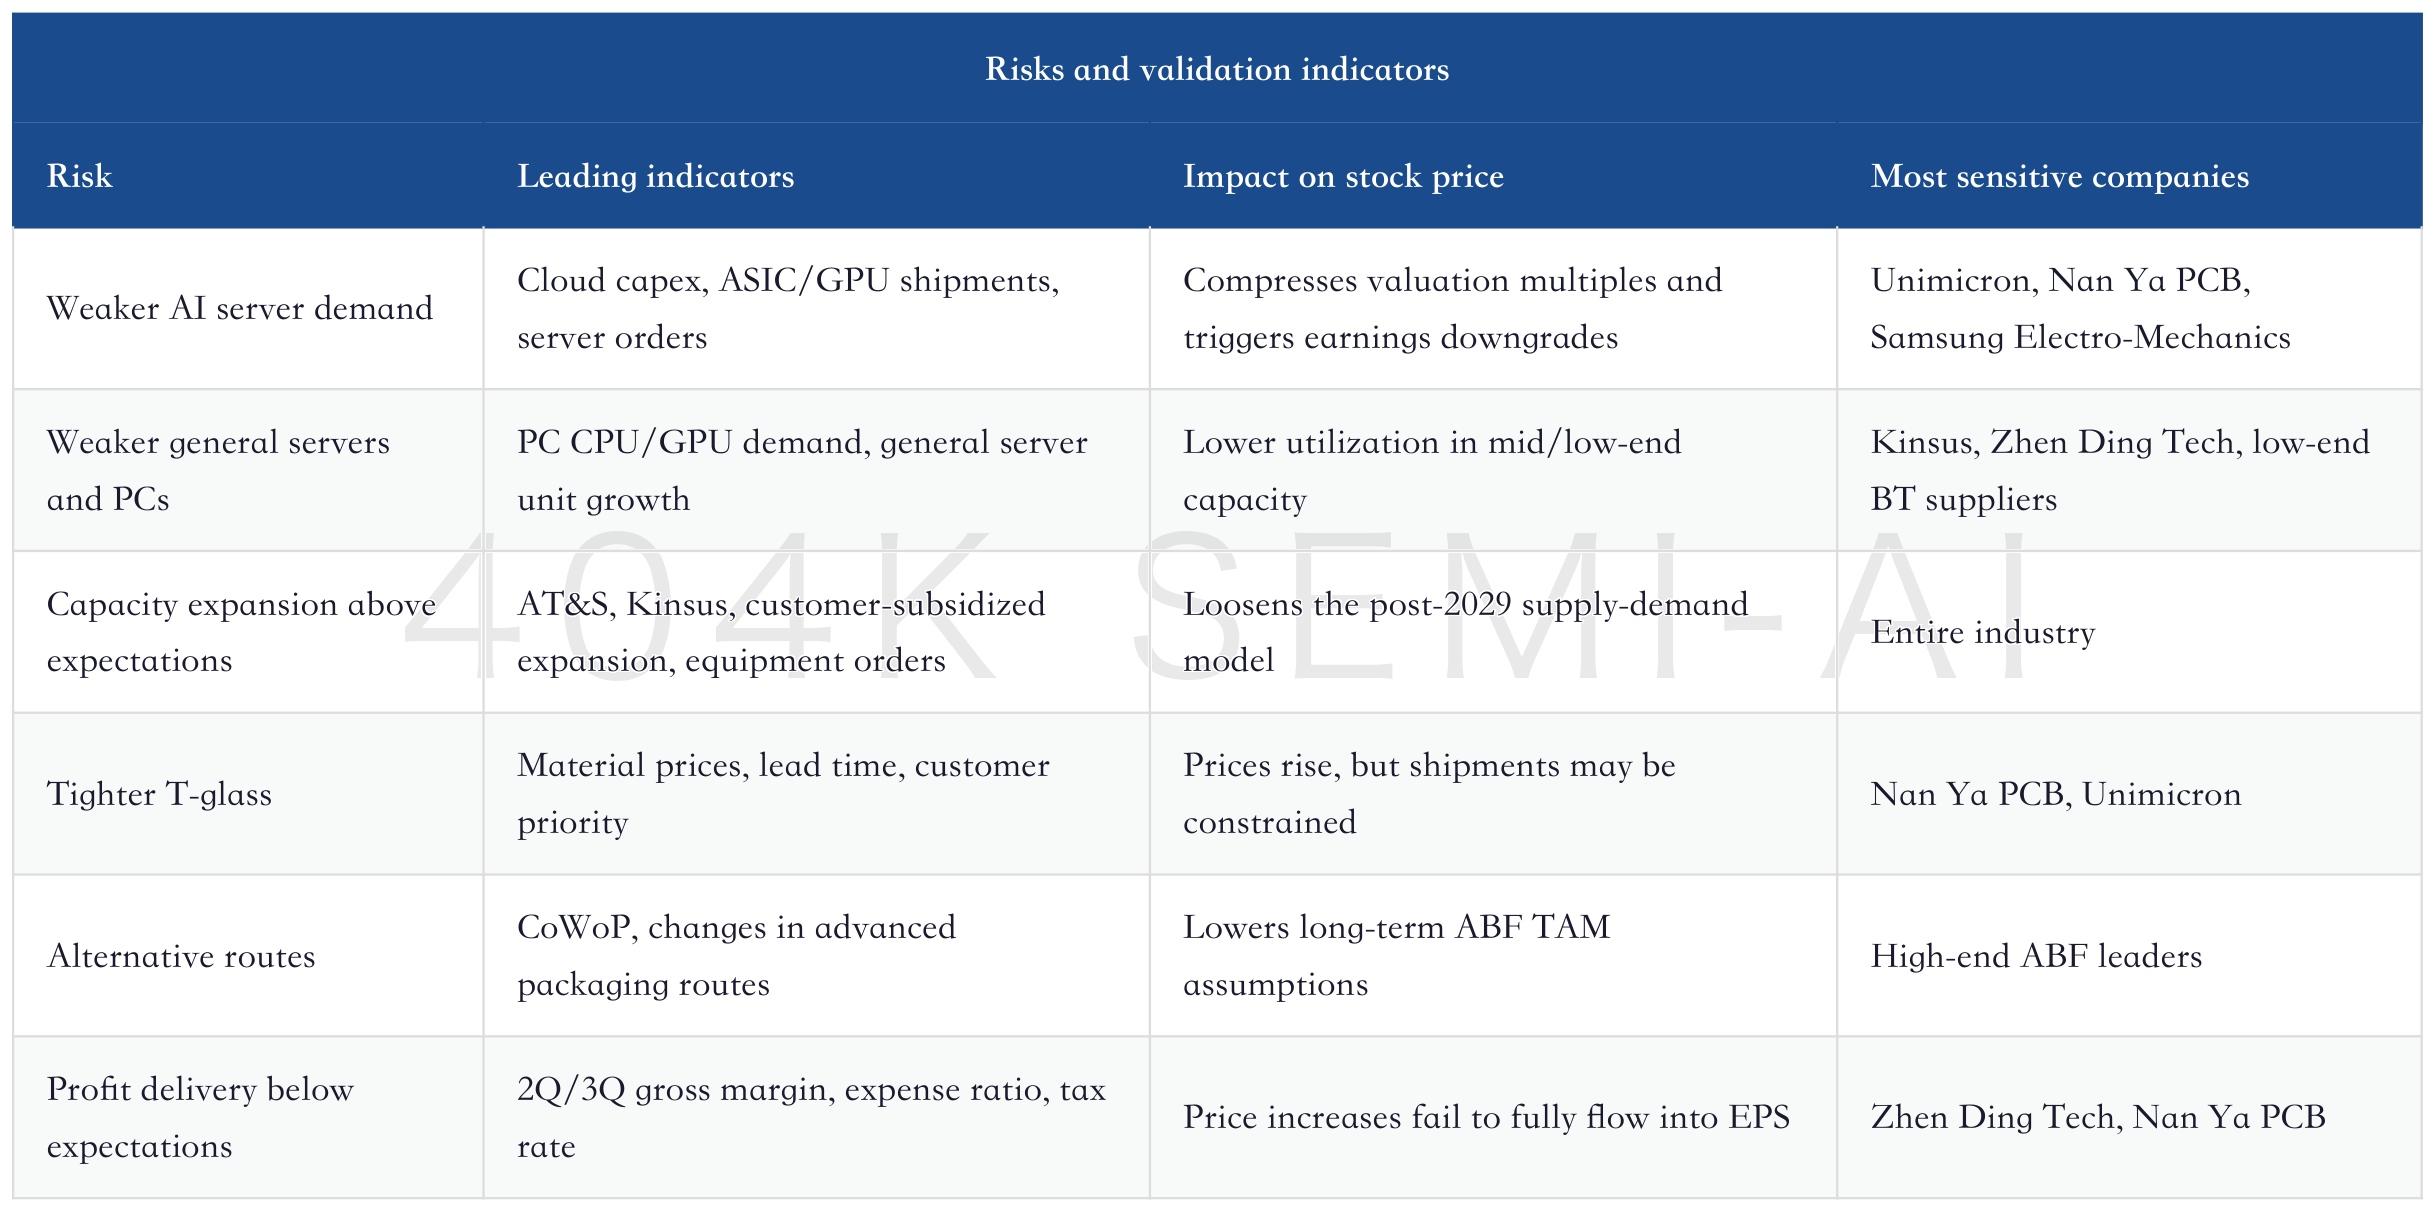
ABF has more risks than just “capacity expansion.” Expansion is of course important, but it often lags. What really changes the slope of the stock price is demand, materials, alternative routes, and profit delivery.
First, weaker demand. If PCs, general-purpose servers, and AI servers are all weaker than expected, price increases will come under pressure first. Demand for high-end ABF is stronger than PCs, but it is not fully immune to macro and capex cycles. If cloud customers delay ASIC/GPU/server CPU projects, customer LTAs and price renegotiations will become harder.
Second, capacity expansion above expectations. New capacity takes at least two years, but if customers use long-term commitments to support capacity expansion by AT&S;, Kinsus, or other suppliers, the post-2029 supply-demand model will need to be recalculated. Expansion is not a near-term risk, but it is a long-term valuation risk.
Third, T-glass and material constraints. Tighter T-glass can have two effects: on one hand, high-end suppliers may prioritize materials for AI chip customers, reinforcing high-end ABF pricing; on the other hand, if material constraints become too severe, they may also cap shipments and revenue recognition. The market should not treat T-glass only as a reason for price increases; it also needs to assess whether it limits suppliers’ deliverable volume.
Fourth, alternative routes such as CoWoP. If some packaging technologies reduce demand for traditional ABF substrate, the long-term model will be affected. Morgan Stanley also lists CoWoP replacing ABF as one risk. In the near term, these alternatives have not changed the 2026-2028 supply-demand balance, but customer roadmaps must be tracked over the long term.
10. What to Track Over the Next Four Quarters
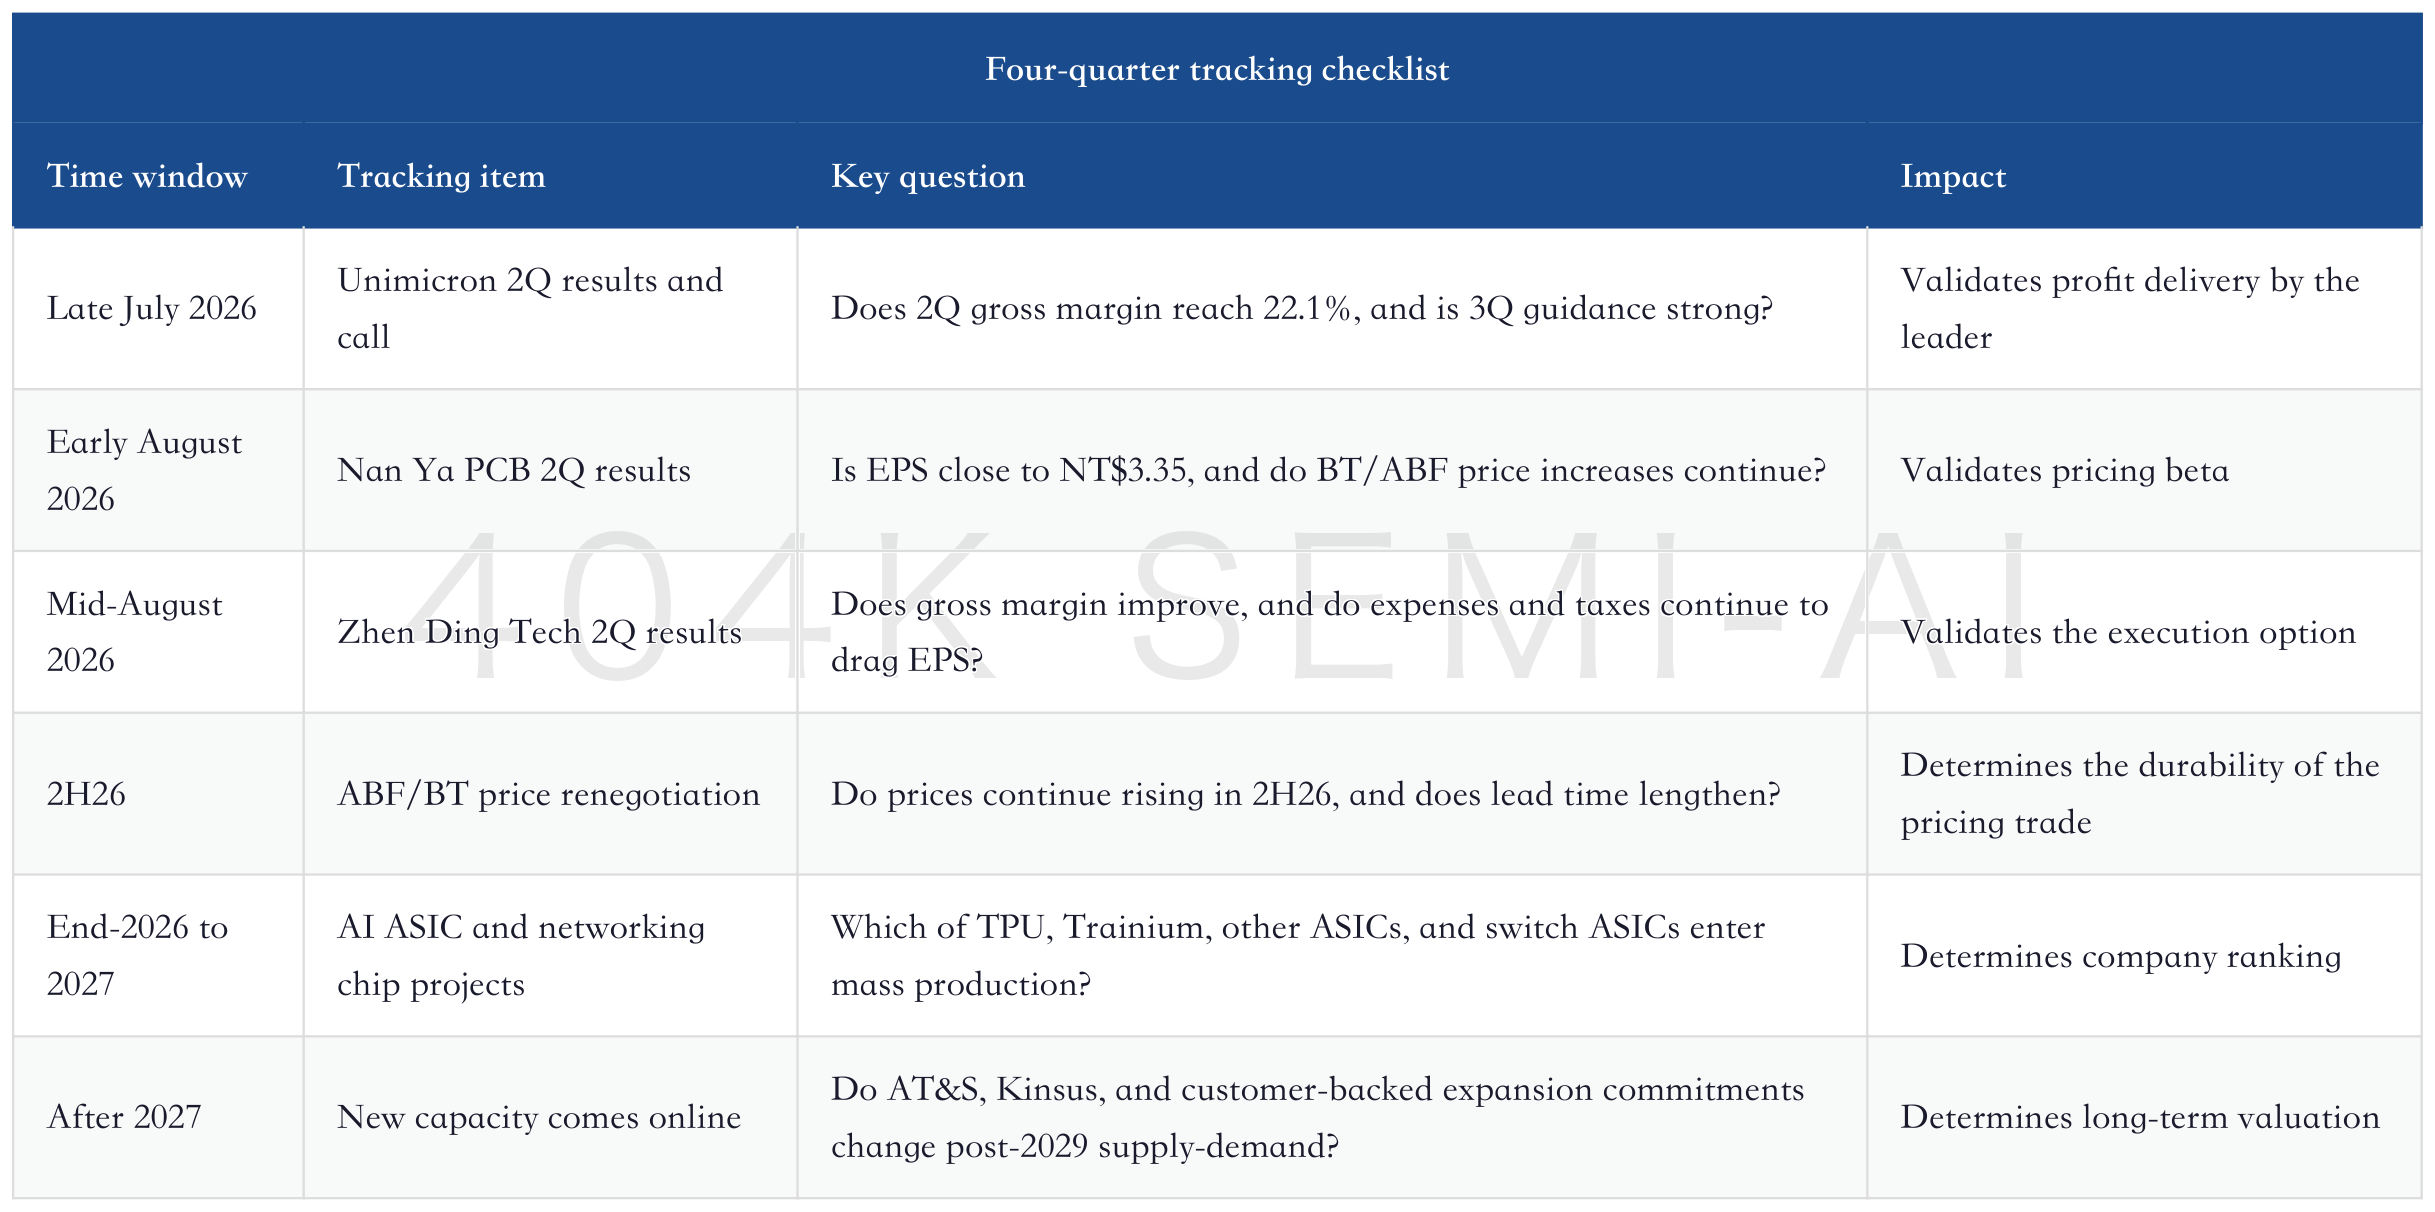
This theme should no longer be tracked only through news on “whether prices are rising.” Effective tracking should be split into four groups: quarterly profits, supply-demand validation, customer qualification, and A-share mapping.
The first group is 2Q26 and 3Q26 results. Unimicron’s 2Q26 results date is July 28, with the earnings call on July 29; Nan Ya PCB’s results are expected on August 6 or 7; Zhen Ding Tech’s results are due before mid-August. Whether the near-term stock move can continue depends on gross margin, 3Q revenue guidance, and management commentary on pricing.
The second group is pricing. Key questions include whether BT prices continue to rise, whether ABF pricing extends from roughly 10% quarterly increases into the second half, whether Nan Ya PCB continues to lead peers in price execution, and whether Unimicron’s LTAs can reflect stronger pricing power when renegotiated in 2027.
The third group is customer qualification. Who gets orders from Google TPU, Amazon Trainium, China AI chips, server CPUs, and networking chips will explain stock-price divergence better than overall industry supply-demand. For Zhen Ding Tech in particular, investors should not only watch ABF prices, but also TPU substrate and AI server PCB customer share.
The fourth group is material-chain linkage. If T-glass, electronic cloth, CCL, copper foil, high-layer-count PCBs, MLCCs, silicon capacitors, and test equipment all show pricing discipline at the same time, it means physical bottlenecks in AI hardware are still spreading. If only ABF rises while other links begin to loosen, investors should be alert to the sustainability of price increases.
The real takeaway from this report is that ABF is no longer just a “materials stock with short-term price upside,” but the packaging foundation after the spread of AI system-level chips. Unimicron represents certainty in high-end effective capacity, Nan Ya PCB represents the sharpest profit leverage from pricing, and Zhen Ding Tech represents the payoff from new qualification breakthroughs. A-share mapping should also be separated along these three lines: PCB companies should be assessed by high-layer-count boards and customers; materials companies by CCL/T-glass/electronic cloth; and substrate companies by customer qualification. As long as the model of an approximately 25% shortage by 2030 is not disproven, the high-end interconnect materials chain remains in the middle stage of moving from cyclical recovery toward asset revaluation.ABF Substrate Deep-Dive Update: 25% Shortfall by 2030, 20-30% BT Price Hikes, and AI ASIC Proliferation: Which of Unimicron, Nan Ya PCB, and Zhen Ding Can Deliver Most
目录
Too Long; Didn’t Read
1. The Key Point of This Upgrade Is Not Price Hikes, but the Cycle Endpoint Moving Later
2. Supply-Demand Ledger: Roughly 25% Shortfall by 2030, and the Price-Hike Cycle Is Not Just About 2026
III. Demand Side: AI Diffusion Is Turning ABF from a PC Cyclical into a System-Level Base Material
IV. Pricing Model: BT Rises First, ABF Follows, and Profit Elasticity Starts Flowing into Gross Margin
V. Company Ranking: Unimicron Is the Steadiest, Nan Ya PCB Has the Most Leverage, Zhen Ding Looks Most Like an Execution Option
VI. Global Peers: High-End Substrates Are Not Only a Taiwan Story; Ibiden and Samsung Electro-Mechanics Define the Technology Ceiling
VII. A-Share Mapping: Do Not Treat Every PCB Company as an ABF Proxy
VIII. Valuation: Why 25x 2028 P/E Is Not Necessarily Expensive
9. Risks: Watch Four Lines: Capacity Expansion, T-glass, CoWoP, and Weaker Demand
10. What to Track Over the Next Four Quarters
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The ABF trade is shifting from validation of 2026 price hikes to a re-rating of effective capacity through 2030. A 25% shortfall, BT moving up first, and AI ASIC proliferation show that substrates have moved from a PC cyclical product to a foundational compute material. The key question is no longer who announces capacity expansion, but who can convert pricing, customer lock-in, and yield into profit.
Too Long; Didn’t Read
The ABF pricing logic has shifted gears. Morgan Stanley raised its 2030 ABF demand/supply ratio from 122.3% in its prior model to 124.6%, implying roughly a 25% supply shortfall. This is not a normal quarterly price hike. It pushes the cycle endpoint from 2027 to 2030 and leads the market to start pricing high-end effective capacity, customer qualification, and materials lock-in.
BT rises first, ABF follows, and Nan Ya PCB has the most direct torque. Supply-chain checks show Nan Ya PCB’s 2Q26 BT substrate prices have already risen by roughly 20-30%, while ABF prices are up about 10%, with further price hikes still possible in the second half. Nan Ya PCB is the most aggressive on pricing execution; the 2028 ABF ASP growth assumption reaches 38.6% YoY, while the gross margin assumption rises to 53.0%.
Unimicron is the most stable core asset. Morgan Stanley raised its target price for Unimicron from NT$1,285 to NT$1,465 and lifted 2026-2028 EPS by 25%, 33%, and 14%, respectively. Its advantage is not short-term spot pricing, but scale profit driven jointly by AI ASICs, server CPUs, major customers, and high-end ABF specification upgrades.
Zhen Ding Tech is a qualification-breakthrough option. Zhen Ding’s target price was raised only from NT$666 to NT$690, and EPS was revised up by just 4%. But the focus is its Shenzhen ABF plant, Google TPU, Chinese AI chips, and AI server PCBs. If TPU substrates and AI PCB yields are delivered, Zhen Ding’s valuation torque will come from execution rather than price hikes.
For A-share mapping, distinguish PCB, CCL, and substrates. WUS Printed Circuit, Victory Giant Technology, Shennan Circuits, Goworld Technology, and Kinwong Electronic are more direct beneficiaries of AI server PCB and switch upgrades, while Shengyi Technology and Shengyi Electronics are more exposed to the CCL and electronic materials chain. The ABF shortfall will lift the industry’s valuation baseline, but not every PCB company should be treated simply as an ABF name.
The biggest counterevidence is not just capacity expansion. New capacity takes at least two years to alter supply-demand. In the near term, what really matters is 2Q gross margin, 3Q revenue guidance, T-glass constraints, customer LTA renewals, spillover from BT pricing, and alternative routes such as CoWoP. If demand weakens simultaneously across AI servers, general-purpose servers, or PCs, the price-hike trade will first pressure valuation multiples.
1. The Key Point of This Upgrade Is Not Price Hikes, but the Cycle Endpoint Moving Later
Morgan Stanley’s ABF substrate report is easily misread as “prices are rising faster than expected.” Pricing is indeed the near-term trigger, but the more important change is in the supply-demand model: the 2030 ABF demand/supply ratio is raised from 122.3% in the old model to 124.6%, implying roughly a 25% supply shortfall. This turns ABF from a 2026-2027 price-hike trade into a 2026-2030 effective-capacity scarcity trade.
Under the old framework, the market asked how much prices rose in 2Q this year, whether they could continue rising in the second half, and whether price hikes could flow into gross margins. Under the new framework, the market needs to ask who still has customer-recognized high-end capacity after 2028, who can secure qualifications for AI ASICs, server CPUs, networking chips, and TPUs, and who can preserve pricing power amid materials constraints, yield ramp, and customer LTAs.
ABF is not a standardized bulk material. It is the packaging foundation between high-performance chips and motherboards. Area, layer count, line density, warpage control, material stability, and qualification cycles all affect effective capacity. Nominal capacity expansion is not the same as deliverable capacity, and customers do not decide who carries next-generation large chips based only on quotes.
This explains why Morgan Stanley raised Unimicron, Nan Ya PCB, and Zhen Ding Tech at the same time, but not in exactly the same order. Unimicron ranks first because its customer position in AI ASICs and server CPUs is the most stable, and it still has 50% upside after the target-price increase. Nan Ya PCB ranks second because it has the most direct pricing leverage in BT and ABF, with strong pricing execution. Zhen Ding Tech ranks third because near-term EPS upgrades are limited, but Google TPU, Chinese AI chips, and AI server PCB add a qualification-breakthrough option.
ABF Substrate Deep Dive: The Packaging Foundation of AI Compute, from Introductory Framework to Supply-Demand Structure and Company Ranking
That historical thesis already made clear that ABF is the packaging foundation of AI compute. The incremental point in this update is that the duration of the foundation shortage has been extended, and profit allocation has also upgraded from “who has capacity” to “who has high-end effective capacity accepted by major customers.”
The key point in this table is not the target prices themselves, but the EPS revision structure. Nan Ya PCB has the largest revisions, showing that its price hikes are most sensitive to the income statement. Unimicron’s revisions are more medium- to long-term, indicating that the high-end ABF shortfall and major-customer structure should release profit year by year. Zhen Ding Tech has the smallest revisions, indicating it remains in a capability-validation phase and should not be placed in the same profit-delivery tier as Unimicron and Nan Ya PCB.
2. Supply-Demand Ledger: Roughly 25% Shortfall by 2030, and the Price-Hike Cycle Is Not Just About 2026
The most important line in the supply-demand model is the new 2030 demand/supply ratio of 124.6%. A demand/supply ratio above 100% means demand exceeds supply. Morgan Stanley’s model implies that 2030 ABF demand will be about one-quarter higher than supply. Compared with the old model, 2026-2028 is already tighter, and the shortfall continues to widen in 2029-2030.
This model imposes two constraints on investment judgment. First, capacity-expansion announcements should not be treated as a simple bearish signal. Morgan Stanley explicitly includes AT&S;’s AI/HPC IC substrate expansion plan in Kulim, Malaysia in its model, yet still sees the 2030 shortfall widening. The reason is that new expansion typically takes at least two years from announcement, equipment, facilities, customer qualification, and yield stabilization, and its real impact on supply-demand usually comes after 2029.
Second, investors should not look only at 2026 price hikes. The 2026 price increases are driven more by materials costs, utilization recovery, and a low base. After 2027, pricing power comes from AI chip specification upgrades and high-end capacity shortages. If 2026 price hikes do not enter gross margins, the trade will be discounted. If high-end capacity lock-in and customer qualifications continue to be delivered in 2027, valuations should not be handled merely as traditional cyclical stocks.
ABF went through a shortage cycle in 2020-2022, then returned to oversupply in 2023-2024 as PCs normalized and new capacity came online. The difference now is that the source of demand has changed. The previous round was driven jointly by work-from-home, PCs, general-purpose servers, and cloud computing. This time, demand is being driven jointly by AI GPUs, ASICs, server CPUs, networking chips, and in-house accelerators. Demand sources are more concentrated in high-end chips, with higher value content and greater manufacturing difficulty.
This is why “effective capacity” matters more than “nominal capacity.” Being able to produce general PC CPU substrates does not mean a supplier can stably produce large-size, high-layer-count, low-warpage ABF compatible with AI ASICs and networking chips. Customer qualification and yield ramp will keep part of nominal capacity outside the income statement.
III. Demand Side: AI Diffusion Is Turning ABF from a PC Cyclical into a System-Level Base Material
ABF used to be a PC cyclical. The demand center has now shifted to servers, AI GPUs, AI ASICs, and networking chips. The mix shift is shown in the table below. The core conclusion is that PCs are rapidly losing explanatory power for ABF, while AI system-level chips are increasingly determining industry pricing and margins.
This structural migration matters more than aggregate growth. PC chips are highly cyclical, face heavy pricing pressure, and offer suppliers limited long-term certainty from customers. AI GPUs, ASICs, server CPUs, and networking chips are different: die sizes are larger, layer counts are higher, packaging complexity is greater, and customers are more willing to pay for delivery certainty, yield, and stable supply.
ABF demand is no longer about “a PC recovery driving a substrate recovery.” It is about “every high-performance logic chip in the AI system becoming larger, more complex, and more expensive.” From GPUs to TPUs, from Trainium to network switch chips, from general-purpose server CPUs to AI orchestration CPUs, substrates are upgrading alongside the chip system.
Morgan Stanley’s demand upgrade mainly comes from three lines. First is the volume ramp of Amazon Trainium and Google TPU. Cloud vendors’ self-developed ASICs are not a small GPU-substitution story, but a new source of ABF area demand. Second is “China AI chips” and other ASICs, where the 2030 assumption has been raised meaningfully, implying local accelerators are also consuming high-end substrates. Third is the networking layer of AI systems, where switch ASICs and high-end networking chips are spreading ABF demand from compute chips to the interconnect layer.
For ABF, the essence of the spillover in the AI server materials chain is that compute systems need not only more GPUs, but also more expensive packaging, interconnects, substrates, PCBs, CCL, electronic glass cloth, MLCCs, and test equipment. ABF is the layer closest to the chip, so pricing and qualification elasticity are the first to be traded by the market.
IV. Pricing Model: BT Rises First, ABF Follows, and Profit Elasticity Starts Flowing into Gross Margin
The hardest short-term evidence is in pricing and gross margin. Morgan Stanley supply-chain checks show Nan Ya PCB’s 2Q26 BT substrate prices rose about 20-30%, while ABF substrate prices rose about 10%, with further increases expected in 2H26. This cadence shows that price hikes are not only sitting in long-term supply-demand models, but have already started to enter quarterly income statements.
BT rising first has two implications. First, supply-demand for low-end or mid-range substrates is also tightening. Memory customers have not pushed prices down; instead, lead times continue to extend. Second, BT price increases will transmit to ABF because materials, equipment, customer scheduling, and supplier resource allocation are connected. If suppliers can raise prices in BT, they have even stronger grounds to demand higher prices for high-end ABF.
Morgan Stanley’s medium-term ABF pricing assumptions have also become meaningfully steeper: ABF pricing is assumed to grow 20-25% YoY in 2026 and more than 25% in 2027; prices continue to rise in 2028, but with wider customer dispersion. Because Unimicron has higher exposure to major customers and long-term agreements, its 2028 price-growth assumption is above 20%; because Nan Ya PCB has tighter supply-demand and more aggressive price execution, its 2028 ABF price-growth assumption reaches more than 40%.
ABF and BT Substrate Price Hikes Revised Up Again: From T-glass Constraints to BT Spillover, Why the AI Substrate Price-Hike Cycle Is Not Over Yet
The linkage between BT and ABF is the short-term main line of this price-hike trade. BT price increases show the market that substrate supply-demand tightness is not limited to high-end AI ABF. ABF price increases confirm that major customers are also paying for certainty in high-end packaging. Together, these two lines are the fundamental reason Nan Ya PCB’s second-quarter earnings exceeded expectations.
This table separates the three companies. Unimicron looks like the core asset in high-end ABF, with profits coming from customer structure, scale, and high-end product mix. Nan Ya PCB looks like the price-hike beta, with the largest profit elasticity when BT and ABF rise at the same time. Zhen Ding Technology looks like a new-qualification option: price hikes help, but the ceiling on valuation depends on whether Google TPU, AI server PCB, and China AI chip projects can be executed successfully.
The short-term verification points are also clear. For Unimicron, watch whether 2Q26 gross margin can reach 22.1%, and whether 3Q revenue guidance proves volume ramp in AI ASIC and server CPU projects. For Nan Ya PCB, watch whether 2Q26 EPS can reach NT$3.35, and whether 3Q gross margin continues to expand. For Zhen Ding Technology, watch 2Q26 gross margin and 3Q margin, but Morgan Stanley believes its EPS may still come in below consensus because expenses and taxes will offset part of the operating improvement.
V. Company Ranking: Unimicron Is the Steadiest, Nan Ya PCB Has the Most Leverage, Zhen Ding Looks Most Like an Execution Option
Unimicron, Nan Ya Printed Circuit Board, and Zhen Ding Technology are all maintained at Overweight, but their payoff profiles come from different sources. Putting them in the same “ABF price hike” basket would miss the real differences.
Unimicron’s keywords are major customers, high-end ABF, AI ASICs, and server CPUs. Morgan Stanley raised its 2026-2028 EPS estimates by 25%, 33%, and 14%, respectively, and lifted its gross margin assumption from 23.1% in 2026 to 38.3% in 2028. Its target price implies 25x 2028 P/E, so it is not cheap. But if high-end ABF remains in shortage from 2027 onward, the leader’s pricing framework could shift from cyclical stock to effective-capacity asset.
Unimicron also has one point that is easily underestimated: it may not be the fastest company to raise prices, but it is the best positioned to take on long-term projects from major customers. If AI ASICs, server CPUs, and next-generation large-scale packaging keep upgrading, customers will want stable supply, not the lowest quotation every quarter. LTAs may suppress price-hike leverage in the short term, but over the long term they could become a source of customer lock-in and capacity-expansion visibility.
Nan Ya PCB’s keywords are price execution, BT spillover, and networking chips. In 2Q26, BT substrate prices rose 20-30% and ABF prices rose about 10%; the second-quarter earnings beat mainly came from pricing and gross margin. Morgan Stanley raised Nan Ya PCB’s 2026-2028 EPS estimates by 36%, 39%, and 23%, respectively, and lifted its target price from NT$1,275 to NT$1,550.
Nan Ya PCB’s advantage is that price hikes flow into the income statement faster. The drawback is the same thing: when the market is trading price leverage, it shines the most; when the market starts worrying about demand, capacity expansion, or substitute technologies, its valuation will also be pressured first. Nan Ya PCB is better viewed as the sharpest earnings-leverage play in the ABF and BT price-hike cycle, rather than the steadiest long-term asset.
Zhen Ding Technology’s keyword is qualification breakthrough. It is not a pure ABF company. iPhone F-PCB, SLP, AI server PCB, optical module PCB, and ABF/BT substrates are all in the model. Morgan Stanley raised Zhen Ding’s 2026-2028 EPS estimates by only 4% and lifted its target price from NT$666 to NT$690, showing that near-term price hikes have limited impact on its income statement.
But Zhen Ding should not be judged only by that 4%. The key is that its Shenzhen ABF fab 1 turned profitable in 1Q26, its Kaohsiung plant is planned for mass production in 2H26, and Shenzhen fab 2 is also under construction. At the same time, it is viewed as one of the key ABF suppliers for Chinese AI chips and is increasing its ABF exposure to international customers, with Google TPU being the most important validation point. If TPU substrates execute well and help it get closer to more ASIC/GPU customers, Zhen Ding’s valuation could shift from “consumer electronics PCB company” to “AI interconnect and substrate platform.”
Put more simply: for certainty, look first at Unimicron; for price-hike leverage, look at Nan Ya PCB; for new qualification breakthroughs, look at Zhen Ding Technology. All three benefit from the ABF gap, but the market values them for different reasons.
VI. Global Peers: High-End Substrates Are Not Only a Taiwan Story; Ibiden and Samsung Electro-Mechanics Define the Technology Ceiling
ABF is not a single-region supply chain. In Morgan Stanley’s peer table, in addition to Unimicron, Nan Ya PCB, and Zhen Ding Technology, the companies include Ibiden, Samsung Electro-Mechanics, AT&S;, and Kinsus. These companies occupy different positions, and the market assigns them different valuations.
Ibiden is the technology-ceiling asset in high-end ABF. It has strong customer relationships in high-end server CPUs, GPUs, and advanced packaging, but its current valuation is already very high, and Morgan Stanley rates it Underweight. Samsung Electro-Mechanics is a broad electronic components leader. ABF, MLCCs, silicon capacitors, and other AI data center materials all enter its income statement, so its valuation logic is not a single ABF shortage, but the re-rating of a “high-value-added electronic components portfolio.”
Kinsus is another type of asset. It has ABF capacity and customer-sponsored expansion signals, and also benefits from tight supply in T-glass and high-end substrates, but it is not a core covered name in this Morgan Stanley report. AT&S; enters the model through AI/HPC substrate expansion in Kulim, Malaysia, showing that customers are willing to support new capacity with long-term commitments, though the capacity ramp is still after 2029.
Ibiden Deep Dive: Citi Sees ¥30,000; How AI CPU Package Substrates Re-rate the ABF Leader
Samsung Electro-Mechanics Deep-Dive Update: Goldman Sachs Raises Estimates Sharply as AI Servers Push MLCCs, Silicon Capacitors, and ABF into the Income Statement
This table has a counterintuitive conclusion: cheaper is not always better for ABF stocks. Ibiden is expensive because its technology ceiling and customer position are extremely strong. Unimicron looks expensive, but its valuation will fall quickly after earnings scale in 2028. Nan Ya PCB has the highest 2028 ROE, proving that earnings leverage is very steep once price hikes flow into gross margin. Zhen Ding Technology’s valuation is not expensive, but ROE has not yet fully reflected the potential of new businesses, and execution risk is also higher.
VII. A-Share Mapping: Do Not Treat Every PCB Company as an ABF Proxy
The most important implication of this report for A-shares is not “buy all PCB names,” but to separate the value chain into three layers: first, ABF substrates themselves; second, AI server PCBs and switch PCBs; third, CCL, electronic cloth, glass fiber cloth, and copper foil materials. All three layers benefit from AI hardware upgrades, but their earnings elasticity, validation metrics, and valuation anchors are completely different.
WUS Printed Circuit is closer to AI server PCBs and switch PCBs. The core variables are 1.6T/3.2T switches, high-layer-count boards, customer mix, and pricing discipline. Victory Giant Technology is more like an effective-capacity asset in AI PCBs; the market needs to track high-layer-count MLPCBs, HDI, overseas capacity, and joint development with customers. Shennan Circuits has packaging substrates, communications PCBs, and server-related capabilities, but investors need to distinguish margin profiles and customer timing across businesses. Guanghe Technology, Kinwong Electronic, and DSBJ correspond respectively to AI PCBs, automotive/server PCBs, optical interconnects, and the migration from consumer electronics to AI.
WUS Printed Circuit deep-dive update: Citi’s RMB189 target price, 1.6T switches, 3.2T R&D;, and AI PCB pricing discipline
Victory Giant Technology deep-dive update: Rubin high-layer-board delays, new TPU orders, and how RMB20bn capex validates effective AI PCB capacity
Guanghe Technology deep dive: Citi’s RMB241 target price and why AI servers need more expensive PCBs
Shengyi Technology and Shengyi Electronics sit more in CCL, electronic materials, and the PCB supply chain. An ABF shortage will raise the market’s valuation tolerance for high-end interconnect materials, but Shengyi Technology is not an ABF leader, and Taiwan ABF pricing assumptions cannot simply be copied into its income statement. A more reasonable read is that the overall AI server materials chain is upgrading, which strengthens pricing discipline for high-end CCL, electronic cloth, glass fiber, copper foil, and high-layer-count PCBs.
AI PCBs and ABF substrates both benefit from the same underlying trend: chips are becoming larger, systems are becoming more complex, and the interconnect value per rack is rising. But they show up differently in the income statement. ABF is closer to chip packaging, where customer qualification and high-end materials are harder. AI PCBs are closer to server and switch systems, and are more affected by layer count, material grade, yield, drilling and lamination, and customer delivery cadence.
Therefore, the real way to trade A-shares is not to copy Morgan Stanley’s target prices for the three companies, but to treat the ABF shortage as an upstream signal for the high-end interconnect value chain. As long as ABF continues to rise in price, the physical bottleneck in AI hardware has not been resolved. As long as BT, CCL, electronic cloth, and PCBs all show pricing discipline at the same time, this is not a single-point shortage, but a system-level revaluation of the materials chain.
AI PCB and CCL deep dive: From GB300 to Rubin Ultra, which becomes scarce first: high-layer boards, M9 materials, or electronic cloth?
The role of these earlier pieces is to place ABF back into the overall AI server value chain. ABF is not an isolated shortage. Together with PCBs, CCL, electronic cloth, T-glass, MLCCs, silicon capacitors, and test equipment, it forms the physical gate for AI hardware. When screening stocks, it is better to move layer by layer along “chip packaging - materials - PCB - server/switch delivery,” rather than simply buying by industry label.
VIII. Valuation: Why 25x 2028 P/E Is Not Necessarily Expensive
Morgan Stanley uses 25x 2028 P/E as the target-price framework for both Unimicron and Nan Ya PCB, and 20x 2028 P/E for Zhen Ding Technology. For traditional substrate cyclical stocks, this valuation does not look low. But if high-end ABF remains in shortage through 2027-2030, the valuation anchor cannot be limited to the historical 10-20x range.
The core difference is earnings quality. For traditional cyclical stocks, price increases come from short-term supply-demand mismatches; once supply comes online, prices and margins fall back. High-end ABF price increases come from customer qualification, technical specifications, effective capacity, and materials constraints. Even with new capacity additions, truly usable capacity still has to go through customer certification, yield ramp-up, and product iteration. Suppliers are not only selling capacity; they are also selling delivery certainty.
Unimicron’s target price implies 44x 2027 P/E and 25x 2028 P/E; Nan Ya PCB’s implies 47x 2027 P/E and 25x 2028 P/E; Zhen Ding Technology’s implies 27x 2027 P/E and 20x 2028 P/E. High multiples are not risk-free, but if 2028 earnings continue to be revised up, valuation will be absorbed quickly by earnings.
The bear cases are most worth noting. The bear-case assumptions for both Unimicron and Nan Ya PCB include ABF prices falling 15-20% or more than 20% in 2026-2027, which shows the market is not assigning an unconditional premium to ABF. As long as demand weakens, capacity additions exceed expectations, alternative routes prove effective, or prices fail to pass through, valuation will compress first, followed by earnings downgrades.
But the base case still has support. Morgan Stanley believes weak PC demand does not affect the high-end ABF theme, because demand from servers, AI GPUs, AI ASICs, and networking chips is strong enough; general servers should still see double-digit unit growth in 2026; ASP has already bottomed and begun to recover; and raw-material price increases plus specification upgrades are jointly pushing up prices. As long as this combination holds, the 2028 income statement will look better than the 2026 income statement.
9. Risks: Watch Four Lines: Capacity Expansion, T-glass, CoWoP, and Weaker Demand
ABF has more risks than just “capacity expansion.” Expansion is of course important, but it often lags. What really changes the slope of the stock price is demand, materials, alternative routes, and profit delivery.
First, weaker demand. If PCs, general-purpose servers, and AI servers are all weaker than expected, price increases will come under pressure first. Demand for high-end ABF is stronger than PCs, but it is not fully immune to macro and capex cycles. If cloud customers delay ASIC/GPU/server CPU projects, customer LTAs and price renegotiations will become harder.
Second, capacity expansion above expectations. New capacity takes at least two years, but if customers use long-term commitments to support capacity expansion by AT&S;, Kinsus, or other suppliers, the post-2029 supply-demand model will need to be recalculated. Expansion is not a near-term risk, but it is a long-term valuation risk.
Third, T-glass and material constraints. Tighter T-glass can have two effects: on one hand, high-end suppliers may prioritize materials for AI chip customers, reinforcing high-end ABF pricing; on the other hand, if material constraints become too severe, they may also cap shipments and revenue recognition. The market should not treat T-glass only as a reason for price increases; it also needs to assess whether it limits suppliers’ deliverable volume.
Fourth, alternative routes such as CoWoP. If some packaging technologies reduce demand for traditional ABF substrate, the long-term model will be affected. Morgan Stanley also lists CoWoP replacing ABF as one risk. In the near term, these alternatives have not changed the 2026-2028 supply-demand balance, but customer roadmaps must be tracked over the long term.
10. What to Track Over the Next Four Quarters
This theme should no longer be tracked only through news on “whether prices are rising.” Effective tracking should be split into four groups: quarterly profits, supply-demand validation, customer qualification, and A-share mapping.
The first group is 2Q26 and 3Q26 results. Unimicron’s 2Q26 results date is July 28, with the earnings call on July 29; Nan Ya PCB’s results are expected on August 6 or 7; Zhen Ding Tech’s results are due before mid-August. Whether the near-term stock move can continue depends on gross margin, 3Q revenue guidance, and management commentary on pricing.
The second group is pricing. Key questions include whether BT prices continue to rise, whether ABF pricing extends from roughly 10% quarterly increases into the second half, whether Nan Ya PCB continues to lead peers in price execution, and whether Unimicron’s LTAs can reflect stronger pricing power when renegotiated in 2027.
The third group is customer qualification. Who gets orders from Google TPU, Amazon Trainium, China AI chips, server CPUs, and networking chips will explain stock-price divergence better than overall industry supply-demand. For Zhen Ding Tech in particular, investors should not only watch ABF prices, but also TPU substrate and AI server PCB customer share.
The fourth group is material-chain linkage. If T-glass, electronic cloth, CCL, copper foil, high-layer-count PCBs, MLCCs, silicon capacitors, and test equipment all show pricing discipline at the same time, it means physical bottlenecks in AI hardware are still spreading. If only ABF rises while other links begin to loosen, investors should be alert to the sustainability of price increases.
The real takeaway from this report is that ABF is no longer just a “materials stock with short-term price upside,” but the packaging foundation after the spread of AI system-level chips. Unimicron represents certainty in high-end effective capacity, Nan Ya PCB represents the sharpest profit leverage from pricing, and Zhen Ding Tech represents the payoff from new qualification breakthroughs. A-share mapping should also be separated along these three lines: PCB companies should be assessed by high-layer-count boards and customers; materials companies by CCL/T-glass/electronic cloth; and substrate companies by customer qualification. As long as the model of an approximately 25% shortage by 2030 is not disproven, the high-end interconnect materials chain remains in the middle stage of moving from cyclical recovery toward asset revaluation.