
ABF and BT Substrate Price-Hike Assumptions Revised Higher: From T-glass Constraints to BT Spillover, Why the AI Substrate Price Cycle Is Not Over Yet
目录
Too Long; Didn't Read
1. Citi Is Revising the Income Statement, Not Just Changing Target Prices
2. The ABF Price Cycle Is Not Over, and BT Supply Is Also Starting to Tighten
3. Nan Ya PCB: The Most Direct Price Elasticity, Watch Broadcom and Switch Chips First
4. Kinsus: Vera CPU and BT Spillover Stack Together; Elasticity Comes from Dual-Line Utilization
5. Unimicron: Stronger Scale and Resource Advantages, but Less Near-Term Elasticity Than Nan Ya PCB and Kinsus
6. The Three Companies Are Not the Same Trade; Ranking Should Be Layered by Price, Utilization, and Resources
7. Valuation Depends on Whether 30x Is Justified by Gross-Margin Revisions
8. Follow-Up Verification Checklist: Four Hard Indicators Determine How Far This Cycle Can Go
9. Risks: When the Cycle Is Strengthening, the Biggest Risk Is Insufficient Realization Speed
10. Investment View: Separate the Three Companies by Capital Type and Realization Window
11. Conclusion: This Is Not "ABF Is Still Short," but "How Does the Shortage Enter the Income Statement"
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The AI substrate trade is moving from "shortages drive price hikes" to "who can translate those hikes into gross margin." Citi has raised target prices for Nan Ya PCB, Kinsus, and Unimicron at the same time. The real incremental point is that both ABF and BT substrate lines are entering a margin upgrade window. The key test is whether monthly earnings can support a 2027 EPS rerating.
Too Long; Didn't Read
This upgrade is a margin trade. Citi raised target prices for Nan Ya PCB, Kinsus, and Unimicron while keeping all three at Buy. The target-price moves themselves are not the point. The point is that Citi materially lifted its 2027E EPS and gross-margin assumptions, which means substrate makers' pricing power is starting to move from order visibility into reported profits.
ABF tightness still extends into 2027. AI GPUs, ASICs, and CPUs continue to consume more large-size, high-layer-count, high-yield ABF capacity. Citi expects ABF prices to rise 15-20% QoQ in 3Q26 and another 10-15% QoQ in 4Q26. If ABF capacity in mainland China does not see demand loosen, global customers will still pay a premium for delivery certainty, making near-term supply easing unlikely to become the main narrative.
BT substrates are moving from supporting role to second source of upside. BT used to be treated mainly as a consumer-electronics and memory-packaging cycle. This time, the change is coming from the supply side: Unimicron plans to cut at least 15% of BT capacity by end-2026, with a possible medium-term cut of 40-50%, while some peers are also converting BT lines to ABF. Order spillover should lift utilization at Kinsus and Nan Ya PCB, giving BT gross margin a chance to rise from the historical 5-15% range to above 20%.
Nan Ya PCB and Kinsus have faster near-term elasticity. Nan Ya PCB is more willing to retain spot-pricing exposure. Broadcom Tomahawk, switch chips, and selected ASIC projects allow ABF price elasticity to enter the P&L; faster. Kinsus benefits at the same time from Vera CPU share, BT order spillover, and capacity ramp. Unimicron's strengths are scale, T-glass resources, and long-term customers, but its near-term price-hike leverage will be diluted by long-term agreements and a broader business mix.
Whether 30x valuation can hold depends on four numbers. First, whether monthly unaudited earnings can beat consensus gross margin by 2-3 ppts. Second, whether 3Q26 and 4Q26 ABF price increases land as scheduled. Third, whether BT utilization at Kinsus and Nan Ya PCB improves sequentially. Fourth, whether Unimicron can prove current gross-margin expansion is not just ABF demand, but a joint contribution from HDI, T-glass, and long-term contract repricing.
The biggest risk is not "ABF is unimportant," but that the shortage is disproved earlier than expected. If new T-glass supplier certification is faster than expected, AI chip development is delayed, demand for mainland China ABF capacity loosens, customers resist repeated price hikes, or effective 2027 capacity additions arrive in a cluster, the valuation base of 30x 2027E EPS will compress. The key risk in the current trade is not lack of demand, but failure of price, utilization, and gross margin to materialize at the same time.
1. Citi Is Revising the Income Statement, Not Just Changing Target Prices
ABF substrates have already been traded repeatedly. The old questions were whether they were short, whether prices would rise, and whether capacity expansion would quickly kill the cycle. The incremental point in Citi's June 30, 2026 report is narrower and closer to the P&L;: ABF price hikes are still progressing, BT supply-demand is also starting to improve, and Taiwanese substrate makers are entering a gross-margin expansion cycle.
This shifts the question from supply-chain position to profit allocation. The rising demand for AI GPUs, ASICs, and CPUs no longer needs to be reproven. What matters is who can turn the shortage into price, who can turn price into gross margin, and who is still held back by long-term agreements, materials, customer mix, or depreciation.
Full Revaluation of AI PCB Materials - From CCL Price Hikes and Glass-Fiber Fabric Looms to the ABF Gap and Rack Upgrades
AI PCB Phase Three: Capacity Expansion Is Not the Answer; Glass-Fiber Fabric Looms, T-glass, HVLP Copper Foil, Lamination/Drilling, and Certification Cycles Determine Who Really Opens Supply
Citi keeps all three companies at Buy this time, but the scale of target-price and earnings-model revisions is large. Kinsus's new target price is 2.75x the old one; Nan Ya PCB is raised by 41%; Unimicron is raised by 39%. The three companies are compared on the same report date, same currency, and same share unit, with no cross-currency or ADR-unit conversion involved.
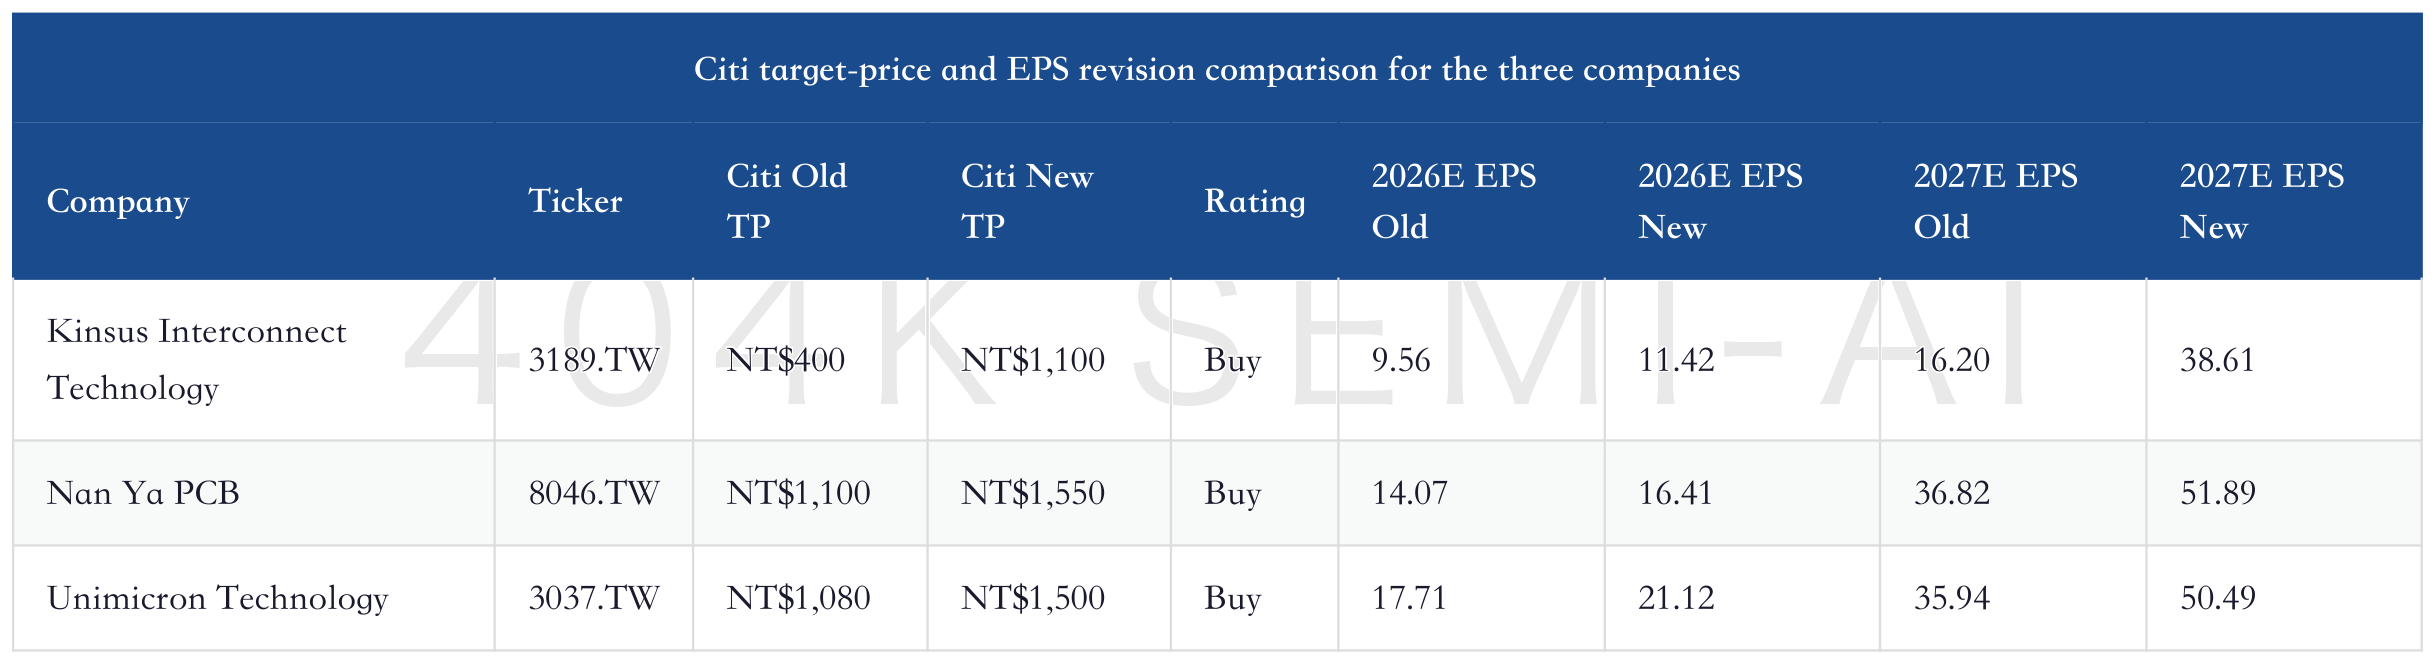
The key information in this table is not the absolute target price, but 2027E EPS. Kinsus's 2027E EPS rises from NT$16.20 to NT$38.61, Nan Ya PCB from NT$36.82 to NT$51.89, and Unimicron from NT$35.94 to NT$50.49. Citi is not only raising the valuation multiple; it is also moving the earnings center higher.
If one looks only at target prices, this can easily be read as a routine upgrade note. Seen within the AI PCB series, it looks more like a phase-shift signal: earlier rounds of the trade relied on material shortages, T-glass, the ABF gap, and high-end CCL. Now the market is starting to ask whether ABF and BT price hikes can land simultaneously in monthly earnings, gross margin, and 2027 EPS.
Cross-reading earlier Taiwanese substrate materials makes this phase shift clearer. Earlier reports on Kinsus emphasized its benefit from ABF and BT substrates, with the core being utilization and target-price upgrades. Materials on Unimicron emphasized that the substrate tailwind was still at an early stage, with the core being ABF strength and leadership. Materials on Nan Ya PCB emphasized strong monthly earnings, with the core being near-term gross margin and order elasticity. T-glass materials placed the material constraint at the bottleneck of the supply chain.
These clues were originally scattered. Kinsus was about operating leverage. Unimicron was about scale and high-end supply. Nan Ya PCB was about near-term price elasticity. T-glass was about the material gate. Citi's report combines them into one income-statement thread: tight materials support ABF pricing, the leader's adjustment of BT capacity creates order spillover, customers accept higher prices for delivery certainty, and gross margin and EPS are then revised higher in a systematic way.
That is why this report should not be treated as merely a "target-price upgrade list." Target prices are the result; the process is supply-demand improvement expanding from a single ABF shortage to dual-line improvement in ABF and BT. Ratings are the surface; underneath, the earnings model is moving from revenue upgrades to gross-margin upgrades. As long as this process holds, the key substrate-stock question shifts from "who has capacity" to "who can retain the profit after price hikes."
Conversely, if later data only prove that ABF is still short, but fail to prove BT order spillover, monthly earnings beats, and continued gross-margin expansion, the optimistic assumptions in this report will weaken. Between industry bottleneck and company profit sit customer bargaining, material costs, yield ramp, depreciation, and product mix. If any one of these is handled poorly, the shortage may remain only on the revenue line.
AI PCB: From Materials Revaluation to Profit Realization - Shennan 30+ Layer MLPCB, TUC High-End CCL, Kingboard Materials Integration, Nan Ya PCB and Unimicron ABF Substrates, Who Books the Price Hikes First
2. The ABF Price Cycle Is Not Over, and BT Supply Is Also Starting to Tighten
ABF tightness is being squeezed from both demand and materials. Citi assumes ABF prices rise 15-20% QoQ in 3Q26 and another 10-15% QoQ in 4Q26. This is not a mild price adjustment, but two consecutive quarters of price increases.
There are three conditions behind the ability of prices to rise sequentially.
First, AI chip demand is still expanding. GPUs, ASICs, and CPUs are all increasing ABF consumption. High-performance chips require substrates with larger size, higher layer counts, lower warpage, and higher yield. Nominal shipment volume cannot be equated directly with capacity consumption. A complex ASIC or AI CPU may consume far more effective capacity than an ordinary PC chip.
Second, T-glass remains the master gate. Citi believes T-glass constraints may last into 2027 because certification of new suppliers is progressing more slowly than expected. Taiwan Glass is advancing faster in thick glass, but its quality has not yet reached Nittobo's level. EMC's ABF CCL, MGC's RS Resin, Nan Ya Plastics' T-glass solution, and other new suppliers still need validation. Customers can look for alternatives, but mass-production qualification cannot be solved immediately by procurement intent.
Third, there is no obvious loosening in mainland China ABF capacity. Citi observes improved utilization of mainland China ABF capacity, while peers such as Zhen Ding are also expanding capacity. For some U.S. customers, mainland China ABF capacity is not the optimal choice, but it will still be used when options are limited. At the same time, AI demand in the China market is also competing for capacity. As long as this capacity does not see demand loosen, global ABF supply-demand is unlikely to ease quickly.
ABF Substrate Deep Dive: The Packaging Foundation of AI Compute, from Basic Framework to Supply-Demand Landscape and Company Ranking
The change in BT is easier to underestimate. In the past, the market was more excited about ABF and more cautious on BT, because BT was tied to memory, smartphones, and traditional packaging cycles, and its margin was not as high as ABF's. Citi calls out BT separately this time because the supply side is starting to change: some peers are unwilling to keep taking BT orders, or plan to convert BT lines into ABF lines.
Unimicron is the key variable. Citi notes that Unimicron plans to cut at least 15% of total BT capacity by end-2026, likely mainly from WBCSP-related products at its Taiwan plants. In the medium term, Citi expects Unimicron could cut 40-50% of BT capacity, but it will not fully exit because Apple and some Chinese customers still have BT demand, and the Suzhou BT plant may be retained.
BT looks lower-end, but supply exits will give remaining makers better pricing and utilization. Citi estimates that Unimicron's 2025 BT sales account for about 11% of BT sales among major global peers. If Unimicron cuts 40-50% of BT capacity in the medium term, orders will gradually flow to Taiwanese peers such as Kinsus and Nan Ya PCB.
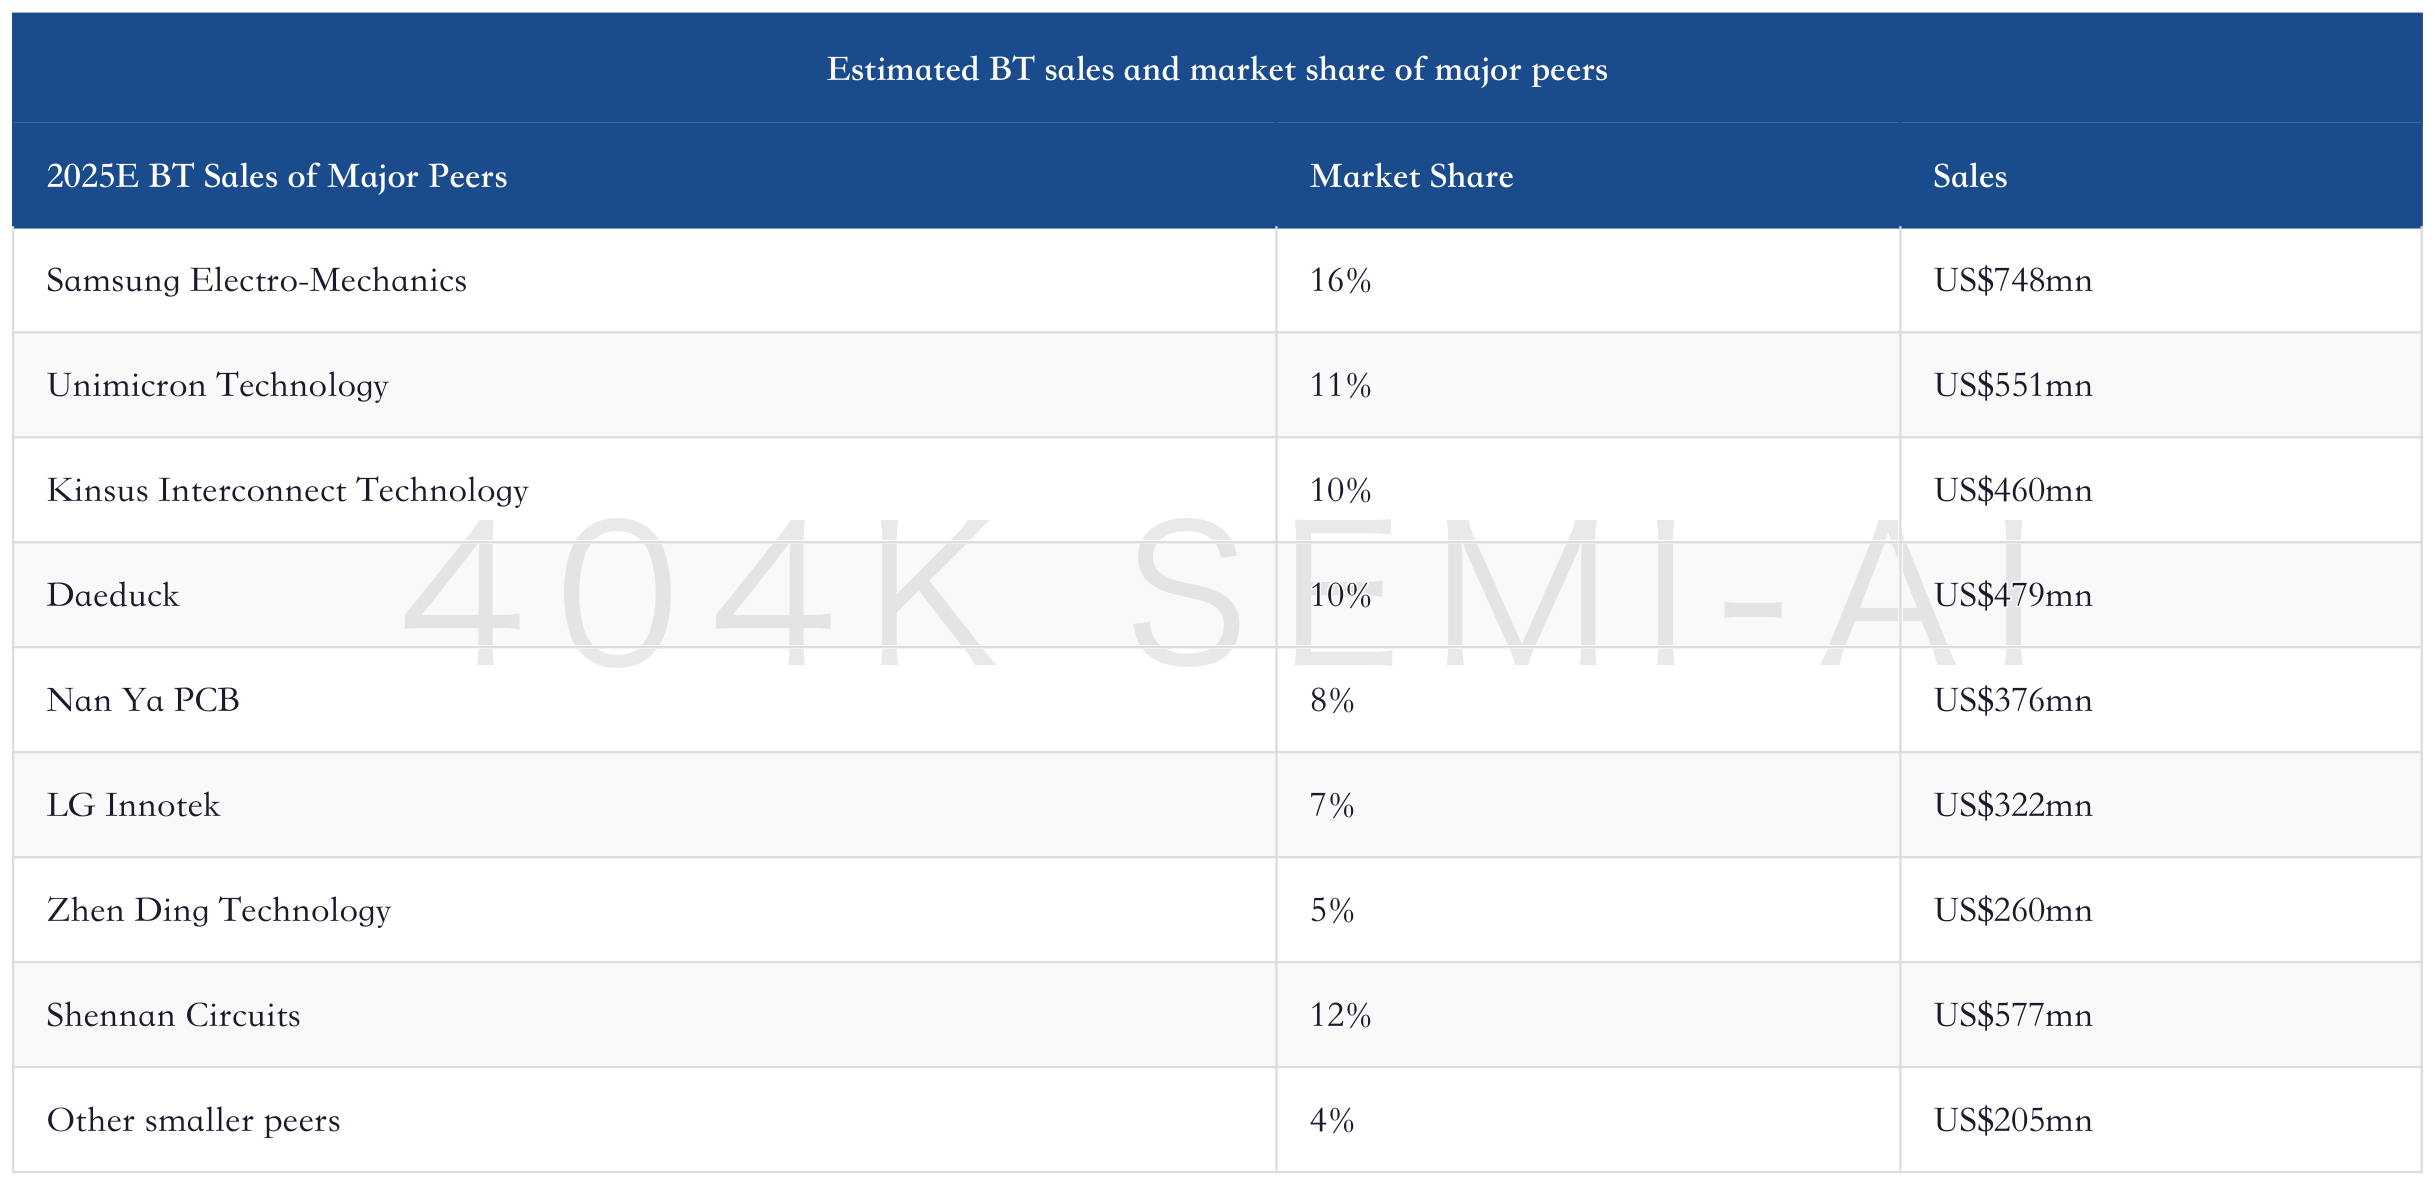
This table shows that BT is not too small to ignore. For Kinsus, BT already accounts for 35-40% of sales. For Nan Ya PCB, BT can drive gross margin together with ABF spot prices. For Unimicron, cutting BT capacity is not an exit from the market, but a shift of lower-profit capacity toward ABF and higher-end projects.
The most important question in this round of substrate price hikes is "why do the price hikes remain with substrate makers?" Material price increases do not automatically mean margin expansion for substrate makers. If customers view price merely as cost pass-through, gross margin will not improve. Only when customers pay for delivery certainty, certification status, and high-yield capacity do price hikes become substrate-maker margin. The real importance of Citi's report is that it points ABF and BT supply-demand changes toward gross margin, not just revenue.
ABF pricing power comes from customers having insufficient alternatives. The substrates used in AI chips are not just an expansion in ordinary area; they require high layer count, large size, low warpage, and high yield at the same time. Customers can certify more suppliers, but each supplier must pass materials, process, reliability, packaging collaboration, and mass-production ramp. Nominal capacity can appear in financial reports or expansion announcements, but qualified capacity must be verified in customers' production schedule.
This is why T-glass is more like the master gate than an ordinary material. A shortage of ordinary materials affects cost; a T-glass shortage affects effective capacity and yield. If substrate makers cannot secure qualified materials, even more expansion equipment cannot become usable capacity. If customers recognize only a few material systems, alternative suppliers will also struggle to ramp immediately. Substrate makers can therefore turn "I have qualified capacity" into bargaining leverage.
BT's logic is more like supply-side clearing. It is not as glamorous as ABF, but once leaders shift low-profit capacity to ABF, the remaining BT orders must look for new suppliers. This process will not finish overnight because customers still need to evaluate product type and certification. But as long as exiting suppliers are unwilling to protect volume at low prices, receiving suppliers can repair gross margin through higher utilization and a better product mix.
When ABF and BT improve at the same time, P&L; elasticity is greater than price hikes on a single line. ABF provides market imagination and valuation multiple. BT provides utilization and expense absorption. ABF price increases make customers acknowledge that substrates are the bottleneck. BT order spillover lifts line utilization. The near-term elasticity of Kinsus and Nan Ya PCB comes exactly from these two lines working at the same time.
That said, there is also an easily overlooked reflexivity here. The faster prices rise, the more customers will push second-source suppliers, regional alternatives, and material substitutions. The more the industry believes the shortage will persist, the more active capacity expansion and certification will become. The substrate makers' window is not unlimited. It is more like a period of margin repricing. The companies that can lift monthly earnings and quarterly gross margin during this window are the real beneficiaries of the cycle.
3. Nan Ya PCB: The Most Direct Price Elasticity, Watch Broadcom and Switch Chips First
Nan Ya PCB is one of Citi's preferred near-term names for a straightforward reason: it looks more like a spot-pricing elasticity play. The company is less willing to sign long-term agreements with customers, has higher spot-market exposure, and ABF and BT price increases can enter the P&L; faster.
Nan Ya PCB's ABF main line is Broadcom Tomahawk-related products. In addition to switch ICs, the company also supplies selected ASIC projects, although its share is not large. Citi's view is that Nan Ya PCB will adopt a more aggressive pricing strategy for both ABF and BT over the next few quarters, with price hikes and utilization improvement driving gross margin upward.
This company is useful for answering one question: can ABF tightness on the AI networking and ASIC side enter the income statement faster than the GPU main line? GPU substrates have long-term agreements, large customers, and strict certification. Switch chips and selected ASIC projects are also complex, but if the company retains more spot-price exposure, price transmission can be faster.
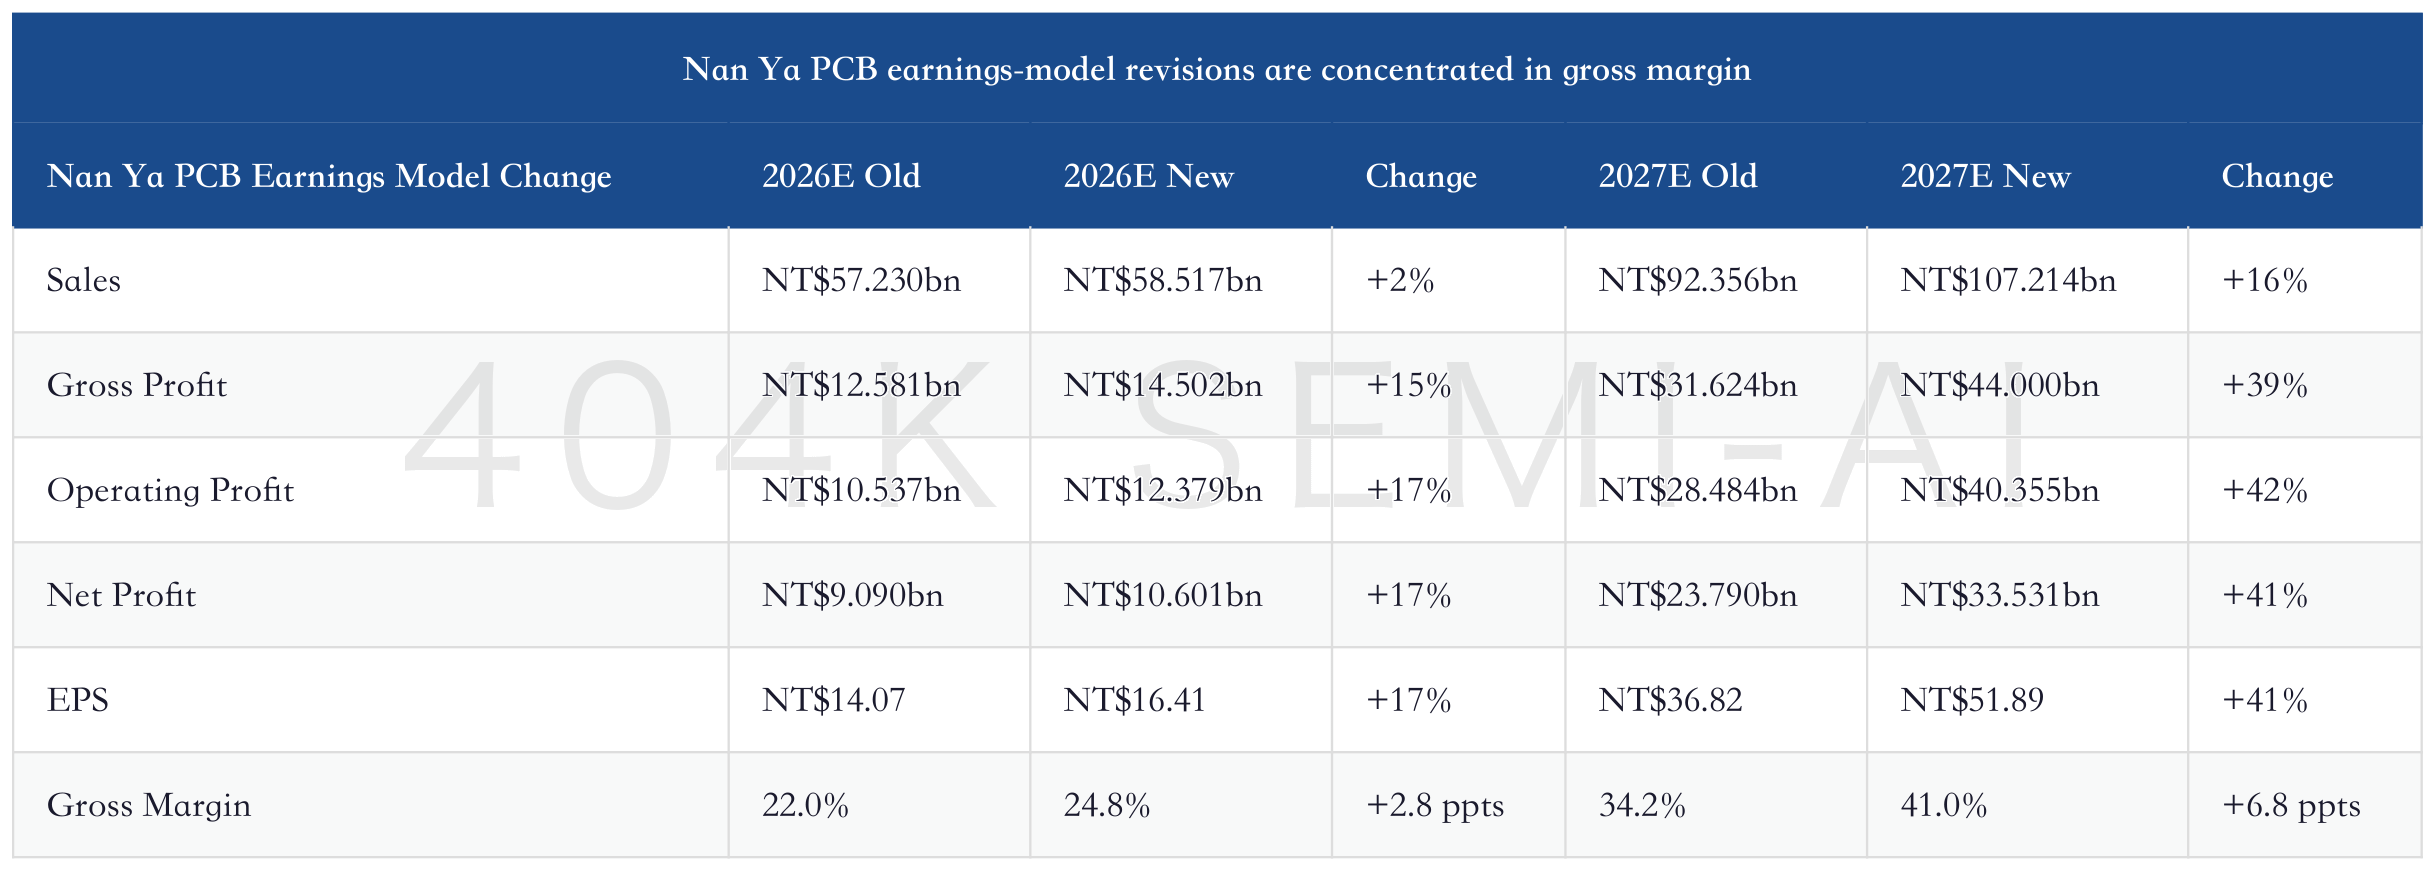
The most important line is the 2027E gross margin revision from 34.2% to 41.0%. Nan Ya PCB is not relying only on revenue upgrades; its profit elasticity mainly comes from gross margin. Citi expects 2027E net profit to rise to NT$33.531bn, and the model already embeds an aggressive ABF/BT pricing strategy.
The near-term catalyst is also clear. Citi added a 30-day upside Catalyst Watch on Nan Ya PCB, arguing that if upcoming monthly unaudited earnings are disclosed, gross margin could be at least 3 ppts above consensus of around 19%. This catalyst is not a macro narrative; it lands directly in unaudited monthly earnings and gross margin.
Nan Ya PCB's risk is also the most direct. High spot-price exposure gives it the fastest elasticity when prices rise; it also gives it the fastest drawdown when prices loosen. If 3Q26 and 4Q26 ABF price hikes disappoint, or BT order spillover is slower than expected, Nan Ya PCB can quickly be repriced from "fastest realization" to "fastest to be hurt."
4. Kinsus: Vera CPU and BT Spillover Stack Together; Elasticity Comes from Dual-Line Utilization
Kinsus has the most dramatic target-price change in Citi's report: from NT$400 to NT$1,100. This cannot be explained only by "ABF price hikes." The real logic is that both ABF and BT are strengthening at the same time.
On ABF, Kinsus's key is Vera CPU. Citi believes Kinsus is positive on its own Vera CPU share and that this is consistent with the view of a share above 50%. How much Kinsus can capture depends on its pace of capacity expansion. After the importance of AI CPUs rises, Kinsus is no longer just a second-tier catch-up name, but a direct beneficiary of CPU substrates.
On BT, Kinsus benefits from order spillover after Unimicron cuts BT capacity. Citi expects both Kinsus ABF and BT utilization to reach full loading by end-2026. More importantly, BT gross margin in this cycle may exceed 20%, above the historical 5-15% range. For a company with BT accounting for 35-40% of sales, this change is enough to rewrite the income statement.
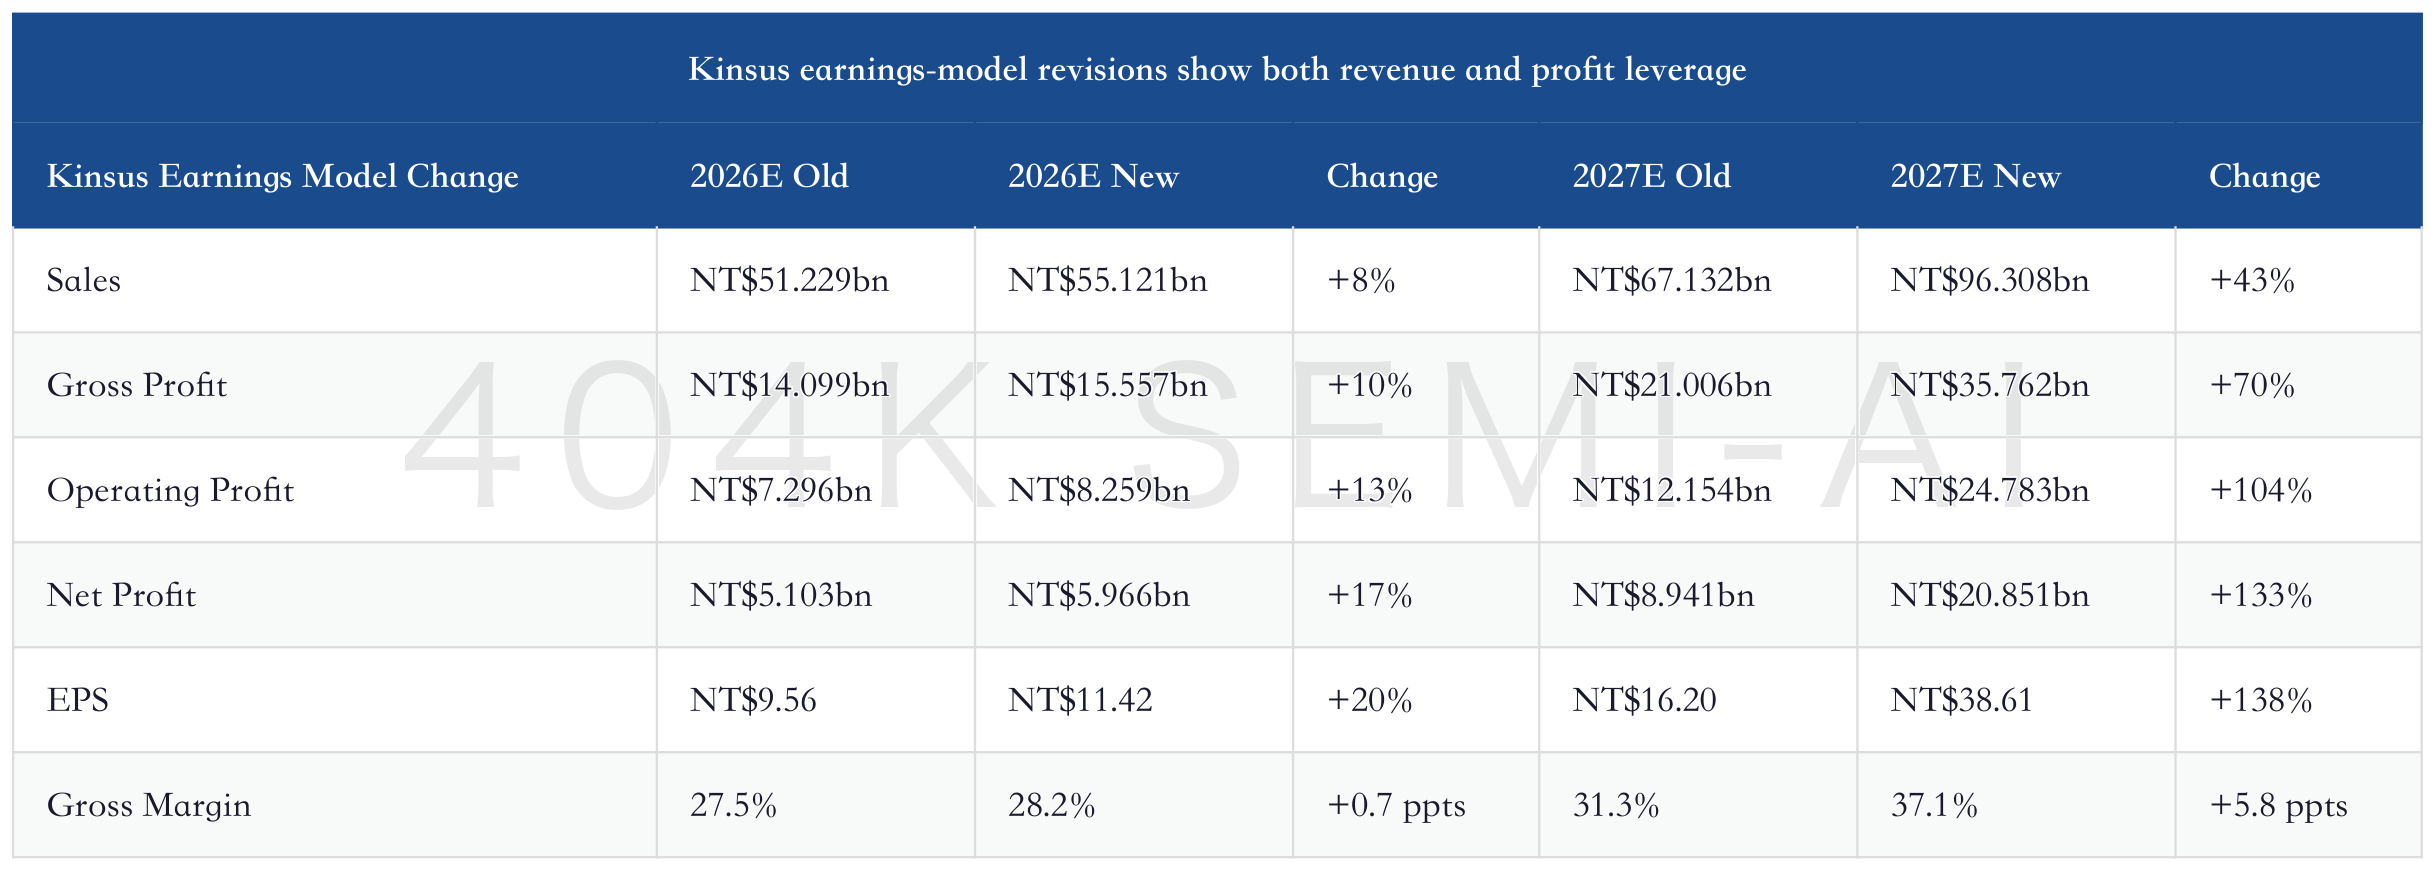
The key in this data set is operating leverage. 2027E sales are revised up 43%, gross profit 70%, operating profit 104%, and net profit 133%. In other words, Citi is not only assuming Kinsus sells more, but that its product mix, BT gross margin, ABF utilization, and expense ratio all improve together.
Kinsus's advantage is "two cycles stacked together": AI CPU pulls ABF, while memory and peer contraction pull BT. Looking only at ABF, it is not a scale leader like Unimicron. Looking only at BT, it is not the market's hottest AI asset. But when Vera CPU, BT order spillover, the K6 capacity ramp, and gross-margin expansion stack together, Kinsus becomes the name most likely to see an earnings jump.
The Second Revaluation of the AI Server Materials Chain: From Passive Components to PCB/CCL, ABF Substrates, and Test Equipment
The near-term Catalyst Watch is also tied to monthly earnings. Citi believes that if Kinsus's upcoming monthly unaudited earnings are disclosed, gross margin could be at least 2 ppts above consensus of around 25%. Compared with Nan Ya PCB, Kinsus has a higher consensus gross-margin base, but its upside comes from dual-line utilization rather than a single spot price.
Kinsus's biggest risk is capacity and customer timing. If Vera CPU share is constrained by capacity expansion speed, the ABF uplift will be delayed. If BT spillover is slower than expected, near-term gross margin will be below Citi's optimistic assumptions. Kinsus's pricing in this round looks the steepest, which also means later monthly data have the lowest margin for error.
5. Unimicron: Stronger Scale and Resource Advantages, but Less Near-Term Elasticity Than Nan Ya PCB and Kinsus
Unimicron is the company that cannot be ignored over the long term. Its advantage is not the fastest price hike, but scale, customers, T-glass resources, and leadership in high-end substrates. Citi also states clearly that it prefers Nan Ya PCB and Kinsus in the near term, but still likes Unimicron's leadership over the long term.
Unimicron's near-term tension is this: the market likes ABF spot-price exposure and earnings slope, but Unimicron has more long-term agreements, a broader integrated business, and a larger customer structure. It benefits from ABF upside, but it may not be the company with the largest near-term price-hike elasticity.
Citi's revisions for Unimicron mainly come from three points. First, gross-margin benefits from long-term agreements. Second, margin improvement after HDI mass production. Third, more sufficient T-glass supply, which gives the company more bargaining power than other ABF peers. Citi also notes that the current 2Q26 gross-margin uplift is likely driven mainly by ABF demand, not by HDI utilization improvement.
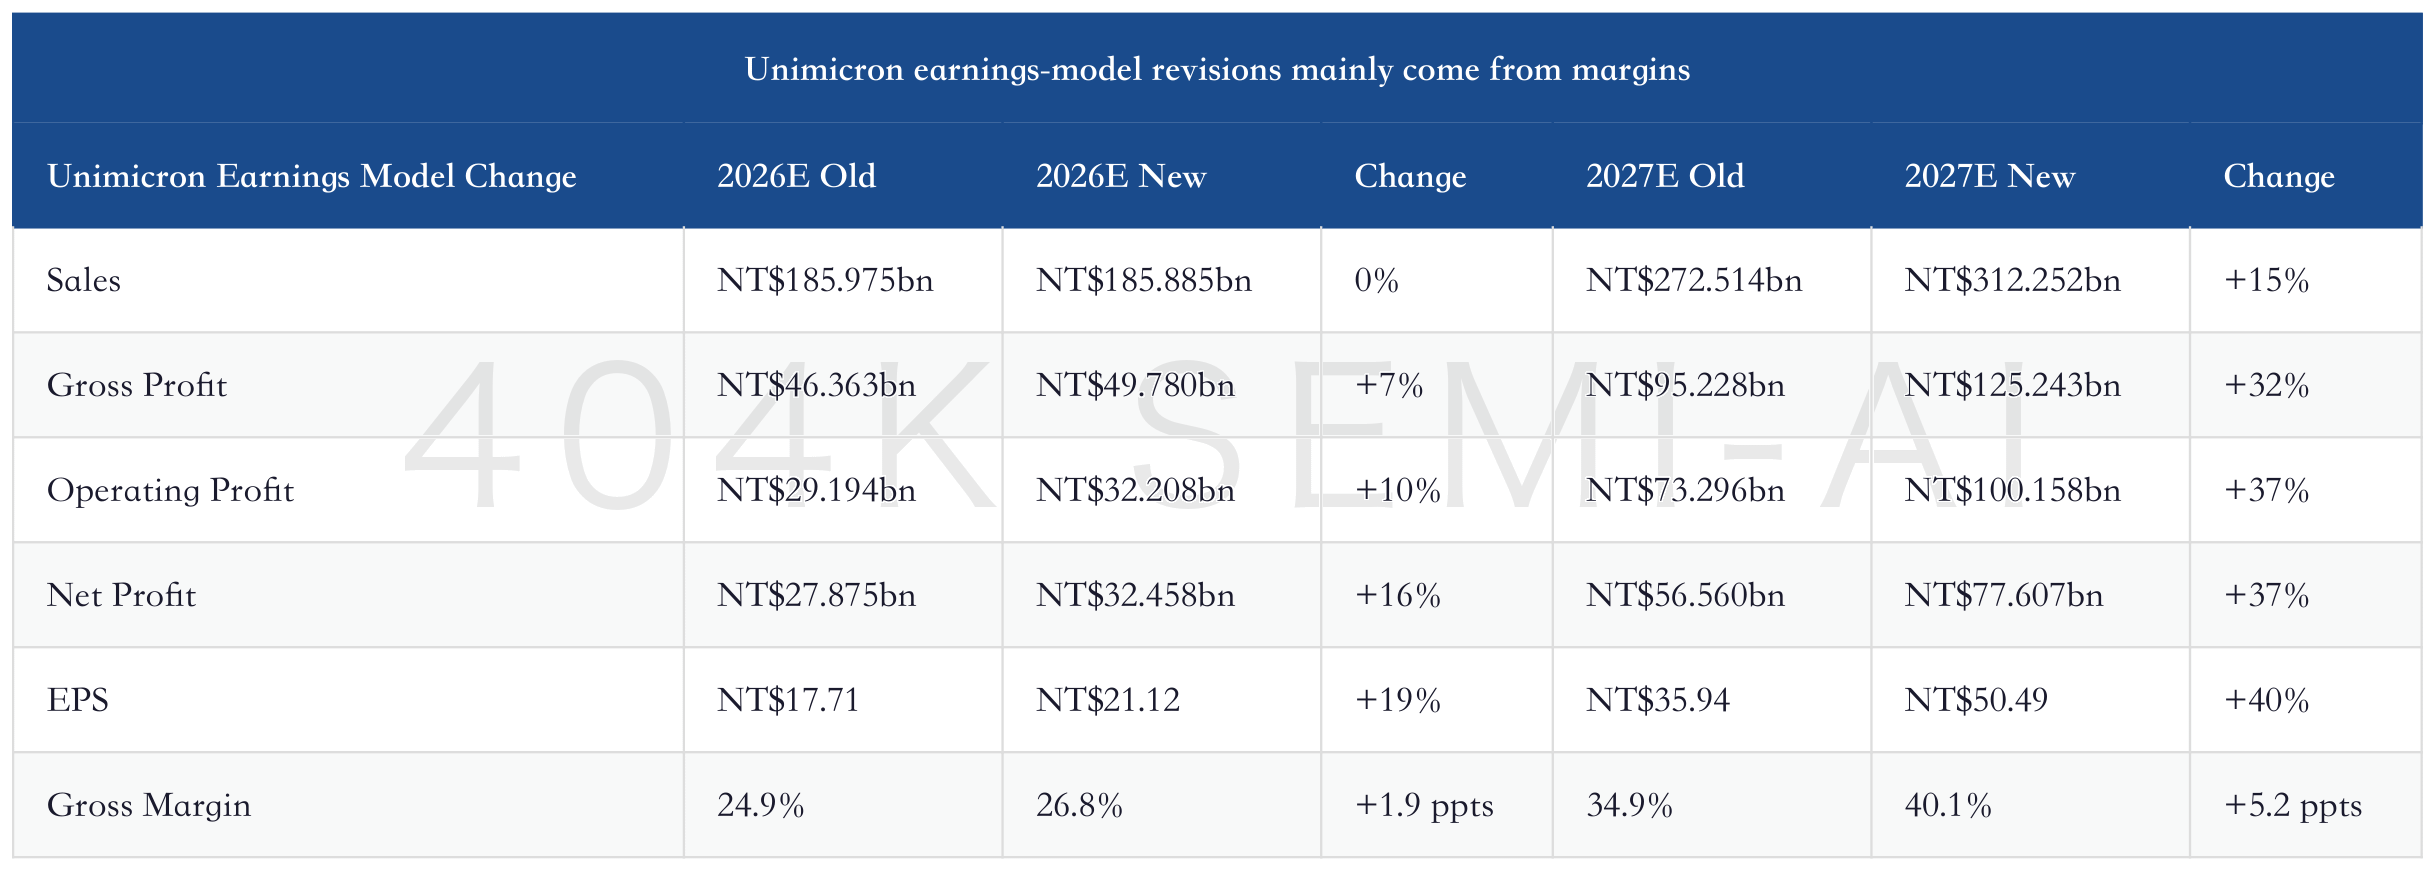
Unimicron's 2026E sales are almost unchanged, but gross margin and EPS are revised up meaningfully. This shows that the current model is not driven by volume, but by structure, price, and gross margin. By 2027, sales are revised up 15%, gross profit 32%, net profit 37%, and gross margin to 40.1%. If realized, Unimicron would move from ABF leader to a high-margin substrate platform.
Unimicron also has one move that looks negative but is actually helpful to industry supply: cutting BT capacity. It will not fully exit BT because Apple and some Chinese customers still have BT demand, and the Suzhou plant may be retained. But cutting low-margin or relatively low-visibility BT capacity and shifting resources to ABF is positive for its own mix, and will also allow Kinsus and Nan Ya PCB to receive BT order spillover.
This is also the profit-allocation relationship among Unimicron, Kinsus, and Nan Ya PCB. Unimicron commits more resources to high-end ABF, T-glass, long-term agreements, and HDI. Kinsus and Nan Ya PCB take part of the orders created by BT supply contraction. Nan Ya PCB then amplifies margin through higher spot-price exposure. The industry is not a case of three companies rising identically; it is a supply chain redistributing profit.
AI PCB and CCL Deep Dive: From GB300 to Rubin Ultra, Who Runs Short First in High-Layer Boards, M9 Materials, and E-glass Fabric
Unimicron's risk is valuation digestion. Citi's new NT$1,500 target price implies 30x 2027E EPS. This is not a cheap-asset multiple. It requires the company to prove ABF demand, T-glass resources, HDI improvement, and long-term-agreement gross margin all materialize at the same time. If 2027E gross margin cannot approach 40%, valuation will come under pressure before fundamentals.
6. The Three Companies Are Not the Same Trade; Ranking Should Be Layered by Price, Utilization, and Resources
This ABF/BT trade can easily be flattened. All three companies have higher target prices, all remain Buy, and all have ABF exposure, but their profit sources are completely different.
Nan Ya PCB benefits from price, especially spot price and switch-chip/ASIC projects. Its keyword is speed: fast price, fast gross margin, fast monthly-earnings response. Kinsus benefits from utilization, especially Vera CPU share and BT order spillover. Its keyword is leverage: after revenue is revised up, profit is revised up faster. Unimicron benefits from resources and scale, especially T-glass, long-term customers, ABF leadership, and HDI mass-production improvement. Its keyword is stability: less sharp in the near term, but the most important long-term supply position.
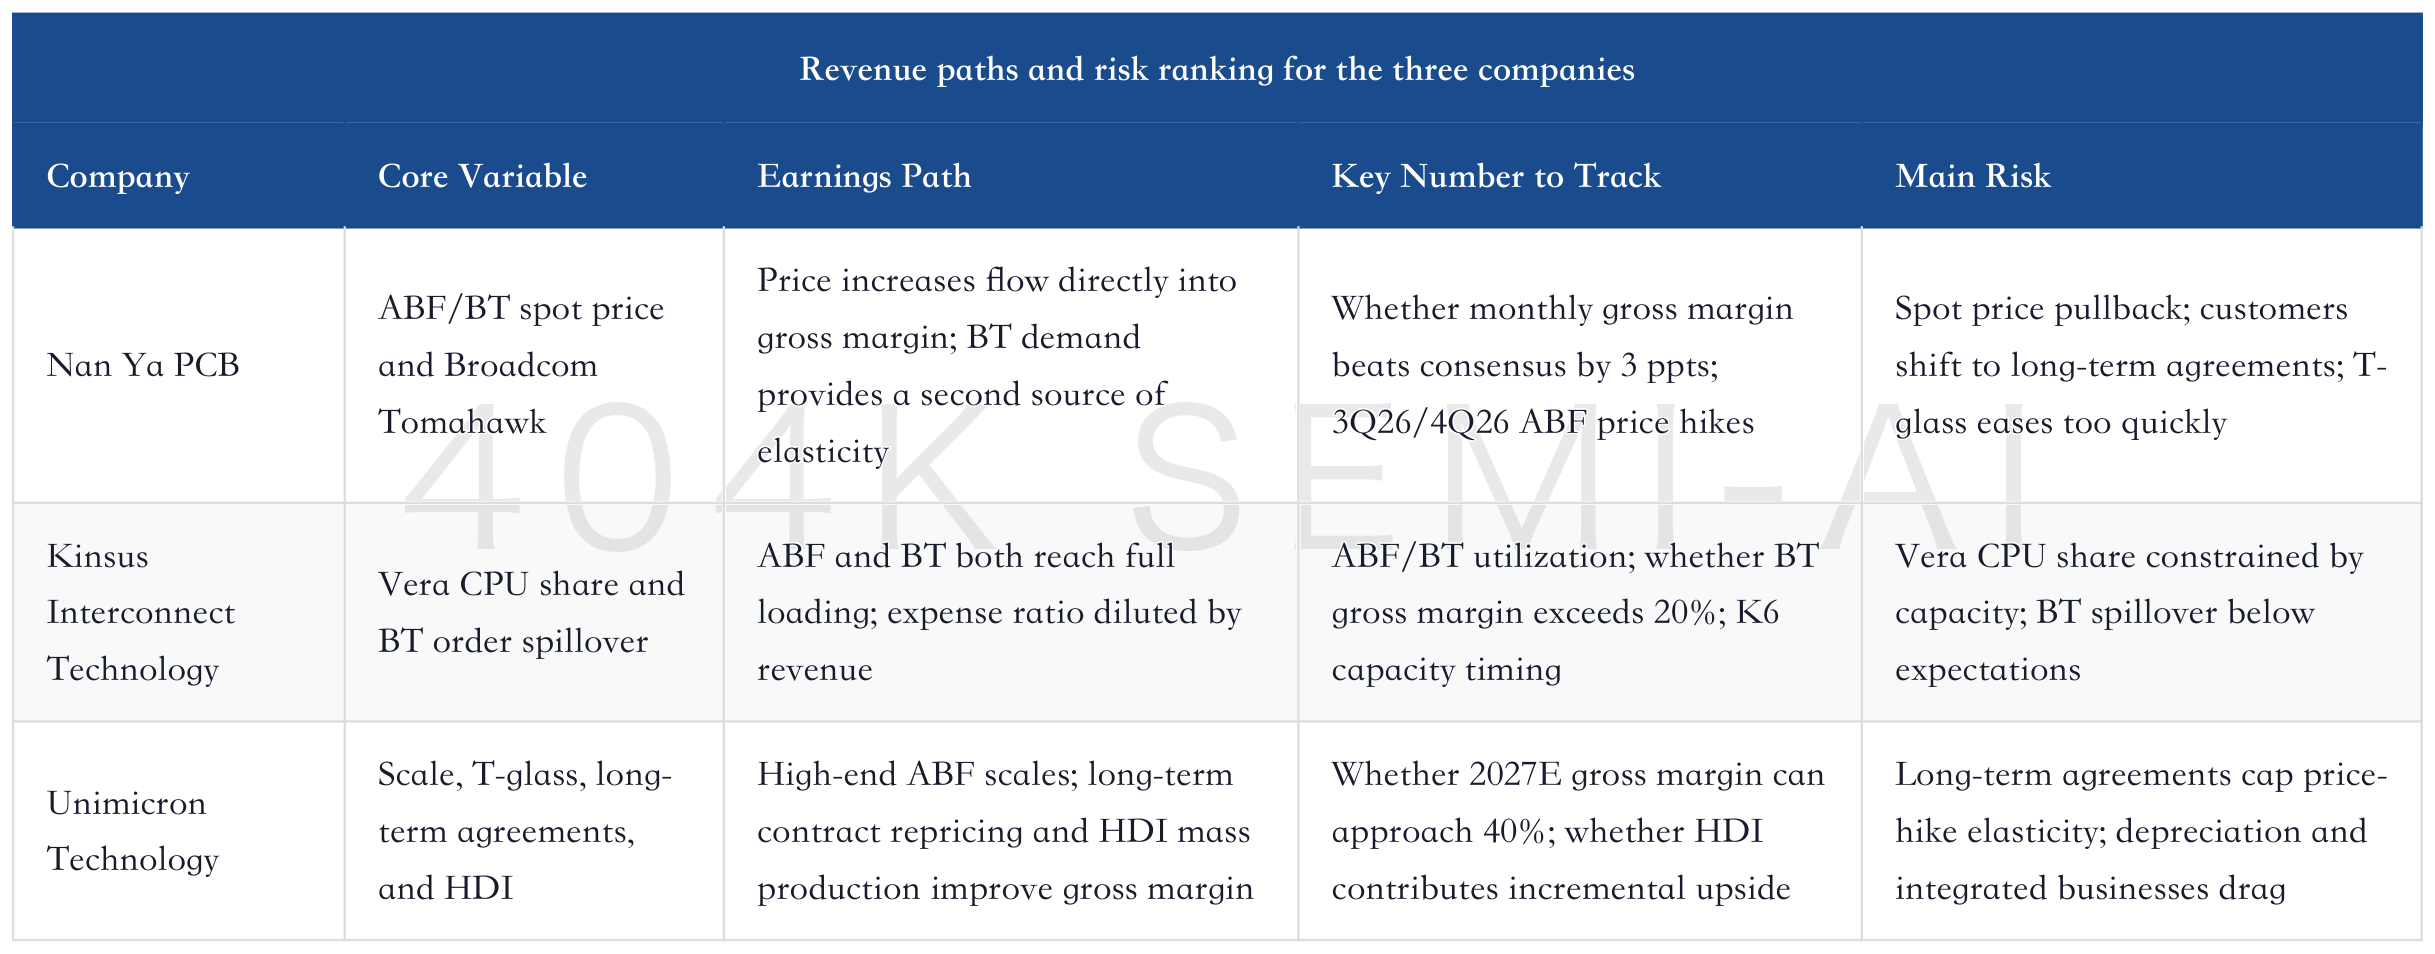
The ranking can be divided into three time dimensions: short, medium, and long term.
Over the next 30 days, Nan Ya PCB and Kinsus have more catalysts. Citi explicitly added 30-day upside Catalyst Watch for both companies, with the core trigger being possible upside in unaudited monthly earnings. Nan Ya PCB has a low consensus gross-margin base and strong spot-price elasticity, with an upside threshold of about 3 ppts. Kinsus has a higher consensus gross-margin base, but ABF/BT dual-line full loading, with an upside threshold of about 2 ppts.
Looking at 2H26, Kinsus and Nan Ya PCB need to prove price and utilization are not one-off. ABF price hikes in 3Q26 and 4Q26 need to land in line with Citi's expectations. BT cannot remain only verbal improvement; it needs to show up in utilization and gross margin. Nan Ya PCB's Broadcom/switch-chip demand and Kinsus's Vera CPU progress need to continue supporting revenue slope.
Looking into 2027-2028, Unimicron remains the scale anchor in high-end ABF. It is not the most exciting near-term elasticity story, but if AI GPU, ASIC, and CPU demand continues to expand, T-glass remains tight, and customers want to lock stable supply, Unimicron's resource and scale advantages will be repriced by the market again.
This ranking cannot be static. The difficulty with substrate stocks is that share prices often first trade on the shortest catalyst, then price in medium-term earnings revisions, and only then return to long-term competitiveness. The strongest near-term company is not necessarily the most stable long-term company, and the most stable long-term company may not deliver the largest earnings surprise in the next few quarters. Comparing the three on one single line can easily mislead.
The first scenario is "price realization." ABF price hikes land in succession, BT order spillover starts to show up in utilization, and monthly unaudited earnings are revised ahead of official quarterly reports. In this scenario, the market is most willing to buy Nan Ya PCB and Kinsus because their earnings slope is the fastest and easier to verify through monthly data. Unimicron also rises, but more as a function of high-end ABF strength and a higher valuation center.
The second scenario is "materials remain the chokepoint." T-glass remains tight, customer certification of alternative suppliers is slow, AI chip projects are not materially delayed, but the speed of spot-price hikes starts to slow. In this scenario, Unimicron's resource value resurfaces. It may not have the steepest earnings elasticity, but it looks more like the long-term supply platform customers are willing to lock in. Nan Ya PCB and Kinsus still have profit elasticity, but valuation will depend more on repeated earnings surprises.
The third scenario is "the shortage is disproved early." Customers start to find alternative supply, T-glass certification progresses faster than expected, or AI chip project schedules move out. In this scenario, all three companies suffer valuation pressure, but in different order: the company with the highest spot-price elasticity is hurt first, the company with the highest operating leverage sees profit revised down fastest, and the scale leader depends on whether long-term customer relationships can buffer the cycle.
Therefore, this report should not be read only as "who has the highest target price." A more useful reading is to ask what scenario the market is buying right now. If the market is buying 30-day earnings surprises, Nan Ya PCB and Kinsus matter more. If the market is buying high-end ABF supply position in 2027, Unimicron matters more. If the market starts worrying about 2028 supply release, all three companies must be rescored on gross margin and order quality.
Sell-side divergence is also here. Earlier Taiwanese substrate reports focused more on "is ABF short?" and "who has new capacity?" Their upgrades for Kinsus, Unimicron, and Nan Ya PCB mainly came from orders, customers, and utilization. Citi pushes the question to gross margin and pricing power this time, effectively moving the framework from a "capacity cycle" to a "margin cycle." This is a higher-order call, and also easier for data to disprove.
If subsequent data show only revenue upgrades without gross-margin upgrades, the industry is still in a capacity cycle. If revenue and gross margin rise together, pricing power is real. If gross margin rises but revenue does not persist, it is only a short-term price or mix improvement. What truly supports a high multiple is the second state, not any one single number.
7. Valuation Depends on Whether 30x Is Justified by Gross-Margin Revisions
Citi now applies a valuation framework near 30x 2027E EPS for all three companies. Nan Ya PCB and Unimicron use 30x 2027E EPS, while Kinsus uses 28x 2027E EPS. This is a high multiple, but during a phase of supply-demand tightness, price increases, and accelerating earnings, the market can accept high multiples, provided earnings revisions keep moving upward.
The issue is that high multiples cannot rely only on a shortage narrative. They need gross-margin data to support them.
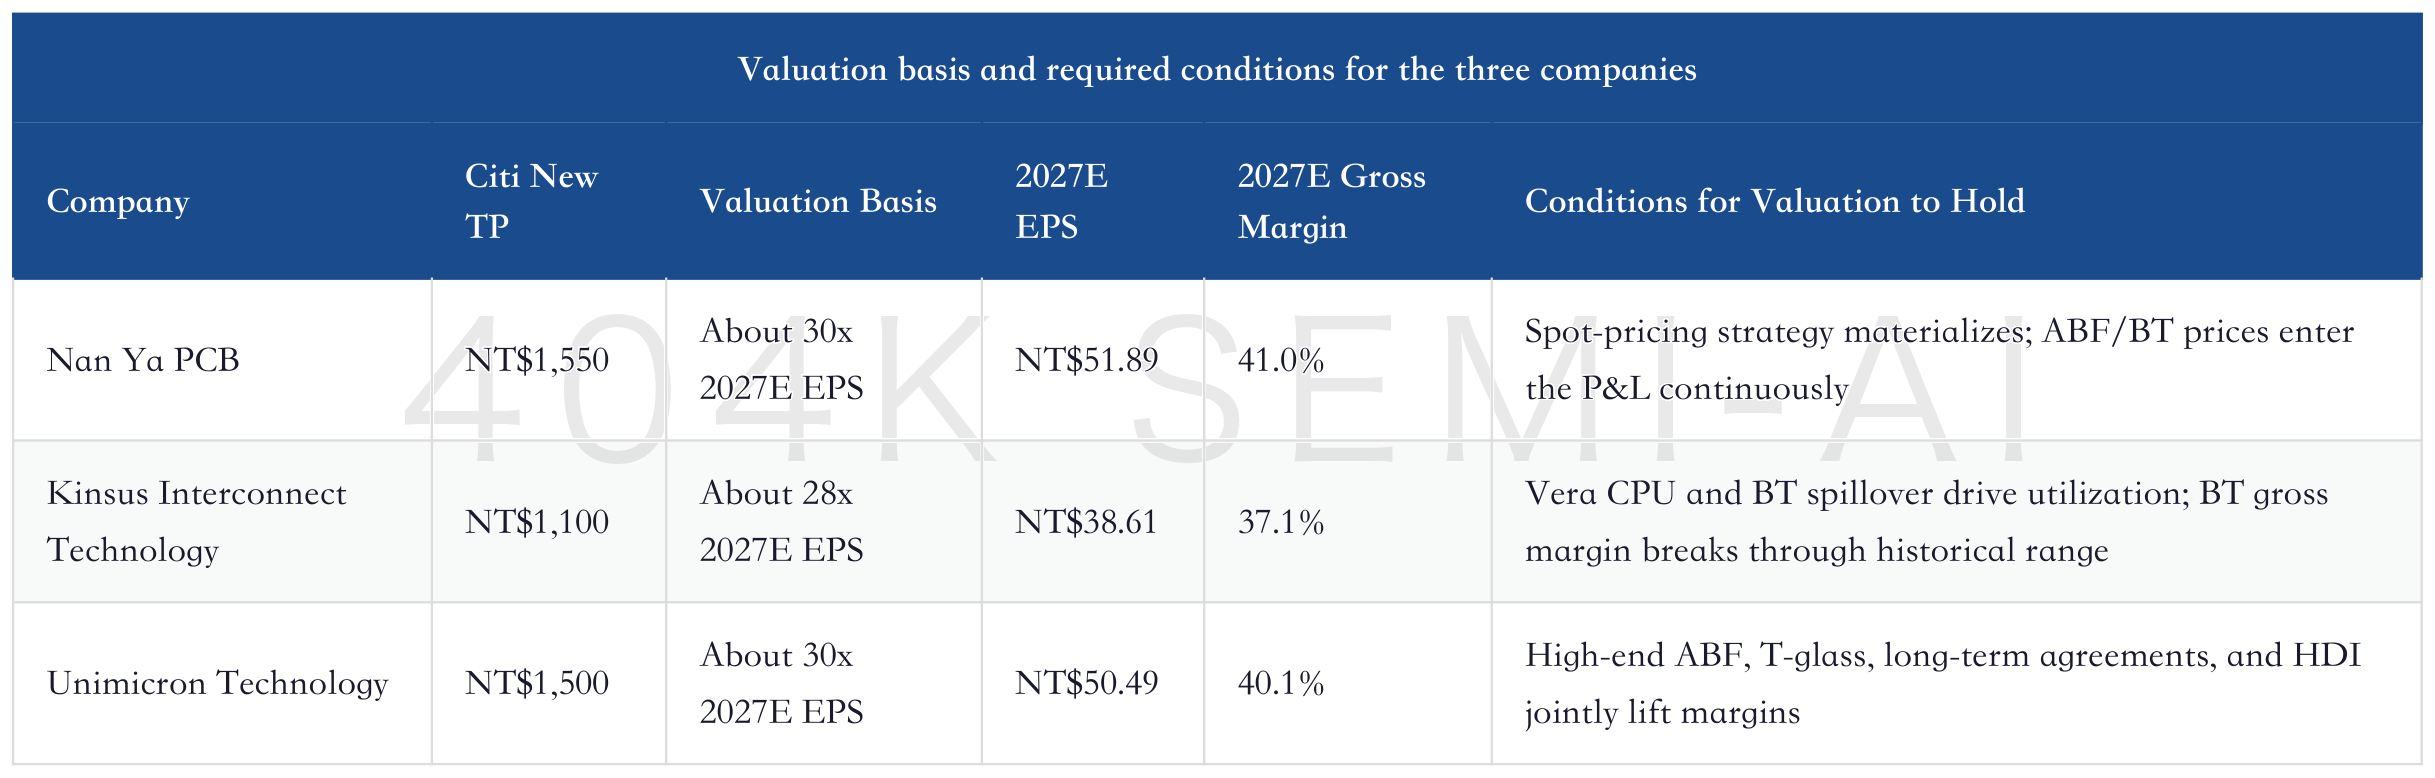
Putting the three companies on the same earnings bridge reveals the real rerating point: 2027E gross margins have all been pushed into the 37-41% range. The substrate industry has had cycles before, but if all three companies can reach gross margins near 40%, the market will reprice them from traditional electronic-component cyclicals into AI bottleneck-capacity assets.
Valuation fears two things most.
First, revenue rises but gross margin does not. That means the price hike is eaten by materials, depreciation, yield, or customer bargaining. For ABF, T-glass tightness can support price hikes, but it can also constrain shipments. For new capacity, ramp and depreciation can also consume profit. A high multiple fears "volume arrived, but profit did not."
Second, gross margin rises, but the market discovers it is only one quarter. Citi's model is a broad 2027 upgrade, not a single 2Q26 or 3Q26 surprise. If price increases slow after 3Q26, or customers renegotiate prices in 2027, a 30x valuation will be hard to defend.
This is why follow-up tracking must look at continuous data, not a single target price. Monthly unaudited earnings, quarterly gross margin, ABF price-hike cadence, BT utilization, T-glass lead time, and customer long-term agreements all need to validate each other continuously. If one link breaks, the share price will react first.
Target-price comparisons also need a consistent basis. The three companies are in the same Citi report, on the same report date, in the same currency, and on the same share-unit basis, so their "revision direction" and "model assumptions" can be compared. Even so, absolute target prices should not simply be ranked as degrees of optimism. Kinsus's new target price jumped the most because its old base was low and earnings-model elasticity was large. Nan Ya PCB's high target price reflects more direct price elasticity and near-term catalysts. Unimicron's target price is close to Nan Ya PCB's because scale and high-end ABF status support a long-term multiple.
What should really be compared is the quality of profit behind the target price. Nan Ya PCB's profit quality depends on whether spot price is sustainable. Kinsus's profit quality depends on whether utilization and BT gross margin improve together. Unimicron's profit quality depends on whether ABF, HDI, T-glass, and long-term agreements can form a combined advantage. All three can rise, but the market's trust comes from different sources.
Valuation multiples in cycles like this usually move in two stages. In the first stage, the supply-demand gap is confirmed and the market is willing to raise the multiple because bottleneck assets are scarce. In the second stage, profit is realized and the market starts to look at the pace of EPS revisions and the stability of gross margin. If the second stage cannot keep up, the multiple granted in the first stage is taken back. If the second stage keeps beating expectations, the multiple can stay high and even allow the next round of earnings upgrades to push the share price higher.
Citi's framework of around 30x 2027E EPS implies that "2027 is still in a margin-expansion cycle." That is more aggressive than looking at 2026E, because 2026 can only prove that price hikes have started, while 2027 proves whether price hikes, utilization, material constraints, and customer mix can annualize. What investors are really buying is the 2027 income statement, not one month of price increases today.
But 2027E also has a natural weakness: the further the year, the higher the requirement for cycle durability. As soon as the market starts to believe 2028 supply will be released in a cluster, or customers can shift more projects to new suppliers, the high multiple on 2027E will be discounted in advance. Substrate stocks usually do not wait for earnings downgrades before falling; they often fall when "can next year have the same slope?" becomes doubtful.
So valuation judgment needs to ask two questions at the same time. The first is whether earnings keep being revised up, which determines whether target prices can rise further. The second is whether the multiple has a reason to hold, which determines whether the share price can fully capture the revision. Looking only at EPS will underestimate valuation elasticity for bottleneck assets; looking only at the multiple will ignore the speed of downward revisions when the cycle turns.
This is also the core of the style differences among the three companies. Nan Ya PCB is more of a price trade, suited to validation through monthly earnings and gross margin. Kinsus is more of an operating-leverage trade, suited to validation through revenue slope, BT gross margin, and expense-ratio dilution. Unimicron is more of a supply-platform trade, suited to validation through high-end ABF resources, customer lock-in, and long-term agreements. Different styles imply different holding patience and different stop-loss signals.
8. Follow-Up Verification Checklist: Four Hard Indicators Determine How Far This Cycle Can Go
First, watch monthly unaudited earnings. Citi added 30-day upside Catalyst Watch for both Nan Ya PCB and Kinsus, with the trigger being upside in monthly unaudited earnings and gross margin. For Nan Ya PCB, watch whether gross margin is 3 ppts above consensus of around 19%. For Kinsus, watch whether gross margin is 2 ppts above consensus of around 25%. This is the shortest and fastest-reacting indicator.
Second, watch the cadence of ABF price hikes. 3Q26 prices up 15-20% QoQ and 4Q26 prices up 10-15% QoQ are important assumptions in Citi's model. If actual increases are below this range, the near-term elasticity of Nan Ya PCB and Kinsus will be hurt first. If the increases land or are even stronger, Unimicron's 2027E long-term-agreement repricing will also have more support.
Third, watch whether BT supply-demand really improves. Unimicron's BT capacity cuts are the supply-side starting point, but spillover to Kinsus and Nan Ya PCB needs data validation. Focus on BT utilization, BT gross margin, memory demand, and WBCSP/BT product mix. If BT gross margin can rise from the historical 5-15% range to above 20%, Kinsus's earnings leverage will be very clear.
Fourth, watch T-glass certification and alternatives. T-glass is the master gate for the ABF price cycle. If Taiwan Glass, Nan Ya Plastics, or other new suppliers see clear certification acceleration, the price cycle will be compressed earlier. If Nittobo and other core suppliers remain tight, substrate makers' bargaining power with customers will hold. Here, one cannot look only at capacity announcements; customer certification, mass-production yield, and real lead times matter.
Fifth, watch AI chip project timing. Nan Ya PCB's Broadcom Tomahawk and switch chips, Kinsus's Vera CPU, and Unimicron's AI GPU/ASIC and HDI projects all need to be tied to specific project mass-production schedules. If AI chip development is delayed, substrate prices can hold in the short term, but earnings revisions will lack persistence.
Sixth, watch valuation divergence. Citi's roughly 30x 2027E valuation is a multiple for a "gross-margin expansion cycle." If the market later shifts to 2028E or longer-term EPS, Unimicron will be more advantaged. If the market focuses only on 30-90 day earnings surprises, Nan Ya PCB and Kinsus will be more advantaged. Rankings change when the time dimension changes.
These indicators are best tracked in four layers. The first layer is the fastest monthly data: revenue, unaudited earnings, gross-margin basis, and company order language. The near-term catalysts for Nan Ya PCB and Kinsus are all here. If monthly data cannot prove price hikes and utilization, the market will not wait for official quarterly reports.
The second layer is the quarterly income statement. Monthly data can be affected by product mix, shipment timing, and one-off projects. Quarterly gross margin is better at showing whether price and cost have truly entered the income statement. It is especially important to see whether gross-margin improvement comes with revenue growth, rather than short-term mix improvement caused by fewer low-margin orders.
The third layer is capacity and materials. ABF capacity, BT capacity, T-glass supply, yield, and customer certification cadence determine how long price hikes can last. Here, one cannot look only at company expansion plans; one must also see whether customers actually put new suppliers into mass production. For AI chip customers, there is still a distance between certification approval and large-scale shipments.
The fourth layer is customer projects. Nan Ya PCB needs Broadcom Tomahawk and switch-chip demand. Kinsus needs Vera CPU and BT spillover. Unimicron needs high-end ABF, HDI, and long-term customer agreements. If customer project timing is unchanged, material tightness supports pricing. If customer projects are delayed, material tightness can only slow downward revisions; it cannot create demand.
Verification should also avoid looking at only one winner. Profit allocation in the substrate chain is interconnected: Unimicron's BT capacity cuts benefit Kinsus and Nan Ya PCB; tight T-glass supports all high-end ABF makers; spot-price increases let Nan Ya PCB show elasticity first; long-term contract repricing benefits scale platforms such as Unimicron more. Single-company data need to be read together with peer data.
A practical tracking method is to treat monthly earnings as the signal, quarterly gross margin as confirmation, material lead times as cycle length, and customer projects as the demand base. If all four indicators move upward together, there is still room for target-price upgrades. If only monthly earnings move up, it may be just short-term shipments. If only materials are tight but customer projects are lacking, price is unlikely to hold for long. If customer demand is strong but materials and capacity ease, margin upgrades will be eaten by customer renegotiation.
This framework also explains why Citi prefers Nan Ya PCB and Kinsus in the near term. They are the first to be verified by monthly data, and also the easiest to be rejected by monthly data. Unimicron's verification is slower, but if quarterly gross margin and long-term contract repricing begin to confirm, its advantage will move from "leader valuation" to "platform margin," and the market will give it longer patience again.
9. Risks: When the Cycle Is Strengthening, the Biggest Risk Is Insufficient Realization Speed
ABF and BT substrates are not risk-free. The most dangerous risk today is not that demand disappears completely, but that fundamentals remain good while share prices have already priced in 2027 profits. Once realization speed falls short of expectations, high valuation will compress first.
The first risk is that T-glass constraints ease faster than expected. If new supplier certification accelerates, customers have more options and substrate makers' ability to raise prices repeatedly will decline. Material shortages support prices, but they also amplify material suppliers' bargaining power. When the material bottleneck eases, industry pricing power will shift back toward customers and large customers.
The second risk is customer resistance to repeated price hikes. Citi assumes ABF prices continue to rise in 3Q26 and 4Q26, but customers will compare long-term agreements, spot prices, alternative suppliers, and capacity in different regions. The faster prices rise, the stronger customers' incentive to seek alternatives.
The third risk is a mismatch between capacity expansion and utilization. Nominal expansion is not effective capacity, but once effective capacity is released in a concentrated window, prices will be reassessed. Kinsus's Vera CPU share, Unimicron's high-end ABF capacity, and Nan Ya PCB's switch-chip projects all require yield and certification to qualify at the same time.
The fourth risk is that BT spillover is overestimated. Unimicron's BT capacity cuts release orders, but whether those orders can all turn into high-margin business for Kinsus and Nan Ya PCB still depends on customer mix, product type, and memory demand. If BT gross margin cannot break 20%, Kinsus's profit elasticity will be revised down meaningfully.
The fifth risk is valuation multiple contraction. 30x 2027E EPS can be supported by high gross margin, high growth, and supply-demand tightness. But if the market starts to worry about supply expansion after 2028, or if the AI hardware chain as a whole becomes crowded, valuation will fall before earnings are revised down.
These risks are not independent. Material easing first affects price. Price loosening affects gross margin. Gross margin falling short affects EPS. Once upgrades stop, the valuation multiple is lowered. Substrate stocks usually do not fall because one project suddenly disappears, but because one link in the chain between price, utilization, and gross margin breaks.
Nan Ya PCB is most afraid of the price chain breaking. Its advantage is spot-price elasticity, and its weakness is also spot-price elasticity. If customers start moving more orders into long-term agreements, or use second-source suppliers to pressure prices, Nan Ya PCB's upgrade speed will slow first. It is not that the company lacks long-term customers; rather, the current premium in the trade comes from "price hikes quickly entering the income statement," and that premium needs continuous proof from monthly data.
Kinsus is most afraid of the utilization chain breaking. Its elasticity comes from ABF and BT being fully loaded at the same time. If the Vera CPU project ramps slowly, or BT spillover orders are below expectations, revenue upgrades will undershoot Citi's model. Once revenue slope is insufficient, expense-ratio dilution and gross-margin improvement will both weaken. The risk for Kinsus is not that the story is invalid, but that simultaneous realization on both lines is difficult.
Unimicron is most afraid of the timing chain breaking. Its long-term logic is more stable, but the market's current valuation already embeds 2027 gross-margin expansion. If HDI mass production, long-term-agreement gross margin, T-glass resources, and high-end ABF demand do not gradually provide evidence over the next few quarters, investors will view it as "good long term," not "upgrading immediately." Long-term quality and near-term upgrades deserve different prices in valuation.
There is also an industry-level risk that customers reallocate profit. AI chip customers are willing to pay for bottleneck links, but they will not hand over margin indefinitely. Once customers see more qualified supply, or believe price increases exceed delivery value, they will renegotiate. Substrate makers currently have bargaining power because customers fear missing qualified capacity. Once that fear declines, some bargaining power returns to customers.
Therefore, the most rational risk management is not to simply turn bearish on ABF/BT, but to keep asking three questions: have price hikes entered gross margin, has gross margin entered EPS, and are EPS upgrades sufficient to support high multiples? As long as all three answers are "yes," the rally can continue. Once any answer becomes "uncertain," reliance on target-price upgrades should be reduced.
10. Investment View: Separate the Three Companies by Capital Type and Realization Window
The easiest mistake in this ABF/BT substrate trade is to treat the three companies as the same beta. They are all in the AI substrate chain, all have Citi target-price upgrades, and all benefit from ABF tightness, but the capital behind their share prices is not the same. Nan Ya PCB is more like price-elasticity capital, Kinsus more like earnings-jump capital, and Unimicron more like long-term supply-platform capital.
Price-elasticity capital looks for "fast." Nan Ya PCB is best suited to this capital because it has higher spot-price exposure, and Broadcom Tomahawk, switch chips, and selected ASIC projects can transmit price hikes into gross margin more easily. For this capital, the most important question is not whether the company is the strongest long-term player, but whether the next monthly data can prove that price hikes have entered the P&L.;
Earnings-jump capital looks for "steep." Kinsus is best suited to this capital because its story is not a single price hike, but simultaneous improvement in ABF and BT utilization. Vera CPU share, BT order spillover, K6 capacity ramp, and expense-ratio dilution: if several of these materialize at the same time, profit upgrades will be steeper than revenue upgrades. Its appeal comes from operating leverage, and so does its risk.
Long-term platform capital looks for "stable, with resources." Unimicron is best suited to this capital because its advantage is not fully reflected in near-term price hikes, but in high-end ABF scale, customer relationships, T-glass resources, long-term agreements, and HDI mass production. It may not be the most exciting in monthly unaudited earnings, but if the 2027 gross-margin rerating holds, the market will give a high-end supply platform longer valuation patience again.
The near-term ranking is therefore quite clear. Looking only at the next few data windows, Nan Ya PCB and Kinsus are sharper than Unimicron. Nan Ya PCB's catalyst is closer to price; Kinsus's catalyst is closer to utilization and BT gross margin. Both are easy to verify through monthly earnings, and both are easy to reject through monthly earnings. Short-term trading must accept this high sensitivity.
The medium-term ranking depends on the persistence of earnings revisions. If ABF price hikes continue into the second half and BT utilization also keeps improving, Kinsus's earnings elasticity may exceed Nan Ya PCB's because its model improves revenue, gross margin, and expense ratio together. If ABF prices are strong but BT spillover is insufficient, Nan Ya PCB will be more stable. If price increases slow but high-end customers still lock supply, Unimicron will regain advantage.
The long-term ranking ultimately returns to resources and customers. AI chip iteration is not a one- or two-quarter question. Customers will balance qualified supply, reliability, yield, and long-term cooperation. A platform company such as Unimicron has more long-term defensiveness, but it must prove that its long-term advantage is not simply "large scale means safety," but that long-term agreements, T-glass, and high-end ABF together can maintain margins at a higher level.
This creates an executable portfolio framework. If the capital objective is to capture monthly earnings surprises, weights in Nan Ya PCB and Kinsus should be higher. If the objective is to capture the long-term supply premium in the AI substrate chain, Unimicron cannot be absent. If one is worried about supply easing and valuation compression, all three companies need to be managed with shorter verification cycles rather than relying on the industry's long-term opportunity to withstand short-term profit disproval.
It is also important to distinguish between "benefiting from price hikes" and "retaining price hikes." Benefiting from price hikes only means the company can raise prices; retaining price hikes means it can turn those price hikes into gross margin. Nan Ya PCB's retention depends on spot price and customer acceptance. Kinsus's retention depends on product mix and utilization. Unimicron's retention depends on long-term contract repricing and high-end projects. If retention capability differs, the same ABF price hike becomes completely different profit elasticity.
For investors, the last thing to do is rank only by target-price increase. Kinsus has the largest target-price increase, but that does not mean the lowest risk. Unimicron has weaker near-term elasticity, but that does not mean low long-term value. Nan Ya PCB has high spot-price exposure, but that does not necessarily make it more suitable for long-term holding. Target prices provide Citi's joint assumptions on earnings and multiple. The real decision must return to how each company realizes those assumptions.
Within the broader AI hardware chain, ABF/BT substrates are distinctive because they rely on both demand and certification. Demand from servers, switch chips, ASICs, and AI CPUs provides the opportunity. Materials, yield, customer certification, and mass-production experience constrain supply. The demand side makes the market willing to buy growth; the supply side makes the market willing to pay a multiple. Only when both sides hold can substrate stocks move from a cyclical trade to a margin rerating.
But this position also brings higher requirements. Many links in the compute chain can talk about AI growth. Substrate makers must prove they are not ordinary electronics manufacturers, but bottleneck capacity. The evidence of bottleneck capacity is not many orders, but customers' willingness to pay higher prices for qualified capacity; not revenue growth, but gross-margin expansion; not a single-quarter surprise, but sustained earnings-forecast upgrades.
Therefore, the investment conclusion can be compressed into one sentence: buy monthly gross margin in the short term, buy dual-line ABF/BT realization in the medium term, and buy high-end supply platforms in the long term. Nan Ya PCB, Kinsus, and Unimicron correspond to these three layers respectively, but no single company can stand without verification. If verification is continuous, all three still have room for upgrades. If verification breaks, target prices lose support first.
This view also provides exit signals. If Nan Ya PCB's monthly gross margin no longer keeps beating expectations, its price elasticity needs to be discounted again. If Kinsus's ABF and BT are not fully loaded at the same time, operating leverage will be revised down. If Unimicron's long-term agreements and HDI do not contribute gross margin, its platform premium will be questioned. Each company should be judged not by one aggregate demand indicator, but by its own most important realization variable.
From a portfolio perspective, the more reasonable approach is not to choose one permanent winner among the three, but to adjust rankings by data window. The monthly unaudited earnings window favors Nan Ya PCB and Kinsus. The quarterly gross-margin confirmation window re-compares all three. The 2027 supply-platform window then returns attention to Unimicron. The substrate theme remains unchanged, but capital should migrate with evidence.
When reading financial reports over the next few quarters, the same order should be used. The first step is revenue, not to confirm whether demand exists, but to see whether orders are keeping pace with price. If a substrate maker raises prices but shipments stagnate, the revenue line will reveal the problem first. If revenue and price both rise, customers are accepting the price increases and the supply-demand tension remains.
The second step is gross margin. Gross margin is the core verification point in this report because it determines who ultimately keeps the price increase. Material suppliers, depreciation, yield ramp, and customer bargaining can all consume price hikes. Only if gross margin continues to rise does it show that substrate makers have retained enough profit.
The third step is operating margin. Many electronics manufacturing upturns stop at gross-margin improvement, with expenses and depreciation eating most of the elasticity. For a company with larger operating leverage such as Kinsus, it is especially important to see whether operating margin improves faster than gross margin. If the expense ratio is diluted by revenue, the market will be more willing to price an earnings jump.
The fourth step is capex and capacity-expansion language. If substrate makers overexpand, it may strengthen customer confidence in the short term but lower price expectations ahead of time in the medium term. Expansion itself is not bad; what matters is which customer, which material system, and which yield target it corresponds to. Expansion without customer certification is only nominal capacity.
The fifth step is customer concentration and product mix. Nan Ya PCB's switch-chip and selected ASIC projects, Kinsus's Vera CPU, and Unimicron's high-end ABF and HDI will all affect gross-margin quality. The market should prefer projects with high complexity, high certification barriers, and high delivery requirements, rather than looking only at total shipment area.
The sixth step is management language on pricing. If companies start emphasizing "customer relationships," "long-term cooperation," and "cost sharing," it may mean price-hike speed is starting to slow. If companies continue emphasizing tight supply-demand, delivery priority, and product-mix improvement, bargaining power remains on the substrate makers' side. Language is not financial data, but it often reflects inflection points earlier than official numbers.
The seventh step is whether peer data validate each other. If Nan Ya PCB's gross margin is strong but Kinsus and Unimicron do not improve, it may be due to individual projects. If Kinsus's BT gross margin is strong but Unimicron does not continue capacity cuts, order spillover may be only phase-specific. If Unimicron's long-term agreements improve but material lead times ease, the long-term platform premium will also be reassessed.
The eighth step is whether customers are willing to sign longer-cycle supply arrangements. Long-term agreements do not necessarily weaken profit; the key is the supply-demand position when they are signed. If signed when substrate makers have strong bargaining power, they can lock in higher gross margin and shipment visibility. If signed when customers have strong bargaining power, they cap spot-price elasticity. Unimicron's long-term-agreement value must be understood in this context.
The ninth step is whether competitors are forced to make trade-offs. Unimicron's BT capacity cuts are essentially a shift of resources from lower-return products to higher-return products. If more manufacturers make similar trade-offs, BT supply will remain tight. If manufacturers only adjust temporarily and later return to low-price order grabbing, BT gross margin will struggle to hold.
The tenth step is whether market expectations are too full. Even if fundamentals keep improving, if the market has already bought all 2027 upgrades in one shot, there can still be a "good results, flat share price" outcome. High-multiple assets need repeated beats, not merely in-line performance. After substrate stocks enter a margin trade, expectation management will be more important than the industry narrative.
Using this financial-report reading framework, each of the three companies has its own most sensitive radar. Nan Ya PCB watches price and monthly gross margin. Kinsus watches utilization and operating margin. Unimicron watches long-term agreements, resources, and high-end projects. As long as the radars point to different things, one cannot apply the same valuation question to all three companies.
This also explains why this rally may continue but will not be linear. When industry supply-demand is still tight, share prices will still switch focus among monthly data, quarterly reports, customer projects, and material news. Investors need to follow the evidence rather than treat one target-price upgrade as a static answer.
Valuation repricing will also proceed in three steps. The first step is theme repricing, in which the market acknowledges that ABF and BT substrates are not ordinary components, but bottleneck links in the AI hardware chain. This stage mainly raises the multiple, and share prices react most strongly to supply-demand news and target-price upgrades.
The second step is earnings repricing, in which the market starts to require companies to turn bottleneck position into gross margin and EPS. This stage no longer rewards all companies in the same chain. Only companies that can show monthly earnings, quarterly gross margin, and order quality continue to receive a premium. Nan Ya PCB and Kinsus are easier to verify quickly at this step.
The third step is quality repricing, in which the market distinguishes short-term price hikes from long-term platforms. If price hikes are only short-term spot prices, the multiple will fall. If price hikes come from customer certification, material gates, and long-term supply position, the multiple can hold. Unimicron's long-term value is mainly reassessed at this third step.
These three steps are not a one-way ascent; they can also reverse. If monthly data miss expectations, theme repricing cools first. If quarterly gross margin cannot keep up, earnings repricing stops. If customer and material supply alternatives emerge, quality repricing is rewritten. Risk management for substrate stocks needs to be broken down by these three steps, rather than waiting for the full cycle to reverse.
Therefore, if share prices pull back in coming quarters, one cannot immediately judge that the logic has failed. First distinguish whether the pullback comes from theme cooling, earnings disappointment, or doubts about long-term quality. Theme cooling can usually be repaired by later data. Earnings disappointment requires the next round of gross-margin proof. Long-term quality doubts are harder to repair because they shake the foundation of the high multiple.
If Nan Ya PCB pulls back only because of profit-taking after a target-price upgrade, but monthly gross margin remains strong, the logic still holds. If the pullback comes with poor price transmission, elasticity assumptions should be lowered. If Kinsus pulls back only because the market worries the move has been too fast, but ABF/BT utilization keeps improving, it may be a reconfirmation point. If Vera CPU or BT spillover misses expectations, operating leverage must be reassessed.
Unimicron's pullback requires even more attention to the cause. If short-term capital rotates into Nan Ya PCB and Kinsus, that does not mean the long-term platform logic has deteriorated. If the market finds that long-term agreements, HDI, or T-glass resources do not bring gross-margin uplift, that is the real problem. Its verification is slower, so judgment should be more patient, but the requirement for profitability should not be relaxed.
This rhythm helps avoid a common mistake: attributing all upside to the industry shortage and all downside to the end of the cycle. The reality is more nuanced. The substrate trade will switch back and forth among theme, earnings, and quality. The more clearly investment judgment separates these three layers, the less likely it is to be led by target prices and short-term volatility.
What would strengthen the view? Not one more optimistic target price, but three types of evidence appearing at the same time. First, substrate makers maintain shipment cadence after price increases, showing customers are not obviously delaying orders because of higher prices. Second, gross-margin improvement gets through single-month volatility, showing product mix and material constraints jointly support margins. Third, company language on follow-up projects shifts from "strong demand" to "tight delivery" and "fully booked capacity," showing the supply side remains the issue customers care about most.
What would weaken the view? Again, not a single bad headline, but evidence starting to conflict. Strong revenue but weak gross margin means price was not retained. Strong gross margin but weak revenue means only mix improved. Companies saying demand is strong while peer utilization falls suggests orders may be concentrated in a few projects. Materials remain tight but customers no longer accept price hikes means bargaining power is returning to customers. The real inflection point is often not one data point, but multiple pieces of evidence no longer moving in the same direction.
The biggest risk for substrate stocks is not that the market does not know ABF, but that it only knows ABF. BT spillover, T-glass constraints, customer certification, long-term contract repricing, and monthly earnings are the full puzzle of this margin trade. Looking at only one piece can overestimate near-term elasticity and underestimate long-term platform value.
A steadier tracking approach is to put every company data point back into this puzzle. Companies that can fill in price, utilization, and gross margin at the same time deserve to keep enjoying high valuations. Companies that can add only narrative but not profit will ultimately be repriced by the market.
This is the largest value of Citi's report: it does not only tell the market "ABF is still short," but breaks the shortage into price, utilization, materials, customers, and gross margin. As long as investors track this chain, they will not be led around by a single target-price upgrade, nor will they confuse the time dimensions between near-term catalysts and long-term resources.
11. Conclusion: This Is Not "ABF Is Still Short," but "How Does the Shortage Enter the Income Statement"
Citi's report pushes the ABF/BT substrate trade one step forward. The industry shortage and T-glass constraints are already old consensus. The new question is whether the income statement can carry them. Nan Ya PCB represents spot pricing and switch-chip elasticity. Kinsus represents the operating leverage of Vera CPU and BT spillover. Unimicron represents high-end ABF scale, T-glass resources, and long-term customer relationships.
All three companies have higher target prices, but they are not the same money. Nan Ya PCB's money comes from price. Kinsus's money comes from utilization and dual-line leverage. Unimicron's money comes from resources, scale, and long-term supply position. In the short term, Nan Ya PCB and Kinsus are sharper. In the long term, Unimicron looks more like the anchor of high-end ABF.
The key takeaway from this report should not be the target-price numbers, but a verification table: 3Q26/4Q26 ABF prices, BT utilization, T-glass lead times, monthly unaudited gross margin, and continued 2027E EPS upgrades. As long as these numbers keep holding together, ABF/BT substrates remain one of the AI hardware-chain links most likely to turn a bottleneck into profit. Once these numbers break, 30x 2027E EPS will reprice faster than the industry narrative.ABF and BT Substrate Price-Hike Assumptions Revised Higher: From T-glass Constraints to BT Spillover, Why the AI Substrate Price Cycle Is Not Over Yet
目录
Too Long; Didn’t Read
1. Citi Is Revising the Income Statement, Not Just Changing Target Prices
2. The ABF Price Cycle Is Not Over, and BT Supply Is Also Starting to Tighten
3. Nan Ya PCB: The Most Direct Price Elasticity, Watch Broadcom and Switch Chips First
4. Kinsus: Vera CPU and BT Spillover Stack Together; Elasticity Comes from Dual-Line Utilization
5. Unimicron: Stronger Scale and Resource Advantages, but Less Near-Term Elasticity Than Nan Ya PCB and Kinsus
6. The Three Companies Are Not the Same Trade; Ranking Should Be Layered by Price, Utilization, and Resources
7. Valuation Depends on Whether 30x Is Justified by Gross-Margin Revisions
8. Follow-Up Verification Checklist: Four Hard Indicators Determine How Far This Cycle Can Go
9. Risks: When the Cycle Is Strengthening, the Biggest Risk Is Insufficient Realization Speed
10. Investment View: Separate the Three Companies by Capital Type and Realization Window
11. Conclusion: This Is Not “ABF Is Still Short,” but “How Does the Shortage Enter the Income Statement”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The AI substrate trade is moving from “shortages drive price hikes” to “who can translate those hikes into gross margin.” Citi has raised target prices for Nan Ya PCB, Kinsus, and Unimicron at the same time. The real incremental point is that both ABF and BT substrate lines are entering a margin upgrade window. The key test is whether monthly earnings can support a 2027 EPS rerating.
Too Long; Didn’t Read
This upgrade is a margin trade. Citi raised target prices for Nan Ya PCB, Kinsus, and Unimicron while keeping all three at Buy. The target-price moves themselves are not the point. The point is that Citi materially lifted its 2027E EPS and gross-margin assumptions, which means substrate makers’ pricing power is starting to move from order visibility into reported profits.
ABF tightness still extends into 2027. AI GPUs, ASICs, and CPUs continue to consume more large-size, high-layer-count, high-yield ABF capacity. Citi expects ABF prices to rise 15-20% QoQ in 3Q26 and another 10-15% QoQ in 4Q26. If ABF capacity in mainland China does not see demand loosen, global customers will still pay a premium for delivery certainty, making near-term supply easing unlikely to become the main narrative.
BT substrates are moving from supporting role to second source of upside. BT used to be treated mainly as a consumer-electronics and memory-packaging cycle. This time, the change is coming from the supply side: Unimicron plans to cut at least 15% of BT capacity by end-2026, with a possible medium-term cut of 40-50%, while some peers are also converting BT lines to ABF. Order spillover should lift utilization at Kinsus and Nan Ya PCB, giving BT gross margin a chance to rise from the historical 5-15% range to above 20%.
Nan Ya PCB and Kinsus have faster near-term elasticity. Nan Ya PCB is more willing to retain spot-pricing exposure. Broadcom Tomahawk, switch chips, and selected ASIC projects allow ABF price elasticity to enter the P&L; faster. Kinsus benefits at the same time from Vera CPU share, BT order spillover, and capacity ramp. Unimicron’s strengths are scale, T-glass resources, and long-term customers, but its near-term price-hike leverage will be diluted by long-term agreements and a broader business mix.
Whether 30x valuation can hold depends on four numbers. First, whether monthly unaudited earnings can beat consensus gross margin by 2-3 ppts. Second, whether 3Q26 and 4Q26 ABF price increases land as scheduled. Third, whether BT utilization at Kinsus and Nan Ya PCB improves sequentially. Fourth, whether Unimicron can prove current gross-margin expansion is not just ABF demand, but a joint contribution from HDI, T-glass, and long-term contract repricing.
The biggest risk is not “ABF is unimportant,” but that the shortage is disproved earlier than expected. If new T-glass supplier certification is faster than expected, AI chip development is delayed, demand for mainland China ABF capacity loosens, customers resist repeated price hikes, or effective 2027 capacity additions arrive in a cluster, the valuation base of 30x 2027E EPS will compress. The key risk in the current trade is not lack of demand, but failure of price, utilization, and gross margin to materialize at the same time.
1. Citi Is Revising the Income Statement, Not Just Changing Target Prices
ABF substrates have already been traded repeatedly. The old questions were whether they were short, whether prices would rise, and whether capacity expansion would quickly kill the cycle. The incremental point in Citi’s June 30, 2026 report is narrower and closer to the P&L;: ABF price hikes are still progressing, BT supply-demand is also starting to improve, and Taiwanese substrate makers are entering a gross-margin expansion cycle.
This shifts the question from supply-chain position to profit allocation. The rising demand for AI GPUs, ASICs, and CPUs no longer needs to be reproven. What matters is who can turn the shortage into price, who can turn price into gross margin, and who is still held back by long-term agreements, materials, customer mix, or depreciation.
Full Revaluation of AI PCB Materials - From CCL Price Hikes and Glass-Fiber Fabric Looms to the ABF Gap and Rack Upgrades
AI PCB Phase Three: Capacity Expansion Is Not the Answer; Glass-Fiber Fabric Looms, T-glass, HVLP Copper Foil, Lamination/Drilling, and Certification Cycles Determine Who Really Opens Supply
Citi keeps all three companies at Buy this time, but the scale of target-price and earnings-model revisions is large. Kinsus’s new target price is 2.75x the old one; Nan Ya PCB is raised by 41%; Unimicron is raised by 39%. The three companies are compared on the same report date, same currency, and same share unit, with no cross-currency or ADR-unit conversion involved.
The key information in this table is not the absolute target price, but 2027E EPS. Kinsus’s 2027E EPS rises from NT$16.20 to NT$38.61, Nan Ya PCB from NT$36.82 to NT$51.89, and Unimicron from NT$35.94 to NT$50.49. Citi is not only raising the valuation multiple; it is also moving the earnings center higher.
If one looks only at target prices, this can easily be read as a routine upgrade note. Seen within the AI PCB series, it looks more like a phase-shift signal: earlier rounds of the trade relied on material shortages, T-glass, the ABF gap, and high-end CCL. Now the market is starting to ask whether ABF and BT price hikes can land simultaneously in monthly earnings, gross margin, and 2027 EPS.
Cross-reading earlier Taiwanese substrate materials makes this phase shift clearer. Earlier reports on Kinsus emphasized its benefit from ABF and BT substrates, with the core being utilization and target-price upgrades. Materials on Unimicron emphasized that the substrate tailwind was still at an early stage, with the core being ABF strength and leadership. Materials on Nan Ya PCB emphasized strong monthly earnings, with the core being near-term gross margin and order elasticity. T-glass materials placed the material constraint at the bottleneck of the supply chain.
These clues were originally scattered. Kinsus was about operating leverage. Unimicron was about scale and high-end supply. Nan Ya PCB was about near-term price elasticity. T-glass was about the material gate. Citi’s report combines them into one income-statement thread: tight materials support ABF pricing, the leader’s adjustment of BT capacity creates order spillover, customers accept higher prices for delivery certainty, and gross margin and EPS are then revised higher in a systematic way.
That is why this report should not be treated as merely a “target-price upgrade list.” Target prices are the result; the process is supply-demand improvement expanding from a single ABF shortage to dual-line improvement in ABF and BT. Ratings are the surface; underneath, the earnings model is moving from revenue upgrades to gross-margin upgrades. As long as this process holds, the key substrate-stock question shifts from “who has capacity” to “who can retain the profit after price hikes.”
Conversely, if later data only prove that ABF is still short, but fail to prove BT order spillover, monthly earnings beats, and continued gross-margin expansion, the optimistic assumptions in this report will weaken. Between industry bottleneck and company profit sit customer bargaining, material costs, yield ramp, depreciation, and product mix. If any one of these is handled poorly, the shortage may remain only on the revenue line.
AI PCB: From Materials Revaluation to Profit Realization - Shennan 30+ Layer MLPCB, TUC High-End CCL, Kingboard Materials Integration, Nan Ya PCB and Unimicron ABF Substrates, Who Books the Price Hikes First
2. The ABF Price Cycle Is Not Over, and BT Supply Is Also Starting to Tighten
ABF tightness is being squeezed from both demand and materials. Citi assumes ABF prices rise 15-20% QoQ in 3Q26 and another 10-15% QoQ in 4Q26. This is not a mild price adjustment, but two consecutive quarters of price increases.
There are three conditions behind the ability of prices to rise sequentially.
First, AI chip demand is still expanding. GPUs, ASICs, and CPUs are all increasing ABF consumption. High-performance chips require substrates with larger size, higher layer counts, lower warpage, and higher yield. Nominal shipment volume cannot be equated directly with capacity consumption. A complex ASIC or AI CPU may consume far more effective capacity than an ordinary PC chip.
Second, T-glass remains the master gate. Citi believes T-glass constraints may last into 2027 because certification of new suppliers is progressing more slowly than expected. Taiwan Glass is advancing faster in thick glass, but its quality has not yet reached Nittobo’s level. EMC’s ABF CCL, MGC’s RS Resin, Nan Ya Plastics’ T-glass solution, and other new suppliers still need validation. Customers can look for alternatives, but mass-production qualification cannot be solved immediately by procurement intent.
Third, there is no obvious loosening in mainland China ABF capacity. Citi observes improved utilization of mainland China ABF capacity, while peers such as Zhen Ding are also expanding capacity. For some U.S. customers, mainland China ABF capacity is not the optimal choice, but it will still be used when options are limited. At the same time, AI demand in the China market is also competing for capacity. As long as this capacity does not see demand loosen, global ABF supply-demand is unlikely to ease quickly.
ABF Substrate Deep Dive: The Packaging Foundation of AI Compute, from Basic Framework to Supply-Demand Landscape and Company Ranking
The change in BT is easier to underestimate. In the past, the market was more excited about ABF and more cautious on BT, because BT was tied to memory, smartphones, and traditional packaging cycles, and its margin was not as high as ABF’s. Citi calls out BT separately this time because the supply side is starting to change: some peers are unwilling to keep taking BT orders, or plan to convert BT lines into ABF lines.
Unimicron is the key variable. Citi notes that Unimicron plans to cut at least 15% of total BT capacity by end-2026, likely mainly from WBCSP-related products at its Taiwan plants. In the medium term, Citi expects Unimicron could cut 40-50% of BT capacity, but it will not fully exit because Apple and some Chinese customers still have BT demand, and the Suzhou BT plant may be retained.
BT looks lower-end, but supply exits will give remaining makers better pricing and utilization. Citi estimates that Unimicron’s 2025 BT sales account for about 11% of BT sales among major global peers. If Unimicron cuts 40-50% of BT capacity in the medium term, orders will gradually flow to Taiwanese peers such as Kinsus and Nan Ya PCB.
This table shows that BT is not too small to ignore. For Kinsus, BT already accounts for 35-40% of sales. For Nan Ya PCB, BT can drive gross margin together with ABF spot prices. For Unimicron, cutting BT capacity is not an exit from the market, but a shift of lower-profit capacity toward ABF and higher-end projects.
The most important question in this round of substrate price hikes is “why do the price hikes remain with substrate makers?“ Material price increases do not automatically mean margin expansion for substrate makers. If customers view price merely as cost pass-through, gross margin will not improve. Only when customers pay for delivery certainty, certification status, and high-yield capacity do price hikes become substrate-maker margin. The real importance of Citi’s report is that it points ABF and BT supply-demand changes toward gross margin, not just revenue.
ABF pricing power comes from customers having insufficient alternatives. The substrates used in AI chips are not just an expansion in ordinary area; they require high layer count, large size, low warpage, and high yield at the same time. Customers can certify more suppliers, but each supplier must pass materials, process, reliability, packaging collaboration, and mass-production ramp. Nominal capacity can appear in financial reports or expansion announcements, but qualified capacity must be verified in customers’ production schedule.
This is why T-glass is more like the master gate than an ordinary material. A shortage of ordinary materials affects cost; a T-glass shortage affects effective capacity and yield. If substrate makers cannot secure qualified materials, even more expansion equipment cannot become usable capacity. If customers recognize only a few material systems, alternative suppliers will also struggle to ramp immediately. Substrate makers can therefore turn “I have qualified capacity” into bargaining leverage.
BT’s logic is more like supply-side clearing. It is not as glamorous as ABF, but once leaders shift low-profit capacity to ABF, the remaining BT orders must look for new suppliers. This process will not finish overnight because customers still need to evaluate product type and certification. But as long as exiting suppliers are unwilling to protect volume at low prices, receiving suppliers can repair gross margin through higher utilization and a better product mix.
When ABF and BT improve at the same time, P&L; elasticity is greater than price hikes on a single line. ABF provides market imagination and valuation multiple. BT provides utilization and expense absorption. ABF price increases make customers acknowledge that substrates are the bottleneck. BT order spillover lifts line utilization. The near-term elasticity of Kinsus and Nan Ya PCB comes exactly from these two lines working at the same time.
That said, there is also an easily overlooked reflexivity here. The faster prices rise, the more customers will push second-source suppliers, regional alternatives, and material substitutions. The more the industry believes the shortage will persist, the more active capacity expansion and certification will become. The substrate makers’ window is not unlimited. It is more like a period of margin repricing. The companies that can lift monthly earnings and quarterly gross margin during this window are the real beneficiaries of the cycle.
3. Nan Ya PCB: The Most Direct Price Elasticity, Watch Broadcom and Switch Chips First
Nan Ya PCB is one of Citi’s preferred near-term names for a straightforward reason: it looks more like a spot-pricing elasticity play. The company is less willing to sign long-term agreements with customers, has higher spot-market exposure, and ABF and BT price increases can enter the P&L; faster.
Nan Ya PCB’s ABF main line is Broadcom Tomahawk-related products. In addition to switch ICs, the company also supplies selected ASIC projects, although its share is not large. Citi’s view is that Nan Ya PCB will adopt a more aggressive pricing strategy for both ABF and BT over the next few quarters, with price hikes and utilization improvement driving gross margin upward.
This company is useful for answering one question: can ABF tightness on the AI networking and ASIC side enter the income statement faster than the GPU main line? GPU substrates have long-term agreements, large customers, and strict certification. Switch chips and selected ASIC projects are also complex, but if the company retains more spot-price exposure, price transmission can be faster.
The most important line is the 2027E gross margin revision from 34.2% to 41.0%. Nan Ya PCB is not relying only on revenue upgrades; its profit elasticity mainly comes from gross margin. Citi expects 2027E net profit to rise to NT$33.531bn, and the model already embeds an aggressive ABF/BT pricing strategy.
The near-term catalyst is also clear. Citi added a 30-day upside Catalyst Watch on Nan Ya PCB, arguing that if upcoming monthly unaudited earnings are disclosed, gross margin could be at least 3 ppts above consensus of around 19%. This catalyst is not a macro narrative; it lands directly in unaudited monthly earnings and gross margin.
Nan Ya PCB’s risk is also the most direct. High spot-price exposure gives it the fastest elasticity when prices rise; it also gives it the fastest drawdown when prices loosen. If 3Q26 and 4Q26 ABF price hikes disappoint, or BT order spillover is slower than expected, Nan Ya PCB can quickly be repriced from “fastest realization” to “fastest to be hurt.”
4. Kinsus: Vera CPU and BT Spillover Stack Together; Elasticity Comes from Dual-Line Utilization
Kinsus has the most dramatic target-price change in Citi’s report: from NT$400 to NT$1,100. This cannot be explained only by “ABF price hikes.” The real logic is that both ABF and BT are strengthening at the same time.
On ABF, Kinsus’s key is Vera CPU. Citi believes Kinsus is positive on its own Vera CPU share and that this is consistent with the view of a share above 50%. How much Kinsus can capture depends on its pace of capacity expansion. After the importance of AI CPUs rises, Kinsus is no longer just a second-tier catch-up name, but a direct beneficiary of CPU substrates.
On BT, Kinsus benefits from order spillover after Unimicron cuts BT capacity. Citi expects both Kinsus ABF and BT utilization to reach full loading by end-2026. More importantly, BT gross margin in this cycle may exceed 20%, above the historical 5-15% range. For a company with BT accounting for 35-40% of sales, this change is enough to rewrite the income statement.
The key in this data set is operating leverage. 2027E sales are revised up 43%, gross profit 70%, operating profit 104%, and net profit 133%. In other words, Citi is not only assuming Kinsus sells more, but that its product mix, BT gross margin, ABF utilization, and expense ratio all improve together.
Kinsus’s advantage is “two cycles stacked together”: AI CPU pulls ABF, while memory and peer contraction pull BT. Looking only at ABF, it is not a scale leader like Unimicron. Looking only at BT, it is not the market’s hottest AI asset. But when Vera CPU, BT order spillover, the K6 capacity ramp, and gross-margin expansion stack together, Kinsus becomes the name most likely to see an earnings jump.
The Second Revaluation of the AI Server Materials Chain: From Passive Components to PCB/CCL, ABF Substrates, and Test Equipment
The near-term Catalyst Watch is also tied to monthly earnings. Citi believes that if Kinsus’s upcoming monthly unaudited earnings are disclosed, gross margin could be at least 2 ppts above consensus of around 25%. Compared with Nan Ya PCB, Kinsus has a higher consensus gross-margin base, but its upside comes from dual-line utilization rather than a single spot price.
Kinsus’s biggest risk is capacity and customer timing. If Vera CPU share is constrained by capacity expansion speed, the ABF uplift will be delayed. If BT spillover is slower than expected, near-term gross margin will be below Citi’s optimistic assumptions. Kinsus’s pricing in this round looks the steepest, which also means later monthly data have the lowest margin for error.
5. Unimicron: Stronger Scale and Resource Advantages, but Less Near-Term Elasticity Than Nan Ya PCB and Kinsus
Unimicron is the company that cannot be ignored over the long term. Its advantage is not the fastest price hike, but scale, customers, T-glass resources, and leadership in high-end substrates. Citi also states clearly that it prefers Nan Ya PCB and Kinsus in the near term, but still likes Unimicron’s leadership over the long term.
Unimicron’s near-term tension is this: the market likes ABF spot-price exposure and earnings slope, but Unimicron has more long-term agreements, a broader integrated business, and a larger customer structure. It benefits from ABF upside, but it may not be the company with the largest near-term price-hike elasticity.
Citi’s revisions for Unimicron mainly come from three points. First, gross-margin benefits from long-term agreements. Second, margin improvement after HDI mass production. Third, more sufficient T-glass supply, which gives the company more bargaining power than other ABF peers. Citi also notes that the current 2Q26 gross-margin uplift is likely driven mainly by ABF demand, not by HDI utilization improvement.
Unimicron’s 2026E sales are almost unchanged, but gross margin and EPS are revised up meaningfully. This shows that the current model is not driven by volume, but by structure, price, and gross margin. By 2027, sales are revised up 15%, gross profit 32%, net profit 37%, and gross margin to 40.1%. If realized, Unimicron would move from ABF leader to a high-margin substrate platform.
Unimicron also has one move that looks negative but is actually helpful to industry supply: cutting BT capacity. It will not fully exit BT because Apple and some Chinese customers still have BT demand, and the Suzhou plant may be retained. But cutting low-margin or relatively low-visibility BT capacity and shifting resources to ABF is positive for its own mix, and will also allow Kinsus and Nan Ya PCB to receive BT order spillover.
This is also the profit-allocation relationship among Unimicron, Kinsus, and Nan Ya PCB. Unimicron commits more resources to high-end ABF, T-glass, long-term agreements, and HDI. Kinsus and Nan Ya PCB take part of the orders created by BT supply contraction. Nan Ya PCB then amplifies margin through higher spot-price exposure. The industry is not a case of three companies rising identically; it is a supply chain redistributing profit.
AI PCB and CCL Deep Dive: From GB300 to Rubin Ultra, Who Runs Short First in High-Layer Boards, M9 Materials, and E-glass Fabric
Unimicron’s risk is valuation digestion. Citi’s new NT$1,500 target price implies 30x 2027E EPS. This is not a cheap-asset multiple. It requires the company to prove ABF demand, T-glass resources, HDI improvement, and long-term-agreement gross margin all materialize at the same time. If 2027E gross margin cannot approach 40%, valuation will come under pressure before fundamentals.
6. The Three Companies Are Not the Same Trade; Ranking Should Be Layered by Price, Utilization, and Resources
This ABF/BT trade can easily be flattened. All three companies have higher target prices, all remain Buy, and all have ABF exposure, but their profit sources are completely different.
Nan Ya PCB benefits from price, especially spot price and switch-chip/ASIC projects. Its keyword is speed: fast price, fast gross margin, fast monthly-earnings response. Kinsus benefits from utilization, especially Vera CPU share and BT order spillover. Its keyword is leverage: after revenue is revised up, profit is revised up faster. Unimicron benefits from resources and scale, especially T-glass, long-term customers, ABF leadership, and HDI mass-production improvement. Its keyword is stability: less sharp in the near term, but the most important long-term supply position.
The ranking can be divided into three time dimensions: short, medium, and long term.
Over the next 30 days, Nan Ya PCB and Kinsus have more catalysts. Citi explicitly added 30-day upside Catalyst Watch for both companies, with the core trigger being possible upside in unaudited monthly earnings. Nan Ya PCB has a low consensus gross-margin base and strong spot-price elasticity, with an upside threshold of about 3 ppts. Kinsus has a higher consensus gross-margin base, but ABF/BT dual-line full loading, with an upside threshold of about 2 ppts.
Looking at 2H26, Kinsus and Nan Ya PCB need to prove price and utilization are not one-off. ABF price hikes in 3Q26 and 4Q26 need to land in line with Citi’s expectations. BT cannot remain only verbal improvement; it needs to show up in utilization and gross margin. Nan Ya PCB’s Broadcom/switch-chip demand and Kinsus’s Vera CPU progress need to continue supporting revenue slope.
Looking into 2027-2028, Unimicron remains the scale anchor in high-end ABF. It is not the most exciting near-term elasticity story, but if AI GPU, ASIC, and CPU demand continues to expand, T-glass remains tight, and customers want to lock stable supply, Unimicron’s resource and scale advantages will be repriced by the market again.
This ranking cannot be static. The difficulty with substrate stocks is that share prices often first trade on the shortest catalyst, then price in medium-term earnings revisions, and only then return to long-term competitiveness. The strongest near-term company is not necessarily the most stable long-term company, and the most stable long-term company may not deliver the largest earnings surprise in the next few quarters. Comparing the three on one single line can easily mislead.
The first scenario is “price realization.” ABF price hikes land in succession, BT order spillover starts to show up in utilization, and monthly unaudited earnings are revised ahead of official quarterly reports. In this scenario, the market is most willing to buy Nan Ya PCB and Kinsus because their earnings slope is the fastest and easier to verify through monthly data. Unimicron also rises, but more as a function of high-end ABF strength and a higher valuation center.
The second scenario is “materials remain the chokepoint.” T-glass remains tight, customer certification of alternative suppliers is slow, AI chip projects are not materially delayed, but the speed of spot-price hikes starts to slow. In this scenario, Unimicron’s resource value resurfaces. It may not have the steepest earnings elasticity, but it looks more like the long-term supply platform customers are willing to lock in. Nan Ya PCB and Kinsus still have profit elasticity, but valuation will depend more on repeated earnings surprises.
The third scenario is “the shortage is disproved early.” Customers start to find alternative supply, T-glass certification progresses faster than expected, or AI chip project schedules move out. In this scenario, all three companies suffer valuation pressure, but in different order: the company with the highest spot-price elasticity is hurt first, the company with the highest operating leverage sees profit revised down fastest, and the scale leader depends on whether long-term customer relationships can buffer the cycle.
Therefore, this report should not be read only as “who has the highest target price.” A more useful reading is to ask what scenario the market is buying right now. If the market is buying 30-day earnings surprises, Nan Ya PCB and Kinsus matter more. If the market is buying high-end ABF supply position in 2027, Unimicron matters more. If the market starts worrying about 2028 supply release, all three companies must be rescored on gross margin and order quality.
Sell-side divergence is also here. Earlier Taiwanese substrate reports focused more on “is ABF short?“ and “who has new capacity?” Their upgrades for Kinsus, Unimicron, and Nan Ya PCB mainly came from orders, customers, and utilization. Citi pushes the question to gross margin and pricing power this time, effectively moving the framework from a “capacity cycle” to a “margin cycle.” This is a higher-order call, and also easier for data to disprove.
If subsequent data show only revenue upgrades without gross-margin upgrades, the industry is still in a capacity cycle. If revenue and gross margin rise together, pricing power is real. If gross margin rises but revenue does not persist, it is only a short-term price or mix improvement. What truly supports a high multiple is the second state, not any one single number.
7. Valuation Depends on Whether 30x Is Justified by Gross-Margin Revisions
Citi now applies a valuation framework near 30x 2027E EPS for all three companies. Nan Ya PCB and Unimicron use 30x 2027E EPS, while Kinsus uses 28x 2027E EPS. This is a high multiple, but during a phase of supply-demand tightness, price increases, and accelerating earnings, the market can accept high multiples, provided earnings revisions keep moving upward.
The issue is that high multiples cannot rely only on a shortage narrative. They need gross-margin data to support them.
Putting the three companies on the same earnings bridge reveals the real rerating point: 2027E gross margins have all been pushed into the 37-41% range. The substrate industry has had cycles before, but if all three companies can reach gross margins near 40%, the market will reprice them from traditional electronic-component cyclicals into AI bottleneck-capacity assets.
Valuation fears two things most.
First, revenue rises but gross margin does not. That means the price hike is eaten by materials, depreciation, yield, or customer bargaining. For ABF, T-glass tightness can support price hikes, but it can also constrain shipments. For new capacity, ramp and depreciation can also consume profit. A high multiple fears “volume arrived, but profit did not.”
Second, gross margin rises, but the market discovers it is only one quarter. Citi’s model is a broad 2027 upgrade, not a single 2Q26 or 3Q26 surprise. If price increases slow after 3Q26, or customers renegotiate prices in 2027, a 30x valuation will be hard to defend.
This is why follow-up tracking must look at continuous data, not a single target price. Monthly unaudited earnings, quarterly gross margin, ABF price-hike cadence, BT utilization, T-glass lead time, and customer long-term agreements all need to validate each other continuously. If one link breaks, the share price will react first.
Target-price comparisons also need a consistent basis. The three companies are in the same Citi report, on the same report date, in the same currency, and on the same share-unit basis, so their “revision direction” and “model assumptions” can be compared. Even so, absolute target prices should not simply be ranked as degrees of optimism. Kinsus’s new target price jumped the most because its old base was low and earnings-model elasticity was large. Nan Ya PCB’s high target price reflects more direct price elasticity and near-term catalysts. Unimicron’s target price is close to Nan Ya PCB’s because scale and high-end ABF status support a long-term multiple.
What should really be compared is the quality of profit behind the target price. Nan Ya PCB’s profit quality depends on whether spot price is sustainable. Kinsus’s profit quality depends on whether utilization and BT gross margin improve together. Unimicron’s profit quality depends on whether ABF, HDI, T-glass, and long-term agreements can form a combined advantage. All three can rise, but the market’s trust comes from different sources.
Valuation multiples in cycles like this usually move in two stages. In the first stage, the supply-demand gap is confirmed and the market is willing to raise the multiple because bottleneck assets are scarce. In the second stage, profit is realized and the market starts to look at the pace of EPS revisions and the stability of gross margin. If the second stage cannot keep up, the multiple granted in the first stage is taken back. If the second stage keeps beating expectations, the multiple can stay high and even allow the next round of earnings upgrades to push the share price higher.
Citi’s framework of around 30x 2027E EPS implies that “2027 is still in a margin-expansion cycle.” That is more aggressive than looking at 2026E, because 2026 can only prove that price hikes have started, while 2027 proves whether price hikes, utilization, material constraints, and customer mix can annualize. What investors are really buying is the 2027 income statement, not one month of price increases today.
But 2027E also has a natural weakness: the further the year, the higher the requirement for cycle durability. As soon as the market starts to believe 2028 supply will be released in a cluster, or customers can shift more projects to new suppliers, the high multiple on 2027E will be discounted in advance. Substrate stocks usually do not wait for earnings downgrades before falling; they often fall when “can next year have the same slope?“ becomes doubtful.
So valuation judgment needs to ask two questions at the same time. The first is whether earnings keep being revised up, which determines whether target prices can rise further. The second is whether the multiple has a reason to hold, which determines whether the share price can fully capture the revision. Looking only at EPS will underestimate valuation elasticity for bottleneck assets; looking only at the multiple will ignore the speed of downward revisions when the cycle turns.
This is also the core of the style differences among the three companies. Nan Ya PCB is more of a price trade, suited to validation through monthly earnings and gross margin. Kinsus is more of an operating-leverage trade, suited to validation through revenue slope, BT gross margin, and expense-ratio dilution. Unimicron is more of a supply-platform trade, suited to validation through high-end ABF resources, customer lock-in, and long-term agreements. Different styles imply different holding patience and different stop-loss signals.
8. Follow-Up Verification Checklist: Four Hard Indicators Determine How Far This Cycle Can Go
First, watch monthly unaudited earnings. Citi added 30-day upside Catalyst Watch for both Nan Ya PCB and Kinsus, with the trigger being upside in monthly unaudited earnings and gross margin. For Nan Ya PCB, watch whether gross margin is 3 ppts above consensus of around 19%. For Kinsus, watch whether gross margin is 2 ppts above consensus of around 25%. This is the shortest and fastest-reacting indicator.
Second, watch the cadence of ABF price hikes. 3Q26 prices up 15-20% QoQ and 4Q26 prices up 10-15% QoQ are important assumptions in Citi’s model. If actual increases are below this range, the near-term elasticity of Nan Ya PCB and Kinsus will be hurt first. If the increases land or are even stronger, Unimicron’s 2027E long-term-agreement repricing will also have more support.
Third, watch whether BT supply-demand really improves. Unimicron’s BT capacity cuts are the supply-side starting point, but spillover to Kinsus and Nan Ya PCB needs data validation. Focus on BT utilization, BT gross margin, memory demand, and WBCSP/BT product mix. If BT gross margin can rise from the historical 5-15% range to above 20%, Kinsus’s earnings leverage will be very clear.
Fourth, watch T-glass certification and alternatives. T-glass is the master gate for the ABF price cycle. If Taiwan Glass, Nan Ya Plastics, or other new suppliers see clear certification acceleration, the price cycle will be compressed earlier. If Nittobo and other core suppliers remain tight, substrate makers’ bargaining power with customers will hold. Here, one cannot look only at capacity announcements; customer certification, mass-production yield, and real lead times matter.
Fifth, watch AI chip project timing. Nan Ya PCB’s Broadcom Tomahawk and switch chips, Kinsus’s Vera CPU, and Unimicron’s AI GPU/ASIC and HDI projects all need to be tied to specific project mass-production schedules. If AI chip development is delayed, substrate prices can hold in the short term, but earnings revisions will lack persistence.
Sixth, watch valuation divergence. Citi’s roughly 30x 2027E valuation is a multiple for a “gross-margin expansion cycle.” If the market later shifts to 2028E or longer-term EPS, Unimicron will be more advantaged. If the market focuses only on 30-90 day earnings surprises, Nan Ya PCB and Kinsus will be more advantaged. Rankings change when the time dimension changes.
These indicators are best tracked in four layers. The first layer is the fastest monthly data: revenue, unaudited earnings, gross-margin basis, and company order language. The near-term catalysts for Nan Ya PCB and Kinsus are all here. If monthly data cannot prove price hikes and utilization, the market will not wait for official quarterly reports.
The second layer is the quarterly income statement. Monthly data can be affected by product mix, shipment timing, and one-off projects. Quarterly gross margin is better at showing whether price and cost have truly entered the income statement. It is especially important to see whether gross-margin improvement comes with revenue growth, rather than short-term mix improvement caused by fewer low-margin orders.
The third layer is capacity and materials. ABF capacity, BT capacity, T-glass supply, yield, and customer certification cadence determine how long price hikes can last. Here, one cannot look only at company expansion plans; one must also see whether customers actually put new suppliers into mass production. For AI chip customers, there is still a distance between certification approval and large-scale shipments.
The fourth layer is customer projects. Nan Ya PCB needs Broadcom Tomahawk and switch-chip demand. Kinsus needs Vera CPU and BT spillover. Unimicron needs high-end ABF, HDI, and long-term customer agreements. If customer project timing is unchanged, material tightness supports pricing. If customer projects are delayed, material tightness can only slow downward revisions; it cannot create demand.
Verification should also avoid looking at only one winner. Profit allocation in the substrate chain is interconnected: Unimicron’s BT capacity cuts benefit Kinsus and Nan Ya PCB; tight T-glass supports all high-end ABF makers; spot-price increases let Nan Ya PCB show elasticity first; long-term contract repricing benefits scale platforms such as Unimicron more. Single-company data need to be read together with peer data.
A practical tracking method is to treat monthly earnings as the signal, quarterly gross margin as confirmation, material lead times as cycle length, and customer projects as the demand base. If all four indicators move upward together, there is still room for target-price upgrades. If only monthly earnings move up, it may be just short-term shipments. If only materials are tight but customer projects are lacking, price is unlikely to hold for long. If customer demand is strong but materials and capacity ease, margin upgrades will be eaten by customer renegotiation.
This framework also explains why Citi prefers Nan Ya PCB and Kinsus in the near term. They are the first to be verified by monthly data, and also the easiest to be rejected by monthly data. Unimicron’s verification is slower, but if quarterly gross margin and long-term contract repricing begin to confirm, its advantage will move from “leader valuation” to “platform margin,” and the market will give it longer patience again.
9. Risks: When the Cycle Is Strengthening, the Biggest Risk Is Insufficient Realization Speed
ABF and BT substrates are not risk-free. The most dangerous risk today is not that demand disappears completely, but that fundamentals remain good while share prices have already priced in 2027 profits. Once realization speed falls short of expectations, high valuation will compress first.
The first risk is that T-glass constraints ease faster than expected. If new supplier certification accelerates, customers have more options and substrate makers’ ability to raise prices repeatedly will decline. Material shortages support prices, but they also amplify material suppliers’ bargaining power. When the material bottleneck eases, industry pricing power will shift back toward customers and large customers.
The second risk is customer resistance to repeated price hikes. Citi assumes ABF prices continue to rise in 3Q26 and 4Q26, but customers will compare long-term agreements, spot prices, alternative suppliers, and capacity in different regions. The faster prices rise, the stronger customers’ incentive to seek alternatives.
The third risk is a mismatch between capacity expansion and utilization. Nominal expansion is not effective capacity, but once effective capacity is released in a concentrated window, prices will be reassessed. Kinsus’s Vera CPU share, Unimicron’s high-end ABF capacity, and Nan Ya PCB’s switch-chip projects all require yield and certification to qualify at the same time.
The fourth risk is that BT spillover is overestimated. Unimicron’s BT capacity cuts release orders, but whether those orders can all turn into high-margin business for Kinsus and Nan Ya PCB still depends on customer mix, product type, and memory demand. If BT gross margin cannot break 20%, Kinsus’s profit elasticity will be revised down meaningfully.
The fifth risk is valuation multiple contraction. 30x 2027E EPS can be supported by high gross margin, high growth, and supply-demand tightness. But if the market starts to worry about supply expansion after 2028, or if the AI hardware chain as a whole becomes crowded, valuation will fall before earnings are revised down.
These risks are not independent. Material easing first affects price. Price loosening affects gross margin. Gross margin falling short affects EPS. Once upgrades stop, the valuation multiple is lowered. Substrate stocks usually do not fall because one project suddenly disappears, but because one link in the chain between price, utilization, and gross margin breaks.
Nan Ya PCB is most afraid of the price chain breaking. Its advantage is spot-price elasticity, and its weakness is also spot-price elasticity. If customers start moving more orders into long-term agreements, or use second-source suppliers to pressure prices, Nan Ya PCB’s upgrade speed will slow first. It is not that the company lacks long-term customers; rather, the current premium in the trade comes from “price hikes quickly entering the income statement,” and that premium needs continuous proof from monthly data.
Kinsus is most afraid of the utilization chain breaking. Its elasticity comes from ABF and BT being fully loaded at the same time. If the Vera CPU project ramps slowly, or BT spillover orders are below expectations, revenue upgrades will undershoot Citi’s model. Once revenue slope is insufficient, expense-ratio dilution and gross-margin improvement will both weaken. The risk for Kinsus is not that the story is invalid, but that simultaneous realization on both lines is difficult.
Unimicron is most afraid of the timing chain breaking. Its long-term logic is more stable, but the market’s current valuation already embeds 2027 gross-margin expansion. If HDI mass production, long-term-agreement gross margin, T-glass resources, and high-end ABF demand do not gradually provide evidence over the next few quarters, investors will view it as “good long term,” not “upgrading immediately.” Long-term quality and near-term upgrades deserve different prices in valuation.
There is also an industry-level risk that customers reallocate profit. AI chip customers are willing to pay for bottleneck links, but they will not hand over margin indefinitely. Once customers see more qualified supply, or believe price increases exceed delivery value, they will renegotiate. Substrate makers currently have bargaining power because customers fear missing qualified capacity. Once that fear declines, some bargaining power returns to customers.
Therefore, the most rational risk management is not to simply turn bearish on ABF/BT, but to keep asking three questions: have price hikes entered gross margin, has gross margin entered EPS, and are EPS upgrades sufficient to support high multiples? As long as all three answers are “yes,” the rally can continue. Once any answer becomes “uncertain,” reliance on target-price upgrades should be reduced.
10. Investment View: Separate the Three Companies by Capital Type and Realization Window
The easiest mistake in this ABF/BT substrate trade is to treat the three companies as the same beta. They are all in the AI substrate chain, all have Citi target-price upgrades, and all benefit from ABF tightness, but the capital behind their share prices is not the same. Nan Ya PCB is more like price-elasticity capital, Kinsus more like earnings-jump capital, and Unimicron more like long-term supply-platform capital.
Price-elasticity capital looks for “fast.” Nan Ya PCB is best suited to this capital because it has higher spot-price exposure, and Broadcom Tomahawk, switch chips, and selected ASIC projects can transmit price hikes into gross margin more easily. For this capital, the most important question is not whether the company is the strongest long-term player, but whether the next monthly data can prove that price hikes have entered the P&L.;
Earnings-jump capital looks for “steep.” Kinsus is best suited to this capital because its story is not a single price hike, but simultaneous improvement in ABF and BT utilization. Vera CPU share, BT order spillover, K6 capacity ramp, and expense-ratio dilution: if several of these materialize at the same time, profit upgrades will be steeper than revenue upgrades. Its appeal comes from operating leverage, and so does its risk.
Long-term platform capital looks for “stable, with resources.” Unimicron is best suited to this capital because its advantage is not fully reflected in near-term price hikes, but in high-end ABF scale, customer relationships, T-glass resources, long-term agreements, and HDI mass production. It may not be the most exciting in monthly unaudited earnings, but if the 2027 gross-margin rerating holds, the market will give a high-end supply platform longer valuation patience again.
The near-term ranking is therefore quite clear. Looking only at the next few data windows, Nan Ya PCB and Kinsus are sharper than Unimicron. Nan Ya PCB’s catalyst is closer to price; Kinsus’s catalyst is closer to utilization and BT gross margin. Both are easy to verify through monthly earnings, and both are easy to reject through monthly earnings. Short-term trading must accept this high sensitivity.
The medium-term ranking depends on the persistence of earnings revisions. If ABF price hikes continue into the second half and BT utilization also keeps improving, Kinsus’s earnings elasticity may exceed Nan Ya PCB’s because its model improves revenue, gross margin, and expense ratio together. If ABF prices are strong but BT spillover is insufficient, Nan Ya PCB will be more stable. If price increases slow but high-end customers still lock supply, Unimicron will regain advantage.
The long-term ranking ultimately returns to resources and customers. AI chip iteration is not a one- or two-quarter question. Customers will balance qualified supply, reliability, yield, and long-term cooperation. A platform company such as Unimicron has more long-term defensiveness, but it must prove that its long-term advantage is not simply “large scale means safety,” but that long-term agreements, T-glass, and high-end ABF together can maintain margins at a higher level.
This creates an executable portfolio framework. If the capital objective is to capture monthly earnings surprises, weights in Nan Ya PCB and Kinsus should be higher. If the objective is to capture the long-term supply premium in the AI substrate chain, Unimicron cannot be absent. If one is worried about supply easing and valuation compression, all three companies need to be managed with shorter verification cycles rather than relying on the industry’s long-term opportunity to withstand short-term profit disproval.
It is also important to distinguish between “benefiting from price hikes” and “retaining price hikes.” Benefiting from price hikes only means the company can raise prices; retaining price hikes means it can turn those price hikes into gross margin. Nan Ya PCB’s retention depends on spot price and customer acceptance. Kinsus’s retention depends on product mix and utilization. Unimicron’s retention depends on long-term contract repricing and high-end projects. If retention capability differs, the same ABF price hike becomes completely different profit elasticity.
For investors, the last thing to do is rank only by target-price increase. Kinsus has the largest target-price increase, but that does not mean the lowest risk. Unimicron has weaker near-term elasticity, but that does not mean low long-term value. Nan Ya PCB has high spot-price exposure, but that does not necessarily make it more suitable for long-term holding. Target prices provide Citi’s joint assumptions on earnings and multiple. The real decision must return to how each company realizes those assumptions.
Within the broader AI hardware chain, ABF/BT substrates are distinctive because they rely on both demand and certification. Demand from servers, switch chips, ASICs, and AI CPUs provides the opportunity. Materials, yield, customer certification, and mass-production experience constrain supply. The demand side makes the market willing to buy growth; the supply side makes the market willing to pay a multiple. Only when both sides hold can substrate stocks move from a cyclical trade to a margin rerating.
But this position also brings higher requirements. Many links in the compute chain can talk about AI growth. Substrate makers must prove they are not ordinary electronics manufacturers, but bottleneck capacity. The evidence of bottleneck capacity is not many orders, but customers’ willingness to pay higher prices for qualified capacity; not revenue growth, but gross-margin expansion; not a single-quarter surprise, but sustained earnings-forecast upgrades.
Therefore, the investment conclusion can be compressed into one sentence: buy monthly gross margin in the short term, buy dual-line ABF/BT realization in the medium term, and buy high-end supply platforms in the long term. Nan Ya PCB, Kinsus, and Unimicron correspond to these three layers respectively, but no single company can stand without verification. If verification is continuous, all three still have room for upgrades. If verification breaks, target prices lose support first.
This view also provides exit signals. If Nan Ya PCB’s monthly gross margin no longer keeps beating expectations, its price elasticity needs to be discounted again. If Kinsus’s ABF and BT are not fully loaded at the same time, operating leverage will be revised down. If Unimicron’s long-term agreements and HDI do not contribute gross margin, its platform premium will be questioned. Each company should be judged not by one aggregate demand indicator, but by its own most important realization variable.
From a portfolio perspective, the more reasonable approach is not to choose one permanent winner among the three, but to adjust rankings by data window. The monthly unaudited earnings window favors Nan Ya PCB and Kinsus. The quarterly gross-margin confirmation window re-compares all three. The 2027 supply-platform window then returns attention to Unimicron. The substrate theme remains unchanged, but capital should migrate with evidence.
When reading financial reports over the next few quarters, the same order should be used. The first step is revenue, not to confirm whether demand exists, but to see whether orders are keeping pace with price. If a substrate maker raises prices but shipments stagnate, the revenue line will reveal the problem first. If revenue and price both rise, customers are accepting the price increases and the supply-demand tension remains.
The second step is gross margin. Gross margin is the core verification point in this report because it determines who ultimately keeps the price increase. Material suppliers, depreciation, yield ramp, and customer bargaining can all consume price hikes. Only if gross margin continues to rise does it show that substrate makers have retained enough profit.
The third step is operating margin. Many electronics manufacturing upturns stop at gross-margin improvement, with expenses and depreciation eating most of the elasticity. For a company with larger operating leverage such as Kinsus, it is especially important to see whether operating margin improves faster than gross margin. If the expense ratio is diluted by revenue, the market will be more willing to price an earnings jump.
The fourth step is capex and capacity-expansion language. If substrate makers overexpand, it may strengthen customer confidence in the short term but lower price expectations ahead of time in the medium term. Expansion itself is not bad; what matters is which customer, which material system, and which yield target it corresponds to. Expansion without customer certification is only nominal capacity.
The fifth step is customer concentration and product mix. Nan Ya PCB’s switch-chip and selected ASIC projects, Kinsus’s Vera CPU, and Unimicron’s high-end ABF and HDI will all affect gross-margin quality. The market should prefer projects with high complexity, high certification barriers, and high delivery requirements, rather than looking only at total shipment area.
The sixth step is management language on pricing. If companies start emphasizing “customer relationships,” “long-term cooperation,” and “cost sharing,” it may mean price-hike speed is starting to slow. If companies continue emphasizing tight supply-demand, delivery priority, and product-mix improvement, bargaining power remains on the substrate makers’ side. Language is not financial data, but it often reflects inflection points earlier than official numbers.
The seventh step is whether peer data validate each other. If Nan Ya PCB’s gross margin is strong but Kinsus and Unimicron do not improve, it may be due to individual projects. If Kinsus’s BT gross margin is strong but Unimicron does not continue capacity cuts, order spillover may be only phase-specific. If Unimicron’s long-term agreements improve but material lead times ease, the long-term platform premium will also be reassessed.
The eighth step is whether customers are willing to sign longer-cycle supply arrangements. Long-term agreements do not necessarily weaken profit; the key is the supply-demand position when they are signed. If signed when substrate makers have strong bargaining power, they can lock in higher gross margin and shipment visibility. If signed when customers have strong bargaining power, they cap spot-price elasticity. Unimicron’s long-term-agreement value must be understood in this context.
The ninth step is whether competitors are forced to make trade-offs. Unimicron’s BT capacity cuts are essentially a shift of resources from lower-return products to higher-return products. If more manufacturers make similar trade-offs, BT supply will remain tight. If manufacturers only adjust temporarily and later return to low-price order grabbing, BT gross margin will struggle to hold.
The tenth step is whether market expectations are too full. Even if fundamentals keep improving, if the market has already bought all 2027 upgrades in one shot, there can still be a “good results, flat share price” outcome. High-multiple assets need repeated beats, not merely in-line performance. After substrate stocks enter a margin trade, expectation management will be more important than the industry narrative.
Using this financial-report reading framework, each of the three companies has its own most sensitive radar. Nan Ya PCB watches price and monthly gross margin. Kinsus watches utilization and operating margin. Unimicron watches long-term agreements, resources, and high-end projects. As long as the radars point to different things, one cannot apply the same valuation question to all three companies.
This also explains why this rally may continue but will not be linear. When industry supply-demand is still tight, share prices will still switch focus among monthly data, quarterly reports, customer projects, and material news. Investors need to follow the evidence rather than treat one target-price upgrade as a static answer.
Valuation repricing will also proceed in three steps. The first step is theme repricing, in which the market acknowledges that ABF and BT substrates are not ordinary components, but bottleneck links in the AI hardware chain. This stage mainly raises the multiple, and share prices react most strongly to supply-demand news and target-price upgrades.
The second step is earnings repricing, in which the market starts to require companies to turn bottleneck position into gross margin and EPS. This stage no longer rewards all companies in the same chain. Only companies that can show monthly earnings, quarterly gross margin, and order quality continue to receive a premium. Nan Ya PCB and Kinsus are easier to verify quickly at this step.
The third step is quality repricing, in which the market distinguishes short-term price hikes from long-term platforms. If price hikes are only short-term spot prices, the multiple will fall. If price hikes come from customer certification, material gates, and long-term supply position, the multiple can hold. Unimicron’s long-term value is mainly reassessed at this third step.
These three steps are not a one-way ascent; they can also reverse. If monthly data miss expectations, theme repricing cools first. If quarterly gross margin cannot keep up, earnings repricing stops. If customer and material supply alternatives emerge, quality repricing is rewritten. Risk management for substrate stocks needs to be broken down by these three steps, rather than waiting for the full cycle to reverse.
Therefore, if share prices pull back in coming quarters, one cannot immediately judge that the logic has failed. First distinguish whether the pullback comes from theme cooling, earnings disappointment, or doubts about long-term quality. Theme cooling can usually be repaired by later data. Earnings disappointment requires the next round of gross-margin proof. Long-term quality doubts are harder to repair because they shake the foundation of the high multiple.
If Nan Ya PCB pulls back only because of profit-taking after a target-price upgrade, but monthly gross margin remains strong, the logic still holds. If the pullback comes with poor price transmission, elasticity assumptions should be lowered. If Kinsus pulls back only because the market worries the move has been too fast, but ABF/BT utilization keeps improving, it may be a reconfirmation point. If Vera CPU or BT spillover misses expectations, operating leverage must be reassessed.
Unimicron’s pullback requires even more attention to the cause. If short-term capital rotates into Nan Ya PCB and Kinsus, that does not mean the long-term platform logic has deteriorated. If the market finds that long-term agreements, HDI, or T-glass resources do not bring gross-margin uplift, that is the real problem. Its verification is slower, so judgment should be more patient, but the requirement for profitability should not be relaxed.
This rhythm helps avoid a common mistake: attributing all upside to the industry shortage and all downside to the end of the cycle. The reality is more nuanced. The substrate trade will switch back and forth among theme, earnings, and quality. The more clearly investment judgment separates these three layers, the less likely it is to be led by target prices and short-term volatility.
What would strengthen the view? Not one more optimistic target price, but three types of evidence appearing at the same time. First, substrate makers maintain shipment cadence after price increases, showing customers are not obviously delaying orders because of higher prices. Second, gross-margin improvement gets through single-month volatility, showing product mix and material constraints jointly support margins. Third, company language on follow-up projects shifts from “strong demand” to “tight delivery” and “fully booked capacity,” showing the supply side remains the issue customers care about most.
What would weaken the view? Again, not a single bad headline, but evidence starting to conflict. Strong revenue but weak gross margin means price was not retained. Strong gross margin but weak revenue means only mix improved. Companies saying demand is strong while peer utilization falls suggests orders may be concentrated in a few projects. Materials remain tight but customers no longer accept price hikes means bargaining power is returning to customers. The real inflection point is often not one data point, but multiple pieces of evidence no longer moving in the same direction.
The biggest risk for substrate stocks is not that the market does not know ABF, but that it only knows ABF. BT spillover, T-glass constraints, customer certification, long-term contract repricing, and monthly earnings are the full puzzle of this margin trade. Looking at only one piece can overestimate near-term elasticity and underestimate long-term platform value.
A steadier tracking approach is to put every company data point back into this puzzle. Companies that can fill in price, utilization, and gross margin at the same time deserve to keep enjoying high valuations. Companies that can add only narrative but not profit will ultimately be repriced by the market.
This is the largest value of Citi’s report: it does not only tell the market “ABF is still short,” but breaks the shortage into price, utilization, materials, customers, and gross margin. As long as investors track this chain, they will not be led around by a single target-price upgrade, nor will they confuse the time dimensions between near-term catalysts and long-term resources.
11. Conclusion: This Is Not “ABF Is Still Short,” but “How Does the Shortage Enter the Income Statement”
Citi’s report pushes the ABF/BT substrate trade one step forward. The industry shortage and T-glass constraints are already old consensus. The new question is whether the income statement can carry them. Nan Ya PCB represents spot pricing and switch-chip elasticity. Kinsus represents the operating leverage of Vera CPU and BT spillover. Unimicron represents high-end ABF scale, T-glass resources, and long-term customer relationships.
All three companies have higher target prices, but they are not the same money. Nan Ya PCB’s money comes from price. Kinsus’s money comes from utilization and dual-line leverage. Unimicron’s money comes from resources, scale, and long-term supply position. In the short term, Nan Ya PCB and Kinsus are sharper. In the long term, Unimicron looks more like the anchor of high-end ABF.
The key takeaway from this report should not be the target-price numbers, but a verification table: 3Q26/4Q26 ABF prices, BT utilization, T-glass lead times, monthly unaudited gross margin, and continued 2027E EPS upgrades. As long as these numbers keep holding together, ABF/BT substrates remain one of the AI hardware-chain links most likely to turn a bottleneck into profit. Once these numbers break, 30x 2027E EPS will reprice faster than the industry narrative.