
目录
Executive Summary
1. The Value of the August Update: One AI Cycle, but Profits Are Concentrating in Fewer Segments
2. The Memory Outlook Keeps Rising, but a 49% Share of Capital Spending Raises New Questions
3. Long-Term Agreements Turn “Peak Profits” into “Lockable Profits”
4. HBM Downsizing Narrows the Gap, but the Shortage Is Not Over
5. ASICs Take Over Incremental Growth; Lower Capacity per Chip Does Not Reduce System Demand
6. The TCB Market Nearly Triples in Three Years, Yet Hanmi Semiconductor May Still Underperform
7. MLCCs and PCBs Absorb Shortage Spillover; Unit Growth Understates Earnings Leverage
8. The Apple Supply Chain Paradox: No Growth from 250 Million Units, but Costs Keep Rising
9. Company Ranking: Contracts and Market Share First, Target-Price Upside Second
10. Six Gates Will Determine Whether a Structural Rerating Materializes over the Next Four Quarters
Conclusion: Asian Technology’s Decisive Factor Has Shifted from Shortages to Securing Profits
This may look like a familiar Asian technology update, but the underlying dynamics have changed: lower HBM content has not derailed the memory upcycle, earnings visibility is replacing the shortage narrative, and consumer electronics has moved to the opposite end of the cycle.
Executive Summary
J.P. Morgan has raised its estimates for the global memory market to approximately $1.4 trillion in 2027 and $1.8 trillion in 2028. More importantly, multiyear supply agreements, price floors, prepayments, and shareholder returns are improving earnings visibility, allowing memory valuations to move beyond a framework based solely on peak-cycle profits.
Following cuts to HBM capacity assumptions per GPU, the CoWoS-adjusted supply-demand deficit for 2026–2028 narrowed from the May estimates of 20%, 26%, and 36% to 15%, 14%, and 22%. The shortage is less severe, but HBM bit demand is still expected to grow at a CAGR of approximately 74% from 2025 to 2028, as ASIC demand and migration to next-generation HBM offset lower content per GPU.
Expansion in HBM back-end capacity is expected to grow the TCB market from approximately $383 million in 2025 to approximately $1.053 billion in 2028. Returns from equipment stocks will depend on customer share, order timing, and valuation. Hanmi Semiconductor is assumed to have a 0% share at Samsung Electronics, limiting its ability to replicate the overall growth of the HBM market.
MLCCs are becoming the next bottleneck in high-end hardware. Total demand is projected to rise from 4.593 trillion units in 2025 to 6.898 trillion units in 2030, while AI-server demand increases from 84 billion units to 888 billion units. High-end specifications are consuming capacity faster than unit volumes are growing, positioning suppliers such as Samsung Electro-Mechanics to benefit from a richer product mix and higher pricing.
The Apple supply chain is moving in the opposite direction. The 2026 iPhone production plan stands at approximately 250 million units, flat year over year, but 4Q production is expected to decline 10% year over year. The current plan could still be revised downward if new models are priced too aggressively. Flat overall volumes will not offset component inflation, end-market price elasticity, and shifting supplier shares.
1. The Value of the August Update: One AI Cycle, but Profits Are Concentrating in Fewer Segments
Two months ago, the central question for Asian technology was whether AI hardware value could spread beyond GPUs and HBM into CPUs, enterprise SSDs, PCBs, ABF substrates, and MLCCs. Our previous in-depth analysis provided the answer: the spillover is underway, but not every segment deserves the same valuation.
The August update takes this divergence one step further. Investors remain bullish on memory fundamentals but are increasingly concerned that the stocks may become a “valuation trap.” Cloud service providers and AI application companies are attracting more attention, while the duration and quality of hardware earnings are being questioned. The shortage narrative has also expanded from memory into MLCCs and substrates, while smartphone supply chains remain out of favor.
These positioning shifts show that the market has accepted the strength of AI-infrastructure demand; the debate has moved to who captures the profits. Only companies that secure long-term agreements, control high-end capacity, manage customer qualification, and convert earnings into cash flow can capitalize 2027–2028 profits into present valuations. Companies with thematic exposure but no protected market share or order visibility may still face multiple compression despite operating in the right industry.
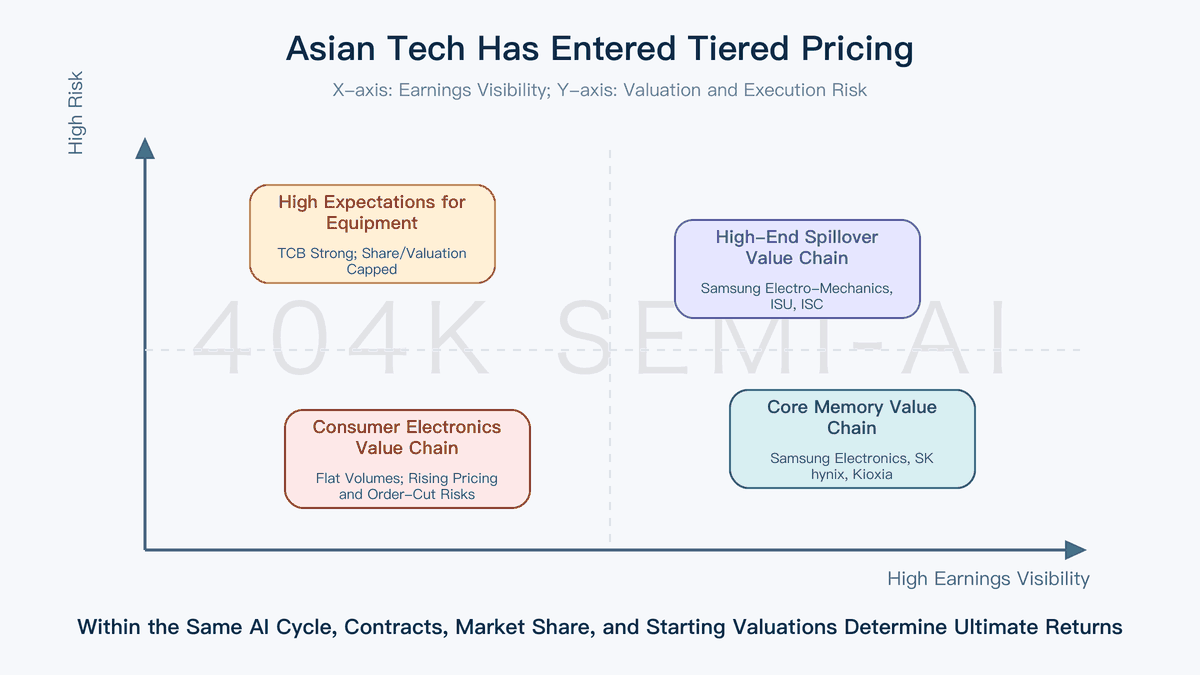
The industry now falls into four tiers. The first is the core memory chain, represented by Samsung Electronics, SK hynix, and Kioxia, where pricing, long-term agreements, and cash flow can all be directly verified. The second is the high-end spillover chain, represented by Samsung Electro-Mechanics, ISU Petasys, and ISC, where earnings leverage is strong but realization depends on customer share and capacity ramp-up. The third comprises high-expectation segments such as TCB equipment: industry growth is clear, but company-specific market share and valuation may dilute returns. The fourth is consumer electronics, where aggregate volumes remain under pressure and only companies gaining share or increasing content per device can offset end-market risk.
2. The Memory Outlook Keeps Rising, but a 49% Share of Capital Spending Raises New Questions
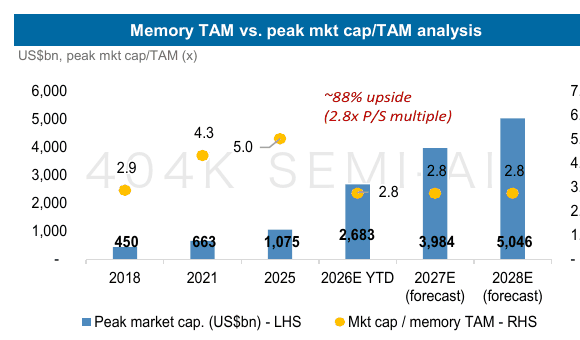
J.P. Morgan expects the global memory market to reach approximately $1.4 trillion in 2027 and $1.8 trillion in 2028. Applying the historical market-cap-to-market-size multiples of Samsung Electronics, SK hynix, and Micron, the firm uses a 2.8x price-to-sales ratio in its 2028 scenario to derive a peak market-cap benchmark of approximately $5.05 trillion. This outcome is highly sensitive to ASPs, margins, and valuation multiples. It should be treated as an upside scenario, not a definitive target.
The first driver of these upgrades is rising AI-system density. Long-context workloads rapidly increase attention-memory consumption, while greater inference concurrency, agentic tasks, and enterprise workflows require more context, caching, and data access. GPUs use HBM, host CPUs require server DRAM, and inference data layers consume enterprise SSDs. Memory demand has expanded from a single premium category into a system-wide requirement.
The second driver is supply allocation. HBM consumes more advanced DRAM wafer capacity, crowding out conventional non-HBM production, while NAND suppliers continue to exercise relative discipline on capital spending. New fabs are large, but cleanrooms, equipment installation, yield ramp-up, and customer qualification all take time. Planned nameplate capacity cannot immediately become qualified bit supply.
The institutional model highlights a ratio that warrants caution: memory’s share of cloud service providers’ hardware capital expenditure rises from 8% in 2025 to 31% in 2026 and 49% in 2027, reaching 60% in 2028. Much of the increase is price-driven. Memory operating margins rise to 77% in 2026–2027, well above the model’s approximately 38% for cloud service providers, approximately 55% for foundries, and approximately 63%–64% for AI semiconductors.
When one upstream component absorbs nearly half of the hardware budget, customers will accelerate architectural optimization, content reductions, and supplier diversification. The 49% figure validates memory’s scarcity value but also signals demand-destruction risk. Memory remains the largest profit pool in this cycle, but valuations must answer two questions: how long can pricing hold, and how much are customers willing to pay for supply certainty?
3. Long-Term Agreements Turn “Peak Profits” into “Lockable Profits”
The most consequential change is the adoption of long-term agreements. Micron has disclosed several types of long-term supply arrangements, with portions of DRAM and NAND volumes covered by multiyear contracts that include volume commitments, price floors, and cash commitments. Samsung Electronics, SK hynix, US NAND suppliers, and Kioxia are also pursuing multiyear contracts, rolling negotiations, prepayments, or financial guarantees.
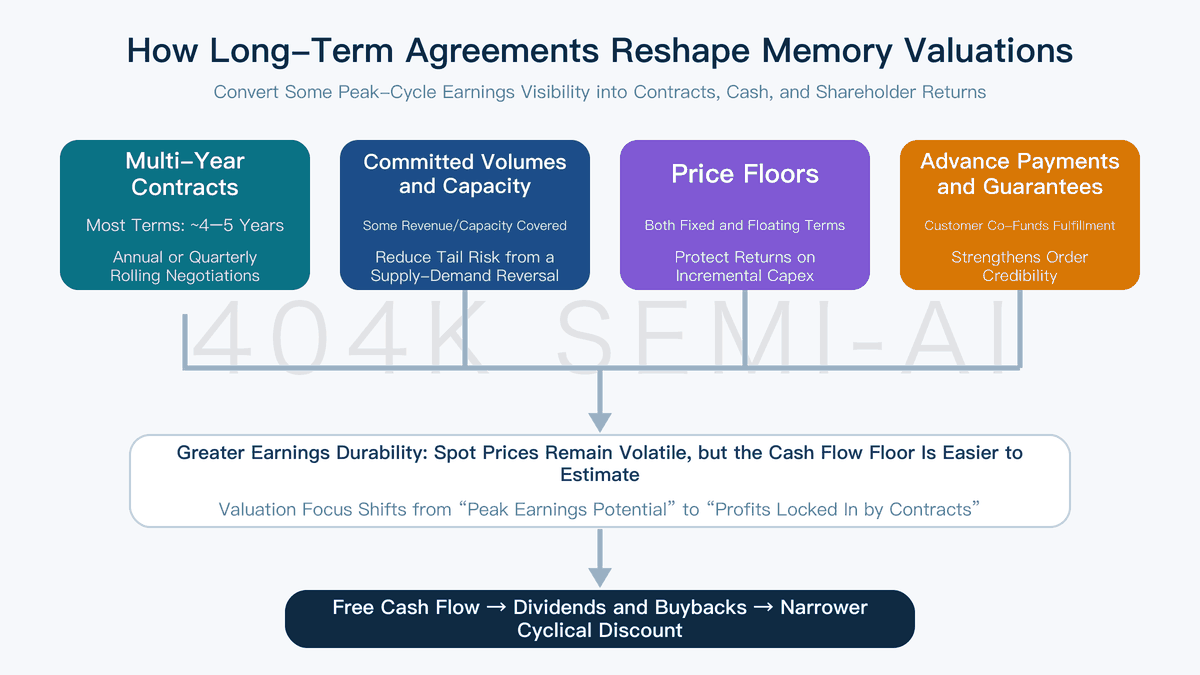
These provisions cannot eliminate the cycle. Product generations will change, annual pricing will still need to be renegotiated, and customers will adjust their procurement mix. What they change is the downside boundary: suppliers gain more stable volume commitments, customers secure capacity and delivery, and returns on incremental capital expenditure become easier to forecast. When spot prices decline, contract floors and prepayments can also cushion cash-flow volatility.
The quality of a long-term agreement depends on four details. First is coverage: a large contracted volume does not necessarily mean a high share of revenue is protected. Second is the pricing mechanism: fixed prices, floating prices, ceilings, and floors provide different levels of protection. Third is enforceability: cash prepayments, deposits, and take-or-pay provisions carry more weight than nonbinding expressions of intent. Fourth is customer concentration: excessive dependence on a few cloud service providers converts industry risk into single-customer risk.
Shareholder returns make this improvement easier to incorporate into valuations. Institutional estimates put 2027 shareholder returns at approximately 8% for Samsung Electronics common shares, approximately 15% for SK hynix, and approximately 8% for Kioxia. Under a uniform assumption that 50% of free cash flow is distributed in 2029, even if 2029 earnings fall 70% from 2028, cumulative shareholder returns for 2027–2029 would still reach approximately 30%, 27%, and 31%, respectively. These are institutional scenarios, and actual buybacks, dividends, and earnings trajectories may differ. Nevertheless, they establish a clear test: earnings durability must ultimately translate into free cash flow and per-share returns.
4. HBM Downsizing Narrows the Gap, but the Shortage Is Not Over
HBM is the most easily misread part of the August update. HBM capacity per next-generation GPU has been reduced: Rubin Ultra’s HBM4E configuration has shifted from more and taller stacks to a lower-capacity combination, while Rubin’s HBM4 configuration has also been scaled back. Institutions have therefore cut their estimated supply-demand deficits for 2026–2028 from 20%, 26%, and 36% in May to 15%, 14%, and 22%.
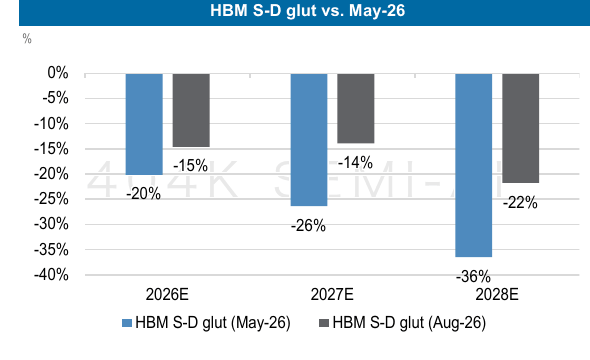
A narrower deficit means a flatter shortage-premium curve, not an easing of supply. Institutional models put 2026 HBM procurement demand at approximately 4,451 million GB, versus CoWoS-adjusted supply of approximately 3,802 million GB. In 2027, demand reaches approximately 7,205 million GB against supply of approximately 6,205 million GB; in 2028, demand rises to approximately 11,449 million GB versus supply of approximately 8,960 million GB. The absolute shortfall therefore widens by 2028.
The generational mix matters more than industry-wide volume. HBM3E and earlier products gradually mature in 2027–2028, while the real bottleneck shifts to HBM4, HBM4E, and HBM5. Institutions estimate that loss-adjusted HBM4E supply will be approximately 9,092 million GB in 2027, versus procurement demand of approximately 12,537 million GB, implying a 27% deficit. The assumed HBM5 supply deficit reaches 58% in 2028. Next-generation products require taller stacks, more complex packaging, and stricter qualification, so incremental wafer capacity cannot immediately replace qualified supply.
The pricing model reflects this transition. Blended HBM ASP rises from US$1.9/GB in 2026 to US$2.8/GB in 2027 and US$3.4/GB in 2028, representing approximately 42% year-on-year growth in 2027. This assumes a strong next-generation product mix and persistent supply constraints. Qualification delays, customer configuration changes, or a concentrated release of new capacity would result in weaker ASP growth than the model projects.
5. ASICs Take Over Incremental Growth; Lower Capacity per Chip Does Not Reduce System Demand
Despite lower HBM capacity per GPU, total HBM demand still rises from 2,033 million GB in 2025 to 10,751 million GB in 2028, an approximately 4.3-fold increase over three years. J.P. Morgan estimates a roughly 74% CAGR in bit demand from 2025 to 2028. Unit volumes, chip types, and product-generation shifts collectively offset the capacity reductions.
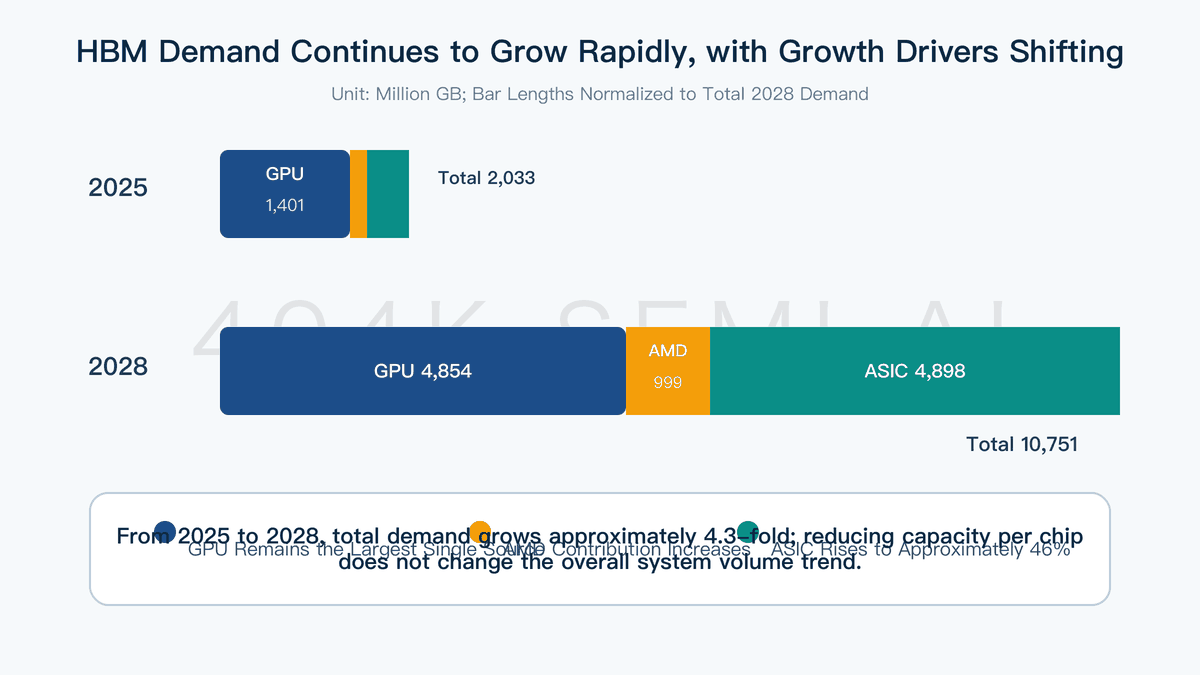
In 2025, Nvidia GPUs account for approximately 1,401 million GB of HBM demand, or about 69% of the industry total, while ASICs account for approximately 455 million GB, or 22%. By 2028, Nvidia GPU demand reaches approximately 4,854 million GB and ASIC demand approximately 4,898 million GB, lifting the ASIC share to about 46%. Rising volumes of Google TPUs, Amazon Trainium, Microsoft MAIA, and Meta MTIA mean that HBM demand is no longer determined by a single GPU roadmap.
ASICs have two implications. First, a more fragmented customer and product mix requires HBM suppliers to support different capacities, packaging formats, and qualification standards simultaneously, increasing the complexity of qualified capacity. Second, custom silicon places greater emphasis on system cost, encouraging customers to eliminate overprovisioning more aggressively. HBM bit demand is therefore broader-based, but also more exposed to architectural optimization.
At the market-share level, institutions expect SK hynix’s share of HBM spending to decline from 46% in 2026 to approximately 42% in 2027–2028. Samsung Electronics’ share is projected to rise from 34% to 37% and 38%, while Micron remains at 20%–21%. Samsung Electronics’ rerating depends on HBM4 qualification, yields, and actual customer share; SK hynix retains advantages in leading-edge products and customer relationships; and Kioxia offers more direct exposure to NAND and enterprise SSD value. The three companies have distinct paths to upside and should not be treated as a generic “memory upcycle” trade.
6. The TCB Market Nearly Triples in Three Years, Yet Hanmi Semiconductor May Still Underperform
More HBM stack layers, expanded back-end capacity, and equipment upgrades are driving TCB demand. Institutions expect the HBM TCB market to grow from US$383 million in 2025 to US$609 million in 2026, US$966 million in 2027, and US$1.053 billion in 2028. Corresponding equipment volumes rise from 177 units in 2025 to 398 units in 2027 and 415 units in 2028.
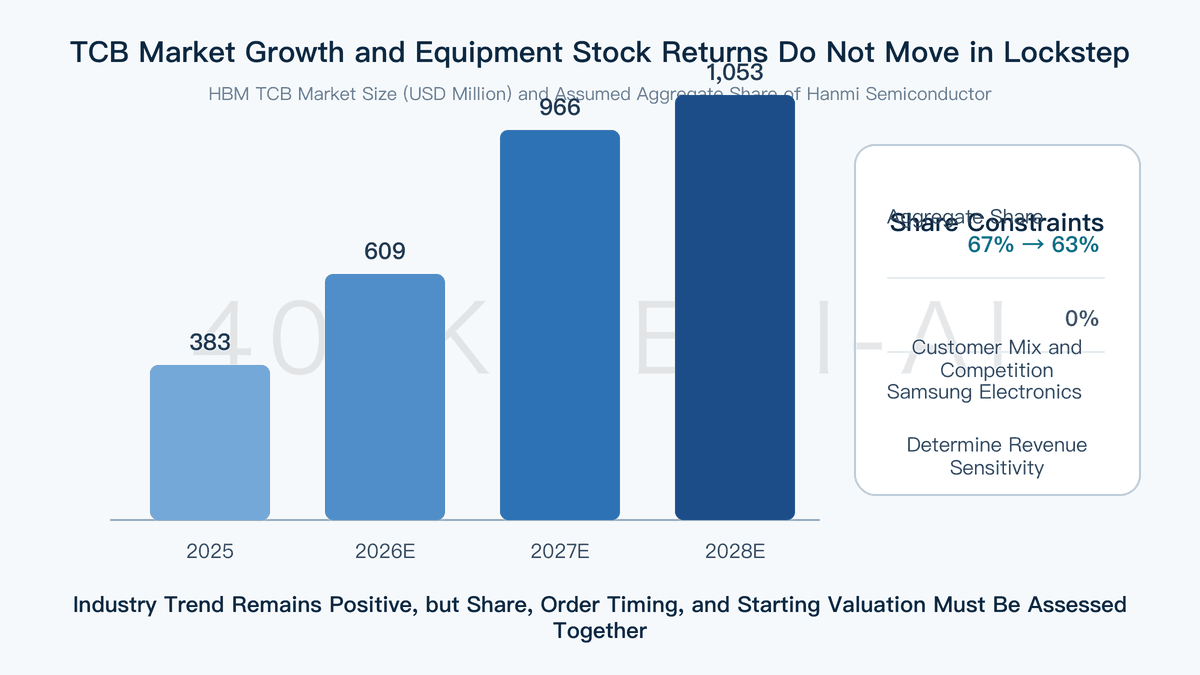
Market growth does not automatically translate into comparable revenue growth for Hanmi Semiconductor. Institutions assume that the company retains a high share at Micron and certain regional customers but has a 0% share at Samsung Electronics. Its blended share is projected to decline from 67% in 2025 to 61% in 2026–2027 before recovering to 63% in 2028. Equipment revenue also depends on order recognition, delivery timing, and technology migration, making quarterly volatility materially higher than that of HBM bit demand.
Valuation further compresses the risk-reward. The report shows that Hanmi Semiconductor has traded at an average valuation premium of approximately 77% to back-end equipment peers since the beginning of 2026, versus an average premium of approximately 43% since the second half of 2023. J.P. Morgan maintains an Underweight rating and a KRW200,000 price target, implying 4% downside from the report’s reference price. This illustrates how exposure to the right theme, an expanding market, and an expensive stock can all coexist.
The TCB value chain should be tracked in this order: customer orders, equipment share, delivery and acceptance, revenue recognition, and valuation. Extrapolating equipment-company earnings solely from HBM back-end capacity expansion risks overlooking new competitors, customers’ in-house solutions, and the impact of hybrid bonding on the product cycle.
7. MLCCs and PCBs Absorb Shortage Spillover; Unit Growth Understates Earnings Leverage
Total MLCC demand is expected to rise from 4.593 trillion units in 2025 to 5.688 trillion units in 2028 and 6.898 trillion units in 2030. While the overall CAGR is not exceptional, the mix is changing rapidly: automotive, server, and humanoid-robot applications collectively increase from 17.5% of demand in 2025 to 35.5% in 2030, while their share of occupied supply capacity rises from 41.2% to 95.8%.
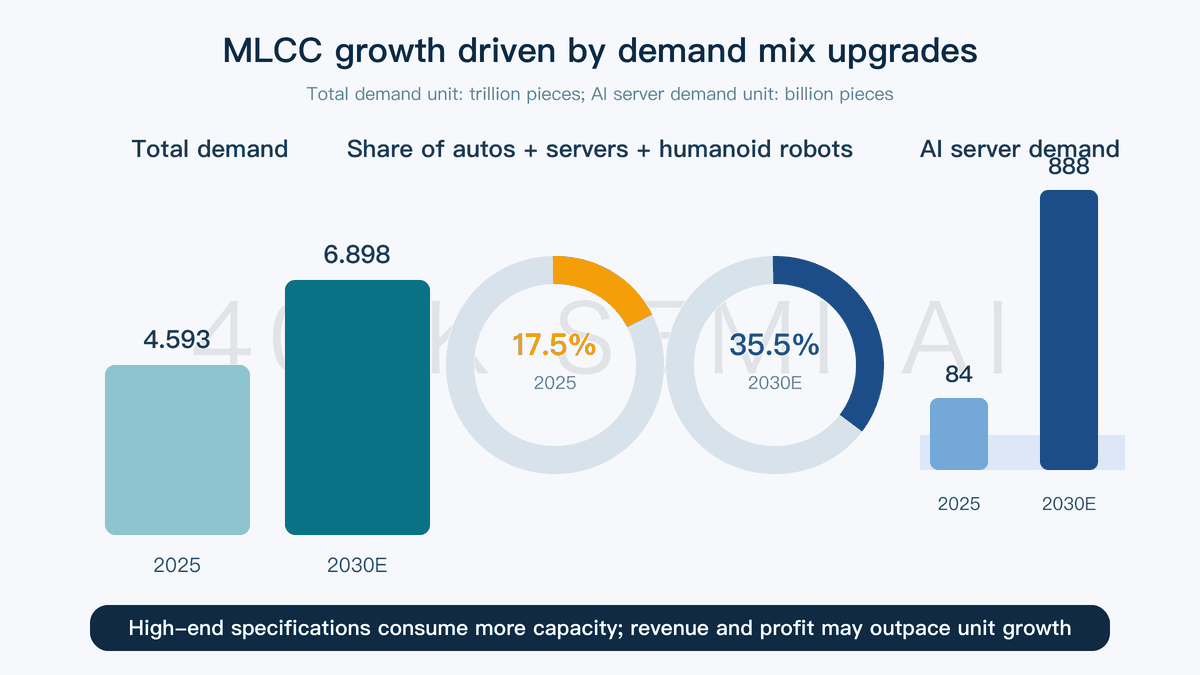
AI-server MLCC demand rises from 84 billion units in 2025 to 487 billion units in 2028 and 888 billion units in 2030, lifting servers’ share of total industry demand from 3.2% to 15.6%. High-end MLCCs require higher capacitance, smaller form factors, greater heat resistance and reliability, as well as customer qualification. Their share of capacity consumption exceeds their unit-volume share, so mix improvement should drive revenue and operating profit growth faster than total industry unit growth.
Our previous MLCC deep dive discussed the divergence between high-end specifications and mainstream consumer products. The August data reinforce this point: conventional smartphone MLCC demand edges up from only 1.254 trillion units in 2025 to 1.265 trillion units in 2030, while AI-server demand grows more than 9-fold. Samsung Electro-Mechanics, Murata Manufacturing, and other suppliers should therefore be assessed on their AI-server and automotive product mix, utilization rates, and ASPs—not merely on industry-average pricing.
PCBs and substrates follow a similar logic. ISU Petasys supplies high-layer-count MLBs for 800G switches, TPUs, and other AI accelerators, with some products requiring more than 40 layers. On a standalone basis, Google’s share of its revenue rose from 39% in 2021 to 79% in 2025 and reached 80% in 1Q26. Customer concentration provides order visibility but also amplifies exposure to the timing of a single platform. If new capacity ramps on schedule, margins in the networking and data-center business should rise; any volatility in yields or customer transitions would magnify valuation downside.
8. The Apple Supply Chain Paradox: No Growth from 250 Million Units, but Costs Keep Rising
The 2026 iPhone EMS production plan is approximately 250 million units, flat with 2025. Quarterly production is projected at approximately 58 million, 55 million, 52 million, and 85 million units. The first 3 quarters represent year-over-year growth of 3%, 16%, and 0%, respectively, followed by a 10% decline in Q4. While the full-year figure appears stable, the quarterly cadence already points to pressure on the new-product cycle.
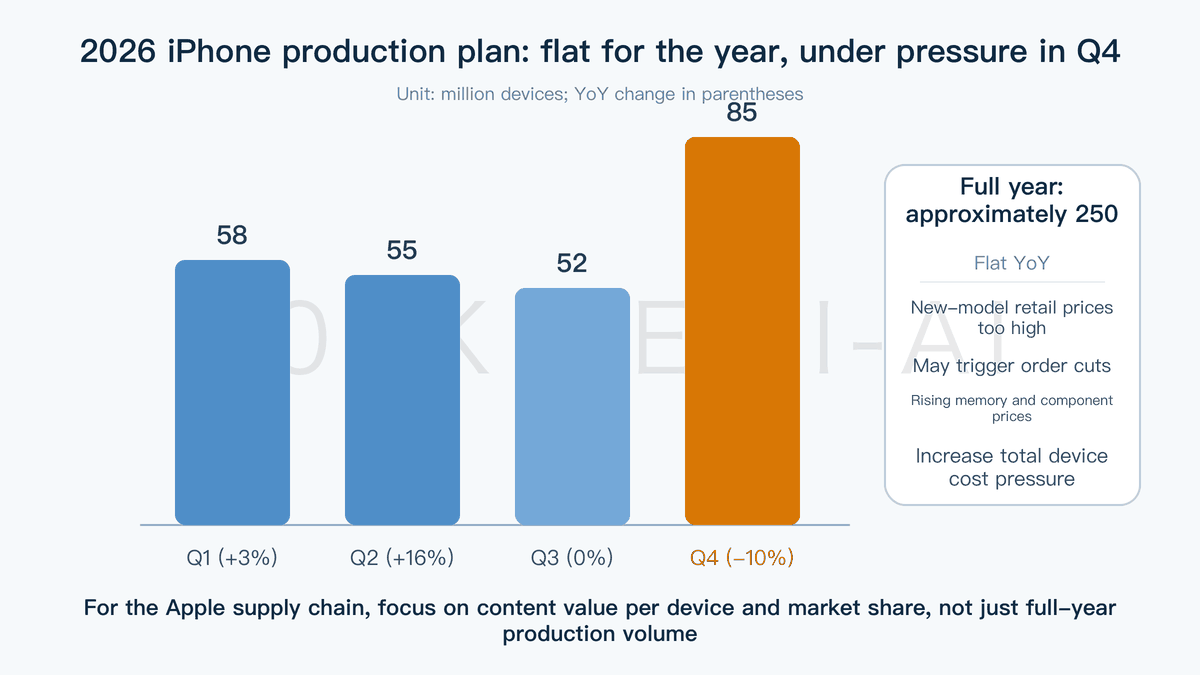
Component inflation compounds the risk. Rising prices for memory, advanced packaging, and high-end passive components will increase the device BOM. Apple can absorb the increase by raising retail prices, squeezing suppliers, or adjusting product configurations. Excessive retail pricing would weaken end demand; supplier price cuts would shift margin pressure upstream; and configuration changes would alter content value per device. The report explicitly warns that the current EMS plan could be revised downward if new iPhones launch at excessively high retail prices.
The model mix offers selective opportunities. The 2026 new-model plan includes approximately 8 million foldable iPhones, 35 million iPhone 18 Pro units, and 45 million iPhone 18 Pro Max units. Premium models support higher content value for cameras, optics, and other high-specification components. LG Innotek’s Overweight rating reflects the ability of its optical business to capture mix benefits despite flat aggregate volumes. LG Display is rated Neutral, indicating that its panel business remains constrained by pricing, market share, and capital intensity.
Three metrics must be assessed together across the Apple supply chain: total production, model mix, and supplier share. Profits can grow only if gains in premium mix and market share outweigh volume and cost pressures. Interpreting 250 million units as evidence of stable industry conditions would overlook both the Q4 decline and pricing risk.
9. Company Ranking: Contracts and Market Share First, Target-Price Upside Second
Based on prices as of August 24, 2026, J.P. Morgan’s target prices imply 55% upside for Samsung Electronics to KRW400,000, 64% for SK hynix to KRW2.75 million, and 155% for Kioxia to JPY130,000. The implied upside for Samsung Electro-Mechanics, ISU Petasys, and ISC is 83%, 65%, and 40%, respectively. These figures are derived from institutional forecasts and valuation models and do not represent guaranteed returns.
Earnings Drivers and Validation Priorities Across Four Asian Technology Asset Categories
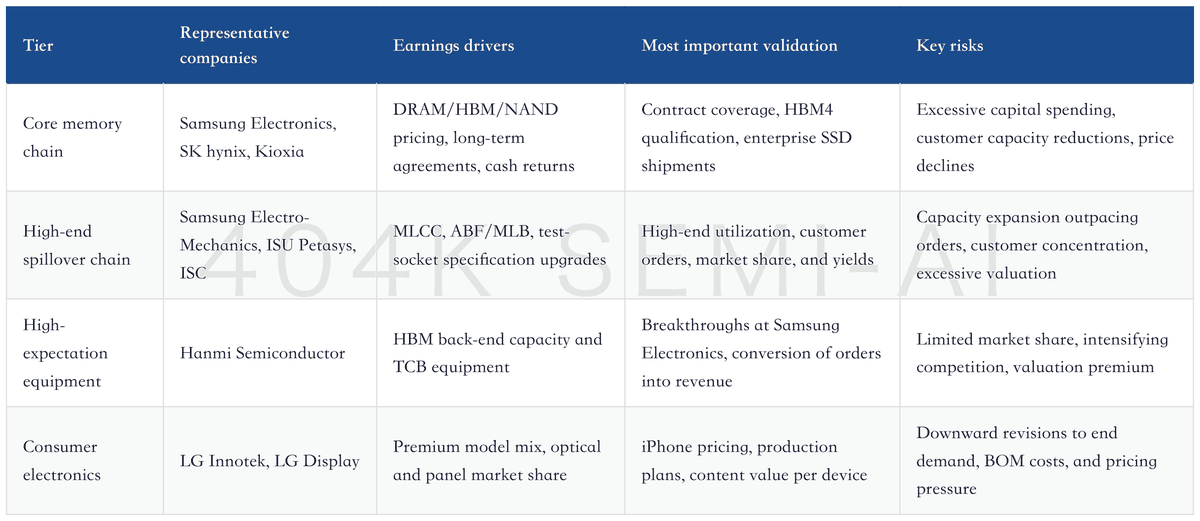
The core memory chain benefits from directly observable indicators. DRAM and NAND pricing, HBM qualification, long-term agreements, capital spending, and cash returns can all be tracked quarterly. The high-end spillover chain may offer greater earnings leverage, but its data depend more heavily on customer orders and capacity ramp-ups. High-expectation equipment names must offset elevated valuations through market-share gains. Consumer-electronics exposure should be selected based on company-specific capabilities, as aggregate industry volumes provide insufficient protection.
10. Six Gates Will Determine Whether a Structural Rerating Materializes over the Next Four Quarters
The first gate is cloud capital expenditure. The report argues that memory stocks will require another 1–2 rounds of upward capex revisions by cloud service providers to sustain their performance. Once budgets rise, data centers, power infrastructure, networks, and servers must come online on schedule. If capex remains only a plan, supply-chain orders will be delayed.
The second gate is long-term agreements. Higher contract coverage, price floors, and prepayments indicate that customers are willing to pay for supply certainty. Earnings durability should be reassessed downward if contracts are frequently renegotiated, price protection weakens, or customers defer deliveries.
The third gate is HBM4 qualification. Actual shipments must validate whether Samsung Electronics can regain market share, SK hynix can maintain yields and its lead, and Micron can broaden customer coverage. Delays to next-generation products would push out both ASPs and equipment demand.
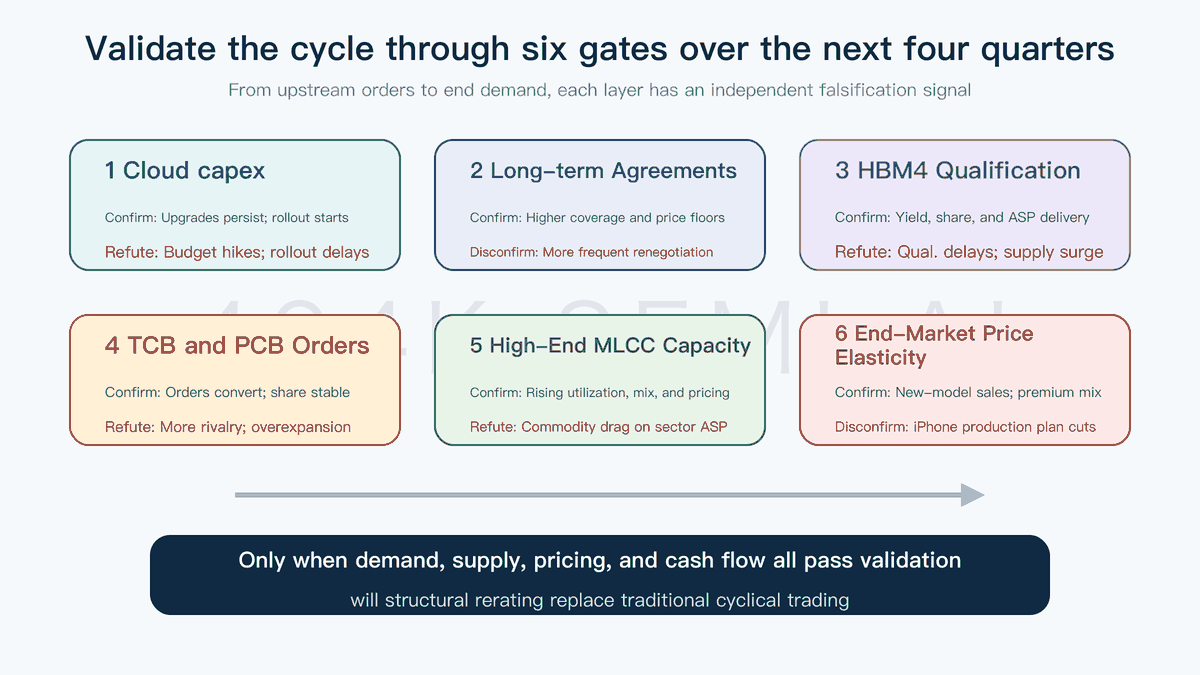
The fourth gate is TCB and PCB orders. Equipment and high-layer-count PCB orders must translate into customer acceptance, revenue, and cash flow; conversion rates will be affected by customer concentration, competition, and capacity expansion. The fifth gate is high-end MLCC capacity: utilization, product mix, and ASP must improve in tandem, and pricing for mainstream consumer-electronics MLCCs must not obscure trends in premium categories. The sixth gate is end-market price elasticity. Retail pricing, sales volumes, and production revisions for the next-generation iPhone will test whether consumers can absorb upstream price increases.
A structural rerating would require broader coverage under long-term memory agreements, an on-schedule HBM4 ramp, MLCC and PCB orders flowing into earnings, and only selective rather than systemic order cuts across the Apple supply chain. A return to cyclical trading would more likely feature stalled upward capex revisions, continued narrowing of the HBM supply gap, customer pricing pressure, faster capacity expansion across spillover beneficiaries, and weaker consumer-electronics demand. The divergence between these scenarios will first appear in contracts, orders, utilization, and cash flow before reaching year-over-year revenue growth.
Conclusion: Asian Technology’s Decisive Factor Has Shifted from Shortages to Securing Profits
The August Asian technology outlook does not overturn the AI hardware upcycle. It does, however, temper the market’s most optimistic assumptions: lower HBM content per GPU is easing shortage intensity, while memory’s rapidly rising share of cloud capital expenditure will also prompt customer optimization and demand destruction. Shortages alone are no longer sufficient to support continued rerating across all assets.
The more valuable signal is profit visibility. Long-term agreements, price floors, prepayments, and shareholder returns improve the visibility of memory cash flows; ASICs and next-generation HBM sustain strong bit-demand growth; and high-end MLCCs and PCBs capture specification upgrades and supply constraints. Samsung Electronics, SK hynix, Kioxia, Samsung Electro-Mechanics, and ISU Petasys offer distinct exposure to market-share recovery, product leadership, enterprise SSDs, high-end passive components, and high-layer-count PCBs, respectively.
The Apple supply chain reminds investors that the AI hardware boom does not extend across every end market. Full-year iPhone production is projected to remain flat, yet Q4 volumes are expected to decline 10% year over year, while component inflation continues to test consumer pricing. Consumer-electronics profits can overcome cost pressure only if total volumes, product mix, and supplier share improve together.
The research agenda should therefore change. Ask less often whether shortages persist and focus more on contract coverage, price floors, qualification yields, customer share, utilization, and free cash flow. The companies that can lock demand into contracts, convert those contracts into cash, and return that cash to shareholders will retain a genuine structural premium as Asian technology assets become increasingly differentiated.
Related Reading
Rubin Ultra HBM Capacity Cut to 192GB: Supply and Power Constraints Drive Roadmap Downgrade