
404K Technology Weekly 2026-07-04 — Memory Pricing Power, Compute Assetization, Hardware Bottlenecks Spreading
目录
This Week’s Overall View
U.S. Equity Rankings Over the Past Week
AI/Semiconductor Full Value Chain
AI Models, CSPs, and Data-Center Infrastructure
Memory, Power Semiconductors, and MLCCs
Semiconductor Equipment, Test, and Materials
Optical Communications, Optics, and High-Speed Interconnect
Robotics, Intelligent Driving, and Overseas Applications
Space, Satellites, and Overseas Hard Tech
Cloud Vendors, Internet, and Software
Software, Consumer Electronics, and Smart Vehicles
Power, Macro Rates, and Risk
Next Week’s Watchlist
This week, technology trading entered the attribution phase: the market began asking how AI capex converts into cash flow, and who can capture profits across compute, memory, power, and software tools.
This Week’s Overall View
This week, the AI trade moved from an “expansion narrative” into a “return-on-investment audit.” From Monday to Wednesday, capital continued to spill over into memory, equipment, advanced packaging, MLCCs, optical interconnects, and power. Starting Thursday, Meta Compute triggered a market repricing, pressuring CoreWeave, Nebius, IREN, TeraWulf, Applied Digital, optical communications, and semiconductor equipment together. This pullback looks more like positioning and valuation rebalancing than a demand collapse.
The hardest evidence remains in memory. DRAM, NAND, enterprise SSDs, HBM, and HDDs are all seeing price increases, long-term agreements, capacity signals, and target-price upgrades. Micron, SanDisk, Samsung Electronics, SK Hynix, Seagate, and Western Digital were all repriced this week as part of the AI memory chain. The logic has shifted from “price elasticity” to “customers are willing to lock in supply early.” The two numbers to watch for disconfirmation are whether contract prices fall and whether customers start cutting configurations.
Compute assetization became the second main theme. Amazon raised prices for reserved GPU workloads; Nebius and CoreWeave continued to win long-term contracts; Applied Digital disclosed Polaris Forge capacity delivery; and IREN, TeraWulf, Cipher, and Galaxy Digital were all placed into the AI data-center asset comparison framework. Meta is both procuring and hosting more than 5GW of capacity while exploring external compute sales, showing that platform companies are turning data centers from cost items into rentable assets.
The third theme is the spread of physical bottlenecks. TSMC CoWoS, Samsung Foundry, glass substrates, ABF, CCL, MLCCs, 800V high-voltage DC, power equipment, liquid cooling, CPO, 1.6T switches, and lasers are taking turns becoming constraint points. AI infrastructure has expanded into a construction chain running from wafers, packaging, substrates, interconnects, and power supplies to campus grid connections.
Software is starting to absorb capital after hardware volatility. Palantir, Adobe, Datadog, MongoDB, Cloudflare, Salesforce, ServiceNow, Palo Alto Networks, CrowdStrike, Shopify, and AppLovin share one trait: all can tie AI back to revenue, retention, costs, or ad conversion. The market’s bar for software is also higher: simply talking about AI features is not enough; companies need to prove ARR, remaining performance obligations, net retention, gross margin, and customer expansion.
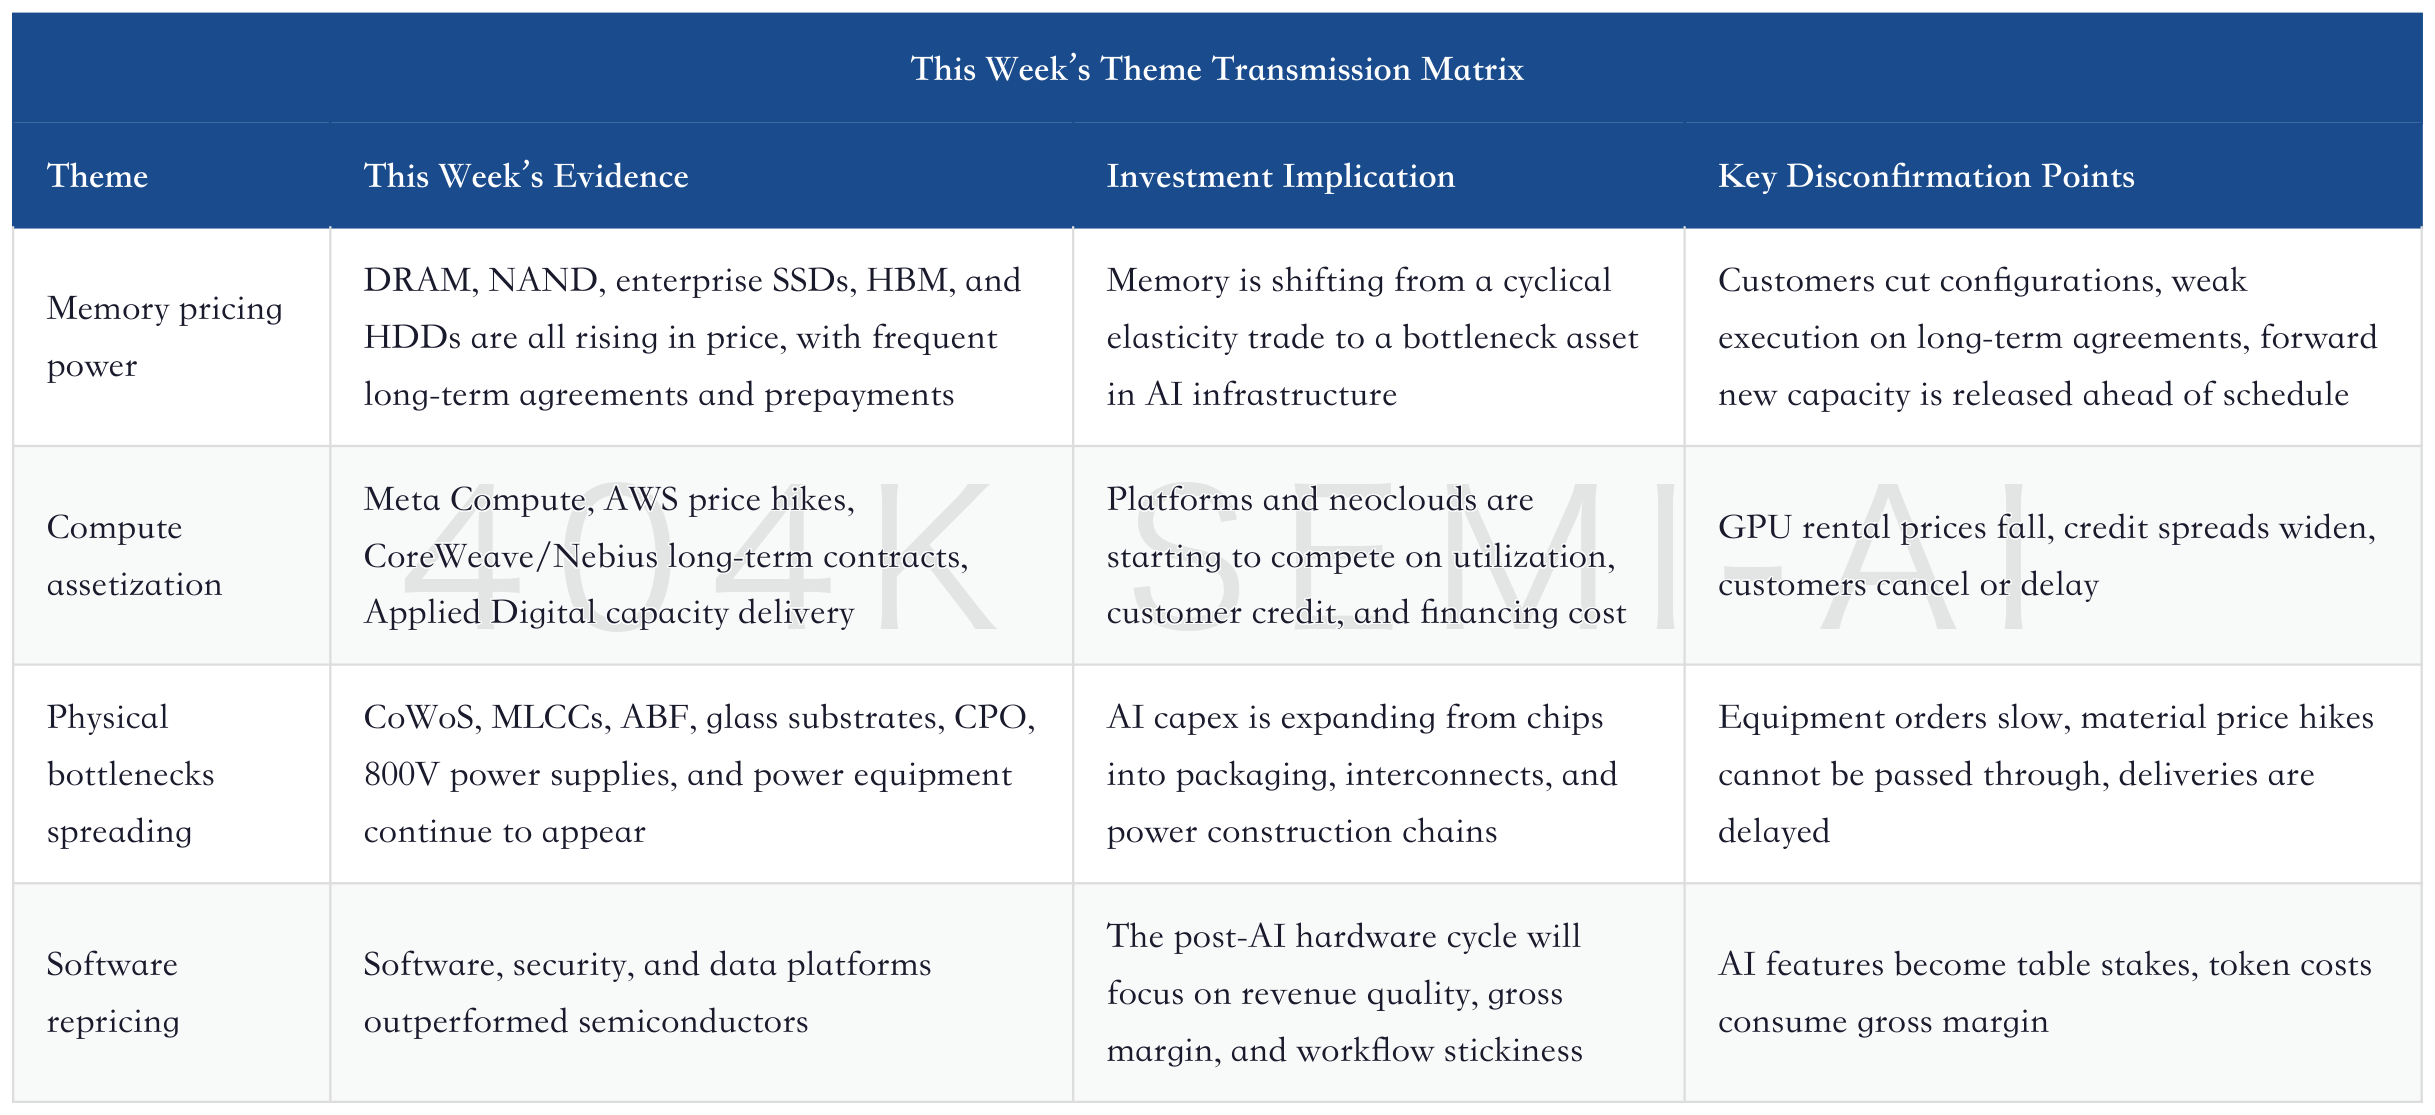
The more practical way to read this week is to look at cash flow by account. Cloud providers need to explain how capex flows back into cloud revenue and advertising efficiency. Neocloud operators need to prove that power and GPUs can be rented out reliably. Memory and materials vendors need to defend pricing. Software companies need to turn AI features into renewals, usage, or margins. As long as these accounts do not all deteriorate at the same time, the AI trade looks more like a move from broad-based Phase 1 gains into a more tiered Phase 2.
This also determines next week’s research order. First, look at segments that can charge directly; then at segments that require upfront investment; finally at segments still stuck at the product-demo stage. If the first two groups continue to deliver orders, long-term contracts, prices, or revenue, they still have fundamental support after the pullback. If the third group cannot show user retention, payment, or delivery numbers, it can only be treated as a long-dated option.
U.S. Equity Rankings Over the Past Week
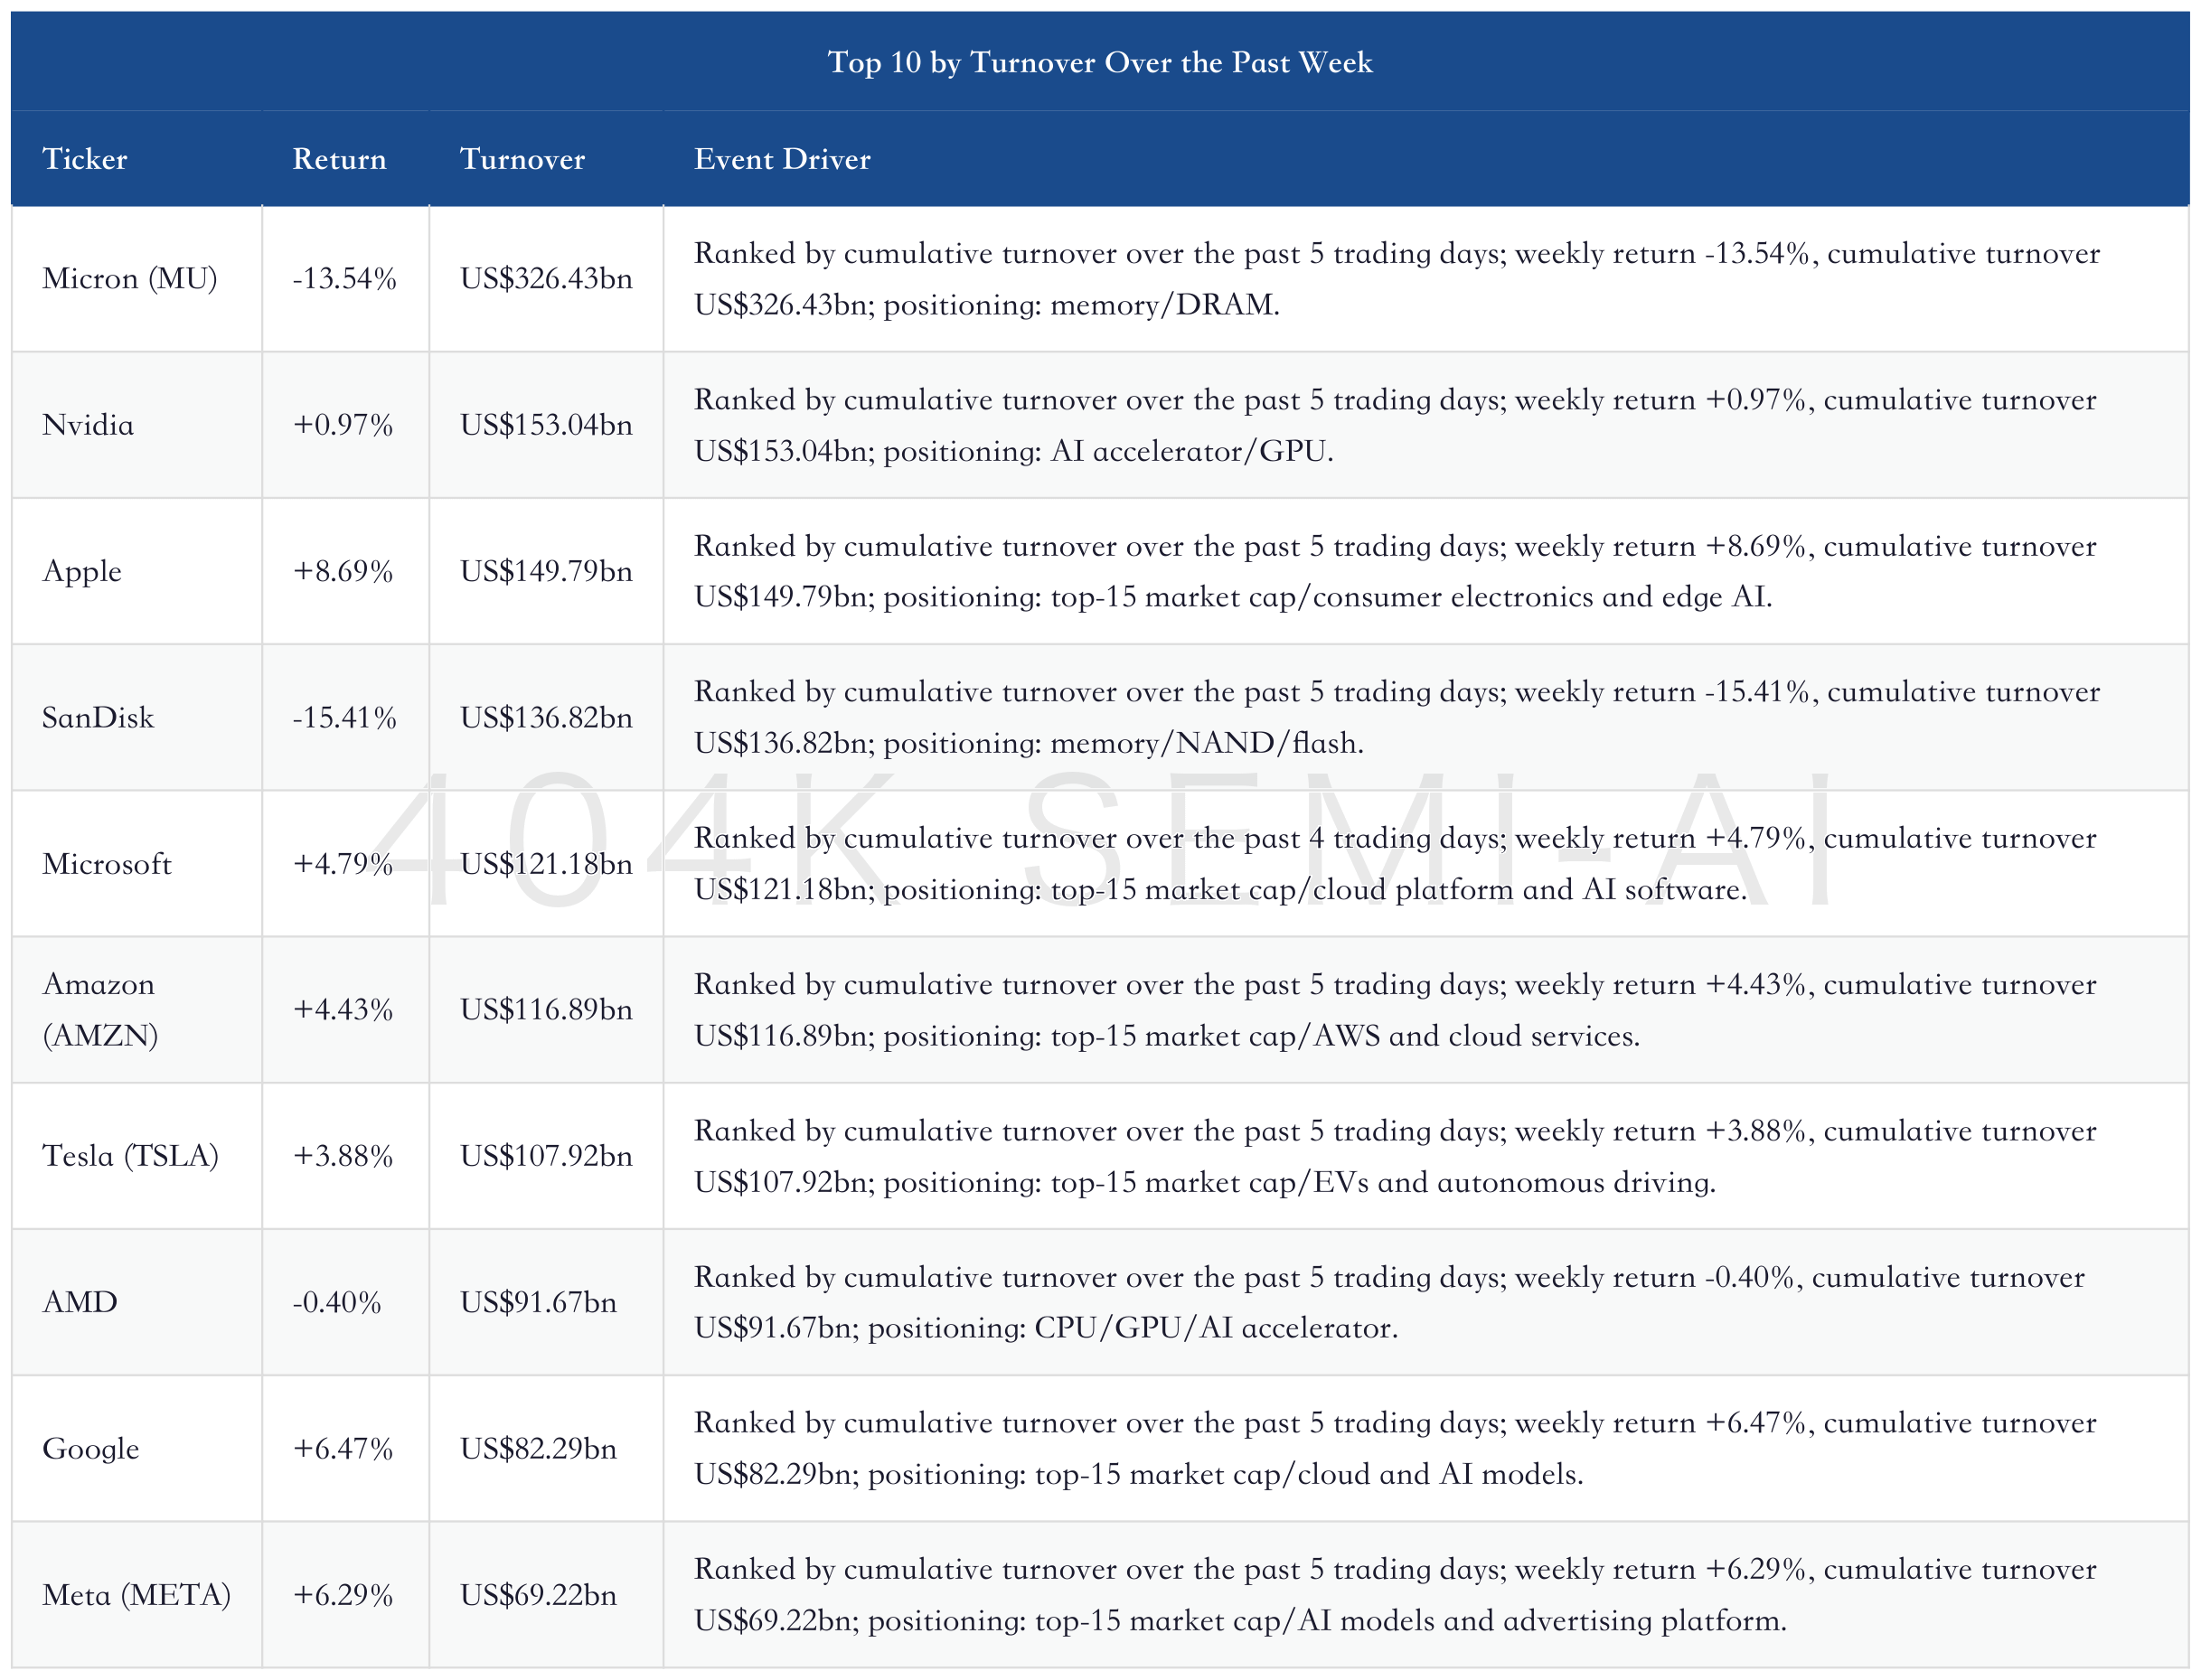
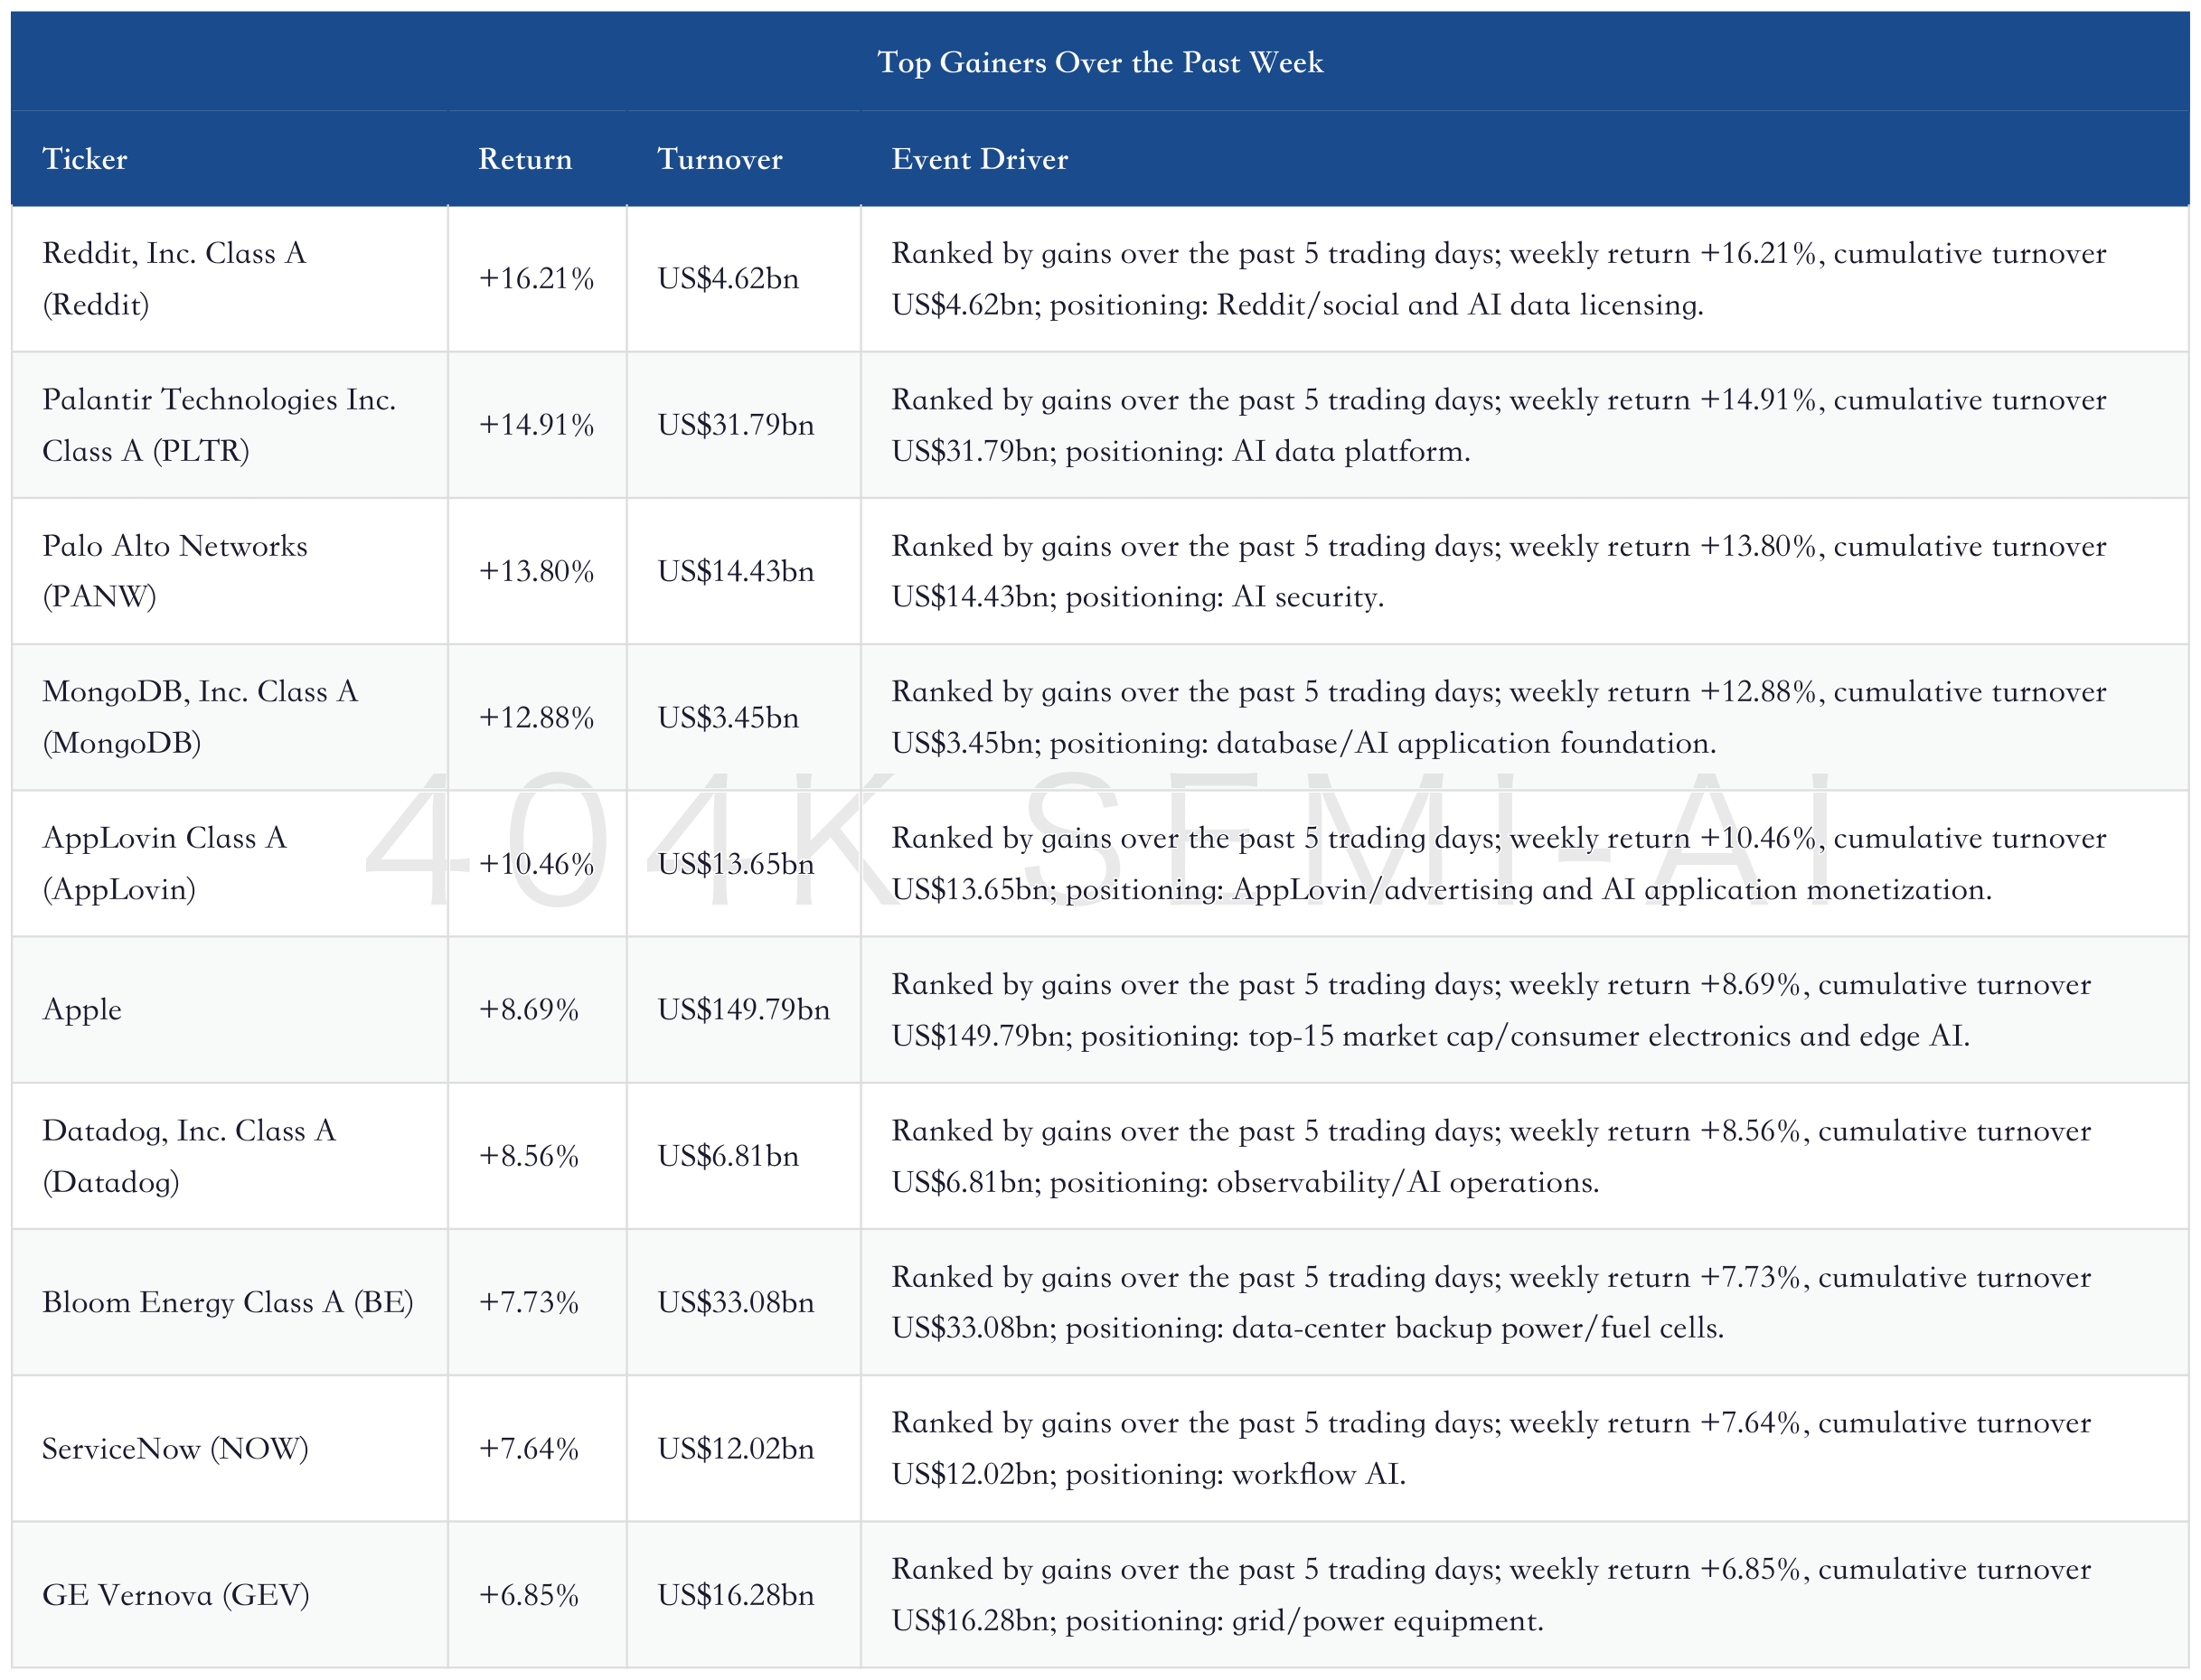
The rankings make this week’s tension very clear. Micron and SanDisk both appeared among the top turnover names and the decliners, showing that memory has not lost attention; capital is selling crowding and volatility, while memory pricing power remains intact. Reddit, Palantir, Palo Alto, MongoDB, Datadog, and ServiceNow entering the gainers list shows that AI applications, software, security, and data platforms are beginning to absorb capital after the hardware pullback.
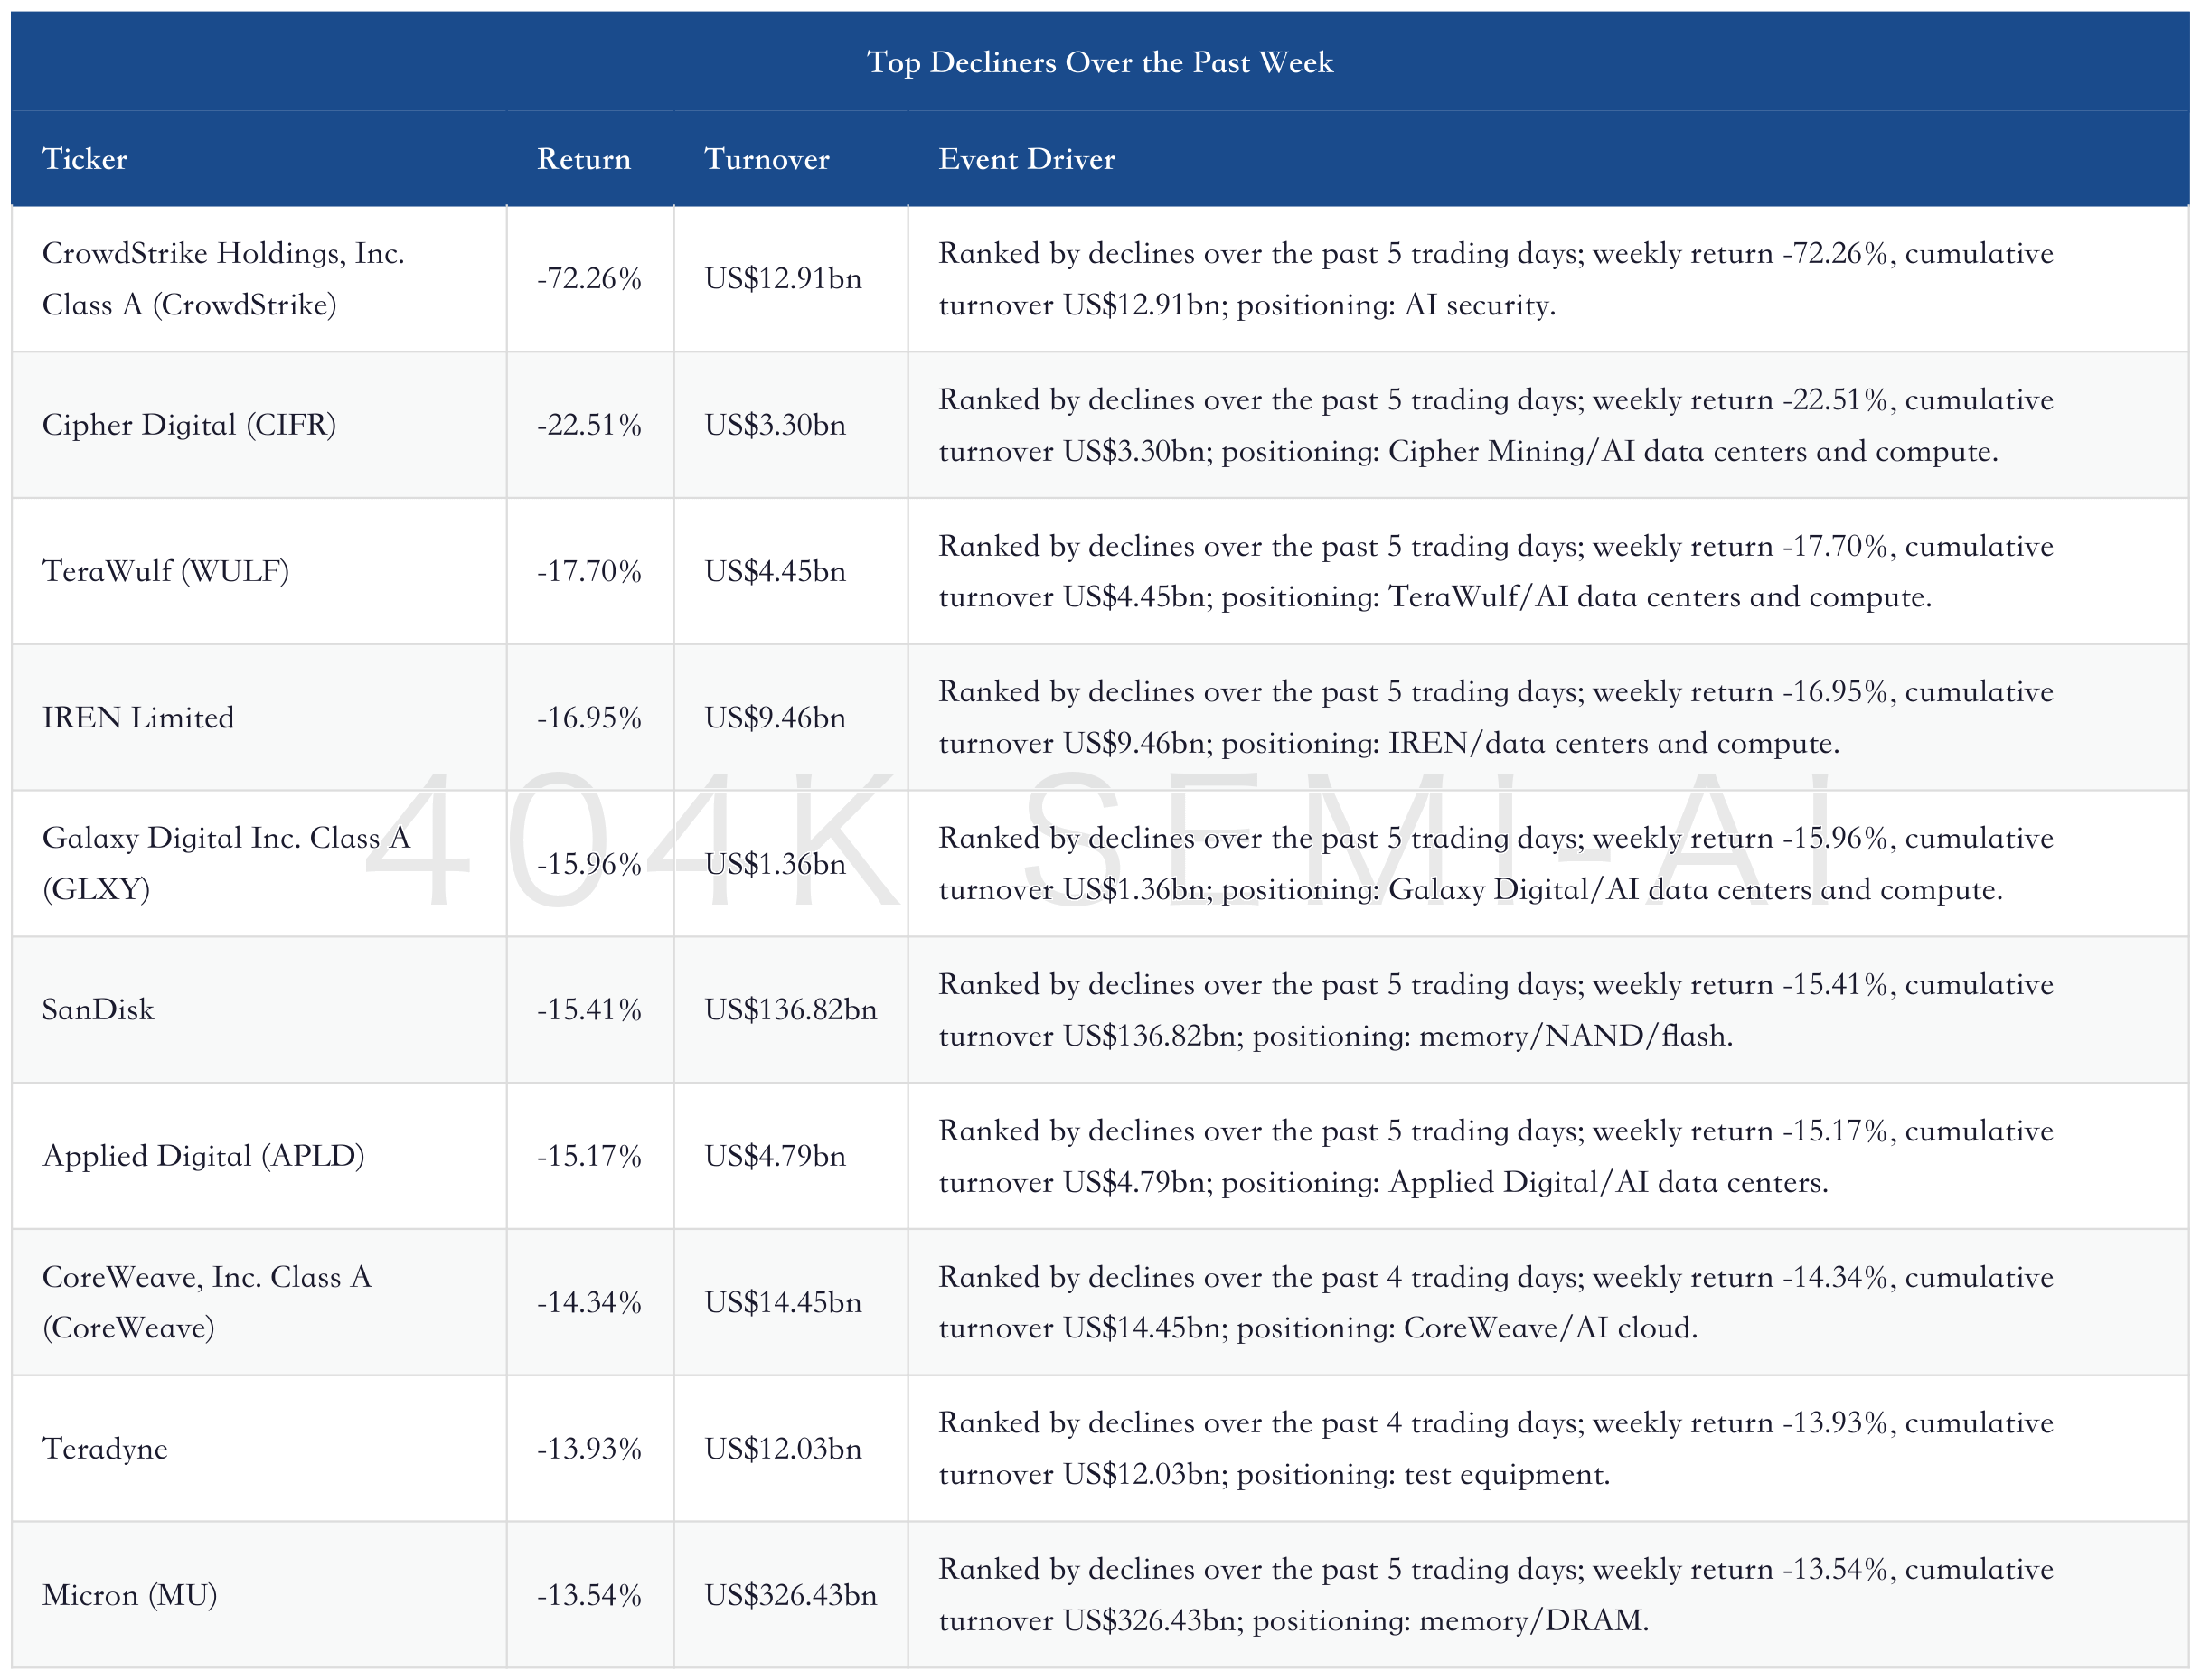
The divergence in AI cloud and power assets was also amplified by the rankings. CoreWeave, IREN, TeraWulf, Cipher, Galaxy Digital, and Applied Digital ranked among the largest decliners, as the market punished financing, customer concentration, and rental-price uncertainty. Bloom Energy and GE Vernova remained in the gainers list, showing that even within AI infrastructure, power delivery and equipment orders look more like a defensive expression.
AI/Semiconductor Full Value Chain
This week, the semiconductor theme broadened from a single-GPU trade into the full value chain. Nvidia remains the core, but incremental signals are increasingly appearing in AMD, Intel, Broadcom, MediaTek, Cerebras, TSMC, Samsung Foundry, memory, packaging, testing, optical interconnects, MLCCs, PCBs, and power. The first business question for this chain is: after AI workloads increase, which segment runs short first, who can raise prices, and who can only absorb costs.
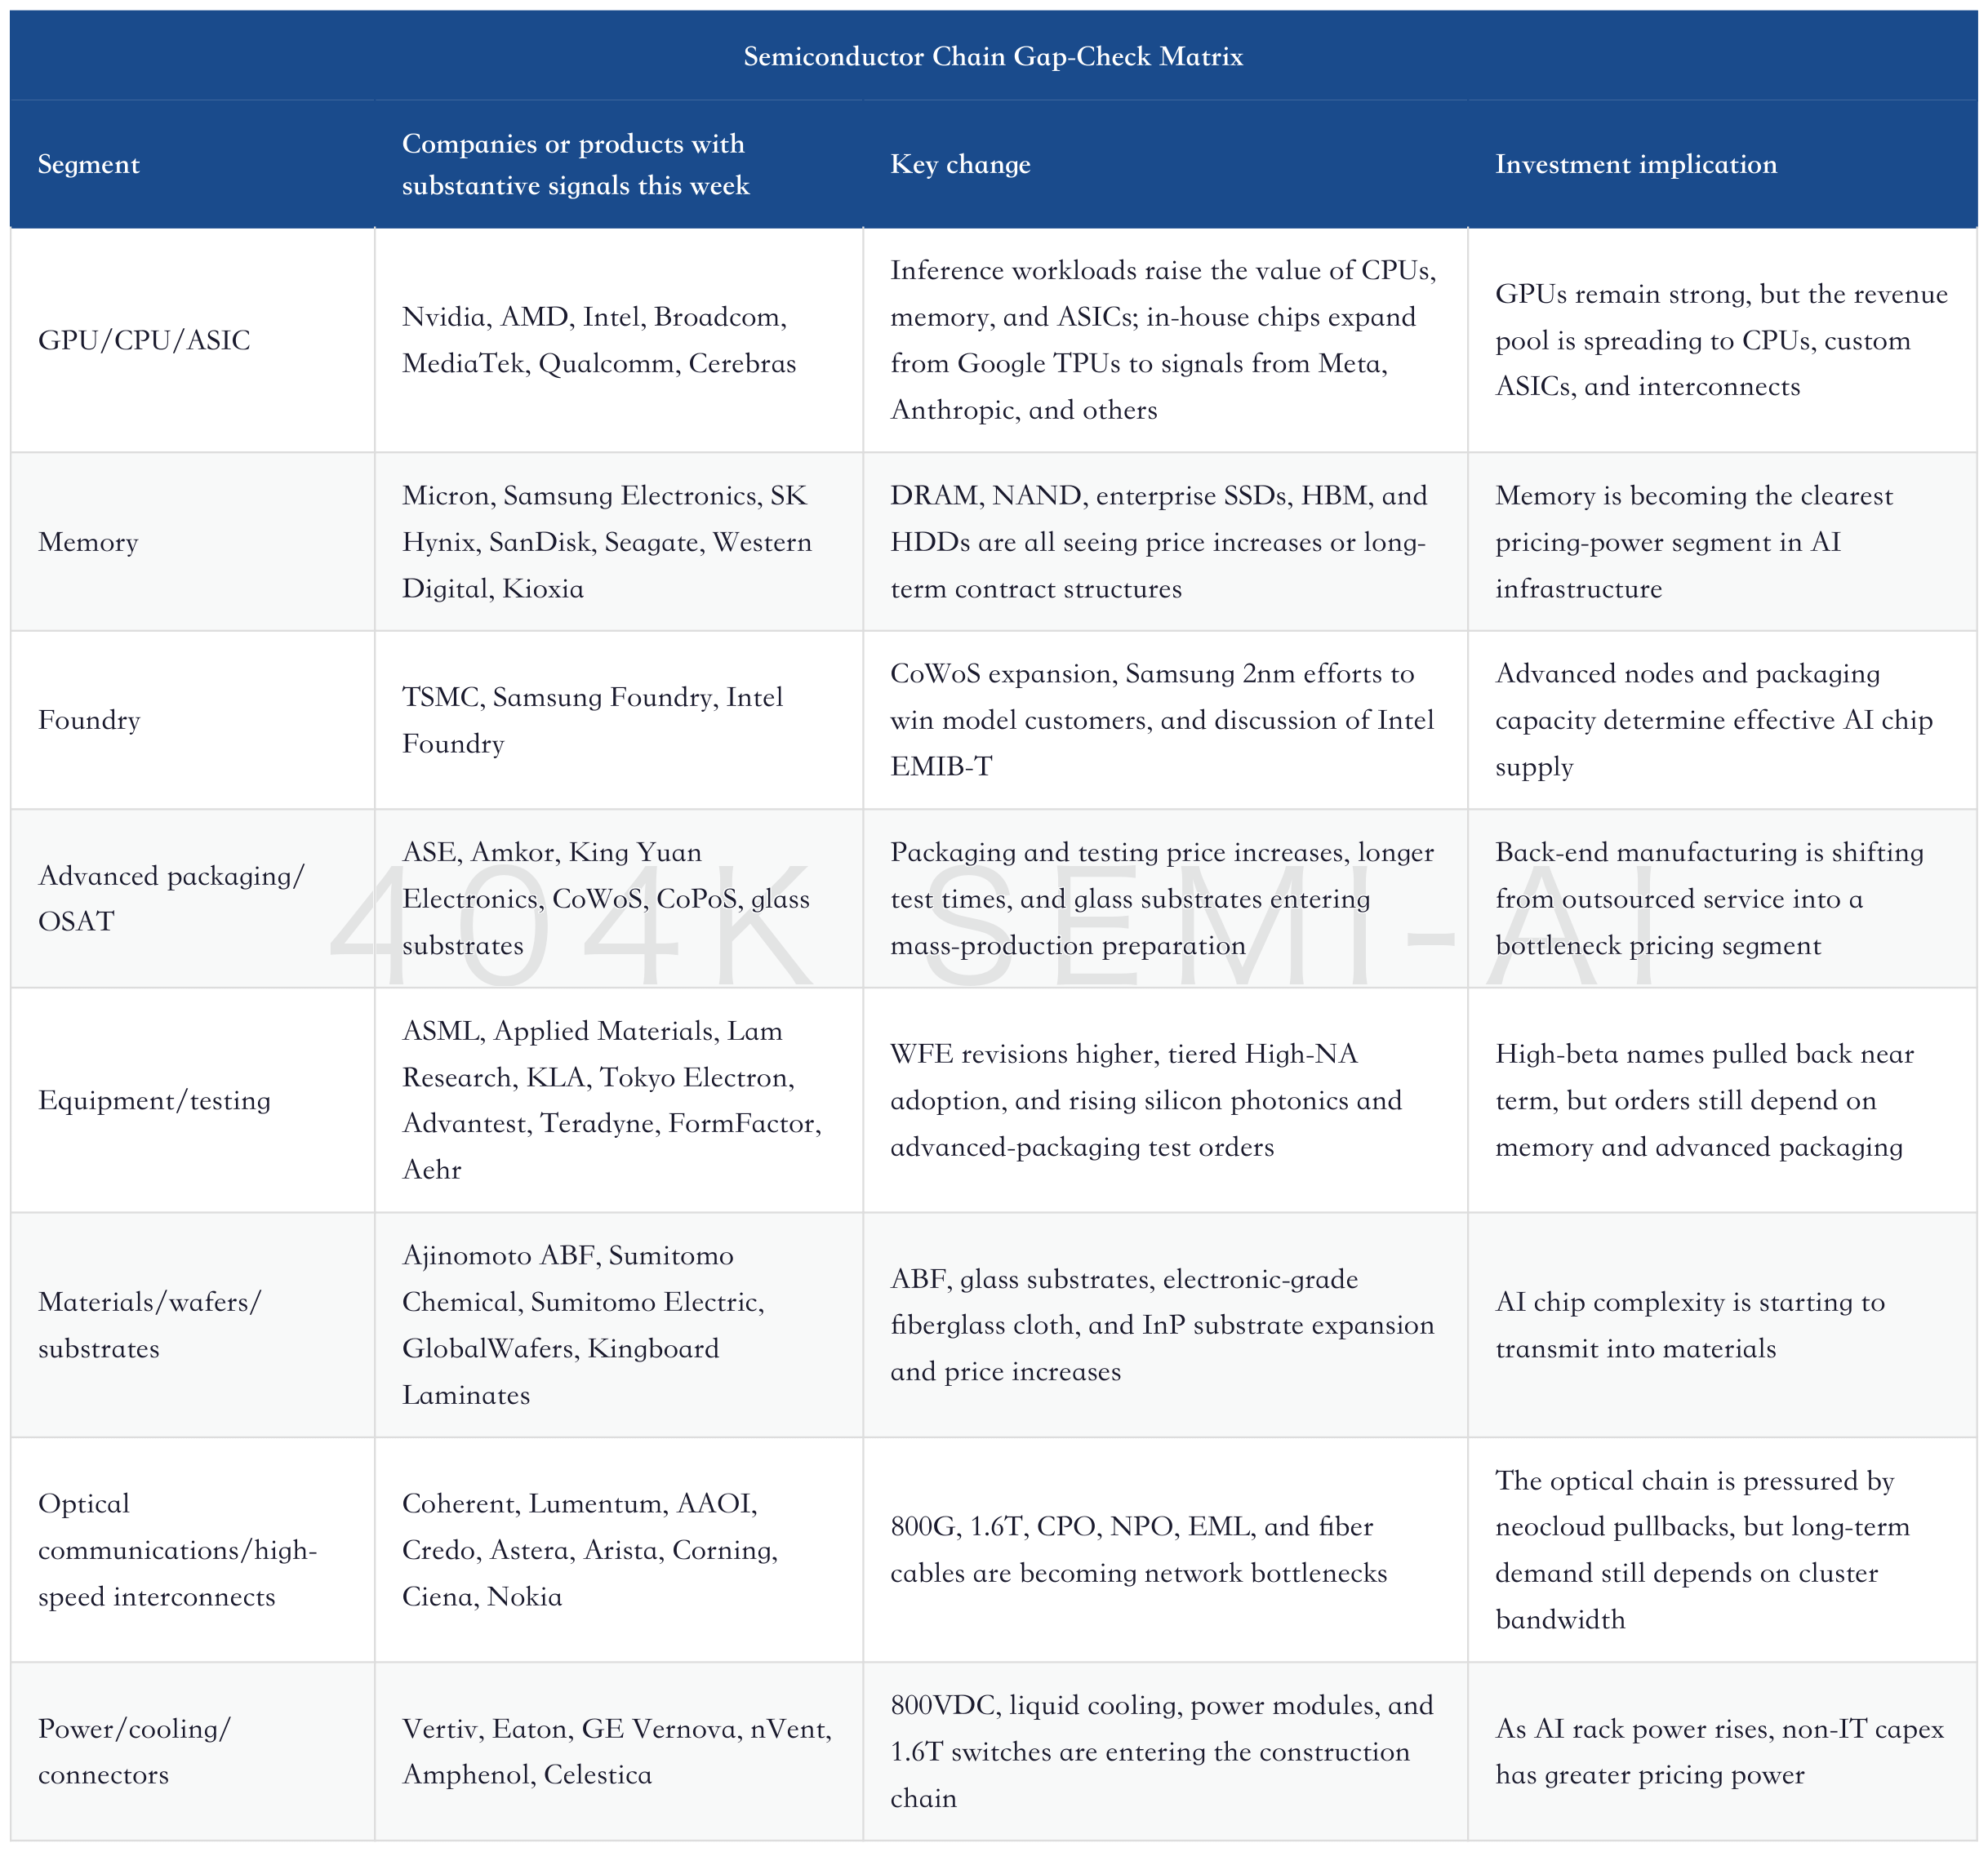
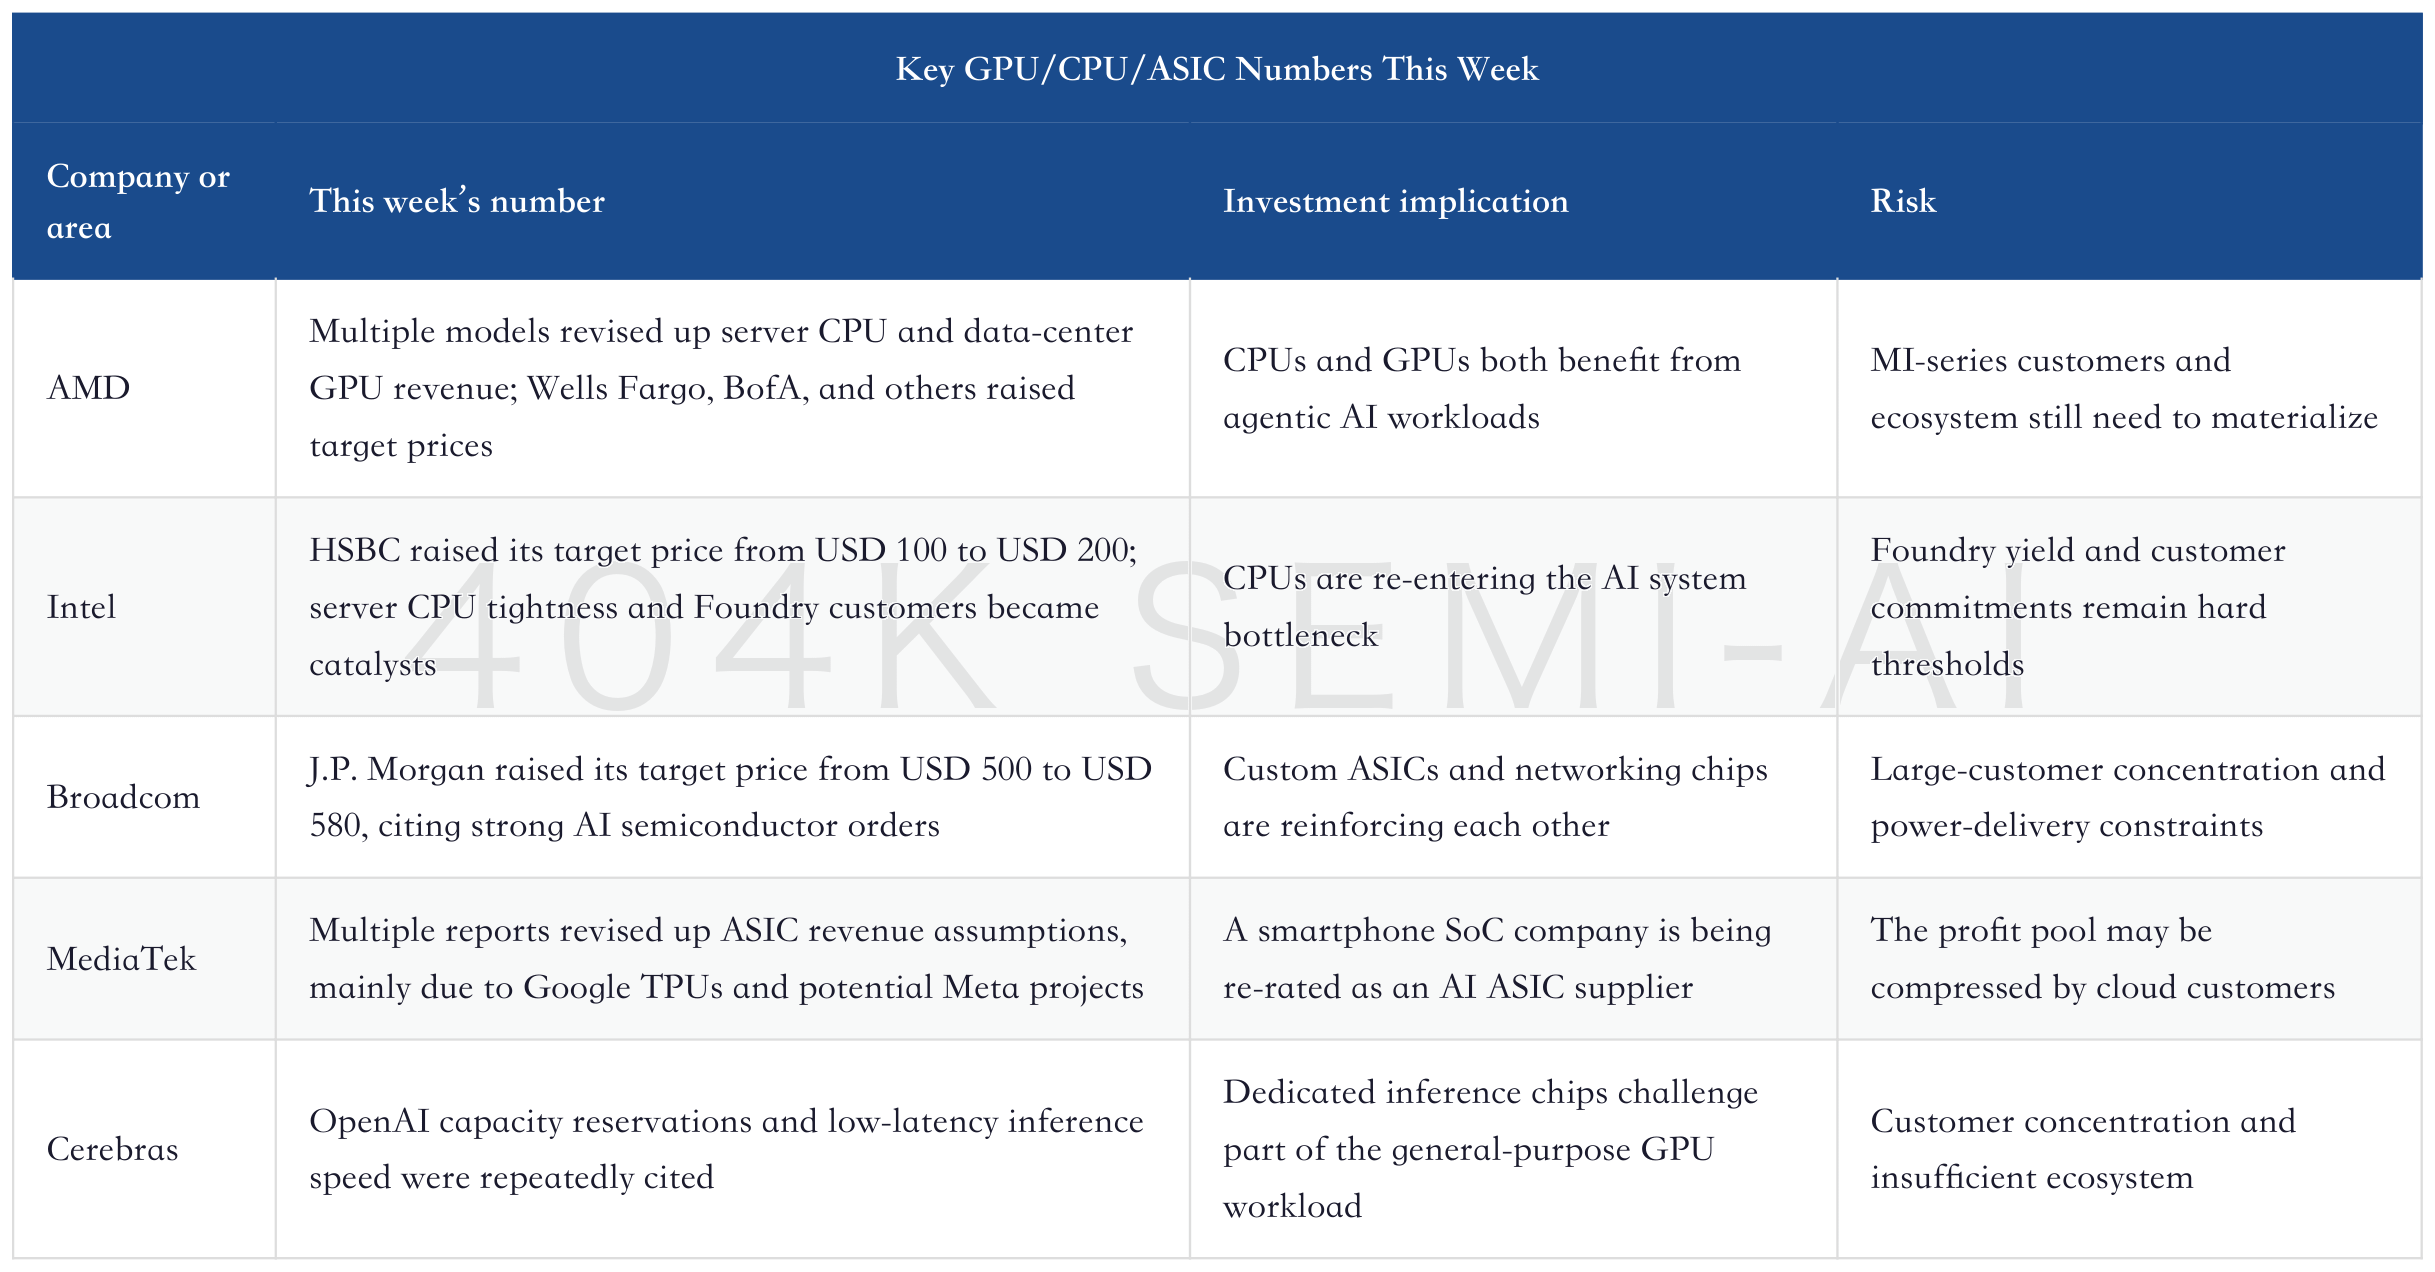
The conclusion for GPU/CPU/ASIC is more complex. Nvidia has not seen near-term demand invalidation, but the market is beginning to scrutinize the quality of the financing, capacity backstops, and revenue-sharing arrangements it provides to AI cloud customers. Multiple firms revised up AMD’s server CPU and data-center GPU models, centered on agentic AI lifting CPU attach rates. Intel, meanwhile, has been placed back on watch lists for server CPUs, foundry, and CPO interconnects.
The valuation logic for Broadcom and MediaTek increasingly resembles “cloud customer in-house ASIC platforms.” Repeated signals around Google TPUs, Meta ASICs, OpenAI custom silicon, and Anthropic in-house chip development show that large customers do not want to hand all inference costs to general-purpose GPUs. The key variables in this chain are tape-out, mass production, packaging, and long-term supply. Announcing a project alone is not enough to support valuation.
AI Models, CSPs, and Data-Center Infrastructure
The model side has not cooled, but cost and revenue structure have become more important. OpenAI, Anthropic, Meta, Microsoft, Amazon, and Google are all tying model capabilities, cloud capacity, and customer deployment together. OpenRouter token volume grew 70% month over month and 20x year over year in June, showing inference demand is still expanding. But Anthropic and Amazon’s shift from compute-hour pricing to token-based pricing also reminds downstream applications to calculate gross margin per call carefully.
Changes at OpenAI and Anthropic affect more than model-company valuations. OpenAI received phased investment from SoftBank, while Anthropic was reported to be exploring in-house AI chips and discussing 2nm and advanced packaging with Samsung Electronics. Frontier model companies are moving from “GPU-buying customers” to “infrastructure players that may design their own chips, bind themselves to cloud platforms, and require government and capital endorsement.” As a result, upstream orders may be reallocated among Nvidia, Broadcom, TSMC, Samsung, cloud providers, and neoclouds.
For CSPs, the main question has shifted from “how much to spend” to “how to recover the spend.” Amazon raised prices for some AWS reserved GPU workloads, and AWS Bedrock request volume was also described as expanding meaningfully. Google’s TPU demand continues to benefit Broadcom, MediaTek, TSMC, and the high-speed interconnect chain. Microsoft is bringing Claude into Azure while using campus energy projects to shorten data-center go-live timelines.
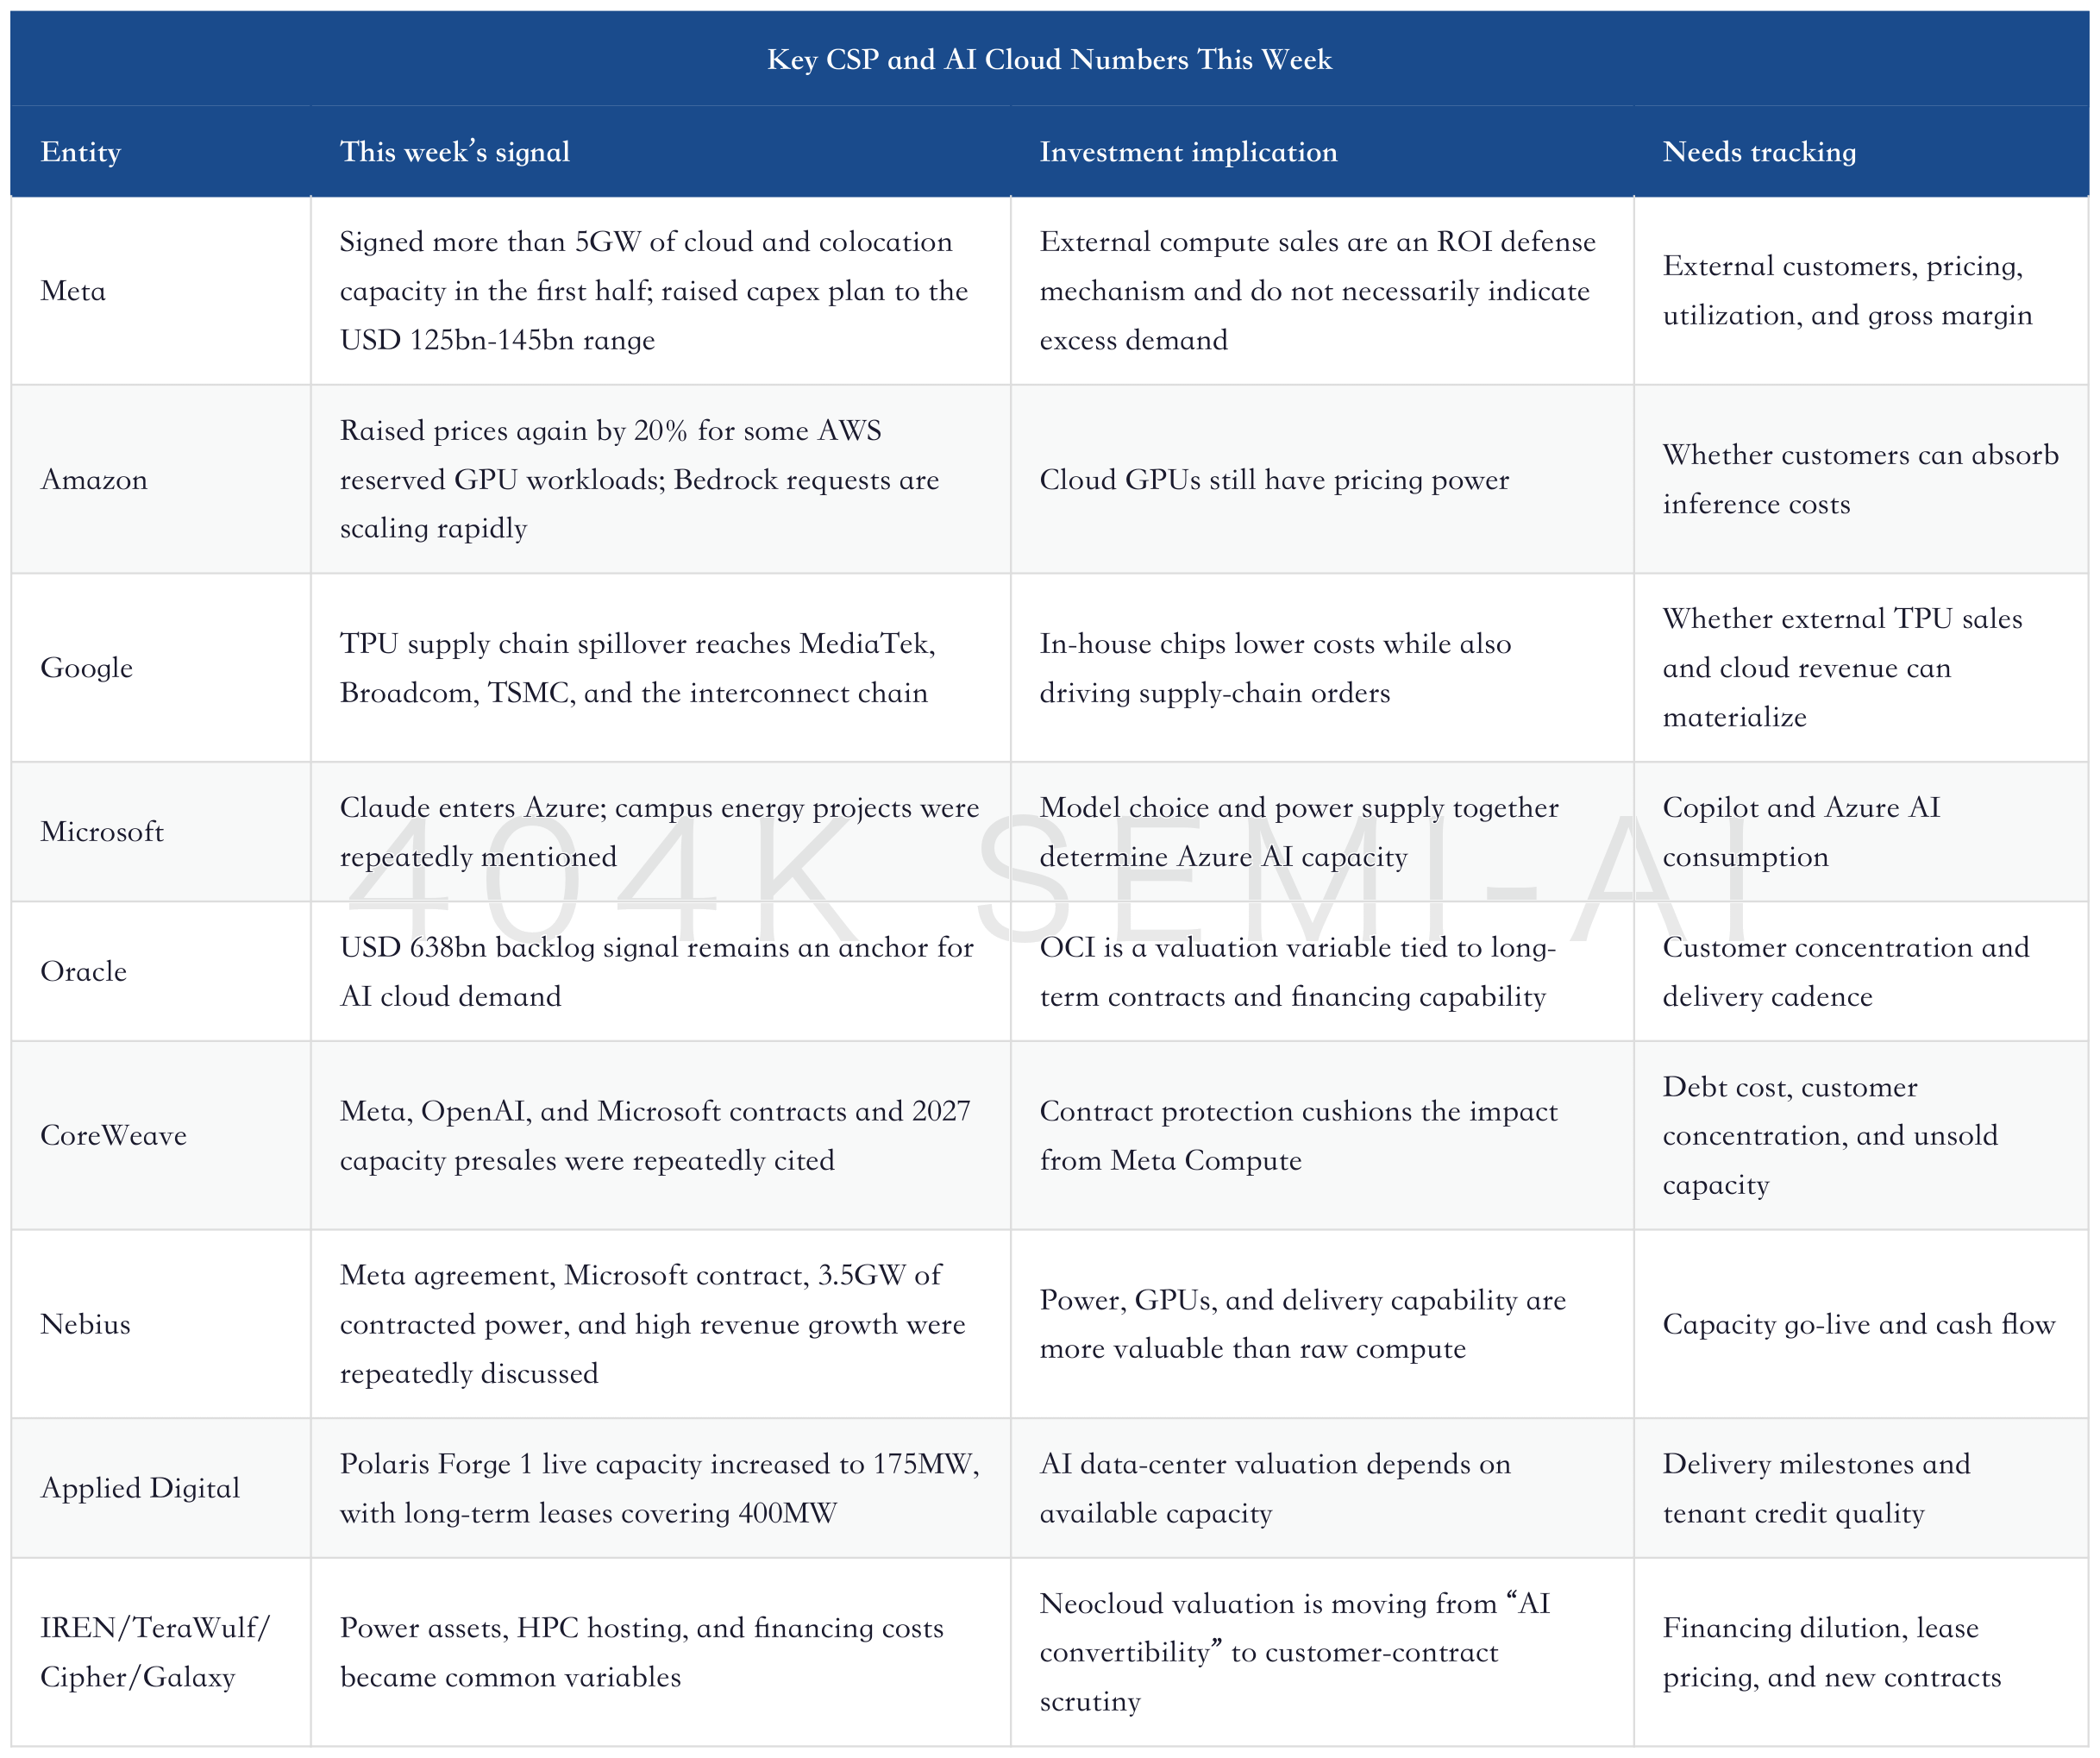
For small-cap AI cloud names, the risk has shifted from demand risk to balance-sheet risk. Galaxy Digital’s Helios, TeraWulf’s power assets, Cipher’s AI data-center optionality, IREN’s 5GW power portfolio, and Applied Digital’s campus delivery all need validation through customers, prepayments, grid connection, and financing costs. Pure share-price volatility cannot prove demand has disappeared, nor can it prove long-term cash flow is reliable.
Memory, Power Semiconductors, and MLCCs
Memory is this week’s strongest fundamental signal, and also the most crowded trade. Micron and SanDisk pulled back sharply, but DRAM, NAND, enterprise SSDs, HBM, HDDs, and automotive memory are all pointing to the same conclusion: AI demand has pushed memory from a back-end cost item into a core bottleneck.
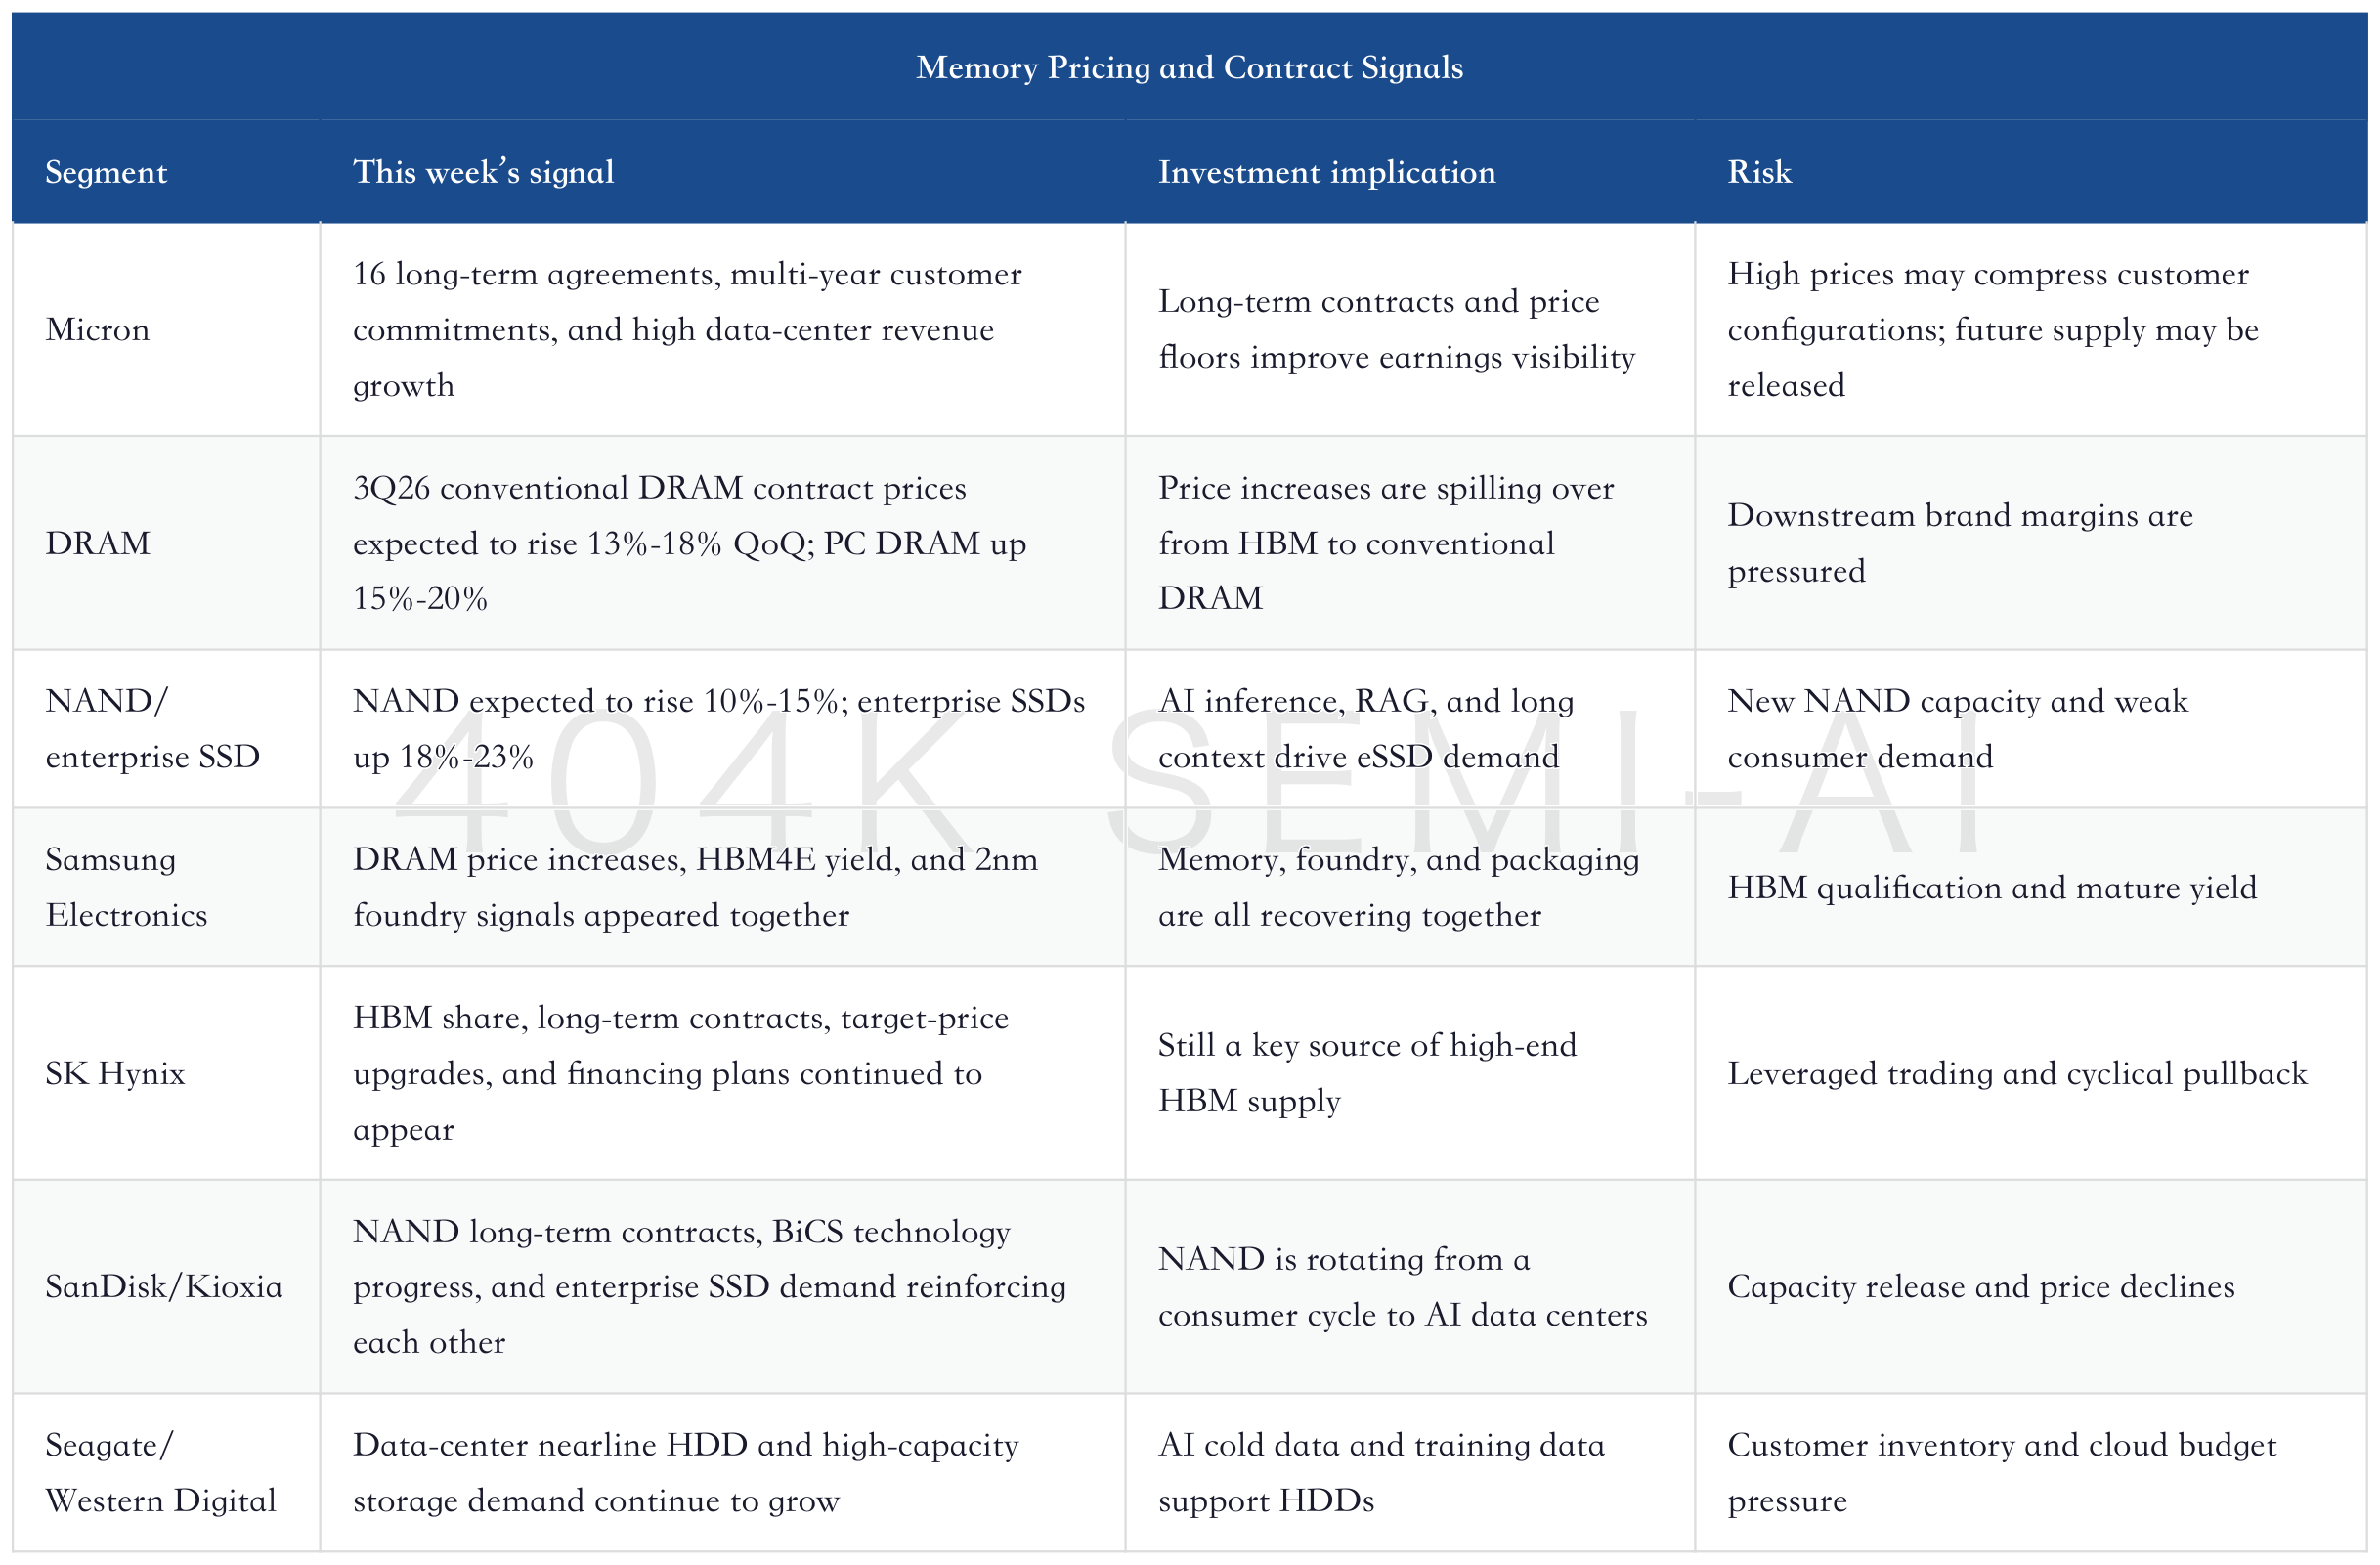
Micron’s main theme is contract conversion. Across the week, there were repeated references to 16 strategic customer agreements, price floors, customer commitments, prepayments, and long-term revenue obligations. The market sold Micron near term, but sell-side analysts continued to raise target prices, implying that the disagreement is not about demand but whether high margins are sustainable. Micron’s most important tracking indicators are DRAM ASP, HBM pricing, SCA-covered revenue, and whether customers reduce per-system memory configurations.
Samsung Electronics and SK Hynix face a different validation process. Samsung has signals in DRAM price increases, HBM4E yield, Foundry 2nm, and glass-substrate investment. SK Hynix continues to be framed as an HBM leader and a beneficiary of rising AI memory mix. Korean export data reinforces the cycle: semiconductor exports, DRAM including module exports, and MCP/HBM all show strong growth. The near-term selloff looks more like leveraged-trade unwind and semiconductor beta clearing.
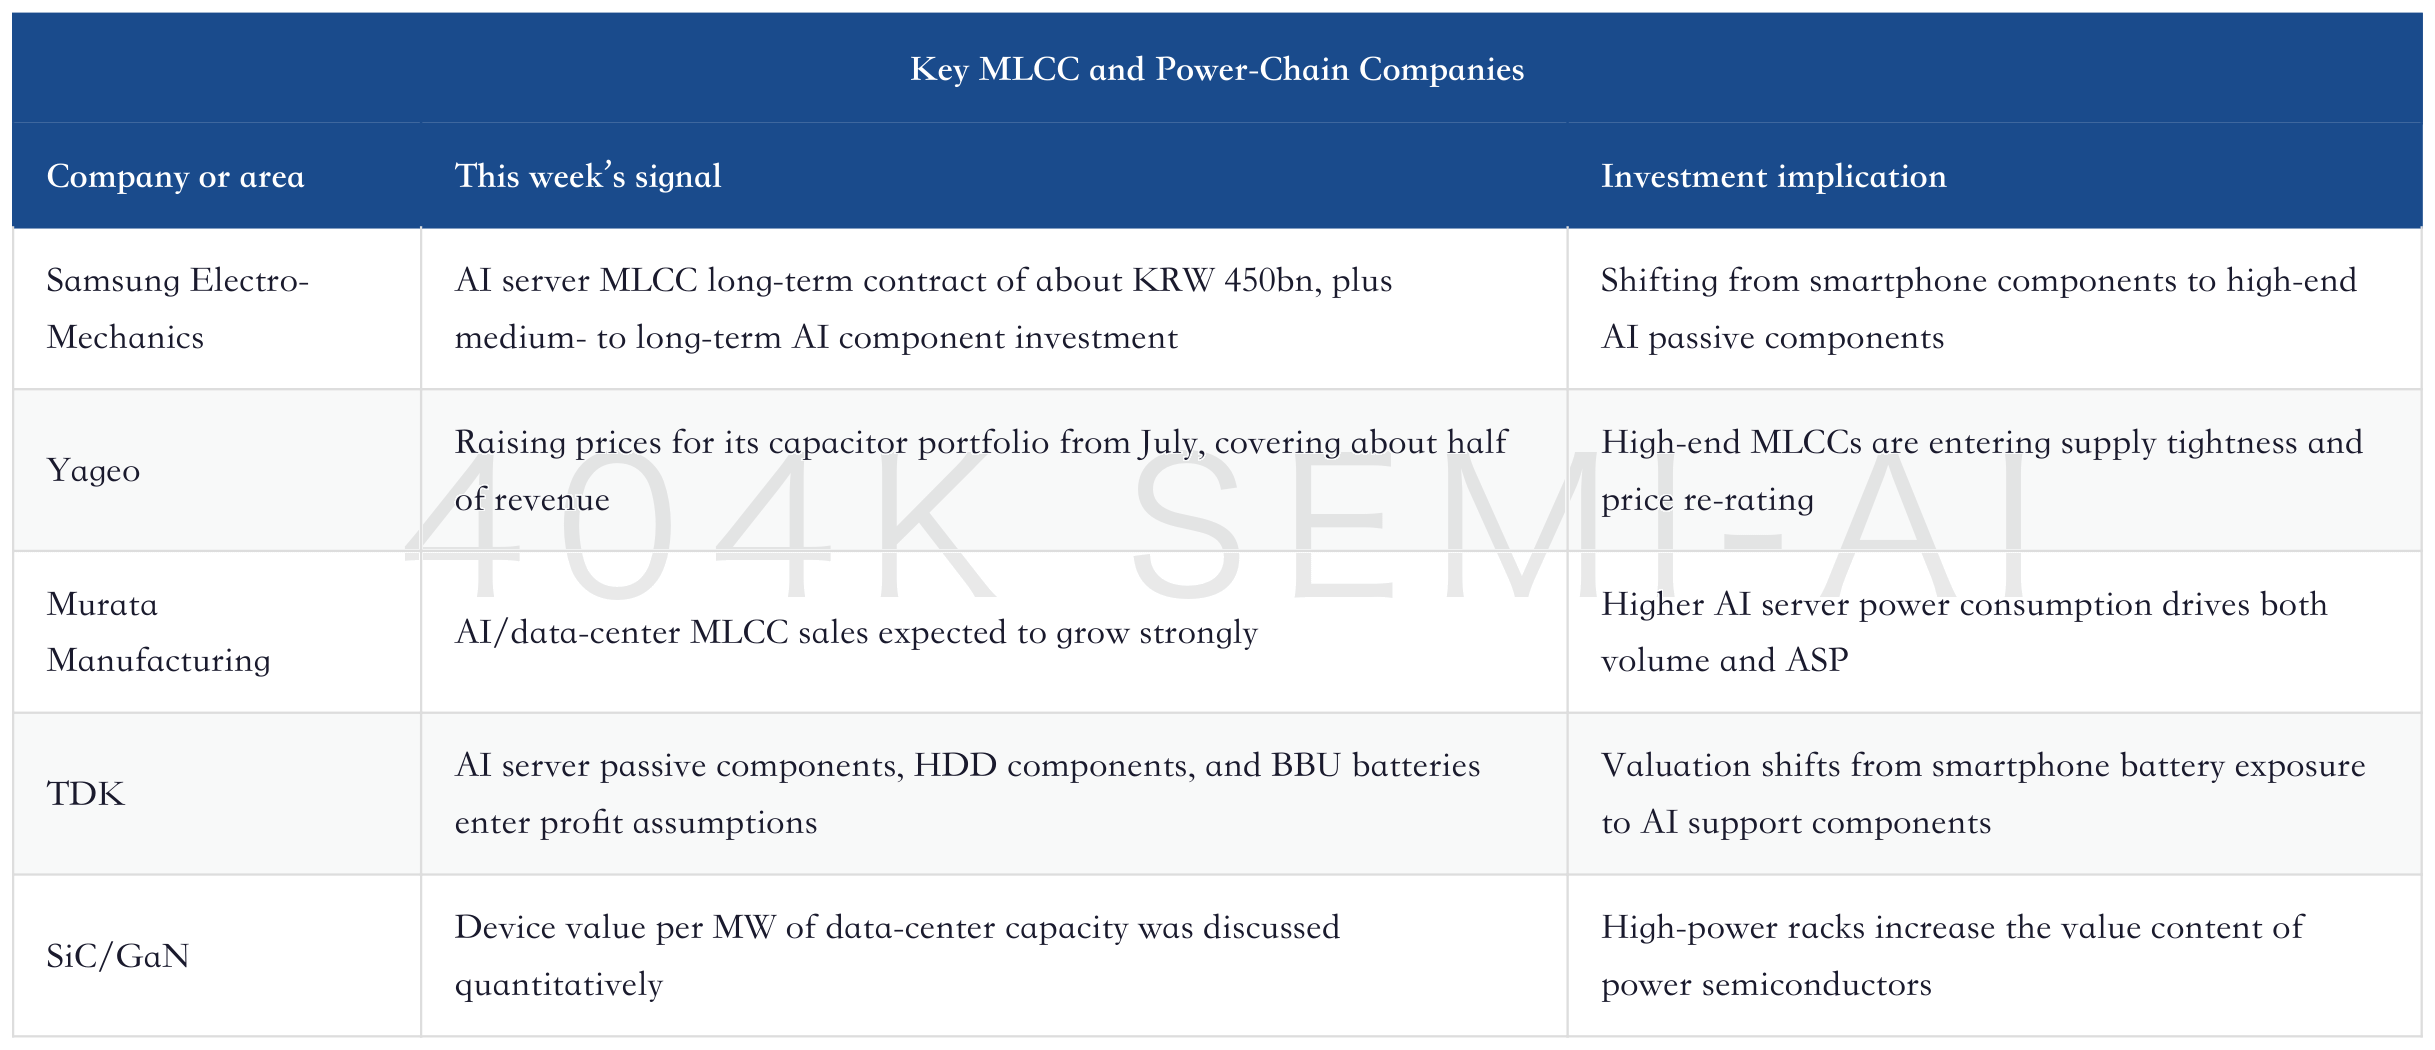
MLCCs and the power chain moved from supporting roles to core themes this week. Samsung Electro-Mechanics signed a long-term AI server MLCC contract, Yageo raised capacitor product prices, and Murata Manufacturing and TDK were added to AI server passive-component profit assumptions. After AI rack power rises, high-reliability MLCCs, VRMs, IBCs, GaN, SiC, and 800VDC will move from “components” to constraints on whether racks can be delivered.
Semiconductor Equipment, Test, and Materials
Equipment stocks went through a week in which “upward revisions and pullbacks happened at the same time.” Applied Materials, ASML, Lam Research, KLA, Tokyo Electron, Advantest, Teradyne, FormFactor, and Aehr all appeared in the AI equipment, test, or advanced-packaging chain. Midweek, the equipment chain pulled back with semiconductor beta, but the medium-term logic around WFE, advanced packaging, and silicon-photonics test remains intact.
Applied Materials is the representative name in the equipment chain. Multiple reports raised target prices and revenue forecasts, and the company was also positioned across GAA, stacked memory, advanced packaging, and new back-end platforms. Lam Research benefits from more etch and deposition steps, KLA maps to process control and yield ramp, while ASML is supported by advanced nodes and layered High-NA adoption. The logic for Tokyo Electron and Advantest lies respectively in the WFE cycle and longer AI-chip test times.
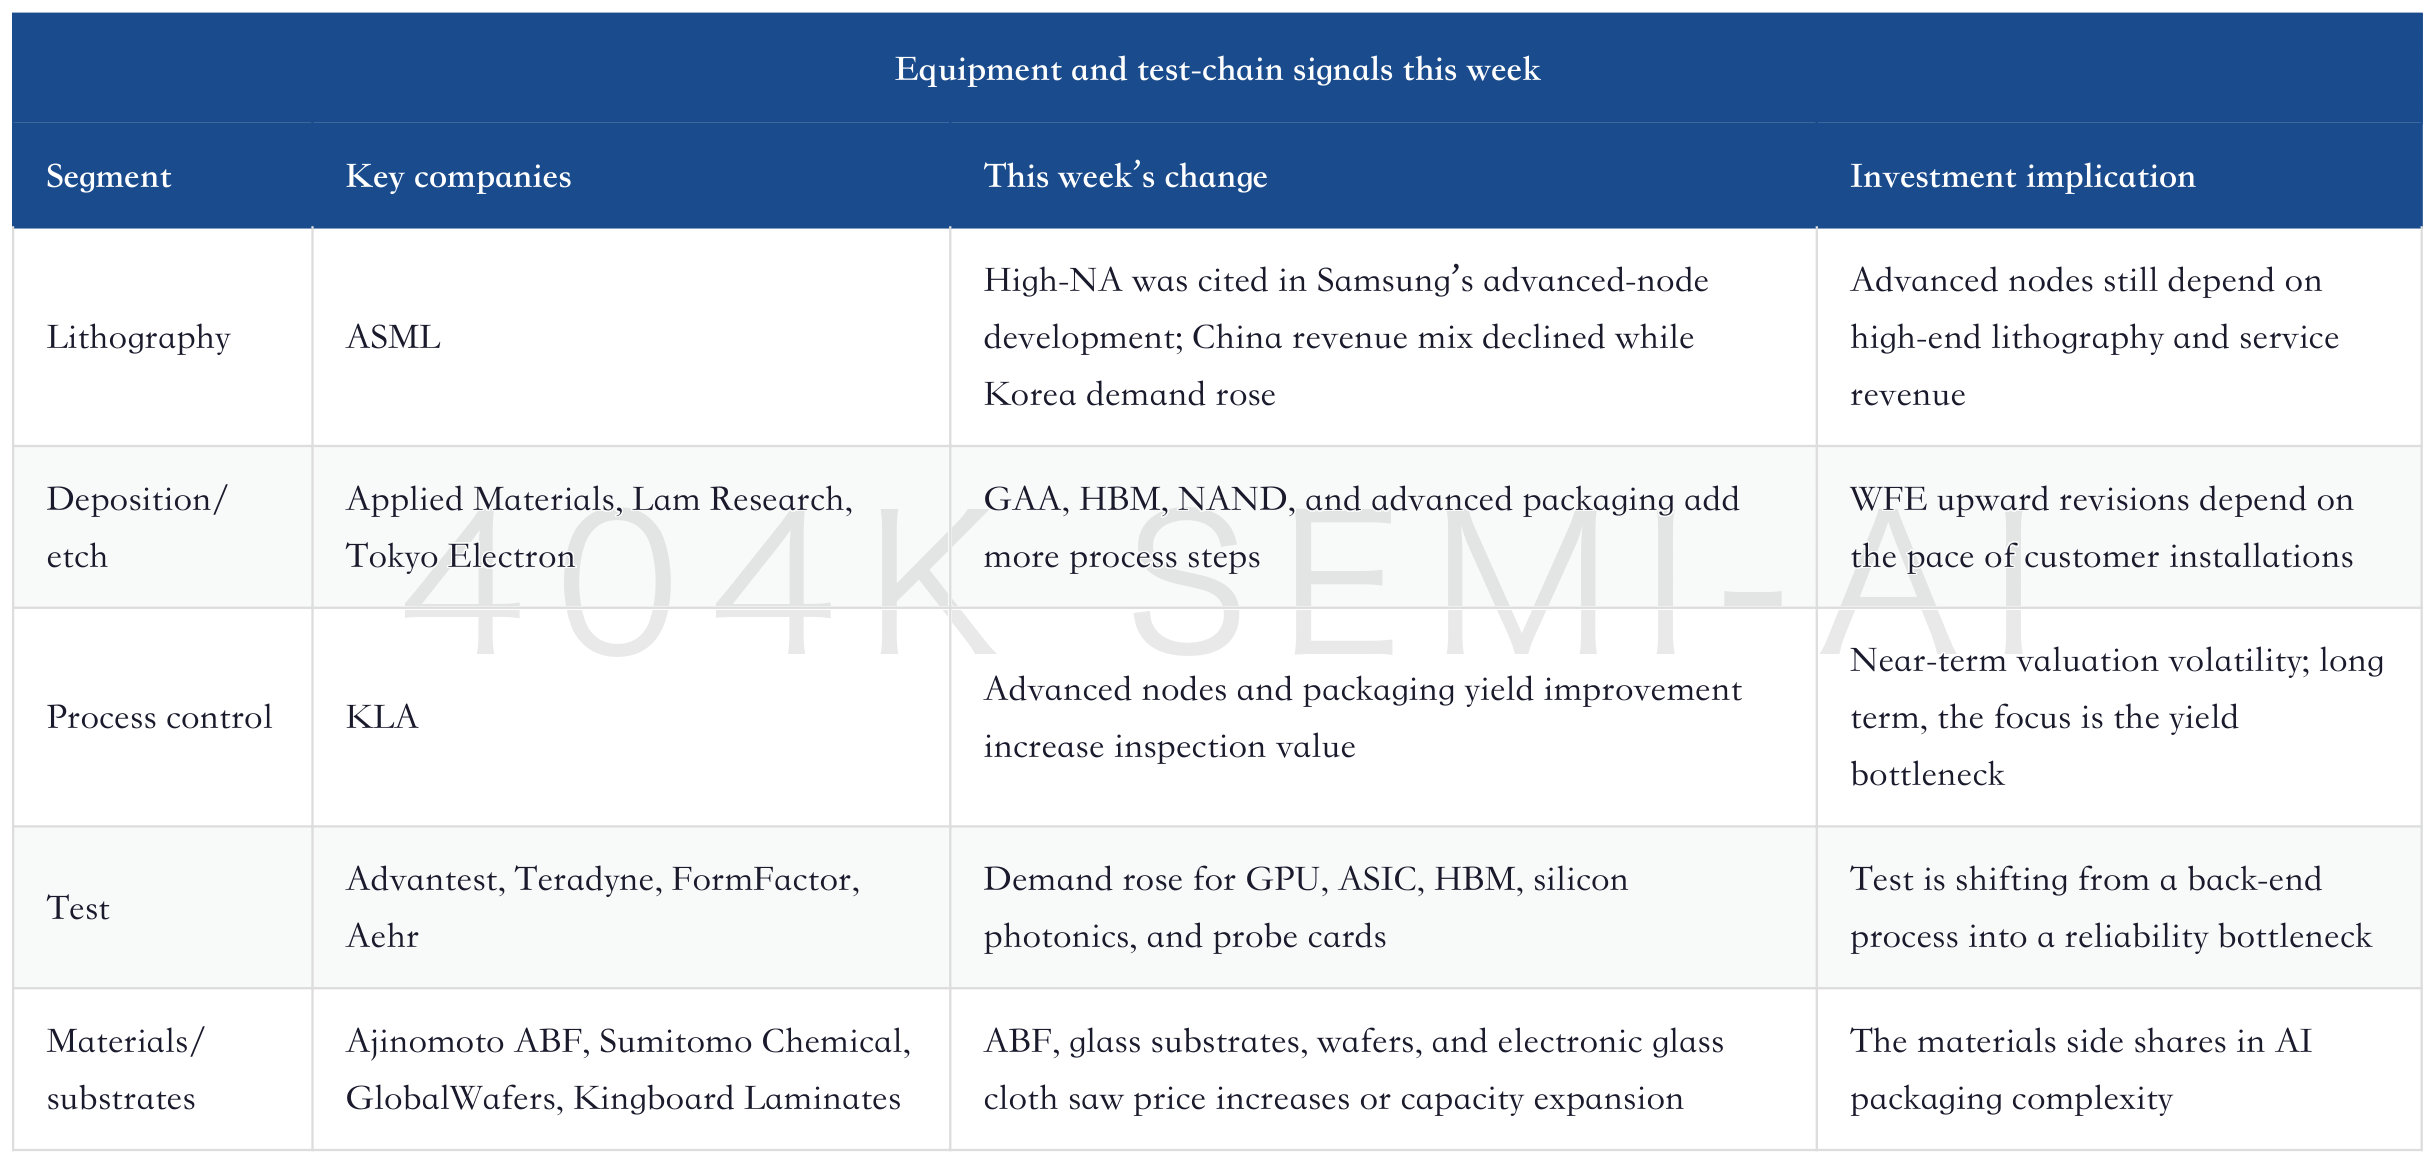
Advanced packaging is where equipment and materials intersect. TSMC’s 2027 CoWoS target was revised up to 2,000 kpcs, but 2026 CoWoS allocations for AI accelerators were revised down, indicating long-term capacity expansion but near-term delivery constraints. ASE, Amkor, KYEC, glass substrates, ABF, underfill, temporary bonding, AOI inspection, and silicon-photonics burn-in all benefit along the same chain.
Two materials-side changes this week deserve attention. First, glass substrates are moving from concept to investment, with Samsung Electro-Mechanics, Sumitomo Chemical, and related joint-venture plans repeatedly mentioned. Second, price increases in electronic-grade glass fiber cloth and CCL have entered the AI server chain. Kingboard Laminates’ new capacity and pricing clues show that PCB/substrate has already joined the list of upstream bottlenecks.
Optical Communications, Optics, and High-Speed Interconnect
Optical communications rose first and then fell this week, but the demand logic was not overturned by Thursday’s pullback. As AI clusters move from 800G to 1.6T and 3.2T, copper connection distances are becoming shorter. CPO, NPO, silicon photonics, EML, optical engines, DSP, AEC, LPO, optical fiber, and InP substrates have all become segments that must be tracked.
Coherent is one of the clearest sell-side upward-revision names in the optical chain. Citi raised its target price and placed AI transceivers, CPO, and OCS among high-growth businesses. AAOI’s logic is in the 800G ramp, 1.6T, and in-house lasers, with a target for the United States to account for about 40% of data-center transceiver capacity by mid-2027. Sumitomo Electric’s InP substrate expansion shows that demand has already moved down from modules into materials.
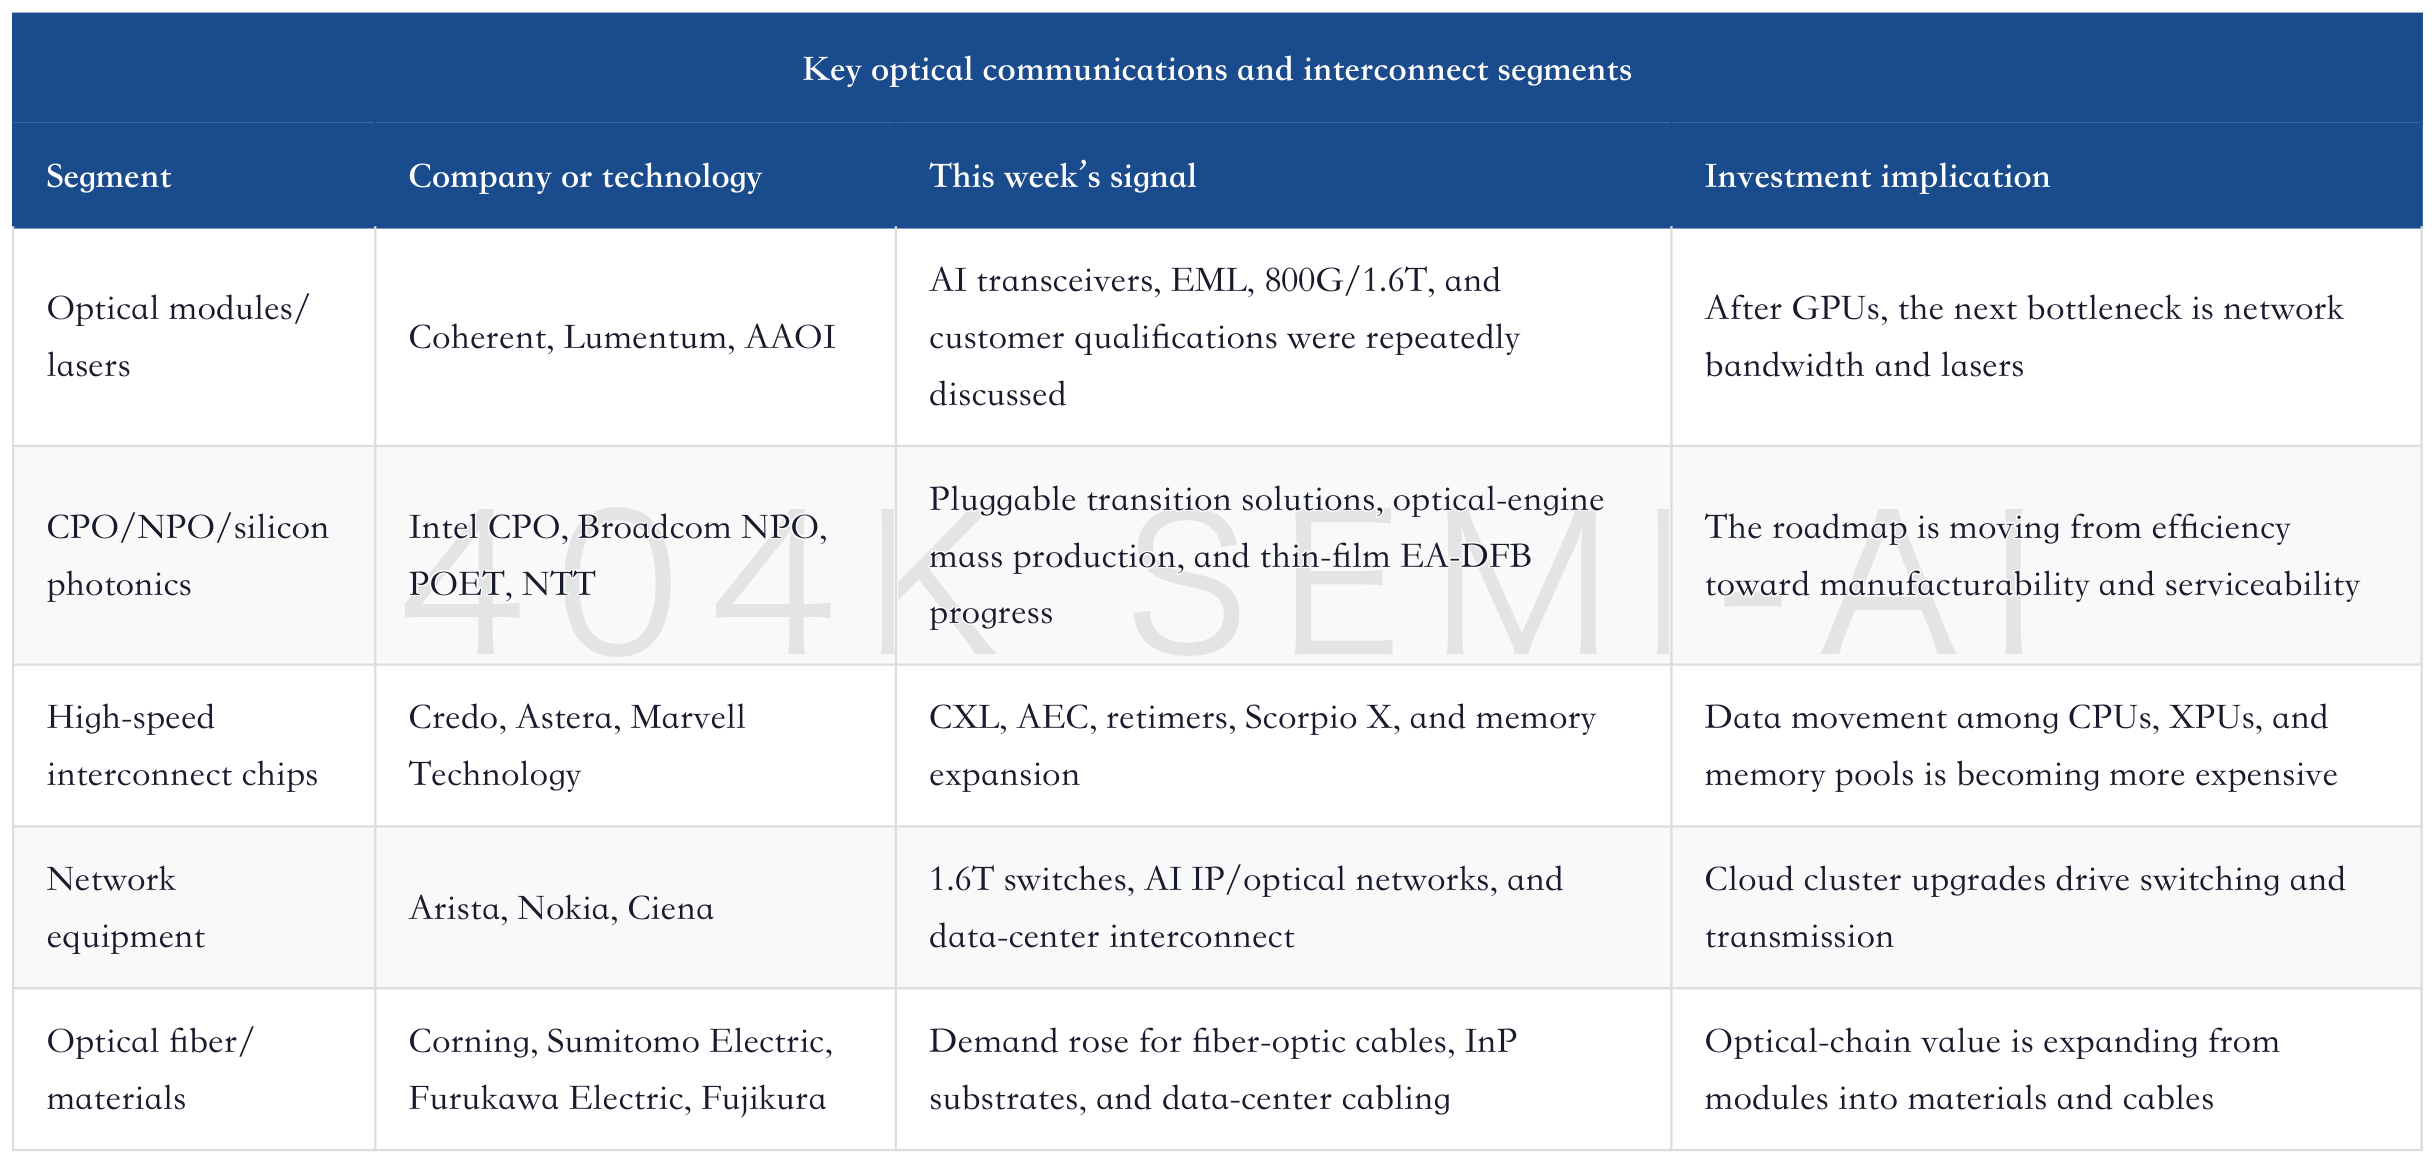
Credo, Astera, and Marvell Technology are representative high-speed interconnect names. CXL, AEC, DSP, retimers, and memory expansion all solve the same problem: data movement among GPUs, CPUs, XPUs, memory, and switches is too expensive. Near-term valuations are pressured by the SOX and the new-cloud pullback. Longer term, the key variables are 800G/1.6T rack deployment, customer concentration, and gross margins.
Arista, Corning, Ciena, and Nokia are more skewed toward network equipment and optical-fiber transmission. They may not have the same explosive price elasticity as optical-module companies, but if AI data centers continue expanding, IP networks, optical networks, long-haul interconnects, and campus cabling will all become budget items. After Friday’s pullback, investors need to distinguish order visibility from pure AI hardware basket risk.
